 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
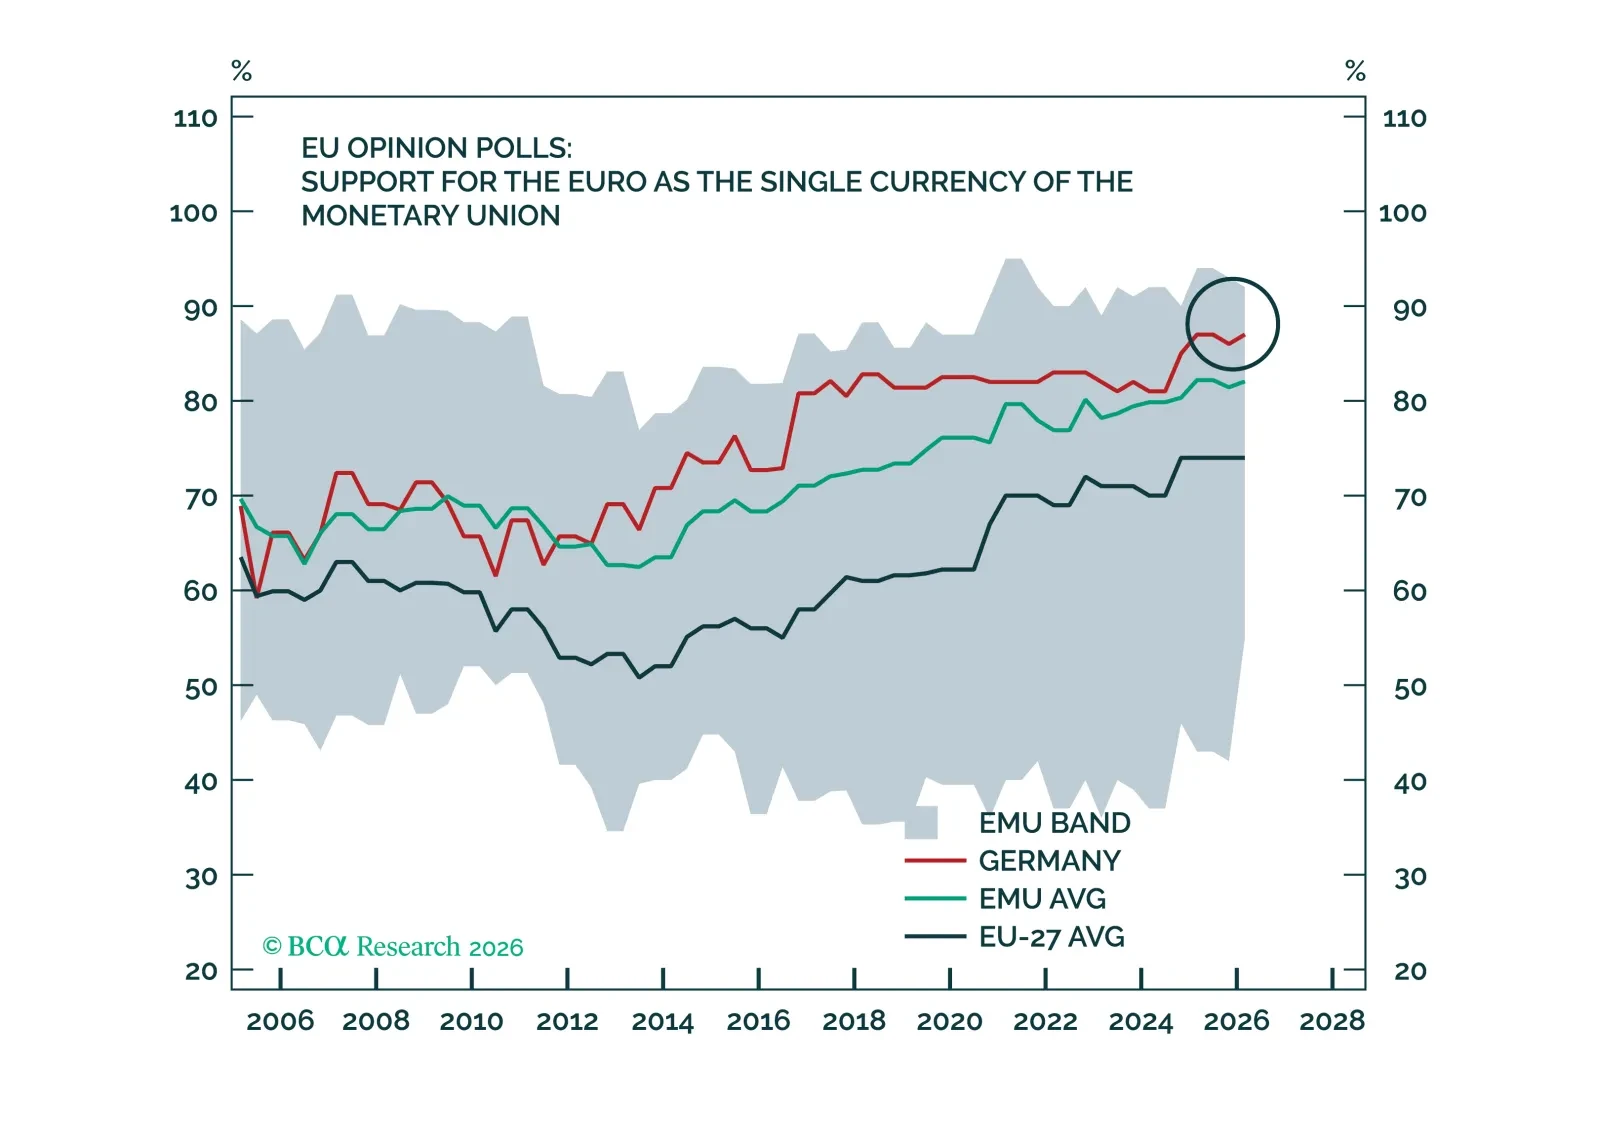
Alternative for Germany’s election win in the state of Saxony-Anhalt is overrated.
There is no evidence that there is a run on US government bonds. All the data at our disposal, and the curated views of our bond specialists, suggest that the US bond market may have 99 problems, but a coordinated run on its safe haven status is not one.
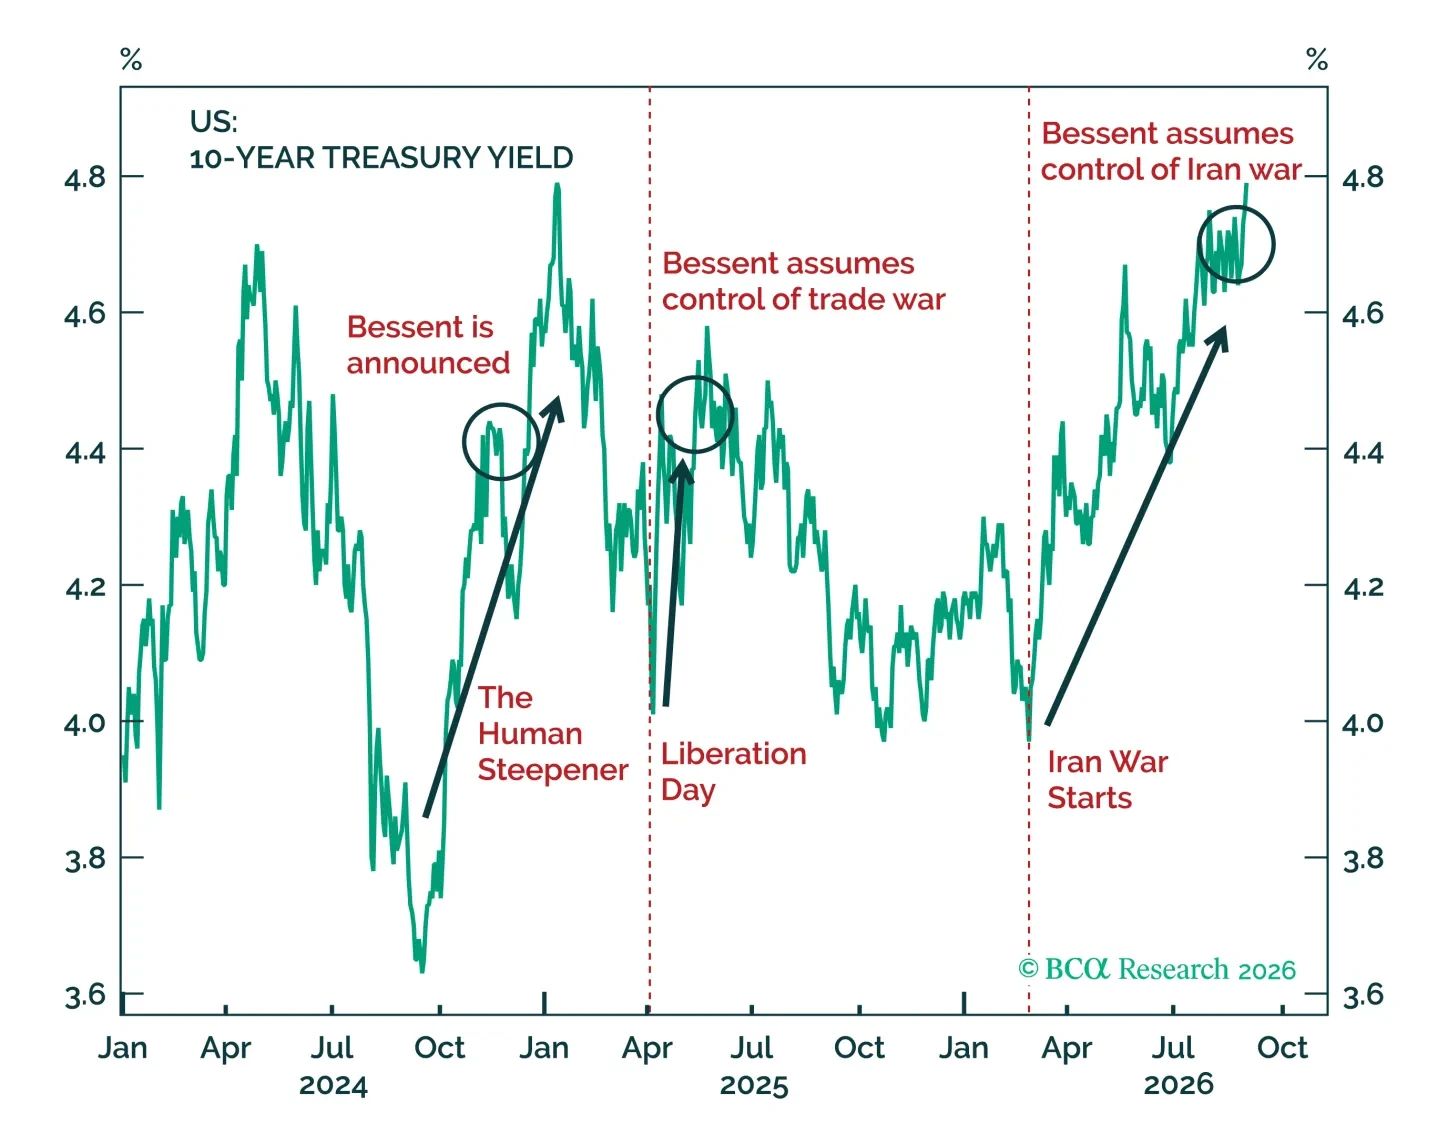
Markets have become obsessed with the rise of global long-dated yields. To some extent, we agree with the concern. Bonds are trading on "vibes," alarmed by the incoherent US geopolitical policy. Oil prices are obviously the conduit between that policy and the markets. On the other hand, growth is also robust. As such, bond market selloff is not all just negativity. The one secular theme driving the bond market selloff that does not bother us all that much is fiscal policy. We see signs — including actual budget deficit data! — that the US, policymakers and voters alike, is starting to understand that there are limits to profligacy. As such, we would advise clients with a long term focus to begin nibbling at the hated bonds.
Our colleague Matt Gertken has penned a sober analysis on the midterms, calling for a Democratic Party sweep in 2026. It is a measured, data-driven, analysis that we encourage you to read. This quick Insight is neither sober nor data driven. It is hyperbolic and based on “vibes.”
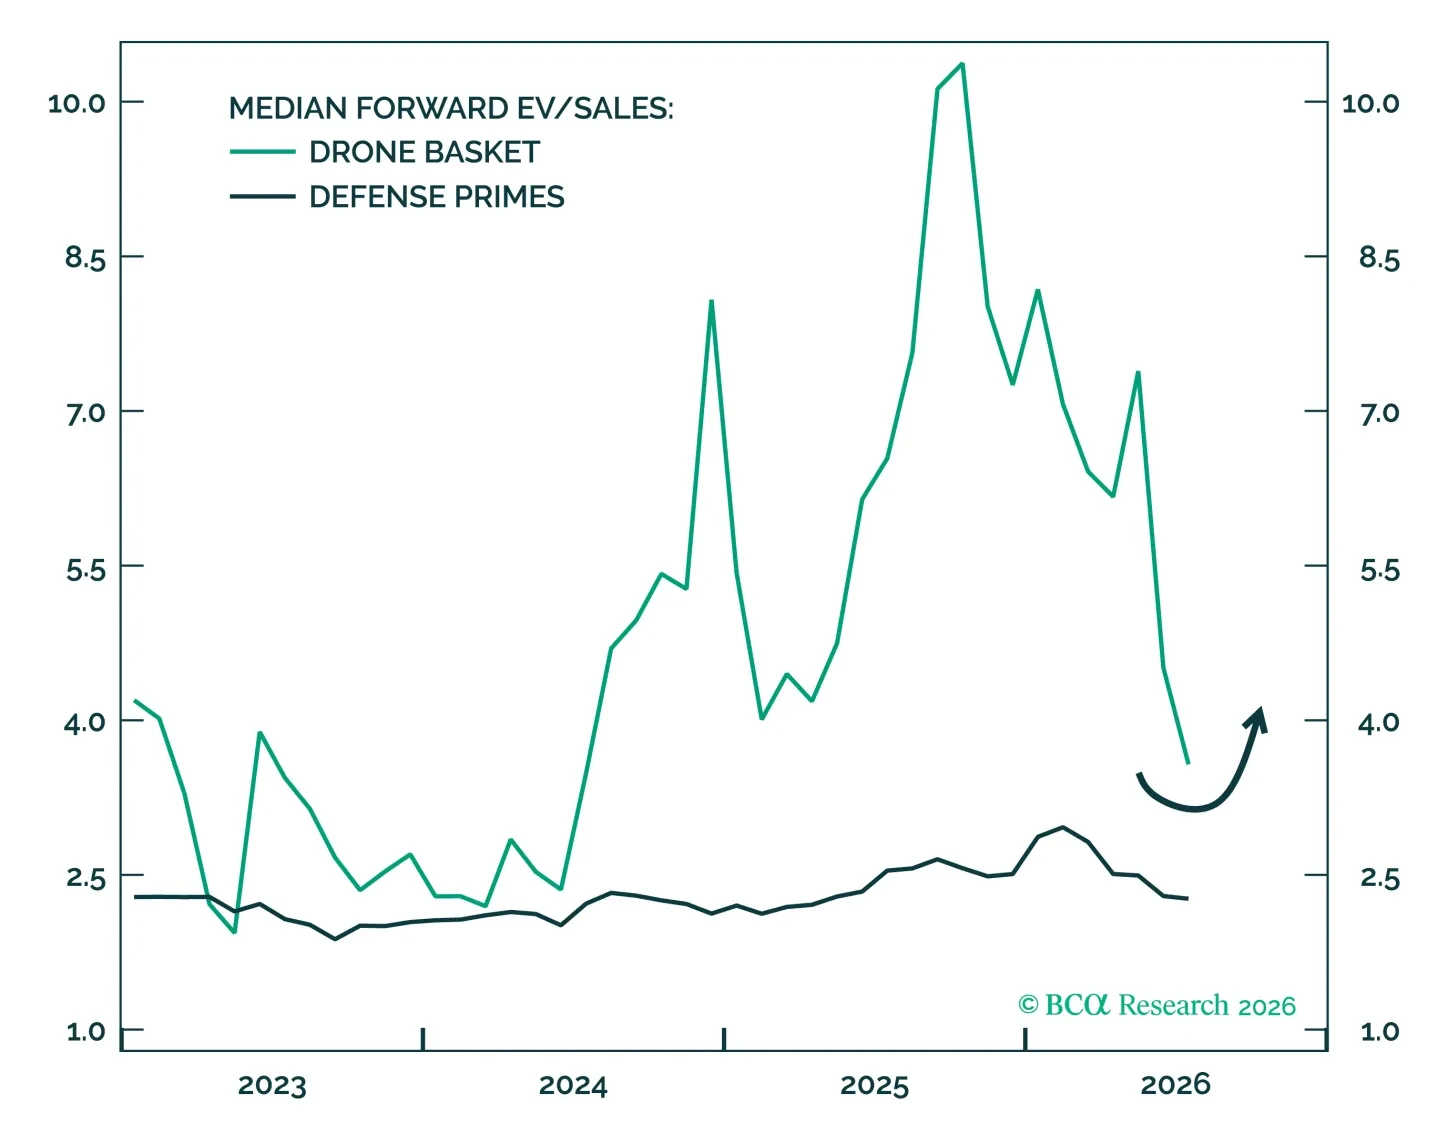
US aerospace and defense stocks still have a structural tailwind from geopolitics, but face rising cyclical challenges from macro and market fundamentals, as well as eventual Iran and Ukraine ceasefires and political change in the United States.
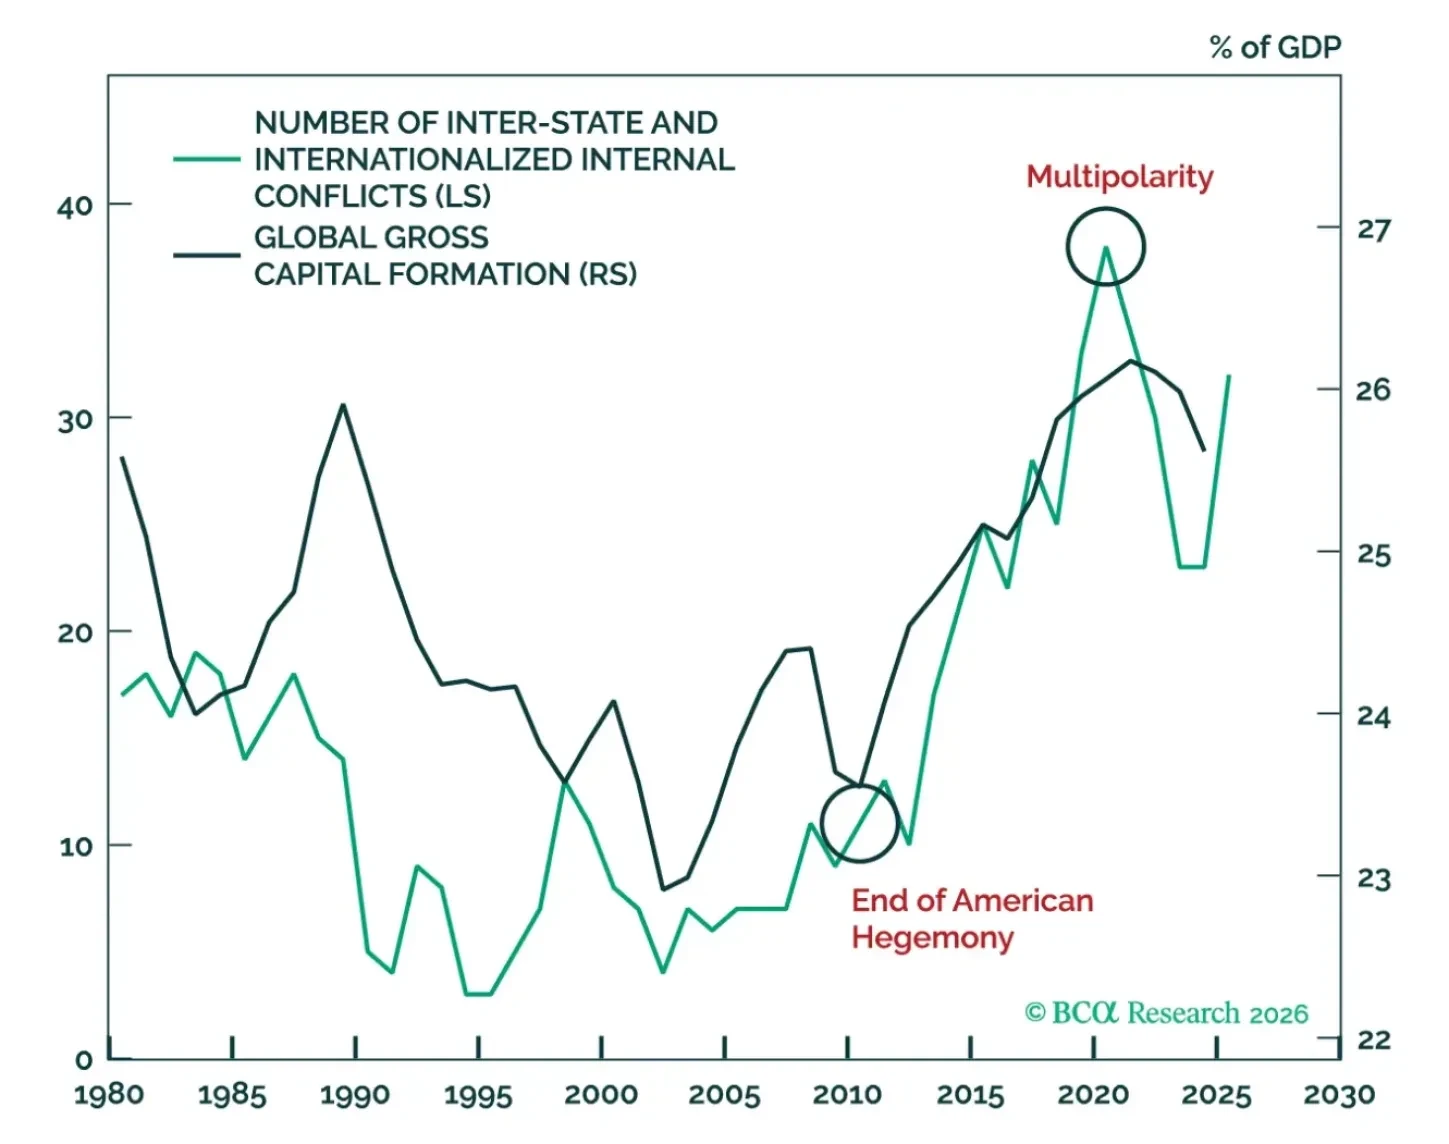
Many clients have asked us for an analysis of the long-term implications of the Hormuz Crisis. In this report, we posit that the conflict has been catalyzed by the multipolar context and that it will merely ossify the trends already afoot. Nothing offers incentives for more global capex like the threat of losing a critical energy supply chain. Therein lies the paradox. While capex is mildly inflationary in the short term, it is wildly disinflationary in the long term. This may be a worthwhile insight given all the consternation about long-dated bonds at the moment.
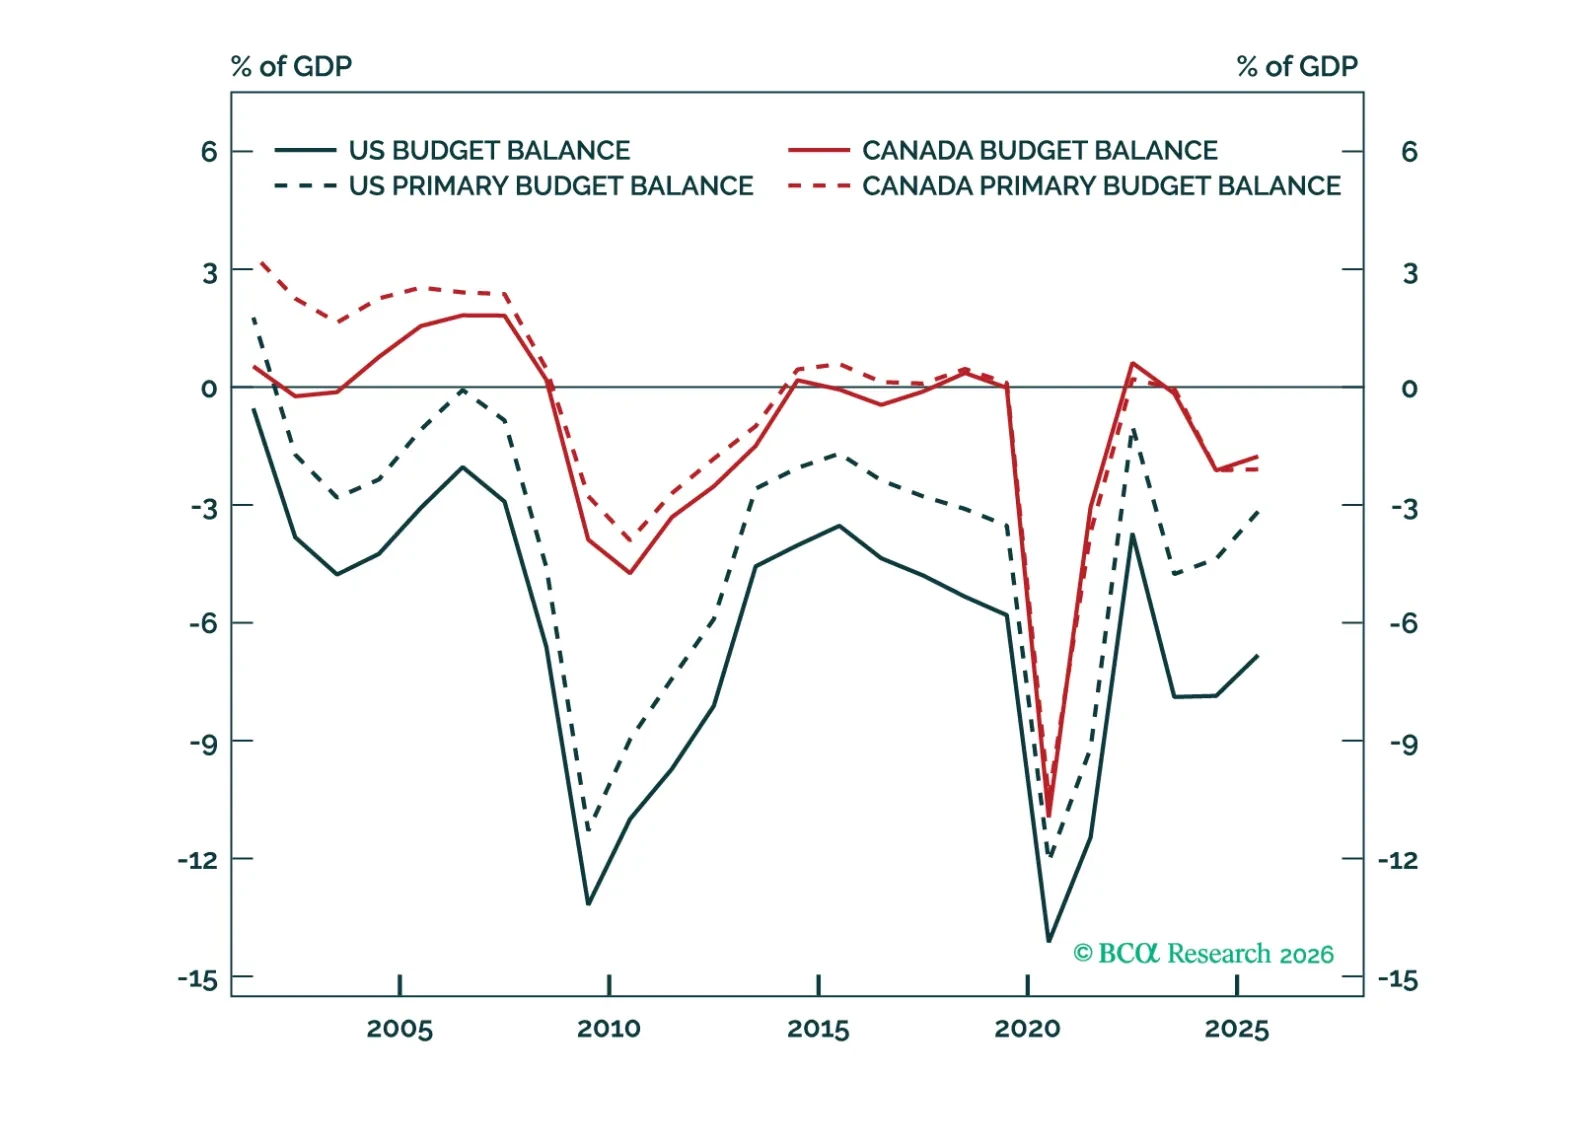
Canada may welcome a trade skirmish with the US. It has ample fiscal room with which to retaliate and its domestic political calculus – with bubbling risk of secession – means that fighting an external threat is a boon, not a bore.
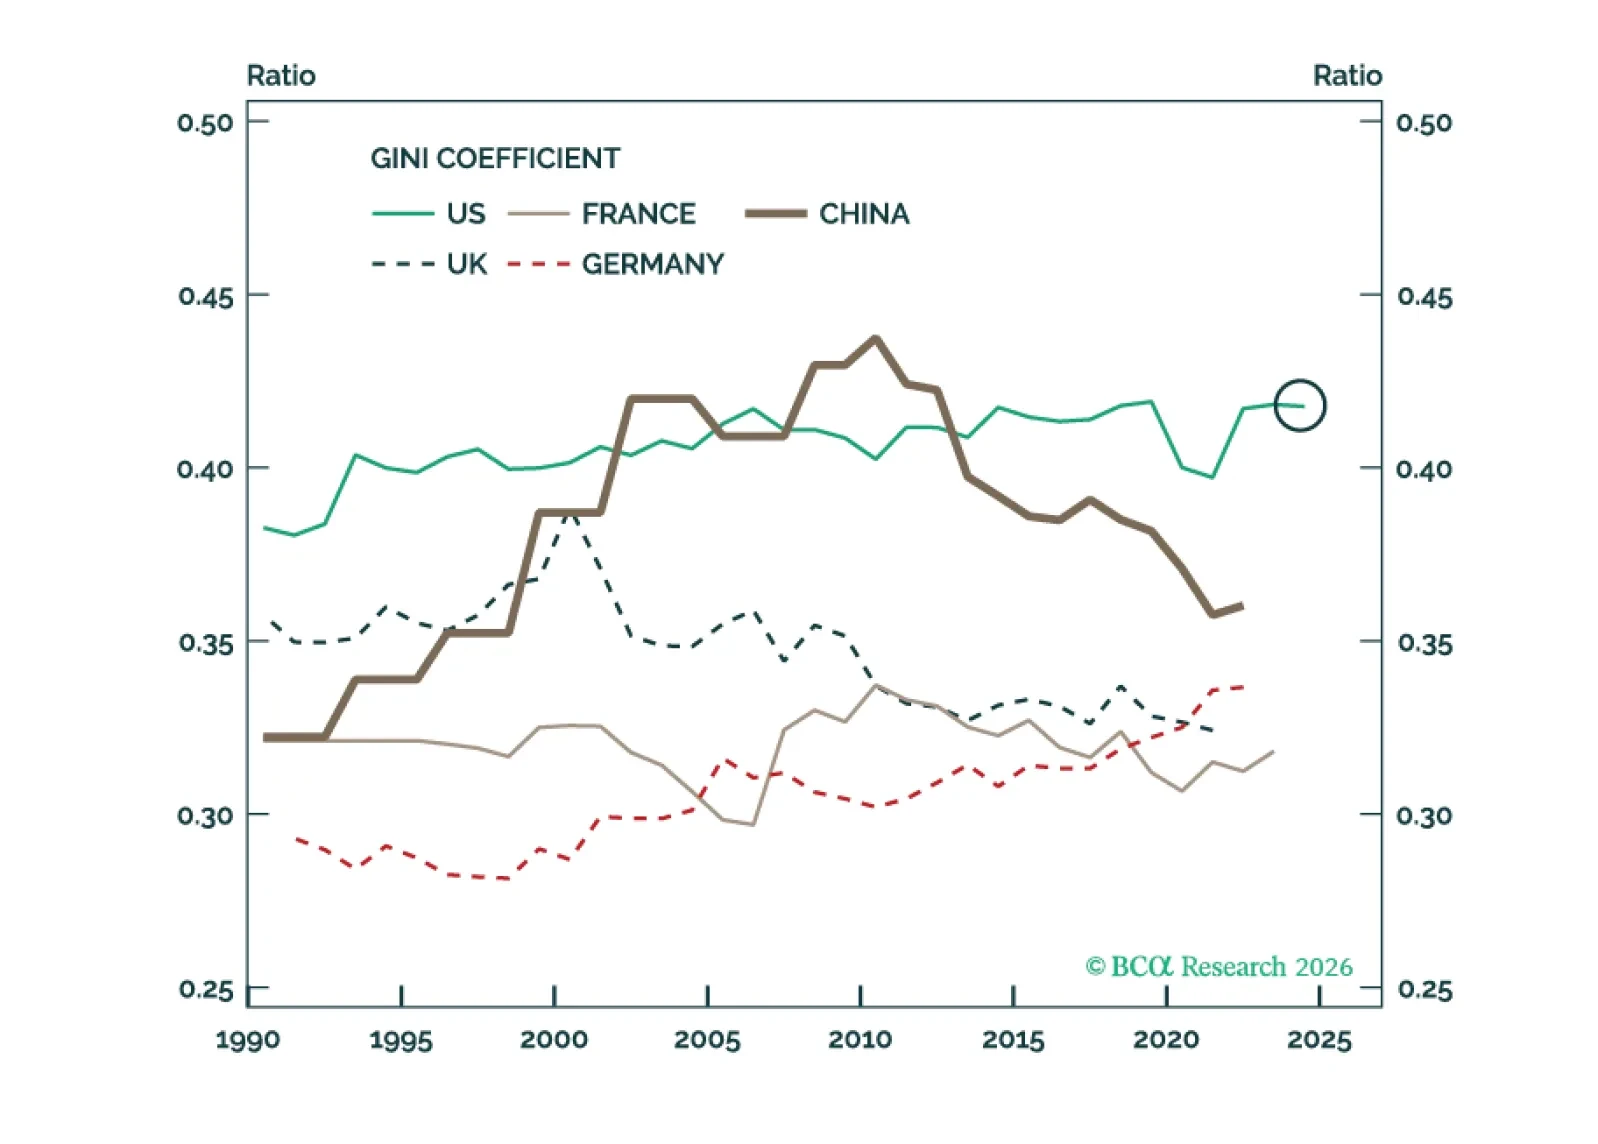
Left-wing populism will likely prevail within the Democratic Party and inspire large tax hikes in 2029. But the US does not face a socialist takeover.
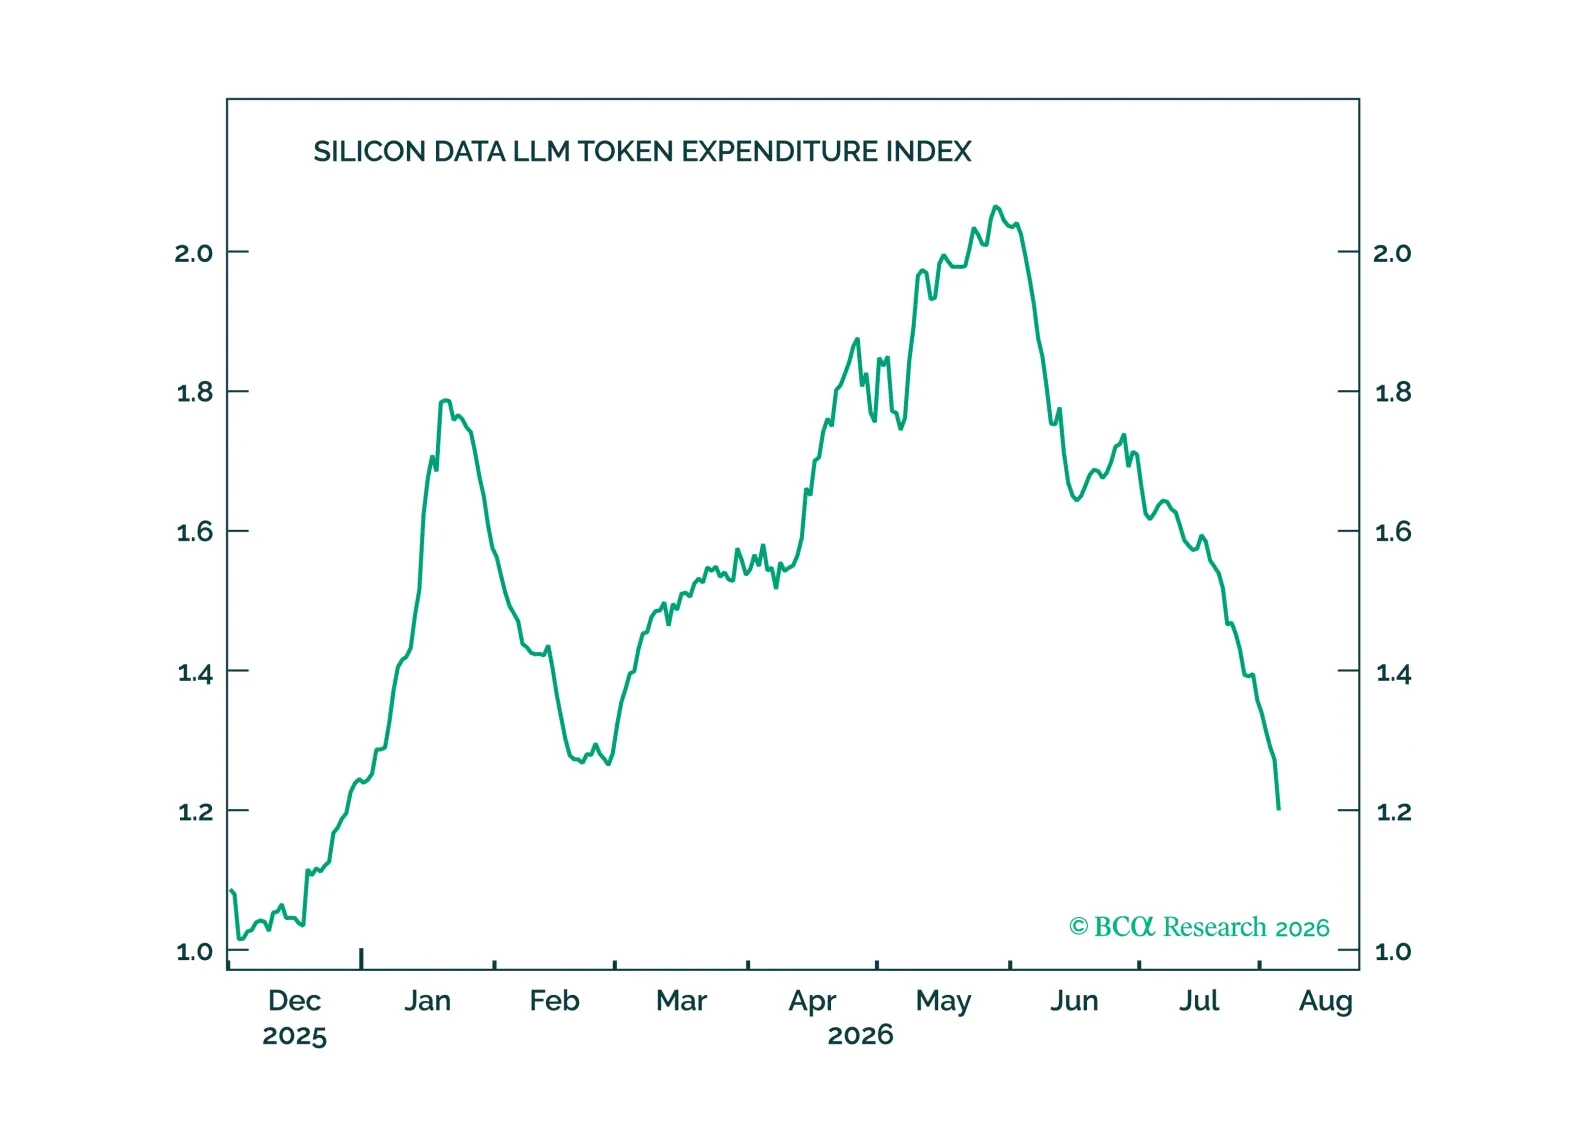
We remain tactically bullish due to the combination of geopolitical risks in the Middle East easing and the ramping up of the AI boom. In this month’s chartpack, we articulate the reasoning behind both sanguine views.
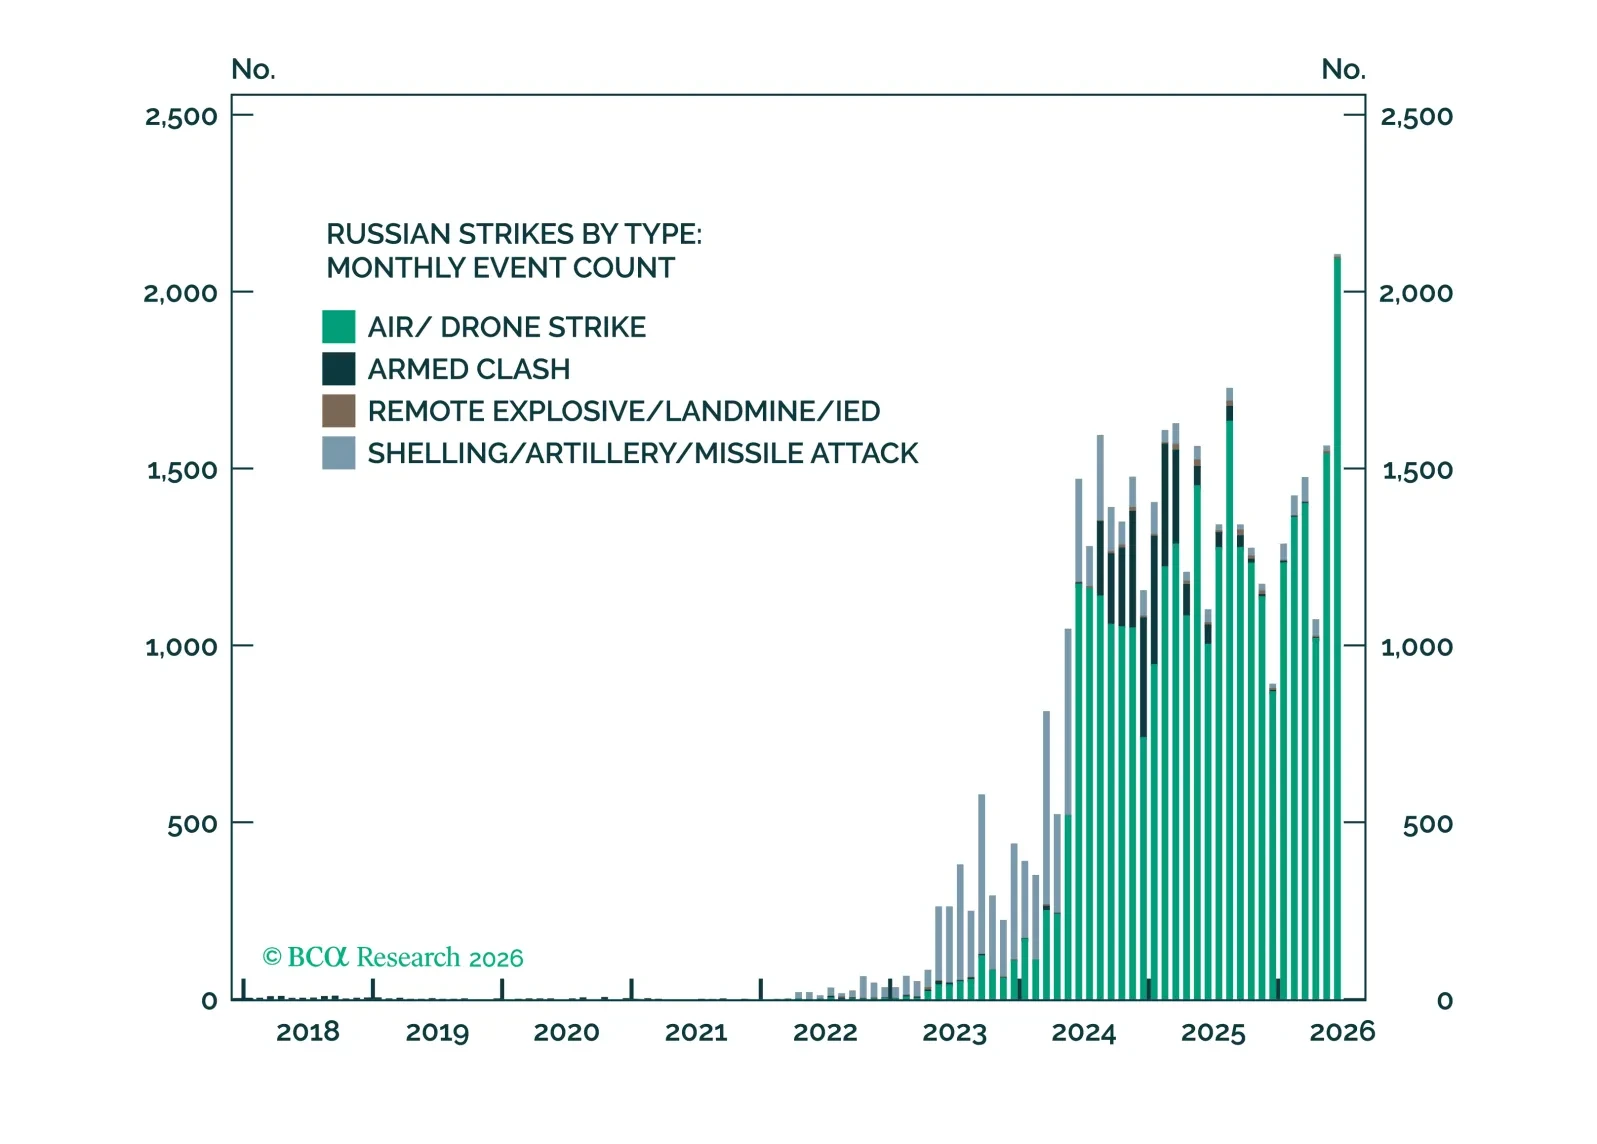
The fragile balance in the Ukraine war has broken – the conflict can escalate and take investors who are focused on Iran by surprise.