Equities
Macro, fundamental, and quantitative analysis translated into actionable equity views across sectors, factors, themes, and baskets.
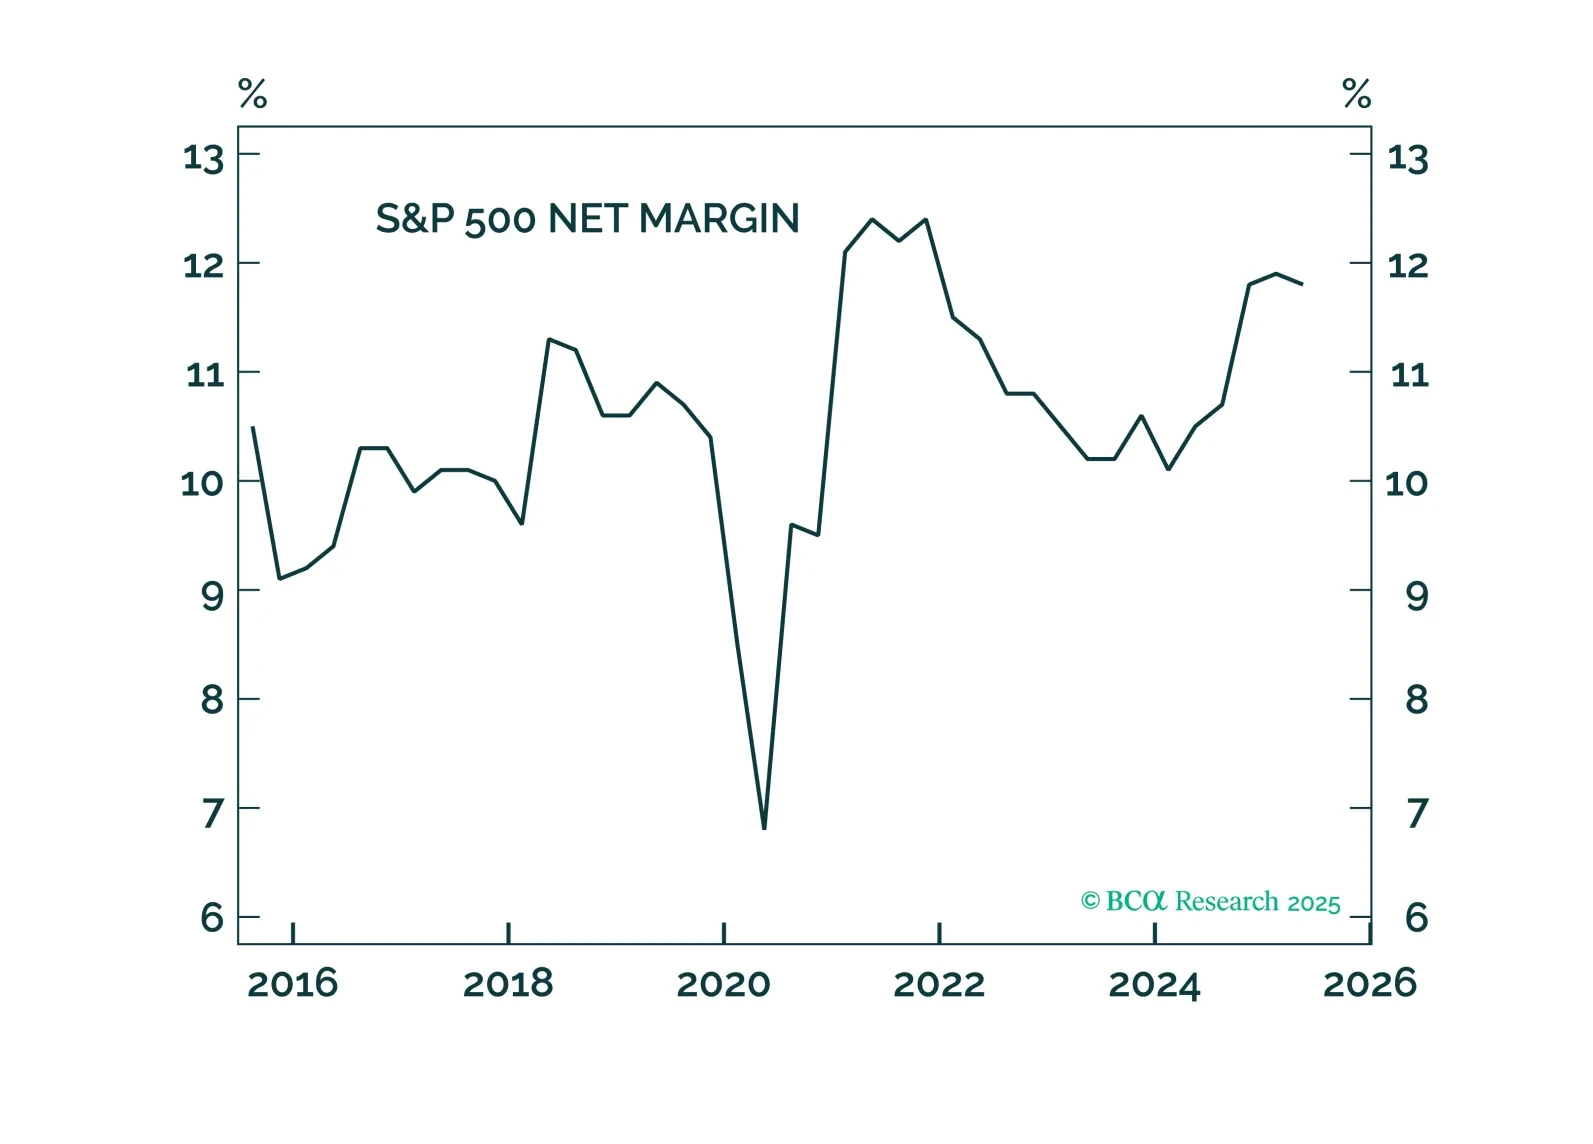
The Q2 reporting season underscores the resilience of corporate earnings, supporting our bullish outlook for equities, an outlook further bolstered by expectations of fiscal and monetary easing. However, for now, we are booking profits, closing overweights in Technology and Growth, and initiating a new overweight in Real Estate.
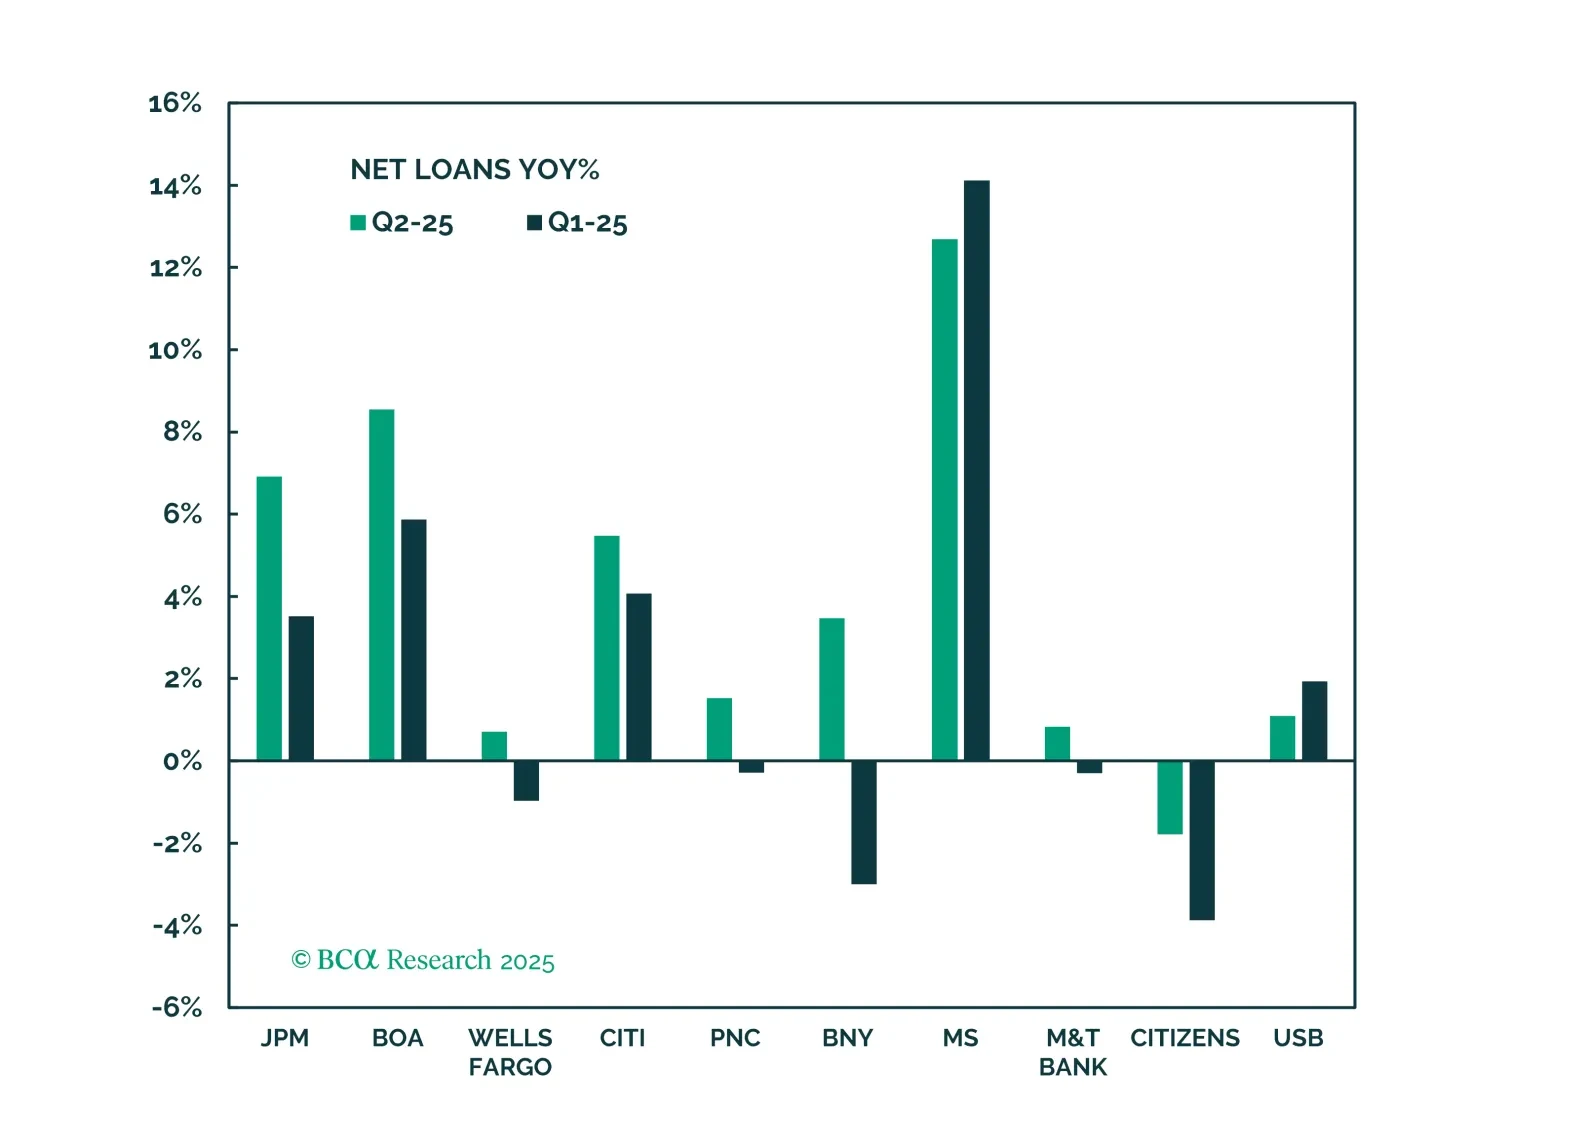
Banks have had a strong run and may continue to outperform, supported by a rebound in capital market activity, improving momentum in the core banking business, and the potential for rerating driven by deregulation. While risks remain, we remain cautiously optimistic.
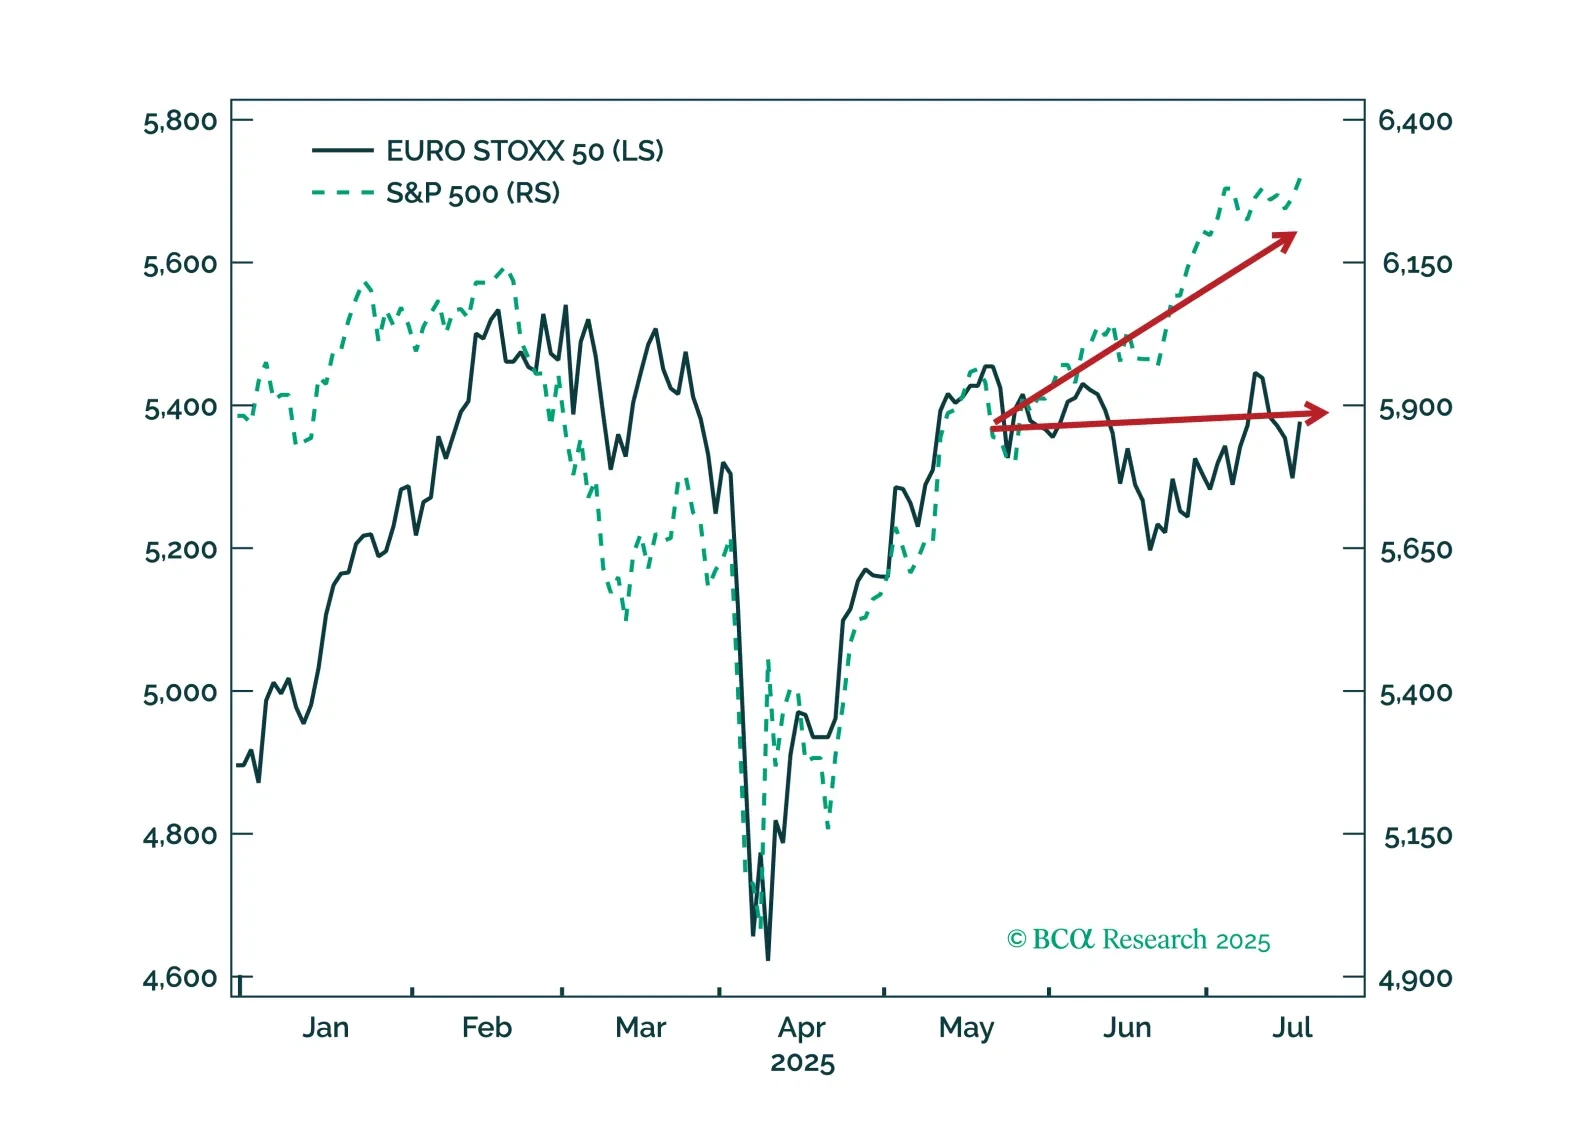
This insight gives life to four high-conviction views on European small caps, aero¬space & defense, banks, and telecoms by harnessing the power of BCA’s Equity Analyzer (EA).
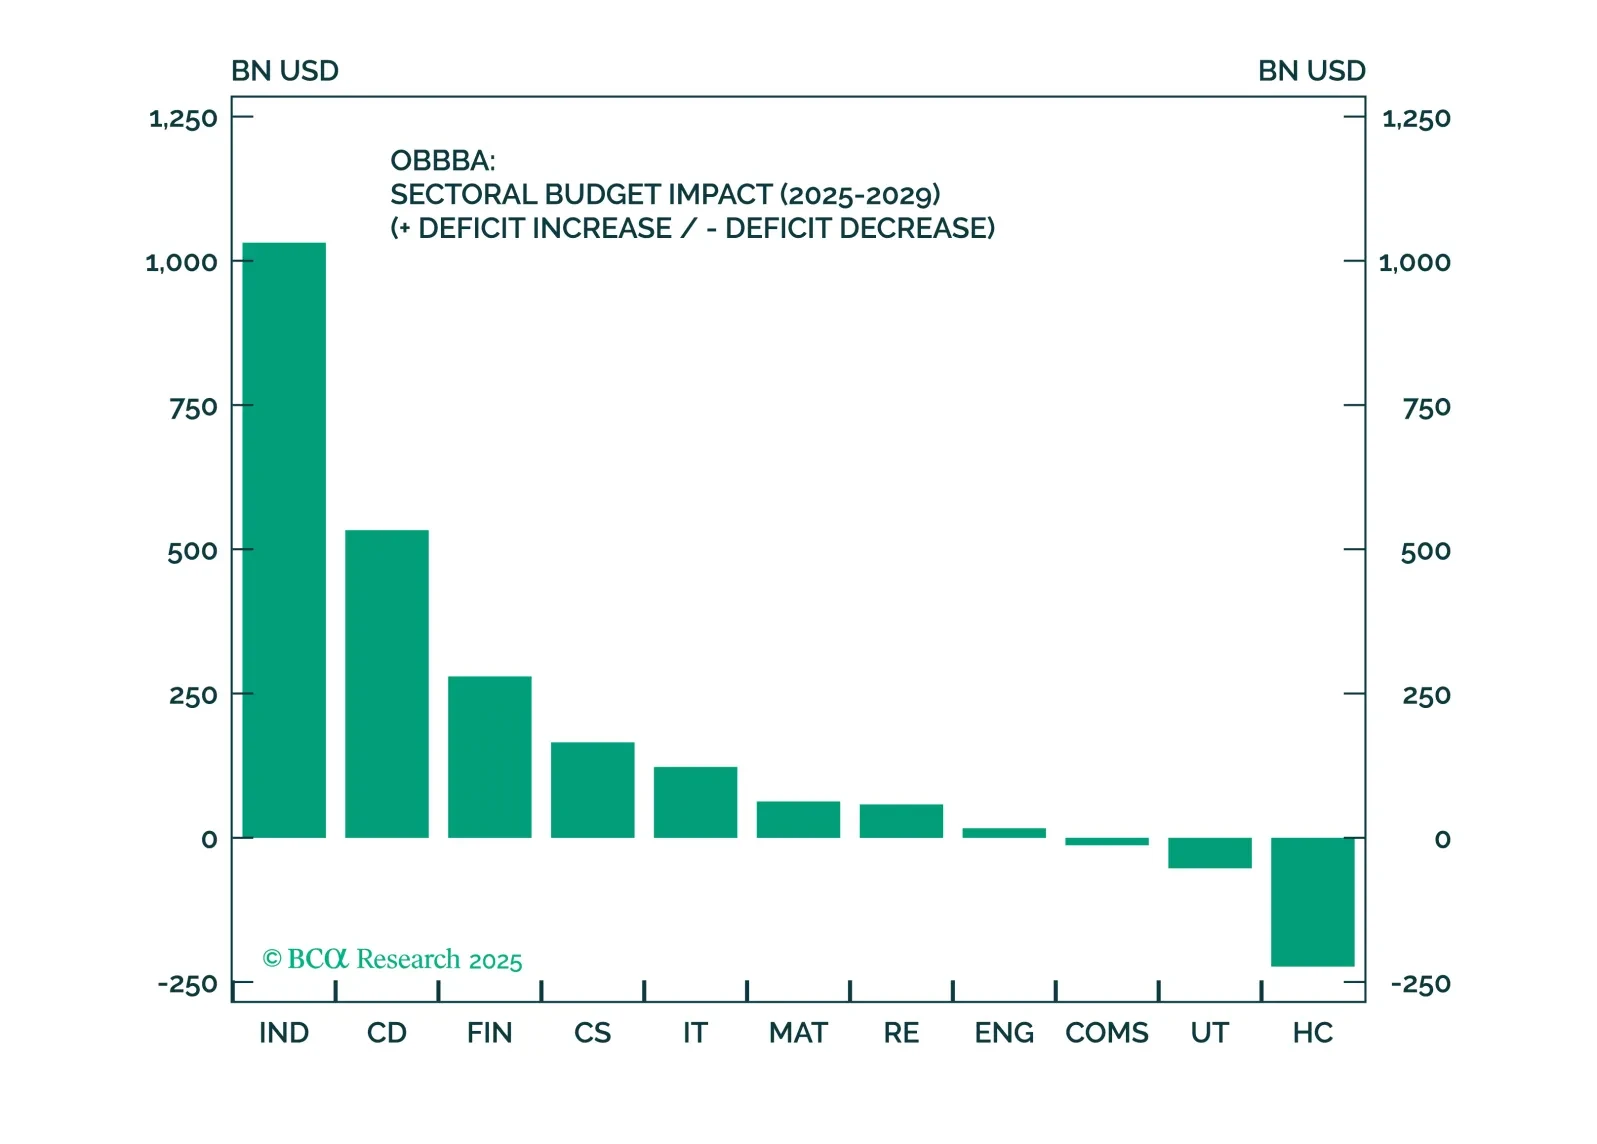
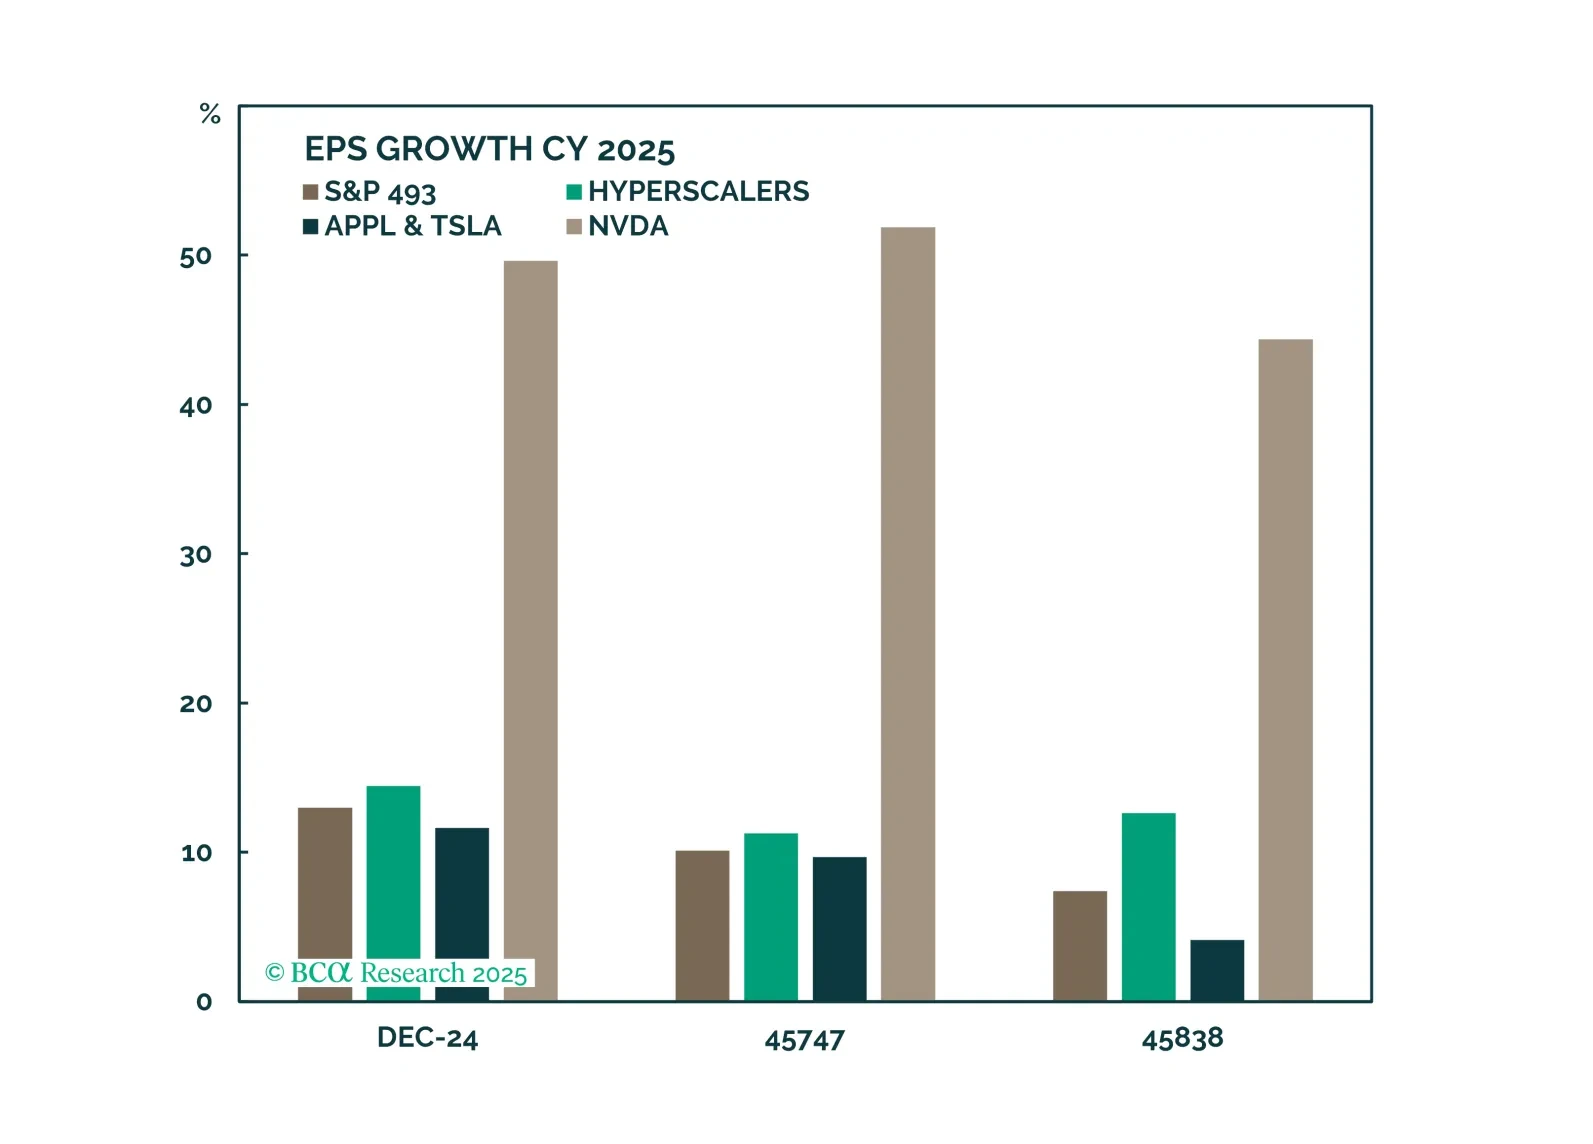
Earnings growth should continue to support equity performance this year. However, after blockbuster gains, some profit-taking is likely. We recommend booking profits and increasing exposure to Defensives.
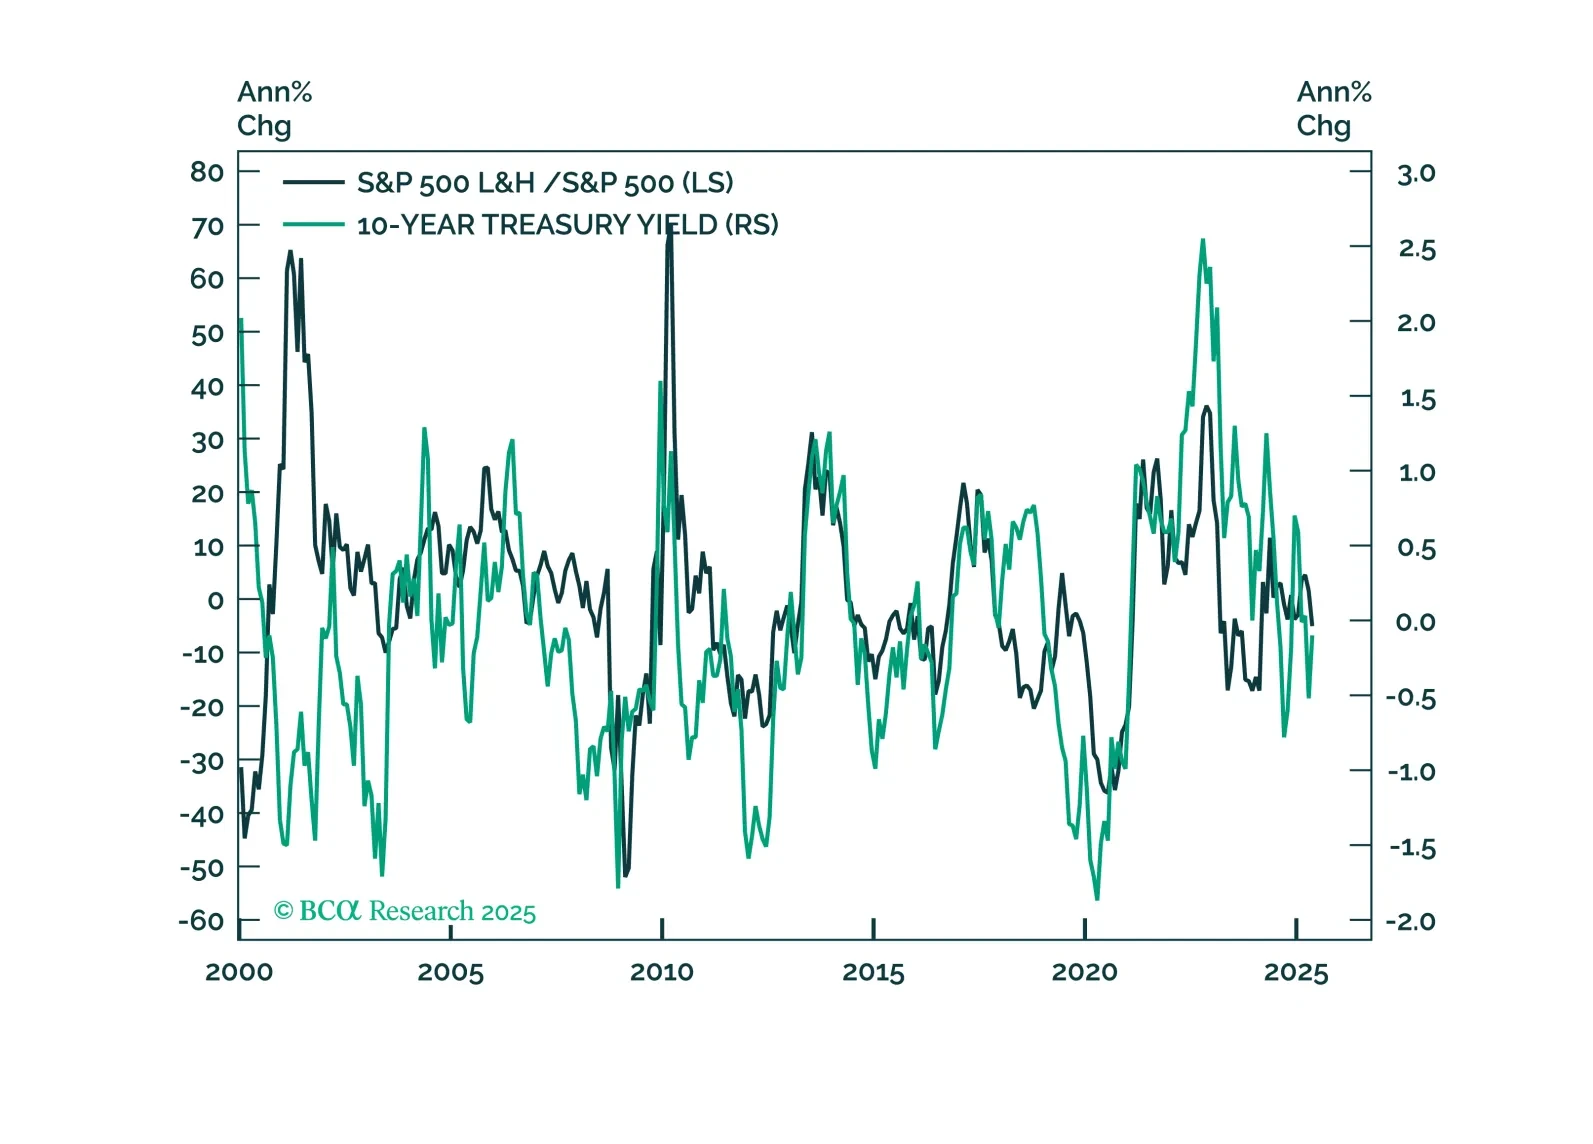
The Life and Health Insurance industry offers downside protection and portfolio diversification in the event of a market correction, surging inflation, or stubbornly high interest rates.
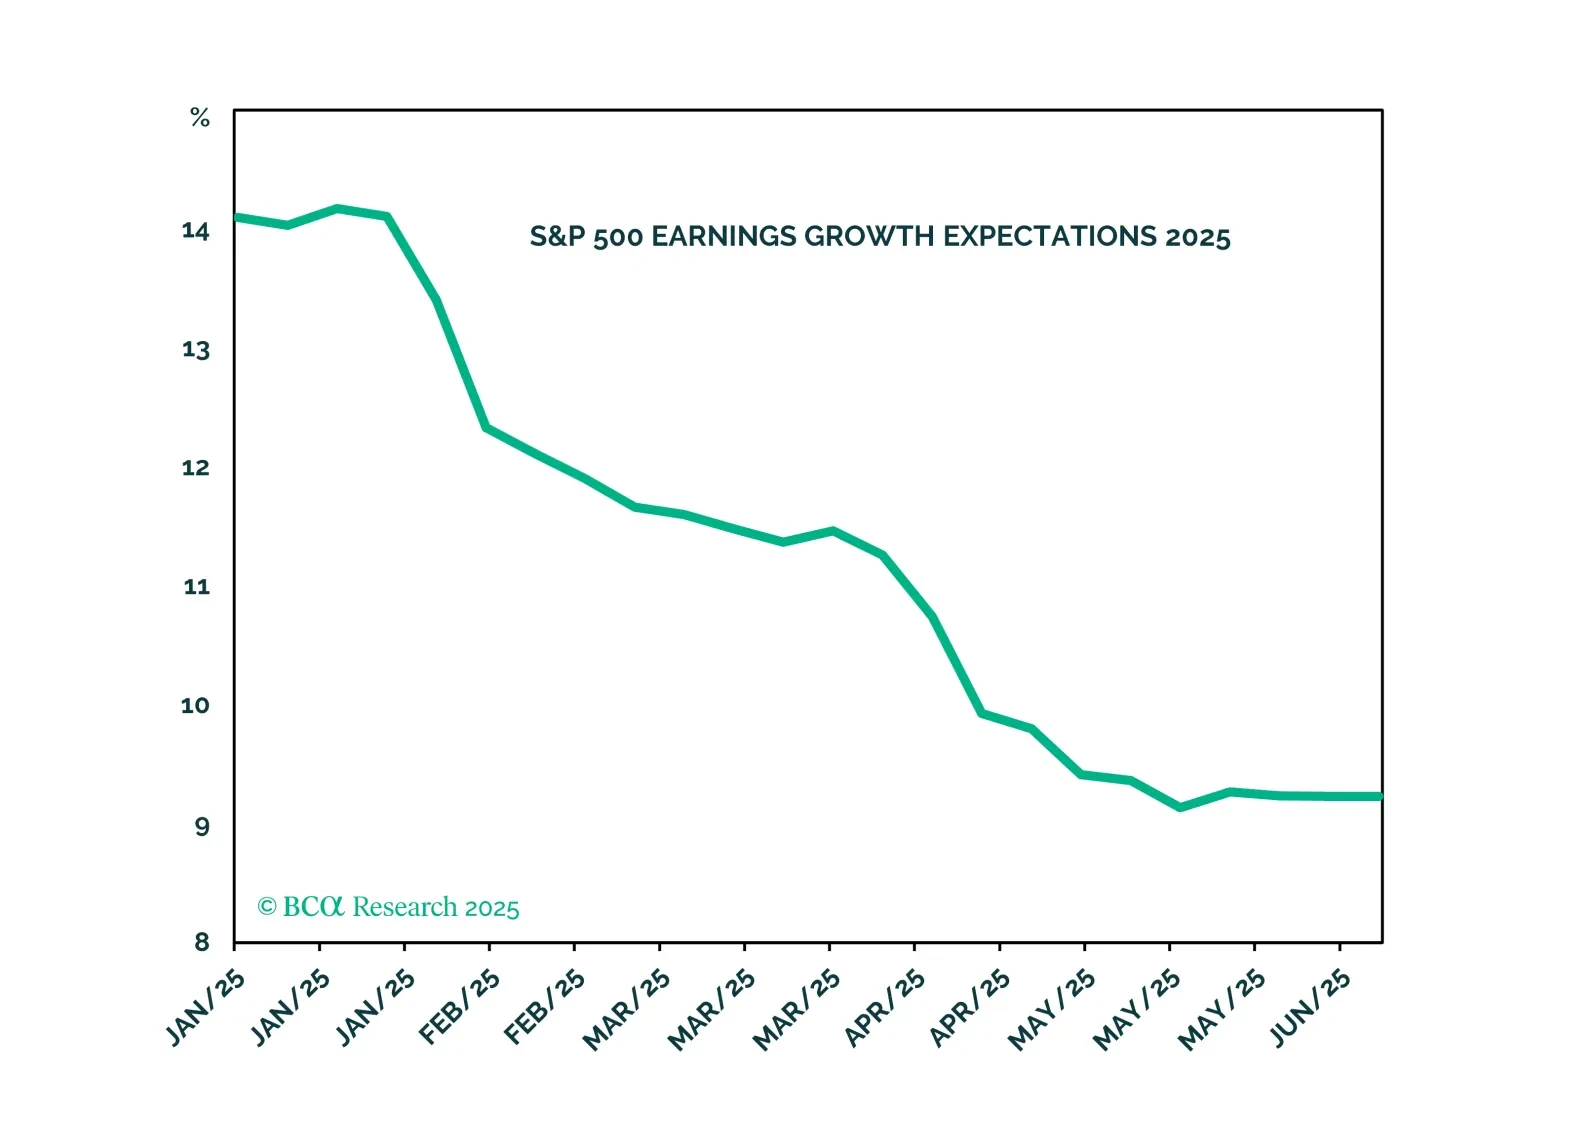
Imminent monetary and fiscal easing, along with resilient earnings growth, support a constructive outlook for equities. However, in the near term, significant tail risks persist. We recommend strengthening downside protection by lowering portfolio beta.
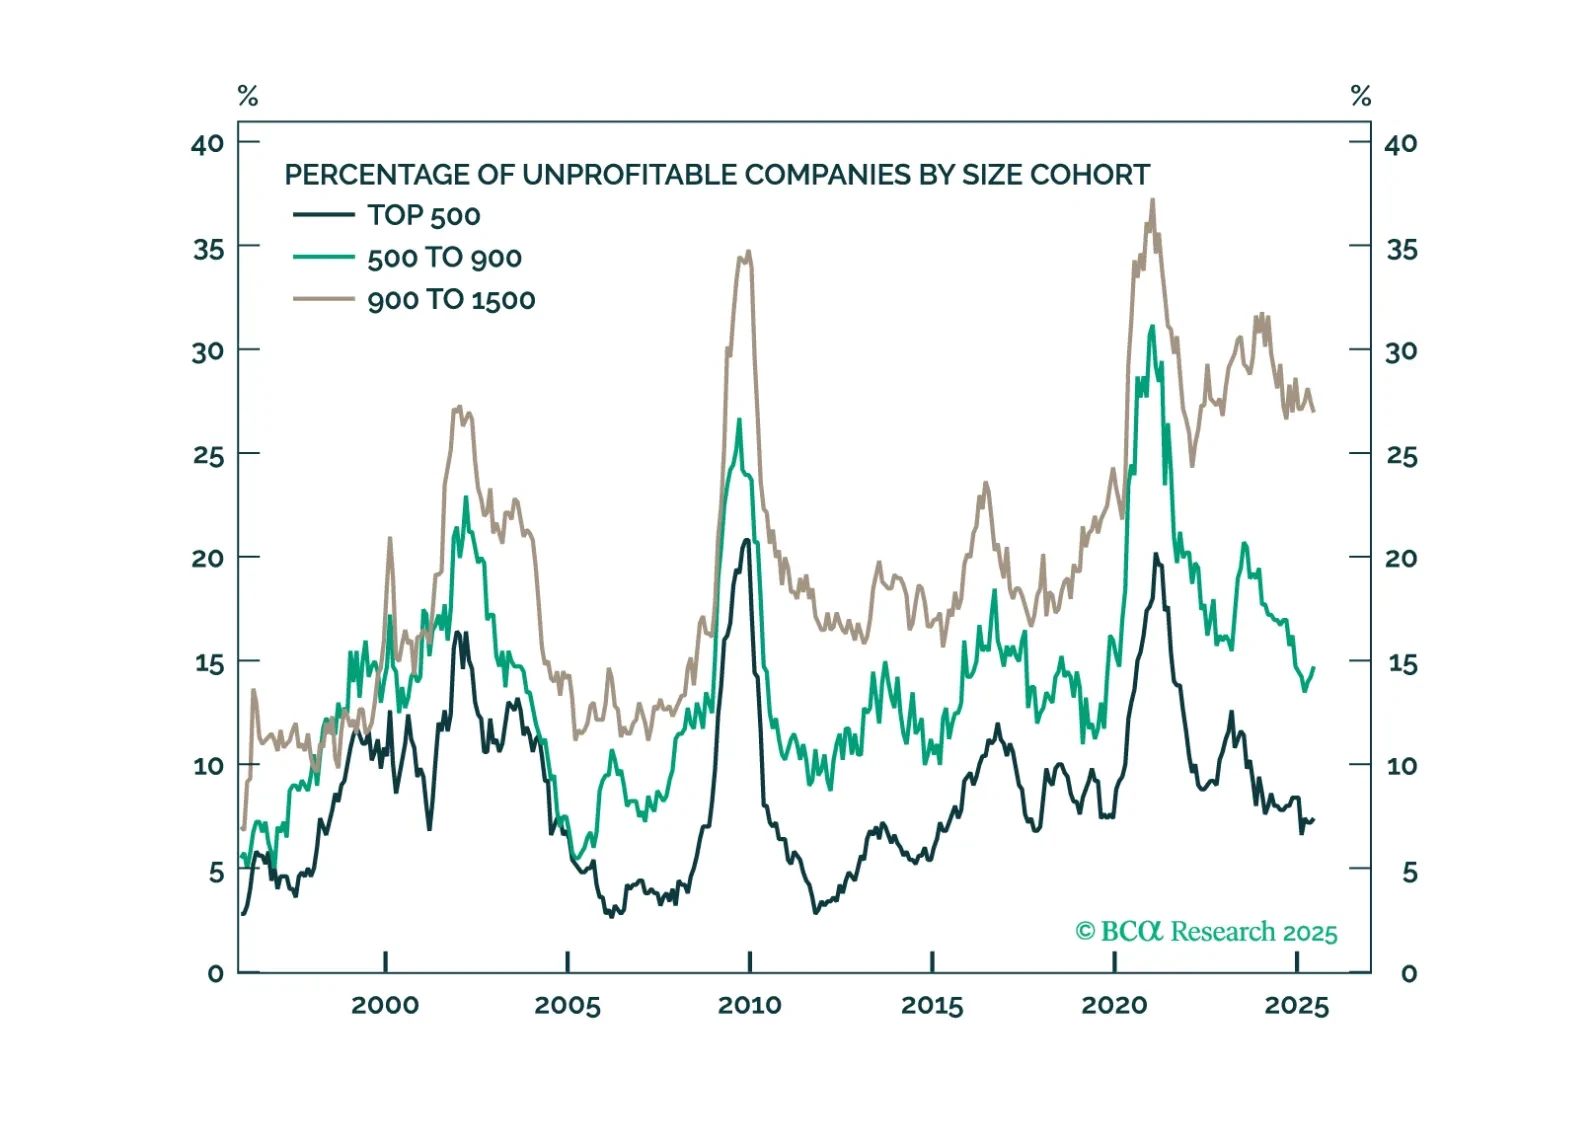
Recently, small-cap stocks have shown signs of outperformance. In this report, we examine whether the rebound is sustainable by analyzing long-term structural trends, the macroeconomic backdrop, the impact of tariffs, and other key factors.