 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
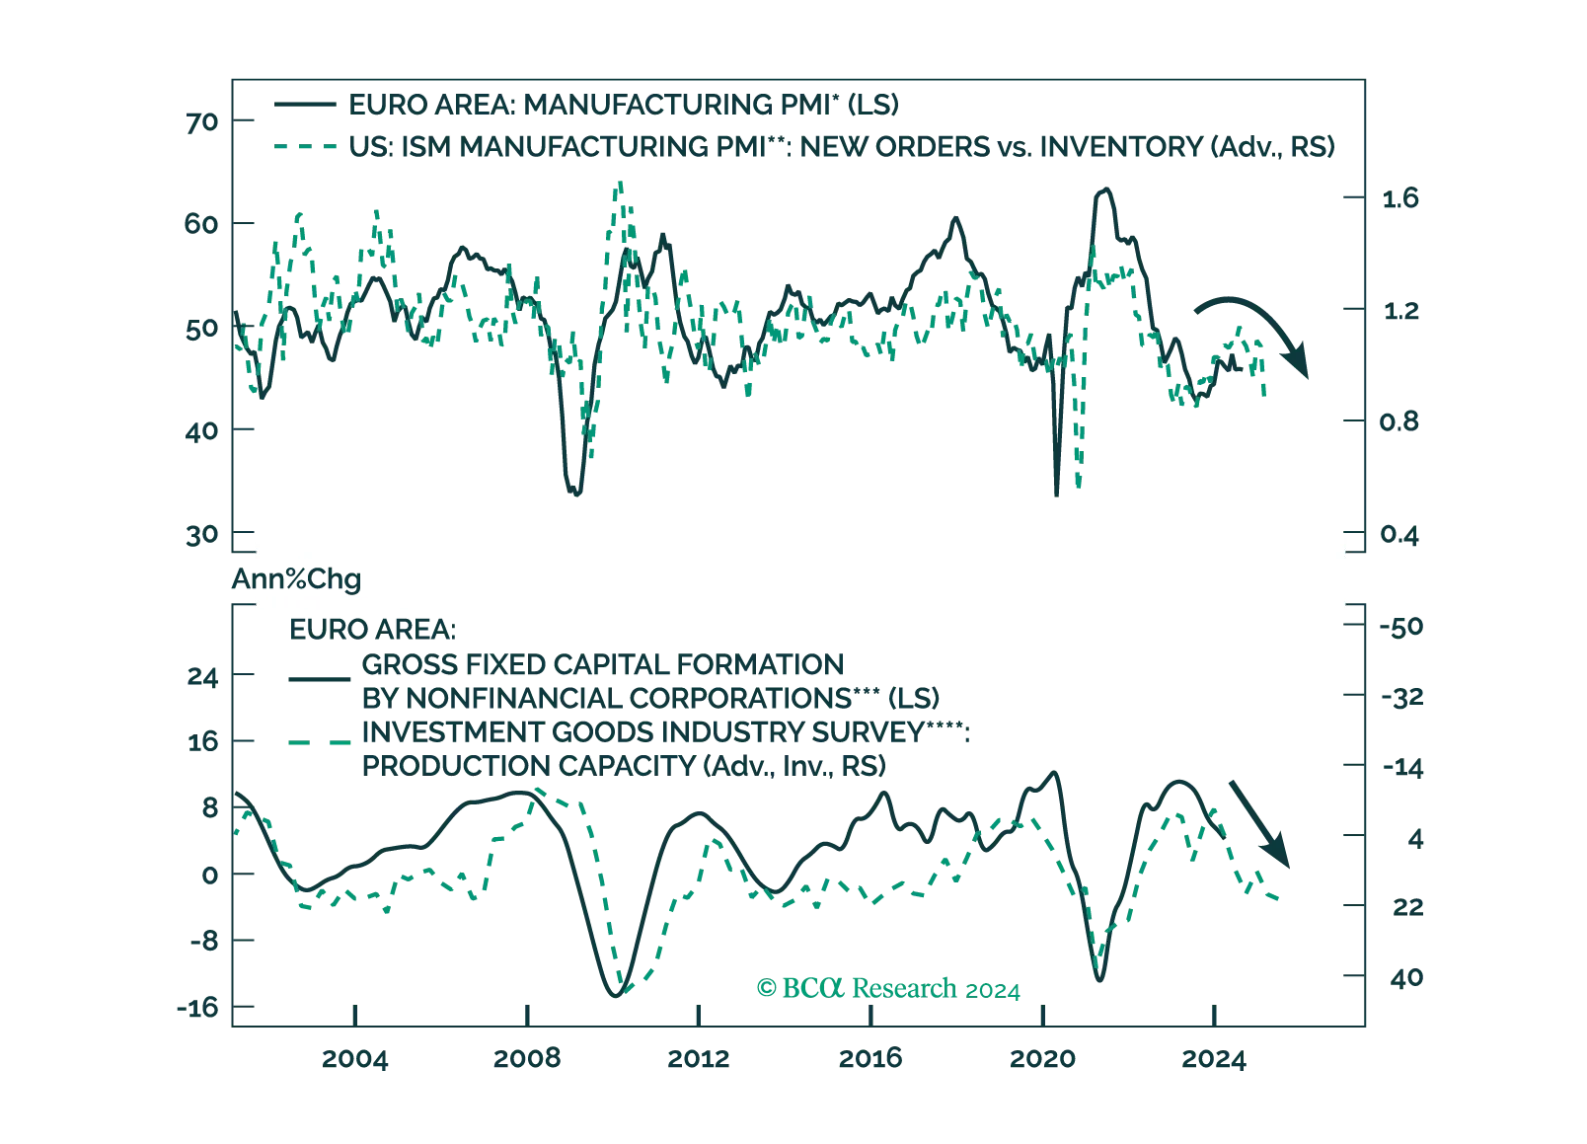
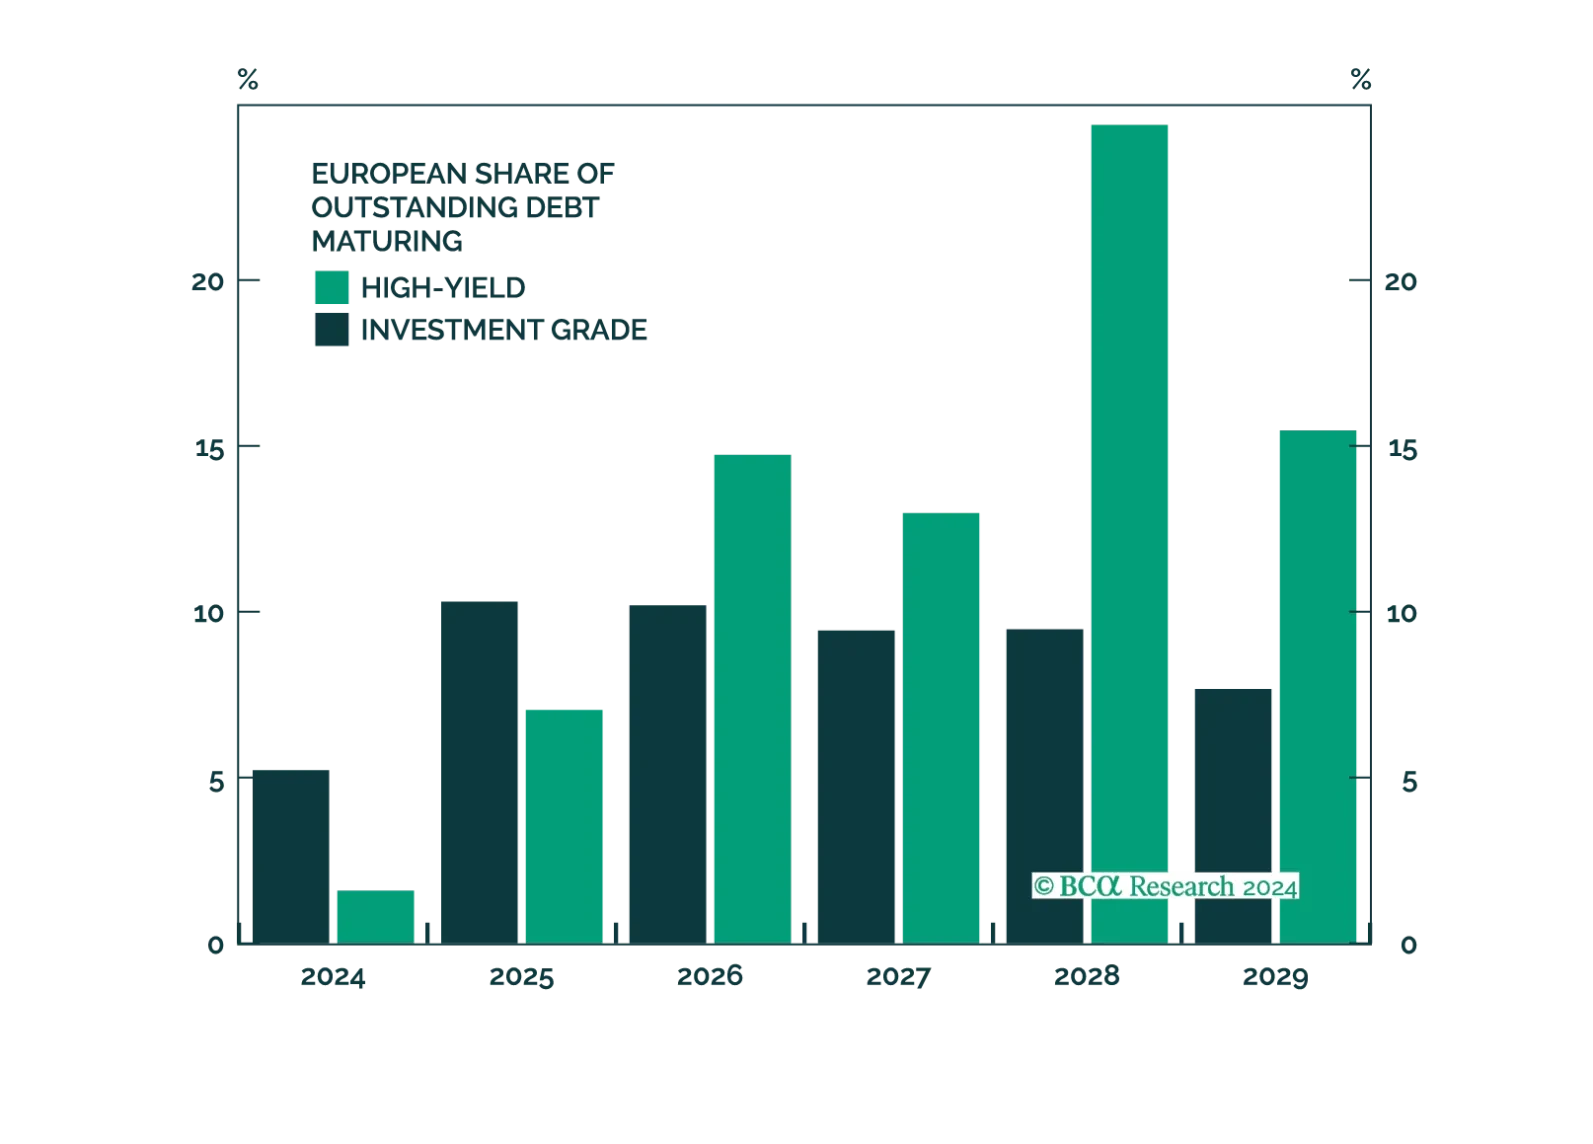
Crucial leading indicators of the global and European economies continue to deteriorate. How should investors position their European portfolios to benefit from these trends?
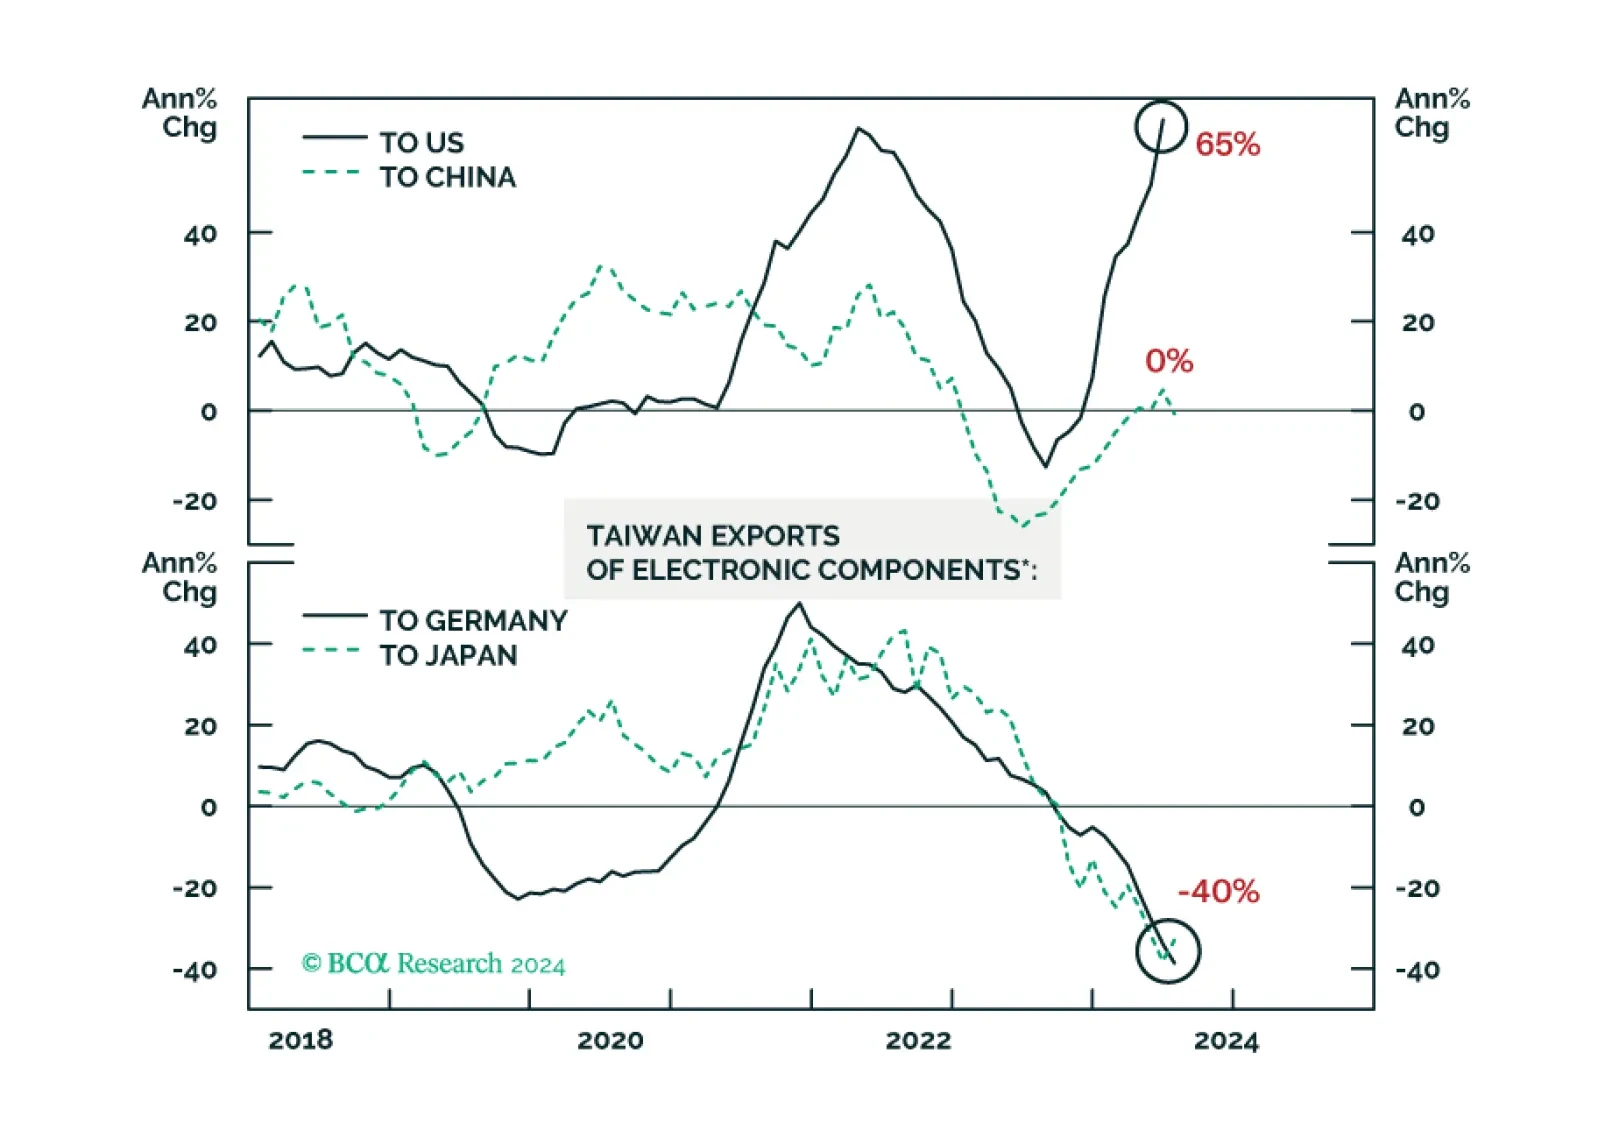
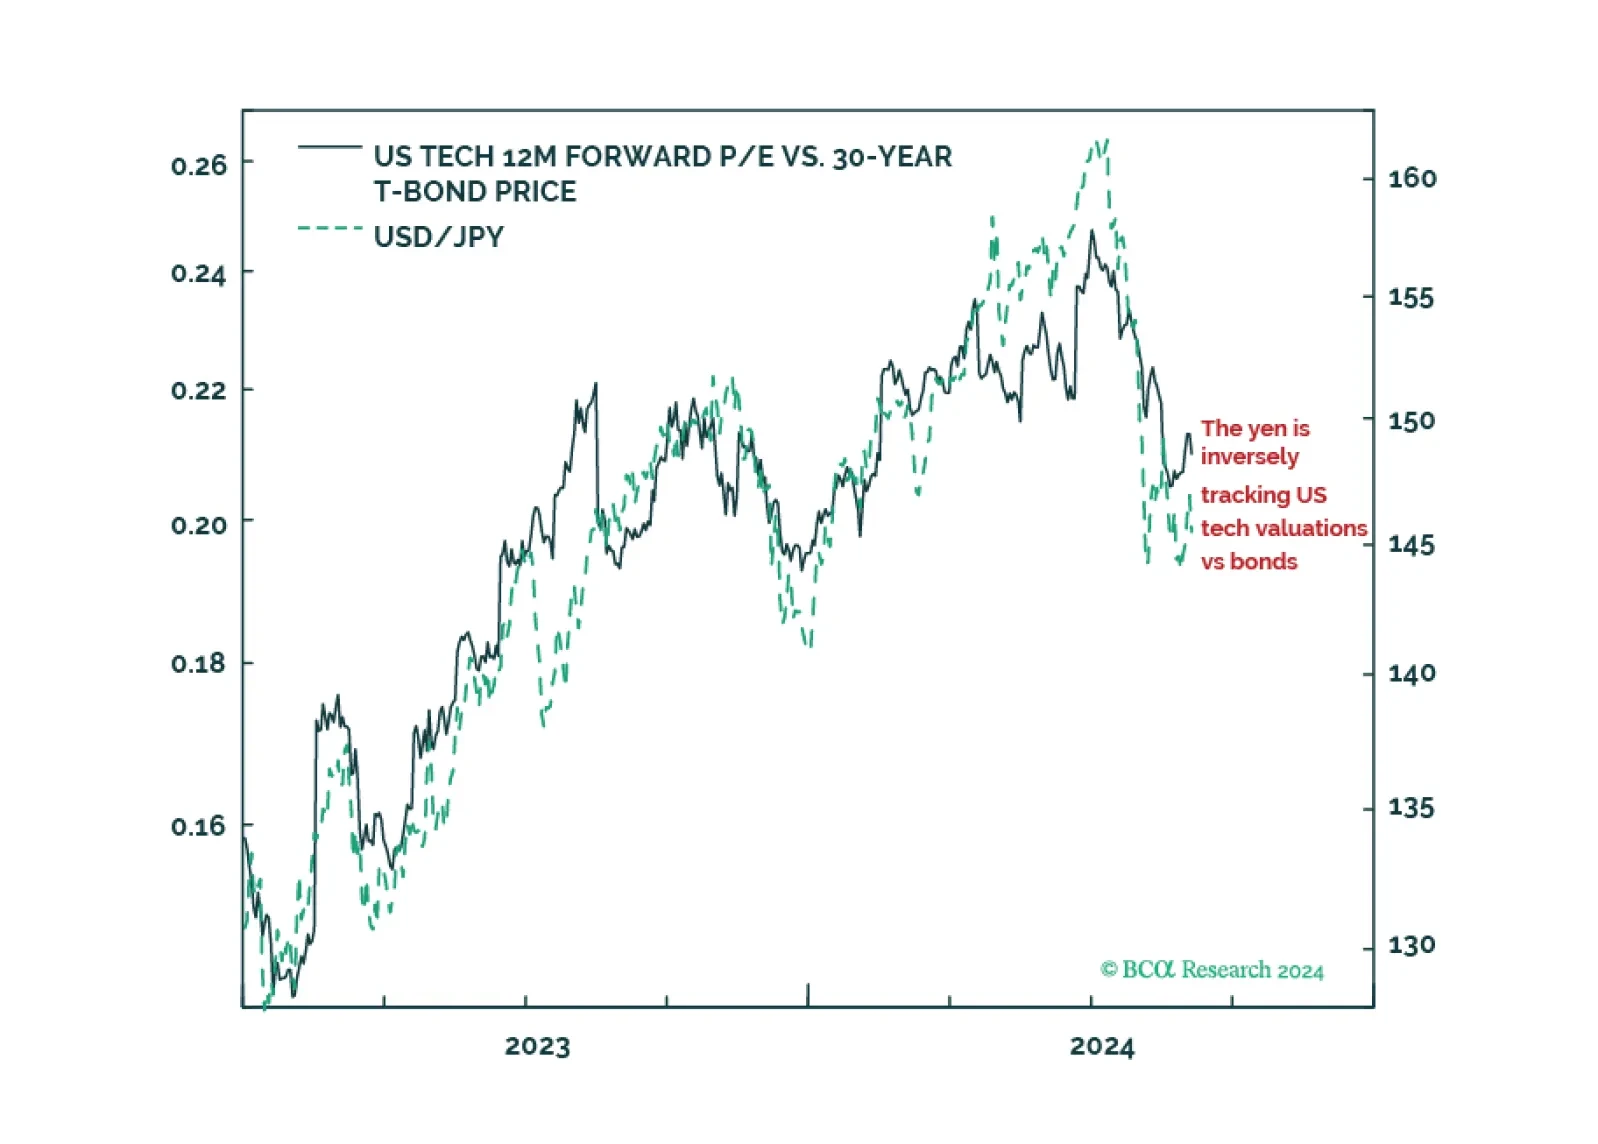
The 15 percent slump in the relative valuation of US tech stocks versus bonds is a bubble starting to burst. Yet the adjustment has been relatively benign so far because a large part has come from the bond price going up. Unfortunately, the adjustment has much further to run and could ultimately turn ugly. The easiest way to play the AI bubble bursting is to go structurally overweight the yen.
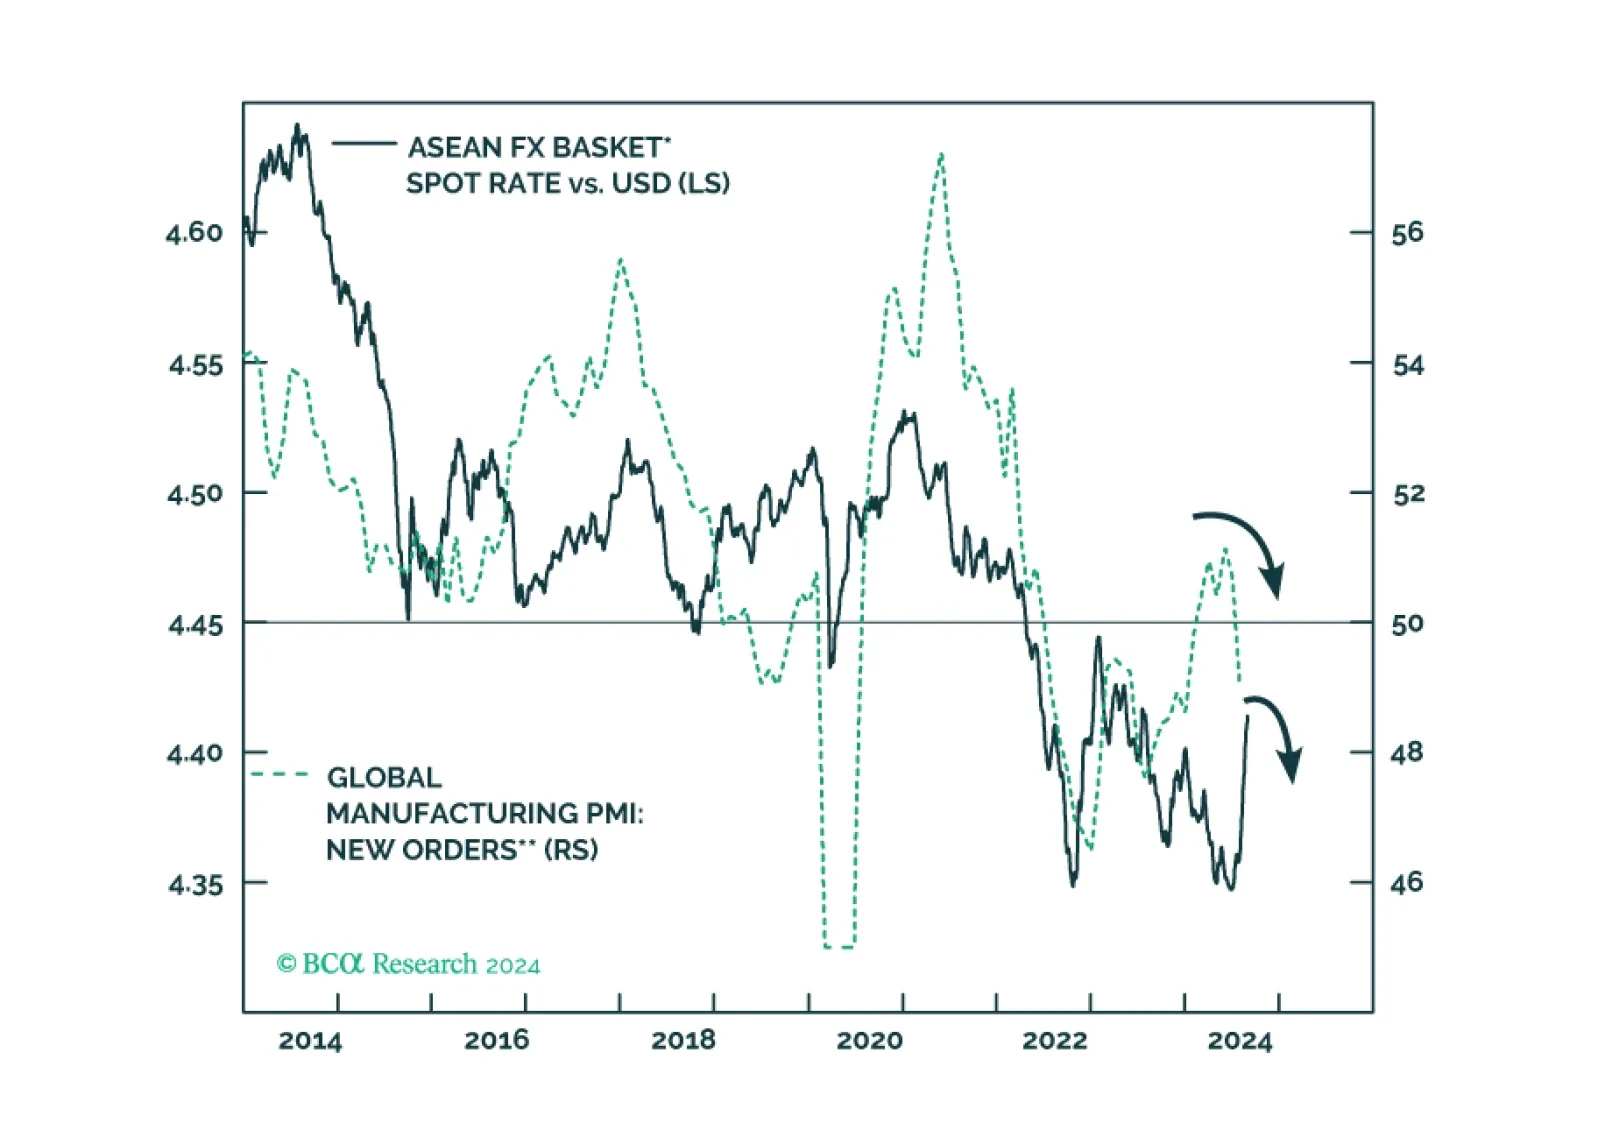
The ongoing rally in ASEAN currencies will fizzle sooner rather than later as they are not supported by fundamentals. The ringgit and the baht, however, will fare better than the peso and the rupiah during the coming global risk-off period. This report explains why.
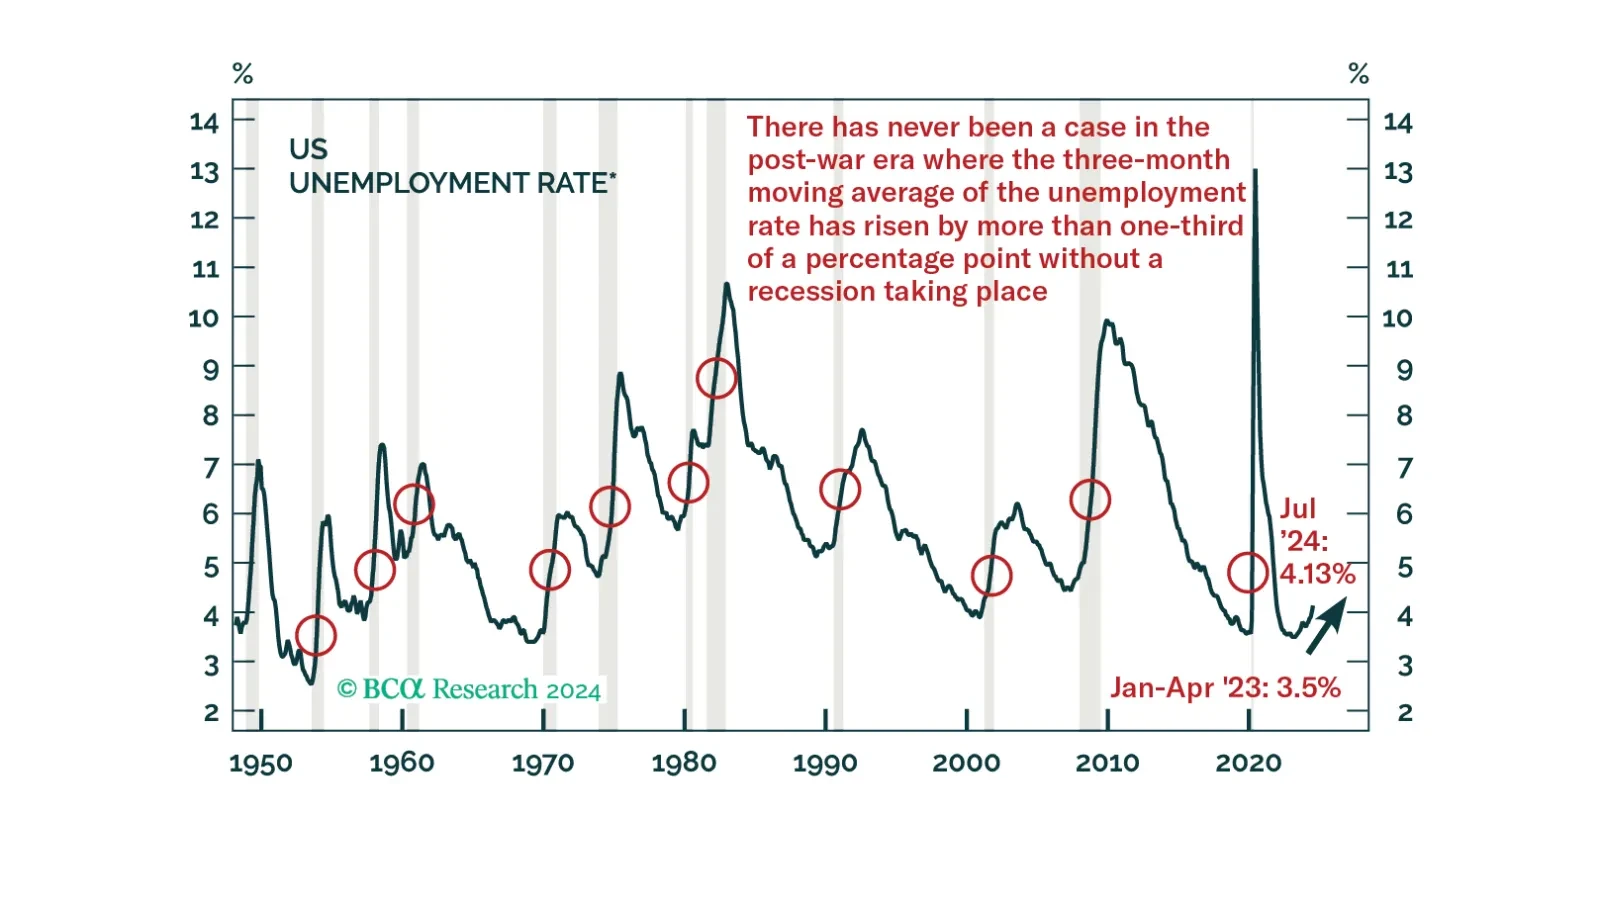
Our annual end-of-summer chartbook report traces the labor market deterioration that led us to downgrade equities at the beginning of August. It also highlights the soft-landing expectations that the credit and equity markets are discounting. We like the risk-reward profile of our newly defensive stance.
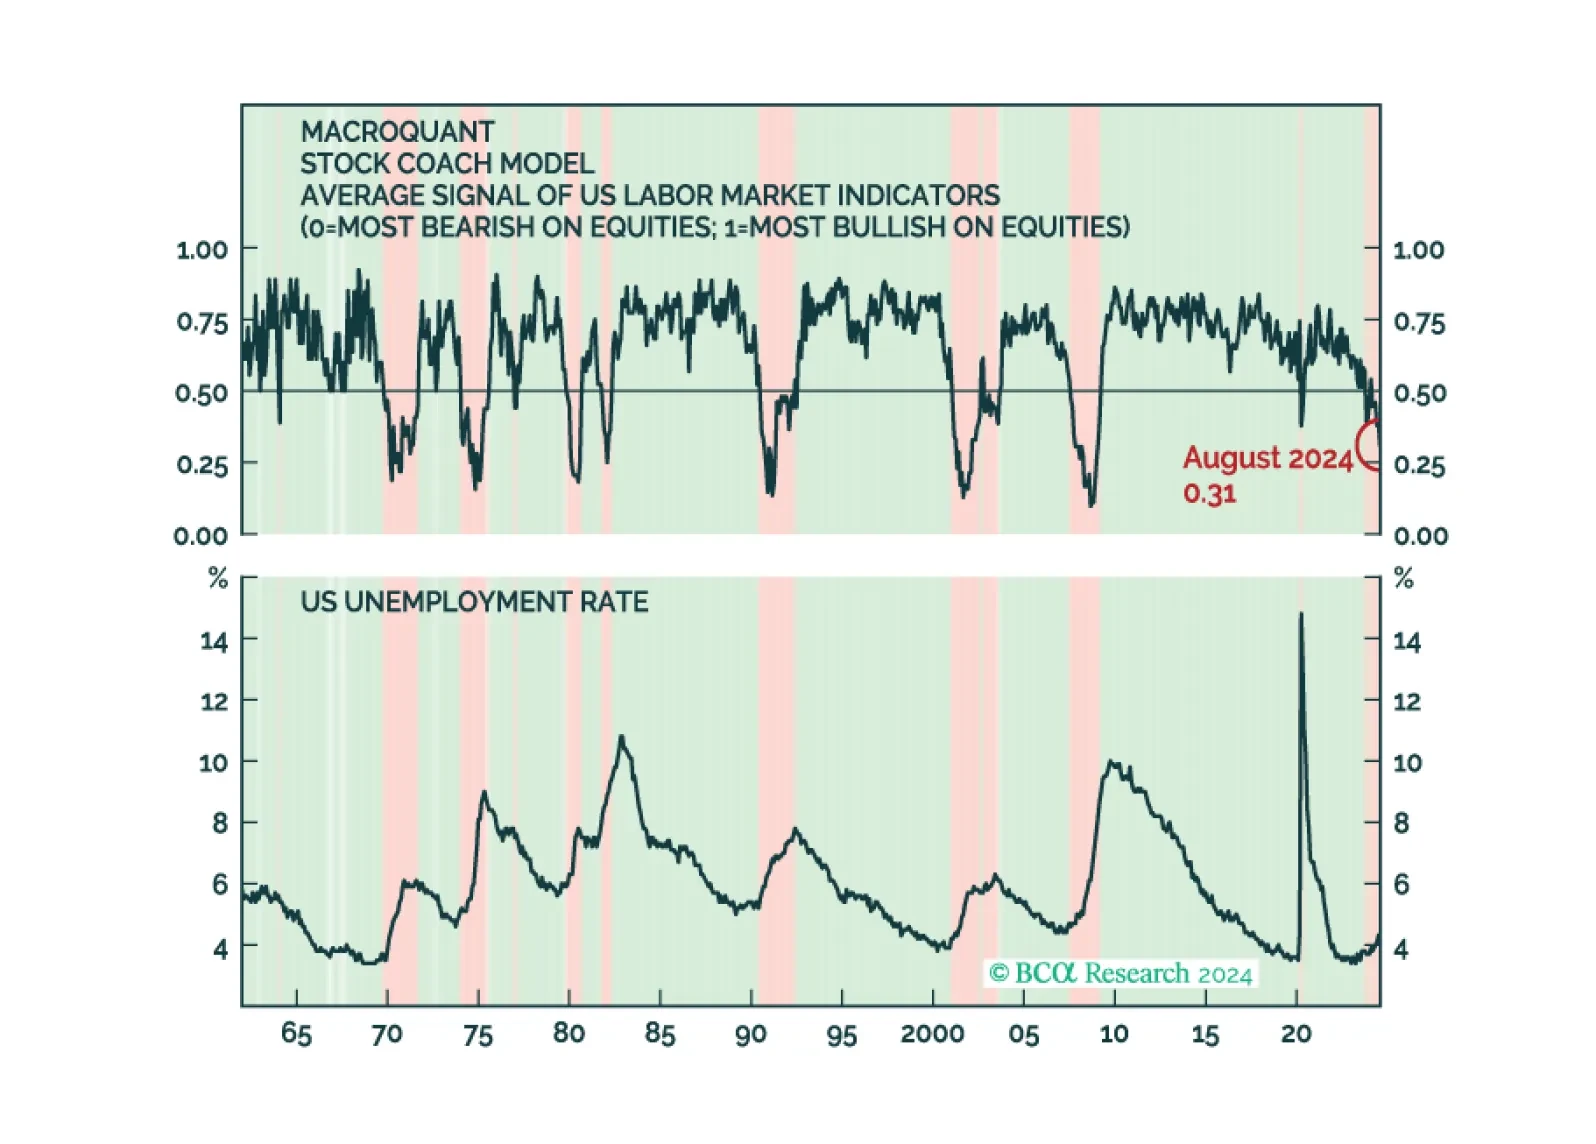
MacroQuant continues to recommend underweighting equities and overweighting bonds. This is consistent with the Global Investment Strategy Team's decision to downgrade global equities to underweight in late June.

Chinese property developers will require at least RMB 500 billion in additional government funding to prevent further declines in housing completions for the rest of 2024. However, without addressing the underlying challenges, any new rescue measures similar to those announced in May are unlikely to effectively support the real estate market.
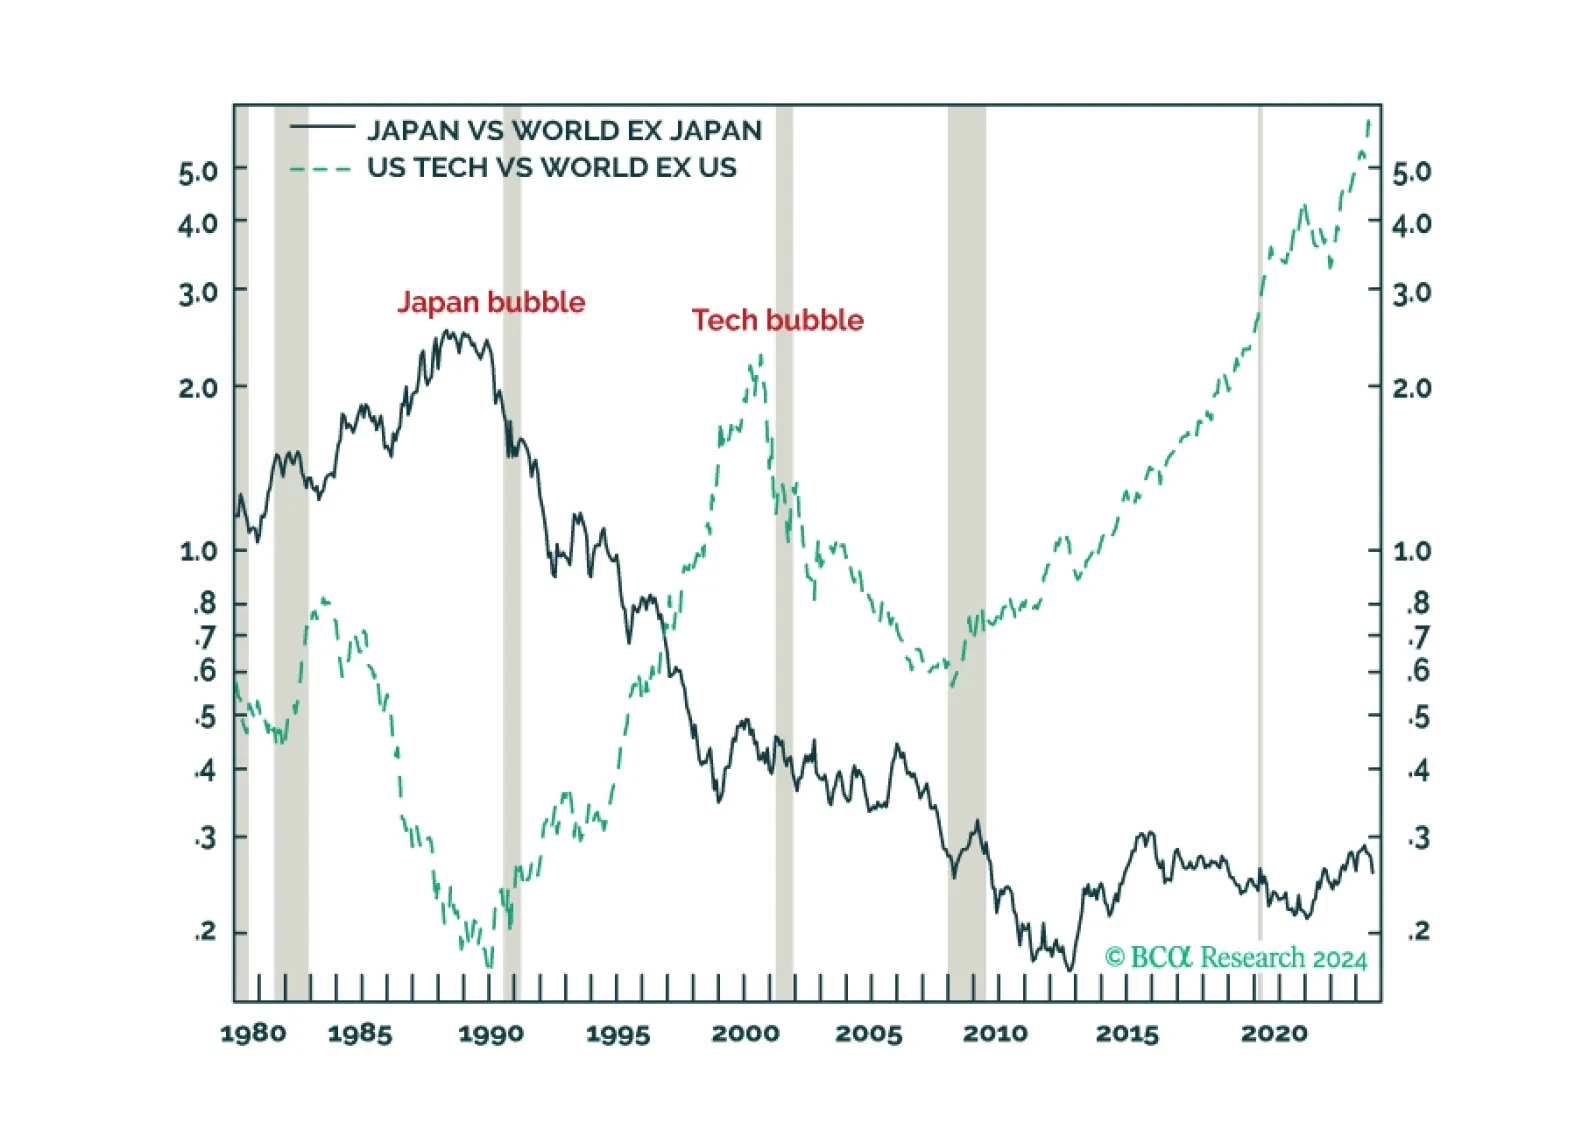
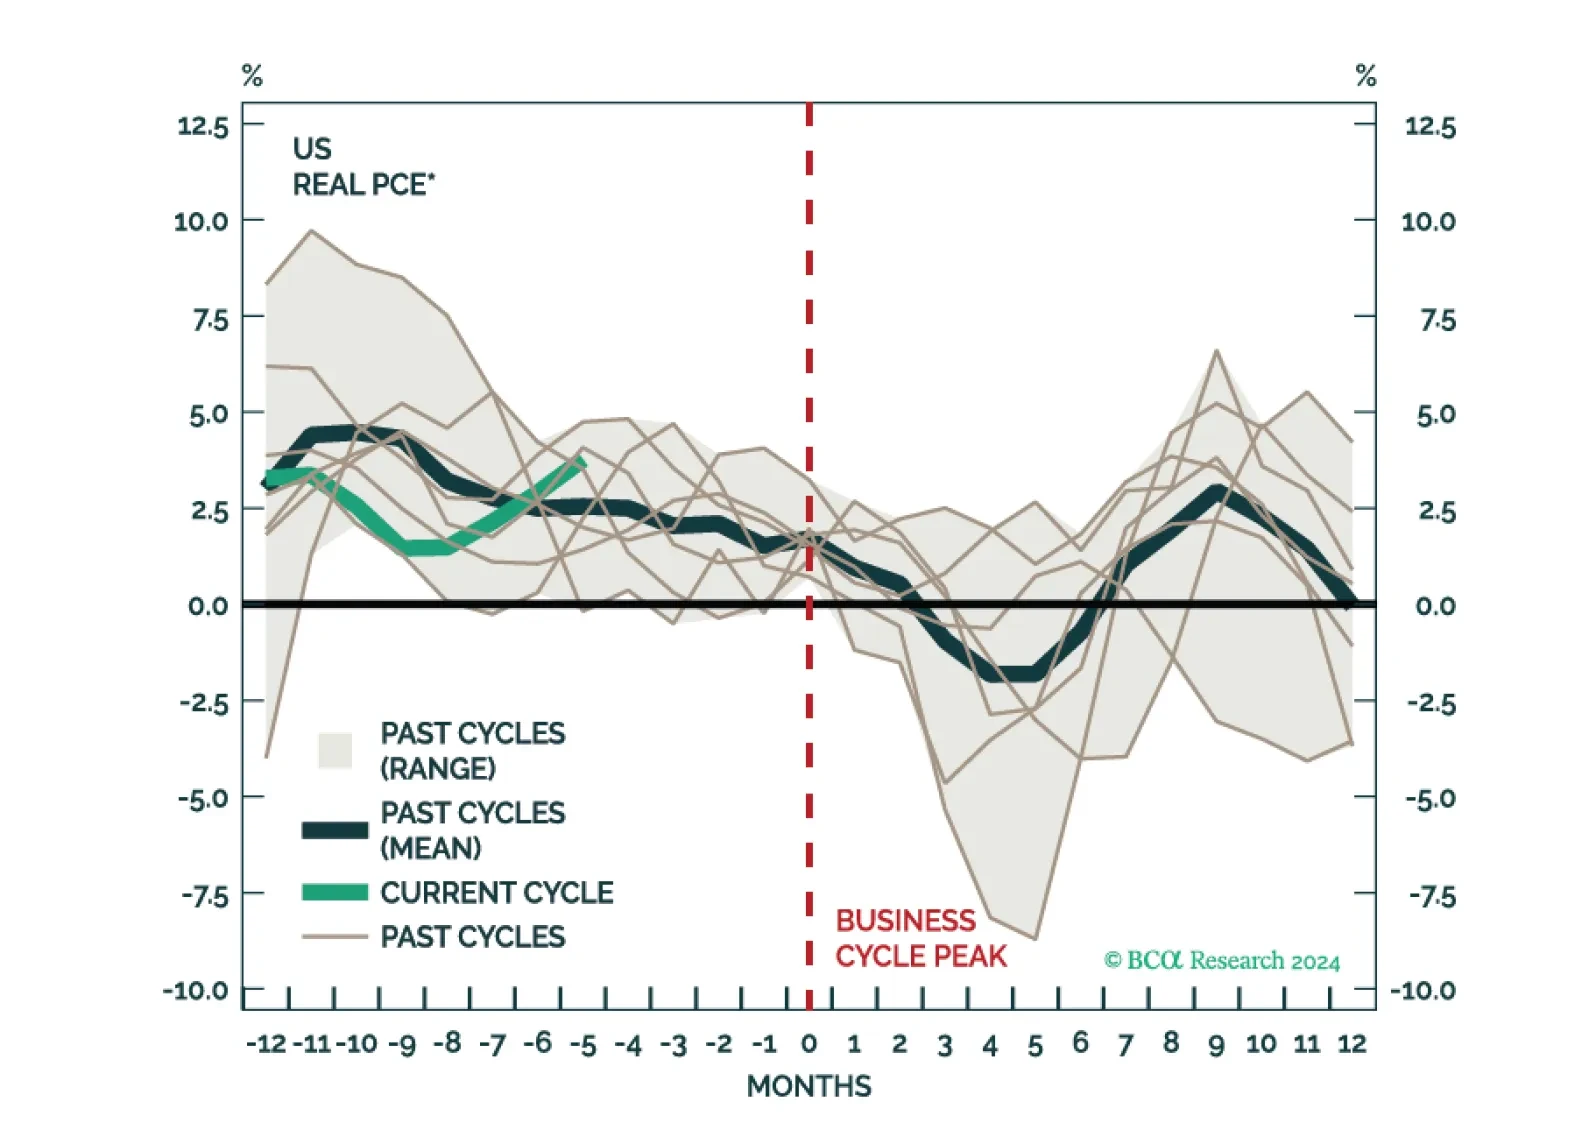
Investors should worry much less about a US or global recession than they should worry about the bubble in anything AI-related. This means staying overweight bonds and the JPY, underweight US tech and quasi-tech, and underweight the US. Plus: SGD/USD is vulnerable to reversal, while copper versus gold can rebound.