 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
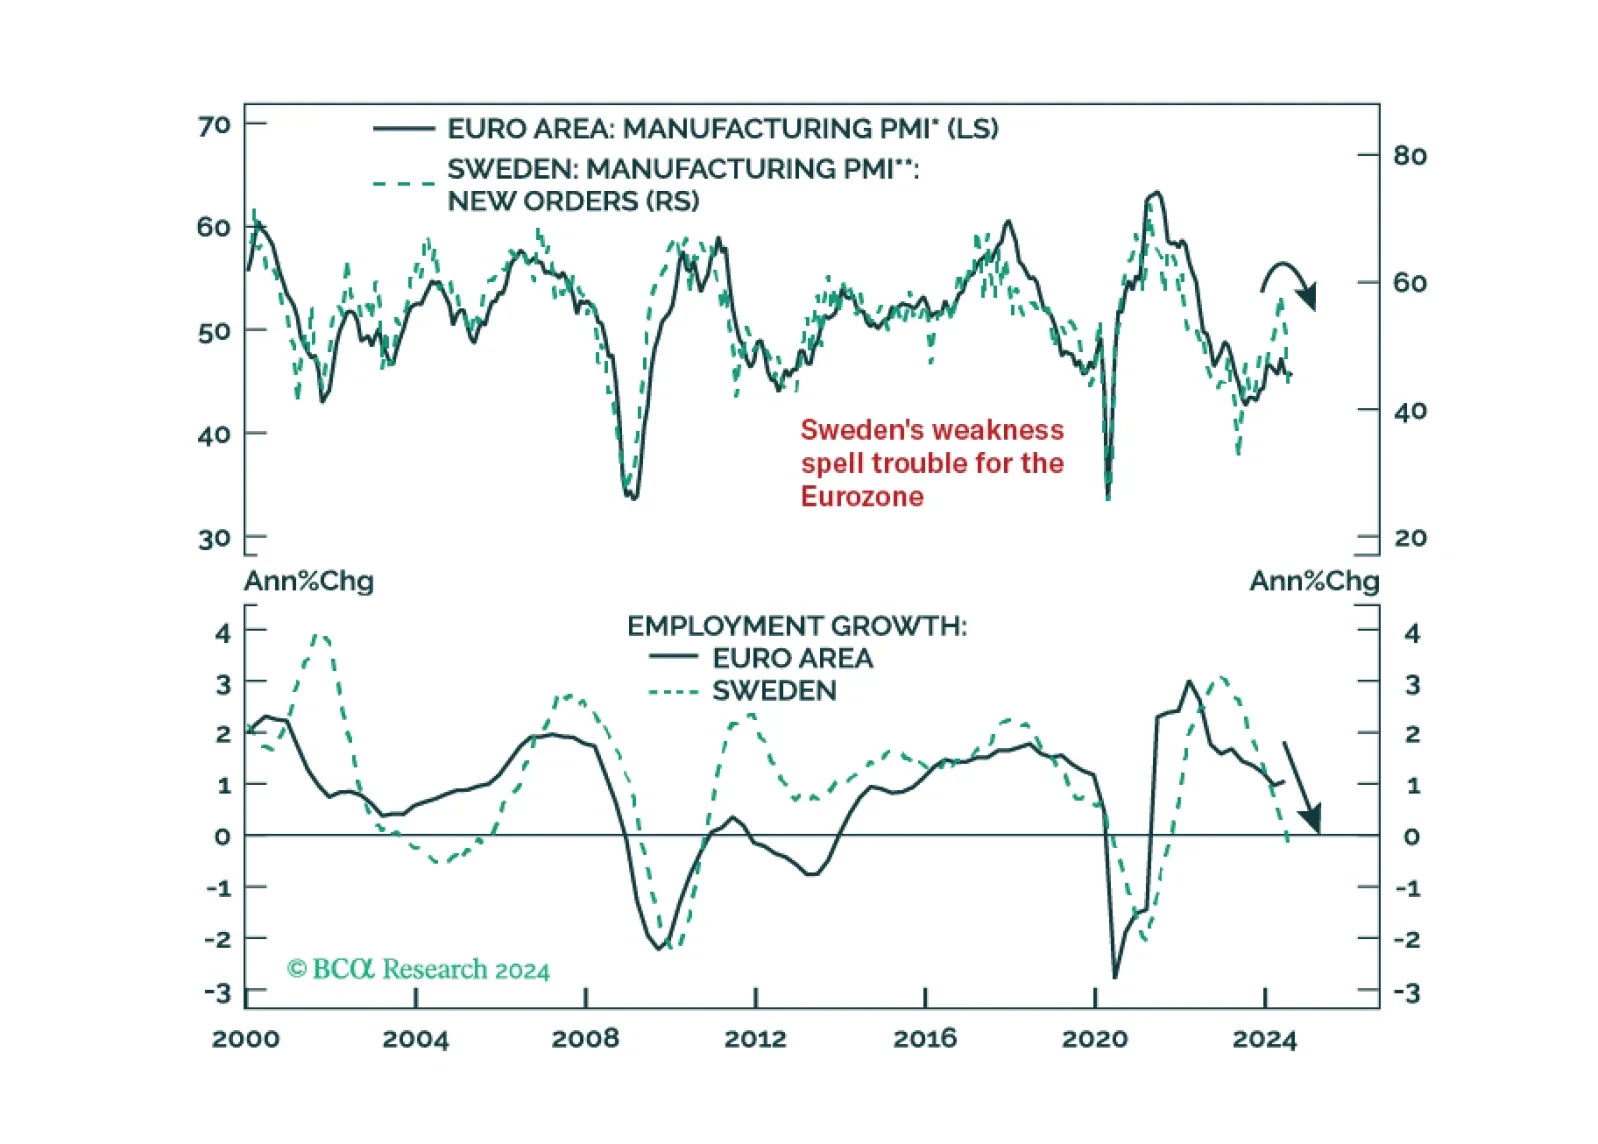
Our negative stance on European growth and assets is not devoid of risks. To gauge whether these risks warrant upgrading our growth outlook, we monitor Sweden closely. So, what is the current message from this Nordic economy?
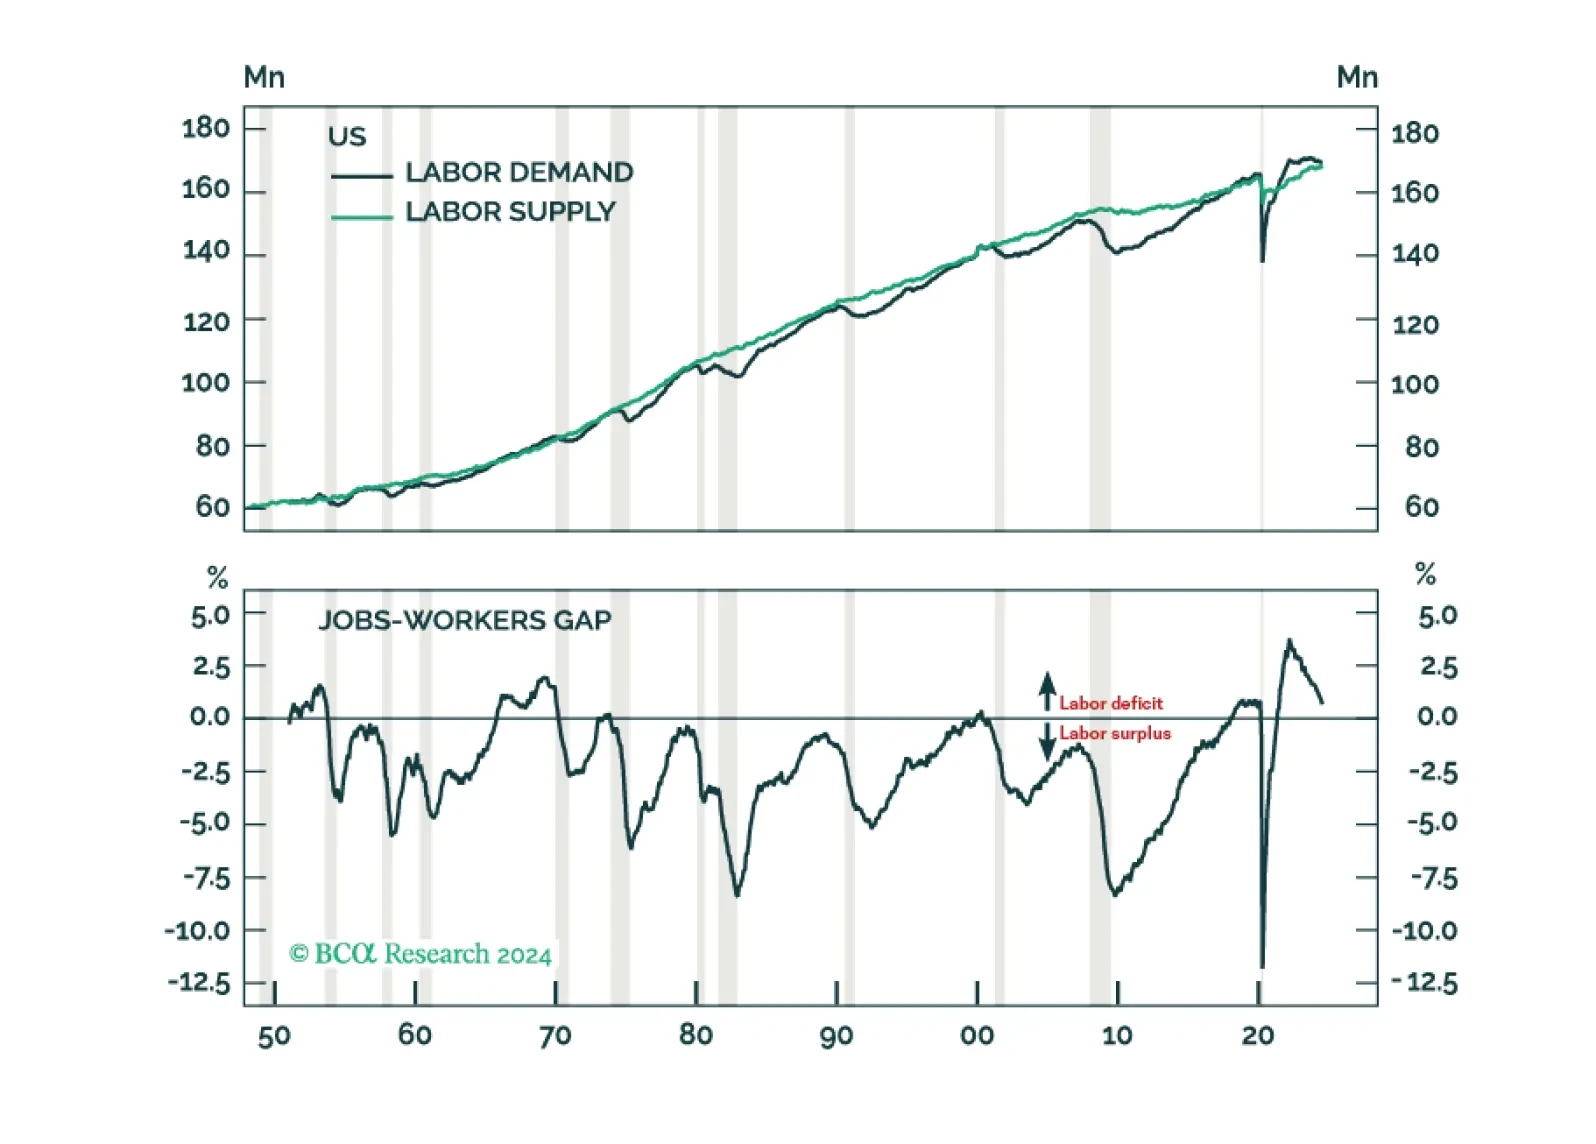
The great US labor market shortage is over. Labor demand will likely fall short of supply by the end of this year, causing unemployment to soar. Neither fiscal nor monetary policy will be able to prevent the coming recession. Investors should underweight stocks and overweight Treasuries.
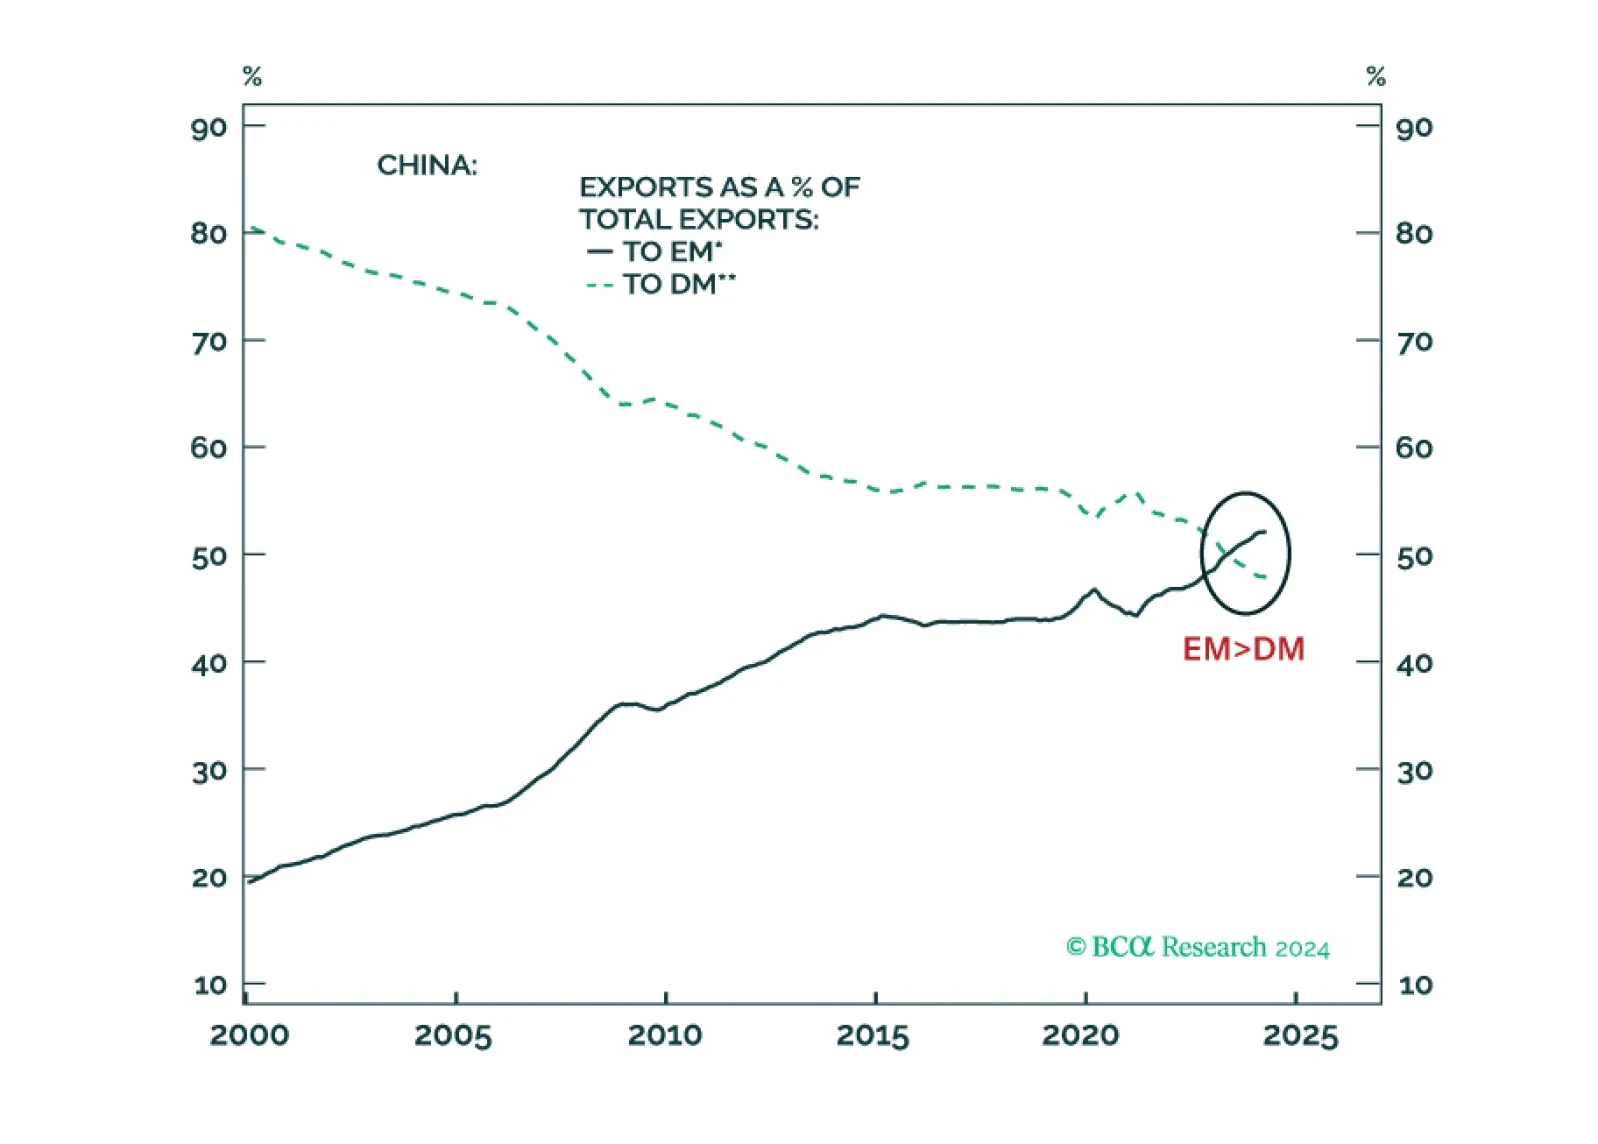
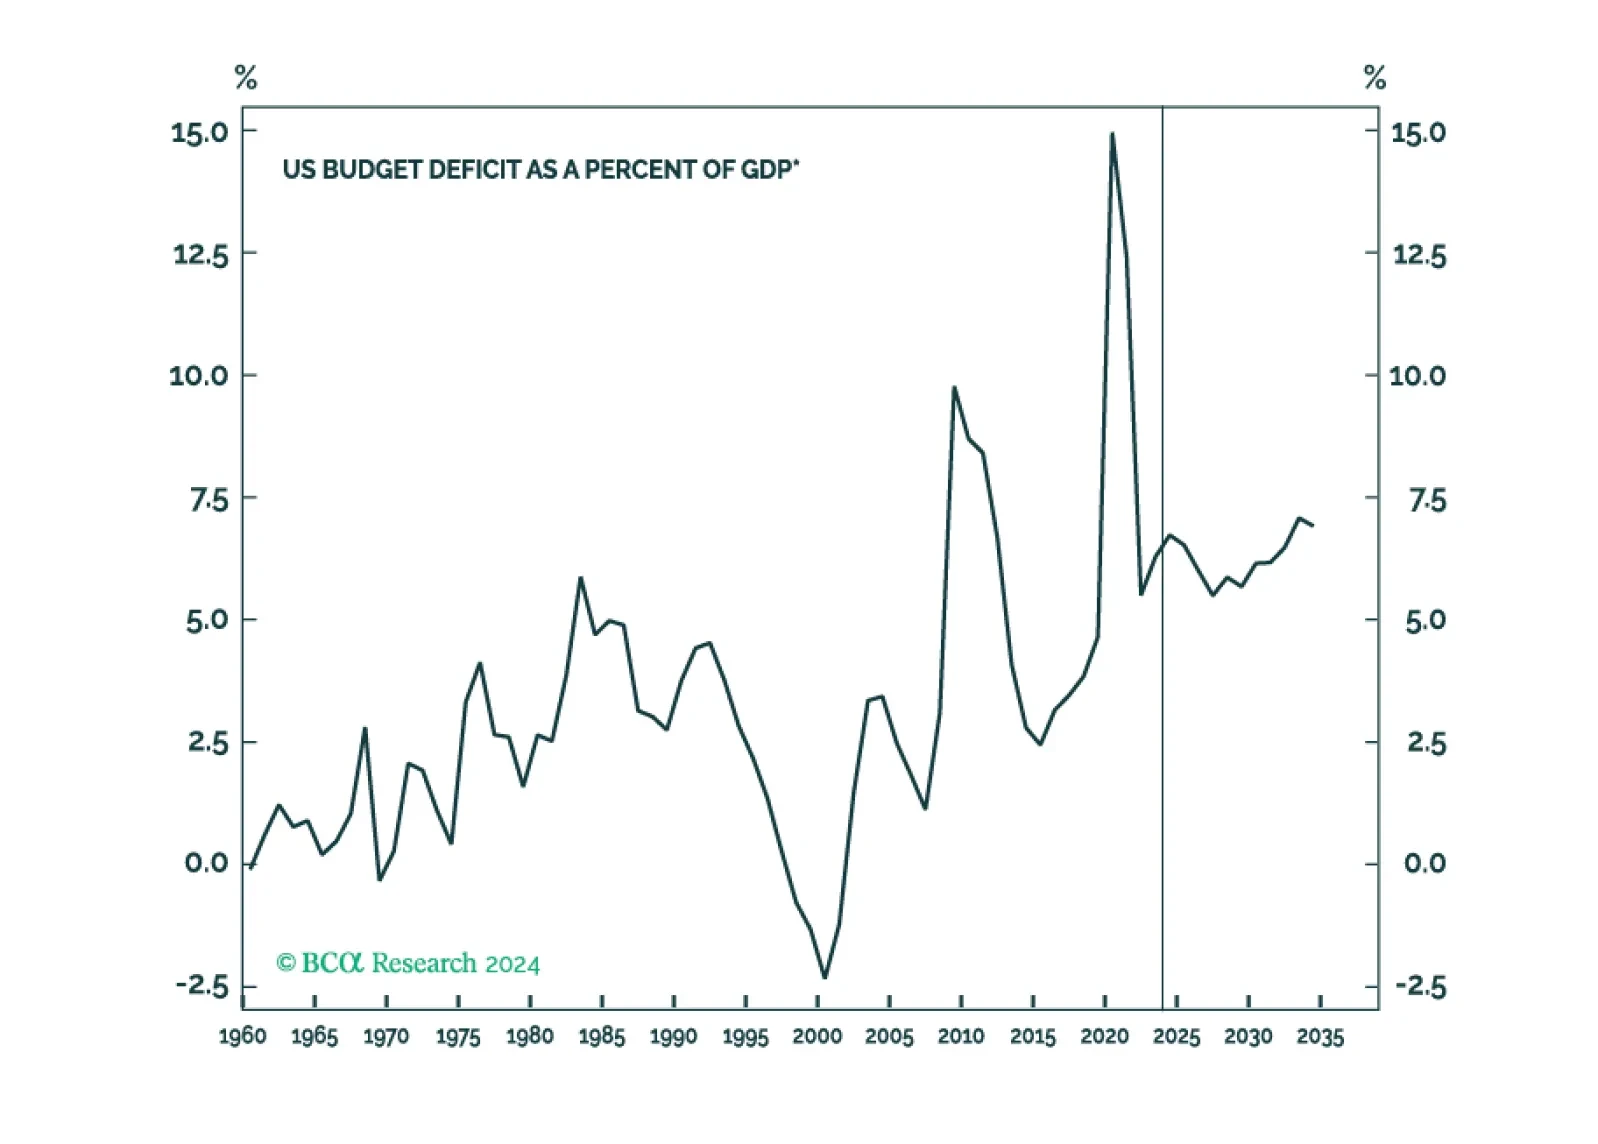
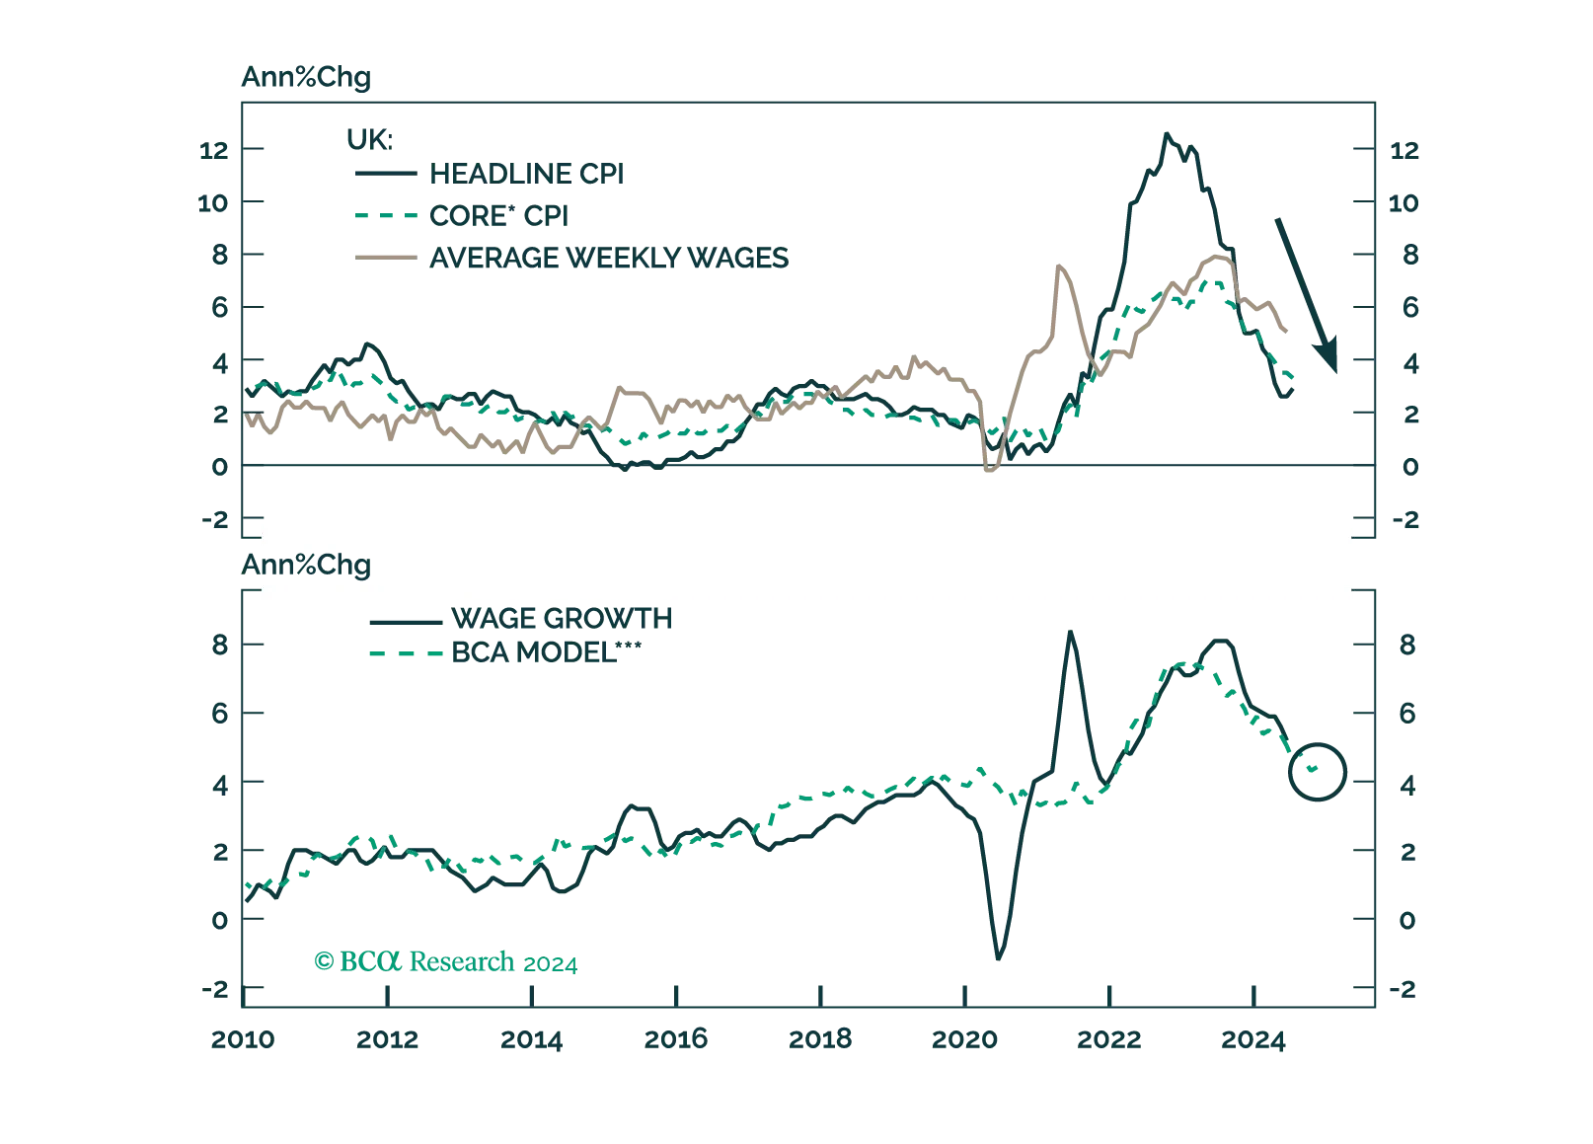
What do the mixed signals sent by the UK economy mean for the Bank of England, and what are the implications for Gilts and the British pound?
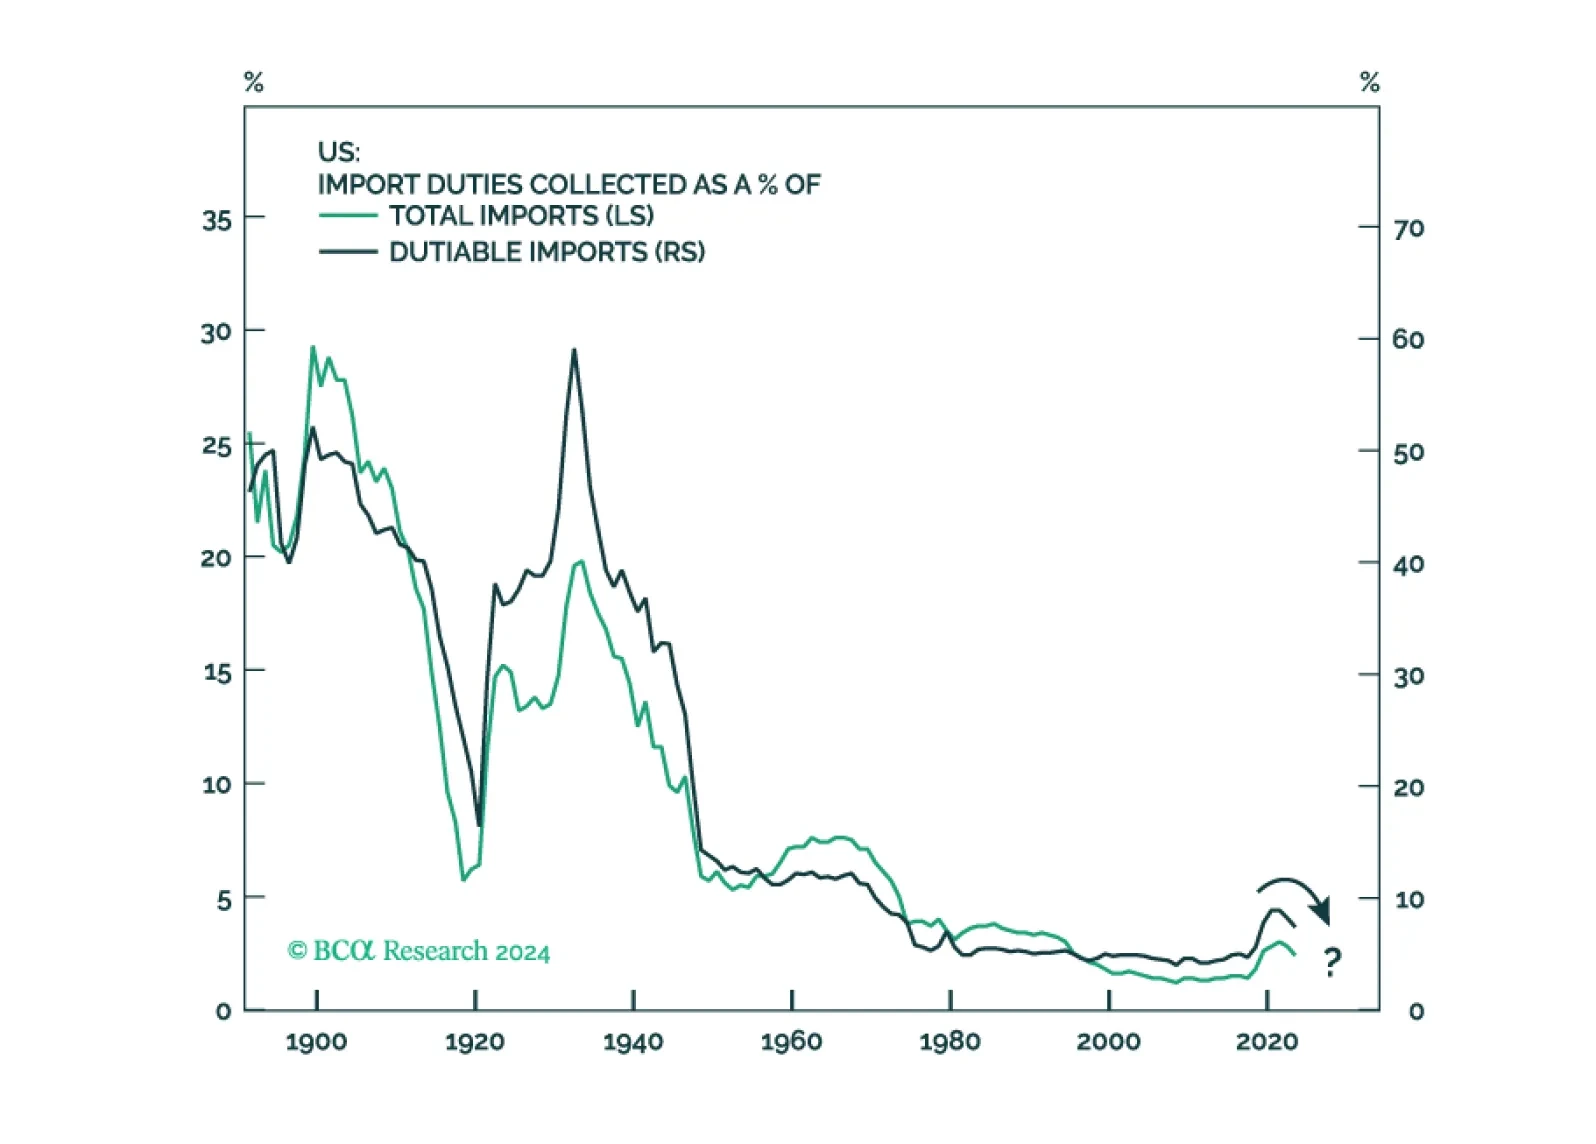

The current Fed easing cycle will likely be a “buy the rumor, sell the news” phenomenon. The basis is our expectation that the US economy is heading into a rough landing. The primary driver of EM currencies is not US interest rates but the global manufacturing cycle.
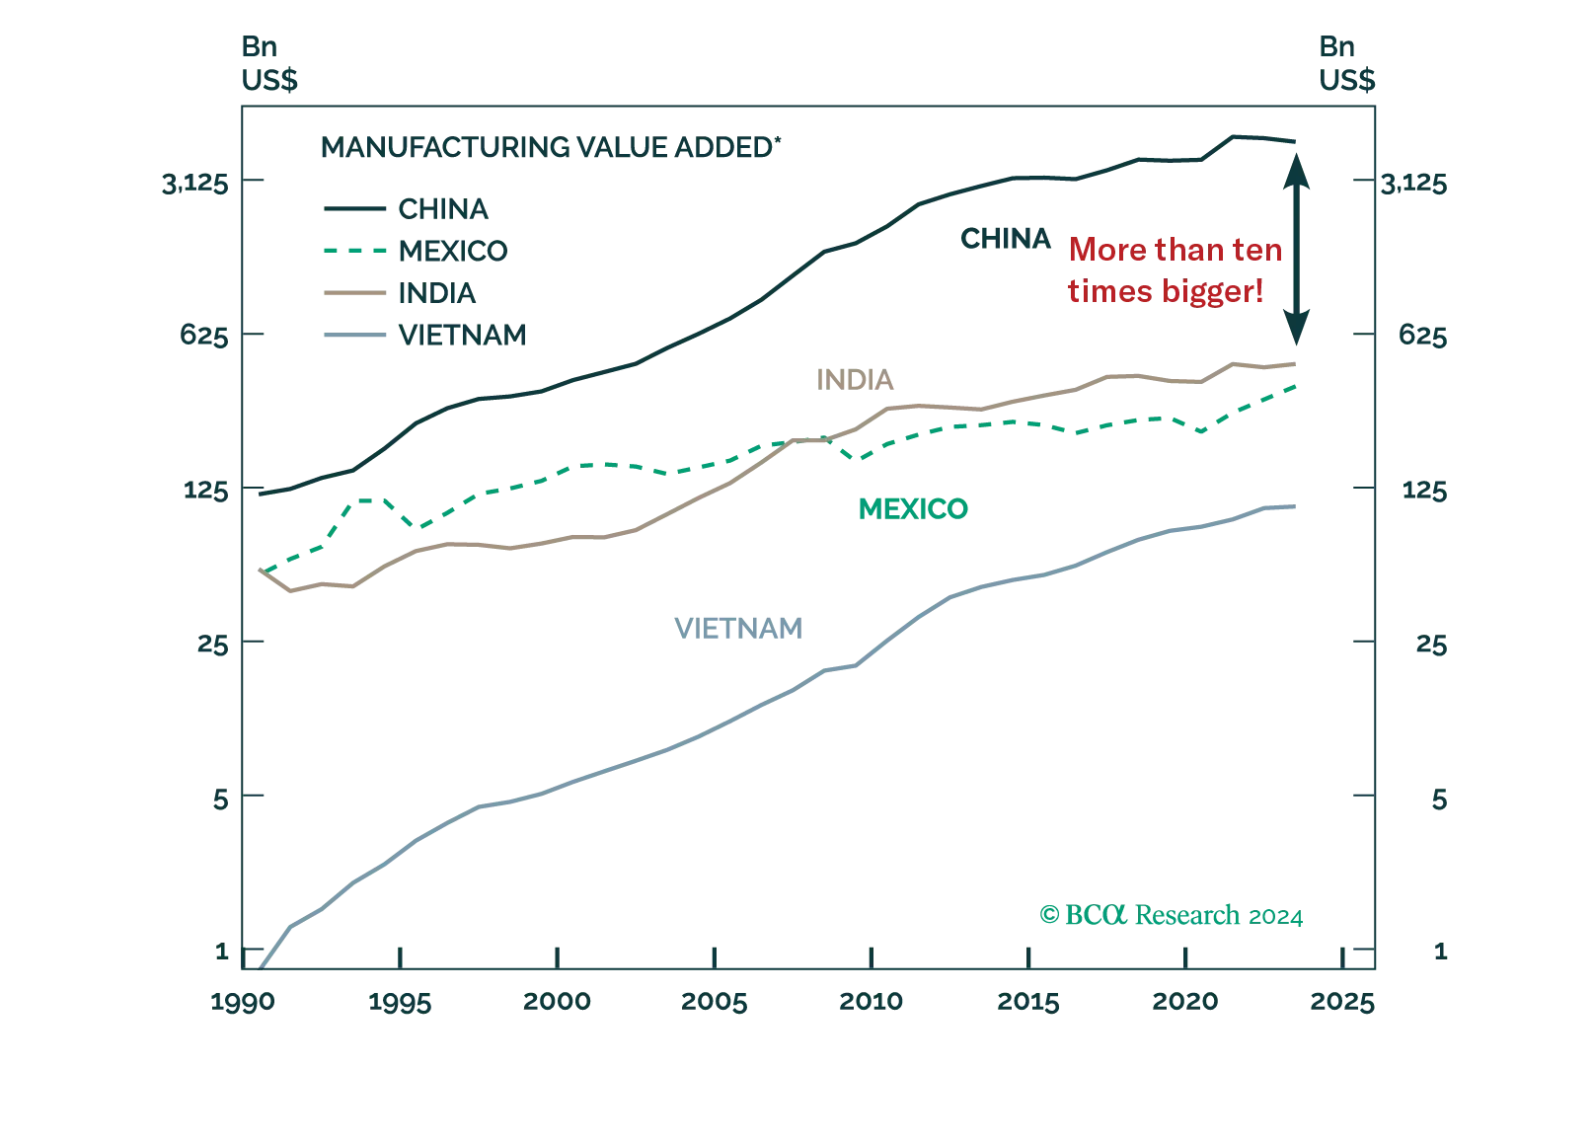
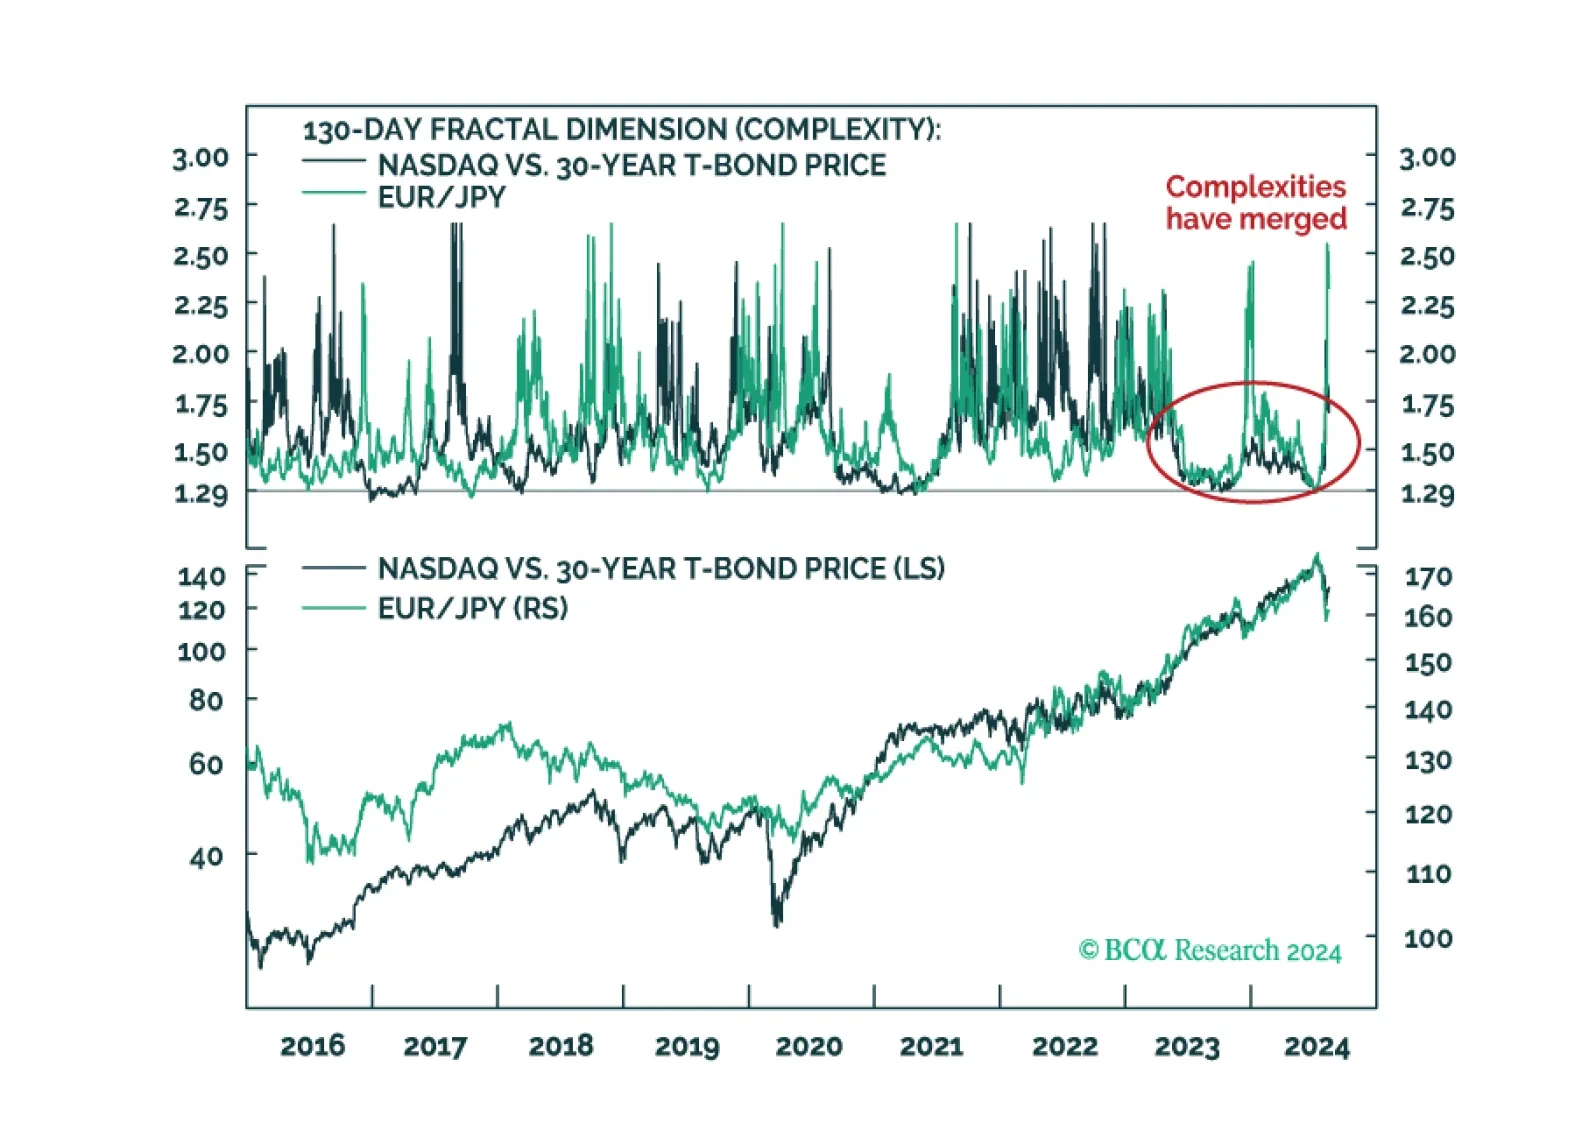
The analysis of price complexity strongly suggests that the ‘yen carry trade’ and the AI bubble are one and the same trade, and that the trade has further to unwind. Plus, go tactically overweight China (CHIQ).
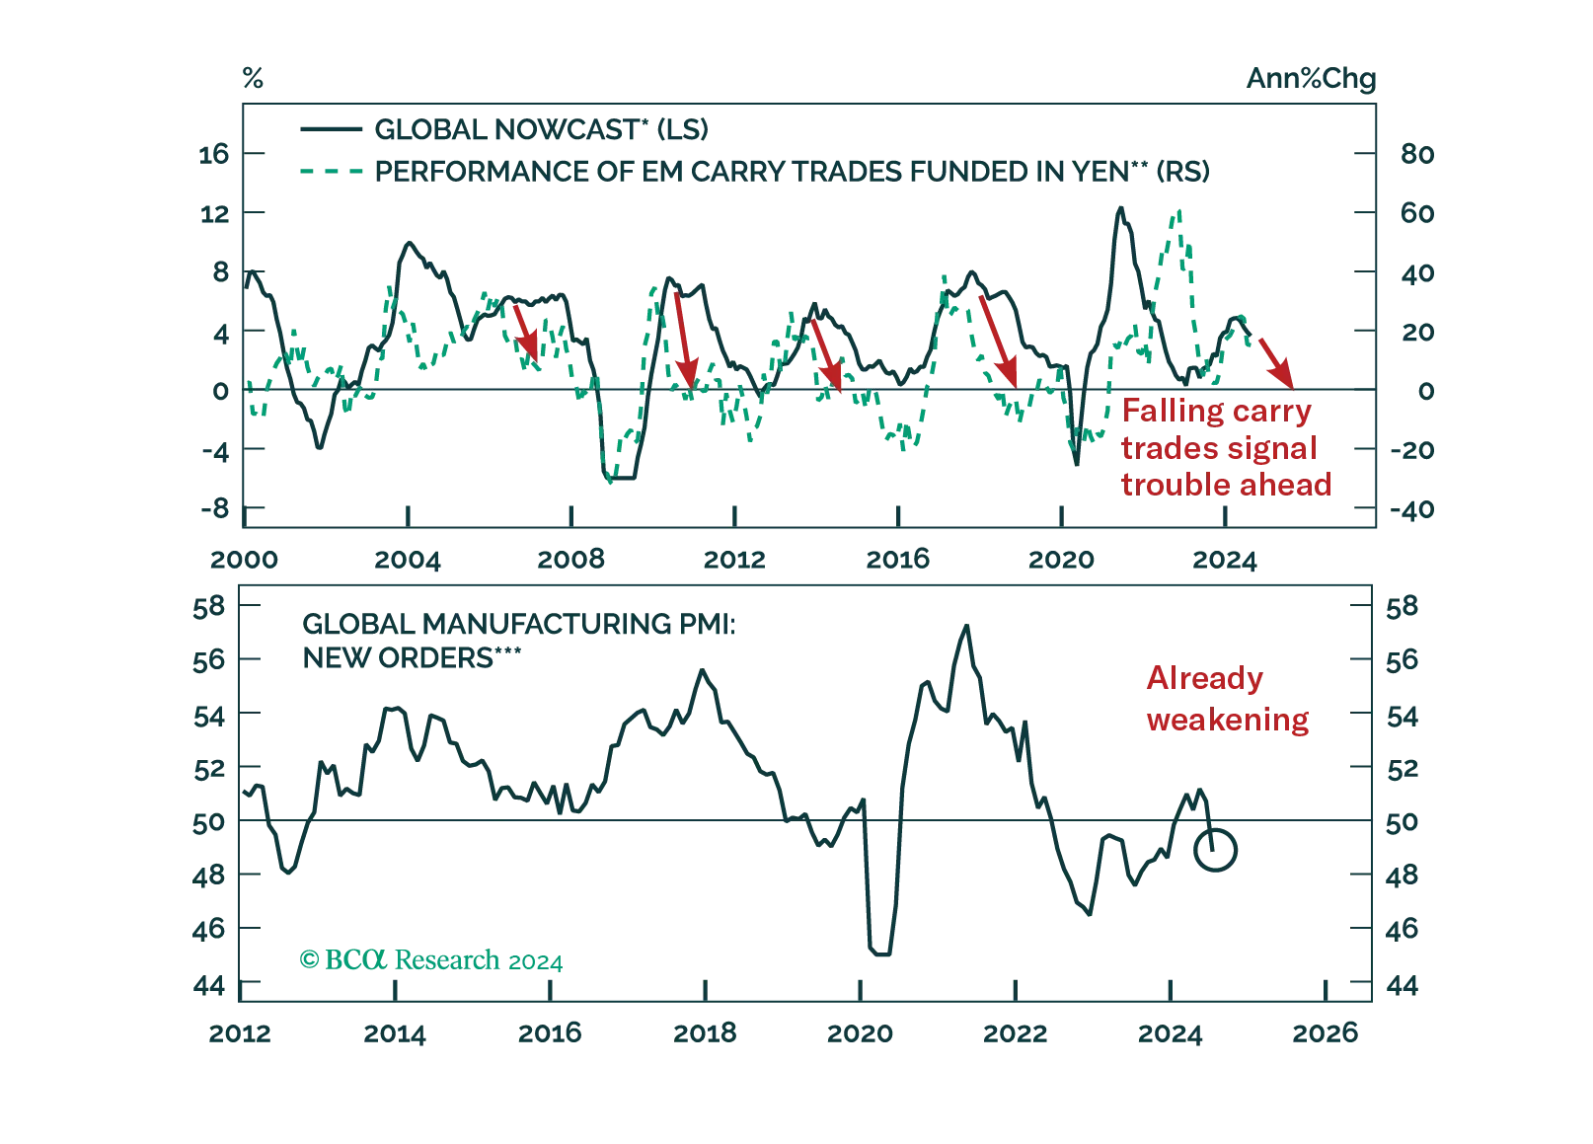
The unwind of yen carry trades caused violent tremors across the globe. Was this shock a one-off event or the prelude to more troubles?