 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
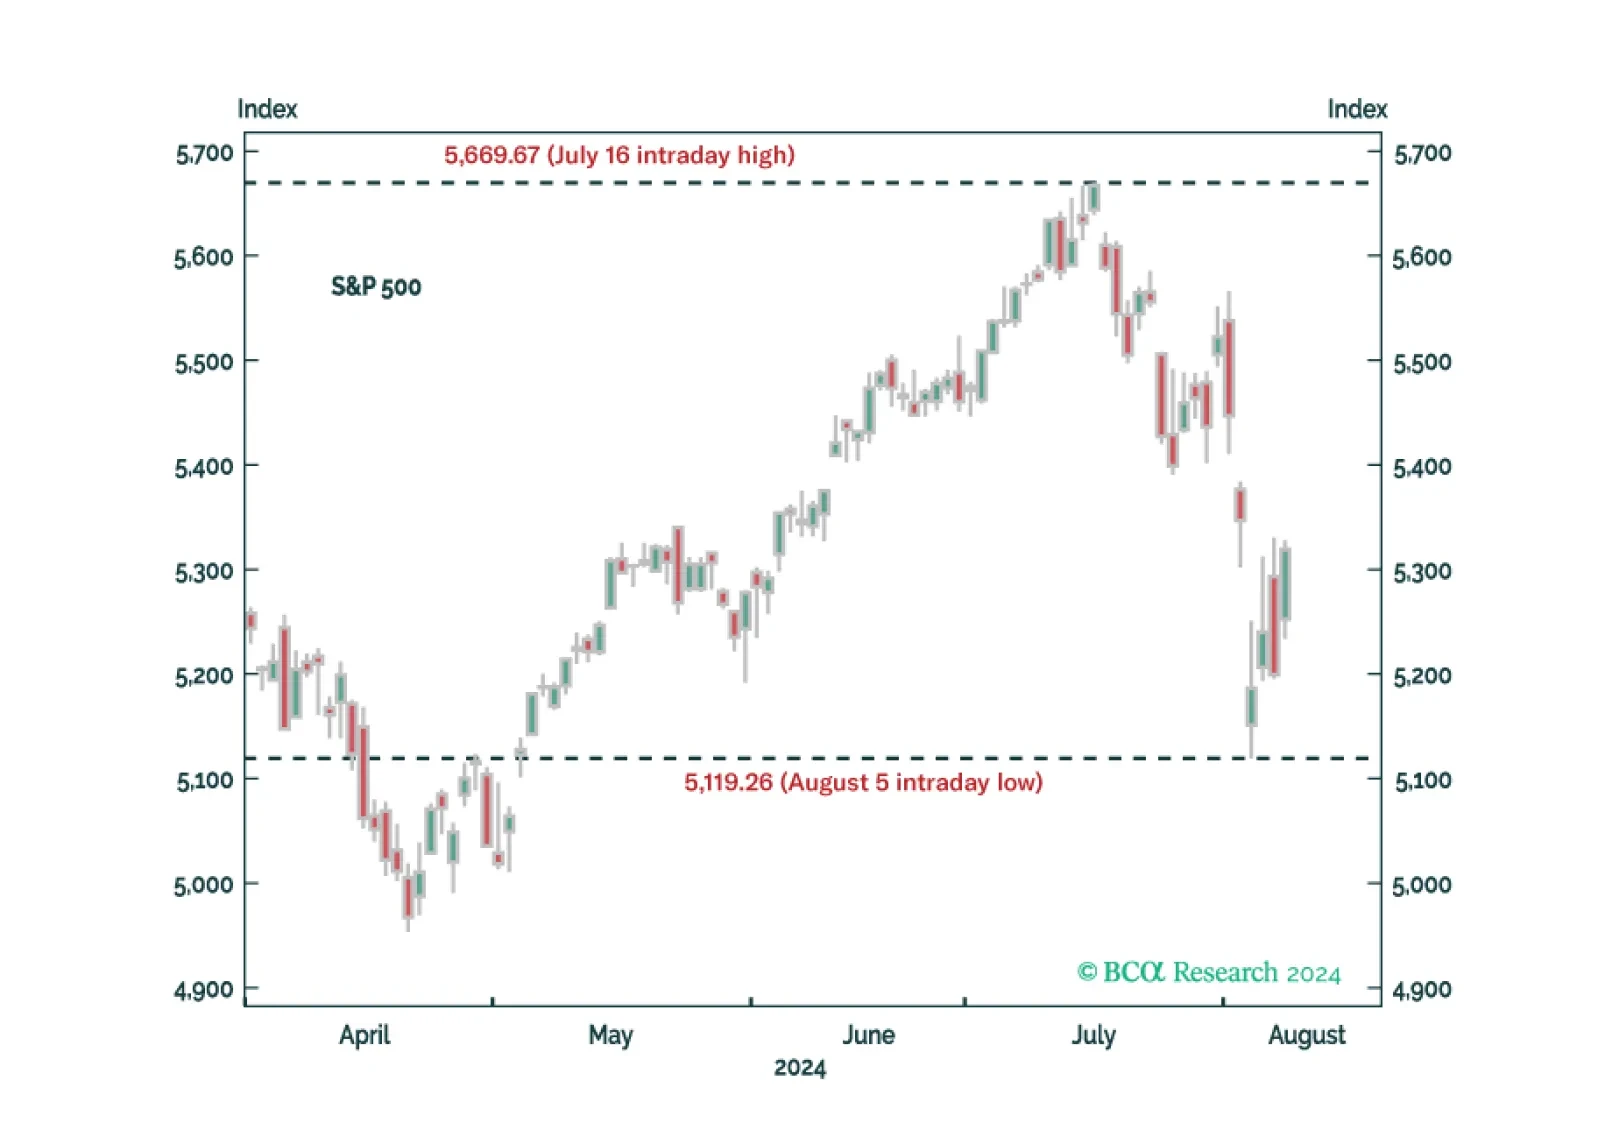
The market backdrop changed a lot between the preparation and the publication of our equity downgrade report. We publish this companion Insight to help investors navigate the new environment.
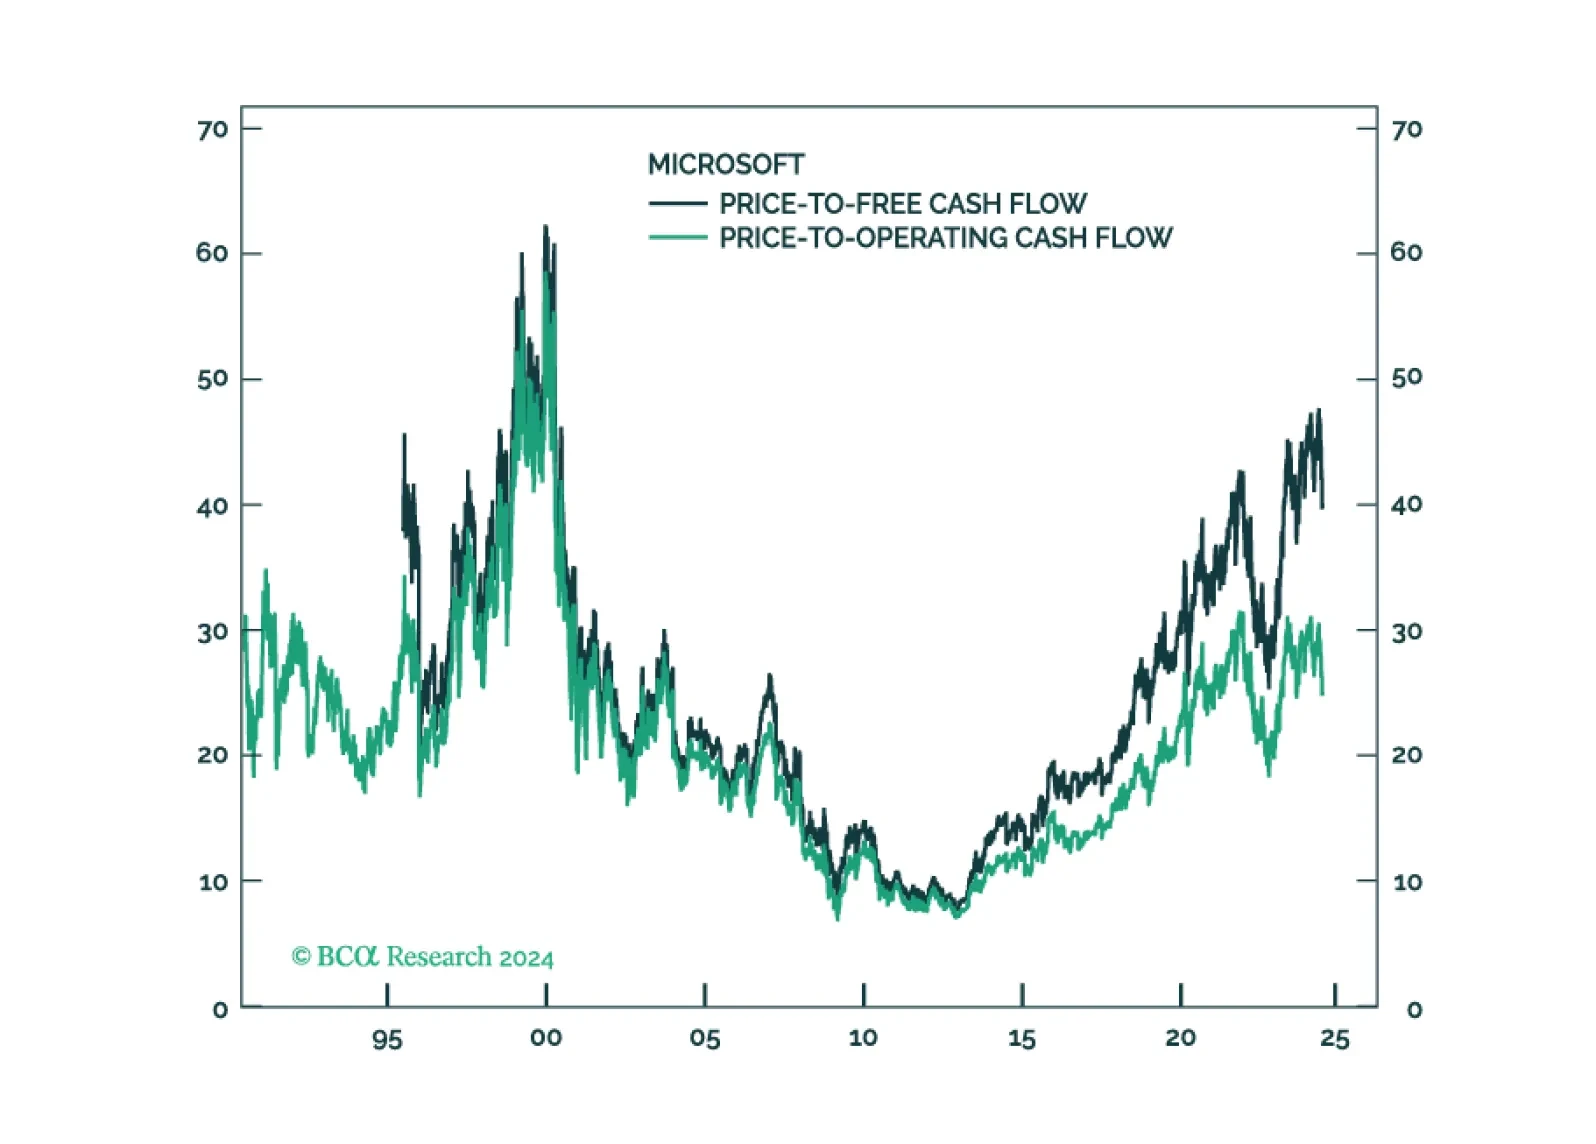
Over the past few weeks, global equities have been hit by rising scepticism over the bullish AI narrative and increasing concerns over global growth. Stocks should stabilize in the near term, but the medium-term direction is to the downside. We expect the S&P 500 to drop to 3750 in 2025 and the 10-year Treasury yield to fall to 3%.
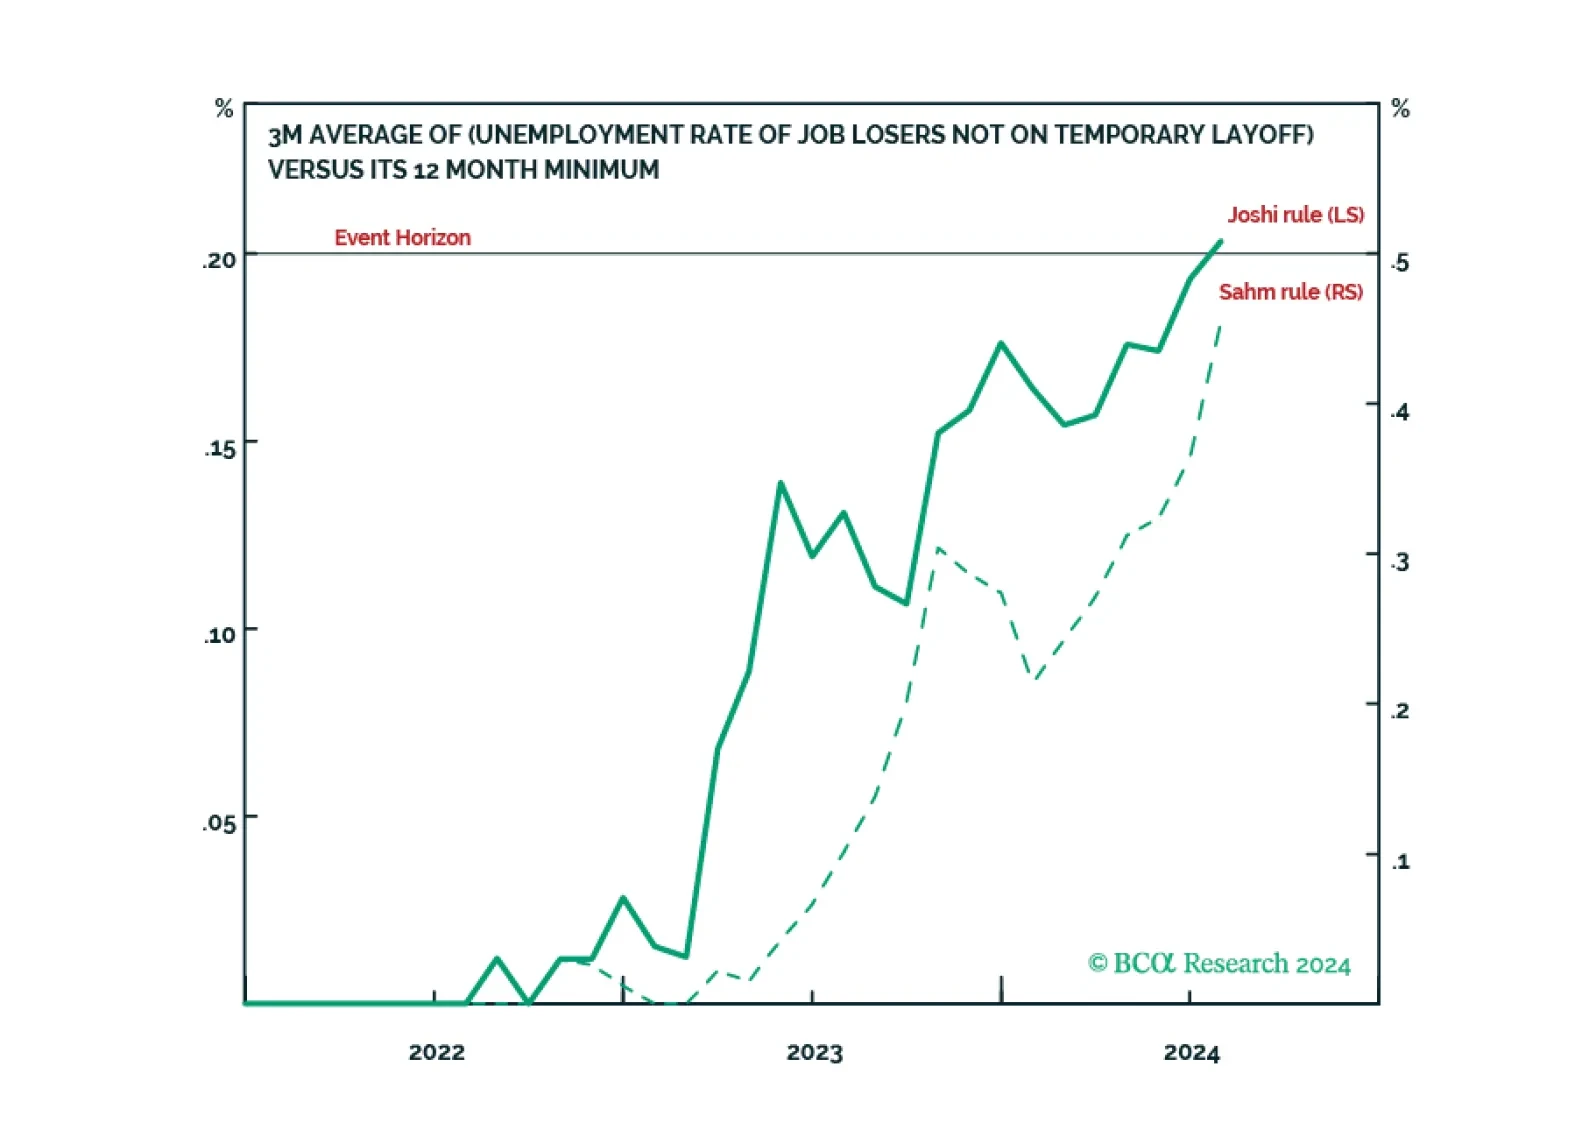
Why the Joshi rule gives a much better signal than the Sahm rule, and what it means for the US economy, the US election, and the markets.

The prices of multiple financial assets have failed to break above their technical resistances. When this occurs, a breakdown ensues. In brief, global risk assets remain vulnerable. We are upgrading Chinese onshore stocks from neutral to overweight and offshore ones from underweight to neutral within EM and global equity portfolios.

China's cyclical and structural headwinds will likely undermine Beijing’s initiative to accelerate urban migration over the next five years.
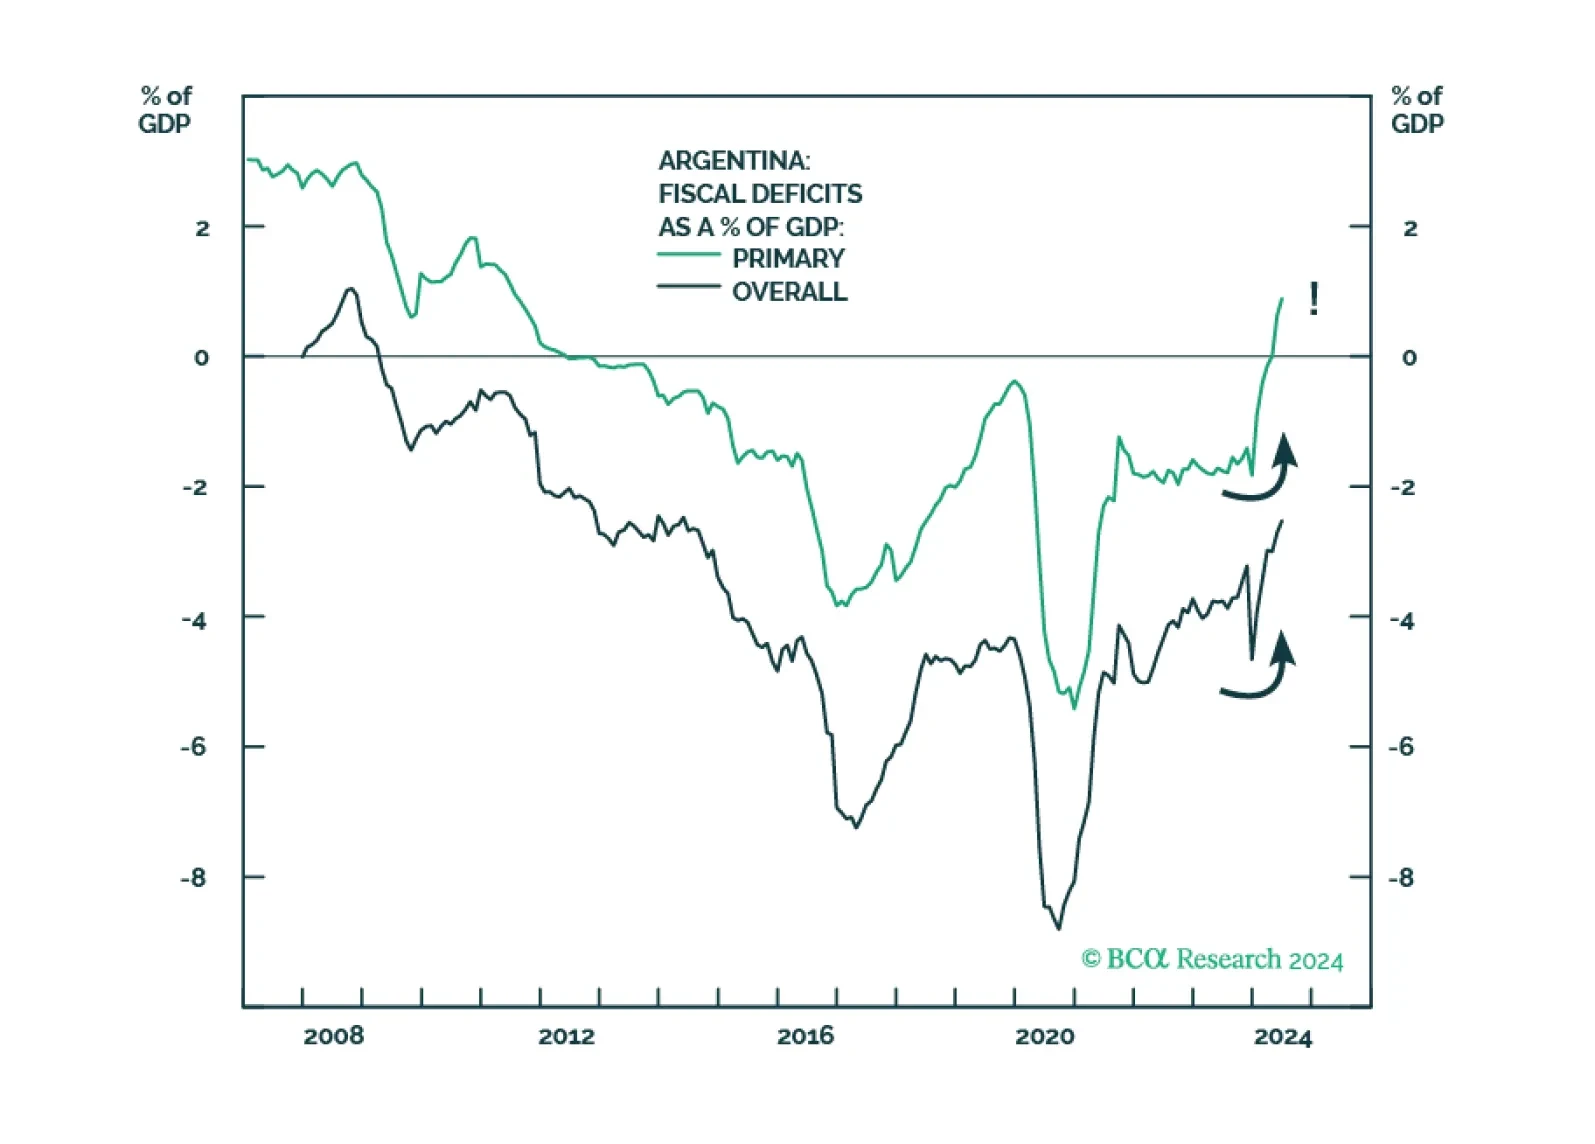

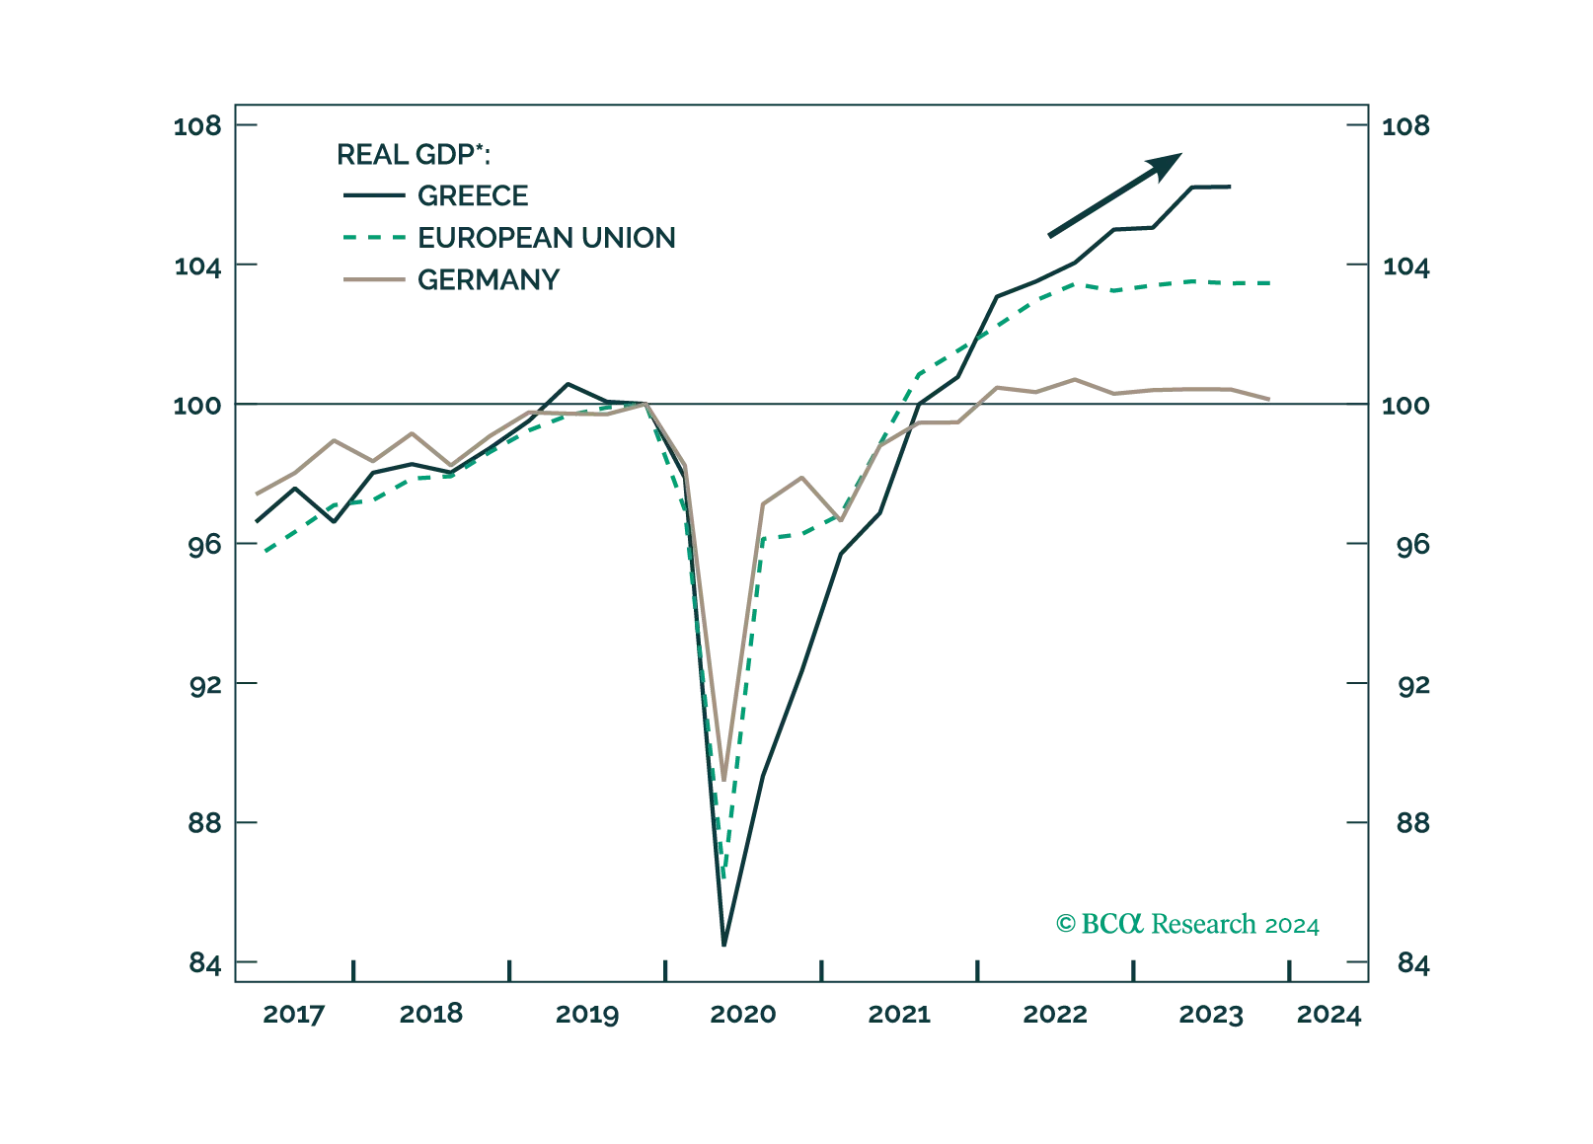
Absolute return investors should be tactically cautious on Greek assets. Dedicated EM equity portfolios, however, should overweight Greek stocks.
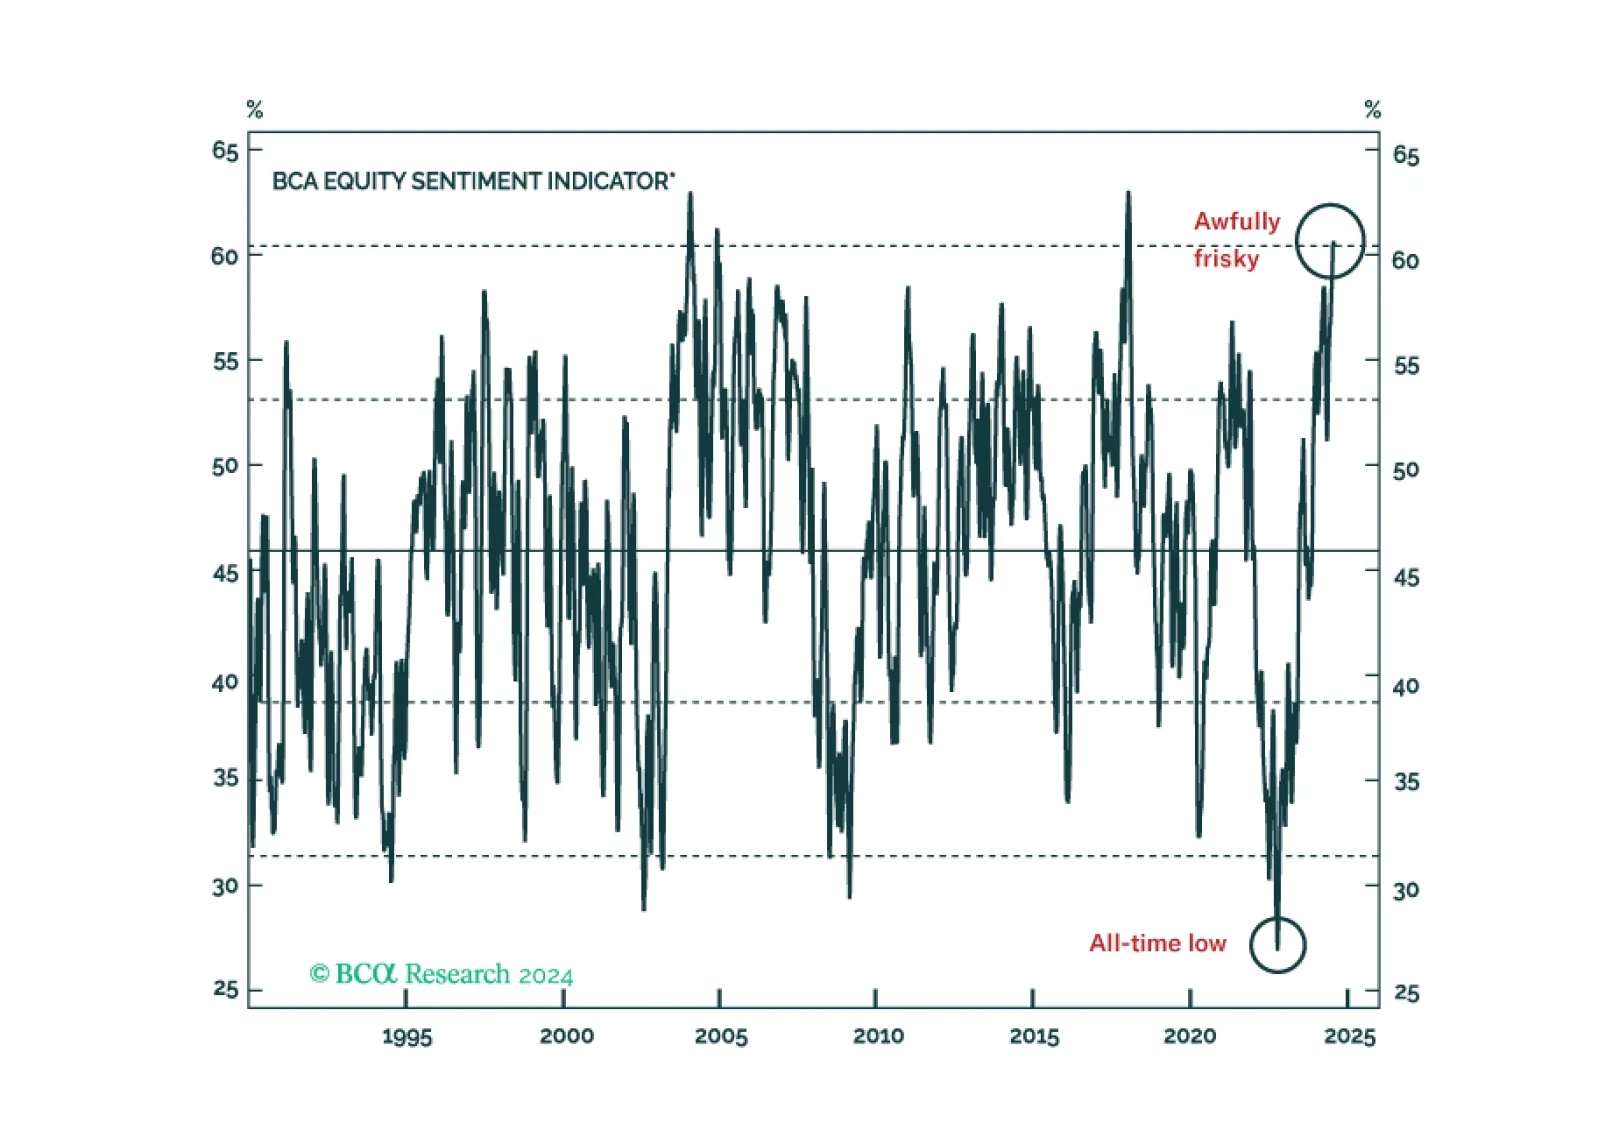
Mounting evidence that the labor market is on its way to cracking checked two more boxes on our checklist, driving us to tactically downgrade equities to underweight while upgrading fixed income to overweight. Our tactical and cyclical (6-12 months) views are now aligned as our conviction that a recession will begin before year-end has increased.
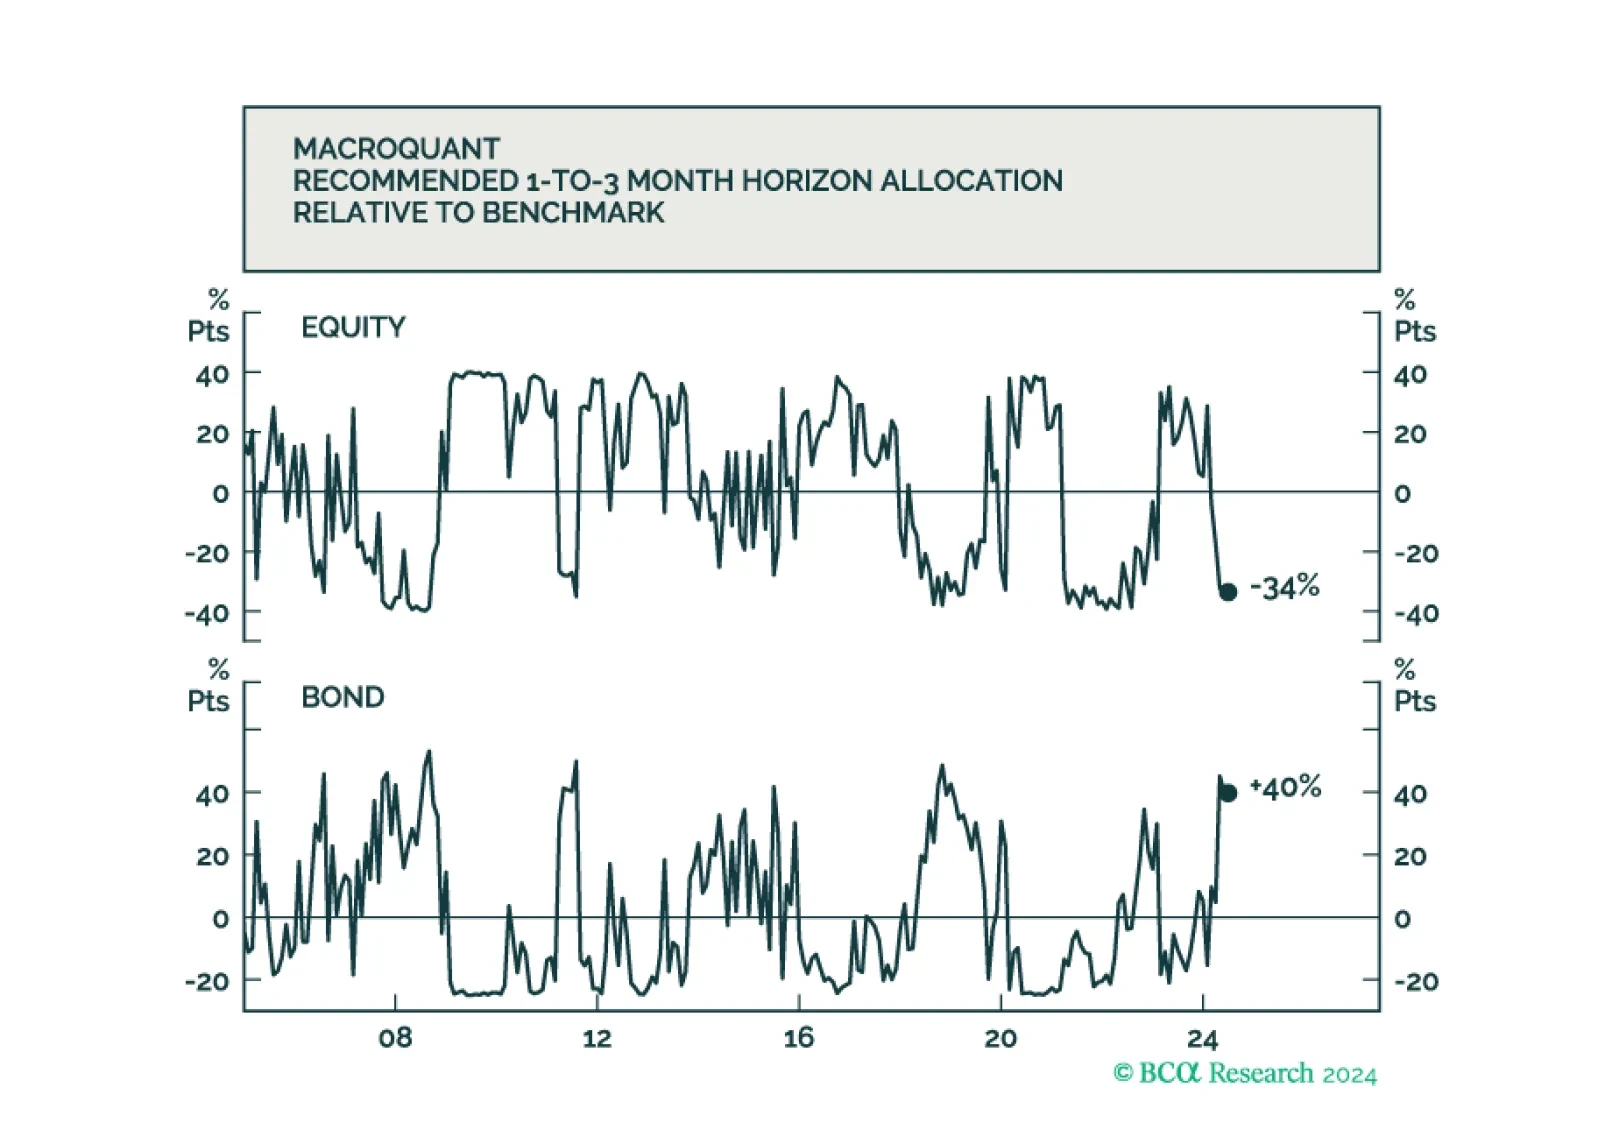
The Global Investment Strategy team downgraded global equities to underweight in late June. The latest reading from our MacroQuant model is consistent with this decision.