CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
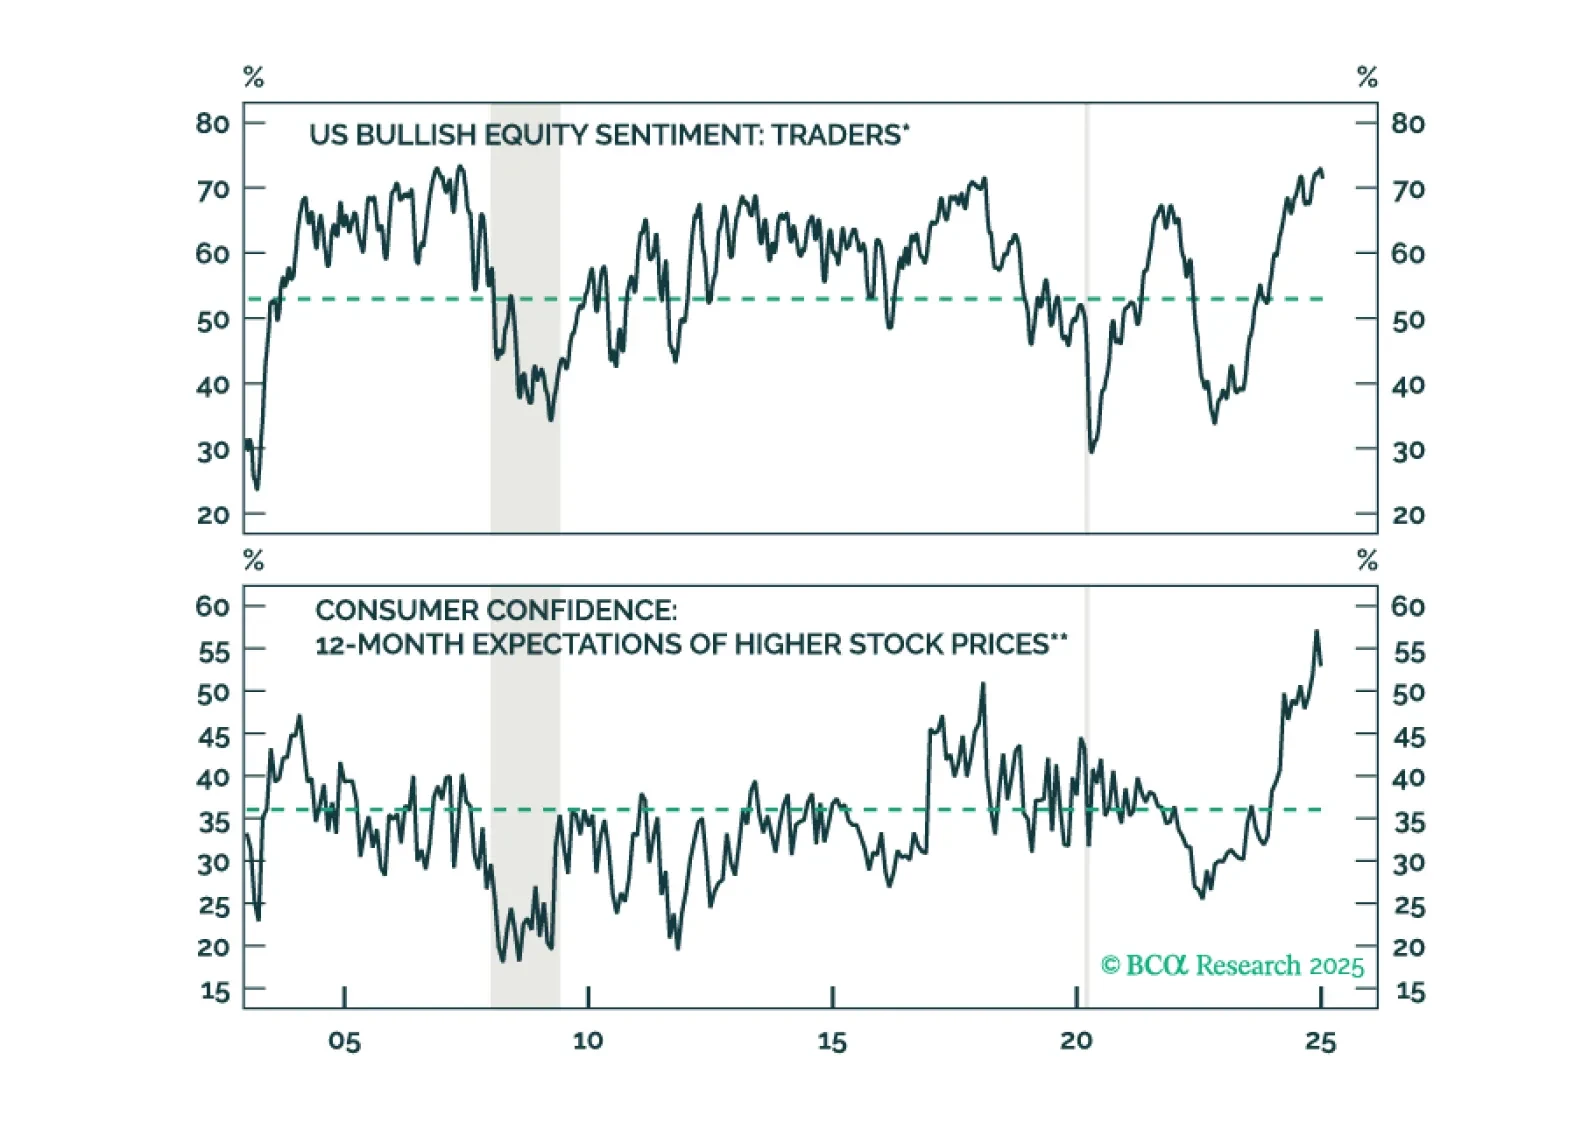
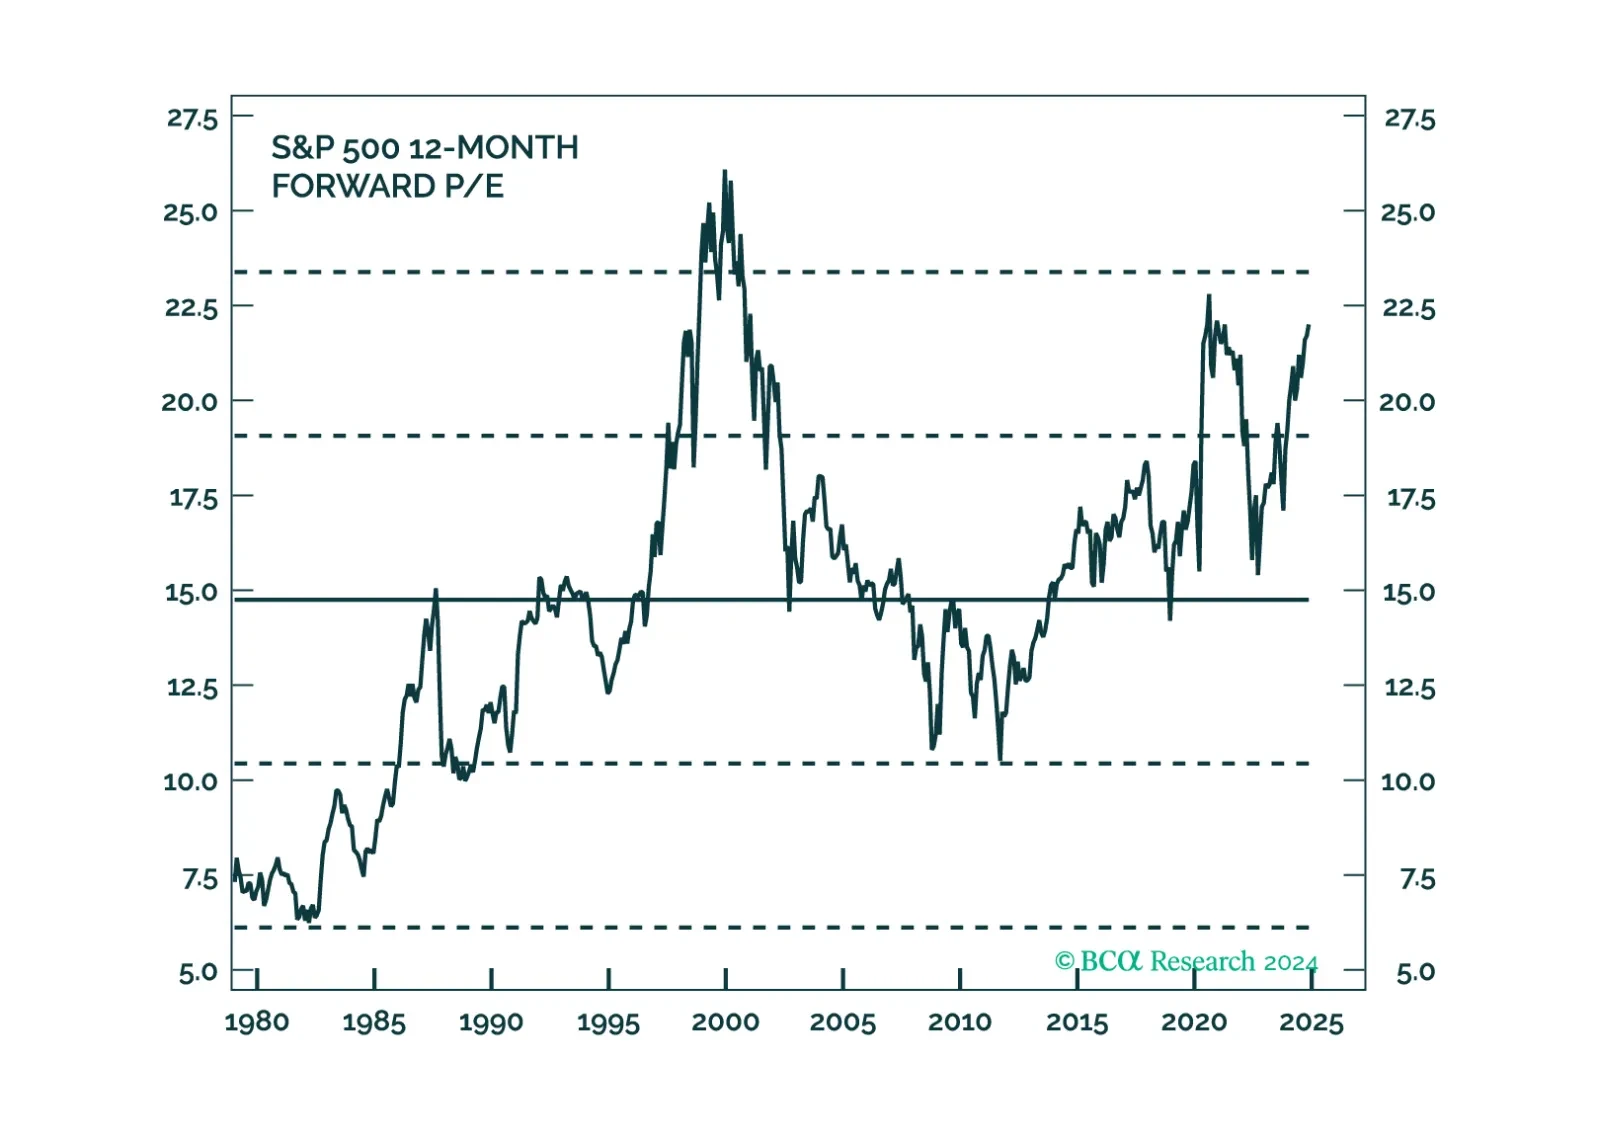
Stocks have climbed the wall of worry and we are about to see what is on the other side (it won’t be pretty). We will be using our MacroQuant model to determine when to go maximally underweight equities.
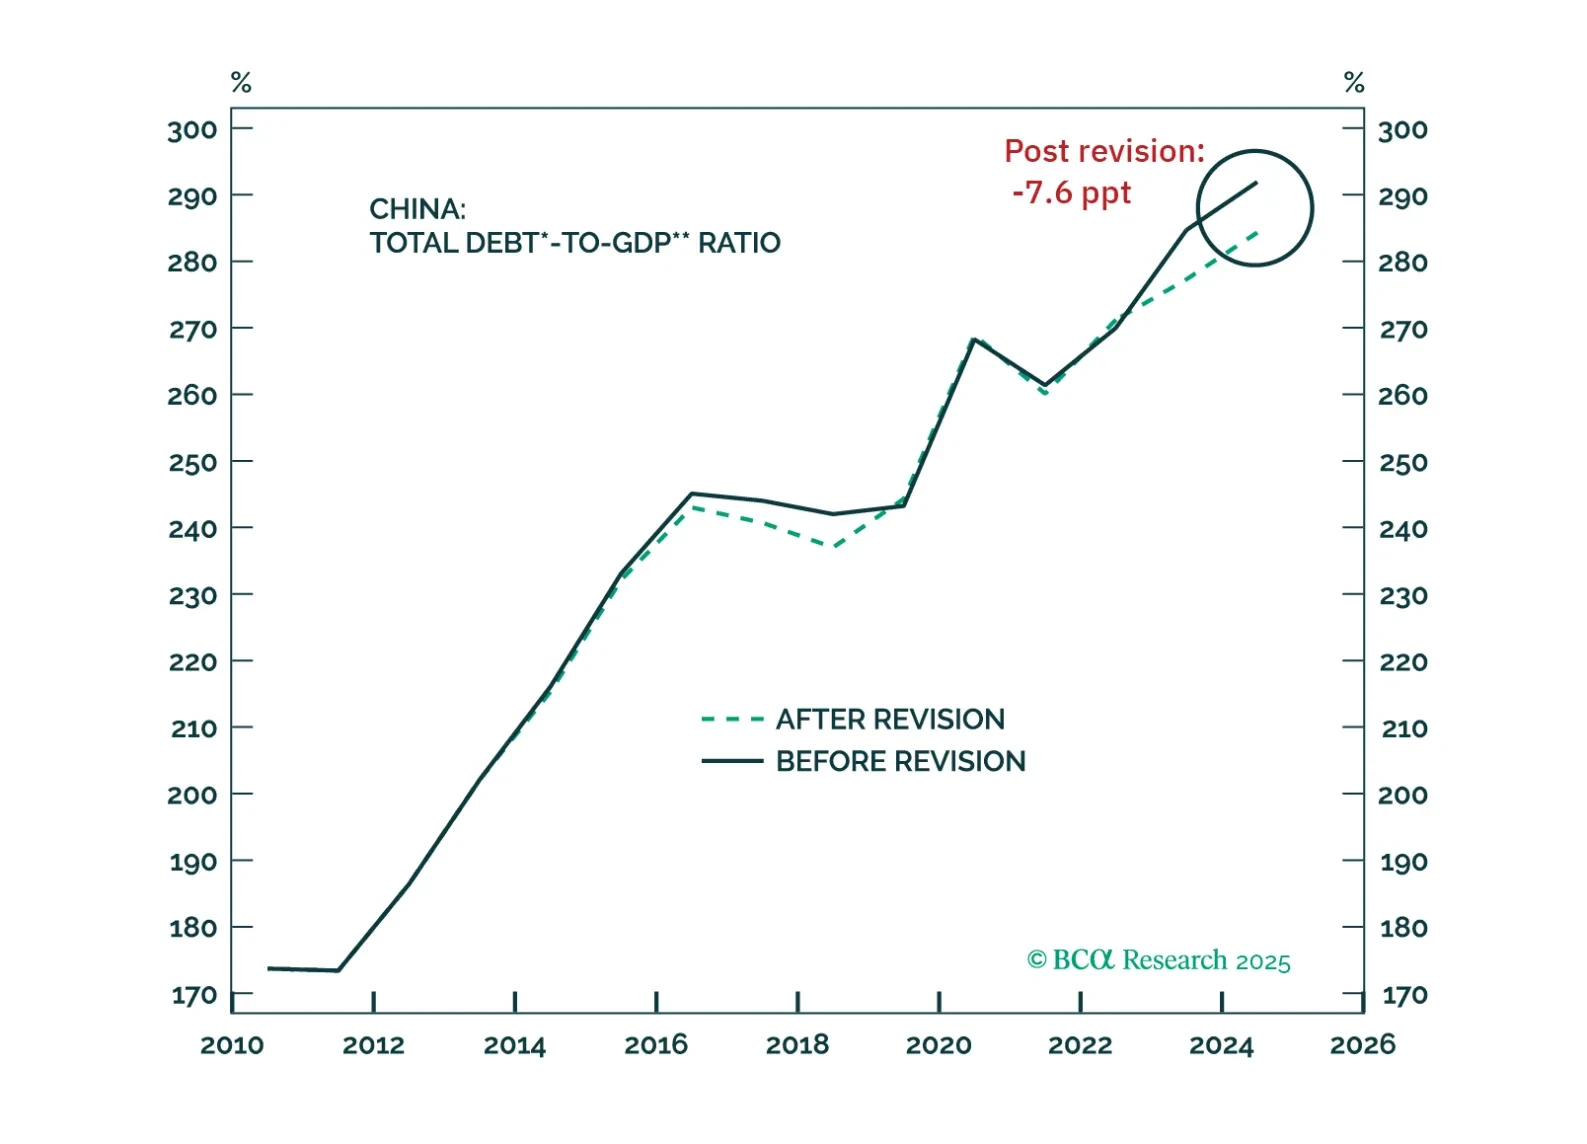
In this week’s report, we present our key takeaways from China's two notable adjustments recently implemented: an upward revision to its 2023 GDP and the reduction of the USD weighting in the RMB Exchange Rate Index.
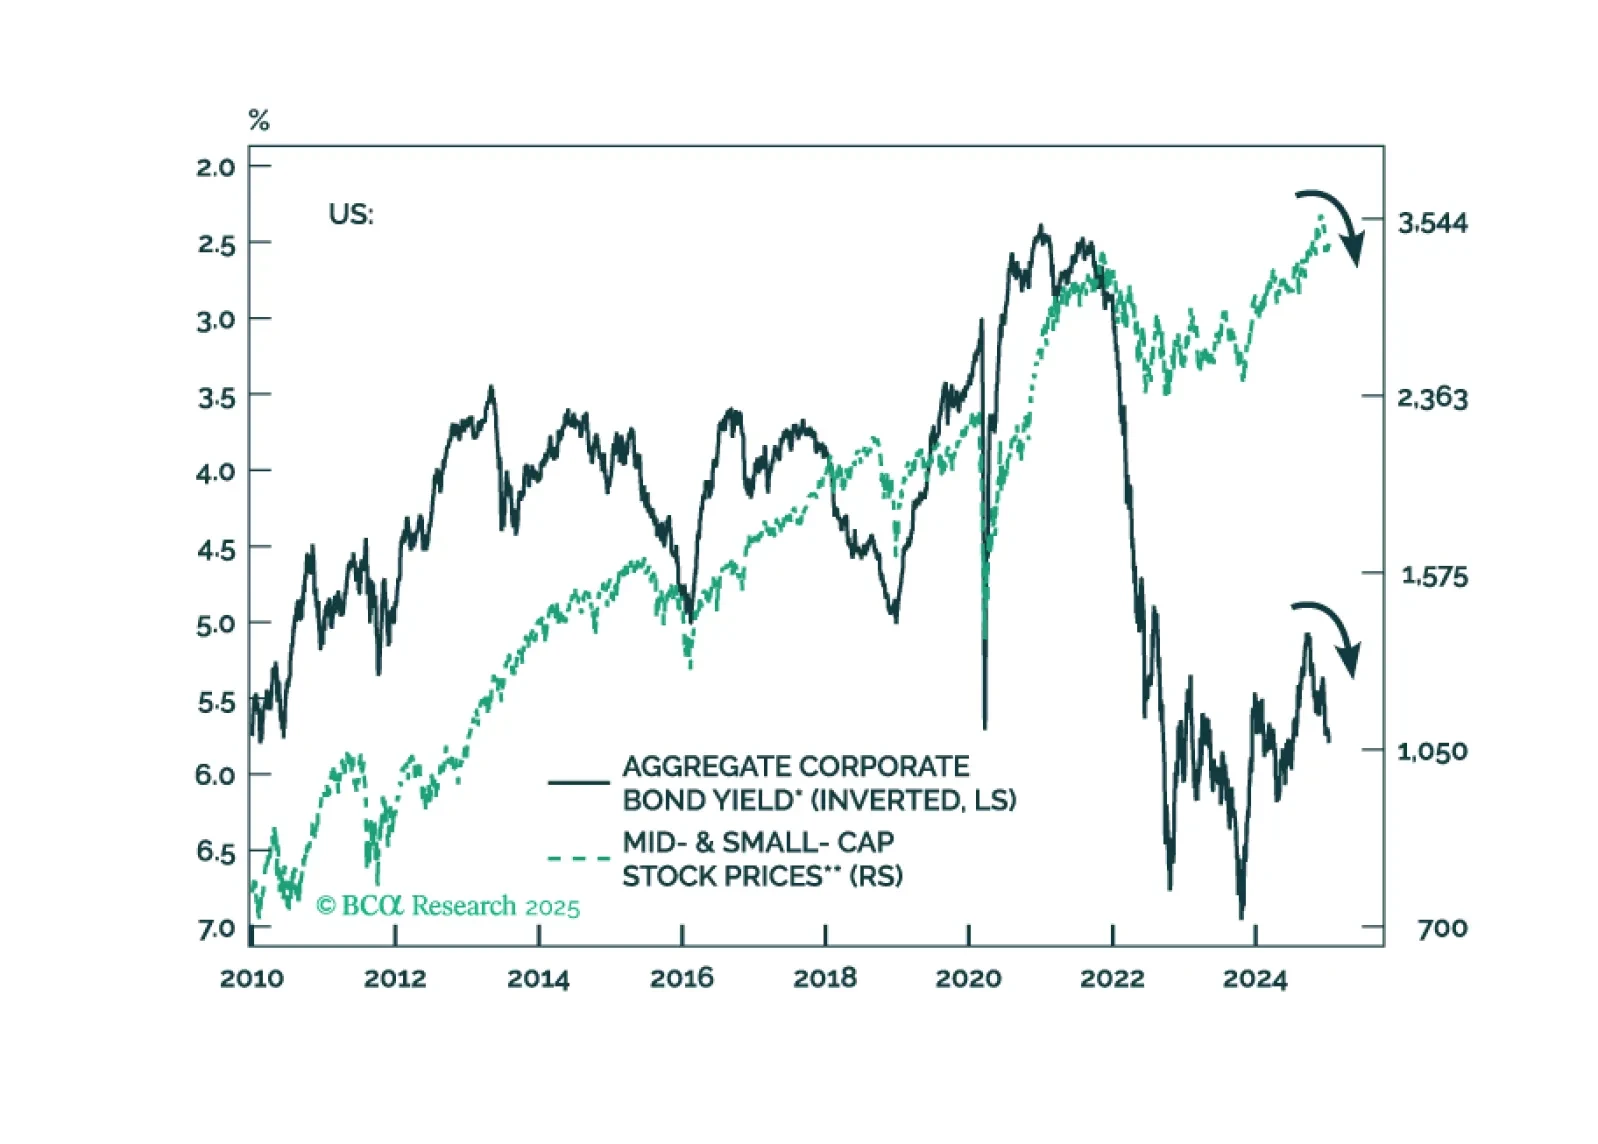
US bond yields will move higher, unleashing a storm in global financial markets. In the US, rising corporate bond yields will produce a selloff in share prices. In Mainstream EM, rising domestic and USD bond yields will weigh on share prices.
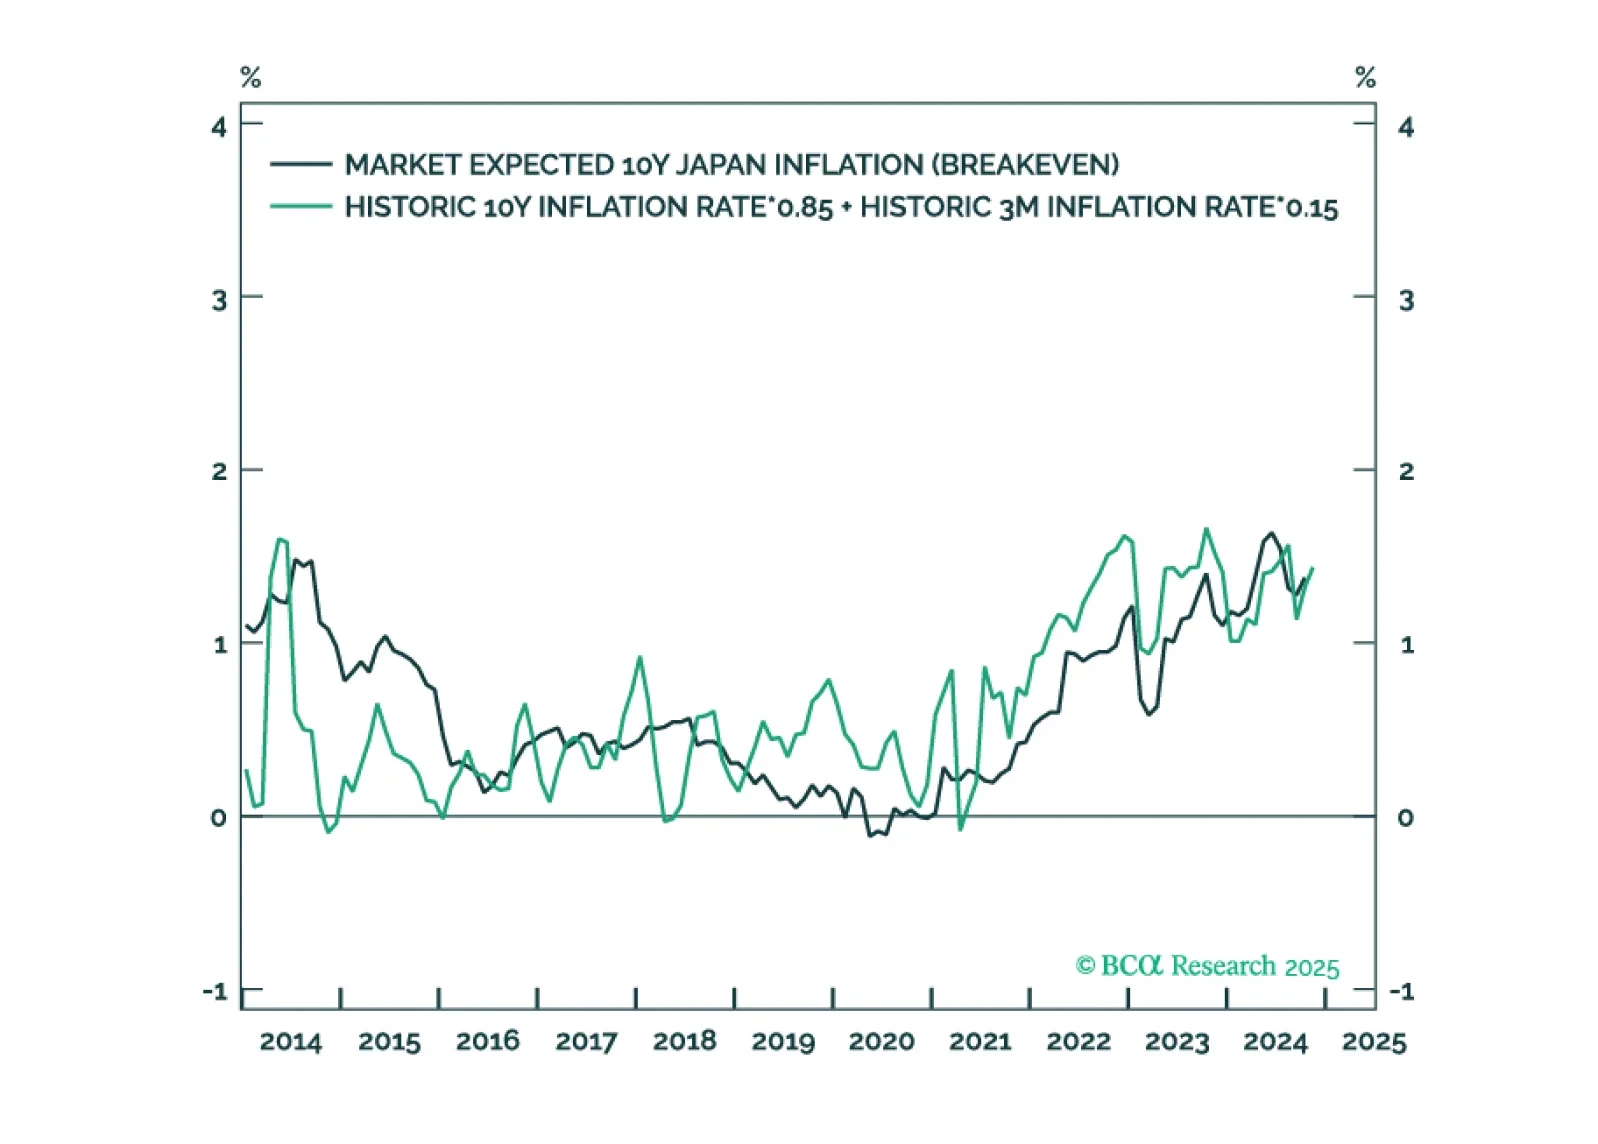
In most developed economies, rising inflation expectations will lift them further above the 2 percent target, limiting the scope for further interest rate cuts. But in Japan, rising inflation expectations will lift them up to the BoJ’s 2 percent target, removing the BoJ’s justification for its zero-interest rate policy. The normalisation of Japan’s monetary policy poses a big structural risk to stocks because Japan has been the main source of financial market liquidity, and thereby, of rising stock market valuations. From a timing perspective though, wait until the complexities of the price trends in USD/JPY and/or Nasdaq versus 30-year T-bond have collapsed. Plus: go tactically long copper.
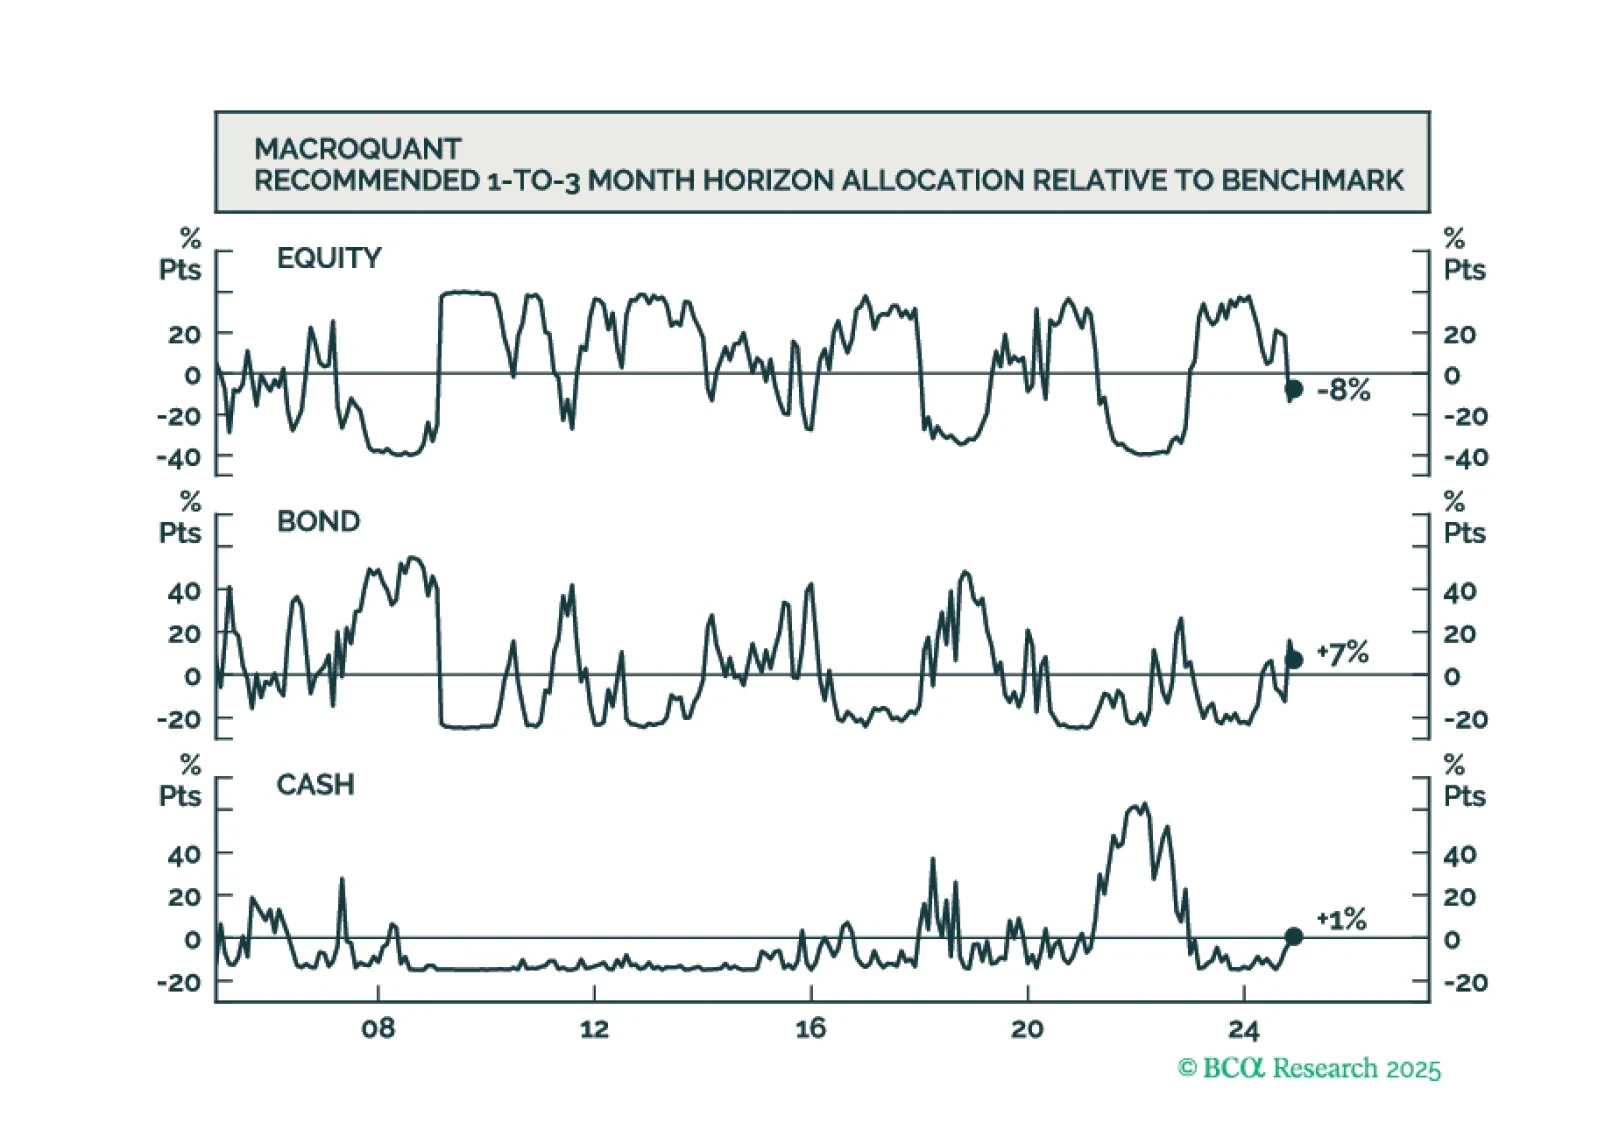
The latest version of the MacroQuant model sees the near-term risks to stocks as slightly tilted to the downside. It is neutral on bond duration and expects the US dollar to continue strengthening in the near term.
Our last publication of the year lets the charts do the talking about why we think the consumer post-pandemic momentum is fading along with the labor market.
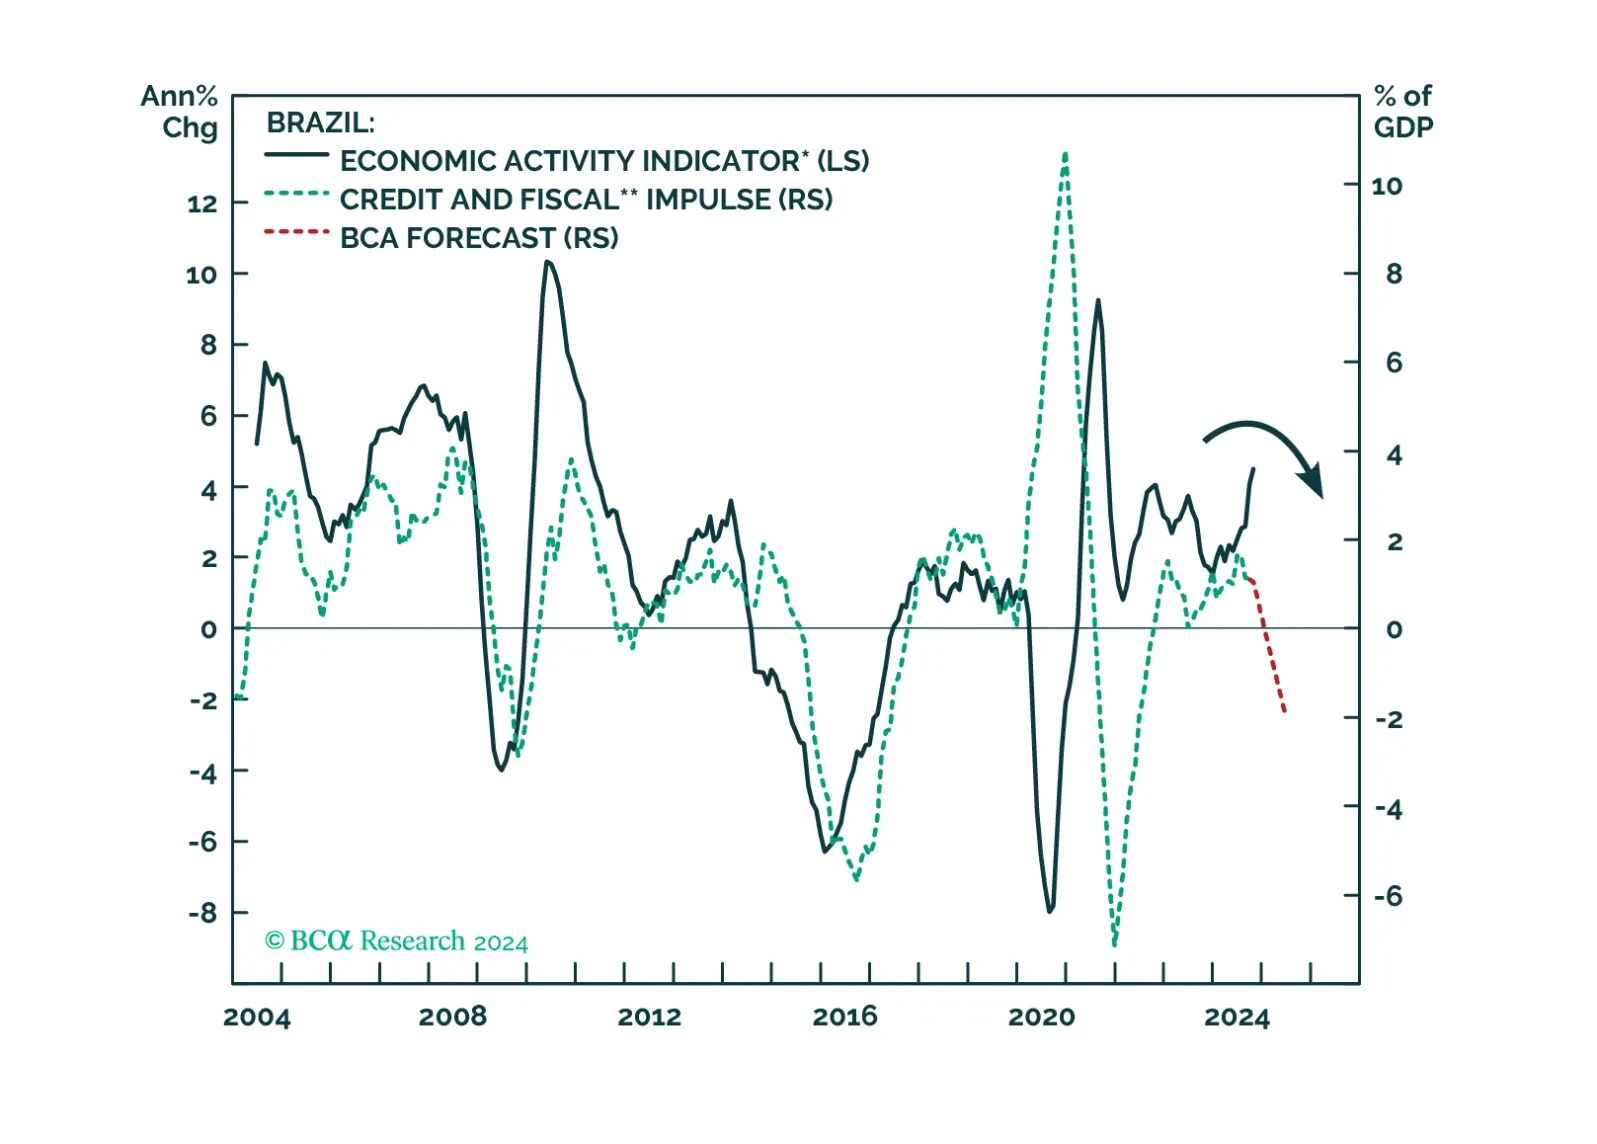
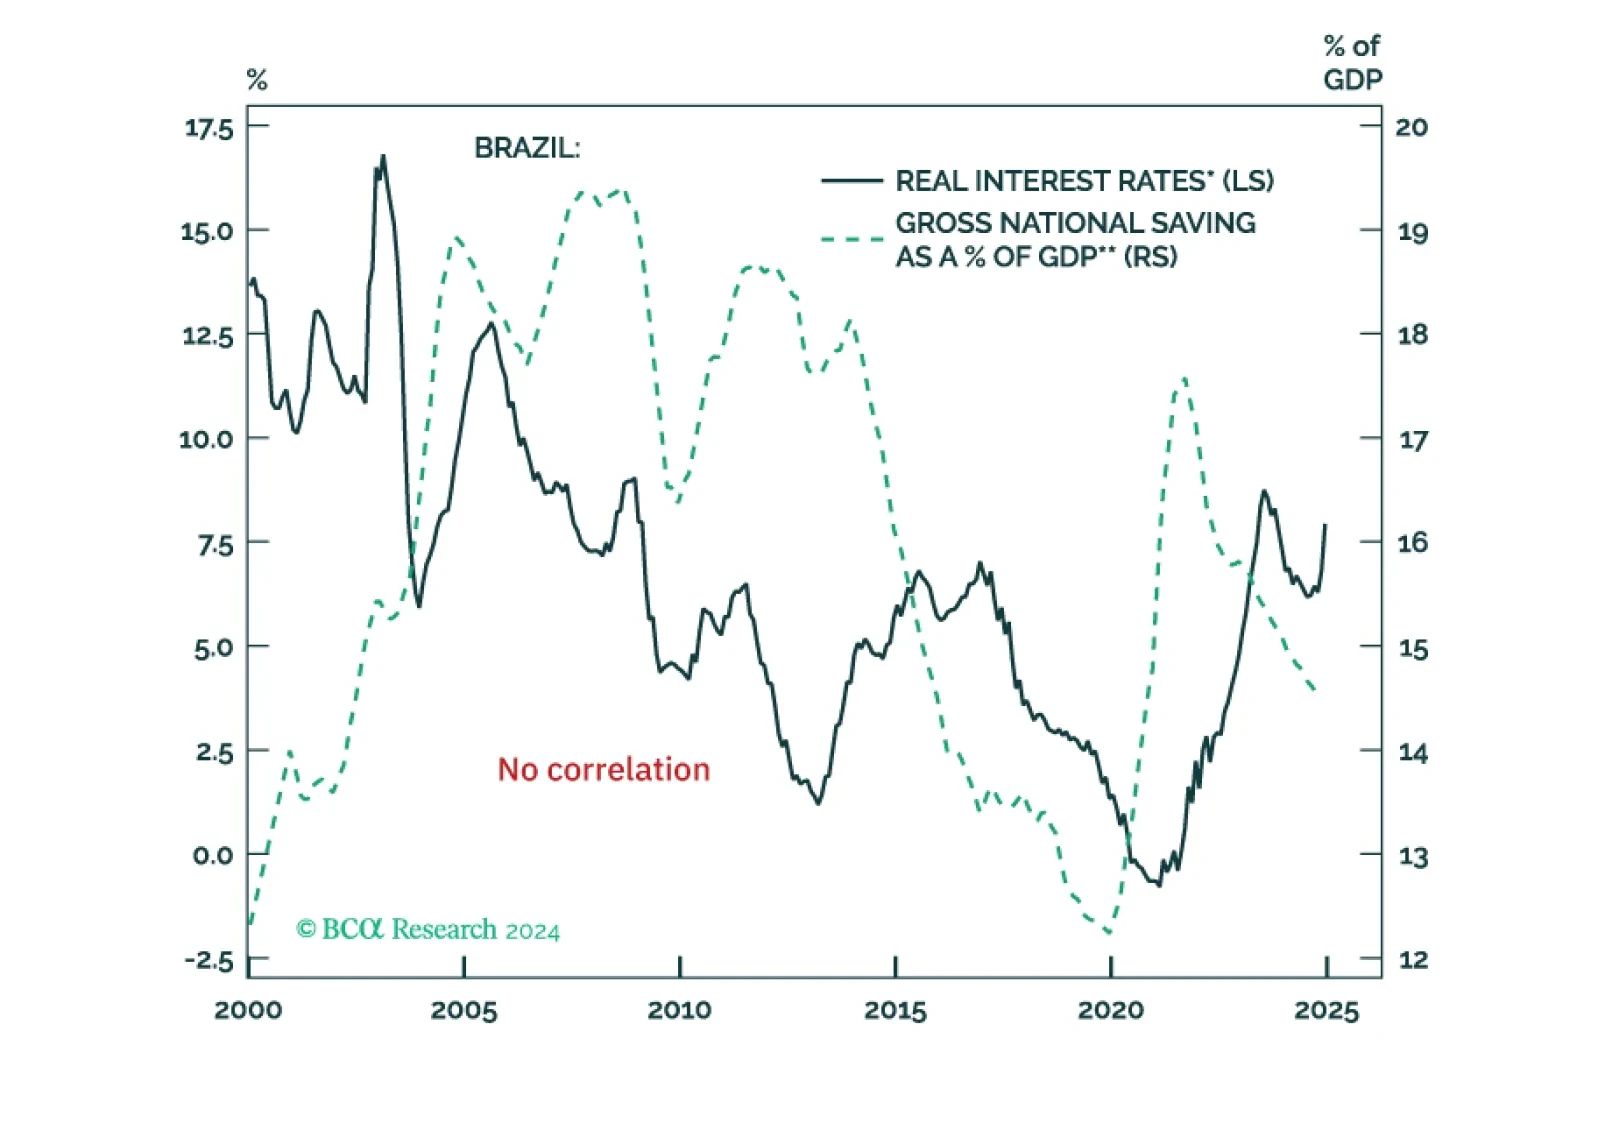
Any additional fiscal tightening and further rate hikes might serve as a band-aid, but not a cure, to Brazilian markets. The country’s risk assets and the currency will continue to face headwinds from an impending recession, a strengthening USD, weak commodity prices, and worsening public debt dynamics. Investors should fade out any relief rallies in Brazilian markets for now.