CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
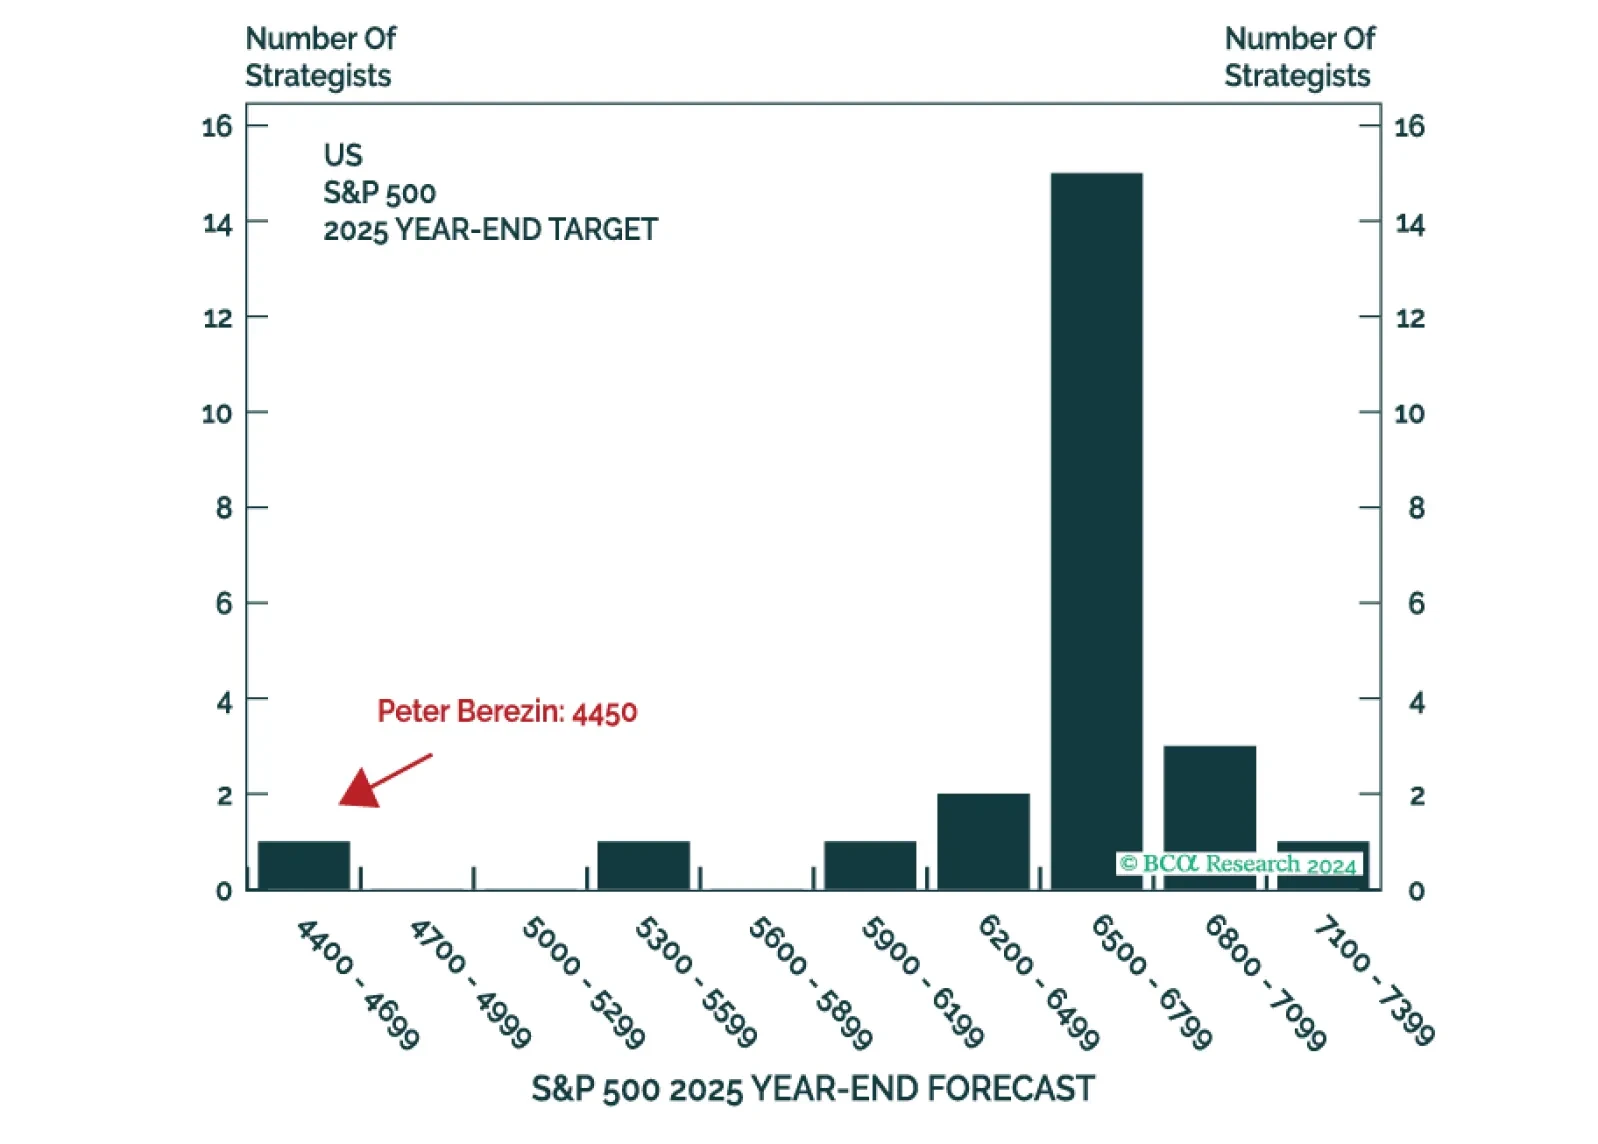
This is the time of the year when strategists are busy sending out their annual outlooks. Here on the Global Investment Strategy team, we decided to go one step further. Rather than pontificating about what could happen in 2025, we decided to harness the power of the multiverse to tell you what did happen (in at least one highly representative timeline). Next week, please join me for a Webcast on Tuesday, December 17 at 10:30 AM EST (3:30 PM GMT, 4:30 PM CET) to discuss the economy and financial markets. And with that, I will sign off for the year. I wish you and your loved ones a very happy and healthy 2025. We will be back in the first week of January with our MacroQuant Model Update.
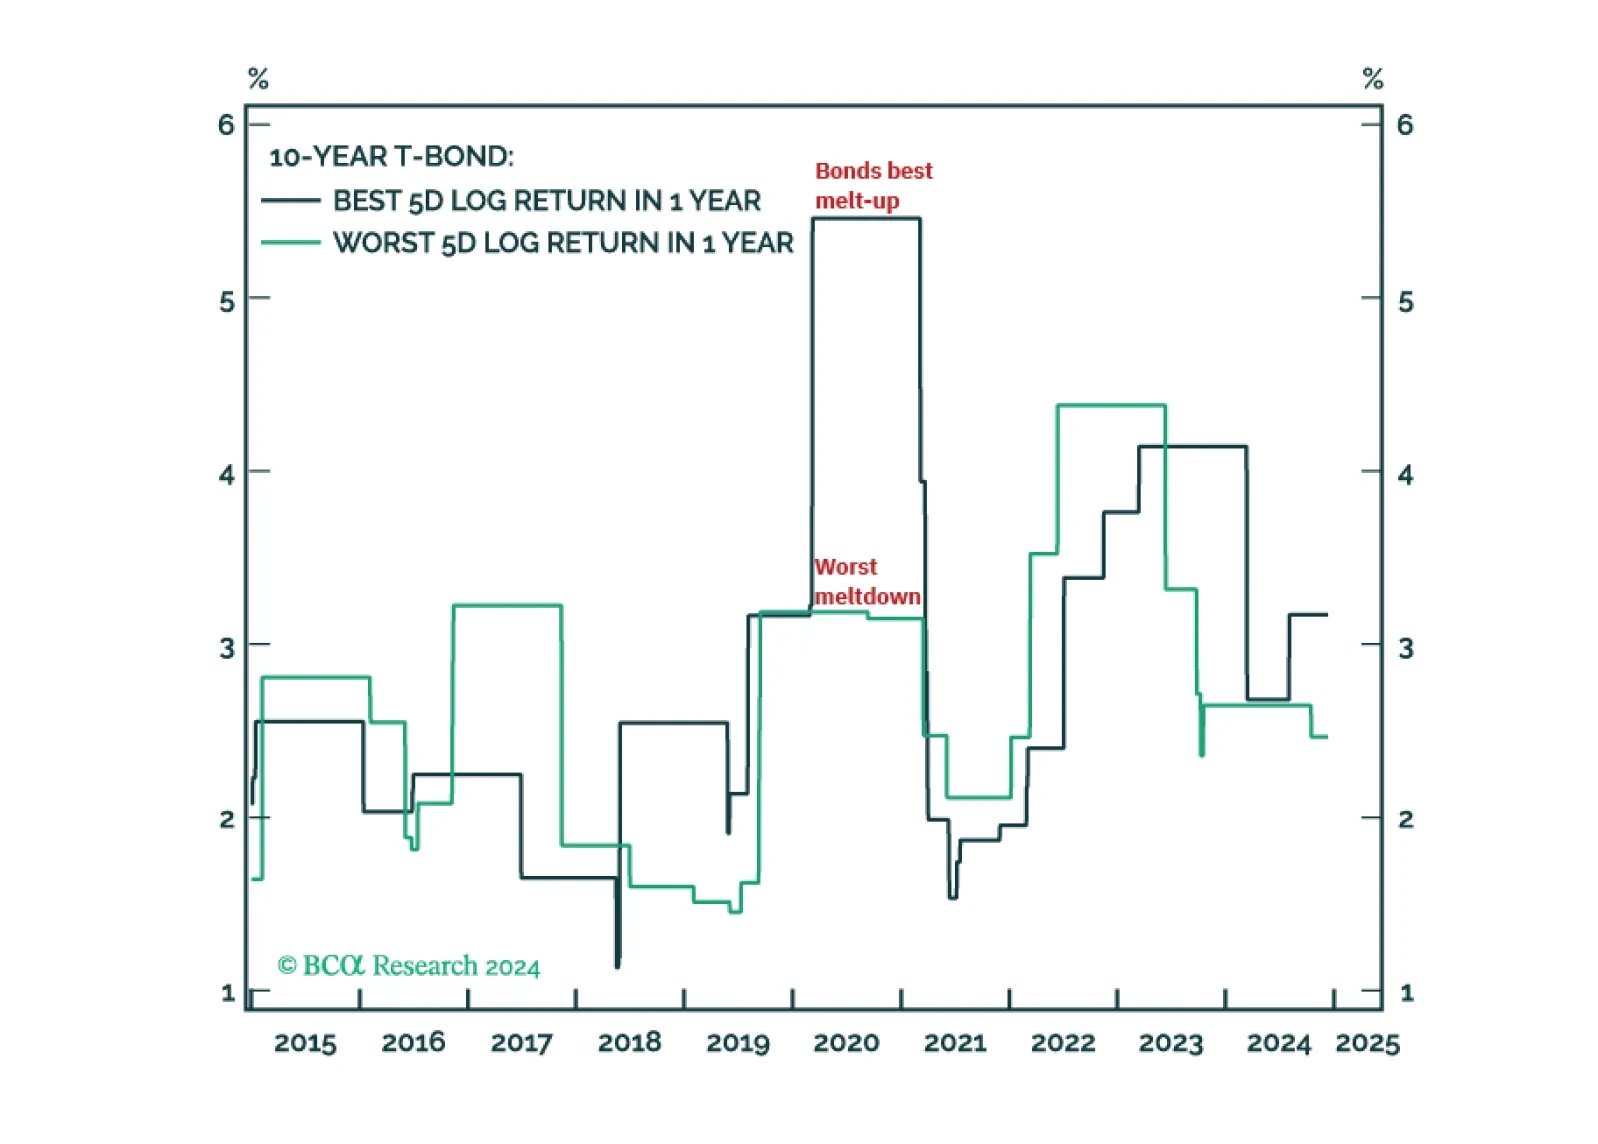
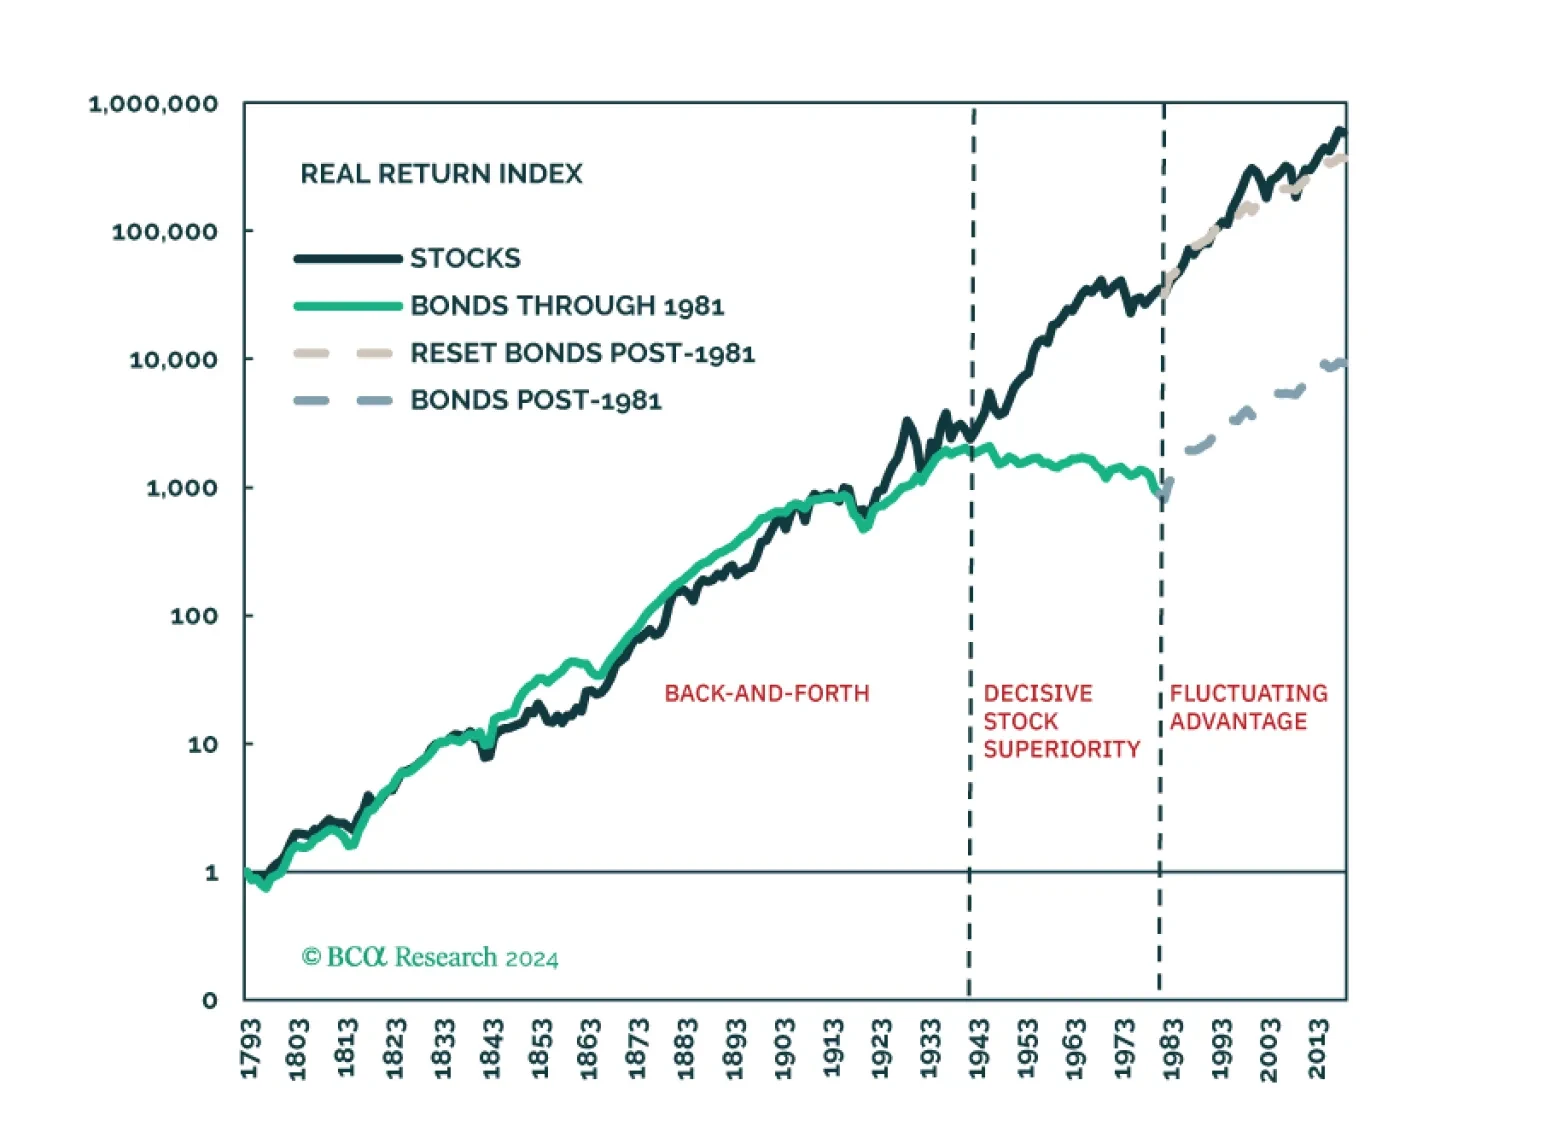
The real reason to own bonds is for their higher propensity to melt up, but anticipating those melt-ups is crucial. We list four indicators to monitor closely in 2025.
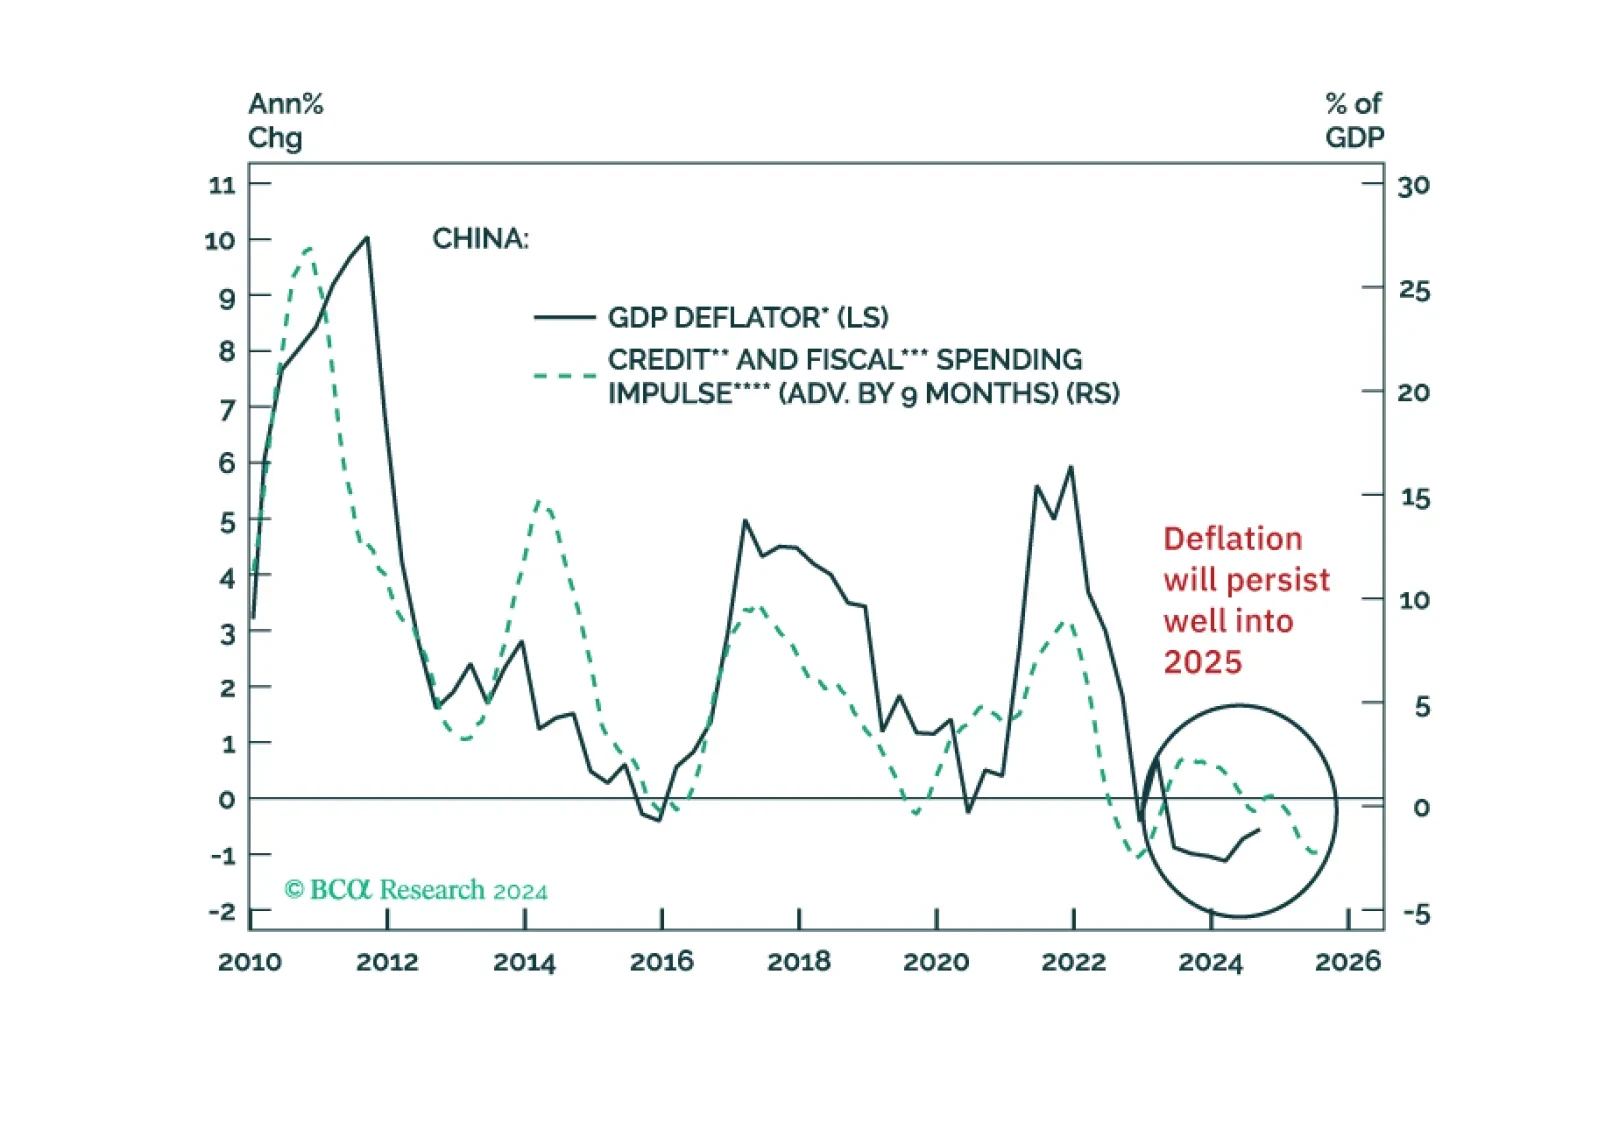
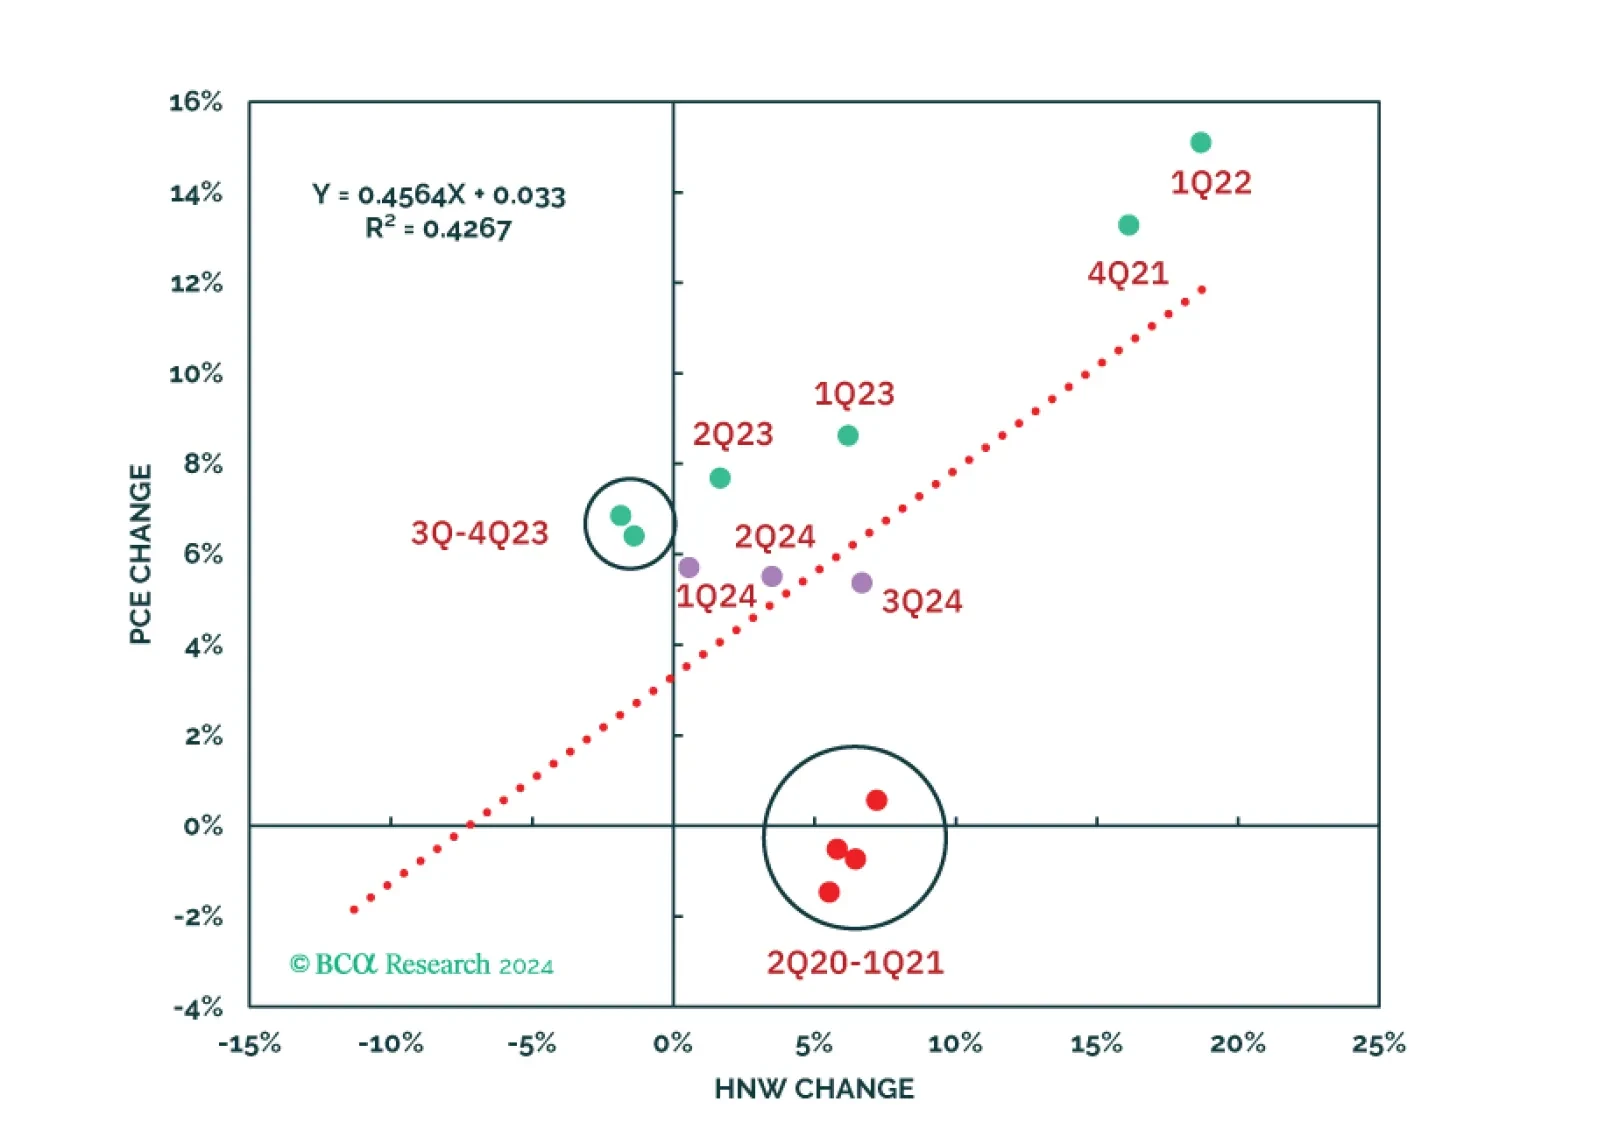
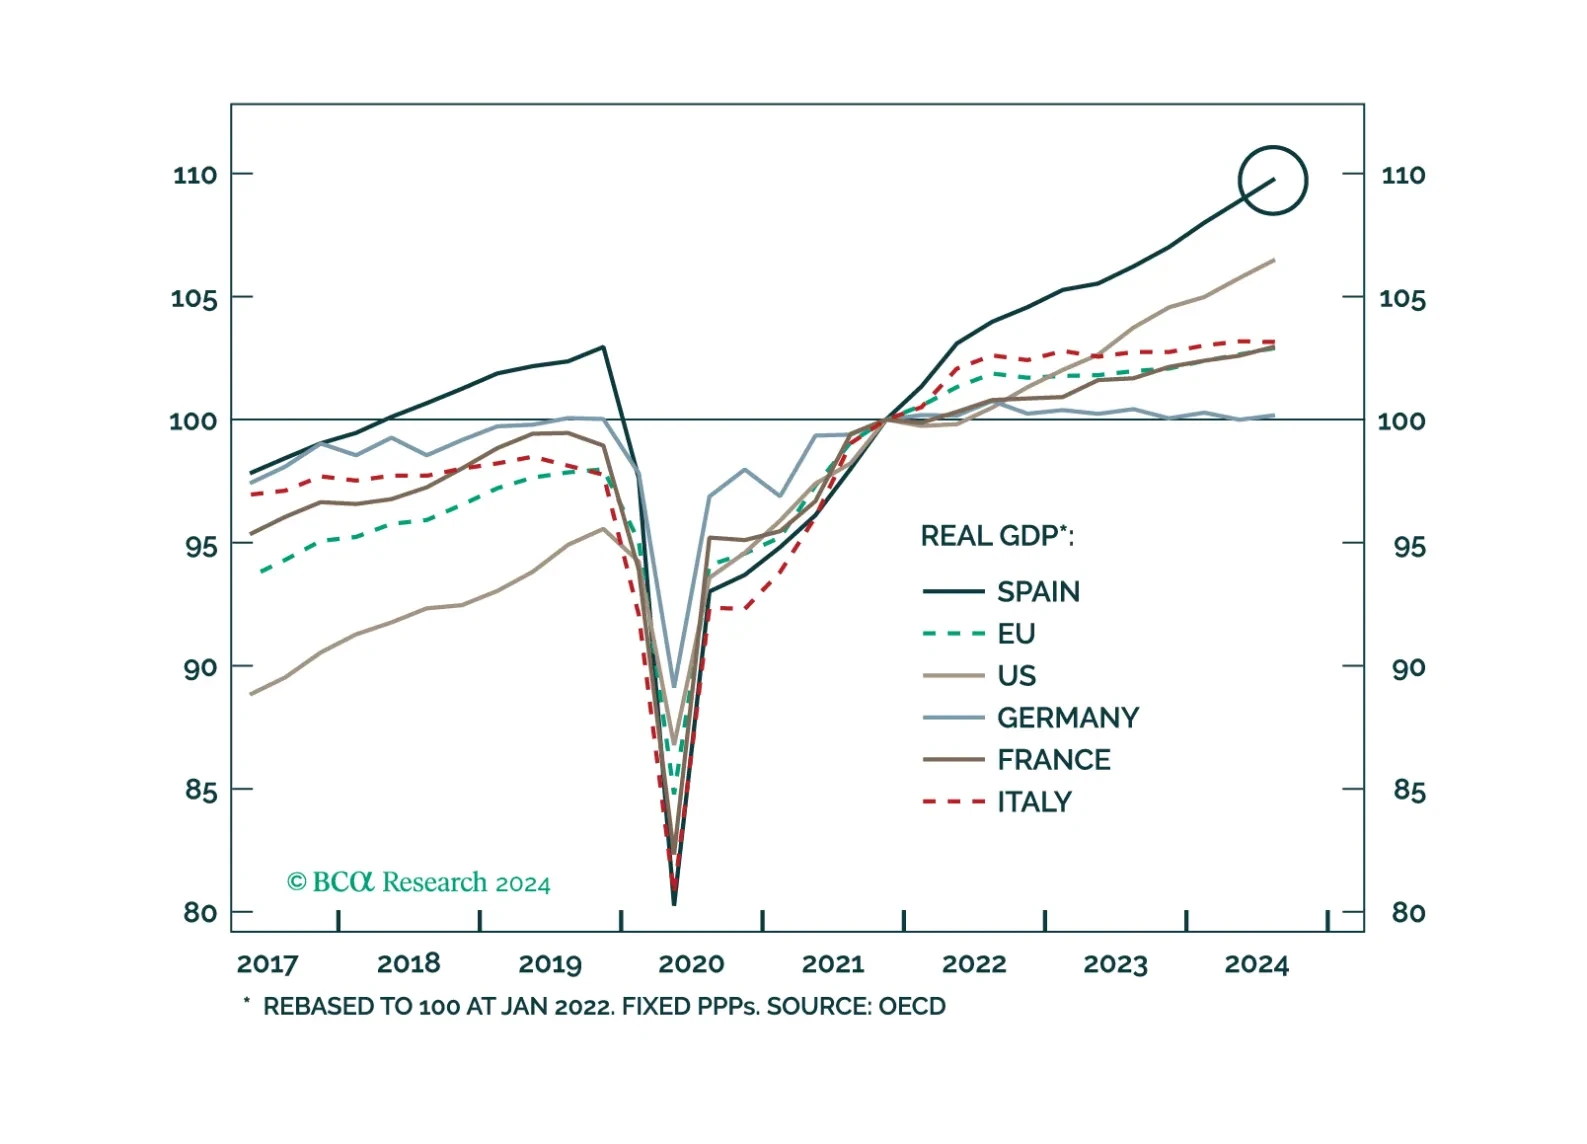
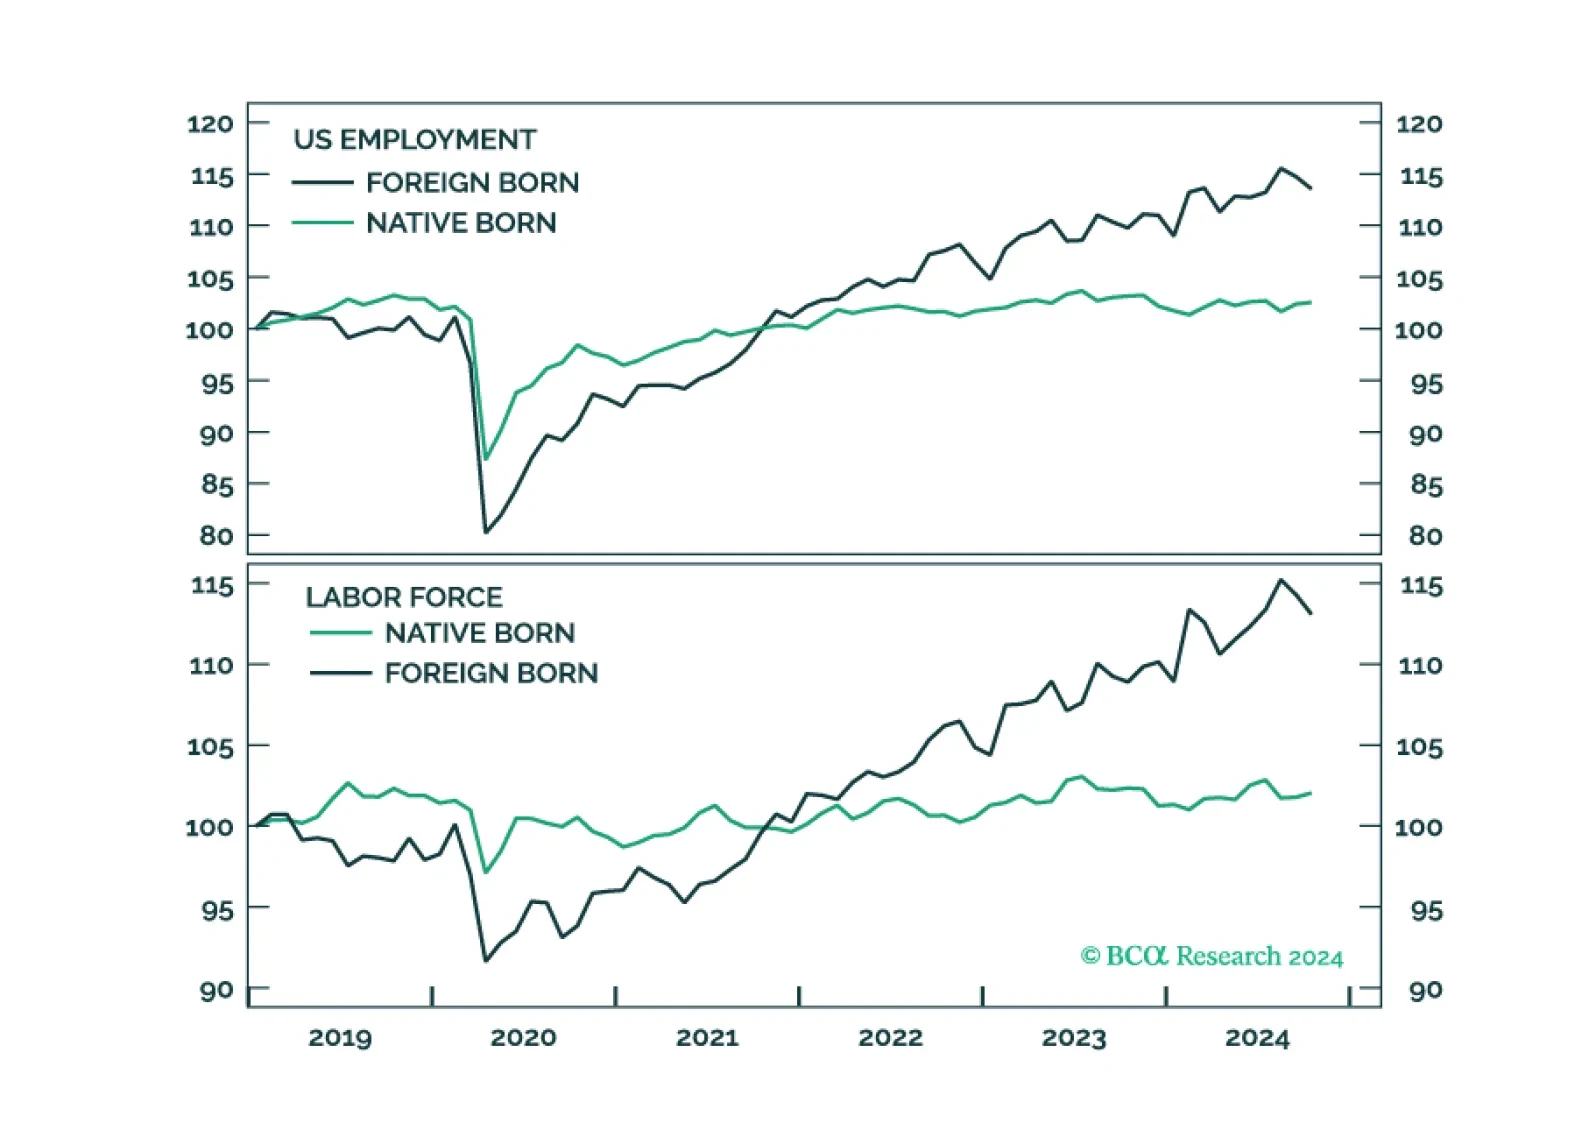
I have been generally sceptical of the reflationary aspects of the so-called Trump trade. If Trump's first term is any guide, lower tax rates will have little impact on business spending while higher tariffs are unlikely to trigger much reshoring of manufacturing activity. Meanwhile, rising debt-service costs could force the Trump administration to cut social spending under the guise of reducing government waste. One open question surrounds immigration. The market consensus seems to be that decreased immigration will lead to a tighter labour market, stoking inflationary pressures in the process.