Latest from BCA Research
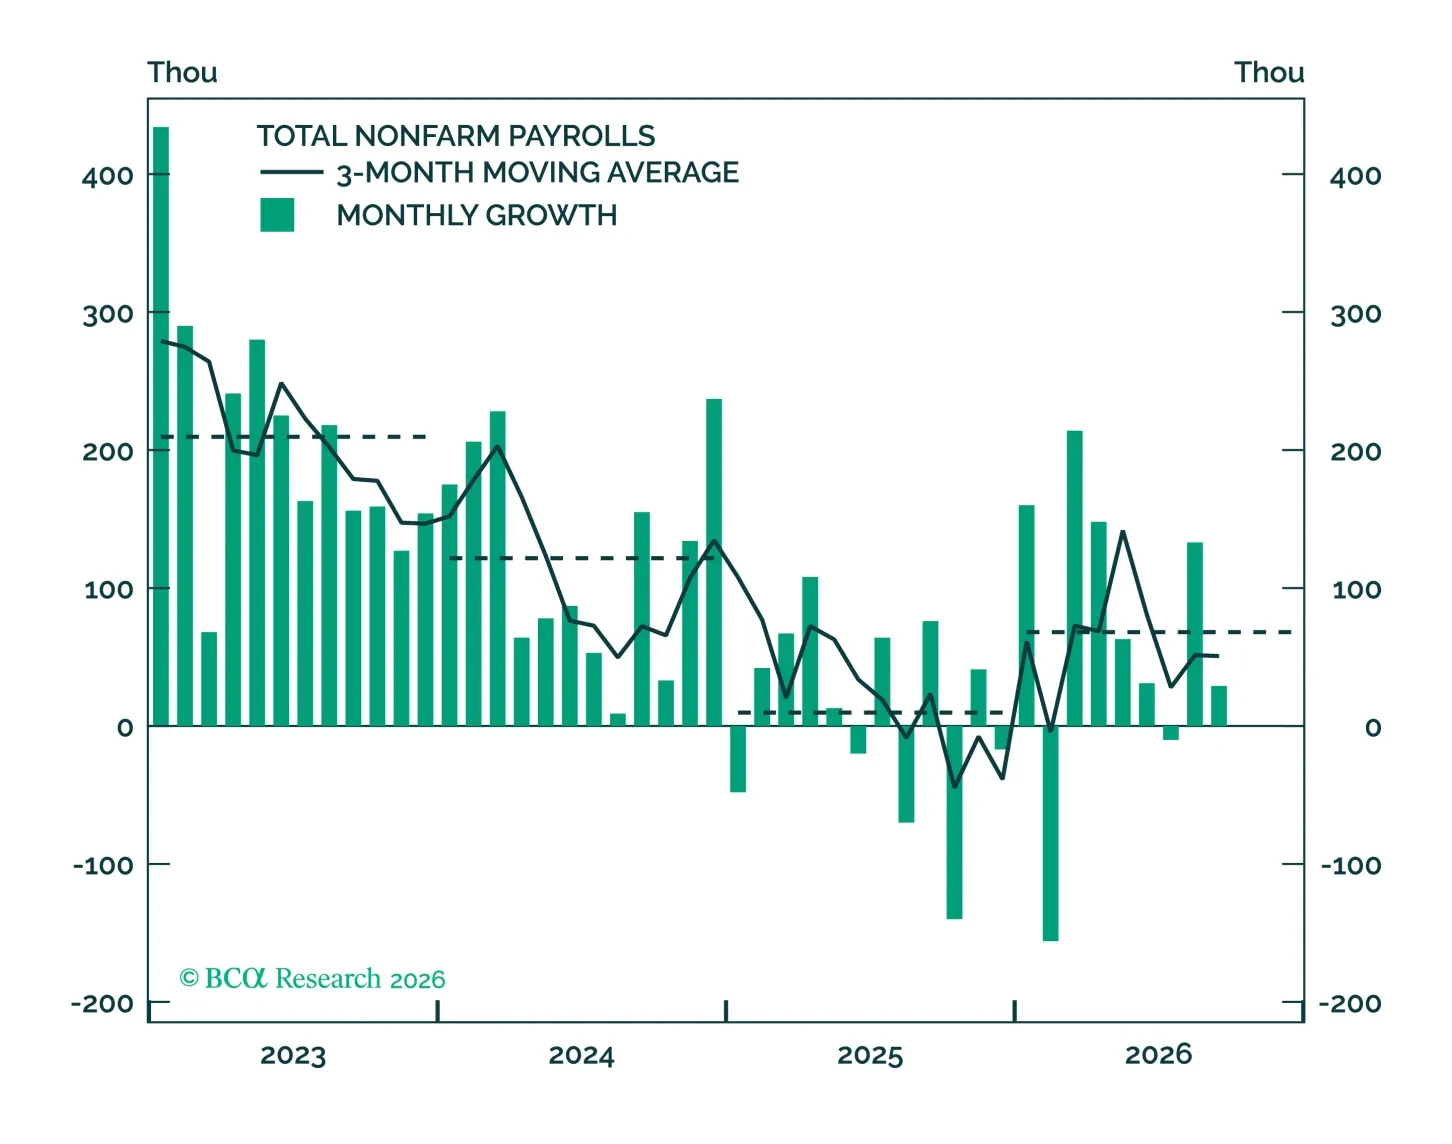
This morning’s jobs report serves to underscore that the labor market is not a source of inflationary pressure and therefore of second-order importance when it comes to the Fed’s near-term decision making.
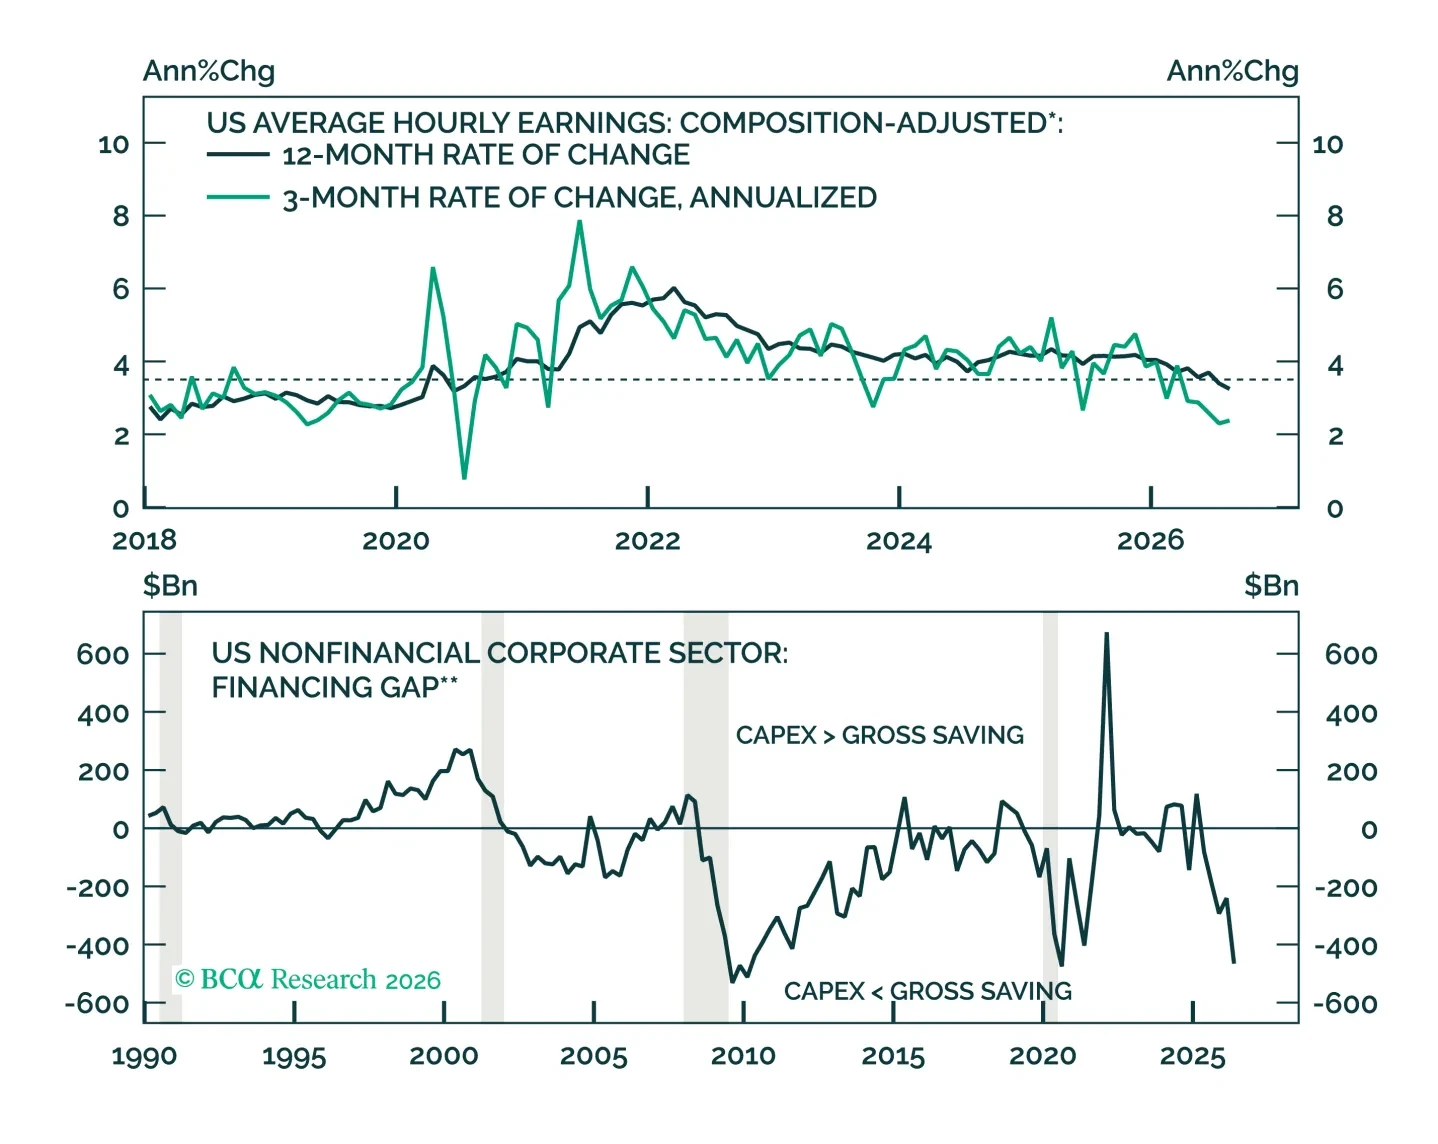
Politics, wars, a global tightening cycle, doubts over AI capex: the wall of worry keeps rising. But the spark that would topple risk assets is missing. Our Q4 FICC outlook explains why to stay long risk, and where the danger lies.
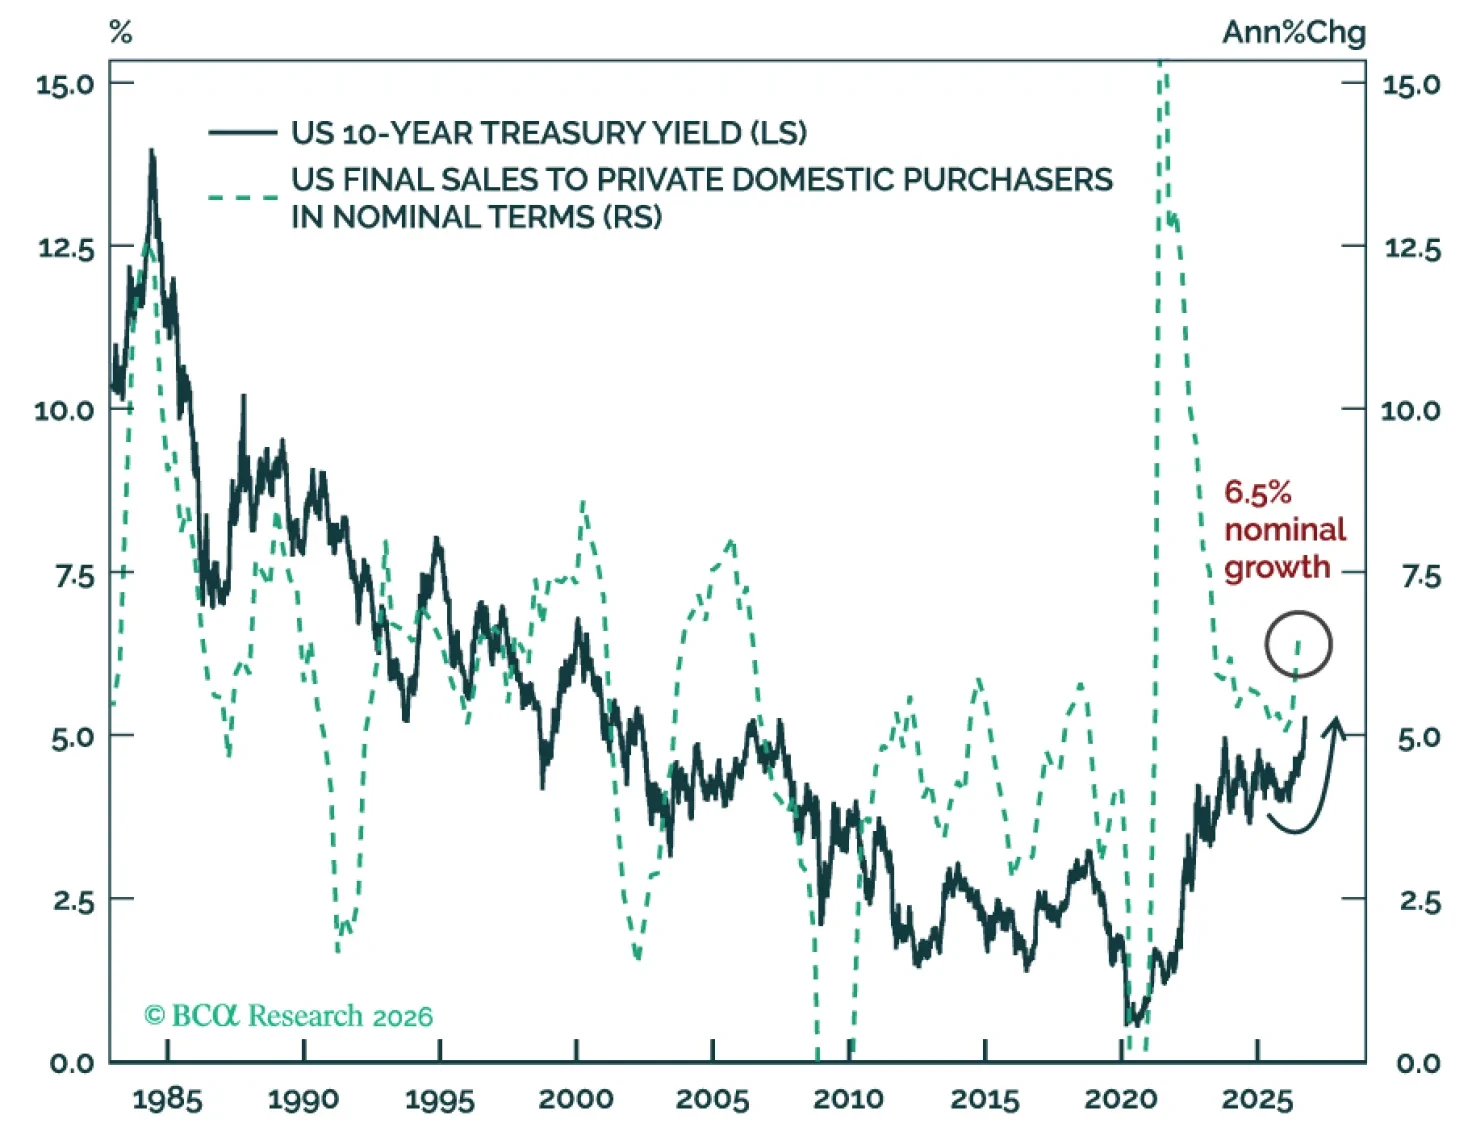
US bonds will likely continue selling off until tighter financial conditions – most plausibly a double-digit decline in the S&P 500 – cool nominal growth. Higher discount rates will threaten US equity valuations before earnings weaken. AI stocks will peak well ahead of AI capex. Remain downbeat on EM stocks.
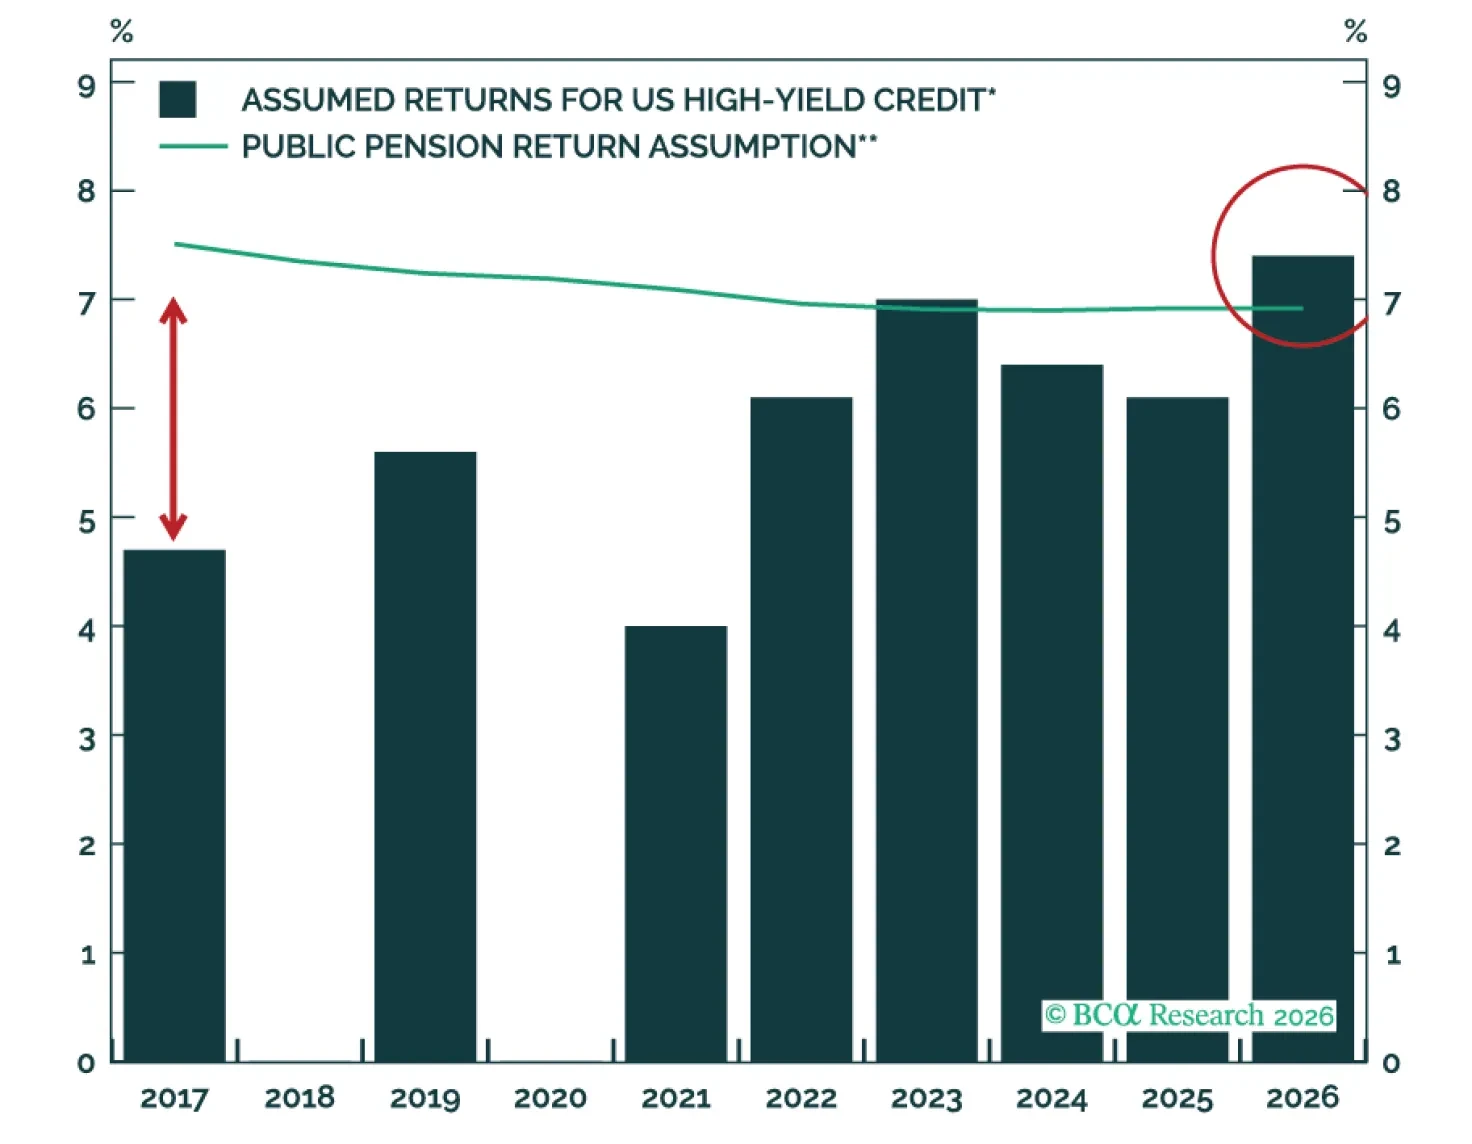
Higher rates have changed the opportunity set. Overweight High-Yield Credit, both within asset allocation and versus Private Credit. Investors are no longer picking up pennies in front of a steamroller.
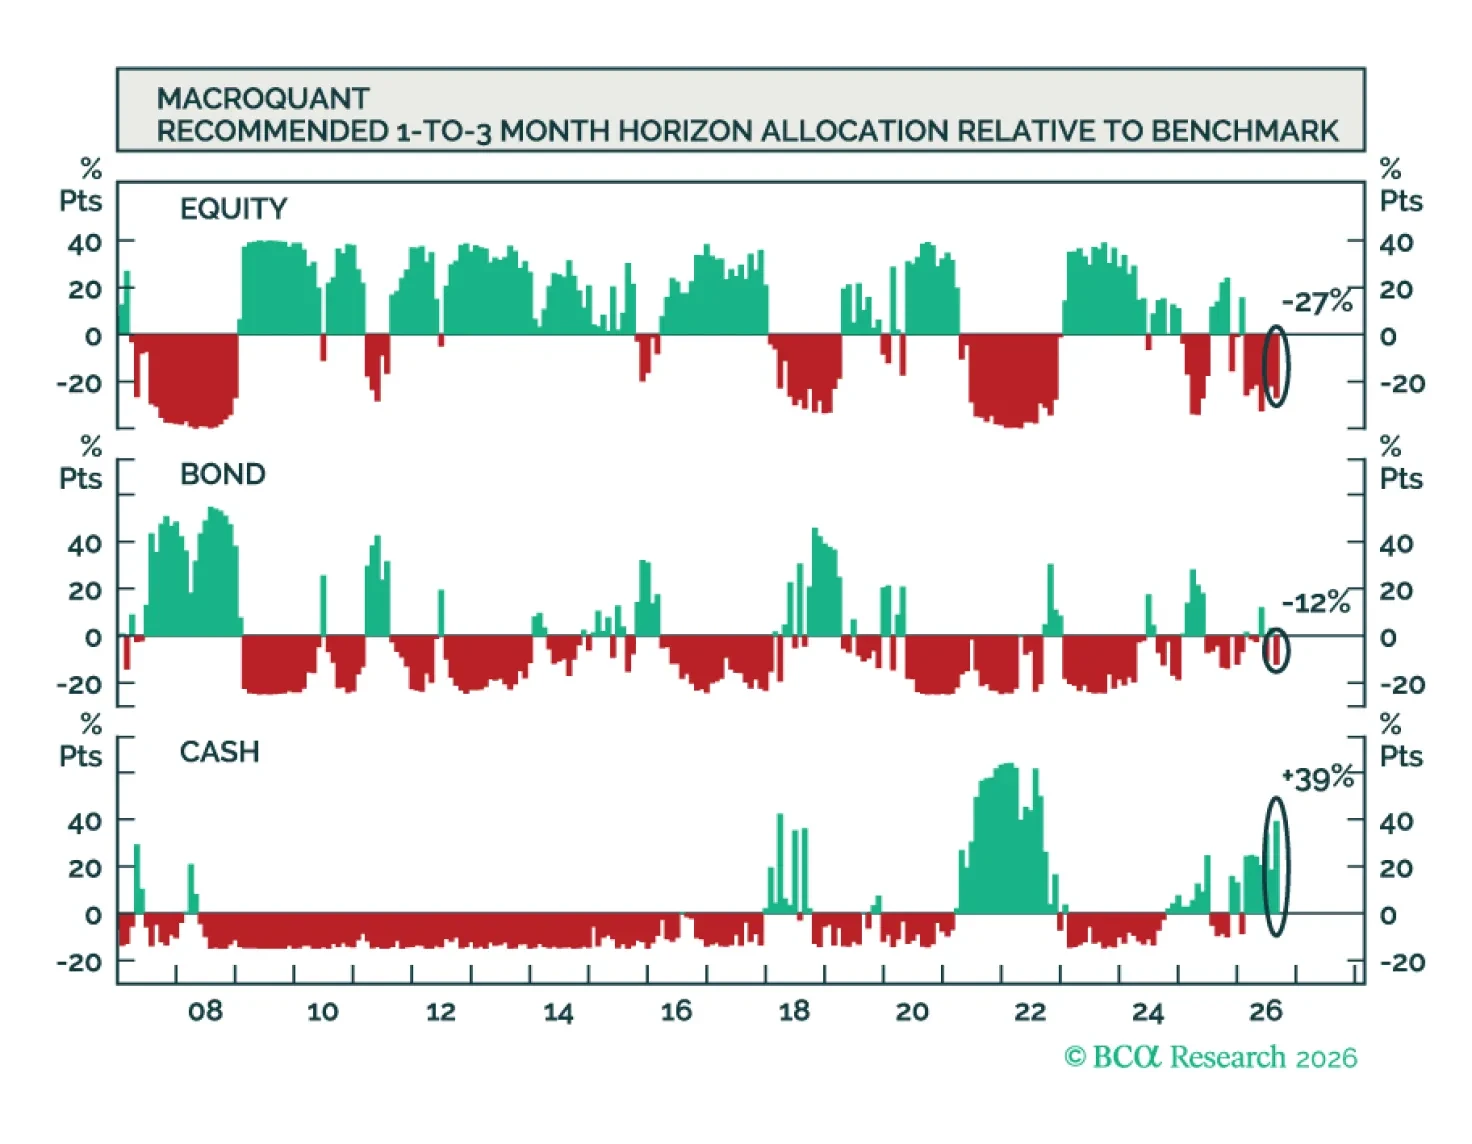
MacroQuant recommends an underweight to equities and bonds, counterbalanced by a significant overweight to cash. The model is very bullish on the US dollar, slightly negative on gold and copper, and positive on oil.
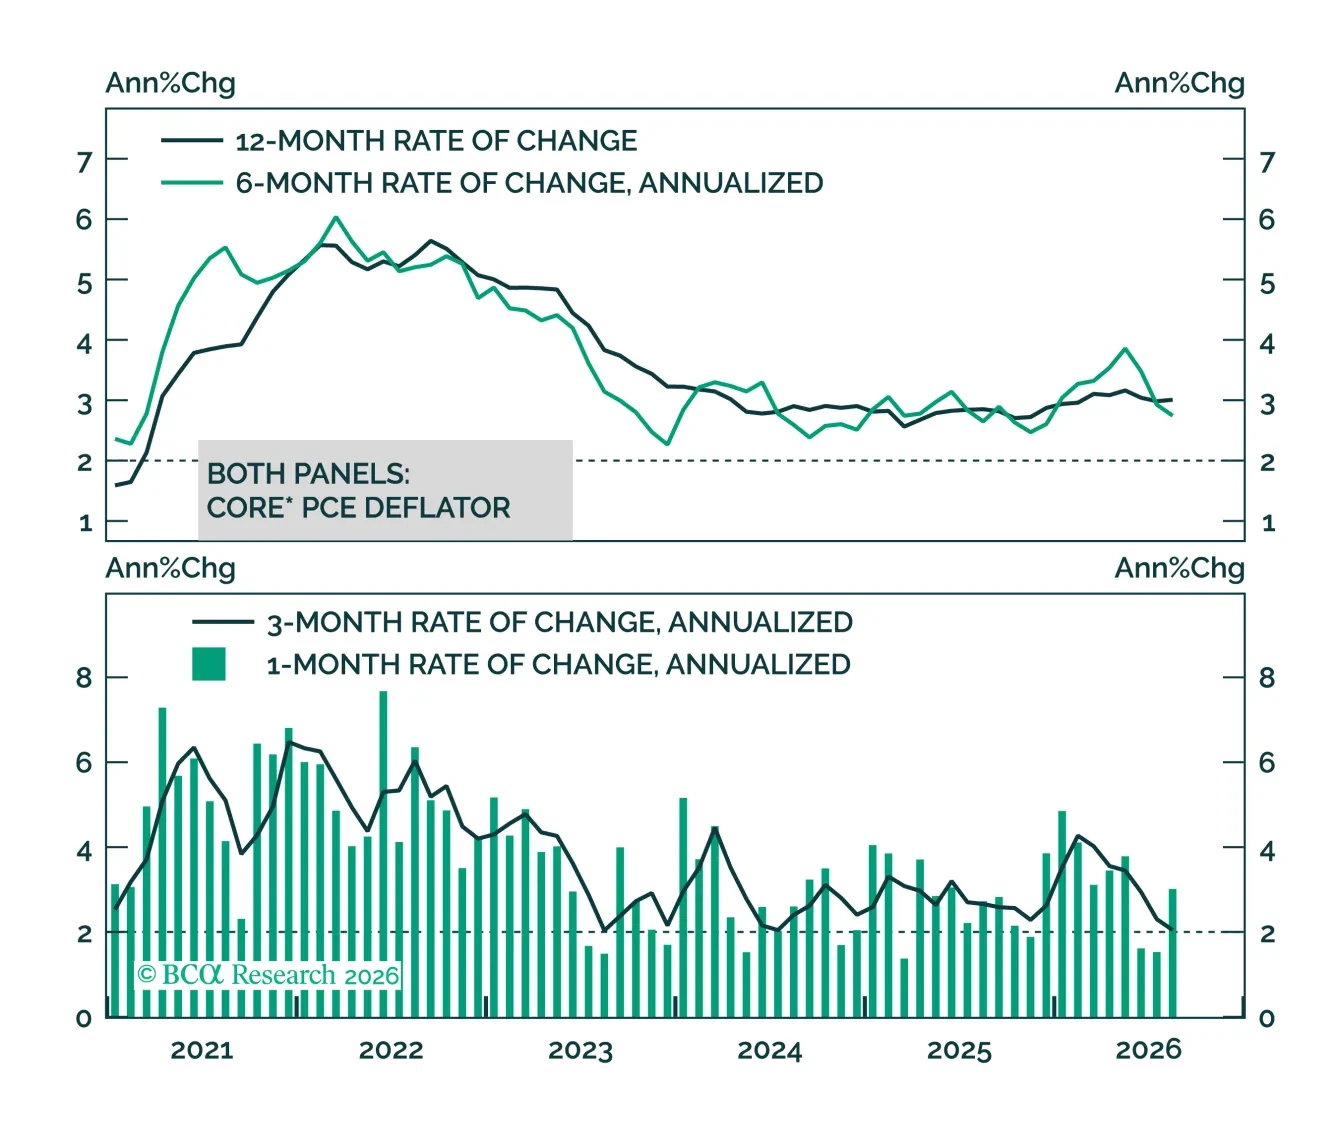
Core US inflation is still running above target. But this morning’s data revisions reveal that the gap is not nearly as large as it appeared yesterday.
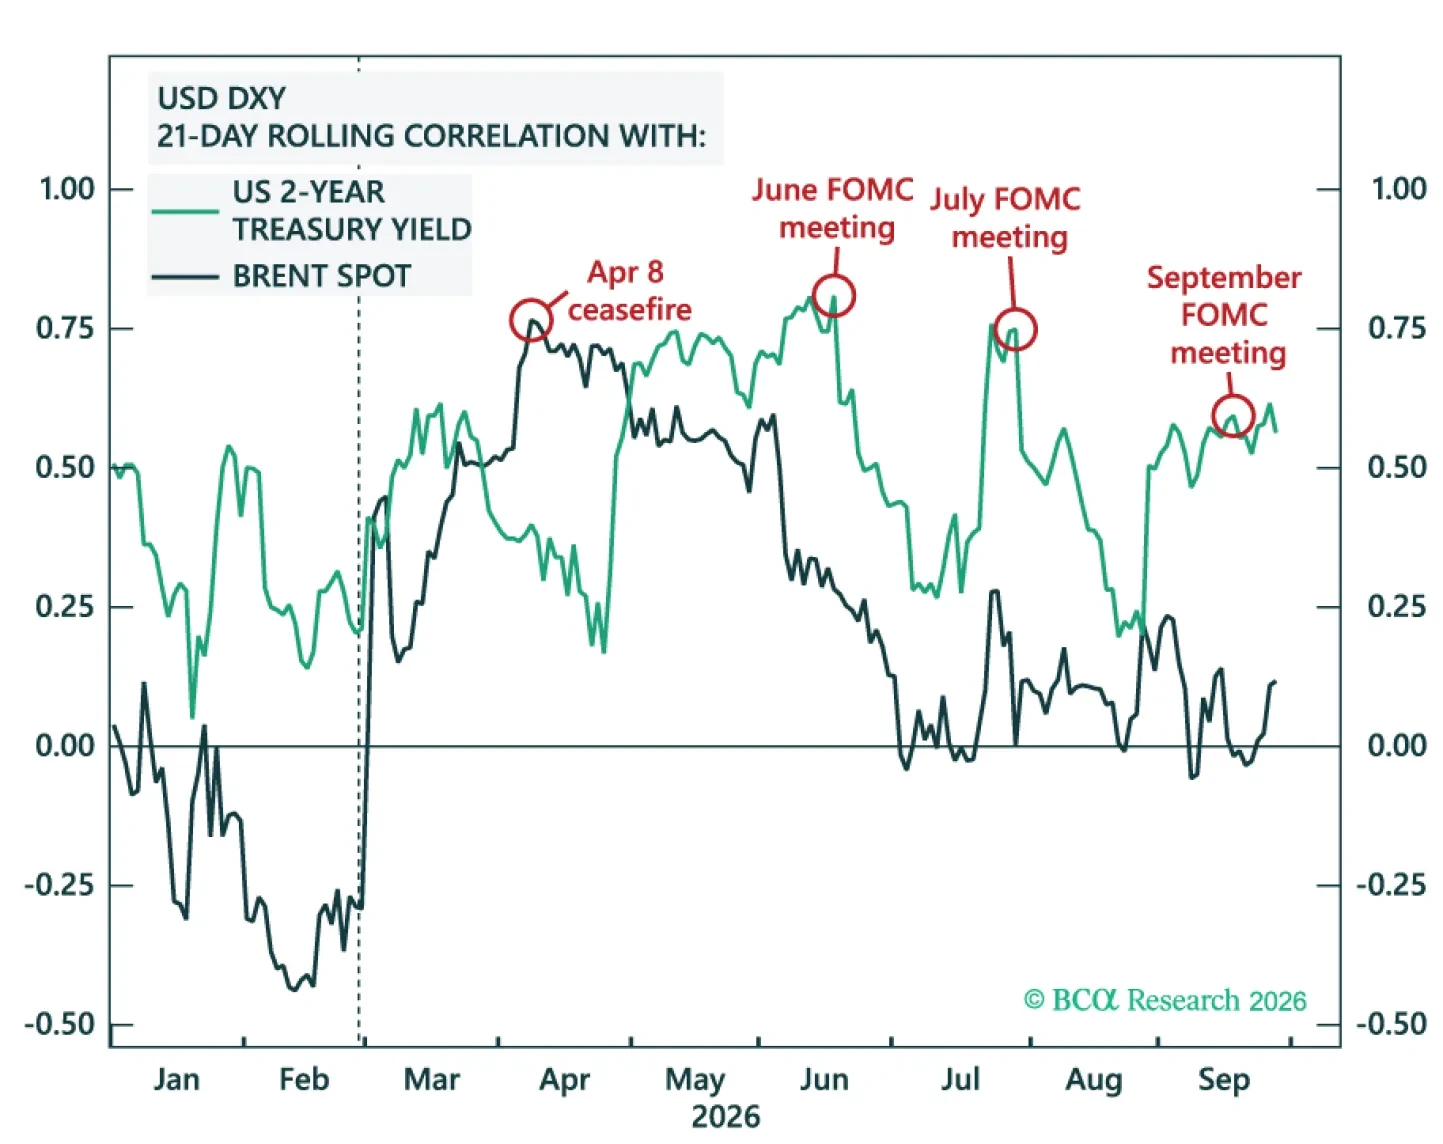
Global capex is driving the strongest industrial cycle since 2021. The US is best positioned to capture the gains and to weather near-term risks, supporting widening real-rate differentials and favoring continued upside in the dollar in the coming months.
Most investors would argue that Europe overregulates relative to the US. However, that was not always the case. Political Scientist David Vogel of University of California, Berkeley, posited that the two economies shifted models in the 1990s. Prior to that decade, the US led health, safety, and environmental regulations, having far more stringent rules than Europe. As a prominent example of this, it was the US that quickly banned all non-essential CFCs, chemicals that harm the ozone layer, whereas European governments did not act initially, favoring their industries while awaiting evidence.
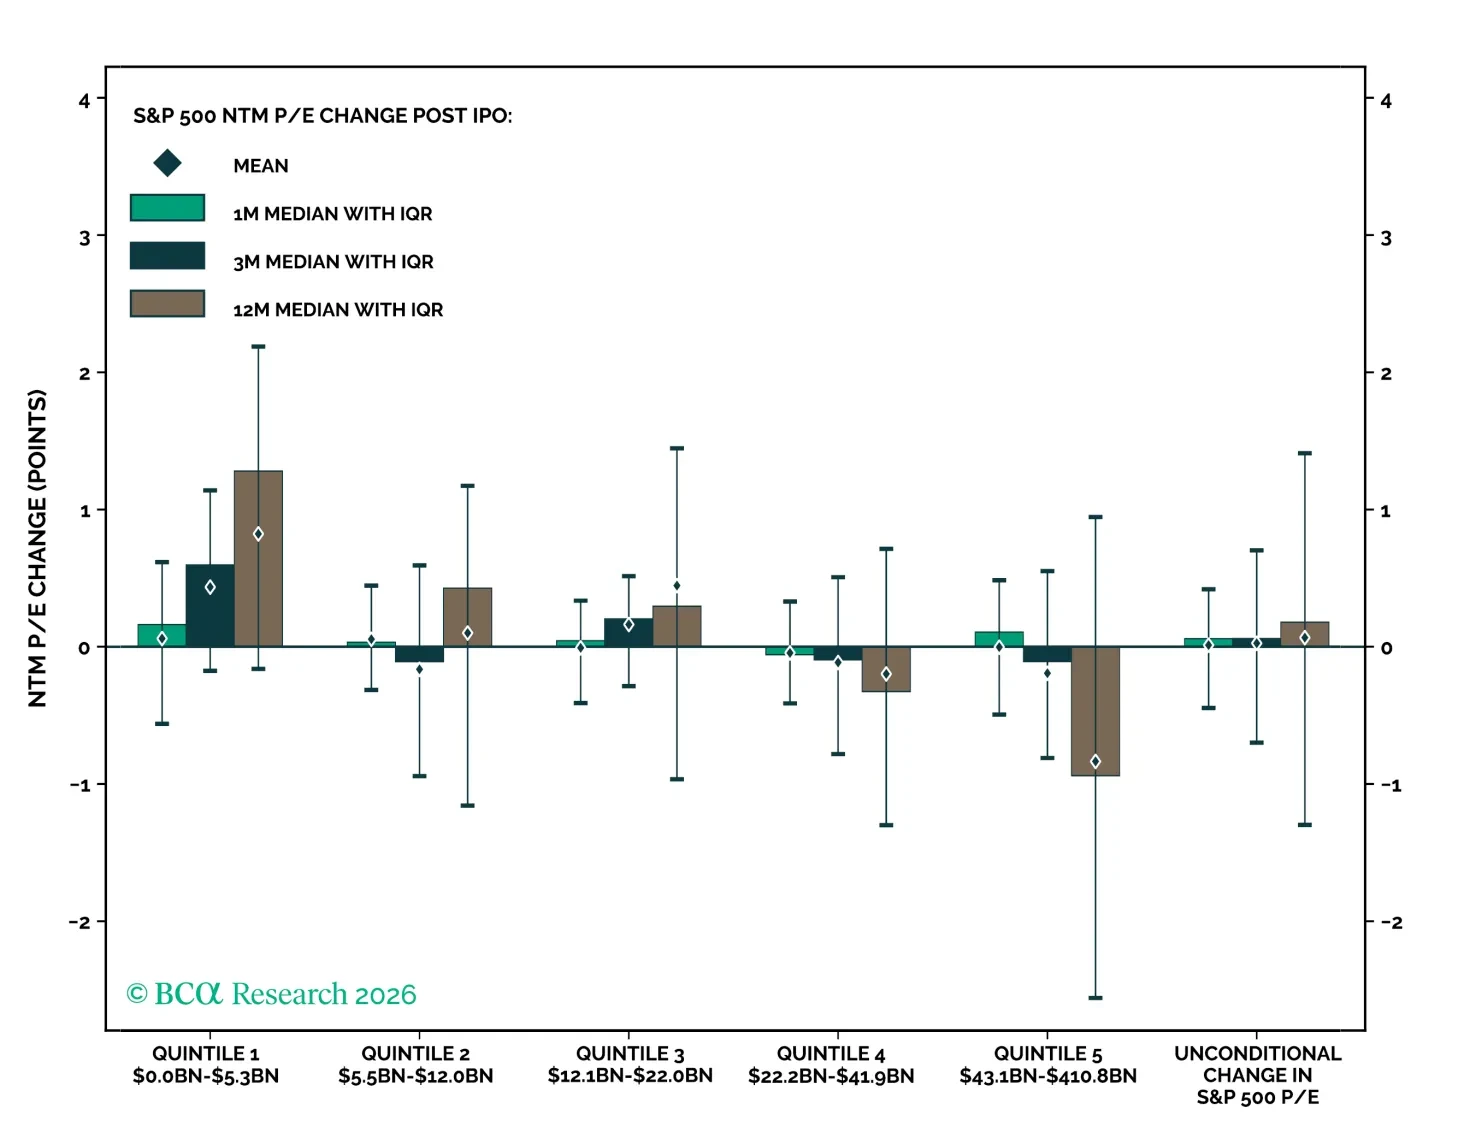
The IPO wave has arrived, dominated by SpaceX’s massive listing. Aftermarket performance has been weak, and elevated issuance is weighing on S&P 500 multiples, although some pressure is already priced. SpaceX remains only partly digested, while Anthropic and OpenAI will bring further supply and greater business model scrutiny.