Industrials
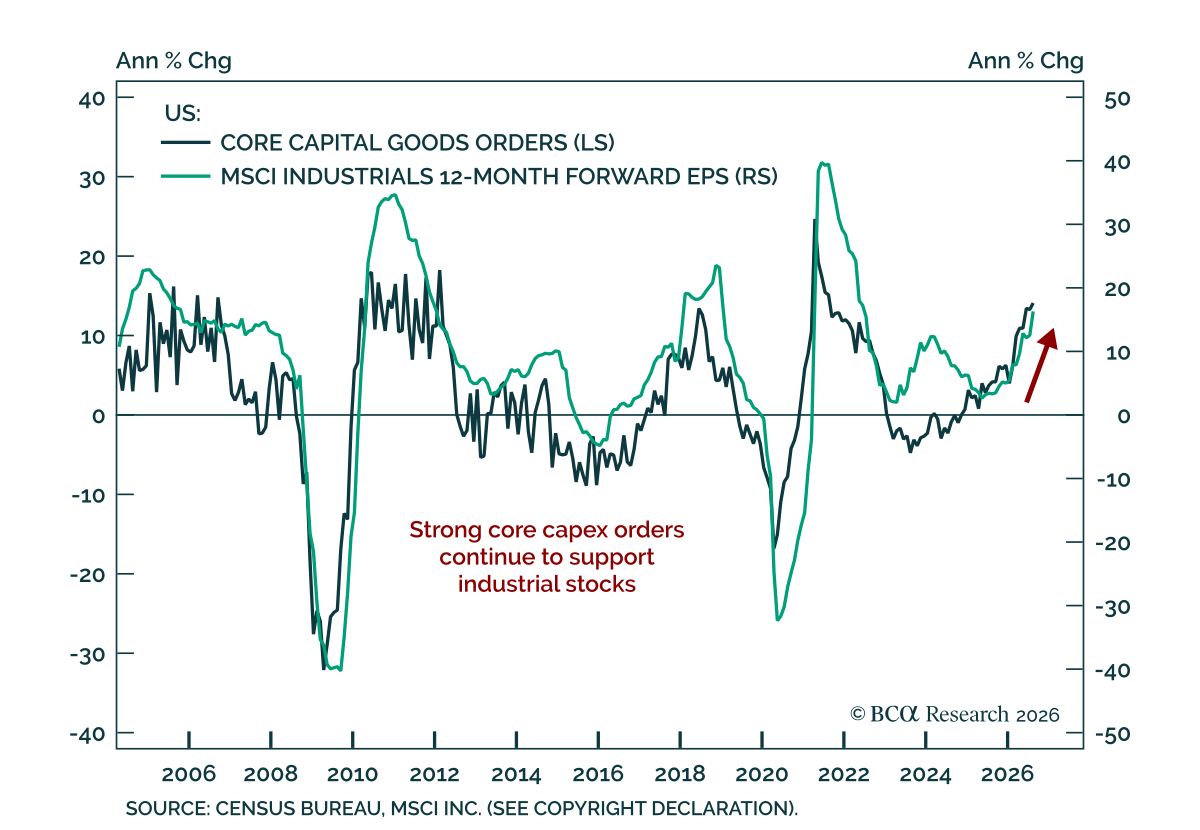
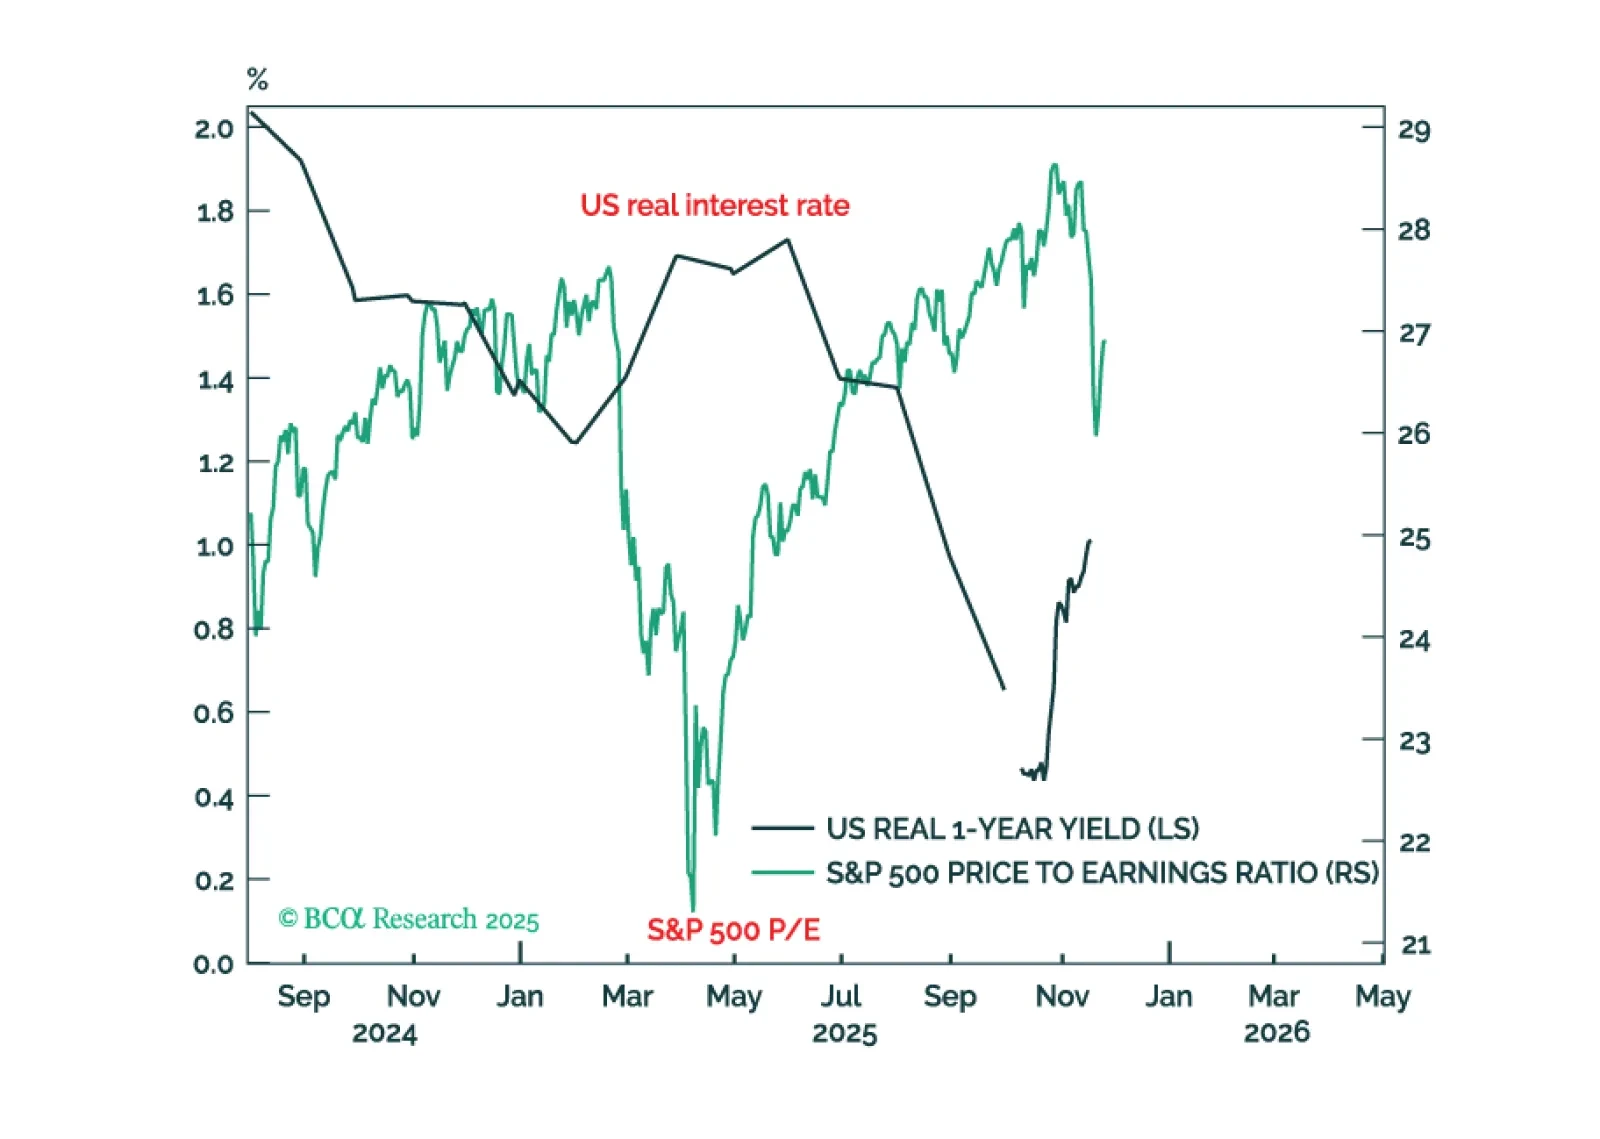
株式市場のバリュエーションは米国実質金利のほぼ完全な鏡像として動いており、FRBが株式市場を支えていることを意味します。しかし、市場がAI主導の利益成長を信じるのをやめれば、FRBの努力にもかかわらず、バリュエーションは崩壊するでしょう。それはいつ起きるのでしょうか?さらに、新しい2つの戦術的トレードとして、ビットコイン(BTC)対ゴールドのロング、および工業株のオーバーウェイトがあります。
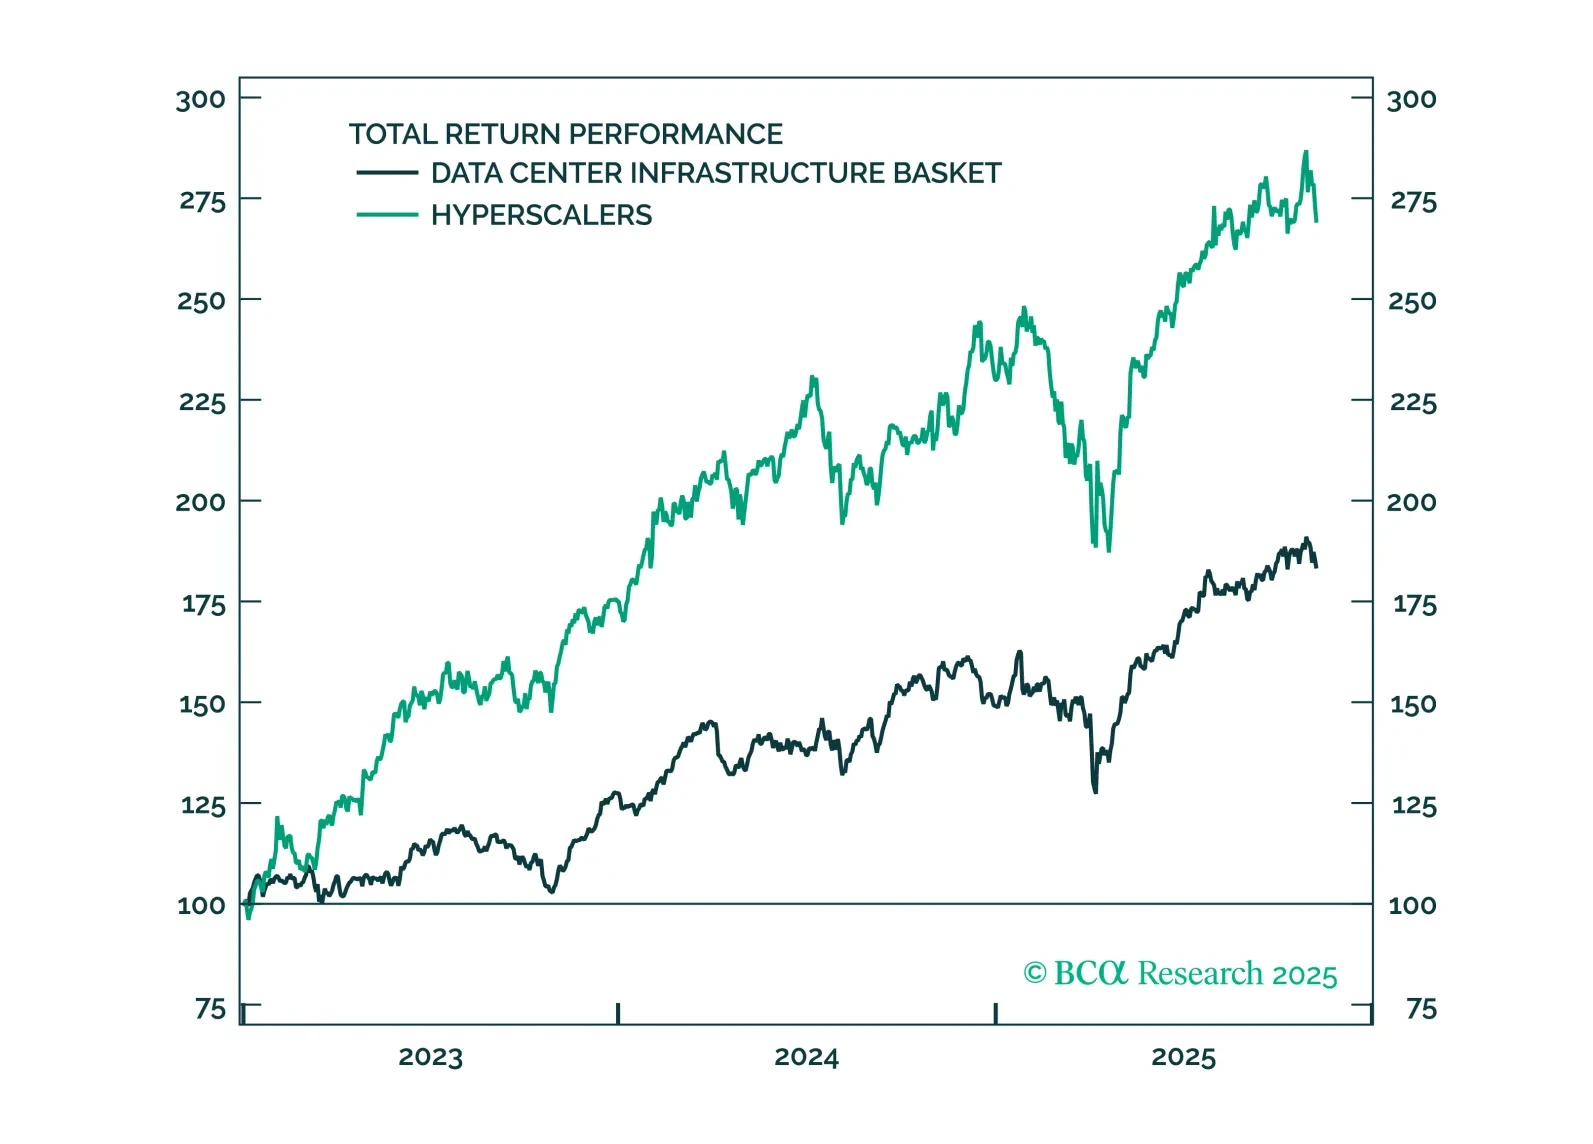
ハイパースケーラーがグローバルデータセンターの容量を拡大する中で、強力な産業サイクルを引き起こしています。データセンターおよびエネルギーインフラ用のタービン、グリッド部品、冷却システム、高度な接続素材を供給するキャピタルグッズおよびマテリアル企業が主要な恩恵を受ける存在として浮上しており、GenAIの需要が経済を再構築する中で、構造的な成長を捉える位置にあります。
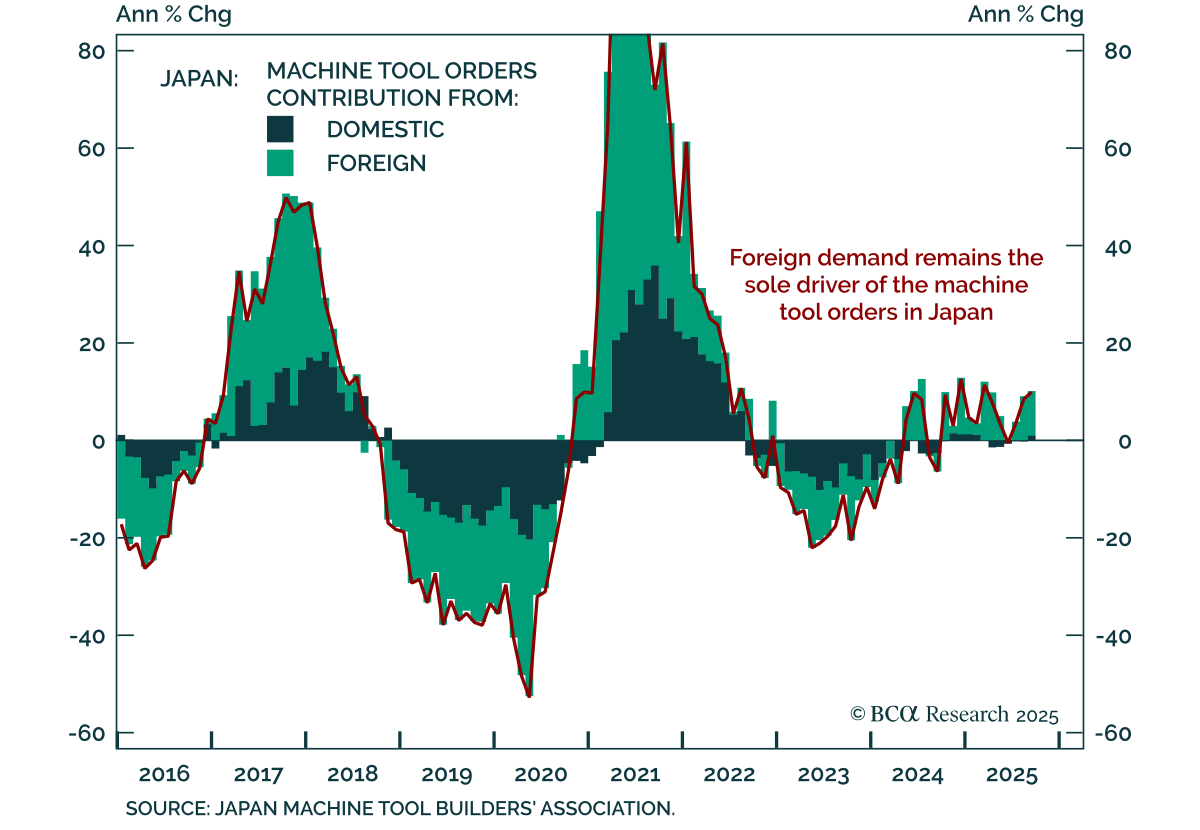
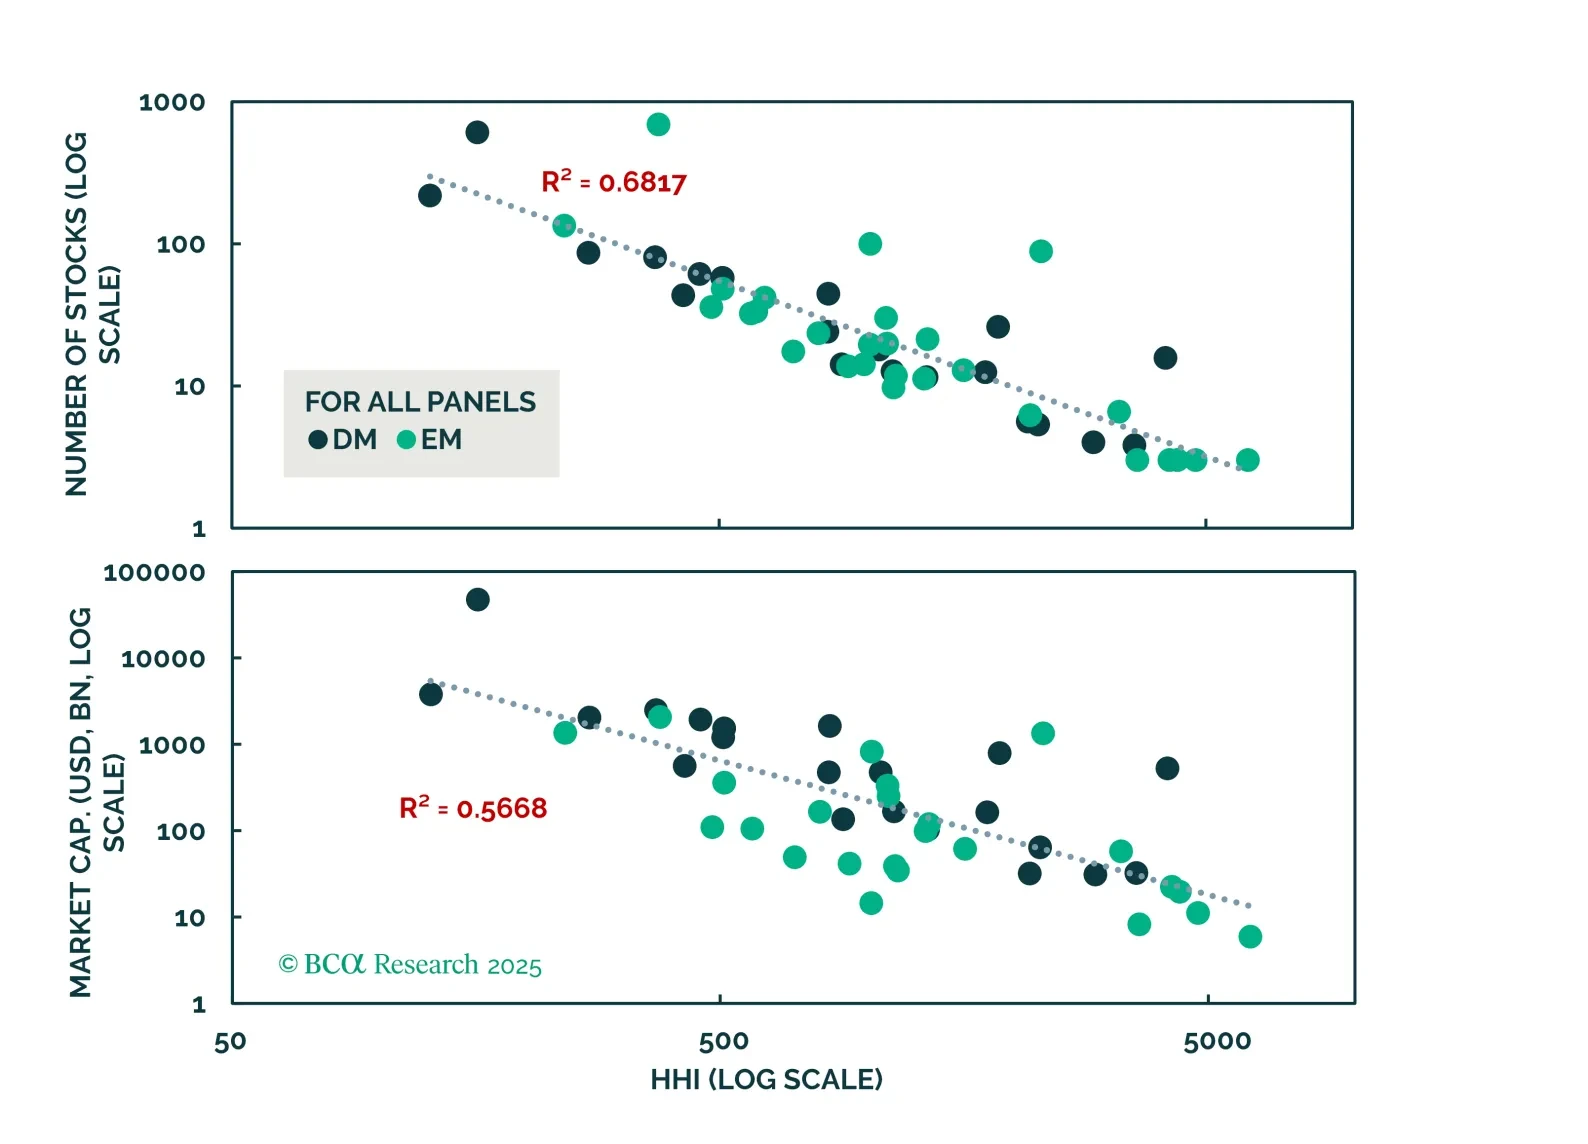
MSCI ACWIの国別指数のデータを使用し、先進国市場は1984年まで、エマージング市場は1988年まで分析した結果、市場の集中度は長期的な将来リターンの予測力にほとんど寄与しないことが分かりました。予測力があるとしても、バリューやサイズといった従来の指標を含めるとその効果は消えてしまいます。同じことが特異的な指数リスクについても言えます。指数の集中度は、エクイティ市場におけるリスクとリターンを決定する上であまり重要ではありません。
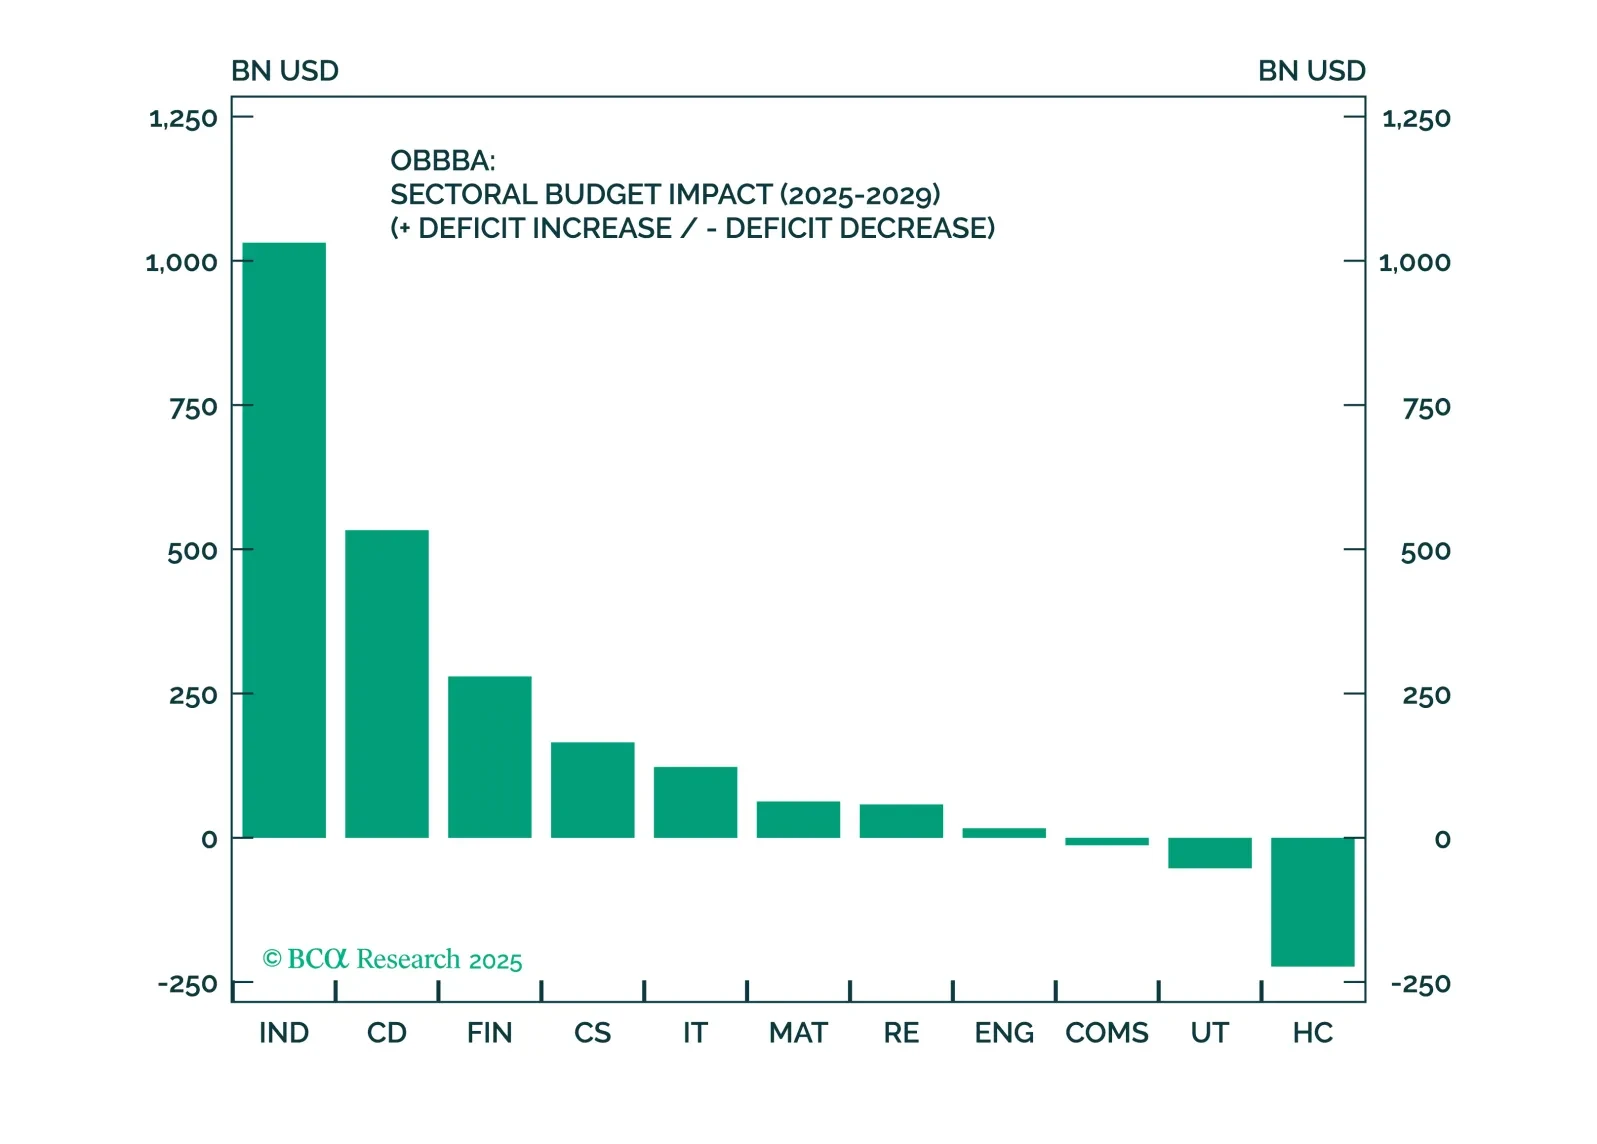
マクロ経済の逆風にもかかわらず、OBBBAは産業株、金融株、および一般消費財株のエクイティセクターを明確に支持しています。これらのセクターにおける十分に構築された、ファクターを意識したバスケットは、財政主導の不確実な環境においてアウトパフォームする良いポジションにあります。

In this month’s Beta report, we continue our series supporting our bullish thesis on Europe. We take a deep dive into the aftermath of the European energy crisis – dispelling the myth that Europe faces risks of imminent deindustrialization – and evaluate the impact the approaching LNG wave will have on European industry and the global natural gas market.
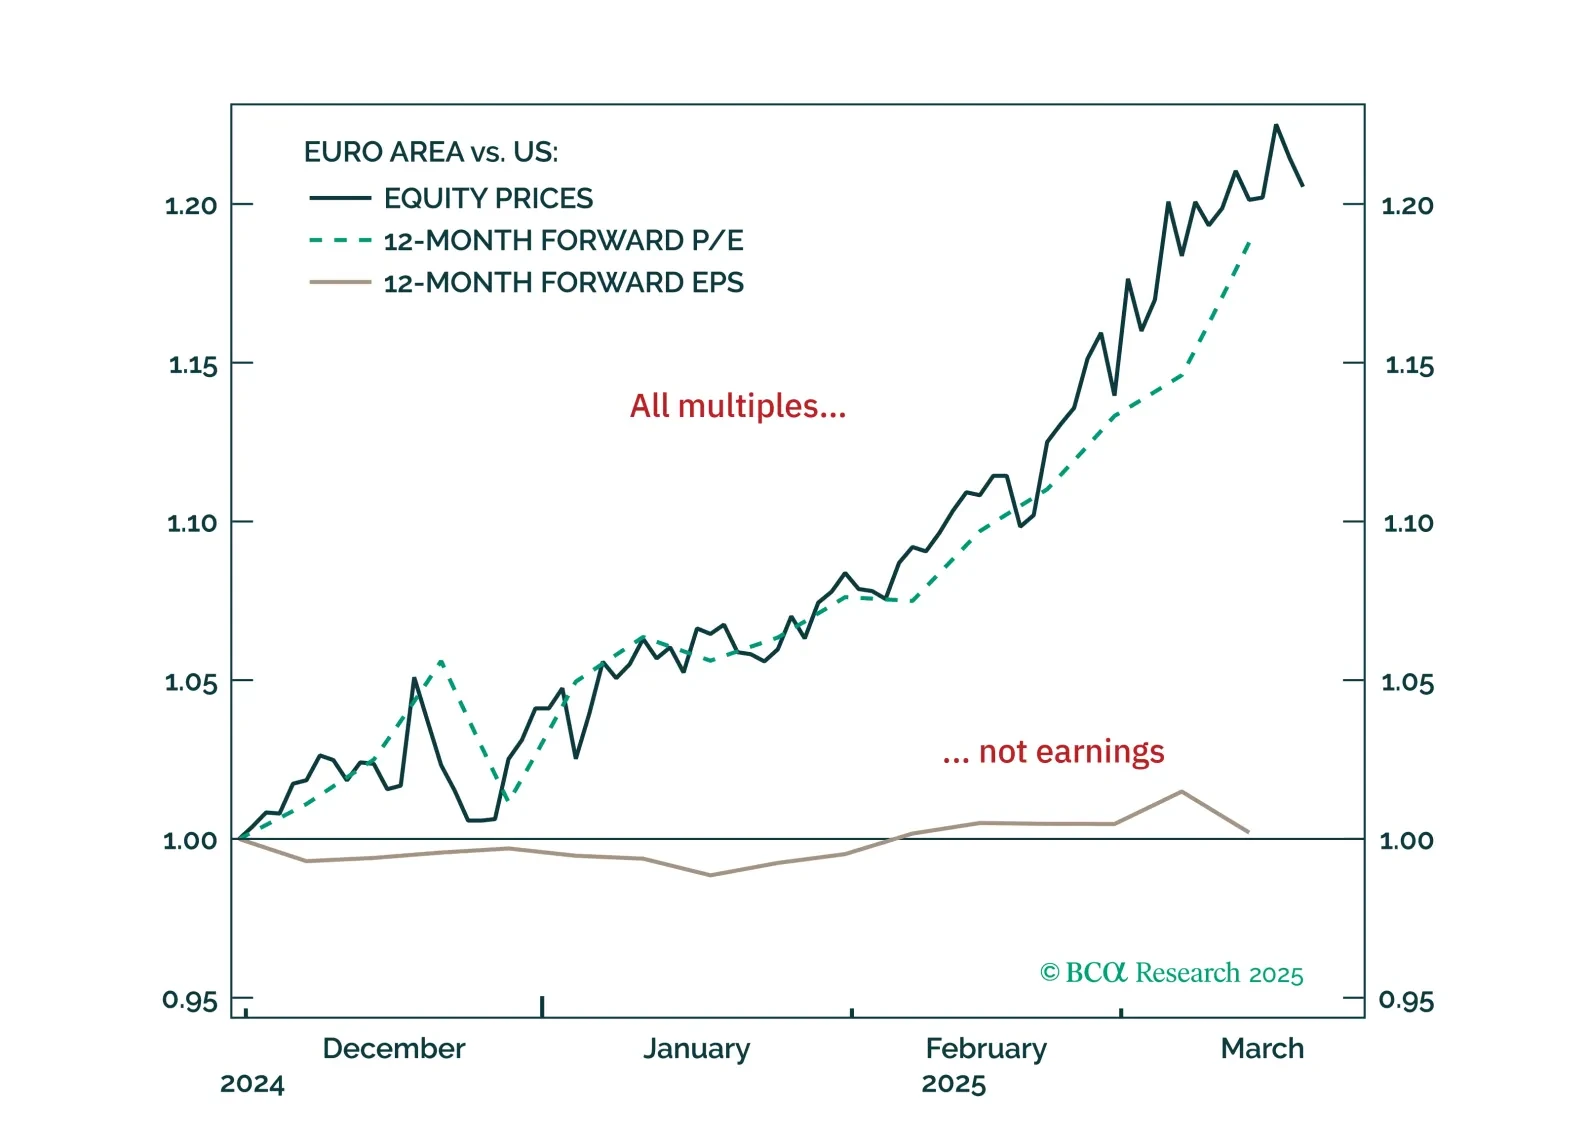
European equities have surged on hopes of a low-inflation boom—but the rally has likely gone too far, too fast. With a pullback now likely, how should investors position themselves over the next 3–6 months?
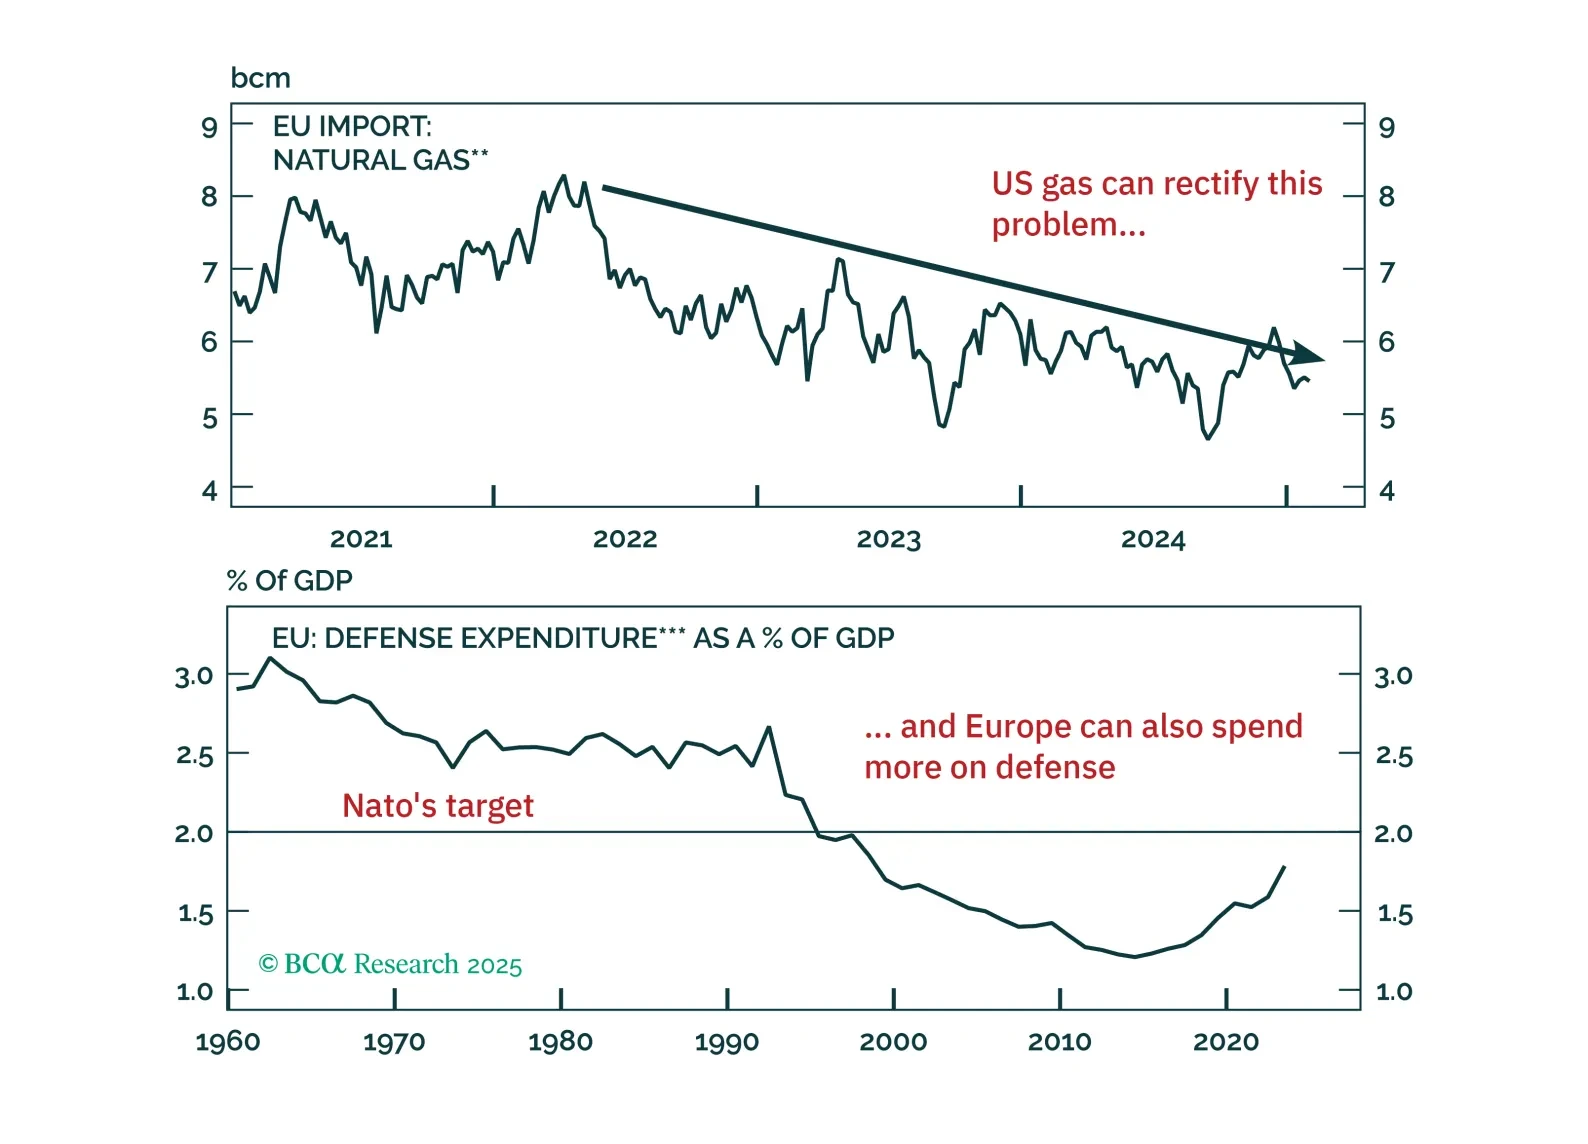
Europe is about to become President Trump’s next target. The good news: a US/EU trade war will be short as common ground to achieve a deal exists. The bad news: European assets remain at the mercy of heightened uncertainty. How should investors position themselves in this tricky context?