戦争/紛争
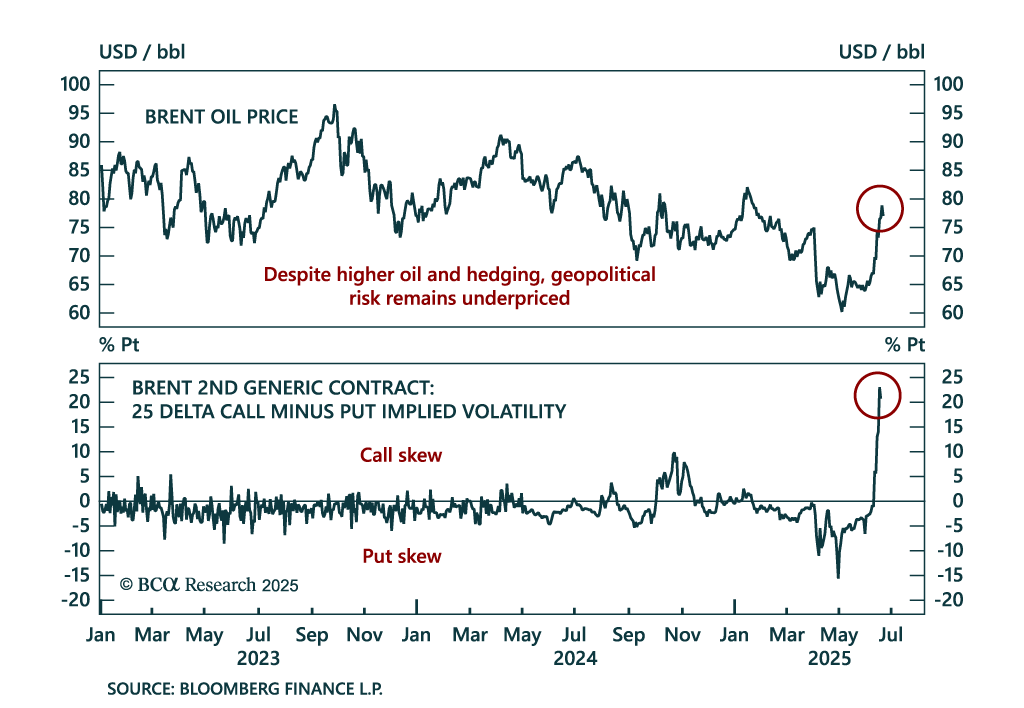
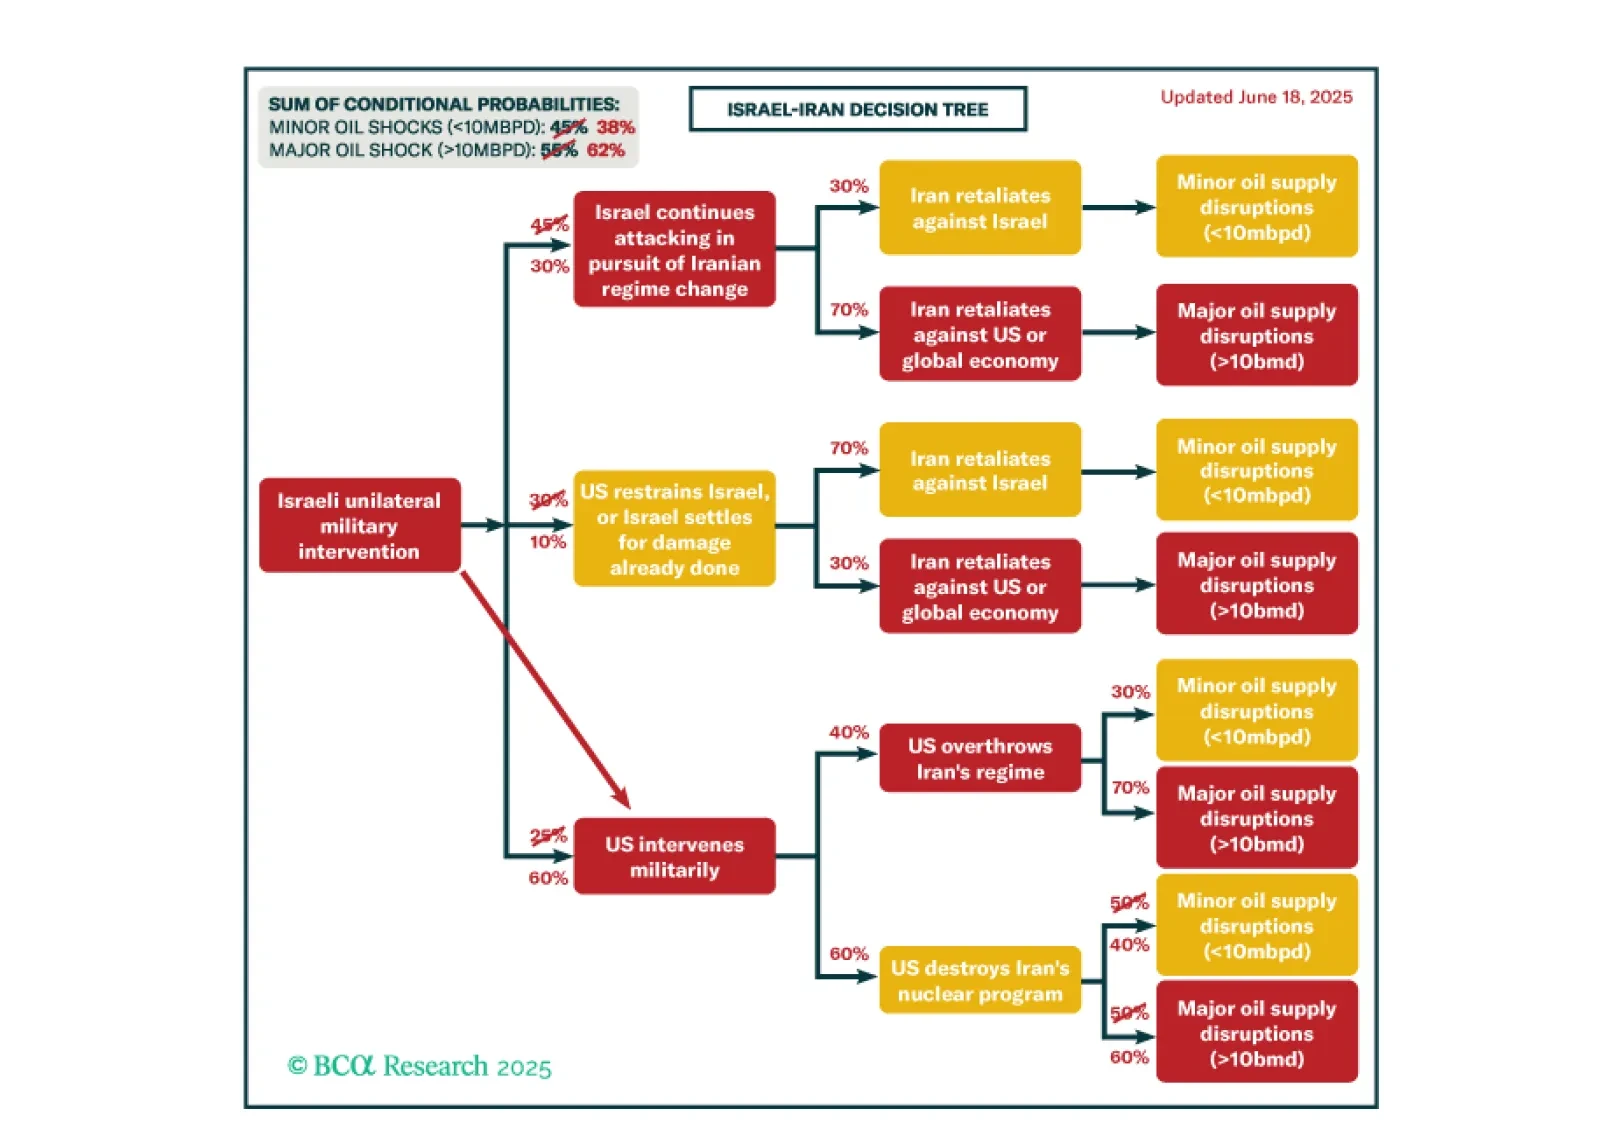
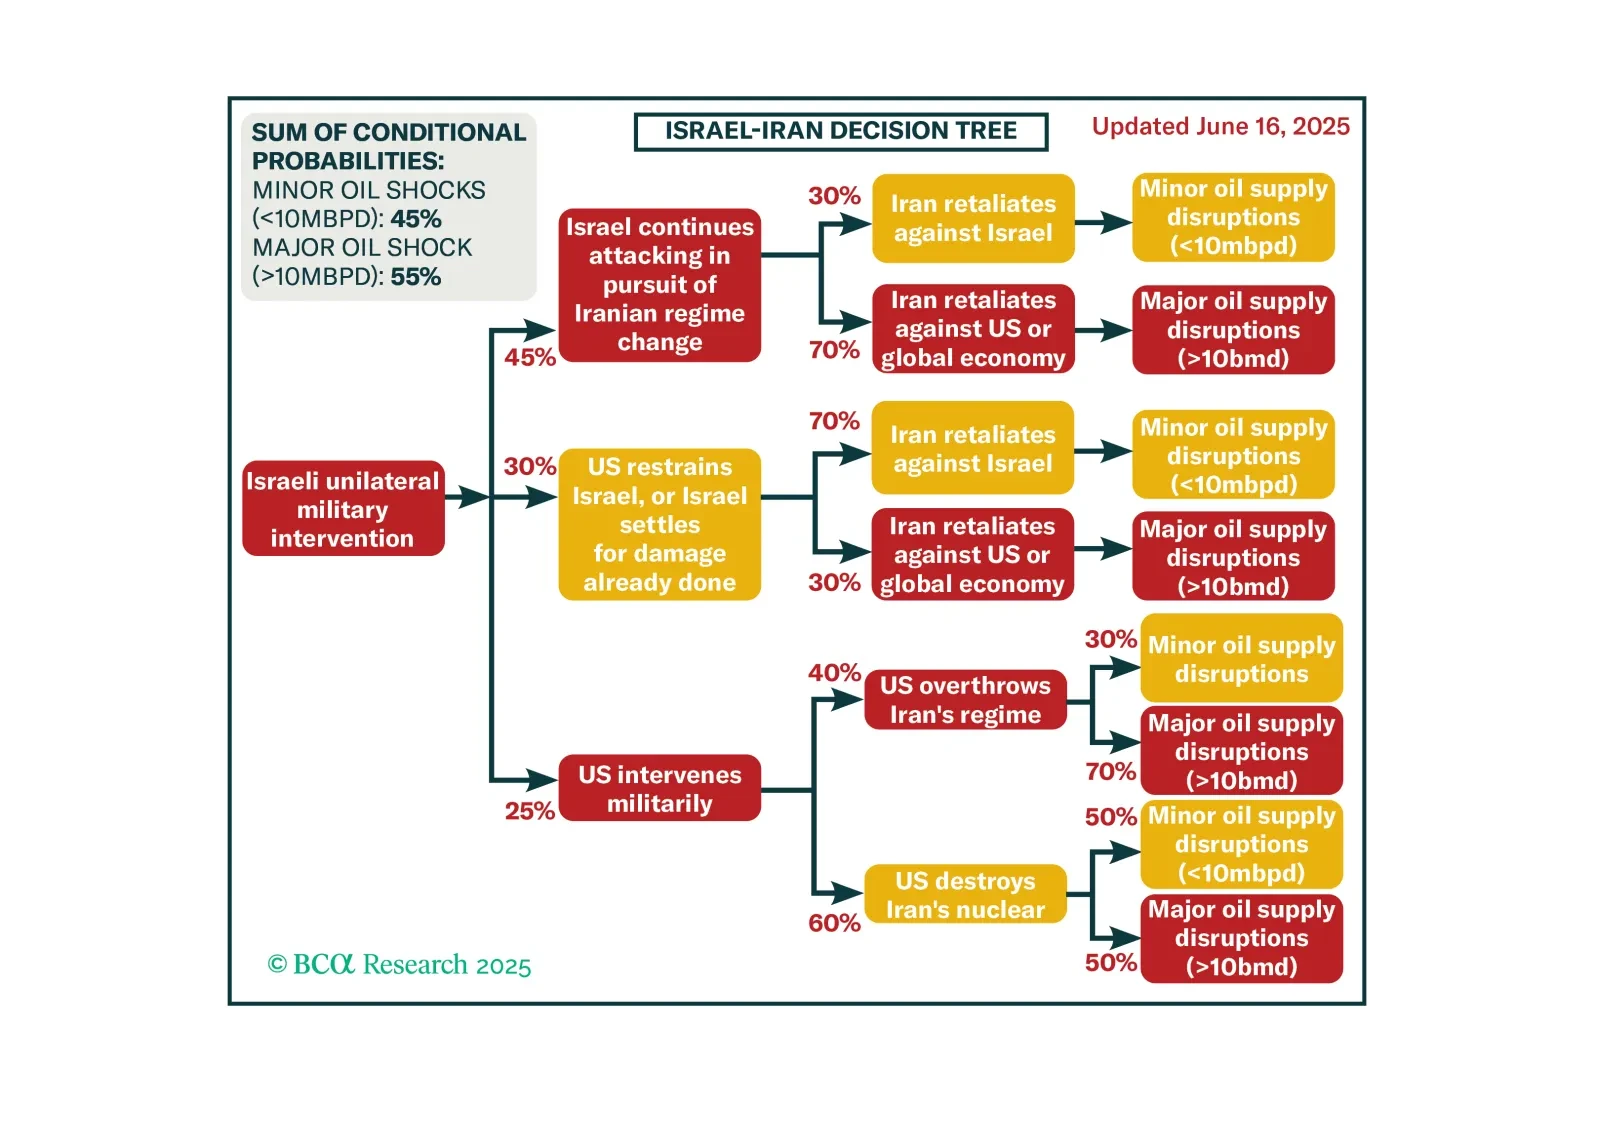
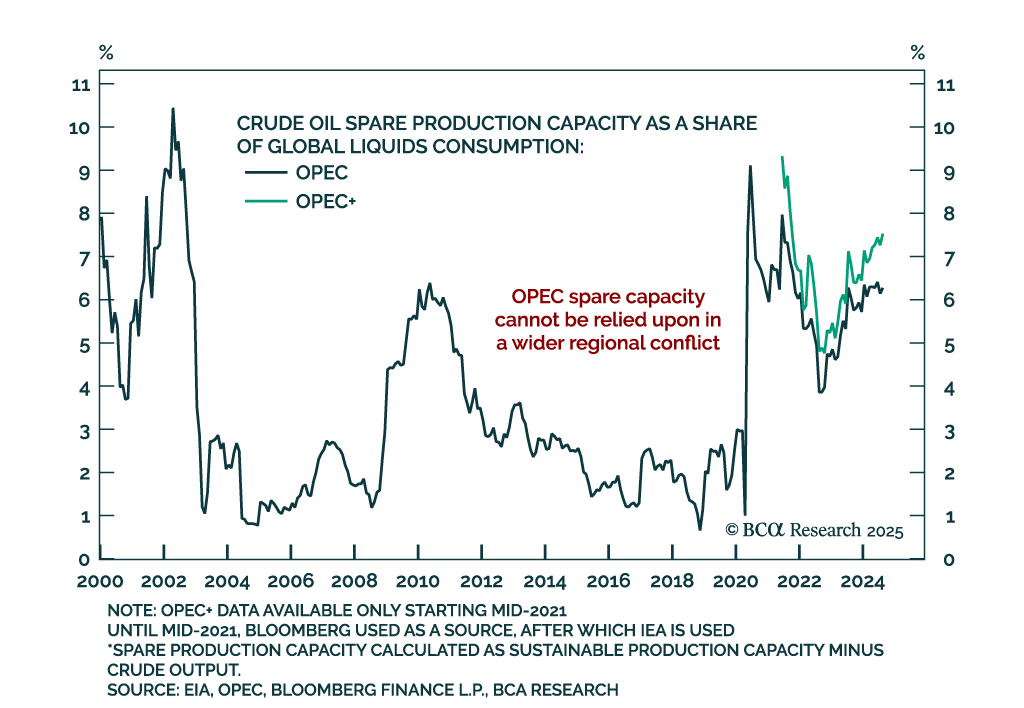
イスラエルによるイランへの攻撃は、イランが地域の石油供給を攻撃し、アメリカがイスラエルを抑制するよう強制されるまで継続するでしょう。しかし、それがうまくいかない可能性もあります。投資家は、紛争が経済全体に及ぼすより広範な影響に備えるべきです。
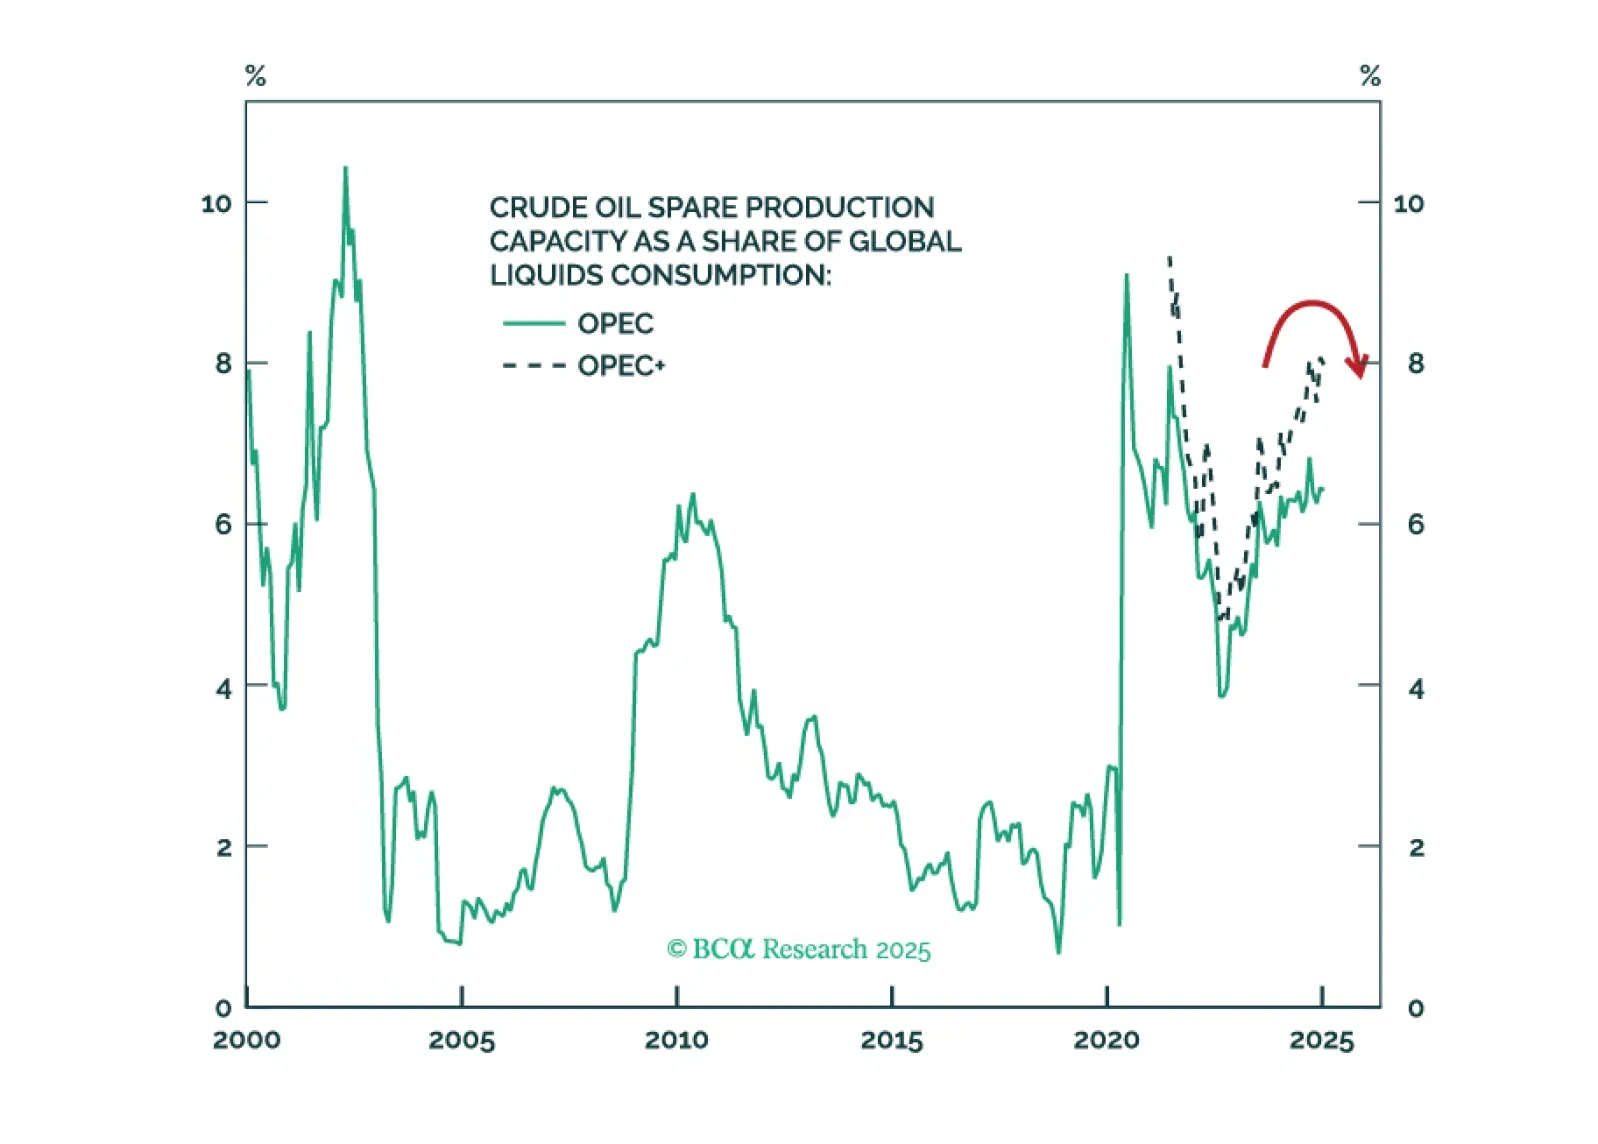
Investors should hold gold, build up some cash, tactically overweight US equities relative to global, and prepare for at least minor oil supply shocks – possibly major shocks – as the Israel-Iran war escalates.
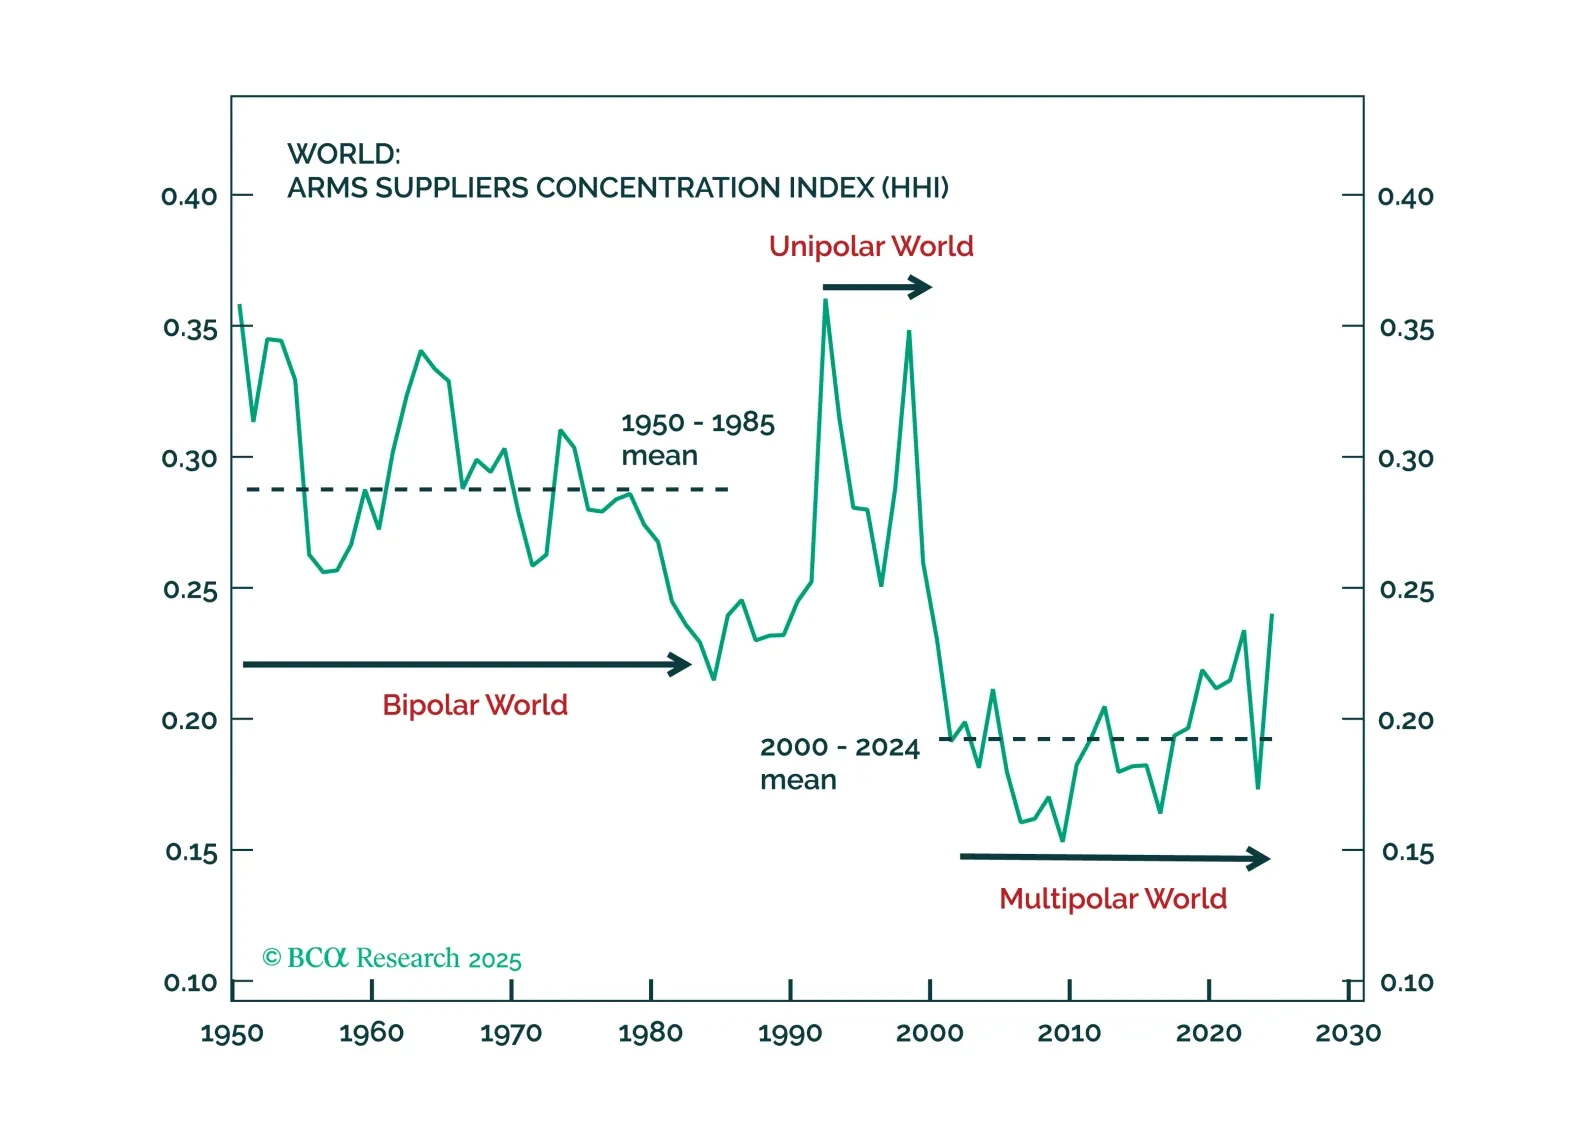
In our Beta report, we focus on our decade view. Many of our global allocator clients are scrambling to incorporate geopolitics into their strategic asset allocation. For most, this means thinking about war… or about future end-states. This is a mistake. We consider the next five years (maybe a decade) as the transition to the new era, a transition away from American unipolarity. And the transition itself is investment relevant. A transition to a multipolar world – which we think is occurring – will crush the USD and favor non-US assets. A transition to a bipolar world – not our base case, but still possible – would do the opposite.
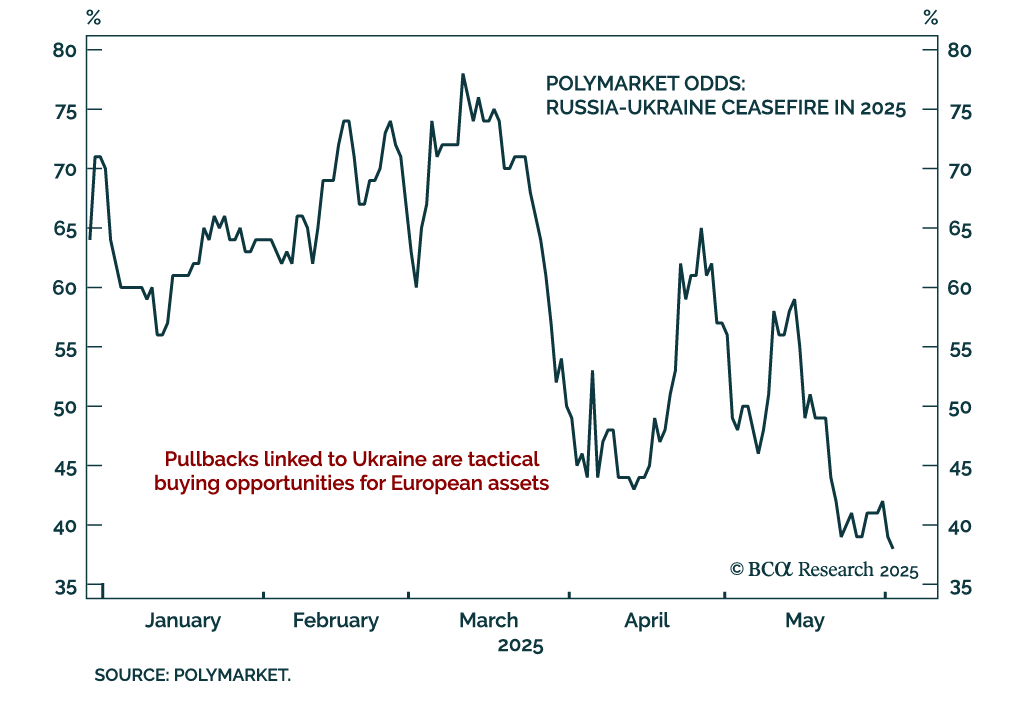
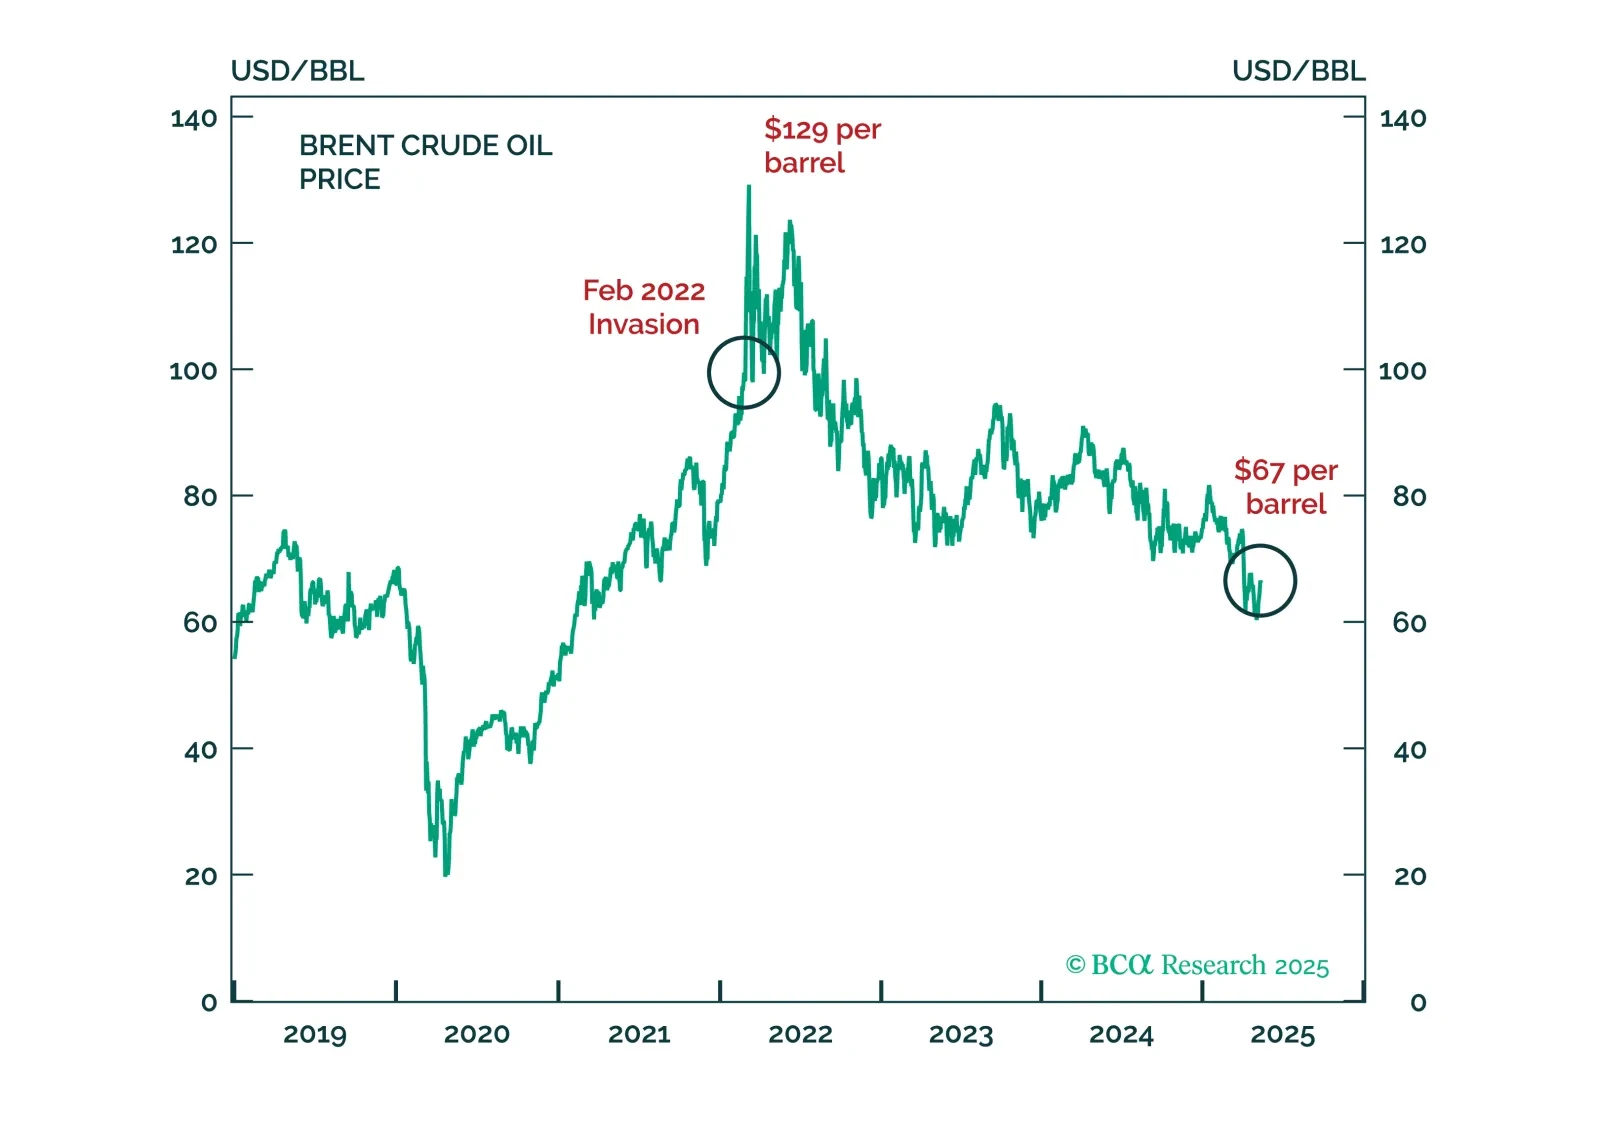
Russia has strong incentives to sign a ceasefire with Ukraine – namely its weak economy as the oil price falls. European assets will continue to benefit.
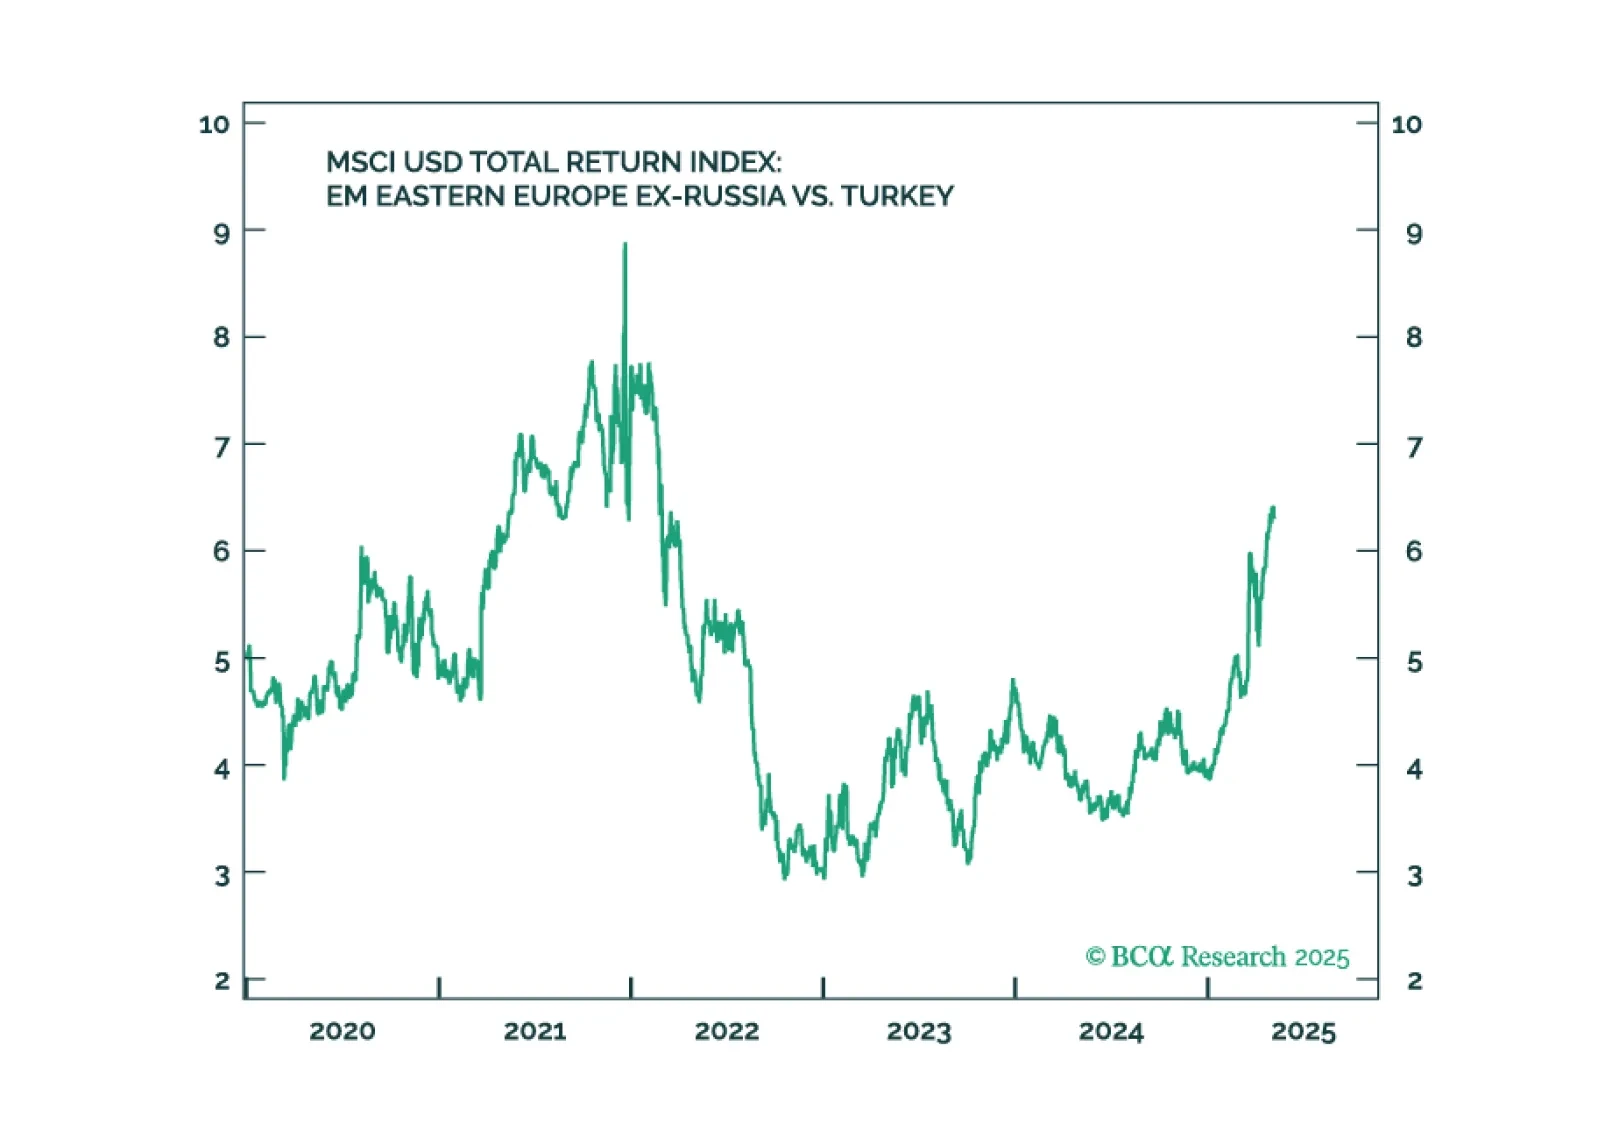
Erdogan's rule continues to decline. Social unrest will persist, governance will erode, and the macro backdrop will deteriorate further. We recommend underweighting Turkish assets.
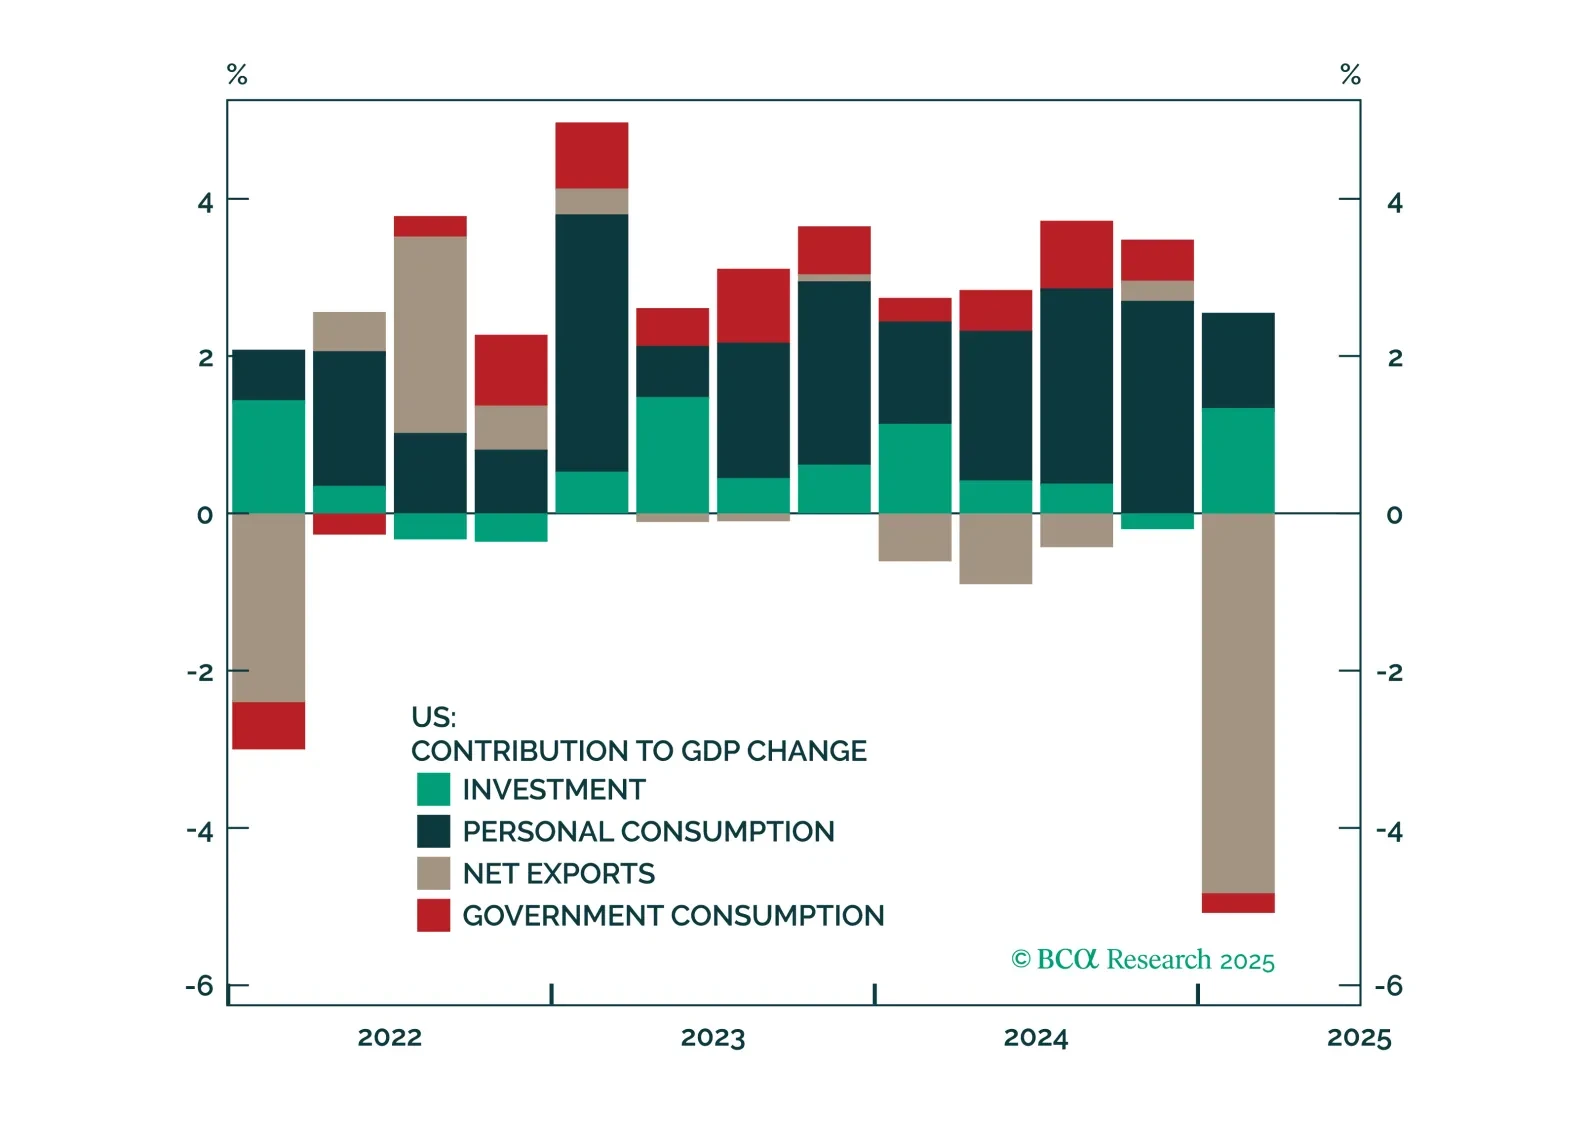
Negotiations on trade, Iran, and Ukraine will prove critical this month. Markets will remain volatile because positive data surprises enable the White House to press its hawkish tariff hikes, while negative surprises force the White House to backpedal.