Debt Trends
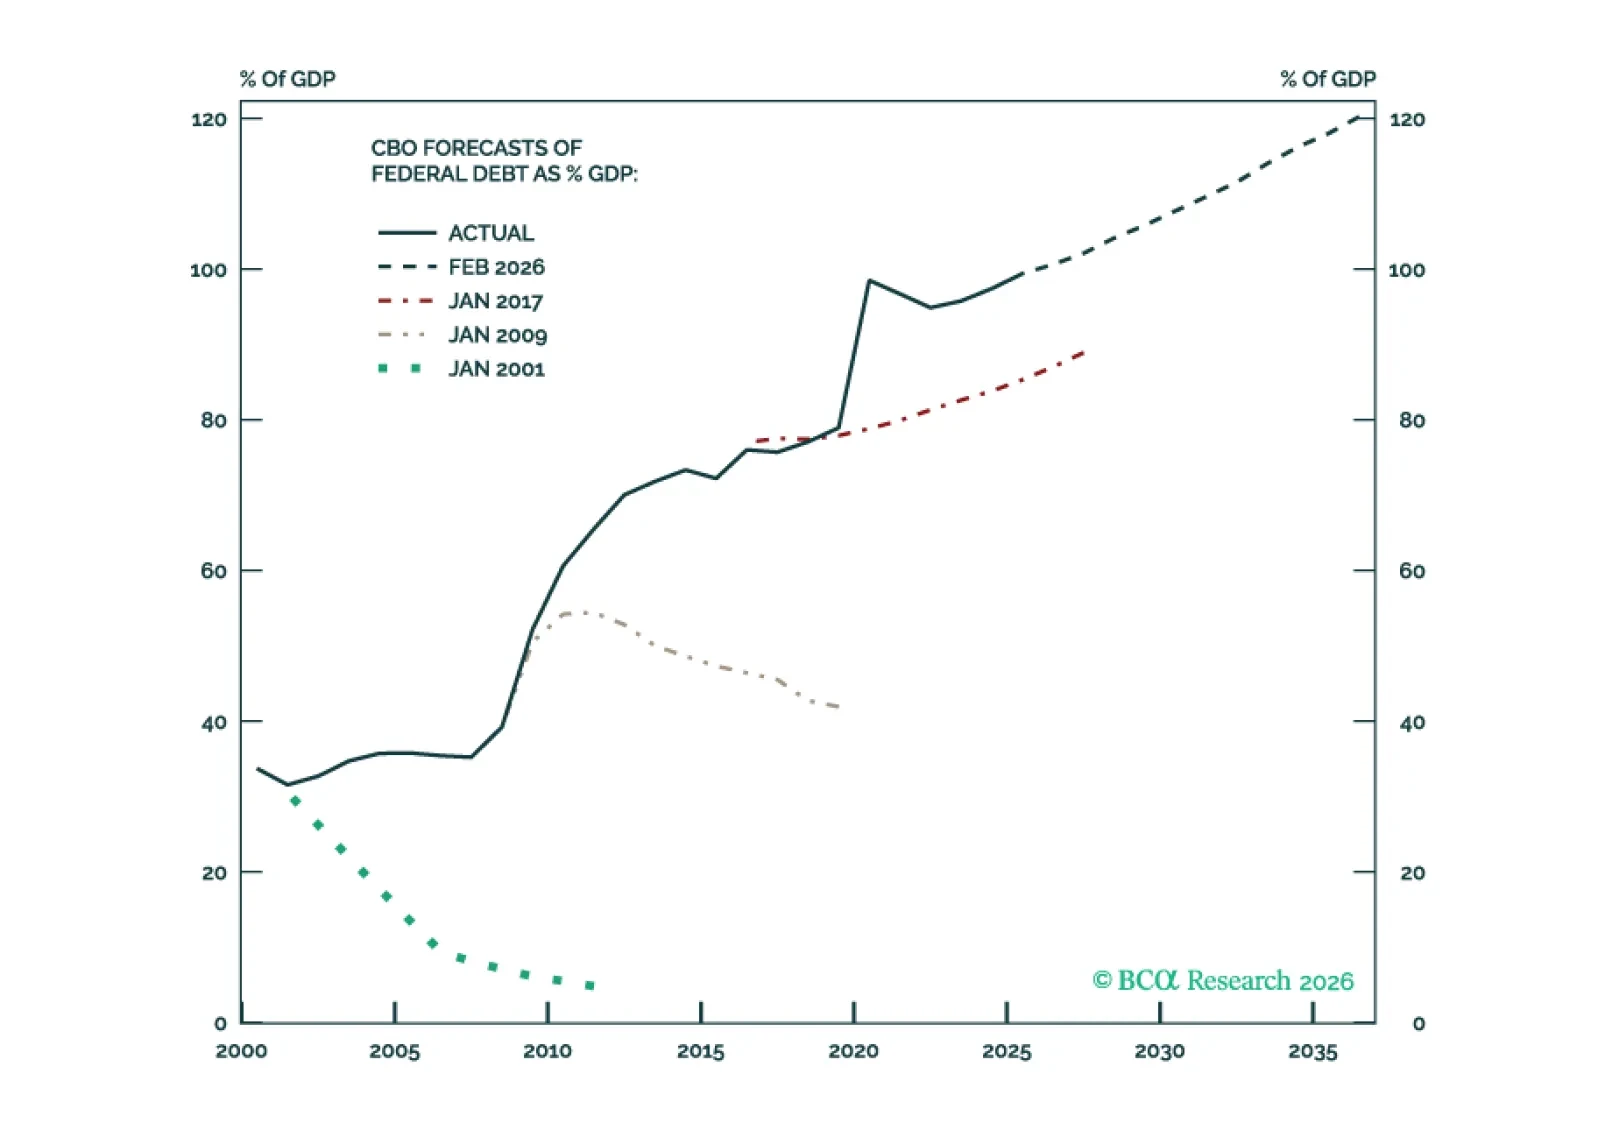
En este informe, Martin Barnes, economista jefe emérito de BCA, reflexiona sobre el aumento de la deuda del gobierno de Estados Unidos, la fortaleza del dólar y la expansión de los márgenes de beneficio que se ha producido en los últimos 25 años. Sostiene que estas tendencias son insostenibles y están destinadas a revertirse en los próximos años.
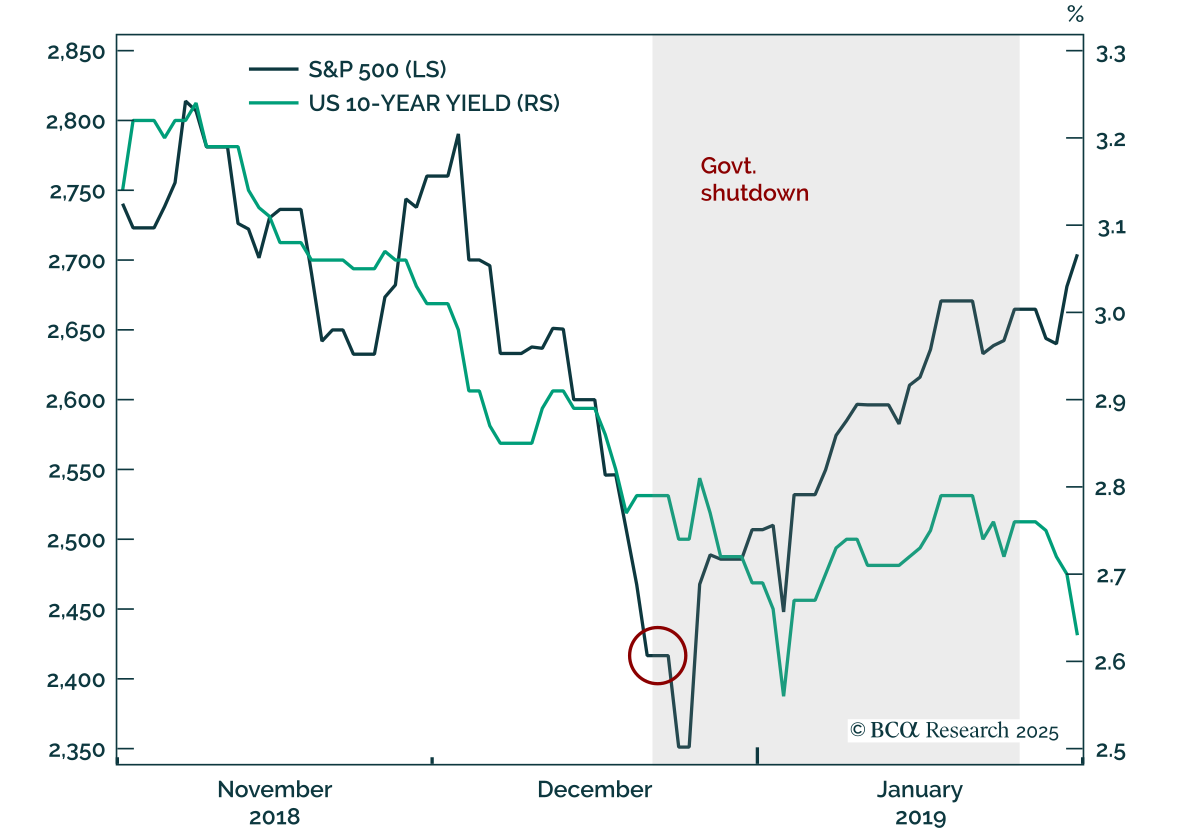
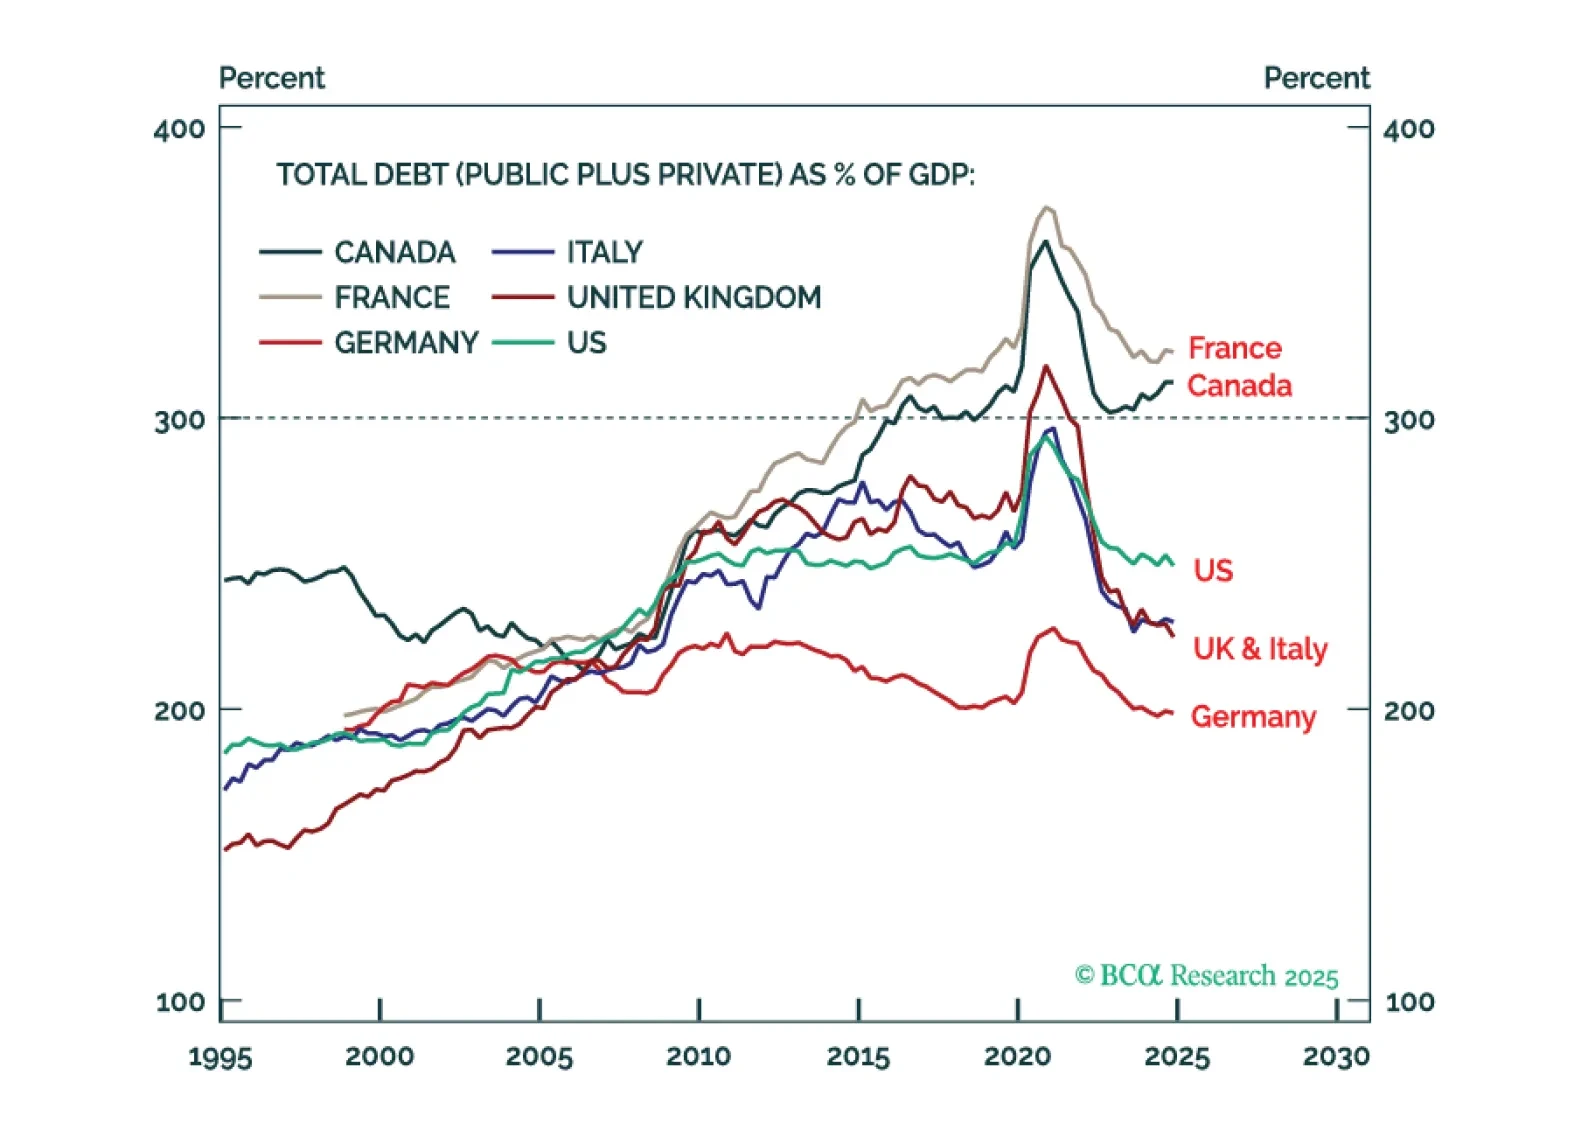
Los vigilantes de los bonos están rondando sobre varios objetivos en este momento: Francia, el Reino Unido y Japón. Pero Francia es el más vulnerable debido a una combinación tóxica: un ratio total de deuda muy por encima del 300 por ciento más el peor déficit primario del G7 más un estancamiento político, que empeorará aún más si el Primer Ministro François Bayrou pierde la votación de confianza el 8 de septiembre en su gobierno minoritario. Explicamos por qué el BCE no puede salvar a Francia y las implicaciones para la inversión. Además, presentamos nuestro nuevo ‘mapa de calor’ de complejidad para la asignación global de activos, que conduce a una nueva estrategia táctica para infraponderar los servicios de comunicación mundial (WTEL).
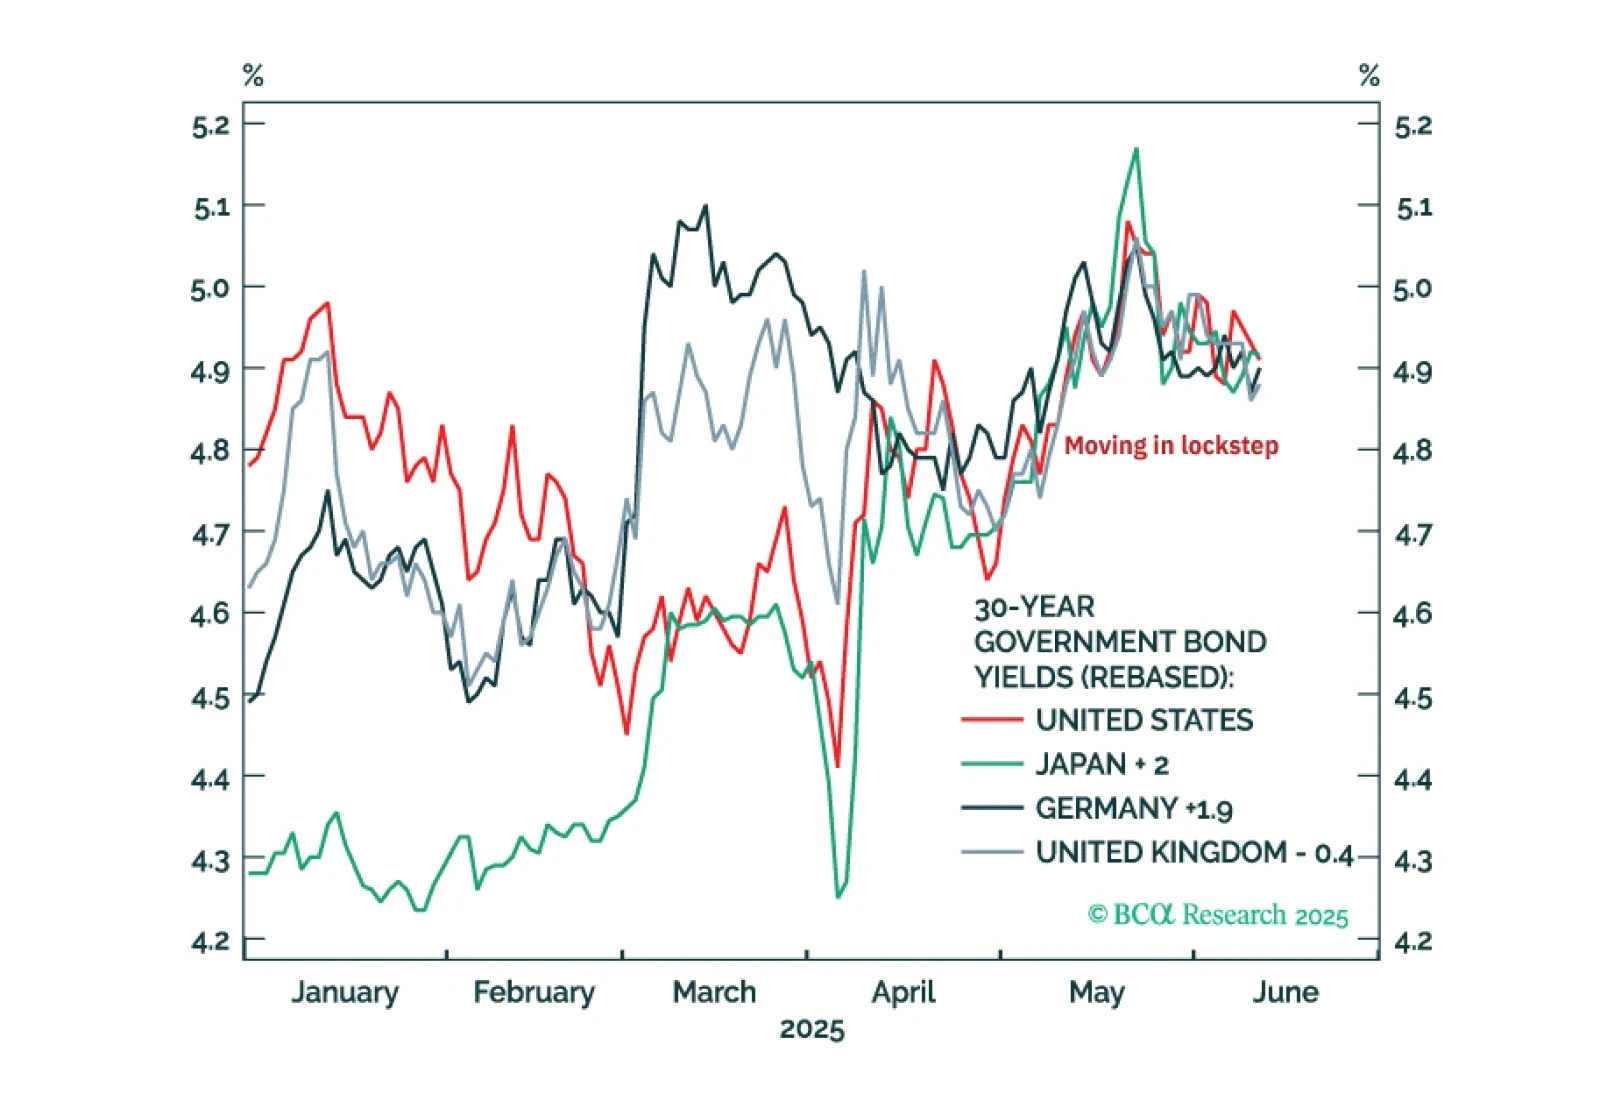
The perfectly synchronised moves in US, Japanese, German, and UK 30-year bond yields through the past two months are odd… and irrational. These irrational moves present compelling investment opportunities.
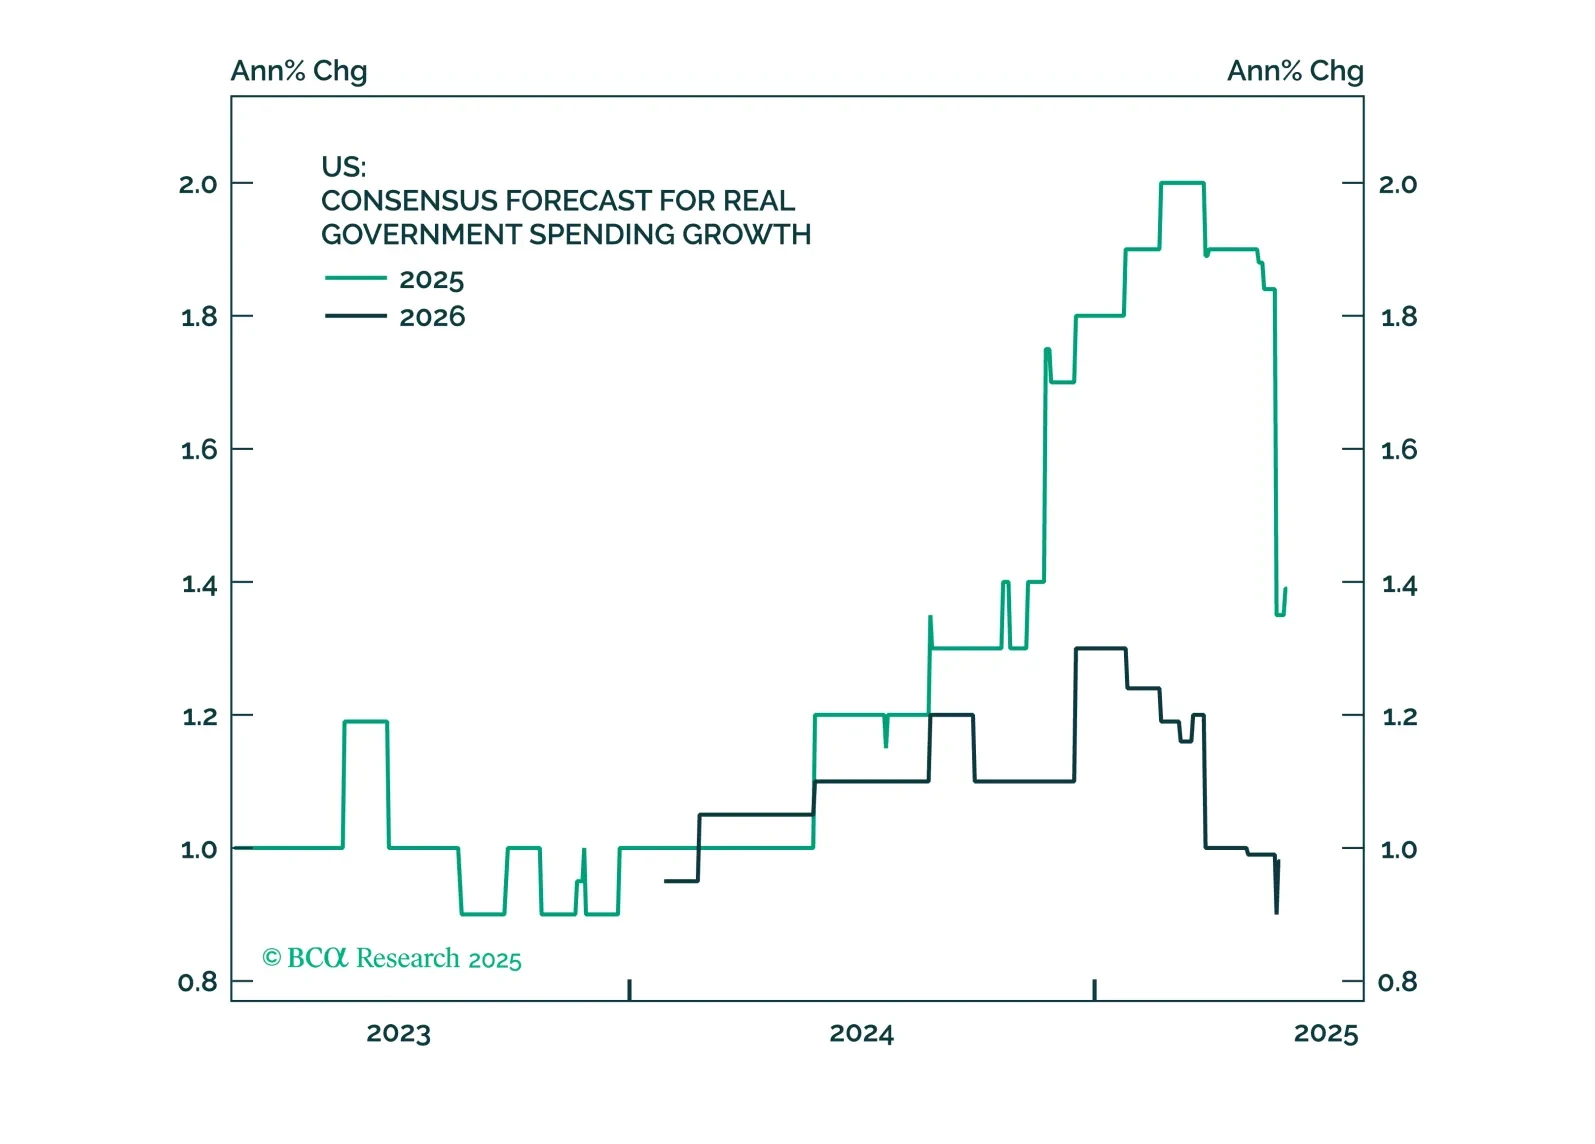
This month, we focus on the One Big Beautiful Bill Act (OBBBA). Our assessment in the Alpha report is that there won’t be any remaining alpha to harvest by shorting duration. The team that coined the “Human Steepener” moniker for President Trump is, effectively, throwing in the towel on looking for more upside to yields. There are many reasons for that view, but the main one is that the OBBBA legislation is just not that profligate, especially not relative to the investors’ expectations in the early days of the Trump 2.0 term.
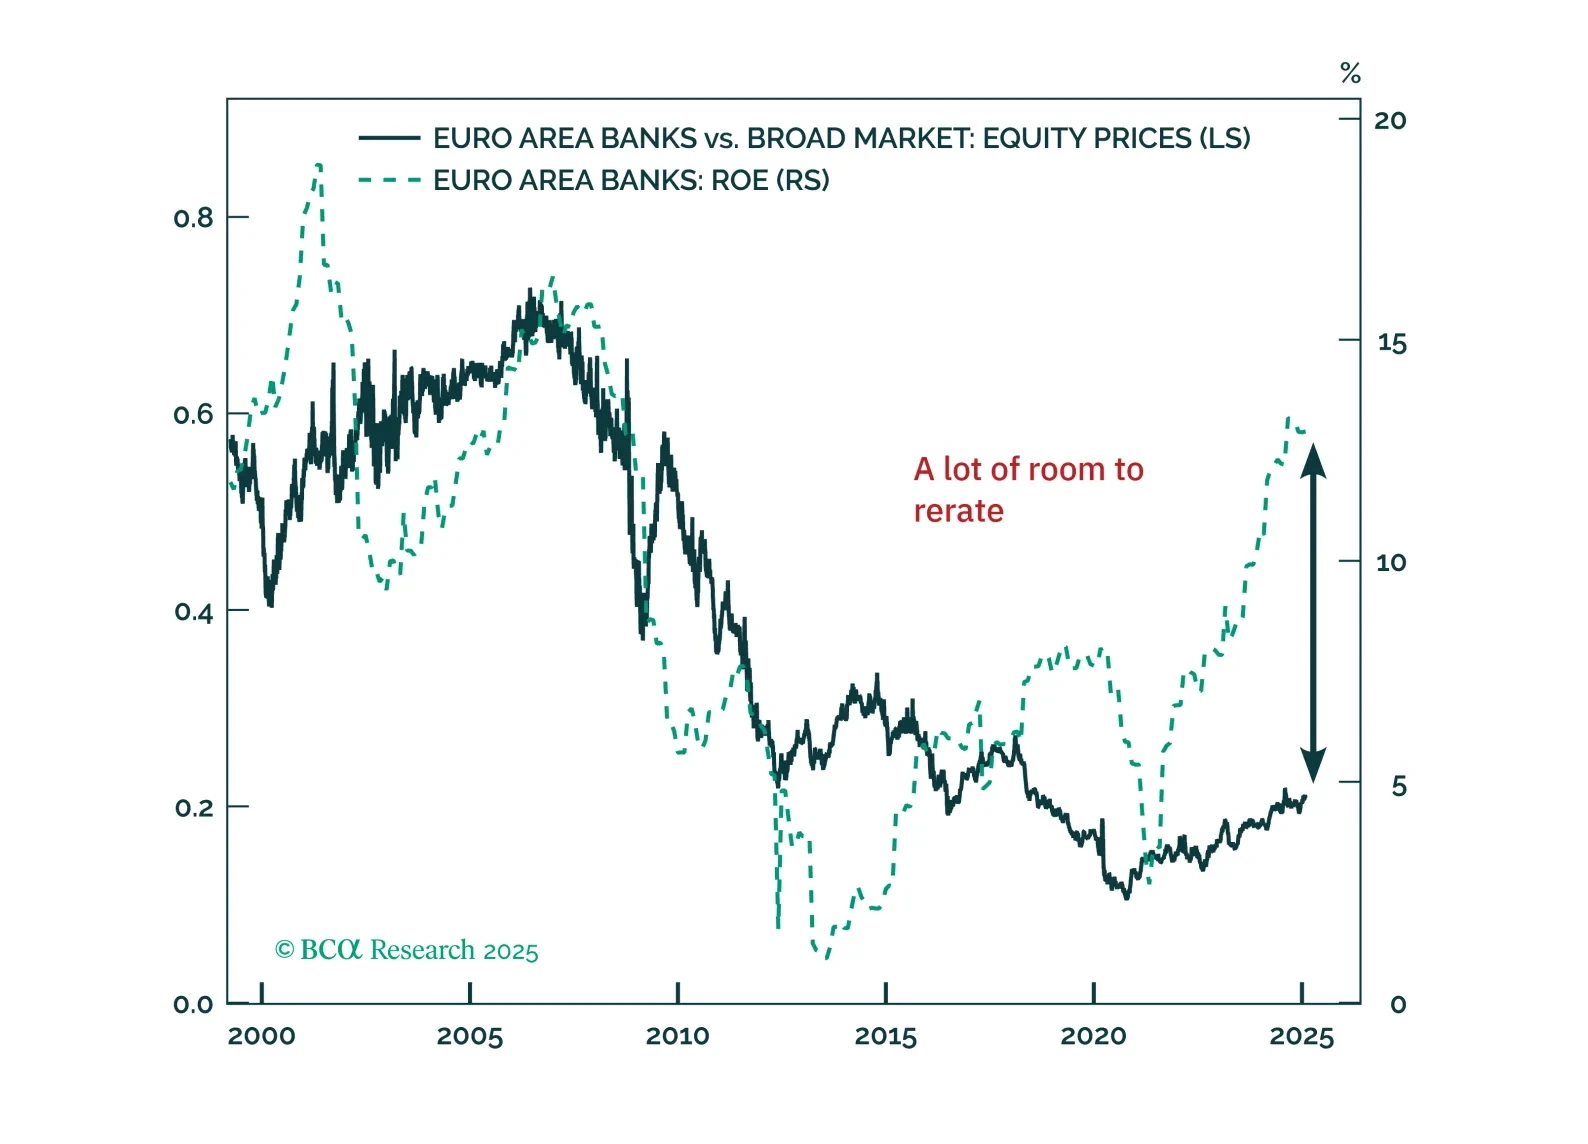
Eurozone banks have quietly outpaced the Magnificent 7—can they keep winning? With strong balance sheets, rising profitability, and structural tailwinds, European lenders still offer value despite short-term risks. Meanwhile, German equities continue to defy expectations, but is a near-term pullback on the horizon?
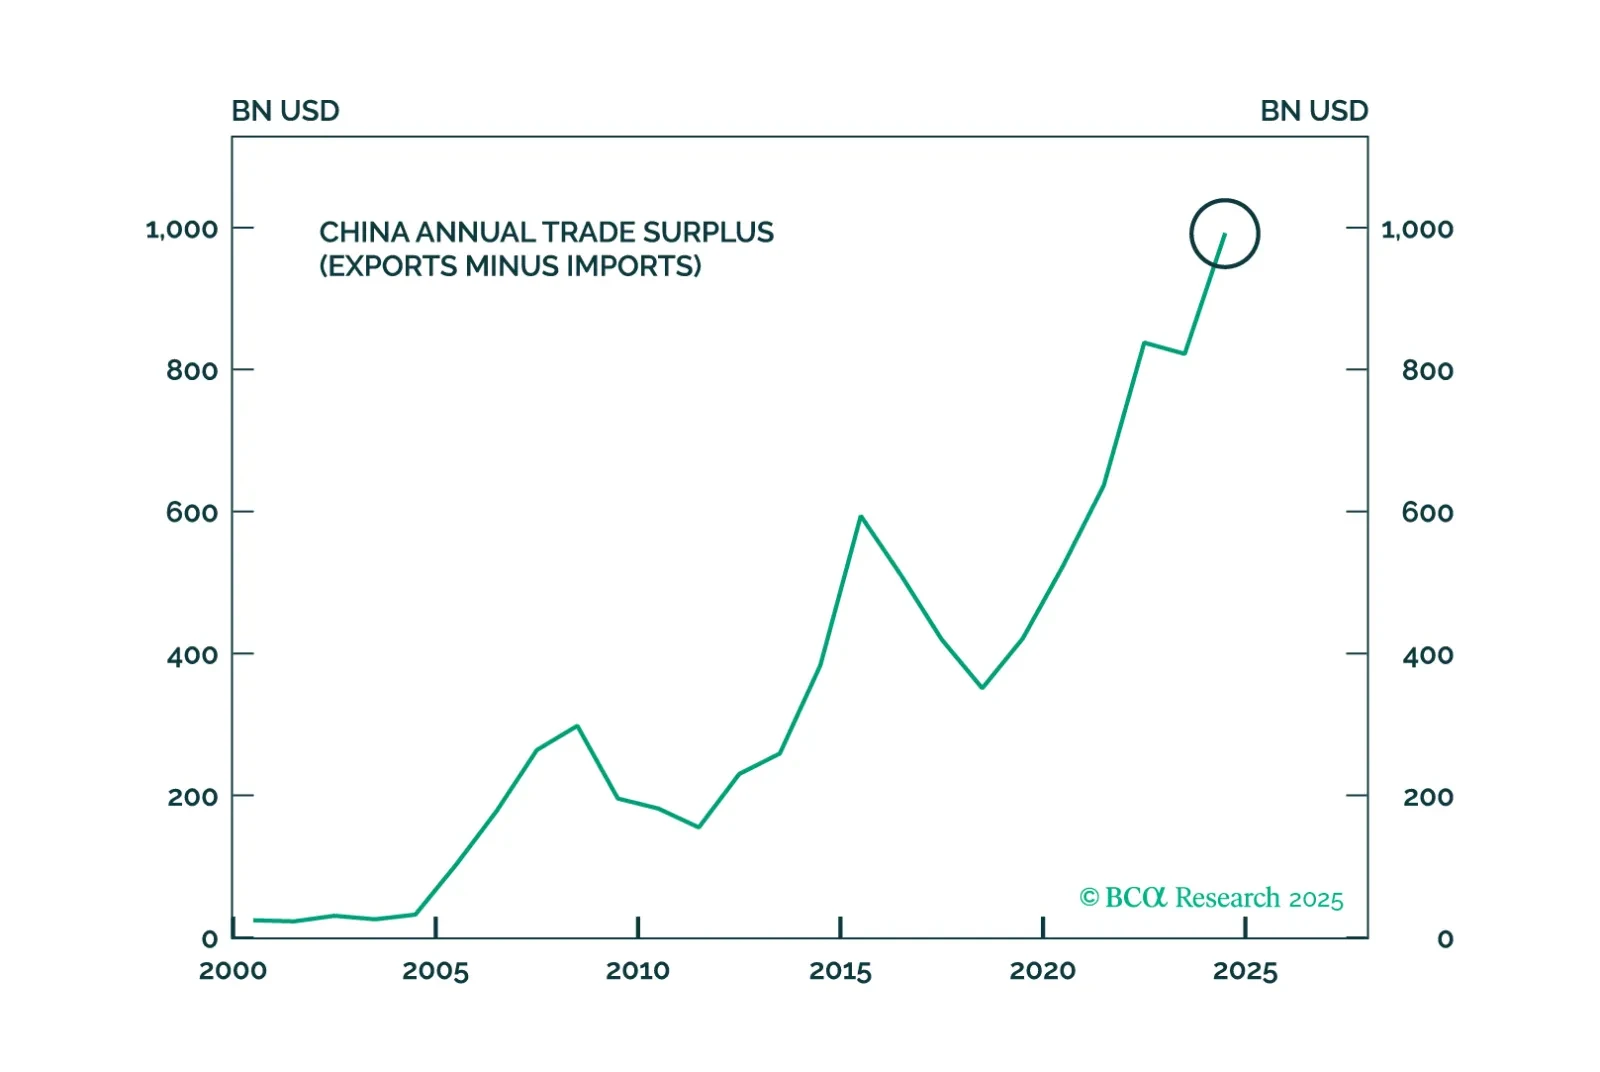
China barely hit its growth target in 2024 by shifting back to its old model of exports, racking up a record trade surplus with the world – right as Donald Trump walks back into the White House. Tariffs will elicit larger fiscal stimulus even as China rolls out innovations such as DeepSeek to meet its 2025 industrial goals, creating a volatile mix this year.
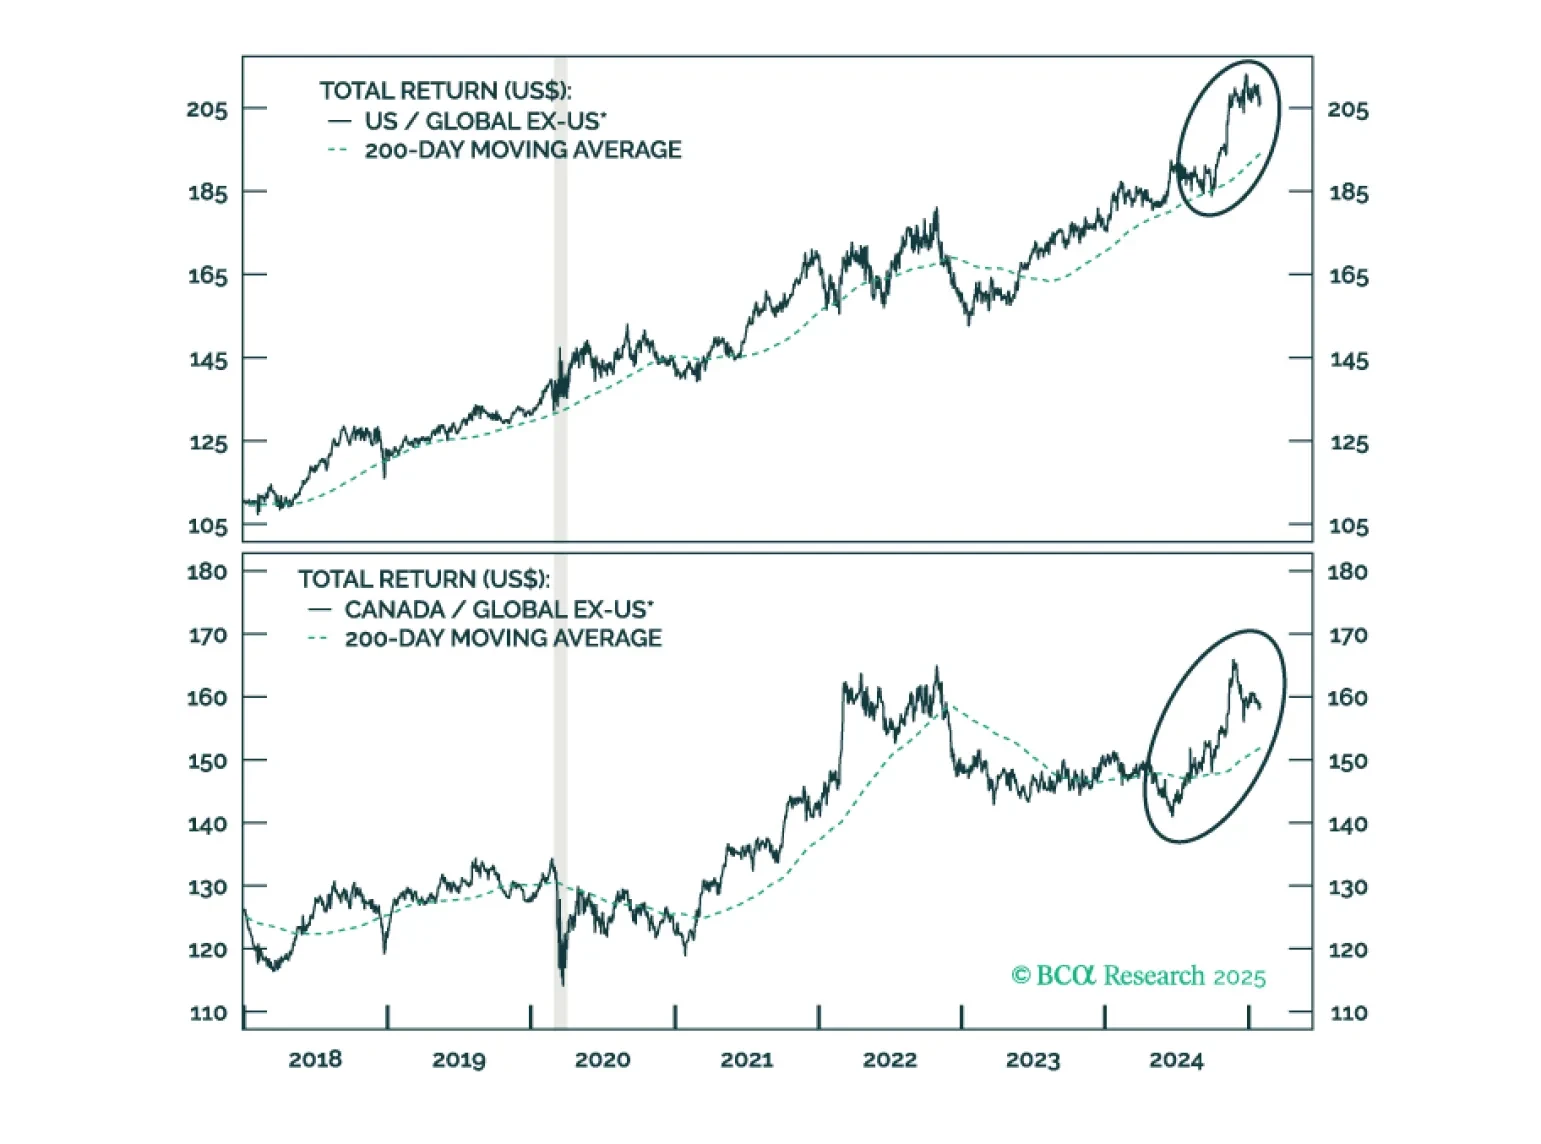
Jonathan provides an update on Canada following strong performance from Canadian stocks last year. On a tactical basis, underweight Canada versus global ex-US on the expectation of tariffs targeting Canada and Mexico. Following a sell off, or if a trade war is avoided, investors should place Canadian stocks on upgrade watch with the goal of moving to a modest overweight versus global ex-US.
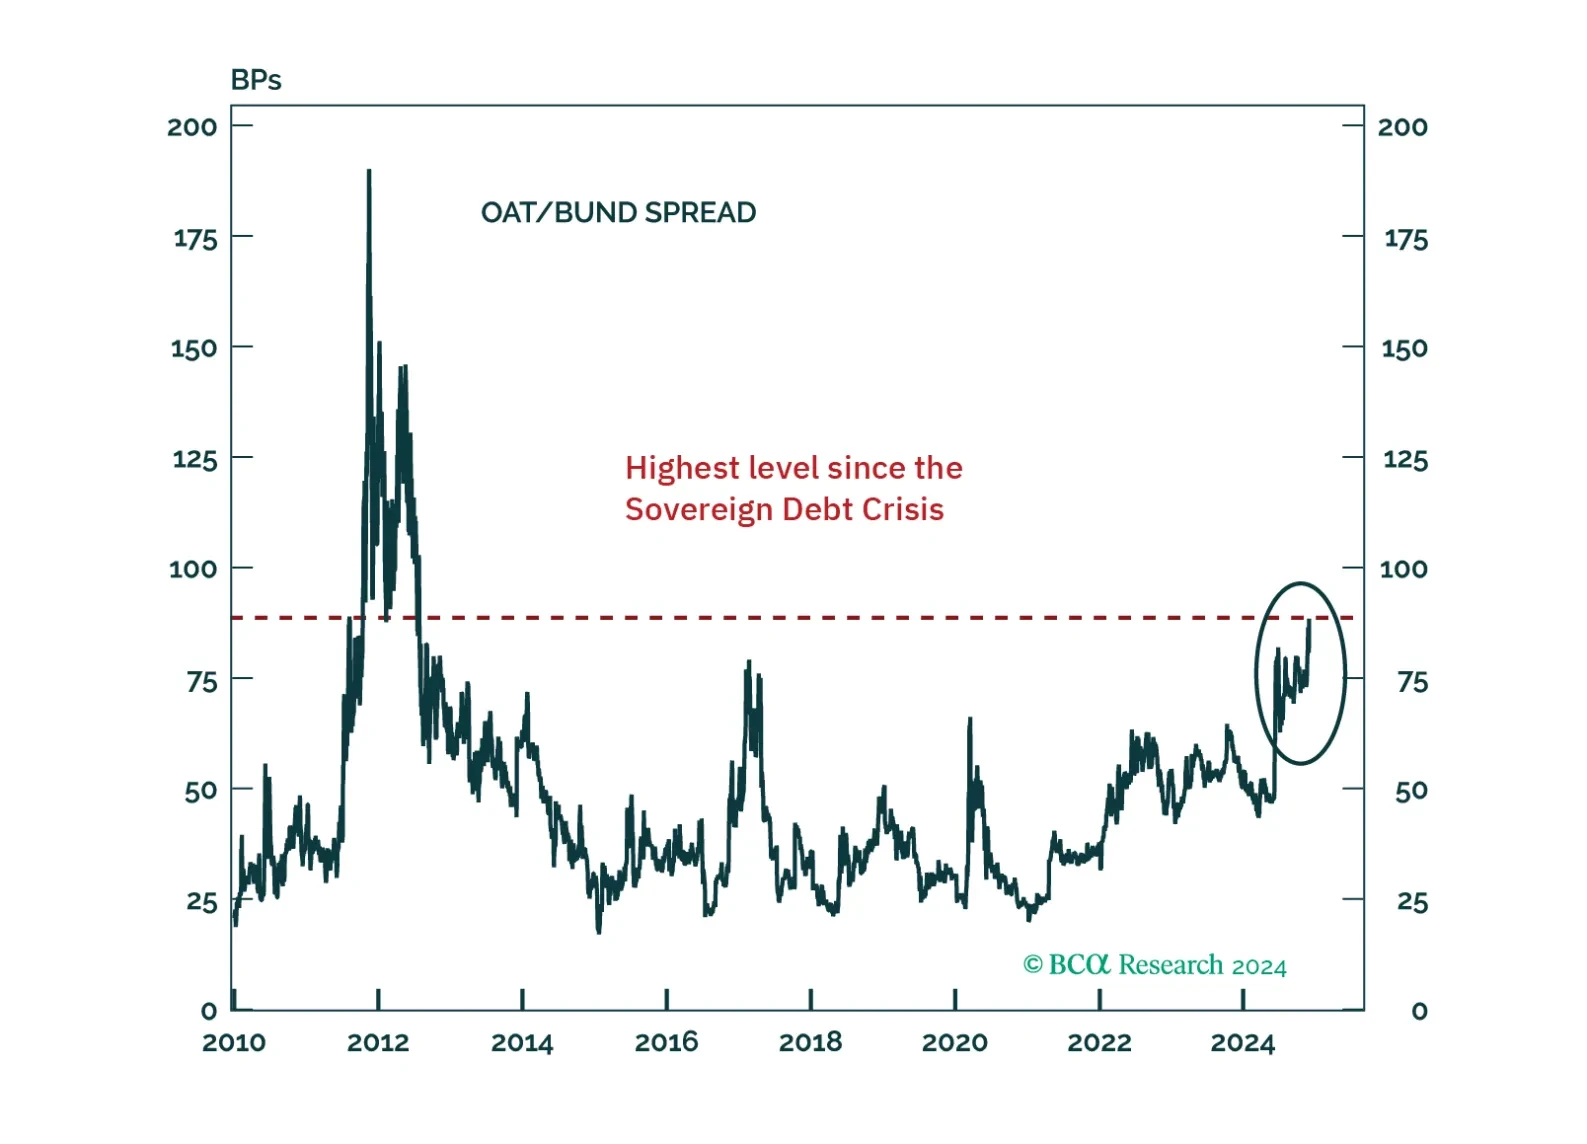
France finds itself in a unique, thorny situation. Can it heave itself out of it? And what does it mean for investors?
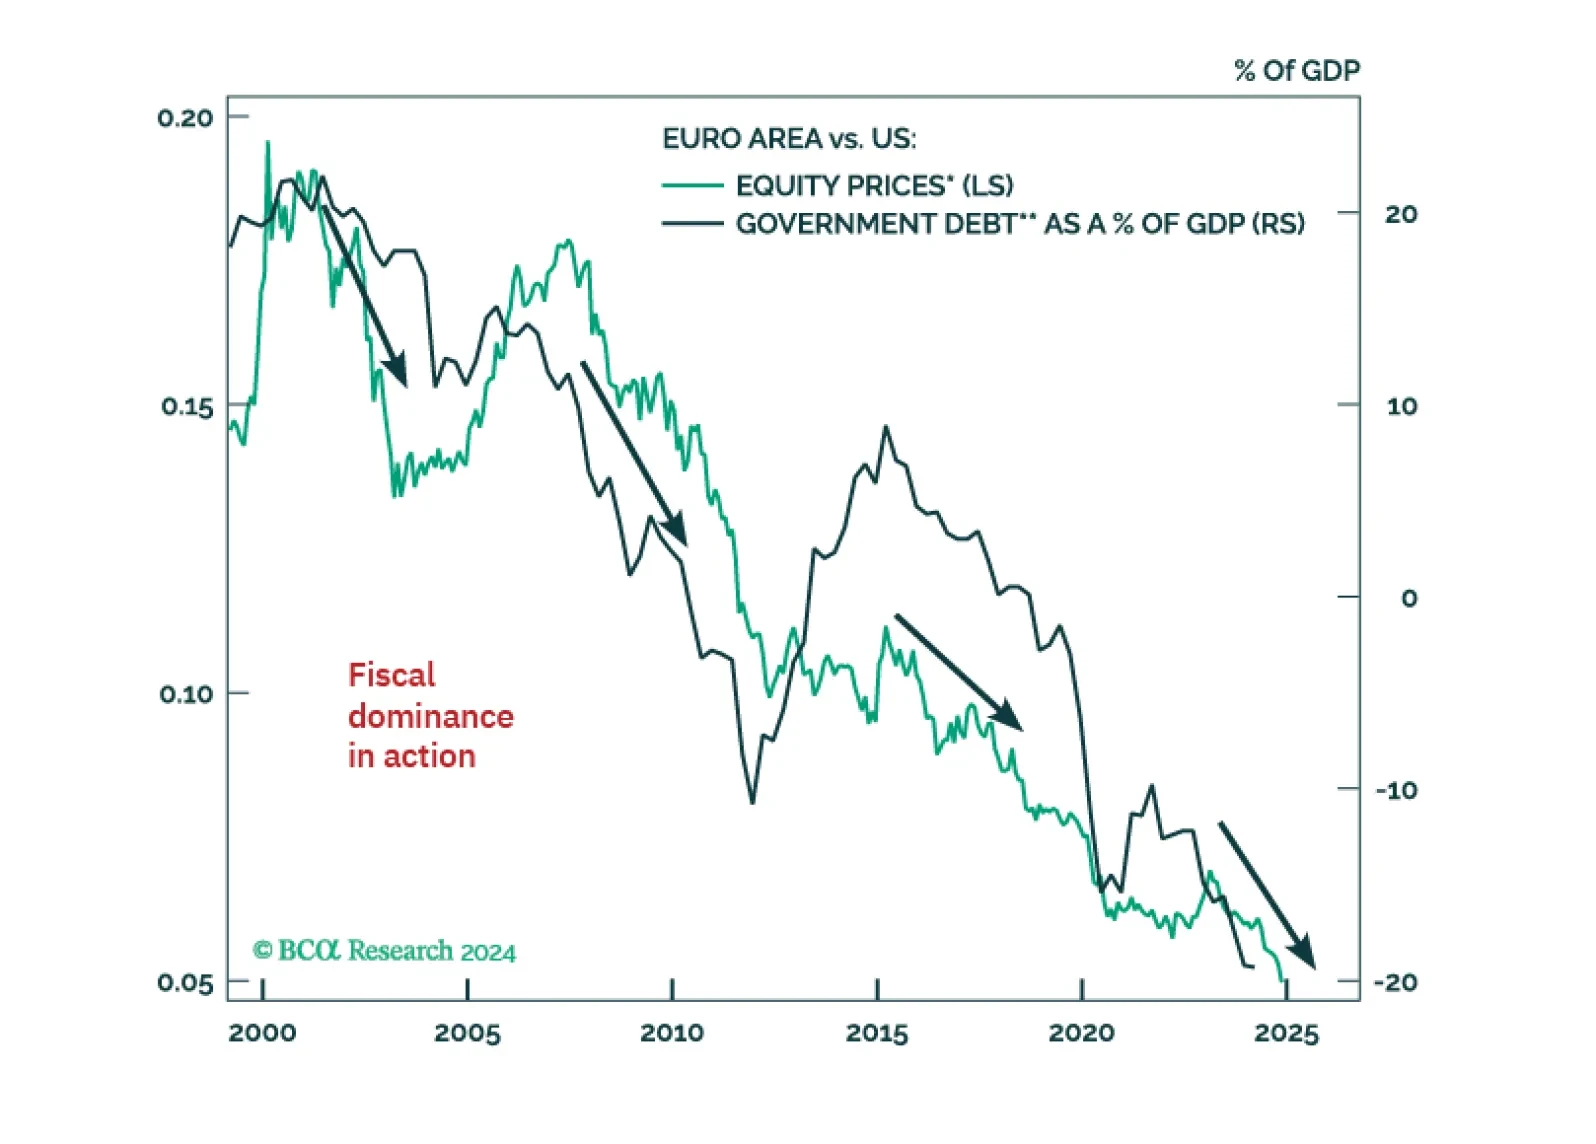
Los inversores han renunciado a los activos europeos, que ahora cotizan con descuentos excepcionales respecto a los activos estadounidenses. Sin embargo, una política fiscal estadounidense más restrictiva, el fin de la austeridad y del desapalancamiento en Europa, el tsunami de GNL a punto de golpear las costas europeas y el capex global impulsado por la Tríada Geopolítica Imposible significan que el momento de gloria de Europa pronto volverá.