Skip to main content

Emerging Markets

Our Portfolio Allocation Summary for October 2026.

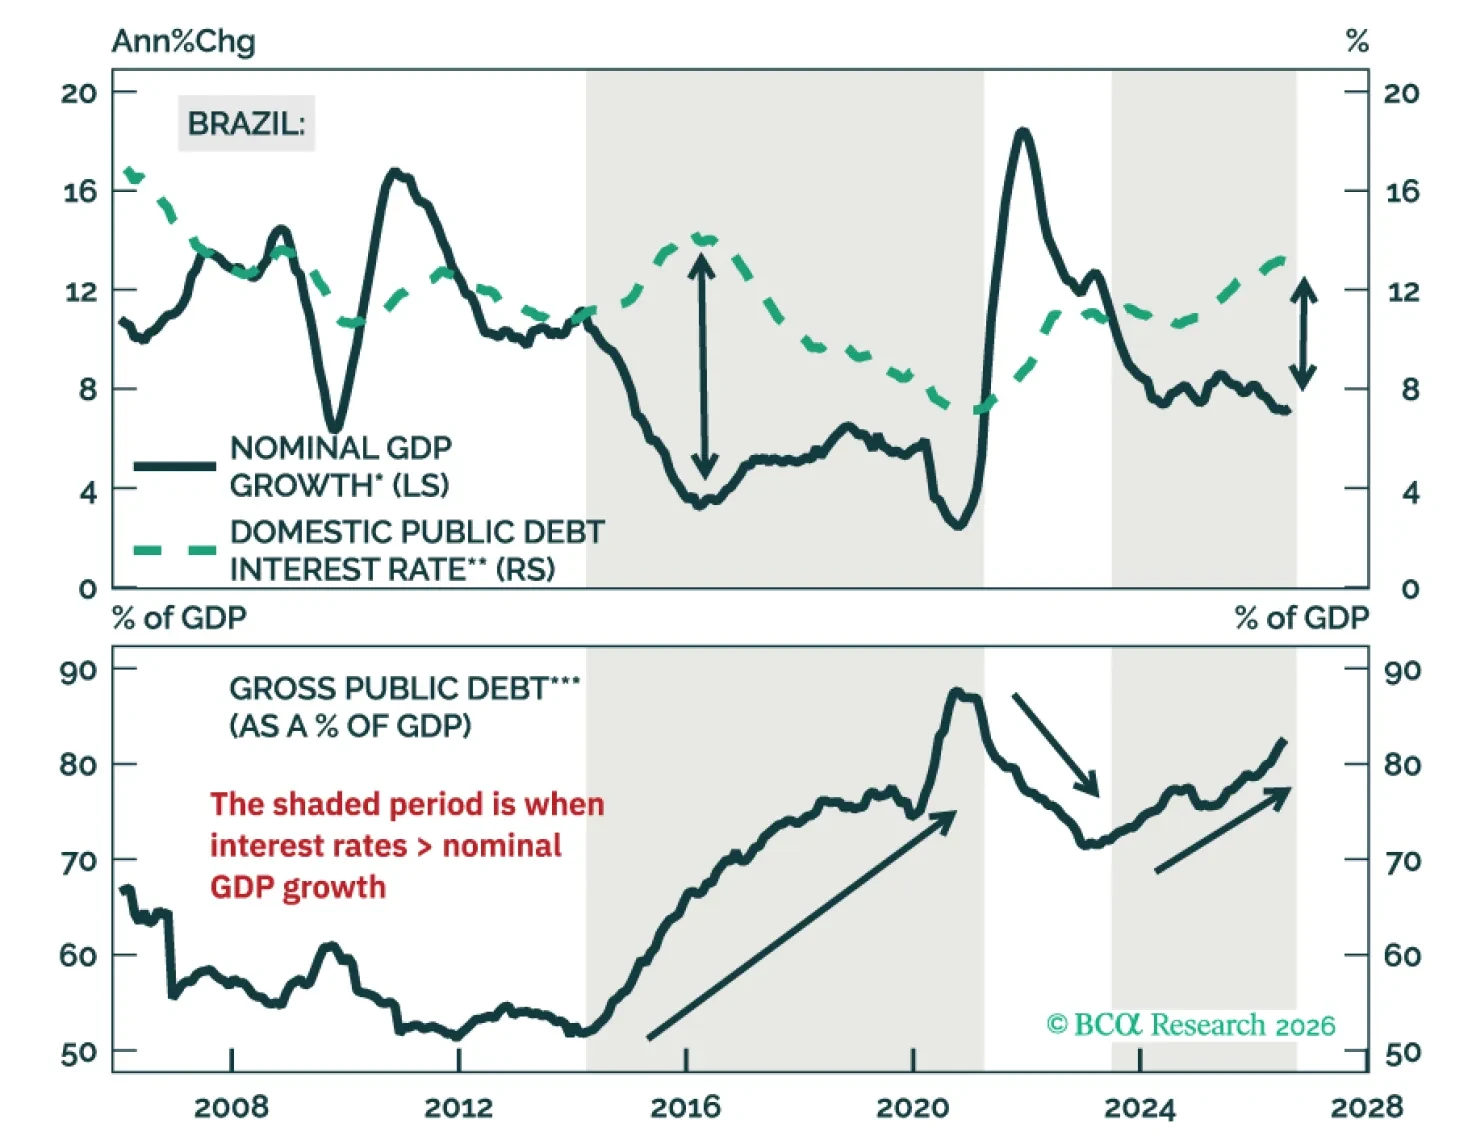
The most bullish development for Brazil from the weekend’s elections was not the higher odds of a right-wing presidency, but the likely president’s (Flávio Bolsonaro) stronghold in Congress. Upgrade Brazilian fixed-income markets to overweight and equities to neutral within their respective EM portfolios.
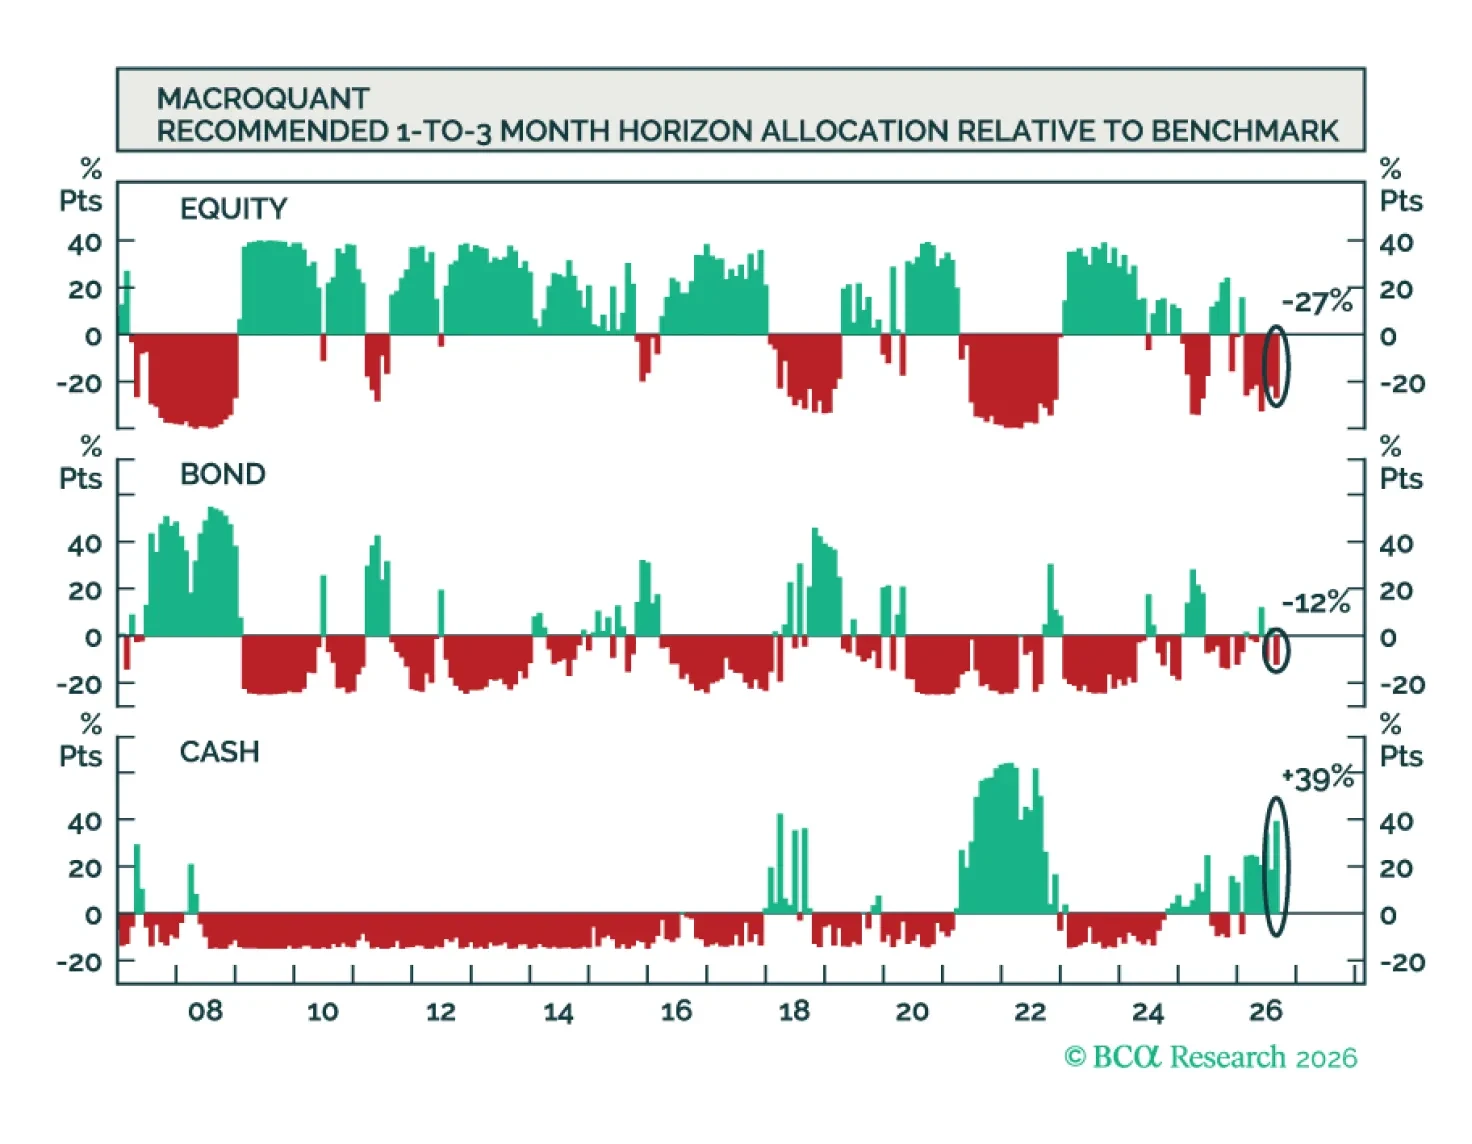
MacroQuant recommends an underweight to equities and bonds, counterbalanced by a significant overweight to cash. The model is very bullish on the US dollar, slightly negative on gold and copper, and positive on oil.
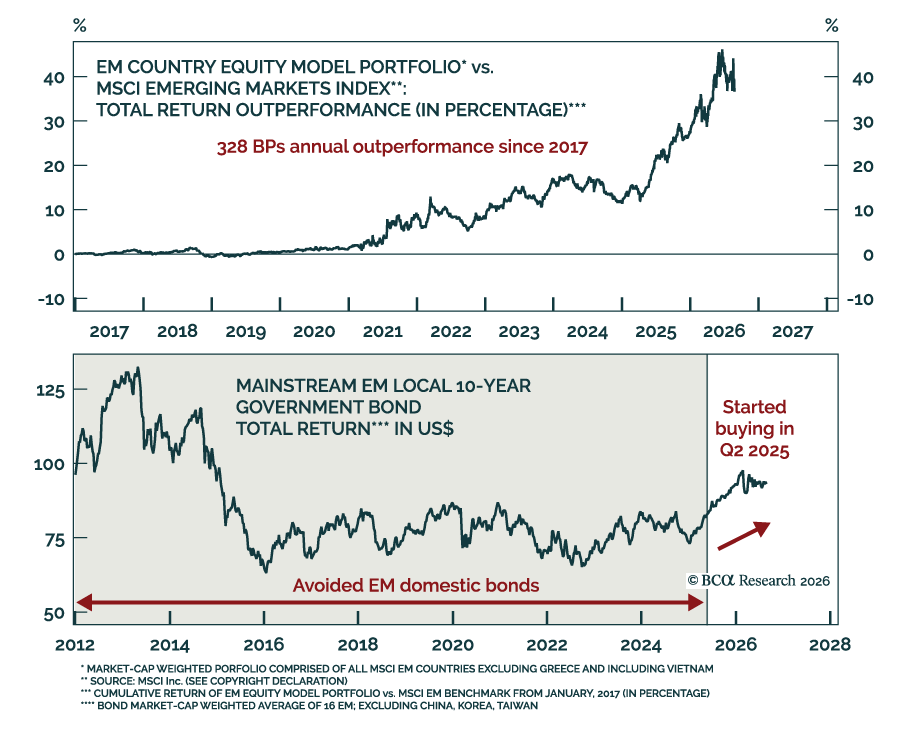
Our EM team has conducted a review of past investment recommendations, highlighting both successful calls and positions that did not work as expected. Our Chart Of The Week comes from Arthur Budaghyan, Chief EM/China Strategist and Head of our CoreMacro…

Our Portfolio Allocation Summary for September 2026.

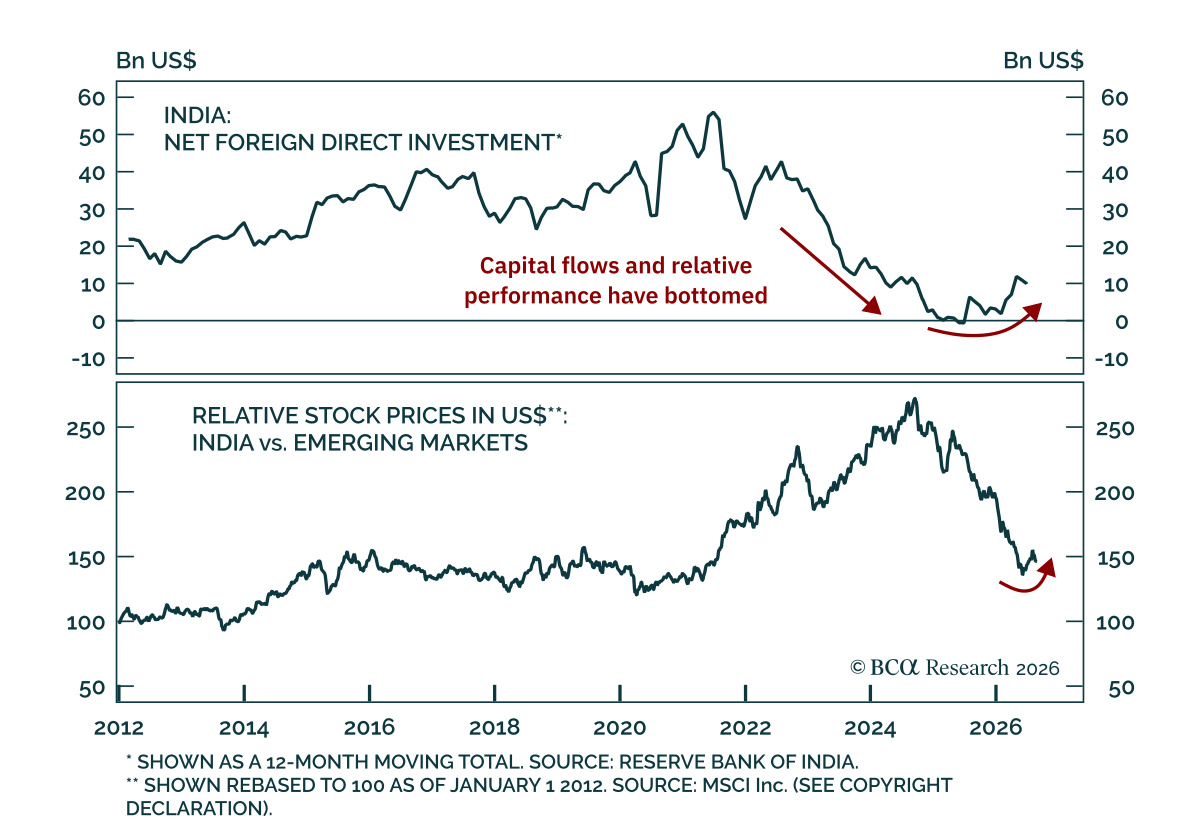
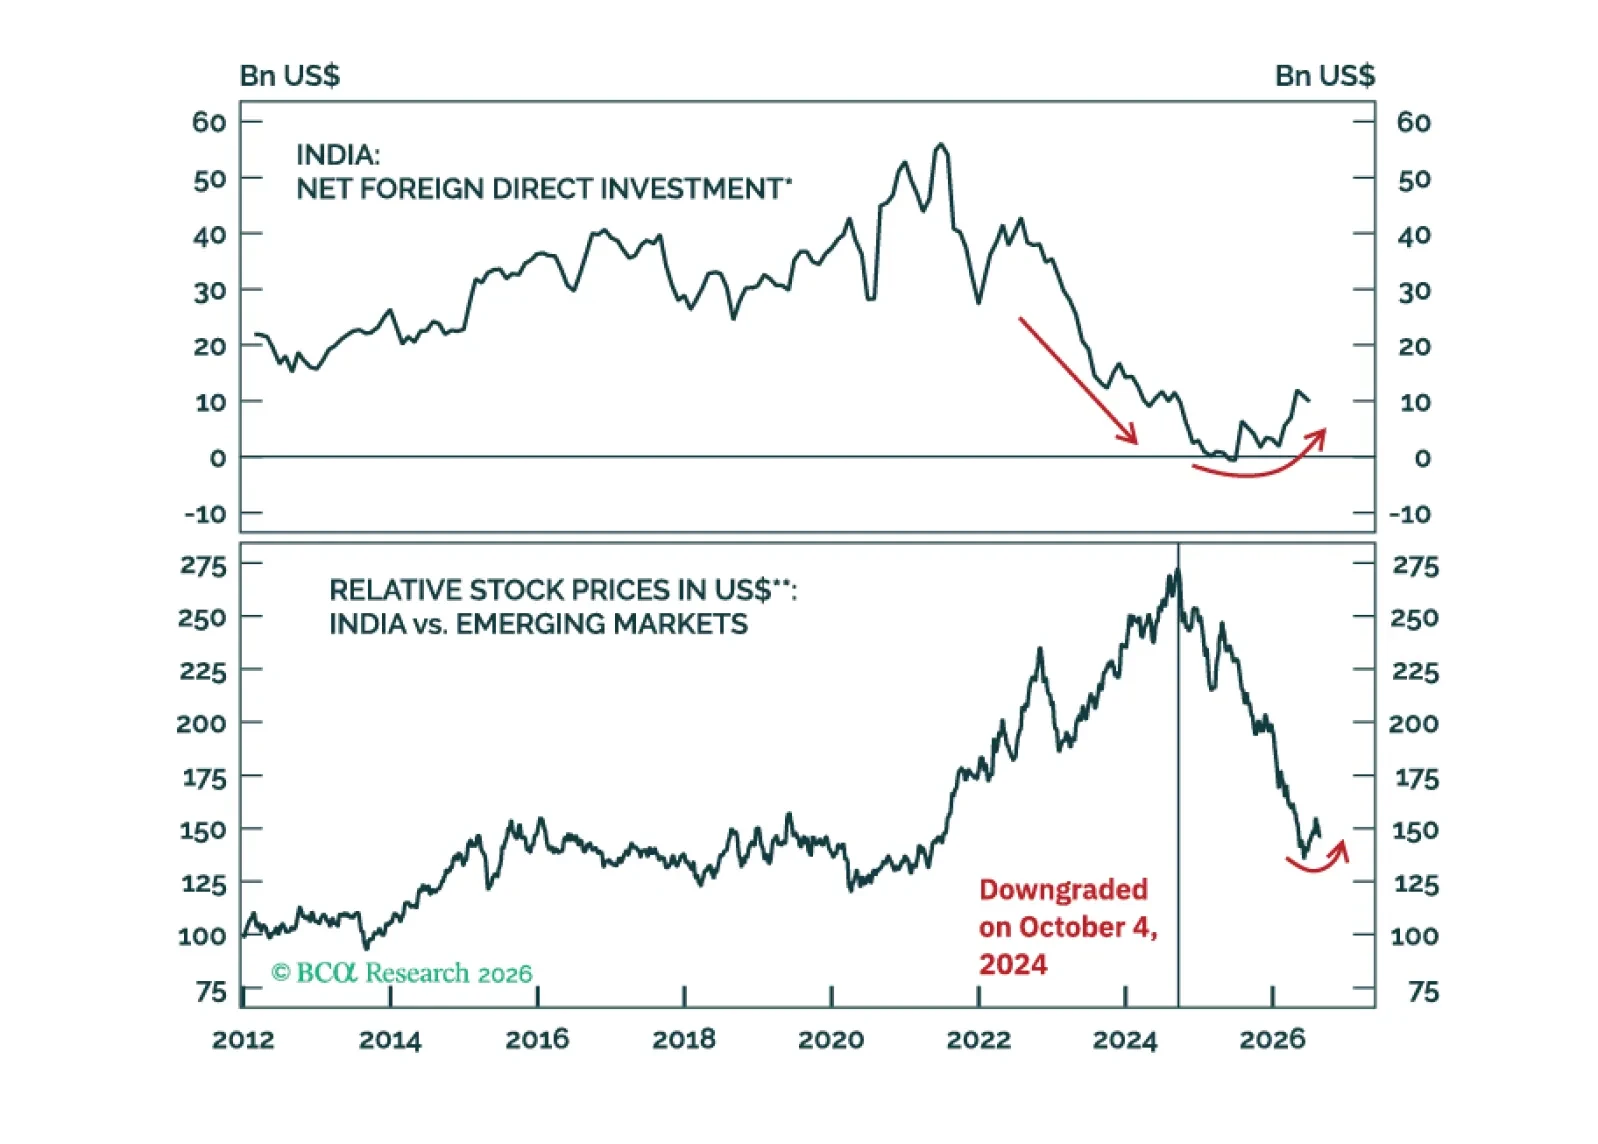
Our EM strategists recommend upgrading India to overweight in EM equity portfolios, lifting domestic bonds to overweight from neutral, while our Private Markets strategists also remain constructive on India. India has largely avoided the Hormuz shock, so…

BCA's CoreMacro and Portfolio Construction teams combine two distinct but intersecting lenses to revisit a once heralded opportunity: India. We upgrade India across both public and private markets, but the conviction is not the same everywhere.
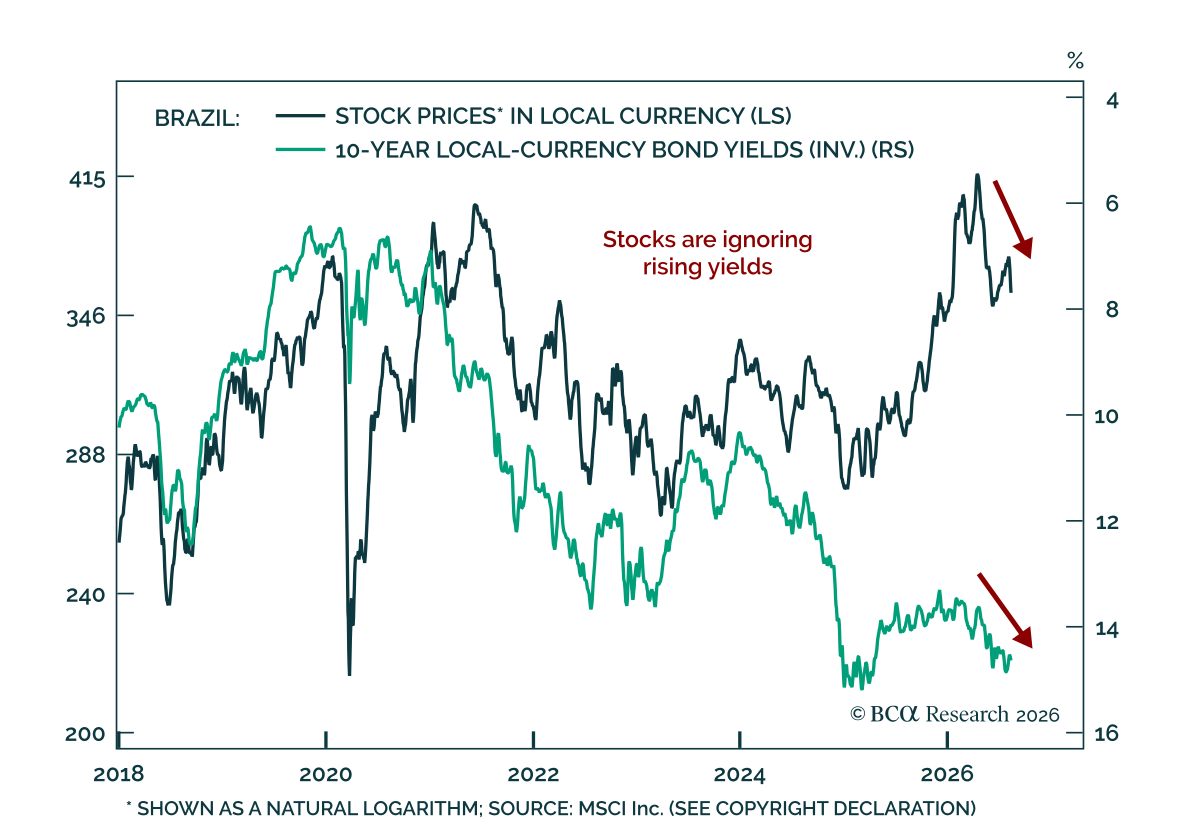
Our EM strategists are downgrading Brazilian equities from neutral to underweight and advise absolute-return investors to stay clear of Brazilian markets. They maintain underweights in domestic bonds and sovereign credit within their respective EM portfolios.…
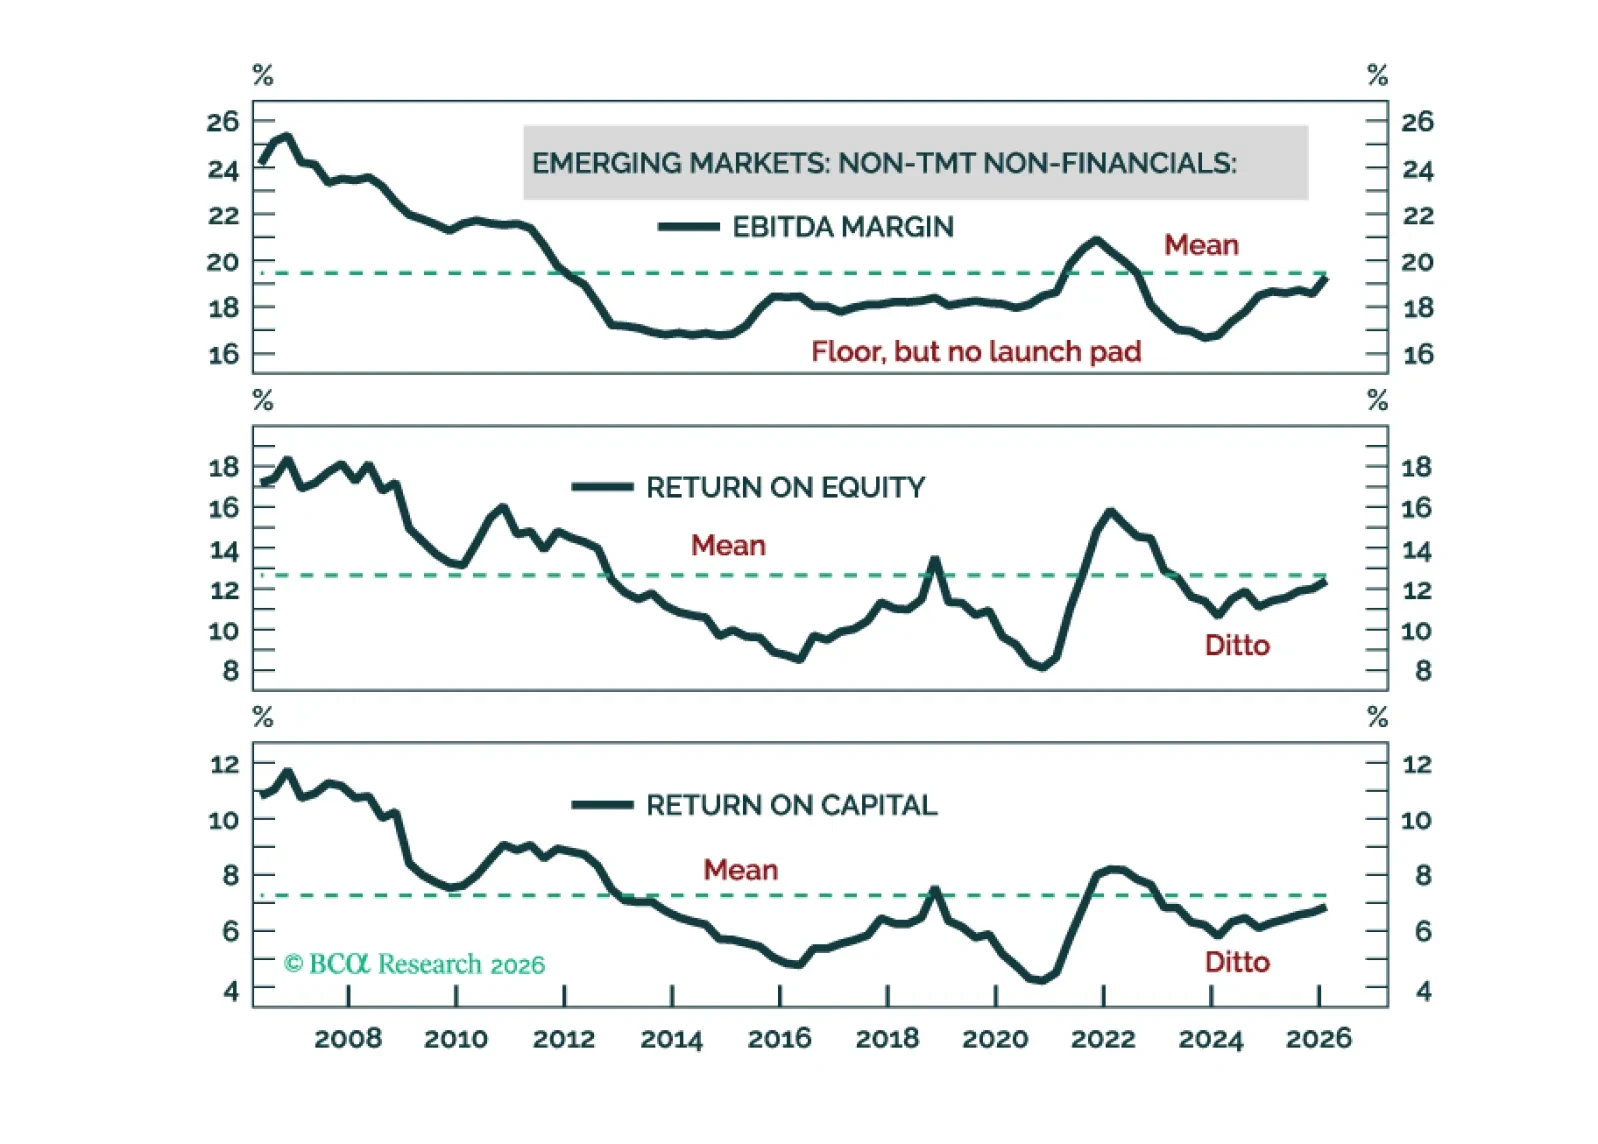
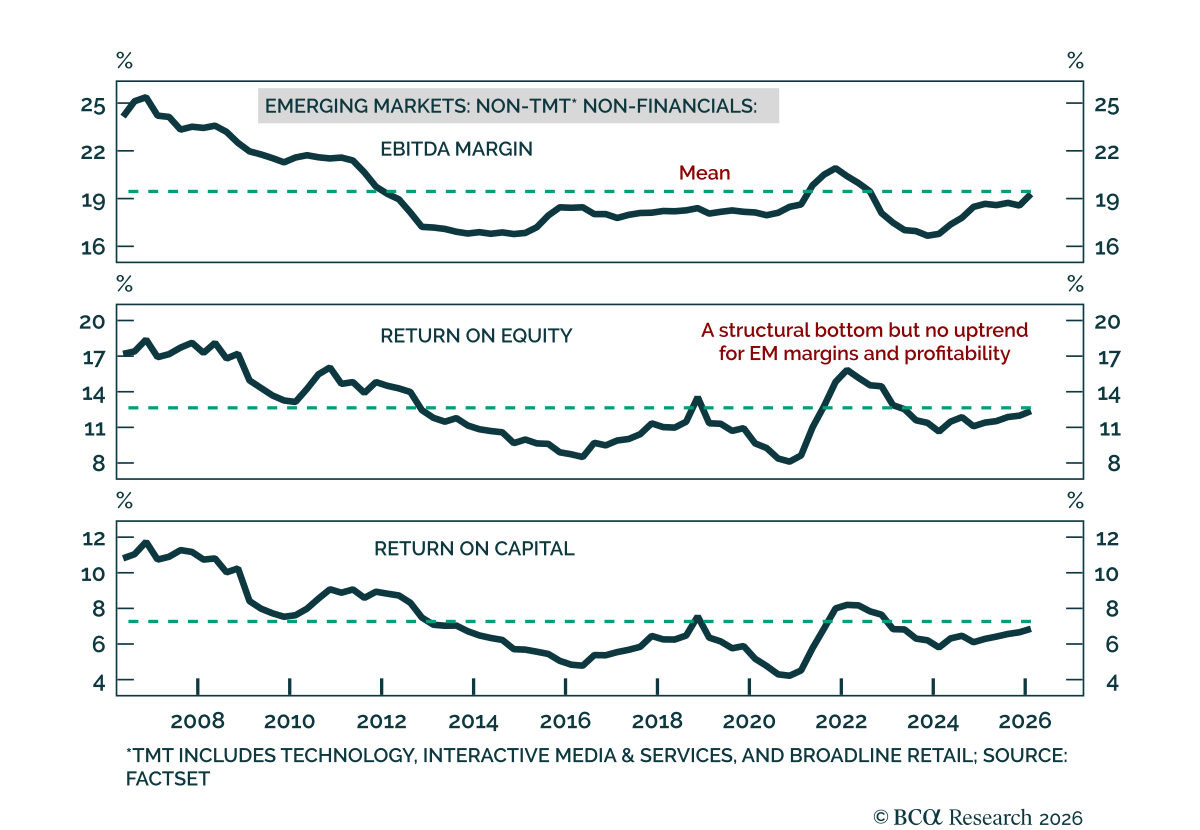
Our EM strategists see no case for structural EM equity outperformance and recommend a neutral allocation within global equity portfolios. Outside semiconductor producers and financials, EM profitability sits well below that of US peers and the levels reached…
Special Report

Outside semiconductor stocks, EM/China profitability has been well below both their US peers and the levels that prevailed during the EM structural bull market in the 2000s. Over a 3- to 5-year horizon, EM/China relative equity performance versus global will be range-bound.