Latest from BCA Research
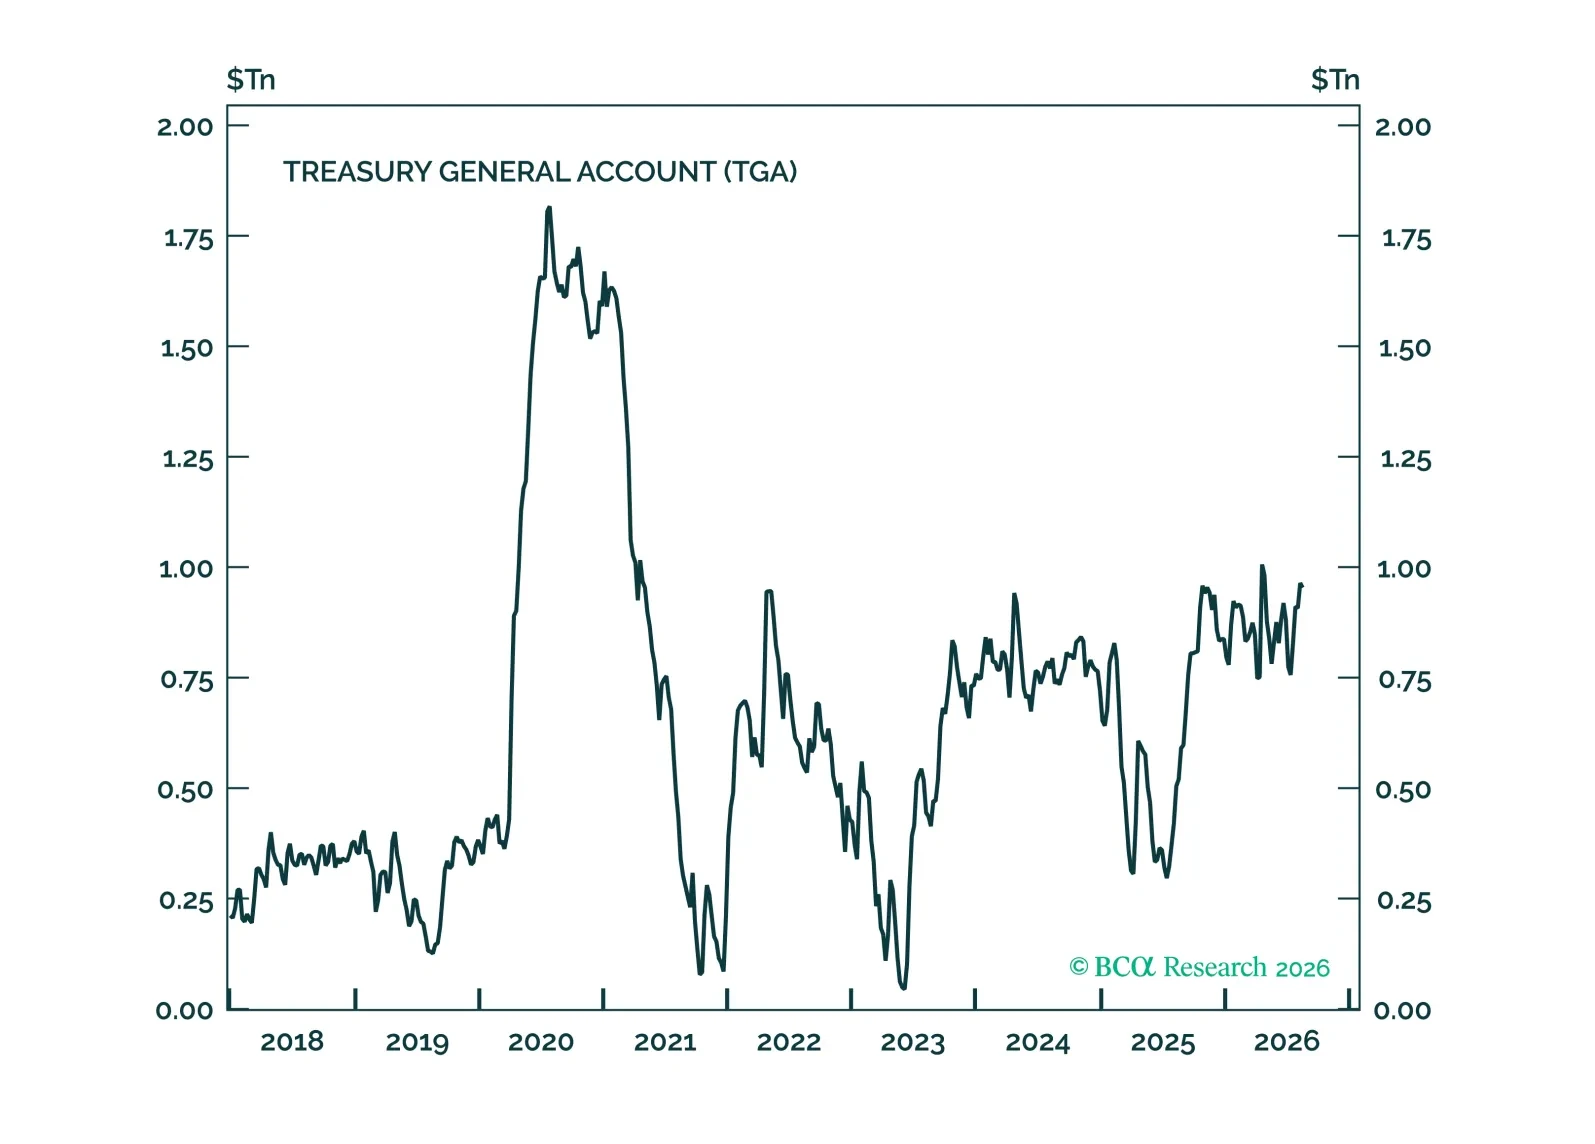
The US Treasury department’s attempts at yield suppression are doomed to fail unless the Federal Reserve gets involved.
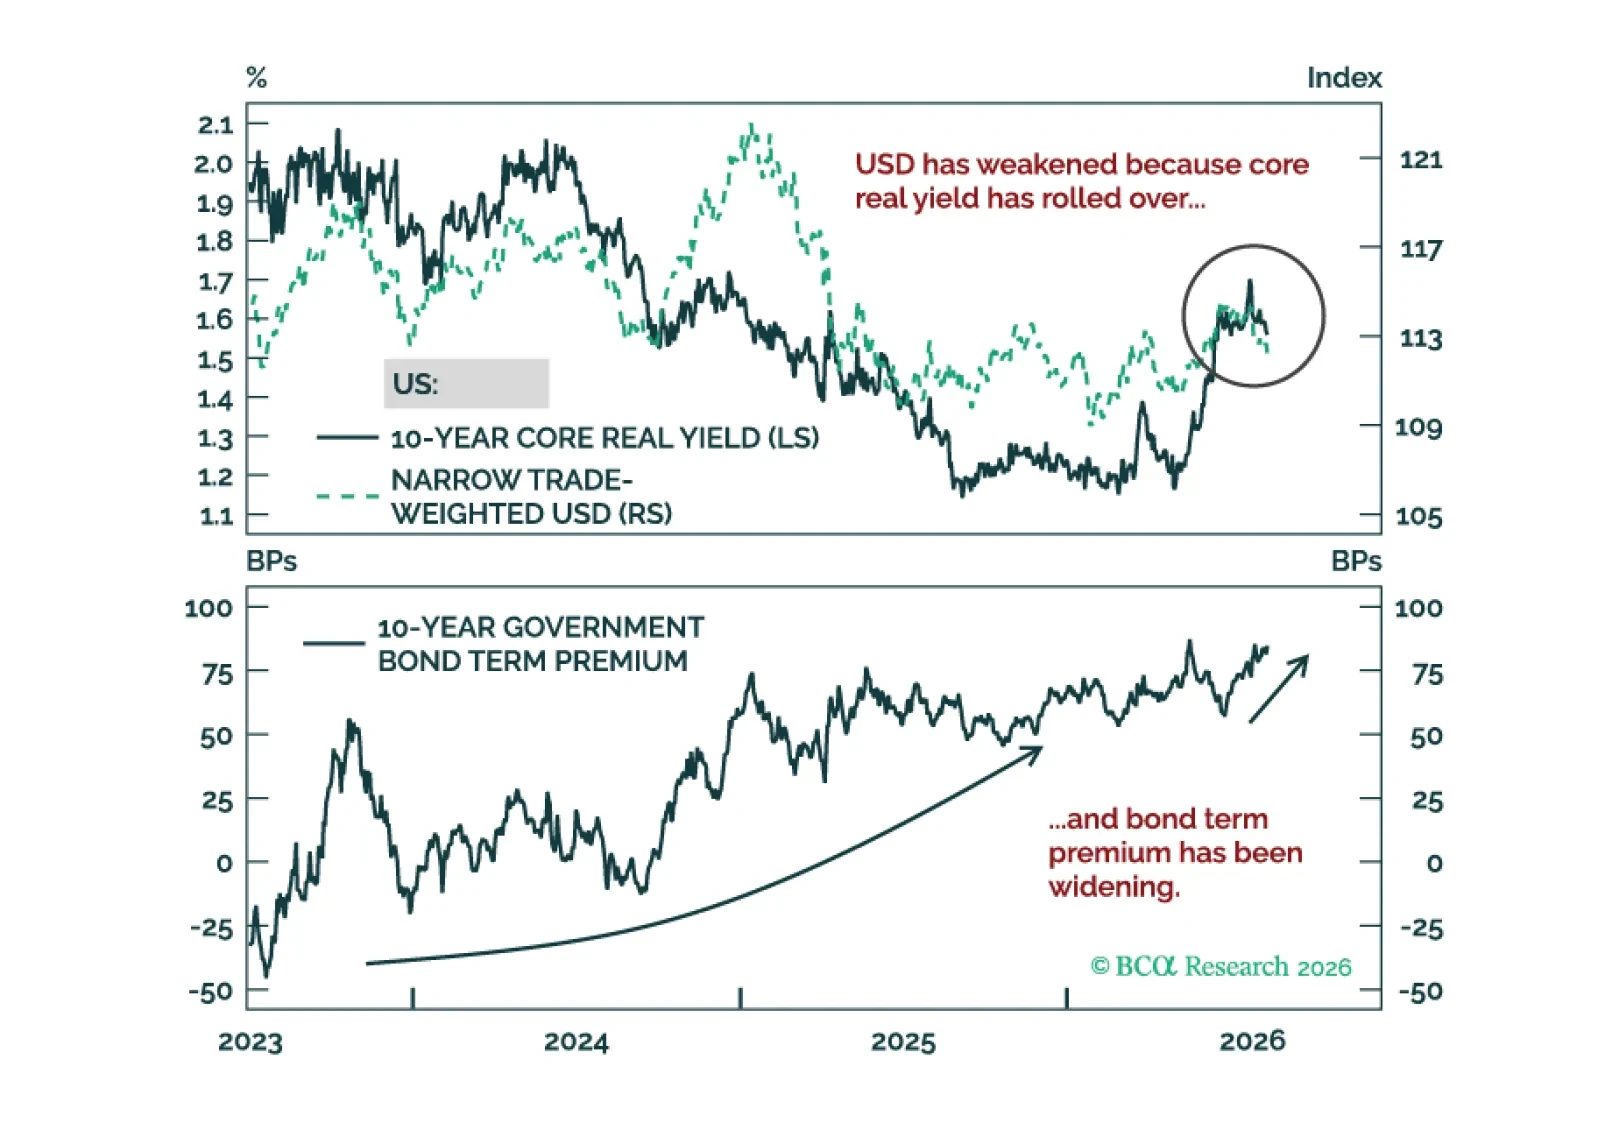
If bond yields rise due to widening bond term premiums or escalating inflation expectations, Bessenomics is unlikely to avert a stock-bond collision. Buy back gold mining stocks.
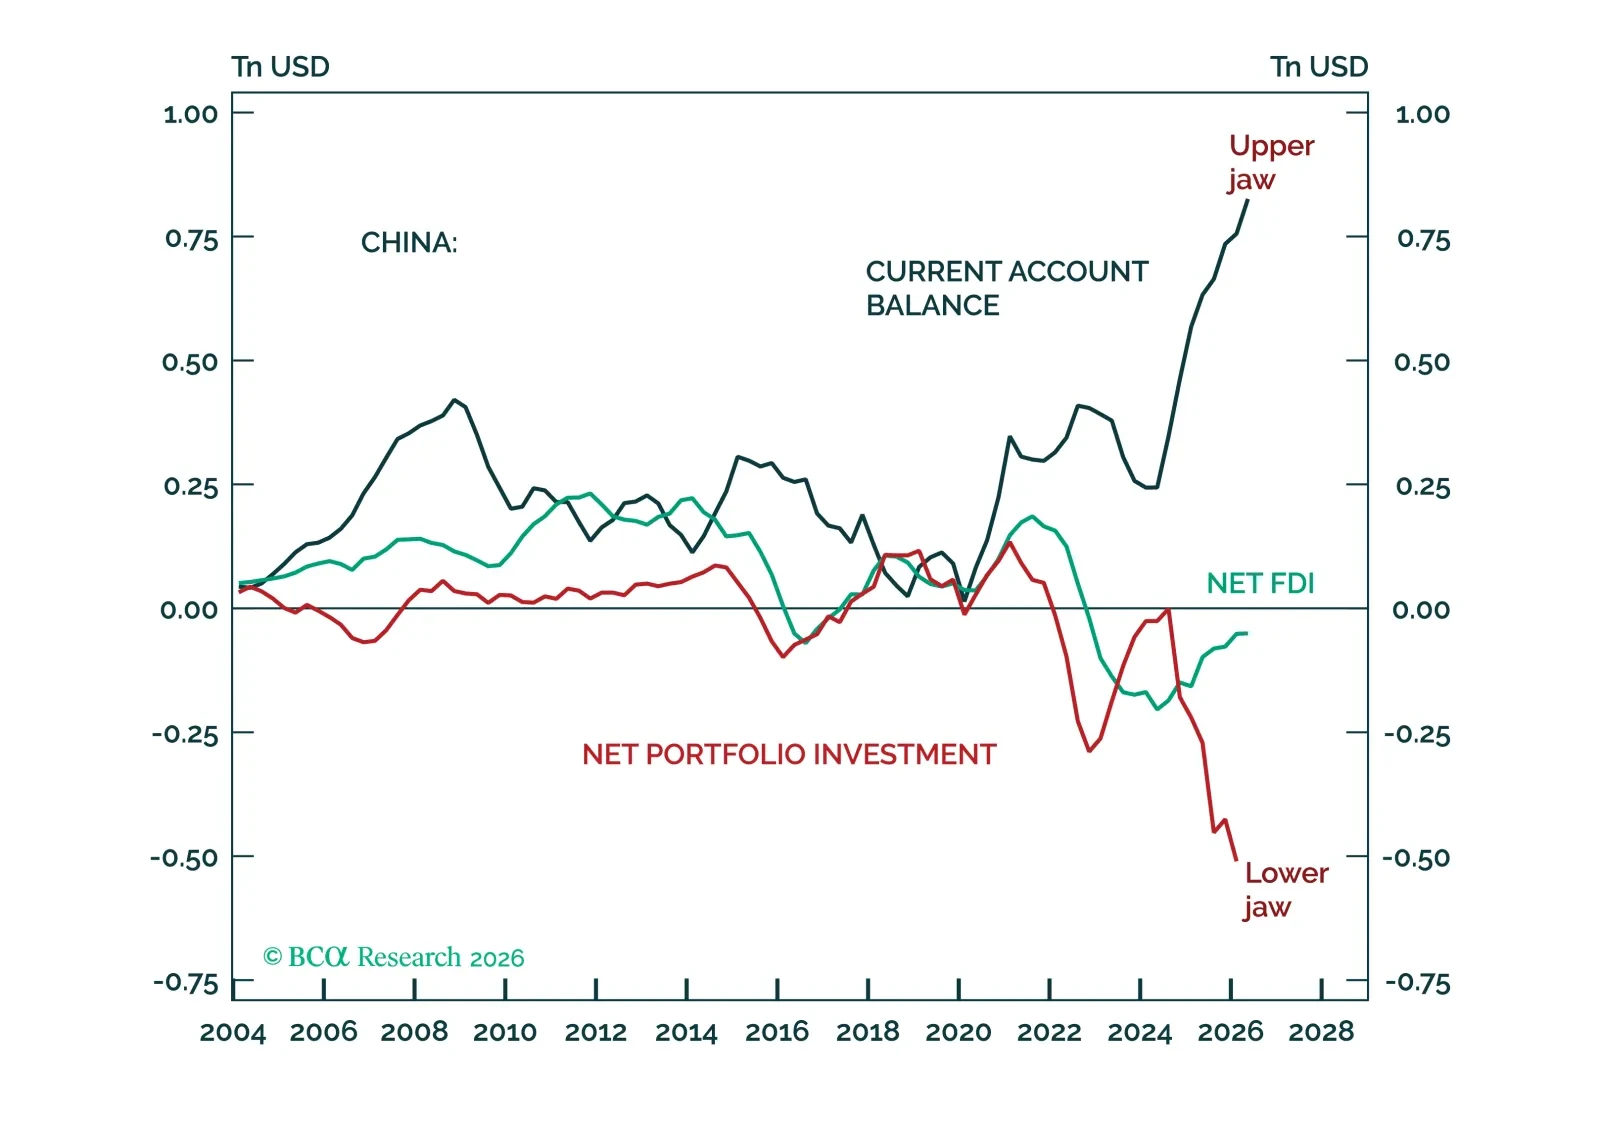
In this report, we highlight notable developments on both sides of China’s BoP: a widening external surplus on the current account side, and shifts in how that surplus is recycled abroad through BoP financial account.
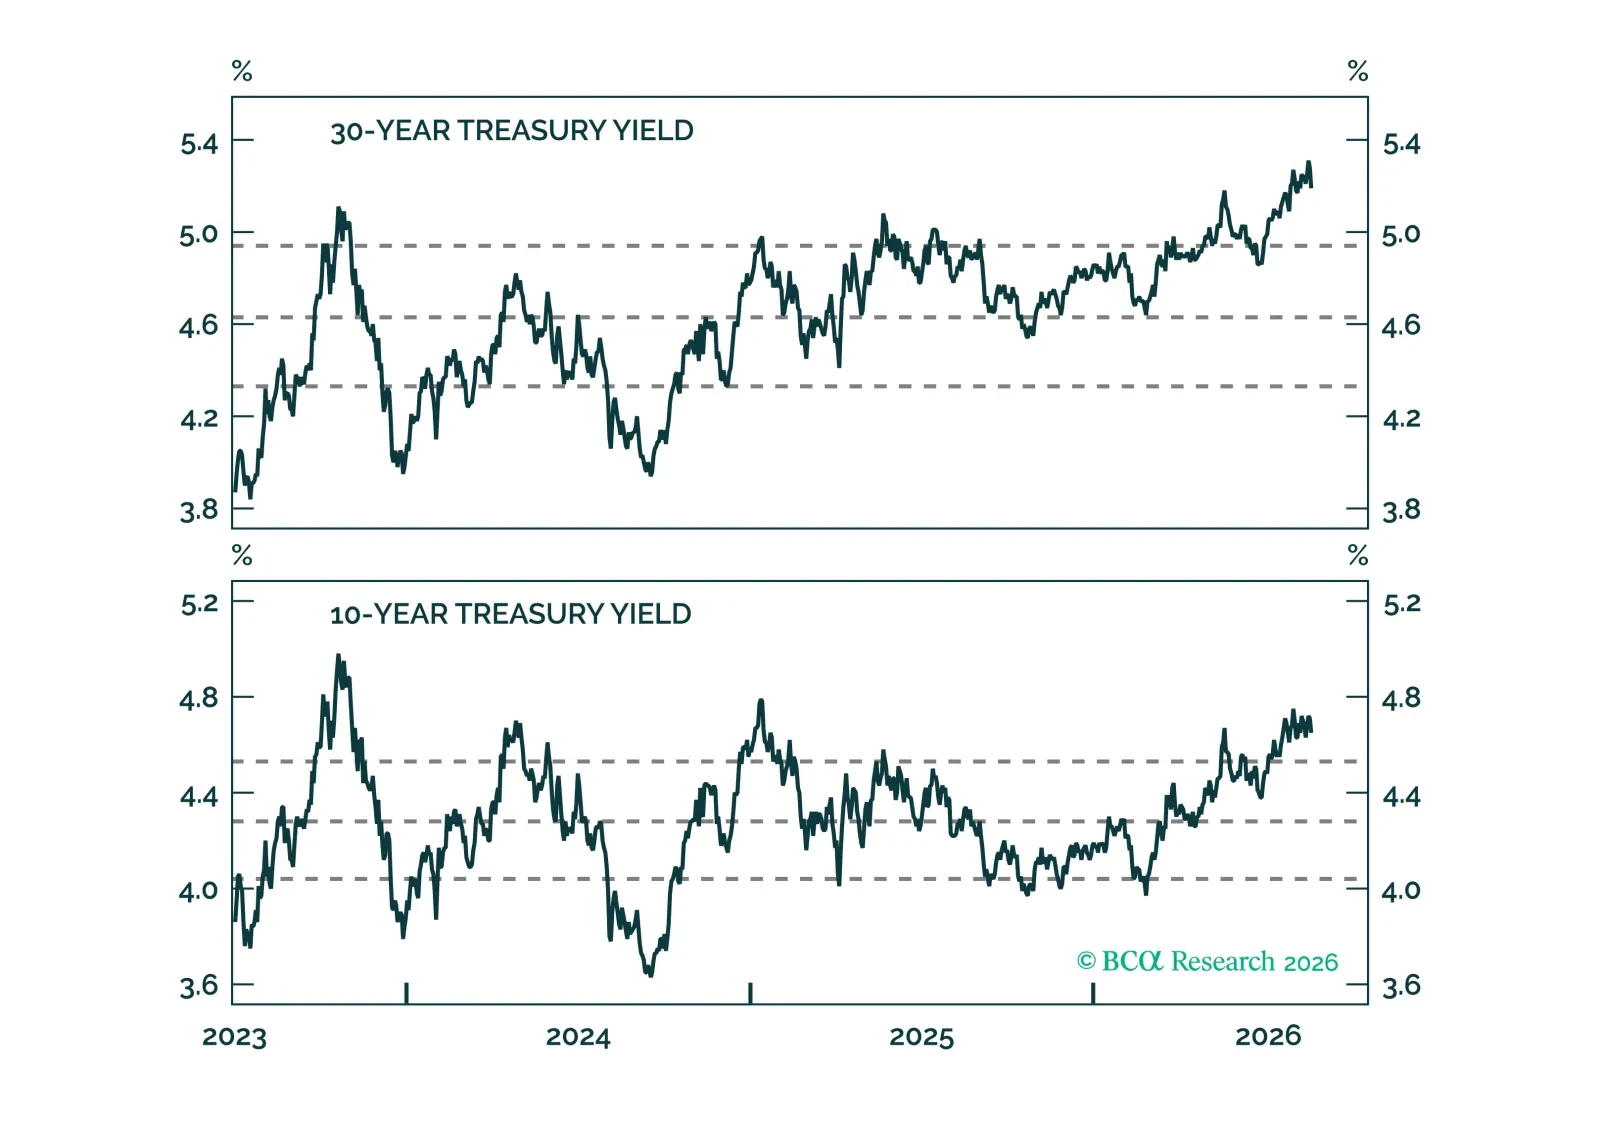
Despite recent increases, long-maturity Treasury yields are roughly consistent with fundamental fair value. We see limited value in long duration plays.
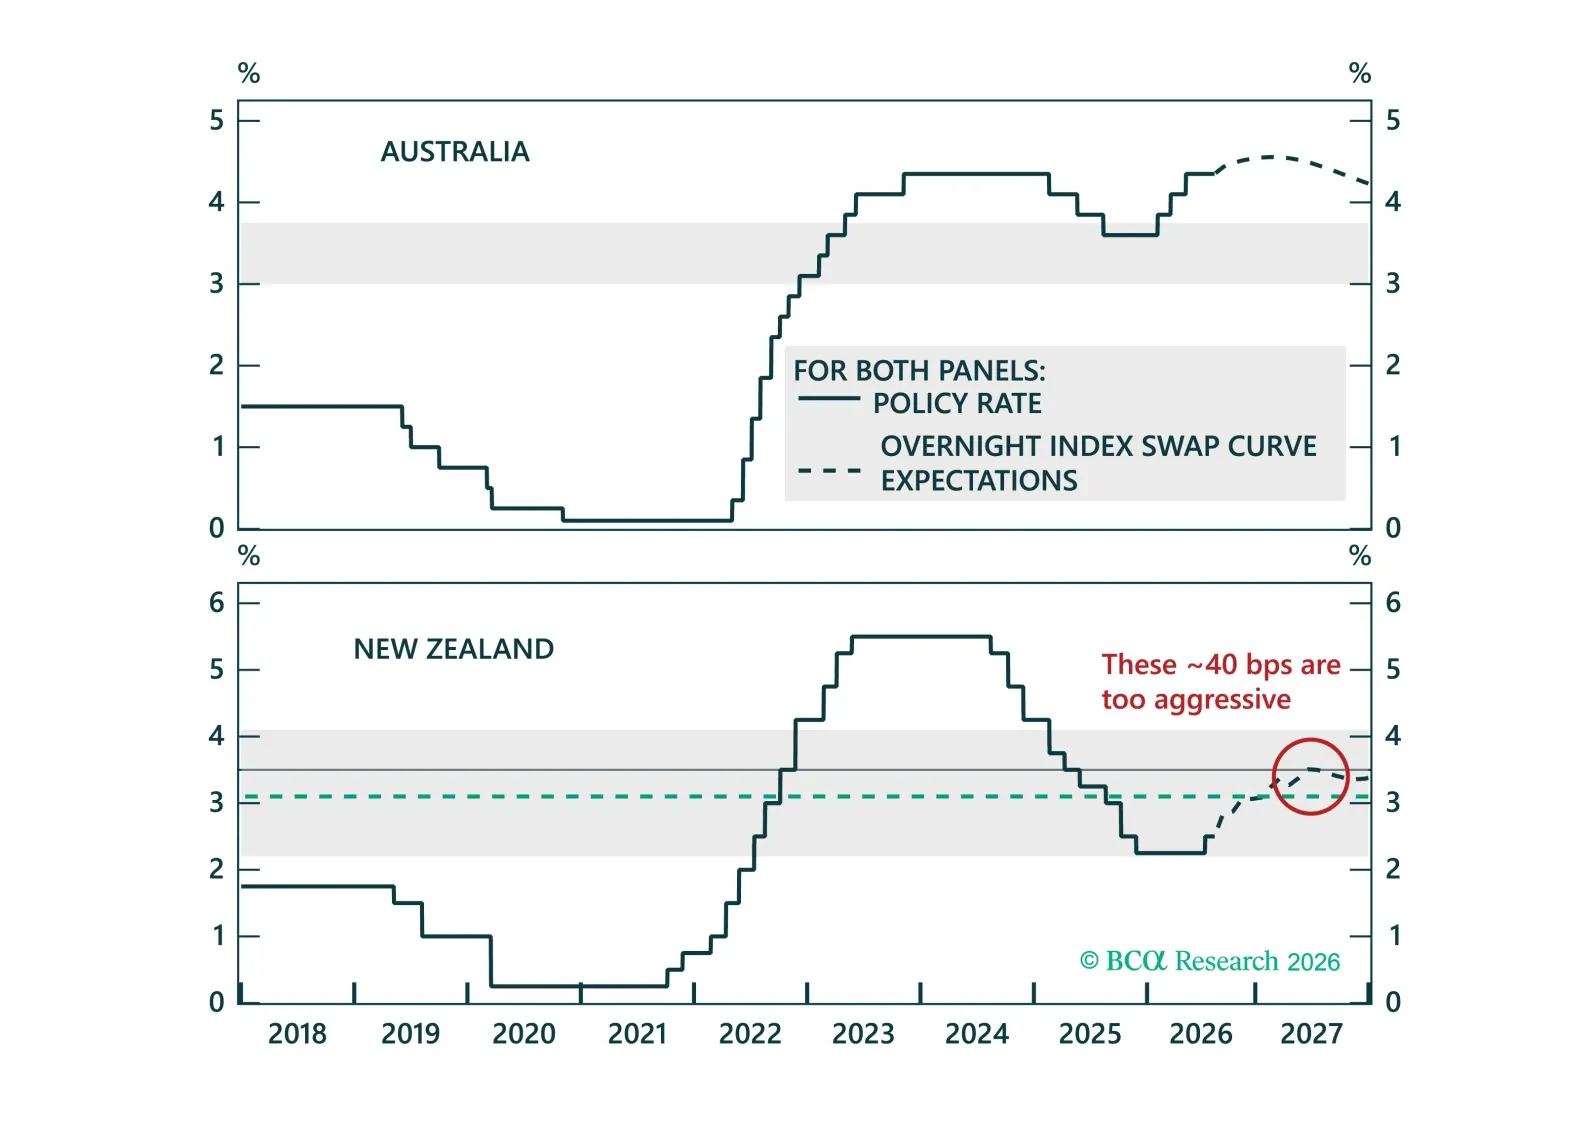
The RBA is likely done hiking, and the RBNZ overpriced for more hikes. We trace both conclusions back to housing, credit, and external dynamics, with implications for our country allocation in ANZ bonds and our long AUD/NZD view.
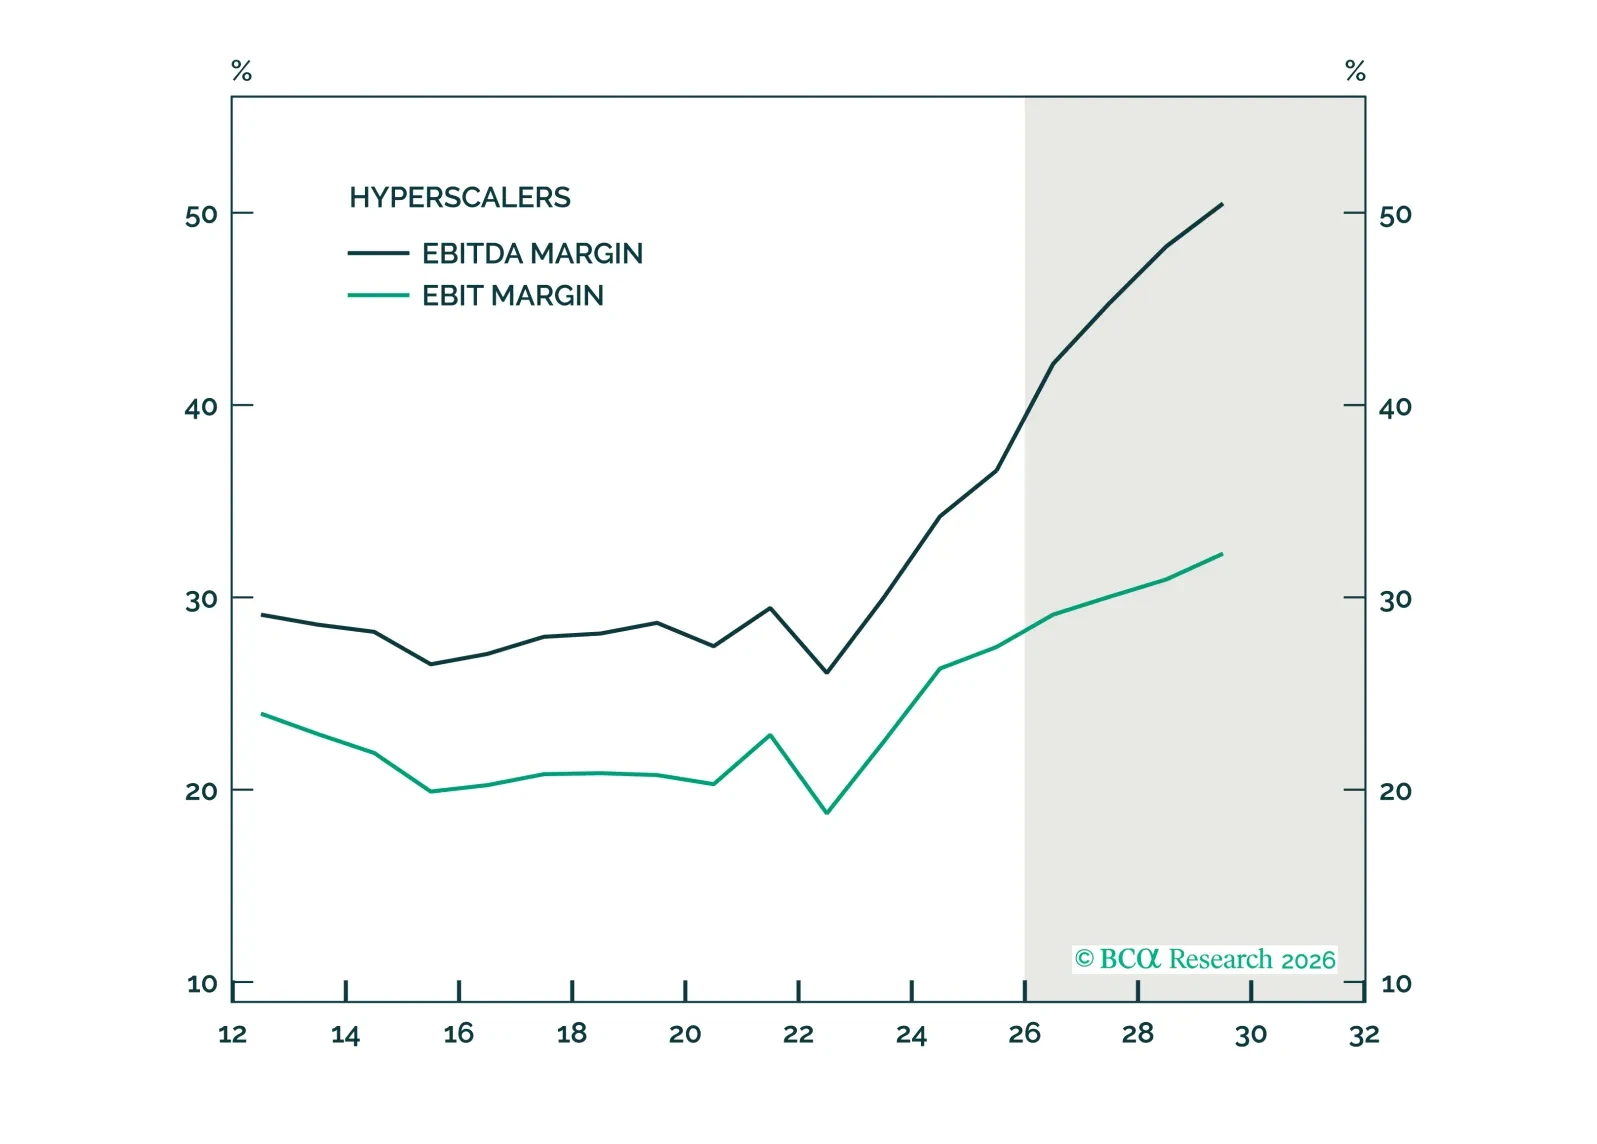
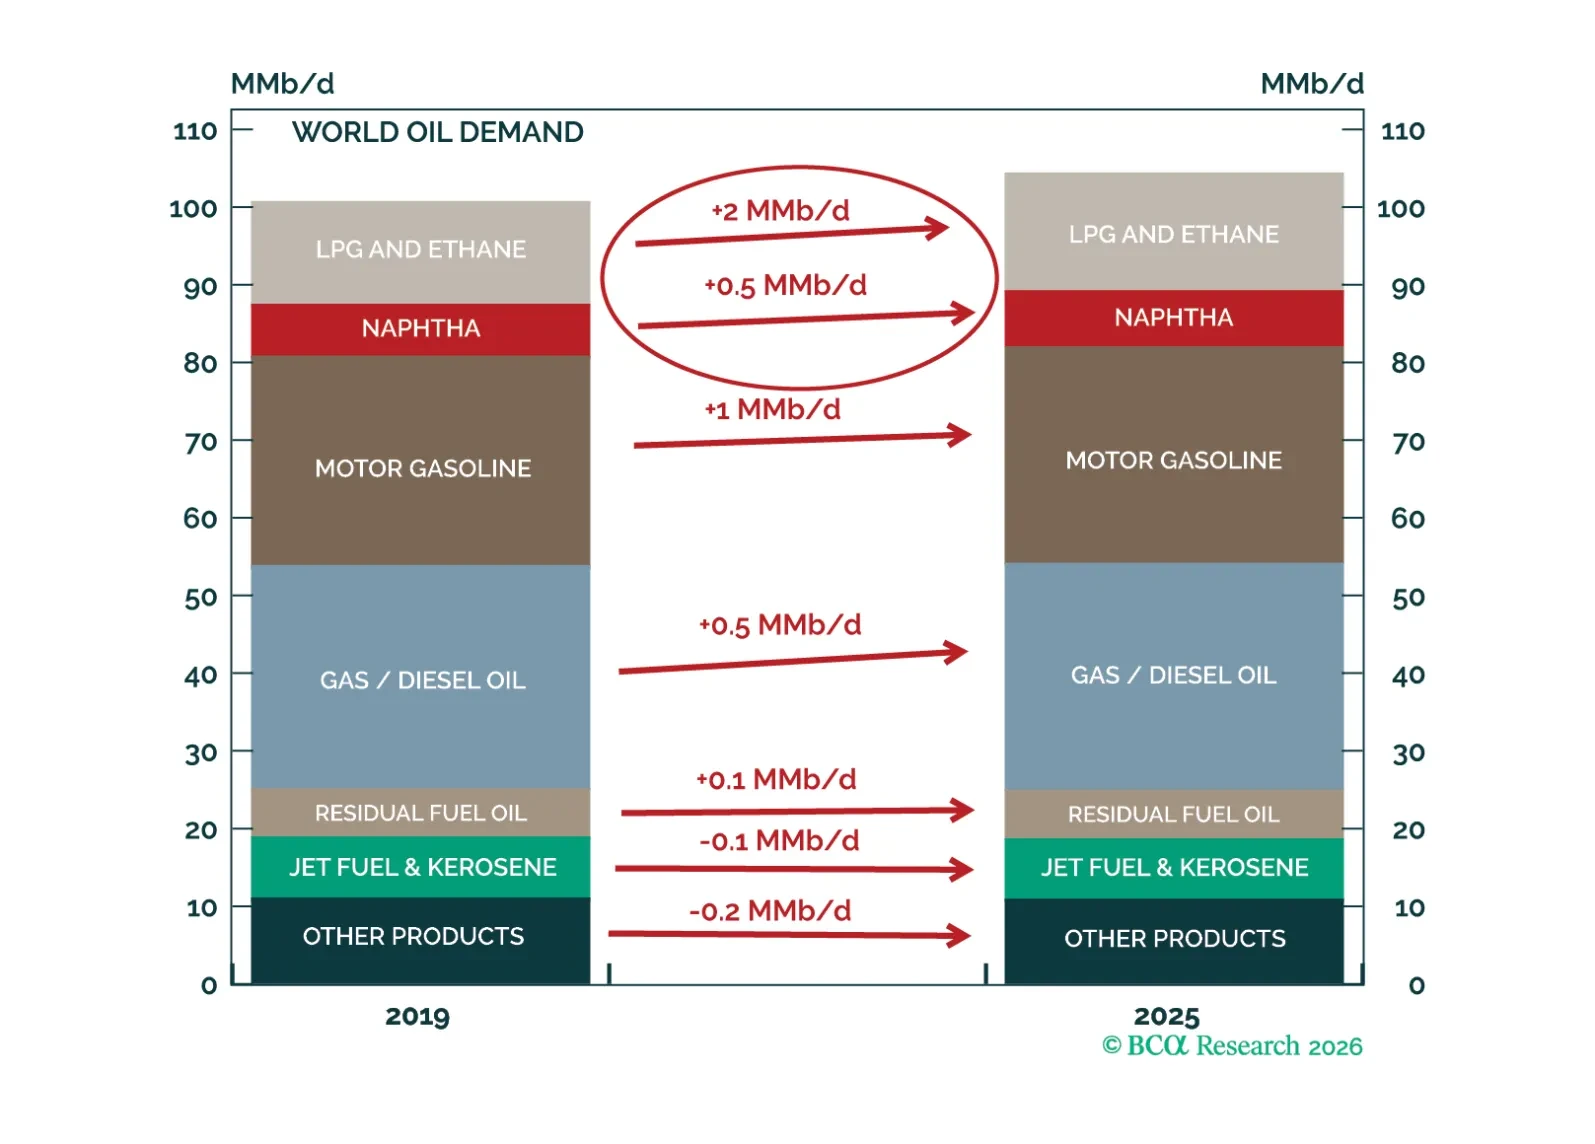
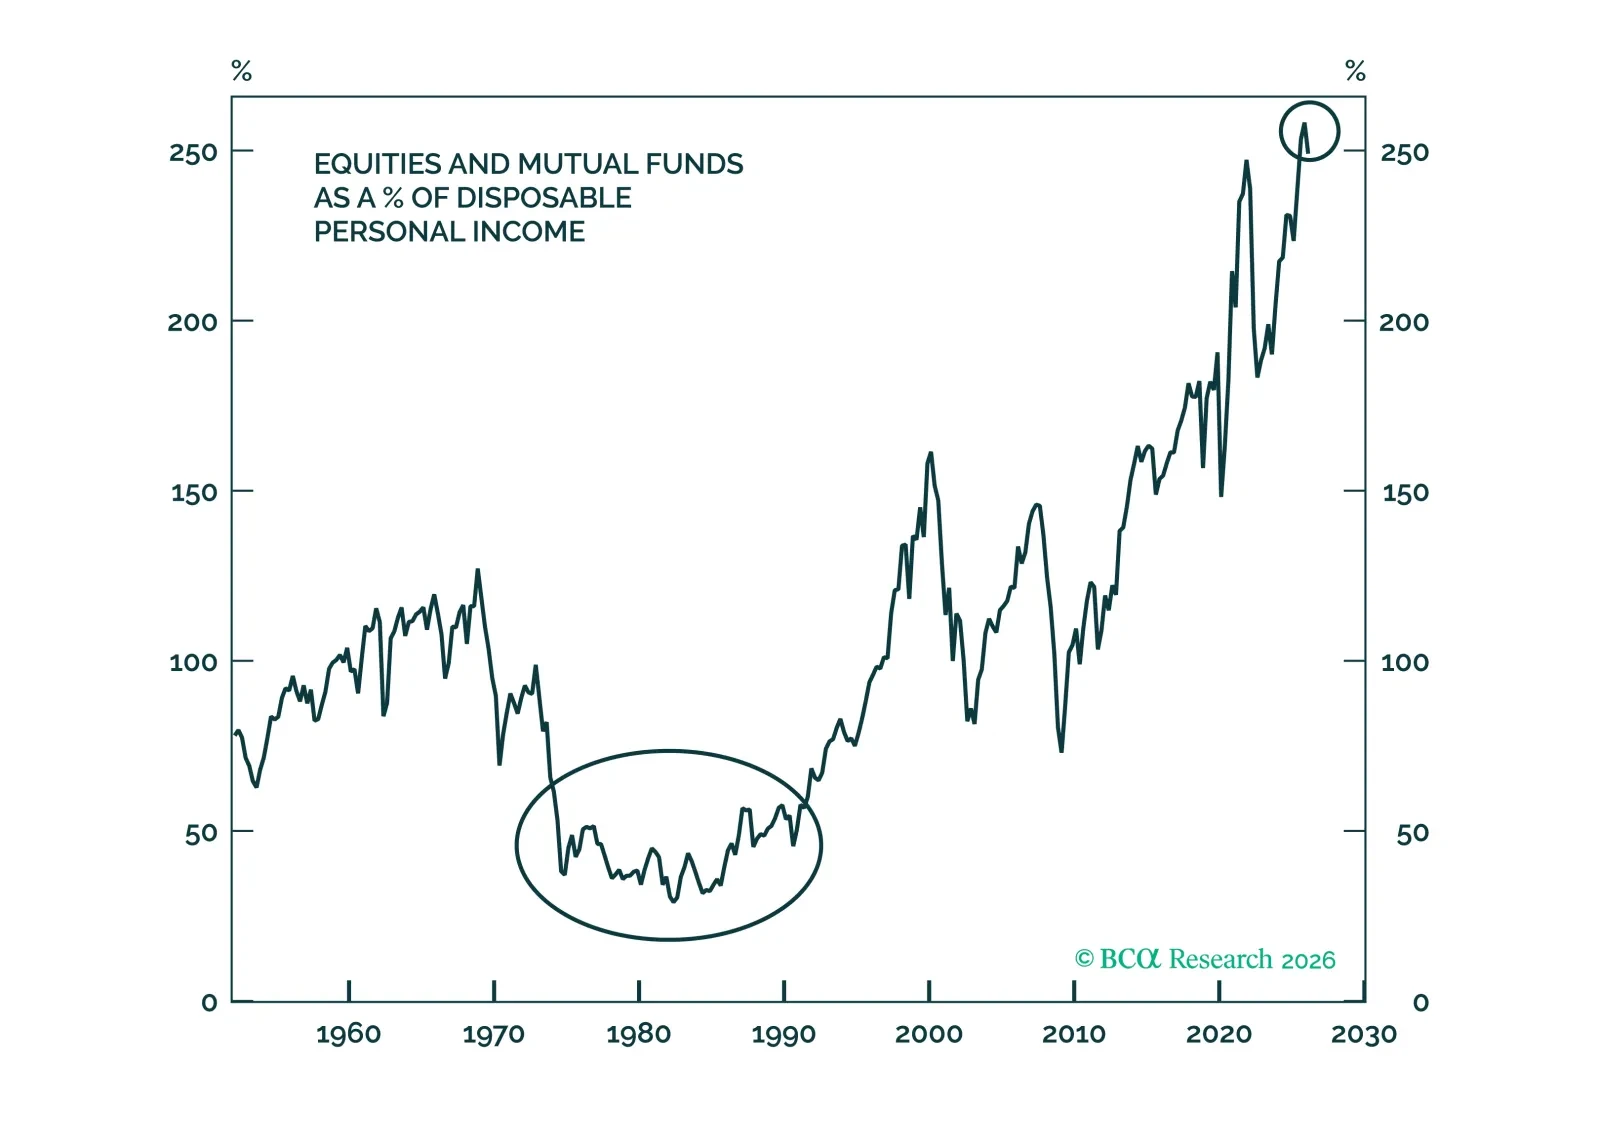
An acute shortage of AI hardware will support tech stocks into year-end. However, AI companies may need to ultimately generate $10 trillion per year in revenue to justify their capex. Barring a massive increase in productivity growth, this will be very difficult to achieve. Despite today’s Treasury announcement of upsized buyback operations, bond yields are likely to remain elevated over the coming months. Rising crack spreads have reduced the demand for crude, which is not encouraging for global growth. On the FX front, recent intervention to support the yen will probably be insufficient, but there is significant long-term upside for the currency.
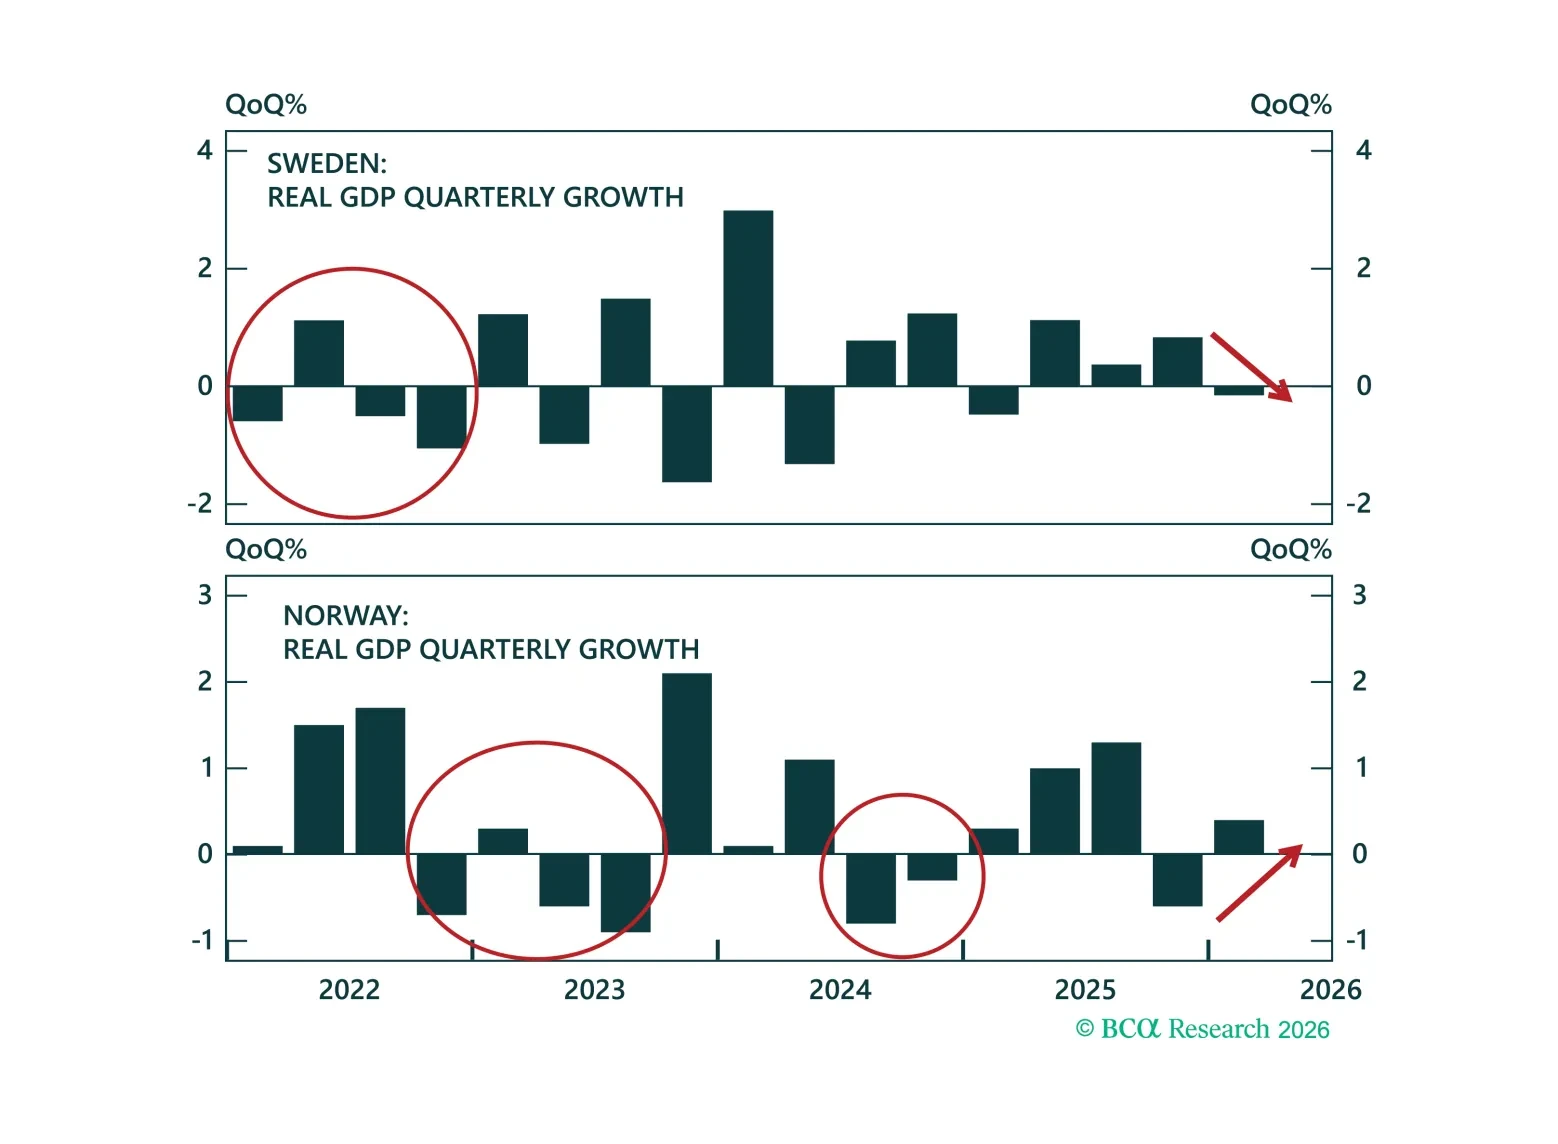
The war in Iran and the energy shock are driving a reversal of Nordic fortunes: Sweden’s recovery is faltering just as Norway receives a welcome energy windfall. Favor Norwegian over Swedish equities and buy NOK/SEK. In rates, fade aggressive Riksbank hike expectations and downgrade Norwegian government bonds to neutral.
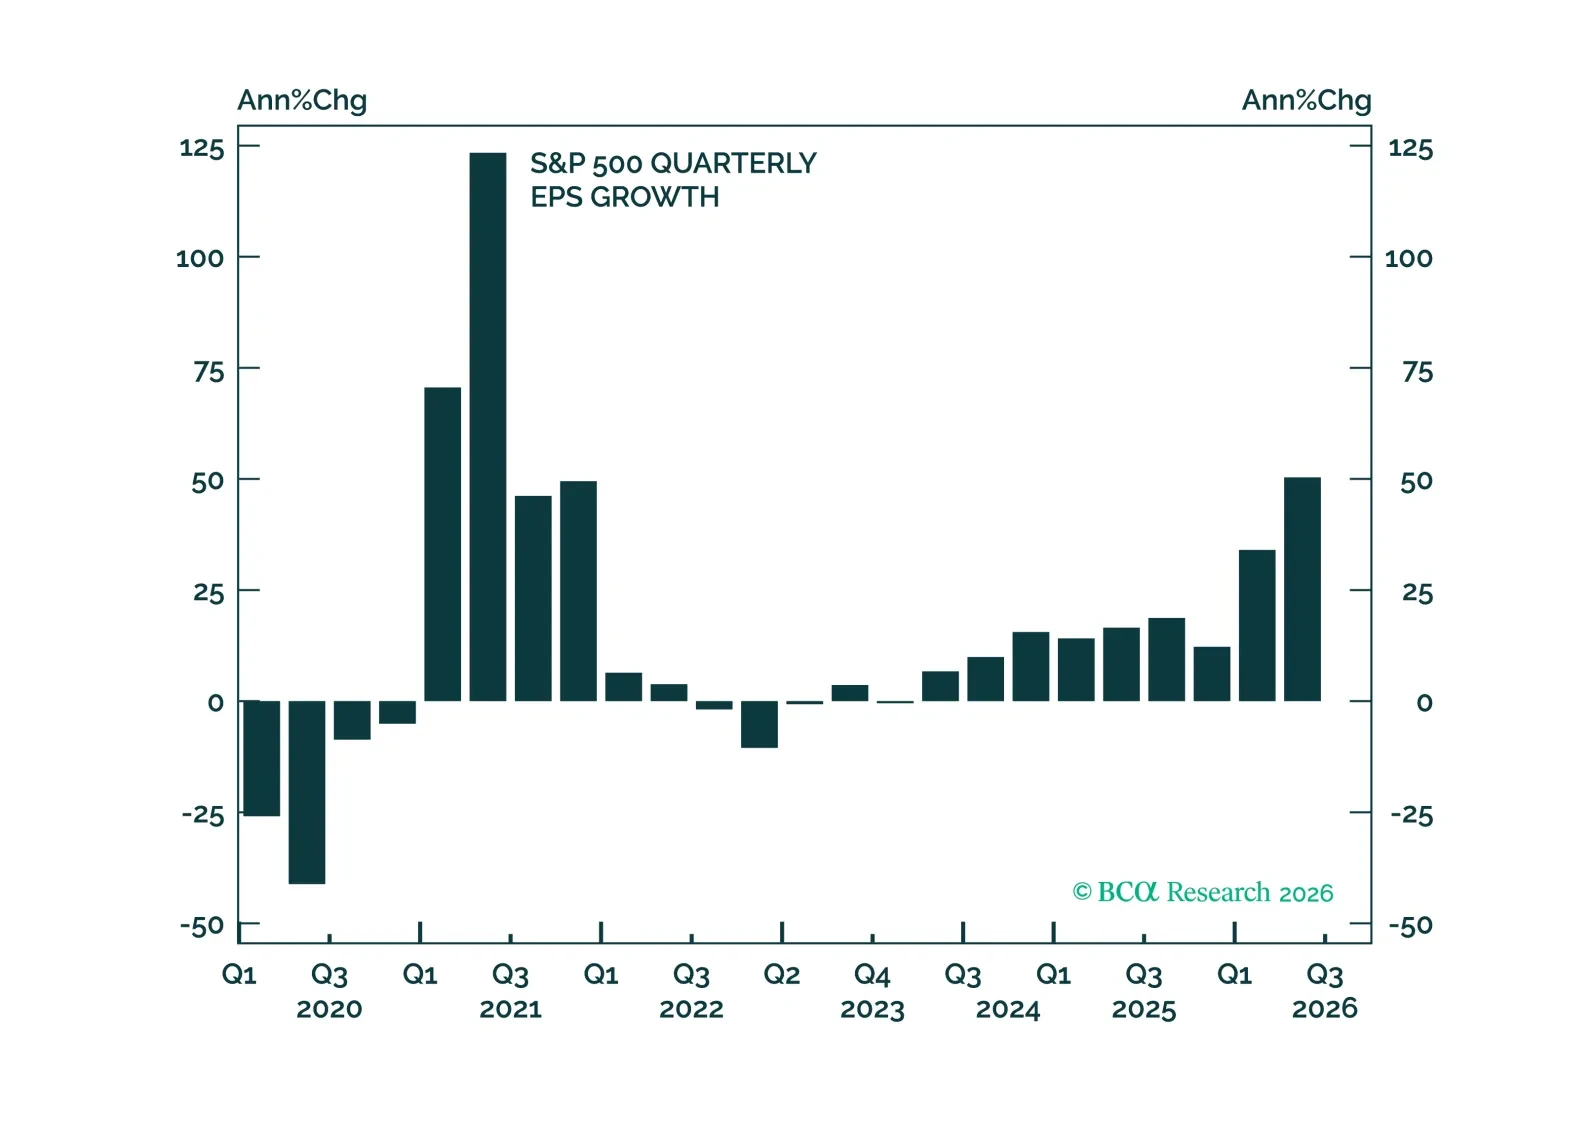
Q2 earnings confirm broad-based strength, but the bond market remains the key risk to equity multiples given today's positive stock/bond correlation regime. We close our tactical GDX long for a 16% gain, though we continue to view goldminers as a valuable structural hedge.