 Portfolio
Public-private allocation guidance, capital market assumptions, and strategic insight to help investors build forward-looking portfolios they can act on and defend.
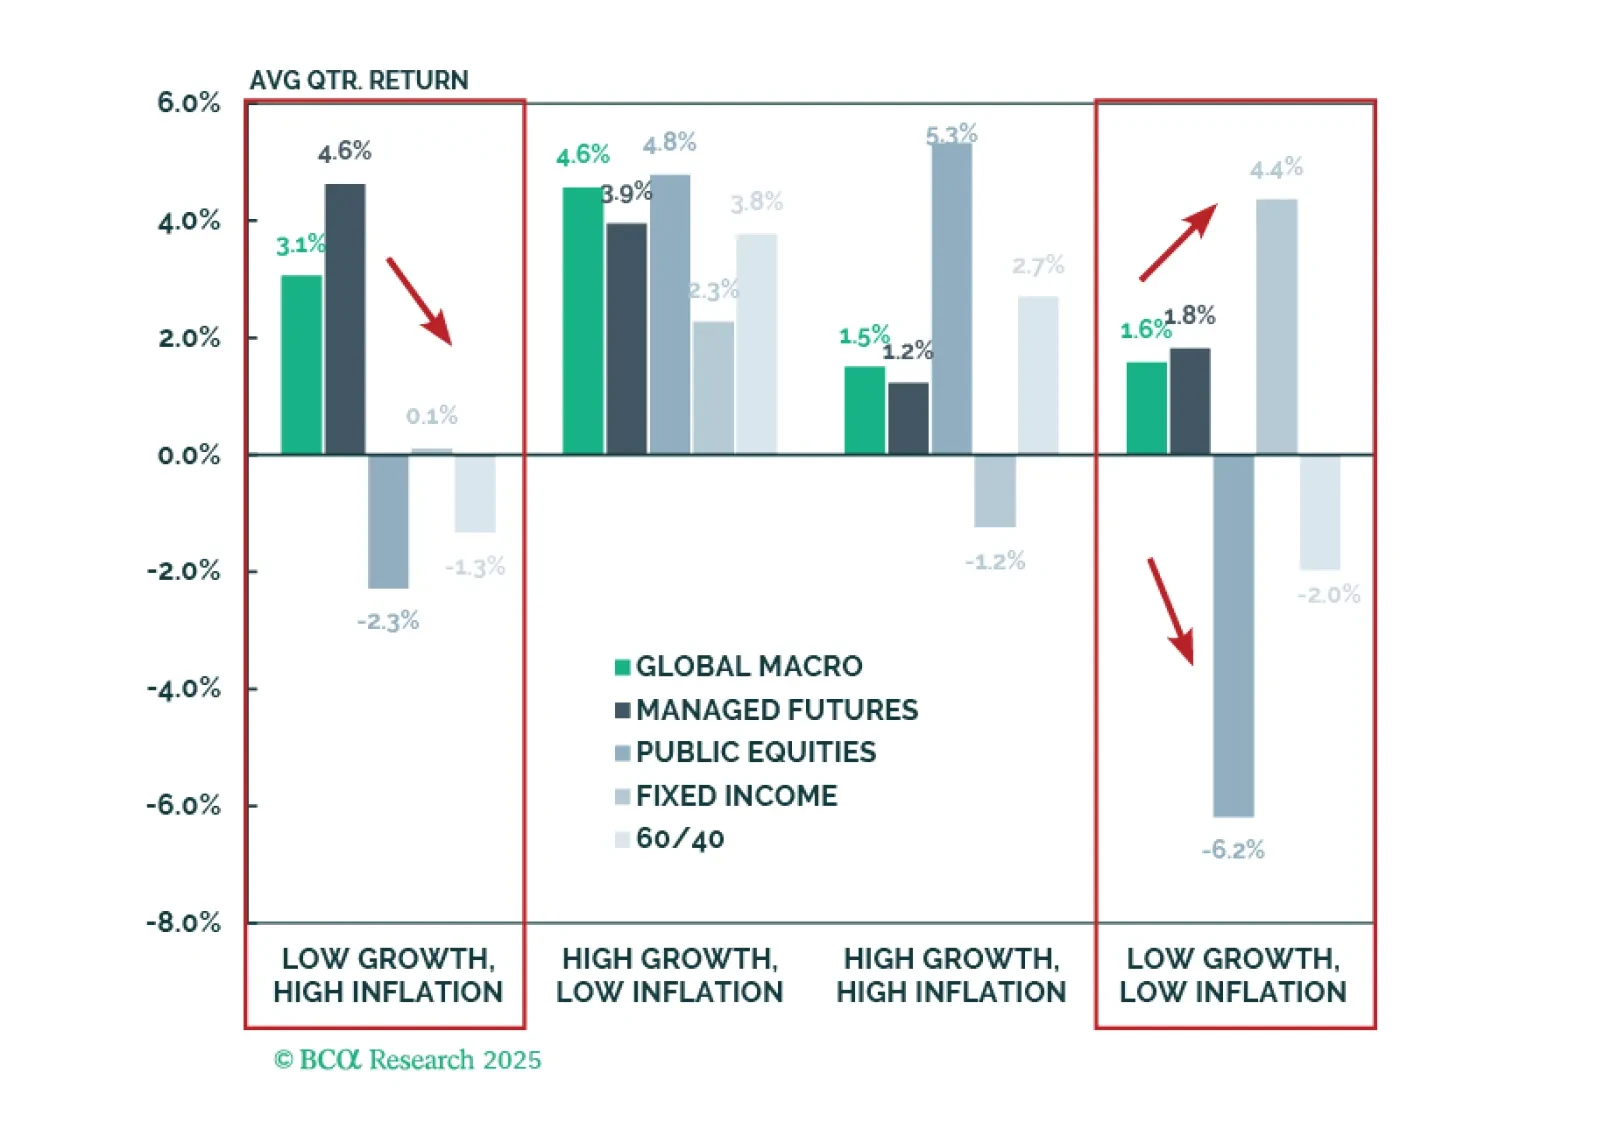
Understanding asset performance across Growth and Inflation regimes helps investors construct and manage balanced portfolios. Our first G&I Catalog report examines Hedge Fund strategies. Global Macro and Managed Futures offer the strongest protection in Stagflation-like periods, when traditional assets typically struggle. Since 1998, these regimes have occurred less than 10% of the time—but that may not hold true going forward.
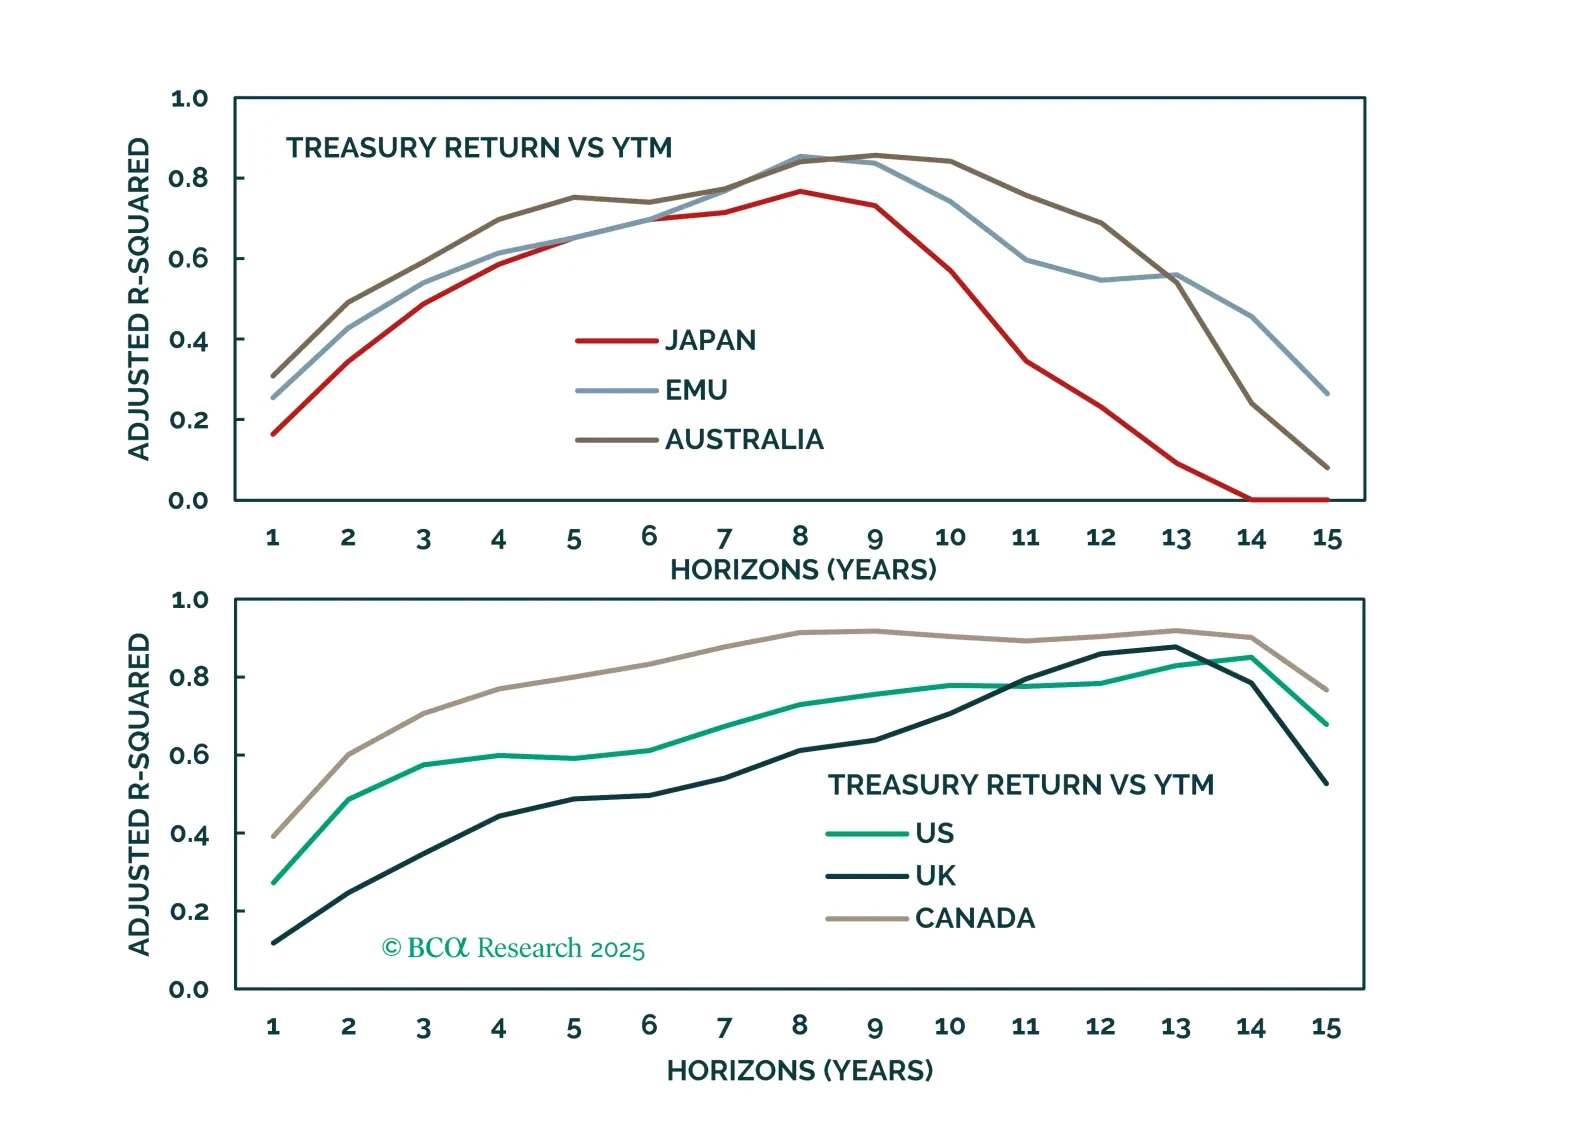
Yield-to-maturity remains the anchor of long-term bond return projections. Incorporating rolldown effects enhances accuracy. Our revamped “building-block” approach to fixed income capital market assumptions provides a solid, data-driven foundation for informed strategic asset allocation decisions.
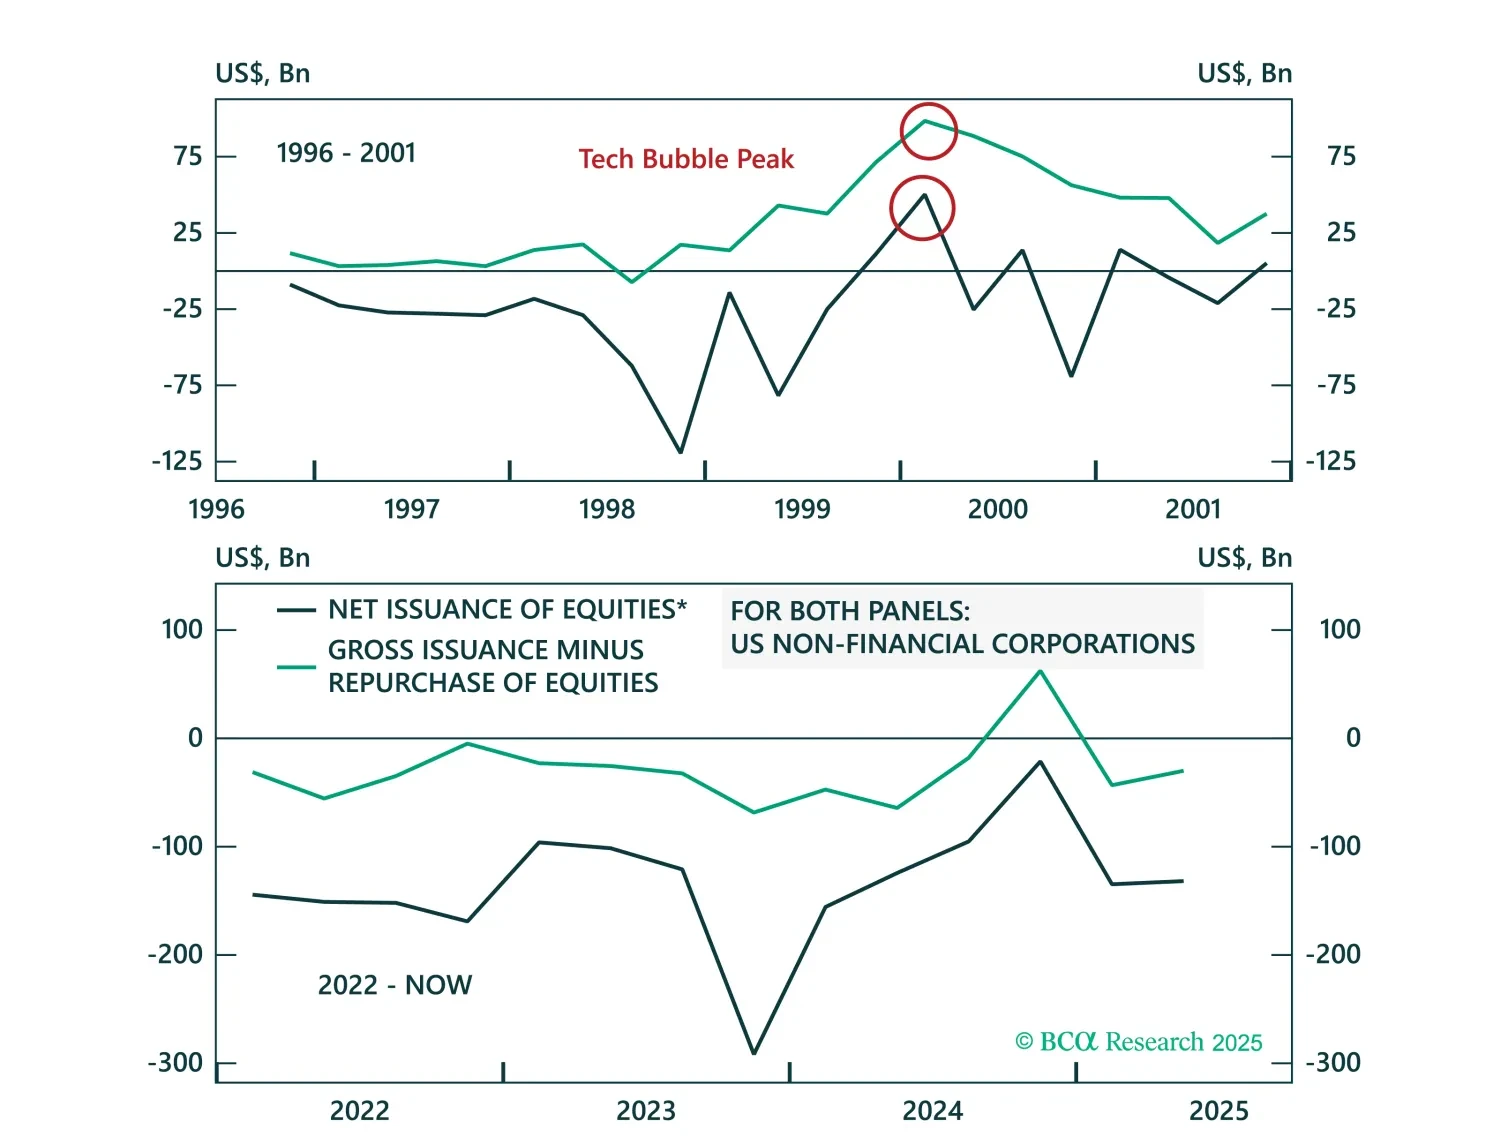
We discuss which variables we are tracking to assess the risks to the bull market in the absence of government data. So far, we do not see any obvious red flags. Remain overweight on equities and fixed income.
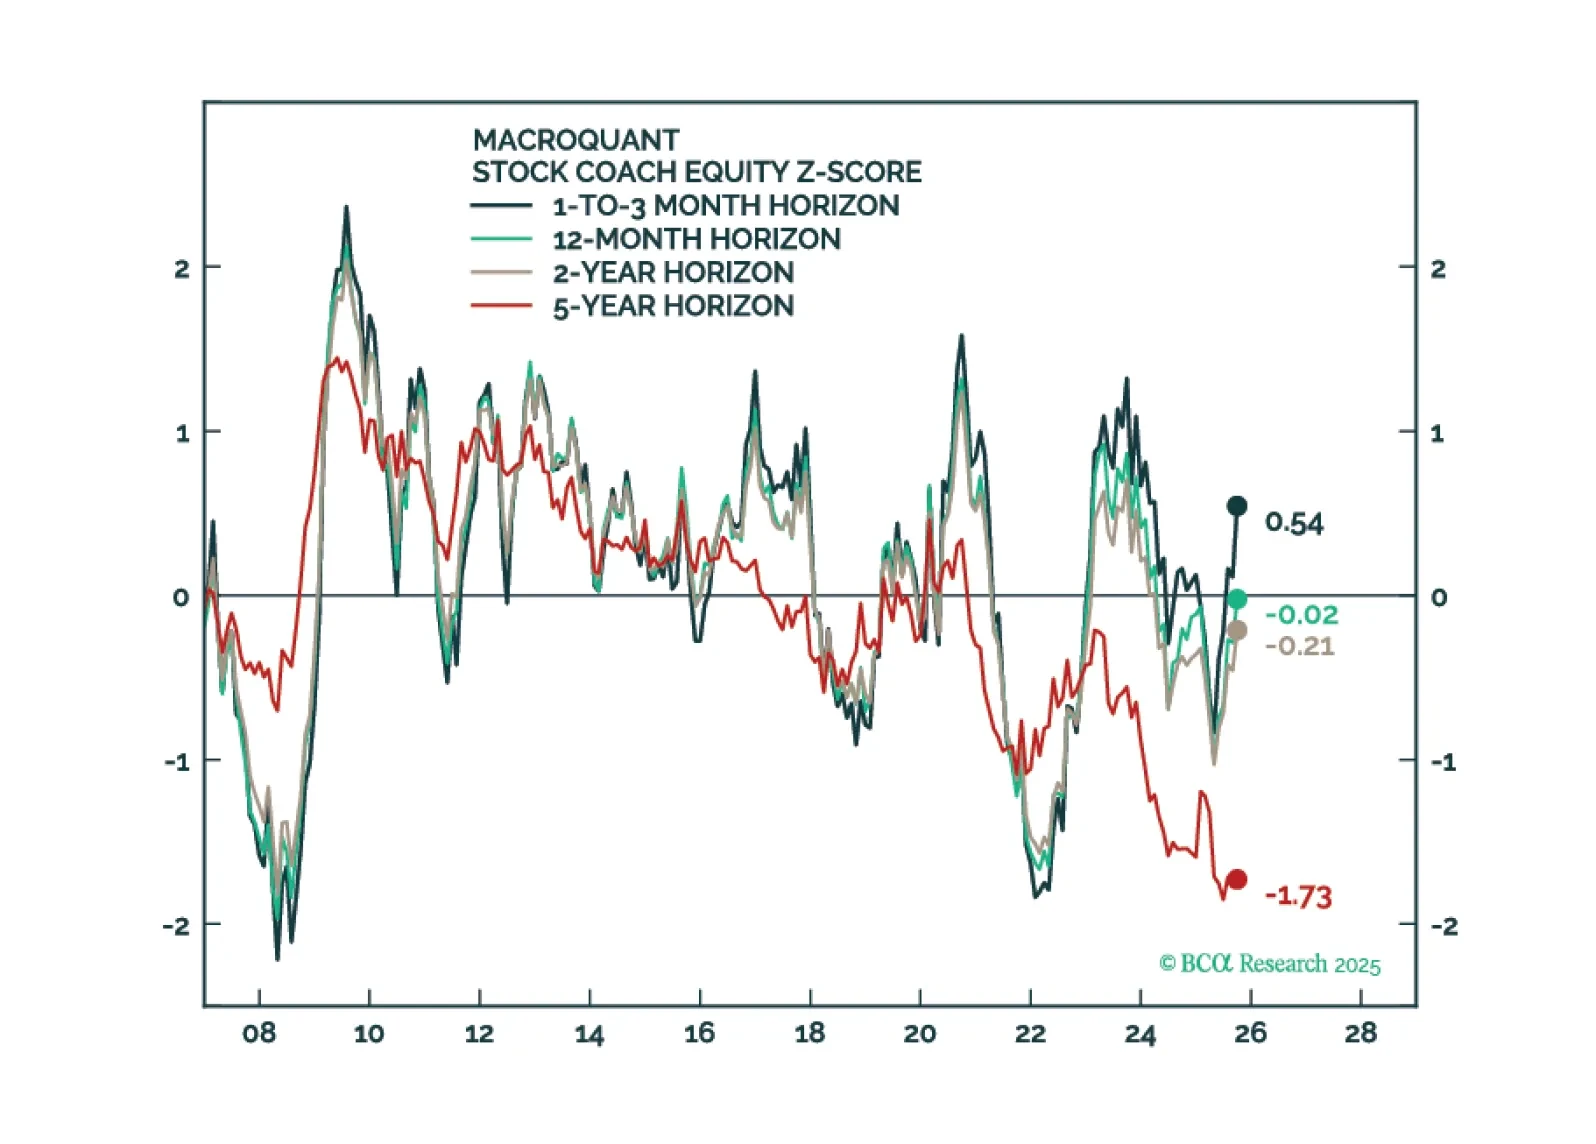
MacroQuant is tactically overweight equities, favors an above-benchmark duration stance in fixed-income portfolios, remains bearish on the US dollar, and is bullish on gold and copper.
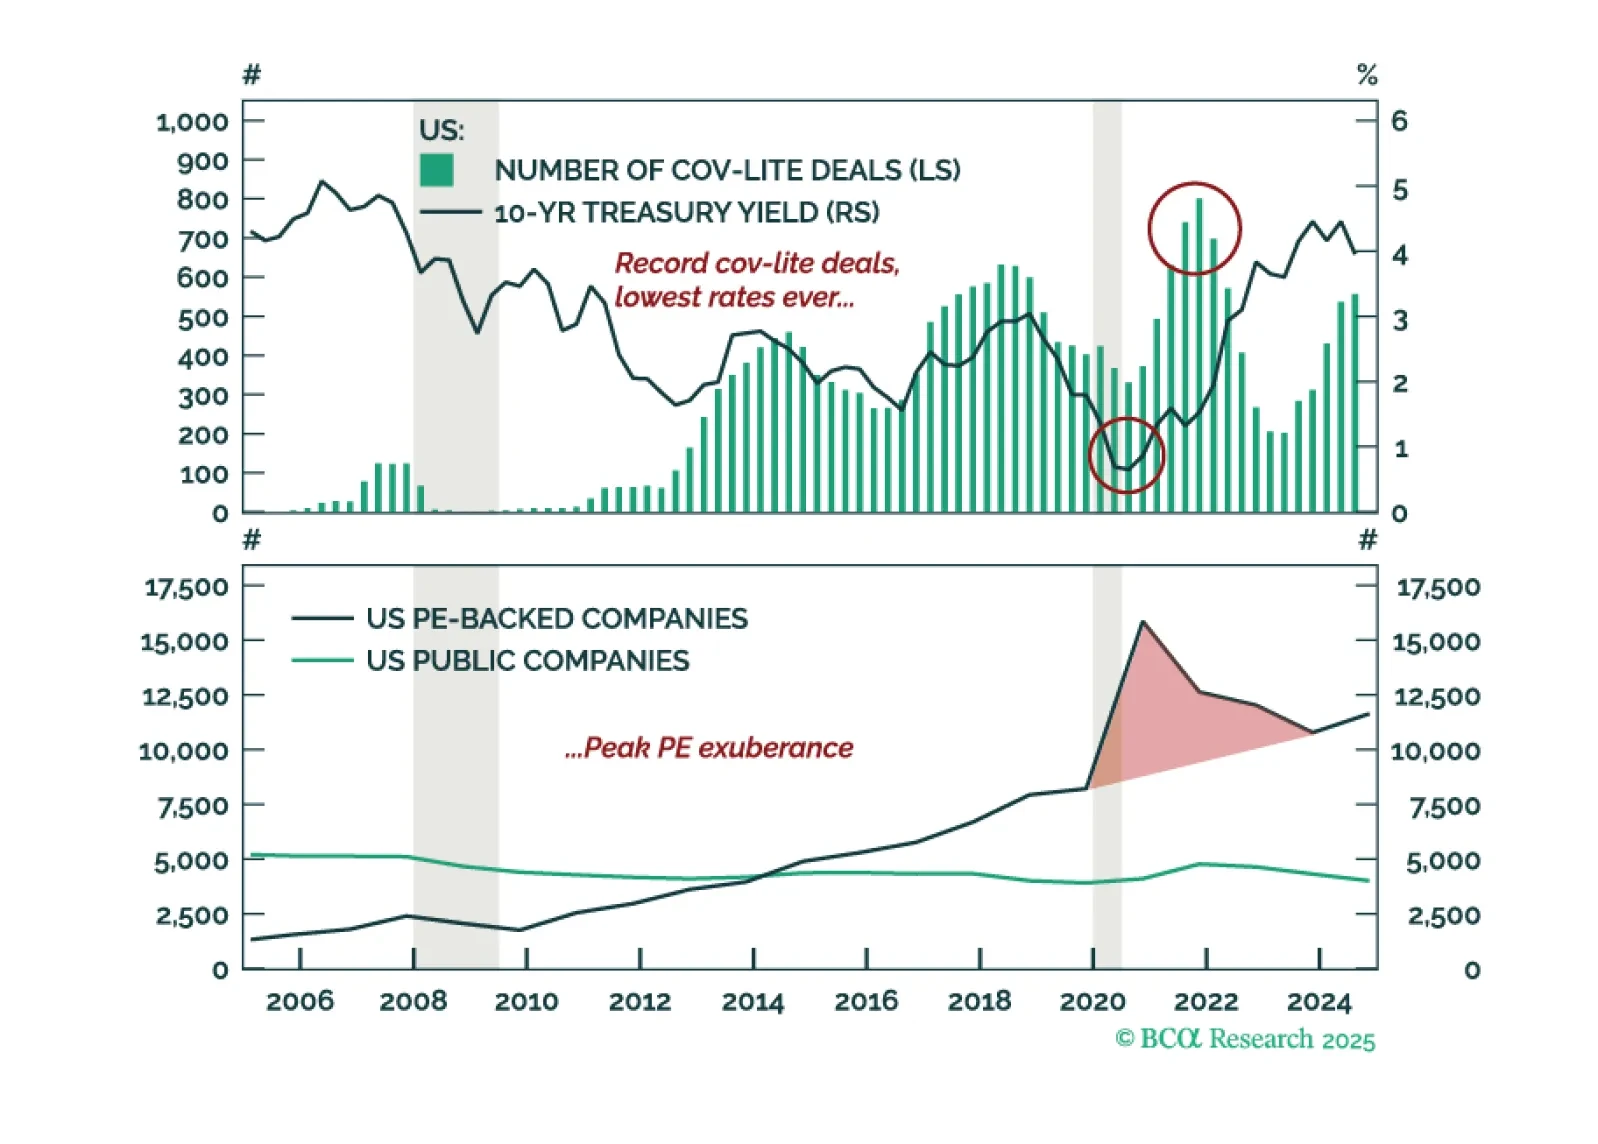
Private Credit outsiders are skeptical, insiders are believers—but are becoming nervous now. In the highlight of this Quarterly Report, we dig beneath the surface to uncover the buried bodies in Private AND Public Credit. The ghosts of 2020-2021 loan originations are catching up with investors.
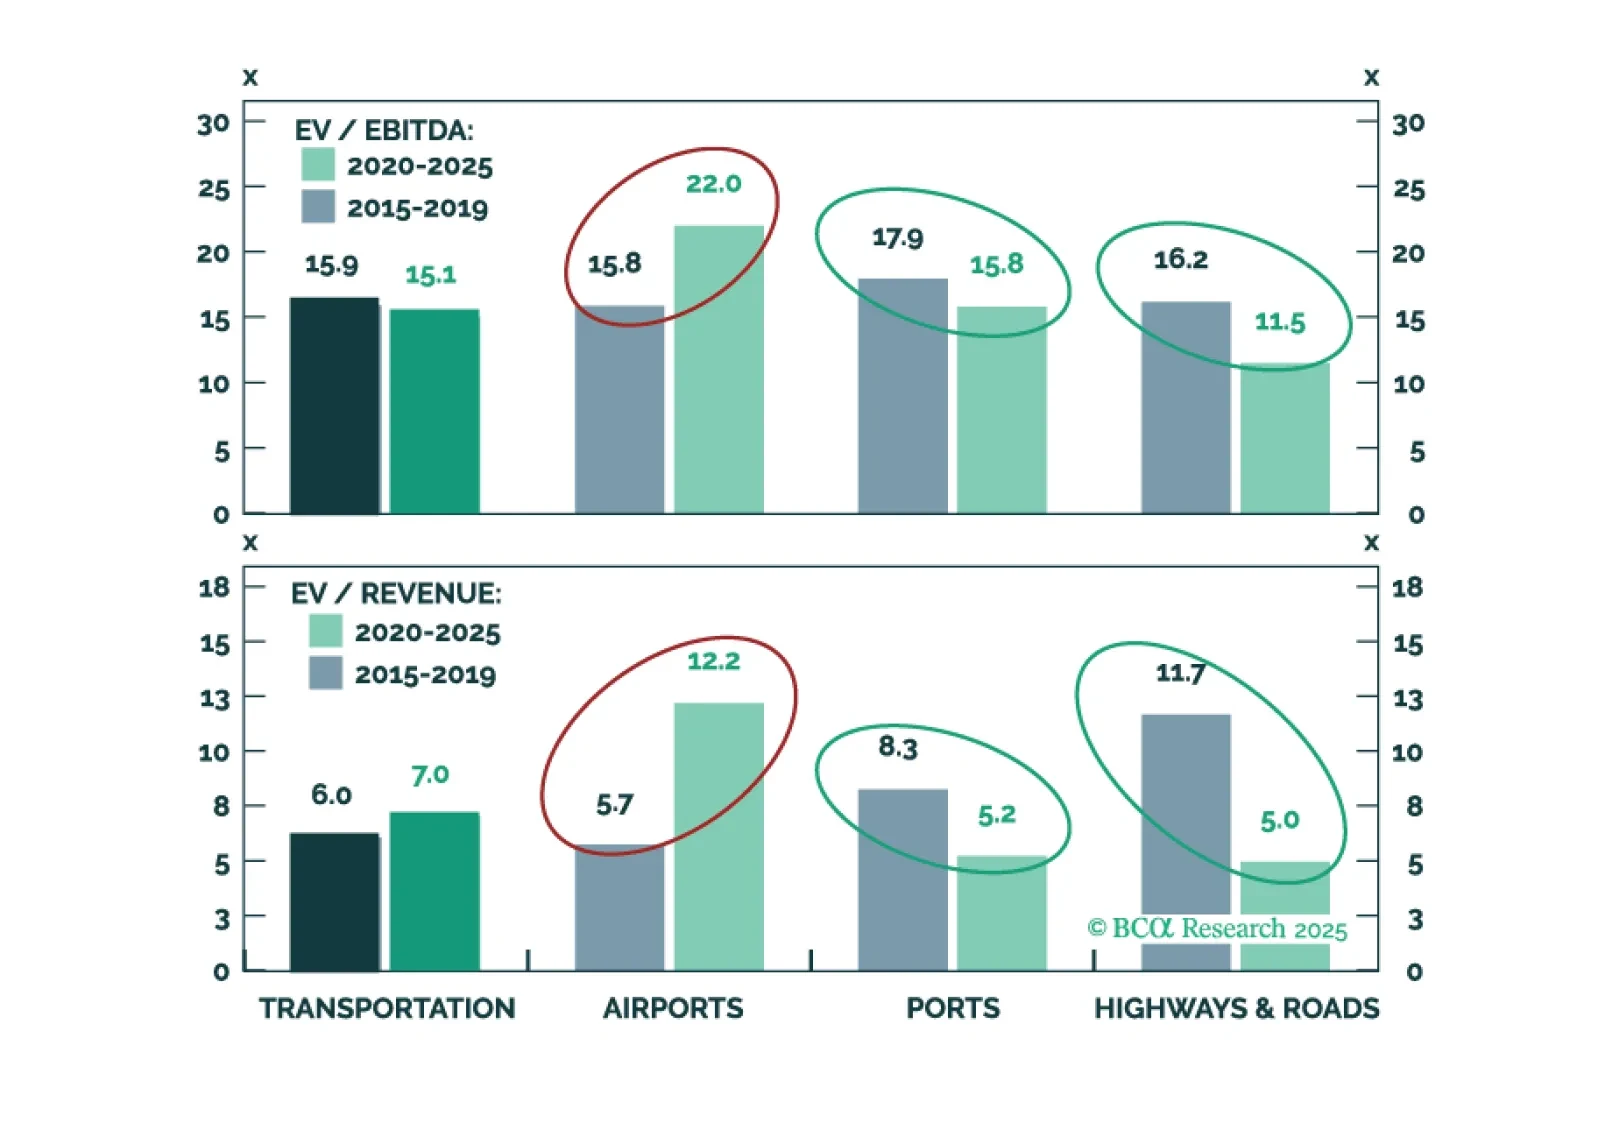
While Transportation Infrastructure is intuitive to grasp, its cash flow dynamics are often less understood. This educational report examines cash flow drivers across sectors, highlighting both macro and micro influences. Current opportunities are strongest in Ports and Highways & Roads over Airports.
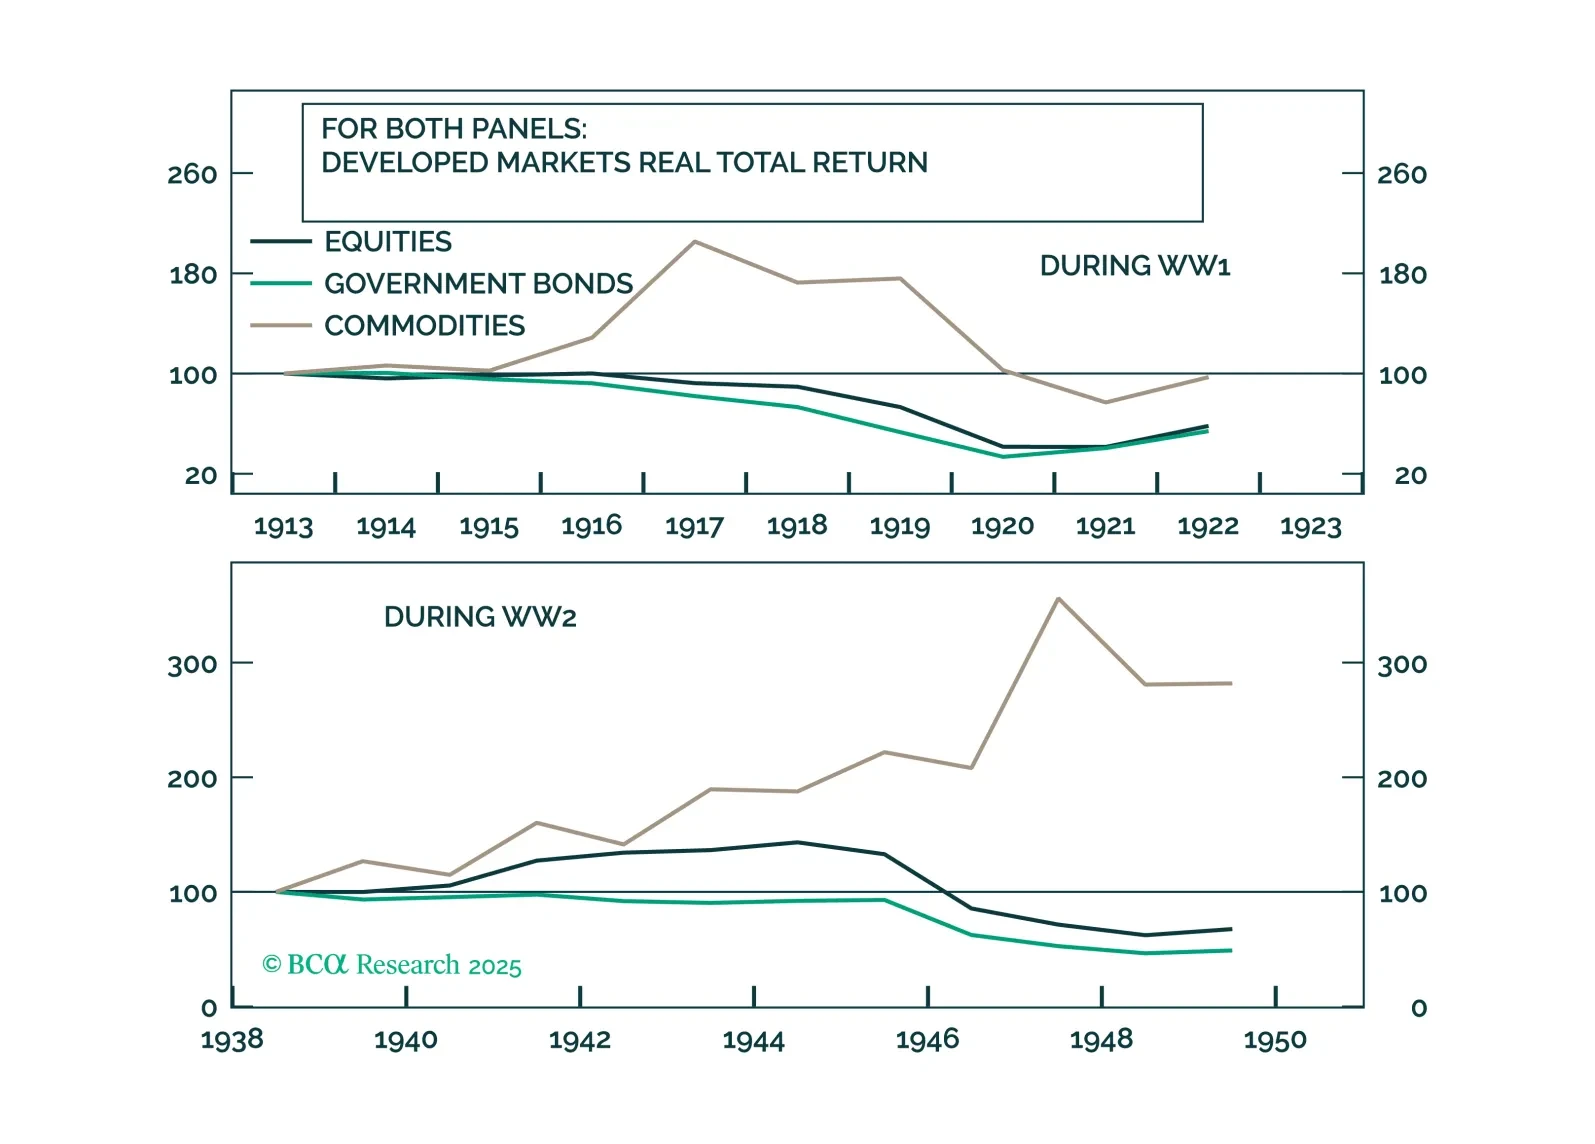
World War III will not happen. But if you disagree, here is our portfolio to hedge it: commodities, neutrals, and crypto.
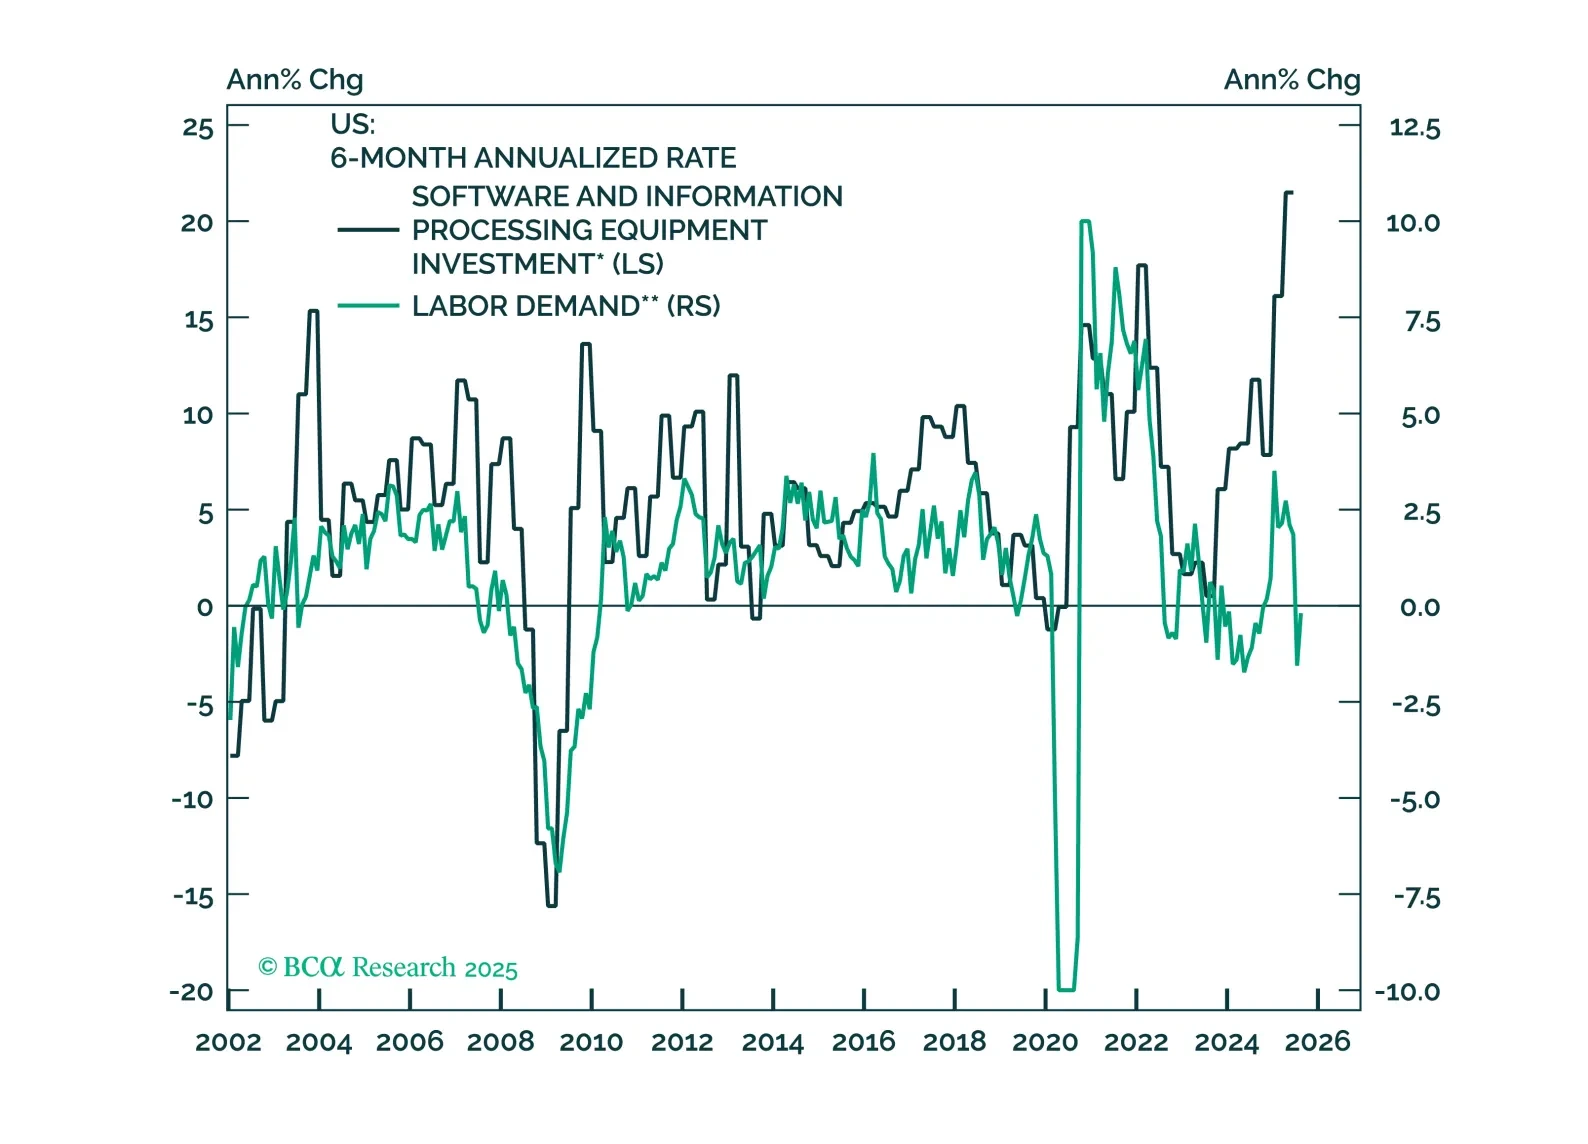
Big Tech and the Trump administration are engineering an industrial boom that favors American hardware over American workers. Economic growth will be robust in the US but the labor market will stay relatively sluggish. Adopt an overweight stance on both equities and fixed income and underweight on cash. Upgrade Canadian equities and downgrade the UK. Upgrade Industrials and downgrade Consumer Staples. Upgrade EM Debt. Downgrade Private Credit.
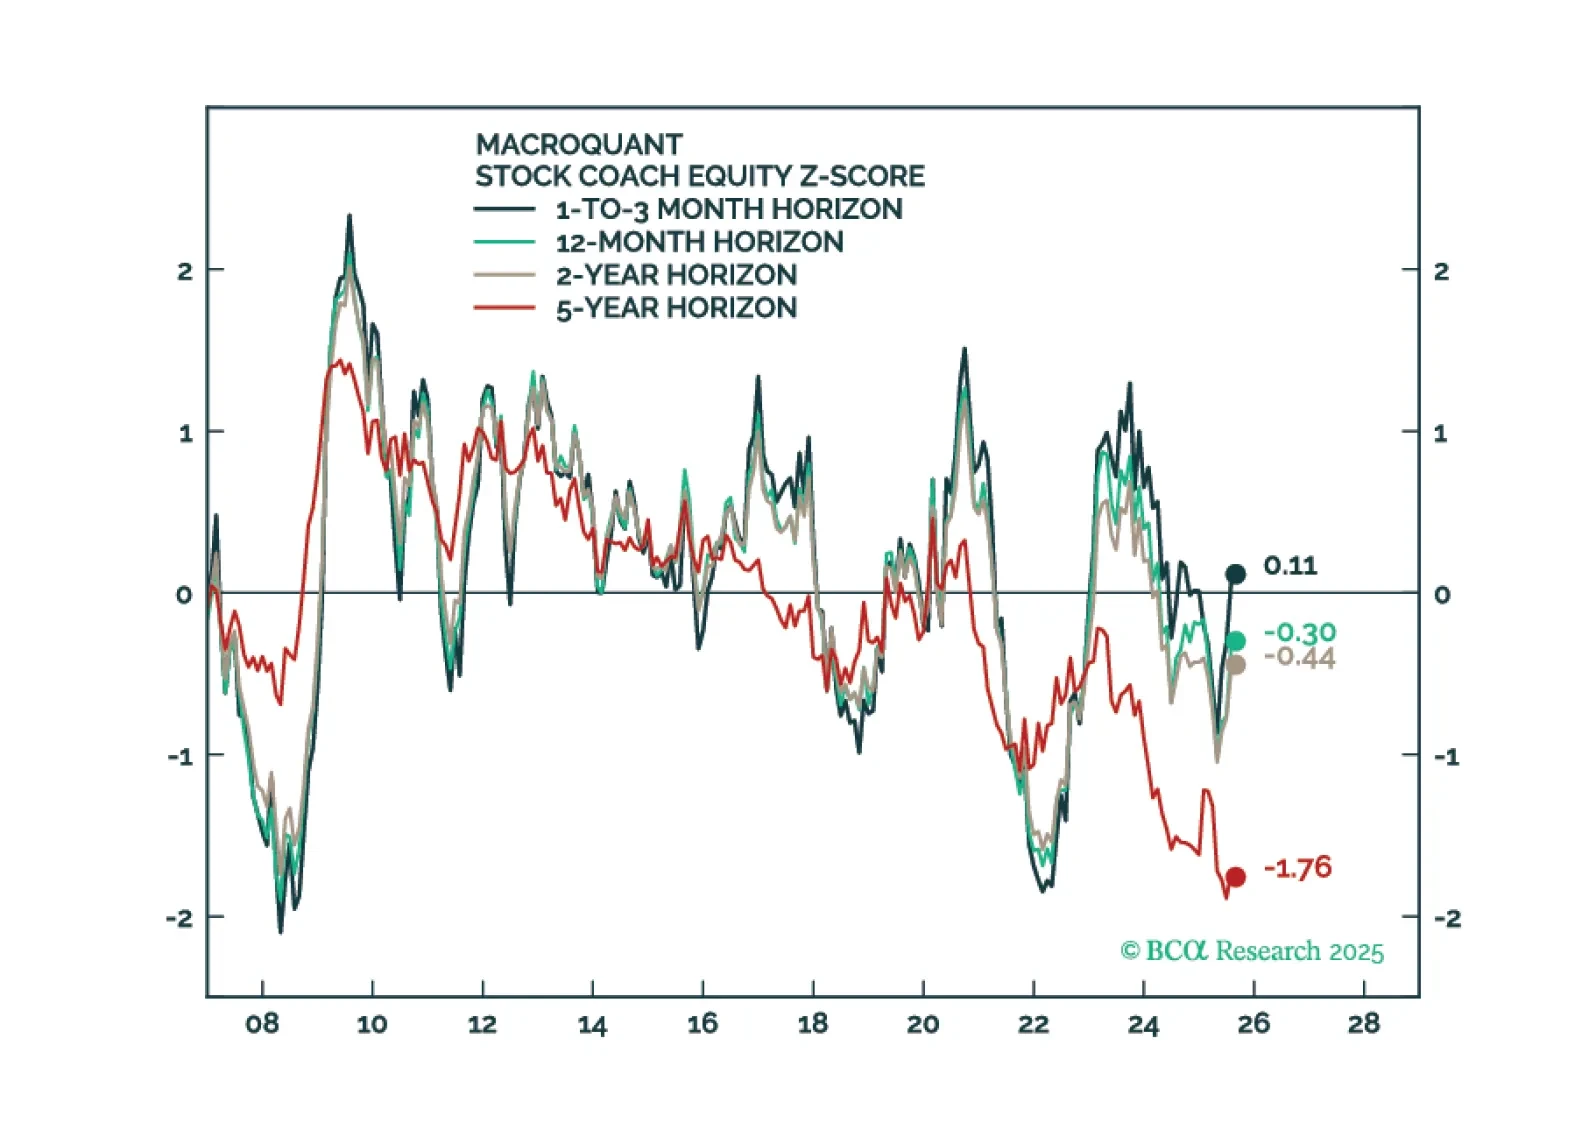
MacroQuant is neutral-to-slightly positive on stocks on a tactical 1-to-3 month horizon but sees downside risks over a longer-term horizon. Its favorite equity sectors are communication services and IT. Regionally, it prefers EM and US equities. The model is bullish on duration. It remains bearish on the US dollar. It is upbeat on gold and copper but is slightly negative on oil.
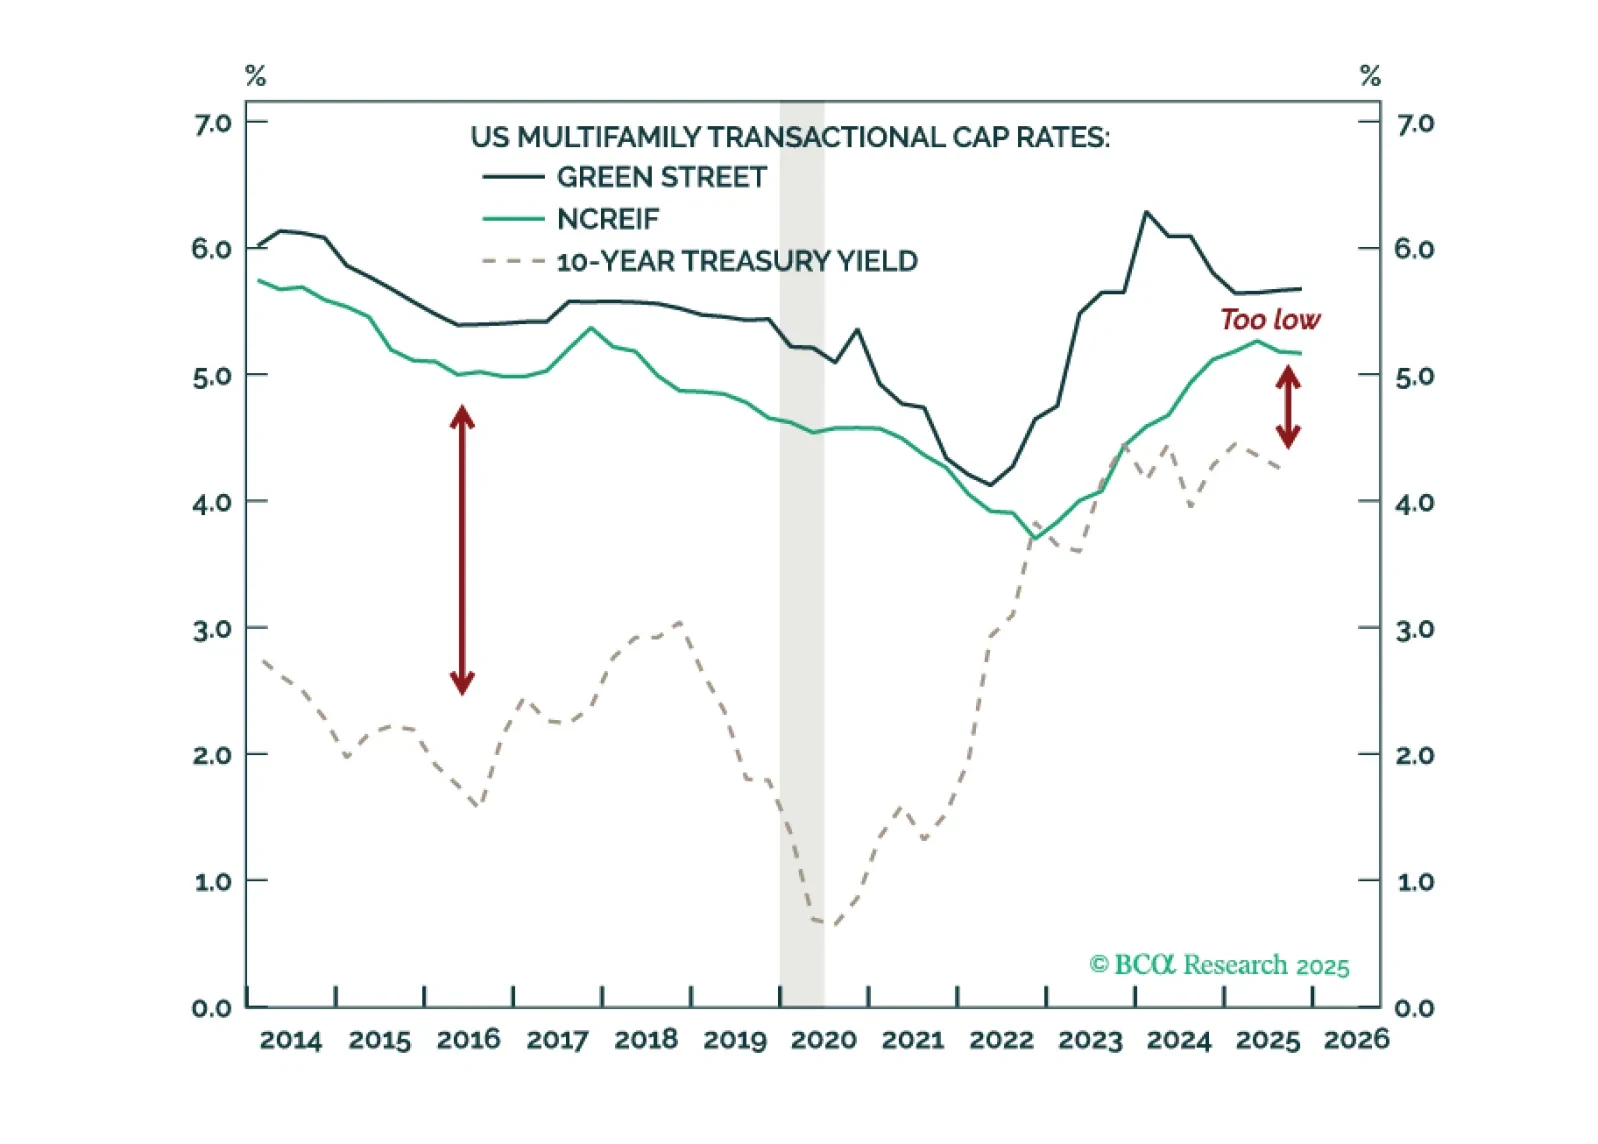
US Real Estate has been under pressure post-2022. This chartpack offers a snapshot of the cap rate cycle across measures, sectors, and cities. Industrial and Multifamily spreads remain tight while Office and Retail have peaked. Chicago and Houston differ as cities, but their Real Estate trends look increasingly alike.