 Portfolio
Public-private allocation guidance, capital market assumptions, and strategic insight to help investors build forward-looking portfolios they can act on and defend.
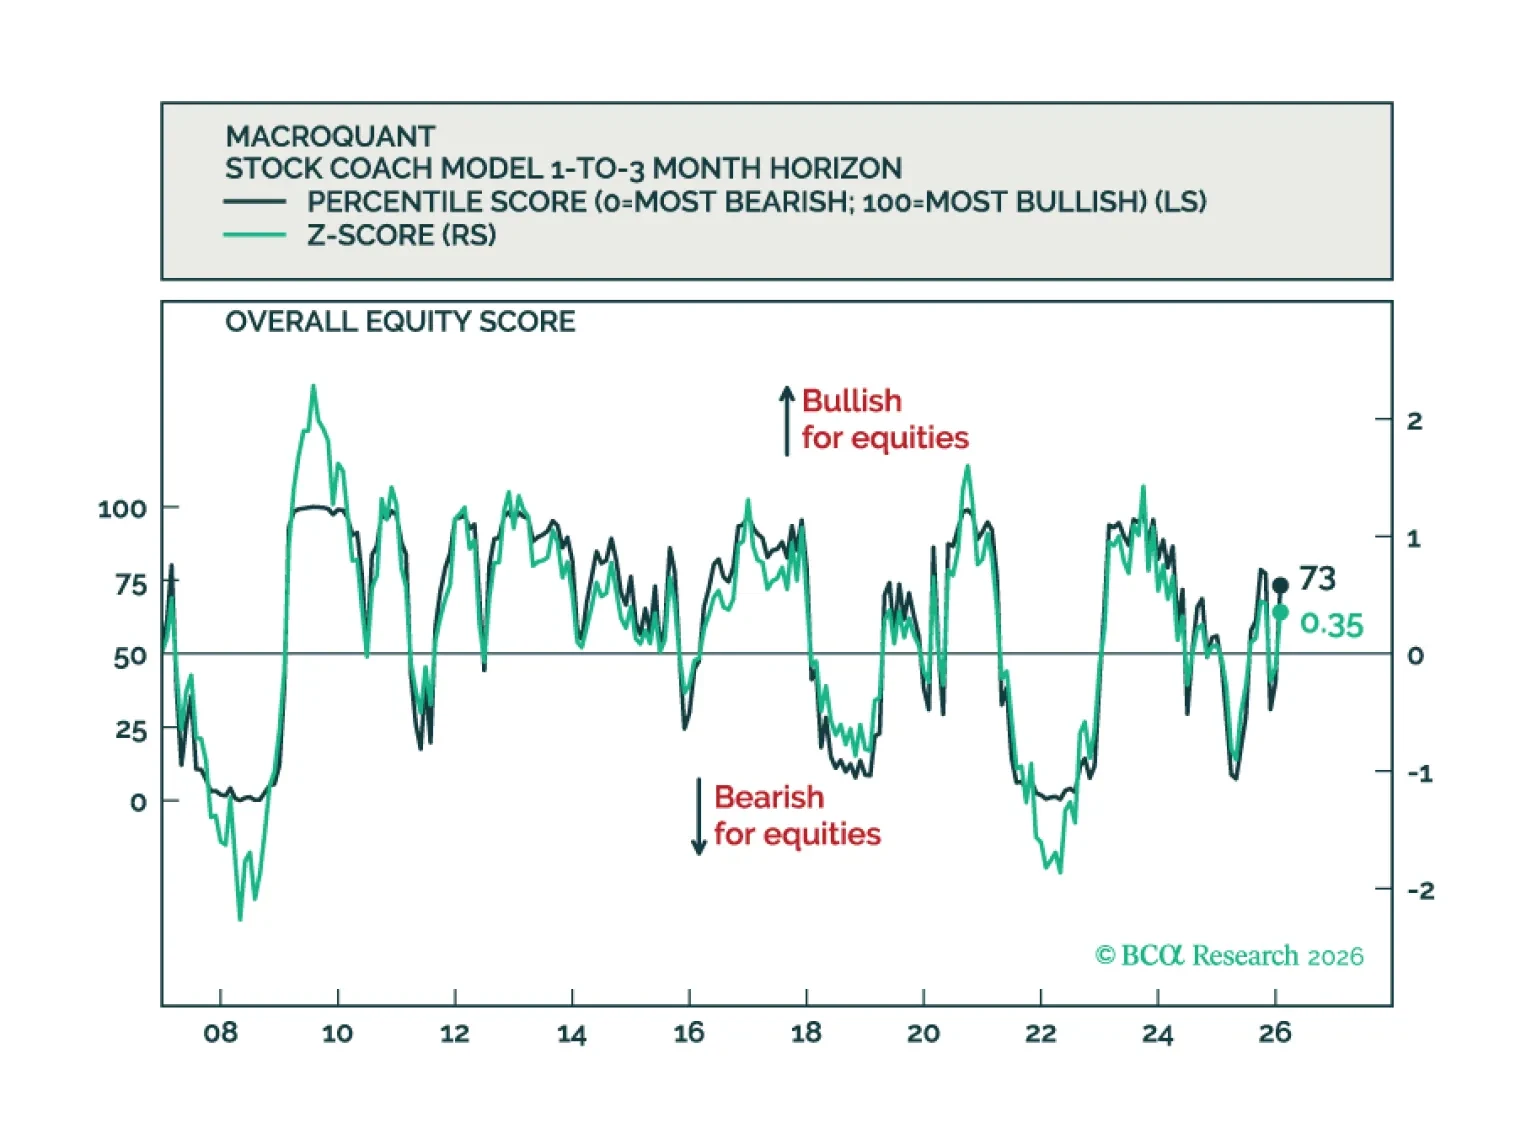
MacroQuant recommends a modest overweight position in equities, favors an above-benchmark duration stance in fixed-income portfolios, remains bearish on the US dollar, has downgraded oil to neutral, and is bullish on copper and gold.
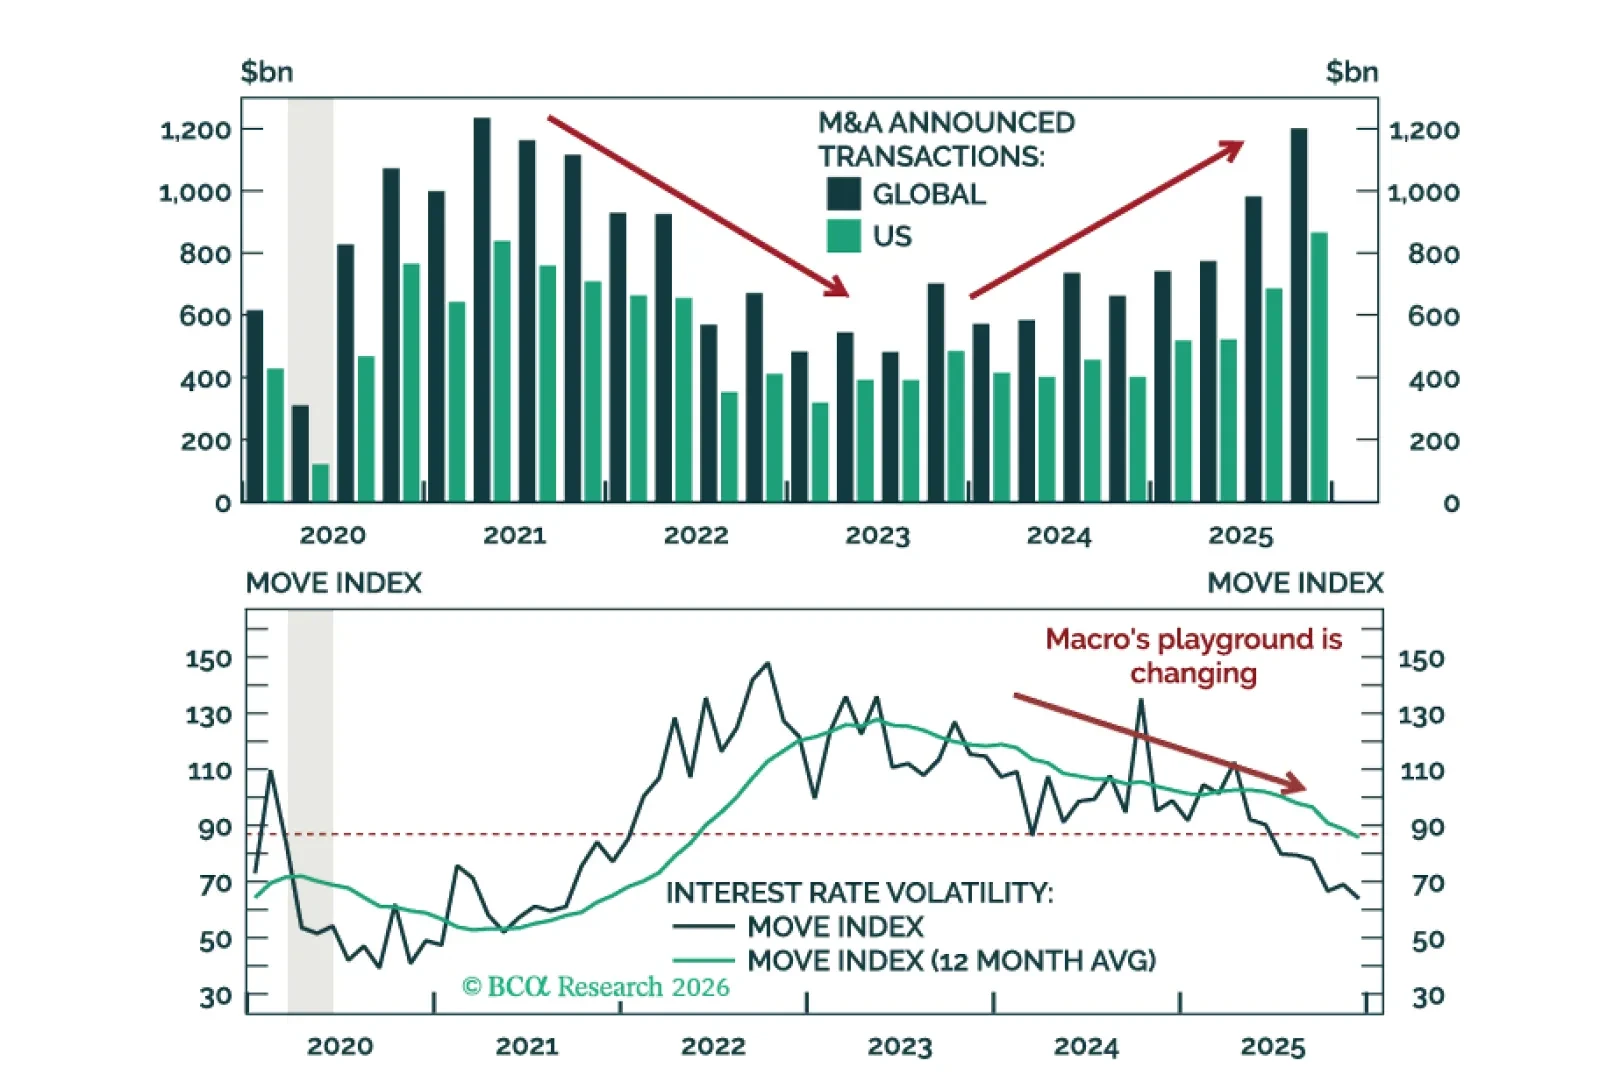
M&A activity finally reaccelerated in Q4 2025—it’s just the start. Macro Hedge Funds have outperformed with top-decile performance from Discretionary Macro—but that’s towards the end. We move Macro from overweight to underweight and Event Driven from neutral to overweight.

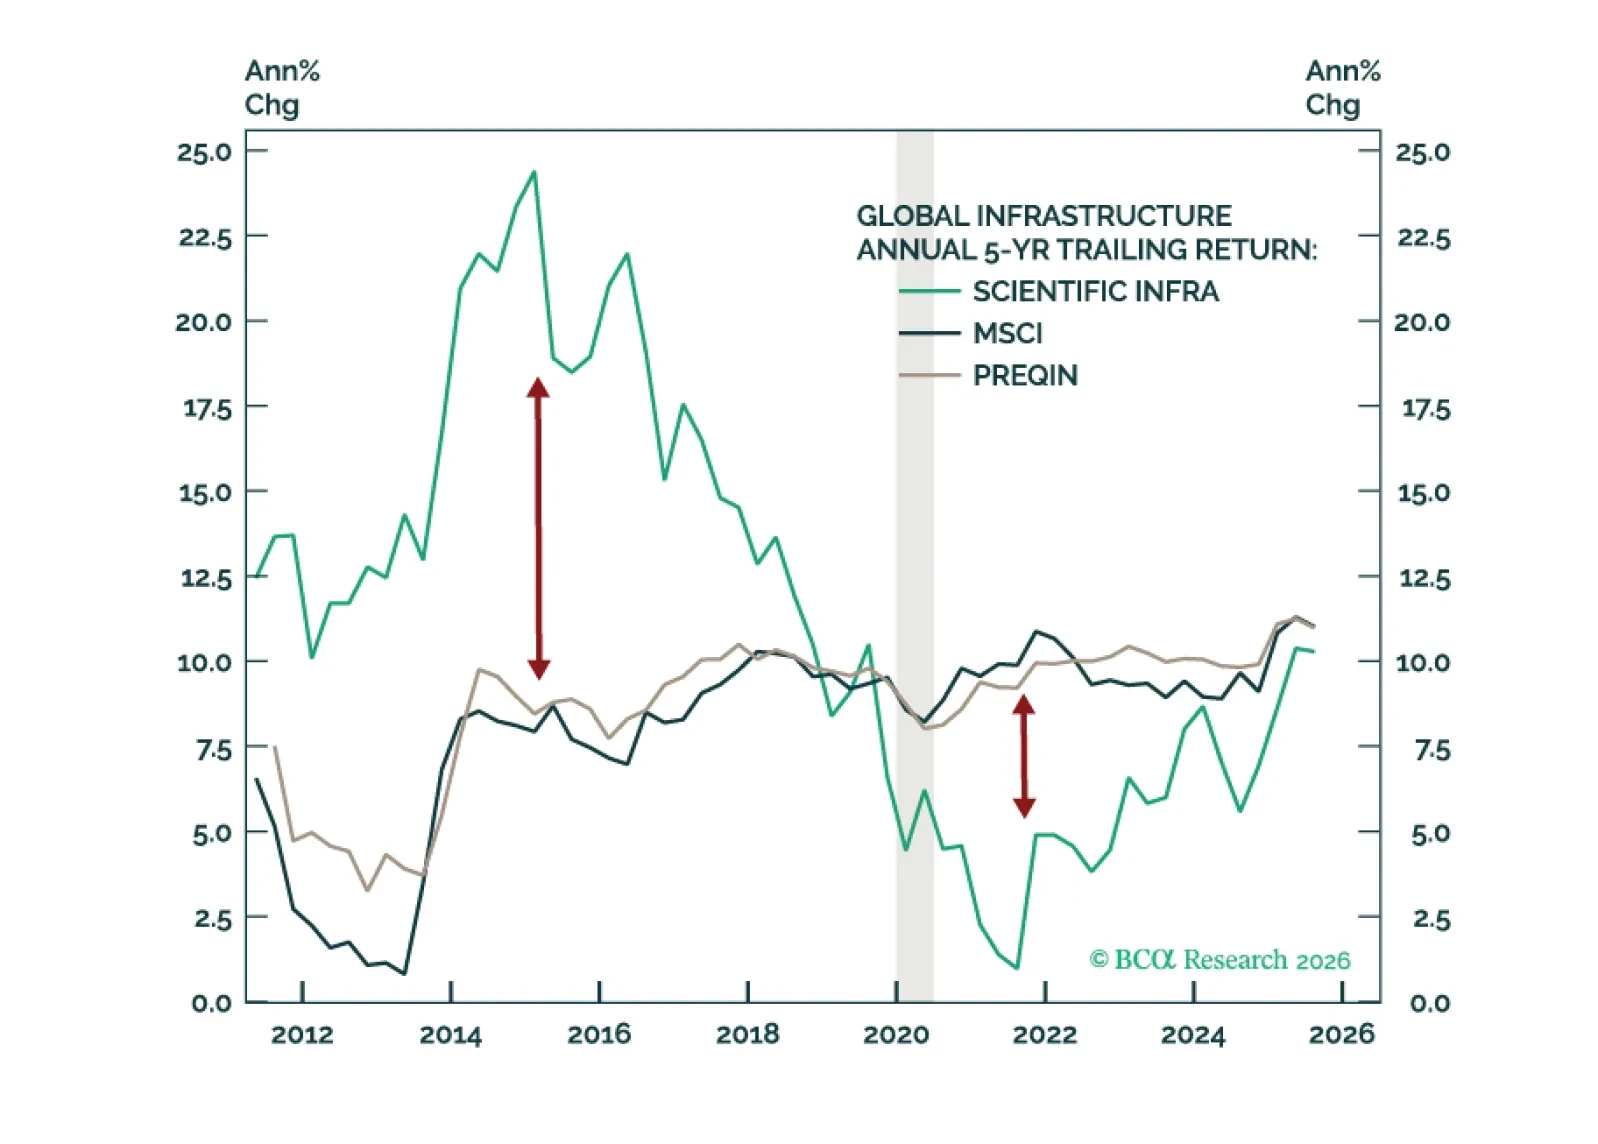
Private Infrastructure is the fastest growing alternative asset class. While metrics vary across data providers, differences largely reflect sector and regional mix. Core Infrastructure inflows have been strong, reversing declines seen in preceding years. Recent returns have been robust, and despite valuation dispersion, levels do not appear stretched.
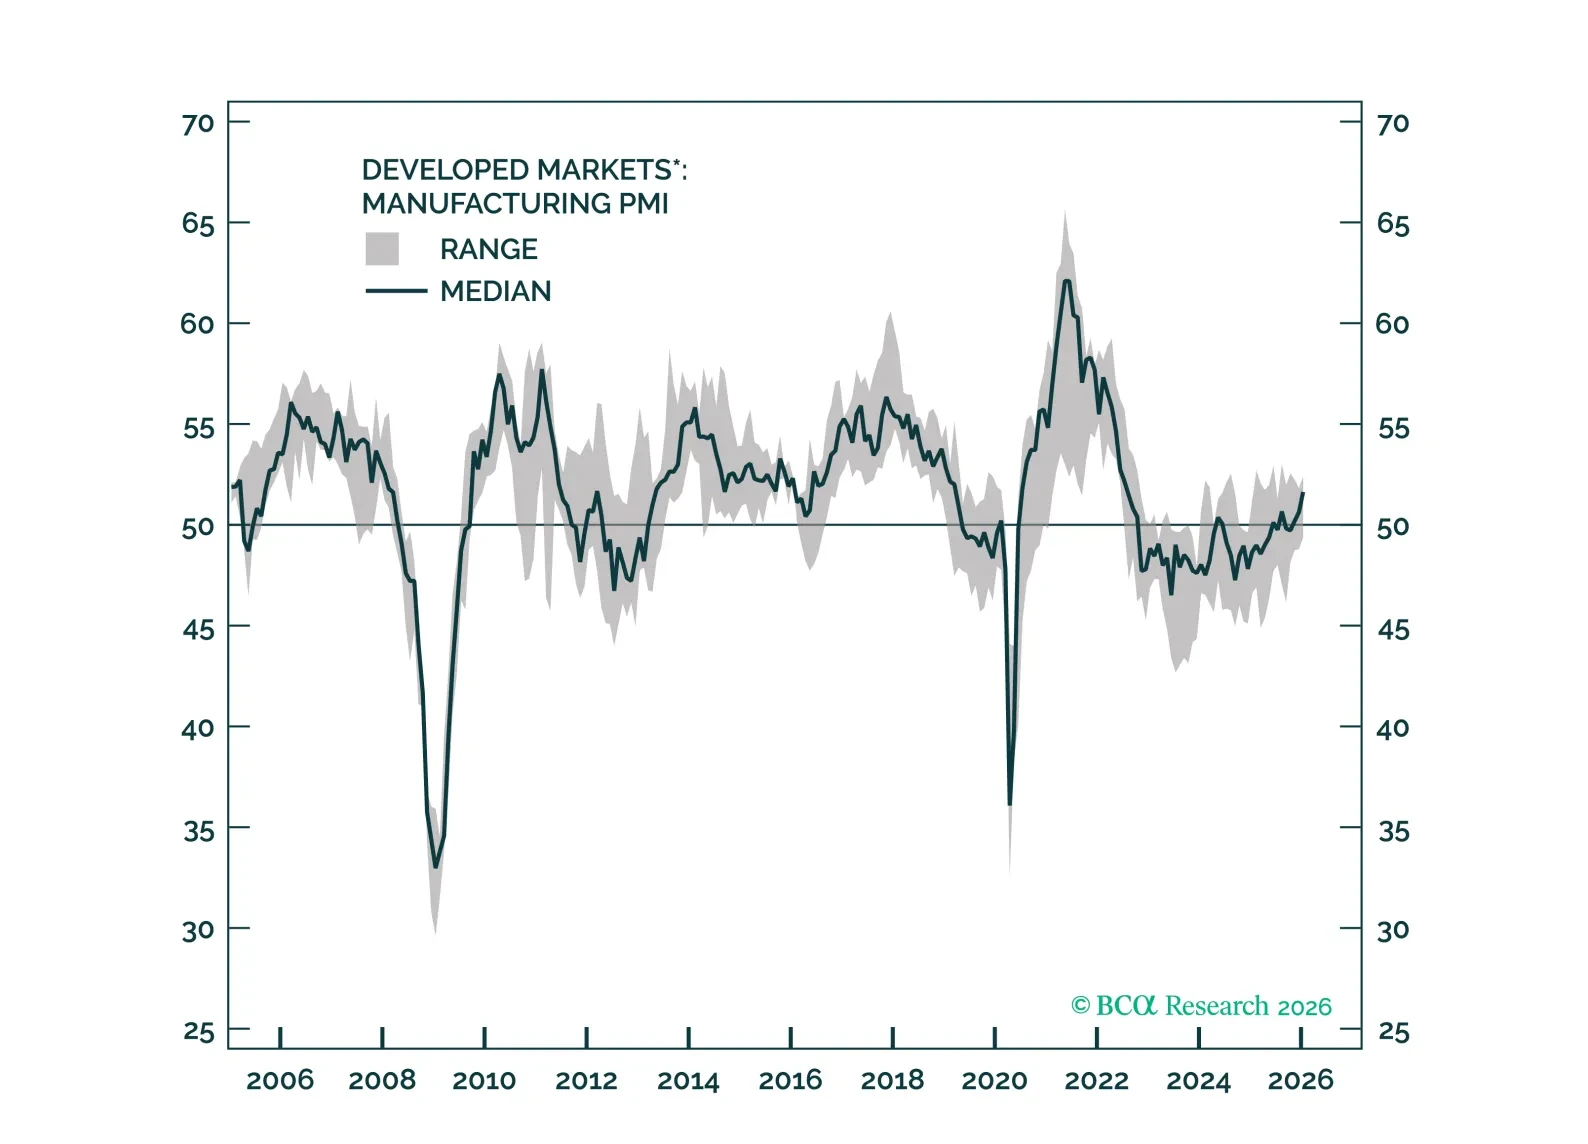
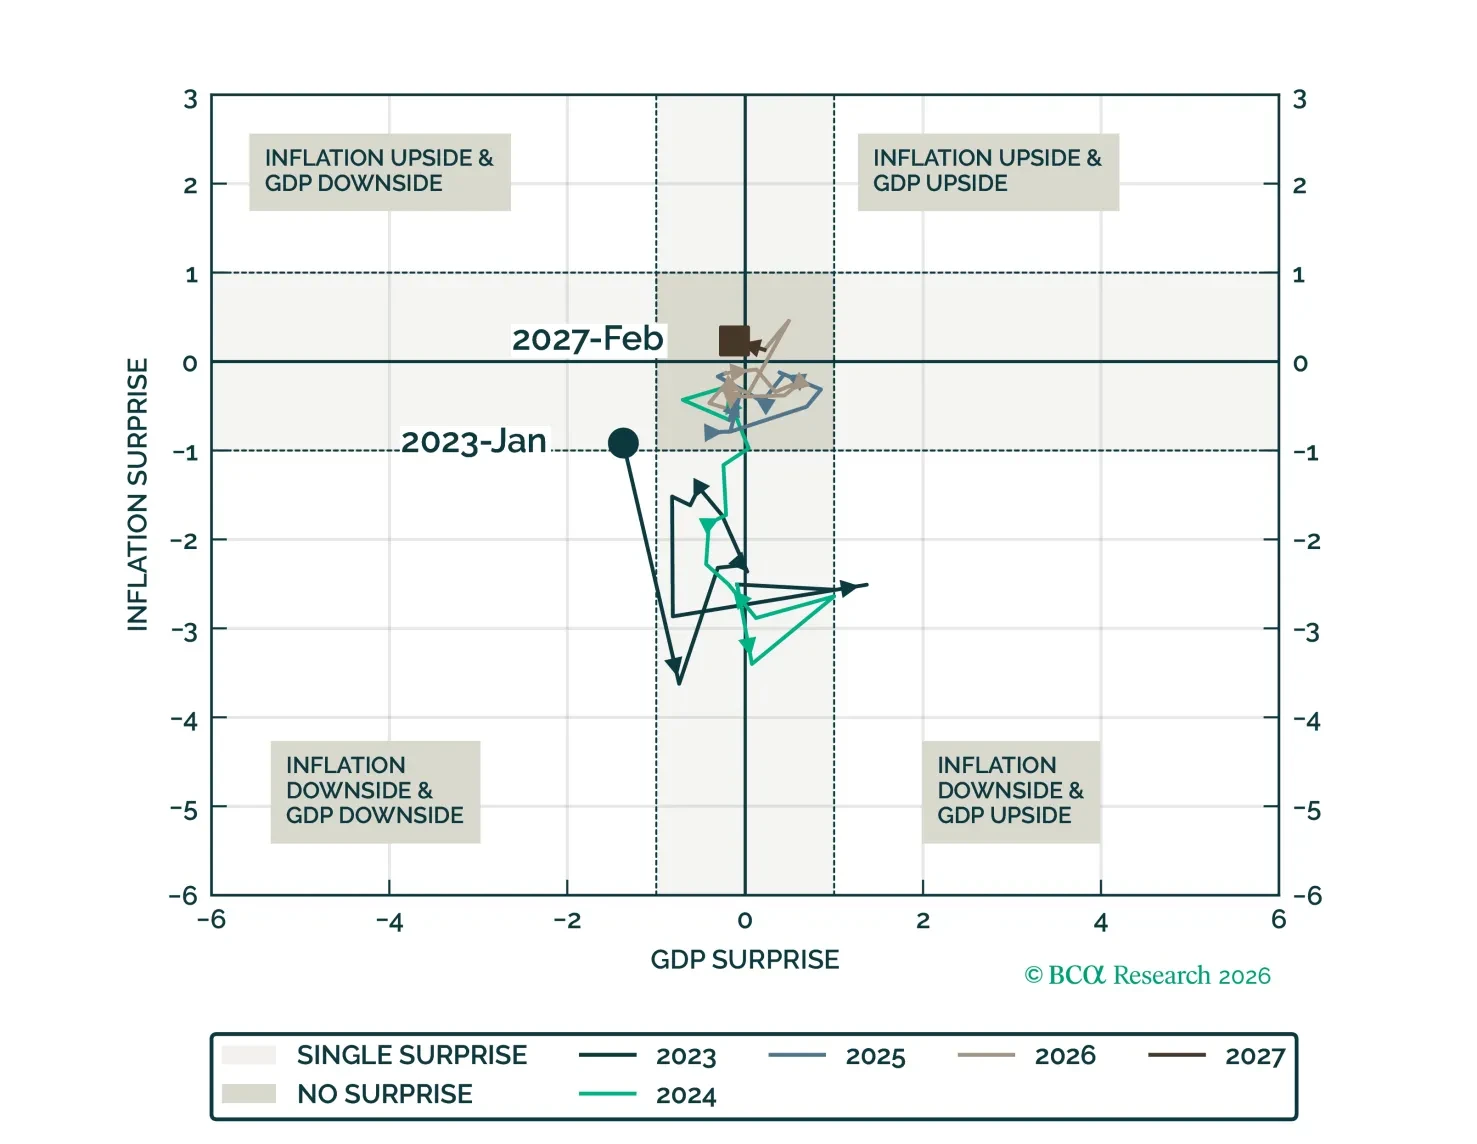
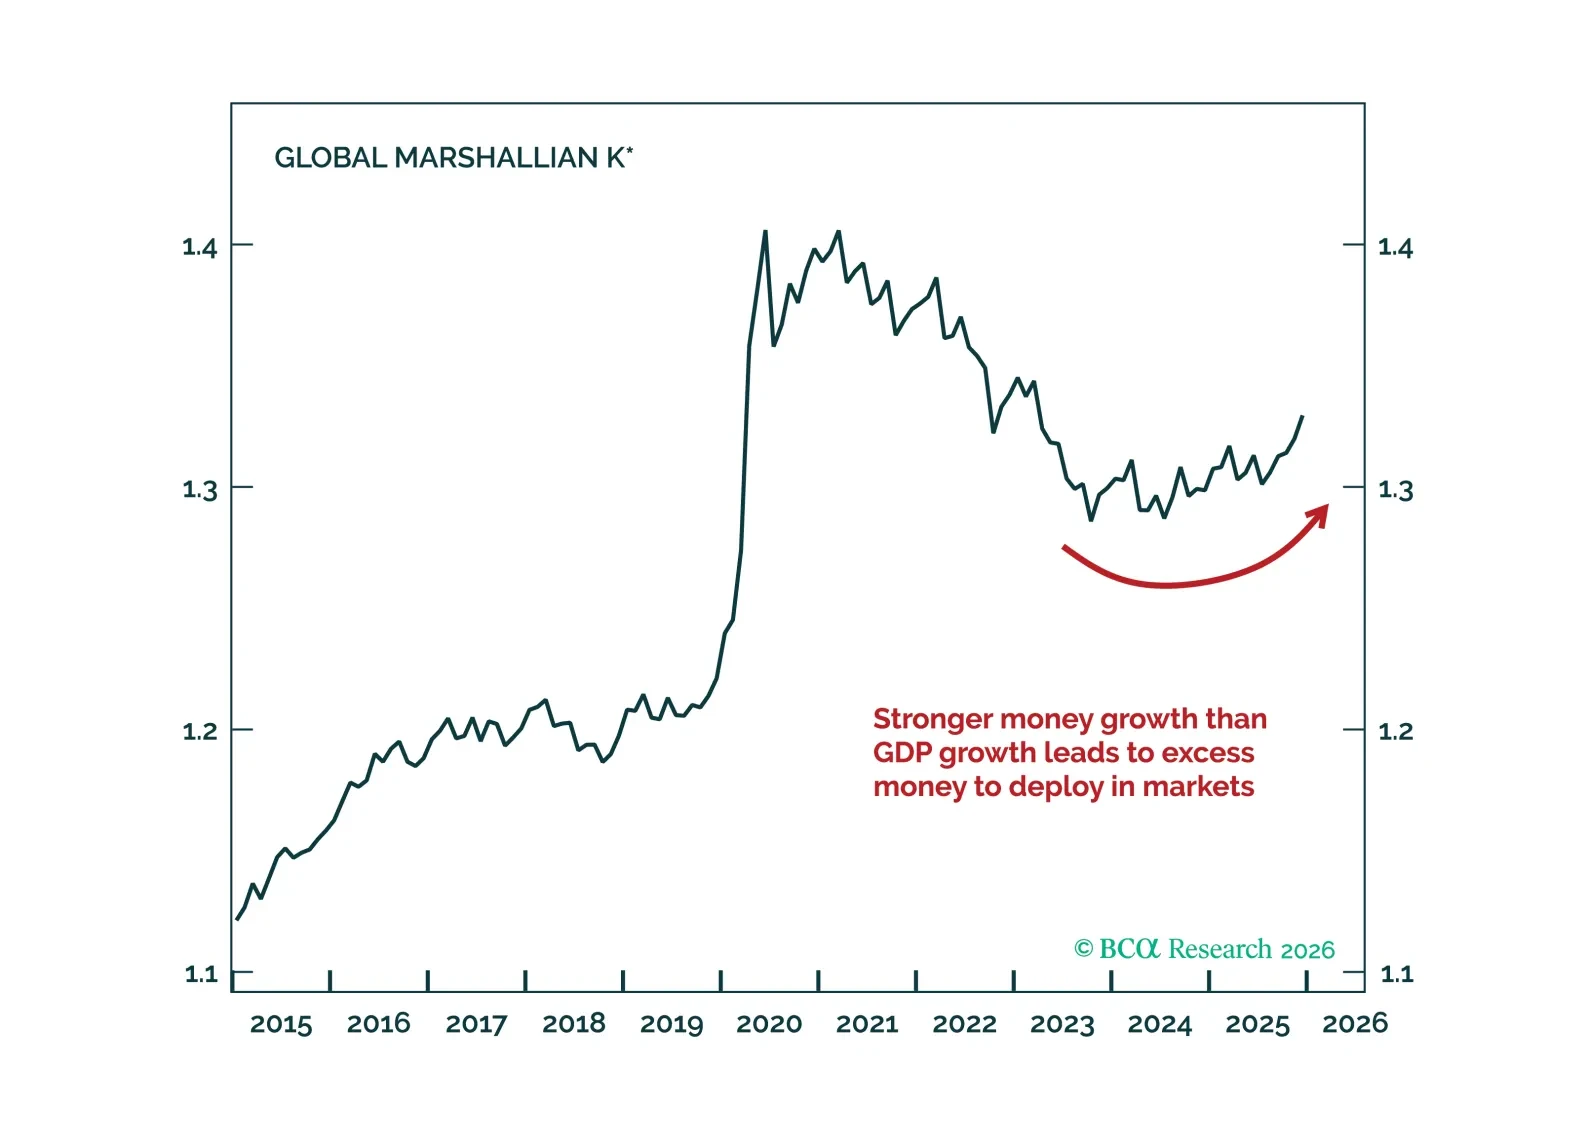
The actions of the Trump administration have dominated the headlines over the past month. They are all noise. Focus on the reactions from the rest of the world. Policy makers outside of the US are now determined to stimulate and reform their domestic economies. Global growth is accelerating without a corresponding increase in inflation. This combination is not only positive for risk assets but is also supercharging returns for Ex-US stocks. Downgrade Fixed Income and duration.
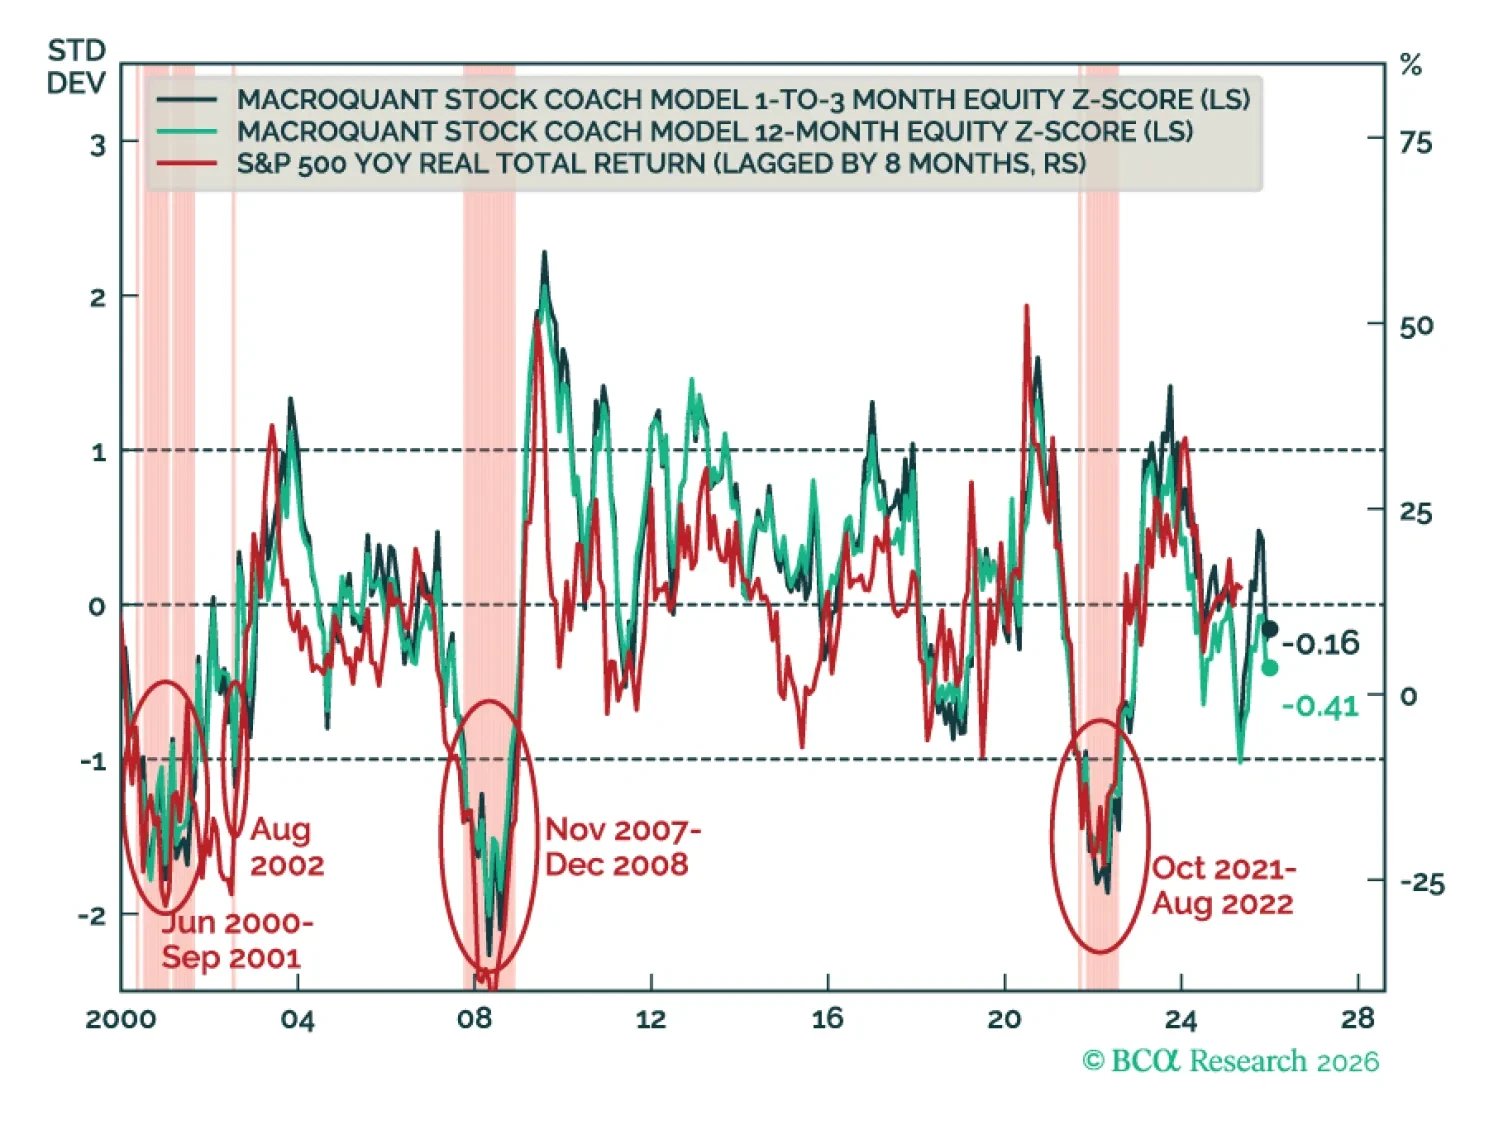
MacroQuant recommends a slight underweight in equities, favors a below-benchmark duration stance in fixed-income portfolios, remains bearish on the US dollar, has upgraded oil and copper to overweight, and is bullish on gold.
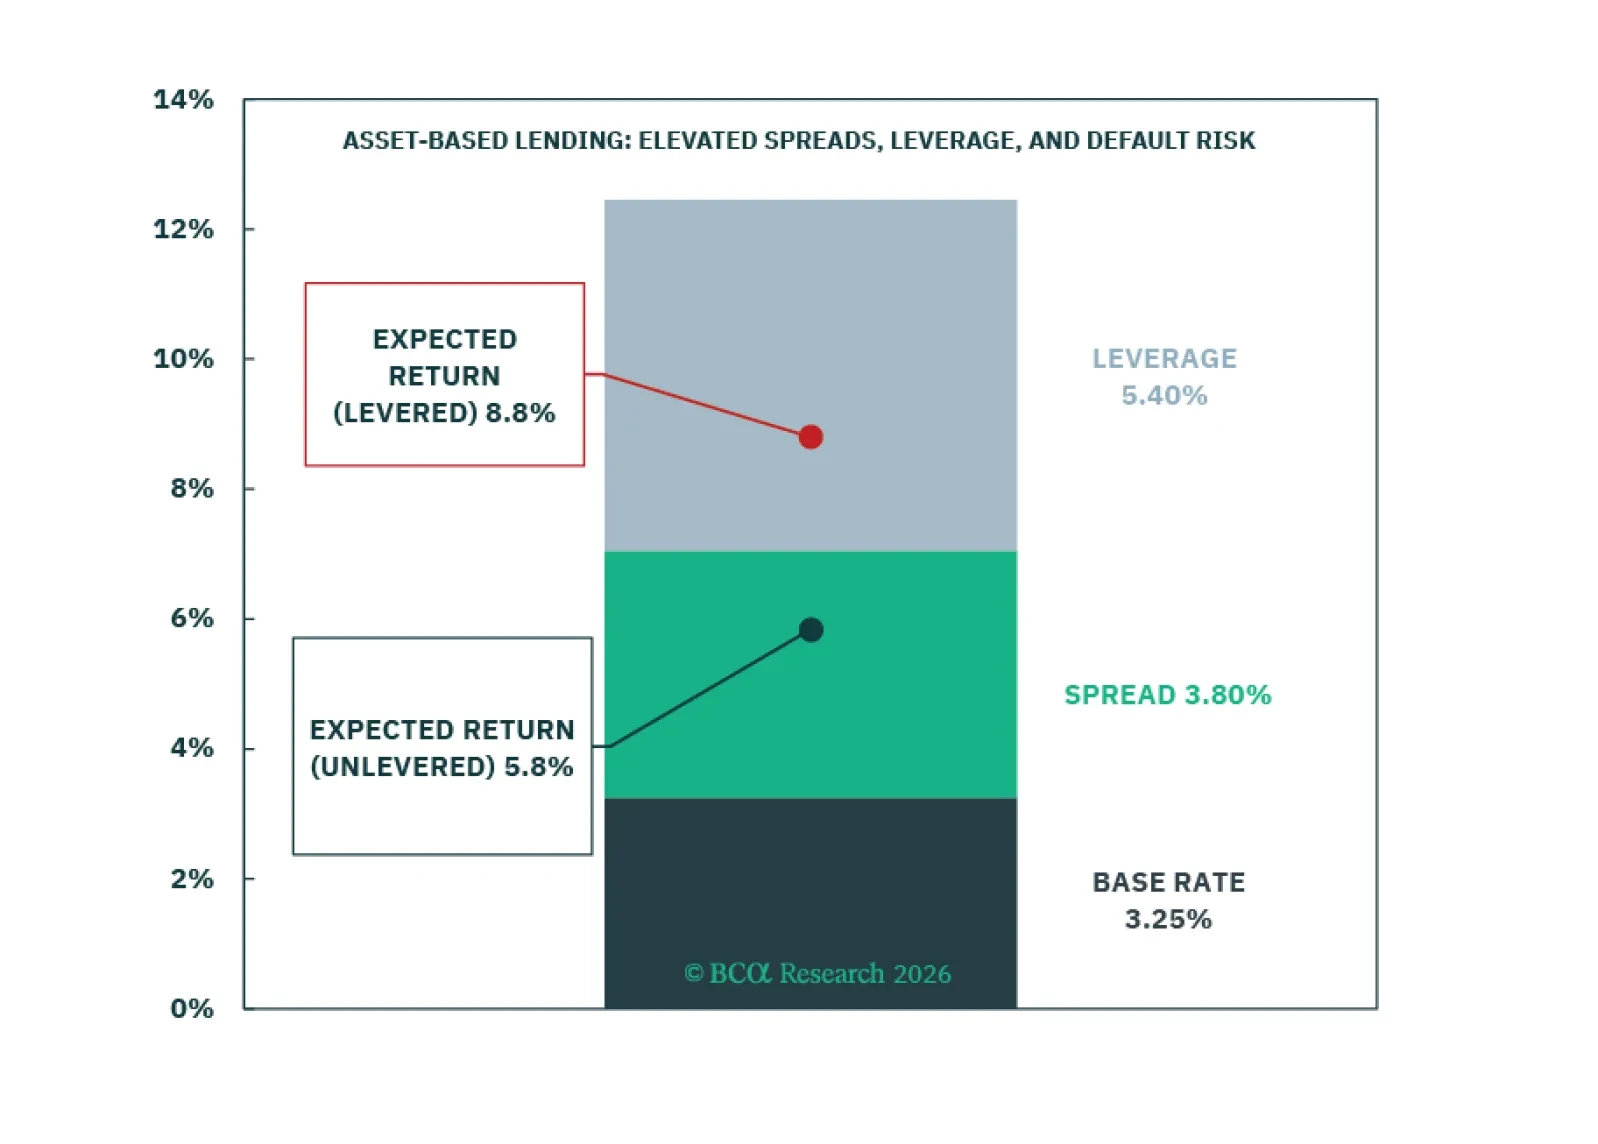
Our new Private Credit taxonomy adds granularity to the opaque lending universe and introduces Asset-Based Lending—attractive entry points, elevated risks. Private Real Estate delivers the largest upgrades from 2025, while Public REITs and Public Infrastructure present compelling opportunities that investors should not overlook.

The AI trade has broadened beyond Public Markets, pulling Private Credit deeper into the ecosystem. Investors are right to understand their overlapping exposures between Public Equities, Venture Capital, Data Centers, and now Private Credit. However, risks from rising Venture Capital Debt and Asset-Based Lending are going unnoticed.