 GeoMacro
Find out more
Did you know that the high-quality Japanese zippers you use every day are macro relevant? That is because YKK dared to sue – and win – against President Richard Nixon 10% across-the-board tariffs.
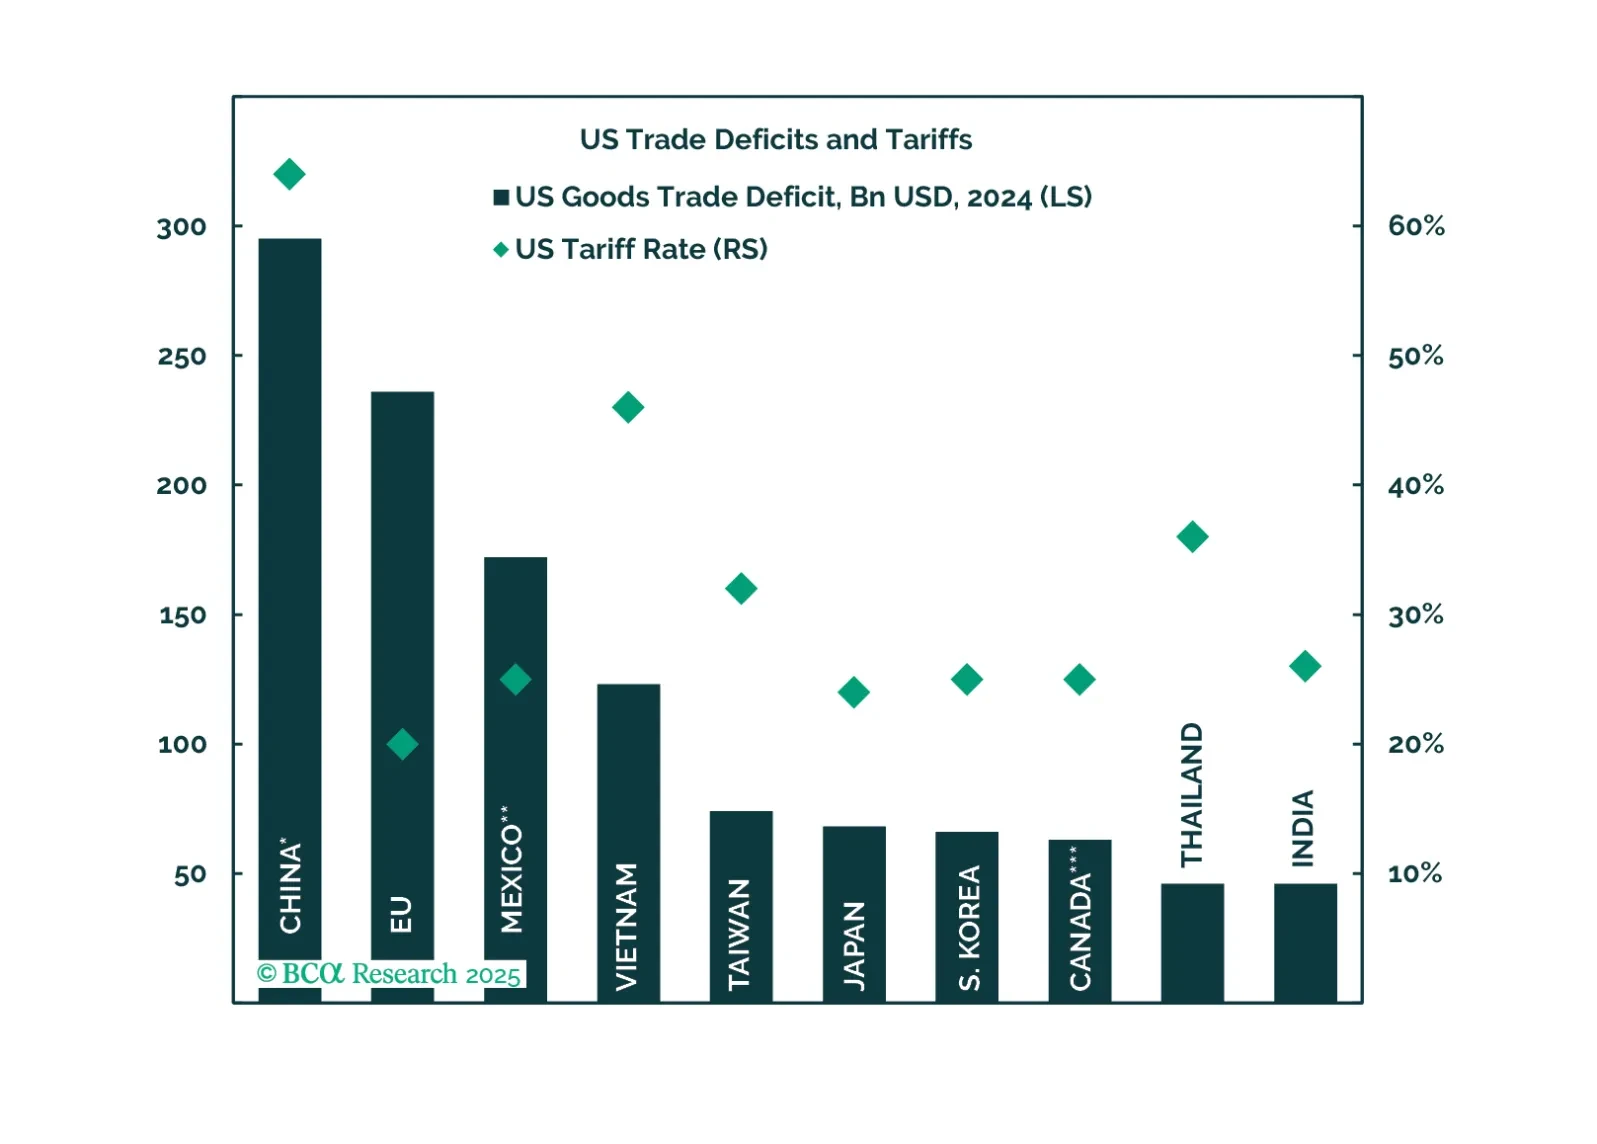
Trump's Tariff D-Day brings a negative surprise to financial markets already anxious over a declining US cyclical economy. Investors should sell risky assets, increase safe havens, and overweight US assets in the near term.
The White House has revealed the plans for Liberation Day. They broadly include: Reciprocal tariffs, on a case-by-case basis. A message from President Trump to other countries to lower their own tariffs and buy US goods. Our take is that April 2 will be remembered – 6-12 months from now – as the peak in “de-globalization” thesis. Markets react to the delta of bad news, not bad news in the absolute.
Liberation Day is coming to America! In honor of the new holiday, GeoMacro will be increasing prices using an algorithm that will determine how much each client owes us for the sweet taste of their liberty (… from the clutches of normative geopolitical analysis)!
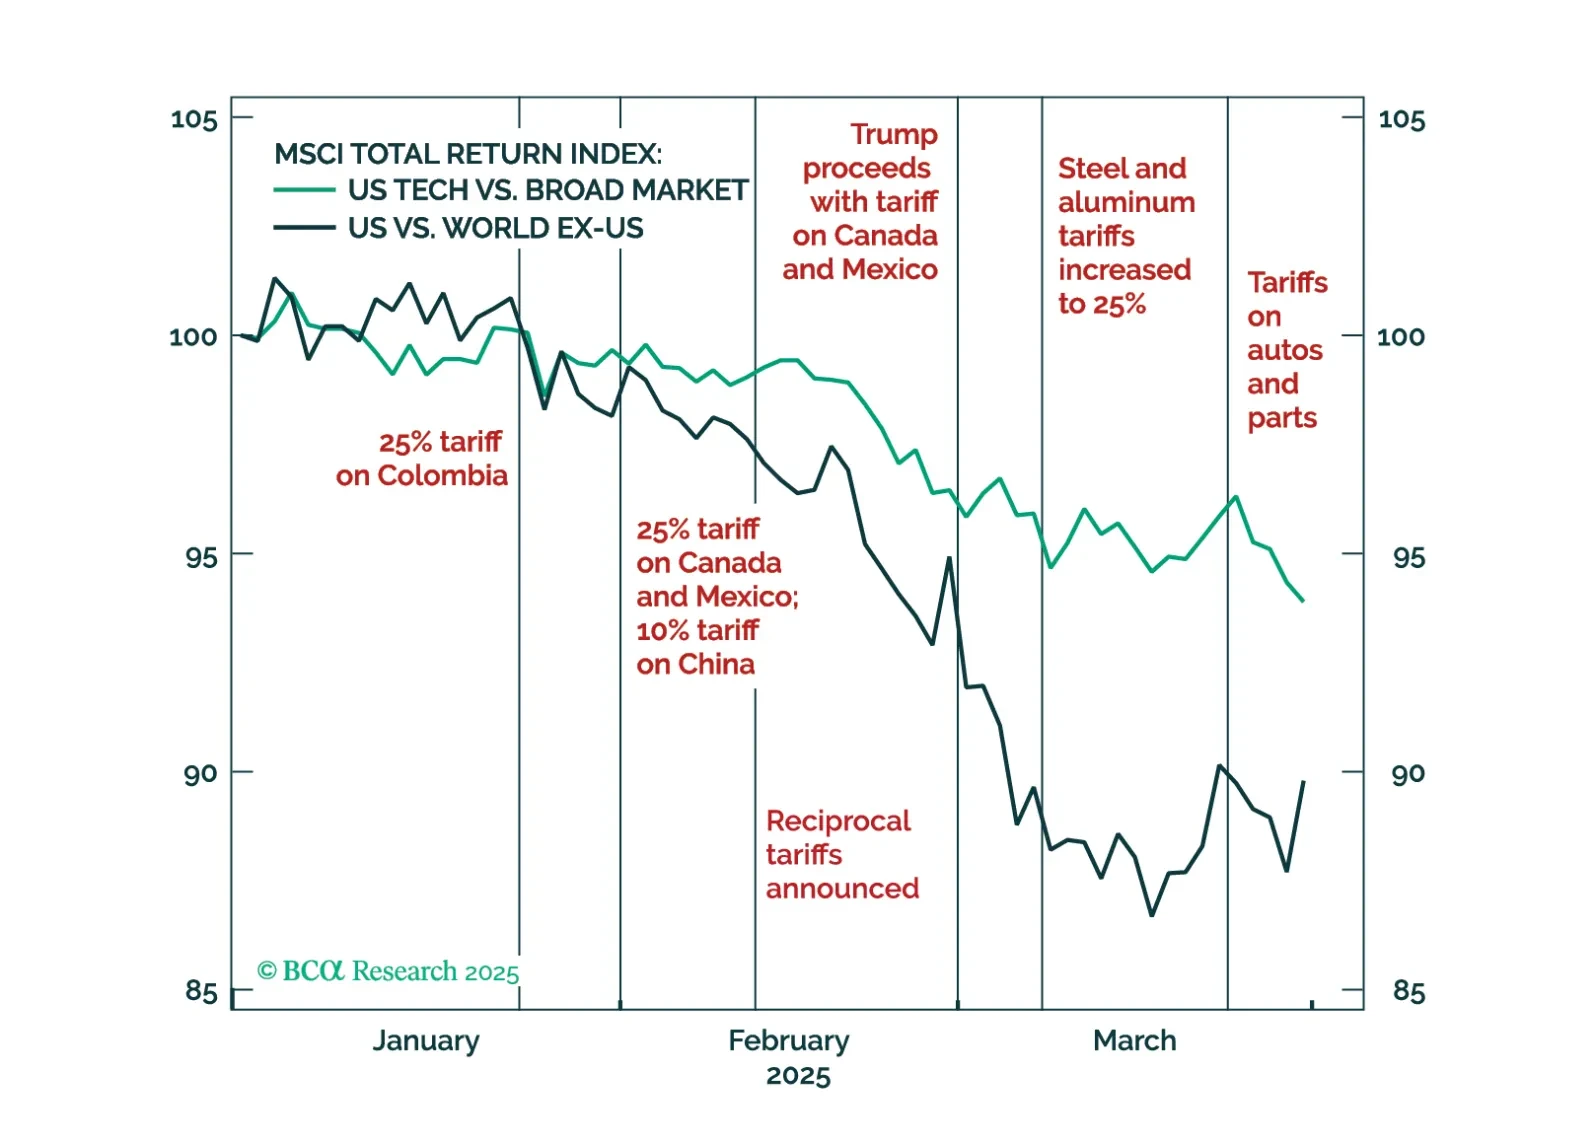
The trade war is on everyone’s mind with America’s “Liberation Day” upon us! However, the reality under the surface is that the main macro narrative has been a rotation – nay… exodus – out of US assets into RoW. This was not supposed to happen with de-globalization and a MAGA trade policy. US assets – form equities to the USD – were supposed to be the safe haven from “America First” policies by Donald Trump. Meanwhile, the noose of material constraints is tightening around Trump, suggesting that a pivot away from brinkmanship may not be long away from “Liberation Day.”

In this month’s Beta report, we continue our series supporting our bullish thesis on Europe. We take a deep dive into the aftermath of the European energy crisis – dispelling the myth that Europe faces risks of imminent deindustrialization – and evaluate the impact the approaching LNG wave will have on European industry and the global natural gas market.
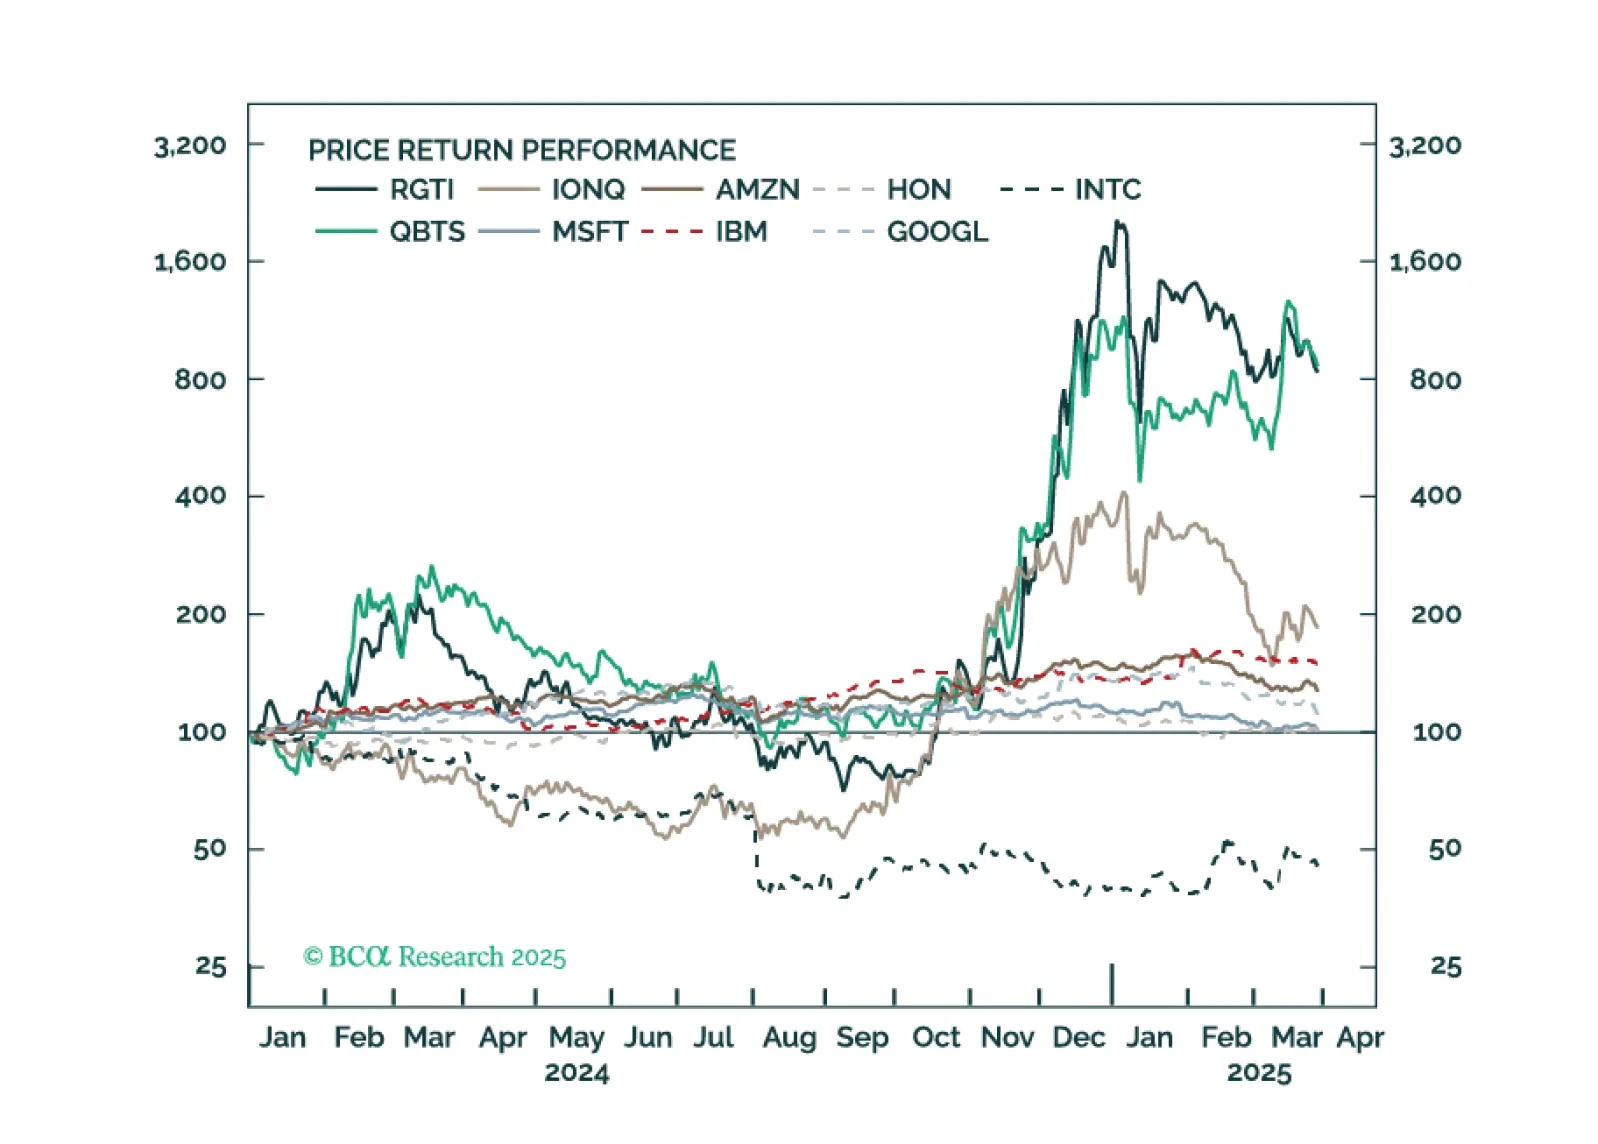
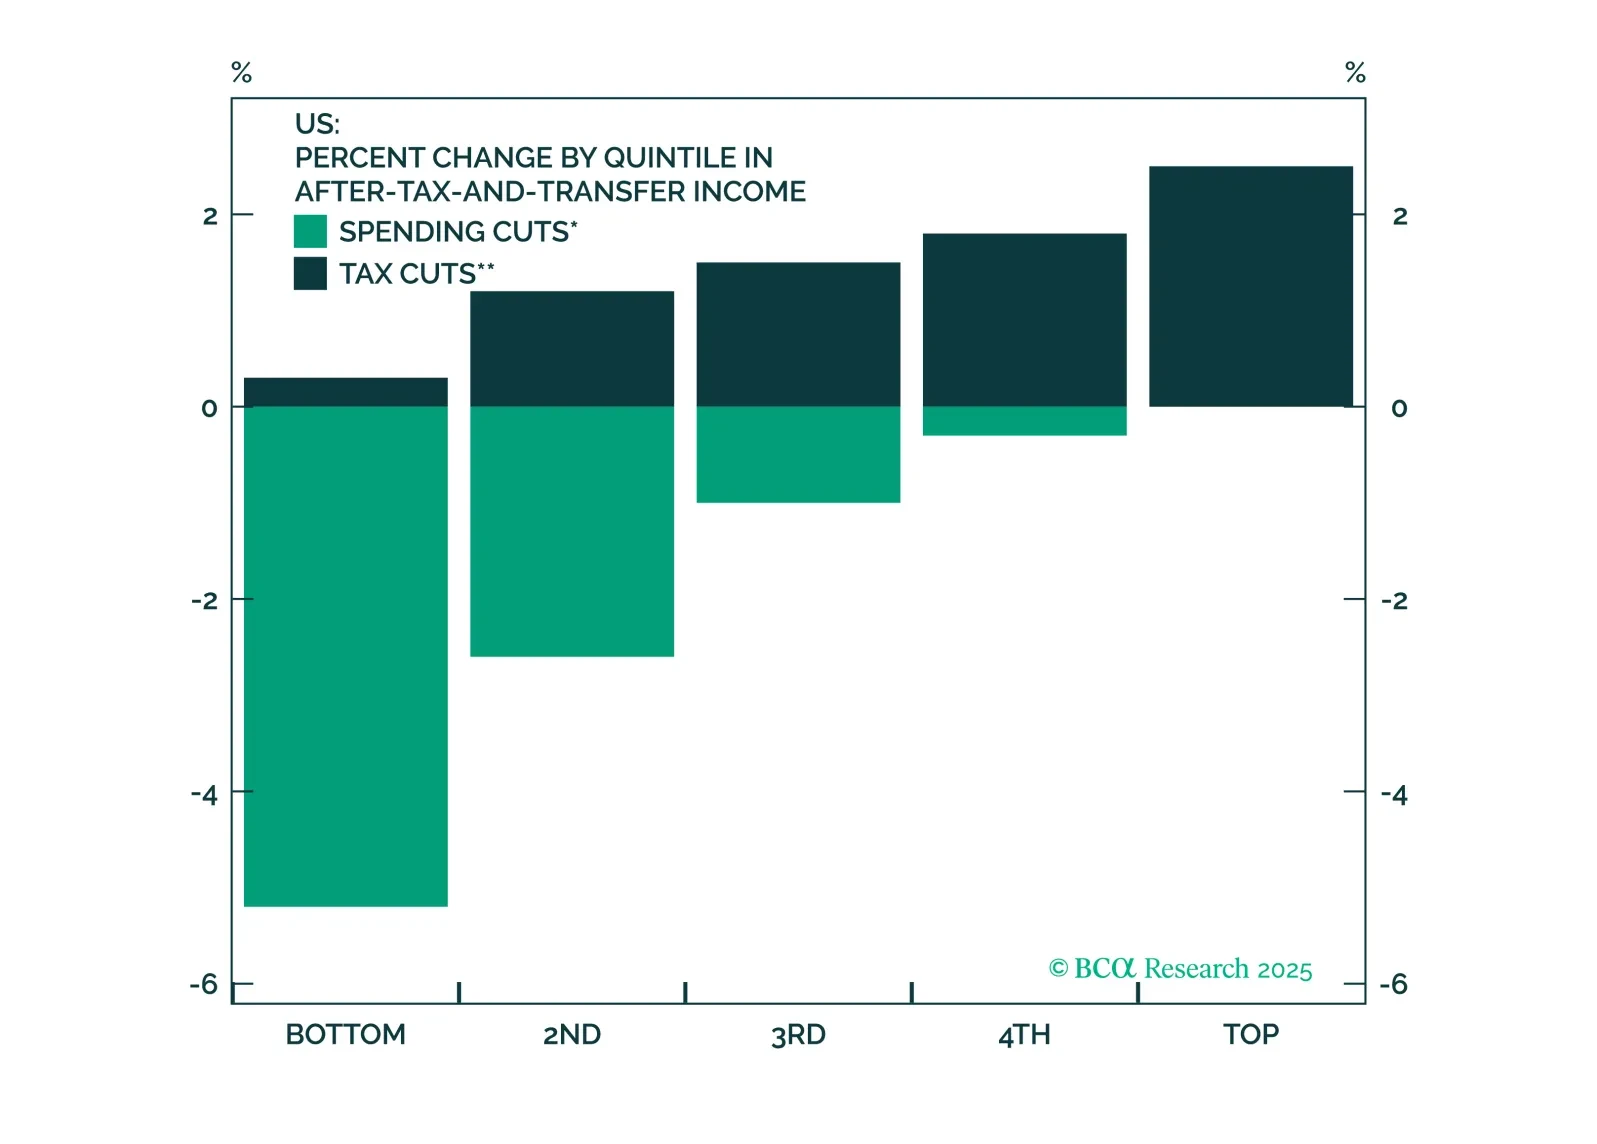
Stocks will continue to struggle in the second quarter as President Trump tries to implement tariffs. Tax cuts will only temporarily dispel growth fears, if at all. Middle Eastern instability will add oil price surprises to an environment that is looking fairly stagflationary.
Clients have asked us repeatedly about our thoughts on the Mar-a-Lago Accord. Our readers know that we believe that the US is constrained by its median voter and the reality of geopolitical multipolarity. As such, the path of least resistance is towards a cheaper USD, which is currently being achieved through an organic macro see-saw of relative fiscal policy. The idea that the US gets to “restructure the global trading system” on its own is, therefore, ludicrous.
We share with our clients a brief rundown of “Washington, DC” intelligence on the upcoming April 2 tariffs. Most of it is bearish. However, the day may mark “peak de-globalization hysteria.” President Trump is also starting his Maximum Pressure campaign against Iran. That is two such campaigns at the same time, perhaps more than the administration can handle simultaneously.