 GeoMacro
Find out more
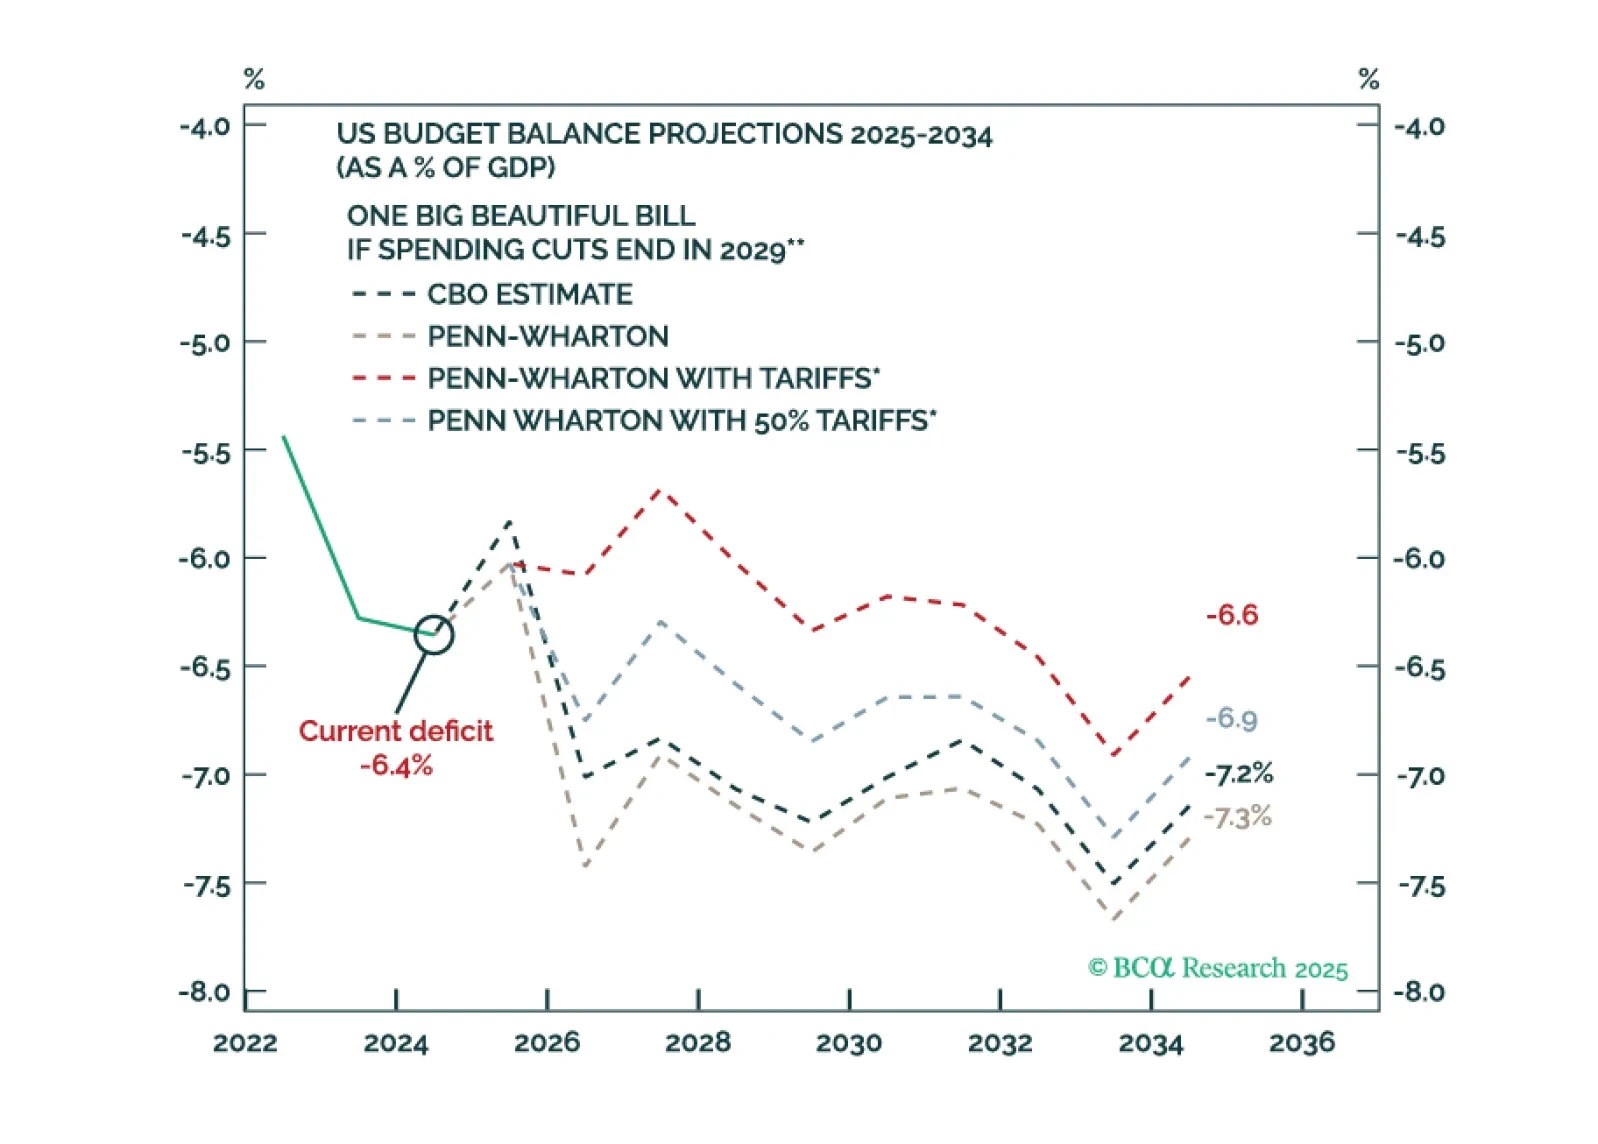
Bond market volatility will spike again in the near term. The Fed is committed to an easing cycle yet the Trump administration’s signature fiscal policy action will stimulate the economy. Tariffs are supposed to keep the budget deficit contained but they are inflationary.
This month, we flip the order of our chartpack. We focus on the secular/long-term first. Both because we think that we have something profound to say and because we believe that our tactical call has very little new value-add. We remain convinced, as we have been for over a year, that President Trump is not willing to upend decades of US trade policy.
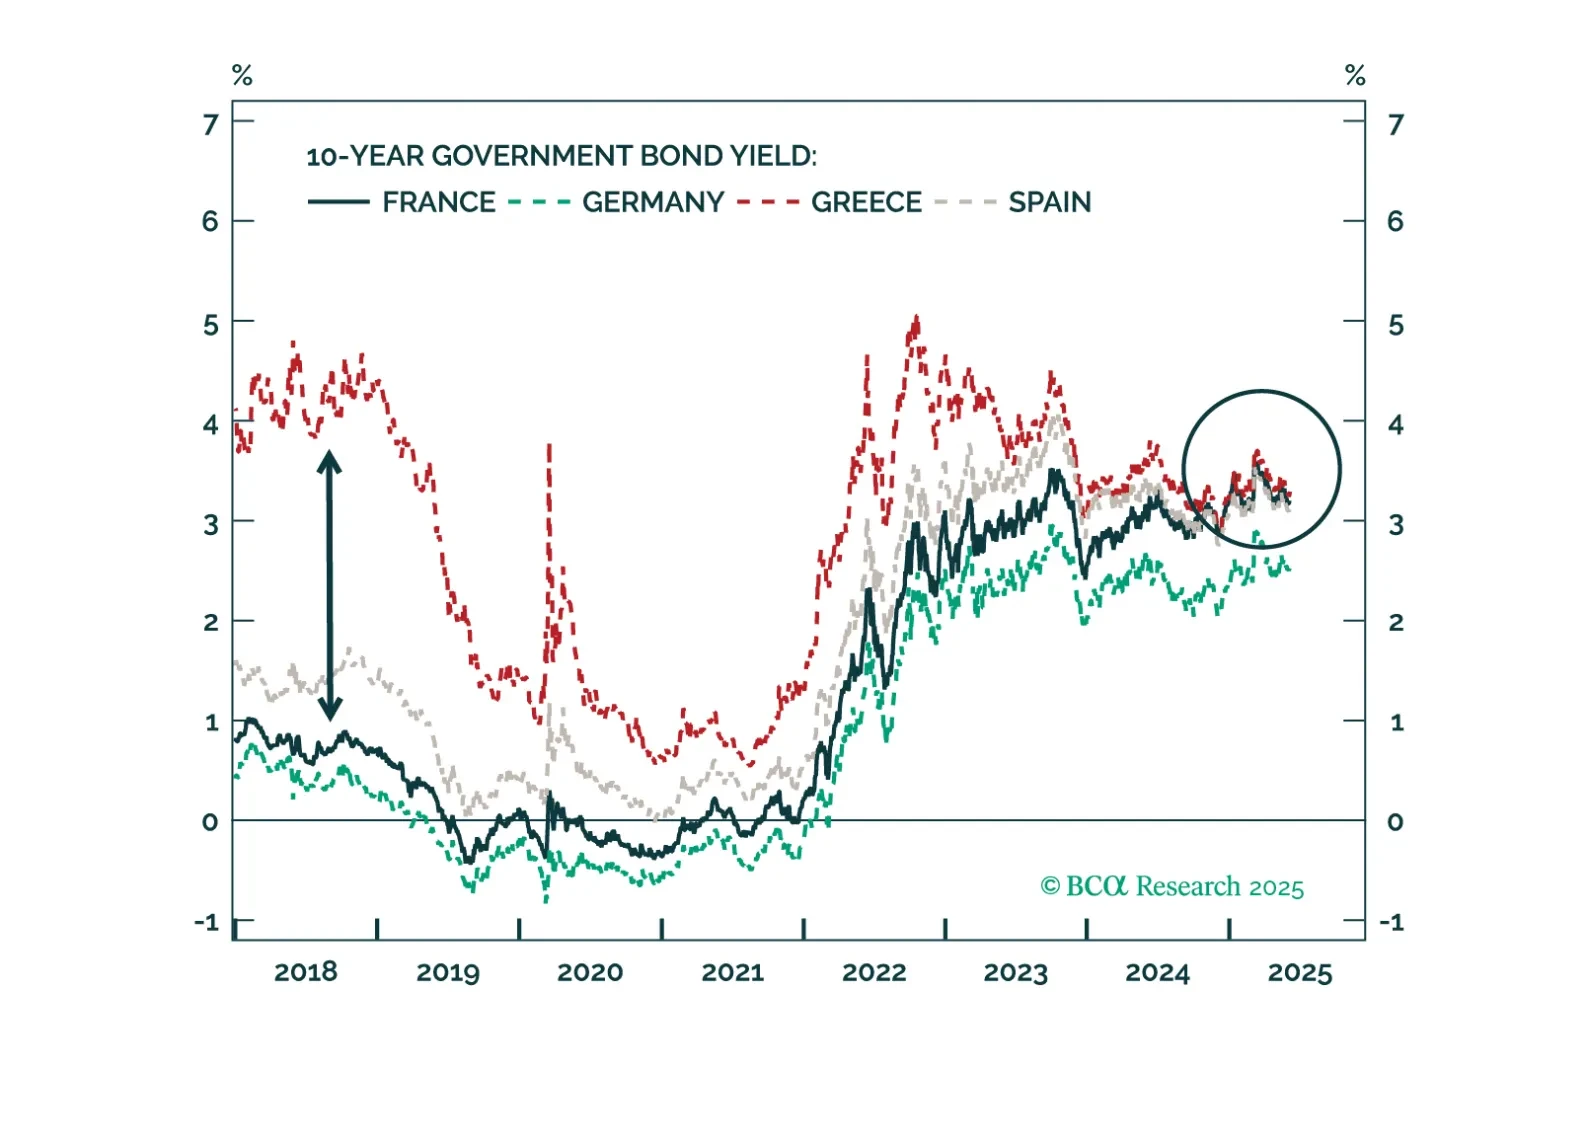
President Trump has activated the California national guard as protests envelop the city of Los Angeles for the third day in the row. This is the first time that the national guard has been activated by the federal government in Los Angeles since the 1992 riots. Our clients from Australia to Greece have inundated us with questions of how far the situation can go.
Several astute clients have asked us to comment on the recent extraordinary attack by Ukraine against Russia. The attack, which did not harm any Russian military personnel, occurred on June 1 and struck airfields across the vastness of Russia, as far as the Far East. According to Ukrainian officials, 41 military aircraft were successfully targeted. This information has not been verified by either Russian or Western officials.
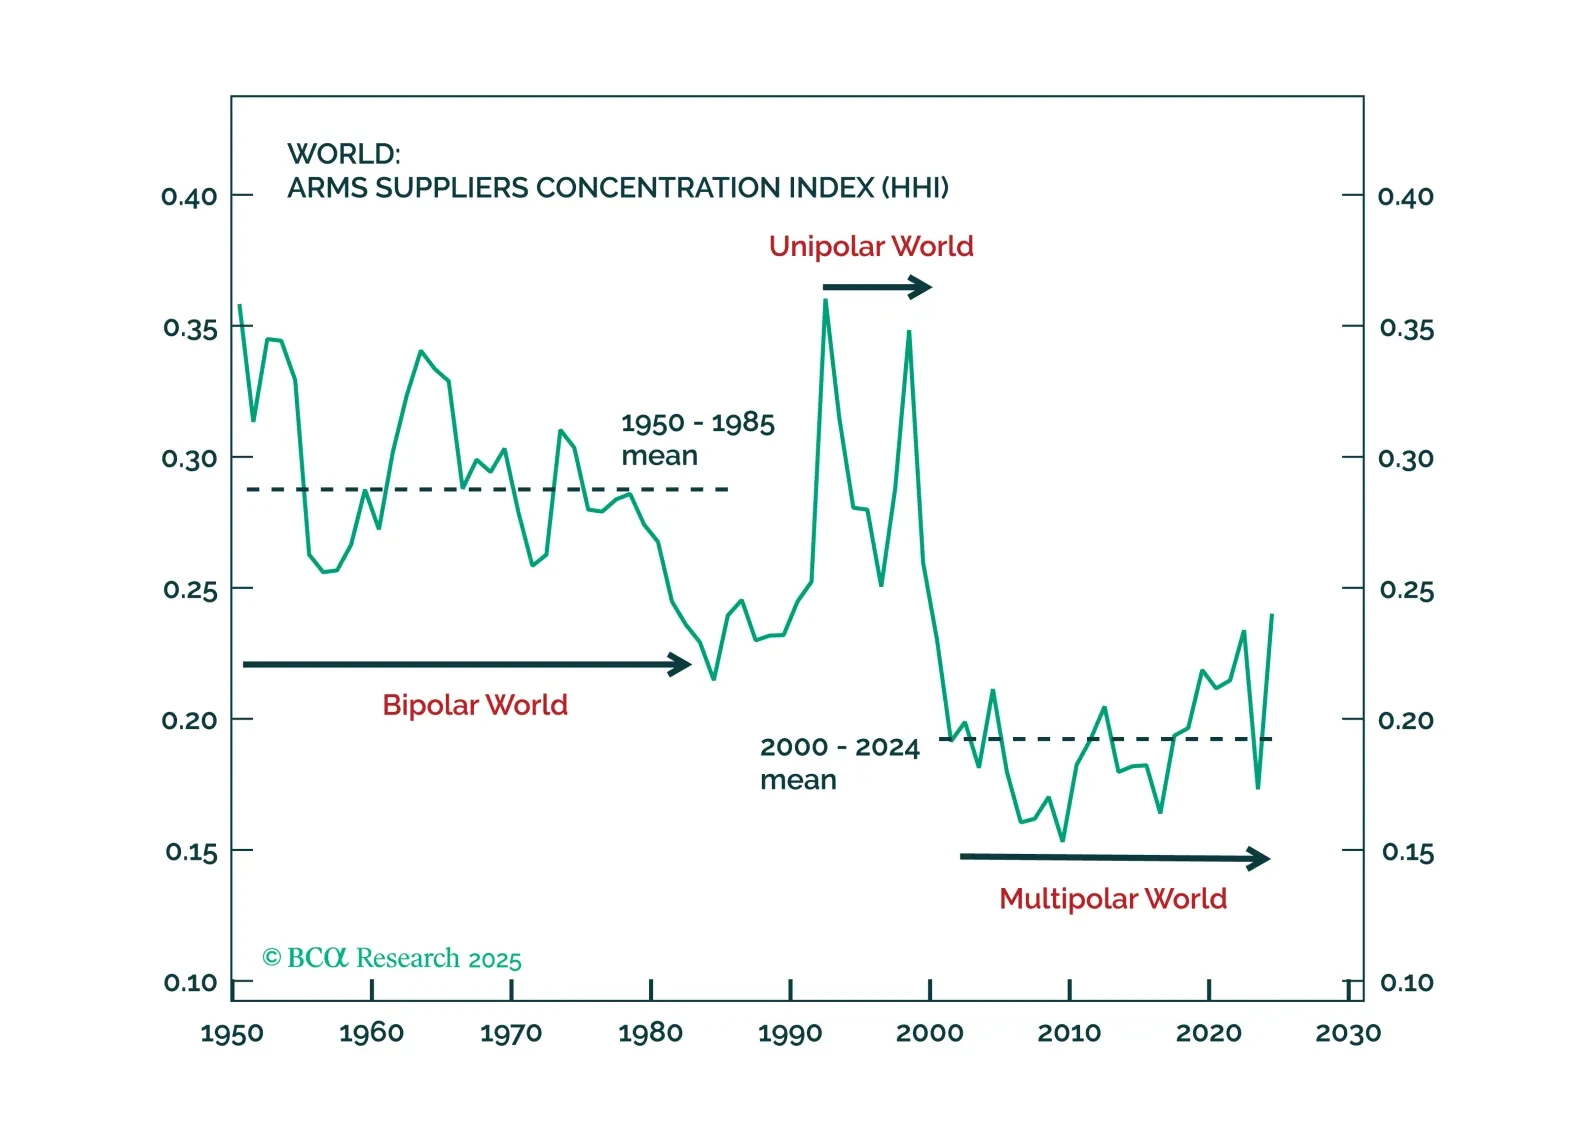
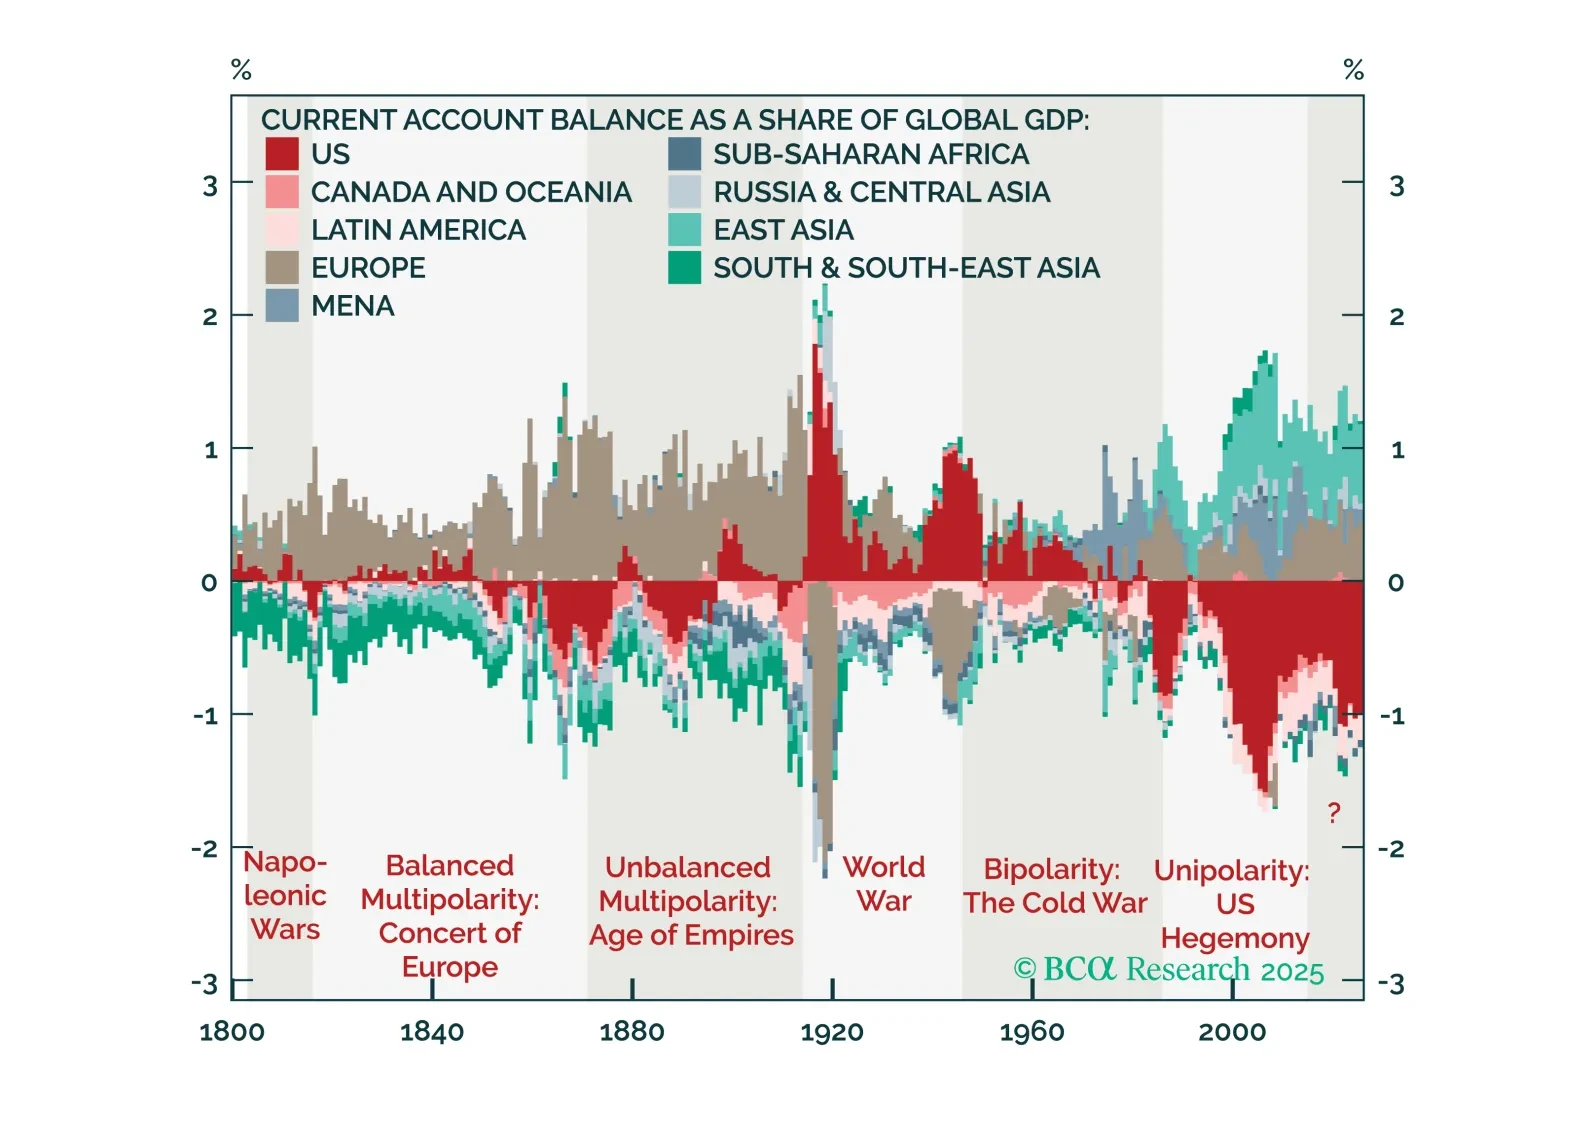
In our Beta report, we focus on our decade view. Many of our global allocator clients are scrambling to incorporate geopolitics into their strategic asset allocation. For most, this means thinking about war… or about future end-states. This is a mistake. We consider the next five years (maybe a decade) as the transition to the new era, a transition away from American unipolarity. And the transition itself is investment relevant. A transition to a multipolar world – which we think is occurring – will crush the USD and favor non-US assets. A transition to a bipolar world – not our base case, but still possible – would do the opposite.
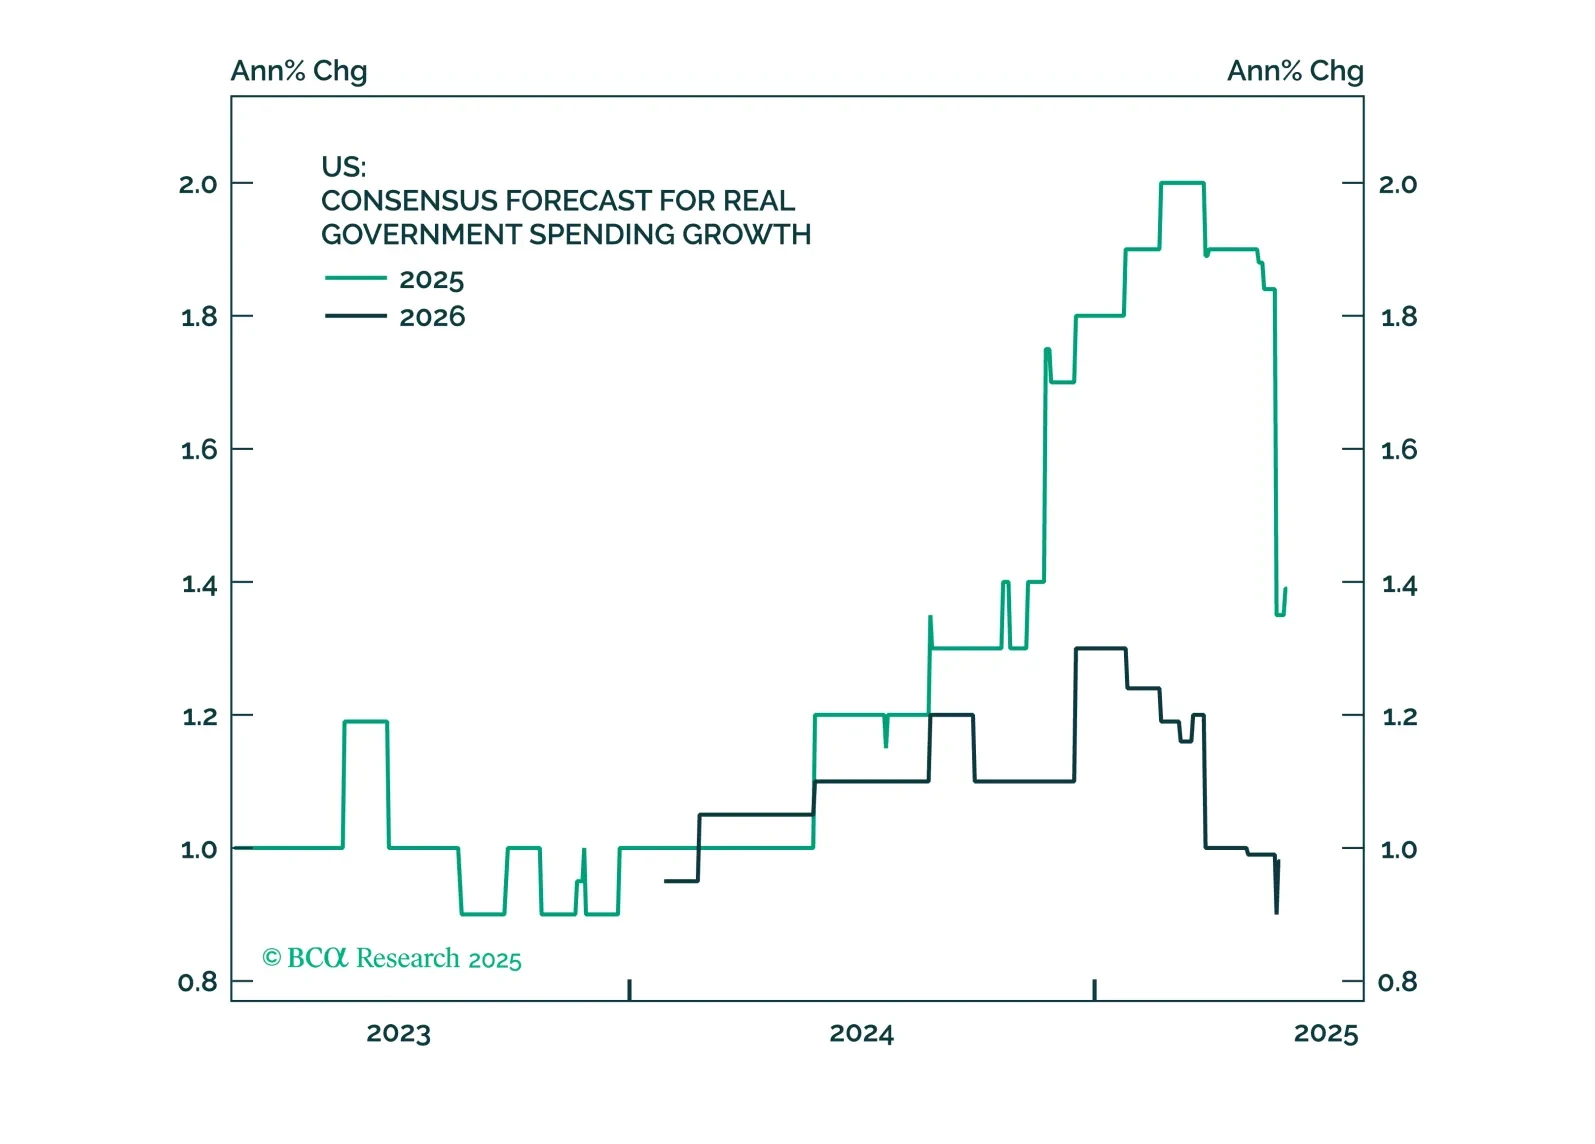
This month, we focus on the One Big Beautiful Bill Act (OBBBA). Our assessment in the Alpha report is that there won’t be any remaining alpha to harvest by shorting duration. The team that coined the “Human Steepener” moniker for President Trump is, effectively, throwing in the towel on looking for more upside to yields. There are many reasons for that view, but the main one is that the OBBBA legislation is just not that profligate, especially not relative to the investors’ expectations in the early days of the Trump 2.0 term.
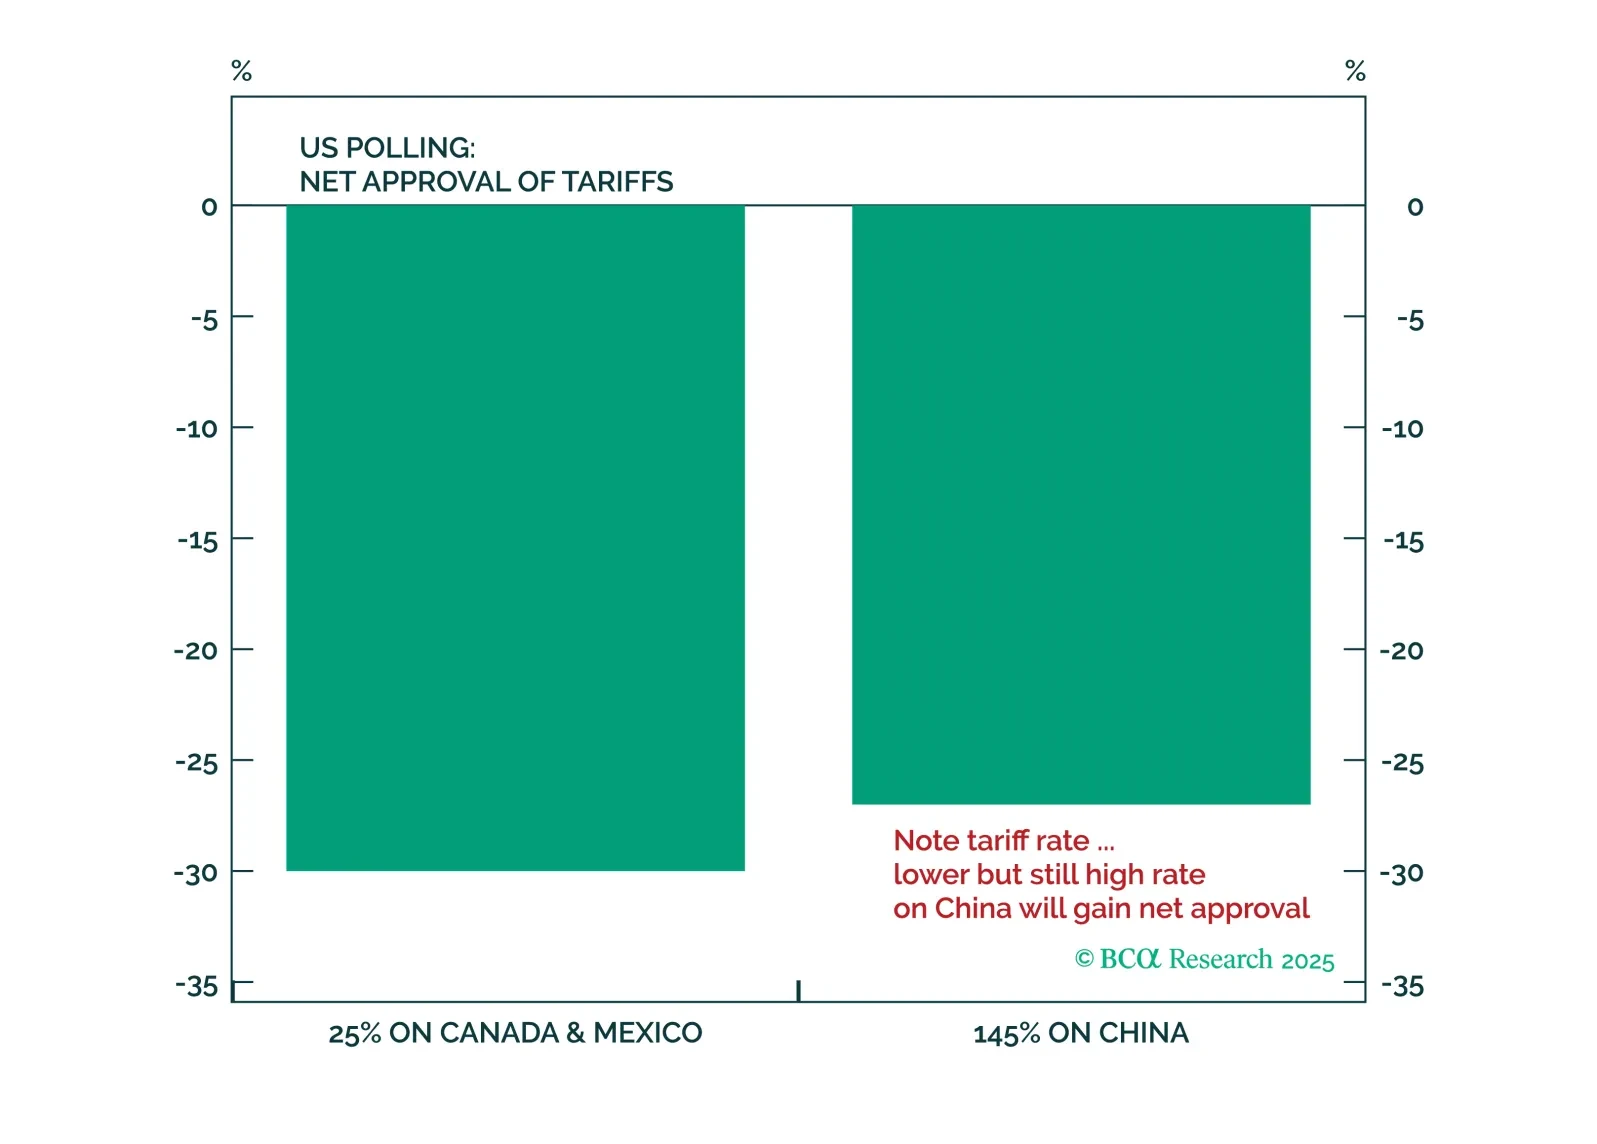
President Trump faces new restrictions on his trade powers coming from the US judicial branch, but they will not prevent him from continuing to restrict trade and investment with China. Rather, they will establish some curbs against entirely arbitrary executive tariffs, especially when wielded against US allies and partners.
On September 11, 1990, President George H. W. Bush addressed a joint session of Congress. The speech – which has come to be known as the “New World Order” address – referenced the emergence of a new geopolitical paradigm. While Bush Sr. was rather vague about what that paradigm was, his national security team filled out the details in subsequent addresses and writings. On December 4, 1992, as Bush Sr. announced the deployment of US troops to Somalia, it became clear that the New World Order was American hegemony.
Several clients hailing from the global allocator community have schooled us to the existence of the “Section 899,” a feature of the “One Big Beautiful Bill Act” (OBBBA) that passed the House of Representatives on May 22. The bill is currently being reviewed by the Senate and Section 899 – which adds a new section to the US tax code titled “Enforcement of Remedies Against Unfair Foreign Taxes” – is likely to remain in place.