 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
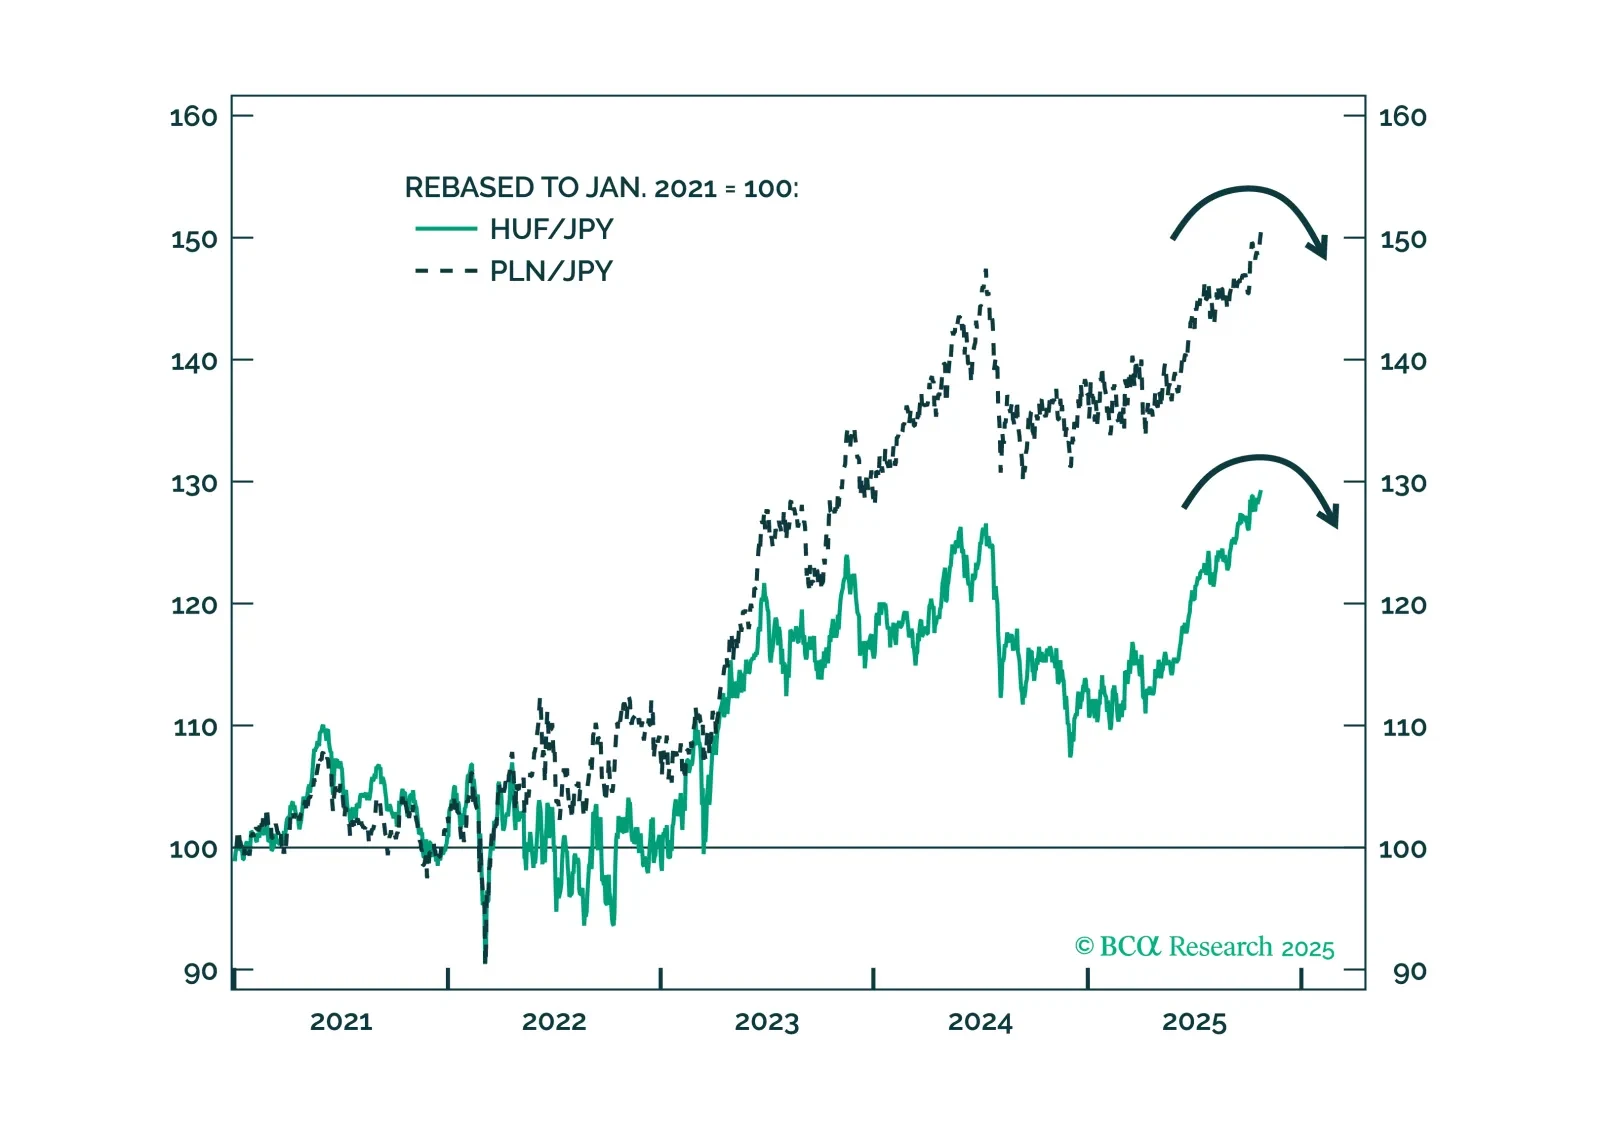
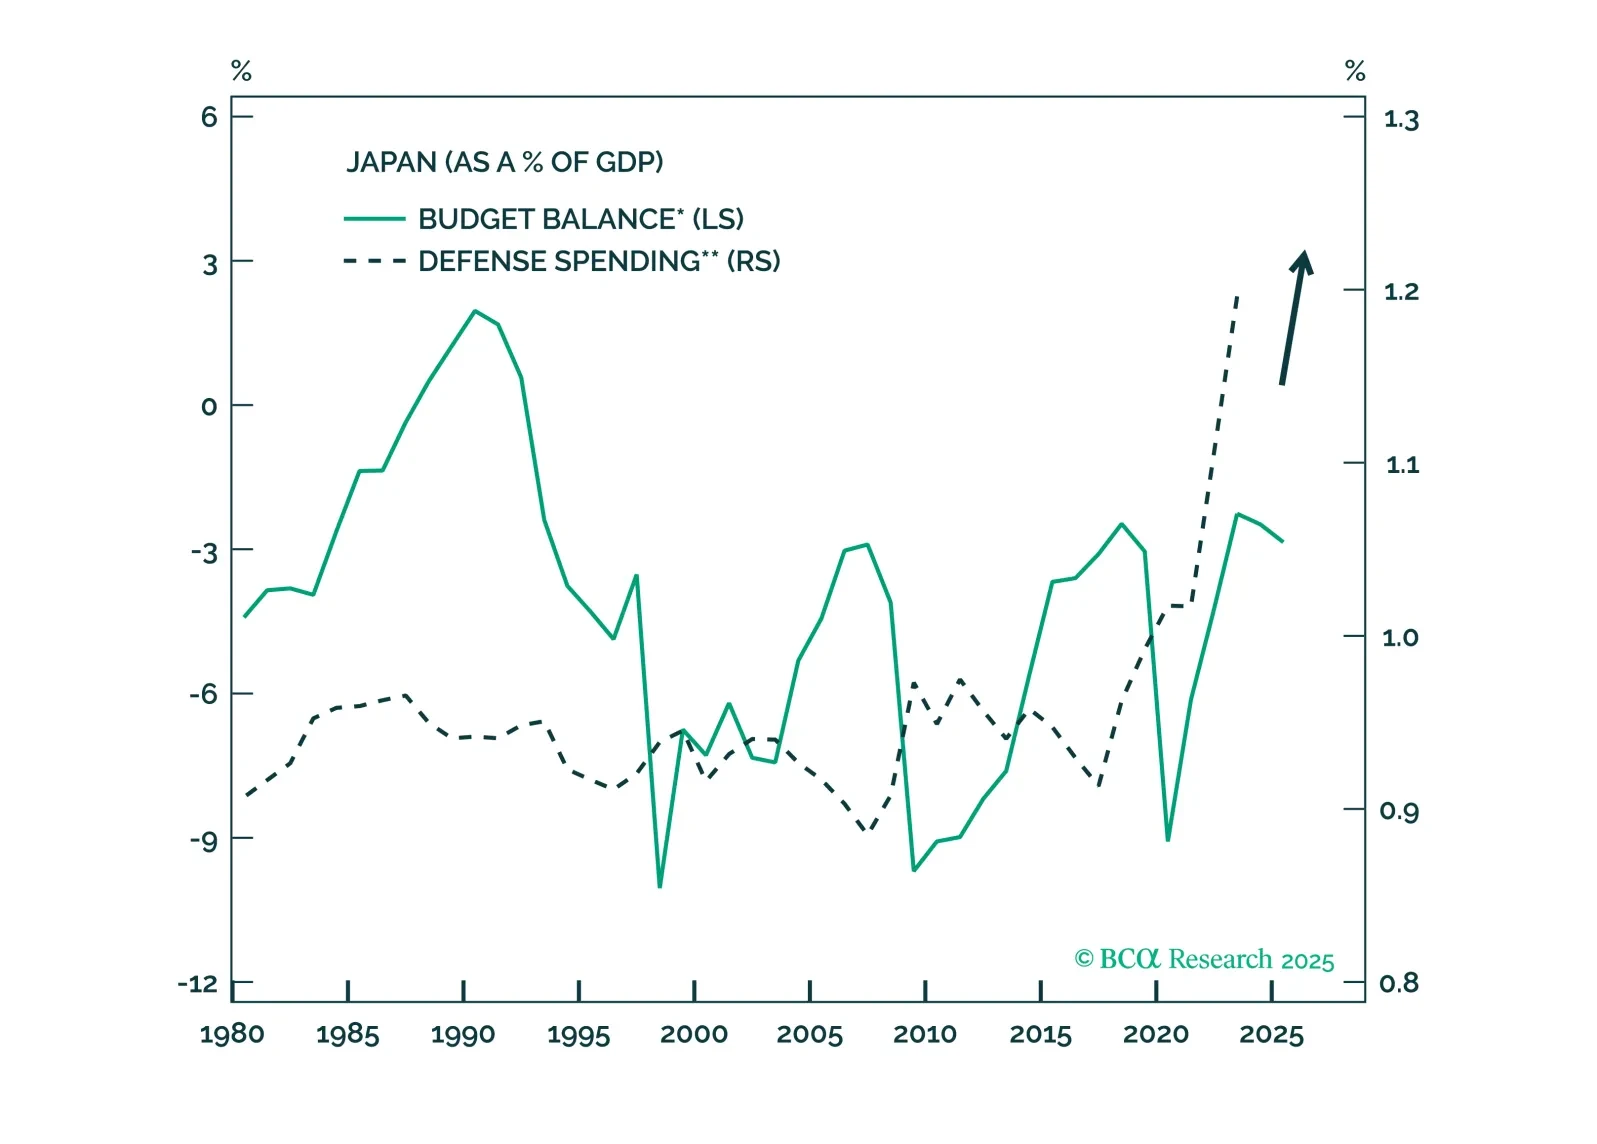
Japan's first woman prime minister, Sanae Takaichi, will underperform on economic stimulus but outperform on defense spending and strategic diplomacy. Stay long Japanese yen.
Reduce risk exposure in the very near term as President Trump's ceasefire effort falters, Russia tensions spike, and US-China trade prospects suffer.
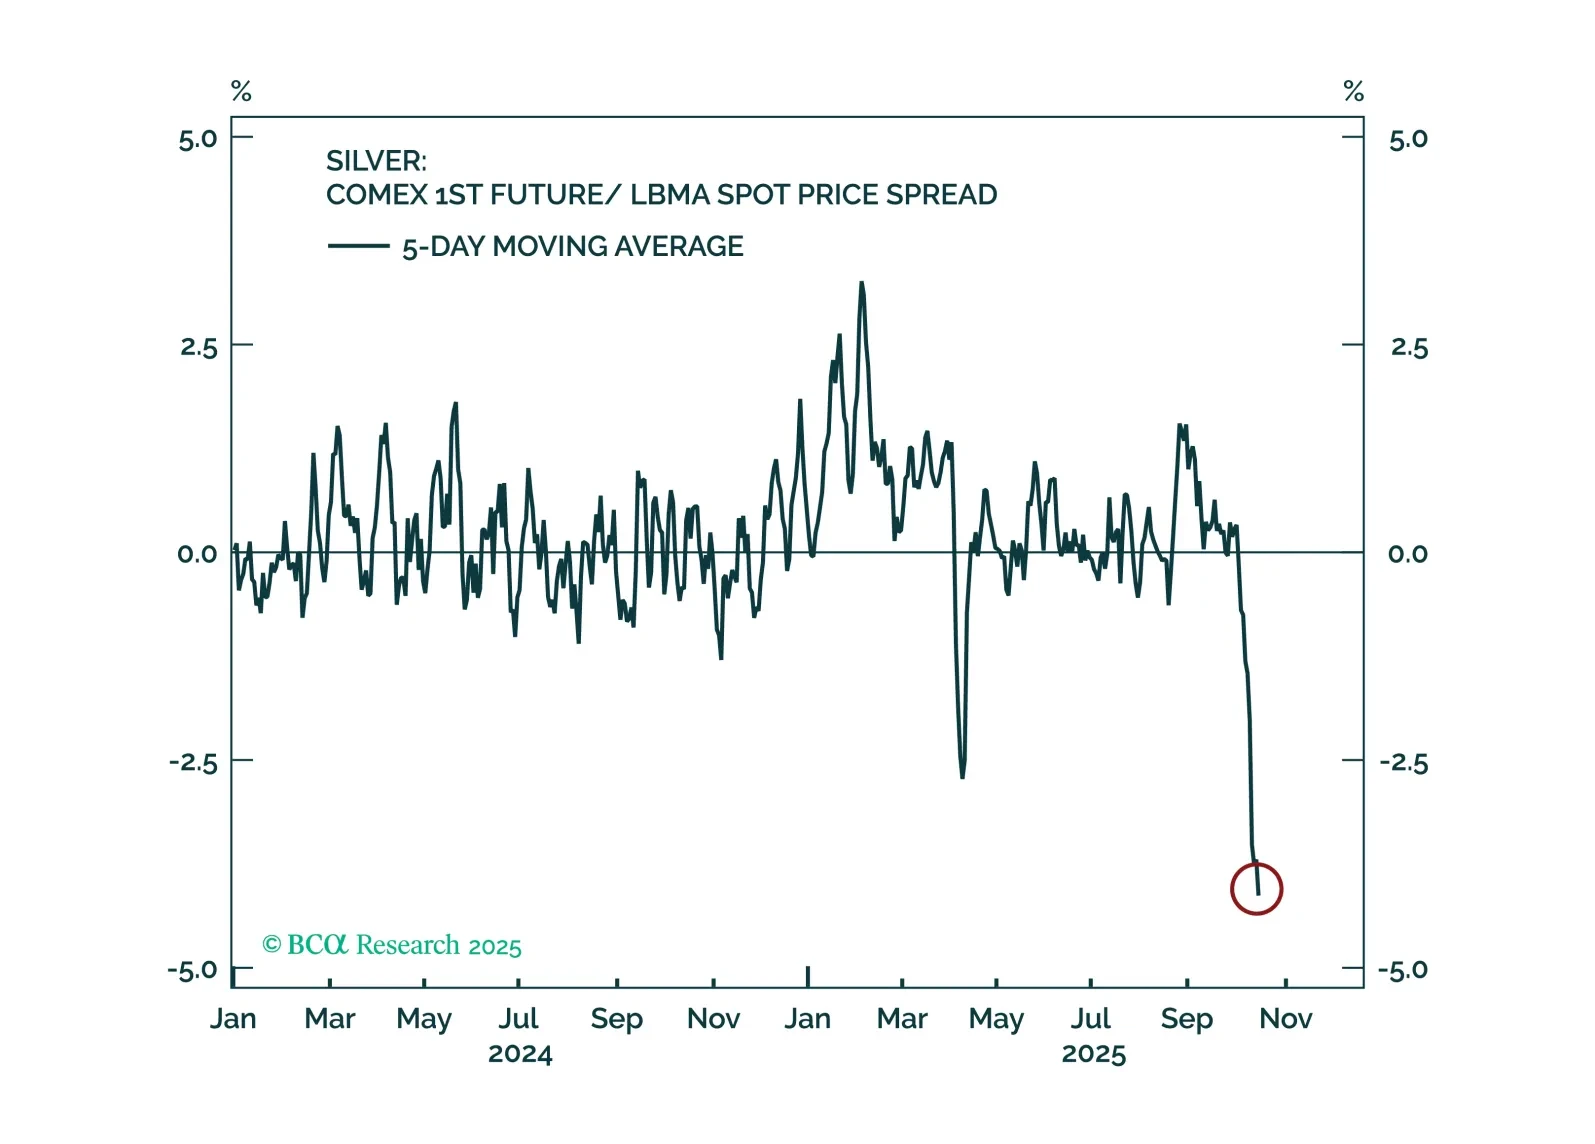
Silver’s short squeeze and stretched technicals warn of a potential tactical pullback.
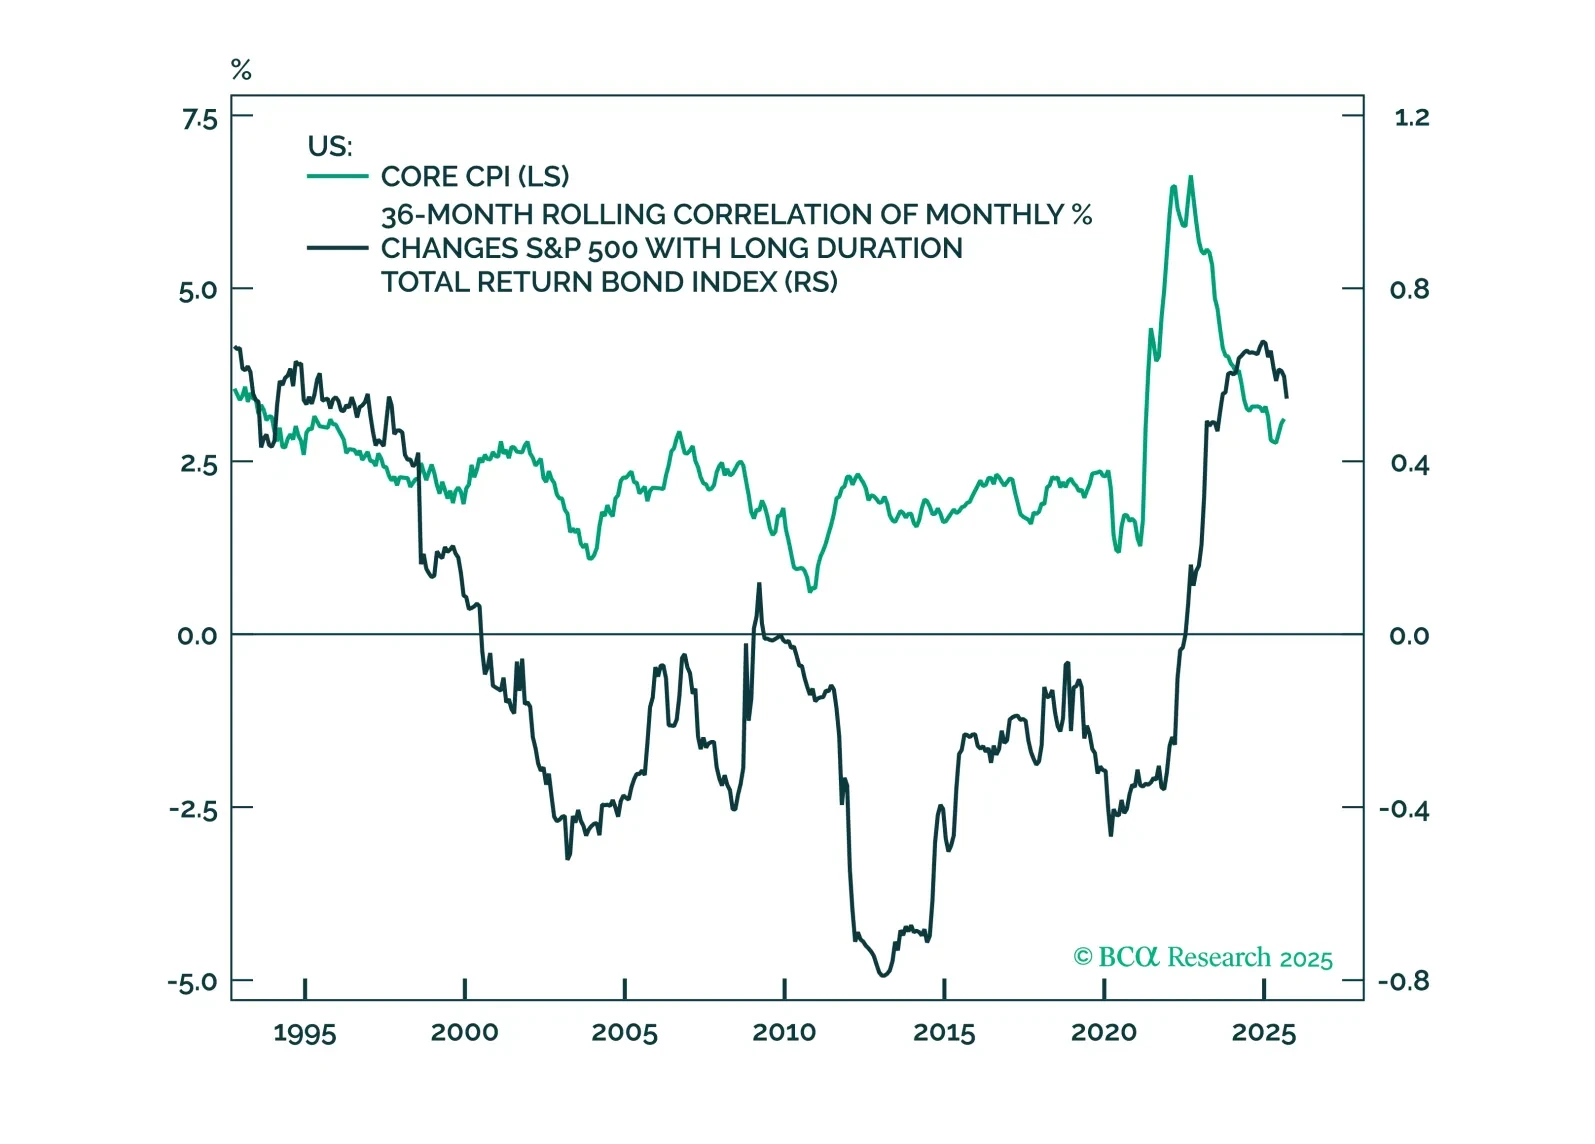
The denizens of GeoMacro strategy have remained bullish into October, despite our gut telling us that the equity rally has overextended itself on a technical basis. On cue, markets ripped our face off with a single missive from the Twitterer-in-Chief. While we scoff at the idea that the President will raise tariffs on China by 100%, the speed of the unwind of the "everything trade" that Friday suggests that market dynamics are not great.
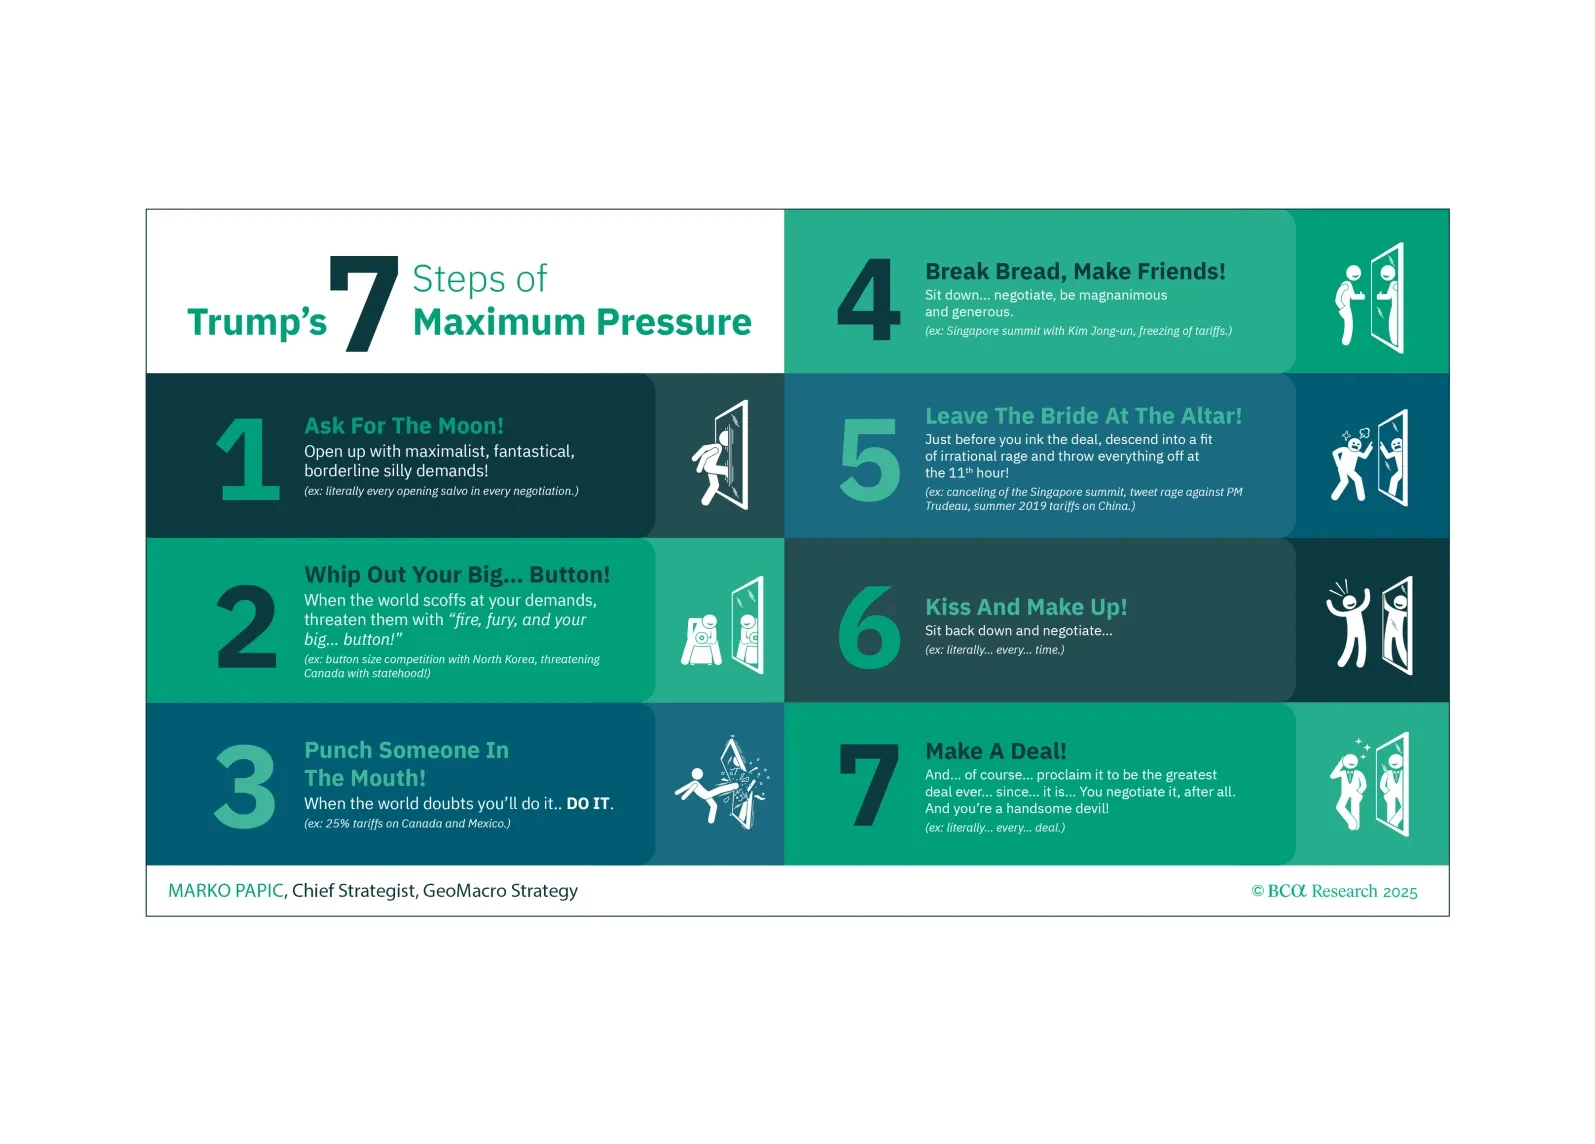
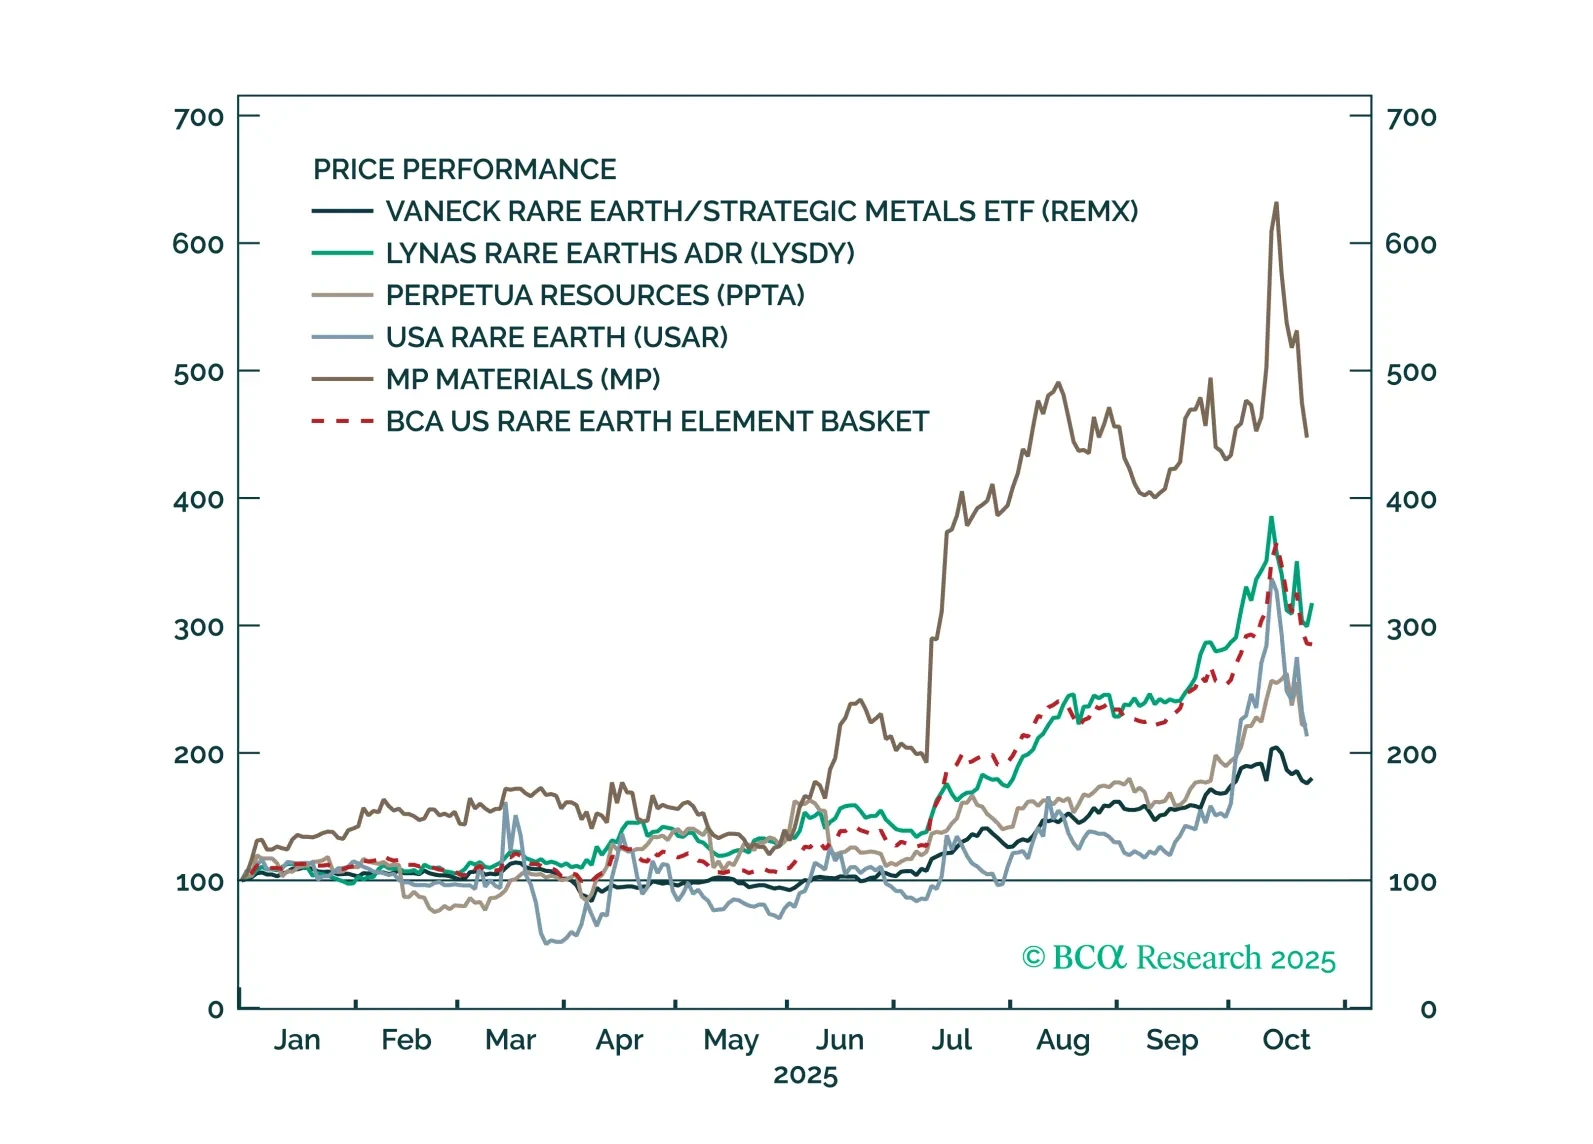
President Trump has threatened to cancel his planned meeting with President Xi Jinping on October 31 in South Korea at the Asia-Pacific Economic Cooperation summit. Responding to the October 9 announcement by Beijing that it was imposing new restrictions on refined rare earth minerals – and technology used to refine them – President Trump suggested that a massive increase in tariffs on China may be coming. Markets have reacted sharply to President Trump’s rhetoric, with a significant selloff in stocks.
A world of political churn favors safe havens — buy yen, stay overweight US stocks, and avoid chasing the fragile rally in China.
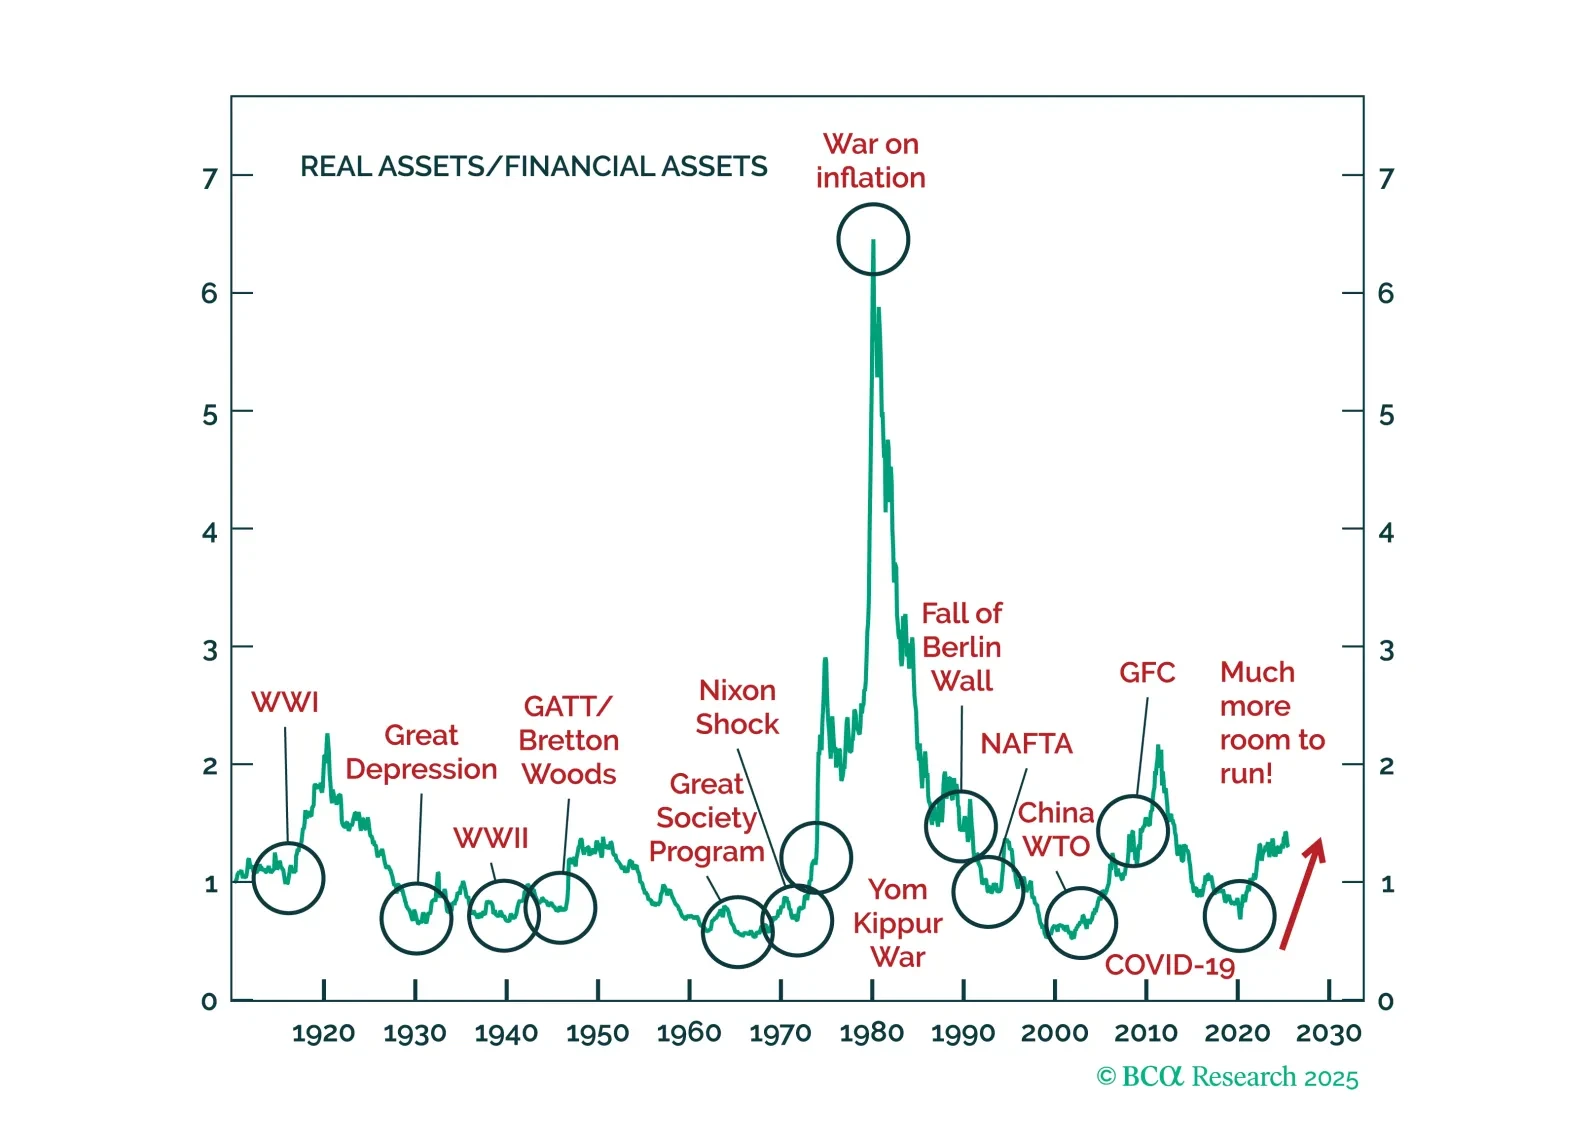
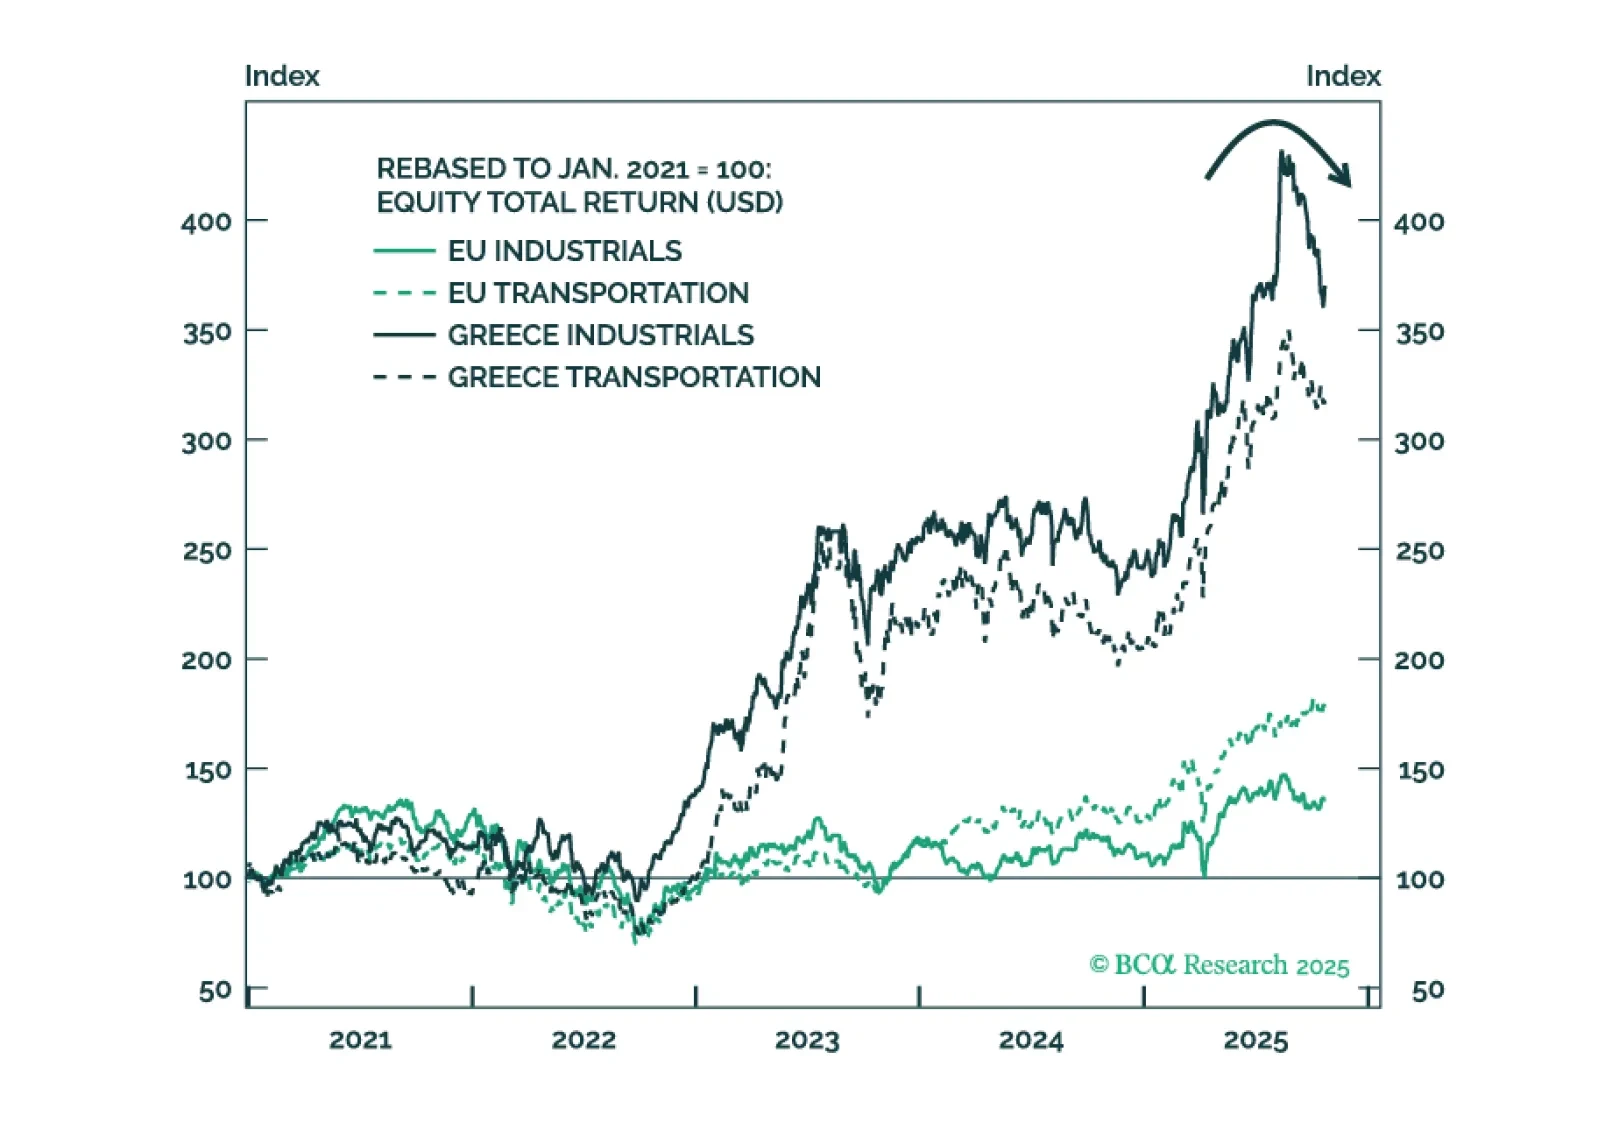
We remain bullish both bonds and equities, but conviction is falling. We are Luddites when it comes to the AI theme, but we have followed it regardless. A bubble is a bubble, not to be shorted. Yet Europe’s weak AI returns reveal 2025’s real story: the fall of King Dollar.
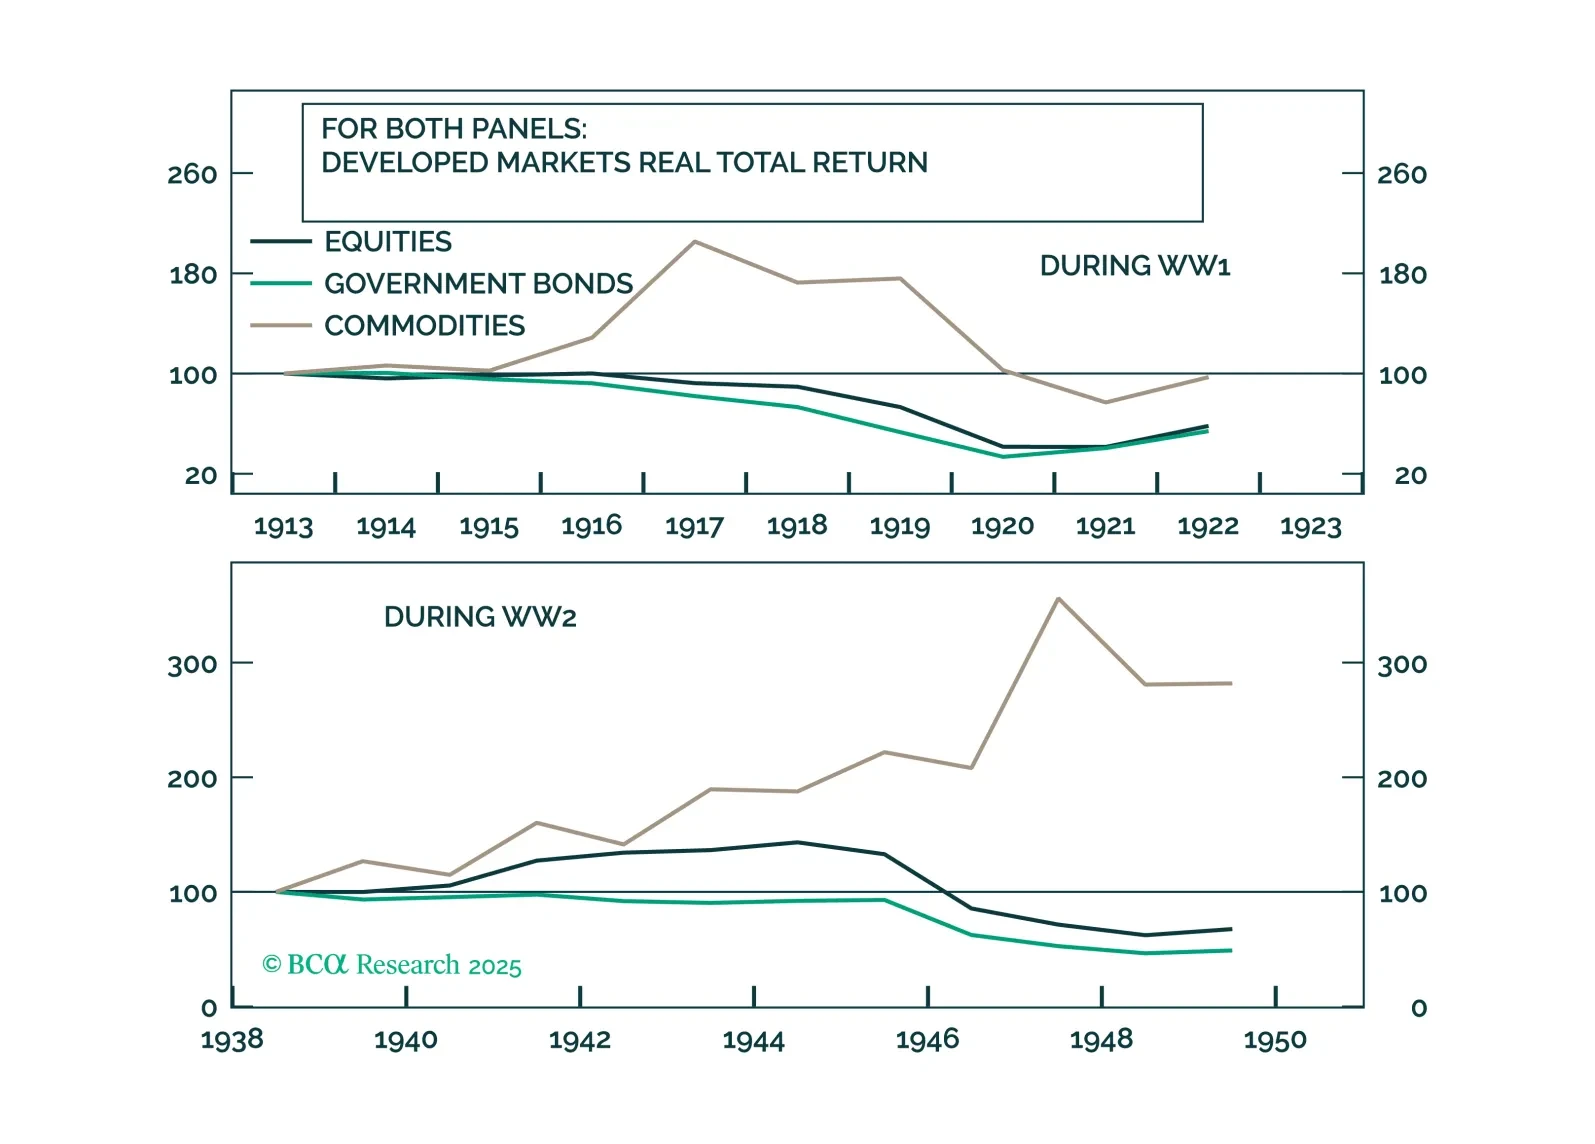
World War III will not happen. But if you disagree, here is our portfolio to hedge it: commodities, neutrals, and crypto.
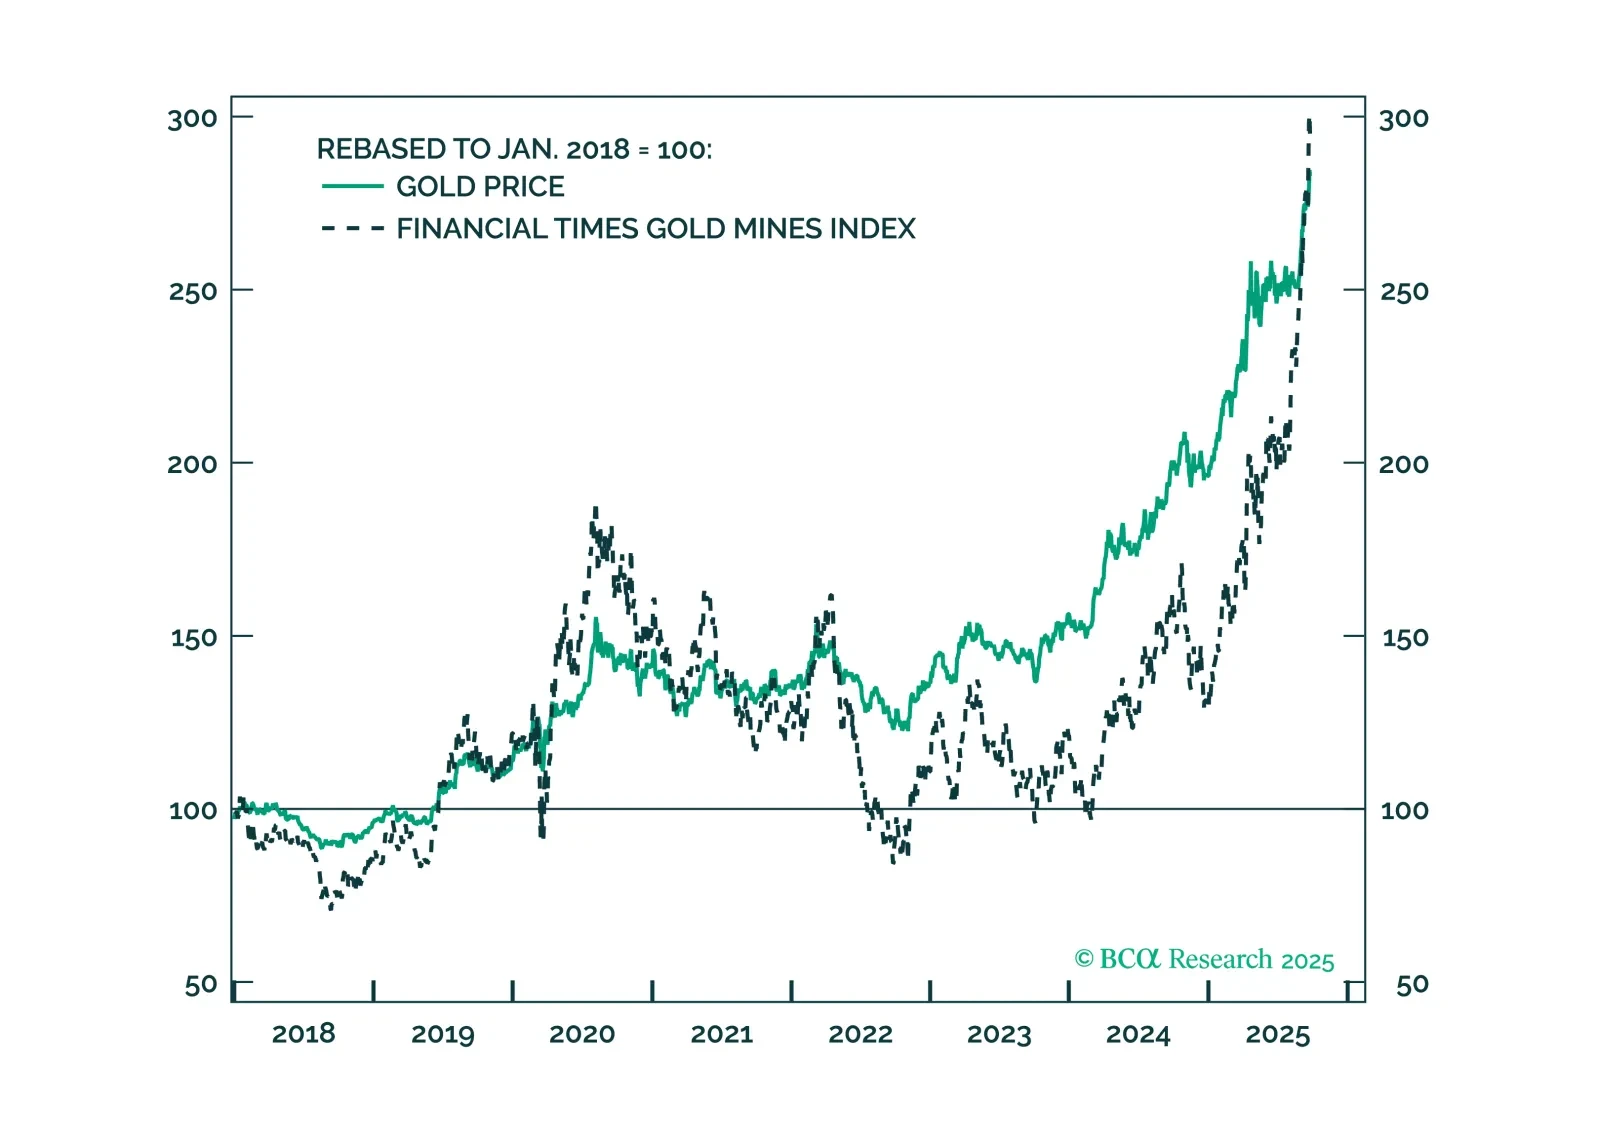
Rising Russia-NATO risks, tactical oil/gold trades, tougher sanctions on Russia (maybe China), China stimulus with ~5% growth target, and US checks on Trump’s ambitions will define Q4.