GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
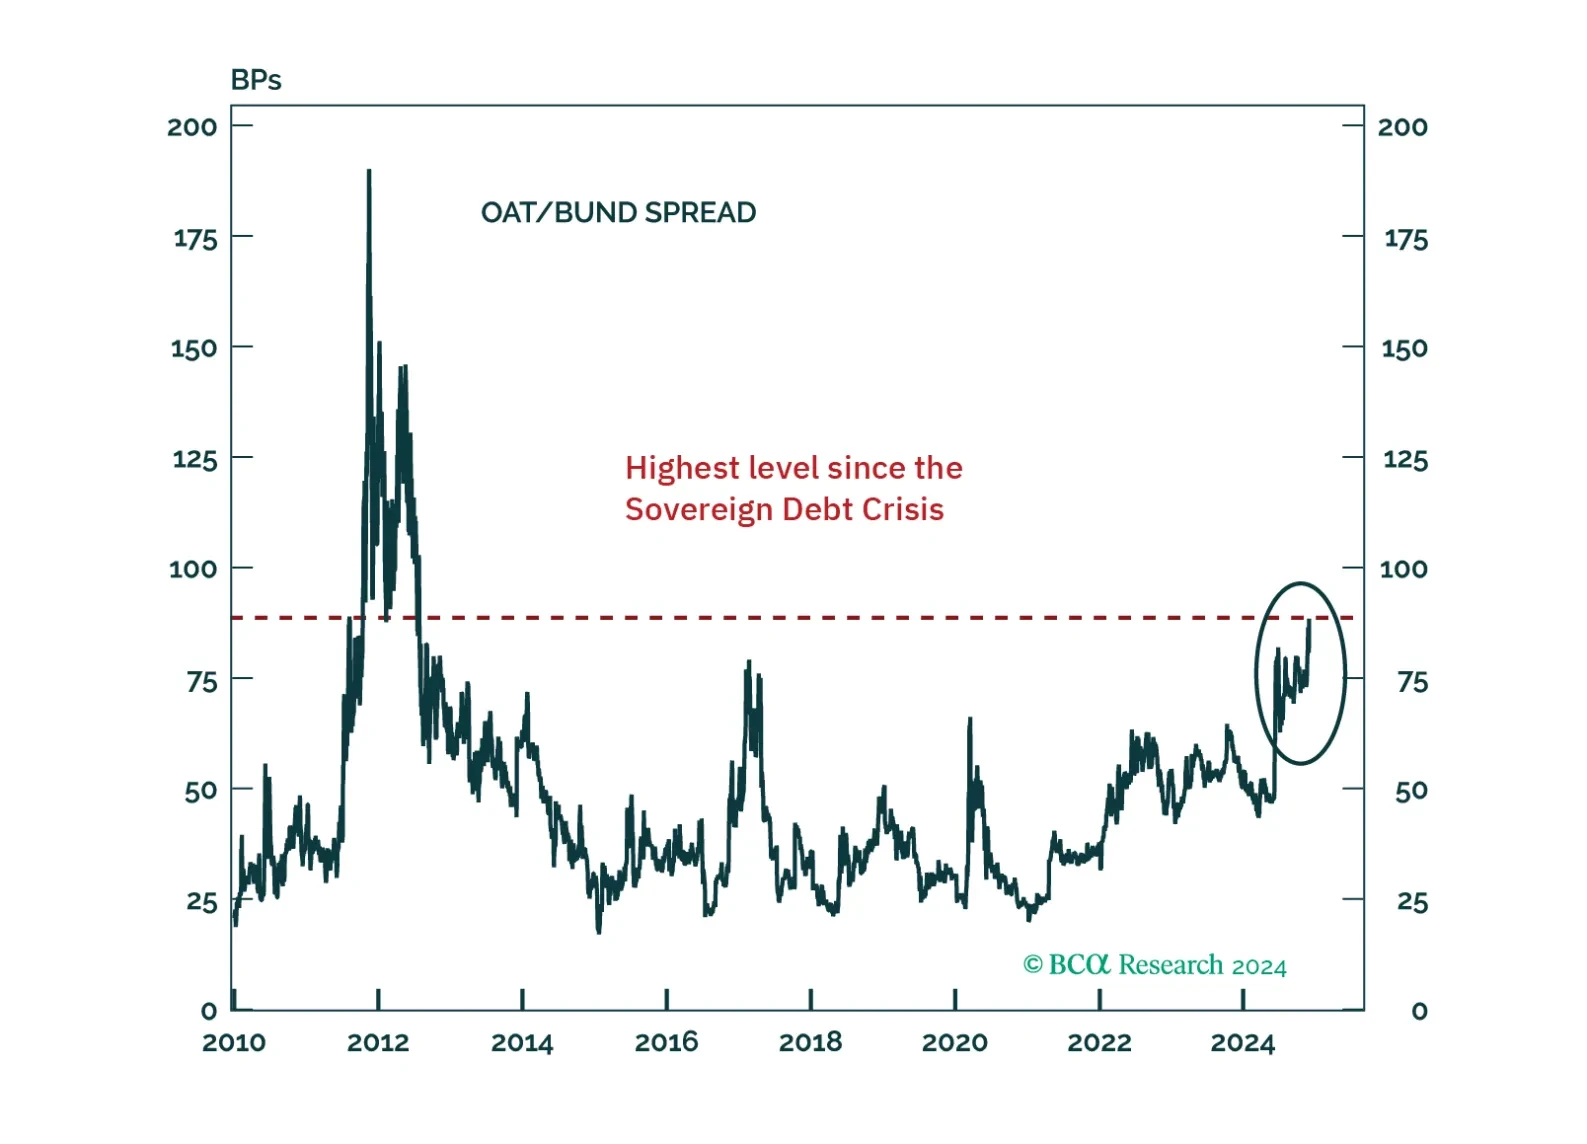
France finds itself in a unique, thorny situation. Can it heave itself out of it? And what does it mean for investors?
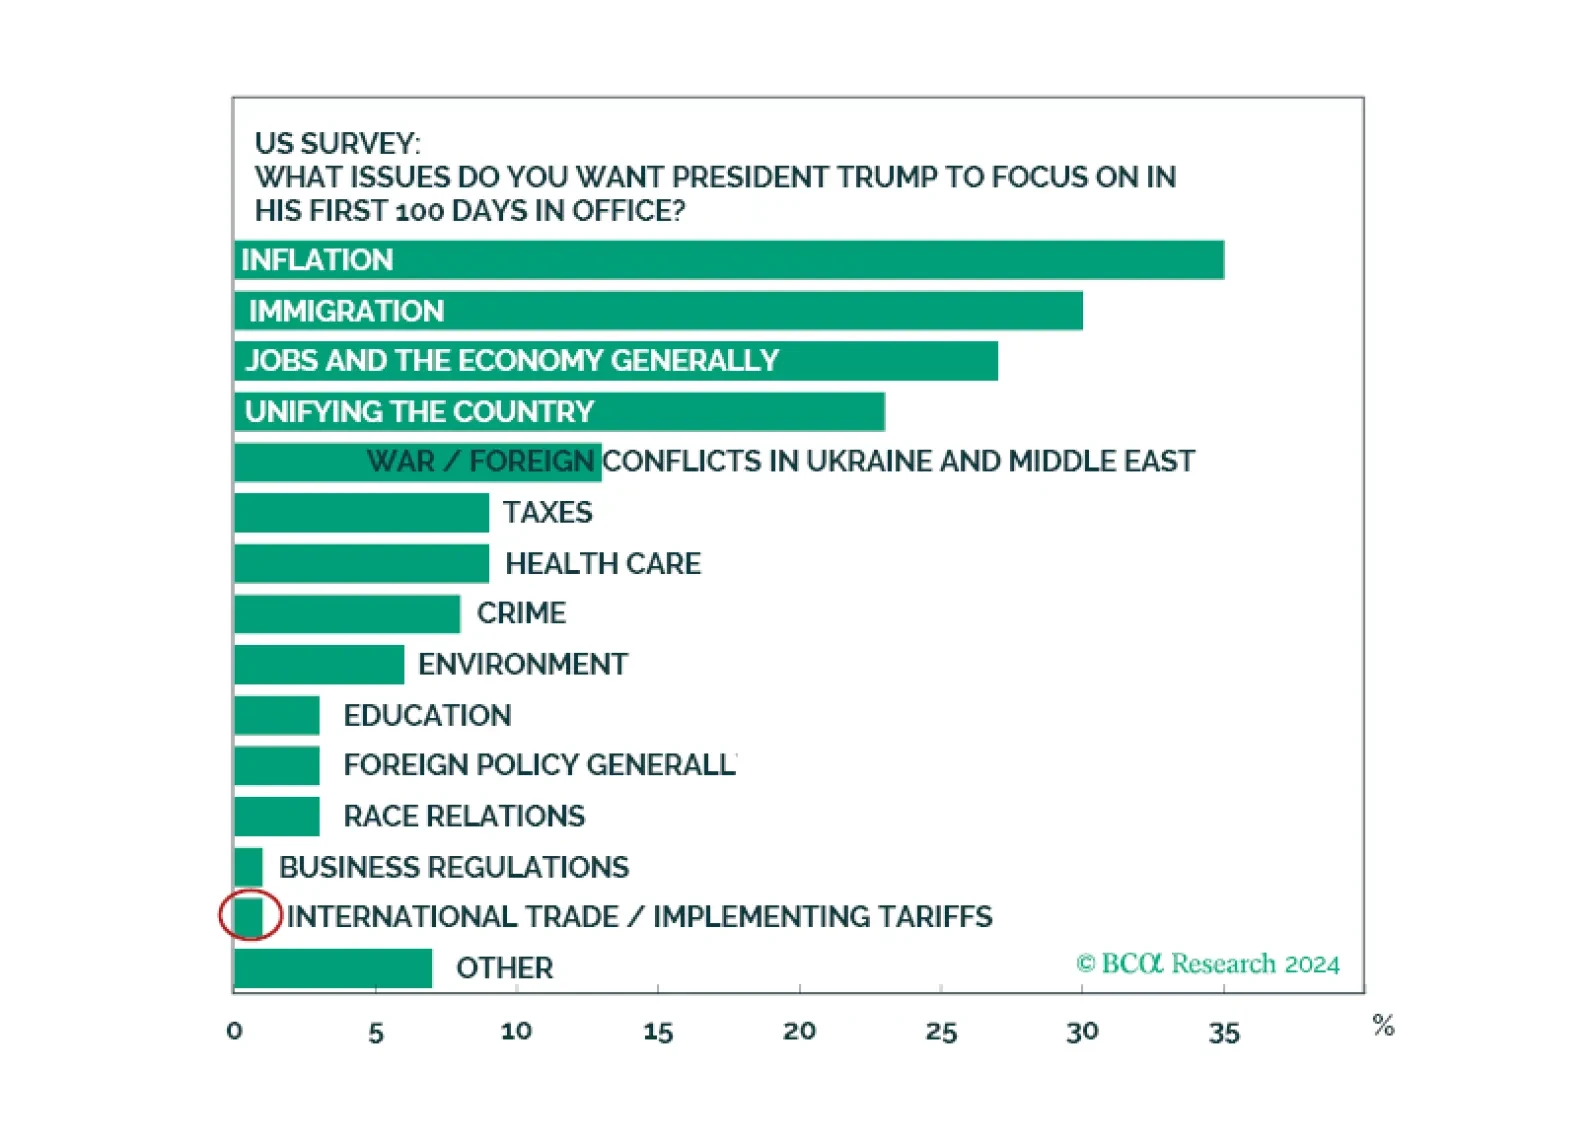
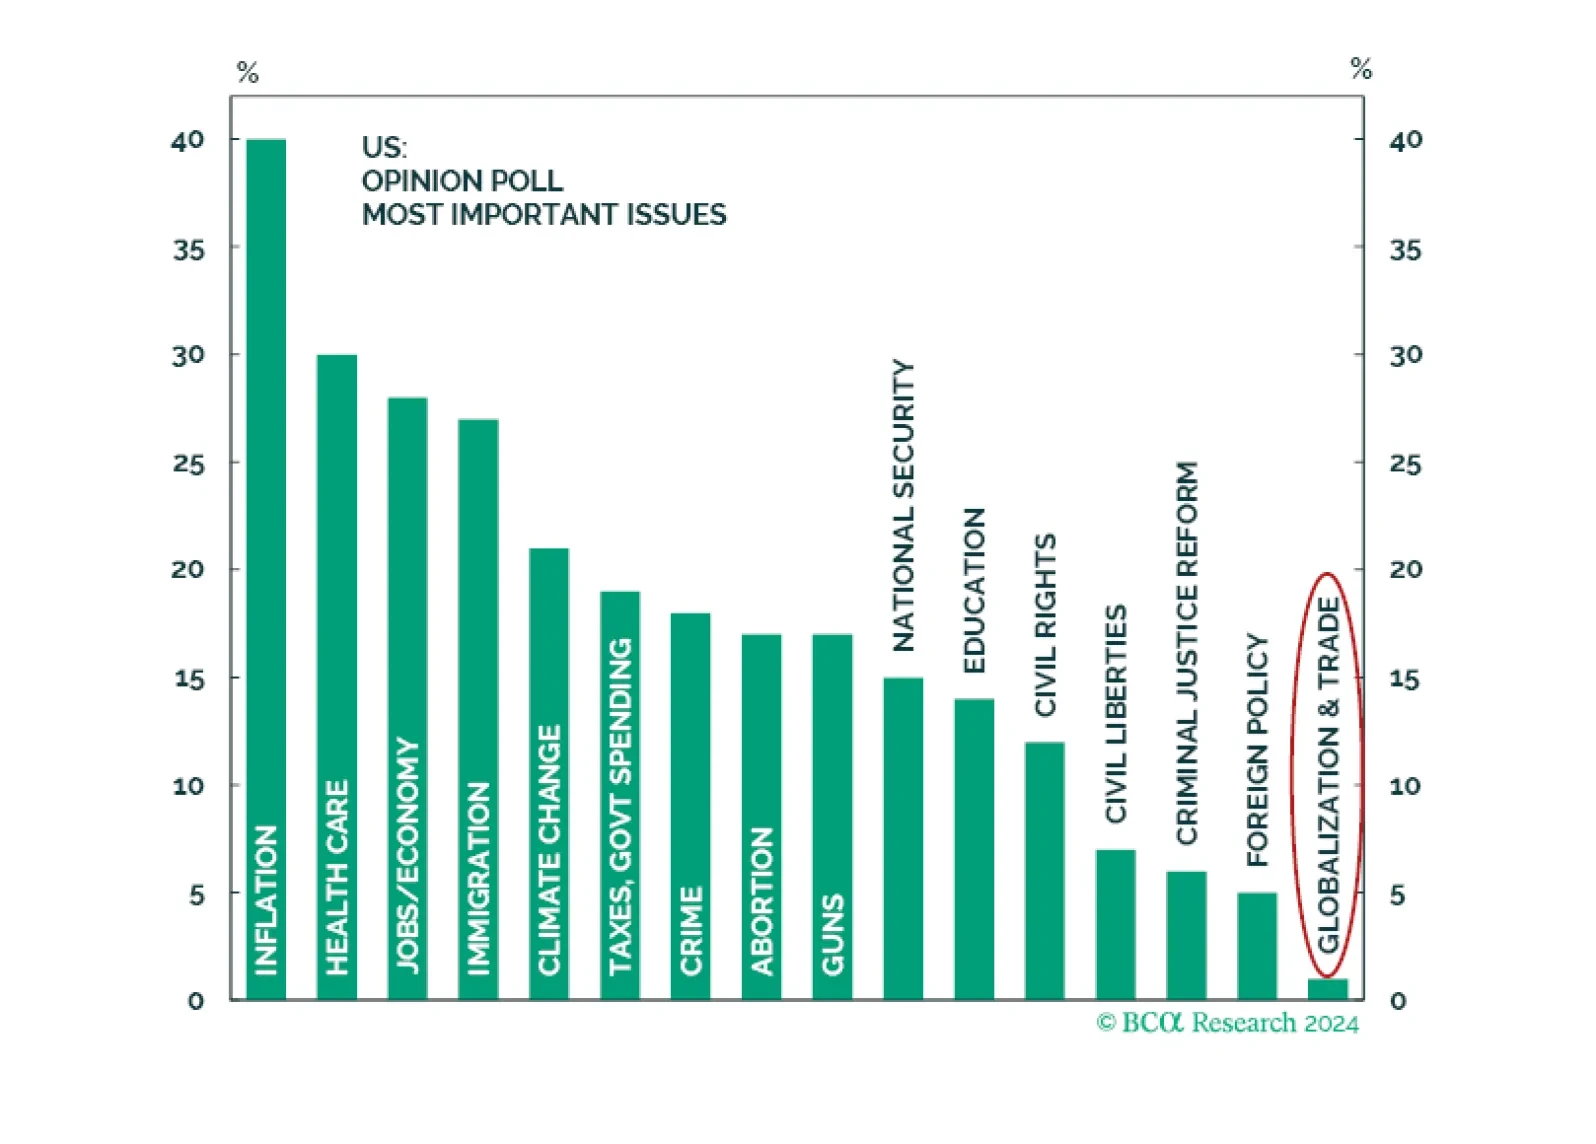
In our Alpha report, we deliver our Annual Forecast. The current macro narrative is that the US will continue to outperform the rest of the world, in large part because President Trump will again deliver fiscally led growth and global tariff carnage. In our view, 2025 will be the year of “Peaks.” Peak fiscal profligacy, peak de-globalization hysteria, and peak geopolitical risks. All three will reverse US Exceptionalism. But getting ahead of that trade is folly. For the time being, we concede that it is “America First” on all fronts. Particularly with the Greenback being a momentum currency.
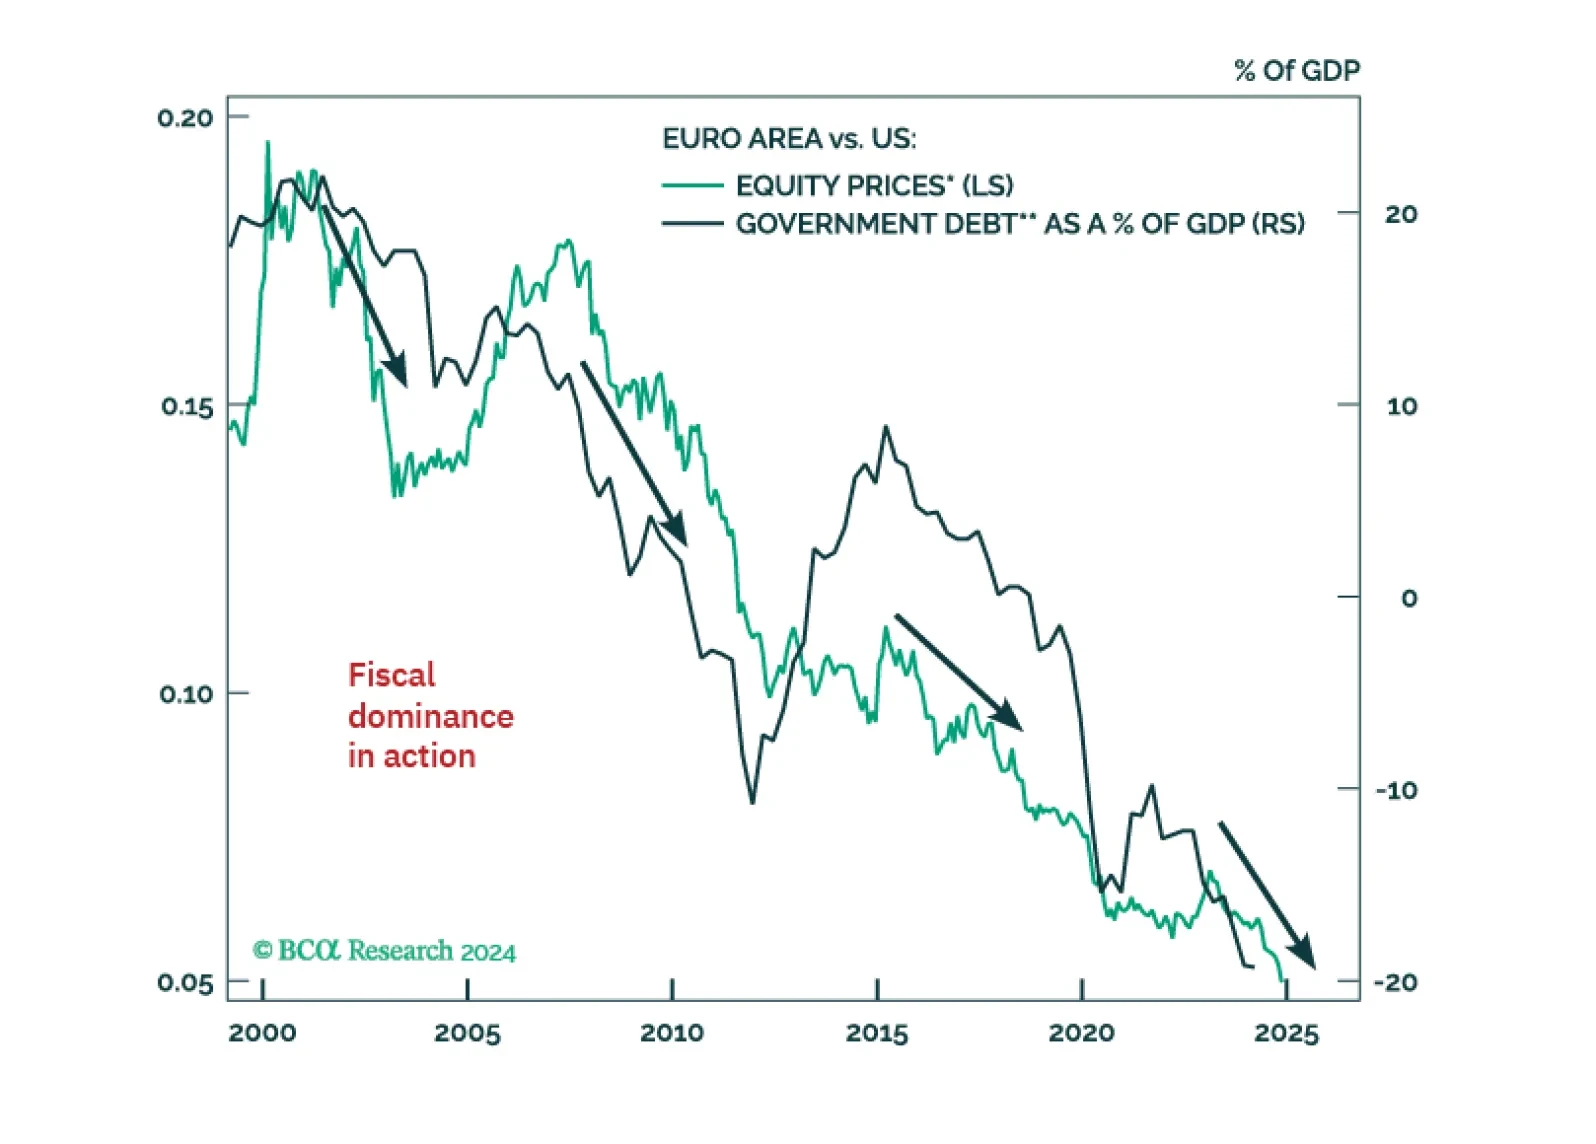
Investors have given up on European assets, which now suffer exceptional discounts to US ones. However, tighter US fiscal policy, the end of Europe’s austerity and deleveraging, the LNG Tsunami about to hit European shores, and the global capex fueled by the Impossible Geopolitical Trinity mean that Europe’s time to shine will soon come back.
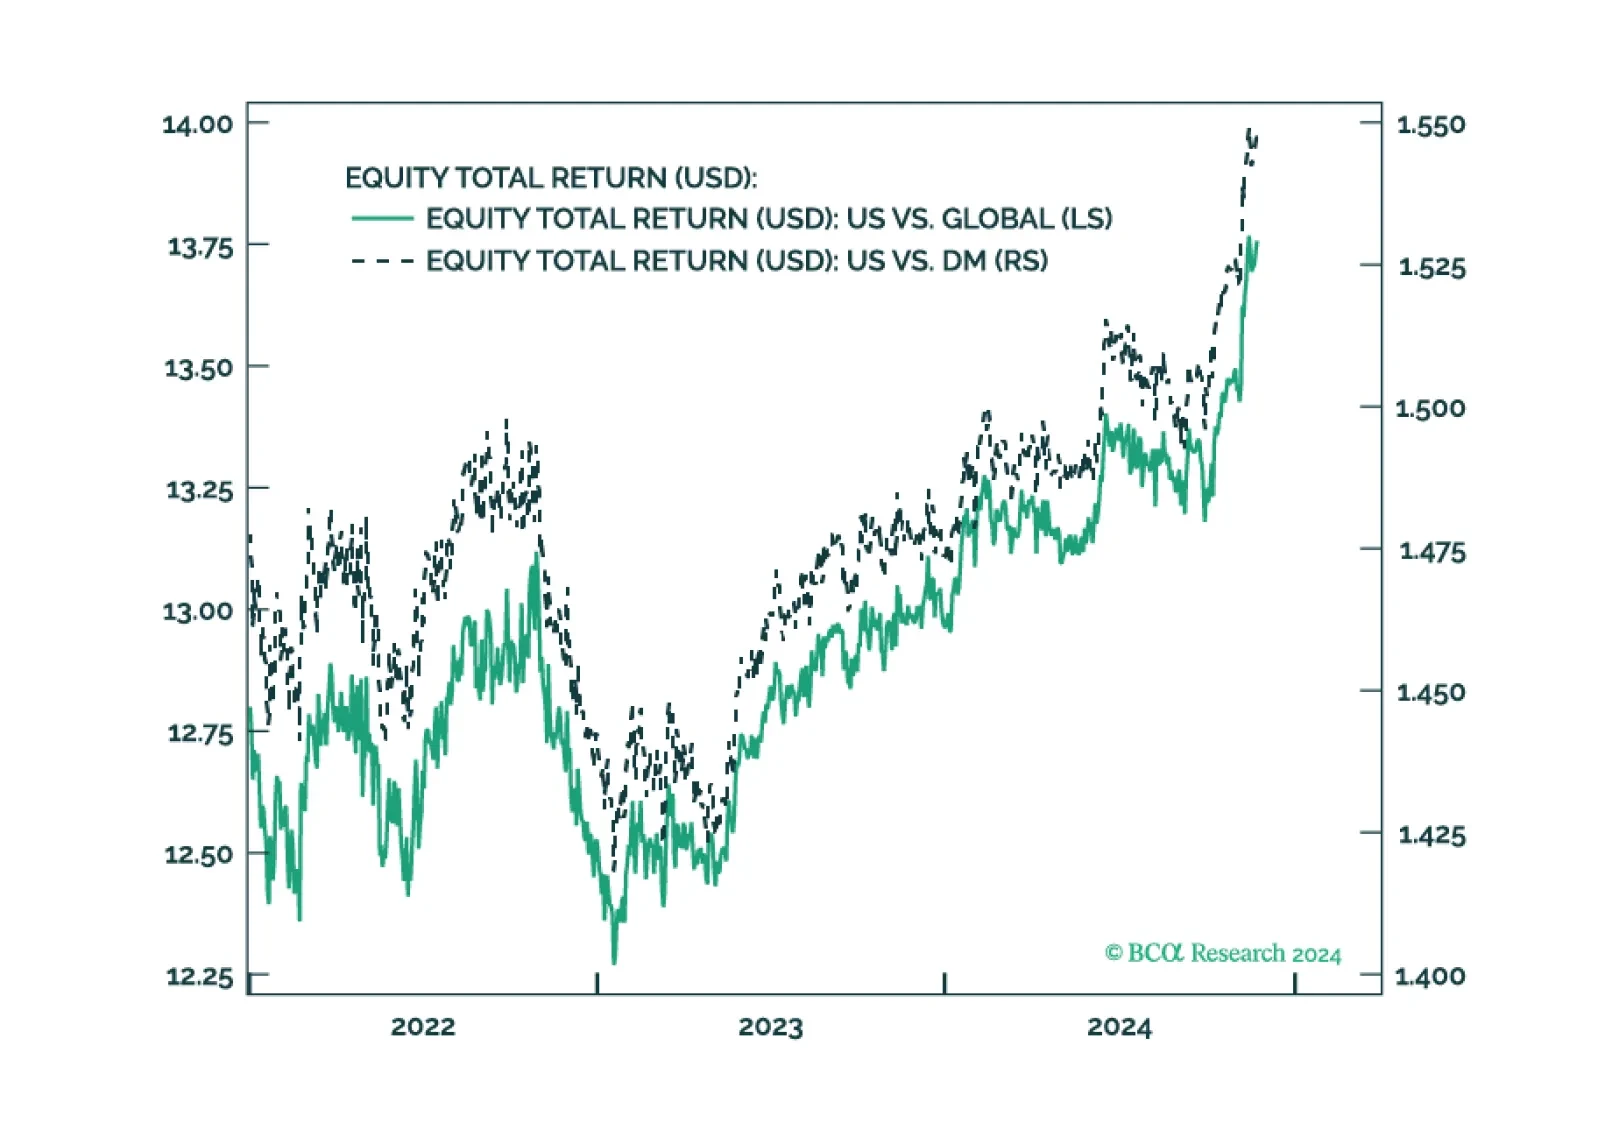
We were far too bearish on the US economy in 2024 – but the global economy remained sluggish and we got the critical geopolitical calls right. We predicted the Republican sweep in the US and the outbreak of direct military hostilities between Israel and Iran. We anticipated the escalation in Ukraine and Russia-NATO tensions that is taking place as we go to press. We stayed overweight US assets relative to global. We did not get blindsided by any of the elections in this “year of elections” – we traded several of them successfully. However, we disfavored cyclical sectors. We fought momentum stocks and lost. Many other trades turned sour. Equity volatility picked up substantially in 2024 as expected, but our attempts to take advantage of this shift fell flat.
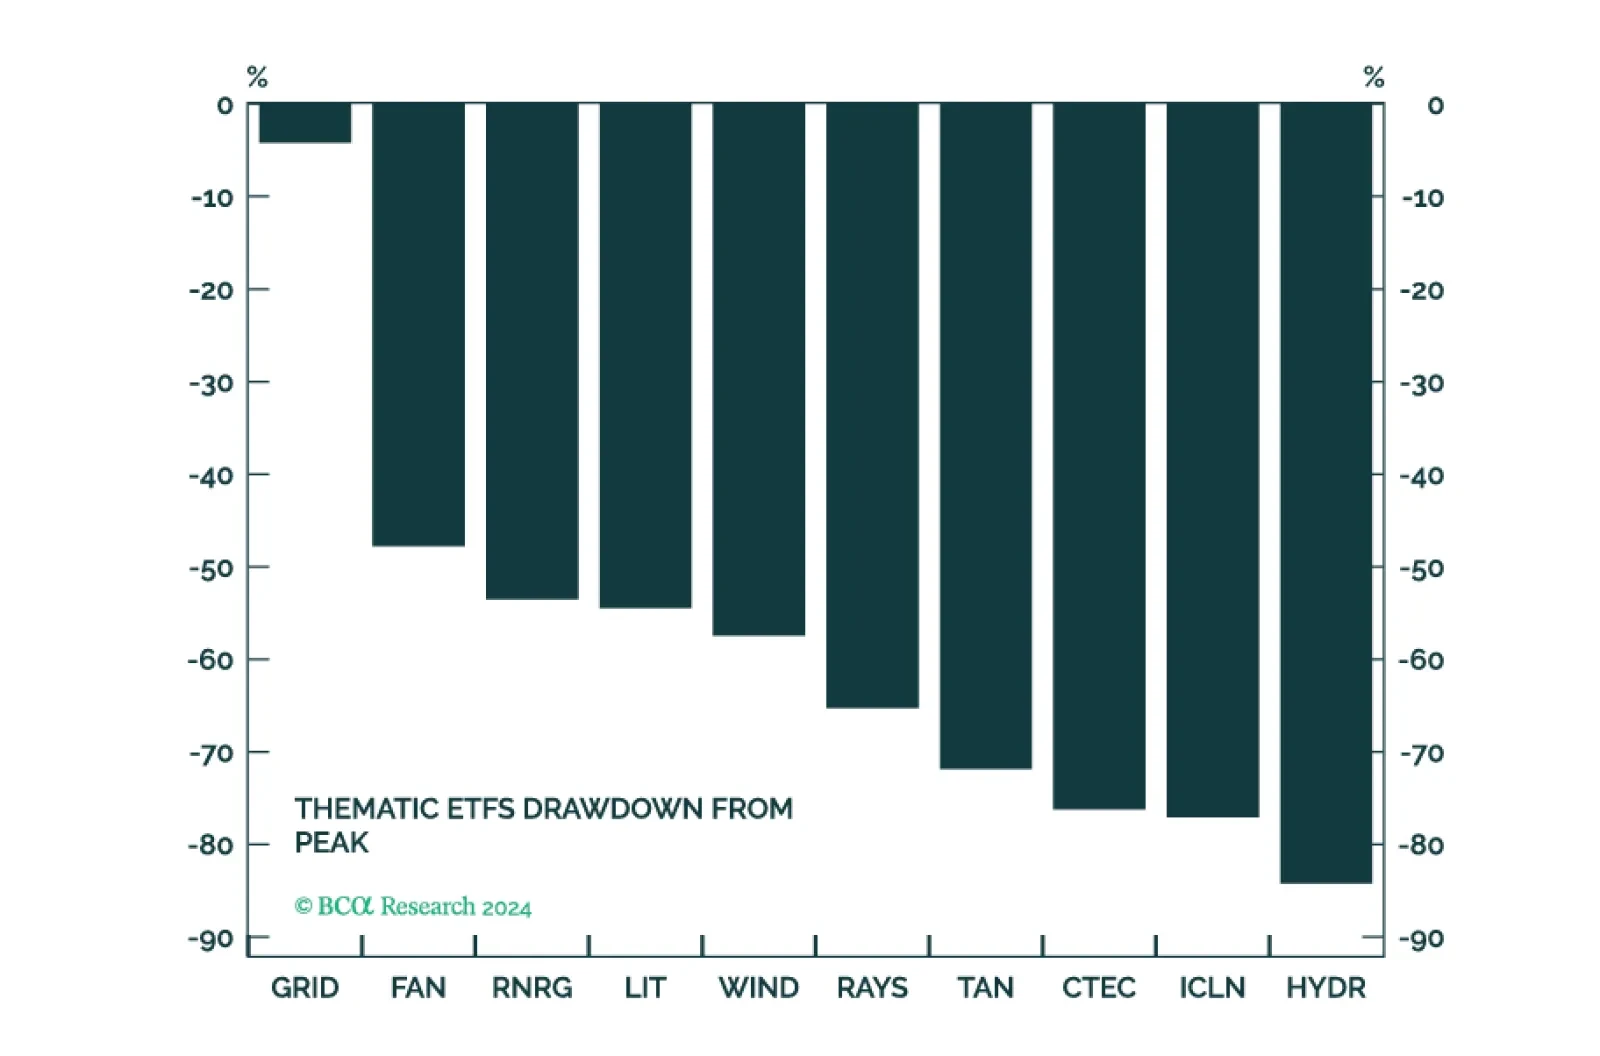
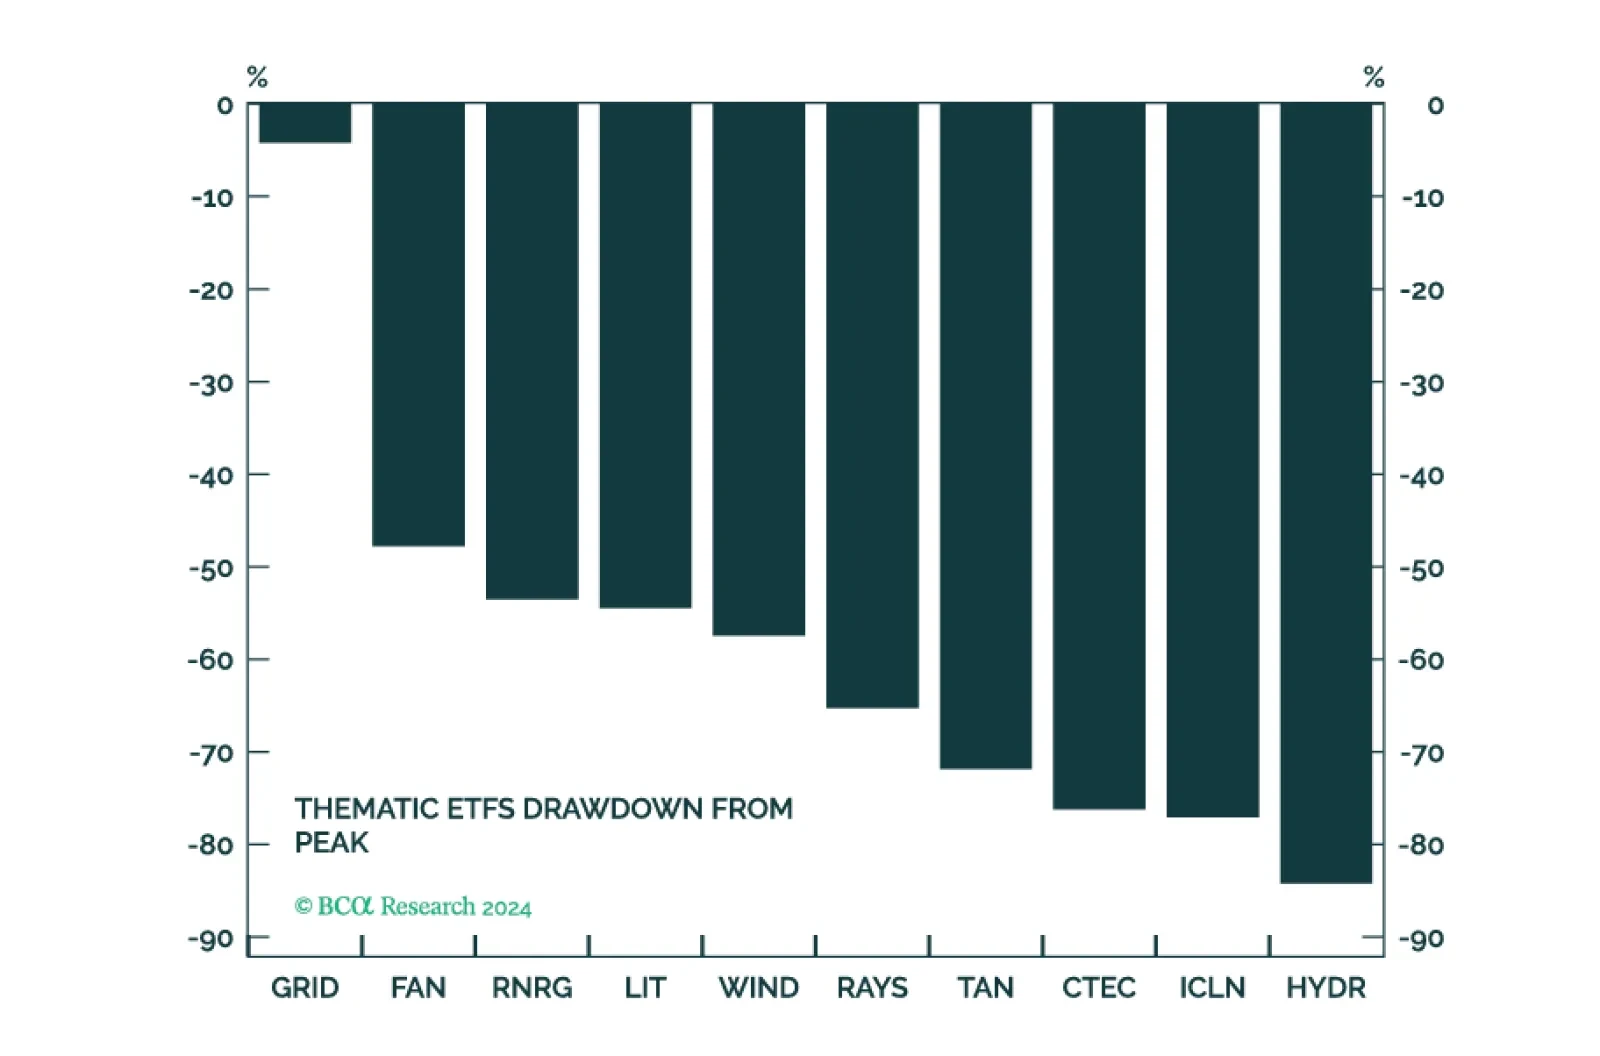
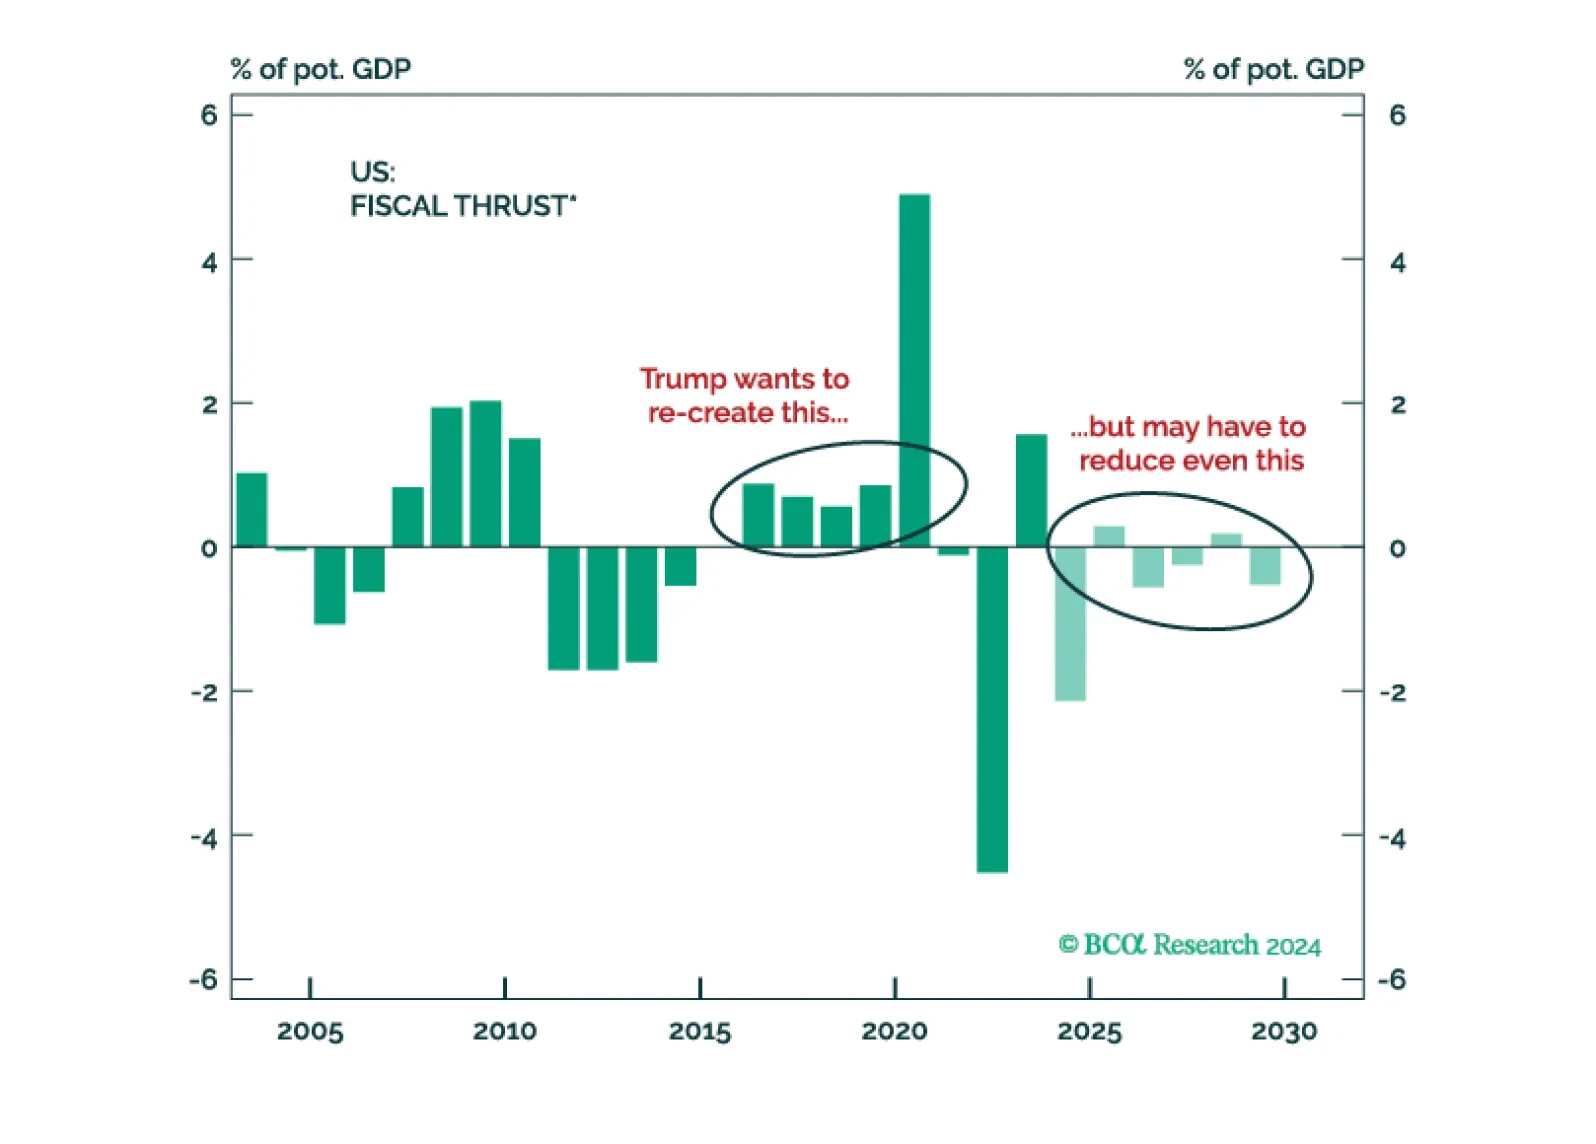
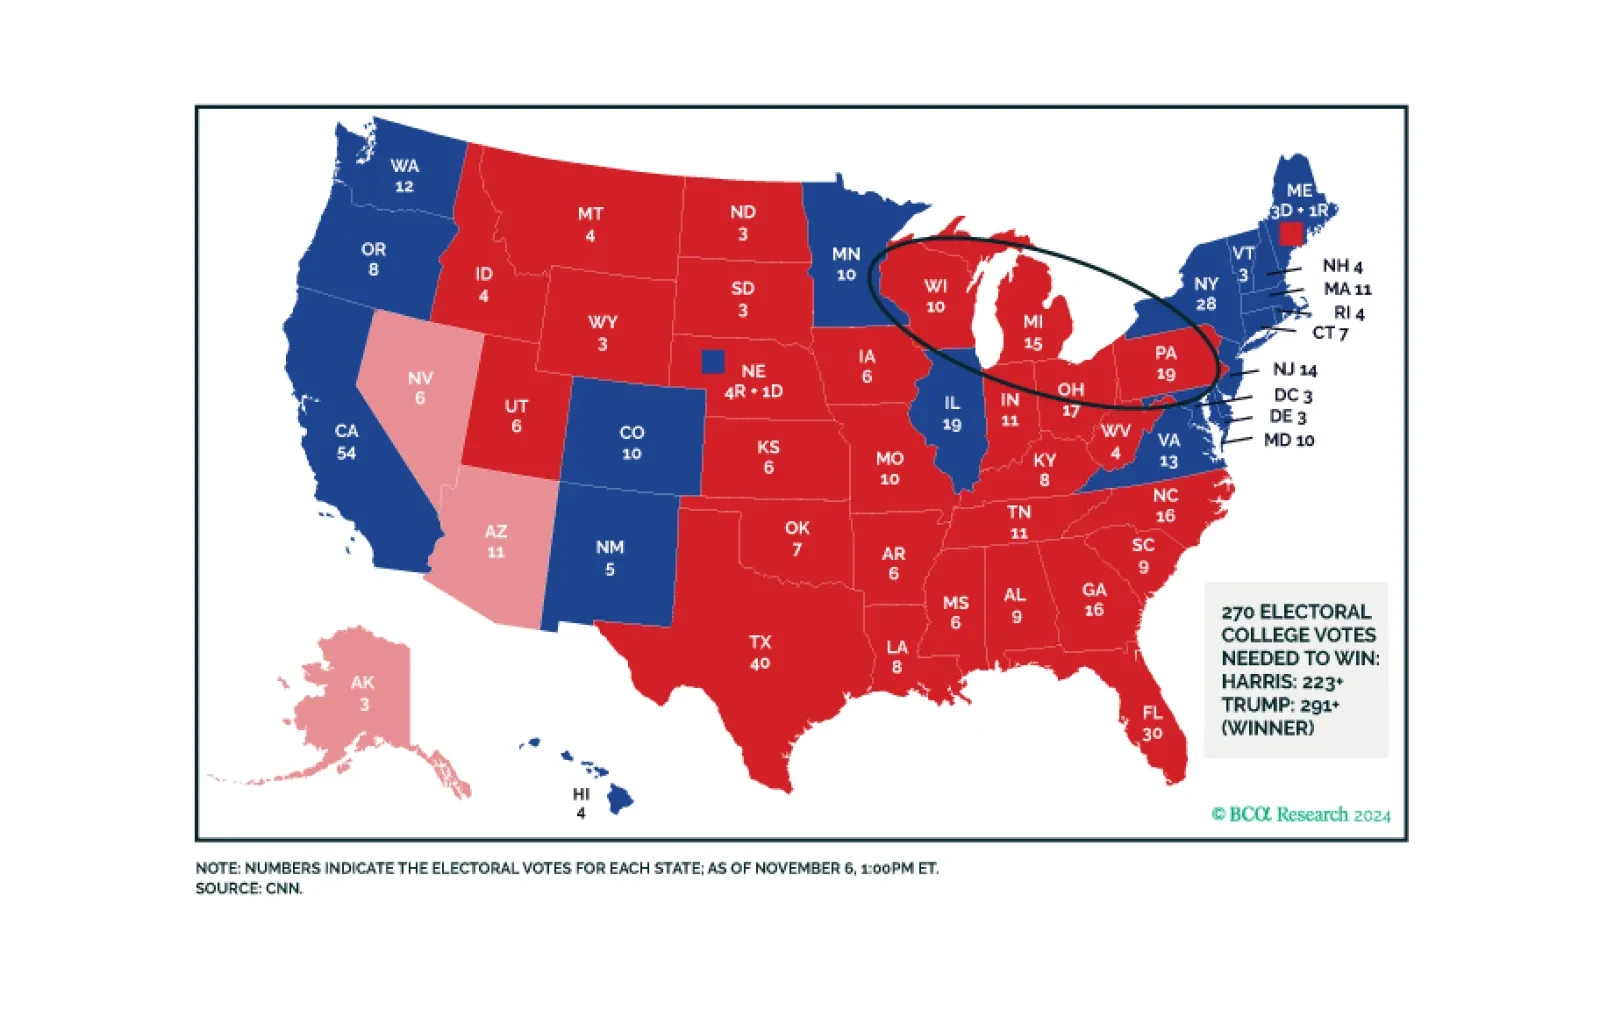
The month of November has brought us S&P 6,000! President Trump has won a “Red Sweep” (as we expected all year) and has ushered in a regime change in America. For now, we are open to chasing momentum. However, the biggest risk to the market are bond yields, which should rise as investors start to price President Trump’s policies and their impact on deficits.