 GeoMacro | Cyclical Trends
Medium-term analysis of geopolitical dynamics and their impact on asset returns. Typically published twice a month.
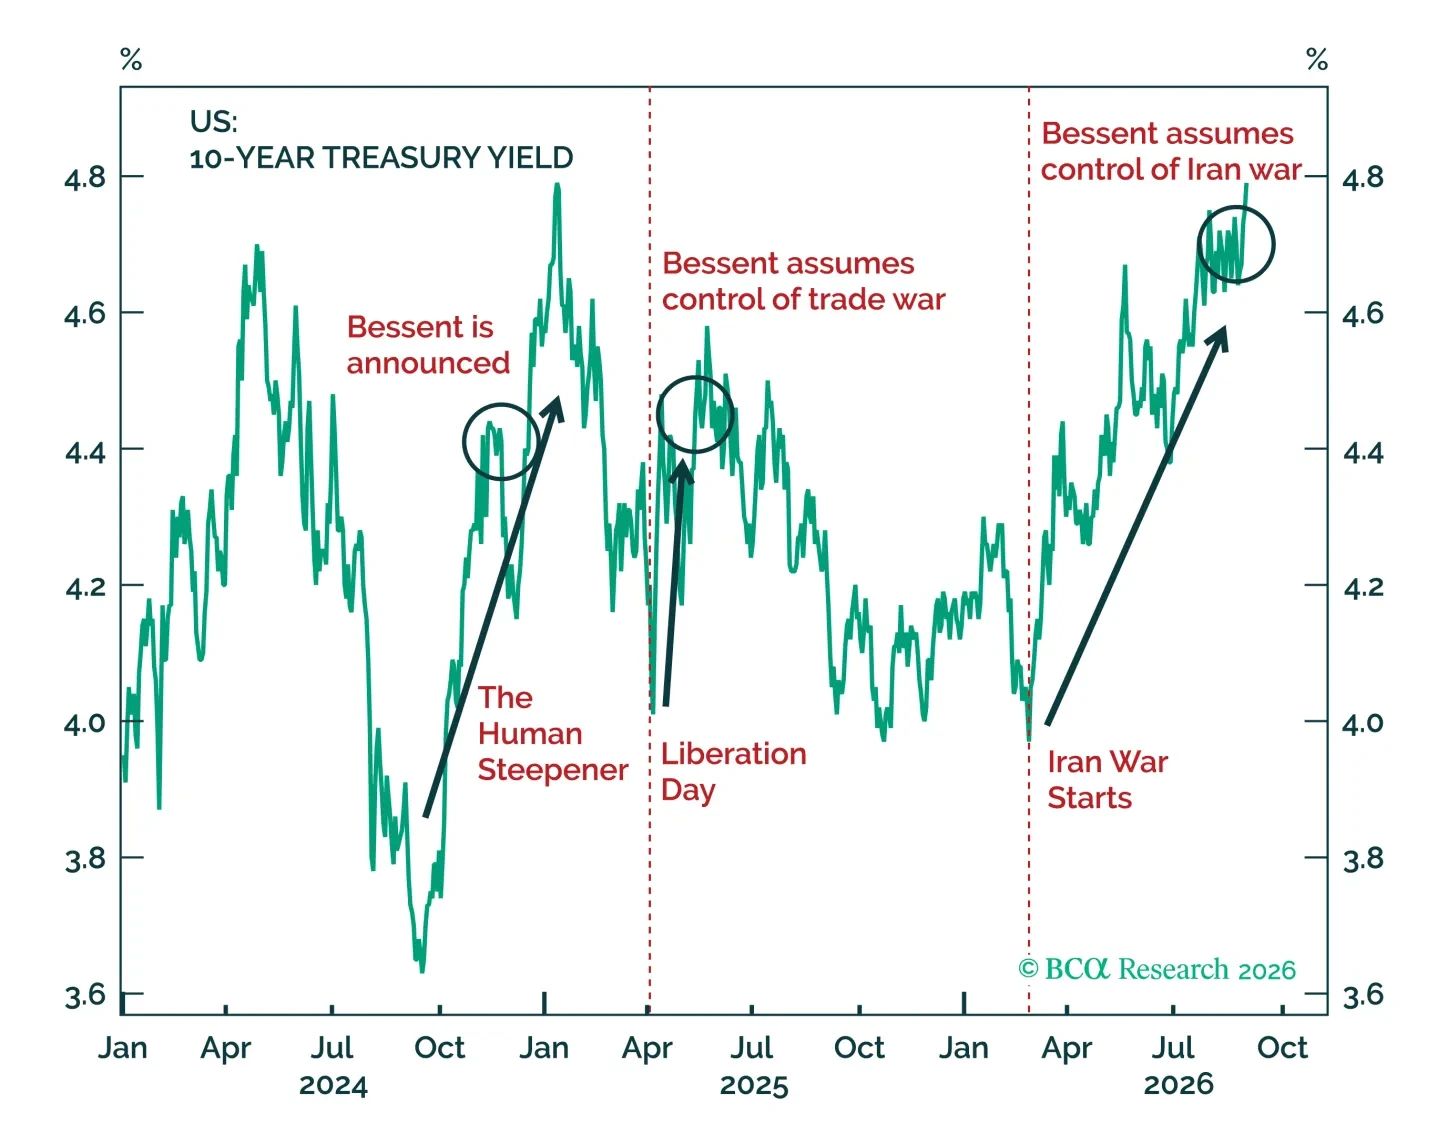
Markets have become obsessed with the rise of global long-dated yields. To some extent, we agree with the concern. Bonds are trading on "vibes," alarmed by the incoherent US geopolitical policy. Oil prices are obviously the conduit between that policy and the markets. On the other hand, growth is also robust. As such, bond market selloff is not all just negativity. The one secular theme driving the bond market selloff that does not bother us all that much is fiscal policy. We see signs — including actual budget deficit data! — that the US, policymakers and voters alike, is starting to understand that there are limits to profligacy. As such, we would advise clients with a long term focus to begin nibbling at the hated bonds.
Our colleague Matt Gertken has penned a sober analysis on the midterms, calling for a Democratic Party sweep in 2026. It is a measured, data-driven, analysis that we encourage you to read. This quick Insight is neither sober nor data driven. It is hyperbolic and based on “vibes.”
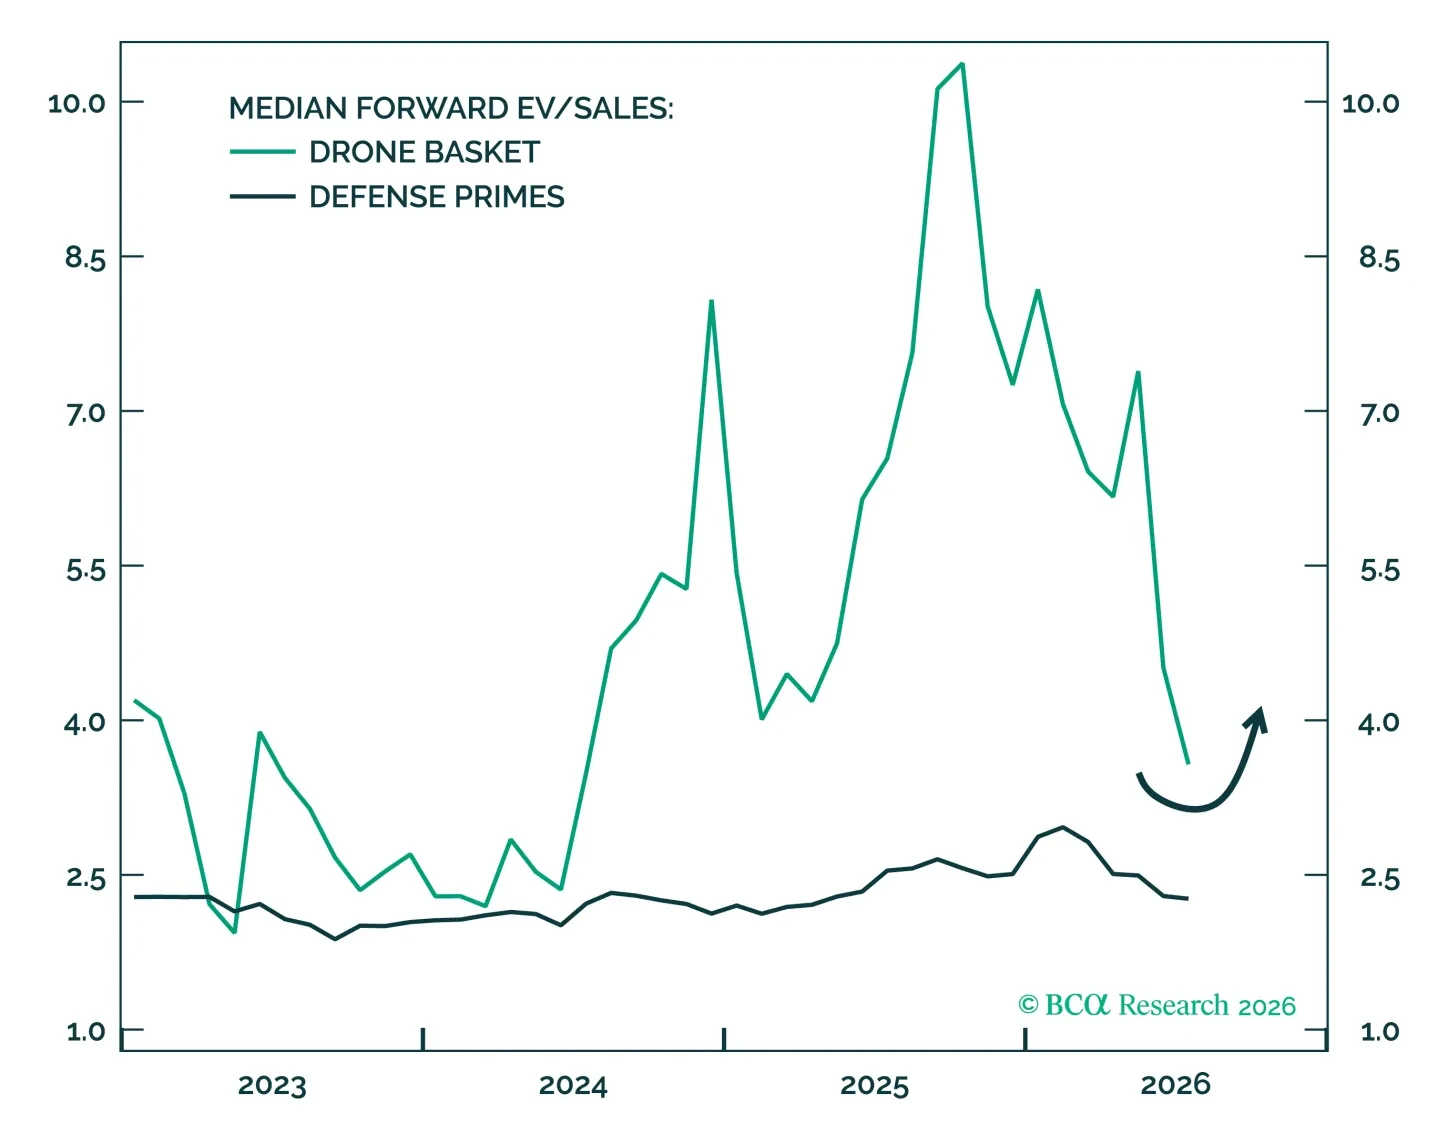
US aerospace and defense stocks still have a structural tailwind from geopolitics, but face rising cyclical challenges from macro and market fundamentals, as well as eventual Iran and Ukraine ceasefires and political change in the United States.
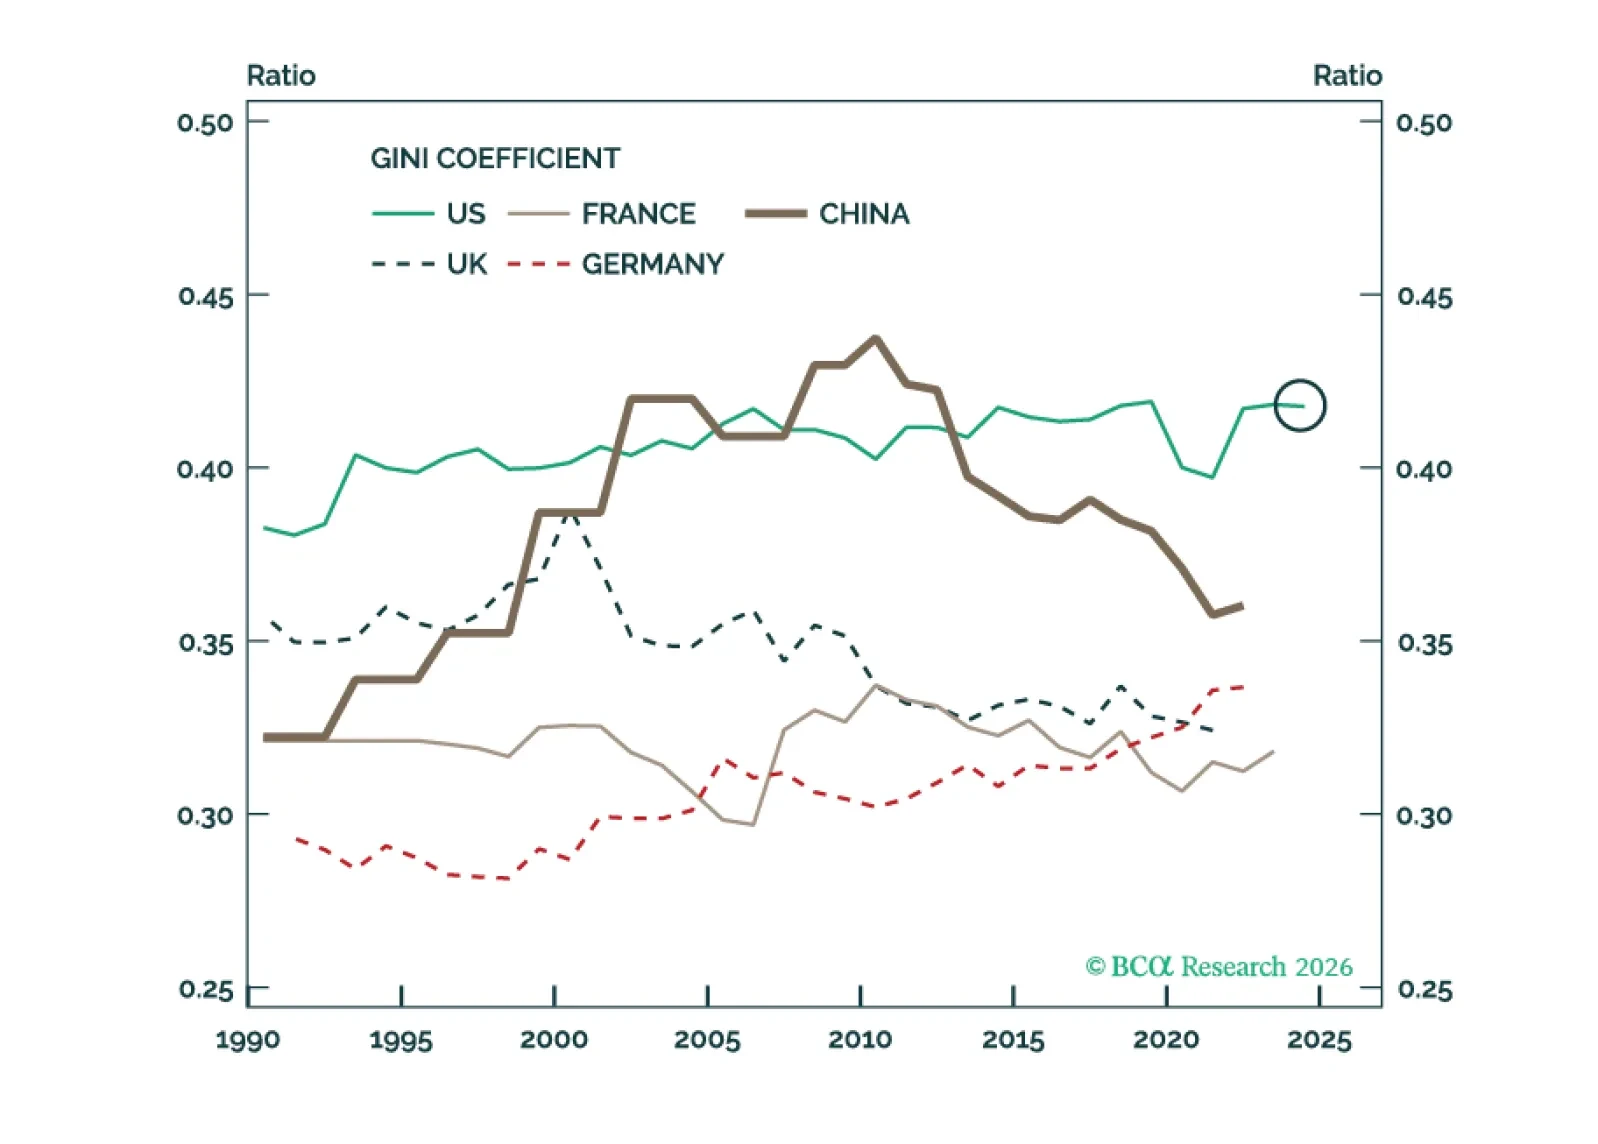
Left-wing populism will likely prevail within the Democratic Party and inspire large tax hikes in 2029. But the US does not face a socialist takeover.
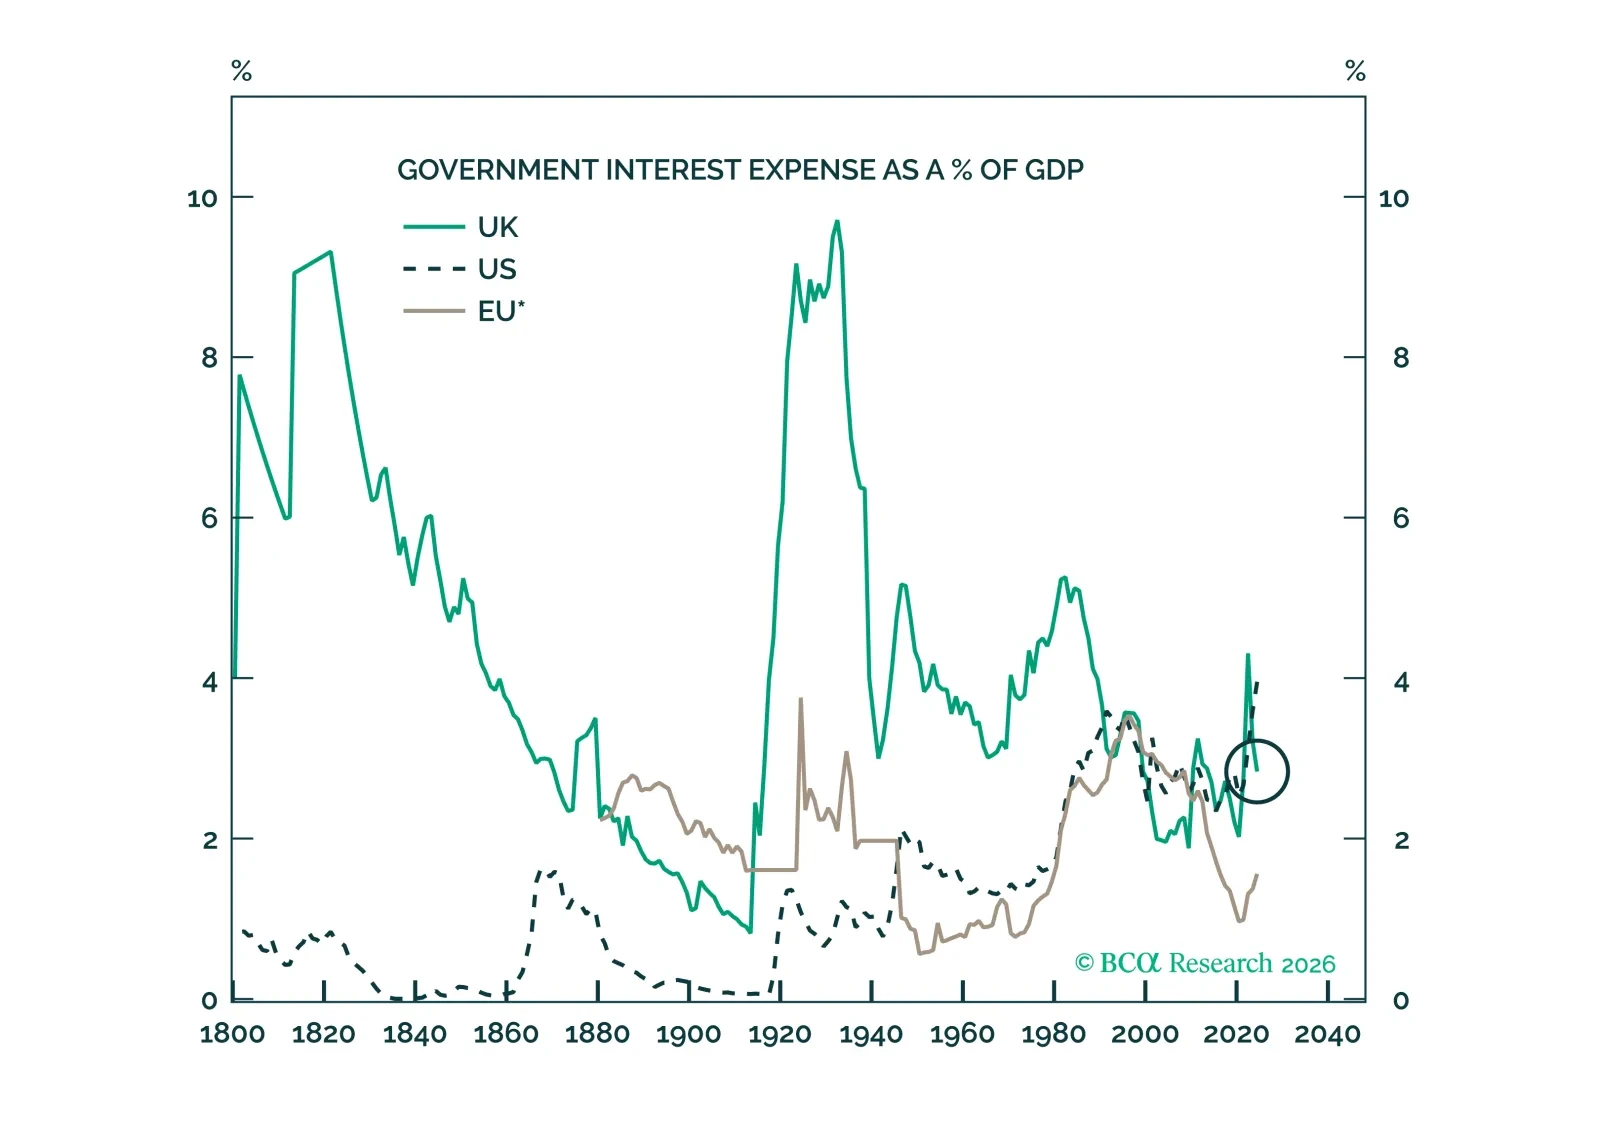
Stay overweight gilts despite renewed political turmoil in the UK.
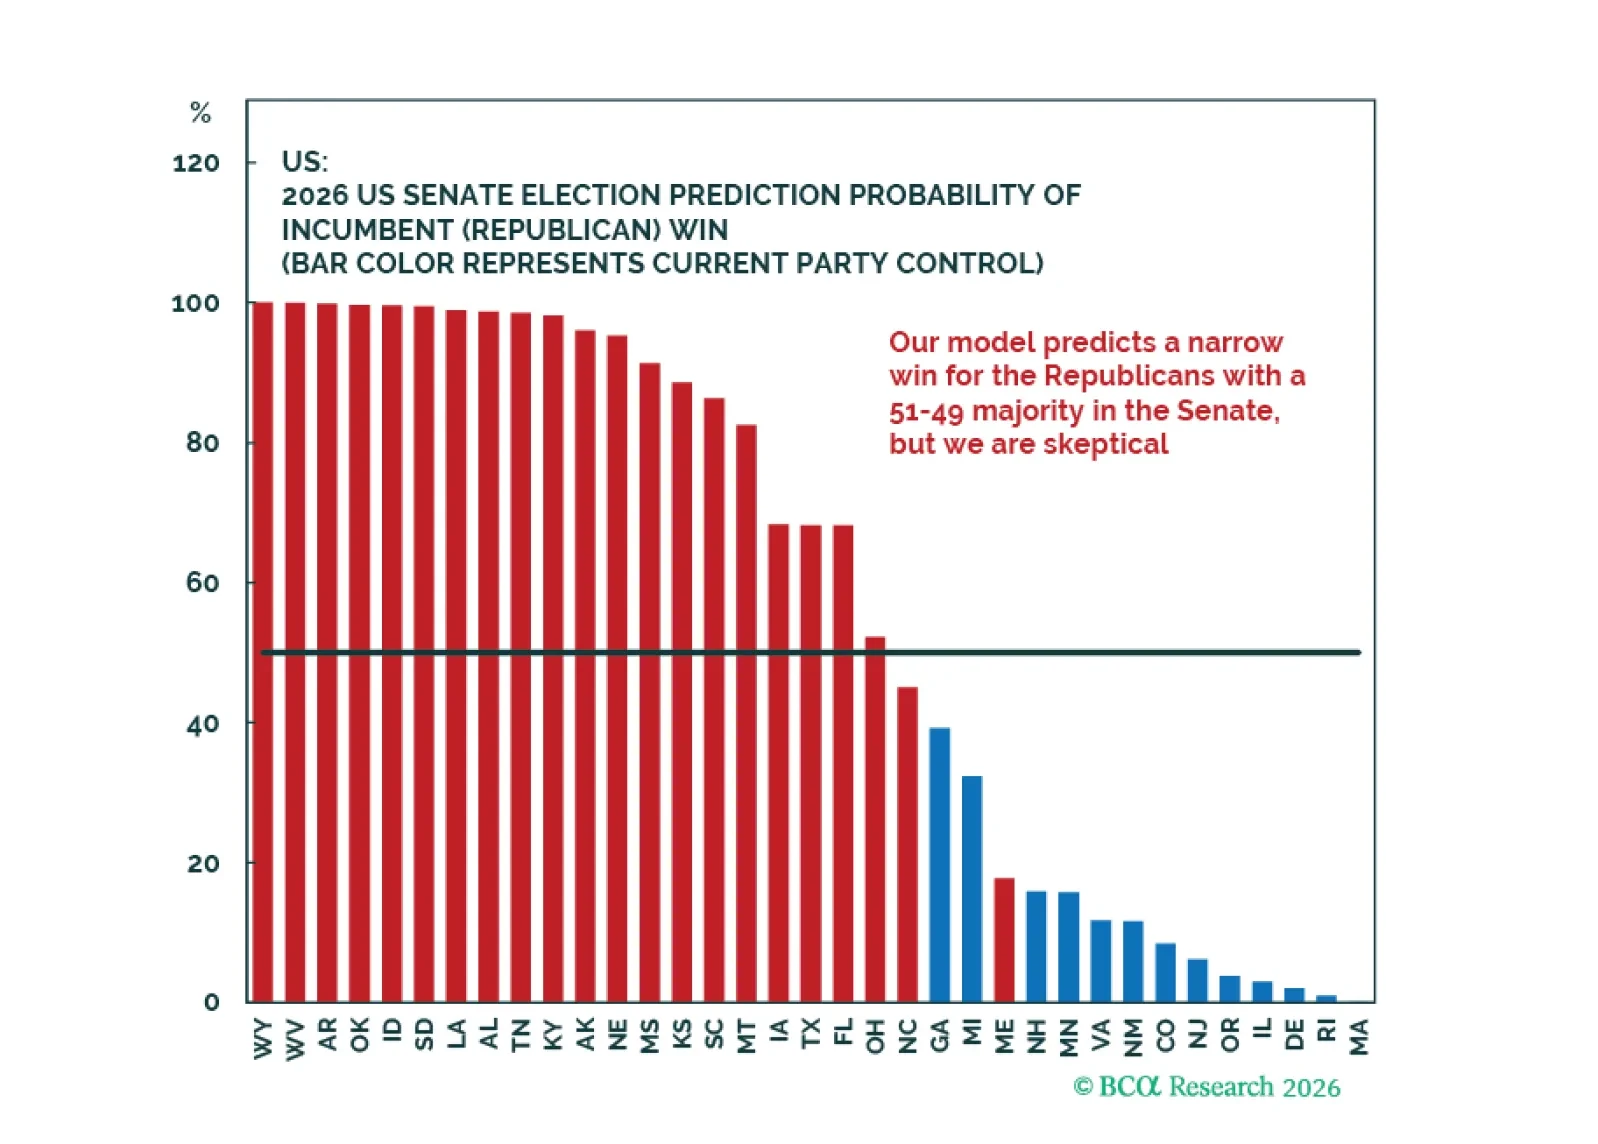
Midterms matter but geopolitics are the main risk this year. Markets will eventually refocus on geopolitical and inflation risks, raising Fed rate hike odds and supporting US dollar and stocks over global counterparts this year.
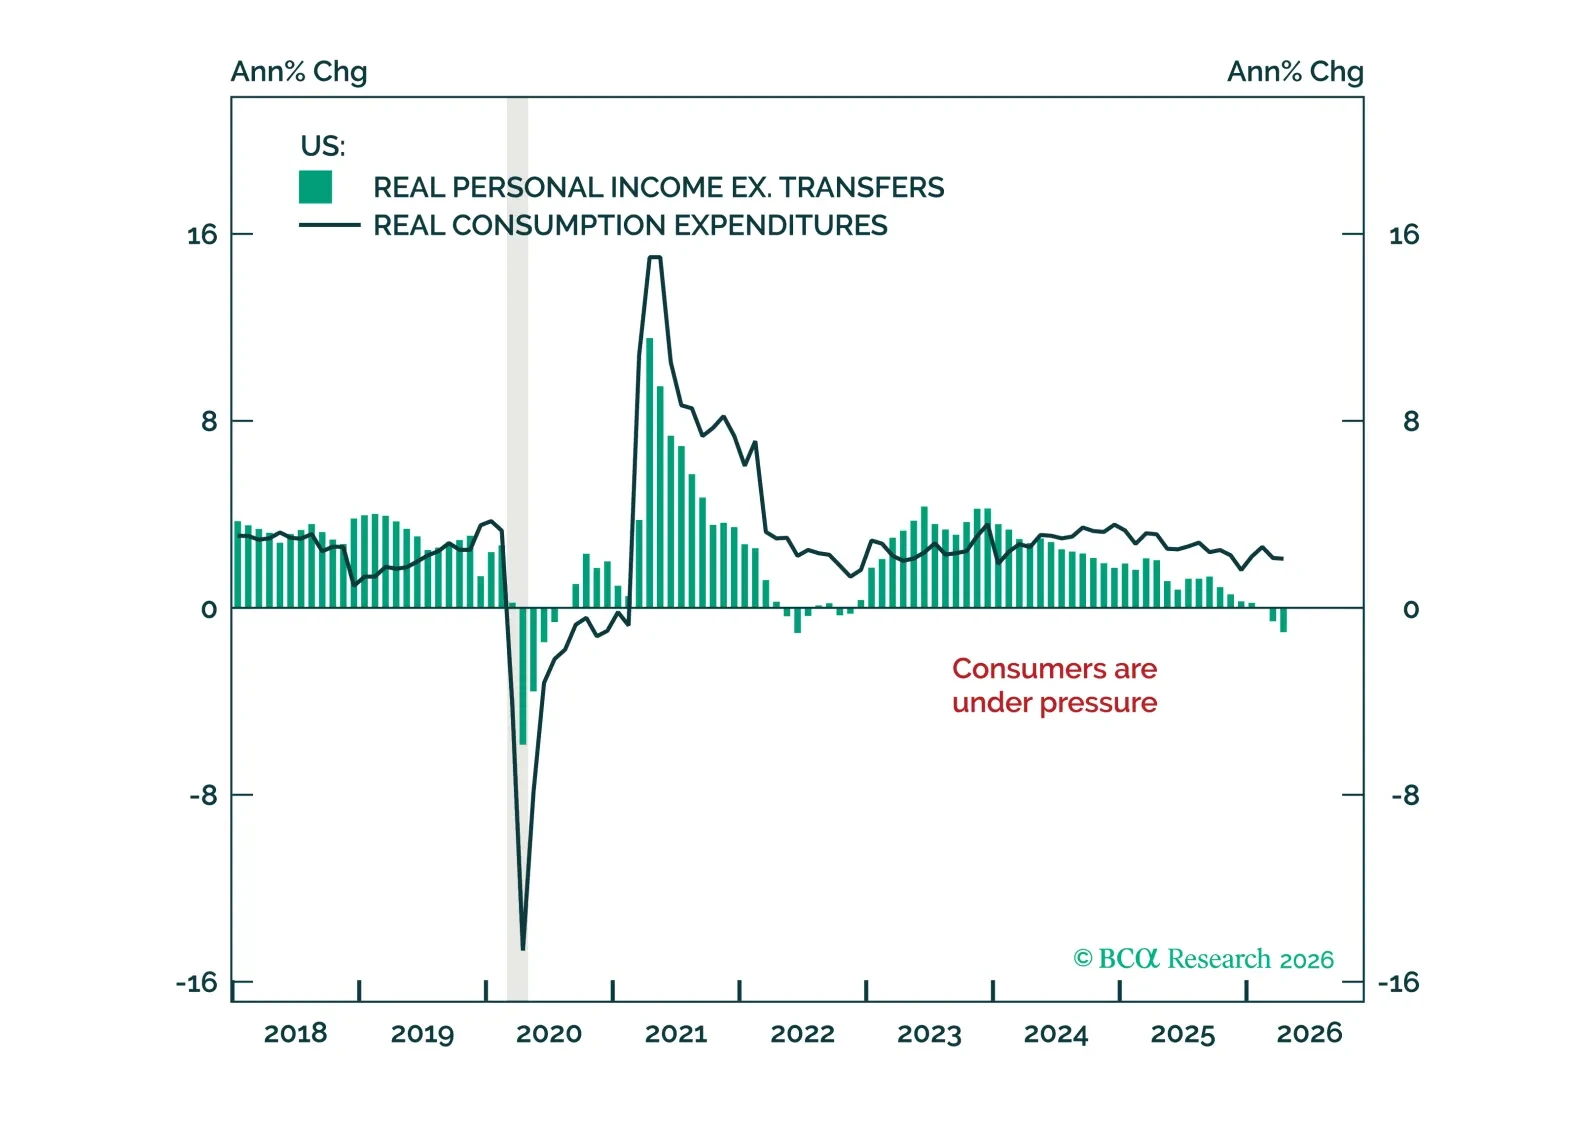
For the first time since… 2022… the GeoMacro team is starting to contemplate the end of the cycle in a serious way.
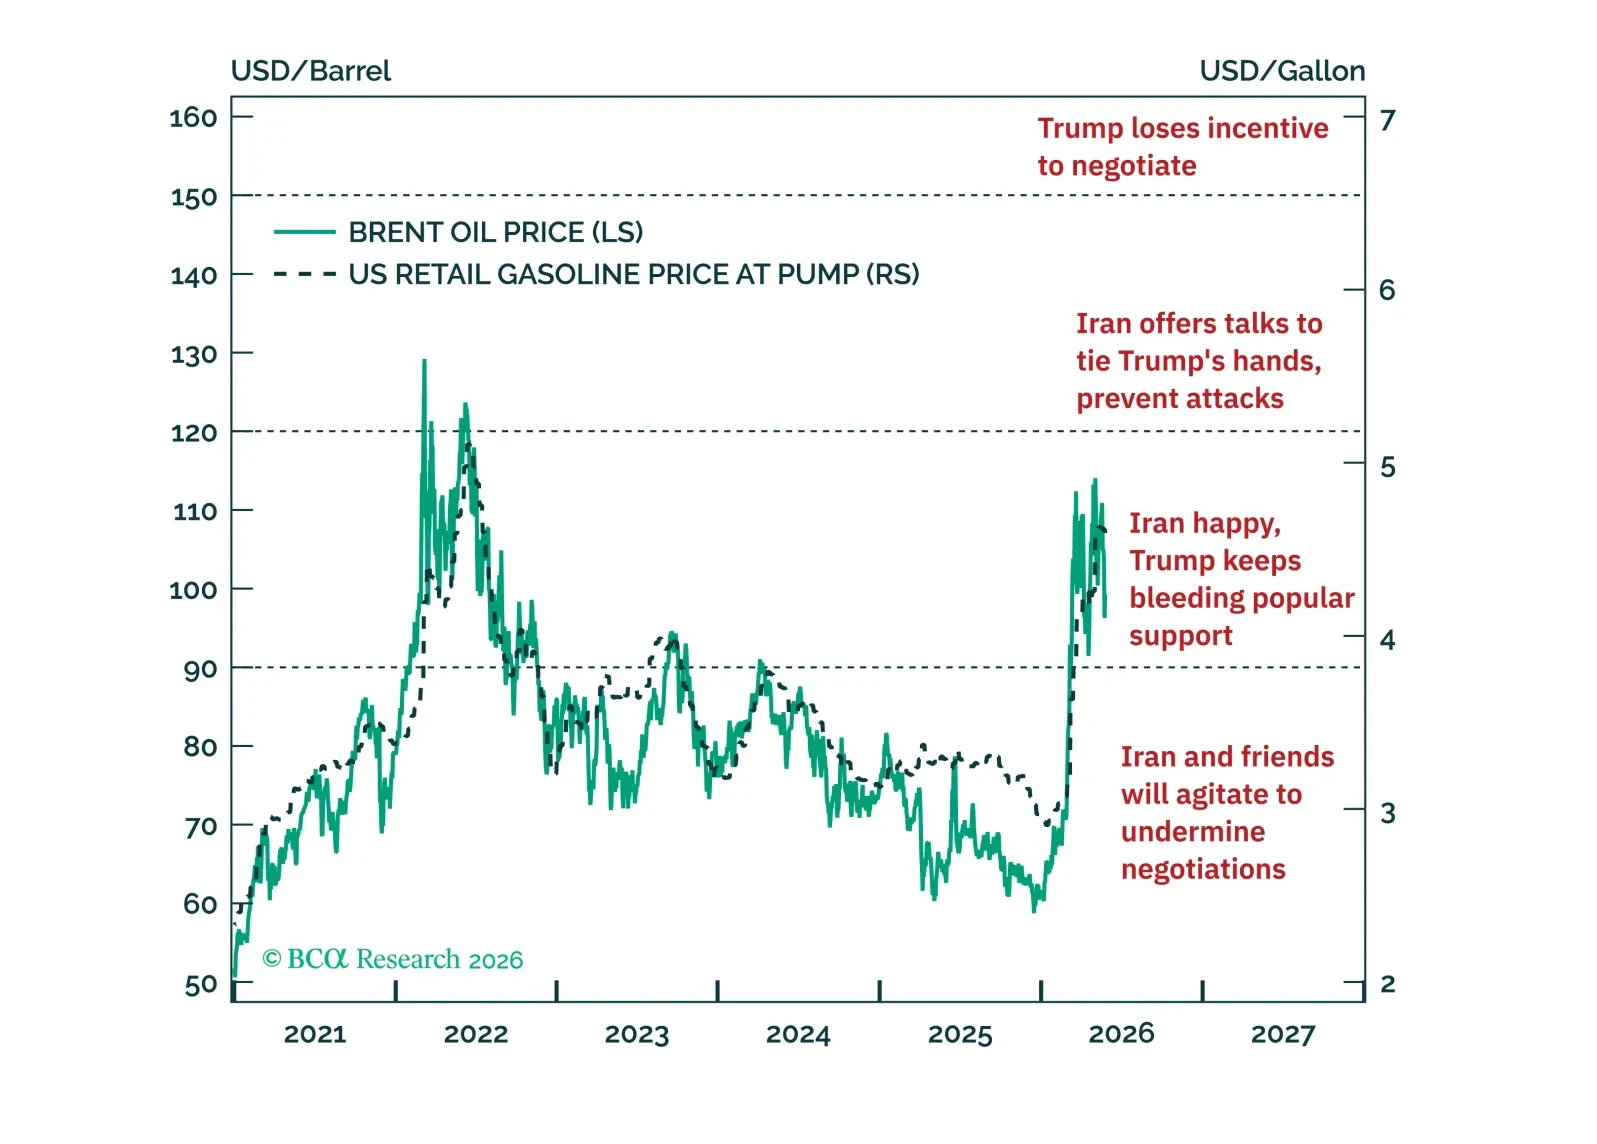
The odds of a near-term US-Iran deal have gone up slightly, but the odds of a Russian provocation that divides NATO have also gone up.
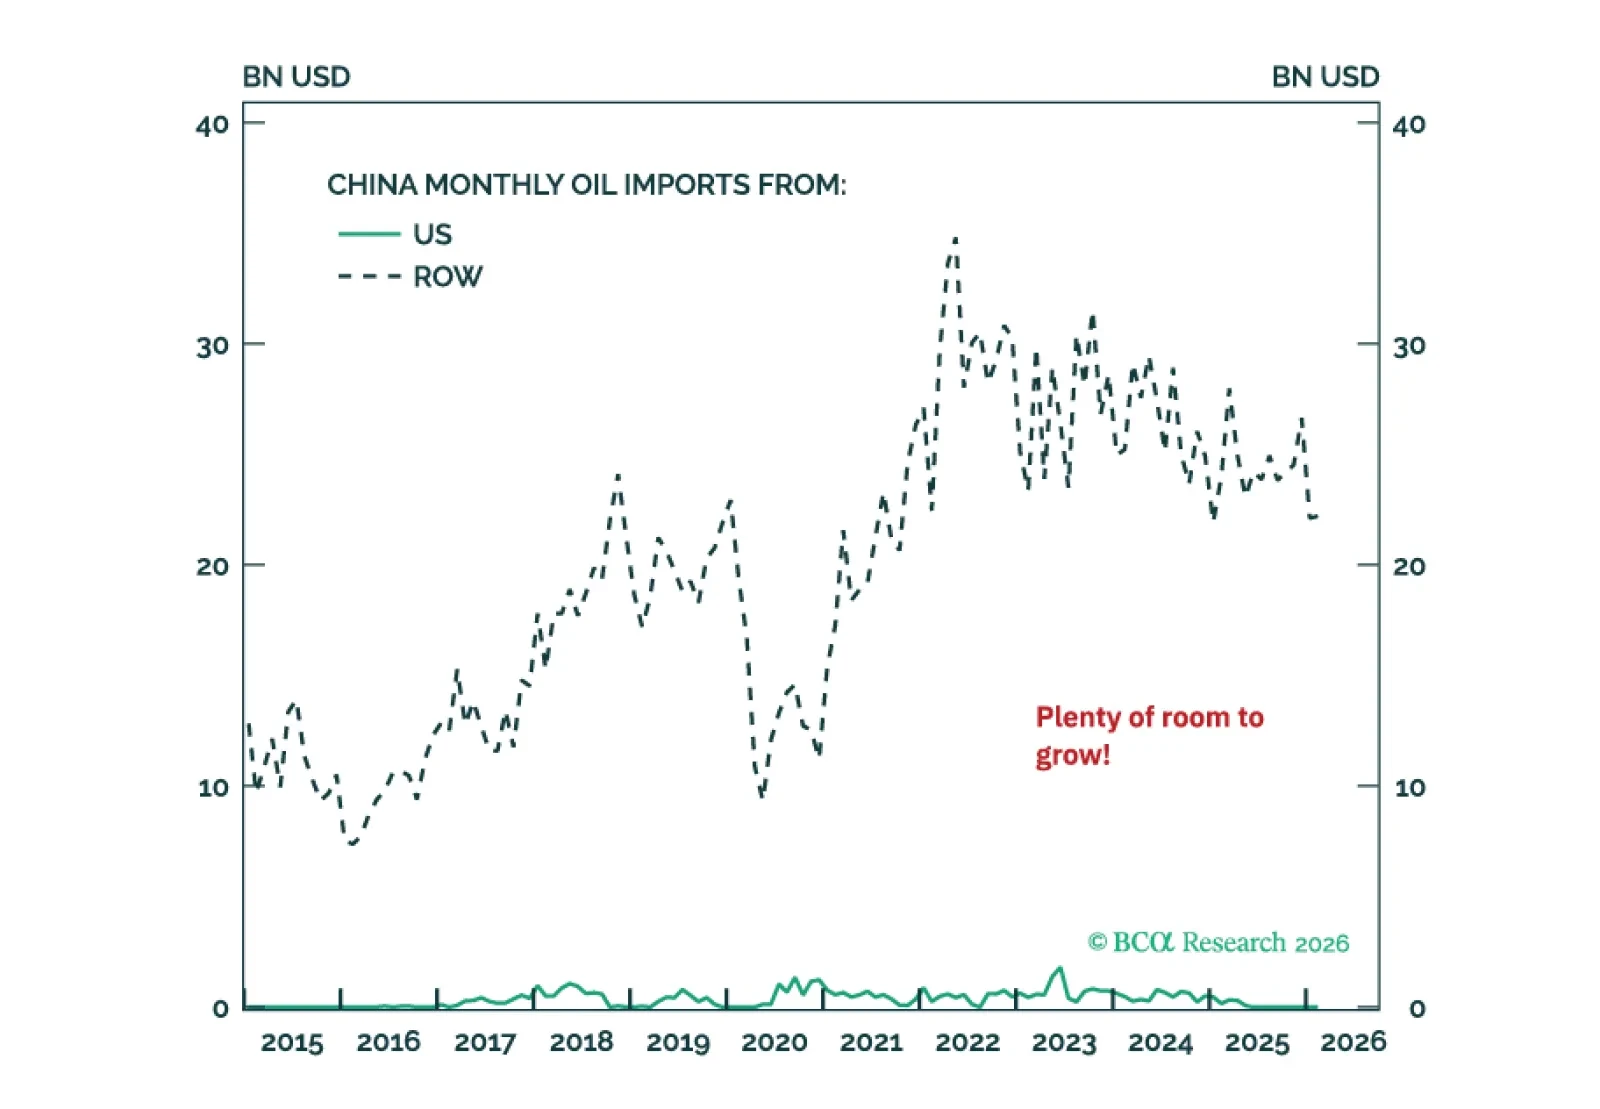
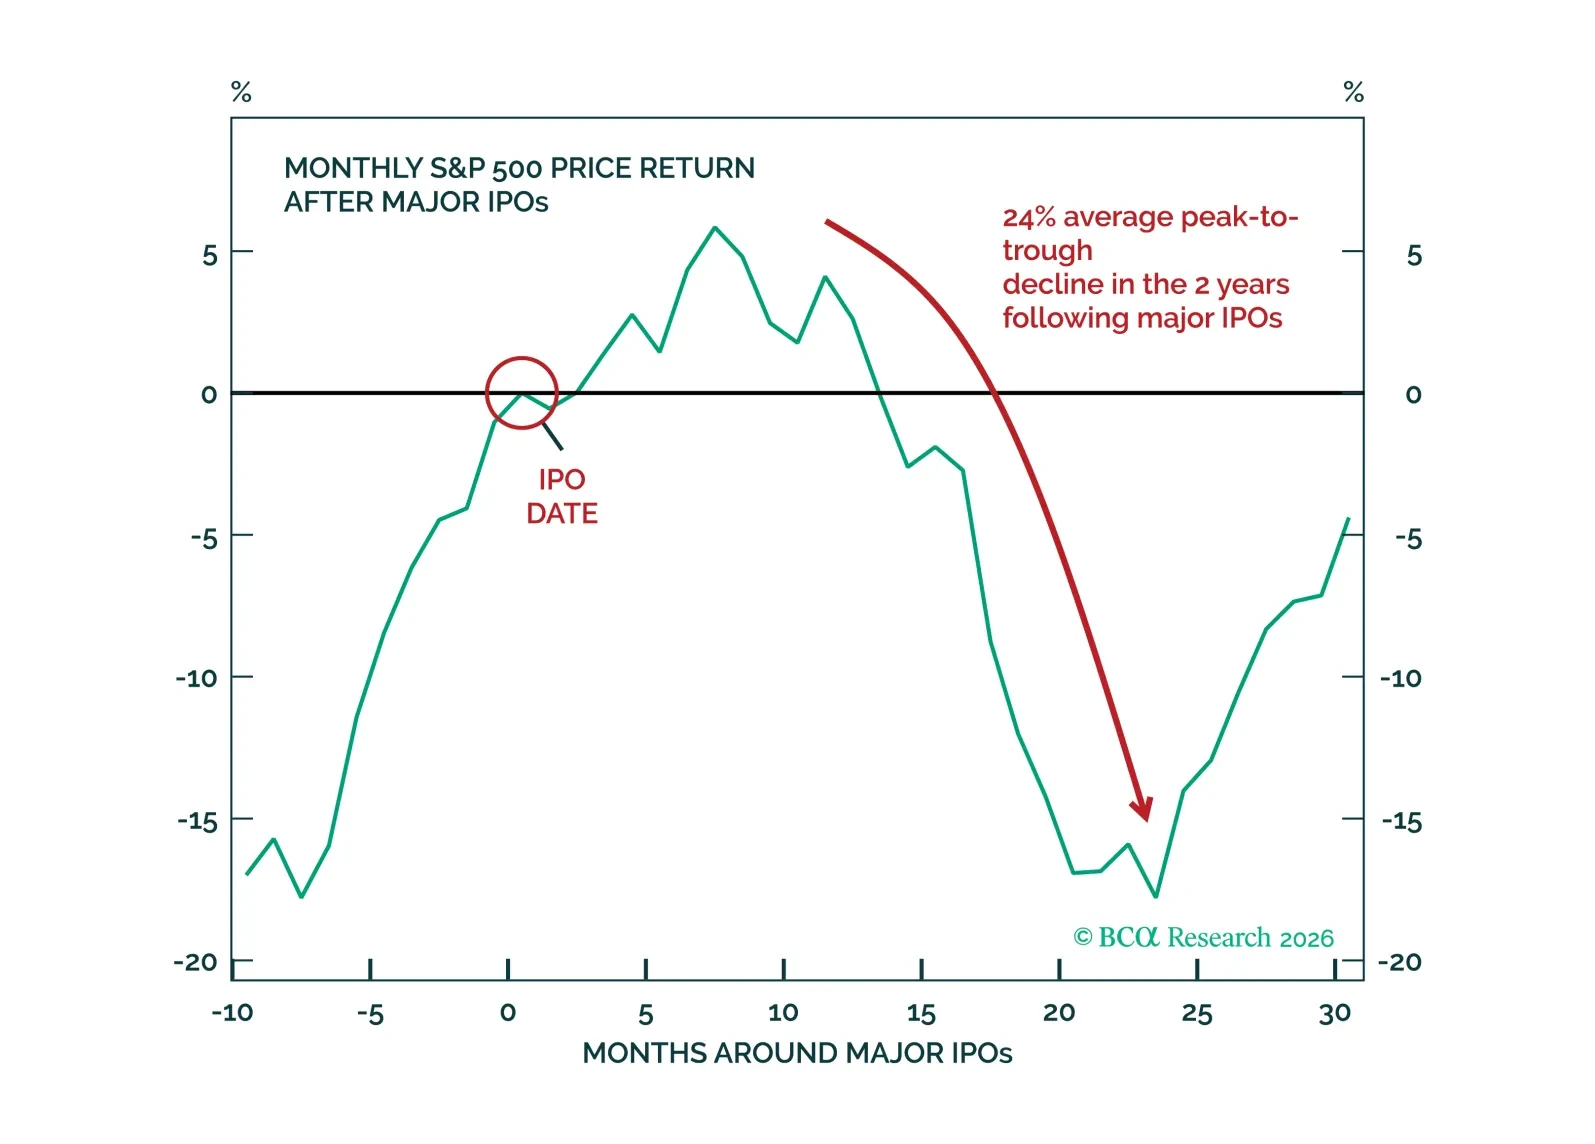
Equities have thrown caution to the wind for much of April and early May. We do not disagree with the sanguine mood, but caution that the Hormuz saga is far from over. Still, the AI capex mania continues and the labor market is firming in the US, suggesting that there is more upside to equities.