 FICC
Find out more
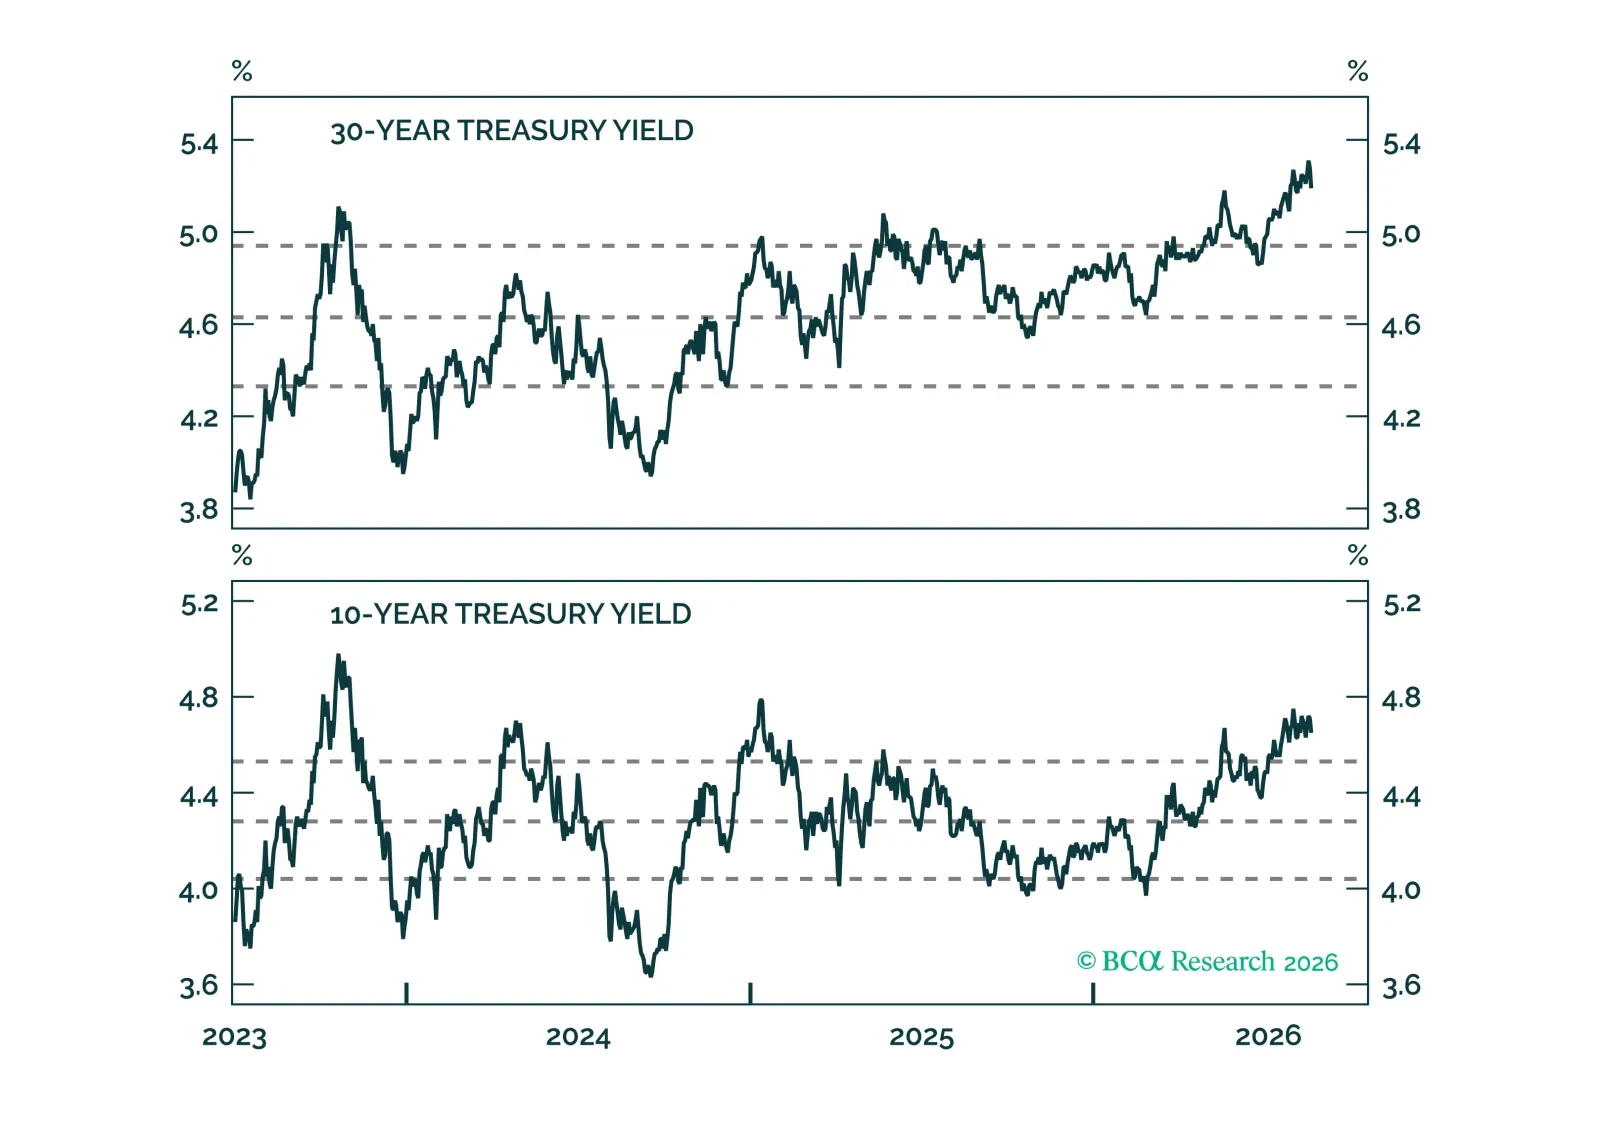
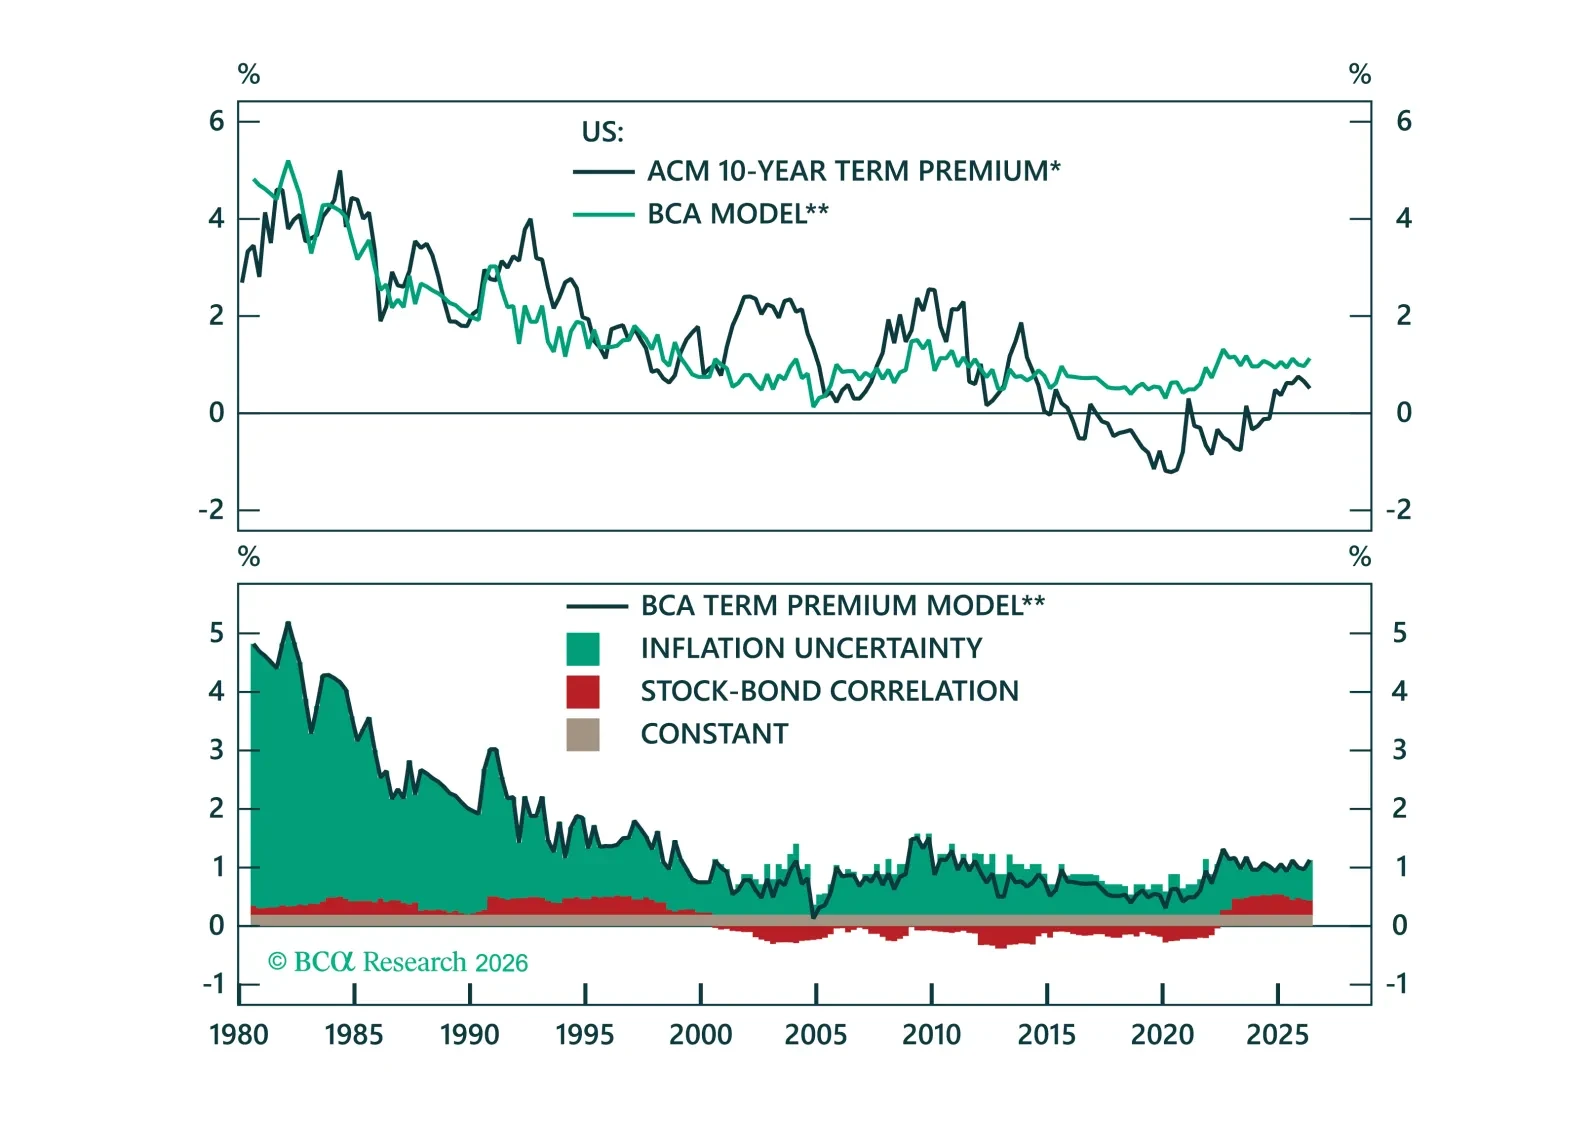
Despite recent increases, long-maturity Treasury yields are roughly consistent with fundamental fair value. We see limited value in long duration plays.
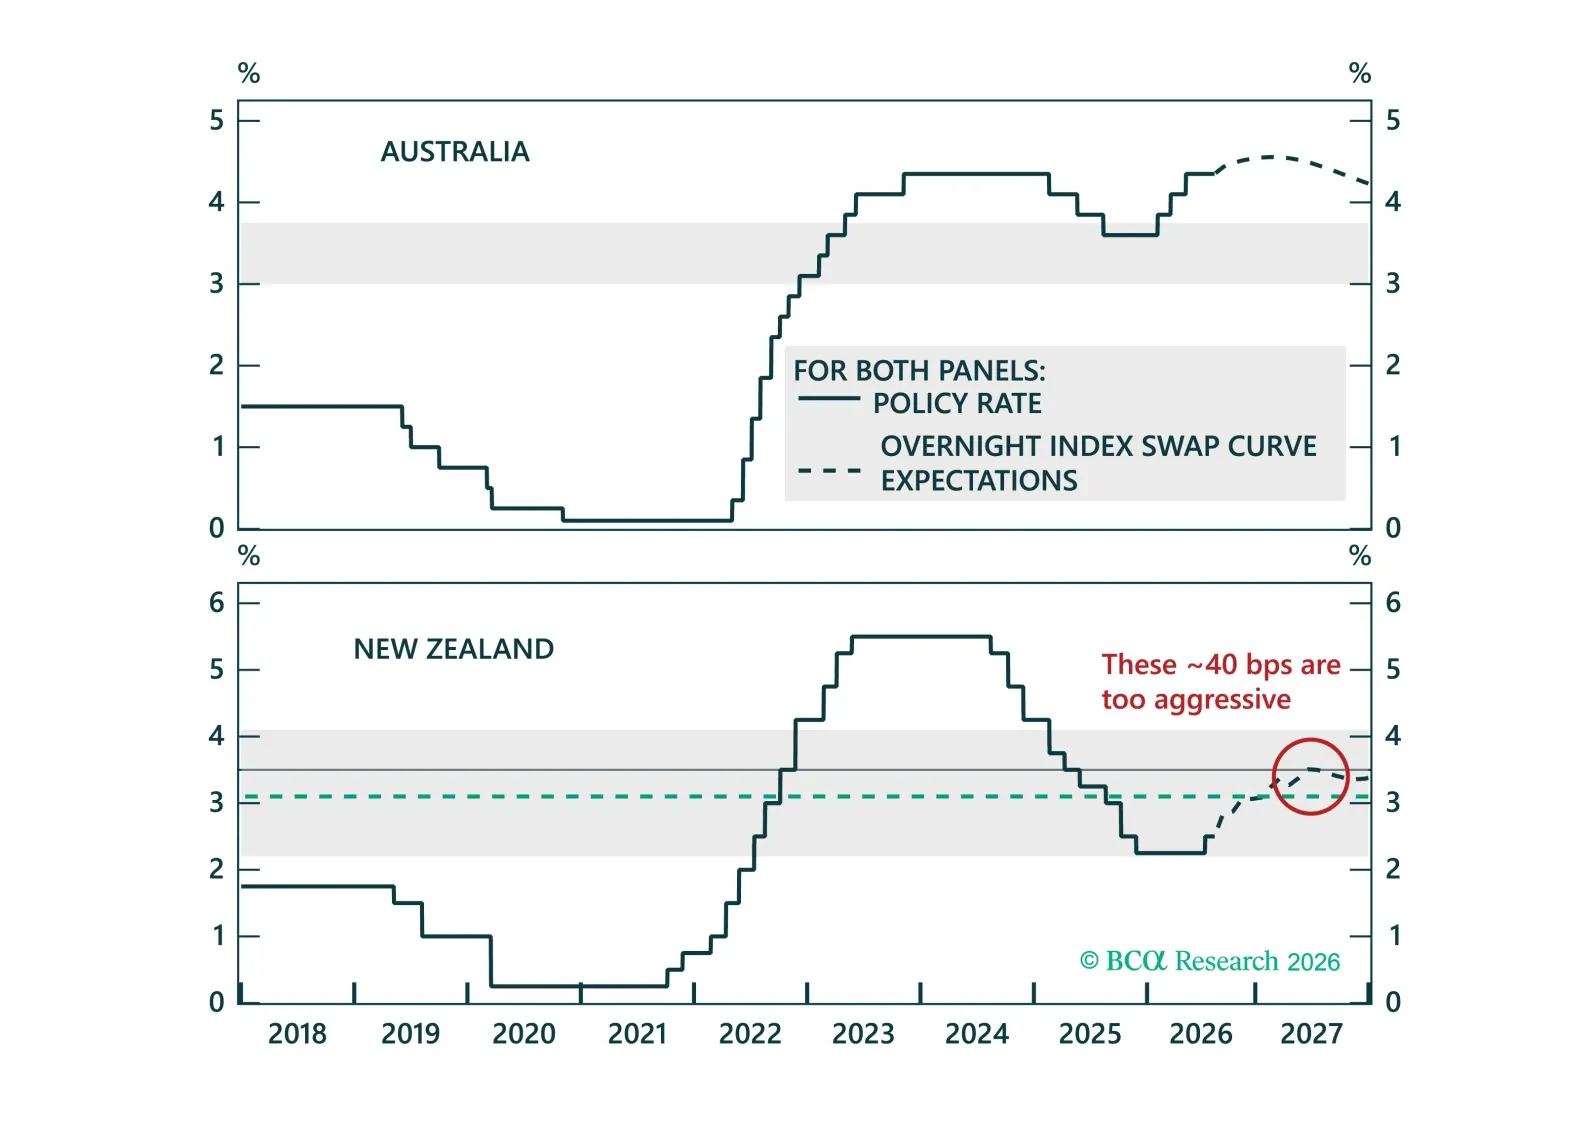
The RBA is likely done hiking, and the RBNZ overpriced for more hikes. We trace both conclusions back to housing, credit, and external dynamics, with implications for our country allocation in ANZ bonds and our long AUD/NZD view.
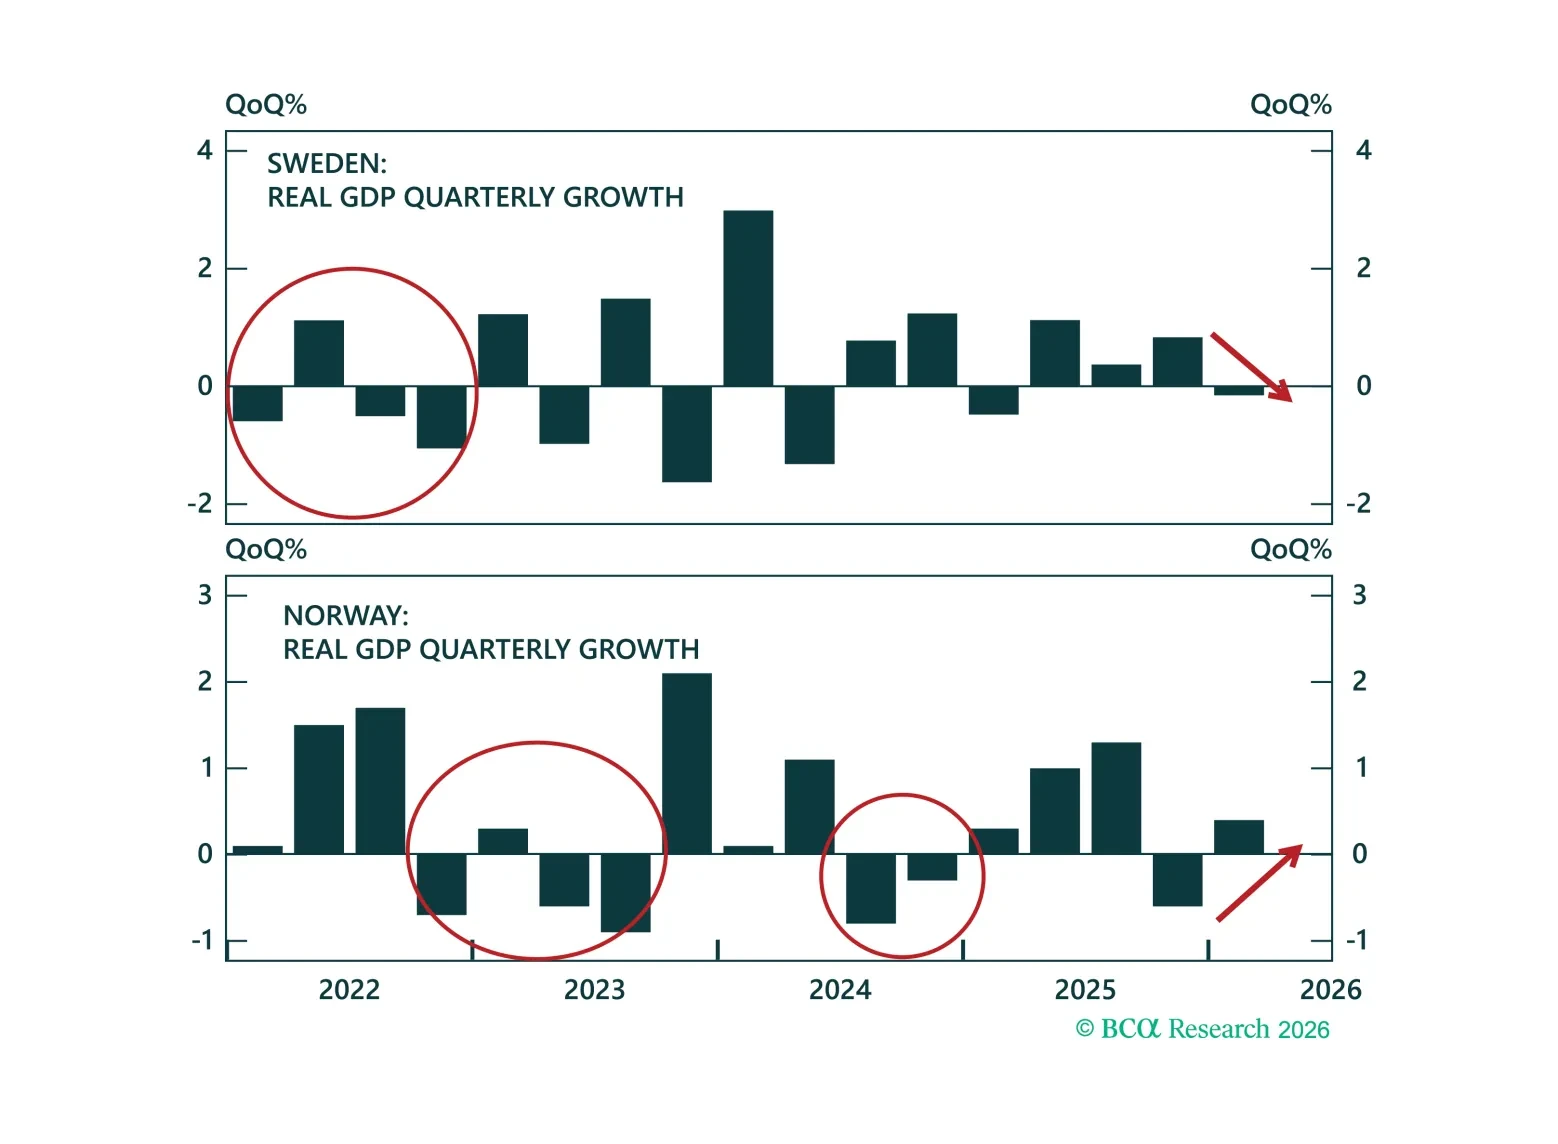
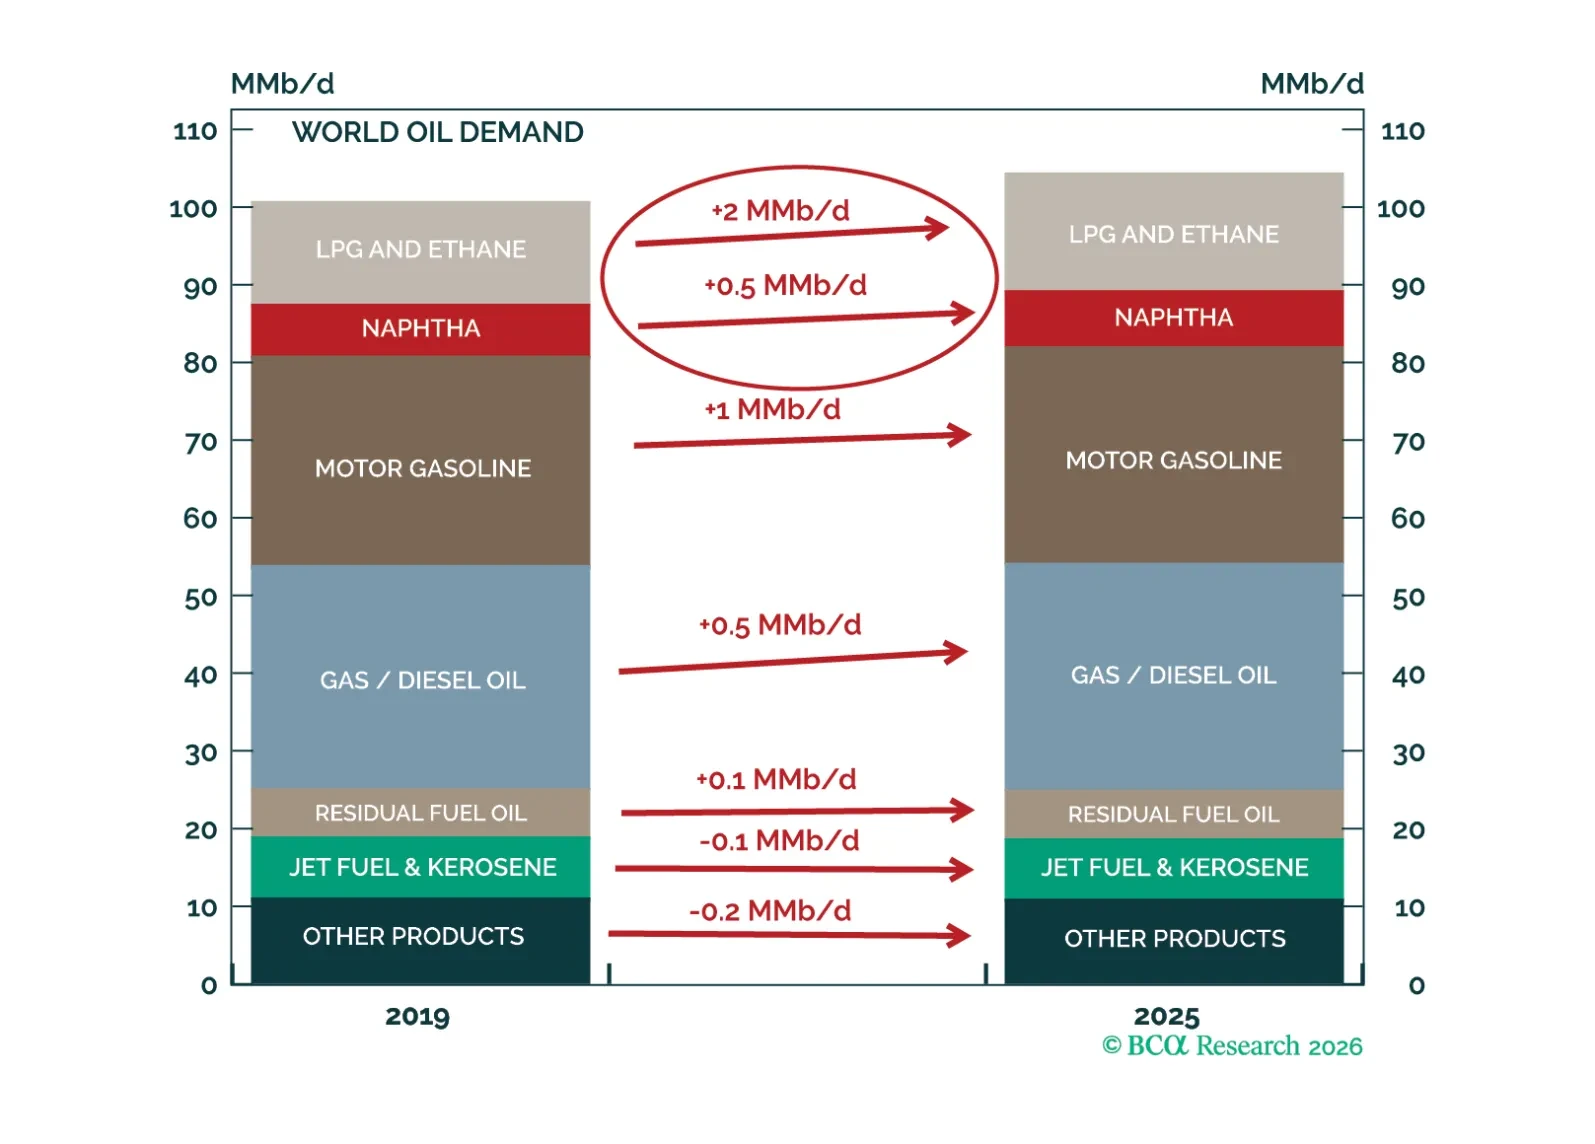
The war in Iran and the energy shock are driving a reversal of Nordic fortunes: Sweden’s recovery is faltering just as Norway receives a welcome energy windfall. Favor Norwegian over Swedish equities and buy NOK/SEK. In rates, fade aggressive Riksbank hike expectations and downgrade Norwegian government bonds to neutral.
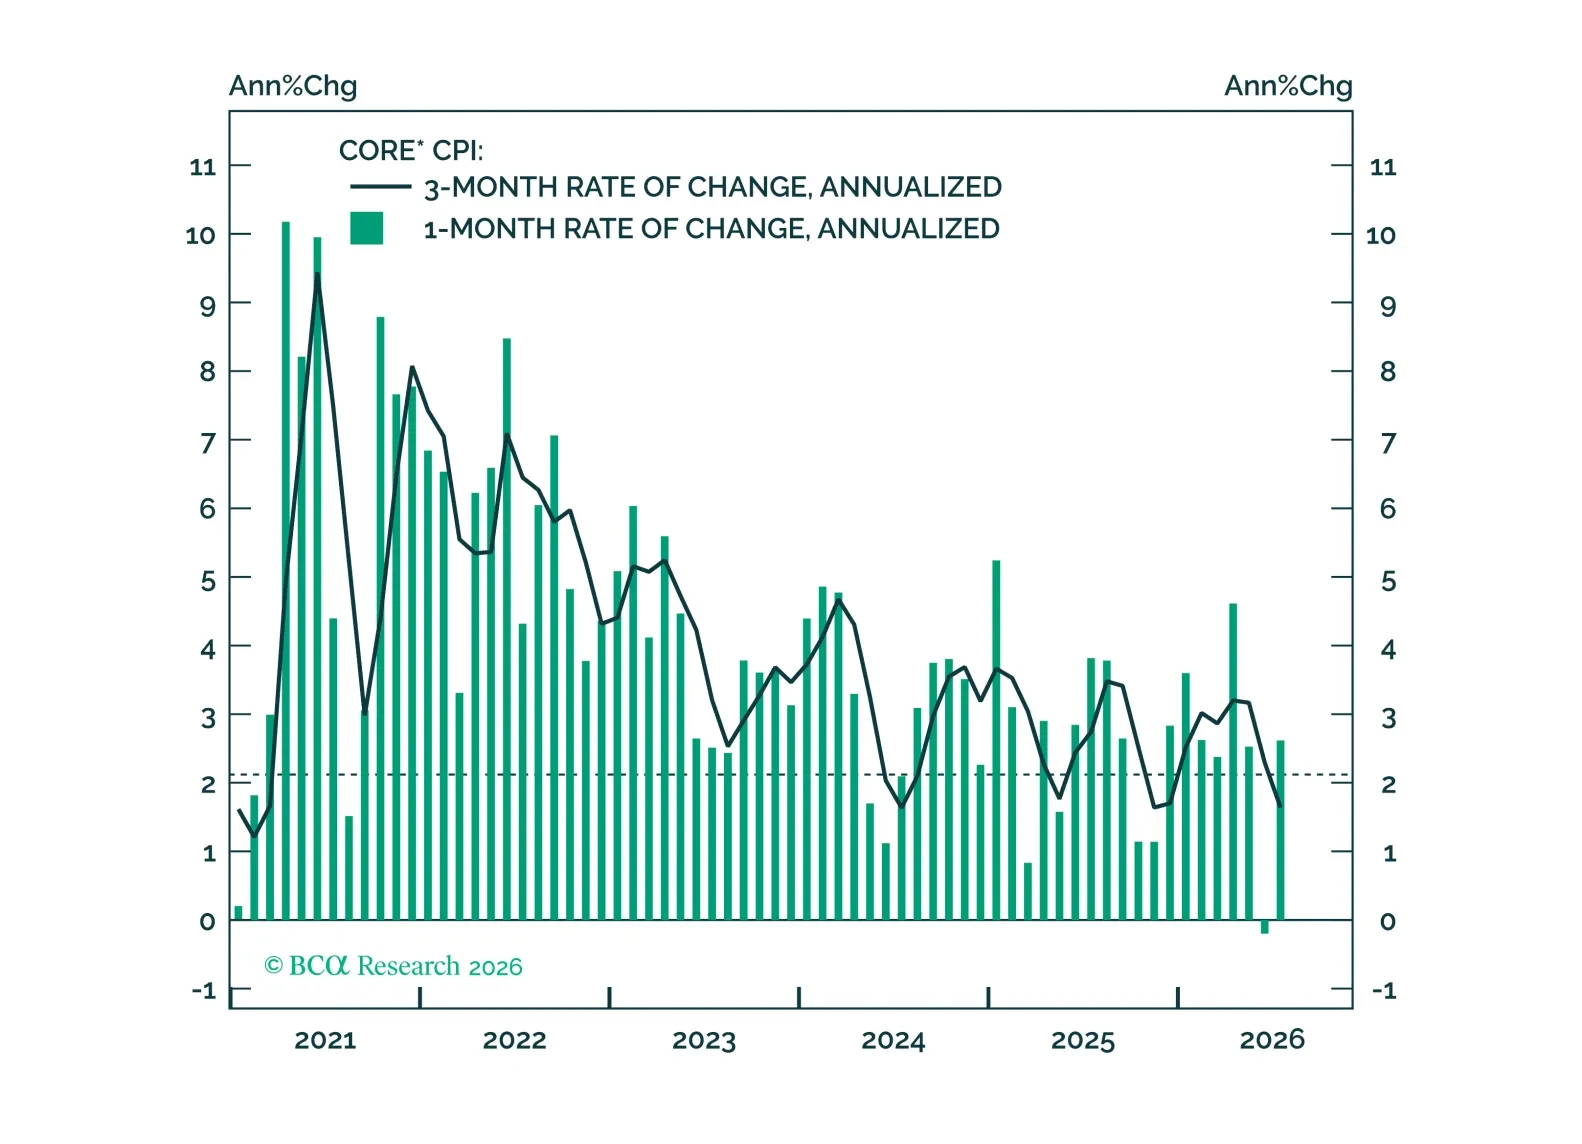
July’s CPI reading was low enough to keep the Fed on hold for now, but near-term upside inflation risks remain.
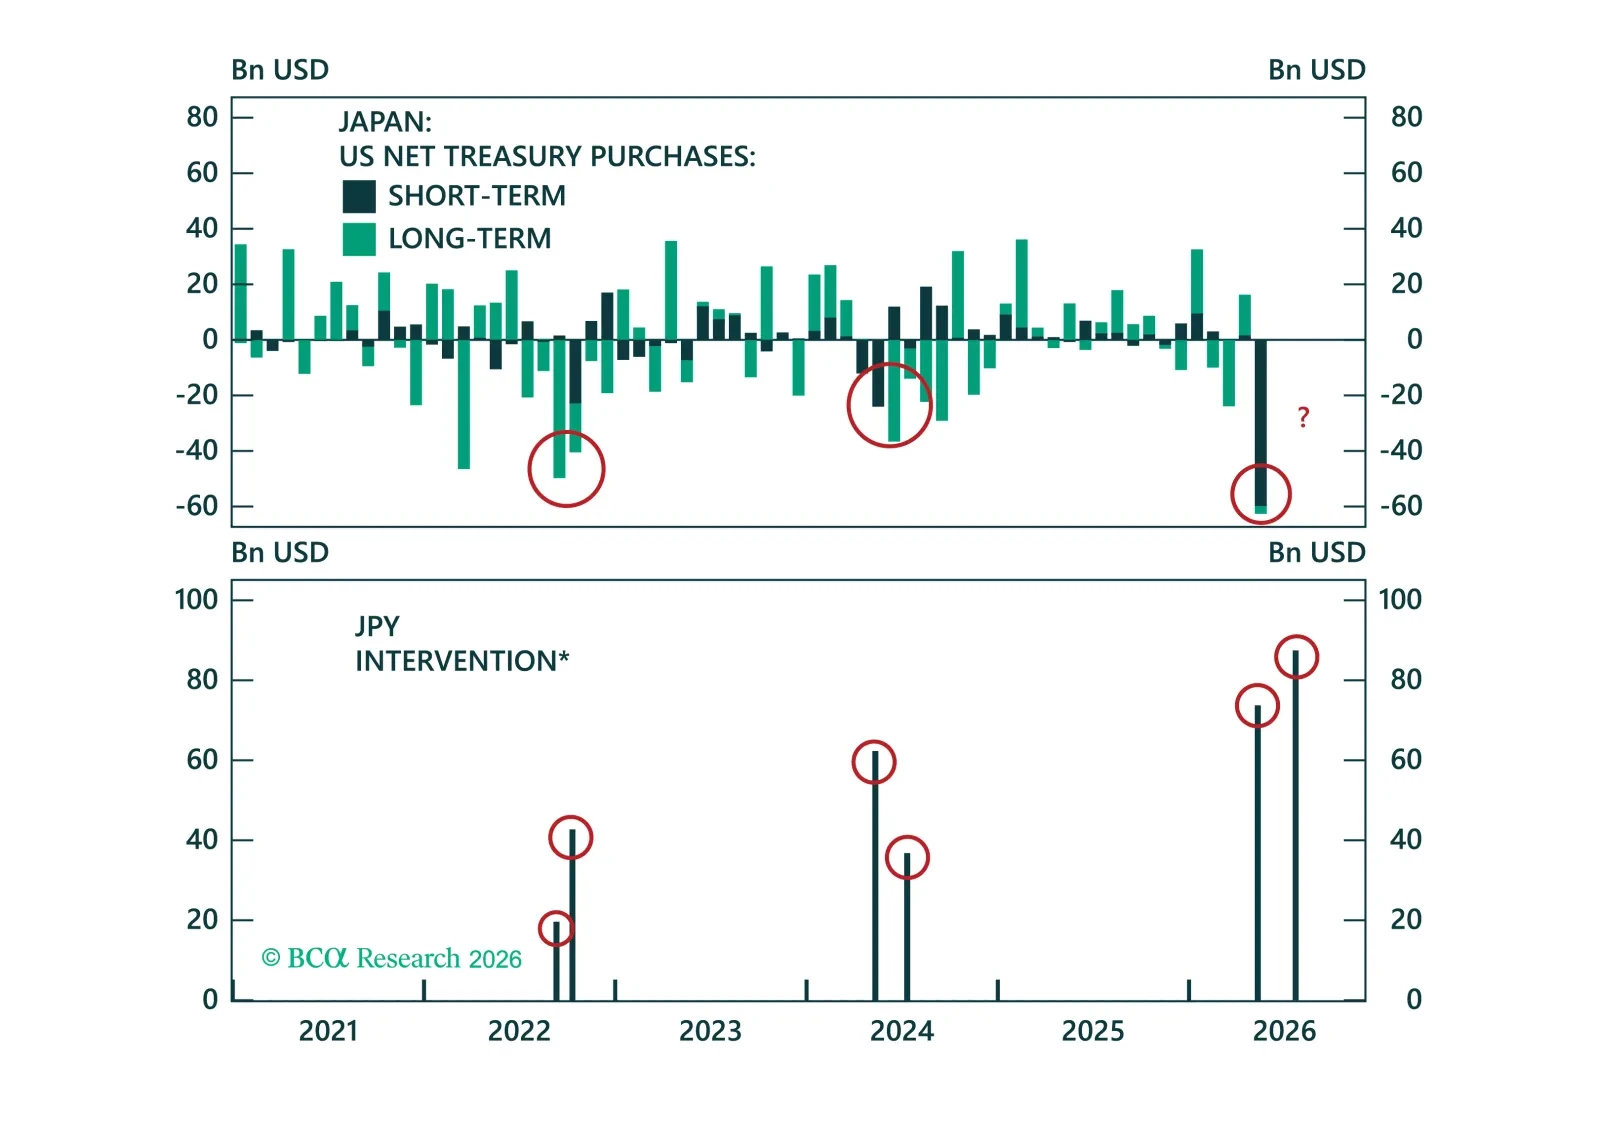
MoF and the US Treasury stepped in together to defend the yen, but even joint intervention cannot reset the fundamentals still weighing on the currency. Washington's pursuit of its own incentives, meanwhile, offers another glimpse of a more activist US Treasury.
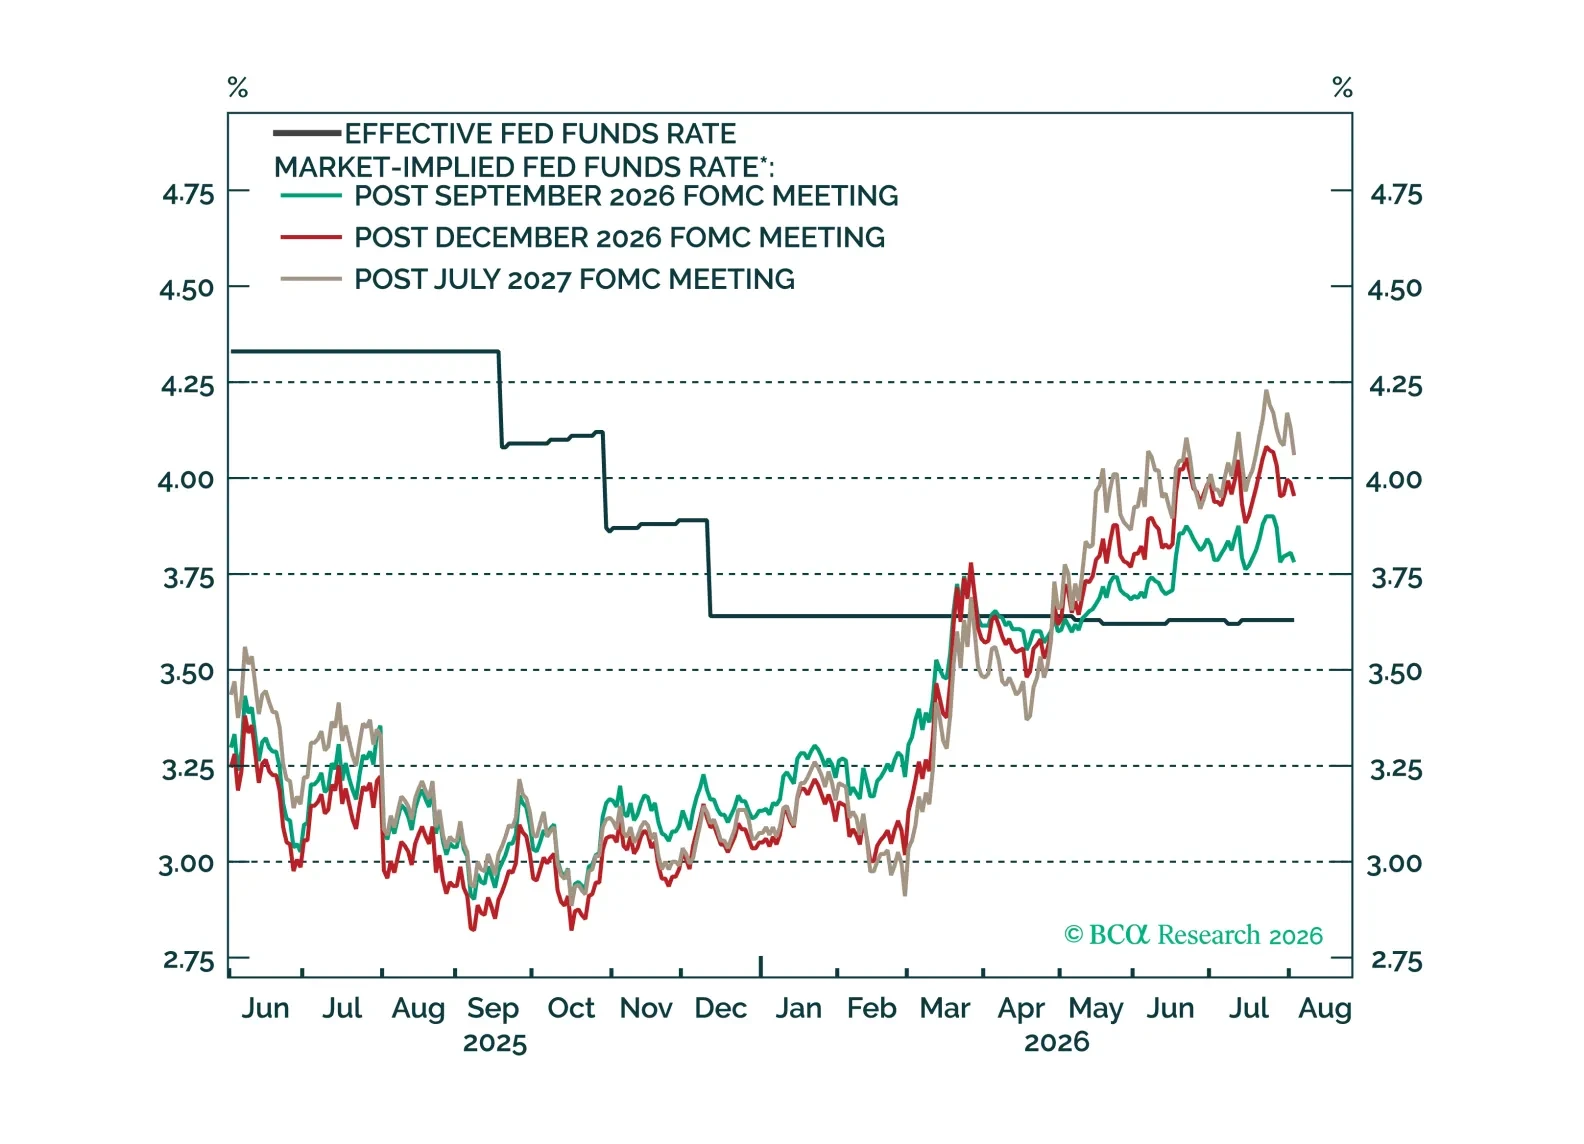
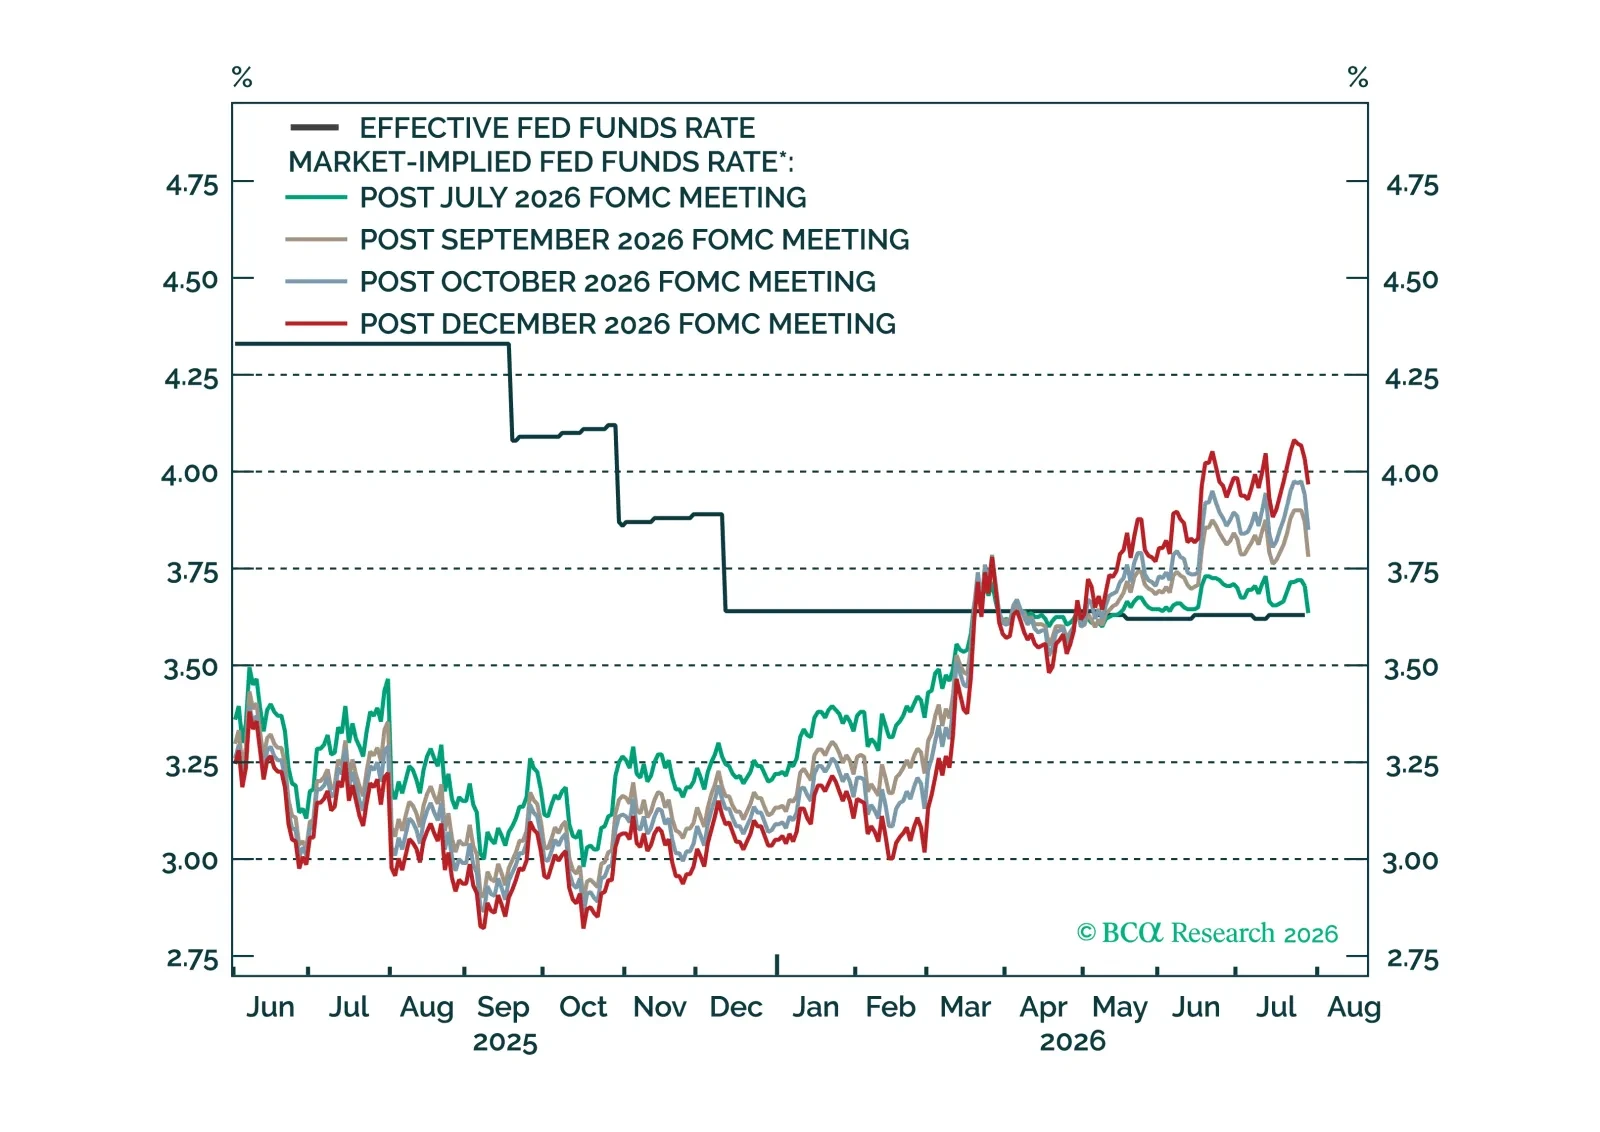
Despite today’s hold, the bar for a rate hike in September remains low and contingent on the next two core CPI reports.