Explore FICC
FICC | Bonds
Actionable asset allocation recommendations for your bond portfolio, drawing on macro analysis of interest rates and global debt market dynamics. Typically published weekly.
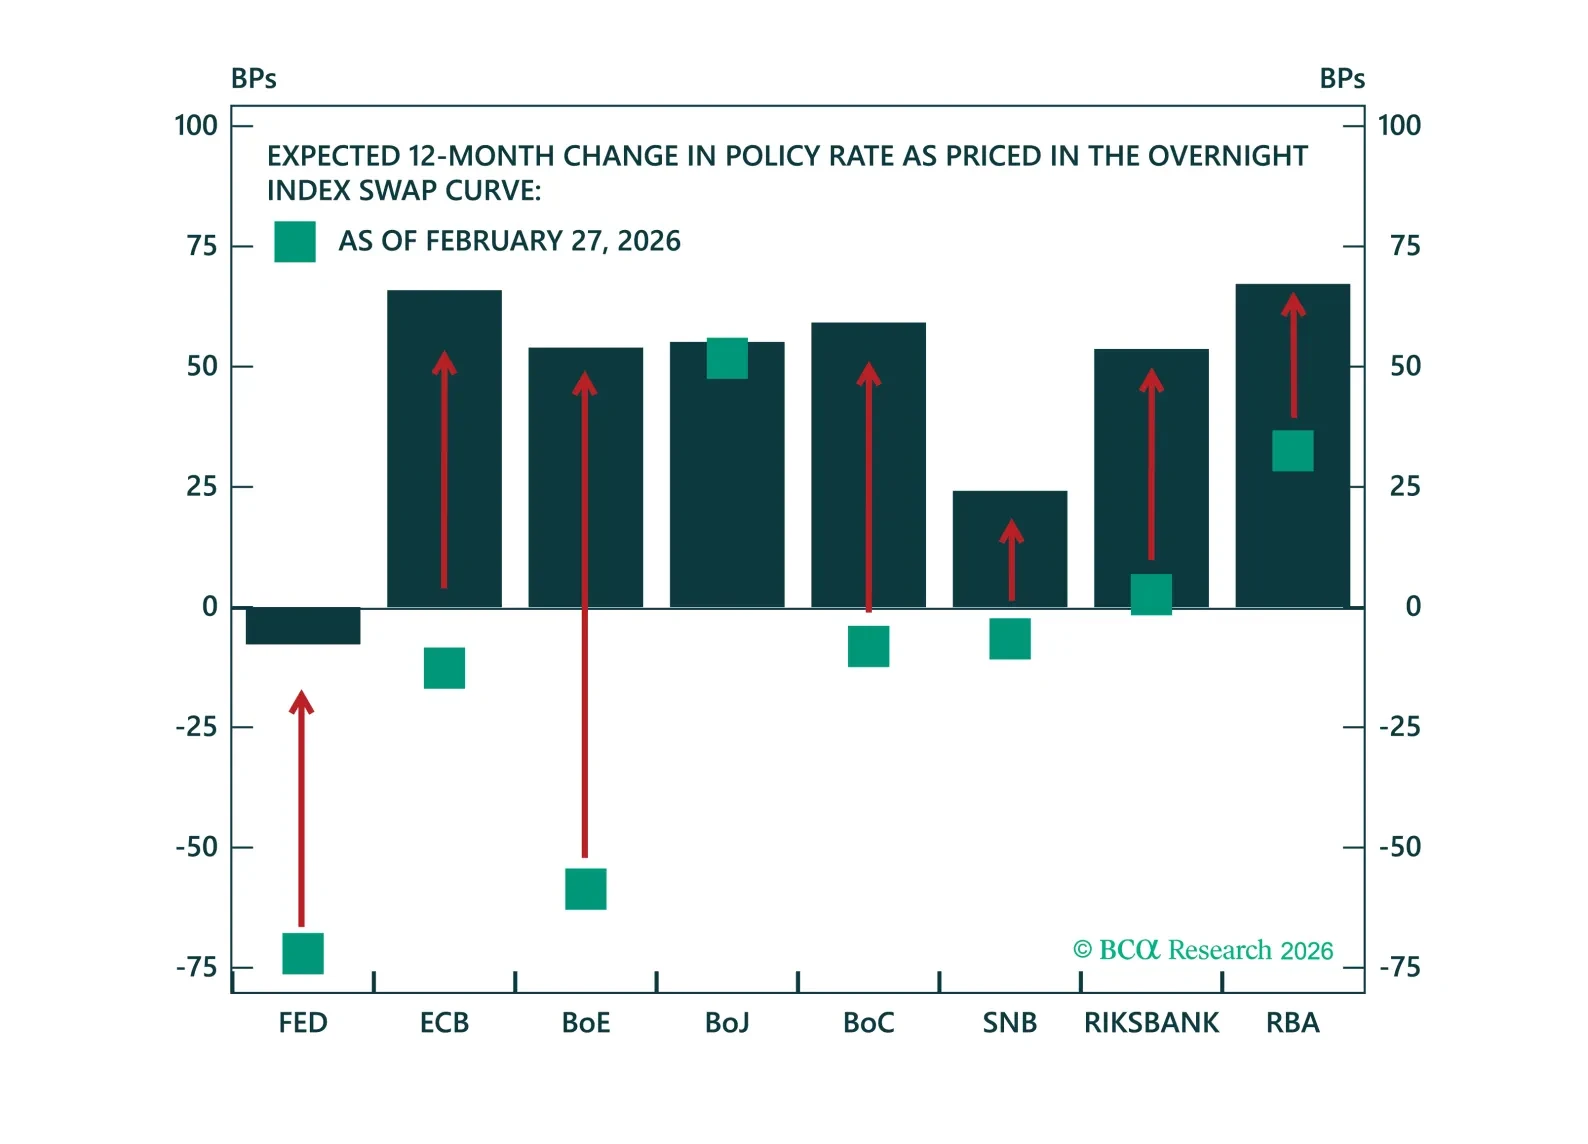
We discuss the takeaways from this week’s central bank meetings amidst the unfolding energy price shock.
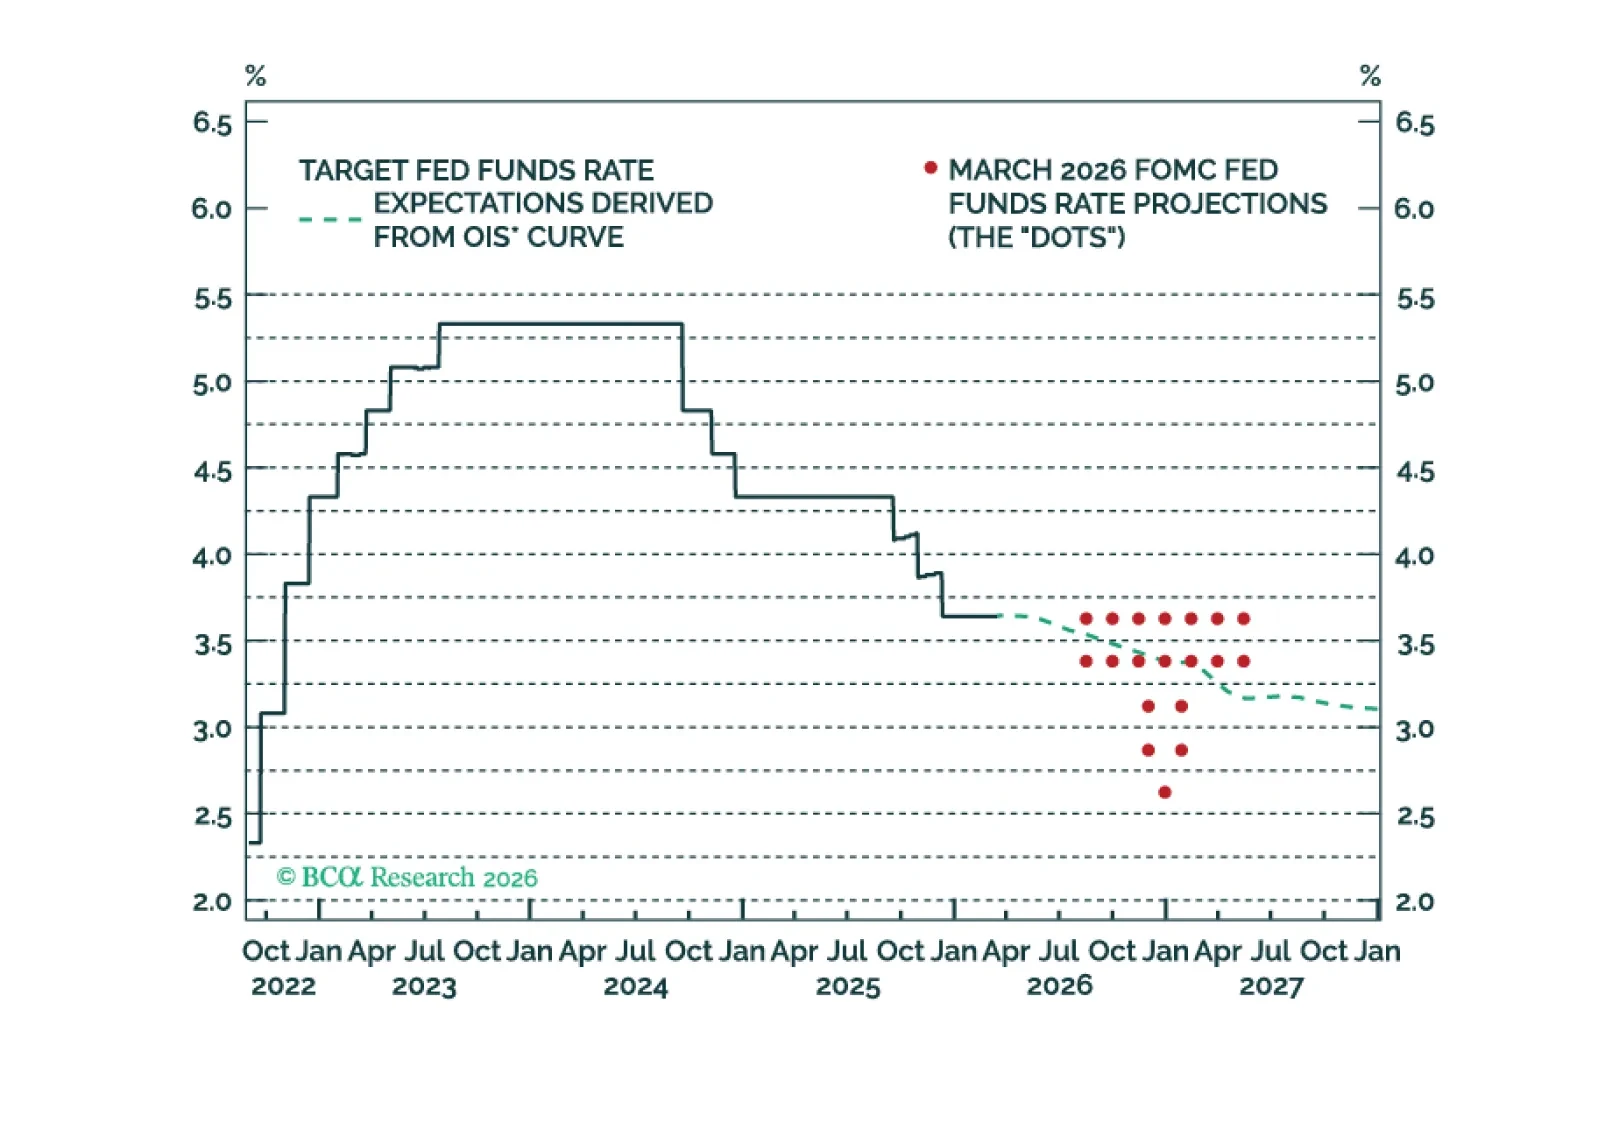
The Fed will not cut rates again until core inflation trends lower. This remains likely as the tariff impact on goods inflation wanes, but the recent energy price shock could delay any meaningful downtrend.
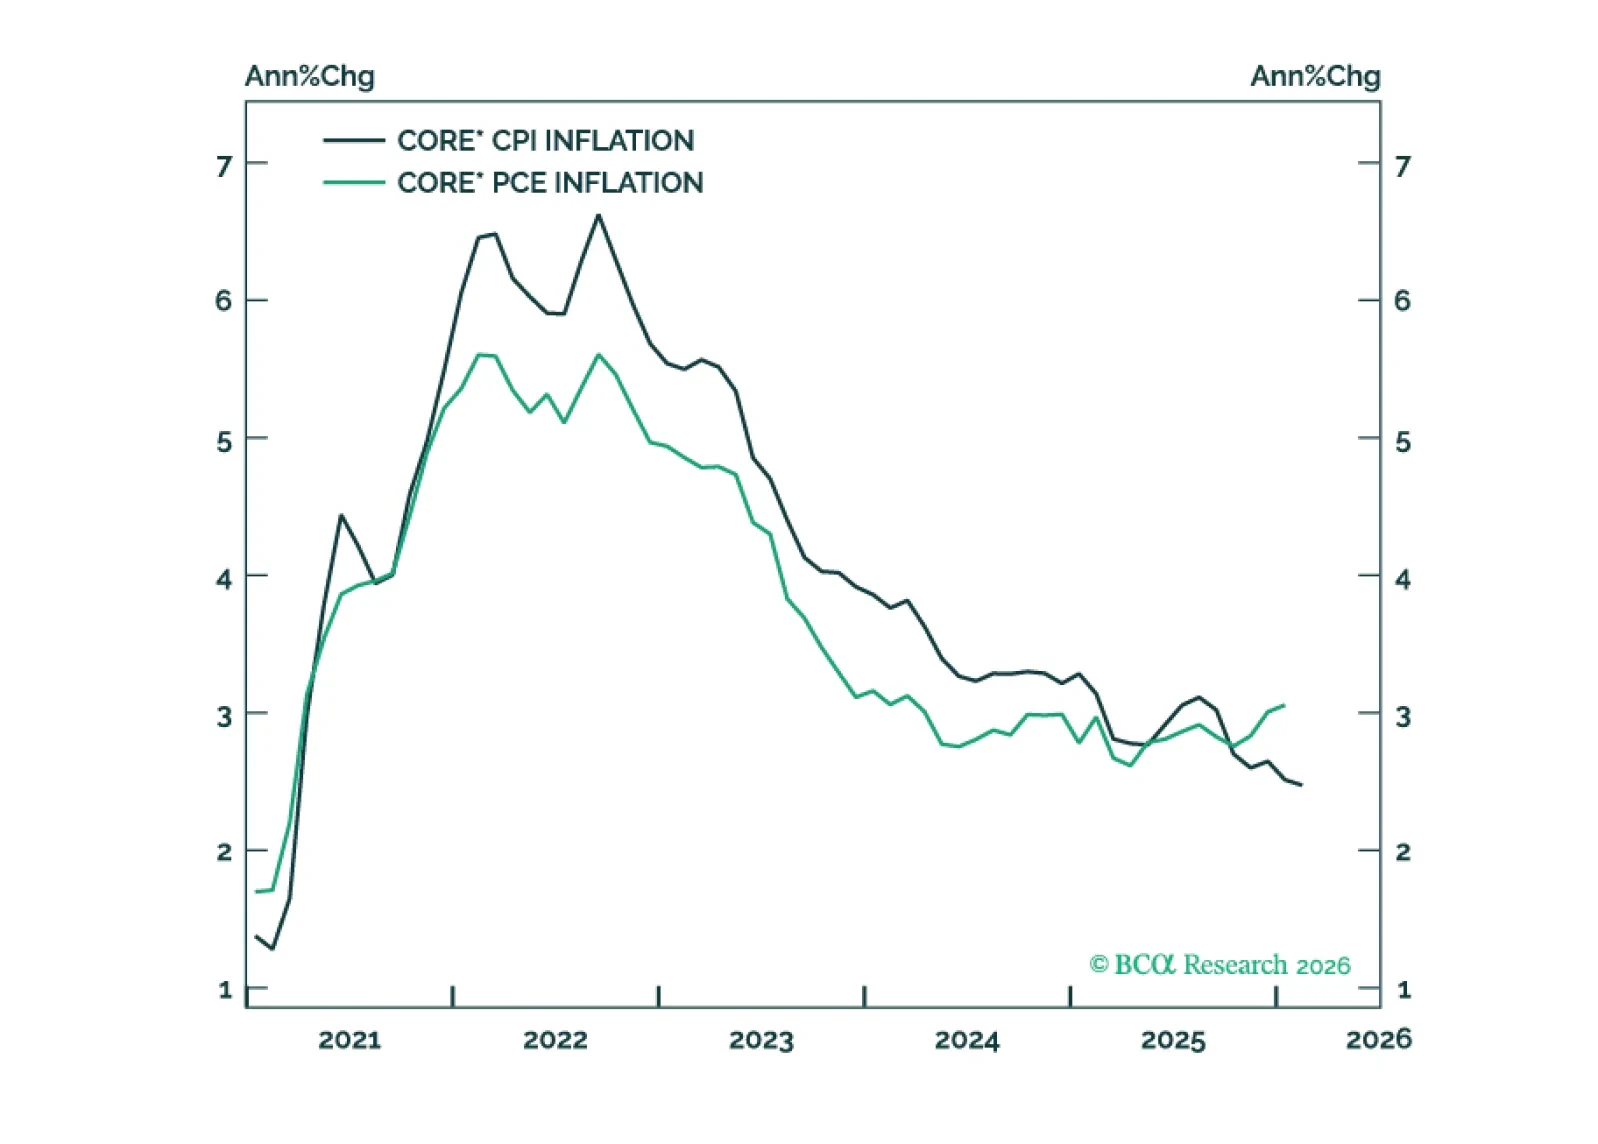
The gap between PCE and CPI inflation will narrow within the next few months, mostly driven by core PCE inflation converging toward its trimmed mean.
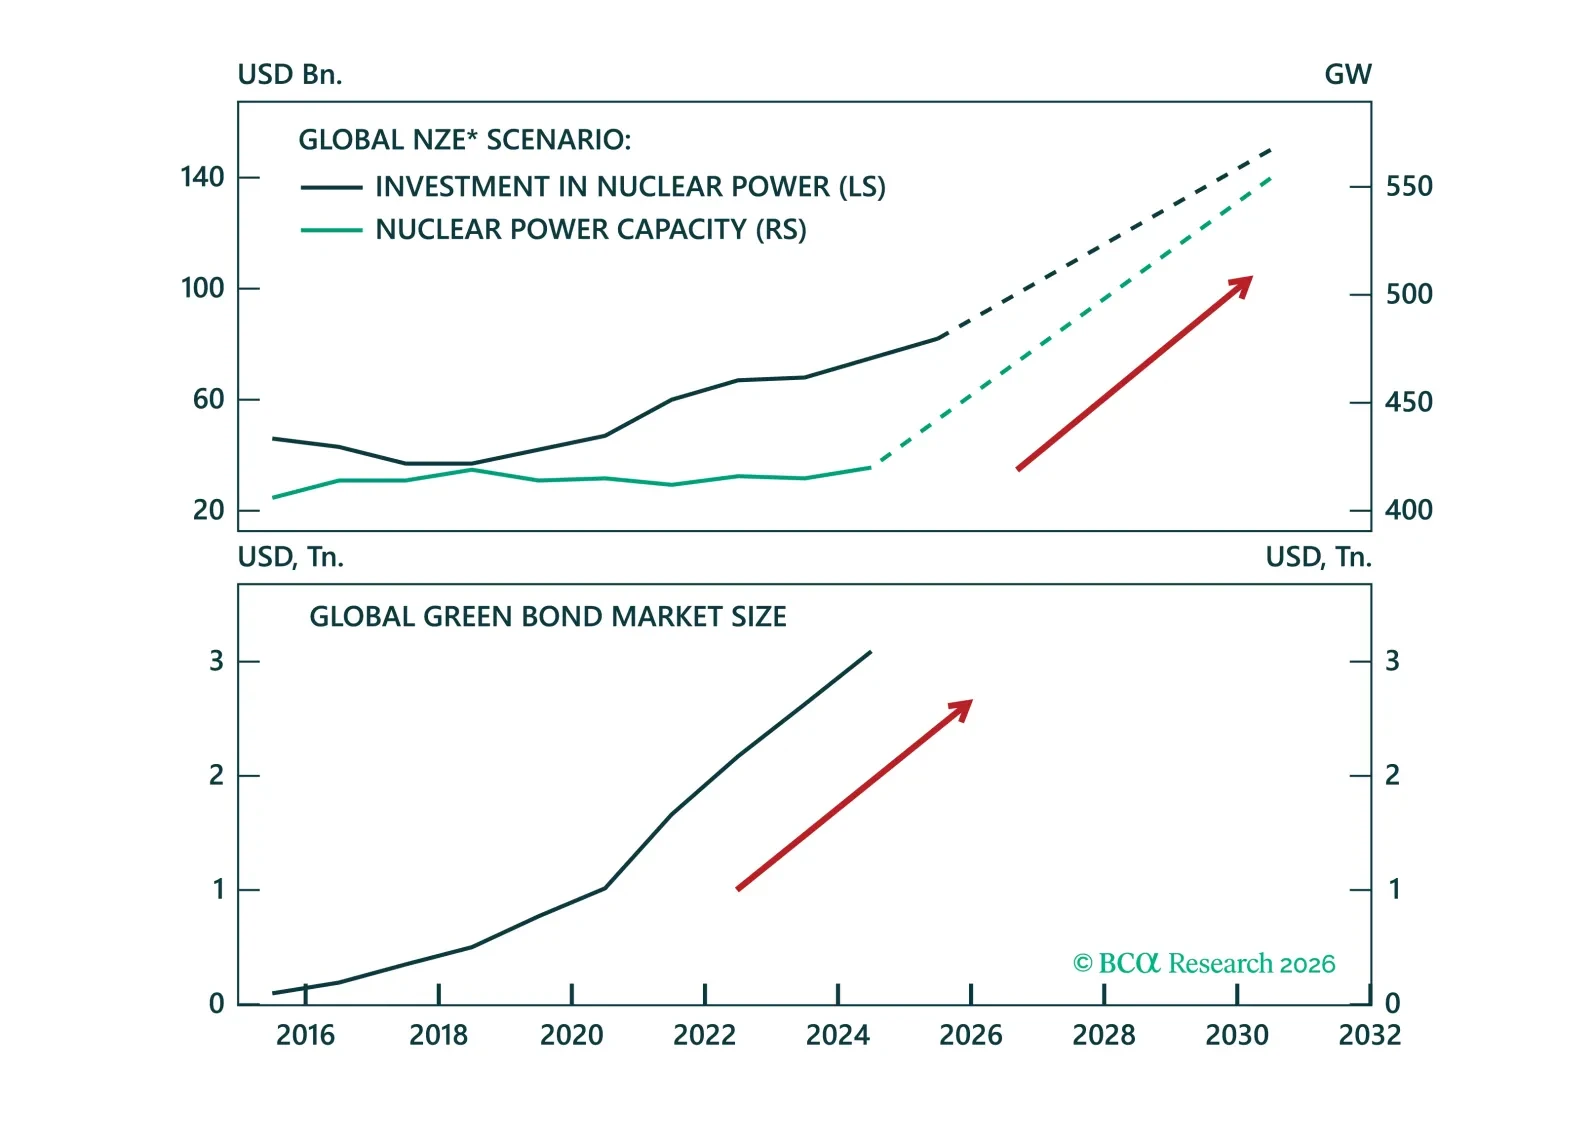

The recent oil price shock reinforces our view that inflation will surprise to the upside during the next few months but fall rapidly in H2 2026.
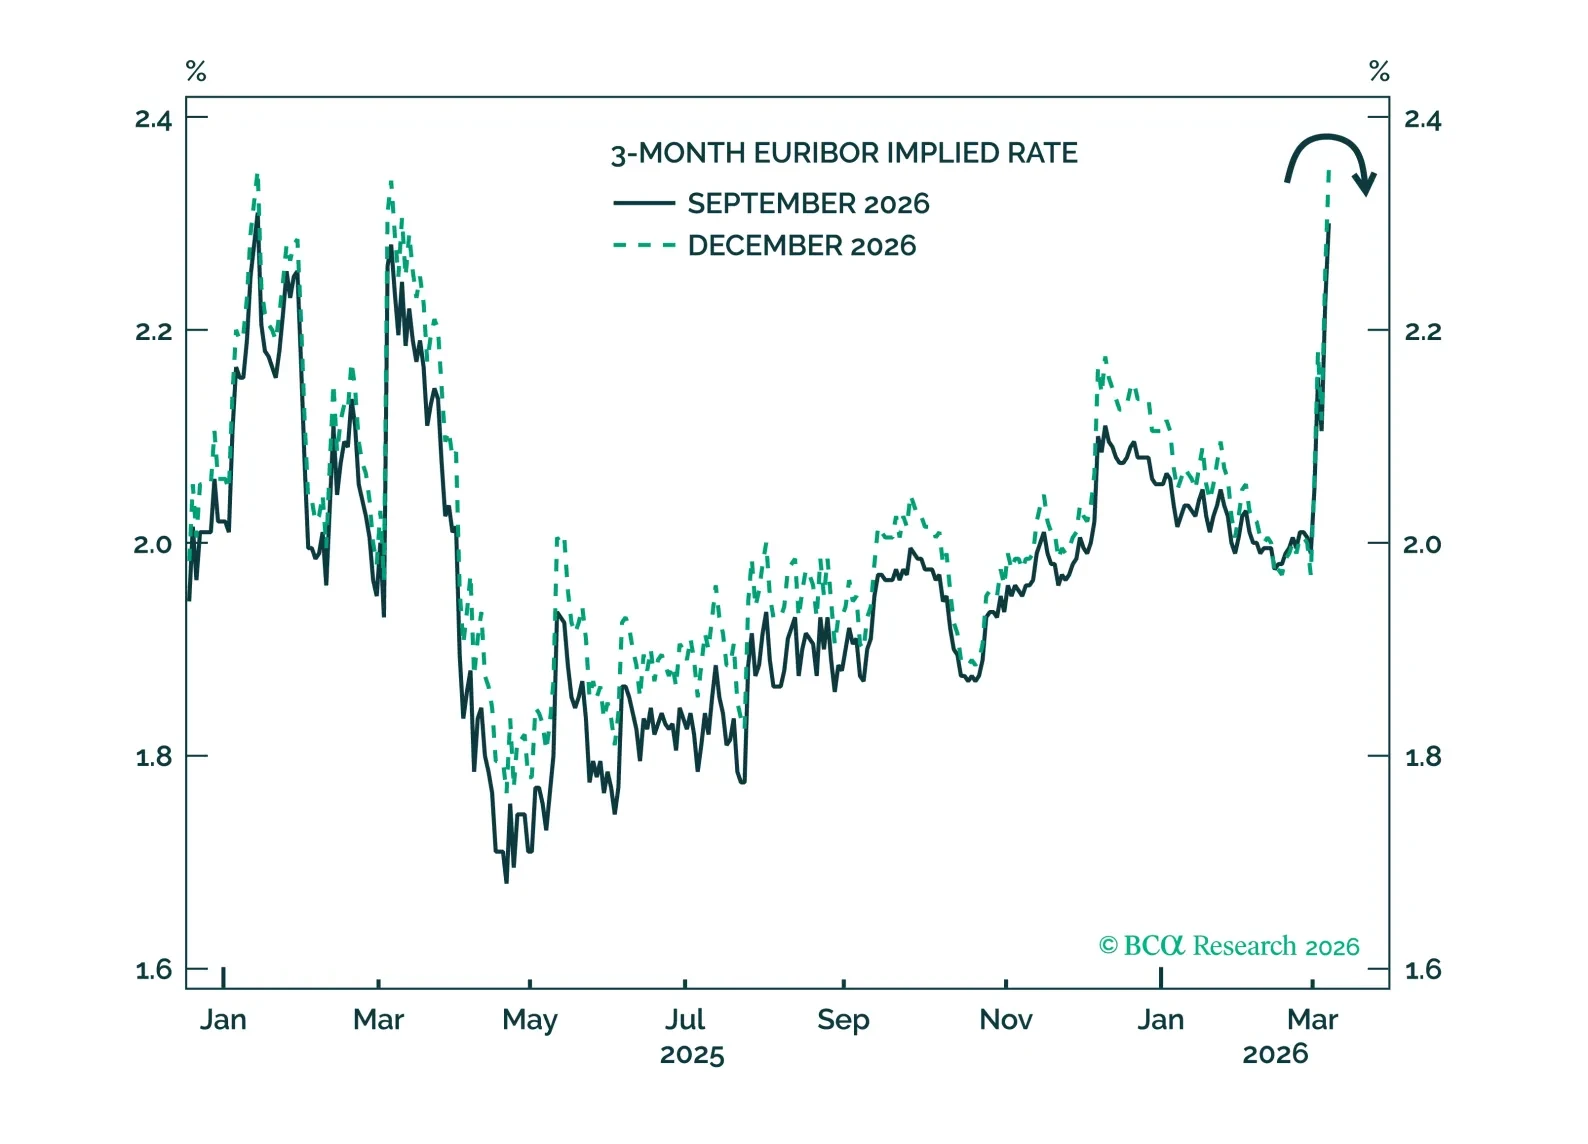
If the 2022 roadmap is any guide, equity markets and cyclical currencies will trough only after confirming that the peak in energy prices is in the rearview mirror. In the very near term, investors should focus on P&L preservation. Reduce exposure to equities, and seek refuge in gold, and inflation-linked bonds (ILBs). Amid a very different demand side than in 2022, today’s supply shock is unlikely to generate lasting inflation, and investors should fade rate-hike odds.

Looking through month-to-month volatility, job growth’s underlying trend is stable and consistent with a flat-to-slightly higher unemployment rate.