Sectors
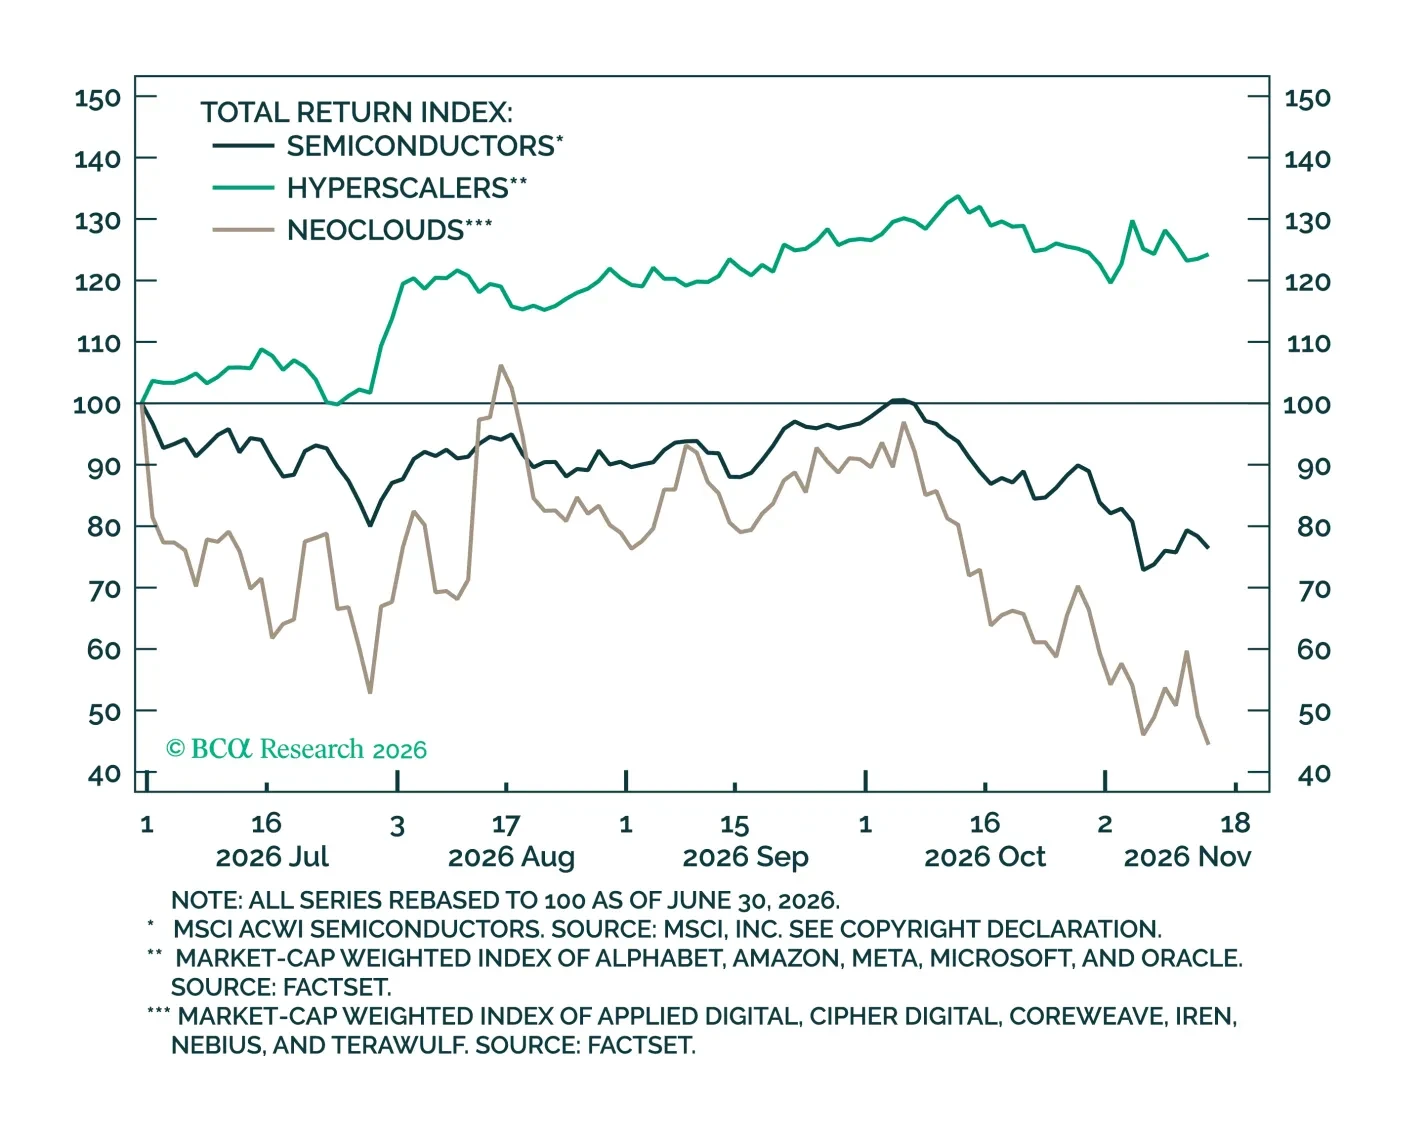
Expect Democrats to heed voters and pursue policies to reduce prices. The ousting of Huang is a blow to the neoclouds but a gift to frontier labs and hyperscalers. Downgrade Health Care and upgrade Consumer Discretionary. Upgrade Europe. Continue to favor the hyperscalers within the AI universe.
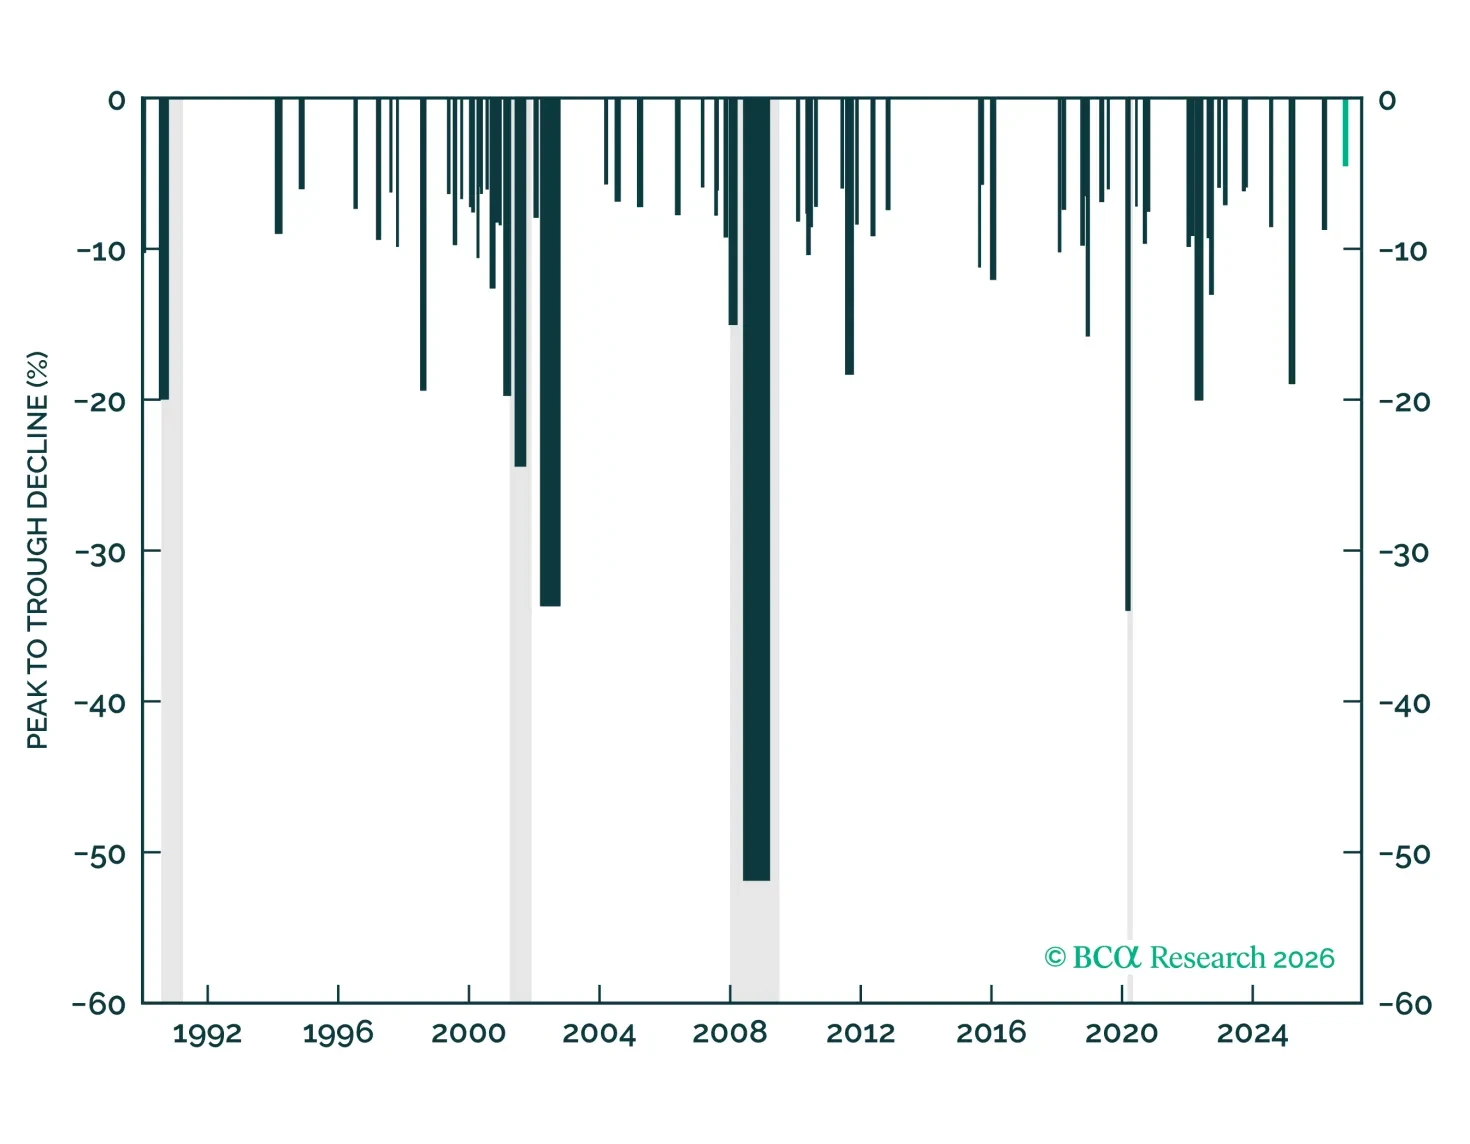
AI capex concerns have pushed the S&P 500 to the brink of a drawdown. But the cycle remains strong, drawdowns rarely last long, and Tech valuations had already compressed. And while Democratic governors now oversee about 80% of the data-center pipeline, a blue governor alone is not necessarily a build-out moratorium.
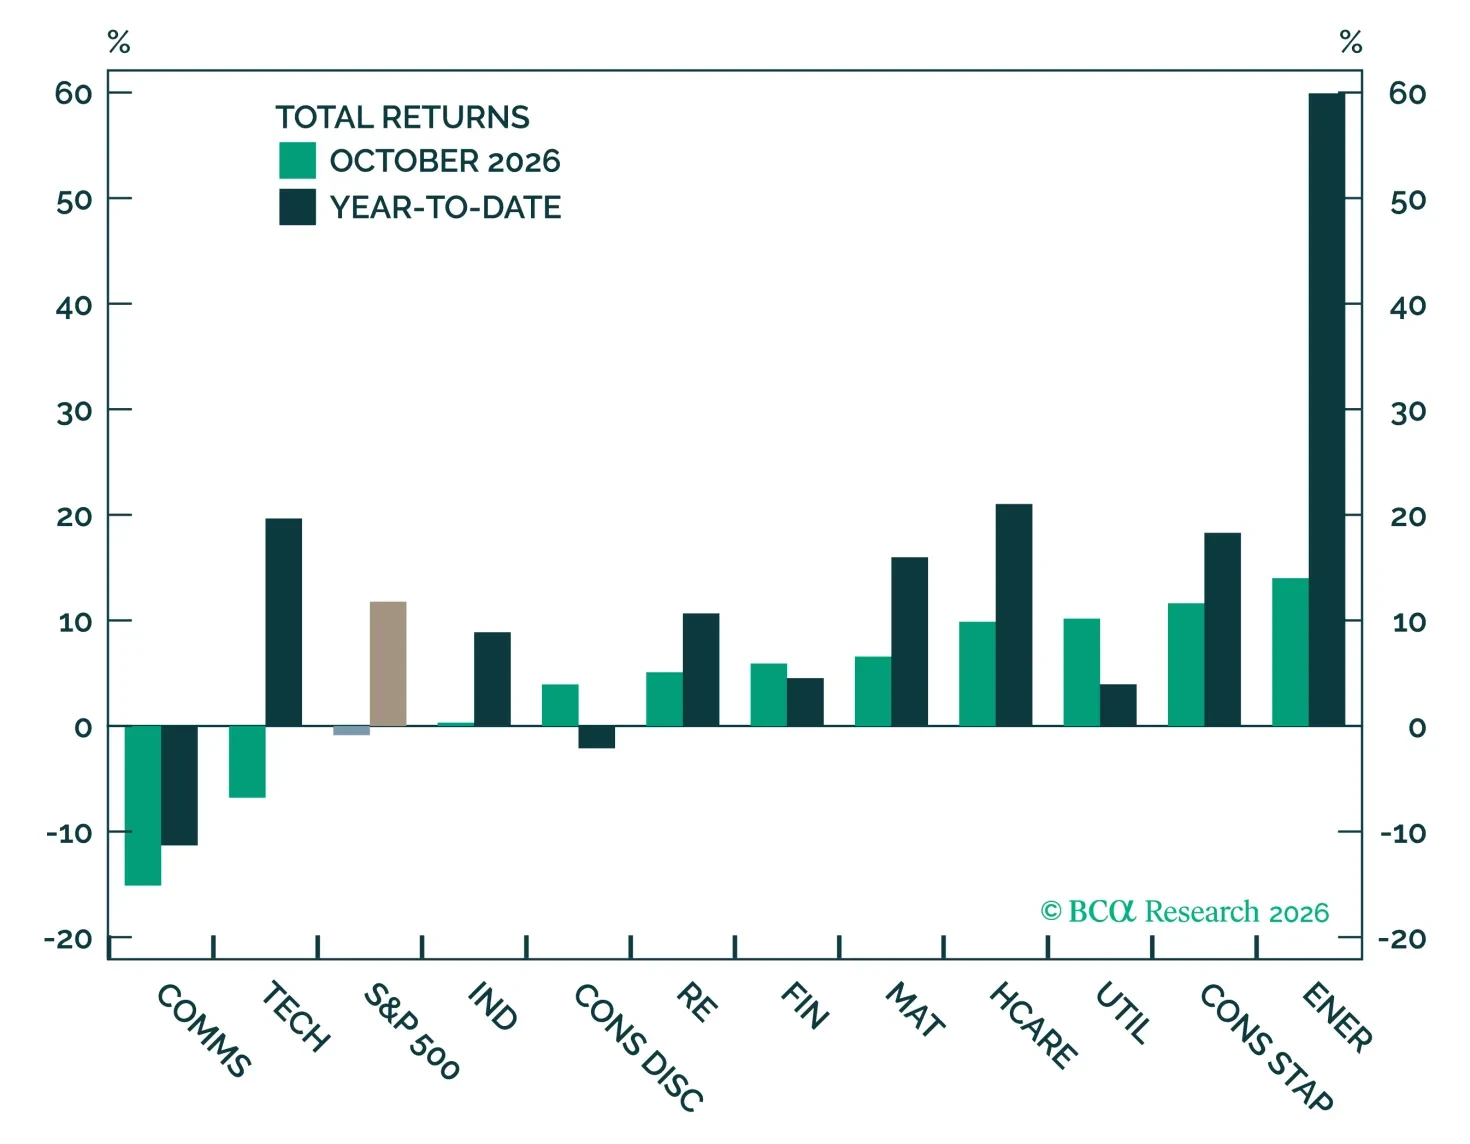
October saw a 0.9% decline in the S&P 500, dragged lower by Communication Services (-15.1%) and Information Technology (-6.8%). All other sectors delivered positive returns, led by traditional defensives – Health Care (+9.9%), Utilities (+10.2%), Consumer Staples (+11.6%) – and Energy (+14.0%). Although our overweight Tech call surrendered some performance during the month, IT has still gained 37% since the view was initiated on March 30, outpacing the S&P 500’s 20% advance.
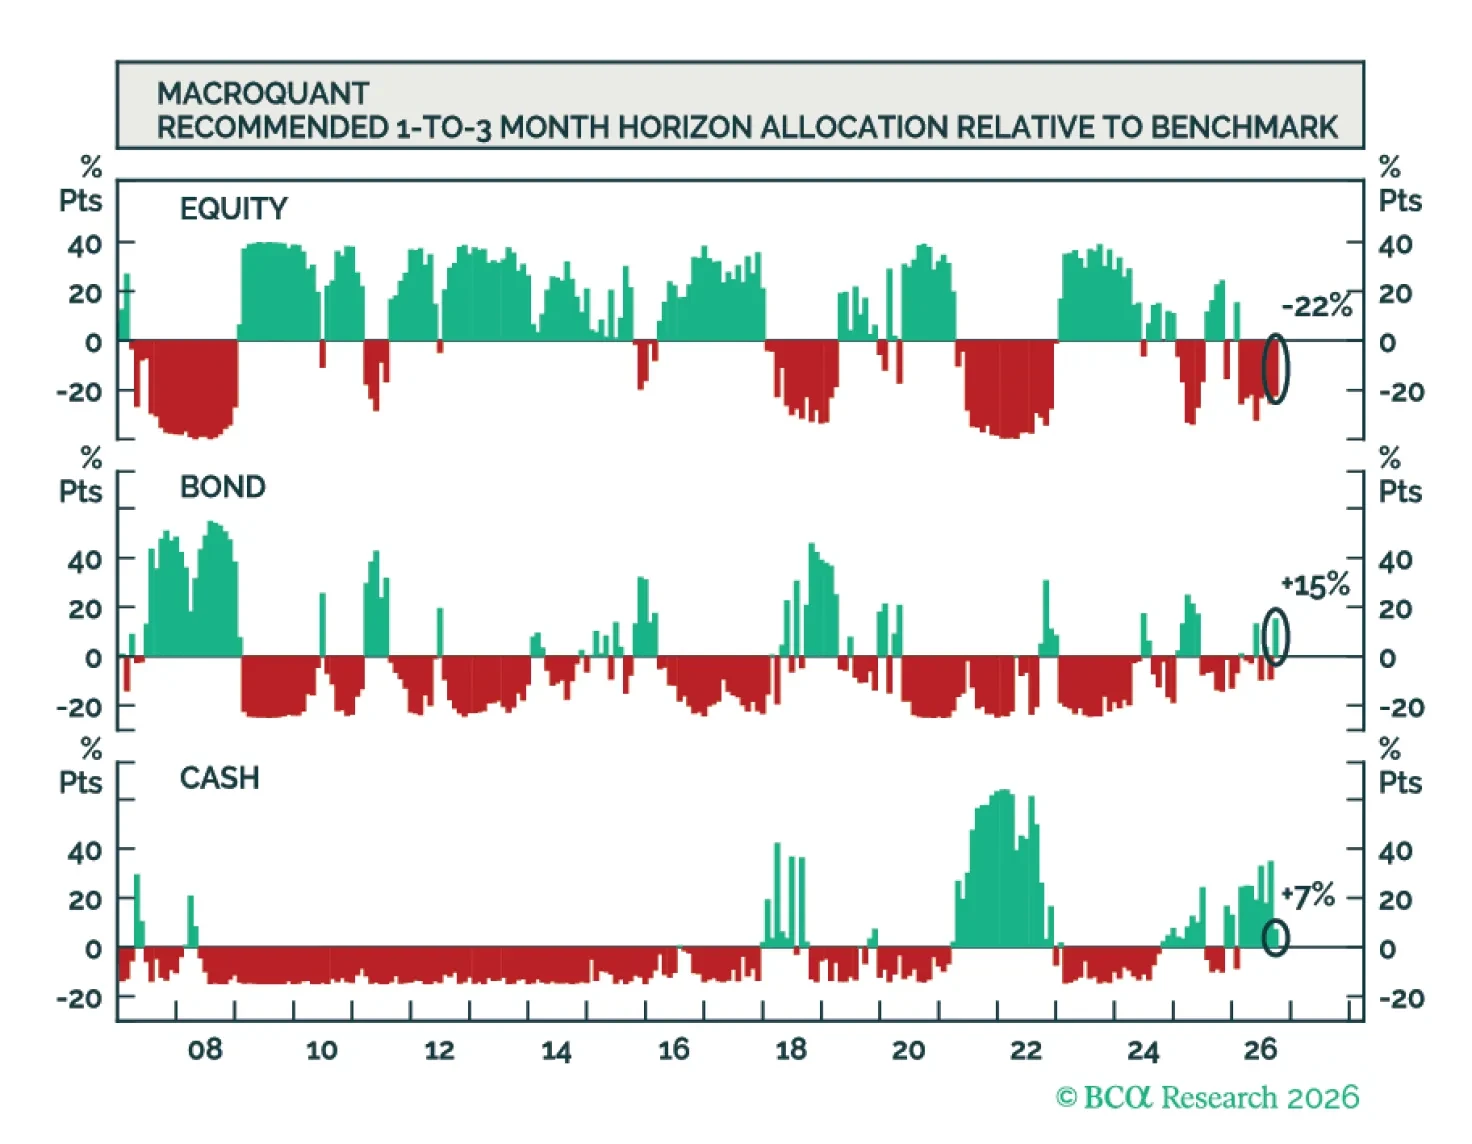
MacroQuant recommends a slight underweight to equities and an overweight to bonds and cash. The model is bullish on the US dollar, negative on gold, very negative on copper, and neutral on oil.
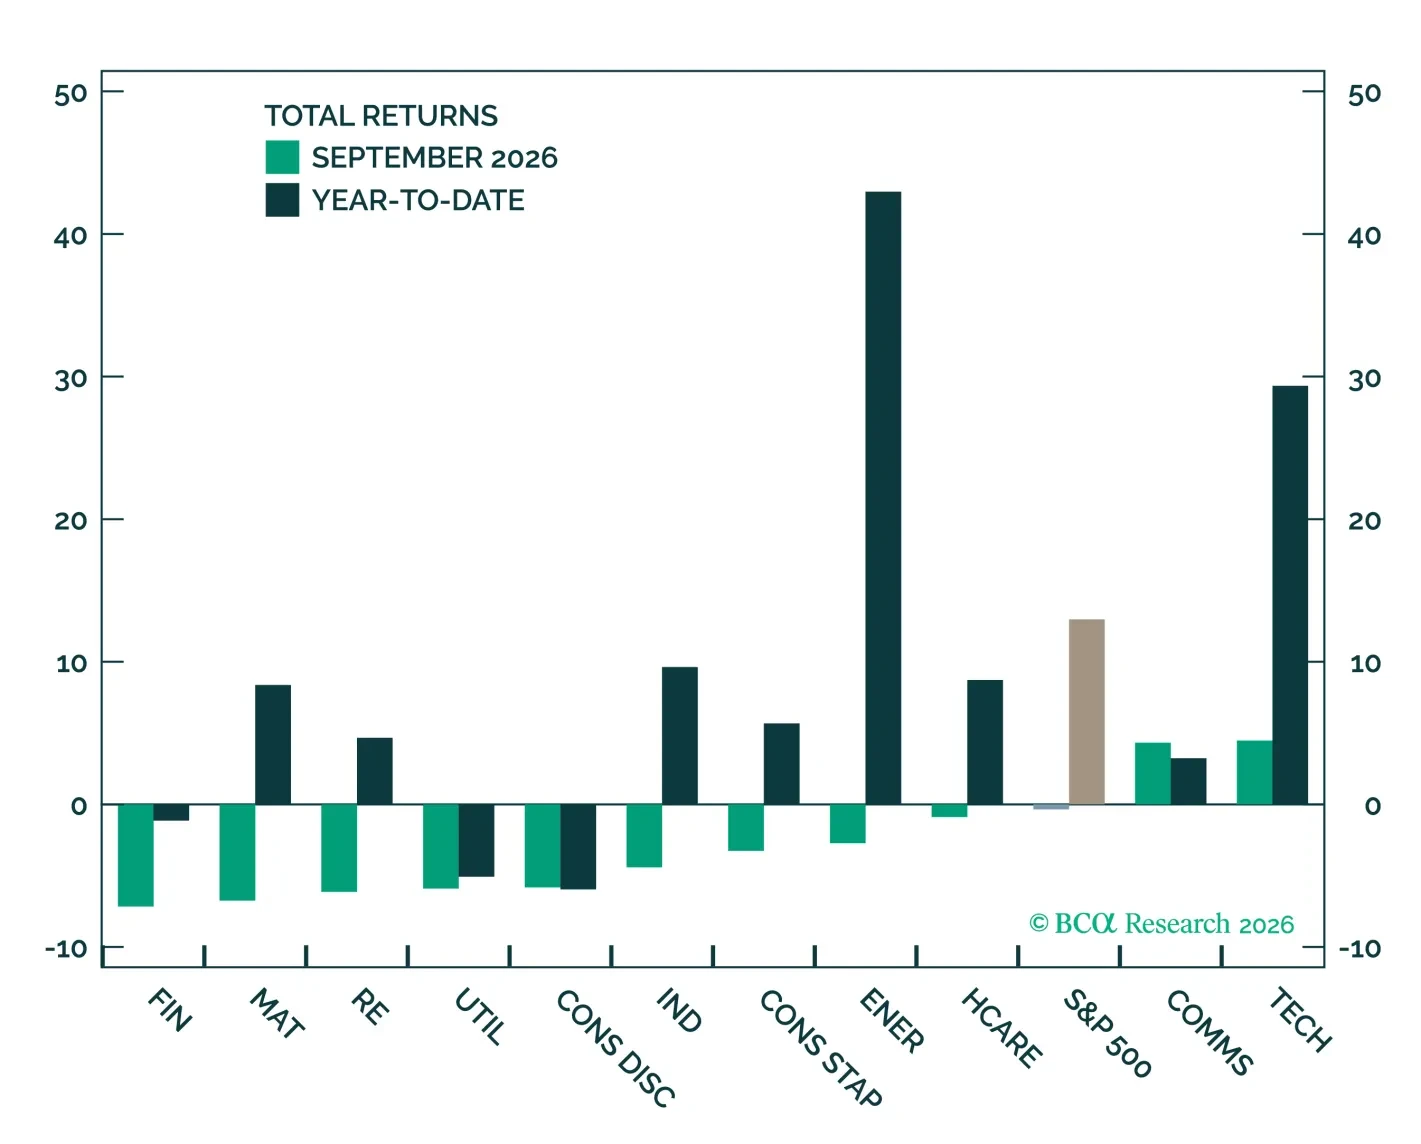
As the 10-year yield surged in September, the S&P 500 slipped but only by 0.3%, supported by Technology and Communication Services. We see upside into year end, with bond yields remaining the key risk.
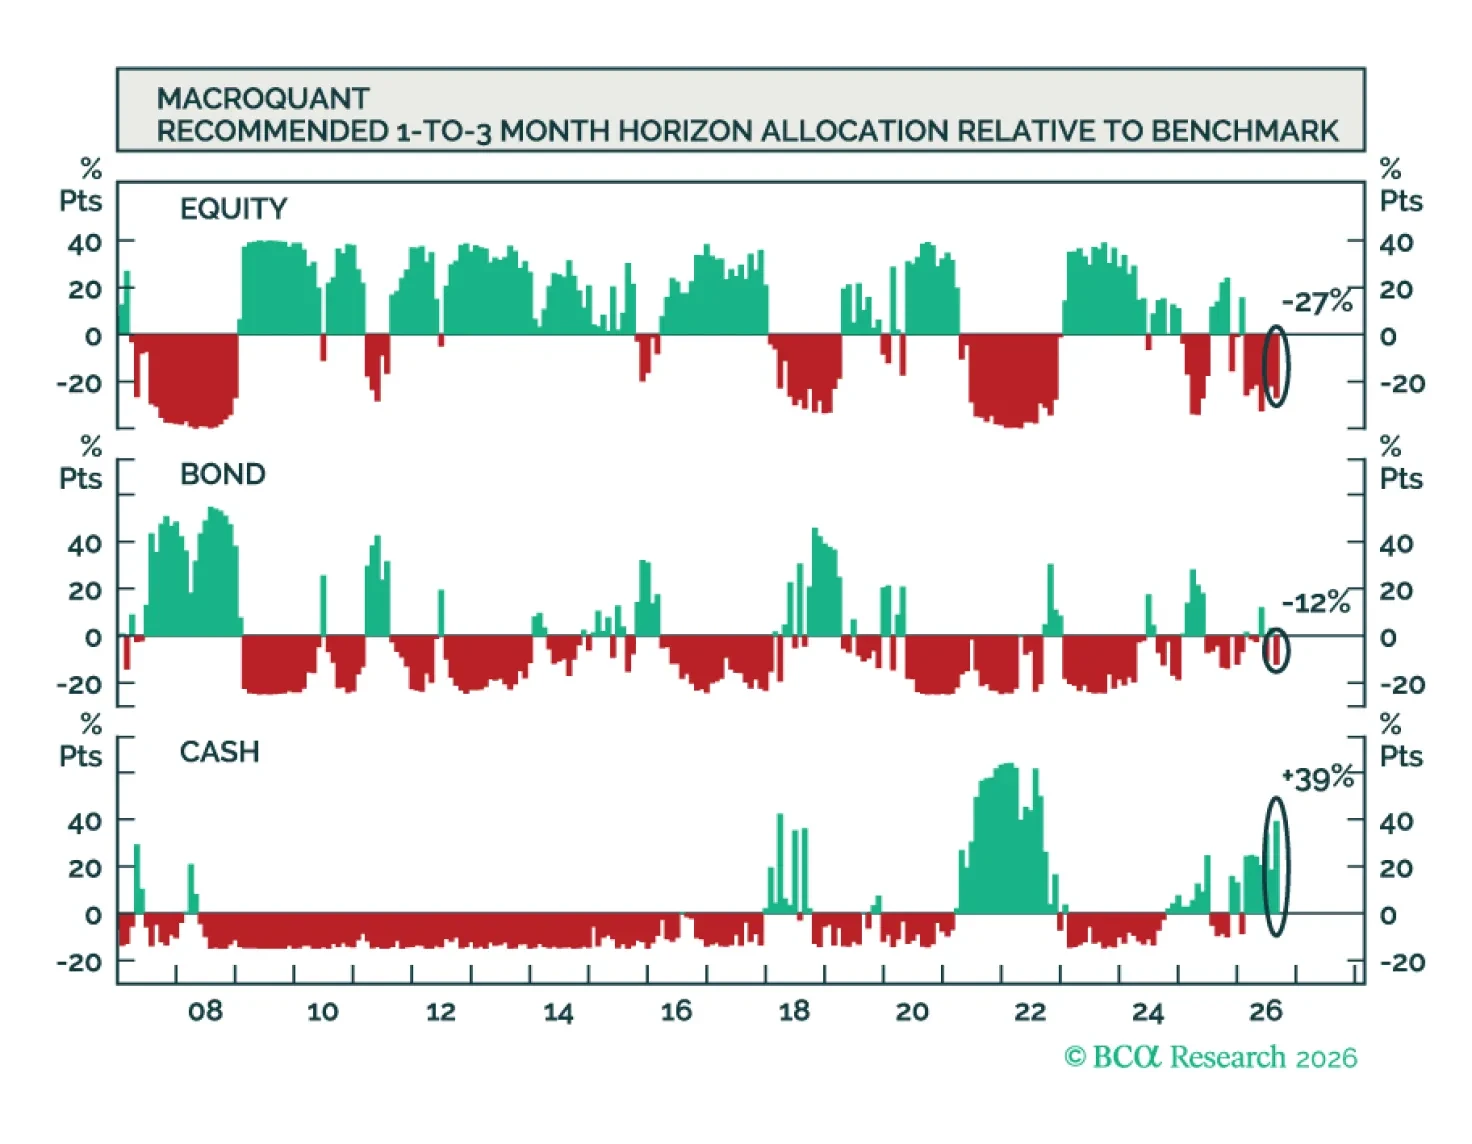
MacroQuant recommends an underweight to equities and bonds, counterbalanced by a significant overweight to cash. The model is very bullish on the US dollar, slightly negative on gold and copper, and positive on oil.
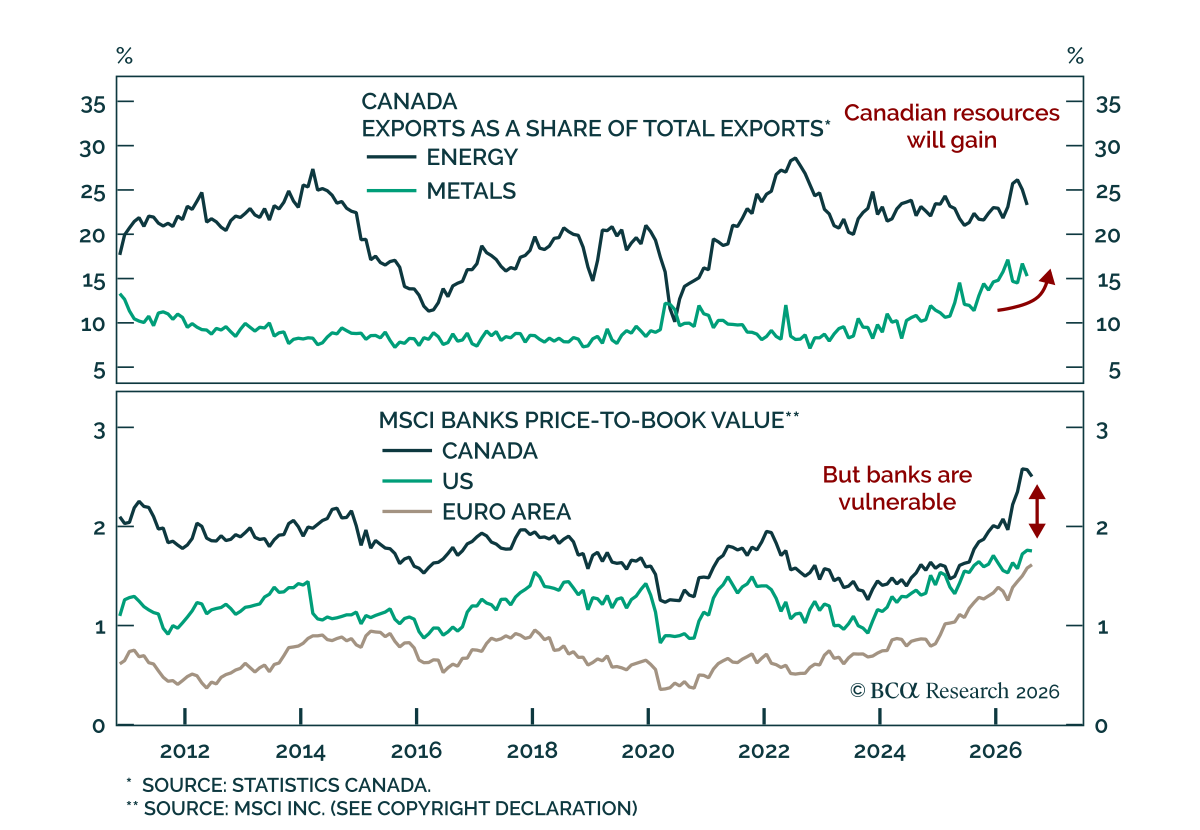
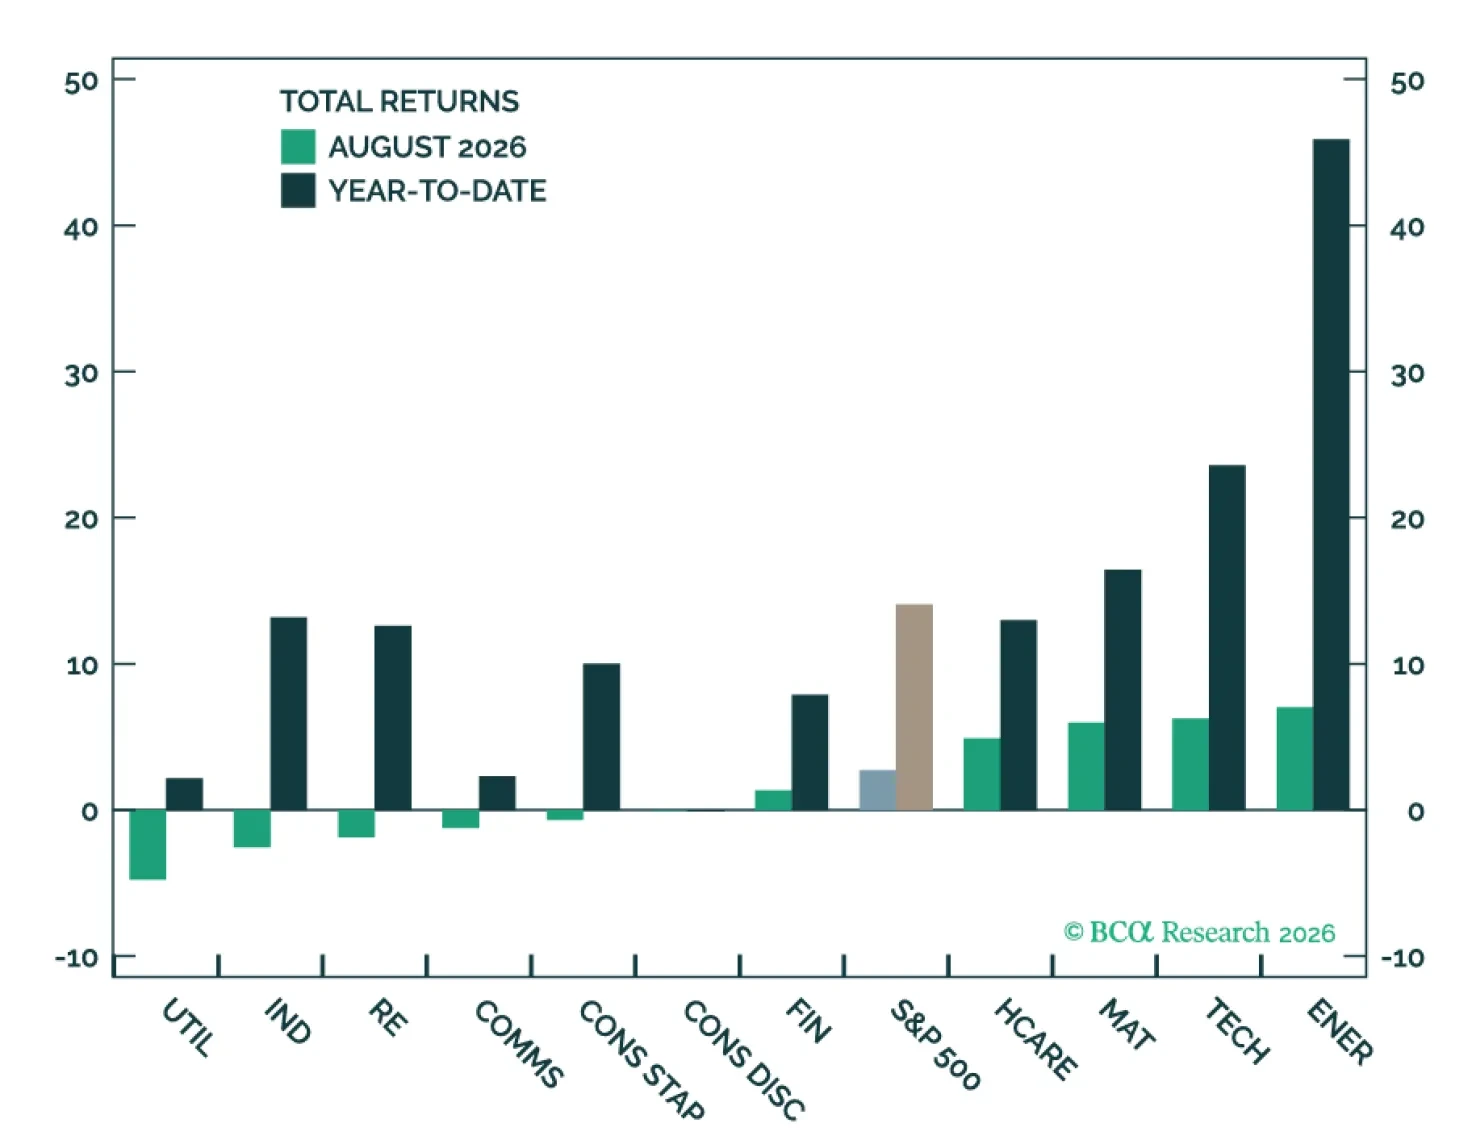
Strong second quarter earnings suggest that the AI story is intact. Buoyed in part by this strength, tech stocks have recoupled with healthy fundamentals after a late-July swoon, posting solid August gains. We continue to see upside for the S&P 500, favoring the cyclical and AI exposure of tech, materials, and industrials. But rising bond yields remain the dominant headwind.
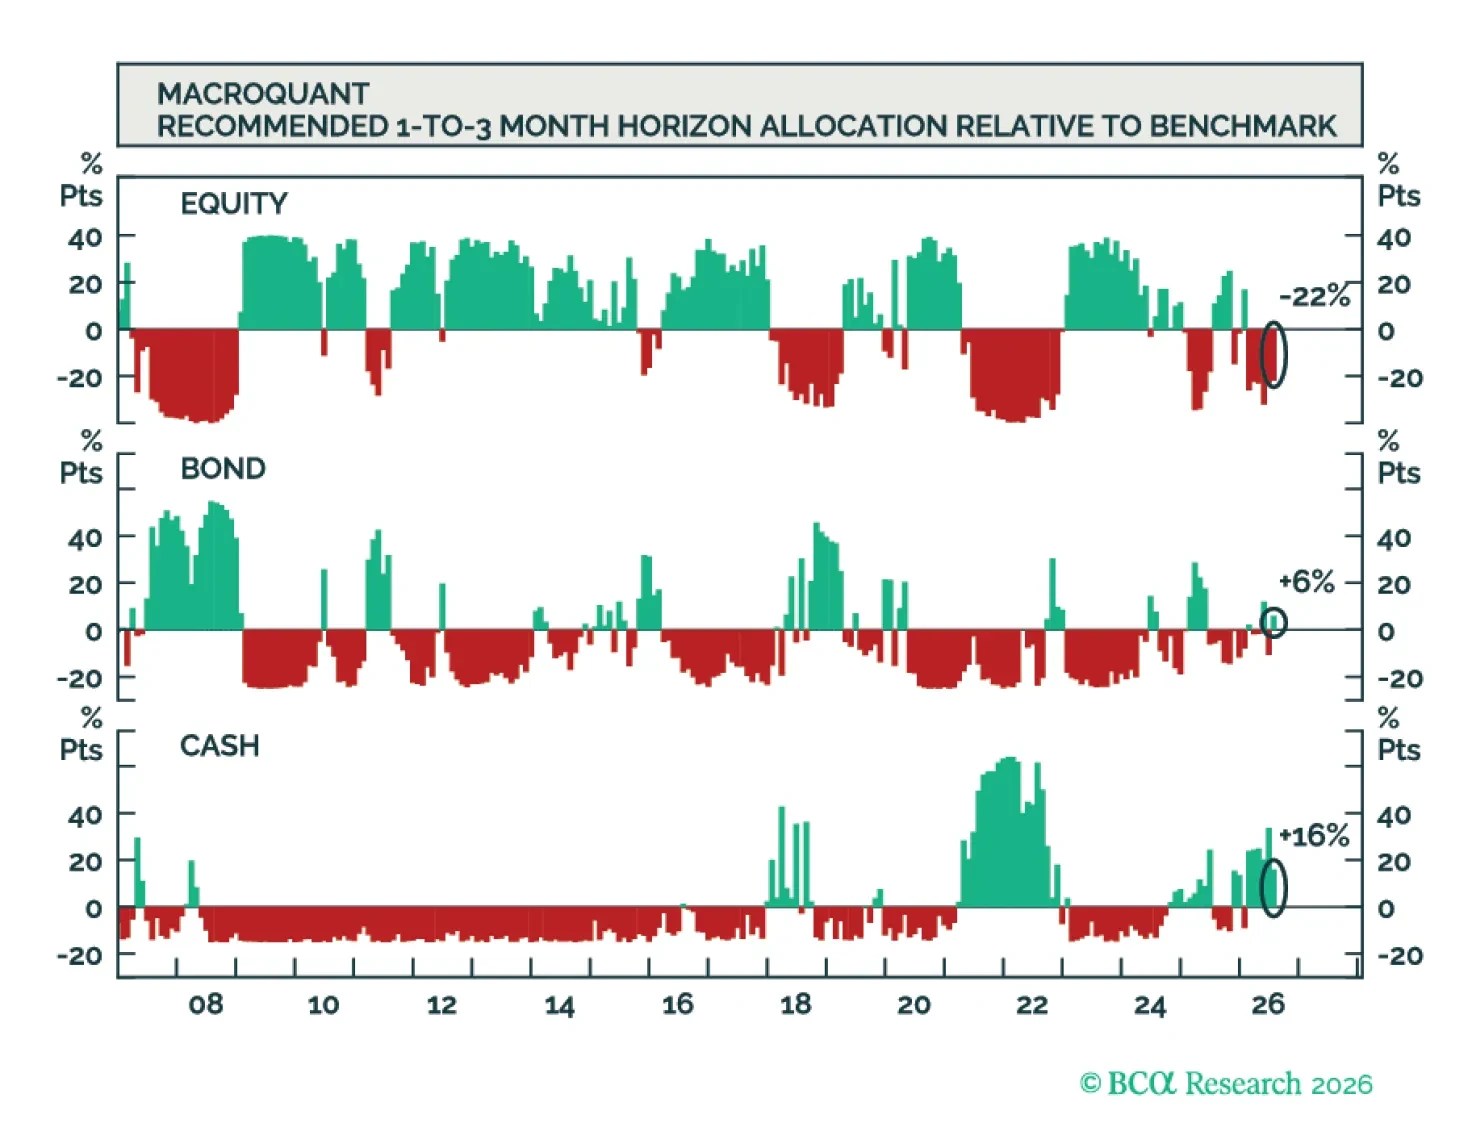
MacroQuant recommends a slight underweight position in equities, counterbalanced by a slight overweight to bonds, and a significant overweight to cash. The model is positive on the US dollar, modestly negative on gold, and bullish on copper and oil.
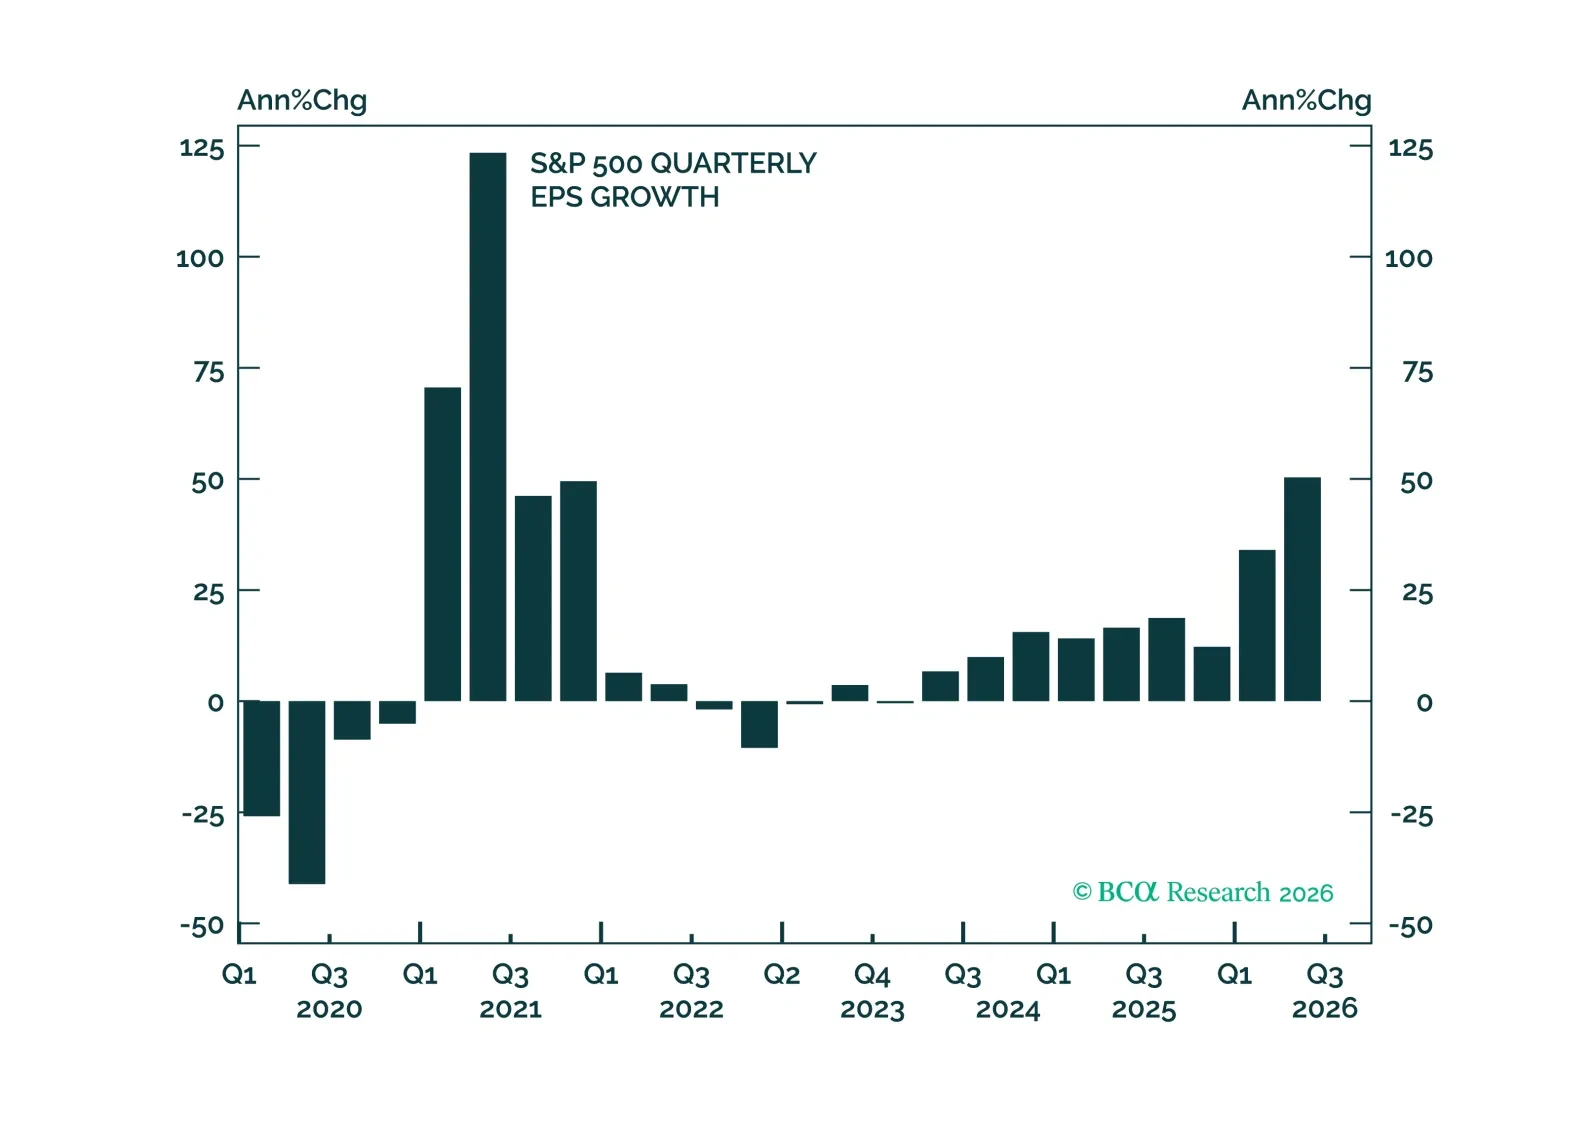
Q2 earnings confirm broad-based strength, but the bond market remains the key risk to equity multiples given today's positive stock/bond correlation regime. We close our tactical GDX long for a 16% gain, though we continue to view goldminers as a valuable structural hedge.