Inflation
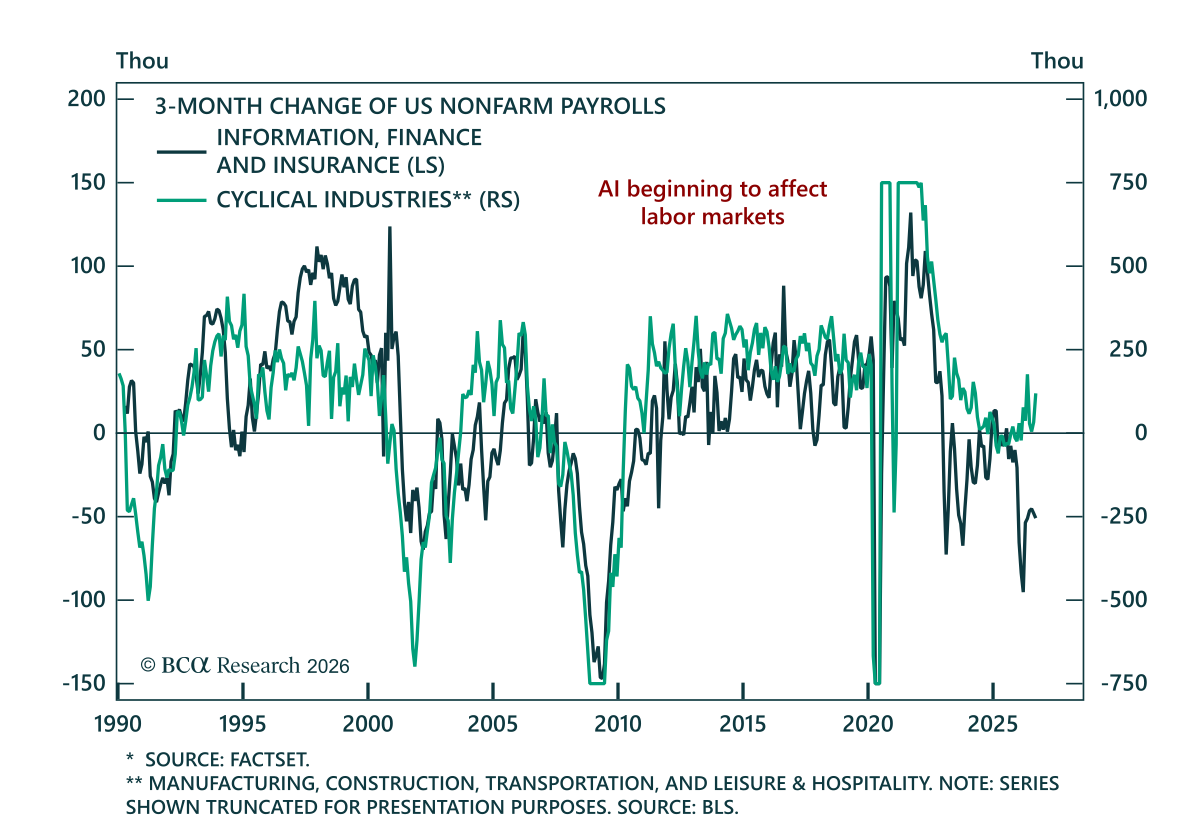
Our Portfolio Construction strategists remain bullish on risk assets but express that view through barbells across the portfolio. October looked cataclysmic from the headlines, with neocloud debt spreads spiking and Alphabet suffering its worst one-day loss…
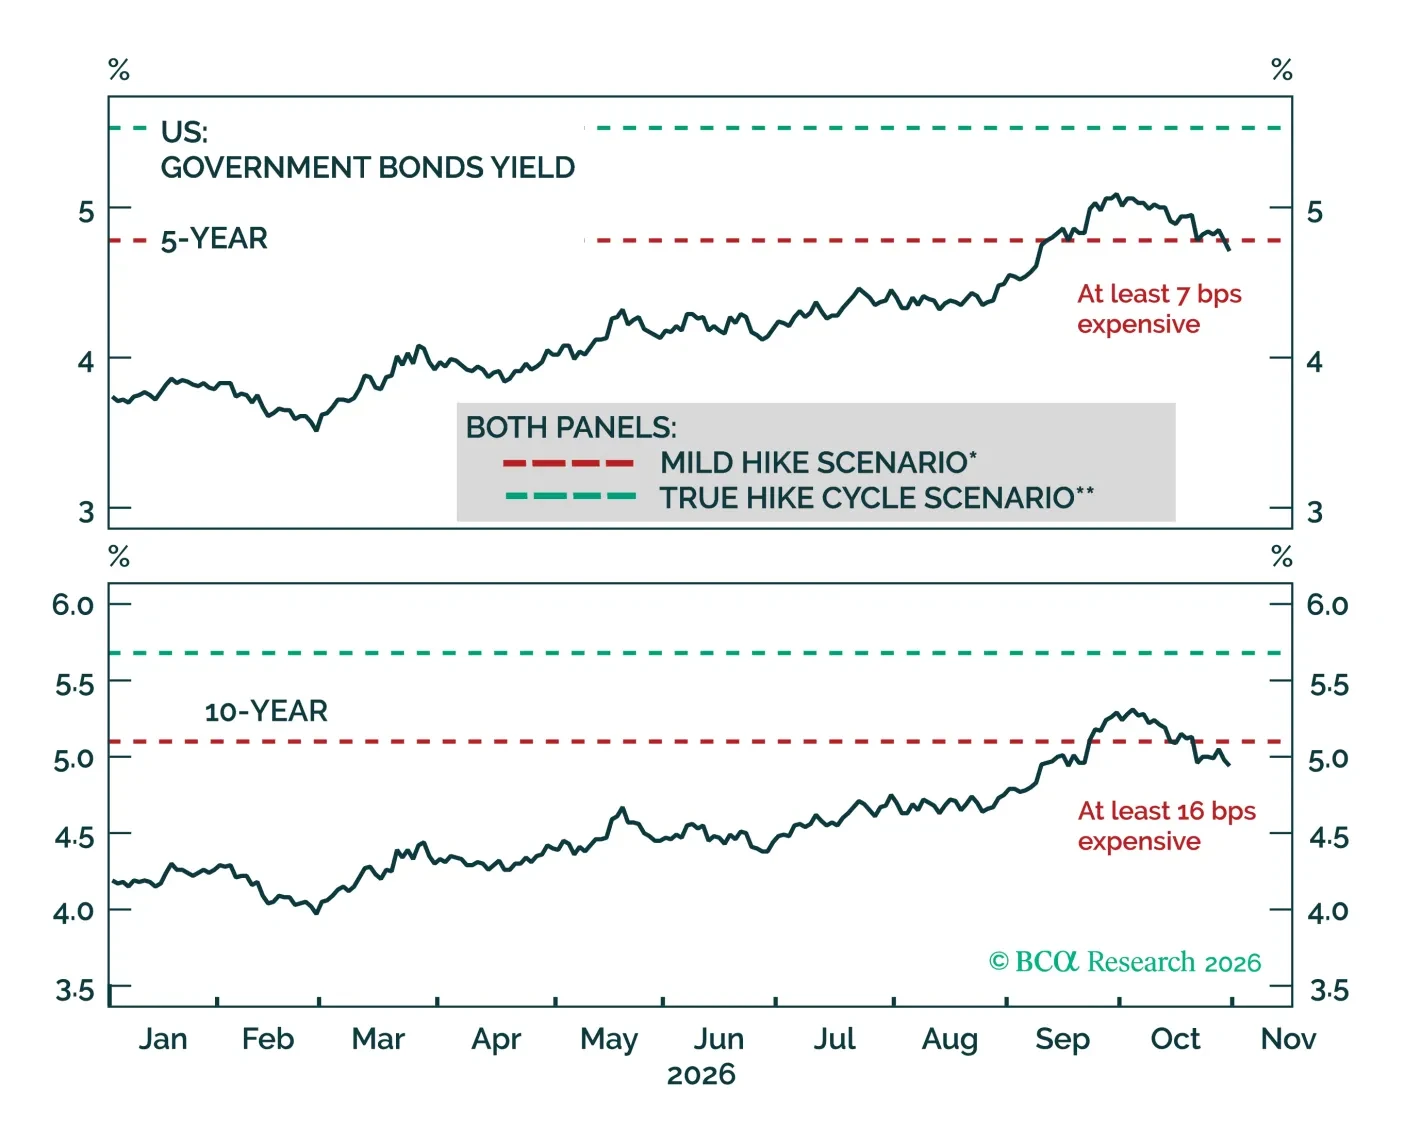
US Treasury yields have fallen below our fair value estimate as investors rotated out of AI equities and into fixed income. We lay out why near-term inflation risks argue for a rebound, and the tactical trades we initiate to position for it.
Despite October’s AI selloff, indices remain resilient thanks to historically high dispersion. We remain bullish, but with barbells across the portfolio. Hedge equity with equity: Overweight Technology and Healthcare. Remain overweight high yield. Downgrade linkers and upgrade nominal bonds. Upgrade tail risk protection to overweight as a hedge against a resumption of the war.
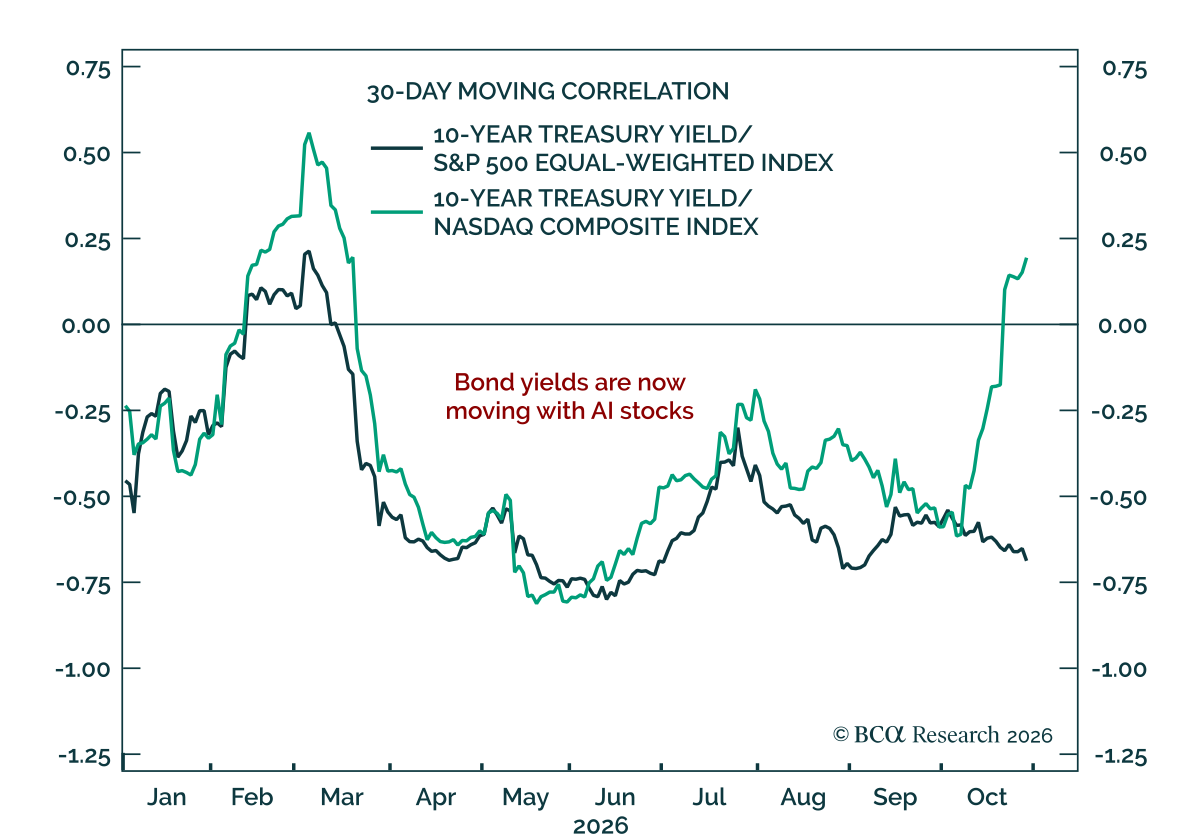
AI equity performance has replaced oil as the main driver of US Treasury yields, setting up a rotation out of AI stocks into the rest of the market. Our Chart Of The Week comes from Ryan Swift, our Chief US Bonds Strategist. Bond yields now track AI stocks…
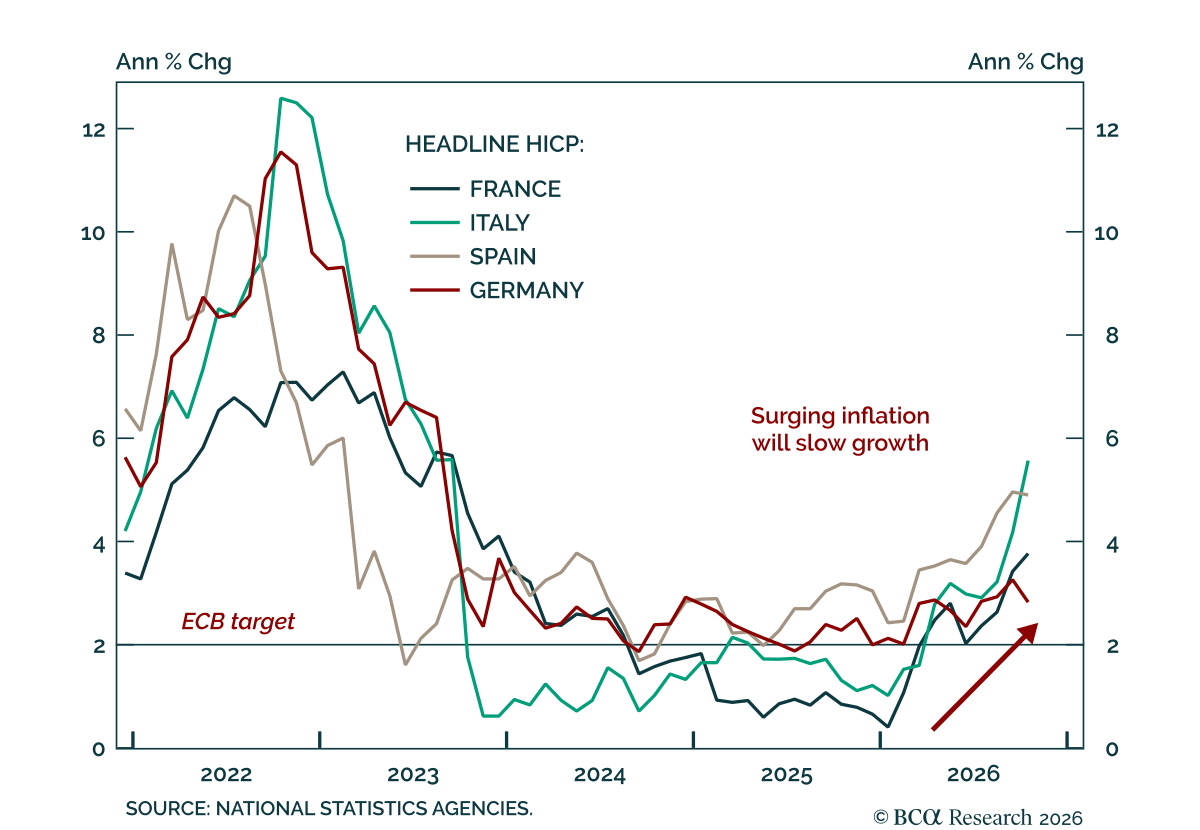
Stronger Q3 euro area growth was likely AI-driven and obscures underlying weakness. Real Q3 euro area GDP came in stronger than consensus expectations. Real GDP grew 1.7% q/q annualized, which was slower than Q2 but meaningfully higher than expectations.…
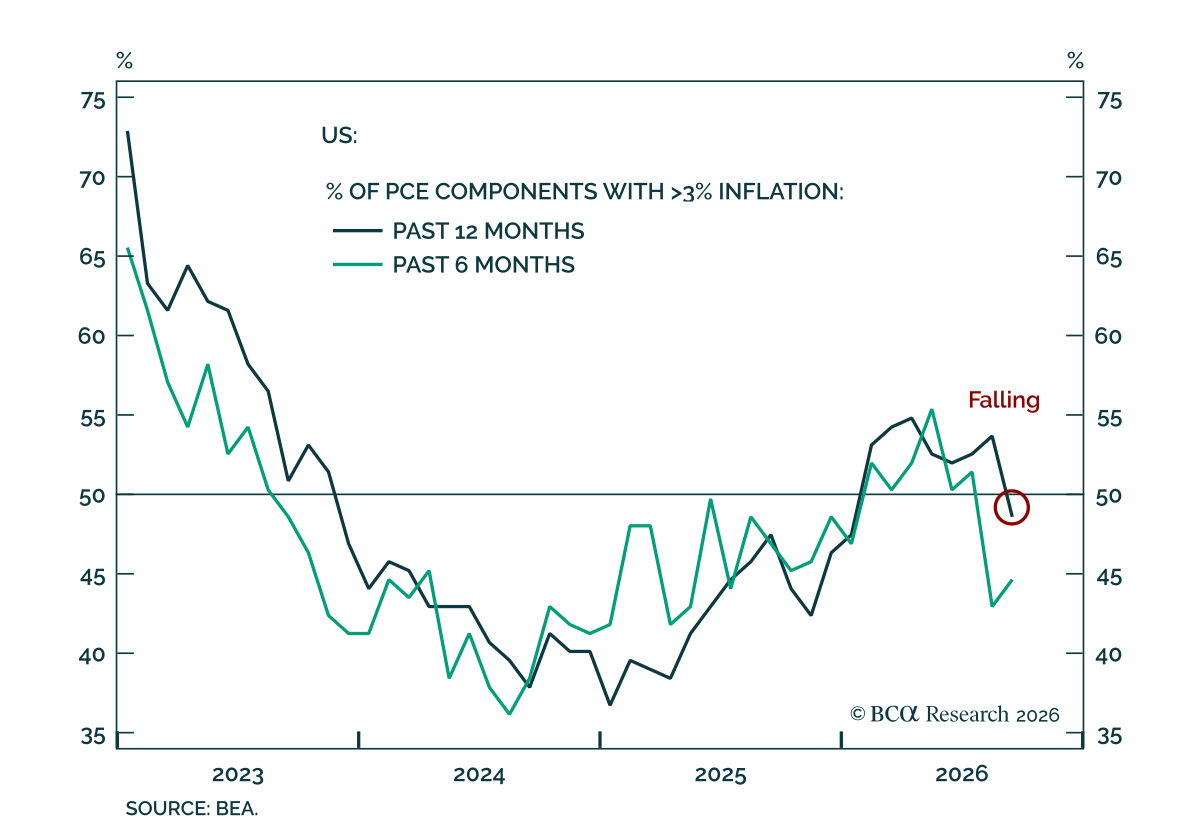
Neither the Q3 GDP release nor the September inflation data will likely shift the Fed away from a quarterly pace of rate hikes. The advance Q3 estimate for US GDP was released on Thursday, alongside the September personal income and outlays report. Annualized…
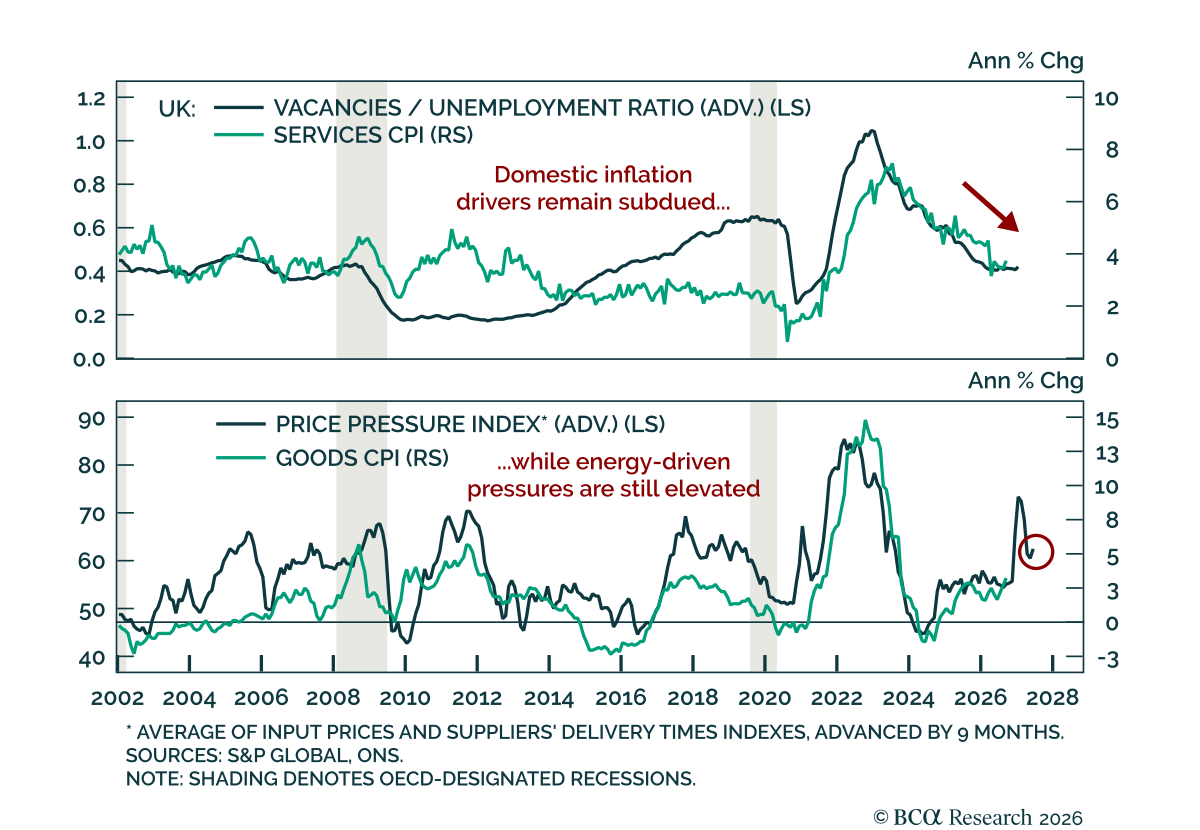
Hot September UK CPI will support BoE hawkishness in the near term, but investors should expect a dovish surprise over the next 12 months. Headline UK CPI rose to 3.5% y/y from 3.1%, which was above consensus. Core CPI rose to 2.8% from 2.6%, in line with…
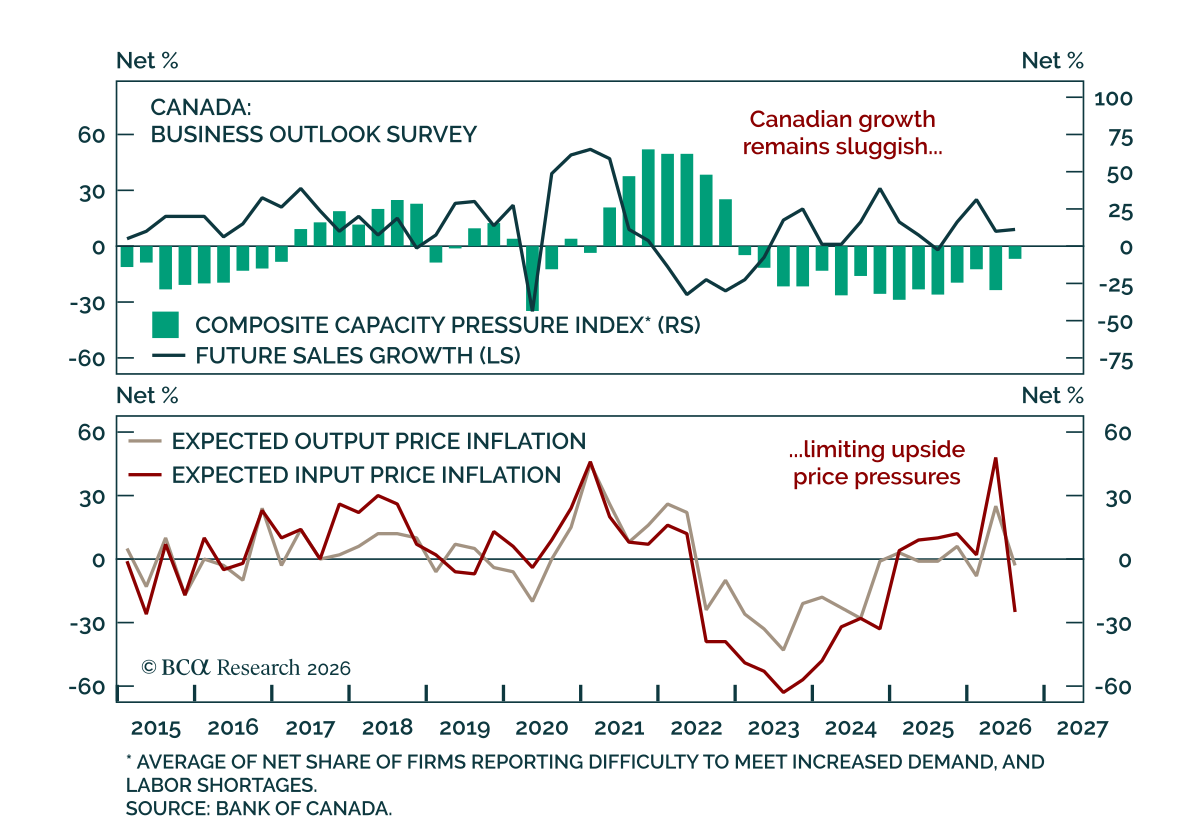
The Bank of Canada’s Q3 Business Outlook Survey improved but still points to weak momentum. The headline BOS indicator edged up to -0.33 from -0.38, and firms’ assessment of business conditions improved. However, most responses predate the August 21 collapse…
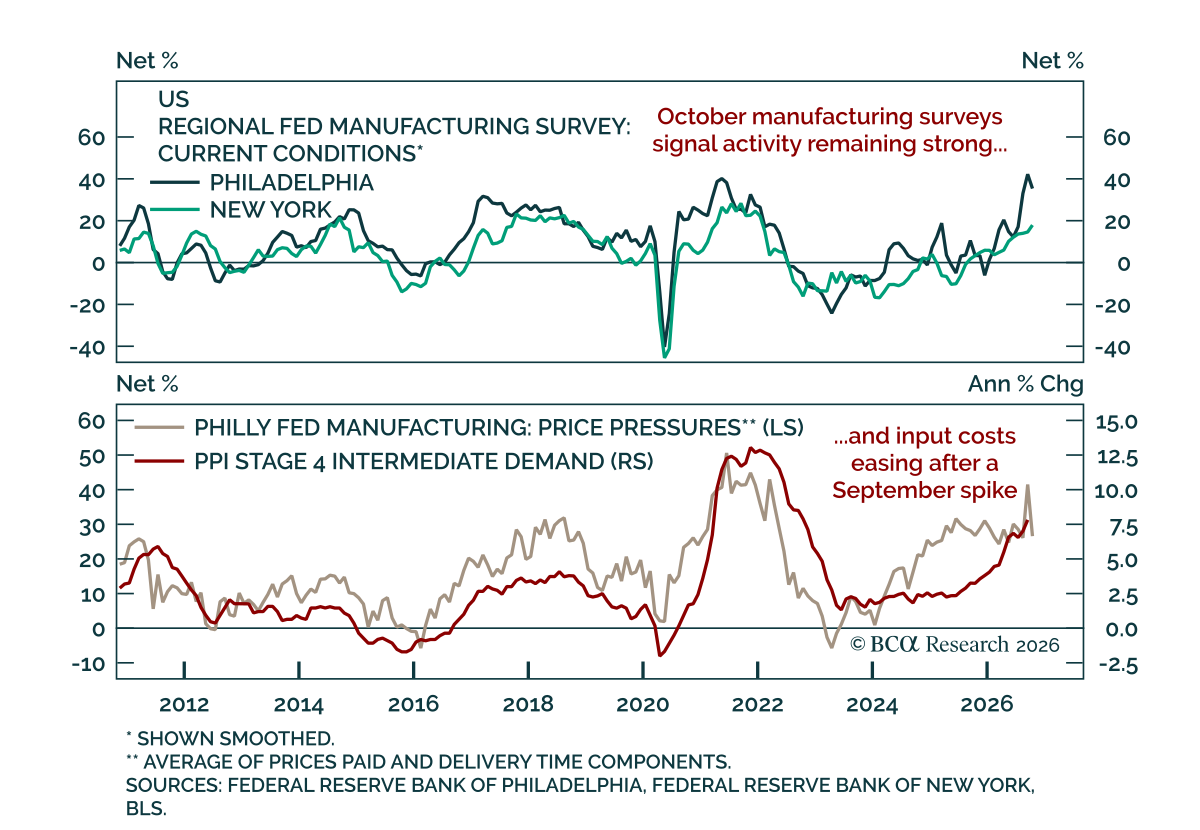
The Philadelphia Fed survey signals that manufacturing momentum remained resilient in October. The headline index fell more than expected, to 20.9 from 37.8, but still points to expansion and sits at a historically high level. New orders, employment, and…
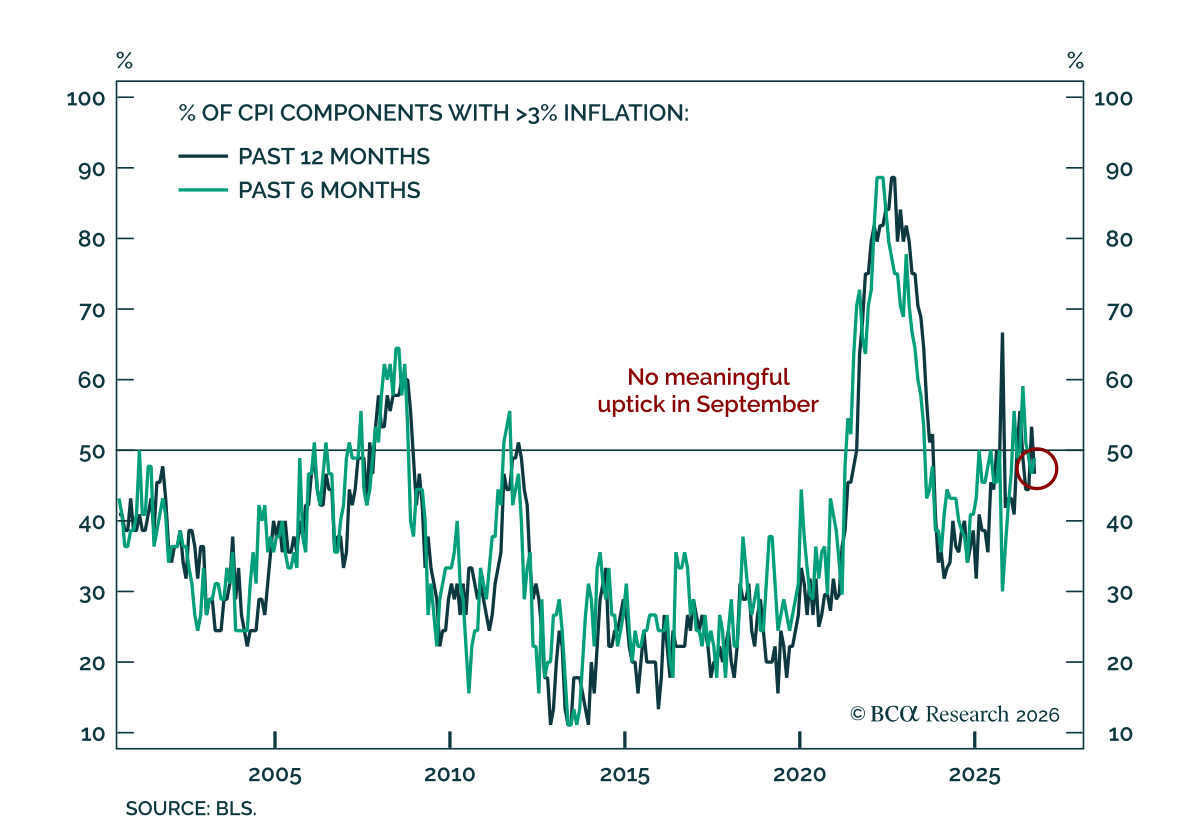
The next Fed hike is still more likely to come in December rather than later this month. Headline CPI in September was in line with consensus at 0.6% m/m, causing the annual rate to rise from 3.4% to 3.7% y/y. Core came in hotter than estimates at 0.3% m/m,…