Global
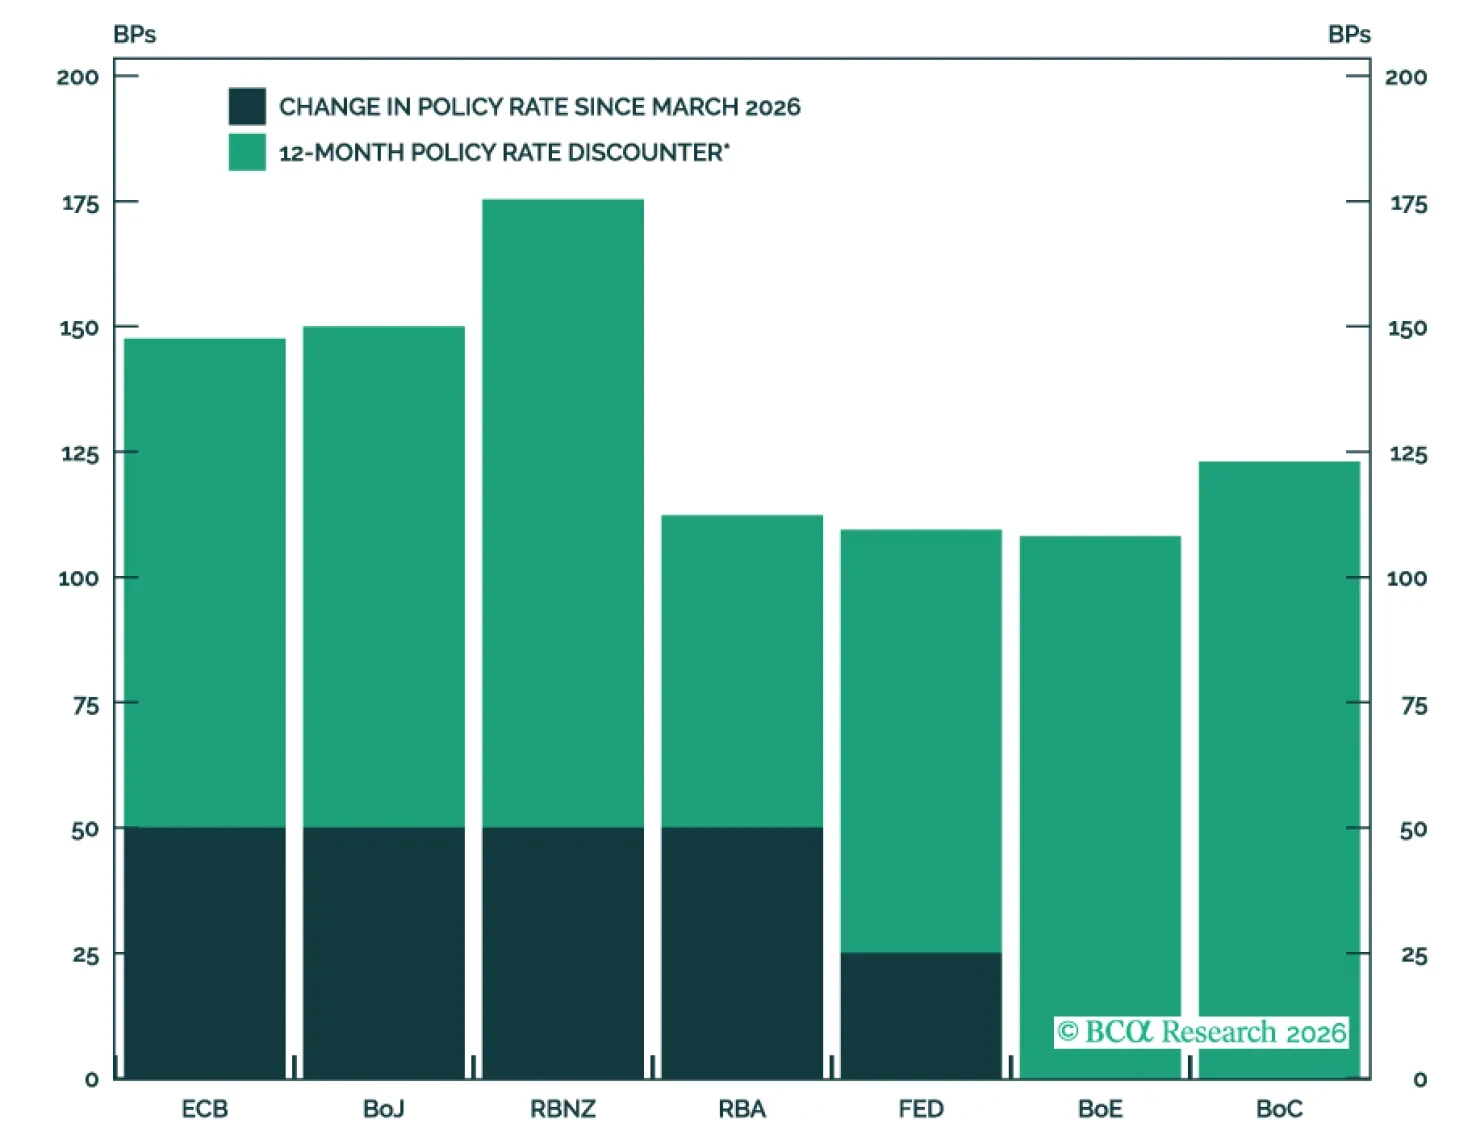
Policy rates are poised to rise across the developed world as central banks are no longer willing to wait out the Iran-US standoff before taking action to combat the inflationary effects of higher oil prices. Outside of Japan, however, we do not think central banks will hike as much as markets expect.
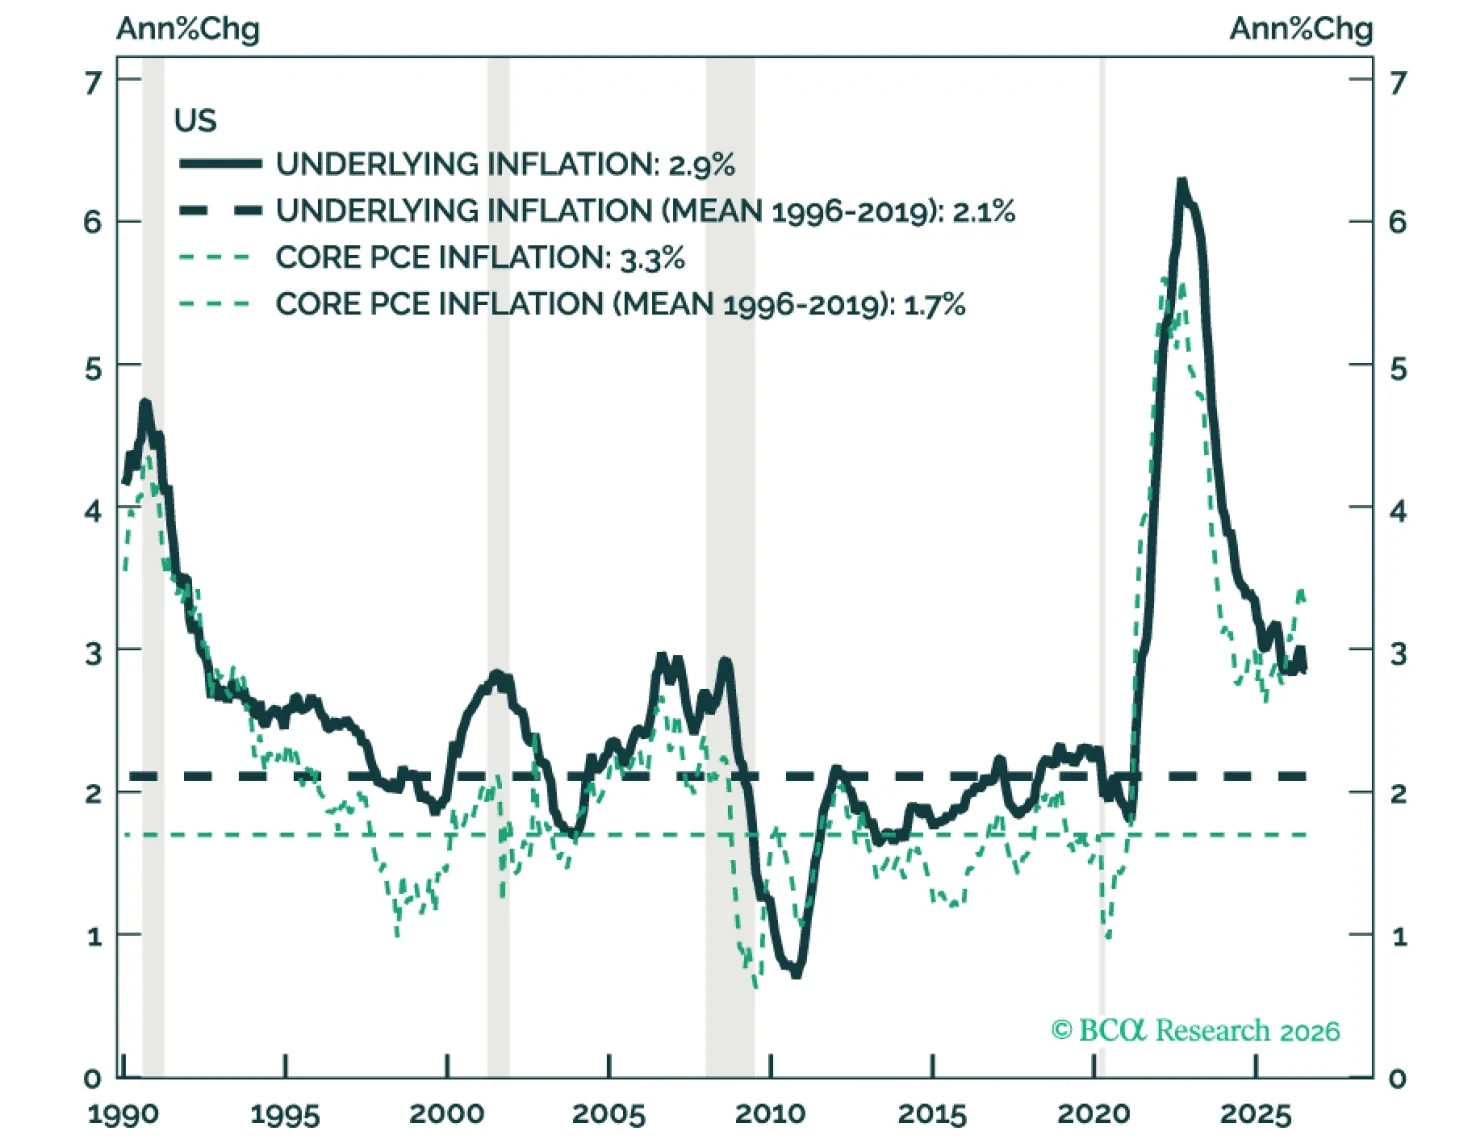
Inflation, not valuation, is the real threat to this bull market. This four-report series lays out where BCA's strategists agree, where they don't, and what to watch for next.
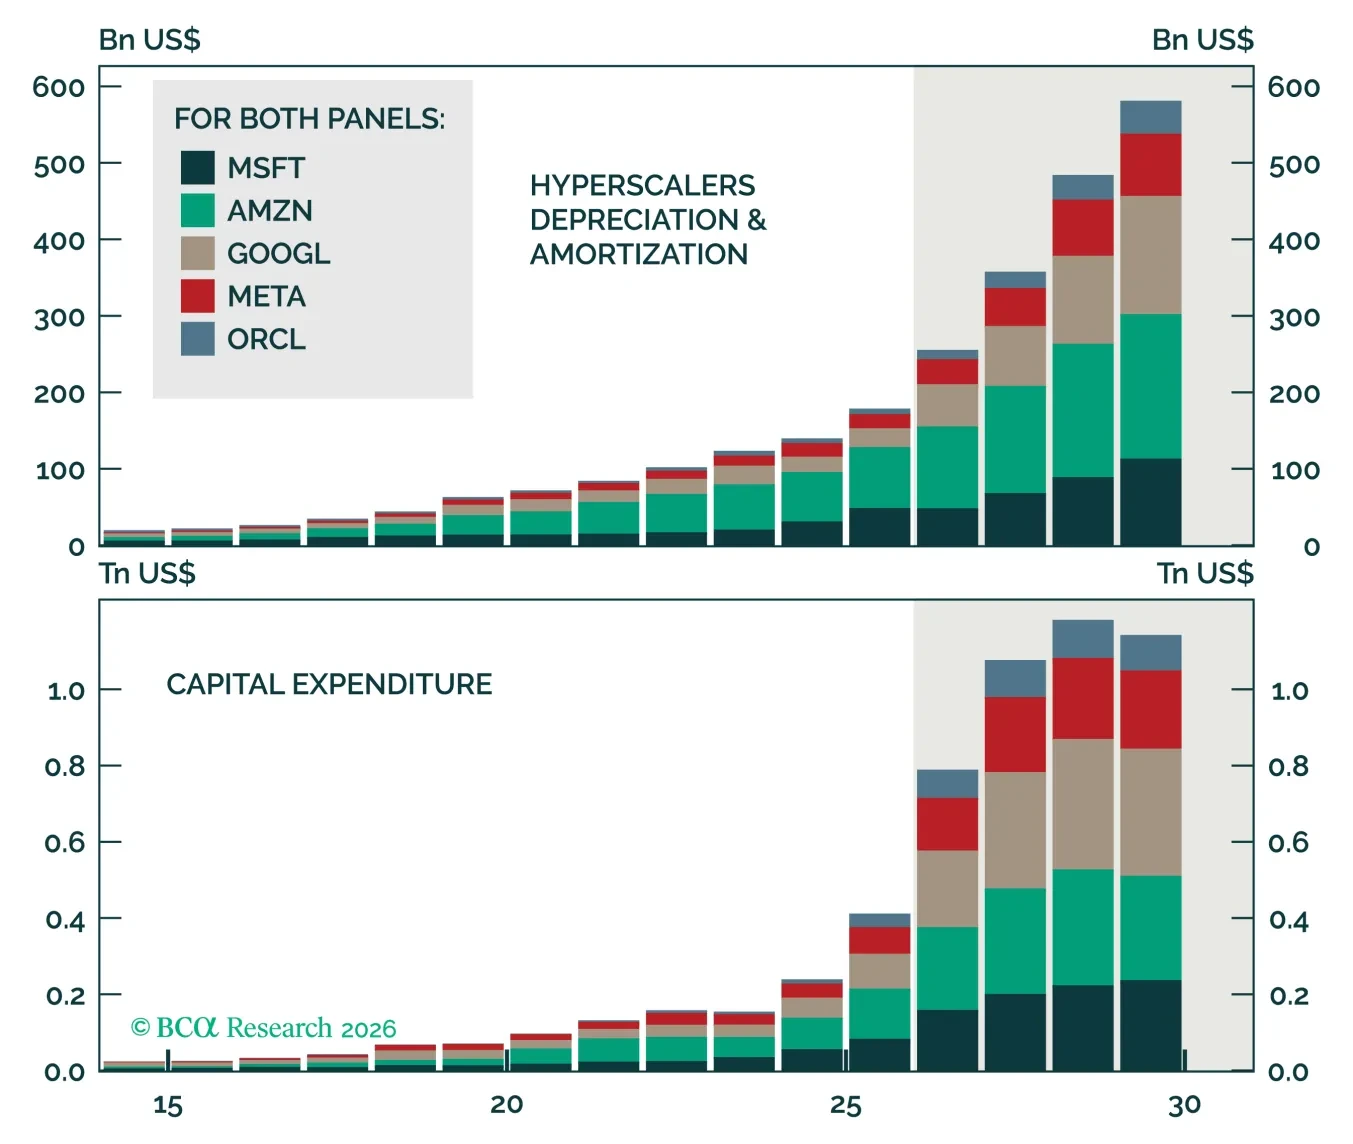
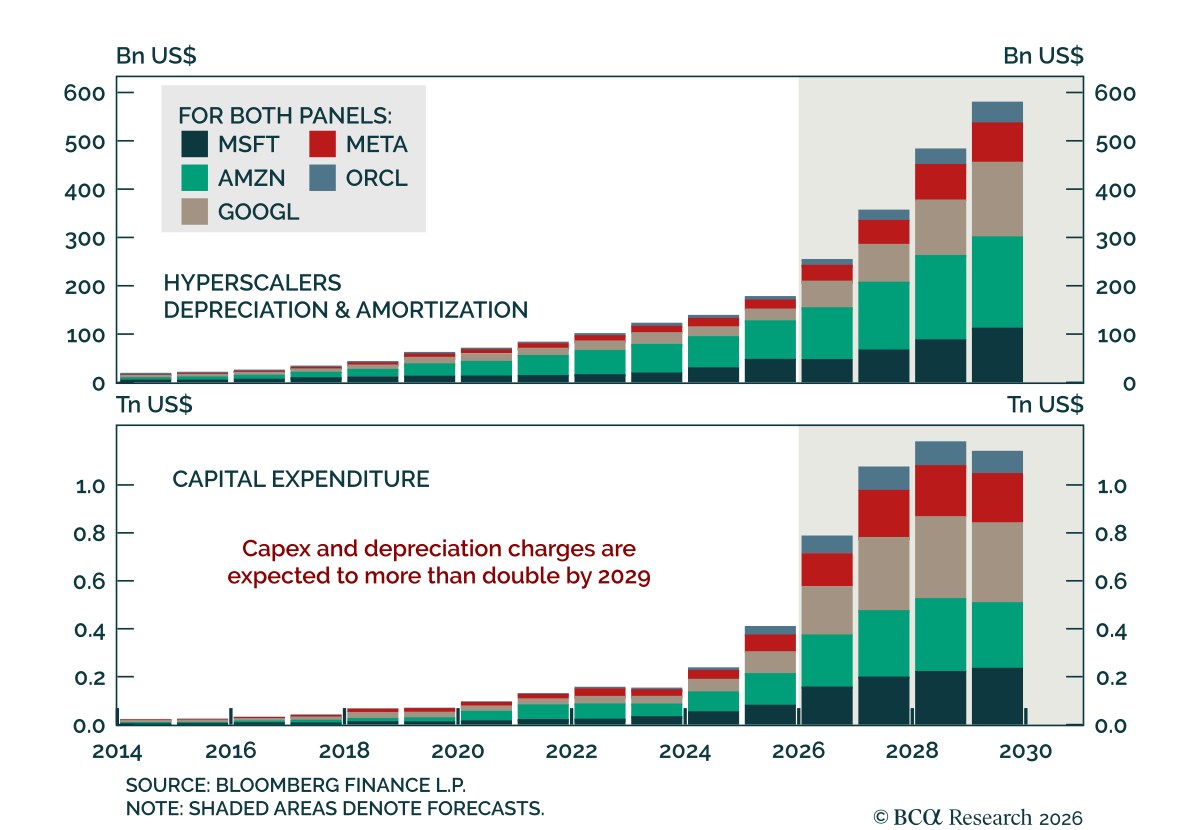
Concerns by the major AI companies that they are locked into a financially unsustainable arms race for AI dominance are likely playing as much a role in their newfound “go slow” approach as concerns over AI doom.
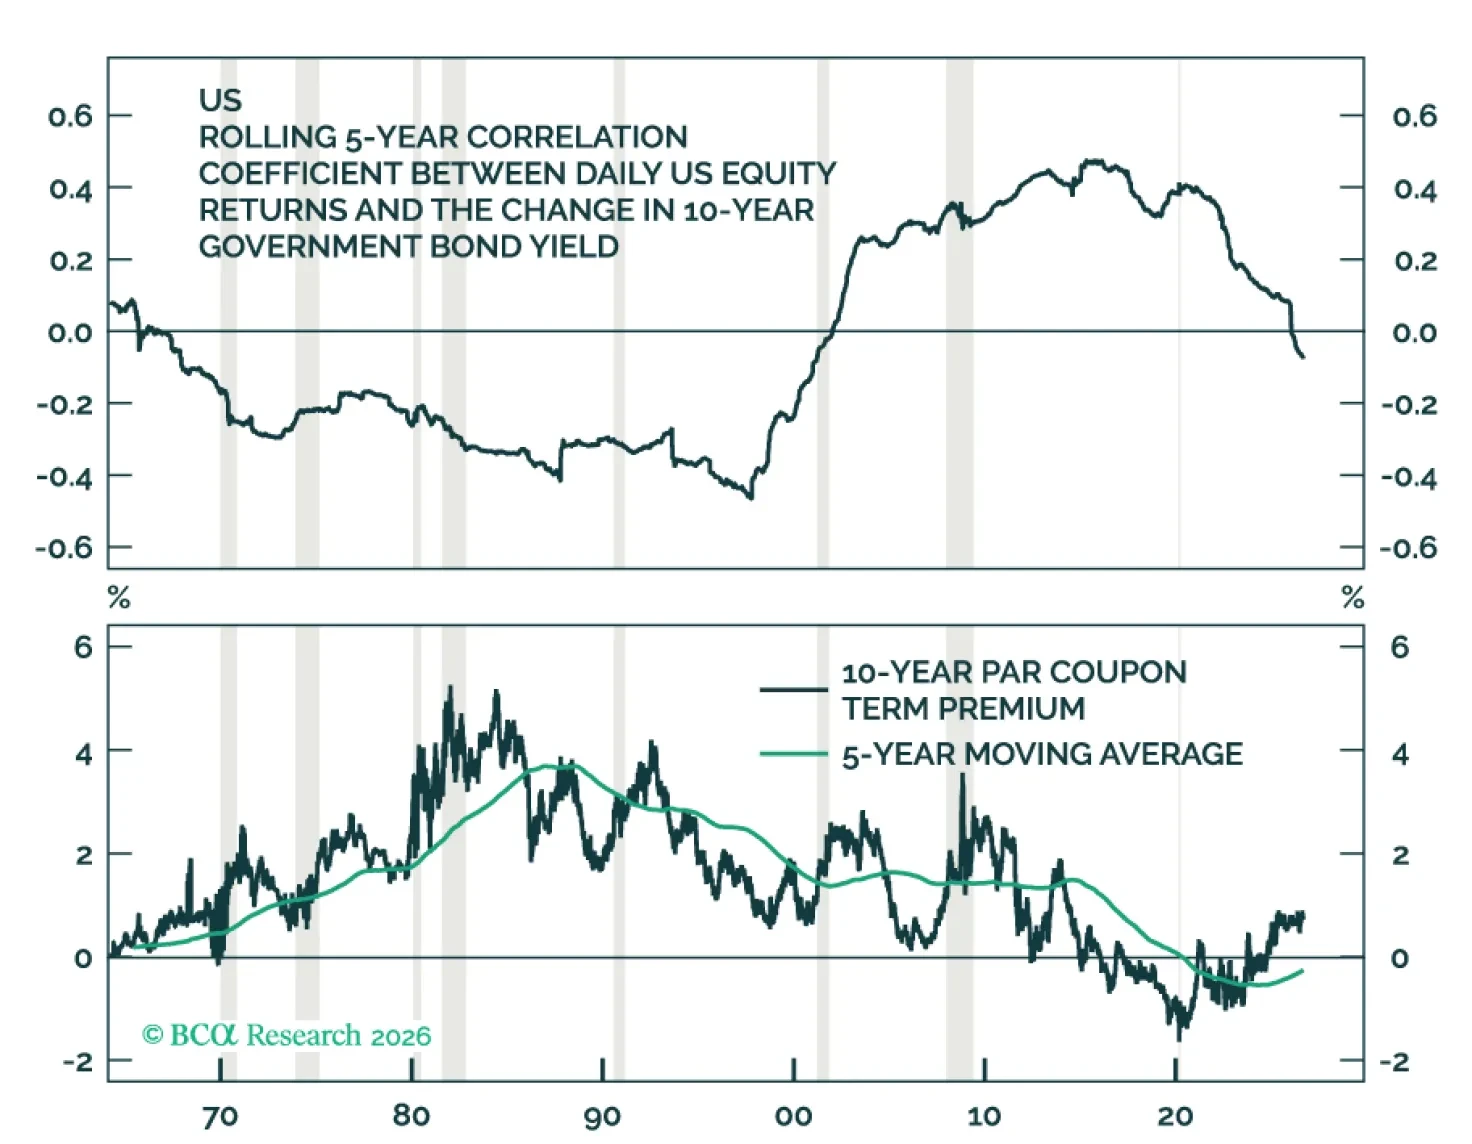
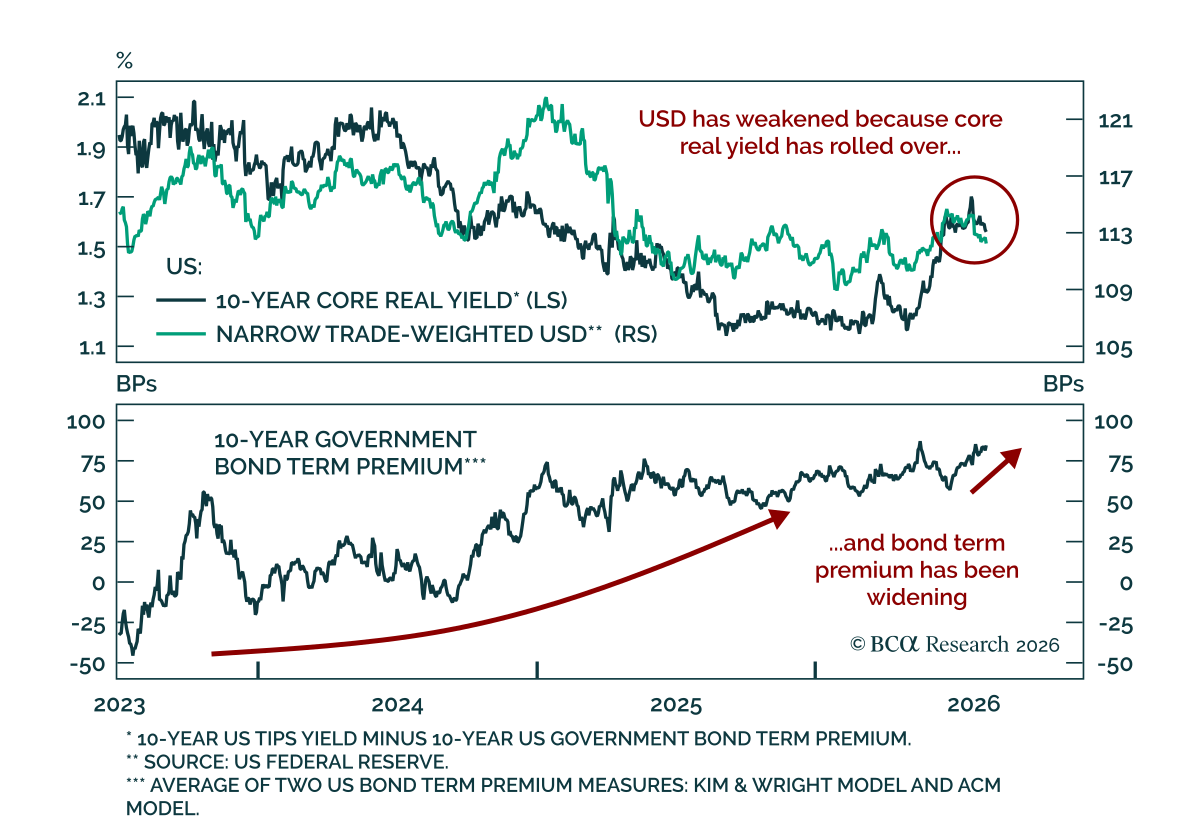
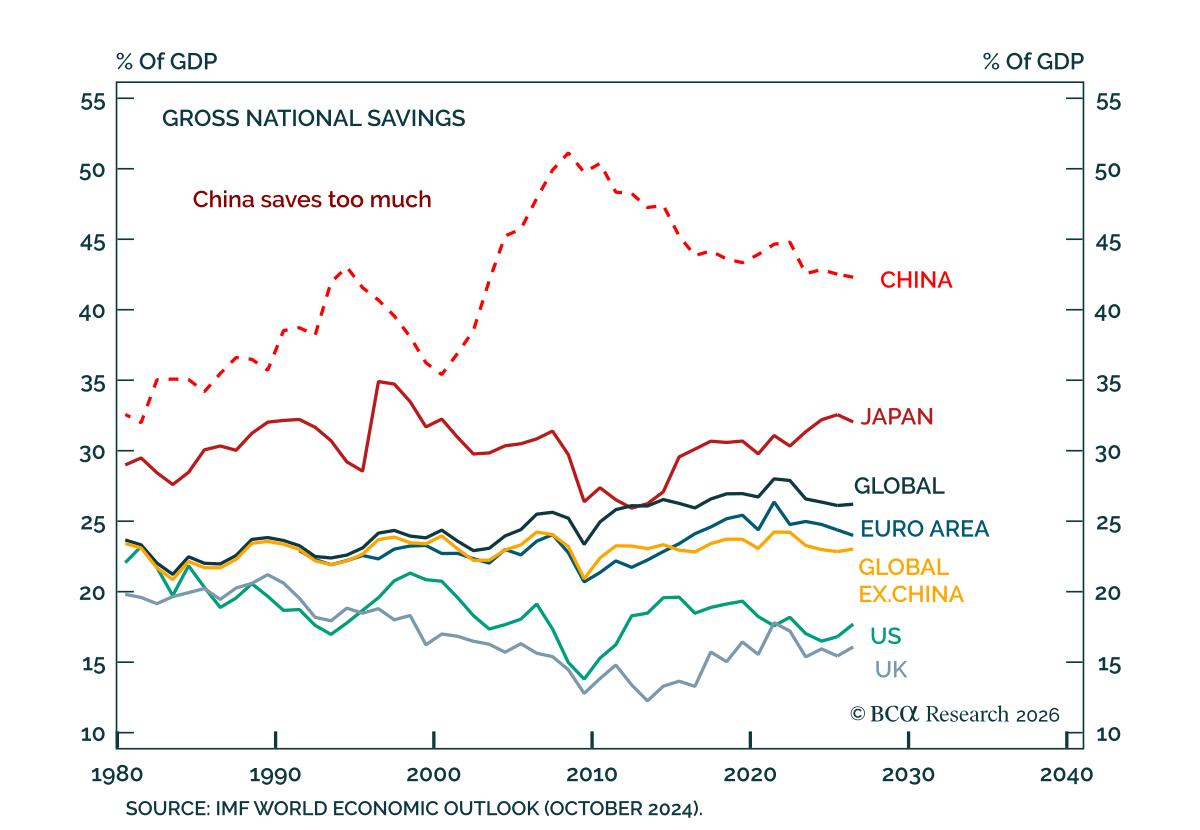
We propose a unified framework for predicting the direction of short-term interest rates and long-term bond yields that brings together three approaches: 1) the saving-investment approach; 2) the Taylor rule approach; and 3) the portfolio balance approach. Our analysis suggests that bond yields in the US and many other countries have increased mainly because of a higher neutral interest rate and a larger term premium. Given the risk of a further rise in inflation expectations, investors should overweight inflation-linked bonds.
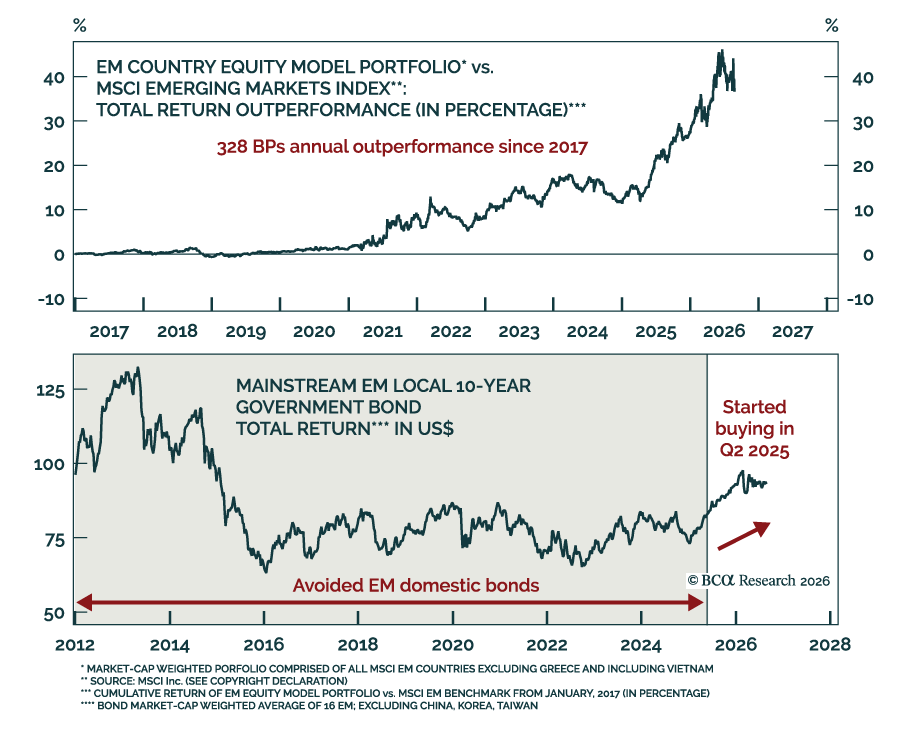
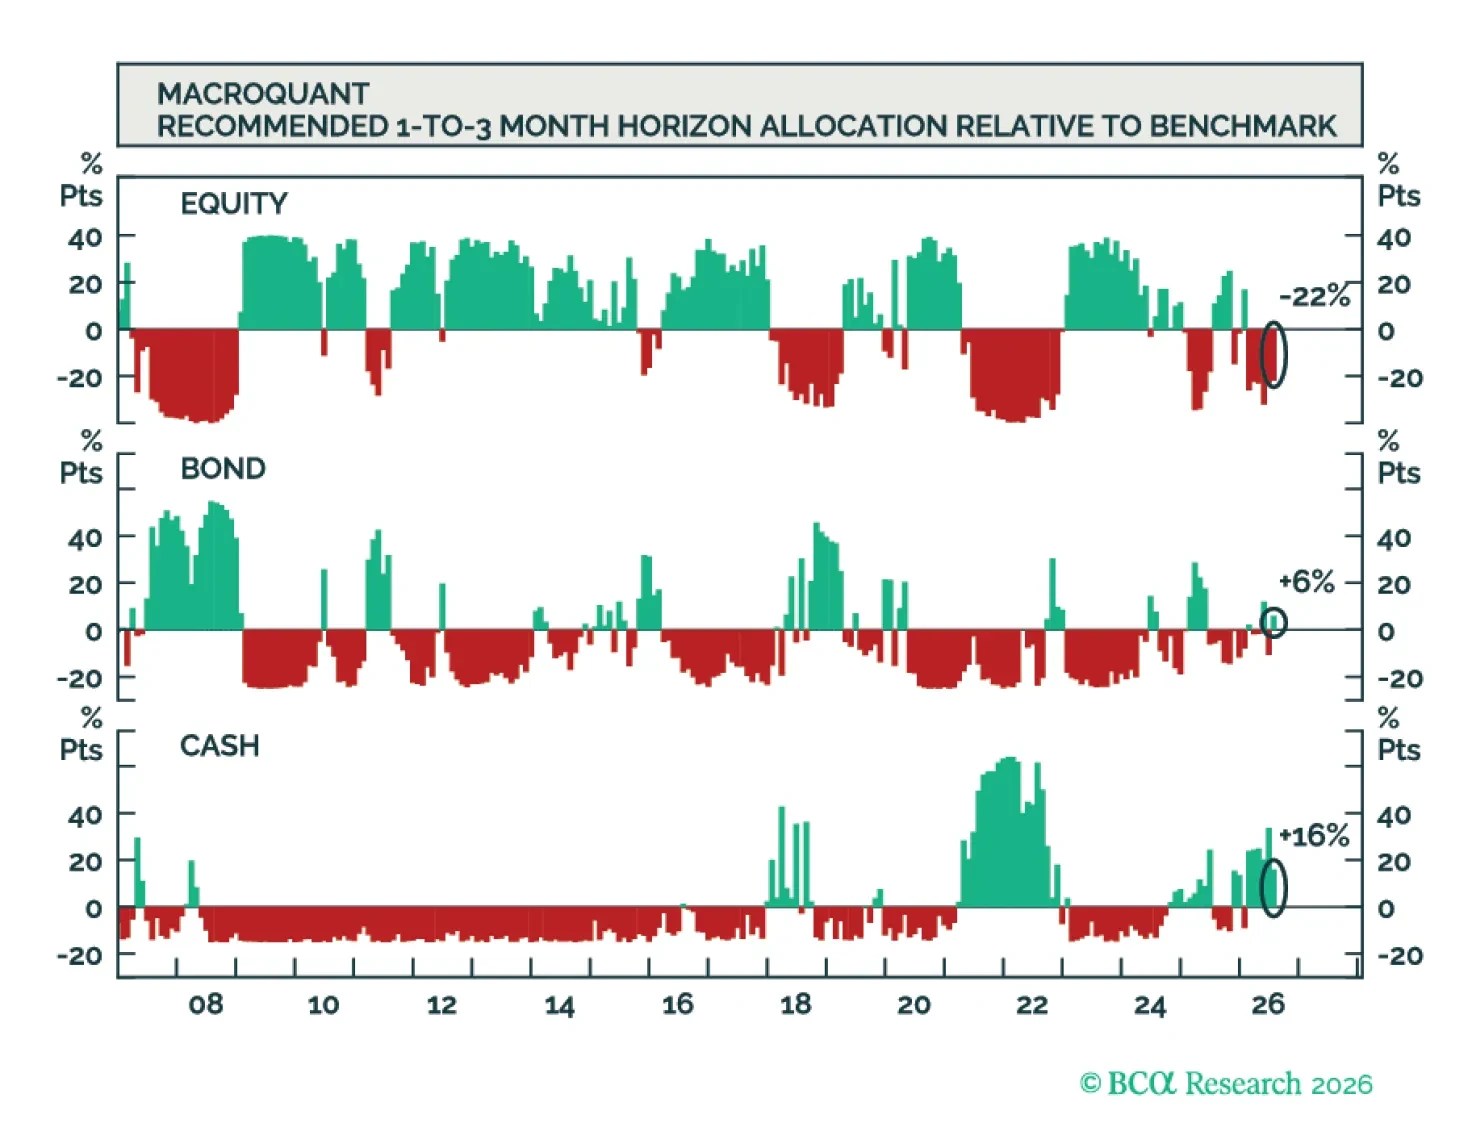
MacroQuant recommends a slight underweight position in equities, counterbalanced by a slight overweight to bonds, and a significant overweight to cash. The model is positive on the US dollar, modestly negative on gold, and bullish on copper and oil.