Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Equities

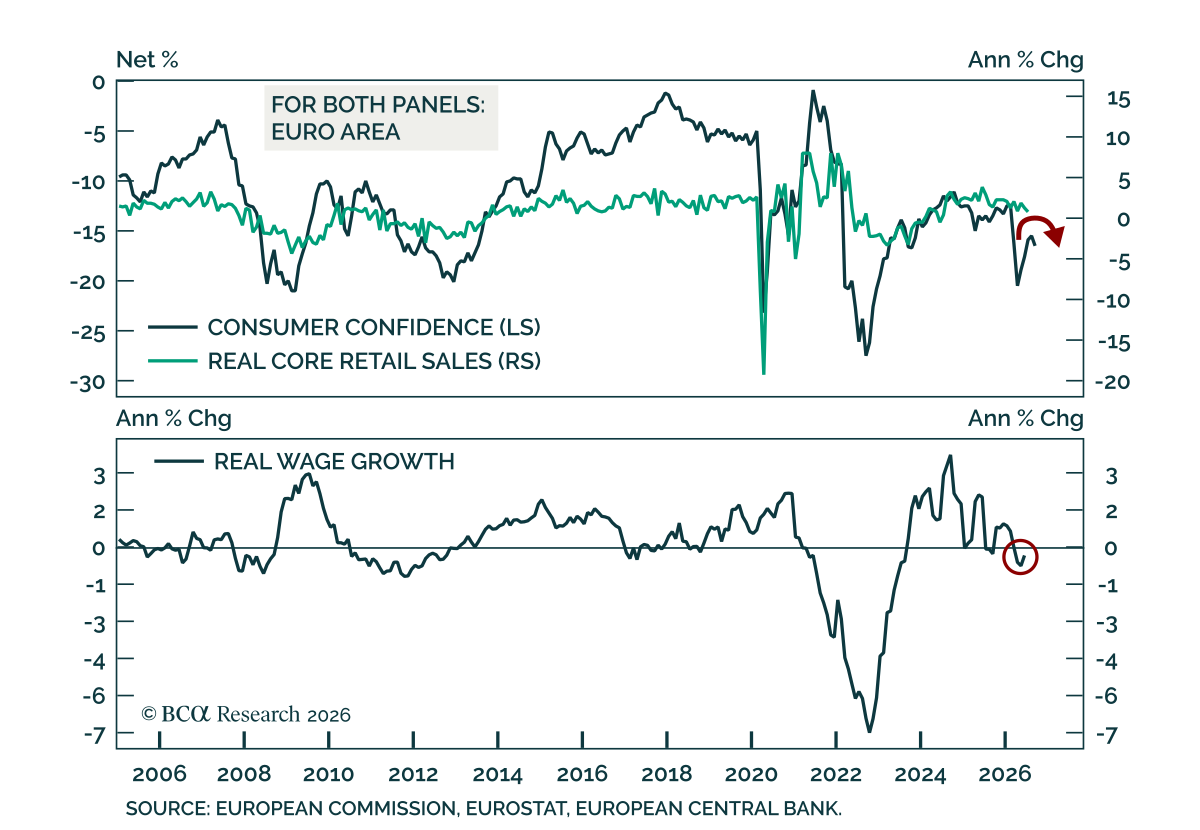
Falling Euro Area consumer confidence and greater energy exposure favor US over European equities near-term. Euro Area consumer confidence fell in September, ending a four-month upswing. The European Commission's flash index dropped 1 percentage point (p.p.)…
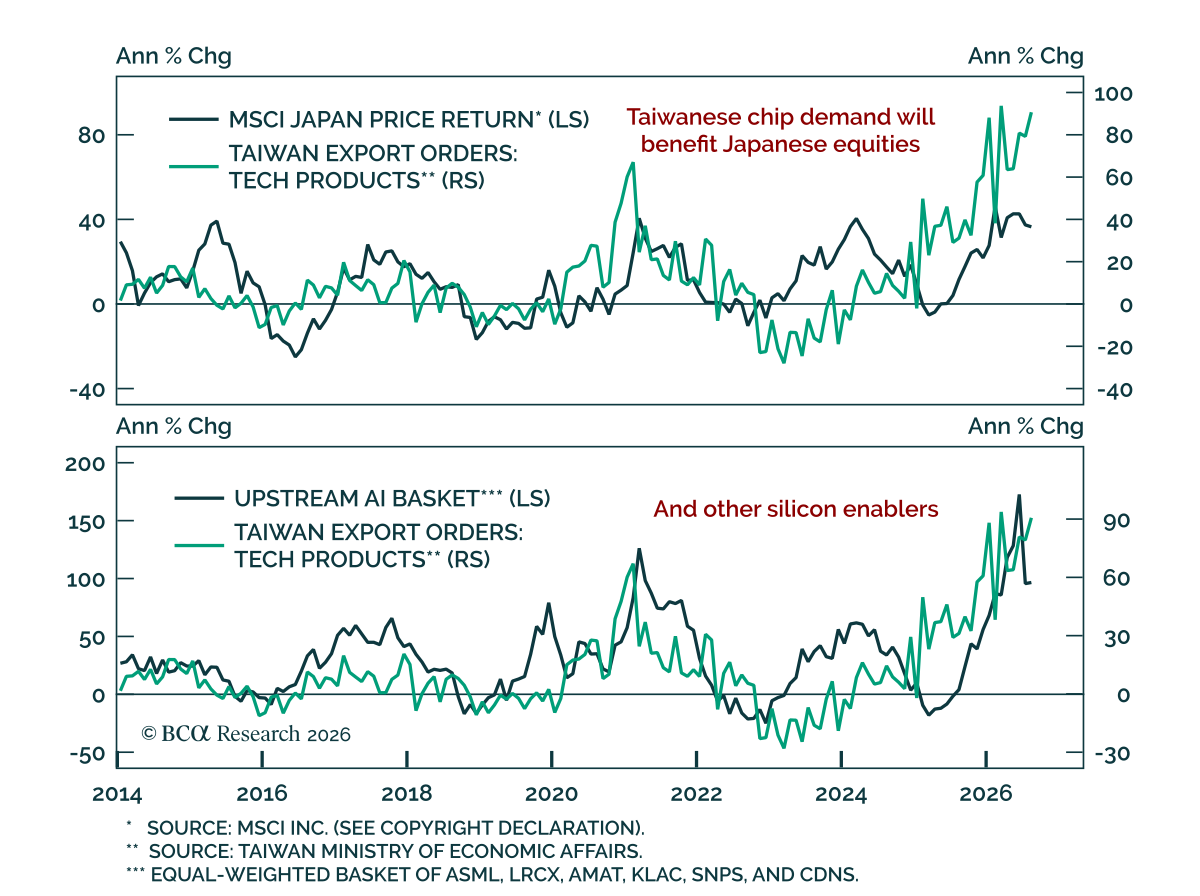
Taiwan’s tech export orders suggest that the global AI investment cycle remains strong, favoring Japan and upstream AI stocks linked to the buildout. Orders are near all-time highs, while the stable inventory-to-shipments ratio indicates that production has…
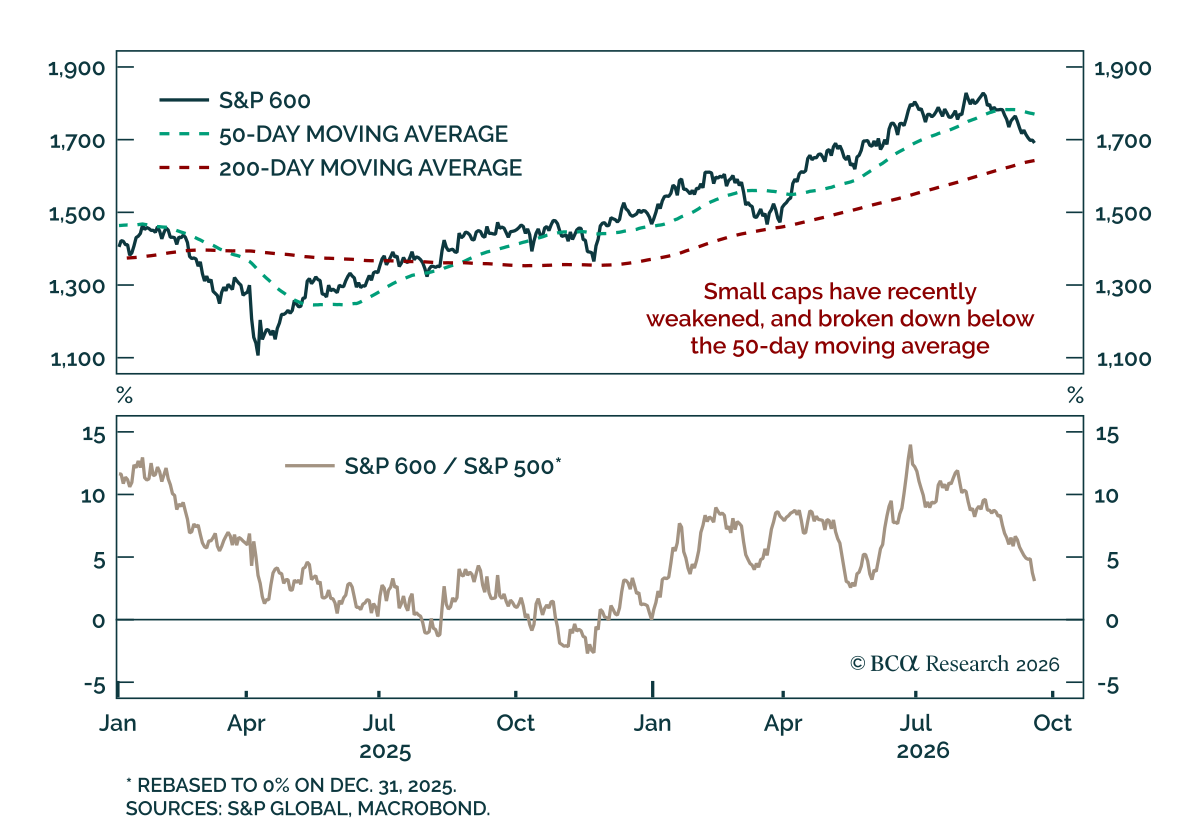
US small caps are coming under pressure. The S&P 600 has fallen below its 50-day moving average after outperforming since late 2025, following roughly five years of substantial underperformance versus the S&P 500. The 200-day moving average is likely the next…
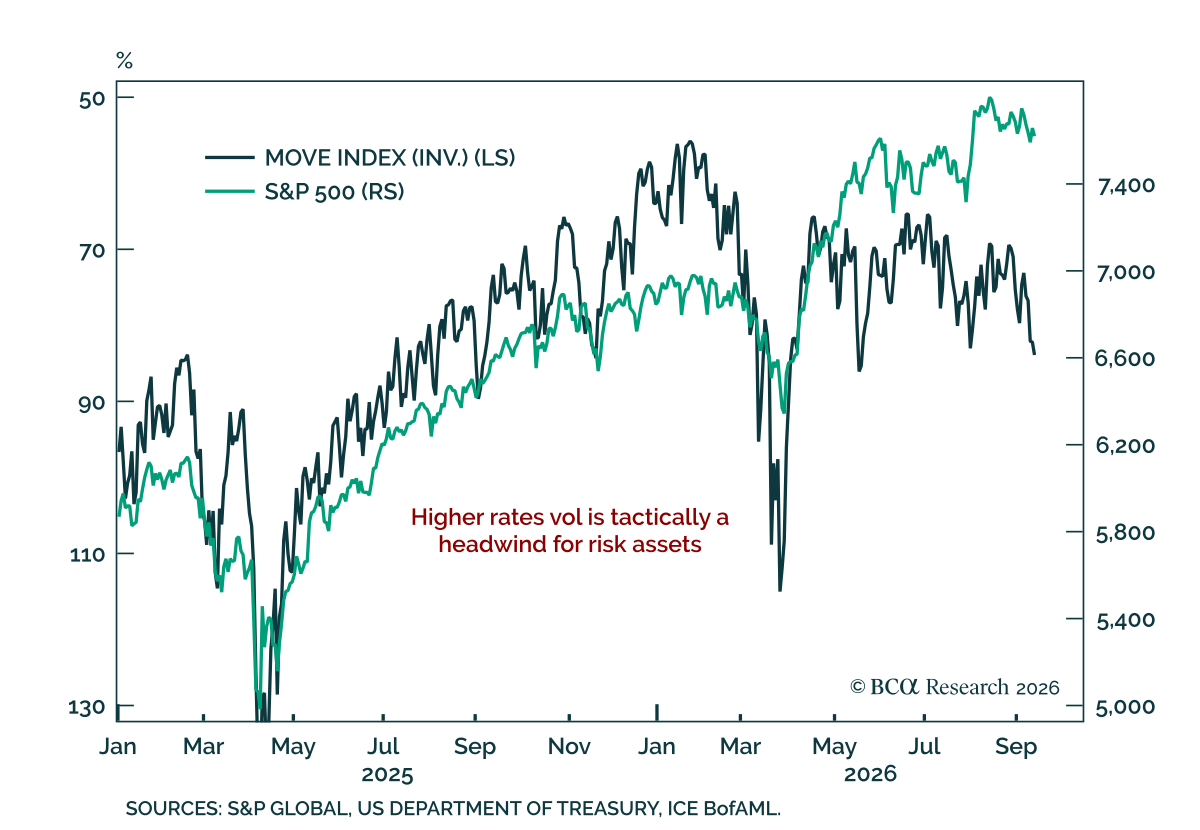
Higher bond yields are becoming a more important risk for equity markets, but the implications depend on whether Fed tightening remains mild or develops into a genuine hiking cycle. At our September Views meeting, our US Bond strategists outlined two…
Special Report

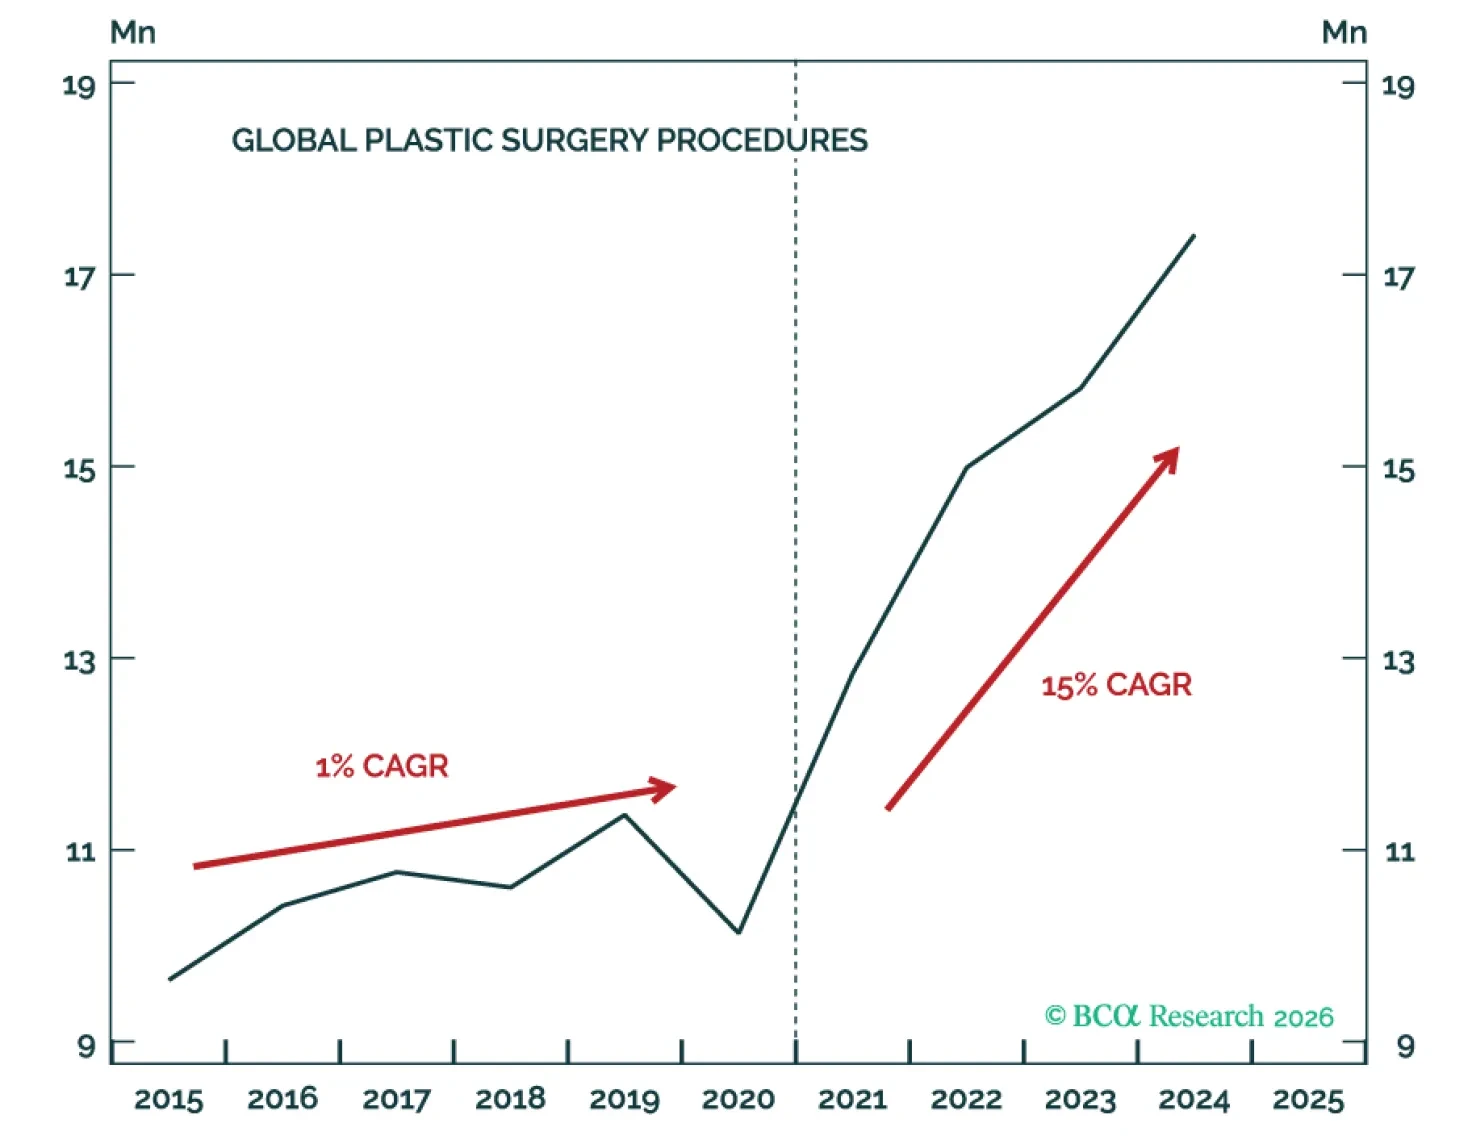
The rise of remote work, online dating, and other demographic changes are increasing the demand for aesthetics. GLP-1s provide an effective and inexpensive cure for obesity, and their secondary effect “Ozempic face” has structurally altered the demand for aesthetic procedures and skincare. Long GLP-1 producers, biostimulator injectable producers, and K-Beauty contract manufacturers.
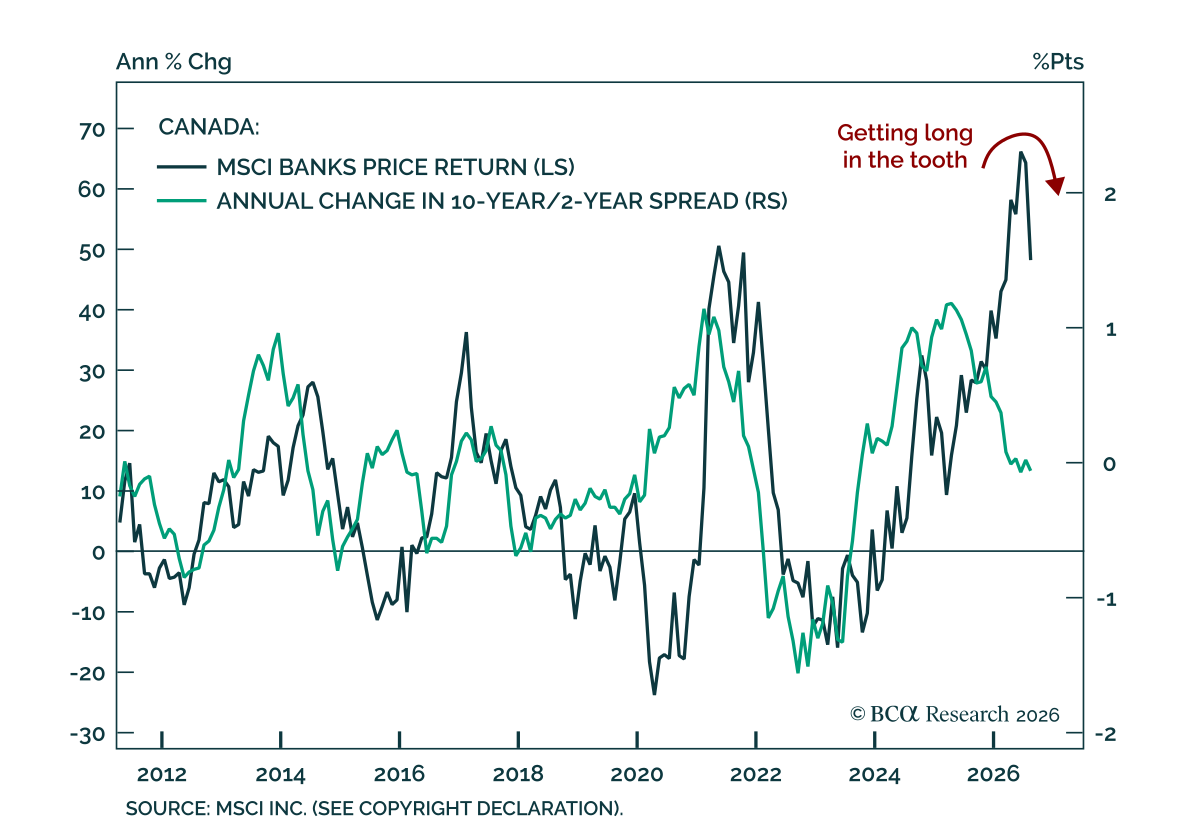
Canadian banks are overdue for a correction as stretched valuations, a weakening housing market and fading support from the yield curve create growing downside risks. Bank equities have continued to surge even as the 2-year/10-year spread has stopped…
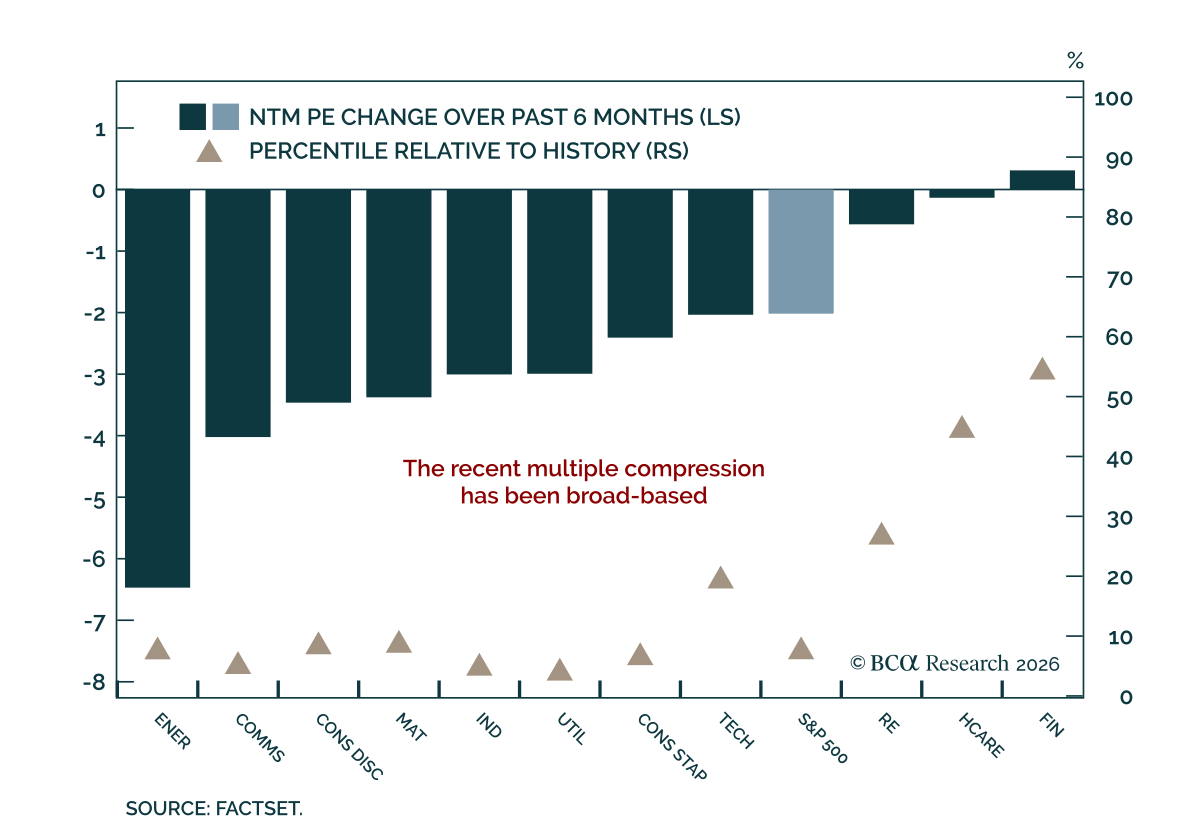
Our US Equity strategists remain constructive on US equities but see the path to their 8100 year-end target as increasingly dependent on earnings, with less scope for multiple expansion to contribute. Higher yields, slower EPS growth and heavy IPO issuance…

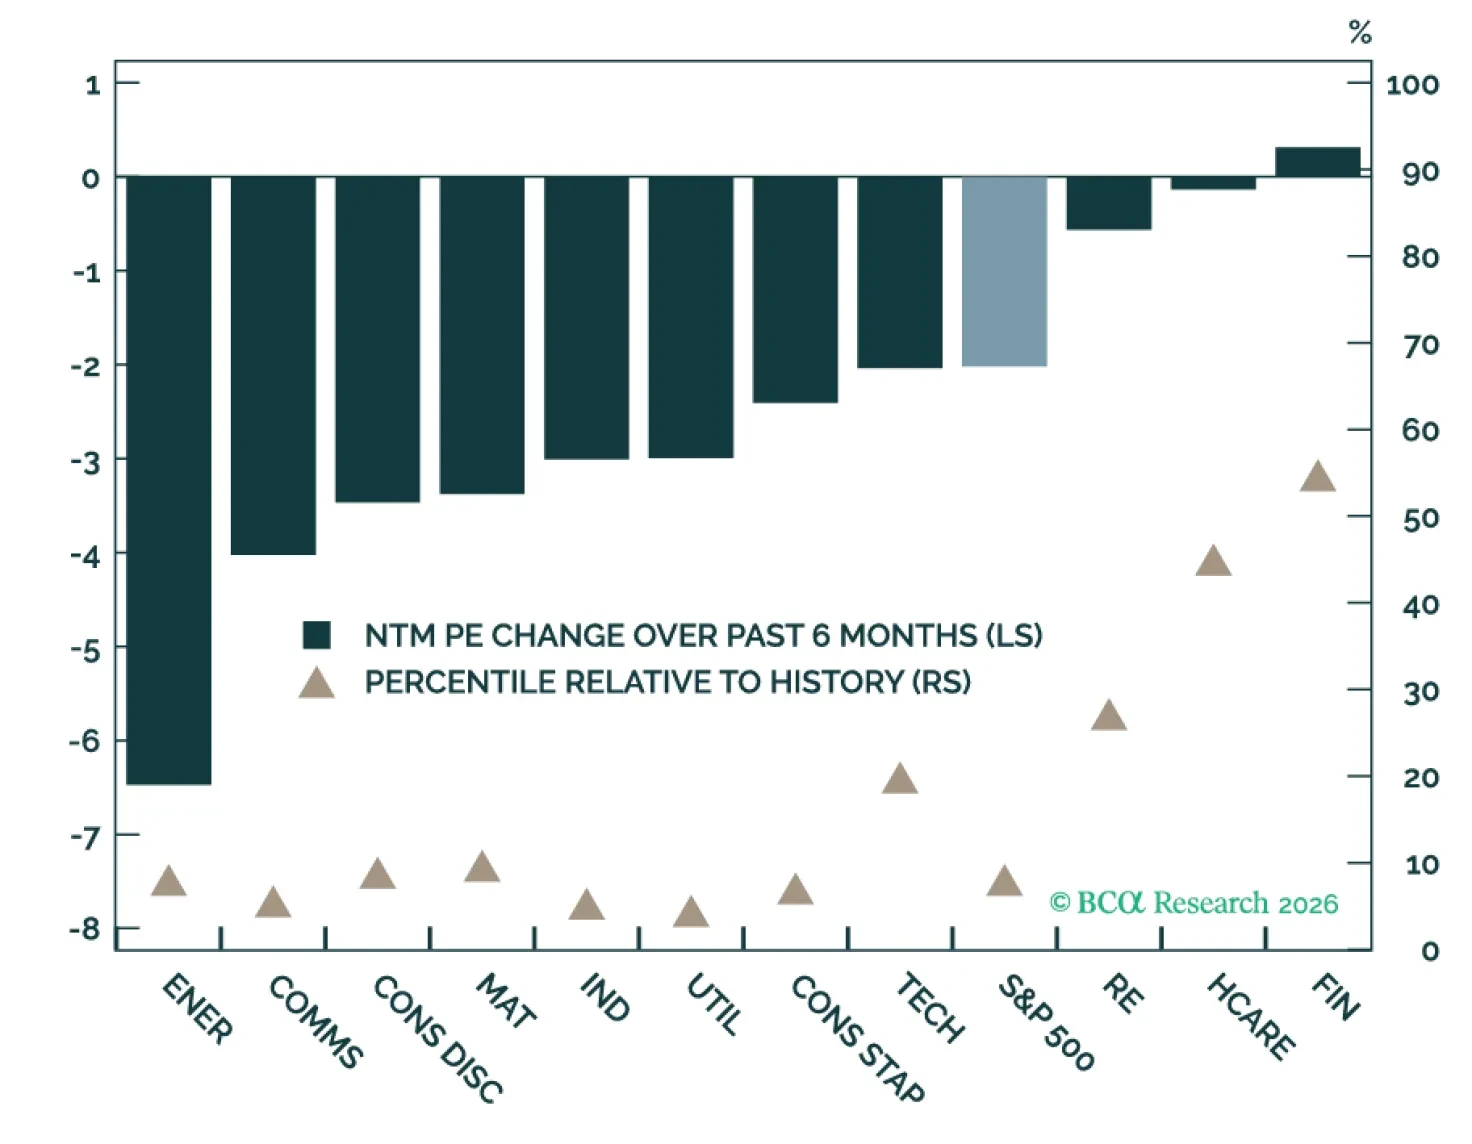
We remain constructive on US equities, but higher yields, slower EPS growth and heavy IPO issuance remain significant risks to valuations, leaving the path to our year-end target increasingly dependent on earnings. Tactically, there has already been a significant, but benign, compression in multiples, as earnings have outpaced prices. A well-communicated Fed hike could ease rather than intensify bond-market uncertainty. 
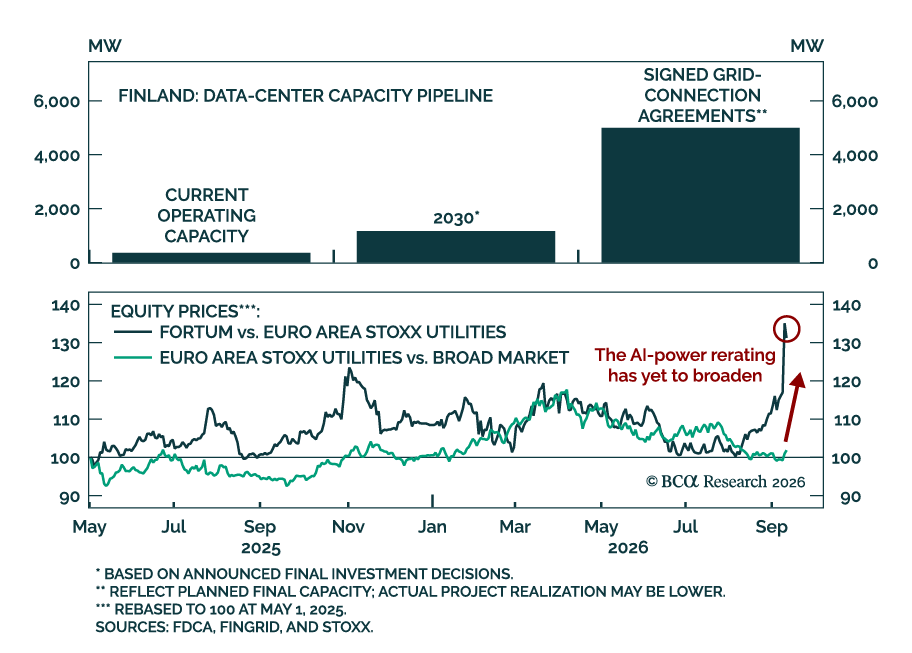
Europe’s AI buildout is creating a new source of structural power demand. Our Chart Of The Week comes from our analyst Eugenia Pan, and shows why this trend is favoring utilities with reliable low-carbon power. Finland offers an early example. While its…
Special Report

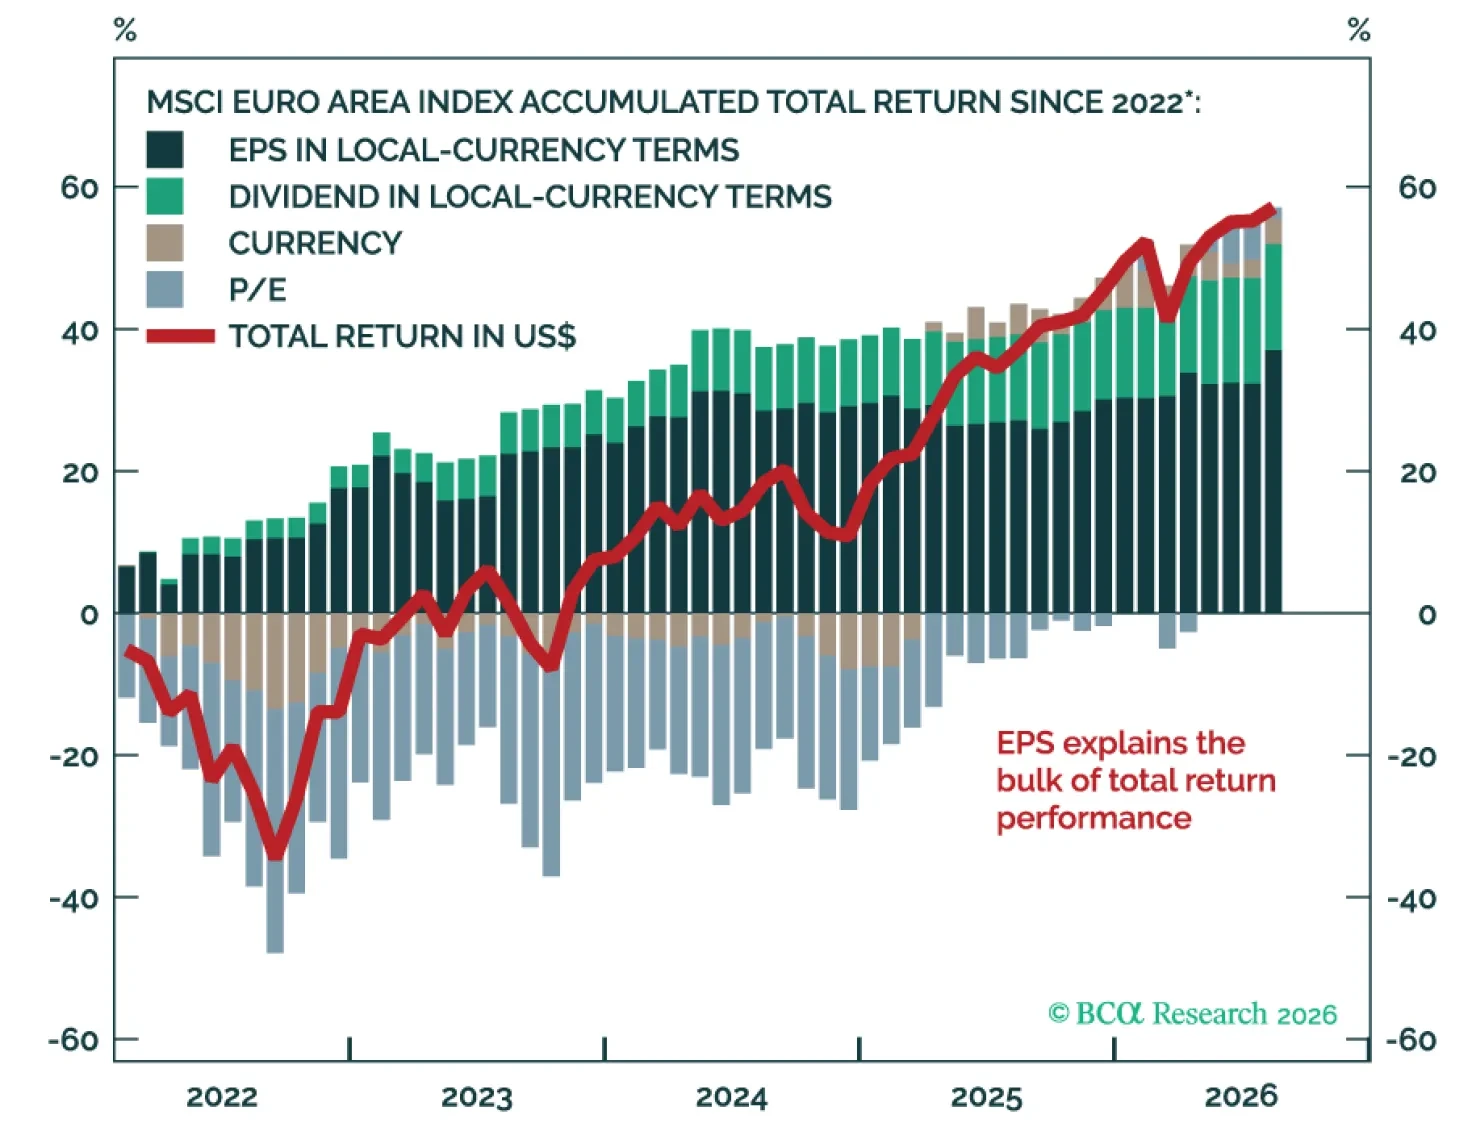
Europe’s earnings recovery is increasingly difficult to dismiss. Margins, ROE, ROIC, and capital efficiency have all improved, while banks have re-emerged as an earnings engine. Cyclical conditions remain supportive, and the structural picture continues to improve: higher investment, improving productivity, and EU reforms could give the recovery staying power.