Latest from BCA Research

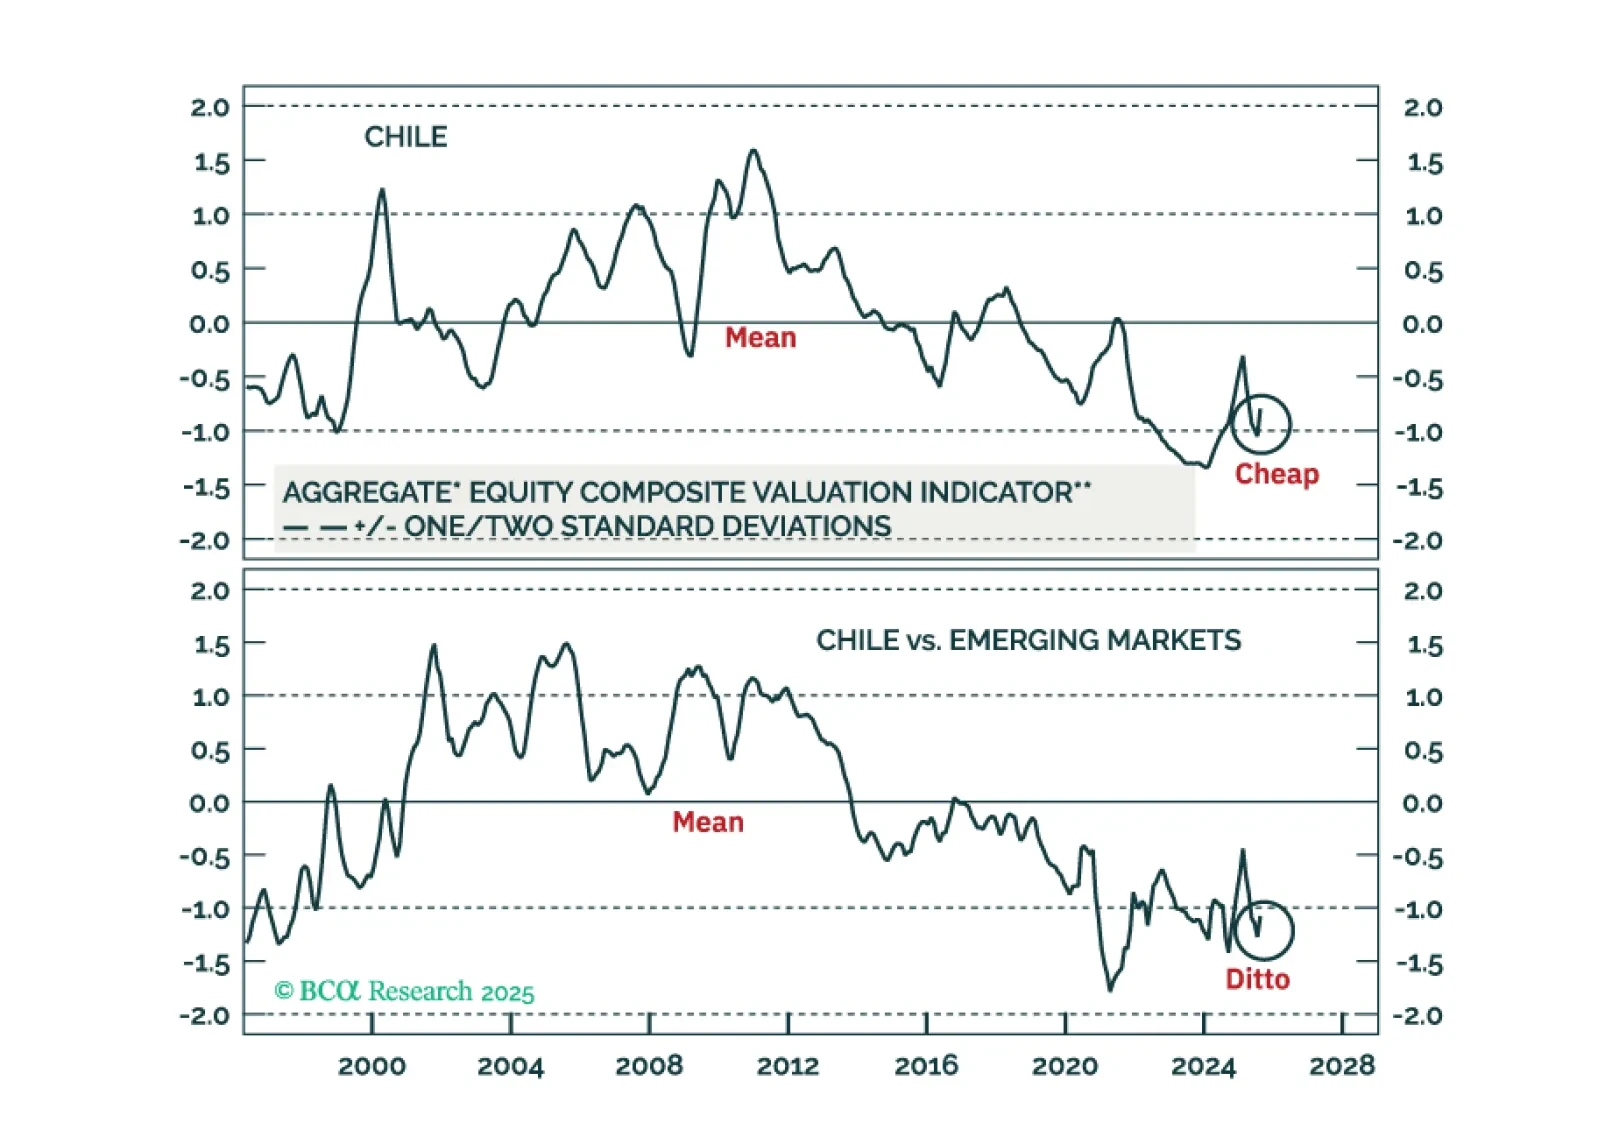
Chilean equities are undergoing a structural re-rating. A political swing back to a pro-business administration, a benign macro backdrop, and a resilient exchange rate will drive Chilean markets’ outperformance versus EM peers.
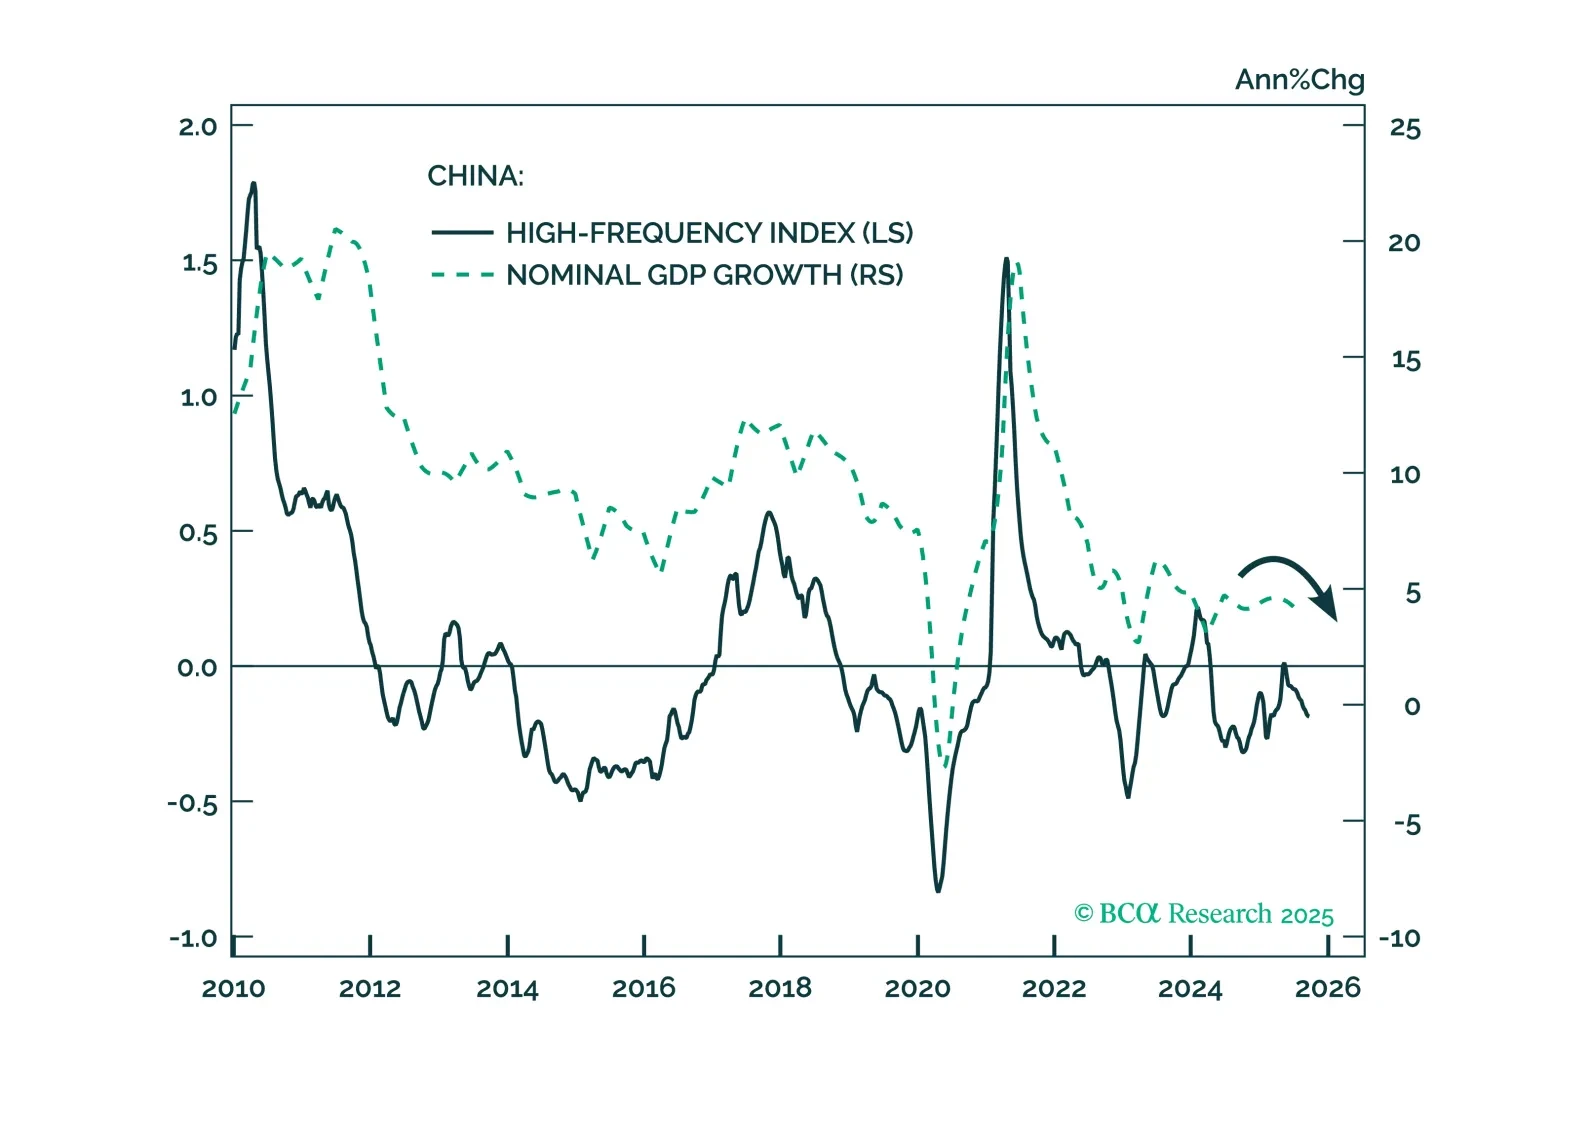
Our high-frequency indicators show China’s growth momentum weakening further in September, increasing the likelihood of new stimulus in the weeks ahead. We remain tactically cautious on Chinese equities, but strategically constructive on offshore Chinese shares.
Putin’s position is weakening as Trump backs Ukraine, NATO threatens retaliation, and Ukrainian drones cripple Russian refineries. Moscow’s petty war aims embolden Eastern Europe, raising NATO-Russia confrontation risks. We remain long oil and long European defense stocks.
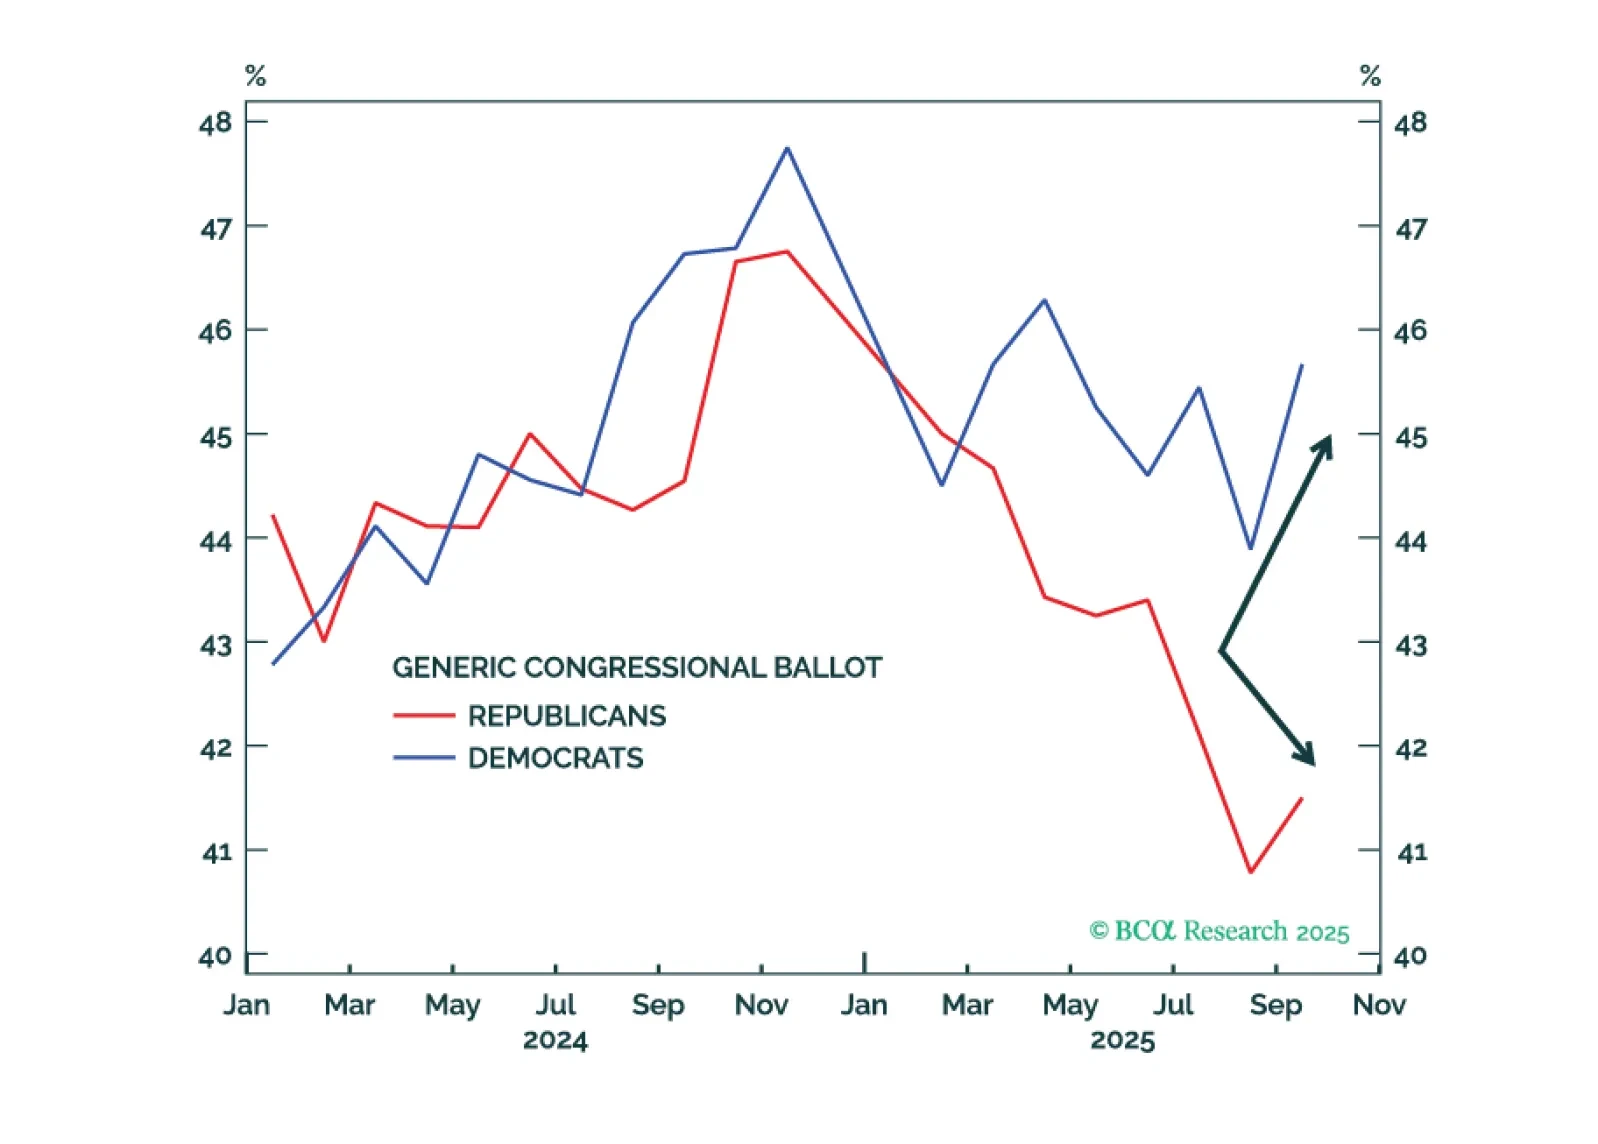
We give a one-third probability of a federal government shutdown. It probably will not happen before November. At worst, government shutdowns only cause temporary market volatility.
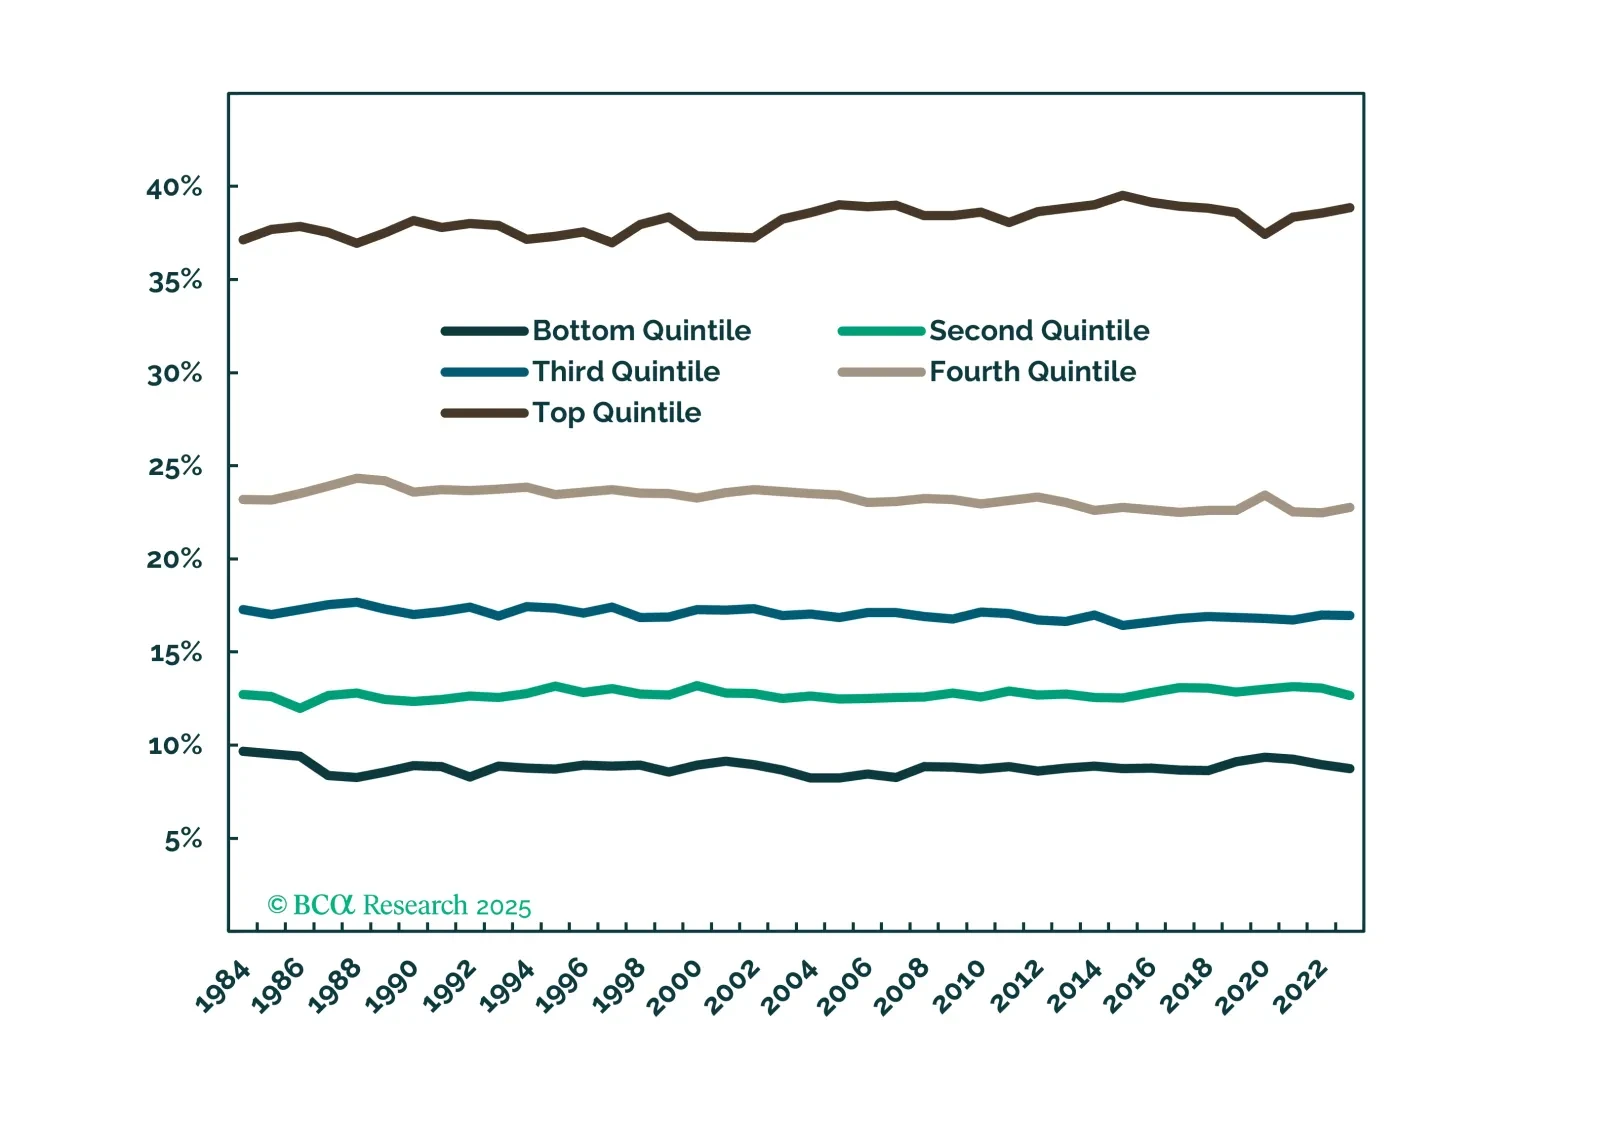
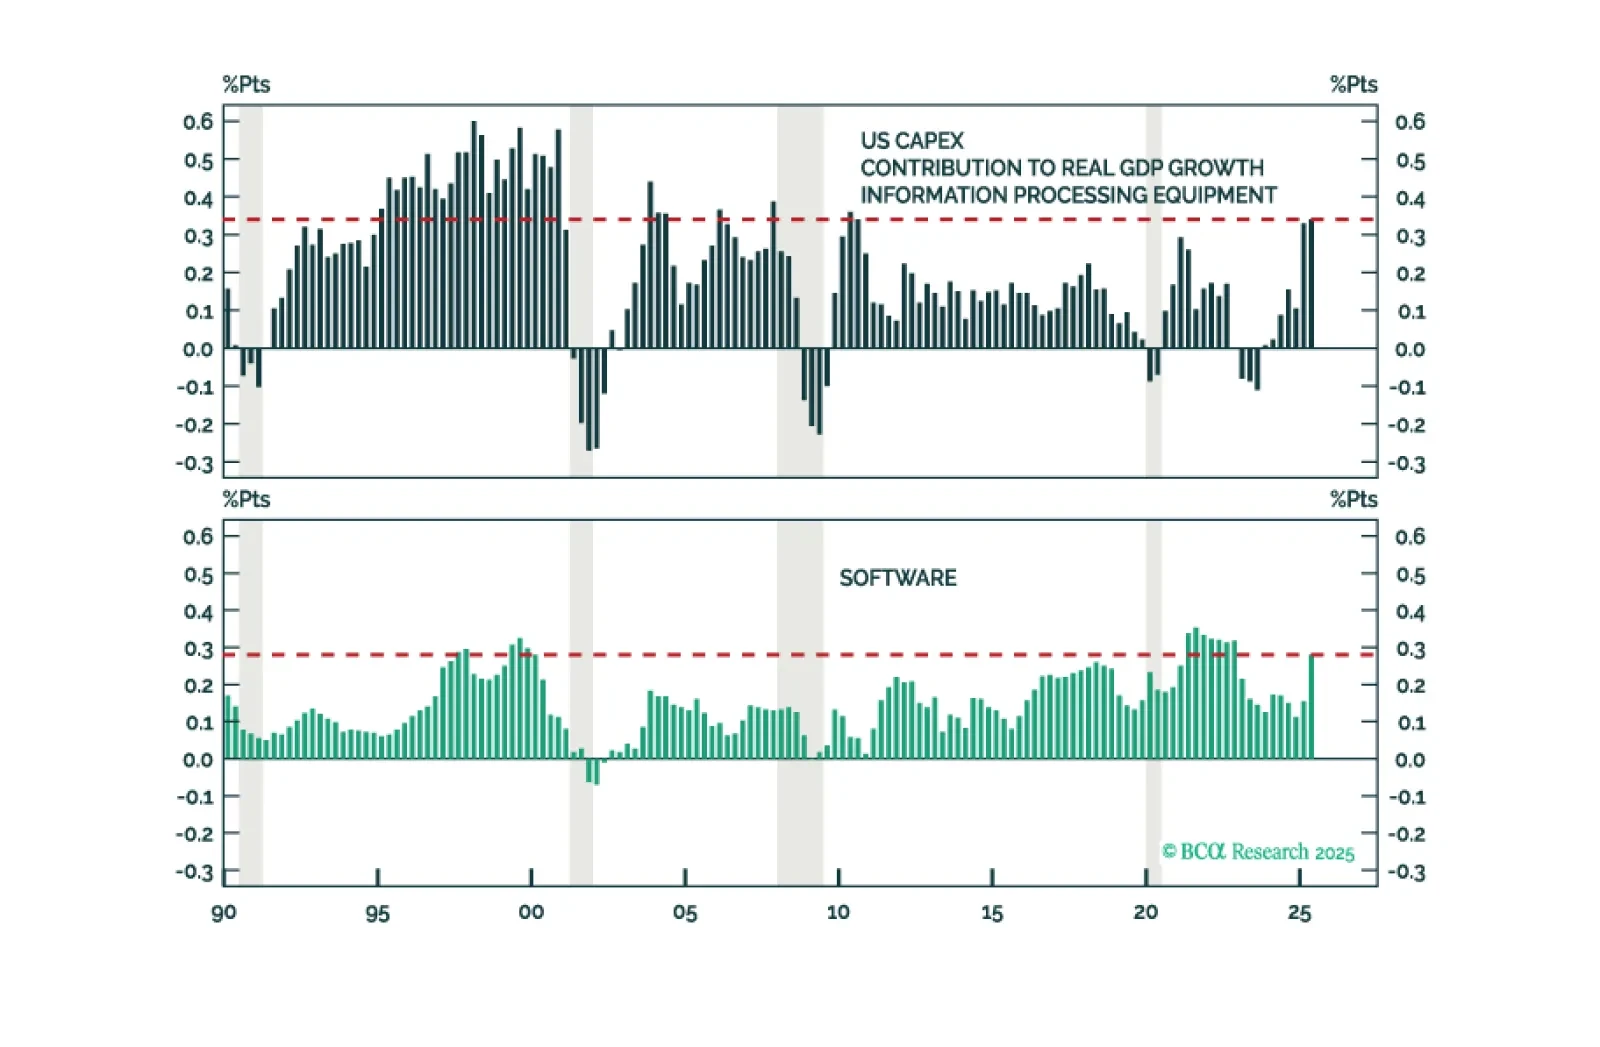
While it is not yet time to bet against risk assets, we push back on the increasingly popular ideas that the wealthiest households and/or AI-related capex can keep the expansion going despite the wobbling labor market.