Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Economy

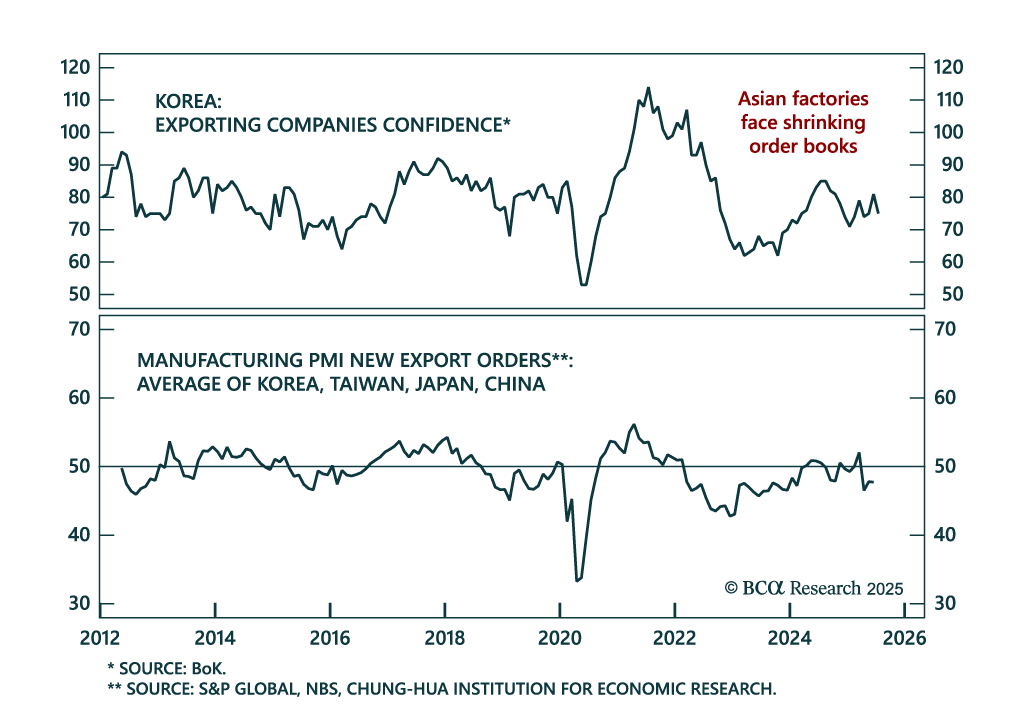
The latest data on Asian exports and manufacturing suggest that the global trade outlook remains downbeat. Korean exports in USD terms grew in June by 4.3% y/y. The three-month moving average is 2.2%. Assuming Q2 export shipments were boosted by frontloading…
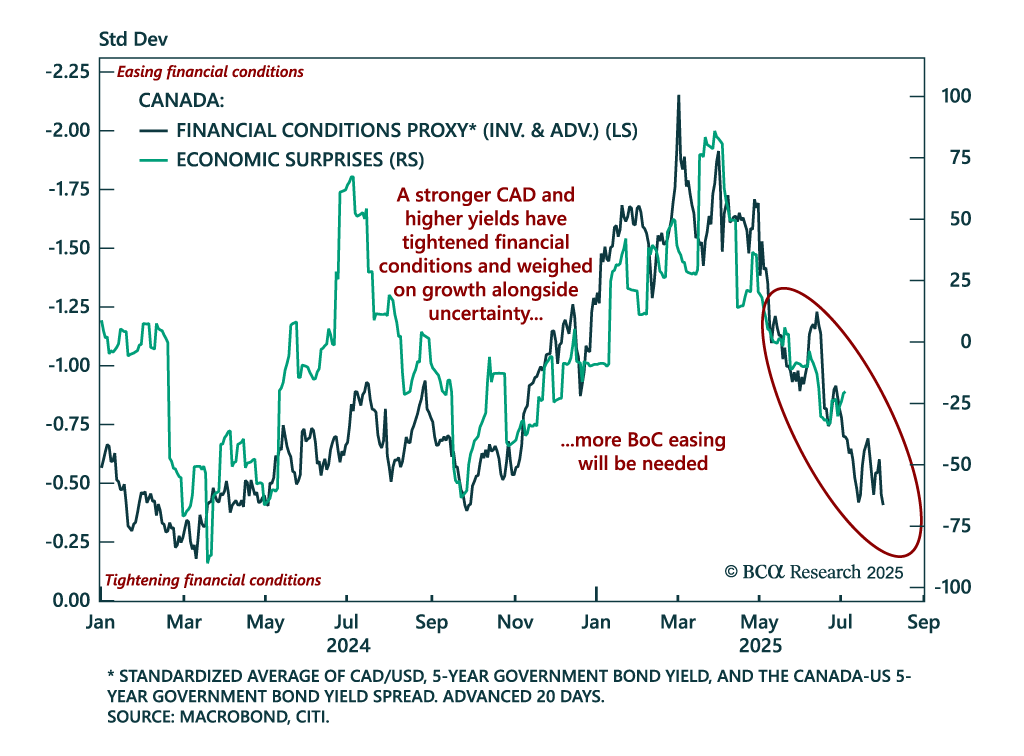
Canada’s stronger currency and tightening financial conditions point to further BoC easing and support long Canadian bond positions. The CAD has appreciated this year alongside the global push to diversify away from USD assets, which has weakened the US…

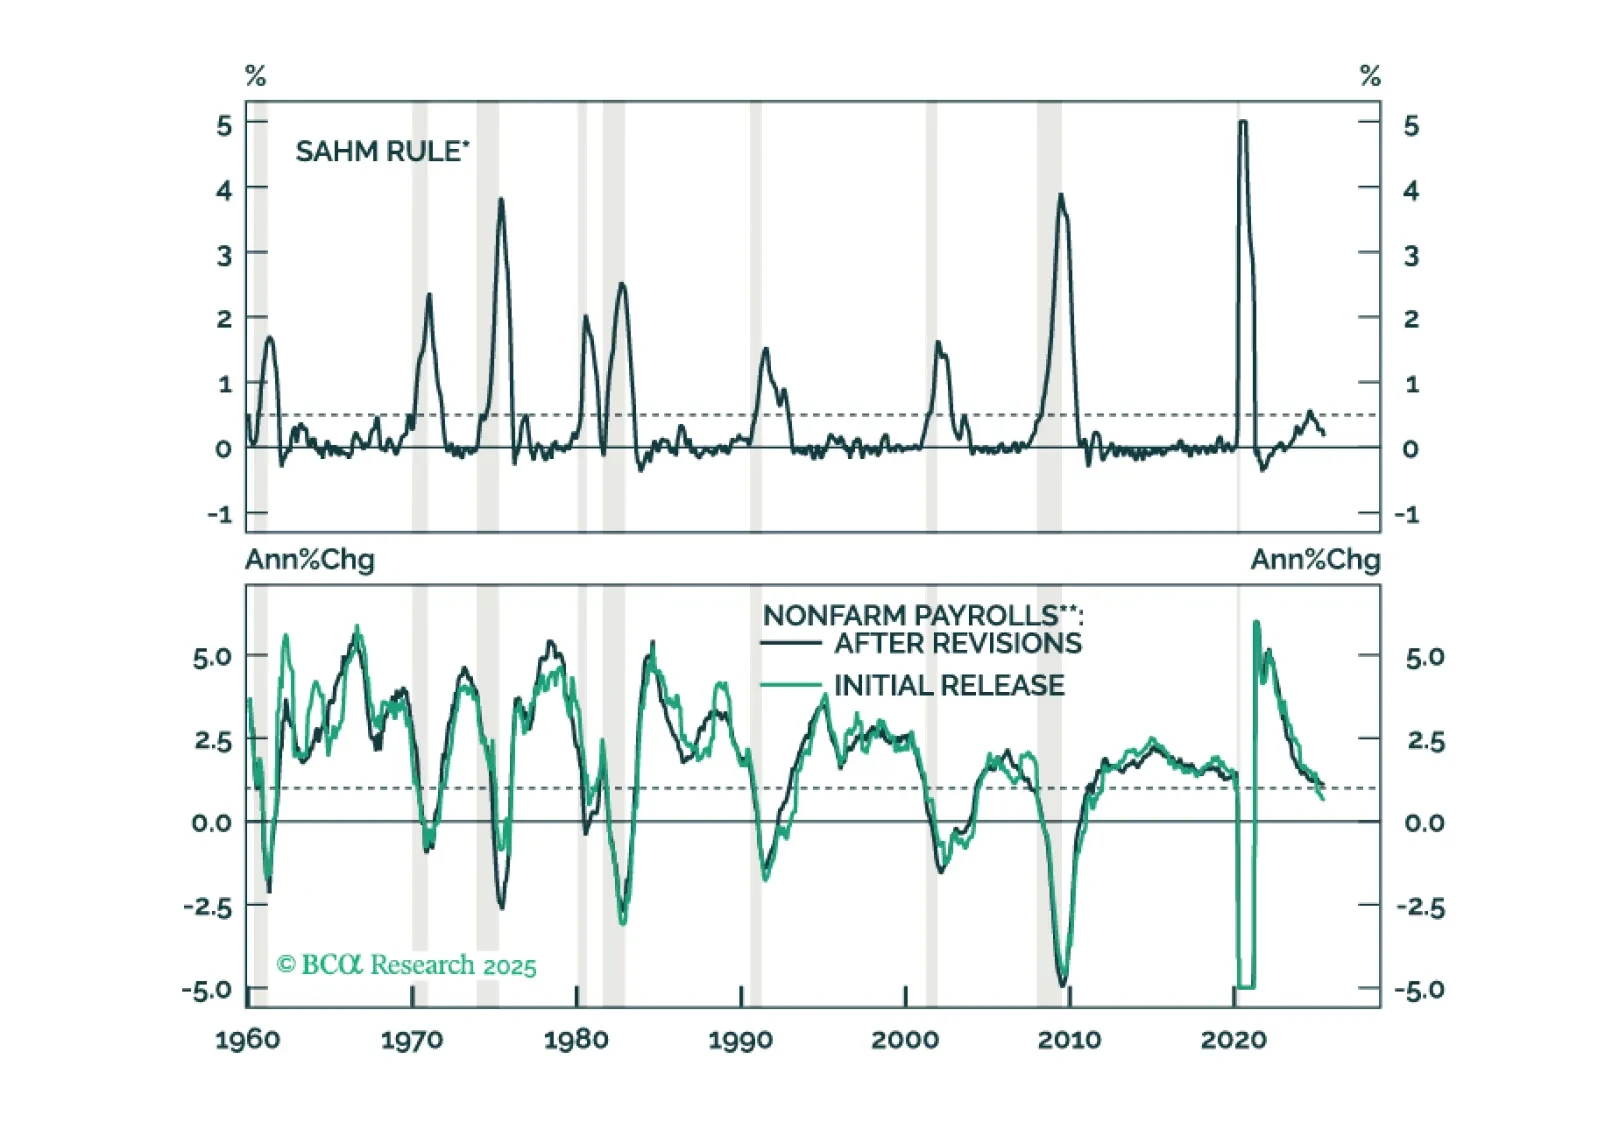
June’s employment report showed a tick down in the unemployment rate, an improvement that rules out a Fed rate cut later this month.
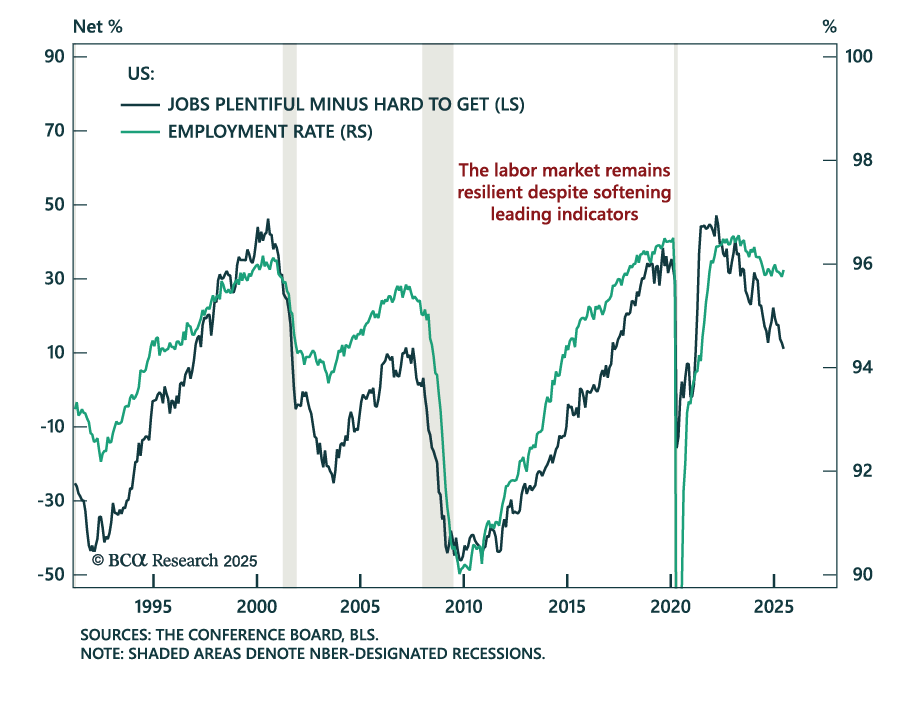
Stronger-than-expected June payrolls rule out a July Fed cut, but the report does not derail the case for long duration and curve steepeners. Nonfarm payrolls printed at 147k, with the two prior months revised up by 16k, leaving the 3-month average at 150k.…
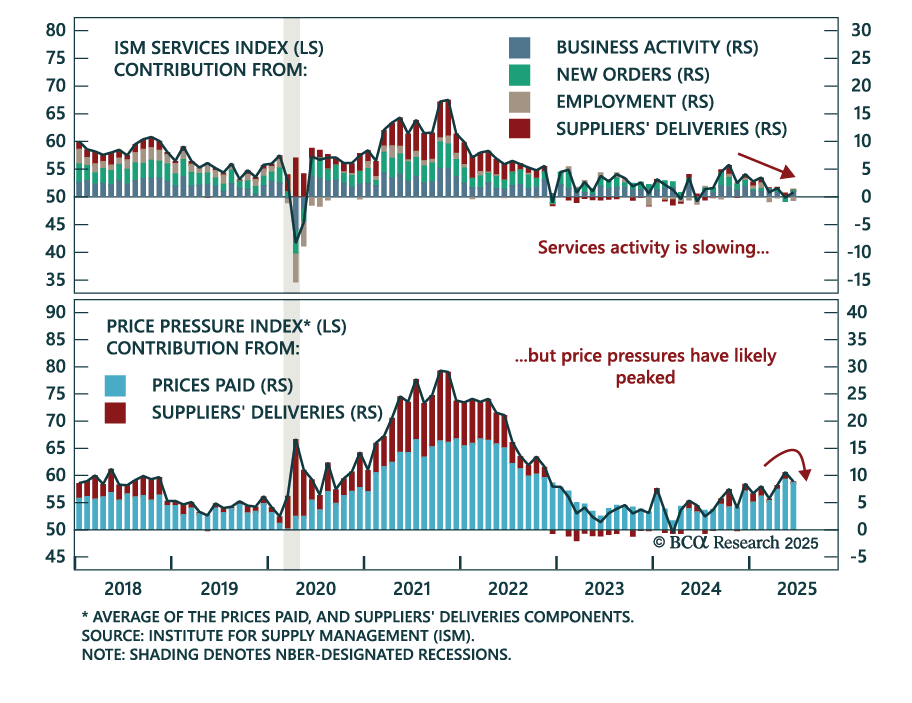
ISM Services data confirm slowing growth and cooling inflation, reinforcing a defensive allocation stance. The index rose slightly to 50.8 in June from 49.9 in May, with new orders rebounding into expansion at 51.3. However, the employment subcomponent…

Acute geopolitical risks, like a massive oil shock, may be abating. But structural geopolitical risk remains high and could upset a blithe market. Cyclical economic risks are underrated as the US slows down and China continues to stumble. Investors should book some profits in anticipation of tariff implementation and a downturn in hard economic data.
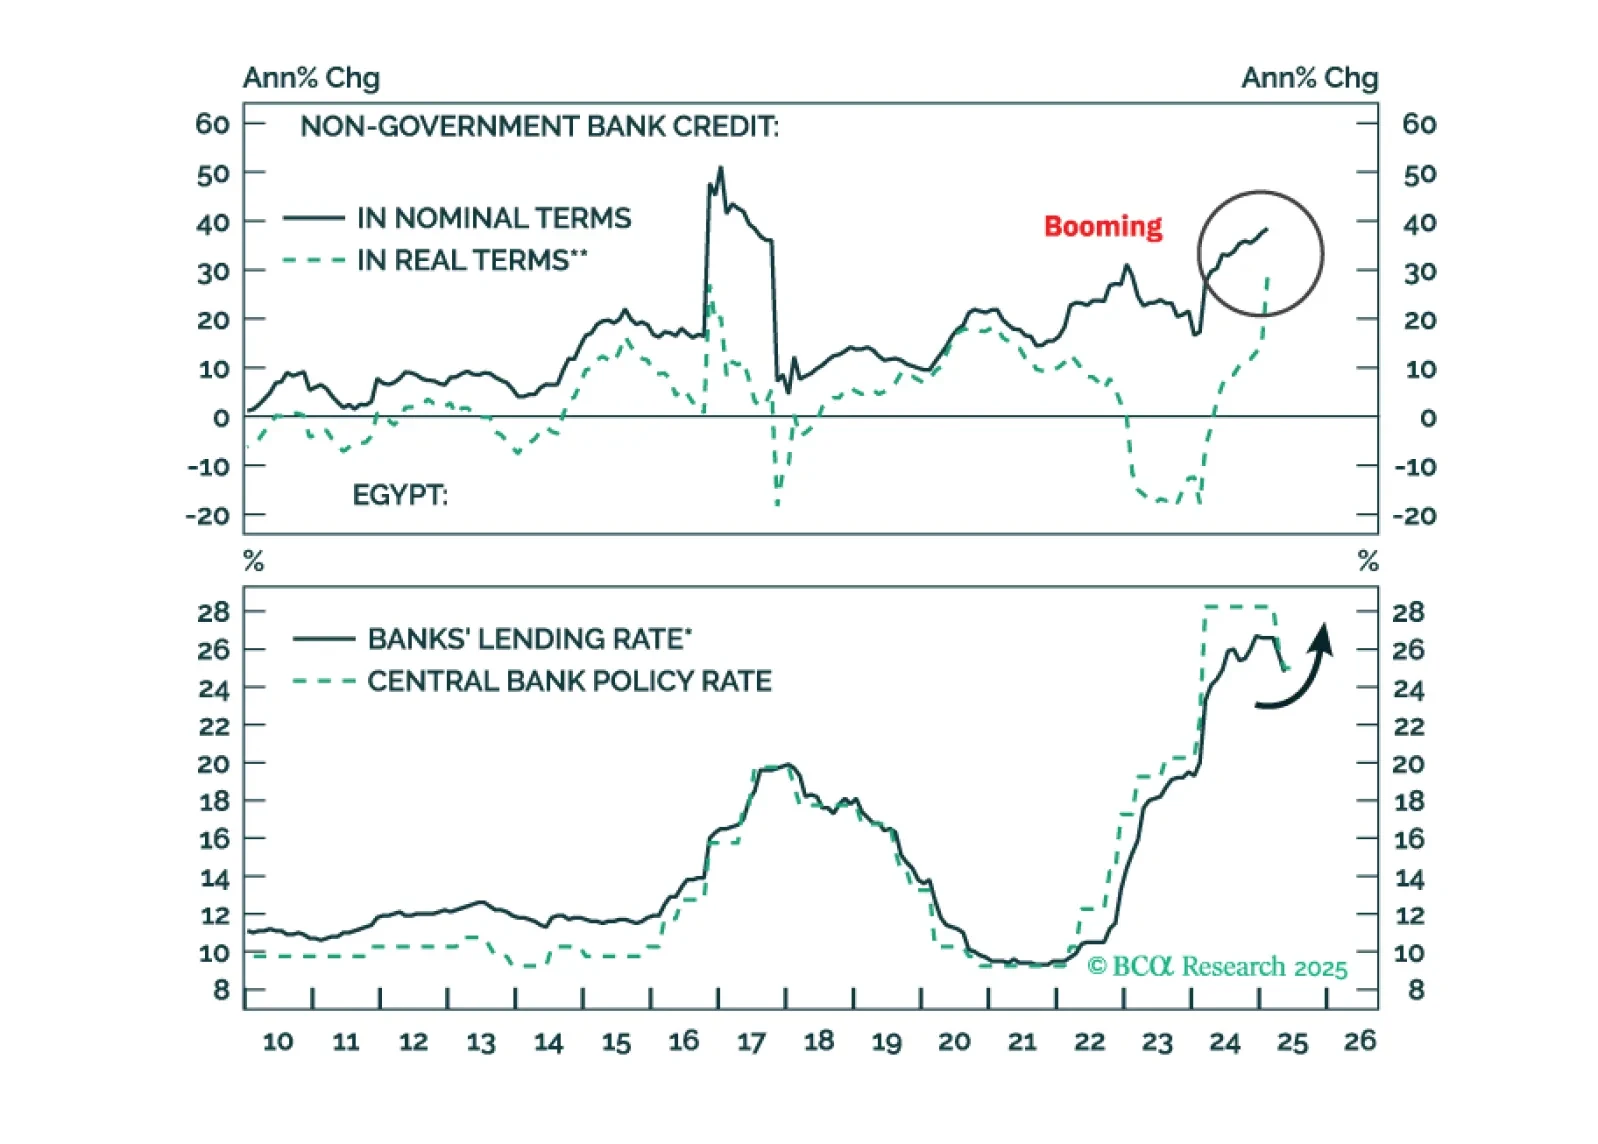
Downward pressure on the pound will rise in the coming months. Inflation will go up, so will bond yields. It’s time to book profits on Egyptian domestic bonds.
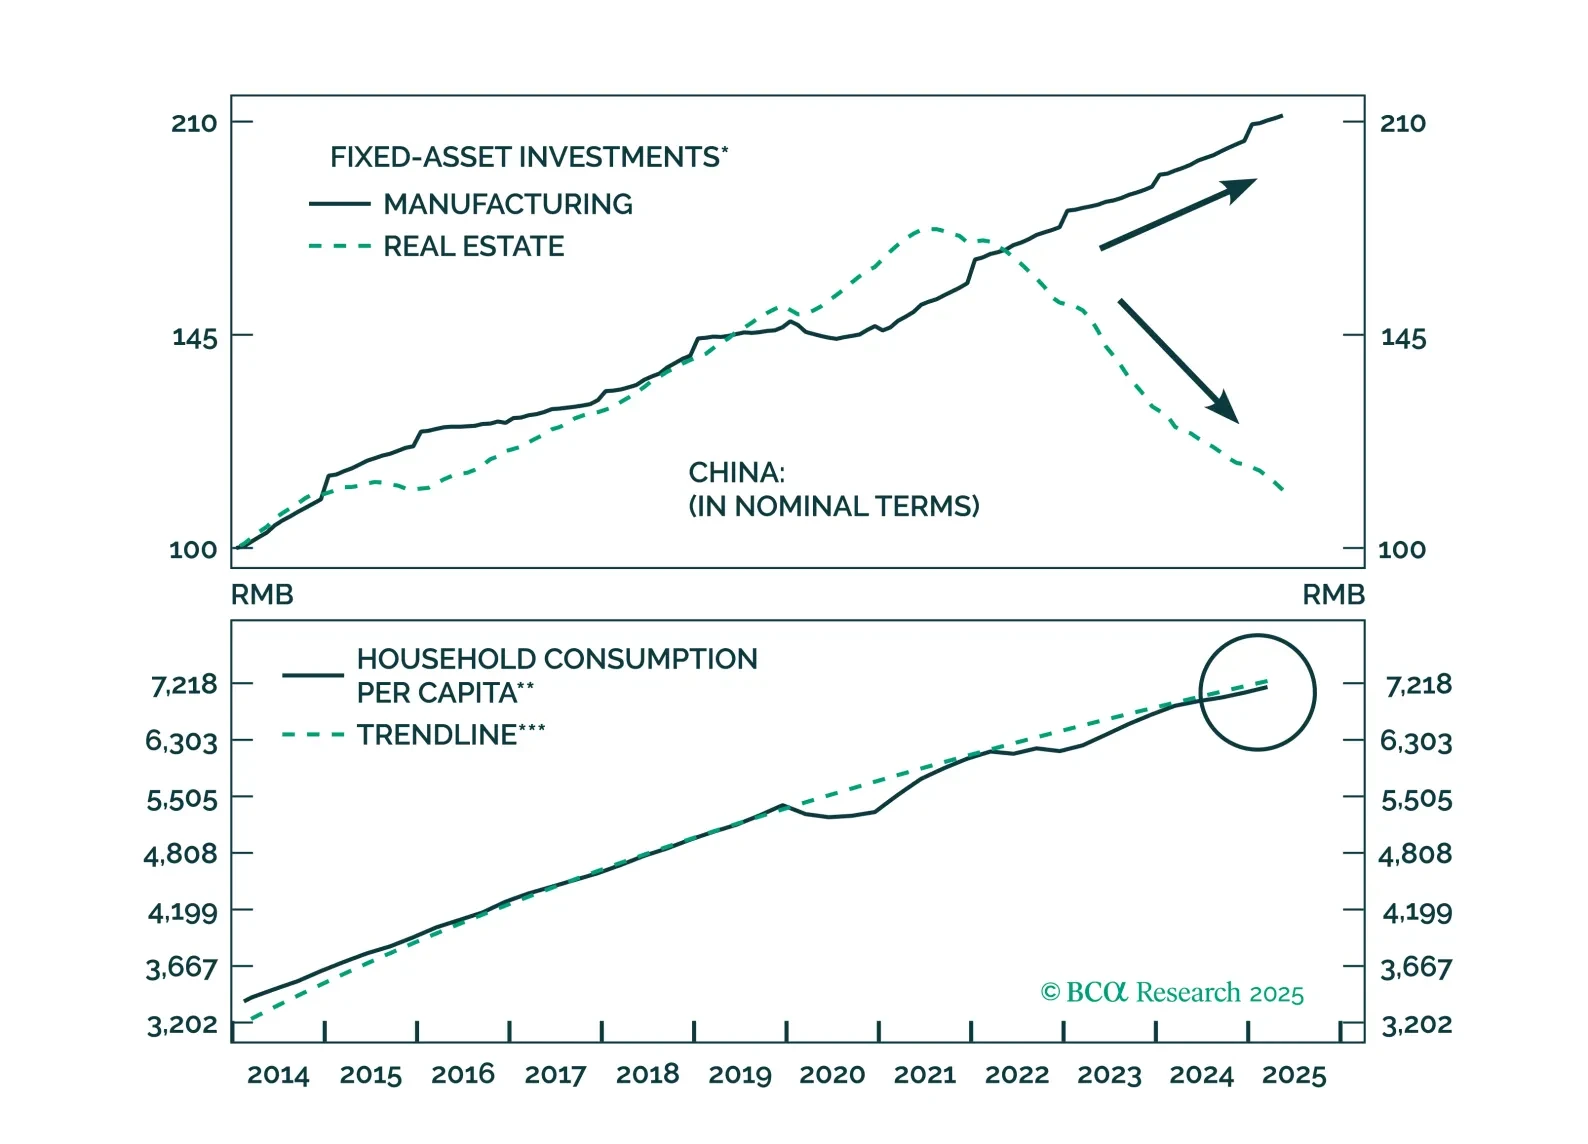
This report analyzes China’s persistent deflation, which is rooted in supply-side forces. Consumption support will be slow and incremental, keeping deflationary pressures elevated for the next 6–12 months.
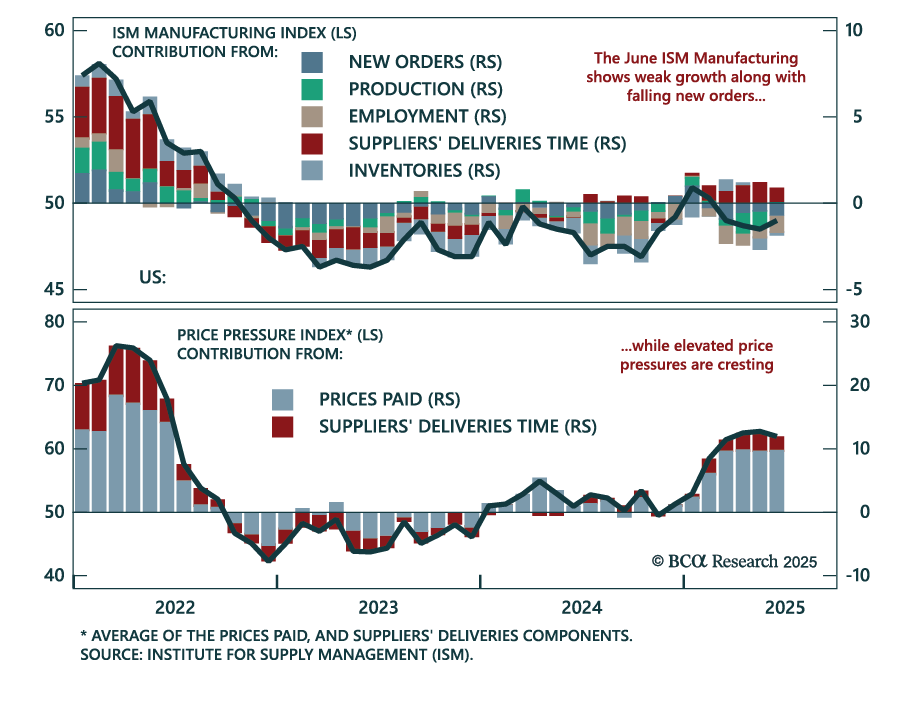
The June ISM points to sluggish US manufacturing and reinforces long duration positioning amid peaking price pressures. The index rose modestly to 49.0 from 48.5 in May, with the rebound driven by slightly higher production and slower supplier deliveries due…
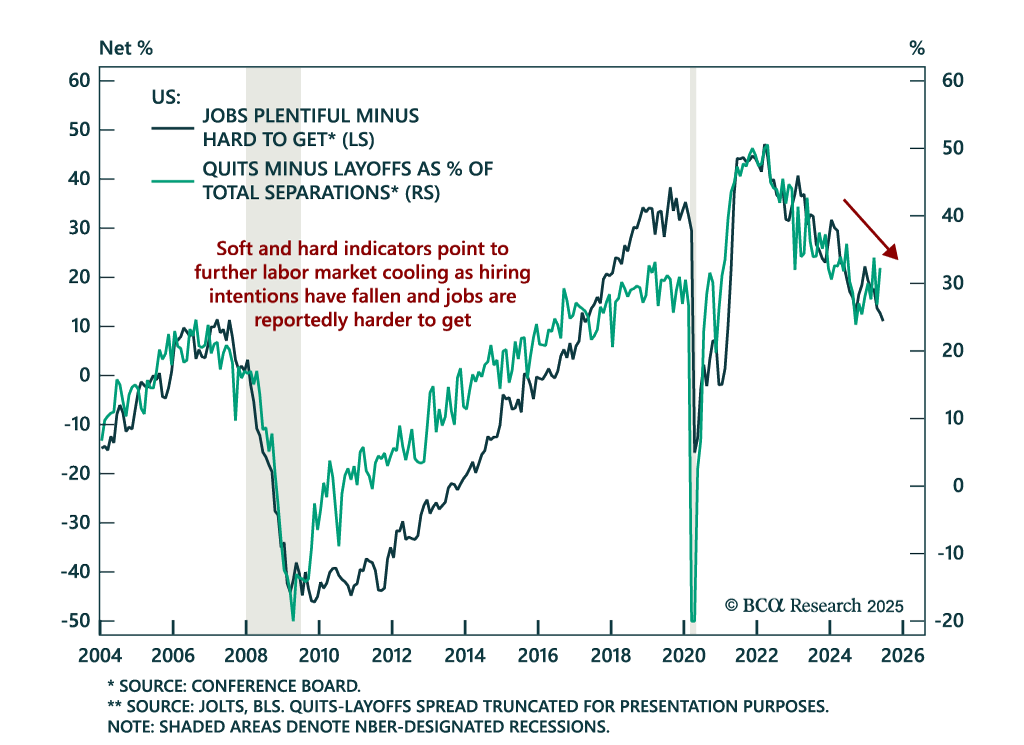
May JOLTS data suggest labor market softening beneath the surface, reinforcing a defensive stance across portfolios. Job openings rose to 7.7m from 7.4m, beating estimates, while quits ticked up to 3.3m and layoffs fell to 1.6m. However, hiring edged lower to…