AI
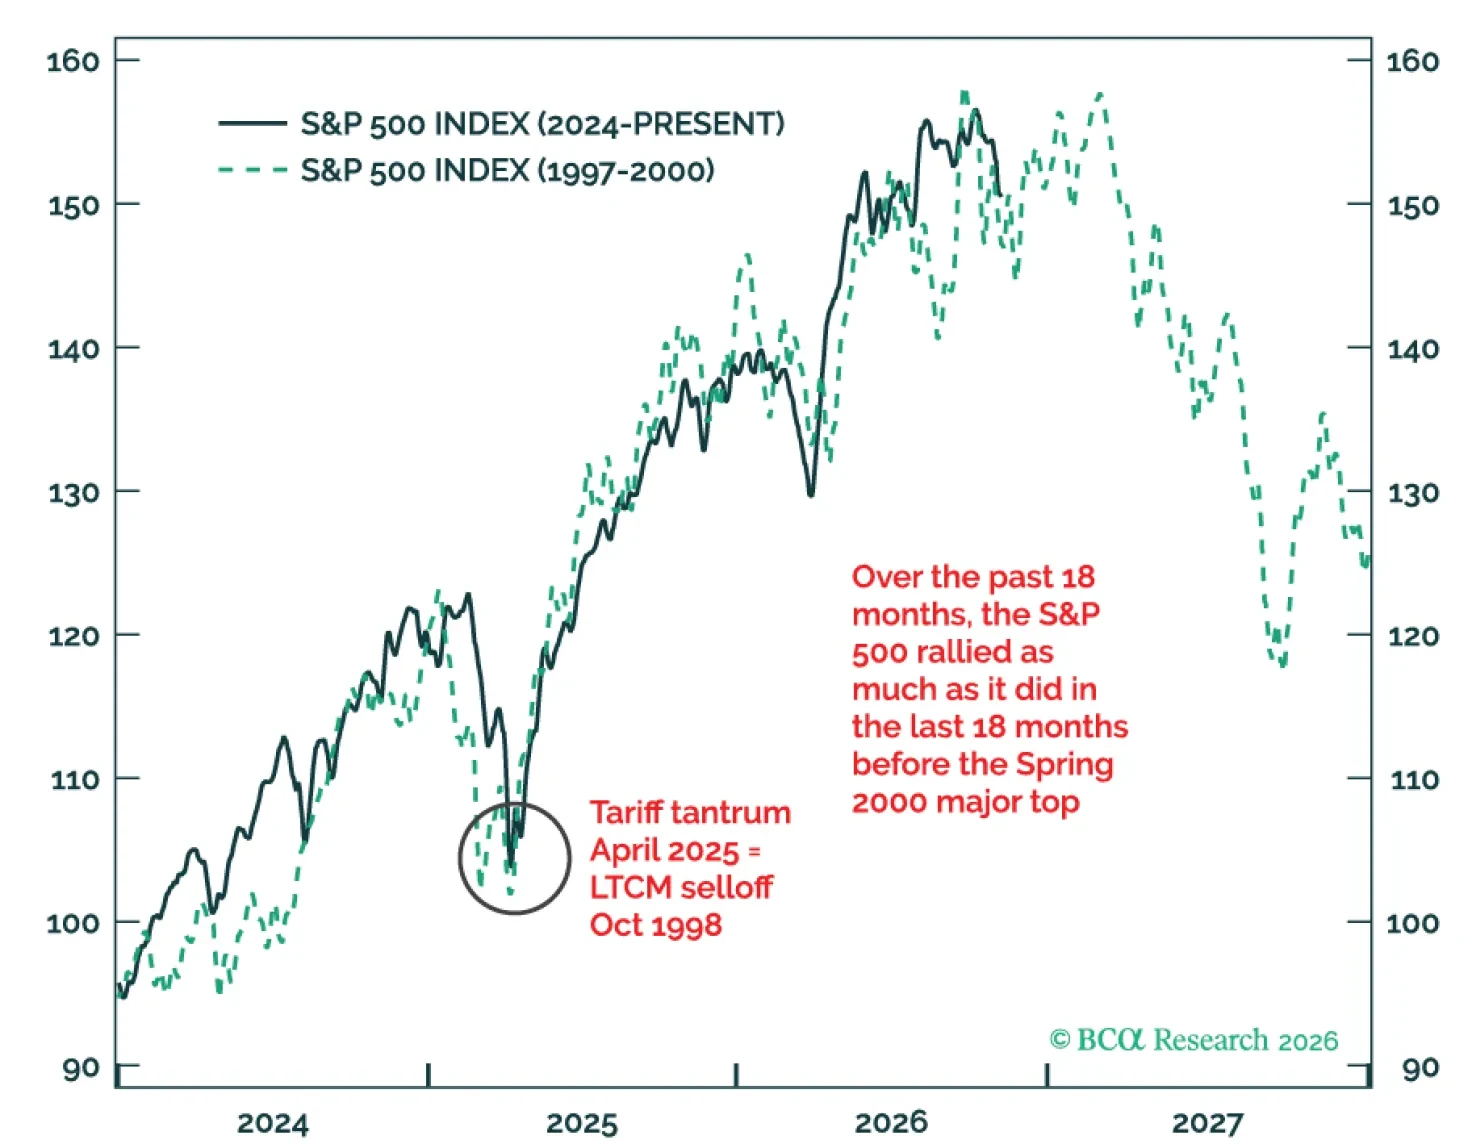
Resist buying the equity dip: a major global market top may already be behind us. Sell the US dollar on strength. Accumulate bonds on weakness, favoring those in countries with current account surpluses.
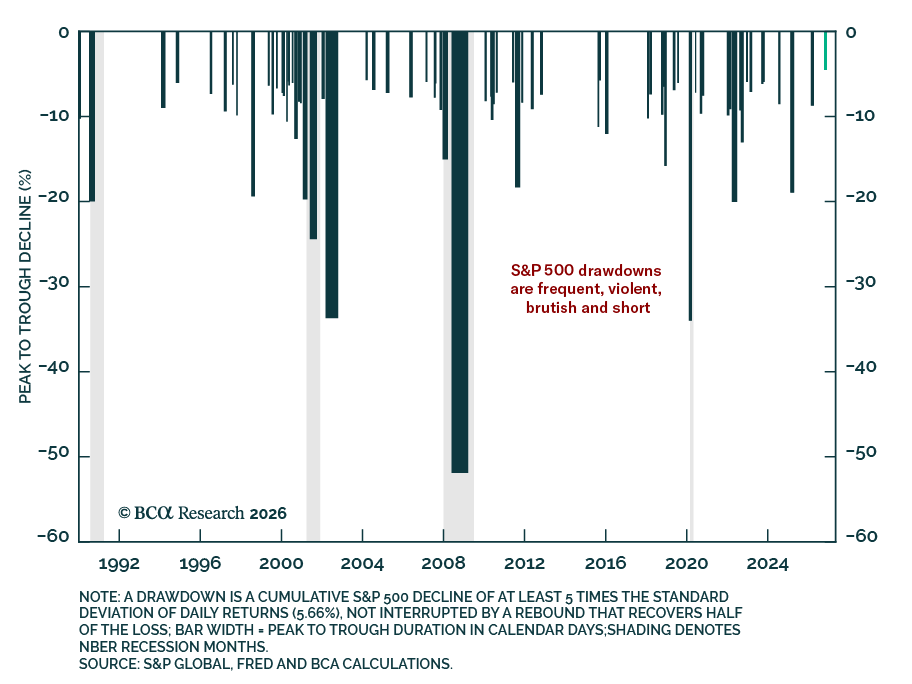
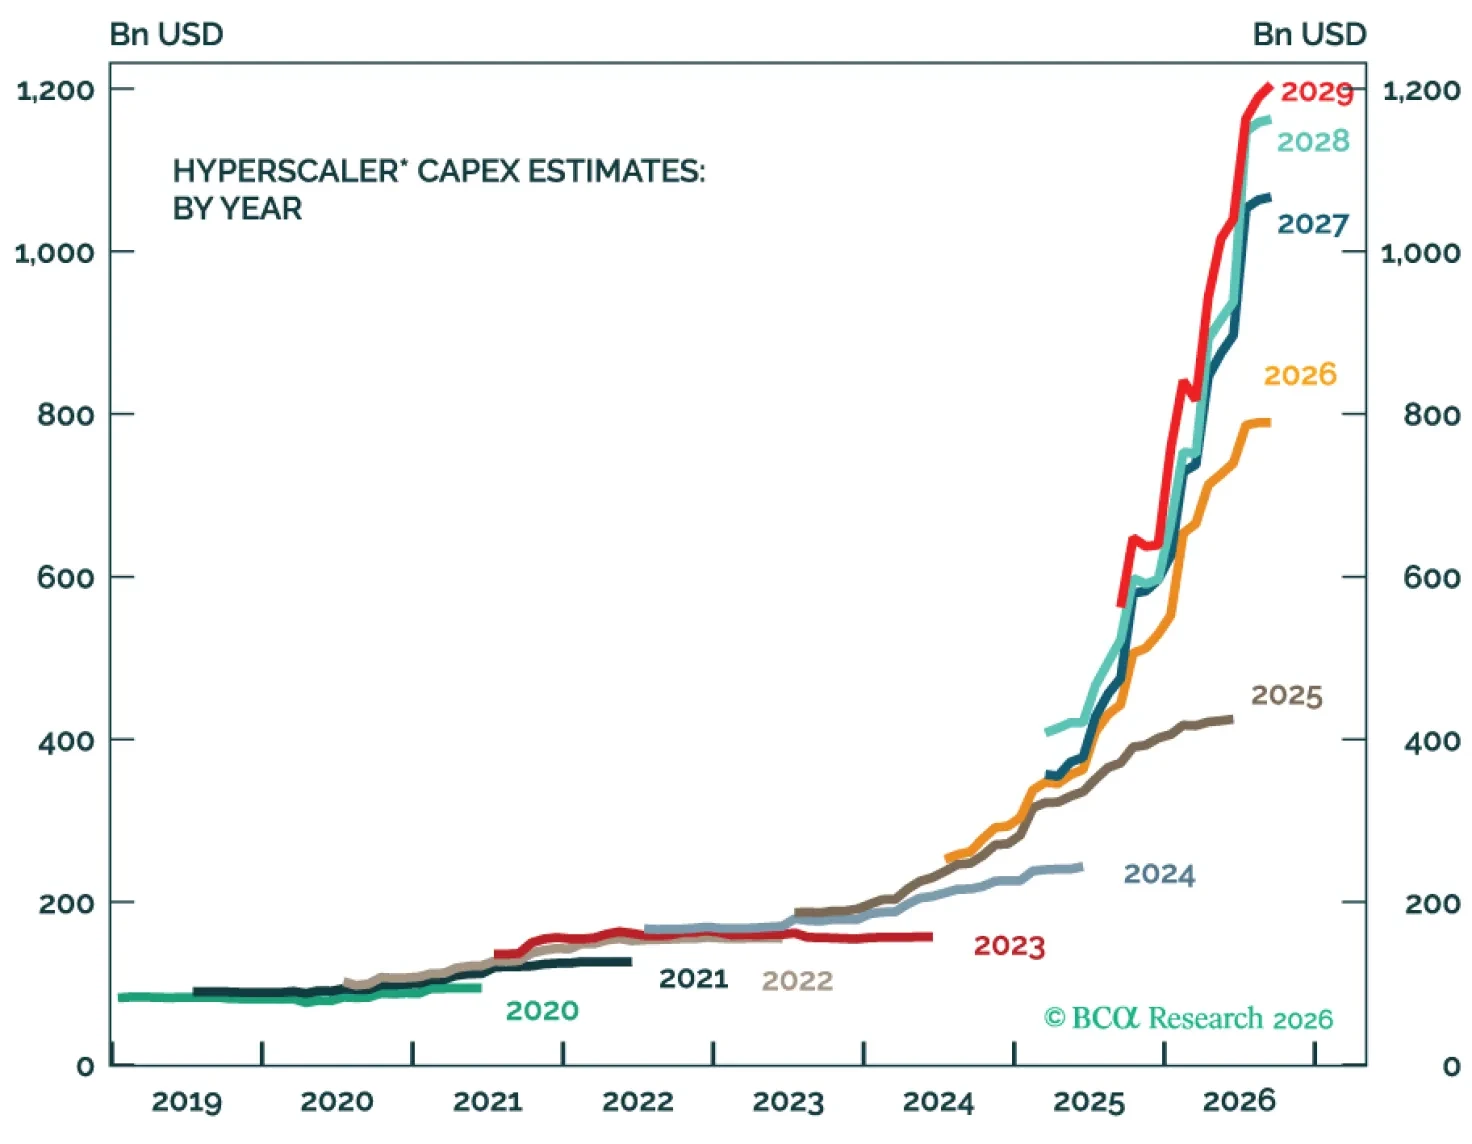
AI capex concerns have pushed the S&P 500 to the brink of a drawdown. But the cycle remains strong, drawdowns rarely last long, and Tech valuations had already compressed. And while Democratic governors now oversee about 80% of the data-center pipeline, a blue governor alone is not necessarily a build-out moratorium.
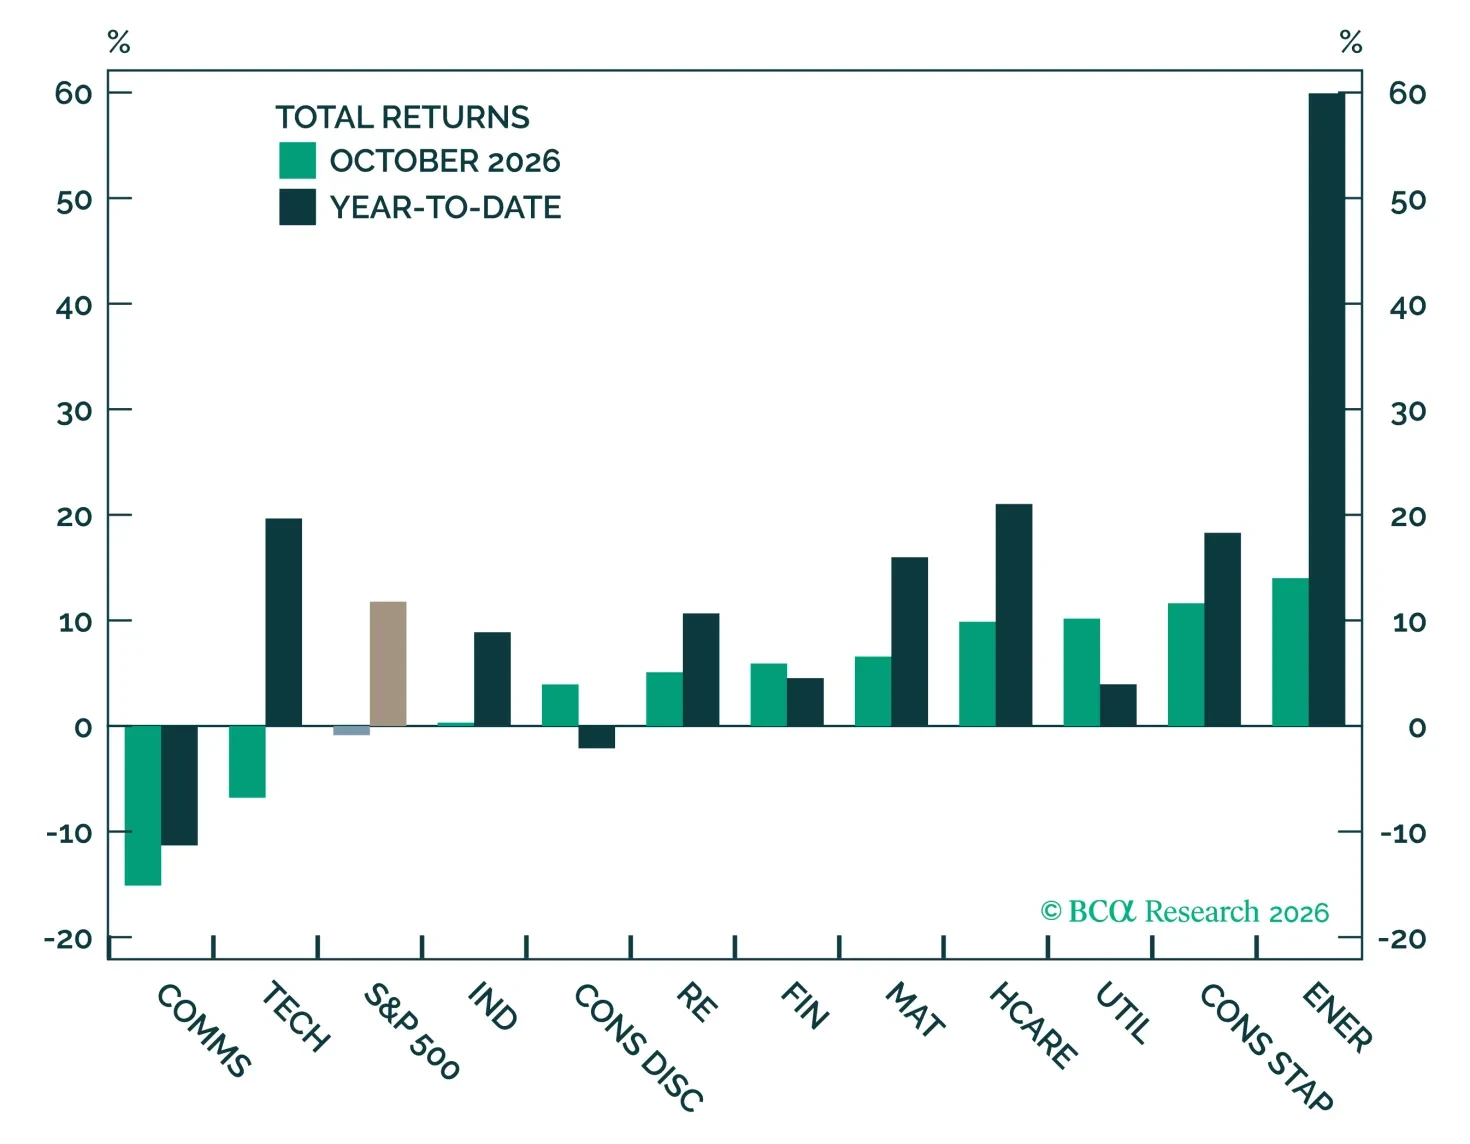
October saw a 0.9% decline in the S&P 500, dragged lower by Communication Services (-15.1%) and Information Technology (-6.8%). All other sectors delivered positive returns, led by traditional defensives – Health Care (+9.9%), Utilities (+10.2%), Consumer Staples (+11.6%) – and Energy (+14.0%). Although our overweight Tech call surrendered some performance during the month, IT has still gained 37% since the view was initiated on March 30, outpacing the S&P 500’s 20% advance.
Today's report examines several of the most interesting ideas we've heard over two weeks of meetings and calls with investors.
Marking the debut of Chief Technology and Innovation Strategist Matt Dyson, this month’s Global Market Outlook examines Matt’s views on the presence and durability of moats for companies at various segments of the AI chain.