Latest from BCA Research
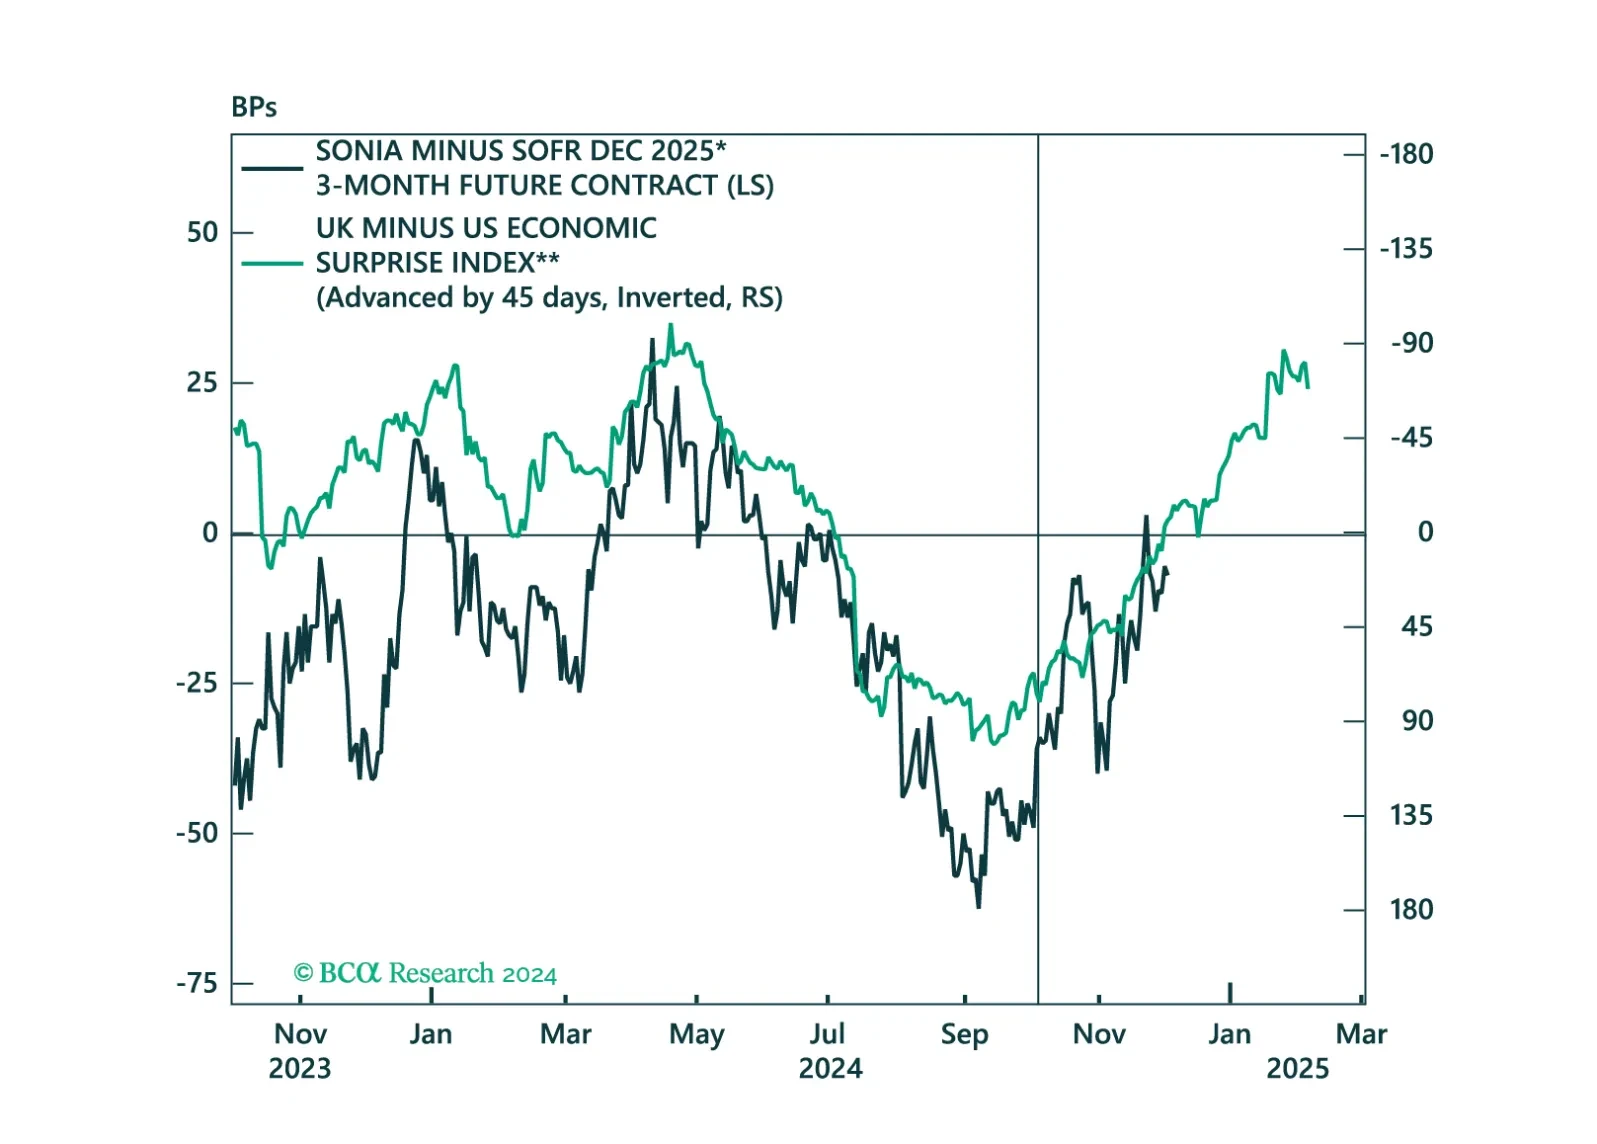
This report reviews our FX and Fixed Income trades over the last year. We look forward to sharing our thoughts for 2025 next week.
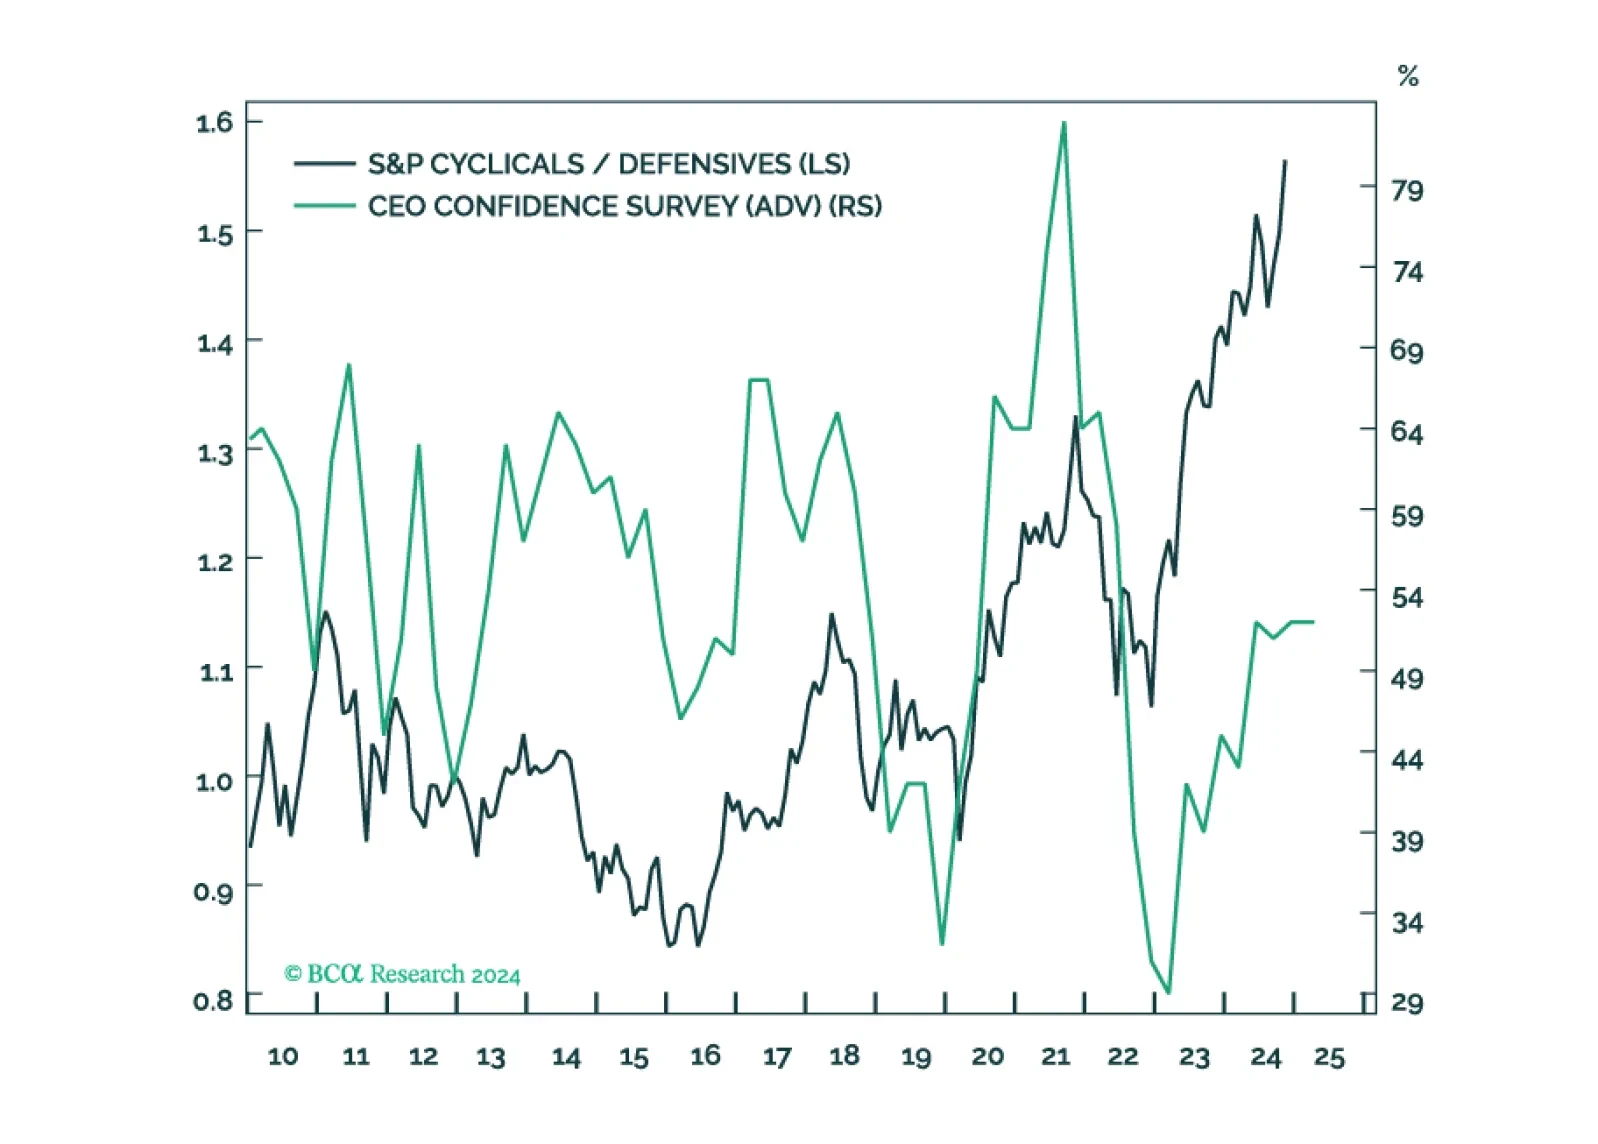
This week, we send you a Style Chart Pack without a front section. We are currently working on the 2025 outlook, which will be released on December 9.
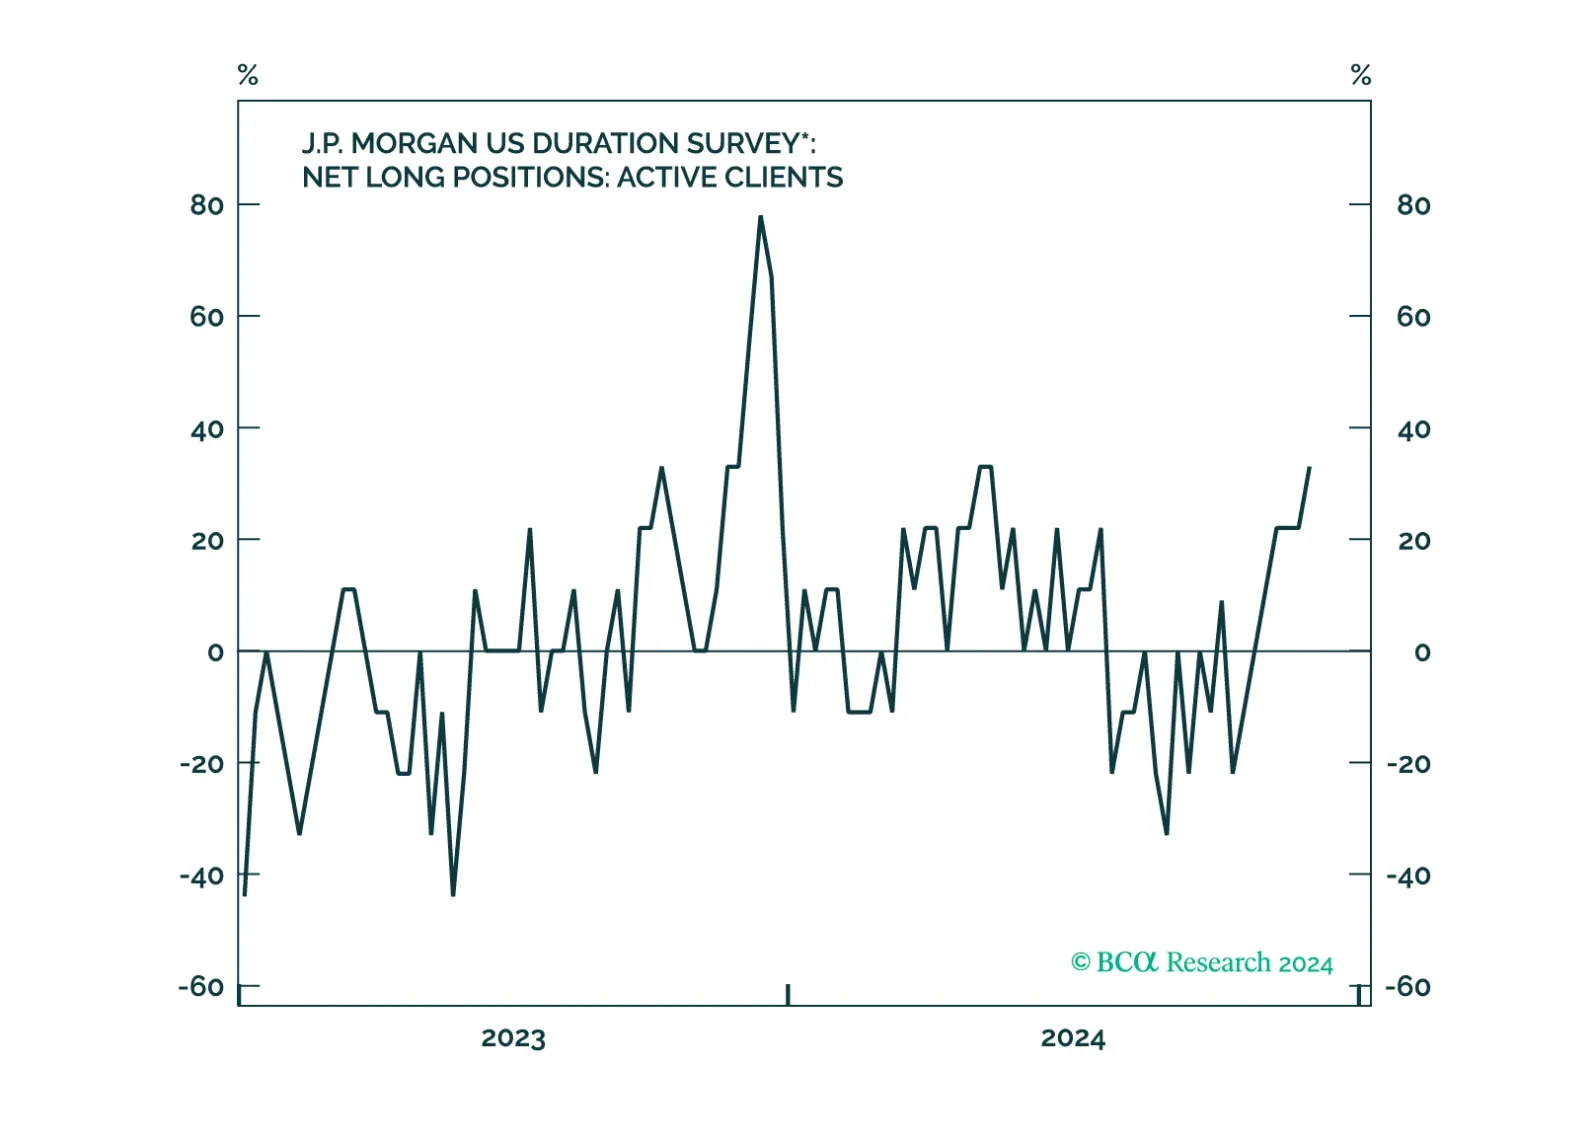
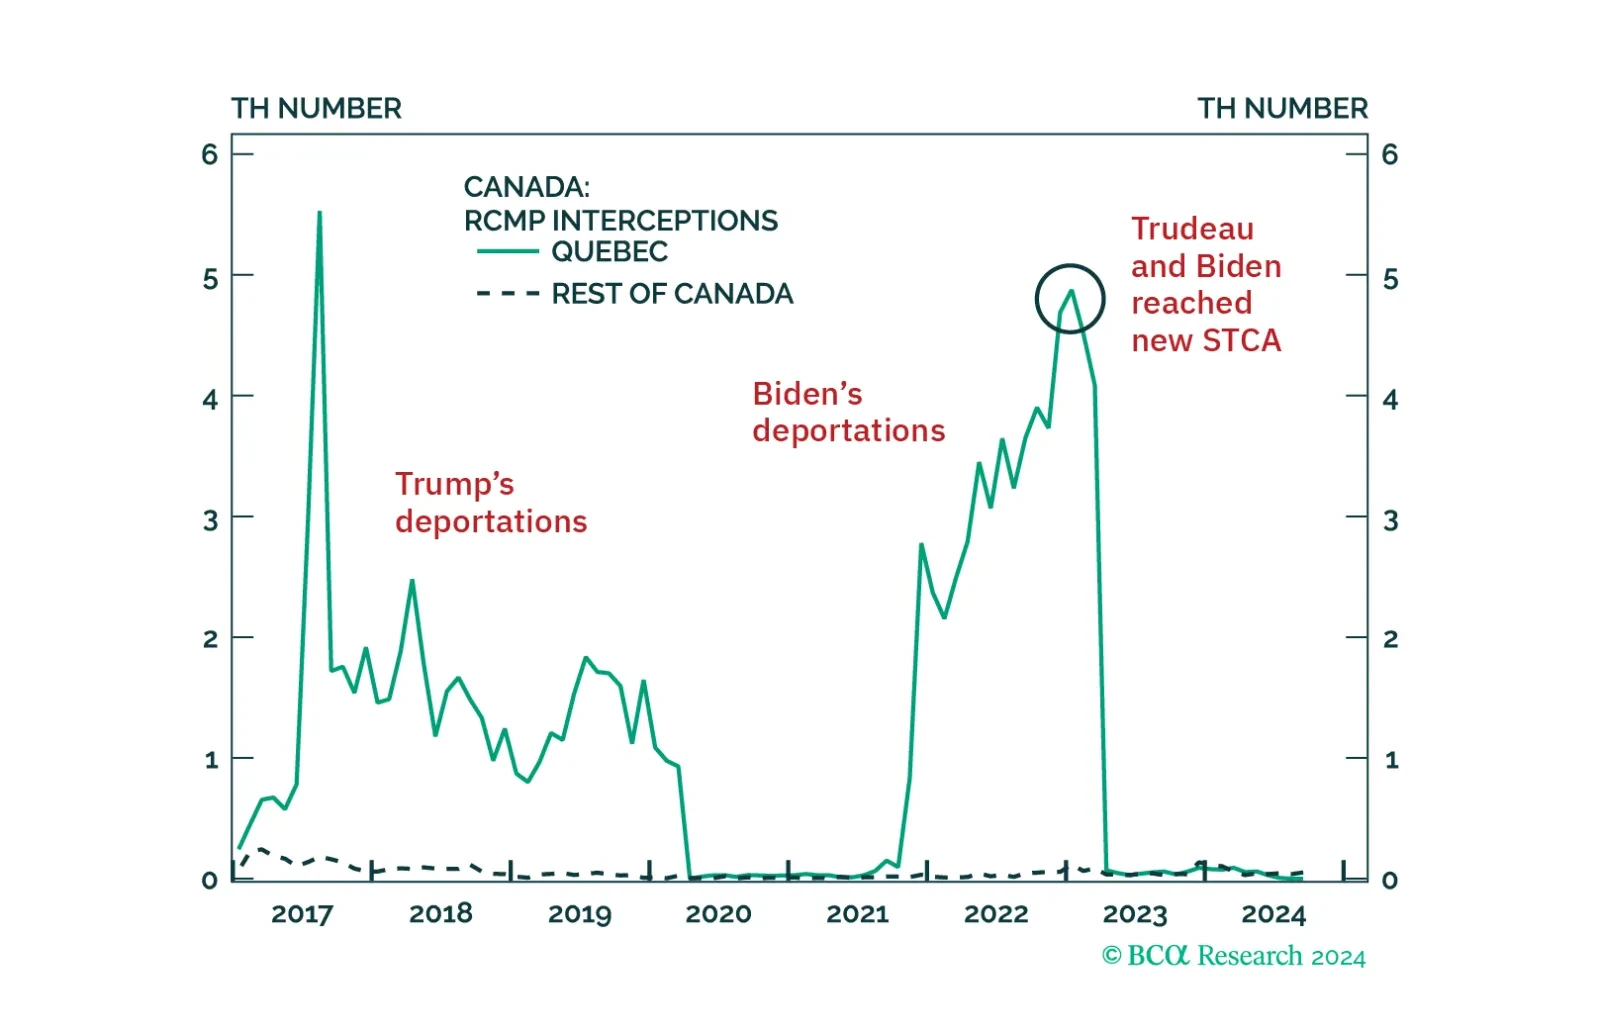
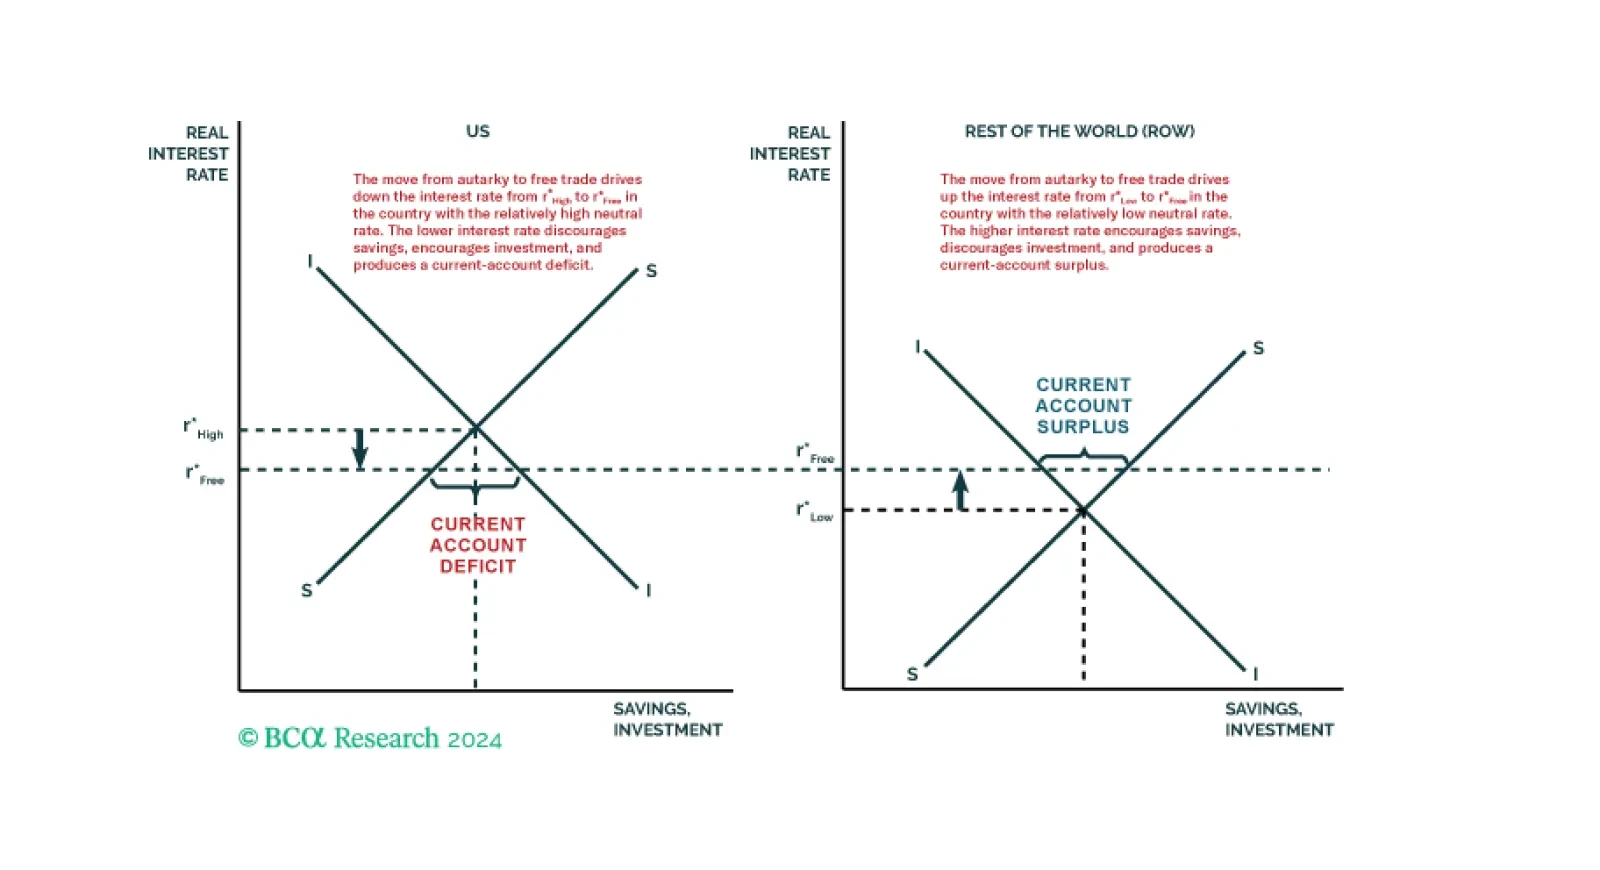
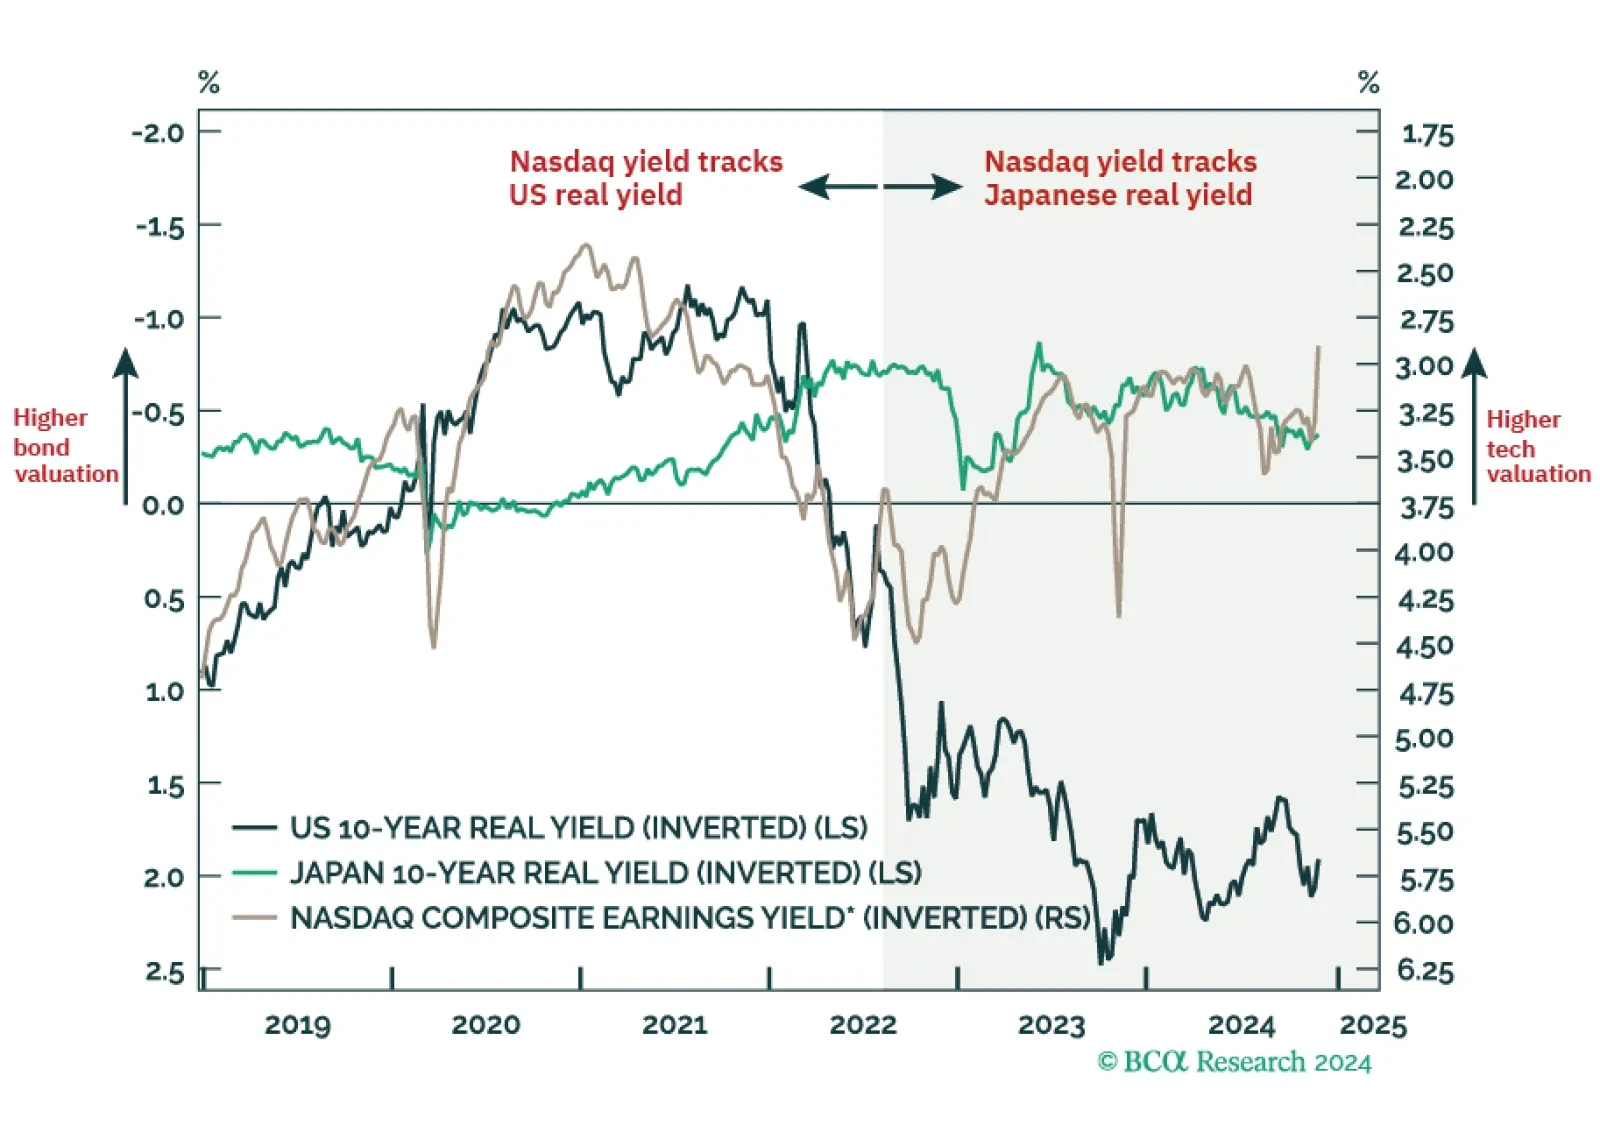
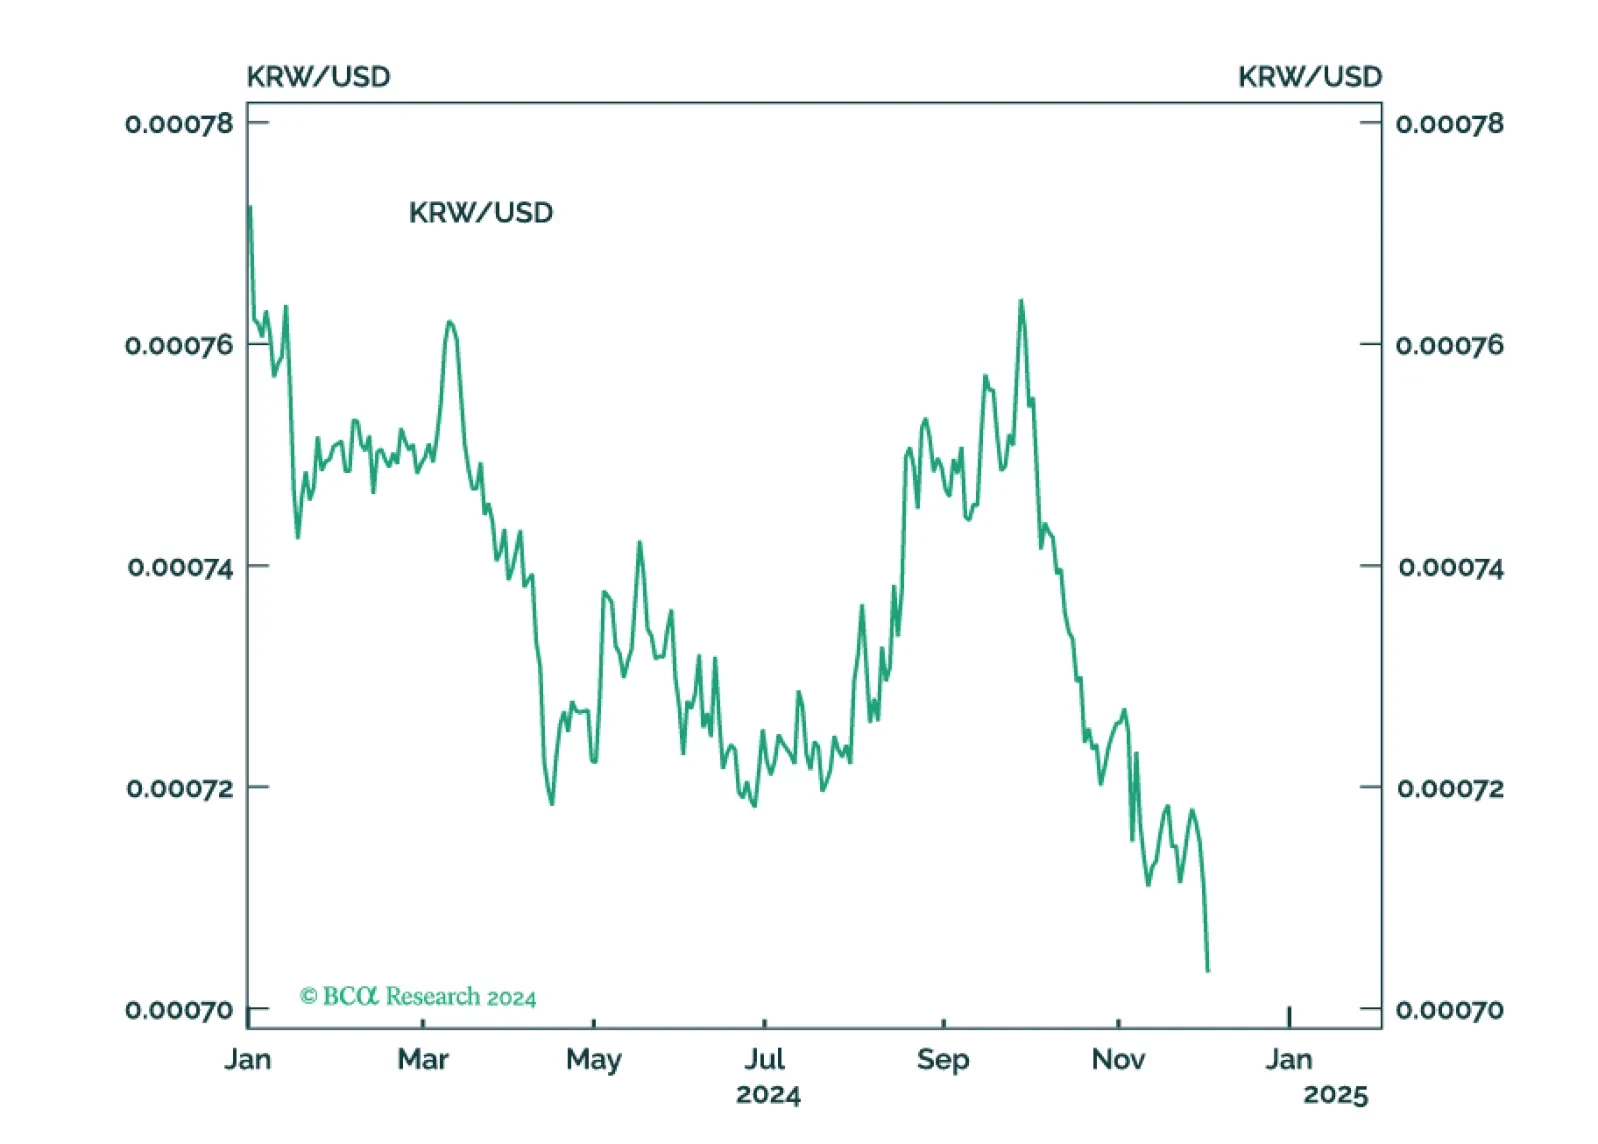
The flurry of global political instability that we expected after the US election is coming to pass. Investors should de-risk in the near term as stocks are flying high but face the turmoil of Biden's last months and then Trump tariffs.
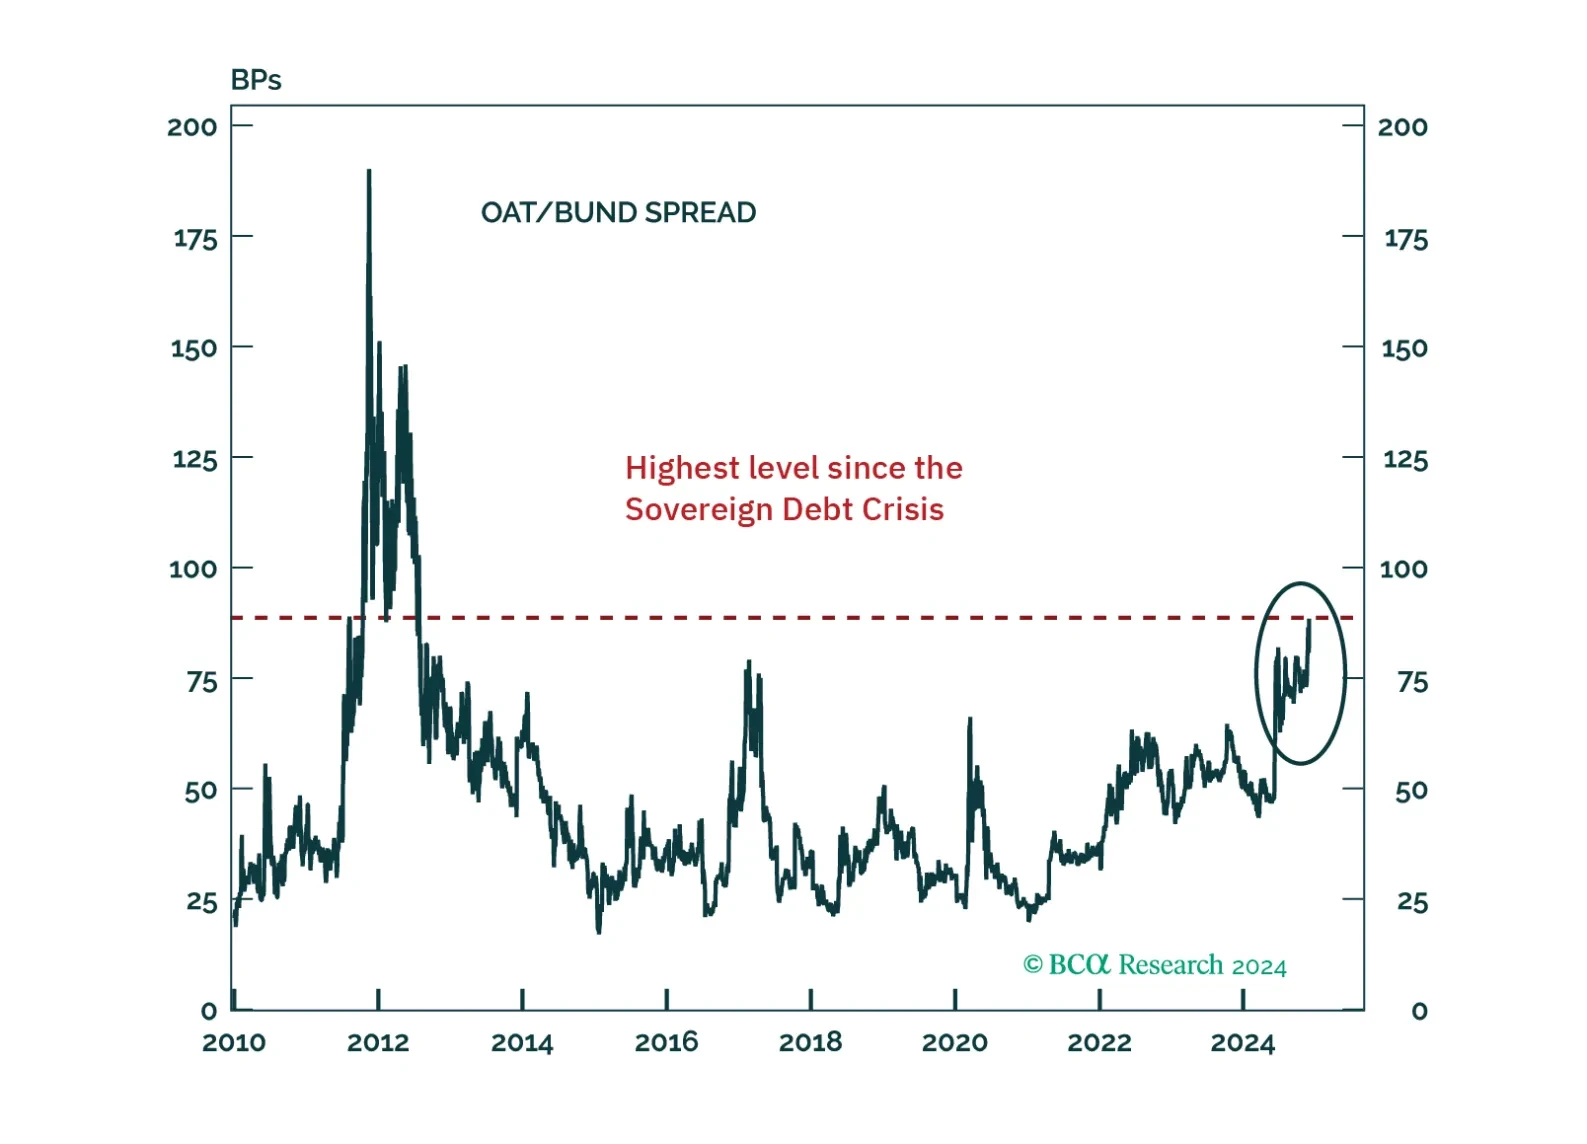
France finds itself in a unique, thorny situation. Can it heave itself out of it? And what does it mean for investors?
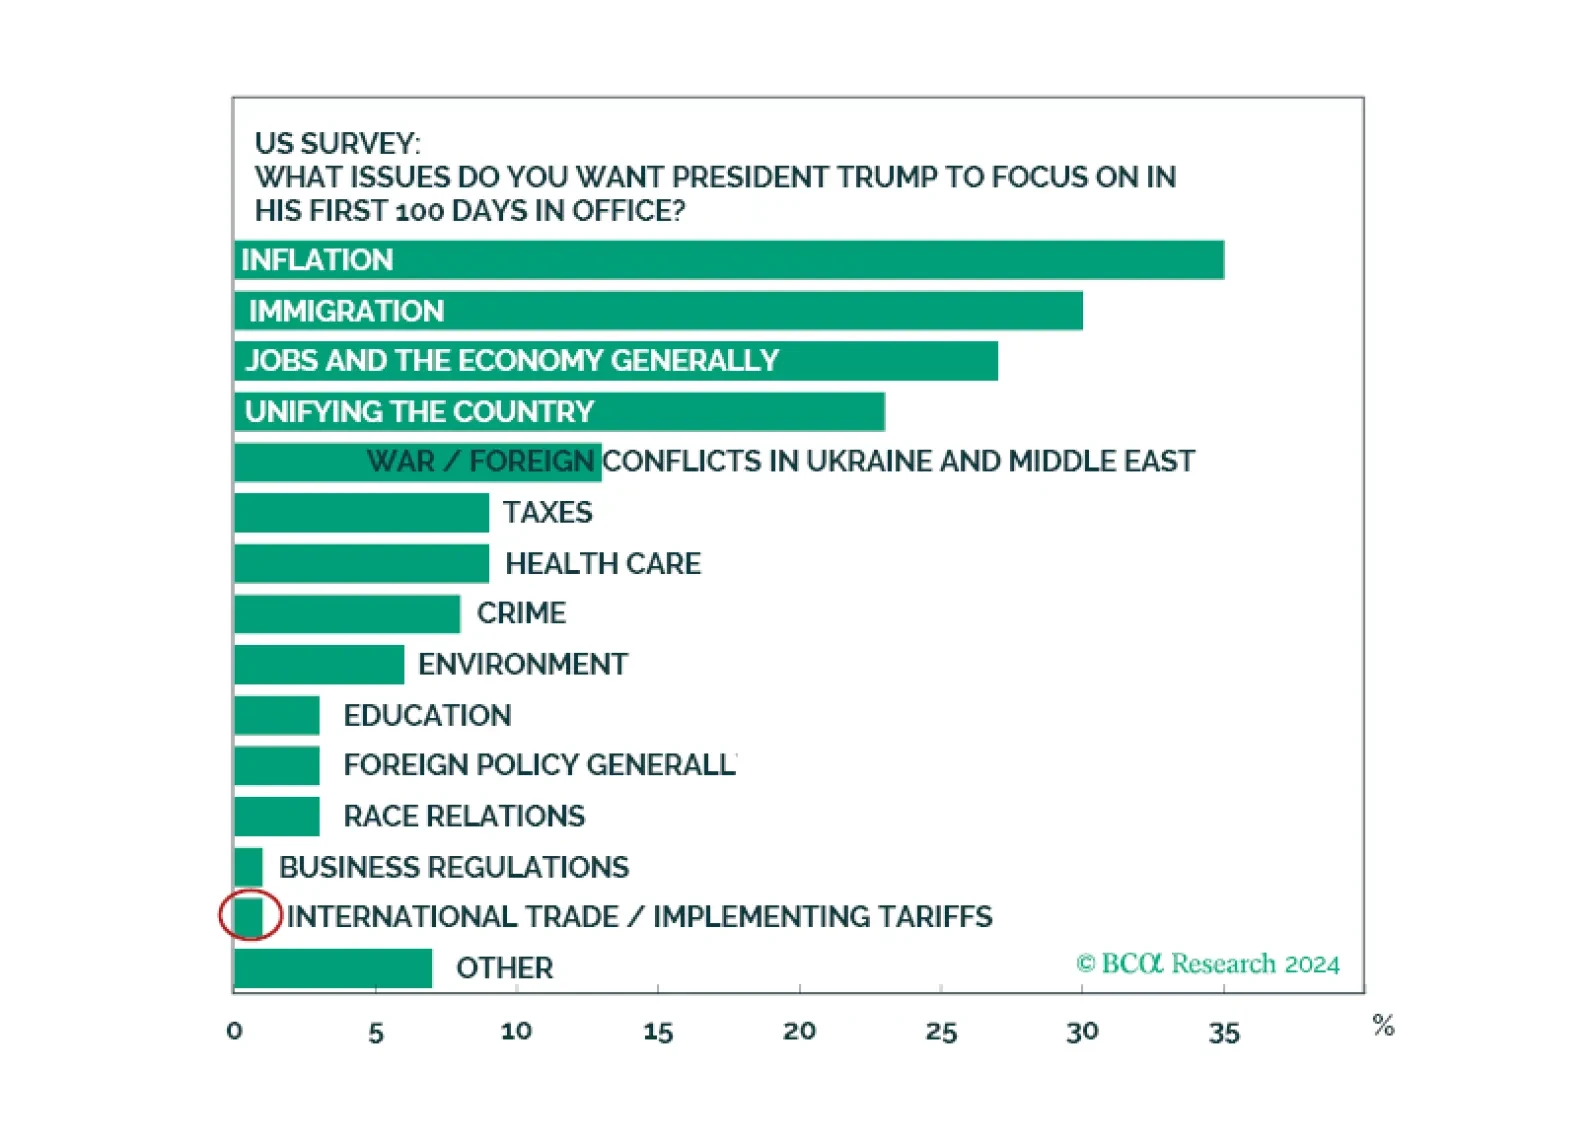
In our Alpha report, we deliver our Annual Forecast. The current macro narrative is that the US will continue to outperform the rest of the world, in large part because President Trump will again deliver fiscally led growth and global tariff carnage. In our view, 2025 will be the year of “Peaks.” Peak fiscal profligacy, peak de-globalization hysteria, and peak geopolitical risks. All three will reverse US Exceptionalism. But getting ahead of that trade is folly. For the time being, we concede that it is “America First” on all fronts. Particularly with the Greenback being a momentum currency.
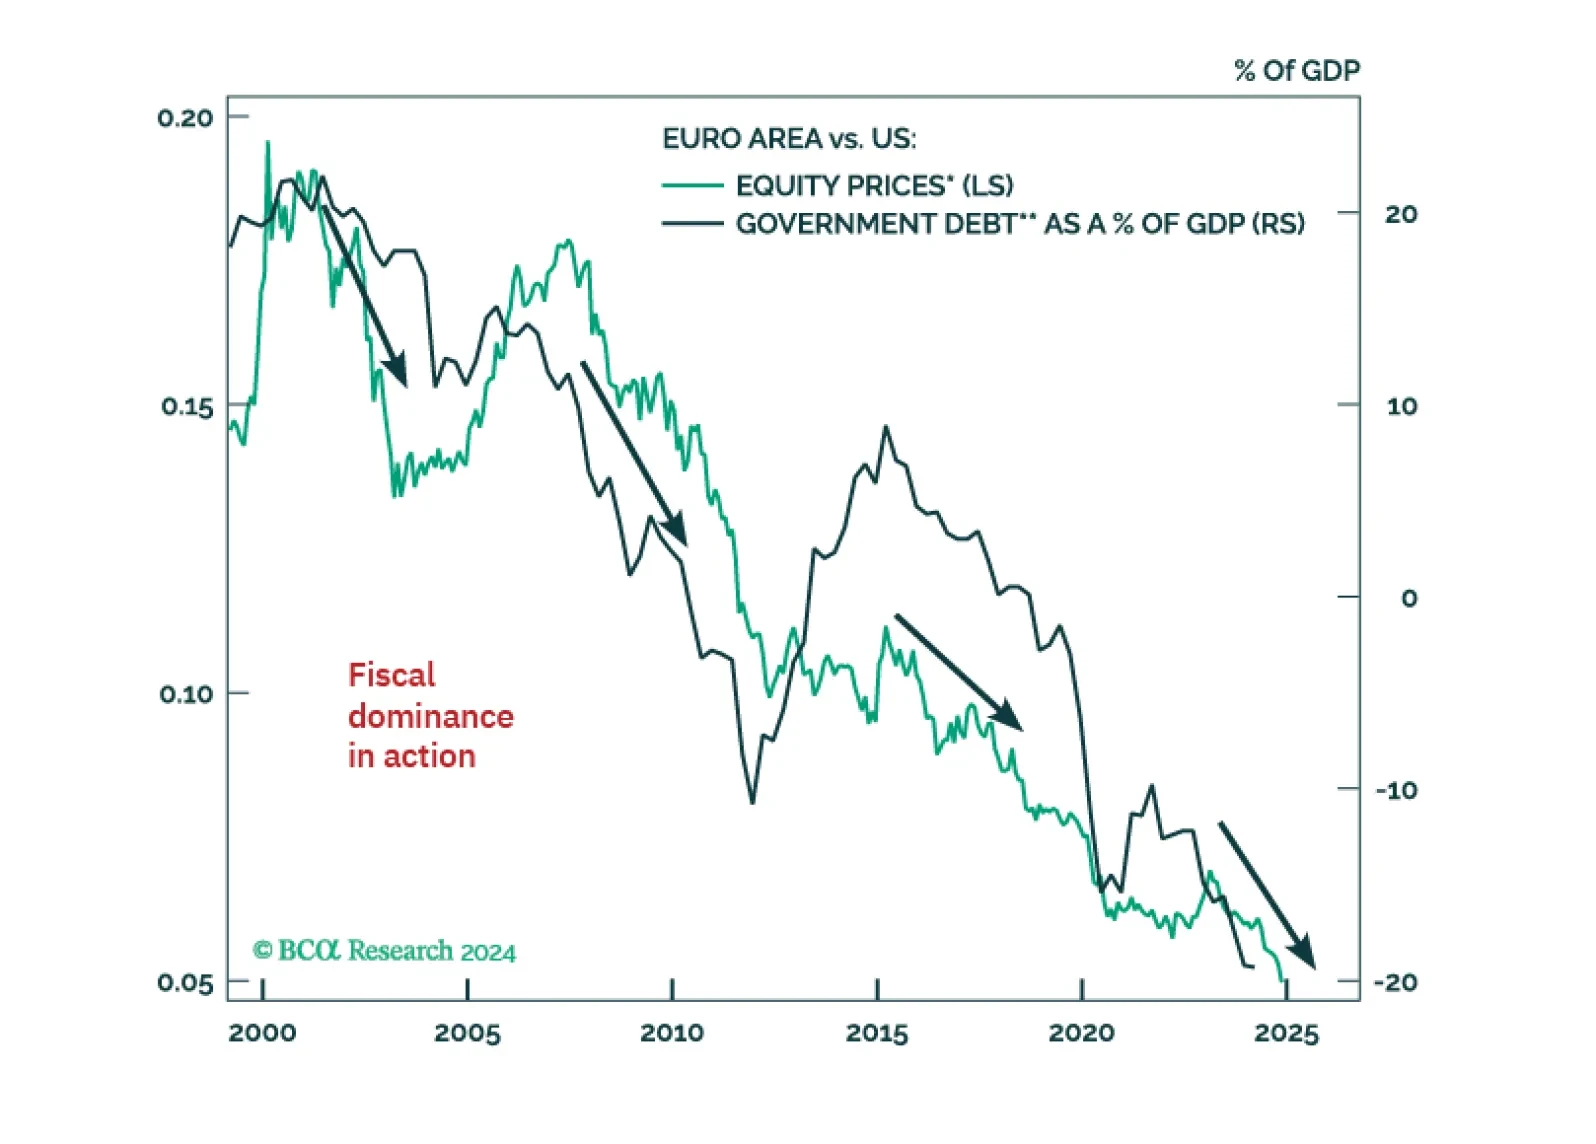
Investors have given up on European assets, which now suffer exceptional discounts to US ones. However, tighter US fiscal policy, the end of Europe’s austerity and deleveraging, the LNG Tsunami about to hit European shores, and the global capex fueled by the Impossible Geopolitical Trinity mean that Europe’s time to shine will soon come back.