 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
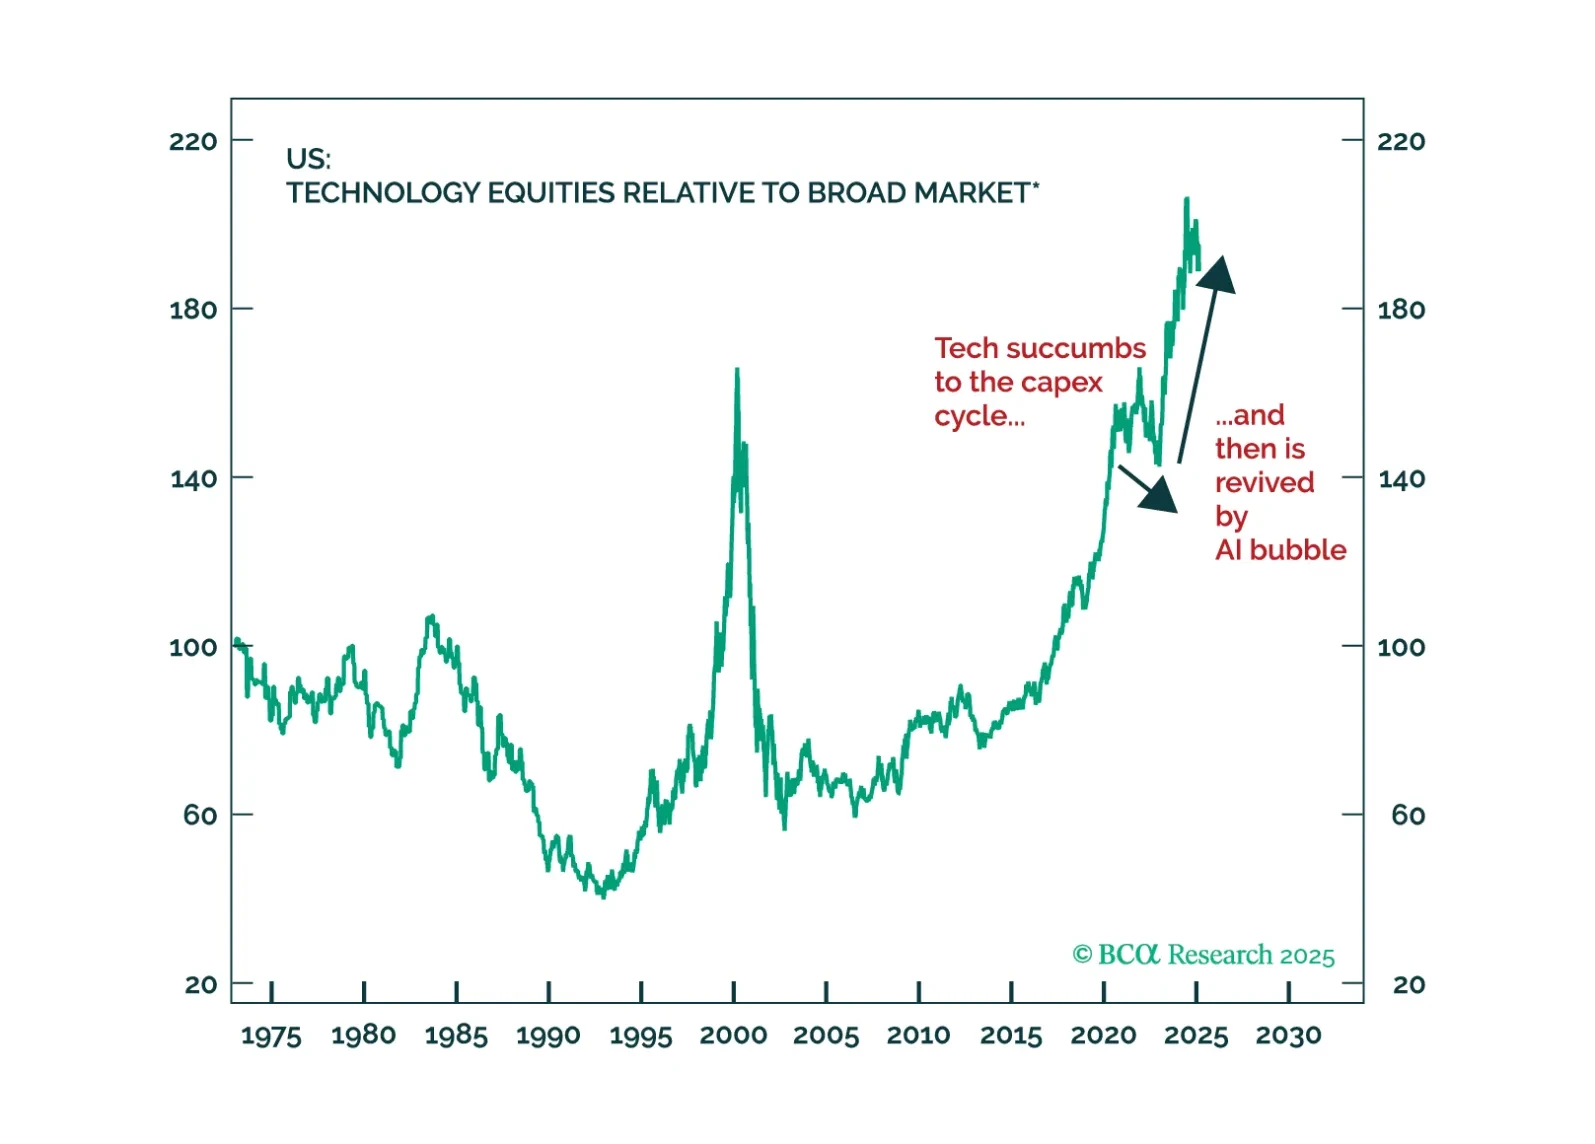
Are you sure you are in a trade war-induced selloff and/or recession? Or, is America – writ large – the bubble? Fed a steady dose of fiscal profligacy over the past five years, the US economy and its various associated assets have become fat and complacent. As such, the end of the fiscal gravy train – our signature macro call for 2025 – is what is causing the underlying weakness, with the Big Tech – the biggest beneficiary of US Exceptionalism – now buckling. Our message? The tech bros are lying to you. The AI revolution is not positive for Big Tech, not at their current valuation. Play the rotation, even if a (mild) recession may be afoot, as we have been saying throughout 2024.
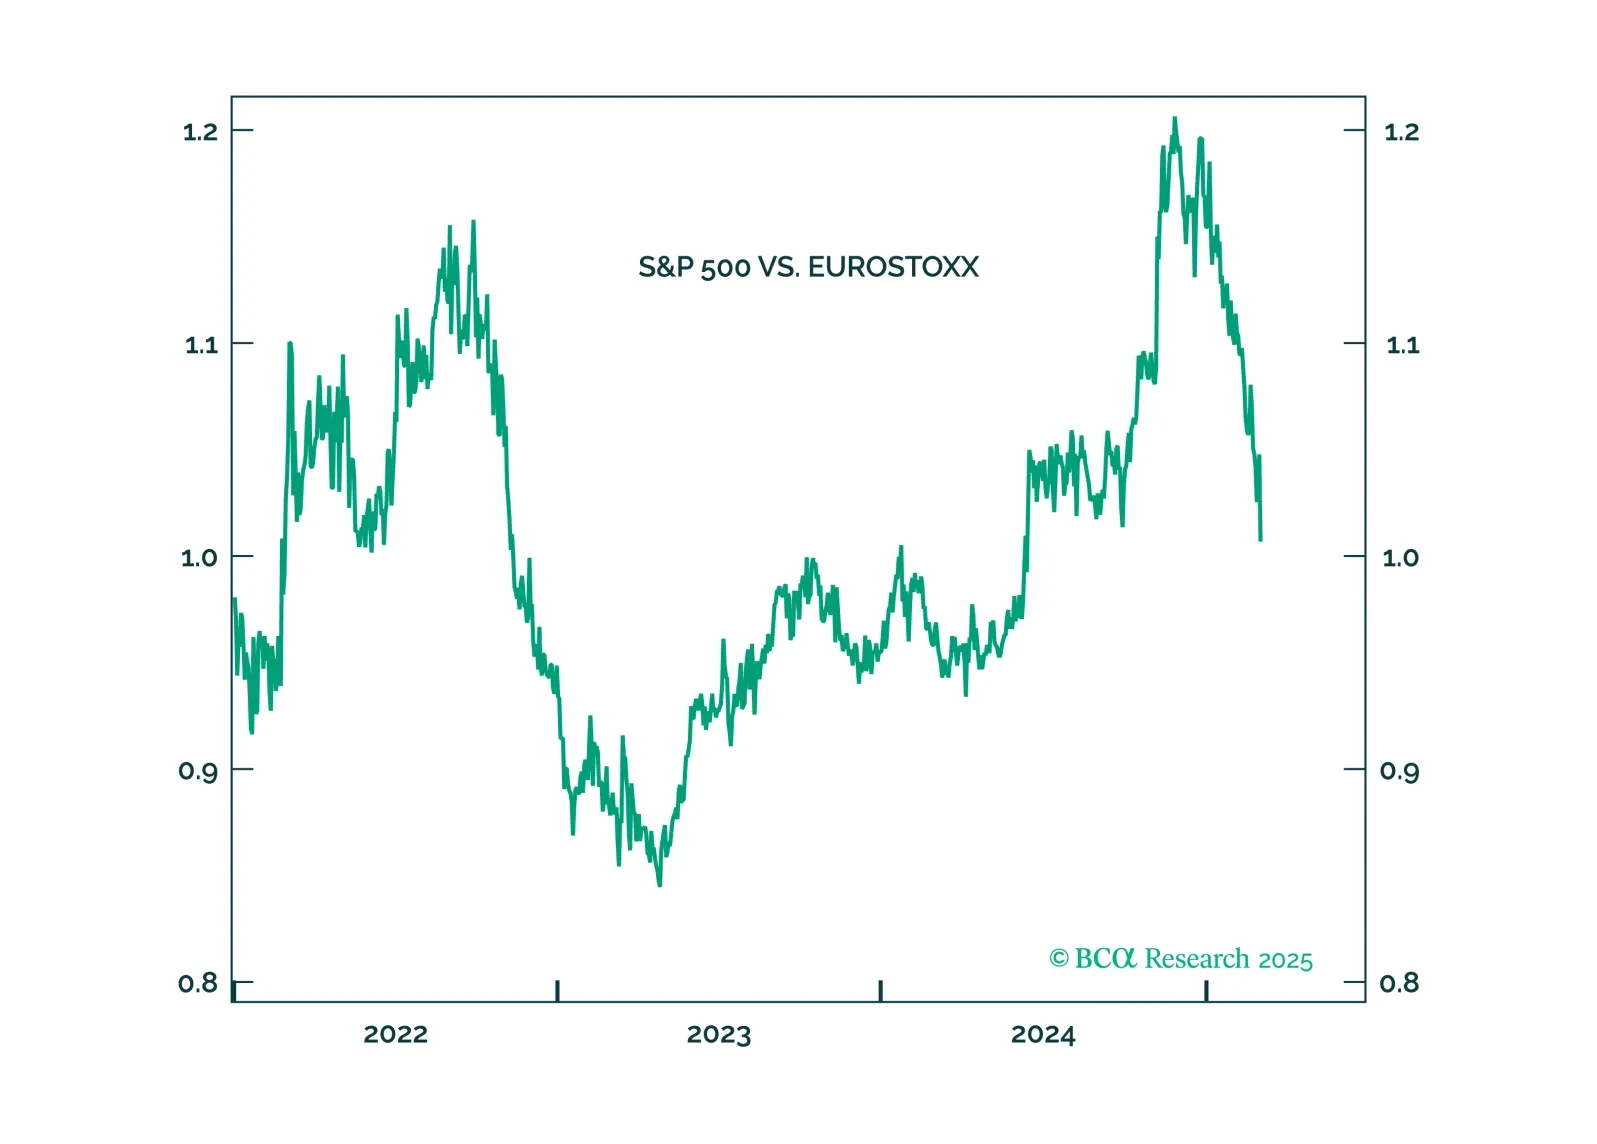
Trump will pull back from the trade war when stocks approach bear market territory. He will not withdraw from NATO. Favor European stocks on fiscal policy.
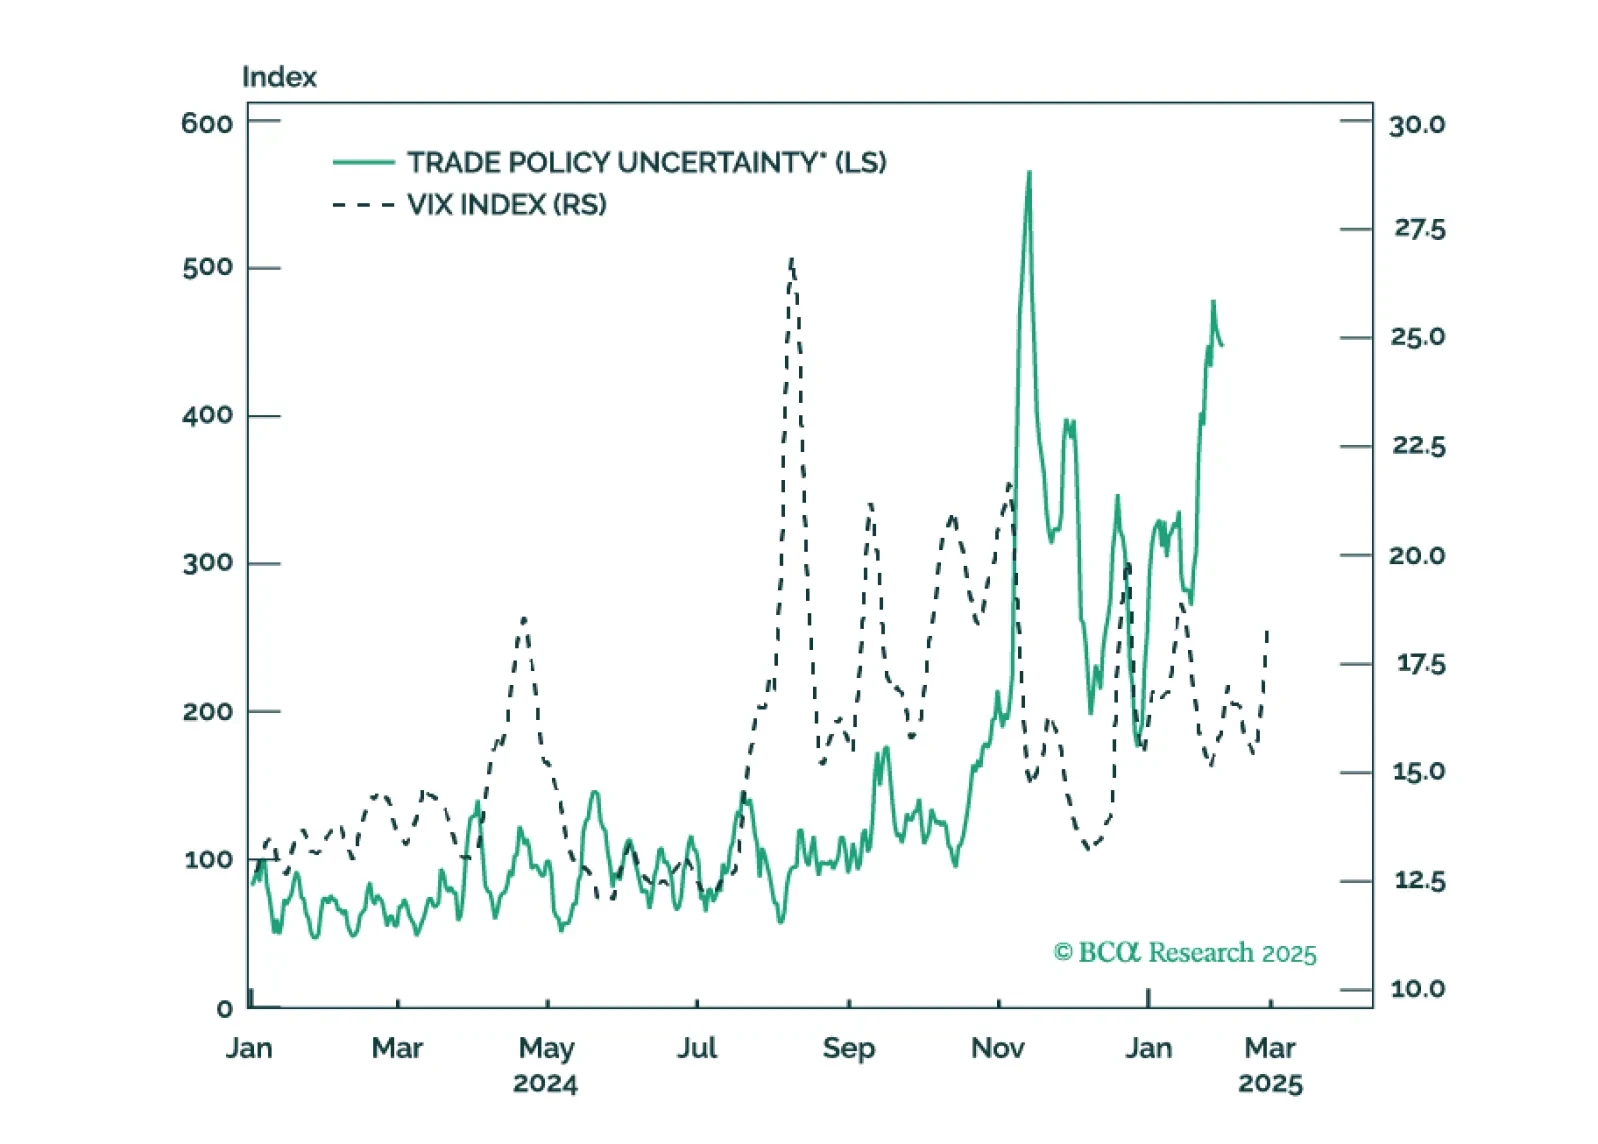
Our defensive strategy for 2025 is coming to fruition so we are re-initiating some of our defensive and risk-off trades. Tariff implementation, hurdles in the tax bill, and geopolitical shocks are materializing in the near term.
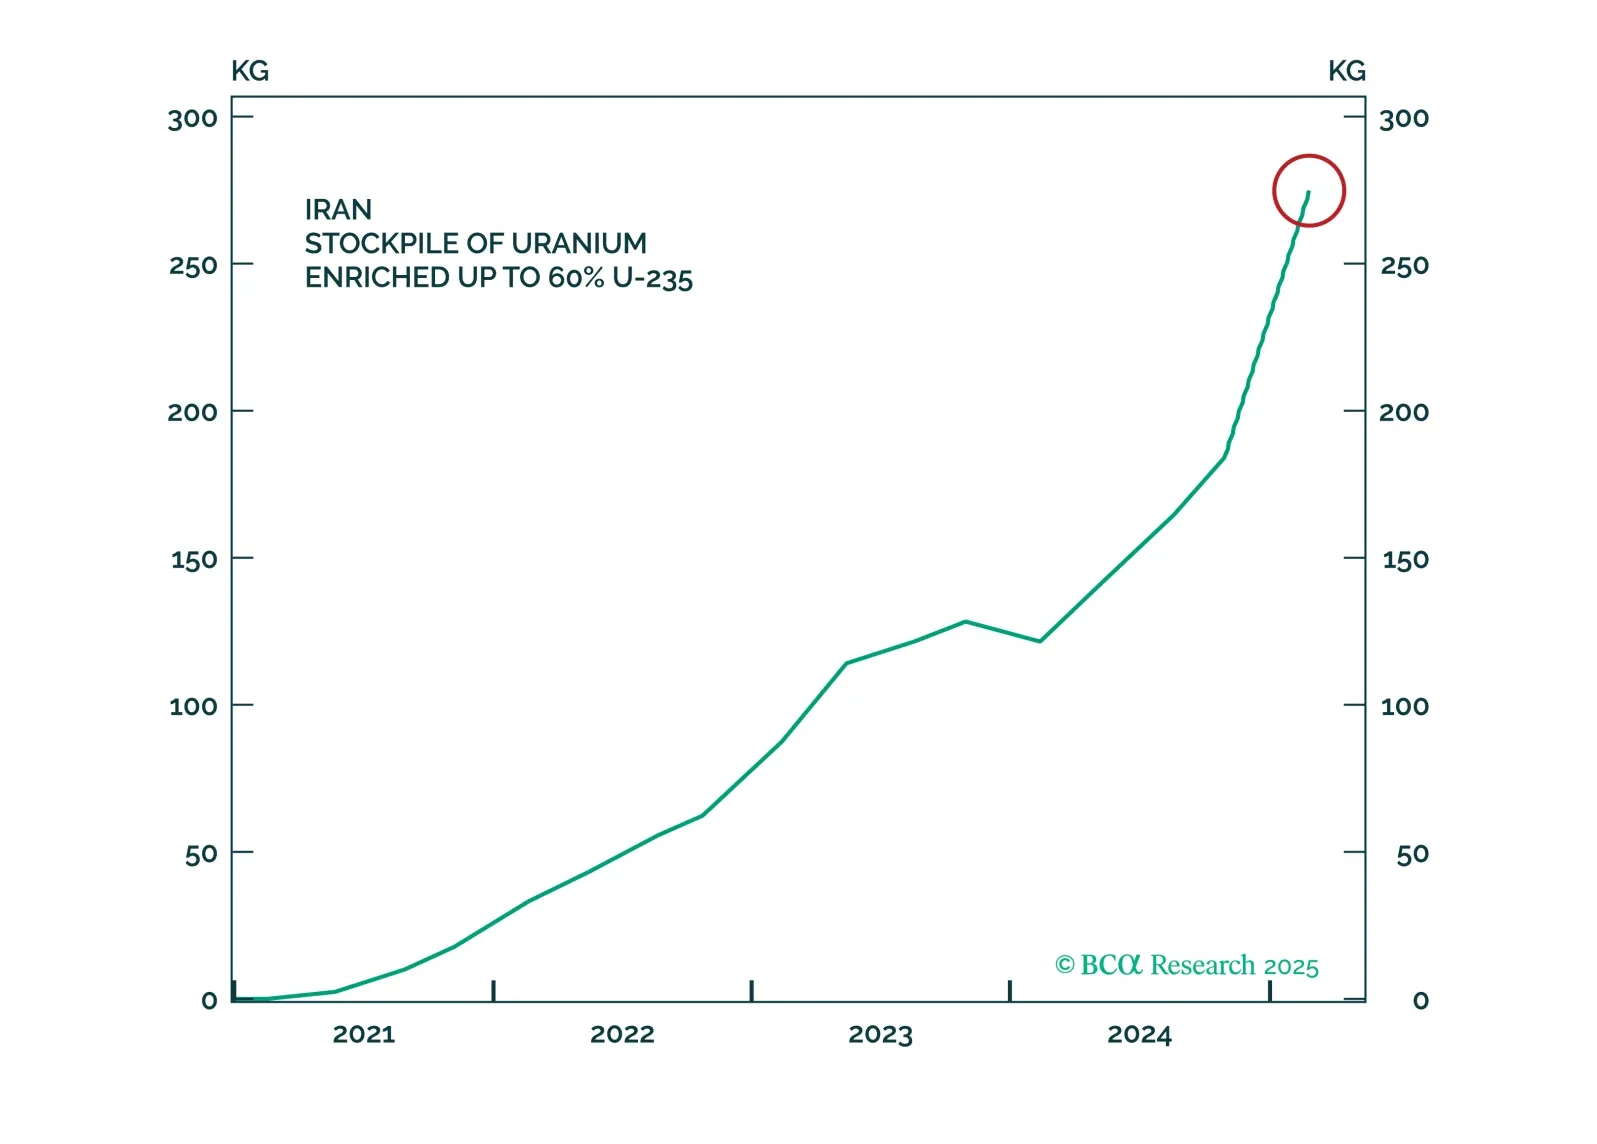
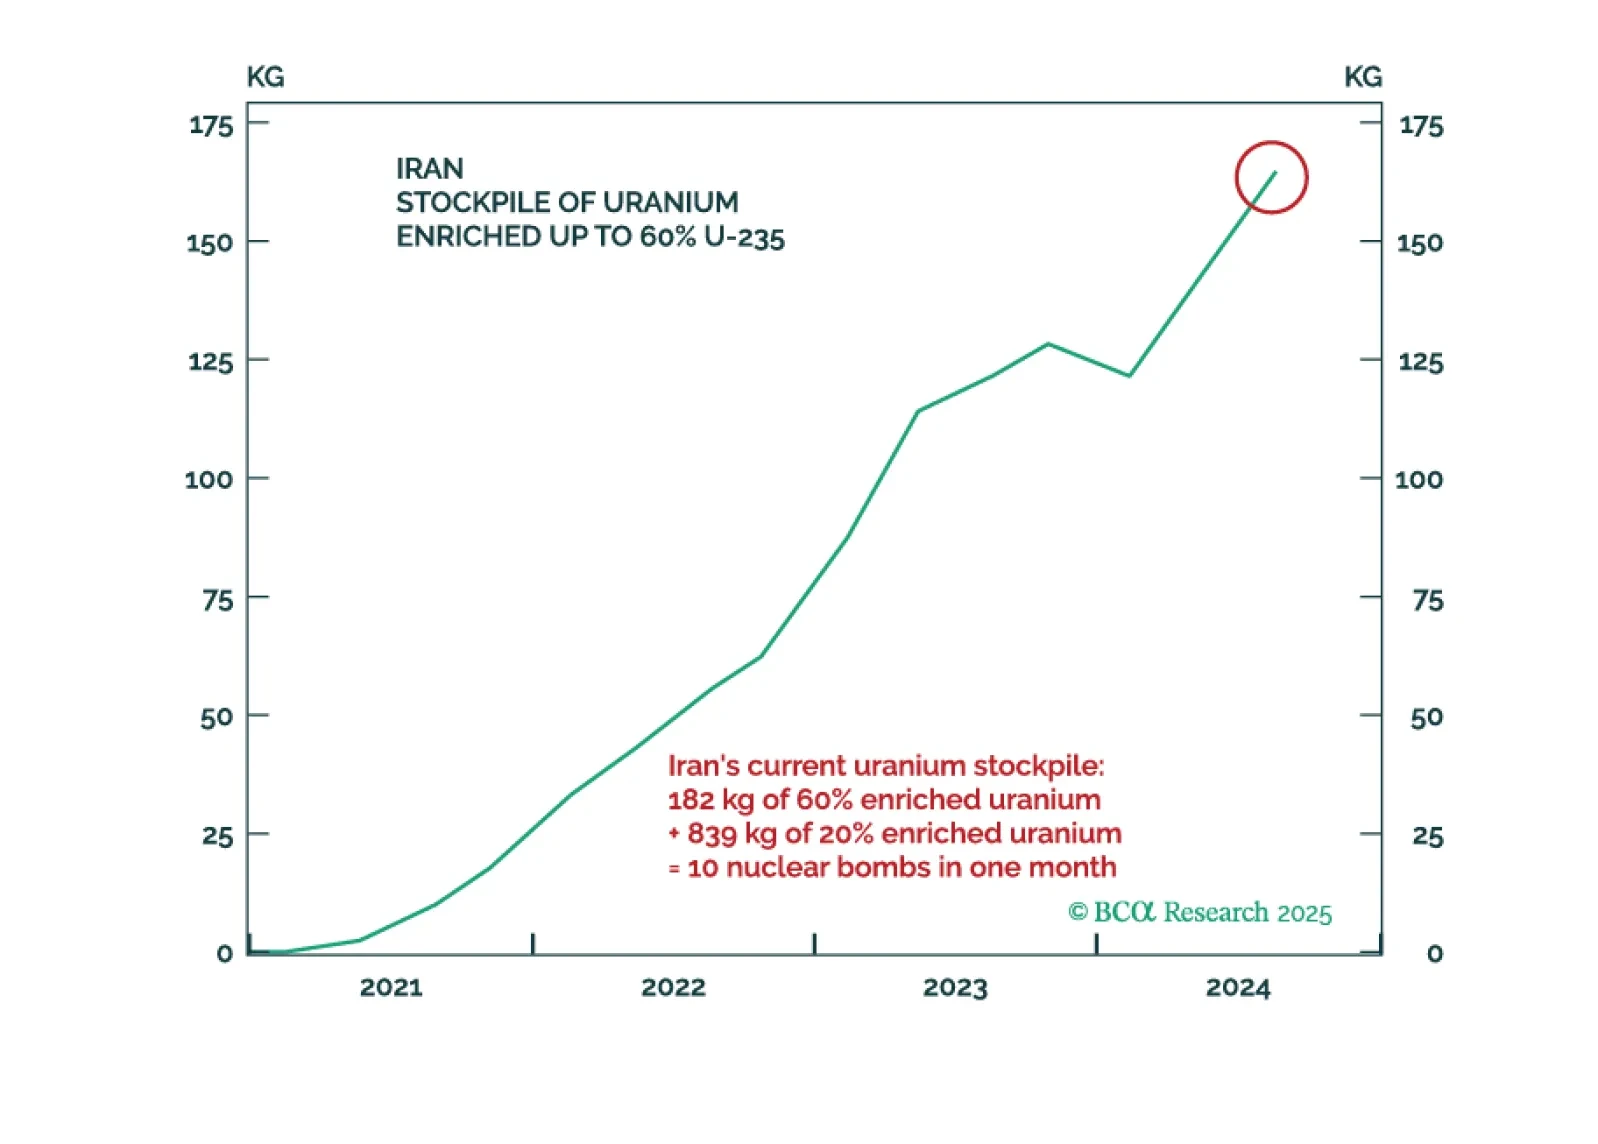
The tariffs on Canada and Mexico will come into effect as scheduled while the tariffs on China will be doubled. In the Middle East, Iranian response to any attack will threaten Middle Eastern oil supply. Meanwhile, Chinese fiscal support will surprise to the upside at the Two Sessions. But Trump's China policy will cause volatility. Now that the stock market is cracking, reinitiate defensive trades, such as long treasuries versus US stocks and long global defensives versus cyclicals.
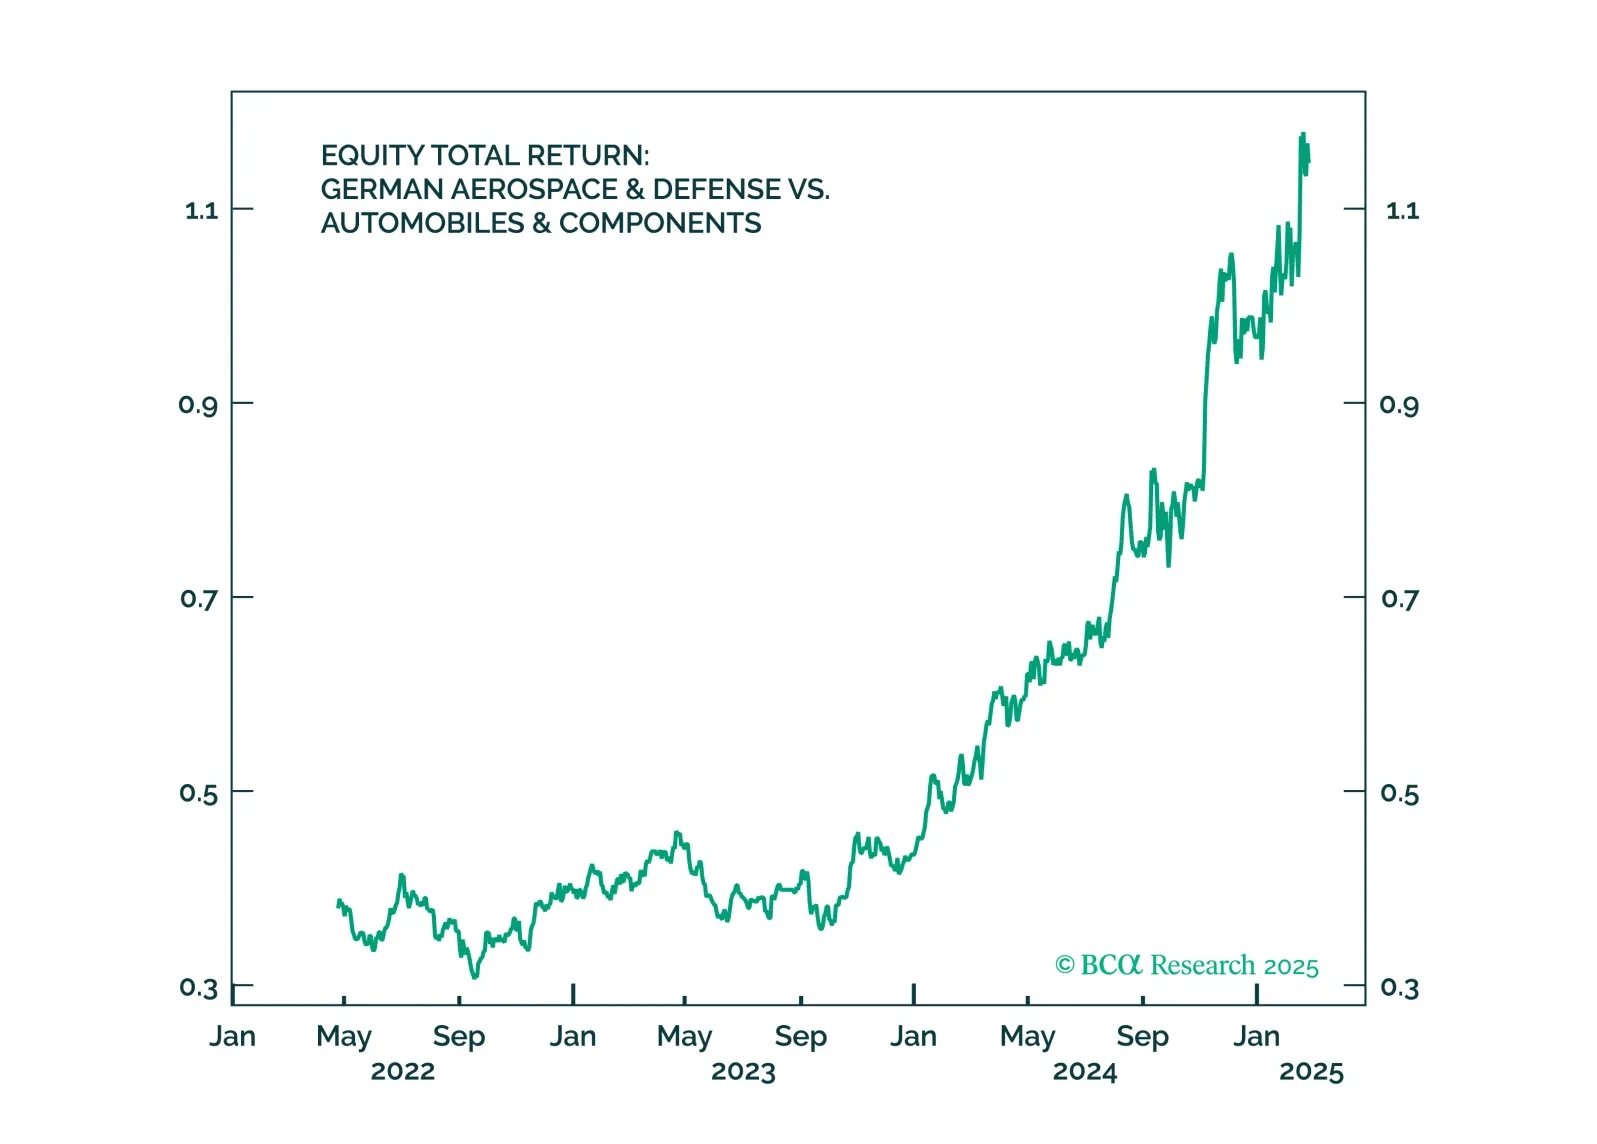
Trump’s ceasefire talks are positive for Germany – and so was the German election result. But Trump’s tariffs will hit Germany soon. Investors should use near-term volatility to increase exposure to Germany.
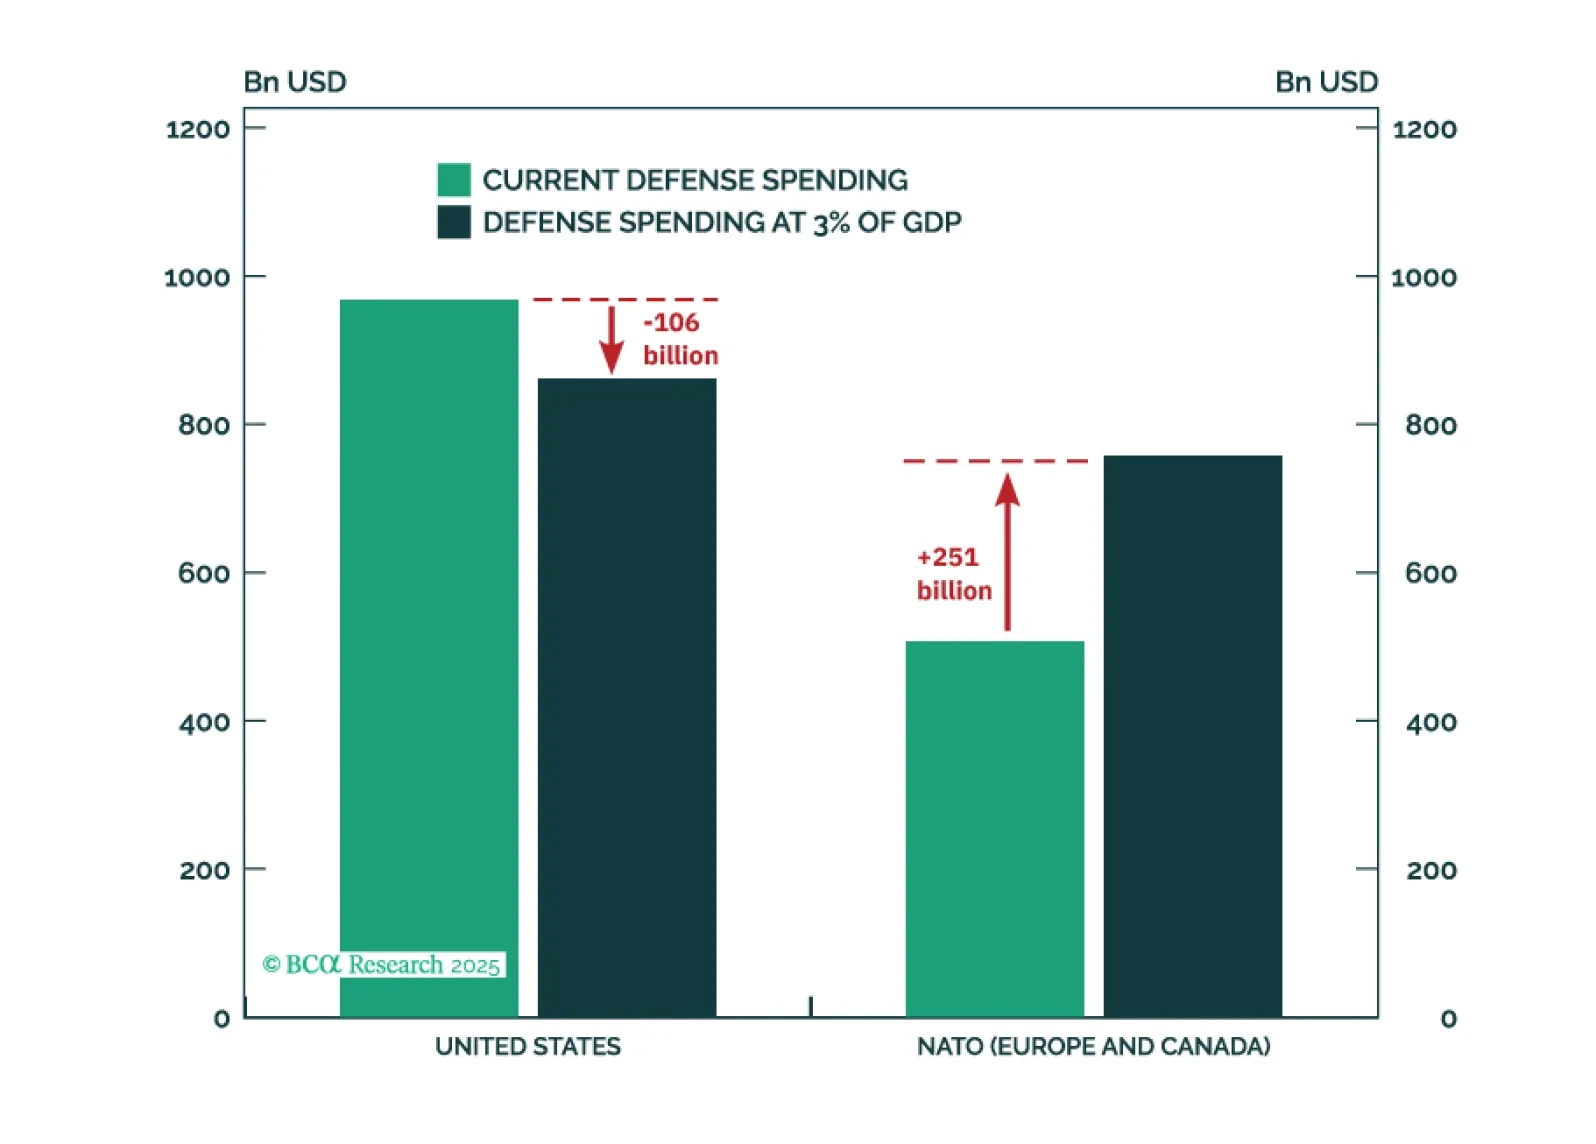
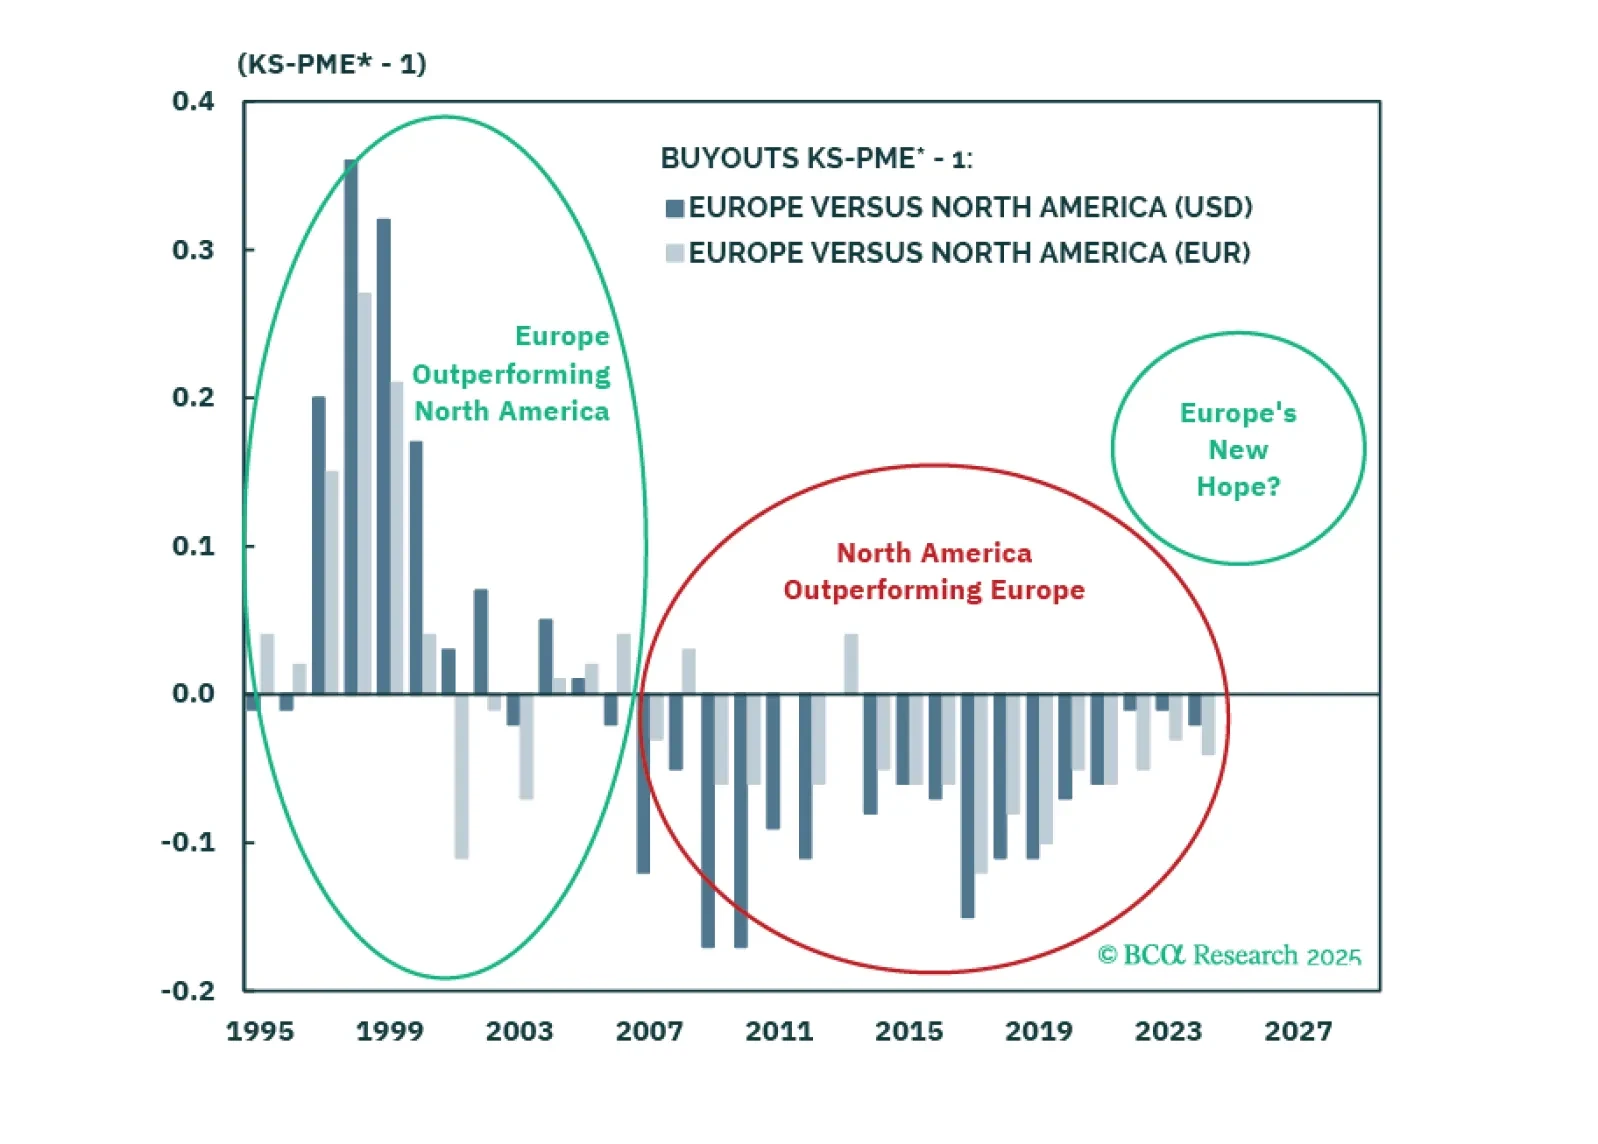
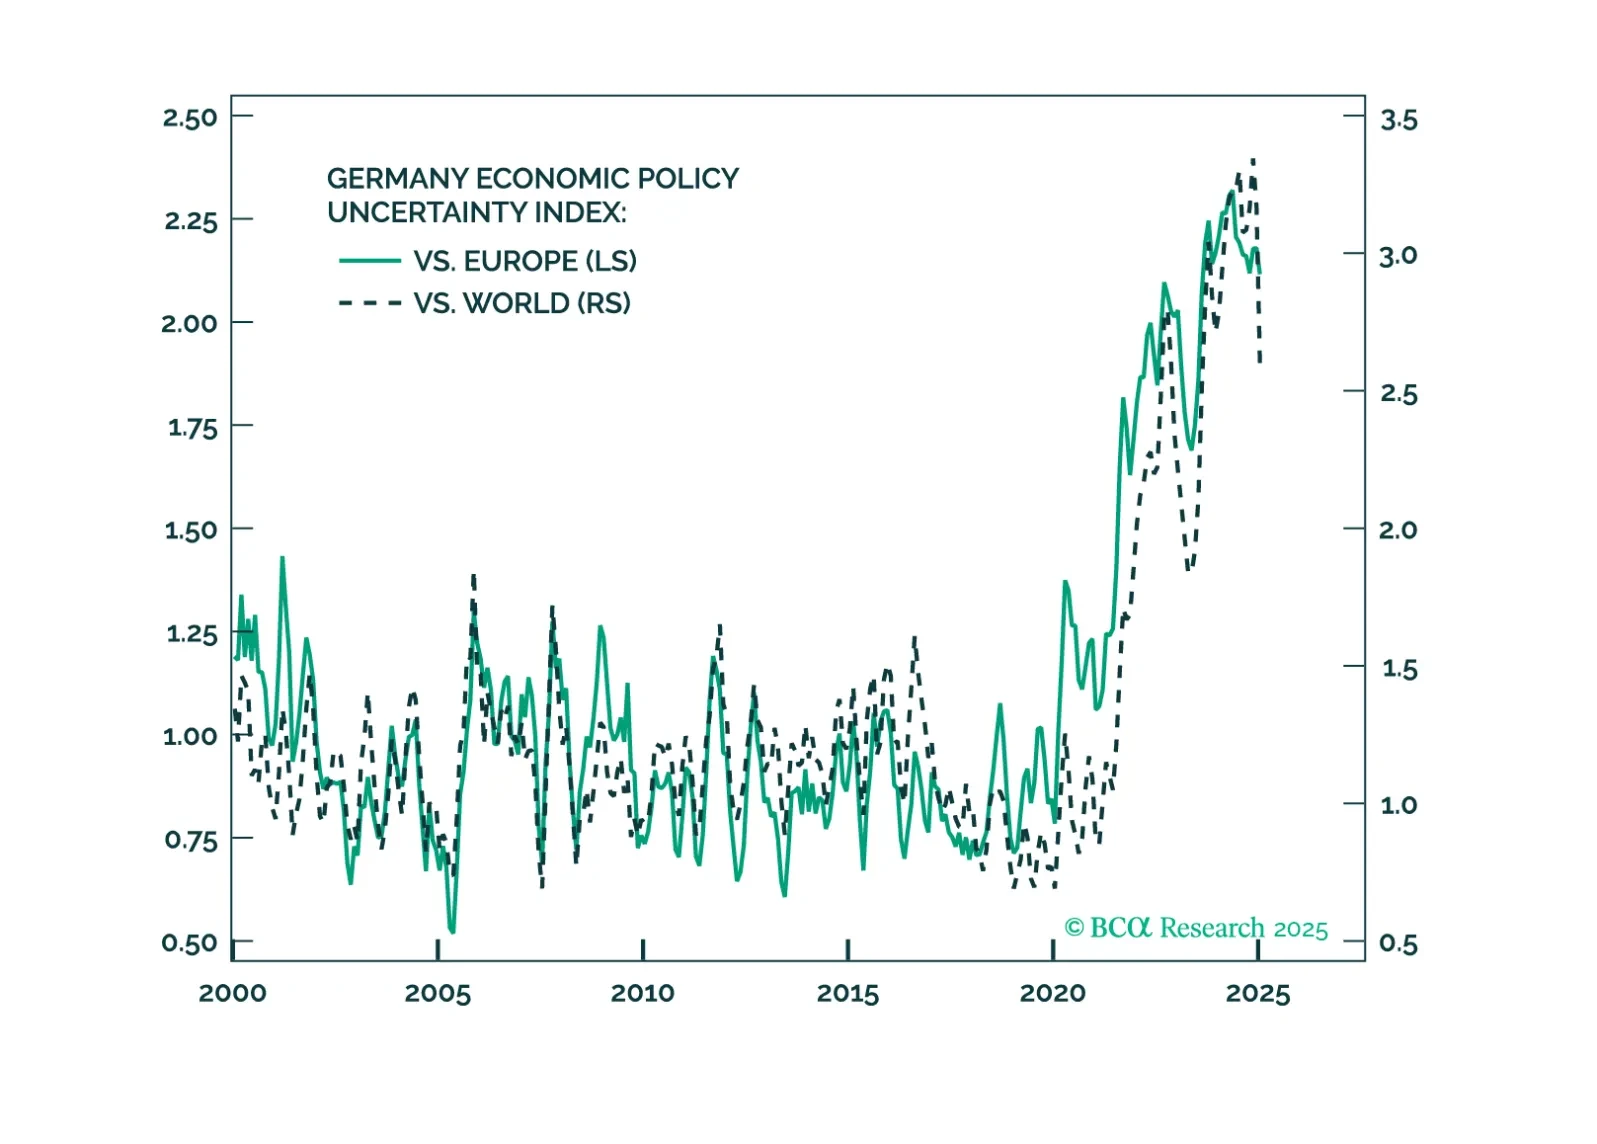
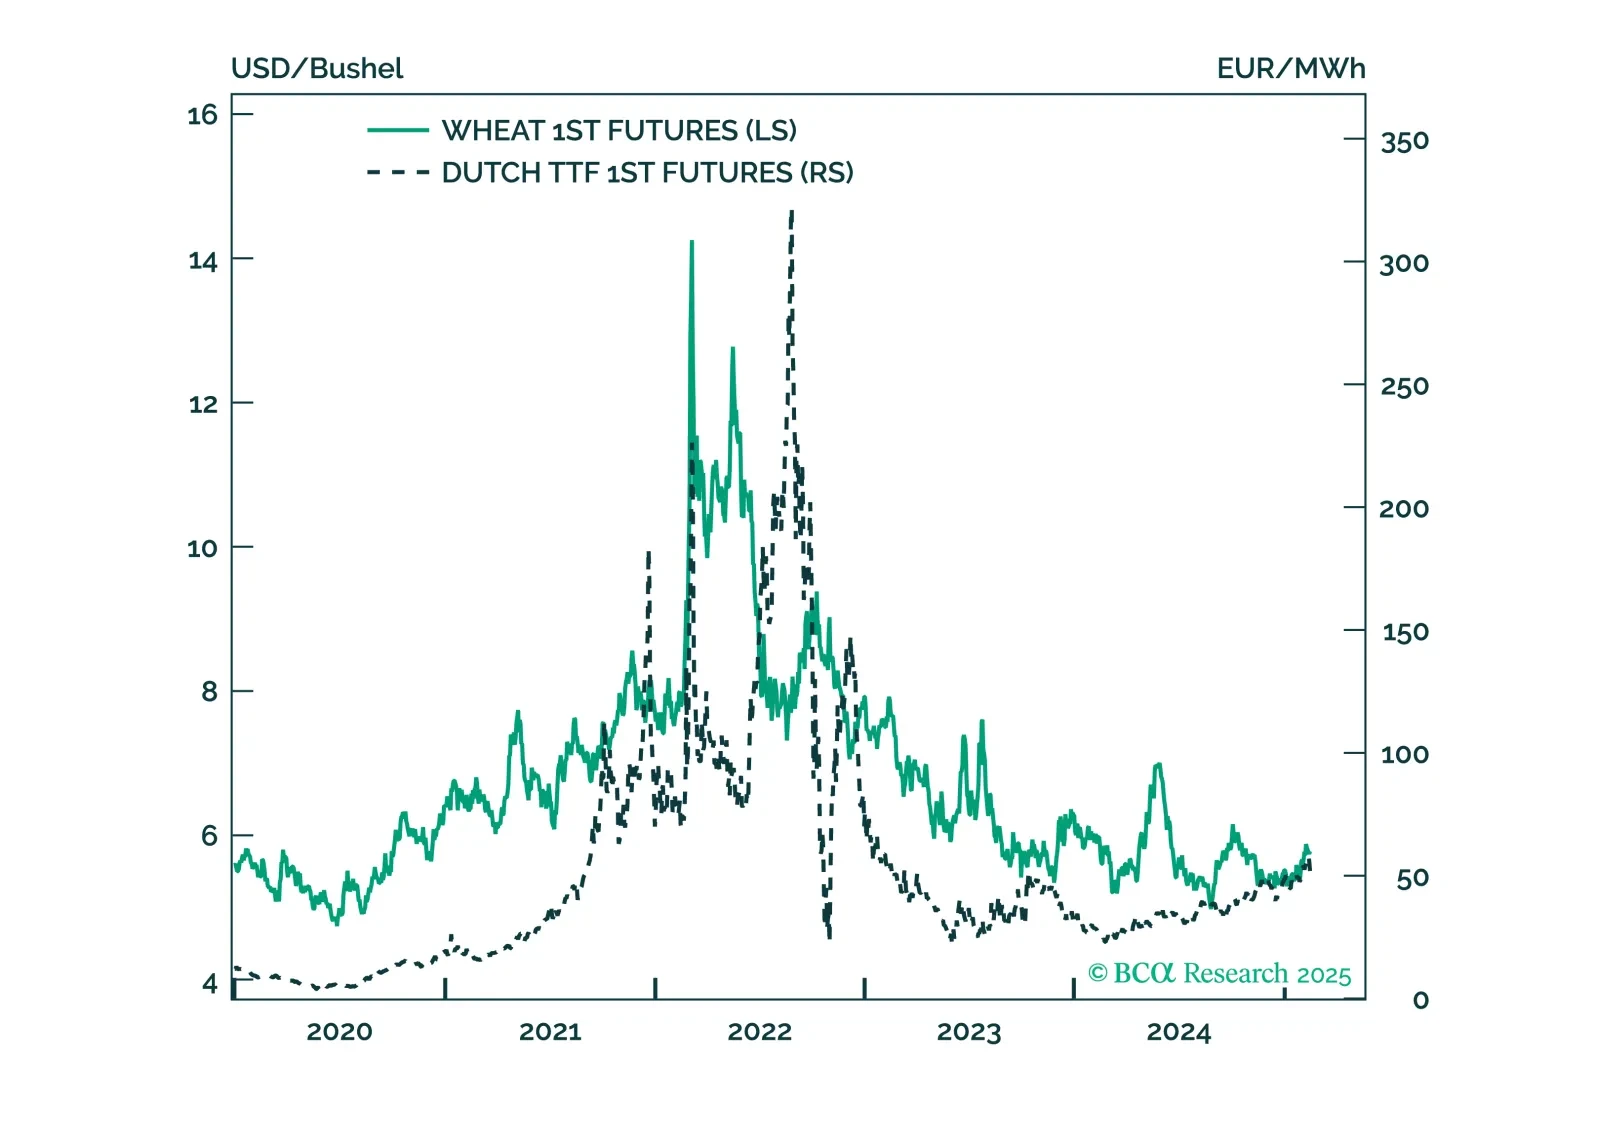
President Trump is negotiating a ceasefire in Ukraine. This will be a marginal headwind to some commodities which benefitted from the conflict like natural gas and wheat, and will be a marginal tailwind for European assets, specifically EM Europe. Use Trump’s tariff shock as an opportunity to buy European assets.
The budget process and debt ceiling will cause stock and bond market volatility. US trade policies will provoke foreign pushback at a time of stretched valuations. Hence US politics and geopolitics will be bullish for US energy, but bearish for the internationally exposed US tech sector.