GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
While the market welcomed the pause in Liberation Day tariffs, we believe investors are overly optimistic about the relief from this Trump-driven uncertainty. Even with the pause, current tariff levels remain higher than they were in January. Elevated tariff levels are likely to be inflationary, which could explain the recent spikes in US Treasury yields. Currently, Congress does not have a veto-proof majority to rein in President Trump’s tariff policies, meaning the trade war with China will persist.
The world is focused entirely on the trade war between the US and… well everyone. This is fair given that there has been no greater market catalyst than Liberation Day since the pandemic. However, we continue to stress that the BIG PICTURE for macro investors is the rotation out of the US. A rotation that started well before April 2, despite the understanding of the investment community that some tariff action would be afoot.
President Trump imposed tariffs on the world in his first 100 days, as we expected. Tariffs may have catalyzed a recession in the US, given the weakness in consumer sentiment and demand. Trump will soon backpedal and grant exemptions to countries that are negotiating, which he will showcase as proofs of his successful trade policy. While he may backpedal on his tariffs on other countries, China is not likely to receive the same treatment due to the US-China strategic competition.
Did you know that the high-quality Japanese zippers you use every day are macro relevant? That is because YKK dared to sue – and win – against President Richard Nixon 10% across-the-board tariffs.
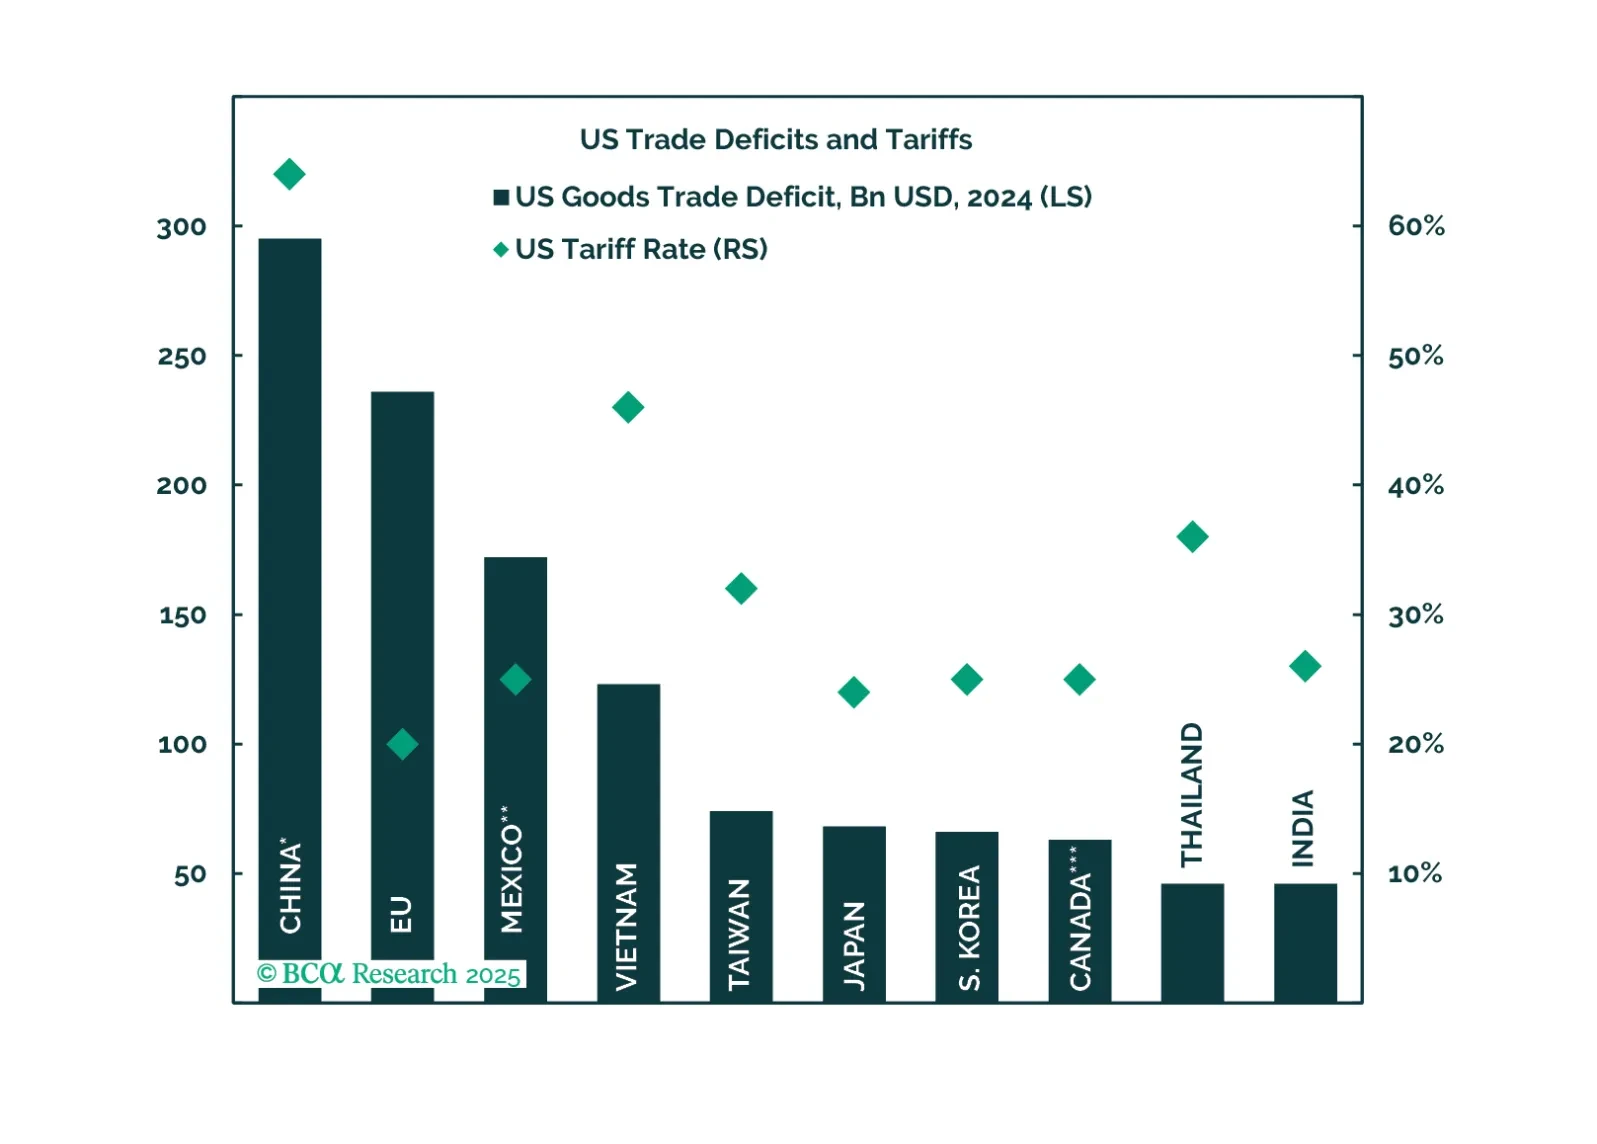
Trump's Tariff D-Day brings a negative surprise to financial markets already anxious over a declining US cyclical economy. Investors should sell risky assets, increase safe havens, and overweight US assets in the near term.
The White House has revealed the plans for Liberation Day. They broadly include: Reciprocal tariffs, on a case-by-case basis. A message from President Trump to other countries to lower their own tariffs and buy US goods. Our take is that April 2 will be remembered – 6-12 months from now – as the peak in “de-globalization” thesis. Markets react to the delta of bad news, not bad news in the absolute.
Liberation Day is coming to America! In honor of the new holiday, GeoMacro will be increasing prices using an algorithm that will determine how much each client owes us for the sweet taste of their liberty (… from the clutches of normative geopolitical analysis)!
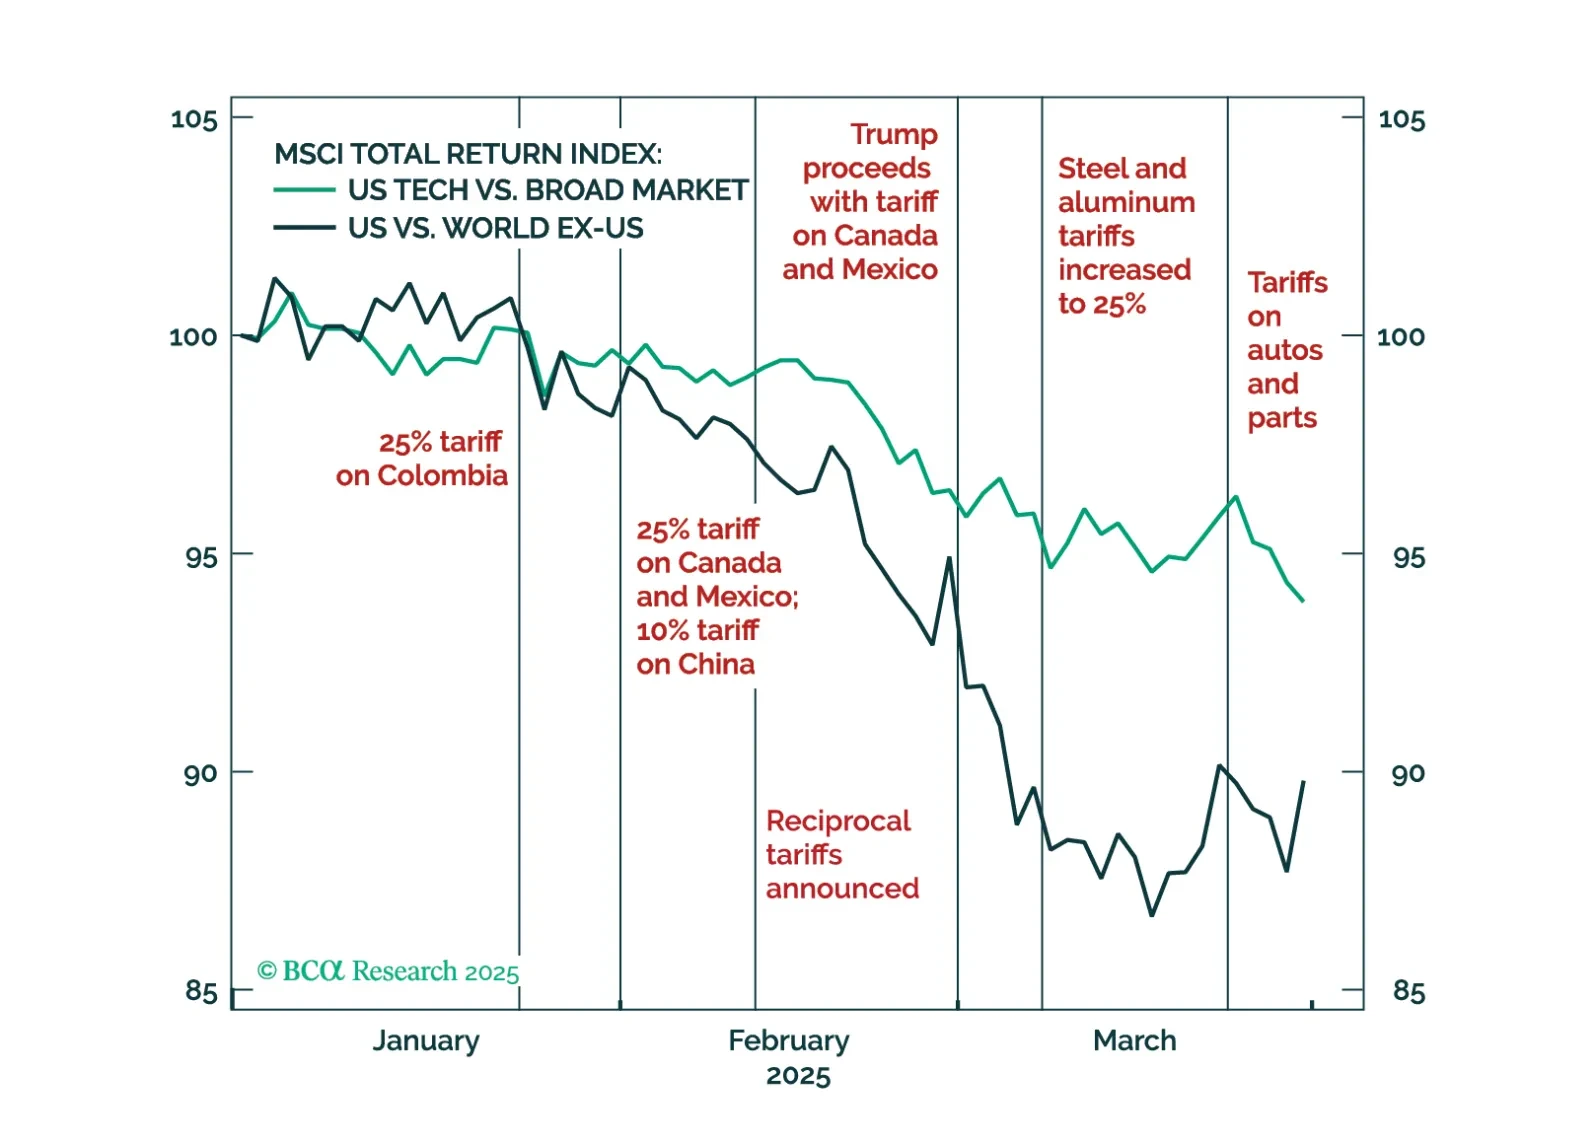
The trade war is on everyone’s mind with America’s “Liberation Day” upon us! However, the reality under the surface is that the main macro narrative has been a rotation – nay… exodus – out of US assets into RoW. This was not supposed to happen with de-globalization and a MAGA trade policy. US assets – form equities to the USD – were supposed to be the safe haven from “America First” policies by Donald Trump. Meanwhile, the noose of material constraints is tightening around Trump, suggesting that a pivot away from brinkmanship may not be long away from “Liberation Day.”

In this month’s Beta report, we continue our series supporting our bullish thesis on Europe. We take a deep dive into the aftermath of the European energy crisis – dispelling the myth that Europe faces risks of imminent deindustrialization – and evaluate the impact the approaching LNG wave will have on European industry and the global natural gas market.