 Equities
Macro, fundamental, and quantitative analysis translated into actionable equity views across sectors, factors, themes, and baskets.
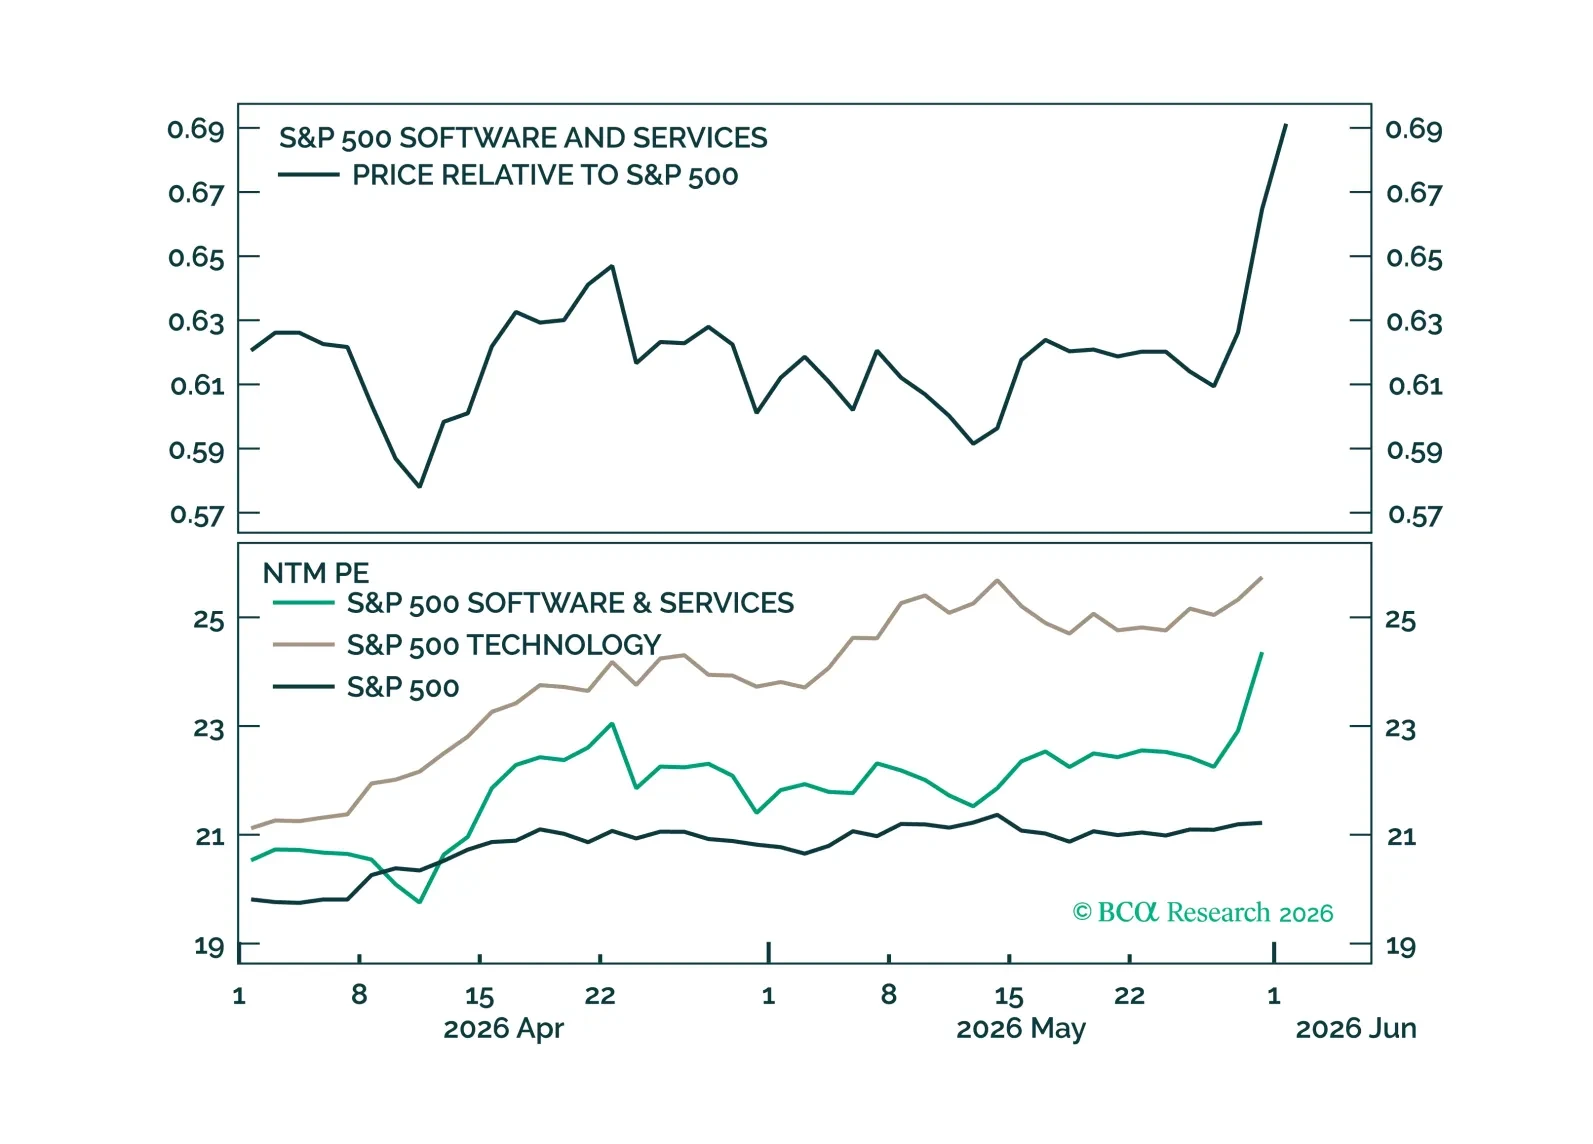
The US economy is moving back toward Expansion, supported by strong investment, improving earnings, and record margins. We are taking profits on our tactical Software long after achieving our target and rotating into Materials, where commodity strength and earnings momentum continue to support the sector.
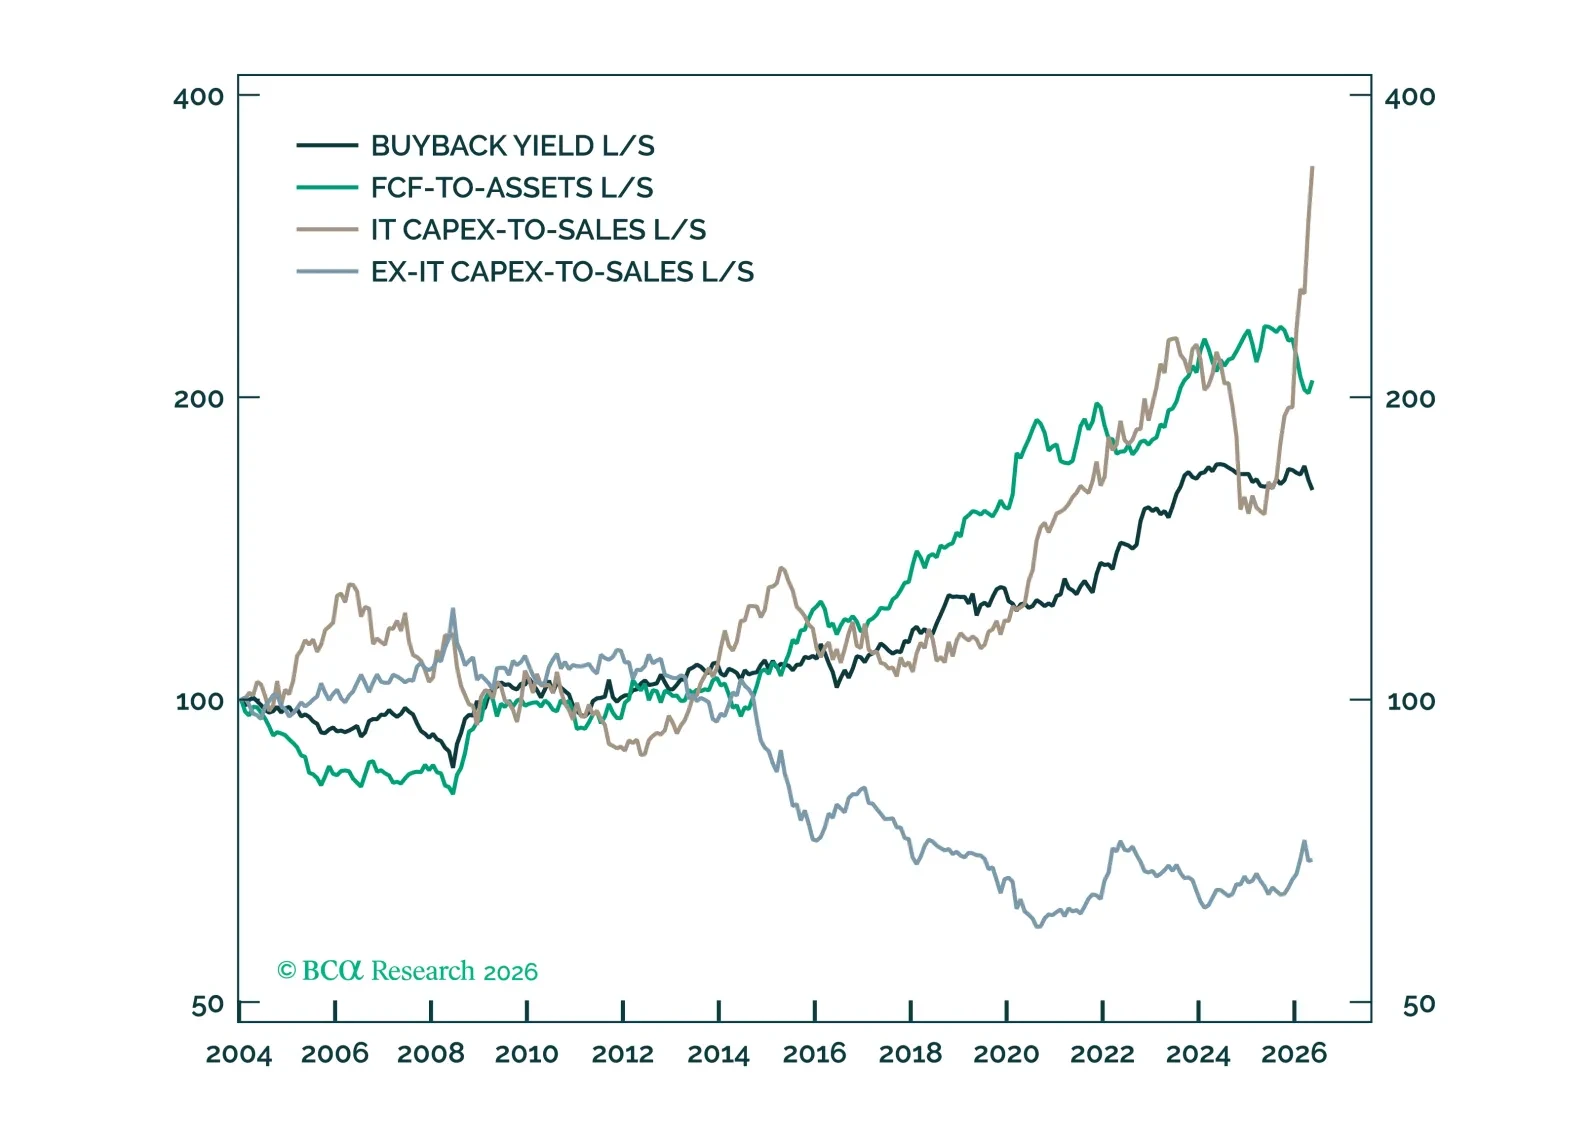
Tech, and increasingly the market, is moving from a cash-return regime to a reinvestment regime. After the GFC, investors rewarded companies that returned cash to investors. In the AI cycle, they are rewarding companies that put that cash back to work. This is not just a story of falling free cash flow; it is the mirror image of a market rewarding reinvestment. Tech has defined both regimes, revealing the old cash-flow “stars” as sector bets masquerading as alpha.
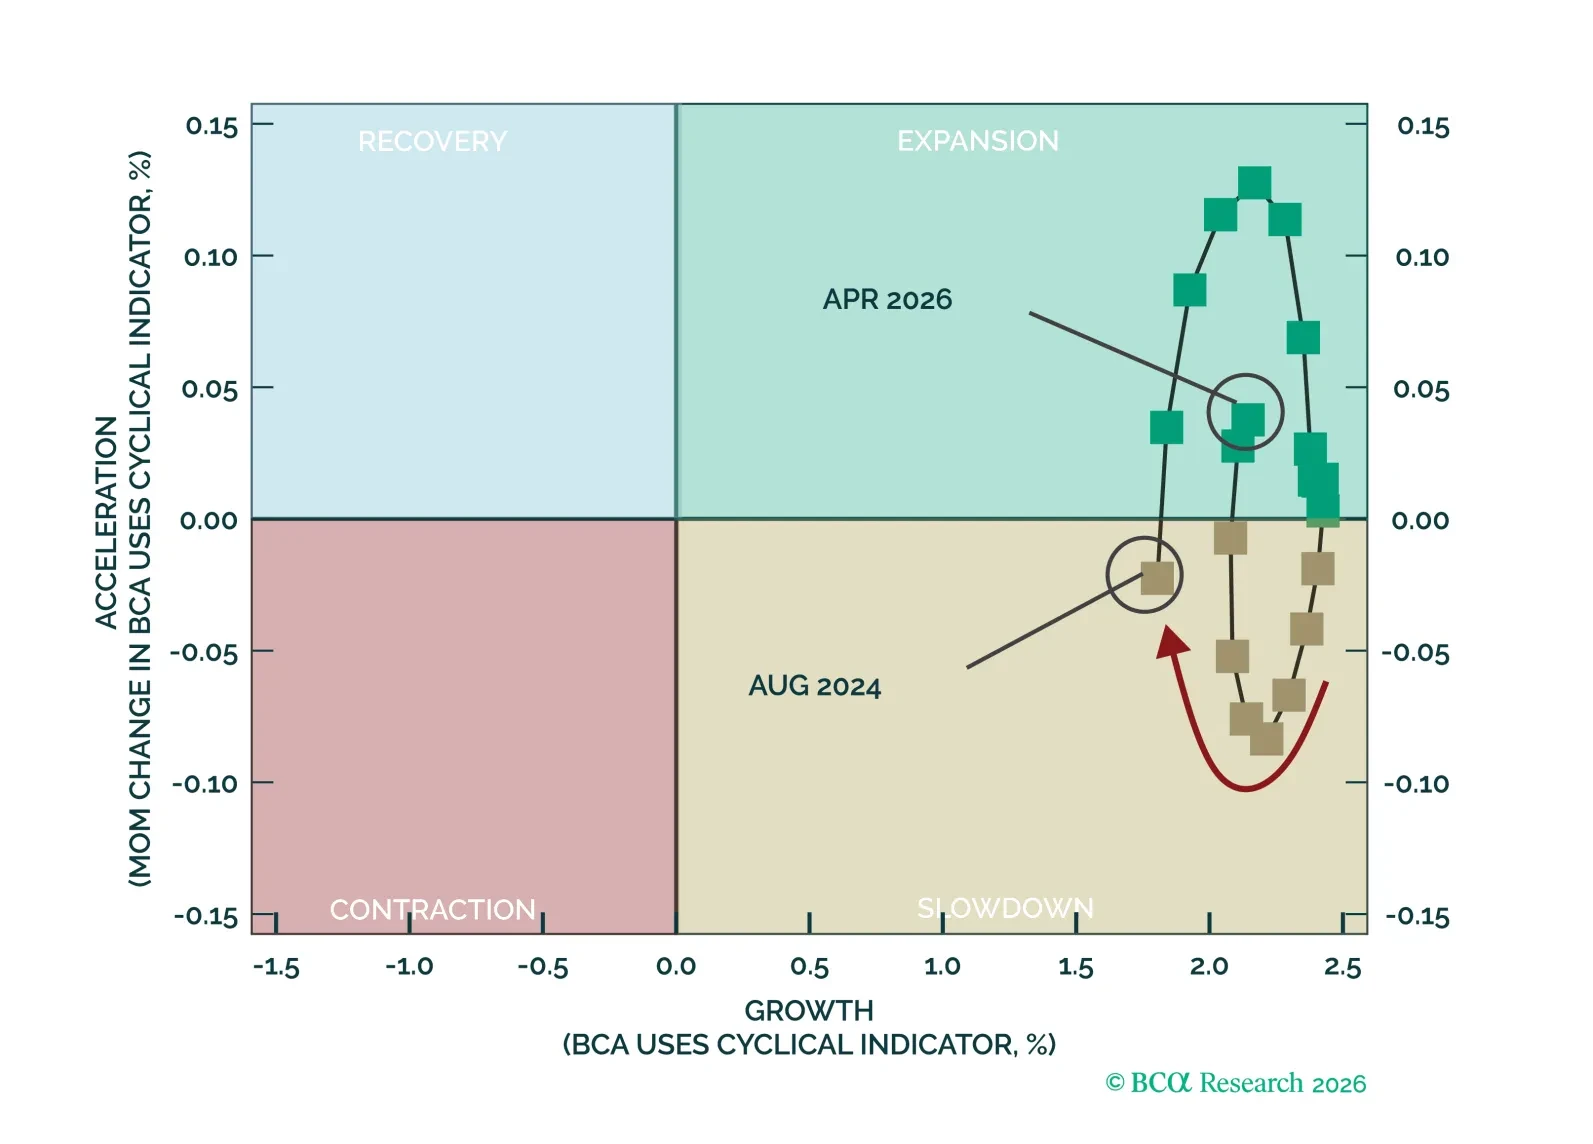
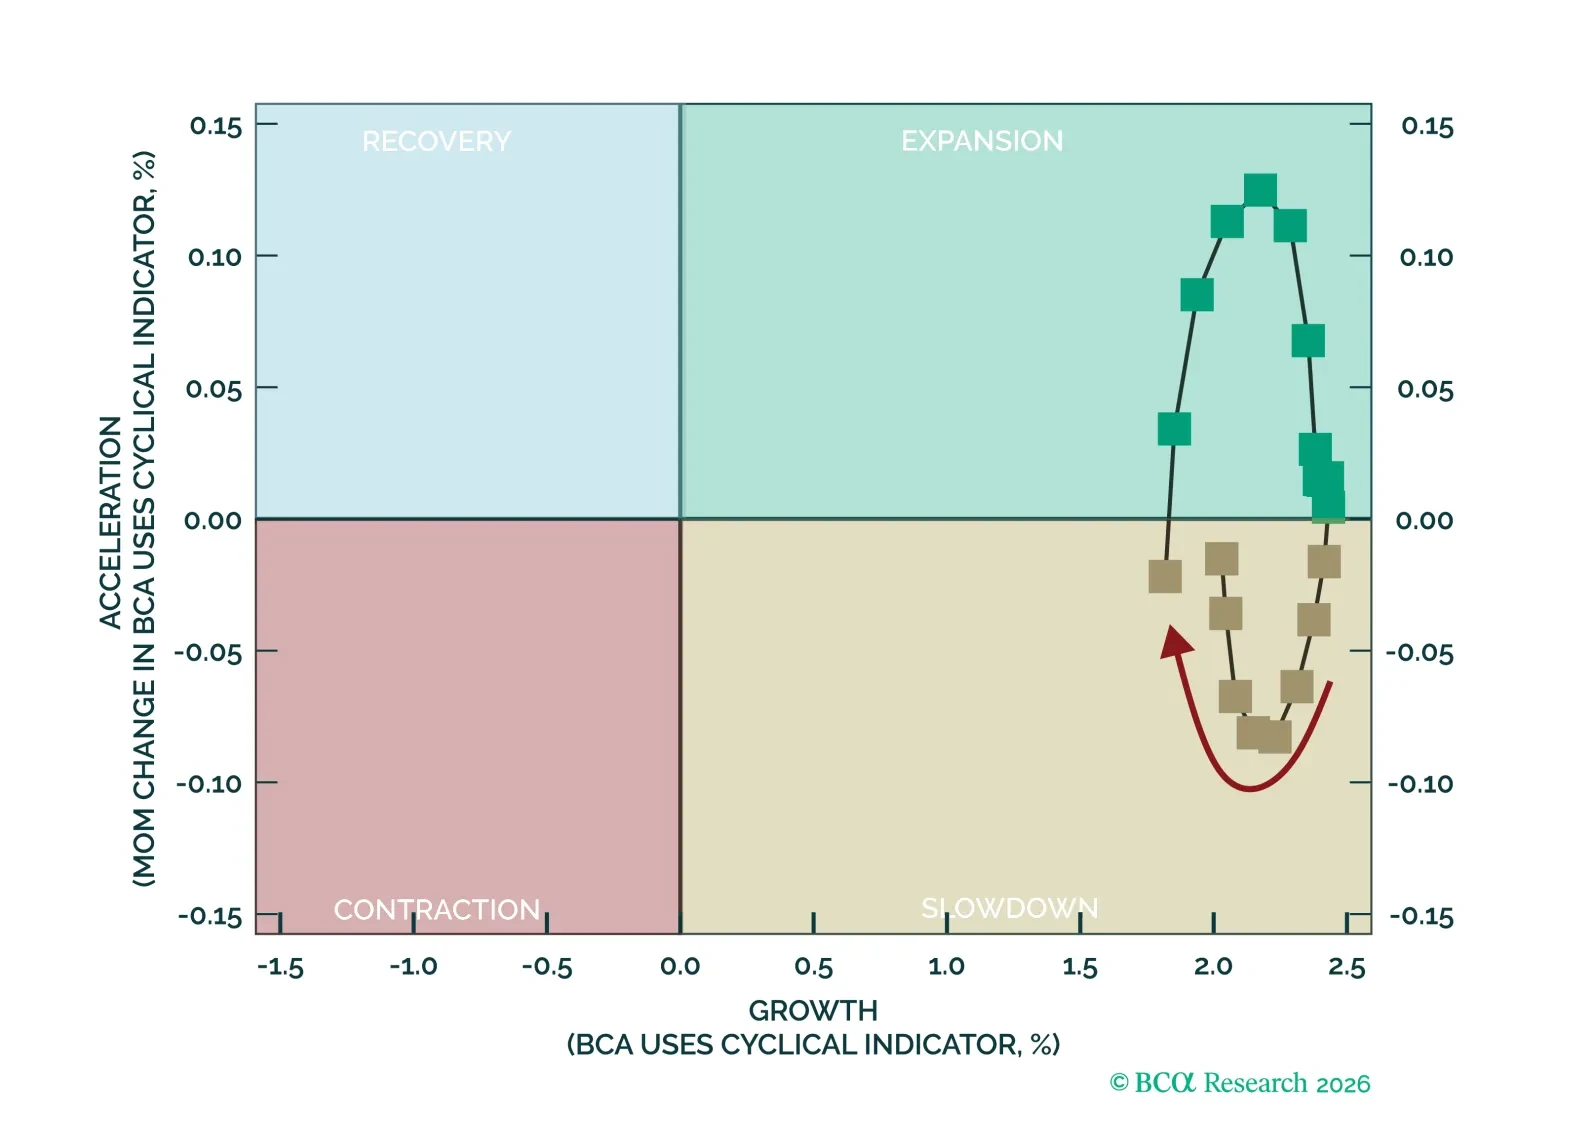
US growth remains positive and is now improving, with the economy seemingly exiting Slowdown and proceeding into Expansion. Markets are reflecting the shift, rewarding revenue growth and capex growth, while earnings expectations continue to advance. The backdrop remains supportive, but expectations are rising and risks from financial conditions linger.
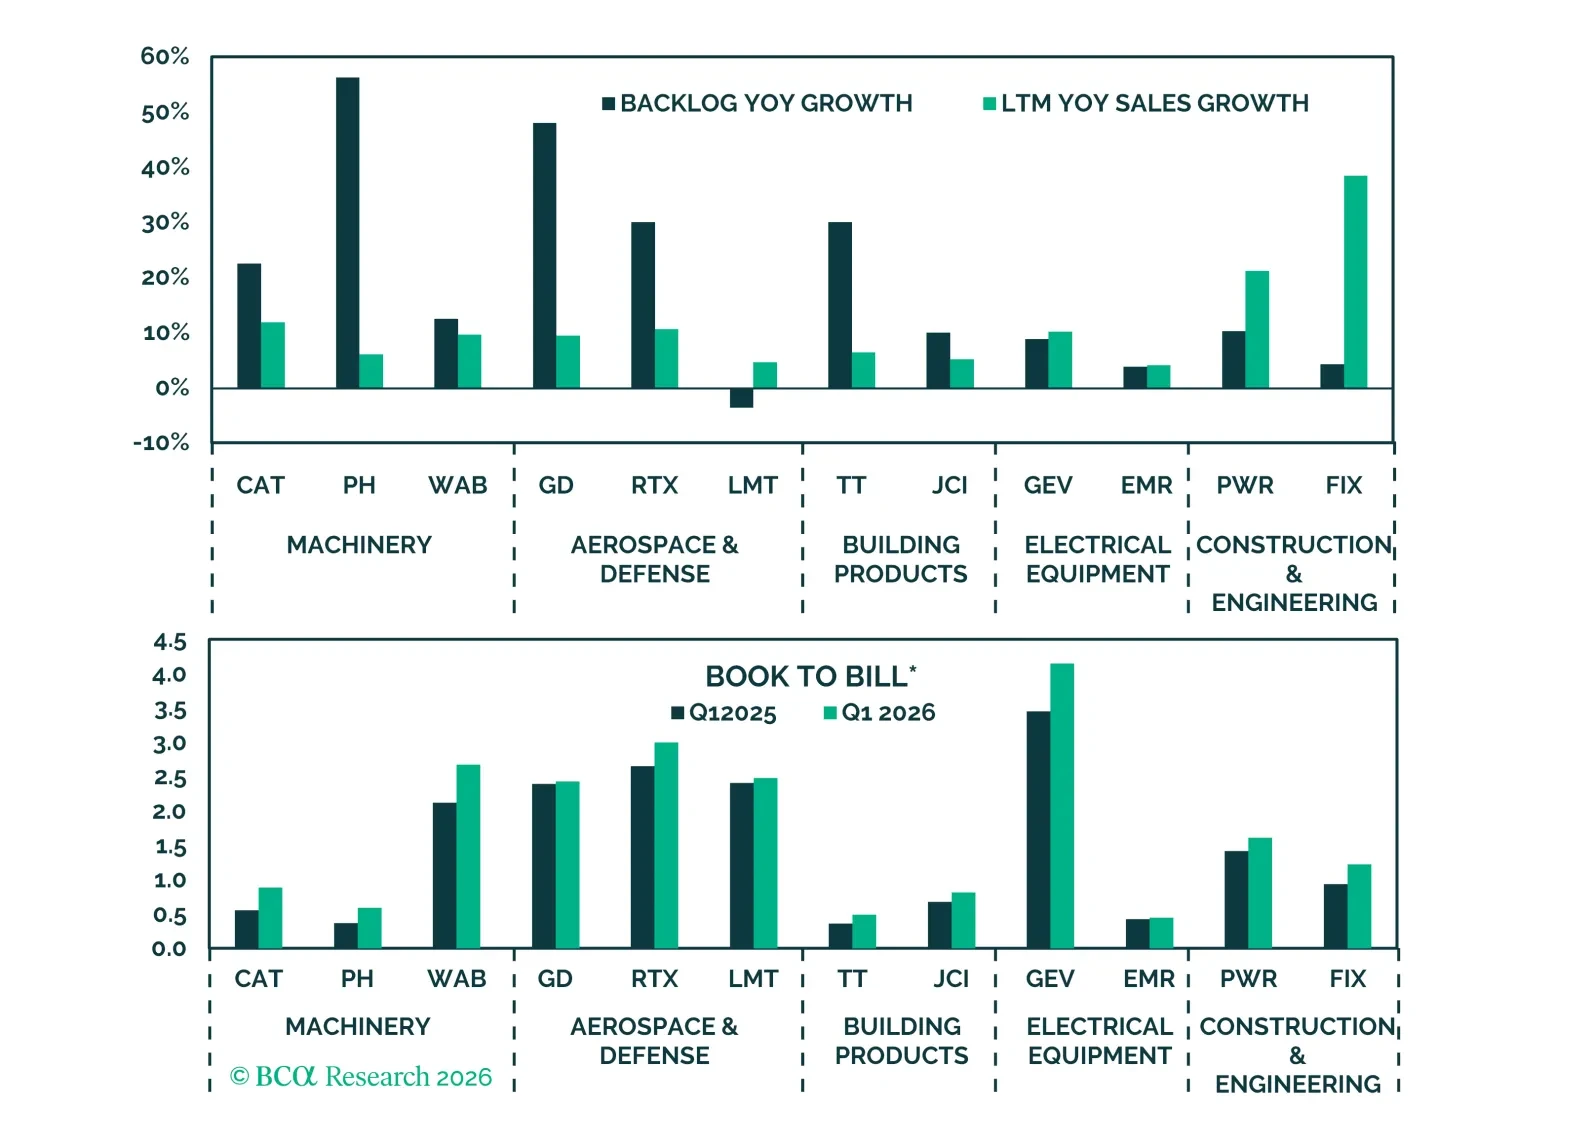
The investment cycle remains firmly intact, driving equity prices and fundamentals, as confirmed by both Q1 data and corporate commentary. Upside surprises, expanding margins, and rising capex expectations point to resilient demand. Companies confirm that AI-related demand is broad and visible, while geopolitical and credit risks remain contained and not yet systemic.
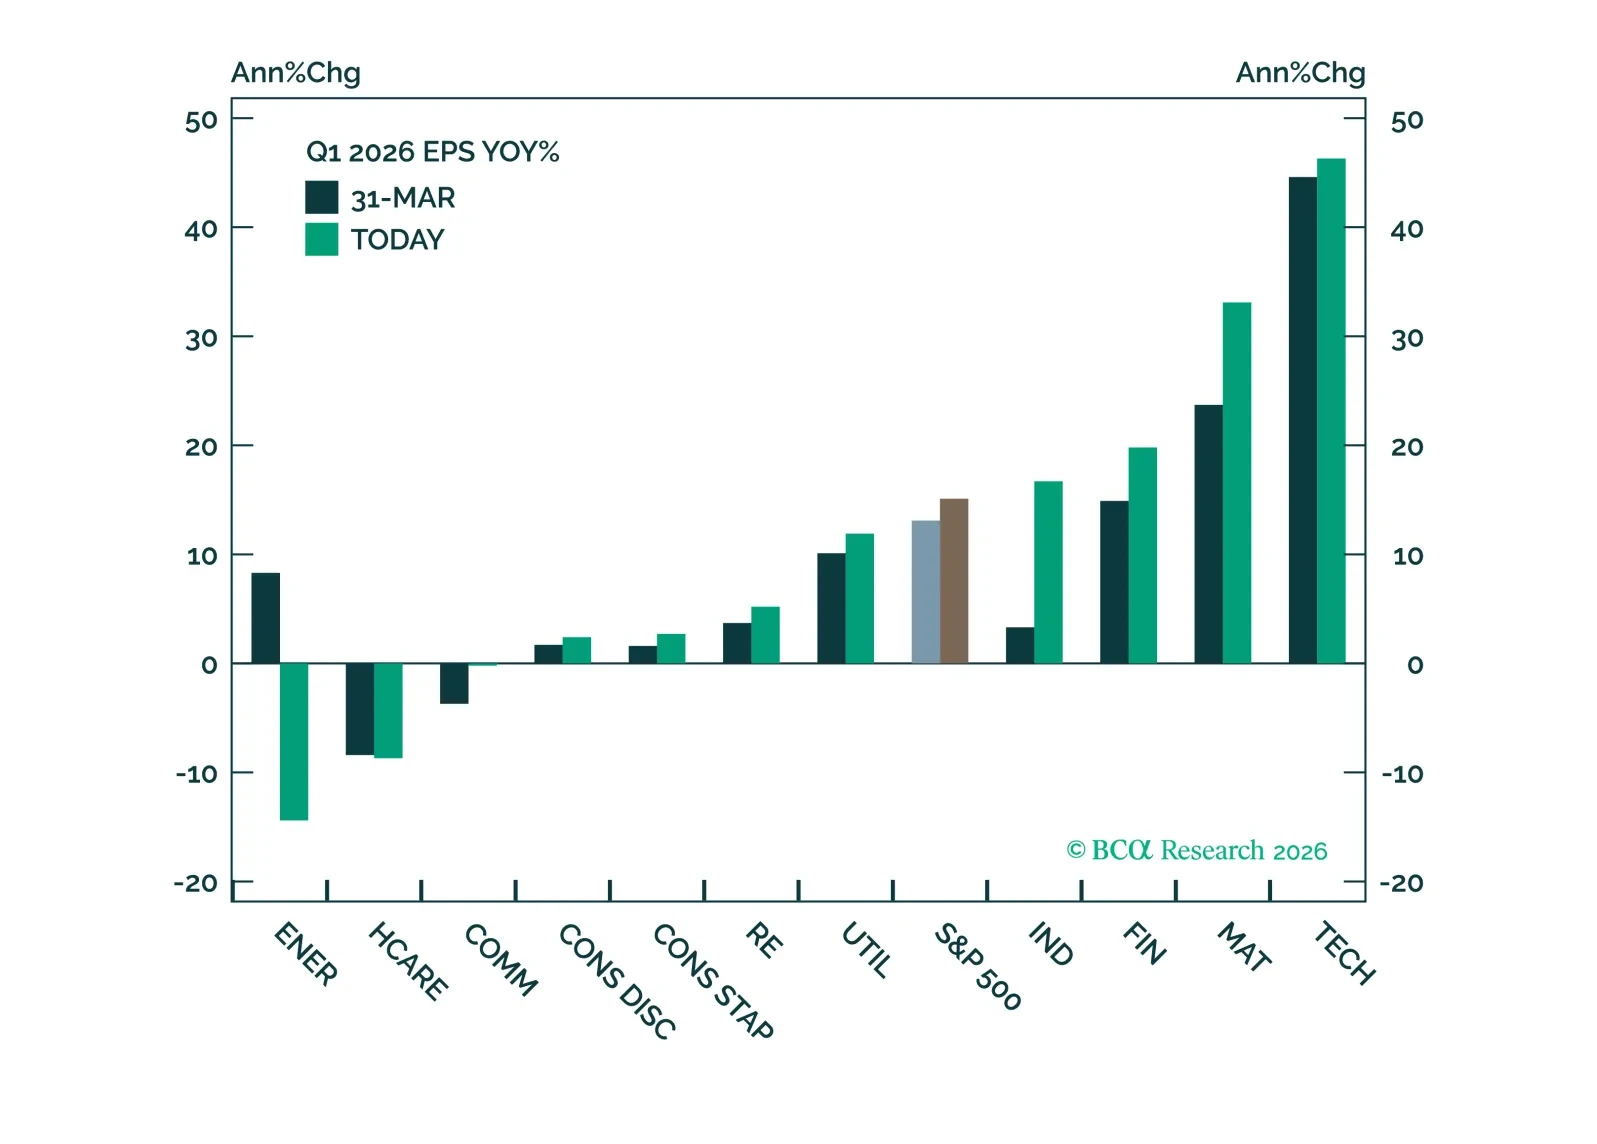
Leadership has rotated toward investment-driven sectors, reflected in both EPS growth and price performance. Expanding margins suggest the cycle may have longer to run, as productivity gains start to work their way through fundamentals. We continue to see upside for the S&P 500, with no change to our sector outlook.
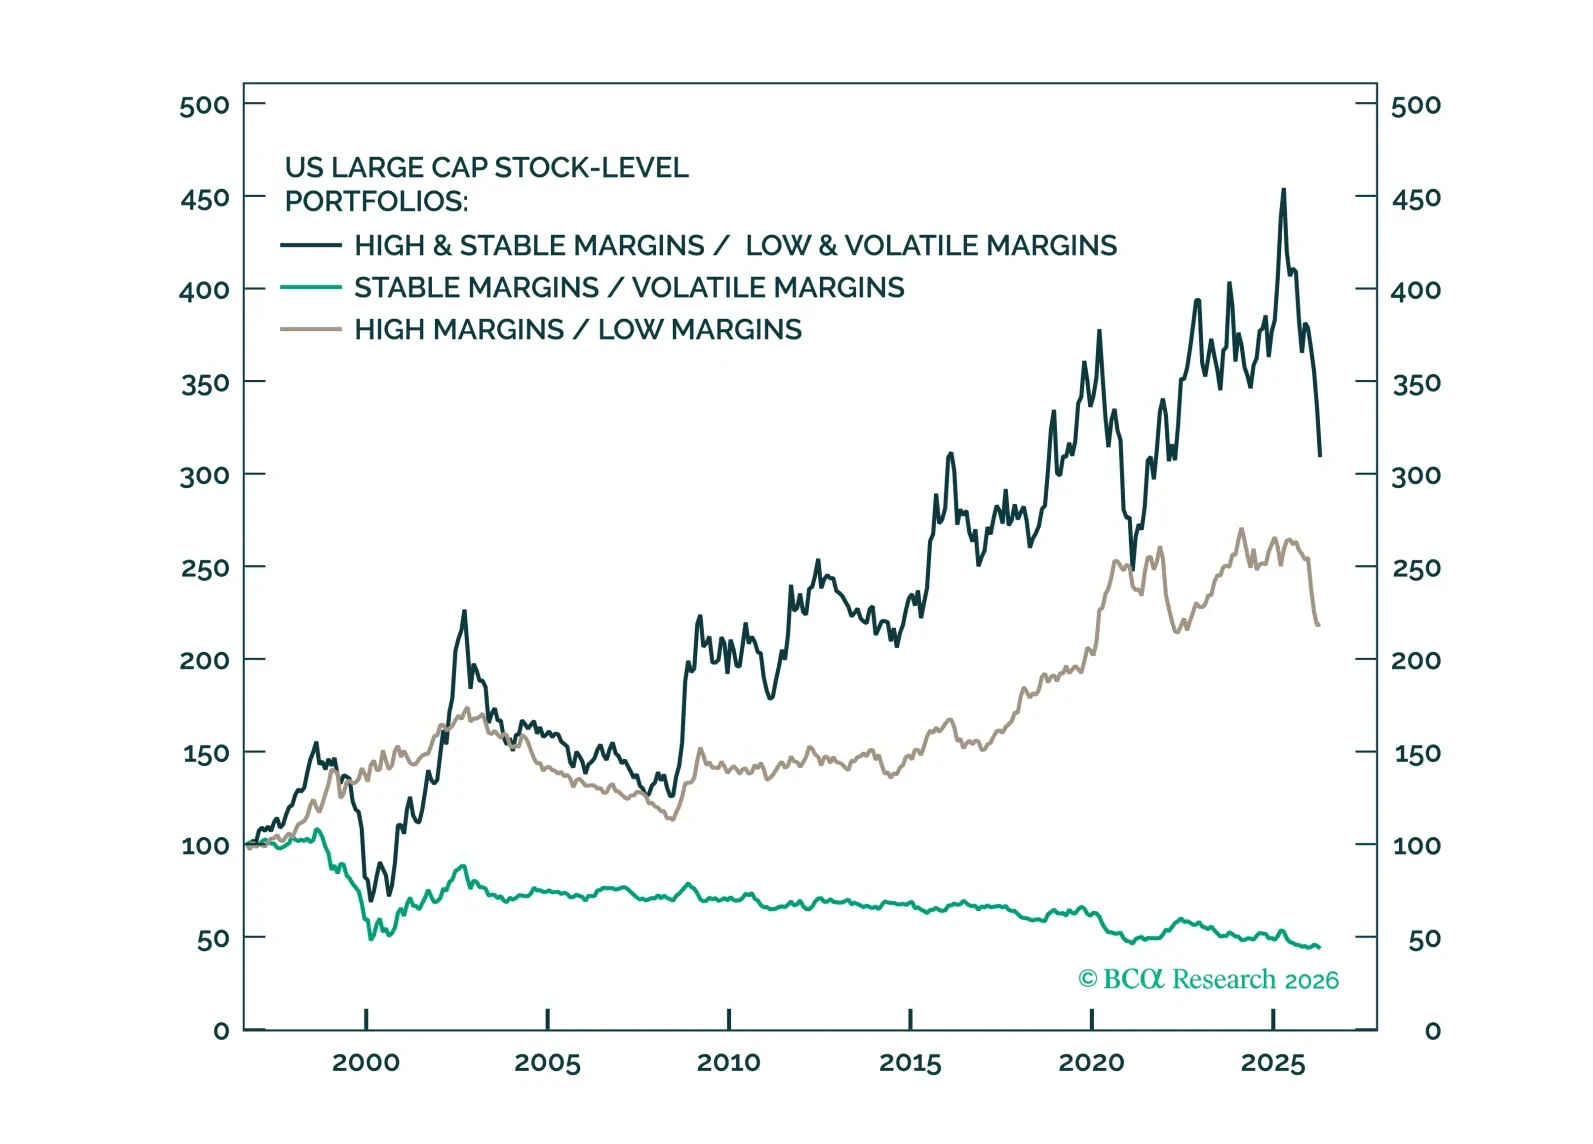
Based on our previous work on margins, three aspects of margins may matter to investors: their level, their variability, and their likely trend. We add two margin-themed baskets: a stock-level High & Stable vs. Low & Volatile basket and an industry-level AI-Supported vs. AI-Insulated basket.
The S&P 500 rally is likely more than just risk-relief. Market internals reflect strengthening economic growth and higher inflation, with support coming from robust earnings. Tight financial conditions have compressed valuations, particularly within the Tech sector. We are initiating a long Software trade ahead of earnings season, given that multiples have declined and earnings growth is strong.
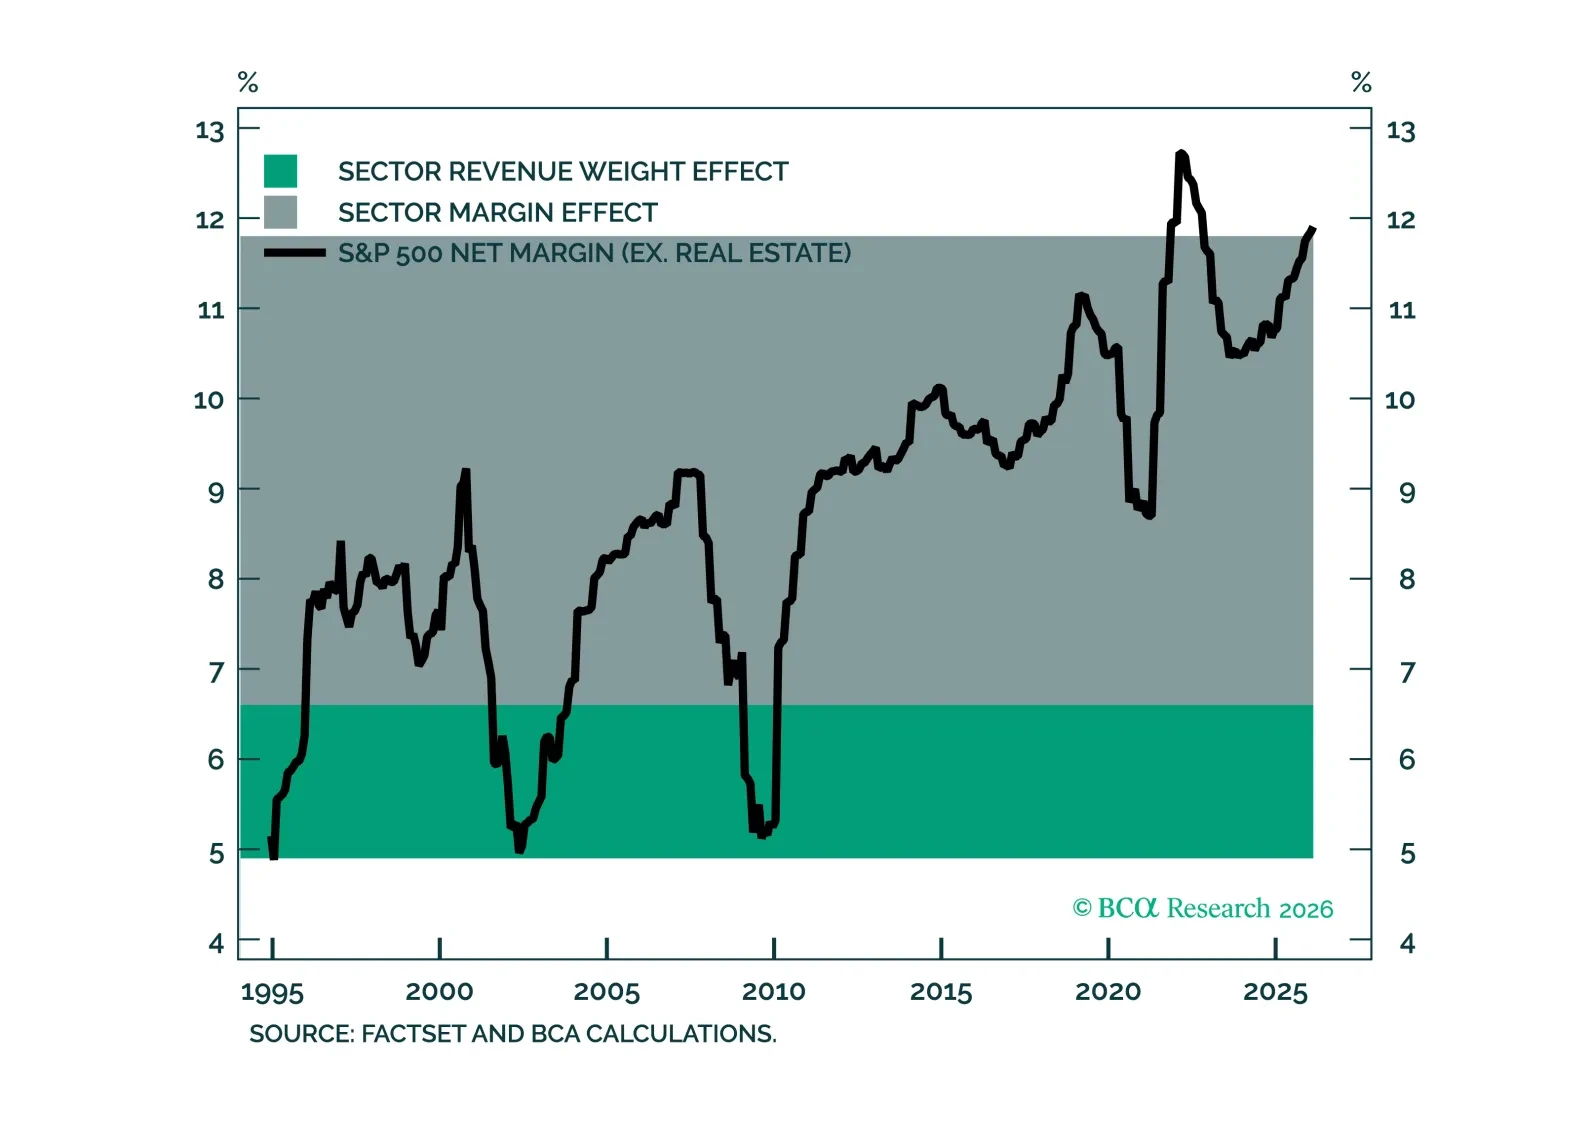
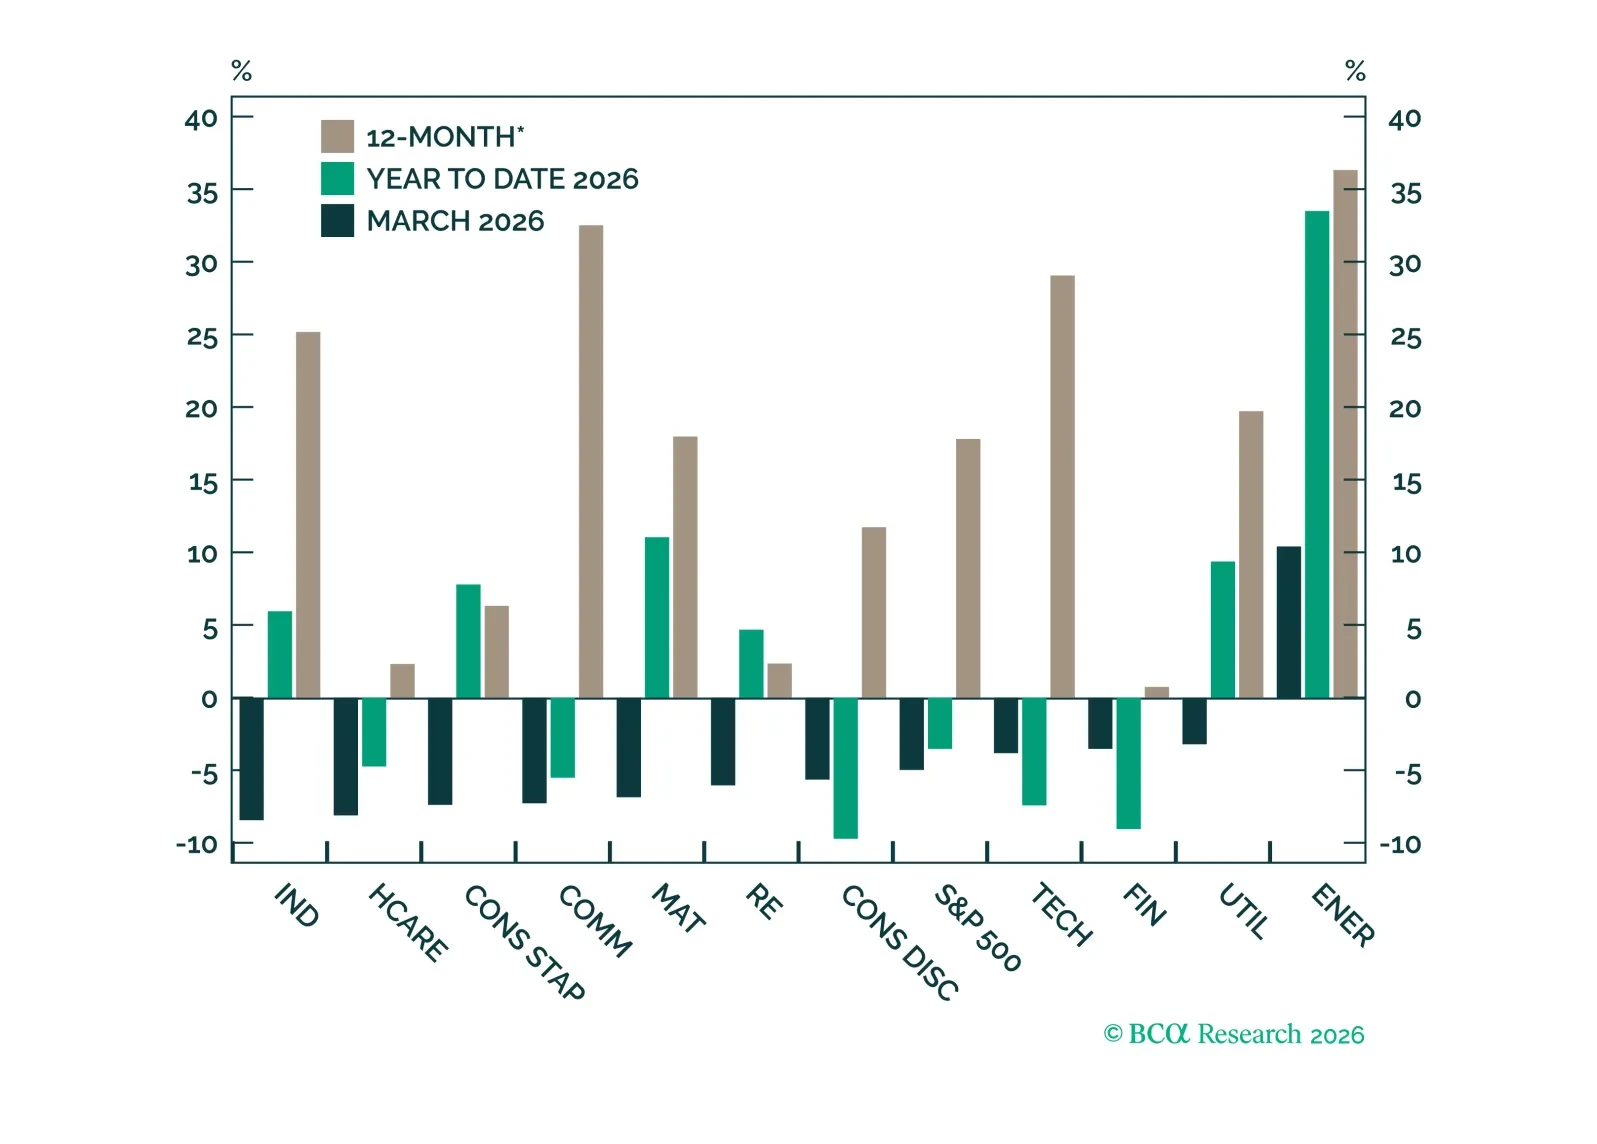
We expect the S&P 500 to deliver $308 of EPS in 2026, with a year-end target of 7700. Revenue growth drives upside, with little margin or multiple expansion. With economic growth tilted toward investment, we are overweight Technology, Industrials, and Materials, market-weight Financials, Energy, Health Care, Communication Services, and Real Estate, and underweight Consumer Staples, Consumer Discretionary, and Utilities.
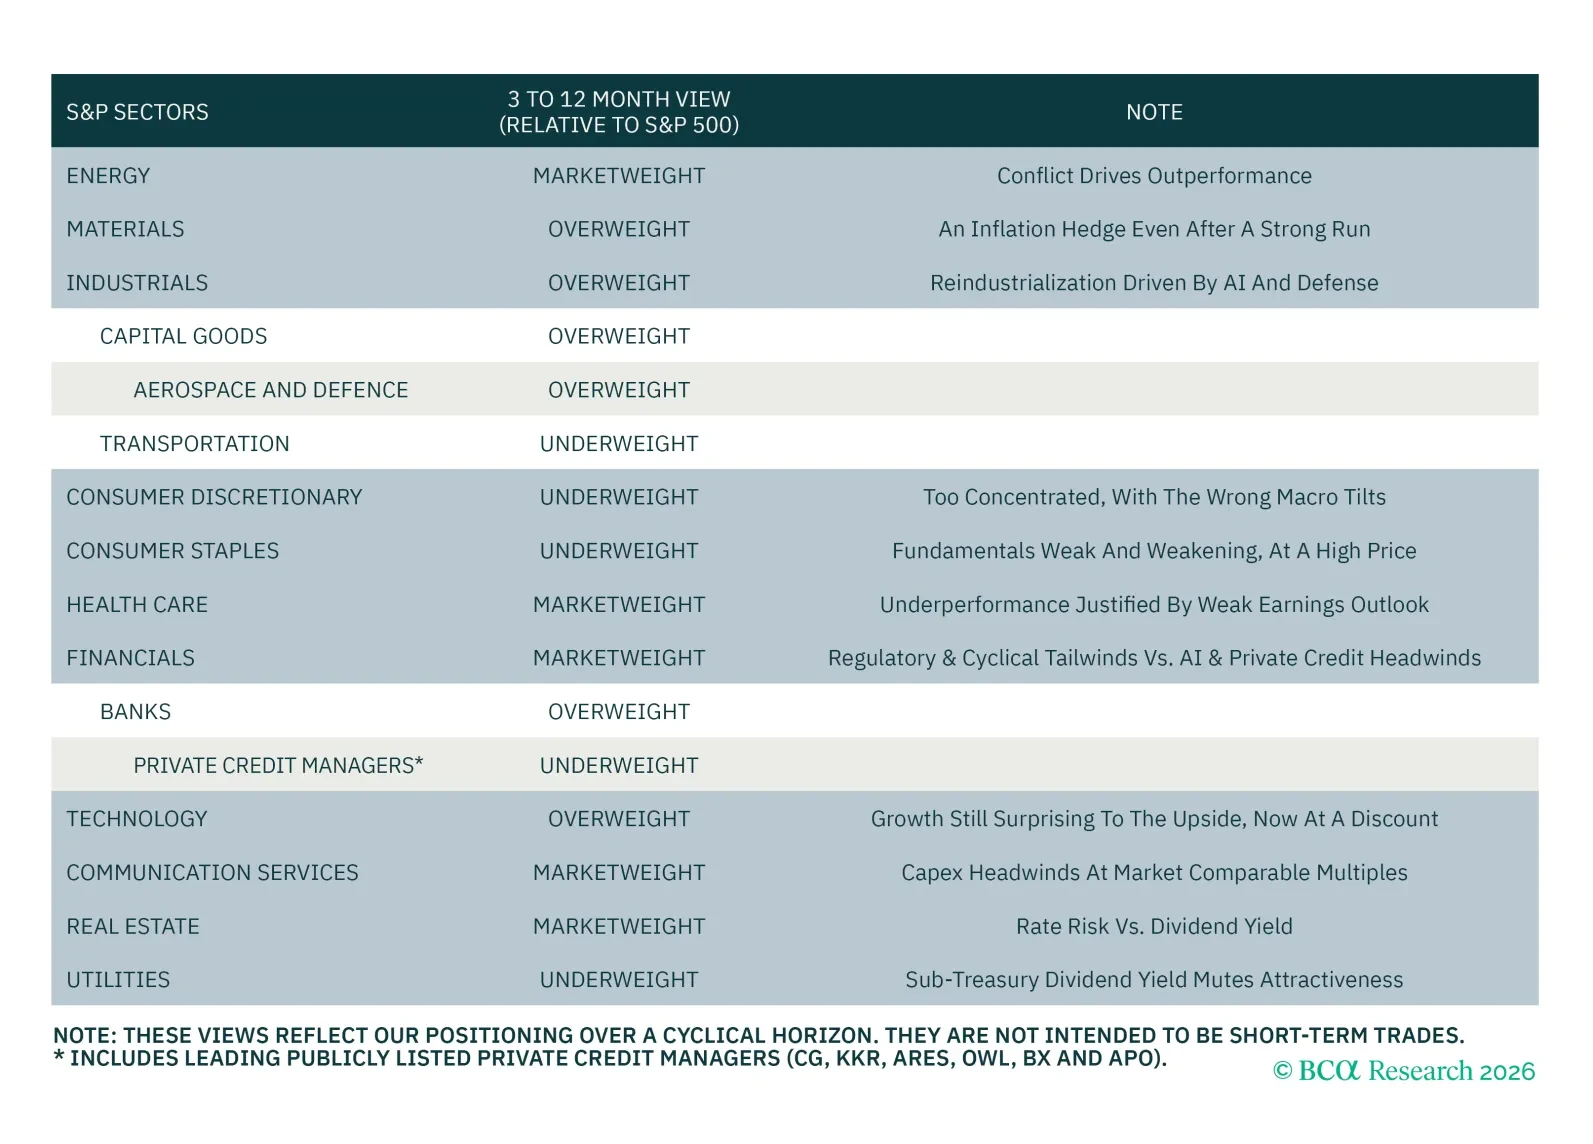
We continue to expect the S&P 500 to gain ground in 2026, driven by revenue growth, with limited scope for margin or multiple expansion. With cyclical upside tilted toward the investment side of the economy, we favor sectors with high-quality, revenue-driven earnings growth, leverage capex, and valuations that leave room for catch-up.