Sentimiento
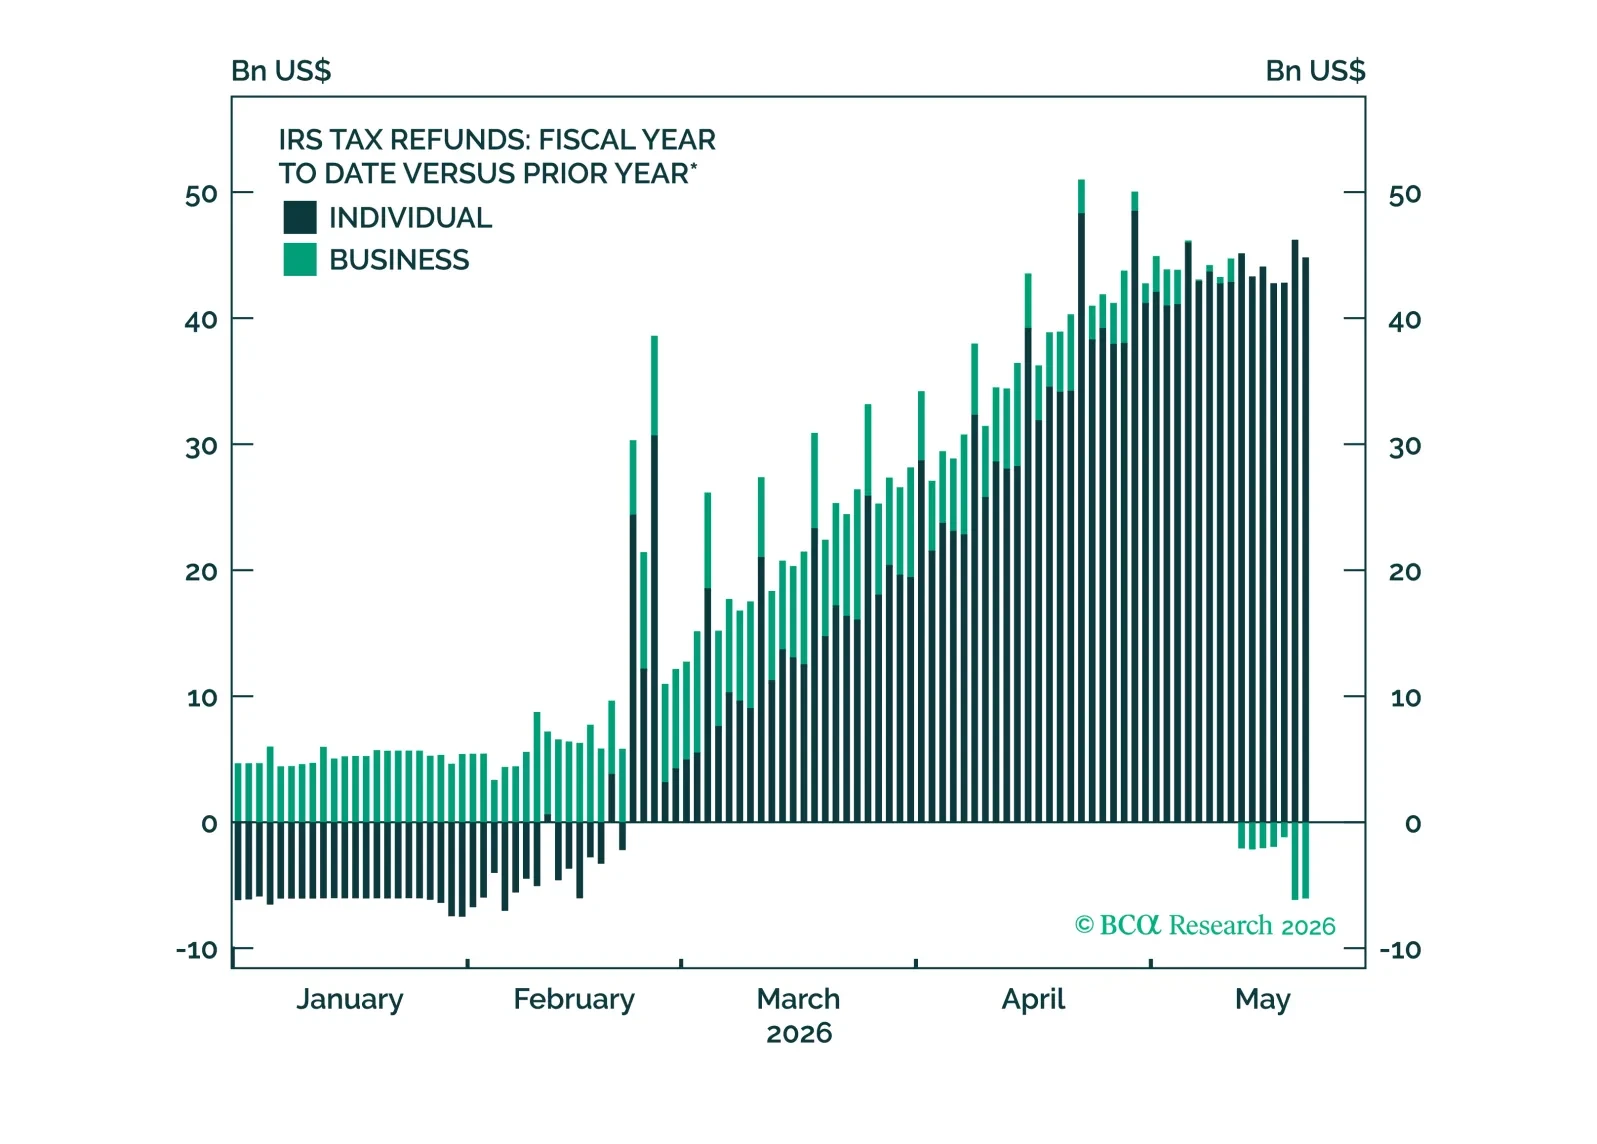
Frente al telón de fondo del mercado de "ganancias frente a todo lo demás", los resultados estelares están superando con facilidad los elevados precios del petróleo, el aumento de los rendimientos y la mayor probabilidad de que la Fed suba las tasas antes de que termine el año. Los asignadores de activos de EE. UU. deberían mantenerse invertidos en acciones.

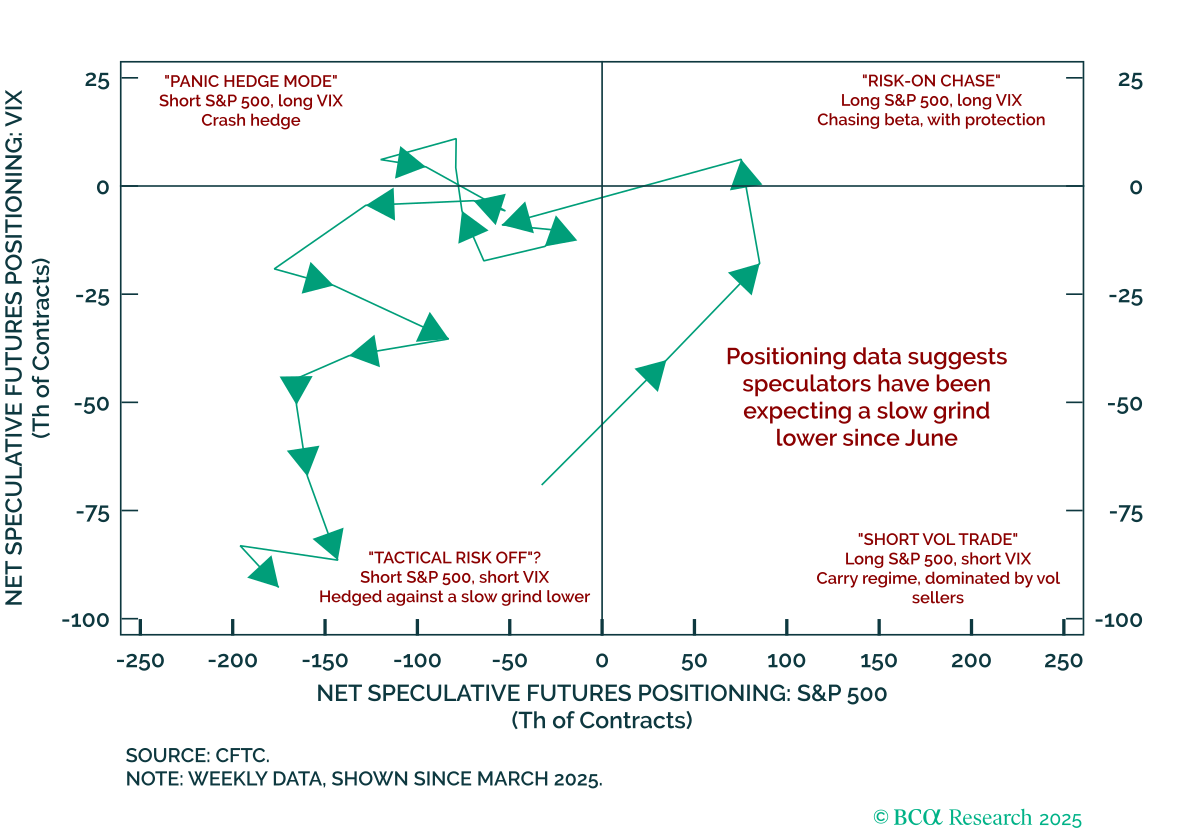
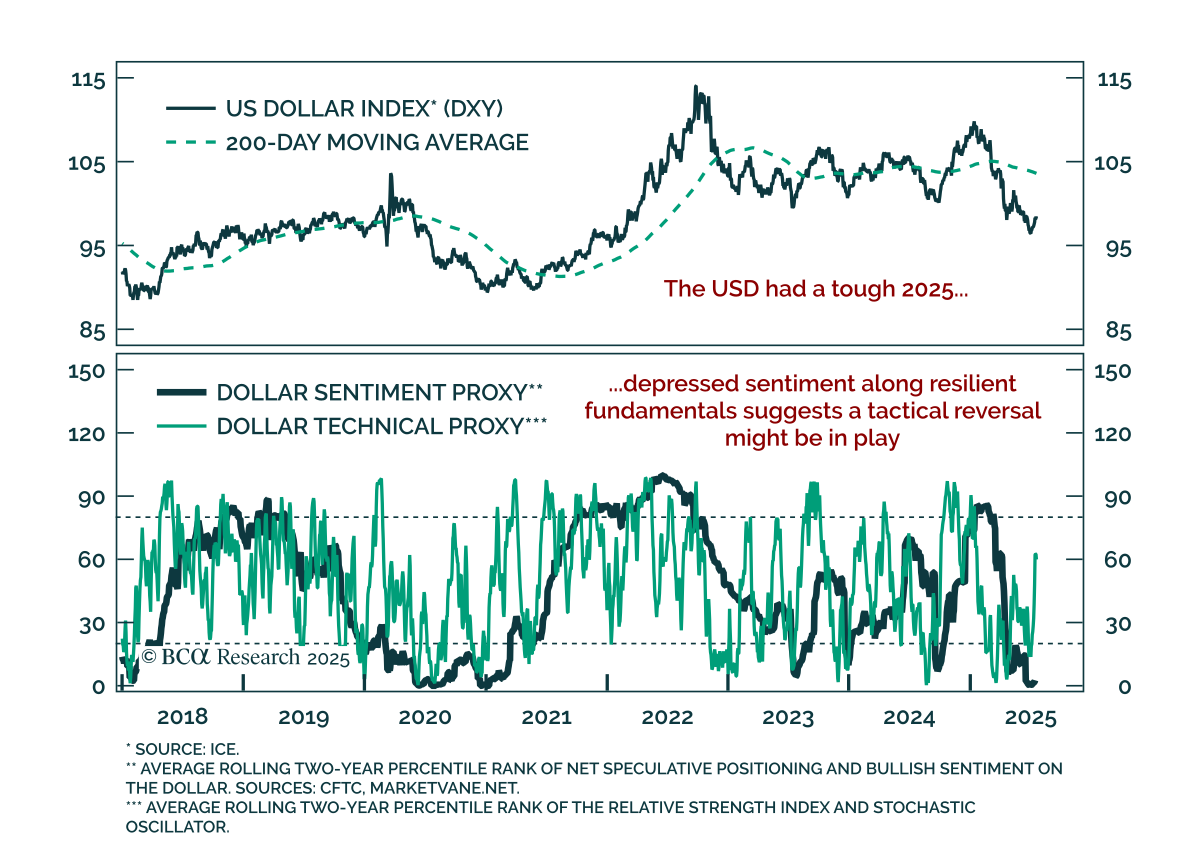
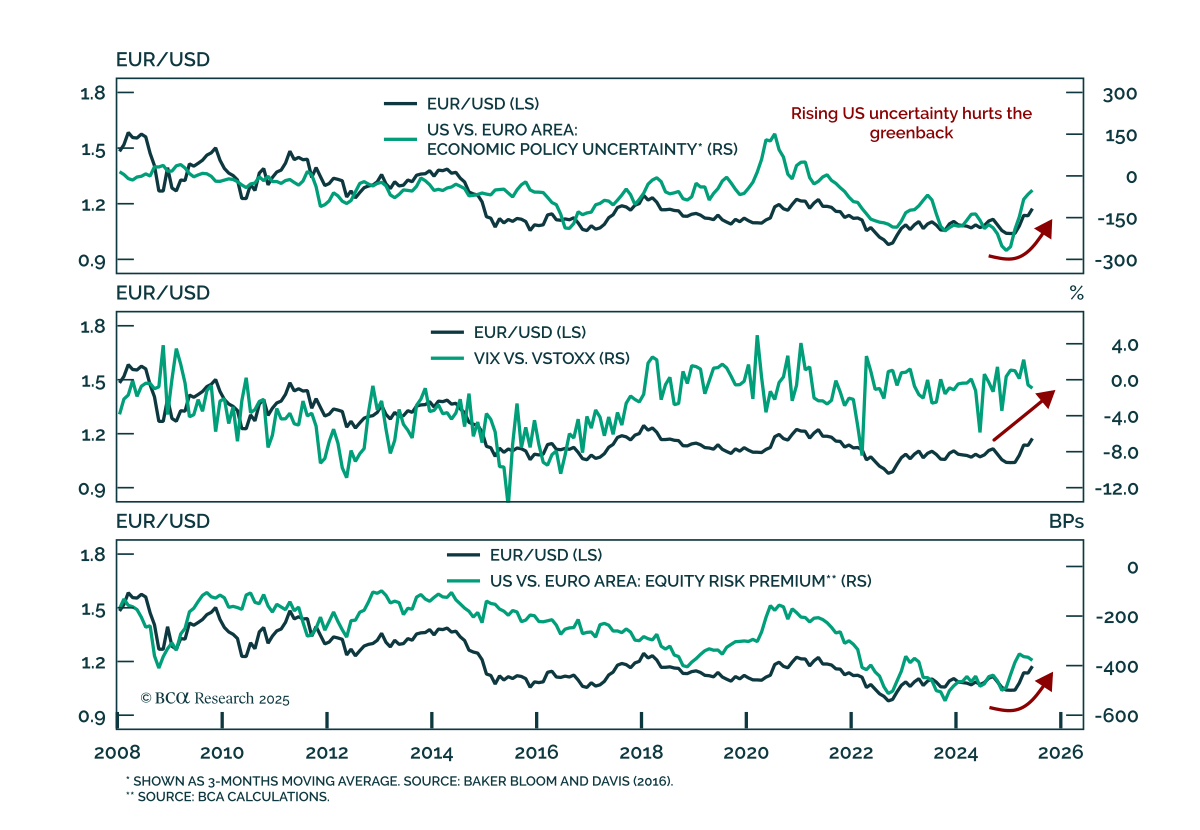
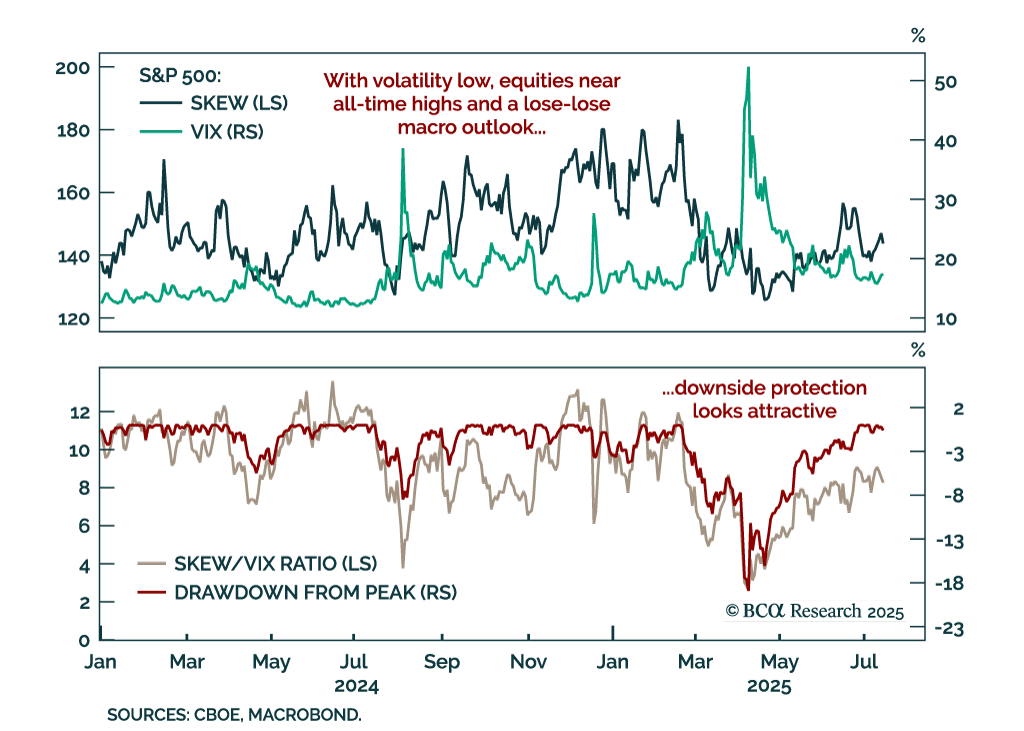
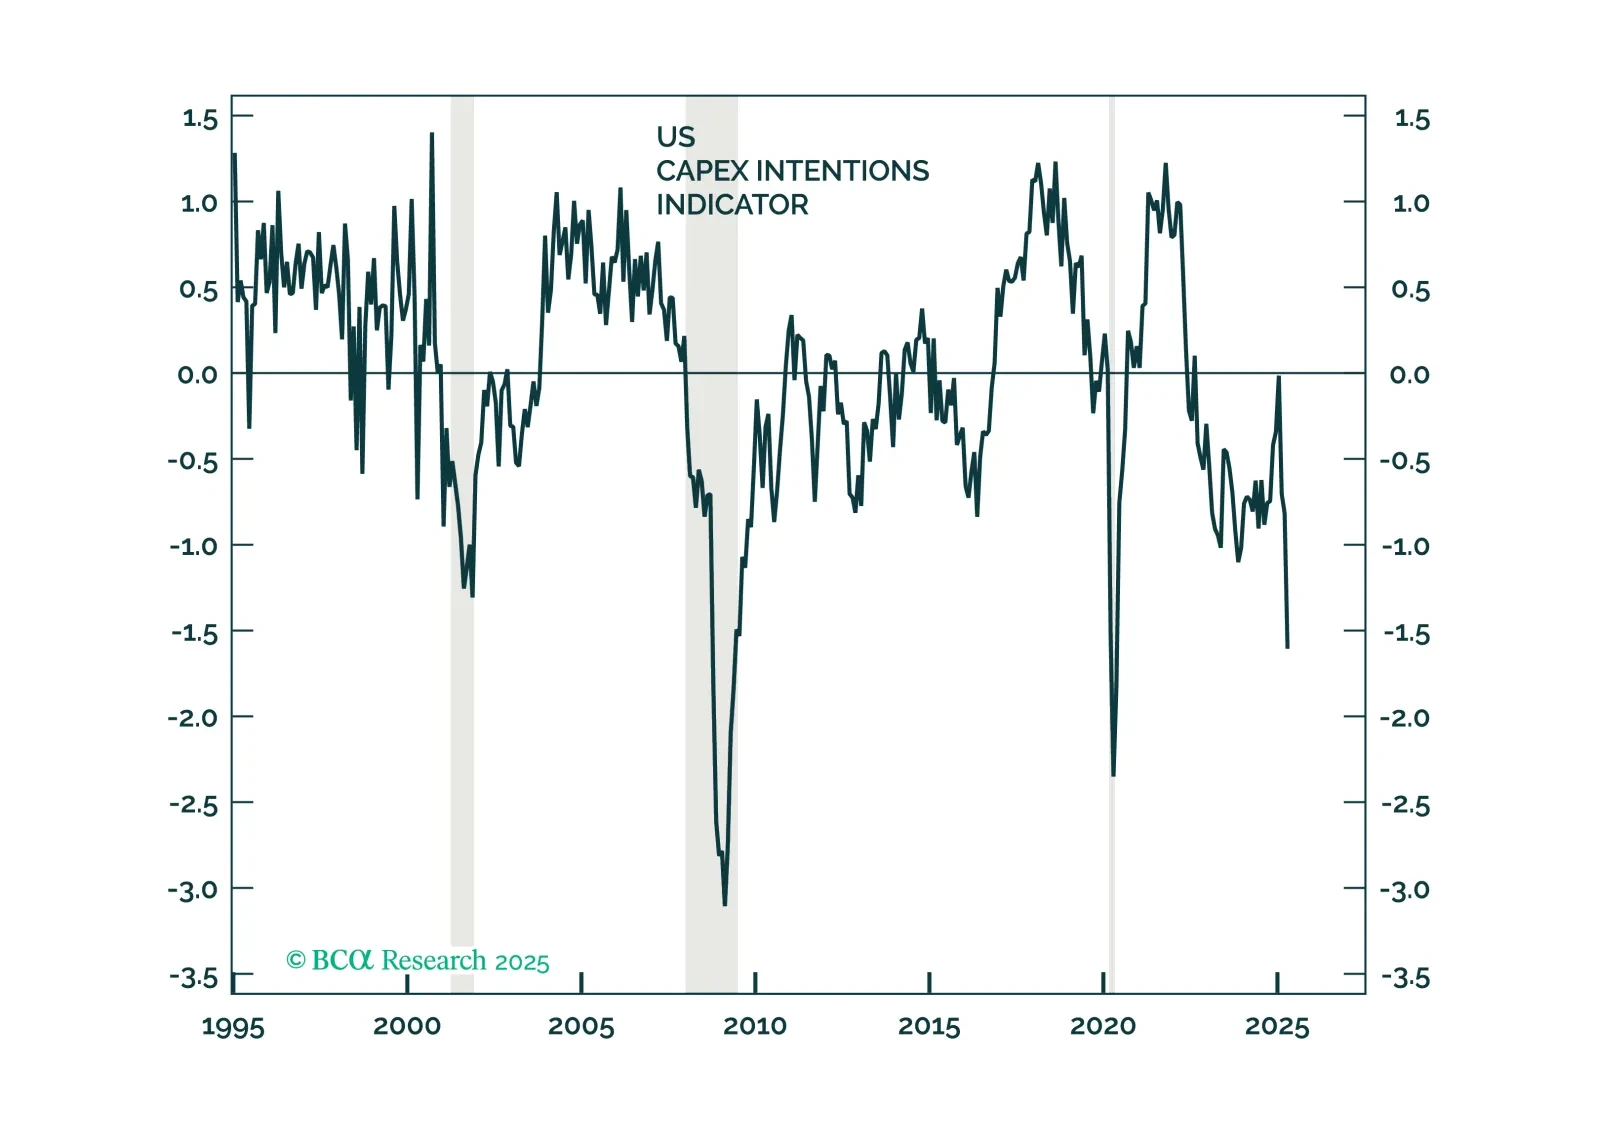
Hard aggregate macro data series remain solid, but surveys of businesses and consumers continue to worsen and the list of consumer-facing companies lowering earnings estimates gets longer by the week. We believe surging equities are ignoring the adverse effects of tariffs and reiterate our defensive asset allocation recommendations.
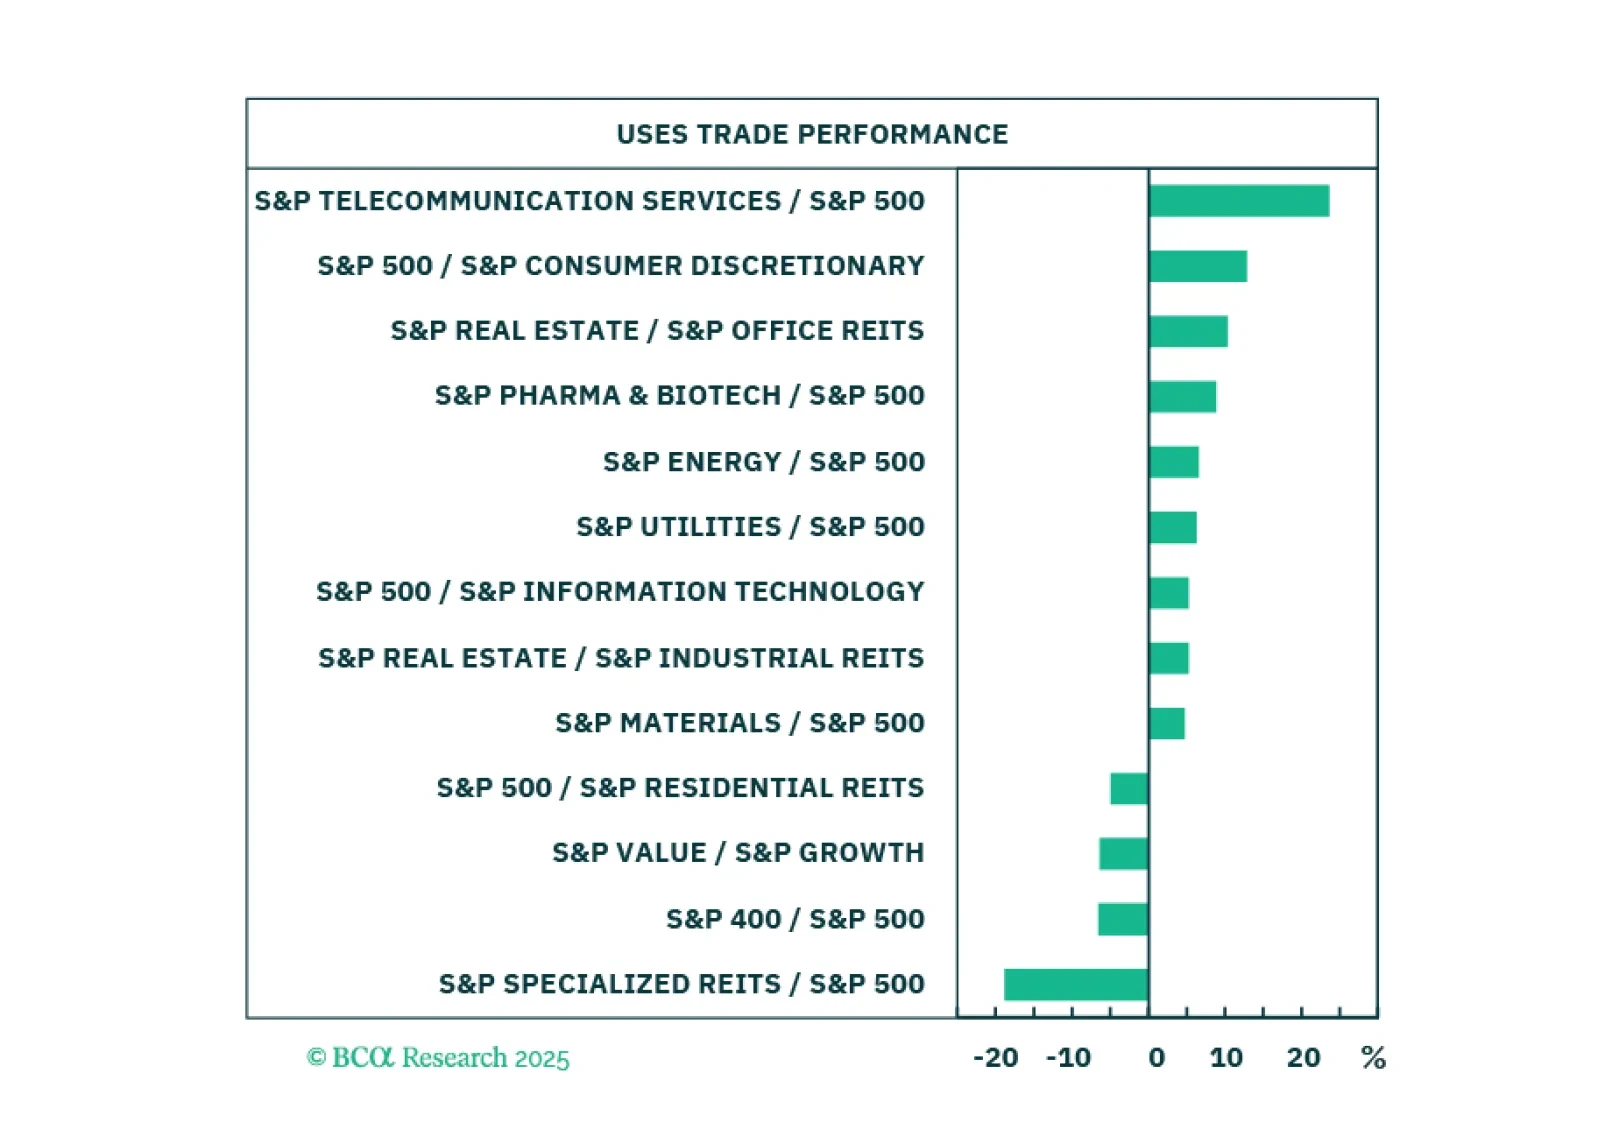
The US economy faces a new investment regime characterized by tighter fiscal and easier monetary policies. The market corrected fast, and a short-lived equity rebound is likely. However, over the long term, US equities face economic headwinds.
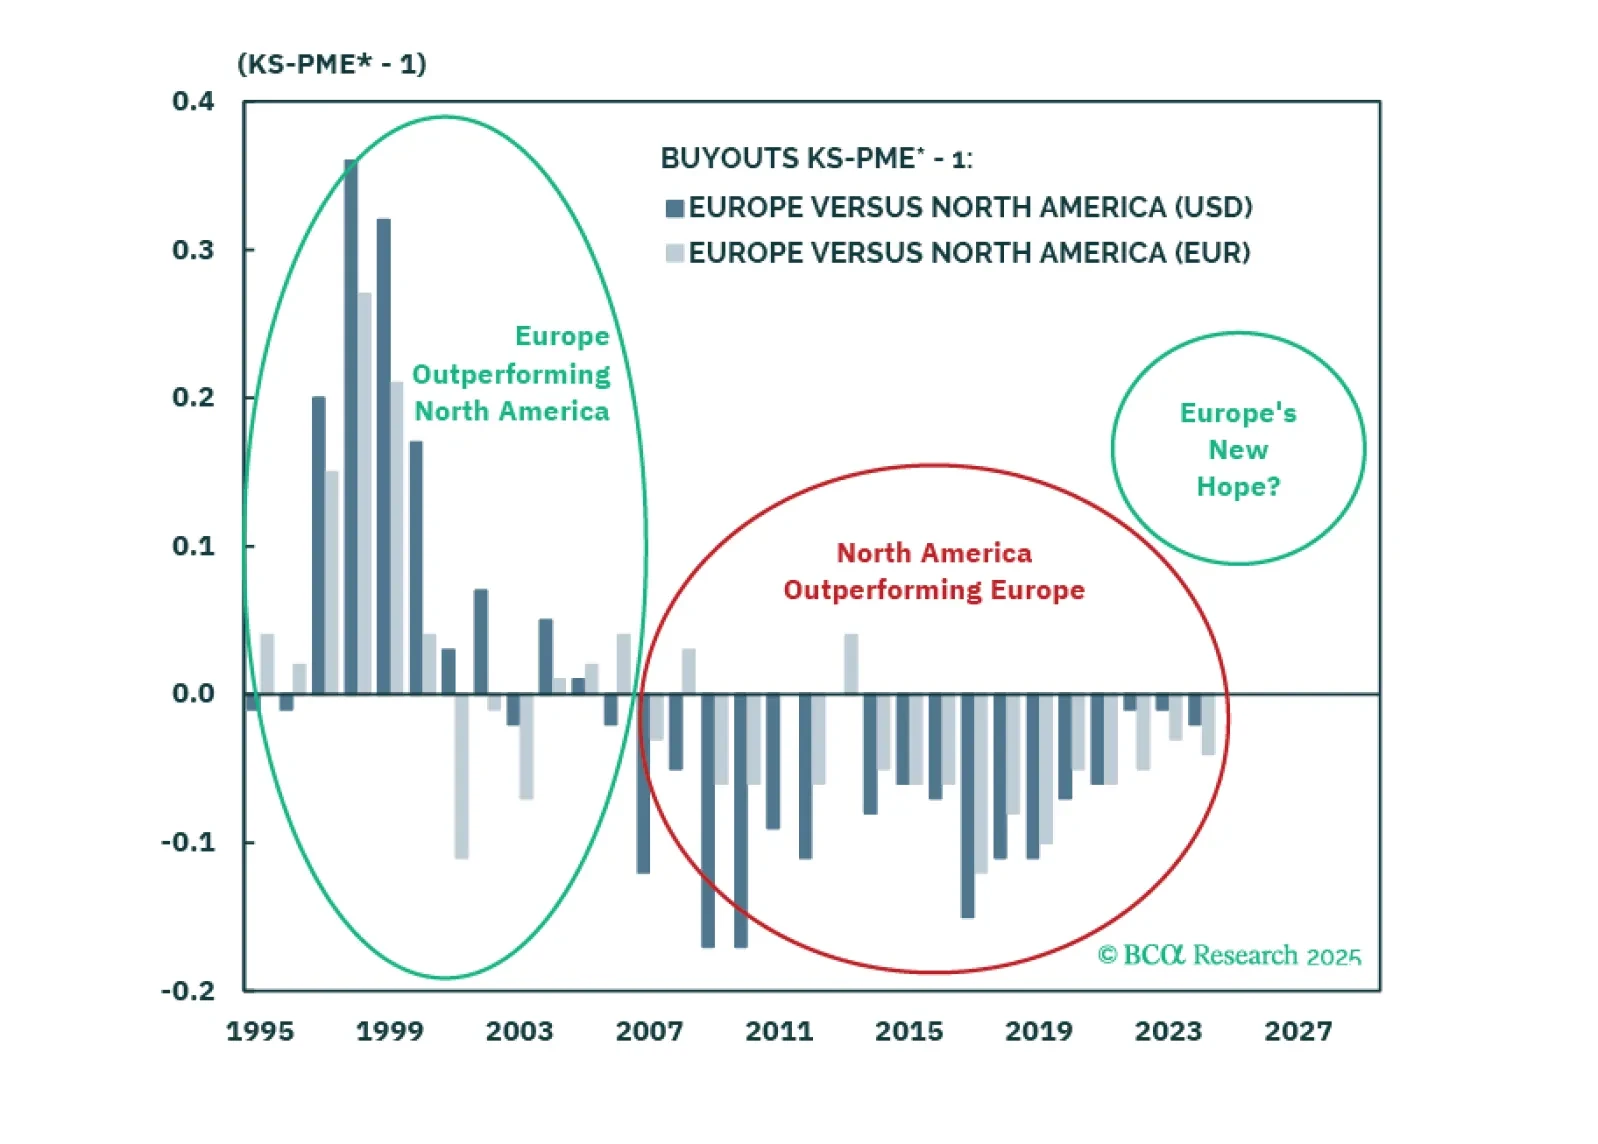
We are at a pivotal moment for Europe, supported by structural reforms and macro catalysts. While expanding credit markets and lower rates favor Private Equity over Private Credit, opportunities vary by segment. Large+ Buyouts are attractive as markets have priced in structural challenges. We downgrade Europe Private Credit, remain neutral on Europe Private Equity broadly but overweight Europe vs. North America in PE portfolios.
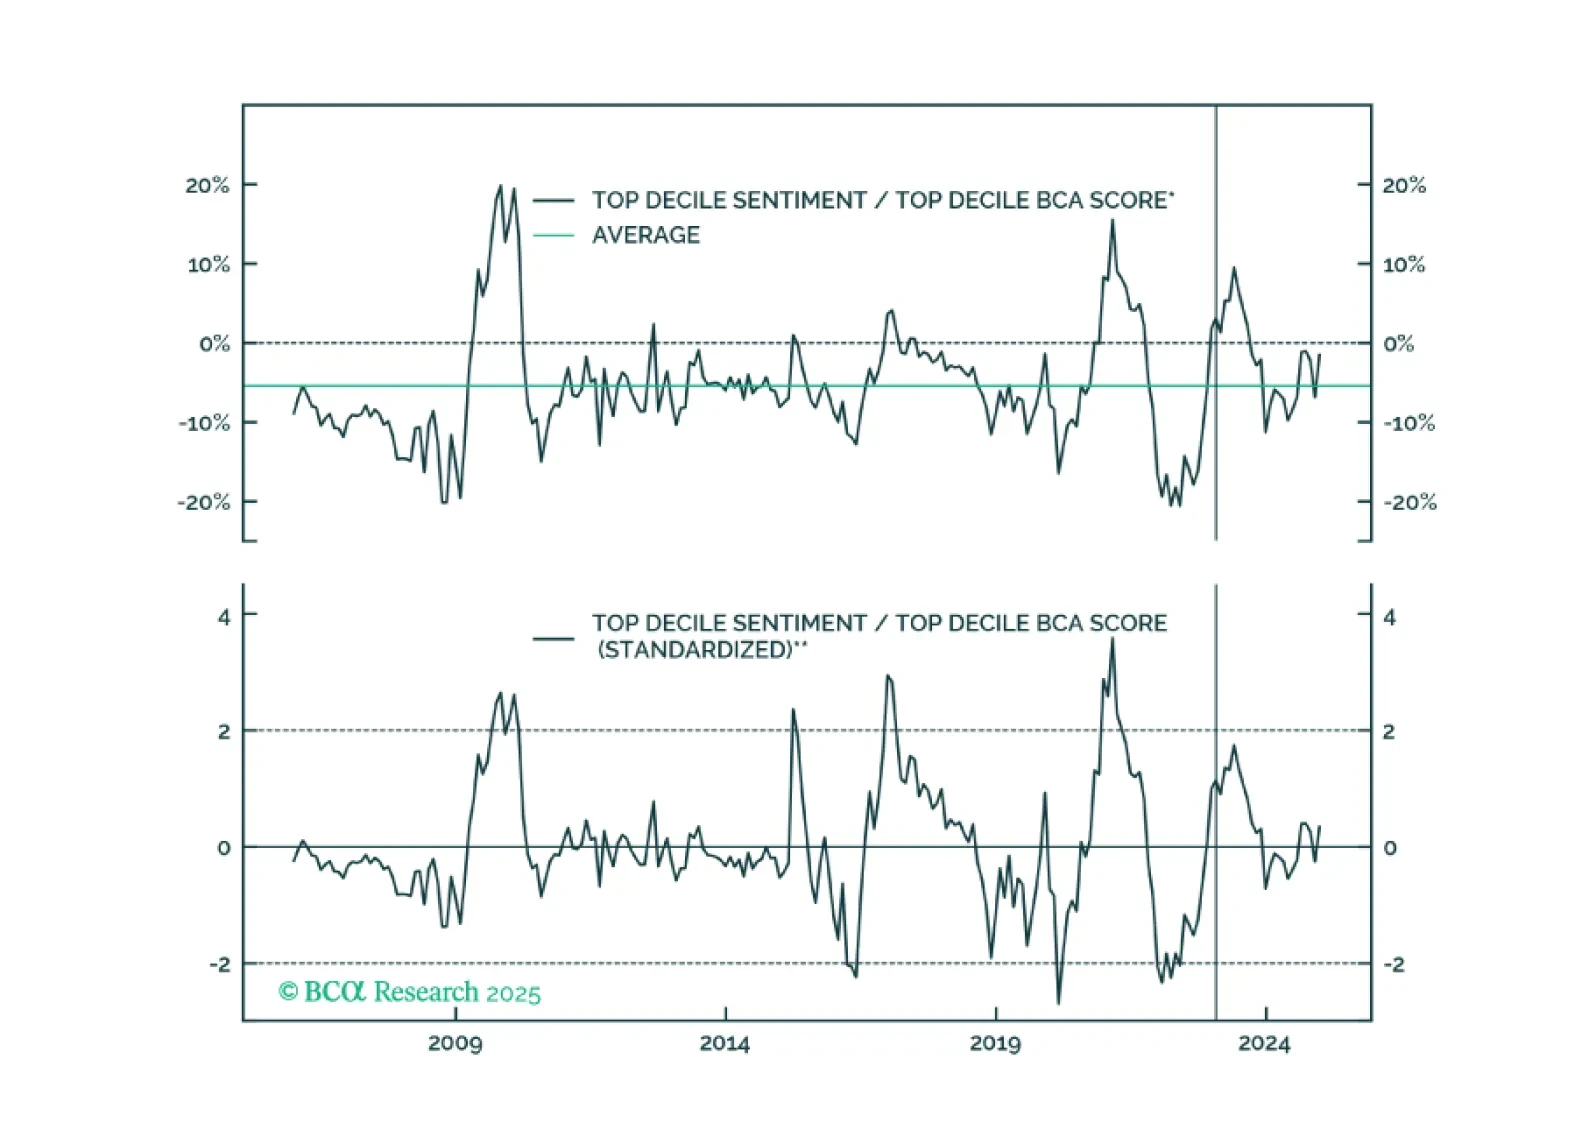
Sentiment will stay positive for now, but downside risks are rising. Investors should proceed cautiously in stock picking and portfolio construction at this juncture, given rising economic and policy uncertainty, which threaten market sentiment, and more broadly, the current bull-market.