Geopolitics
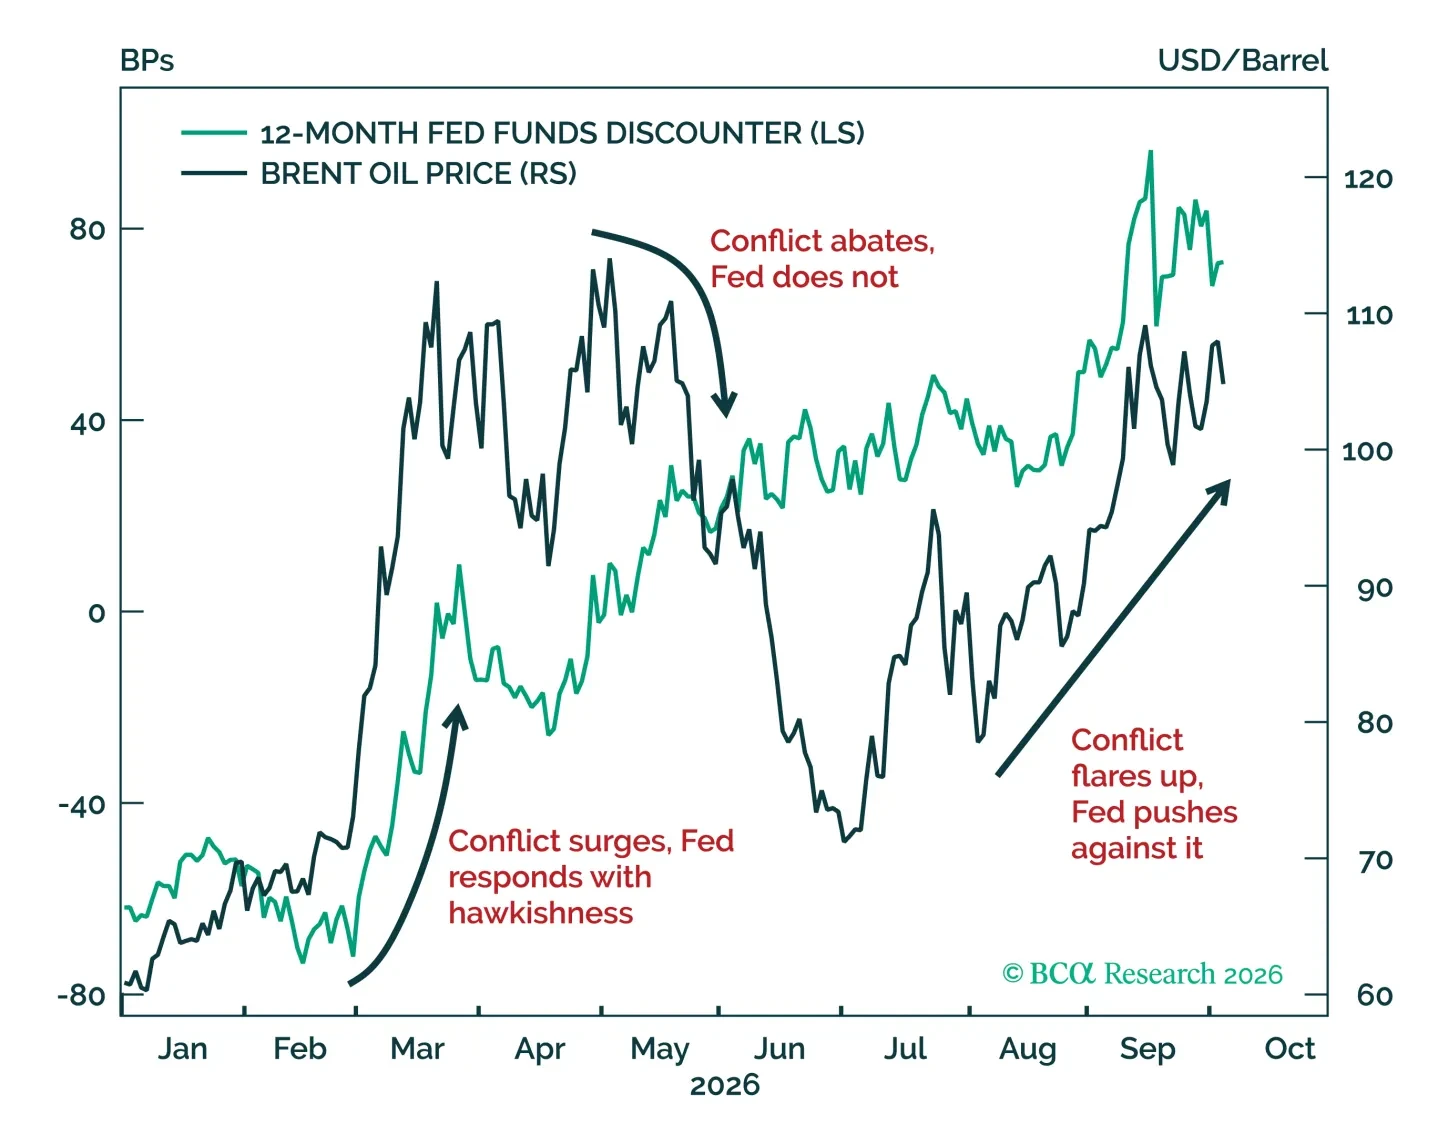
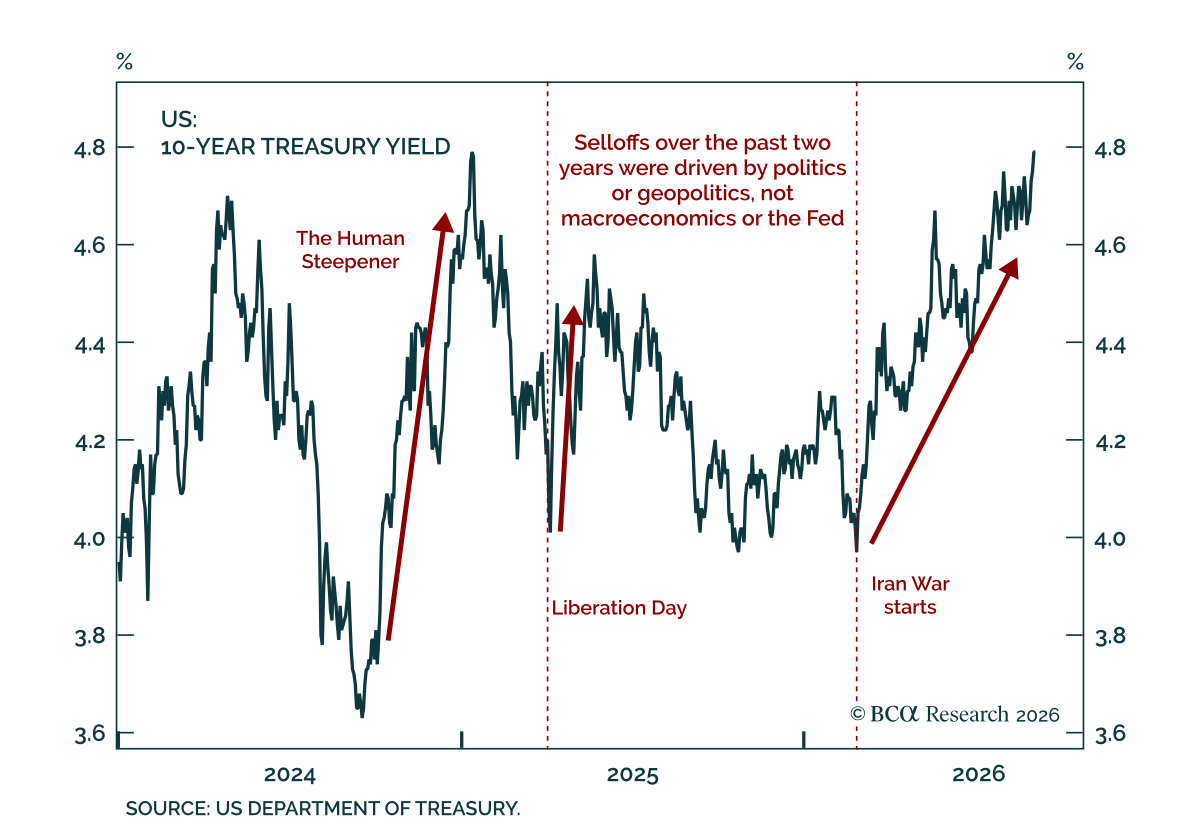
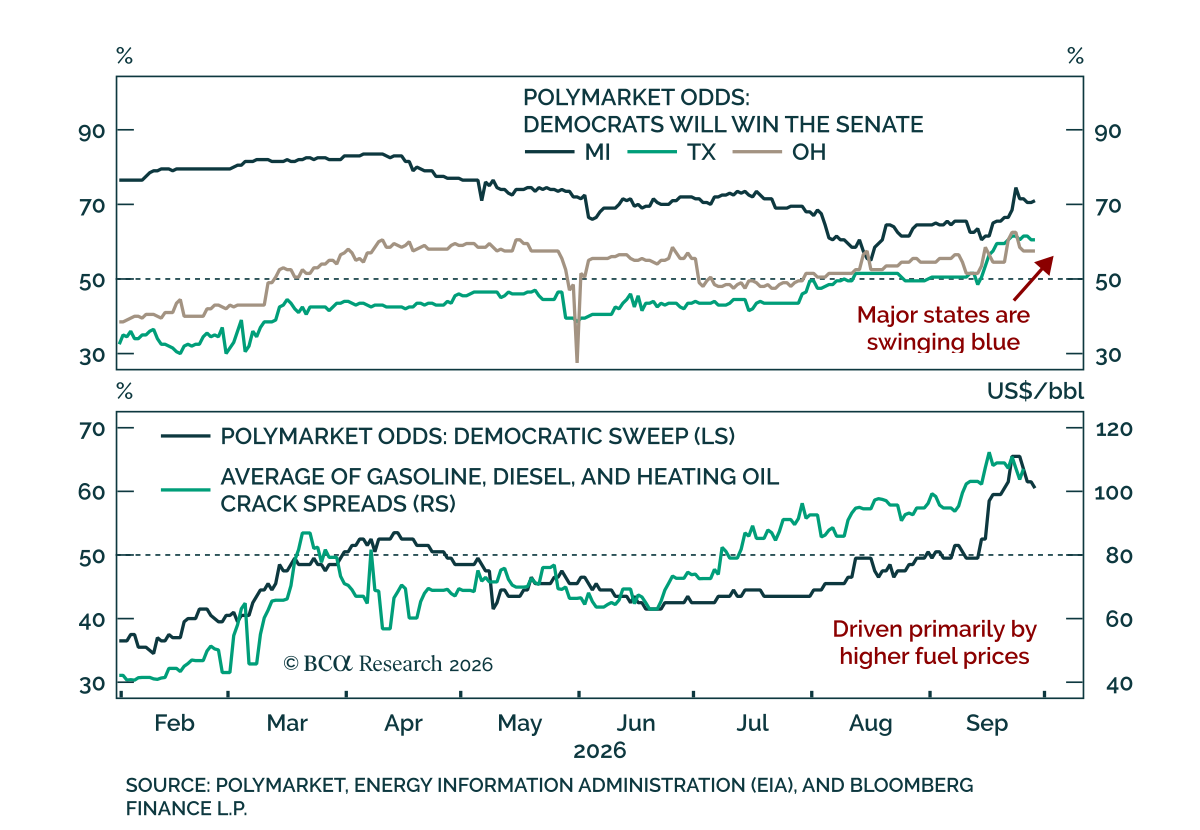
Long-dated bond yields rose another 48 bps since our last missive, quite a move in just a month. And yet, equities have remained resilient. This suggests that the move in bond yields is due to sanguine economic forces, not fiscal profligacy or inflation fears. In addition, the war in Iran is subsiding, partly because the Fed itself has conspired against it. Will President Trump restart the conflict regardless? Perhaps, however, the constraints are mounting against the White House foreign policy. We remain bullish on equities and reaffirm our view that investors with a long-term horizon should be nibbling at the current level of yields.
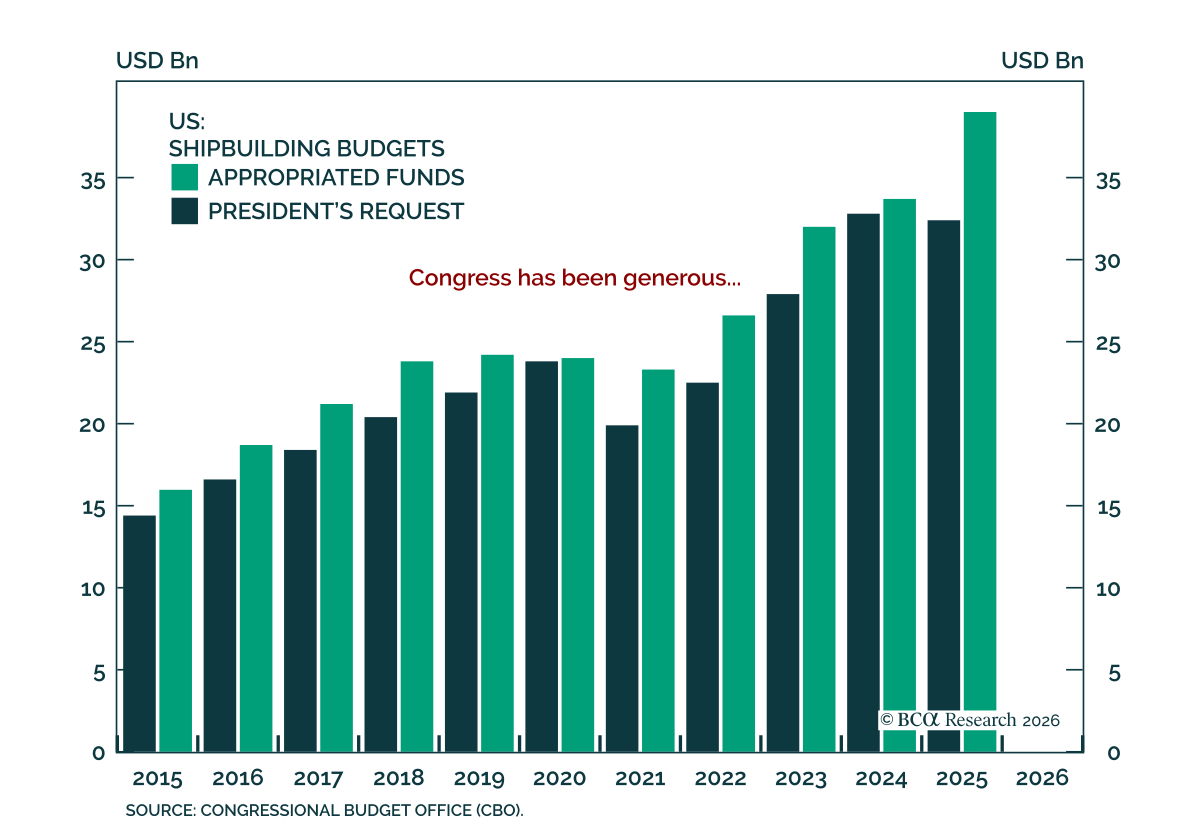
To make sure that our bearish clients are happy, we pivot to the risk of higher tax rates in the US. Specifically, we try to answer the question of when markets price higher tax rates.
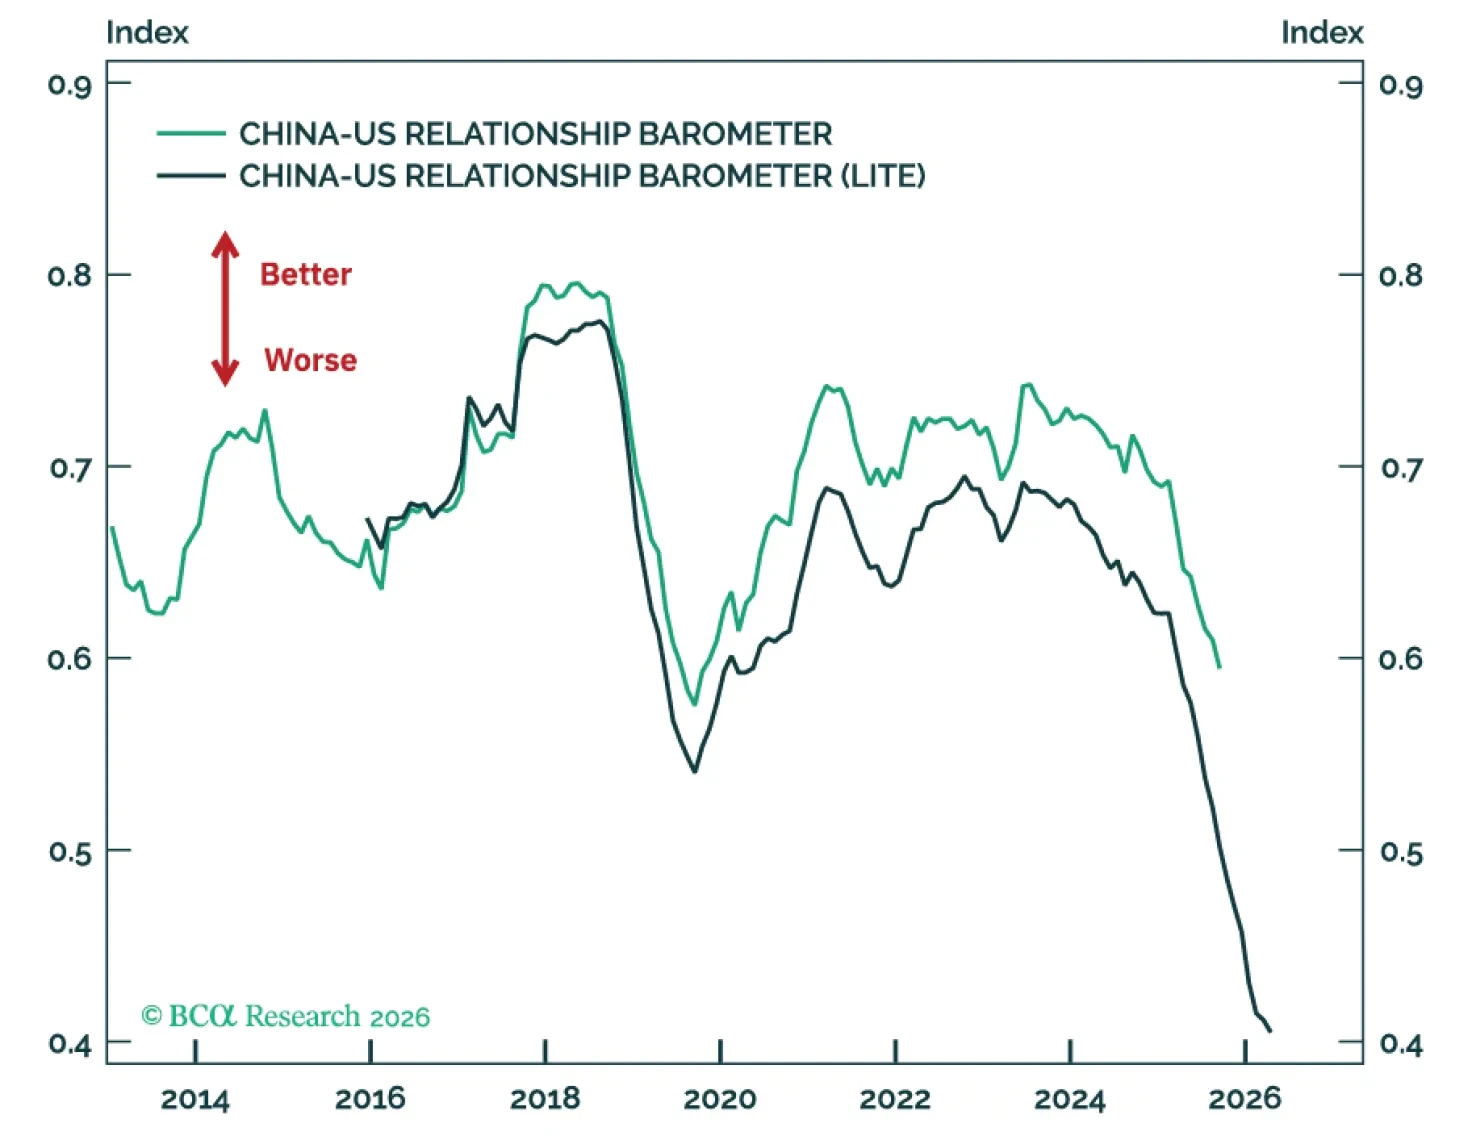
La cumbre Trump-Xi no implica beneficios concretos para el comercio entre Estados Unidos y China. Persisten tensiones estratégicas que obligan a China a aumentar el estímulo fiscal en 2027.
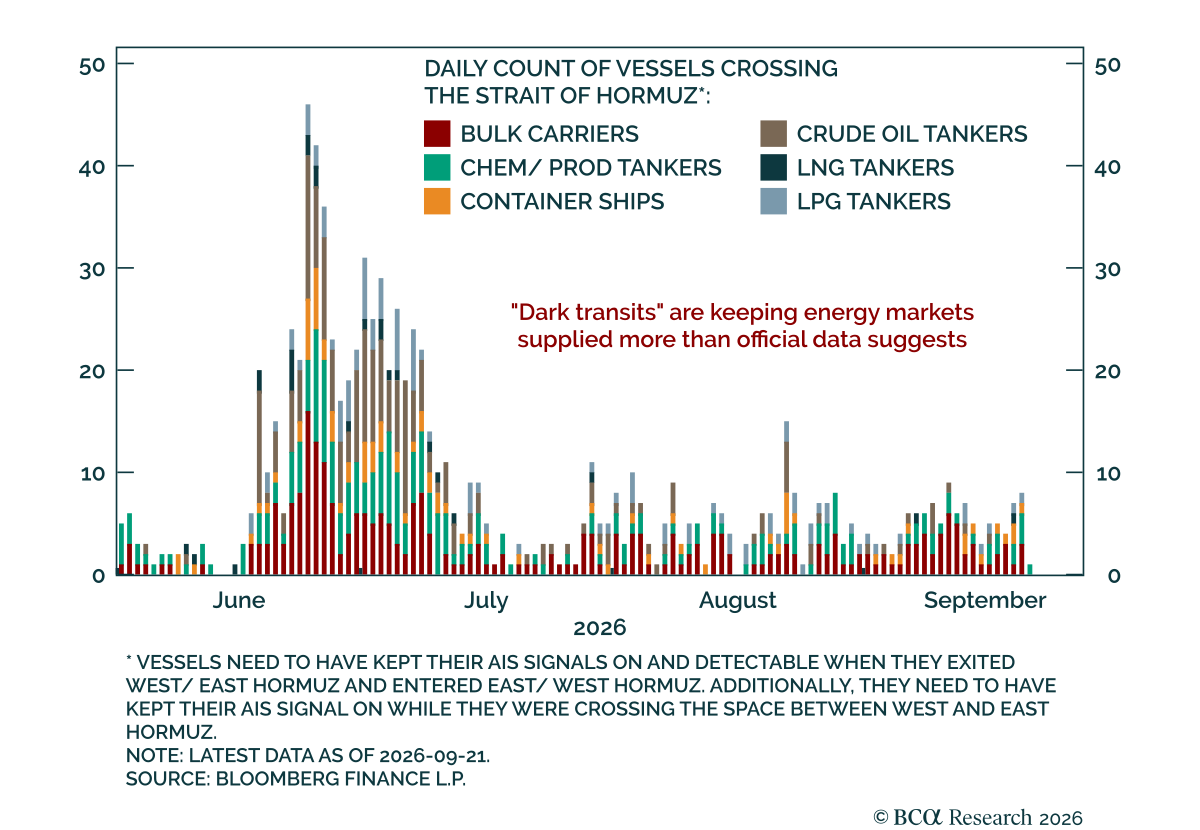

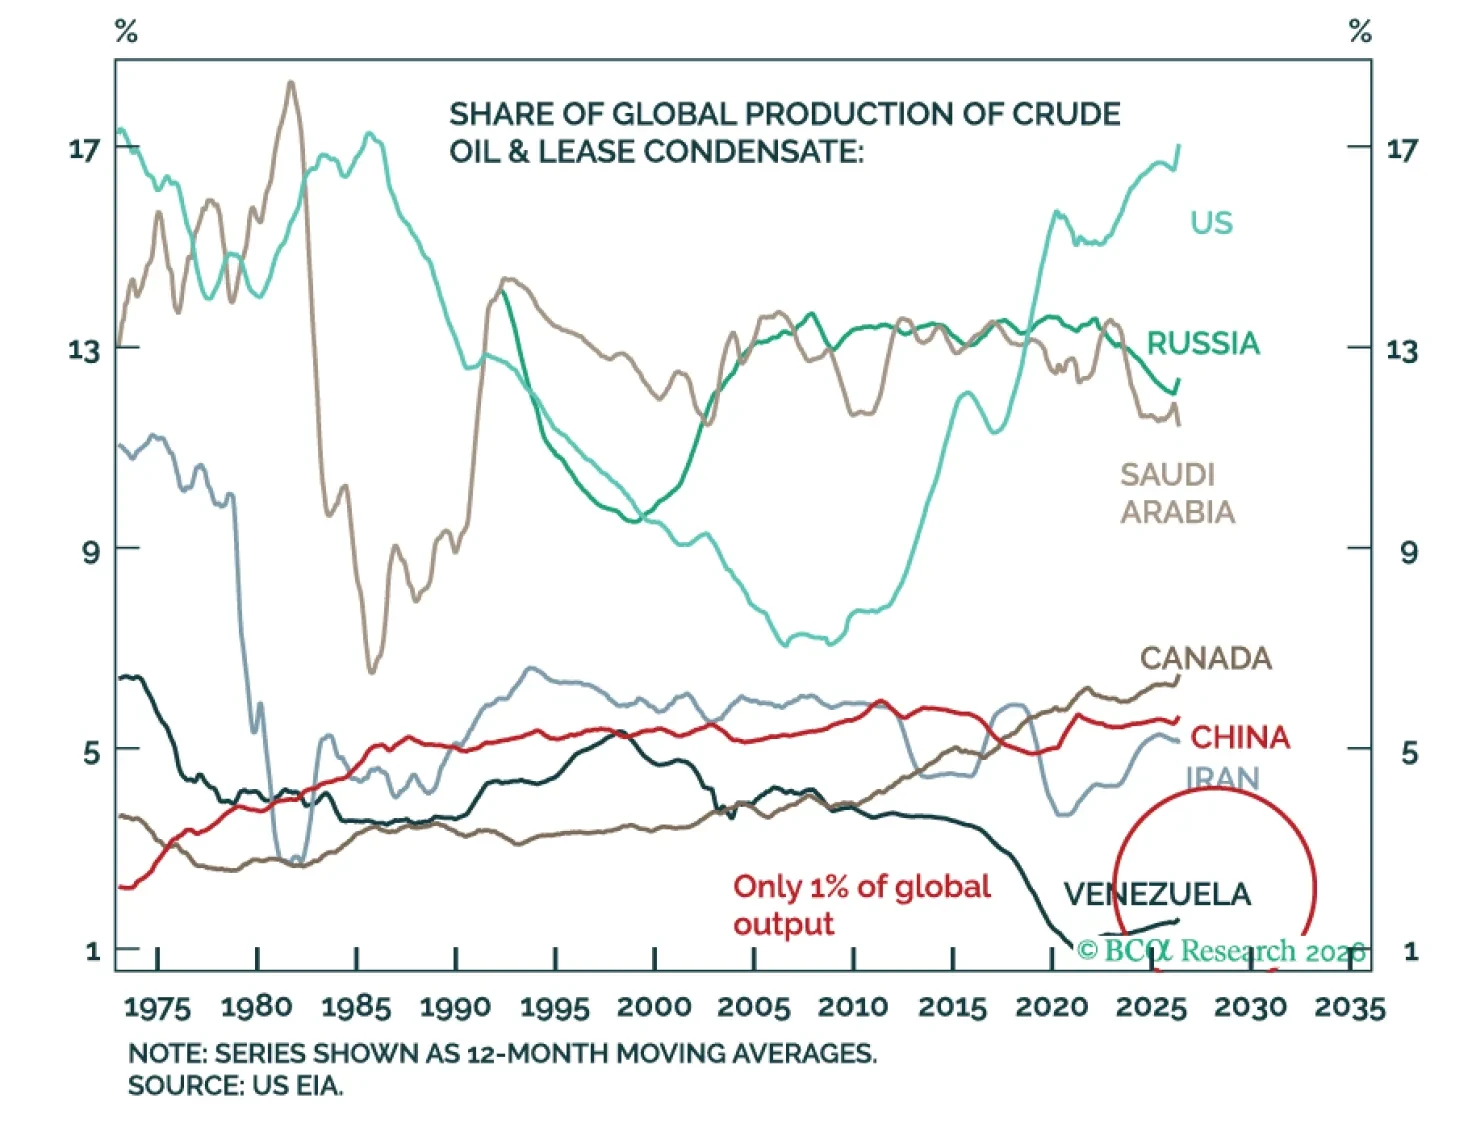
El presidente Trump calificó el acuerdo EE. UU.-Venezuela como el “mayor acuerdo petrolero de la historia mundial”. Sin embargo, las limitaciones al crecimiento de la producción de petróleo reducen su impacto a corto plazo en los mercados mundiales de crudo. En cambio, los acontecimientos en Oriente Medio seguirán dominando la trayectoria del petróleo durante los próximos meses.