Sorry, you need to enable JavaScript to visit this website.
Saltar al contenido principal

Economía

Informe especial

The US and Canada will resolve their trade dispute quickly, leading to a North American deal and better prospects for future relations, as well as for other US trade deals around the world. But even as tariff threats decline, the US economy will slow, weighing on its neighbors. Canada will fare better than Mexico.

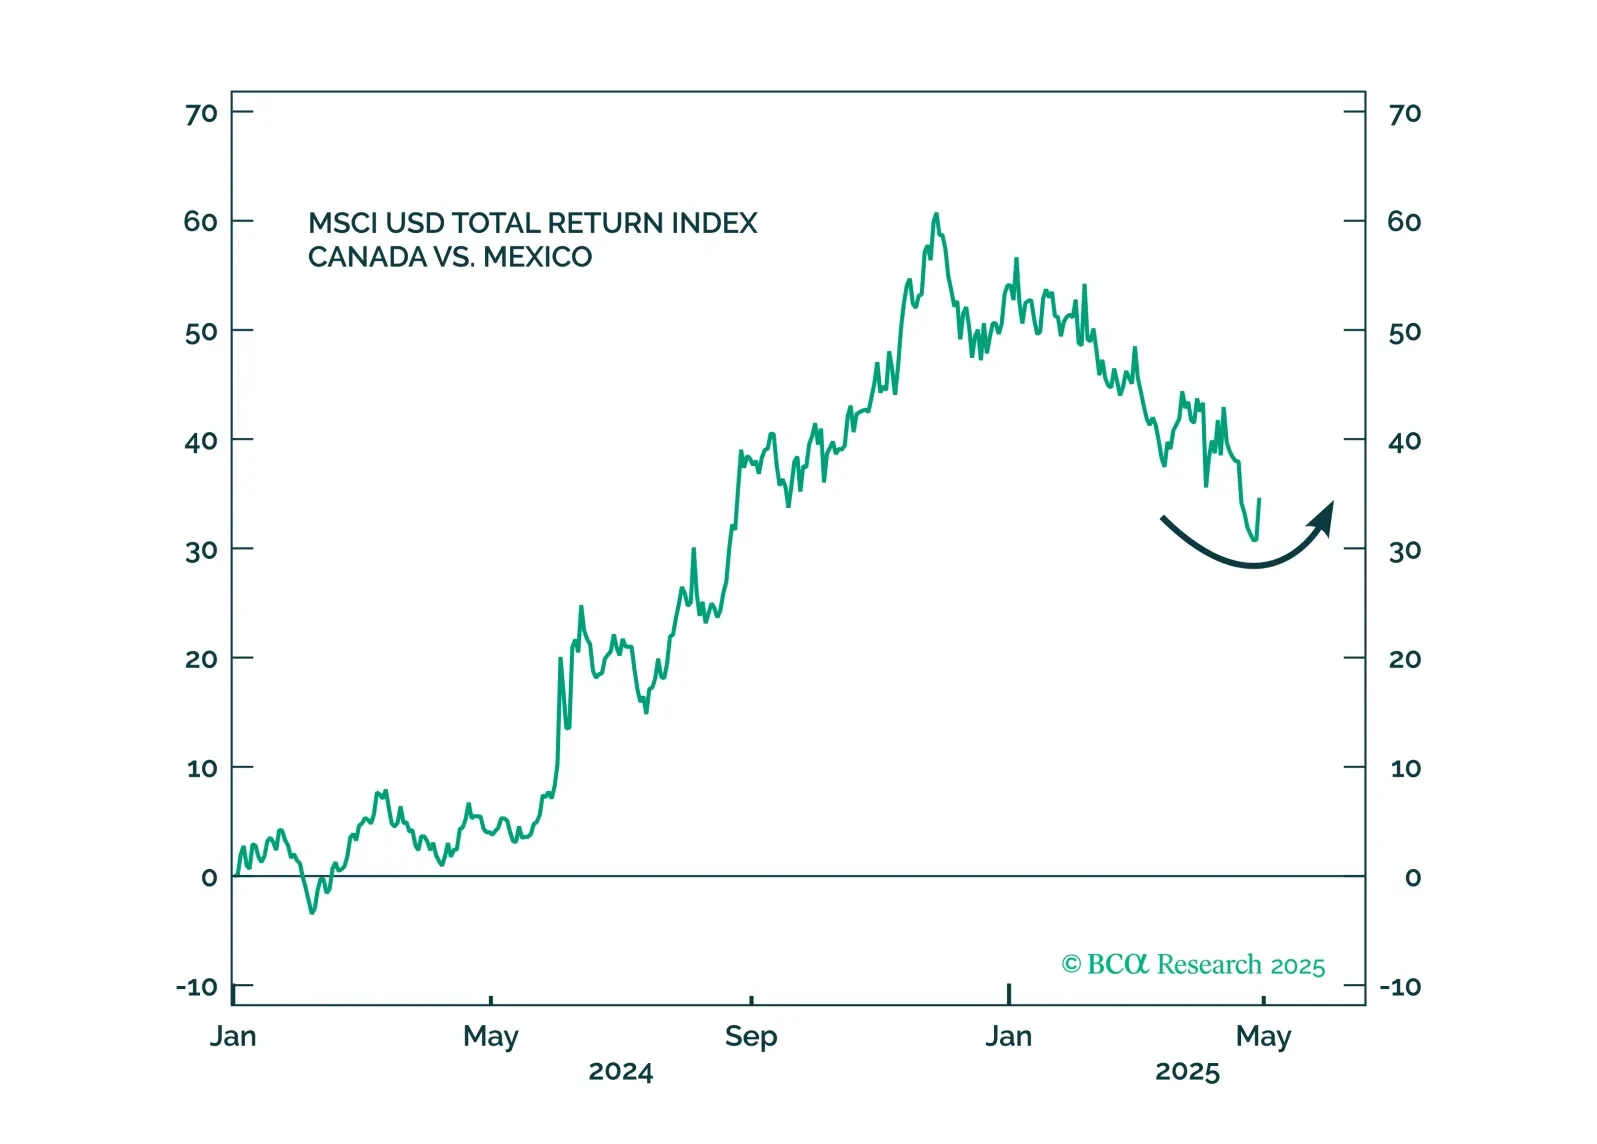
Canada’s election outcome and macro backdrop support our neutral stance on CGBs and long CAD/USD structural positioning. Mark Carney’s Liberals retained power in Monday’s federal election and are likely to form a minority government. The campaign centered on…
The April Conference Board survey adds to signs of labor market softening, reinforcing our defensive asset allocation. The Consumer Confidence index fell for the fifth consecutive month to 86.0 from 92.9. Expectations plunged to their lowest since 2011.…
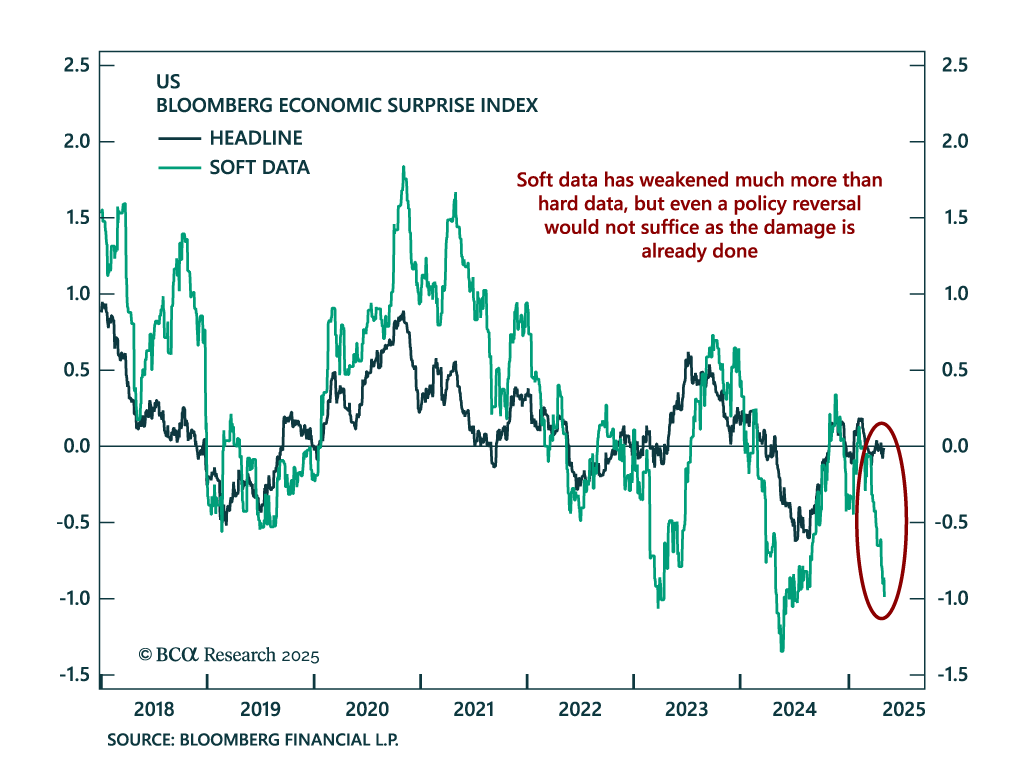
The collapse in soft data points to rising recession risks, but markets are still only priced for a mild slowdown, reinforcing our defensive positioning. As policy uncertainty and market volatility surged, consumers and businesses signaled plans to delay…
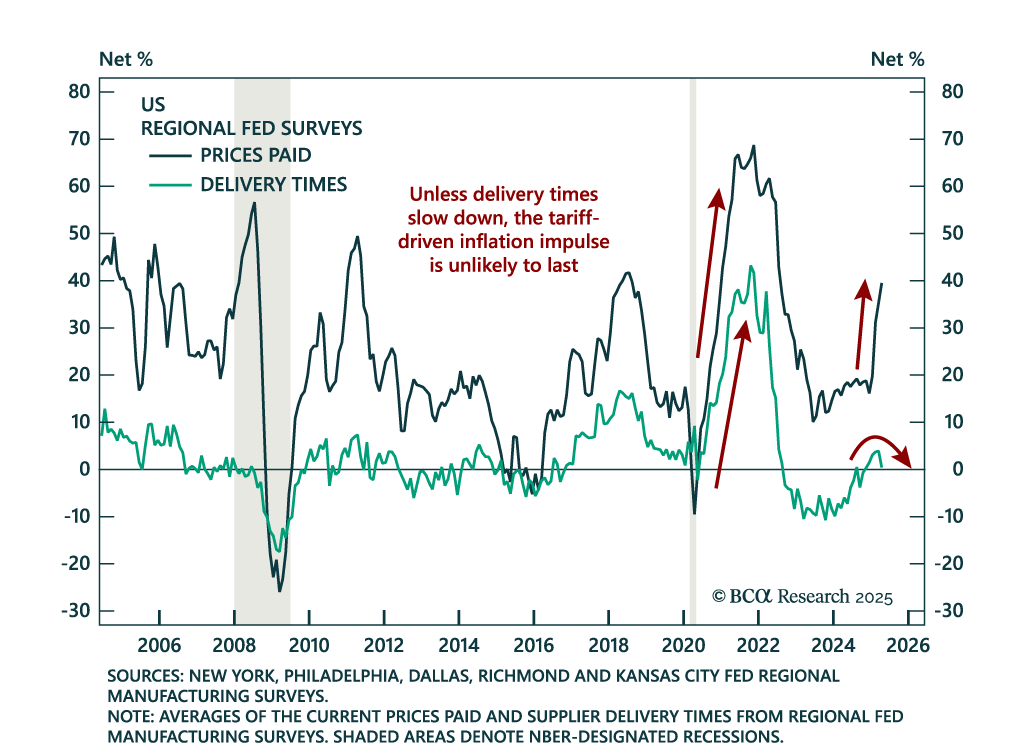
The April Dallas Fed Manufacturing survey adds to recent stagflationary signals, reinforcing our preference for gold over industrial commodities. The index plunged to -35.8 from -16.3 in March, with activity measures deteriorating and price pressures…

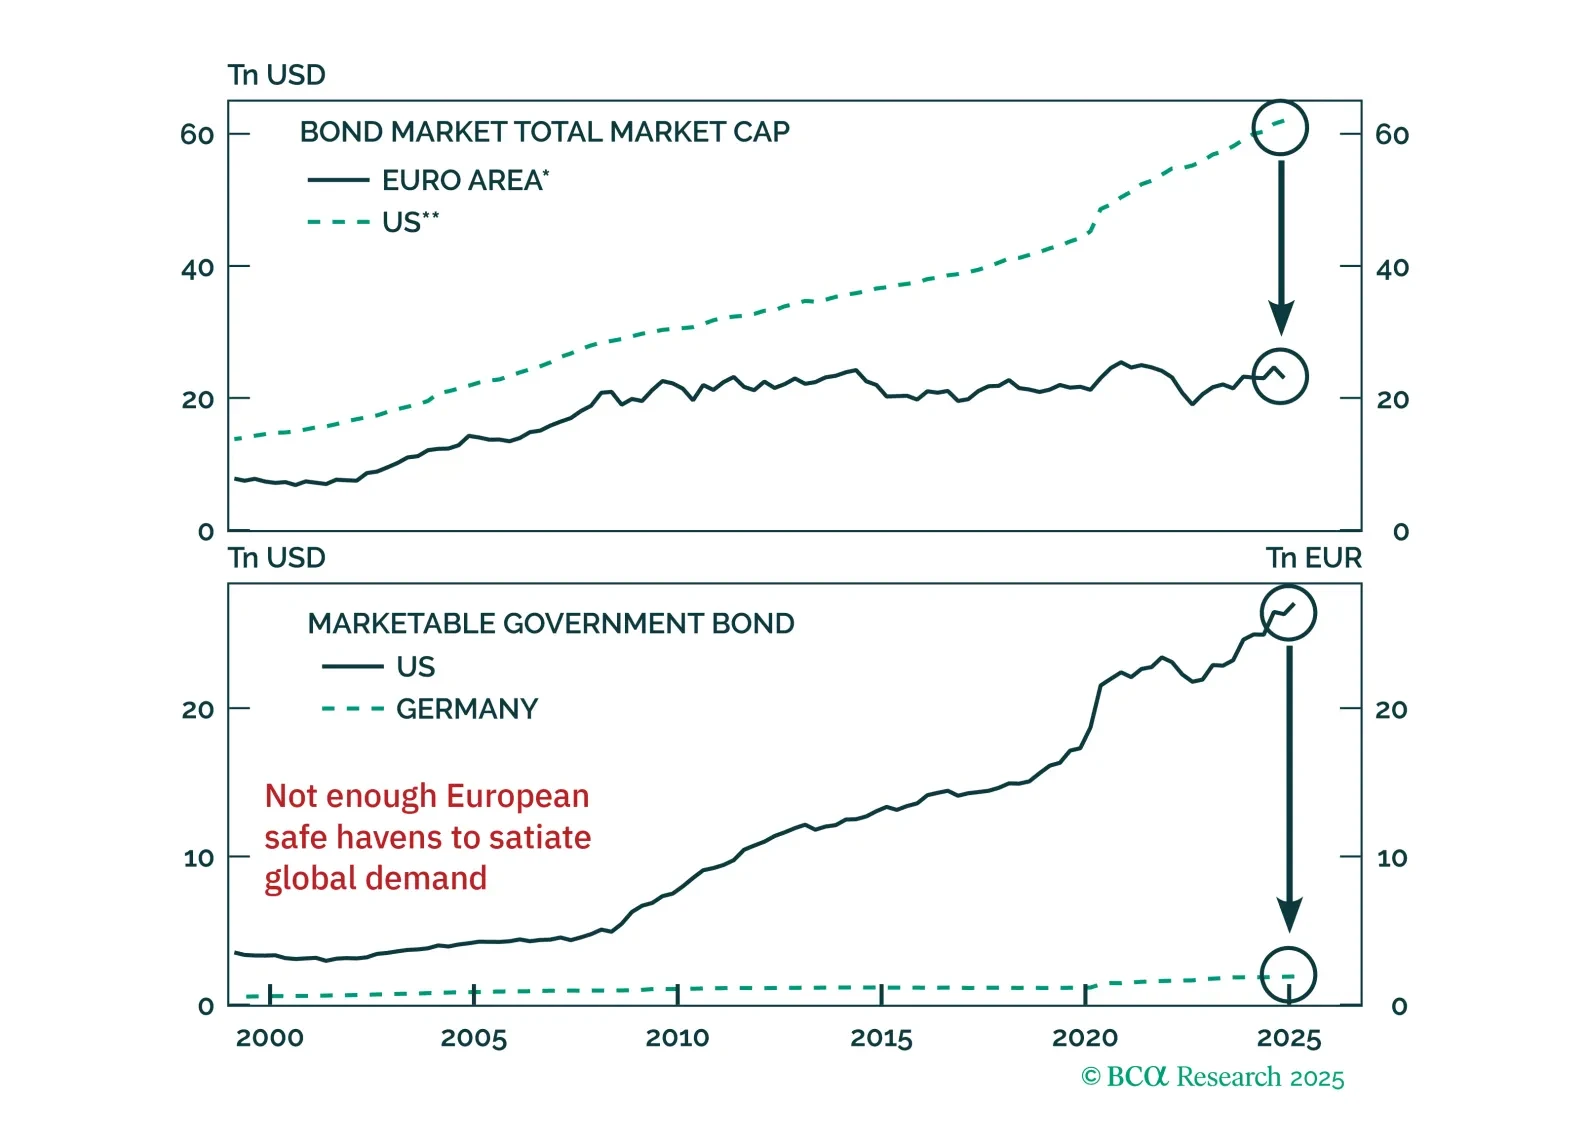
Are bunds the new Treasurys? The euro and German debt are gaining favor as safe havens, but markets may be overplaying the shift. Our latest report dissects what's durable, what's not, and how to trade the dislocation.

BCA’s House View recommends staying underweight stocks versus bonds, even in a stagflationary scenario. The US and global economies are likely to enter a recession this year unless tariffs are swiftly reversed or meaningful fiscal stimulus is enacted. The…

US Treasuries typically outperform both equities and global government bonds during downturns. Recent political shifts could lessen that outperformance this cycle, but we doubt it will disappear completely.
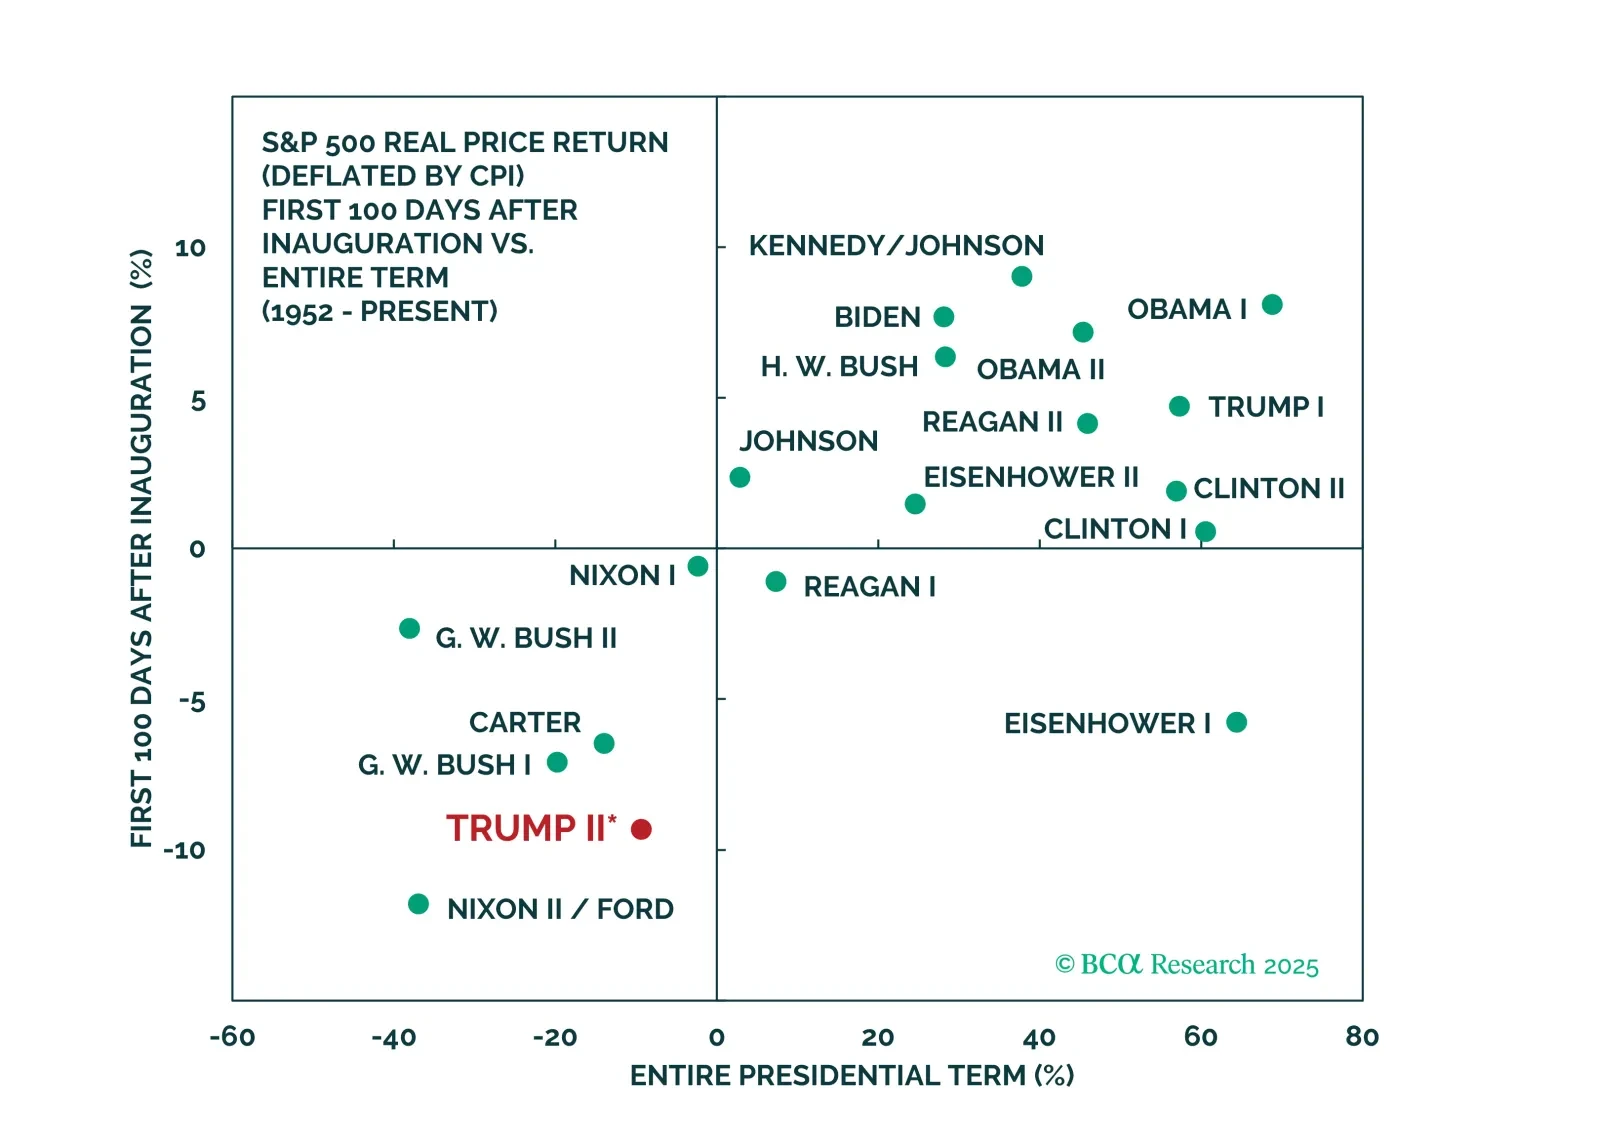
Informe especial

Do not play the bounce in US and global cyclical assets as Trump backpedals from the trade war. China will talk, but the pace will be slow and the outcome disappointing. Fiscal stimulus will surprise marginally in the EU, China, and even the US, but still may not rescue the business cycle. 
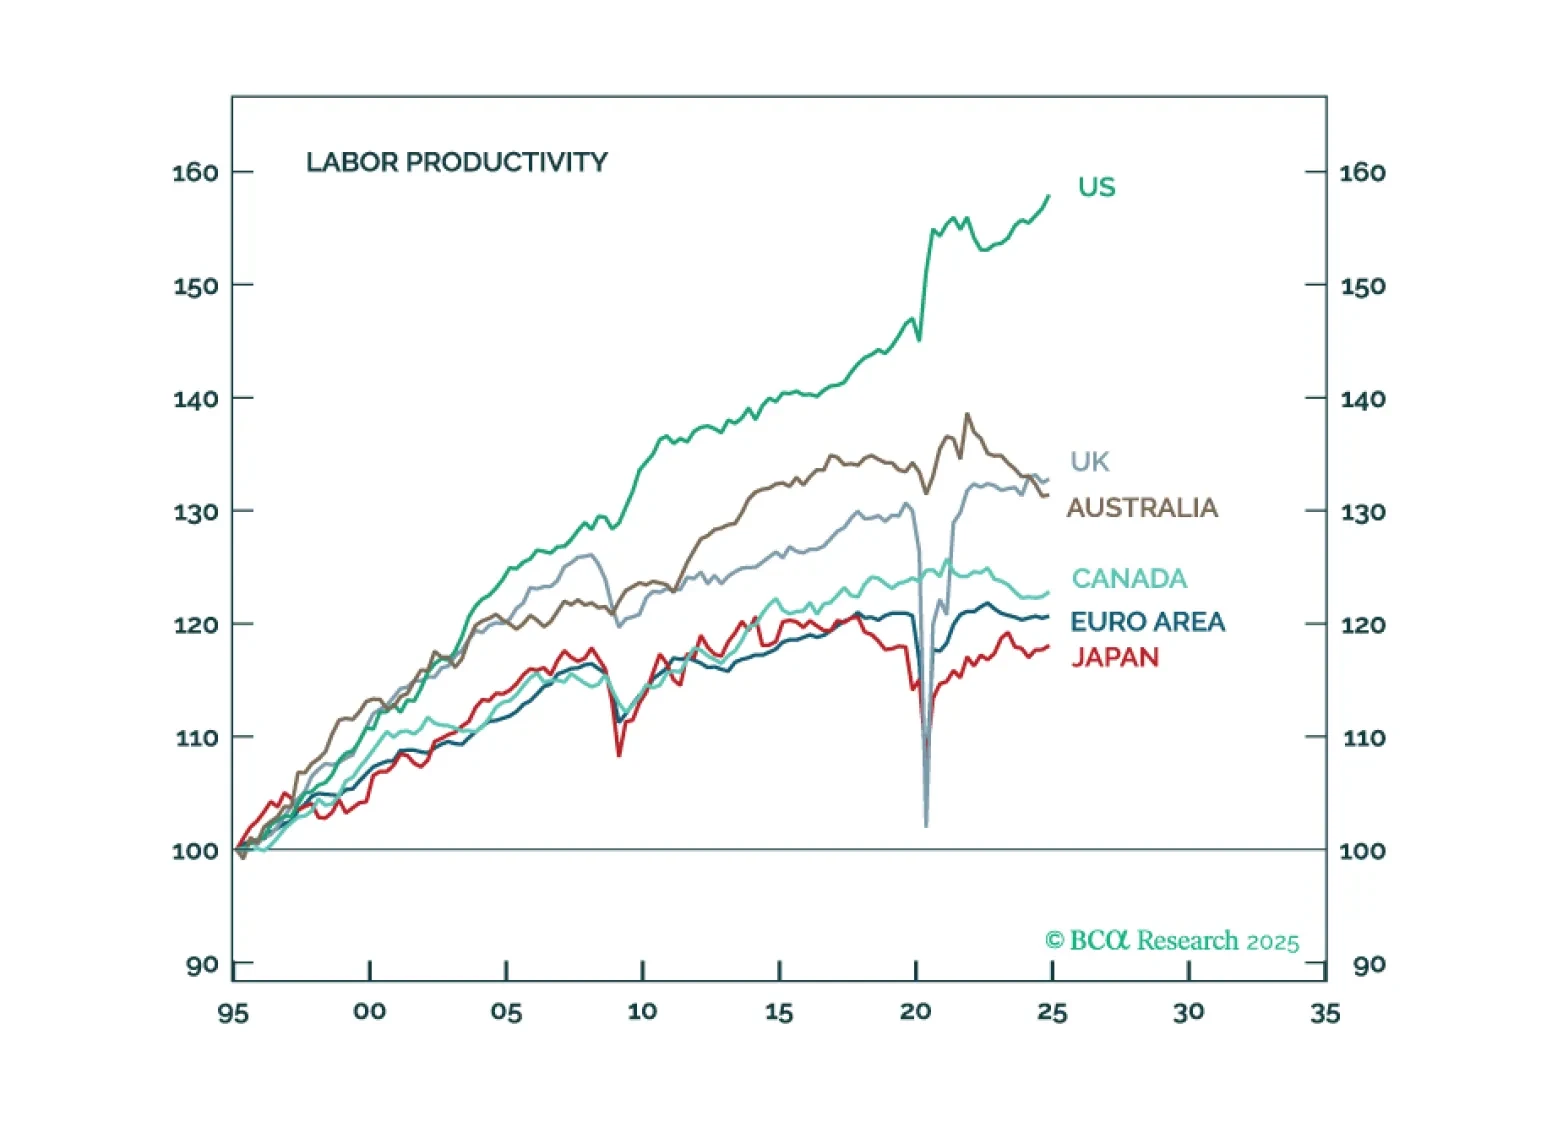
Although the sell-off in the US dollar and relative outperformance of non-US stocks will pause over the coming months as a global recession begins, the fading of US exceptionalism will still cause the dollar to weaken and US stocks to underperform over a multi-year horizon.