Conflicto en el Medio Oriente
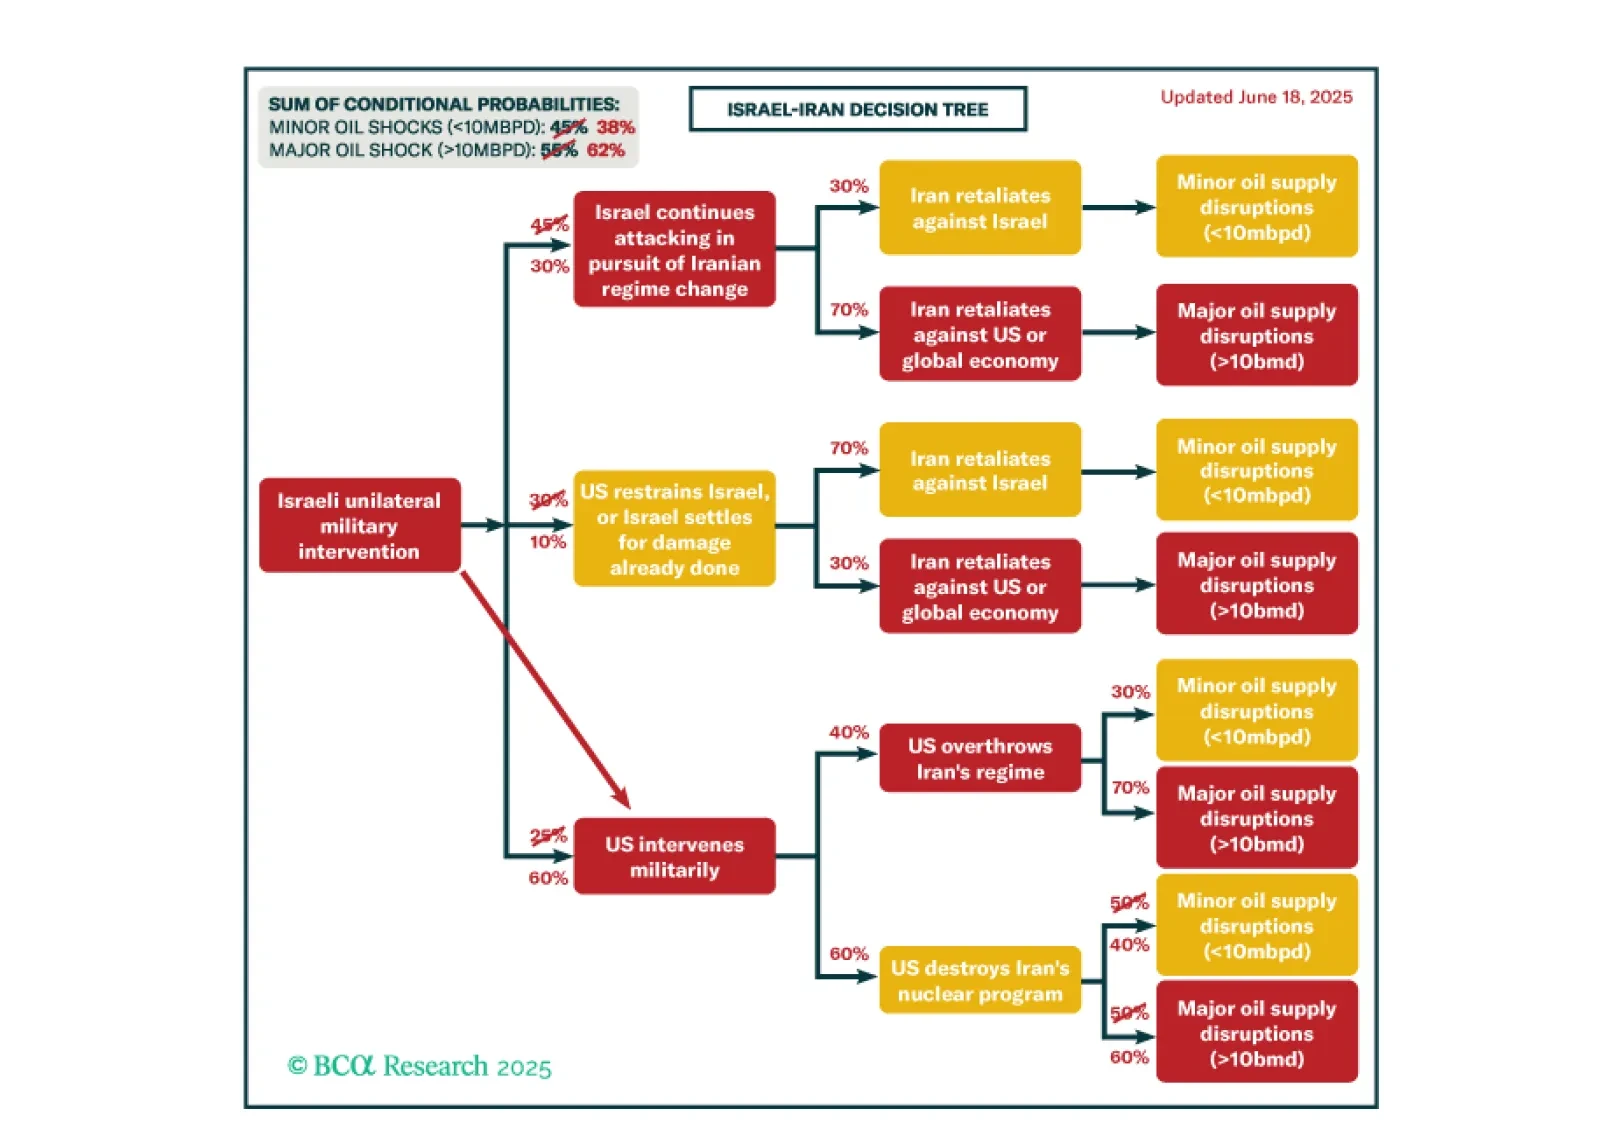
Incluso si Irán intenta revivir las conversaciones, Estados Unidos tiene una oportunidad irresistible para desmantelar su programa nuclear. Tácticamente, los inversionistas deberían favorecer los bonos del Tesoro sobre el S&P, los sectores defensivos sobre los cíclicos, las acciones de energía sobre los cíclicos y las acciones estadounidenses sobre las europeas a corto plazo.
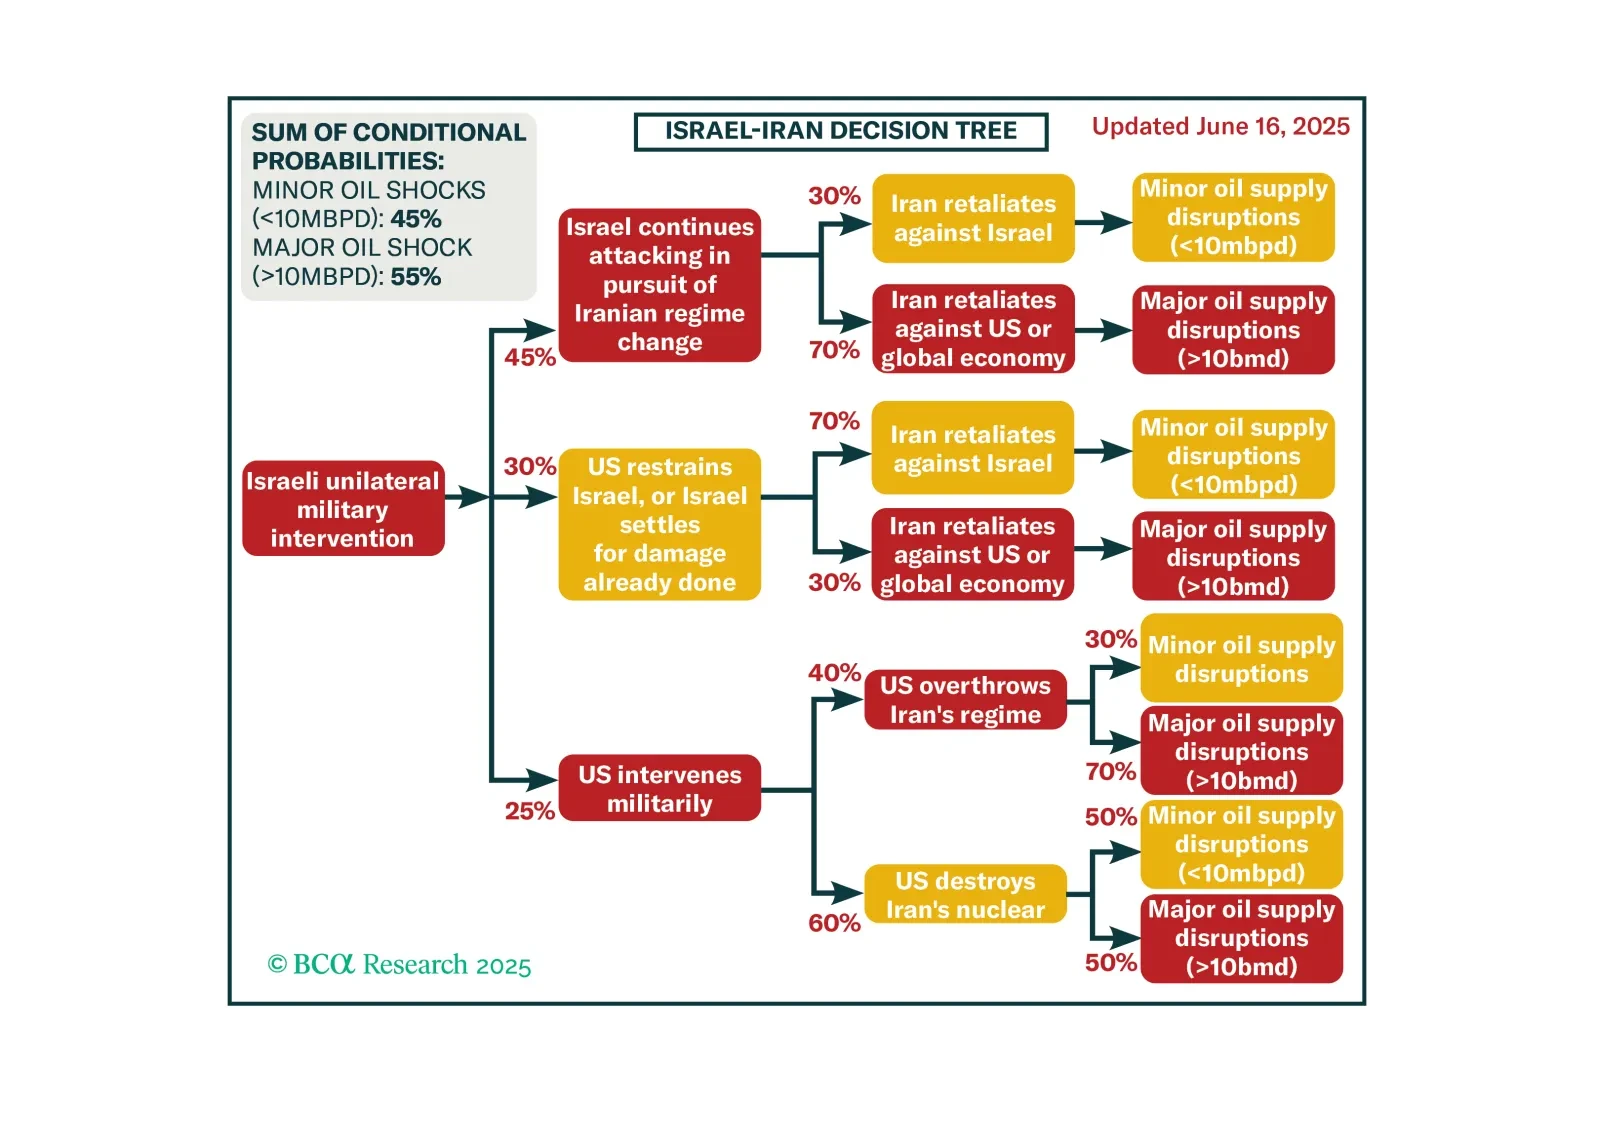
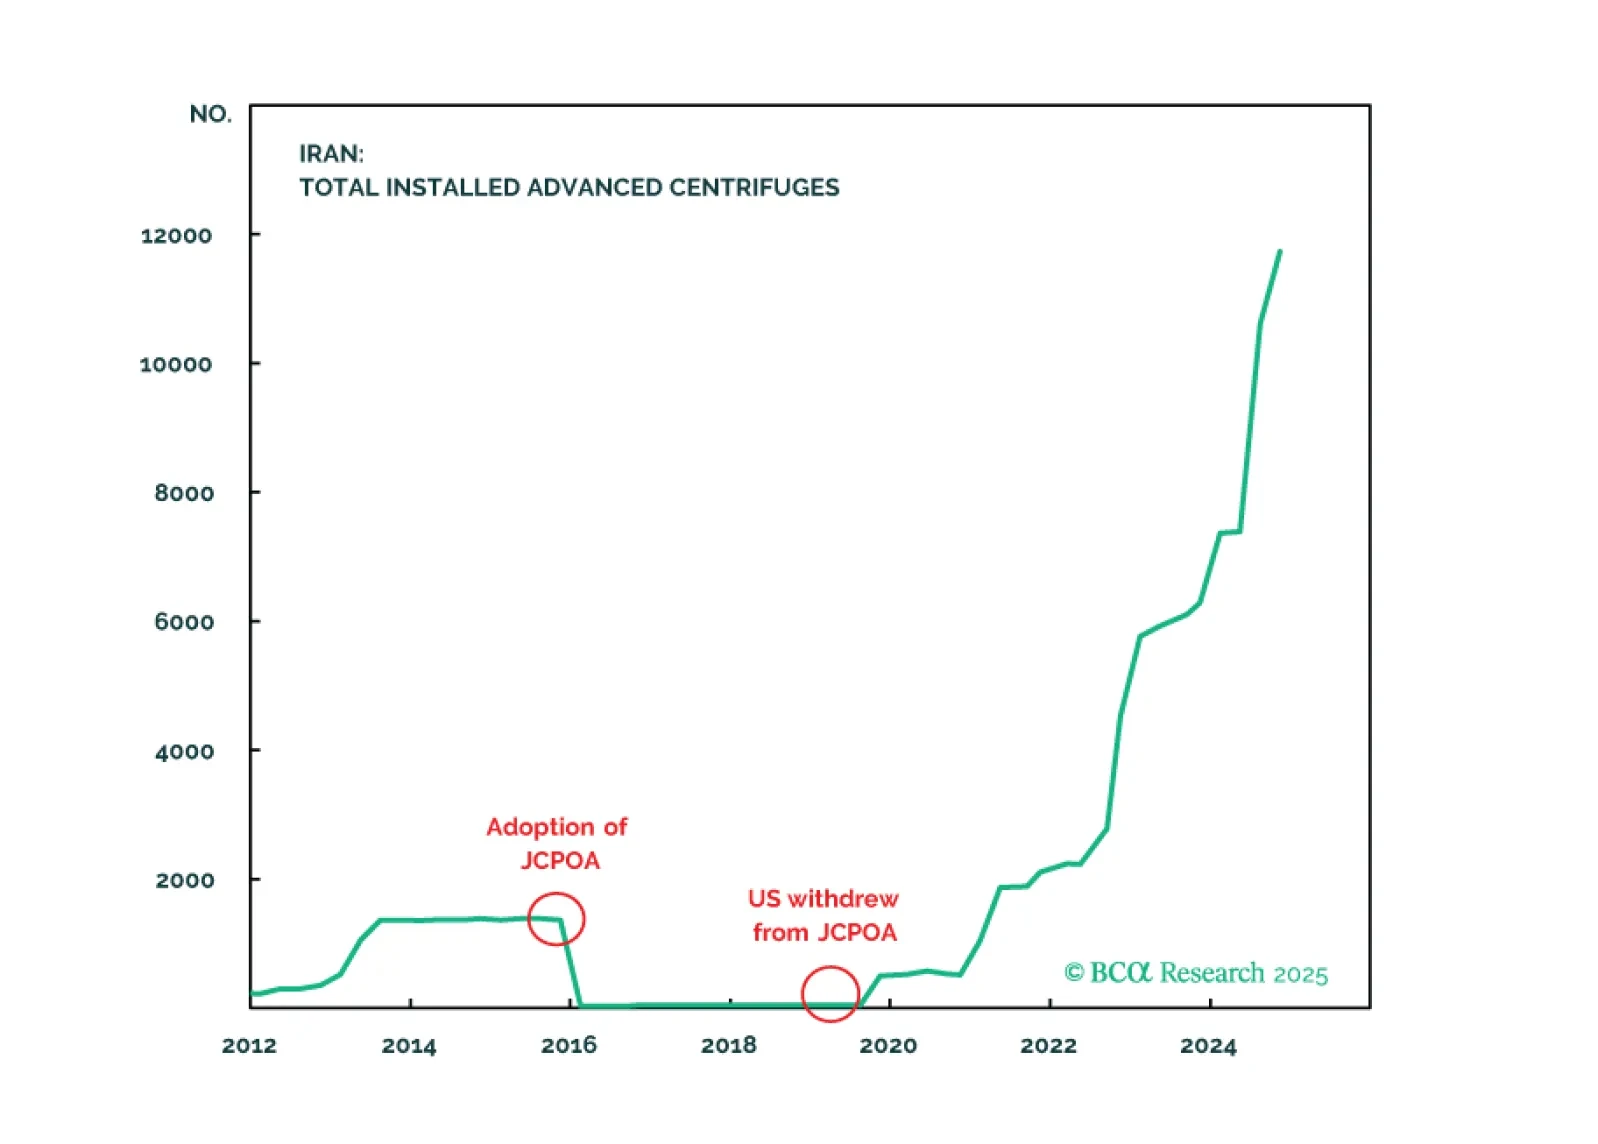
Los ataques de Israel a Irán continuarán hasta que Irán se vea obligado a atacar el suministro regional de petróleo para que Estados Unidos frene a Israel. Eso podría no funcionar. Los inversores deben prepararse para un impacto económico más amplio del conflicto.
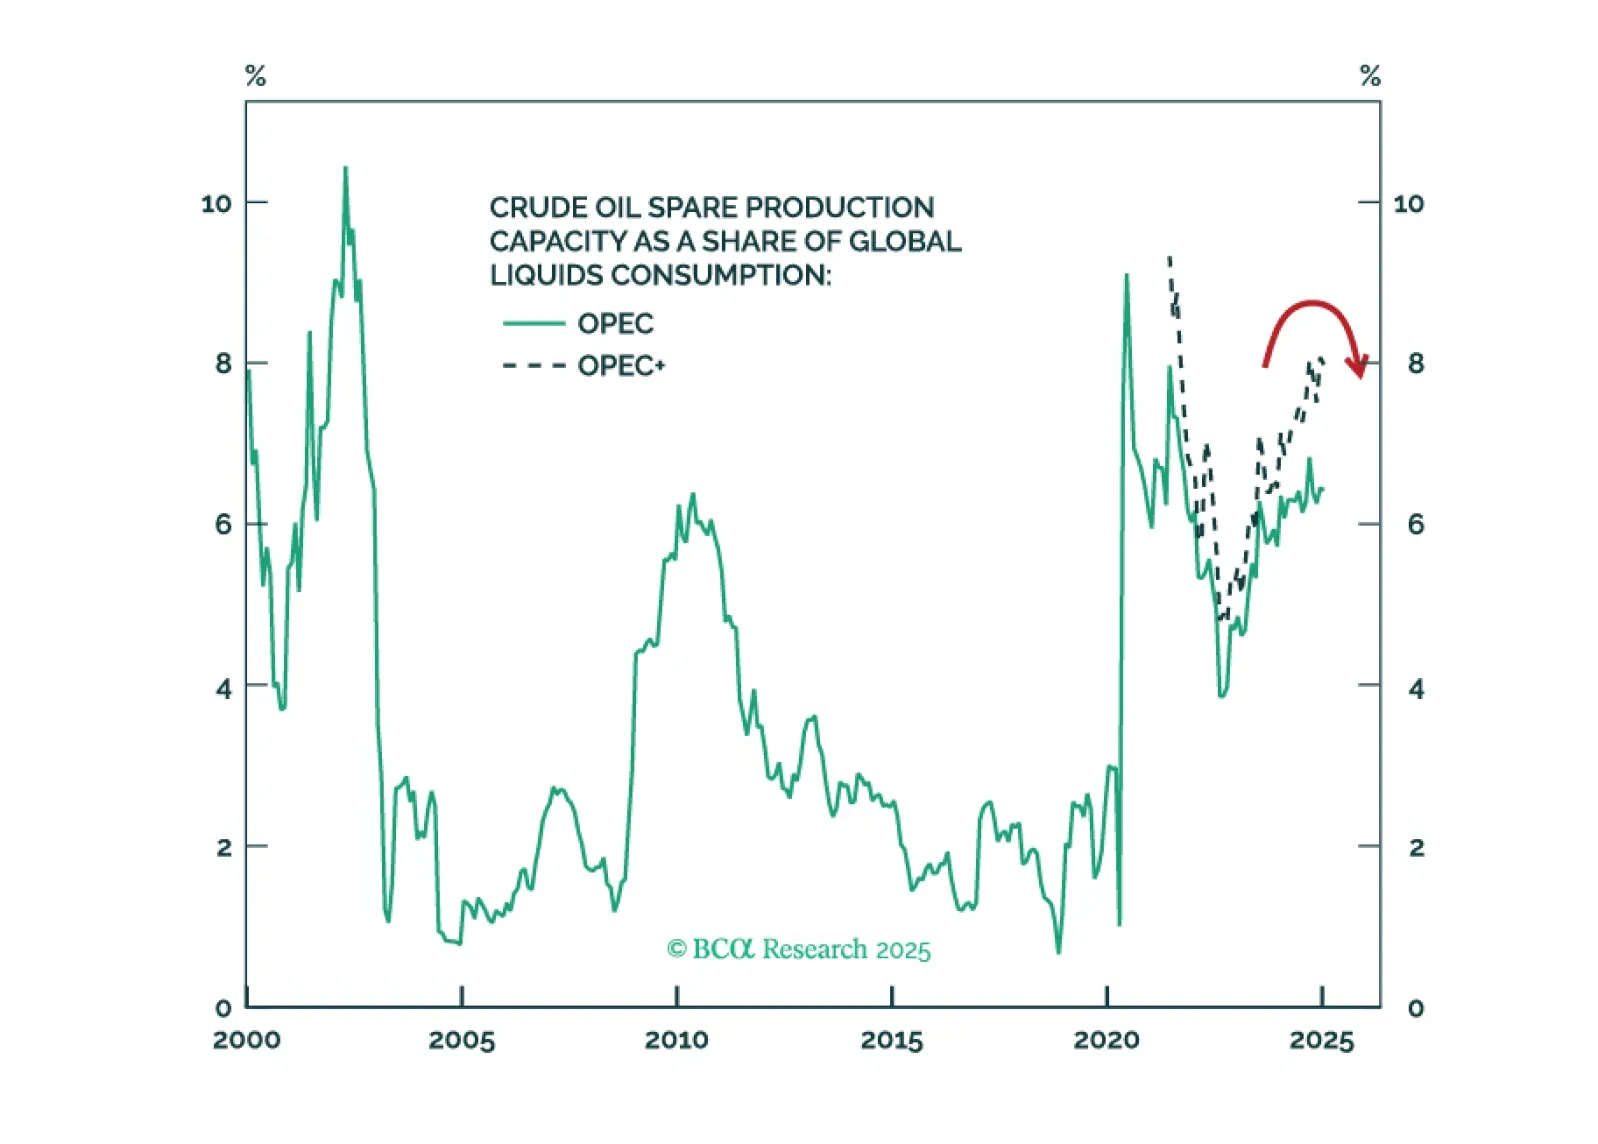
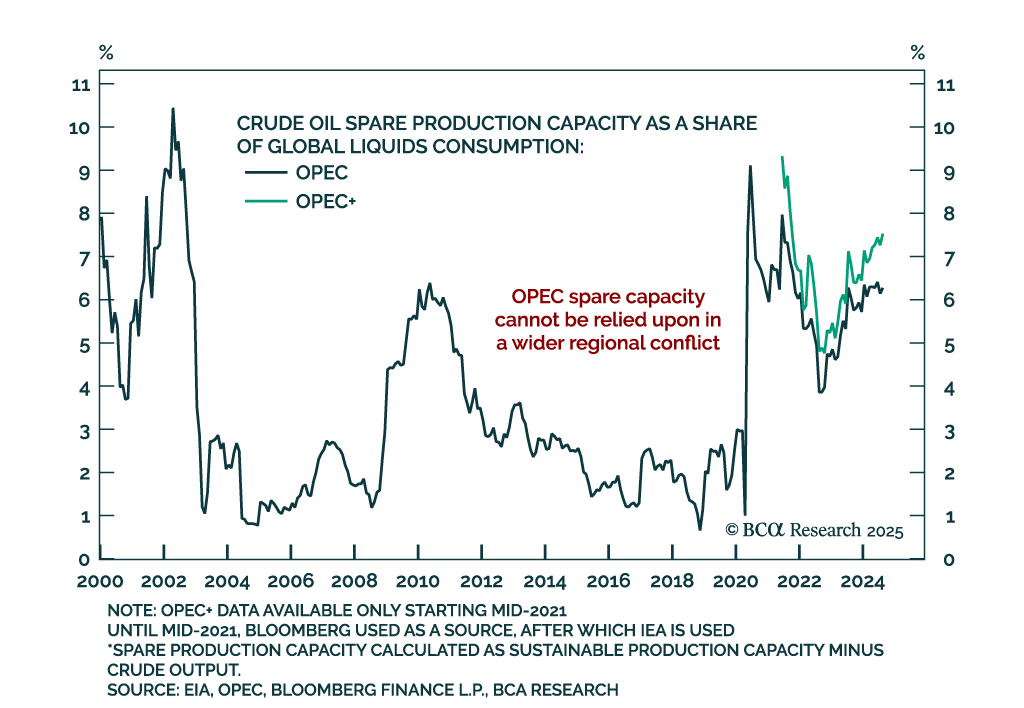
Investors should hold gold, build up some cash, tactically overweight US equities relative to global, and prepare for at least minor oil supply shocks – possibly major shocks – as the Israel-Iran war escalates.
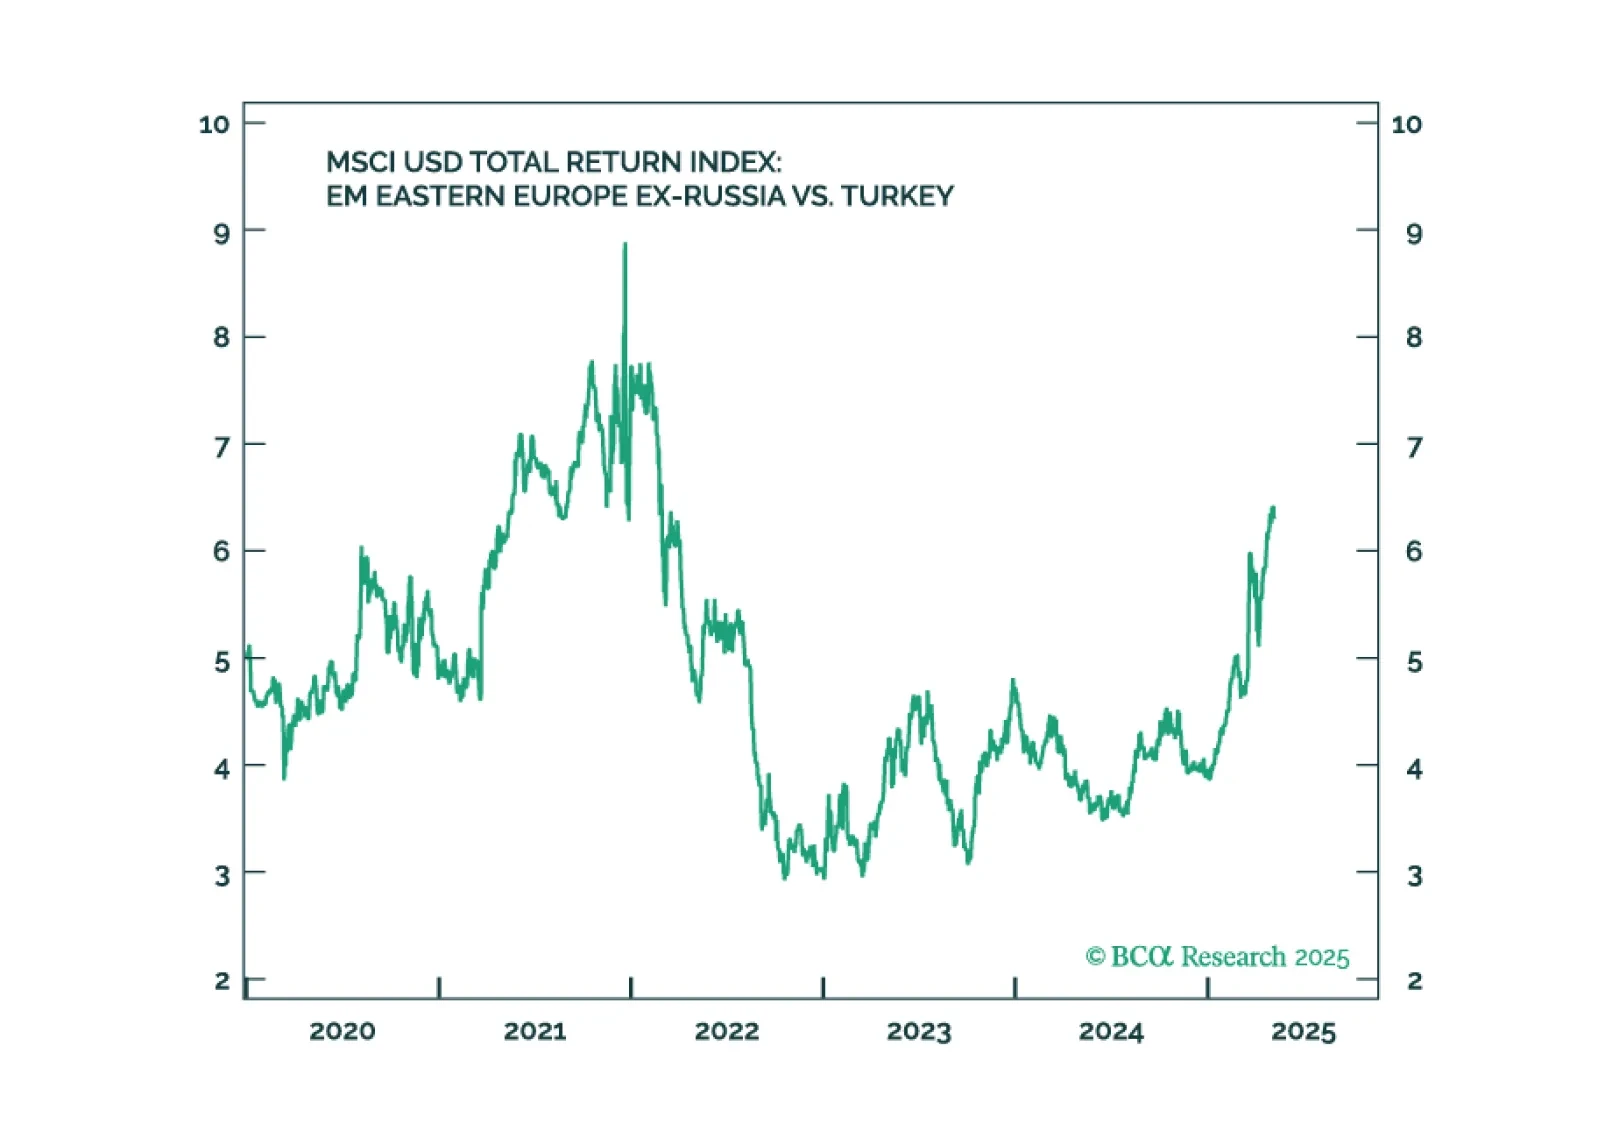
Erdogan's rule continues to decline. Social unrest will persist, governance will erode, and the macro backdrop will deteriorate further. We recommend underweighting Turkish assets.
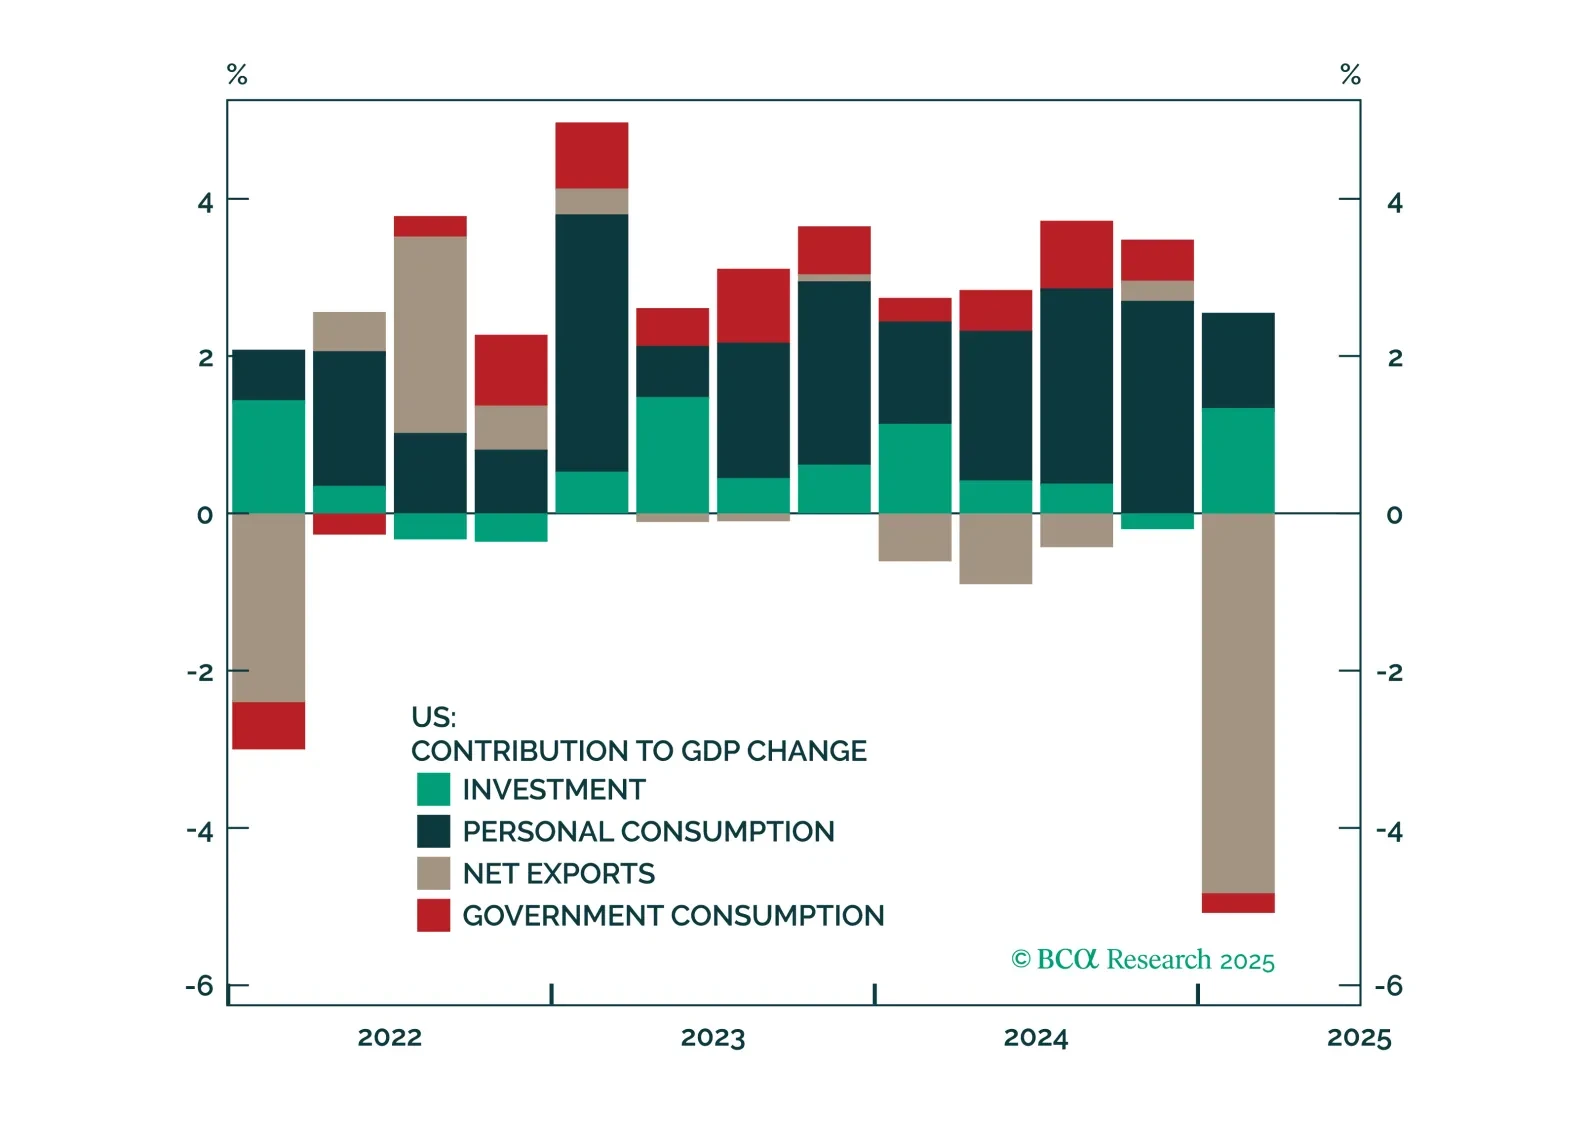
Negotiations on trade, Iran, and Ukraine will prove critical this month. Markets will remain volatile because positive data surprises enable the White House to press its hawkish tariff hikes, while negative surprises force the White House to backpedal.
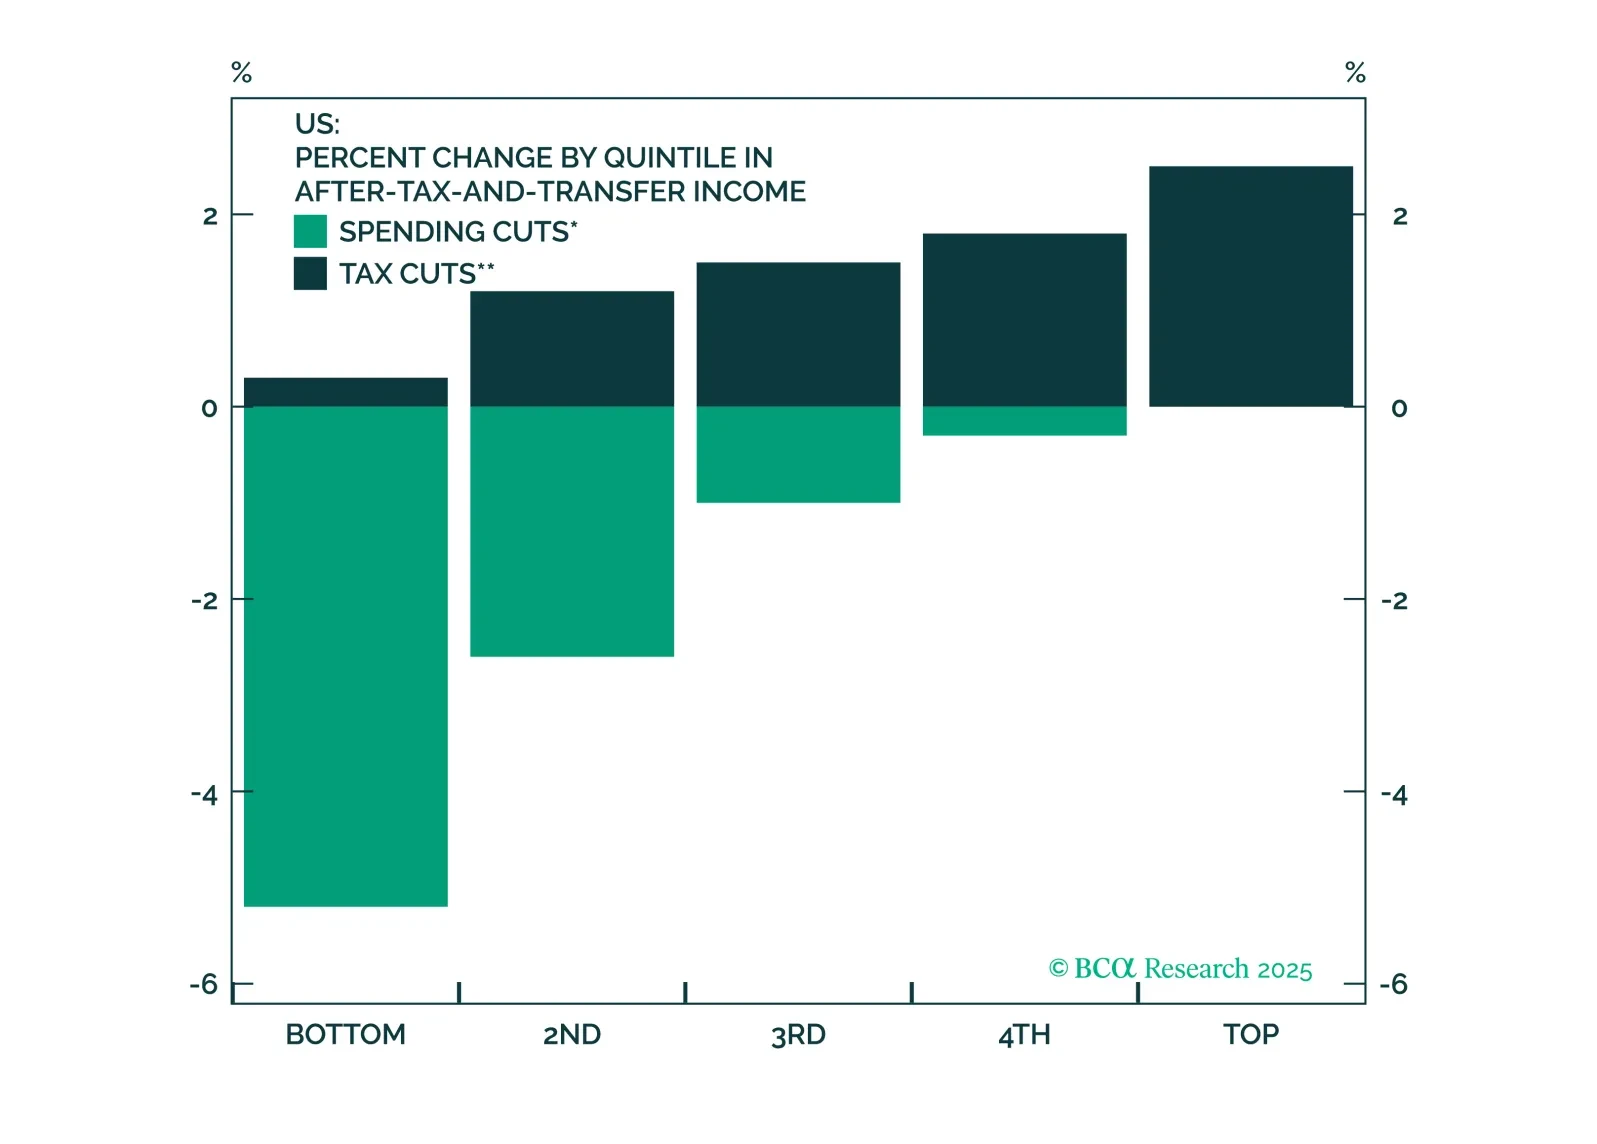
Stocks will continue to struggle in the second quarter as President Trump tries to implement tariffs. Tax cuts will only temporarily dispel growth fears, if at all. Middle Eastern instability will add oil price surprises to an environment that is looking fairly stagflationary.
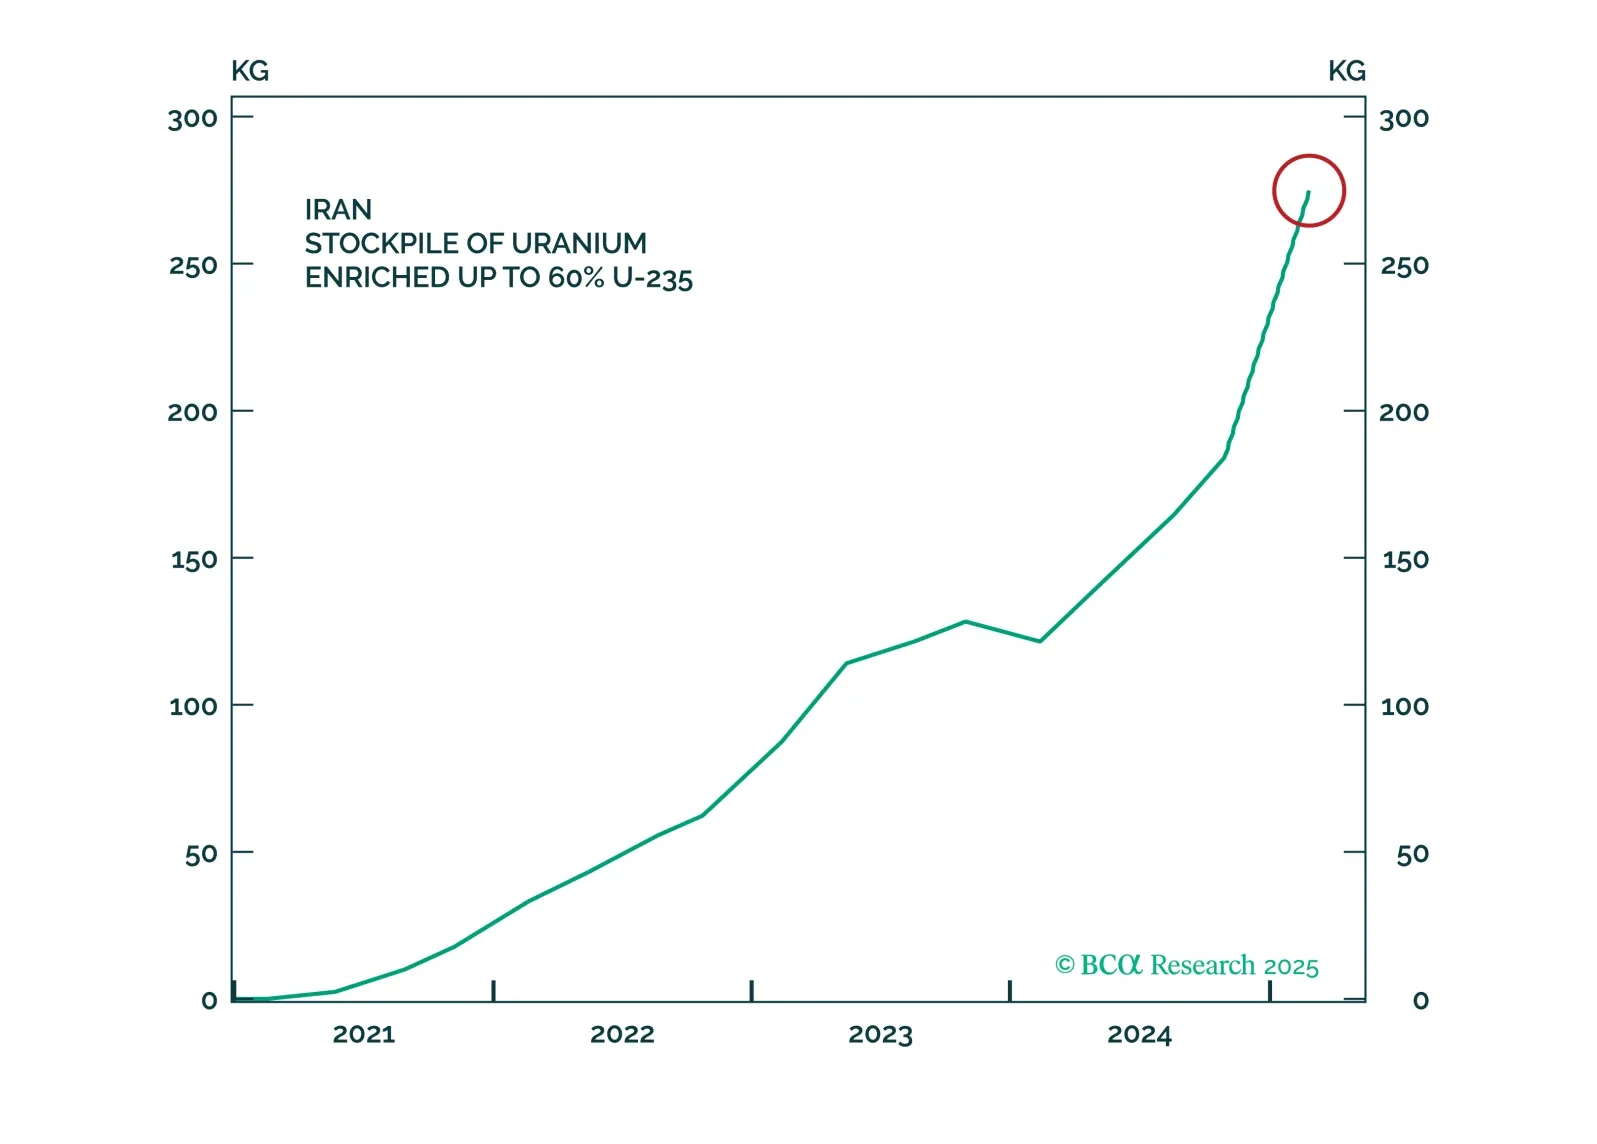
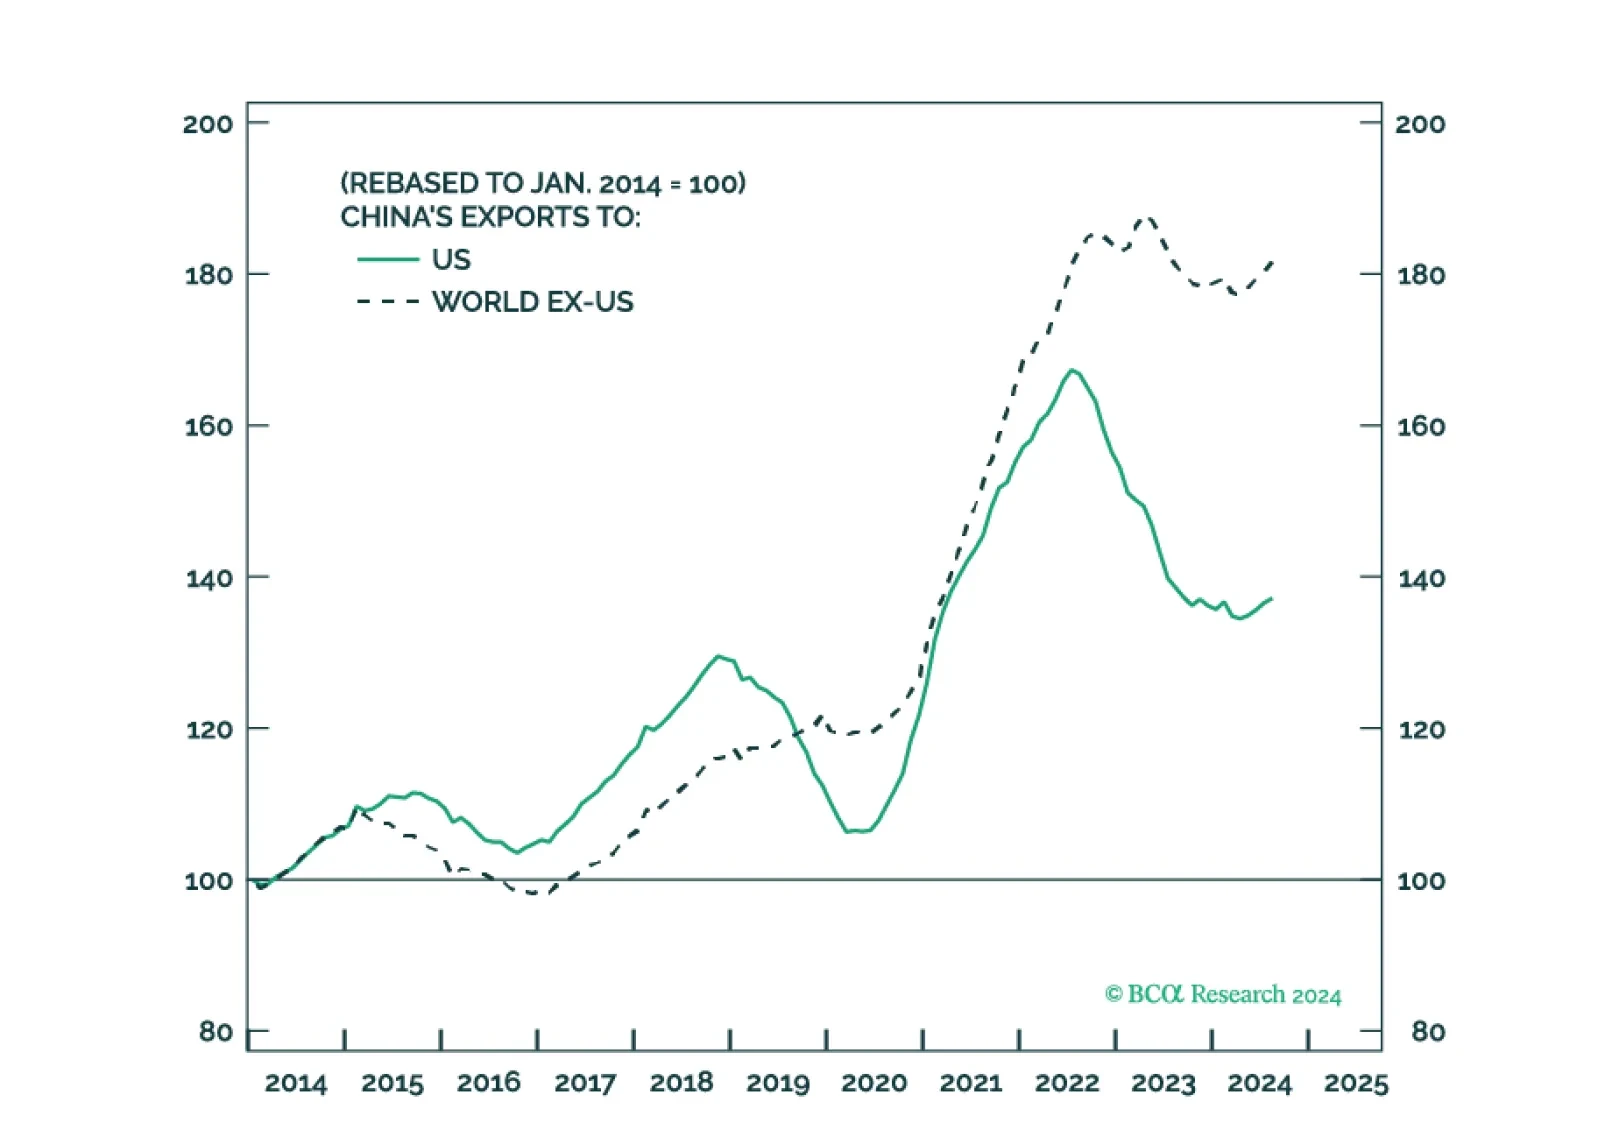
The tariffs on Canada and Mexico will come into effect as scheduled while the tariffs on China will be doubled. In the Middle East, Iranian response to any attack will threaten Middle Eastern oil supply. Meanwhile, Chinese fiscal support will surprise to the upside at the Two Sessions. But Trump's China policy will cause volatility. Now that the stock market is cracking, reinitiate defensive trades, such as long treasuries versus US stocks and long global defensives versus cyclicals.
Every year we highlight five low-odds scenarios that would have a major impact on global financial markets if they happened. This year we contemplate a total reversal of Chinese policy, a US-Iran nuclear deal, a breakdown of NATO, US military action across the Americas, and an internationally coordinated FX intervention.
- Congress will pass tax cuts by end of 2025 producing a fiscal thrust of about 0.9% of GDP in 2026.
- Trump will count on that stimulus as a basis for slapping tariffs on leading trade partners.
- China will retaliate against Trump and stimulate its domestic economy, while pursuing stronger trade ties with other countries. Europe will also retaliate.
- Geopolitical risk will shift from Ukraine-Russia to Israel-Iran, where the conflict will continue to escalate until a crisis point is reached within 2025.