China Stimulus
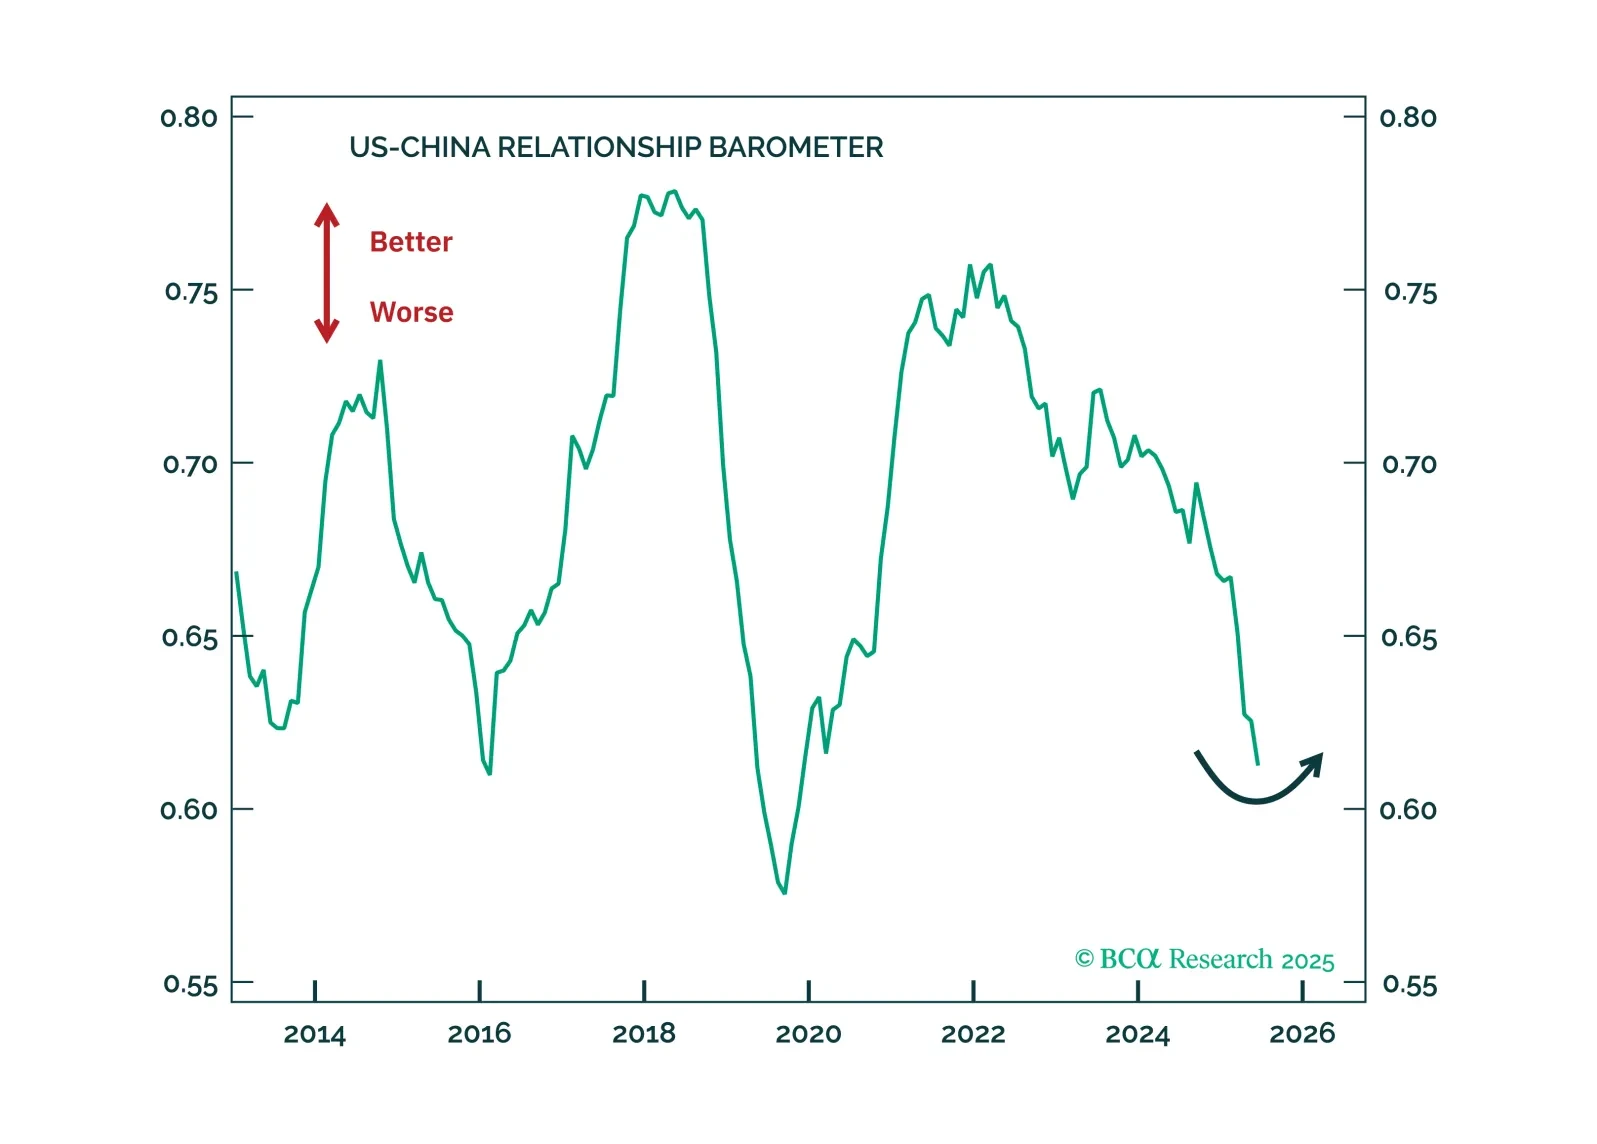
La cumbre Trump-Xi continuó la tregua comercial y creó tentativamente un marco para contener las tensiones sobre 2026. No es un acuerdo comercial, pero es lo suficientemente bueno para los mercados financieros globales, especialmente los activos chinos.
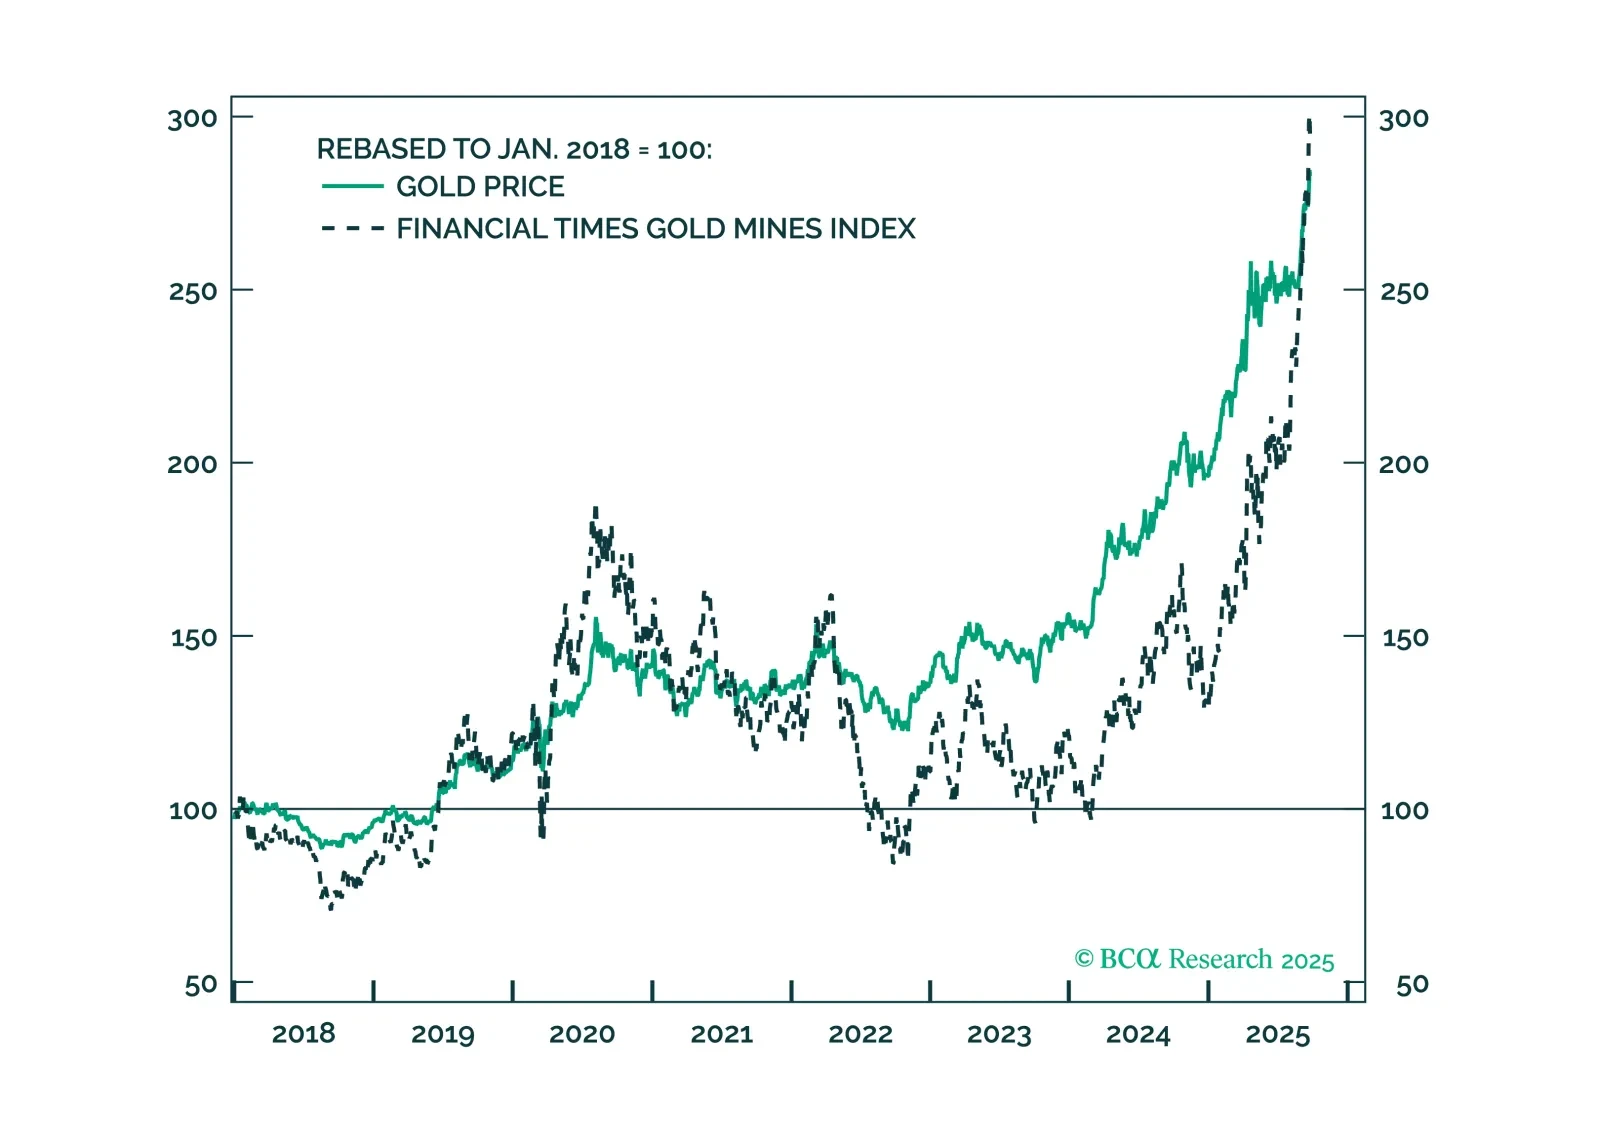
El aumento de los riesgos entre Rusia y la OTAN, las operaciones tácticas con petróleo/oro, sanciones más estrictas a Rusia (quizás también a China), el estímulo de China con un objetivo de crecimiento de ~5% y los controles en EE. UU. sobre las ambiciones de Trump definirán el cuarto trimestre.
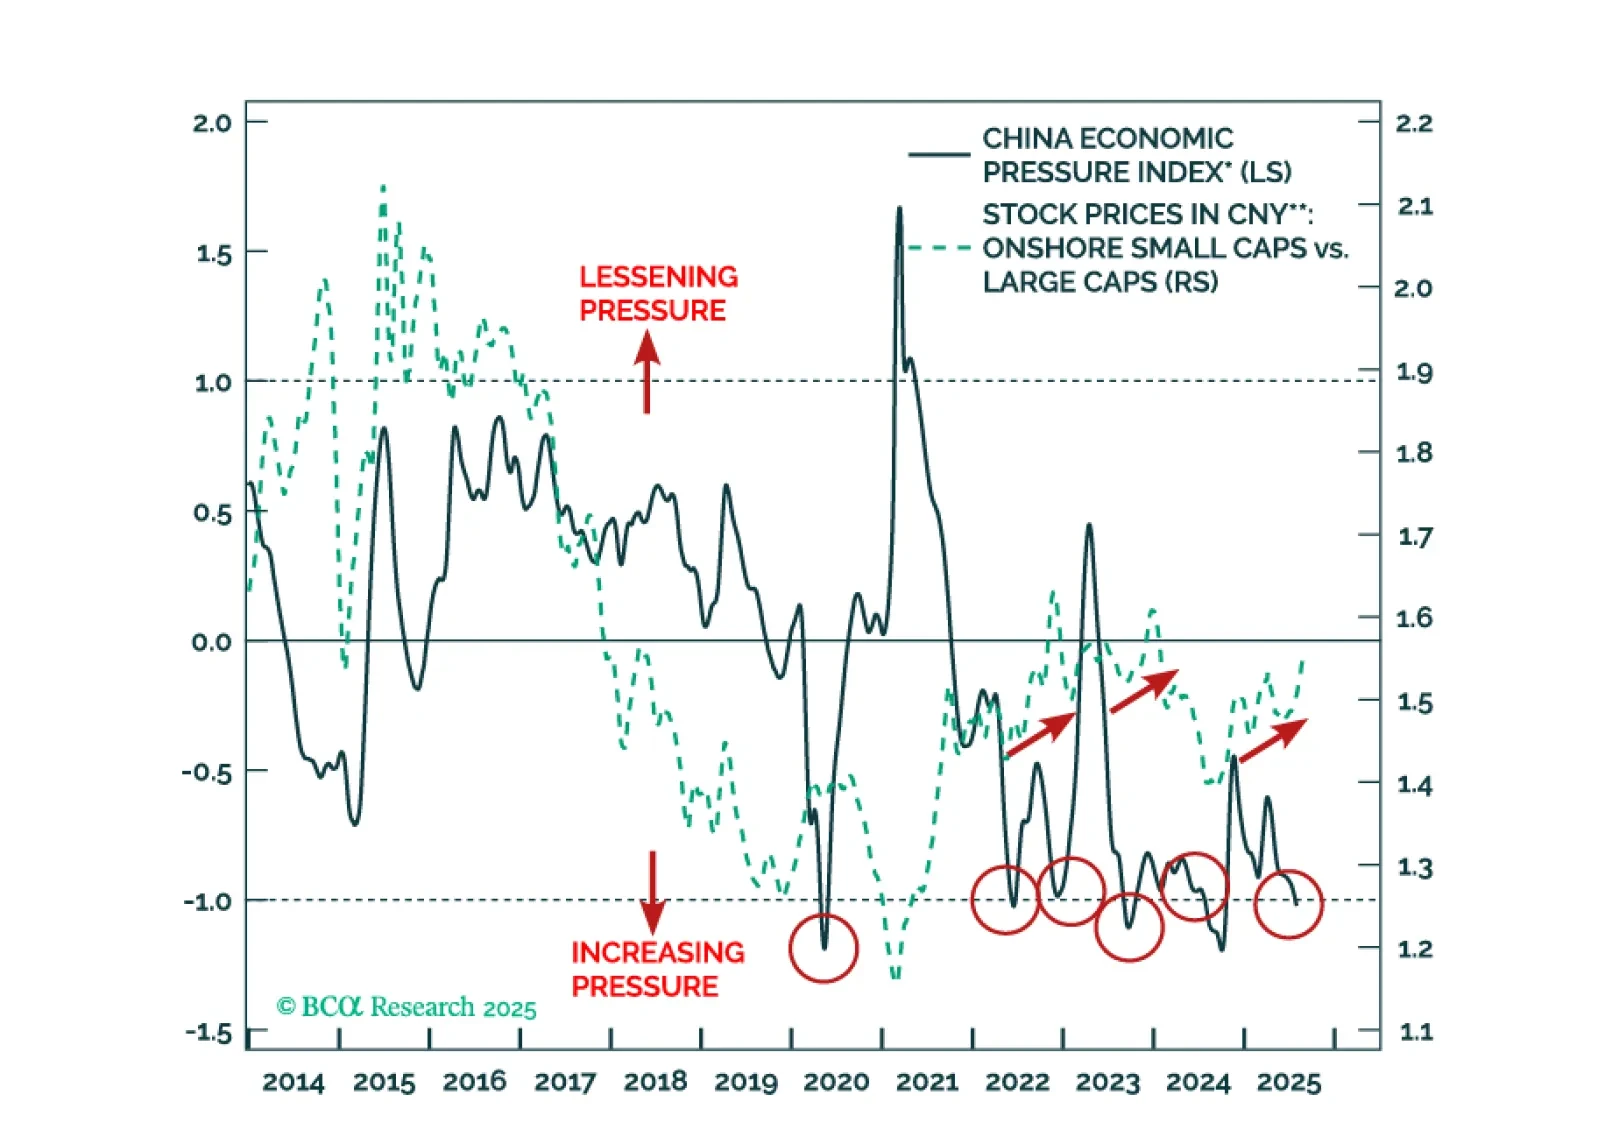
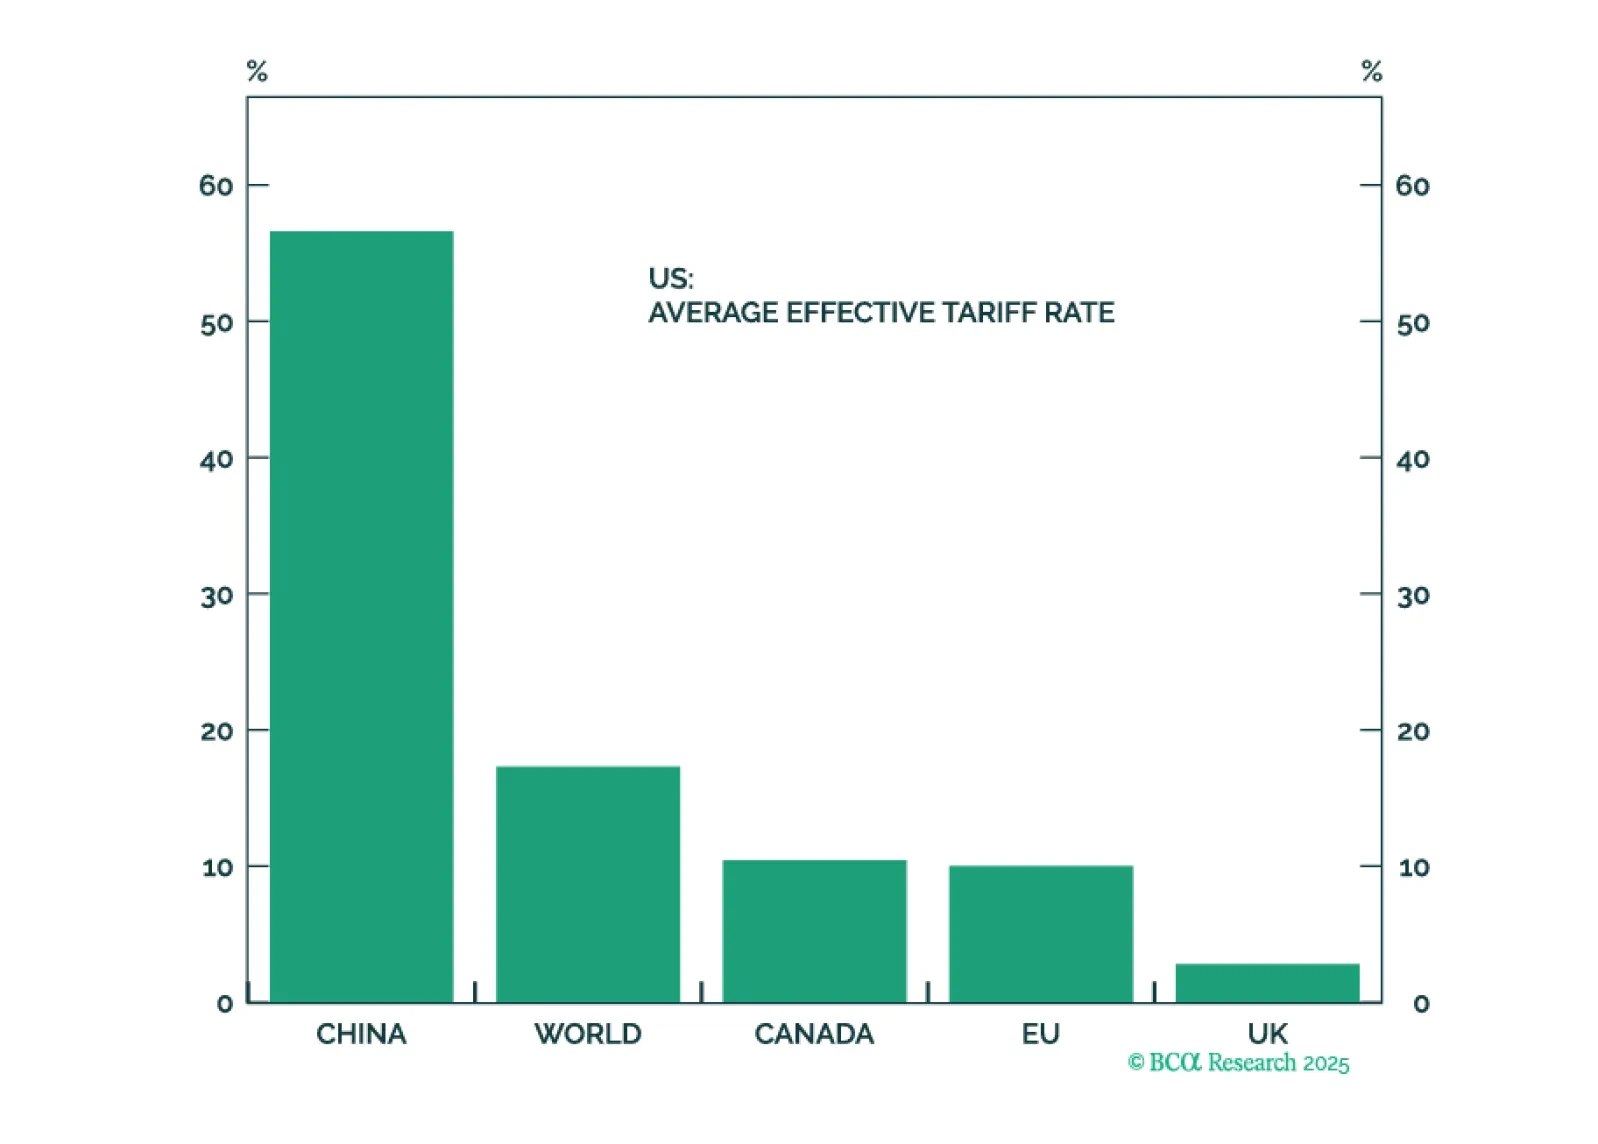
Los riesgos geopolíticos agudos, como un impacto masivo en el petróleo, pueden estar disminuyendo. Pero el riesgo geopolítico estructural sigue siendo alto y podría alterar un mercado despreocupado. Los riesgos económicos cíclicos están subestimados mientras EE. UU. se desacelera y China continúa tambaleándose. Los inversores deberían asegurar algunas ganancias en previsión de la implementación de aranceles y un descenso en los datos económicos sólidos.
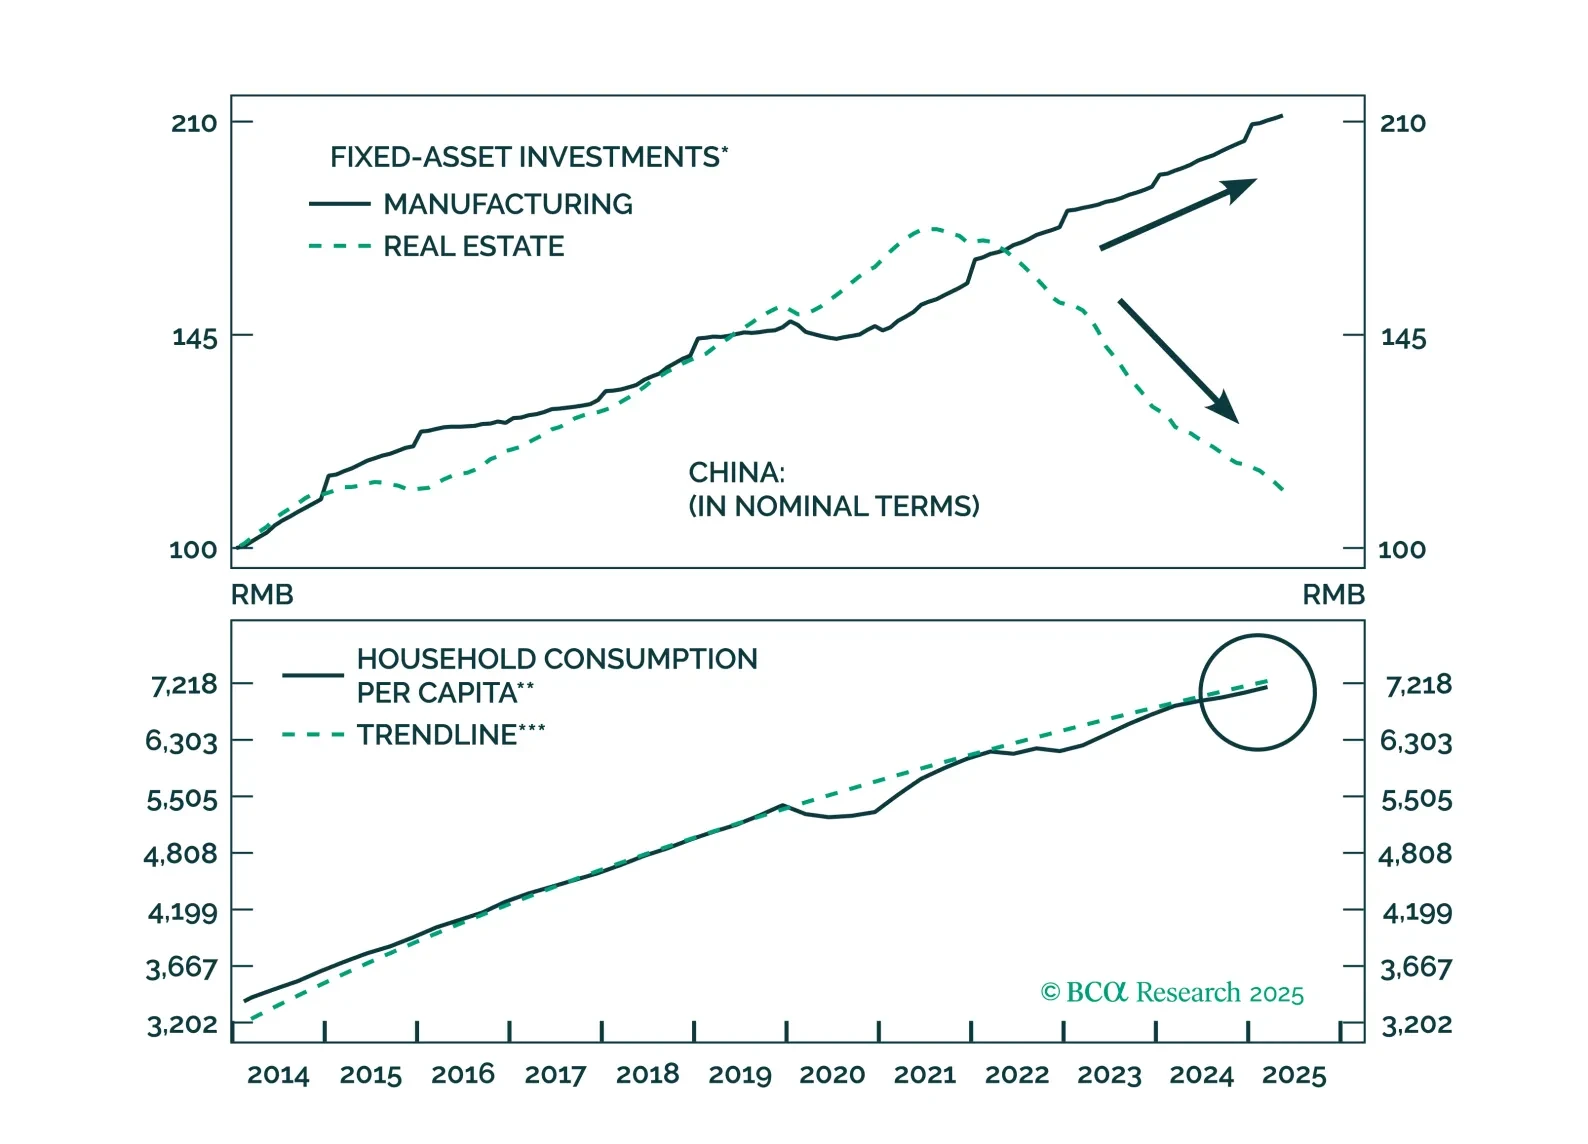
This report analyzes China’s persistent deflation, which is rooted in supply-side forces. Consumption support will be slow and incremental, keeping deflationary pressures elevated for the next 6–12 months.
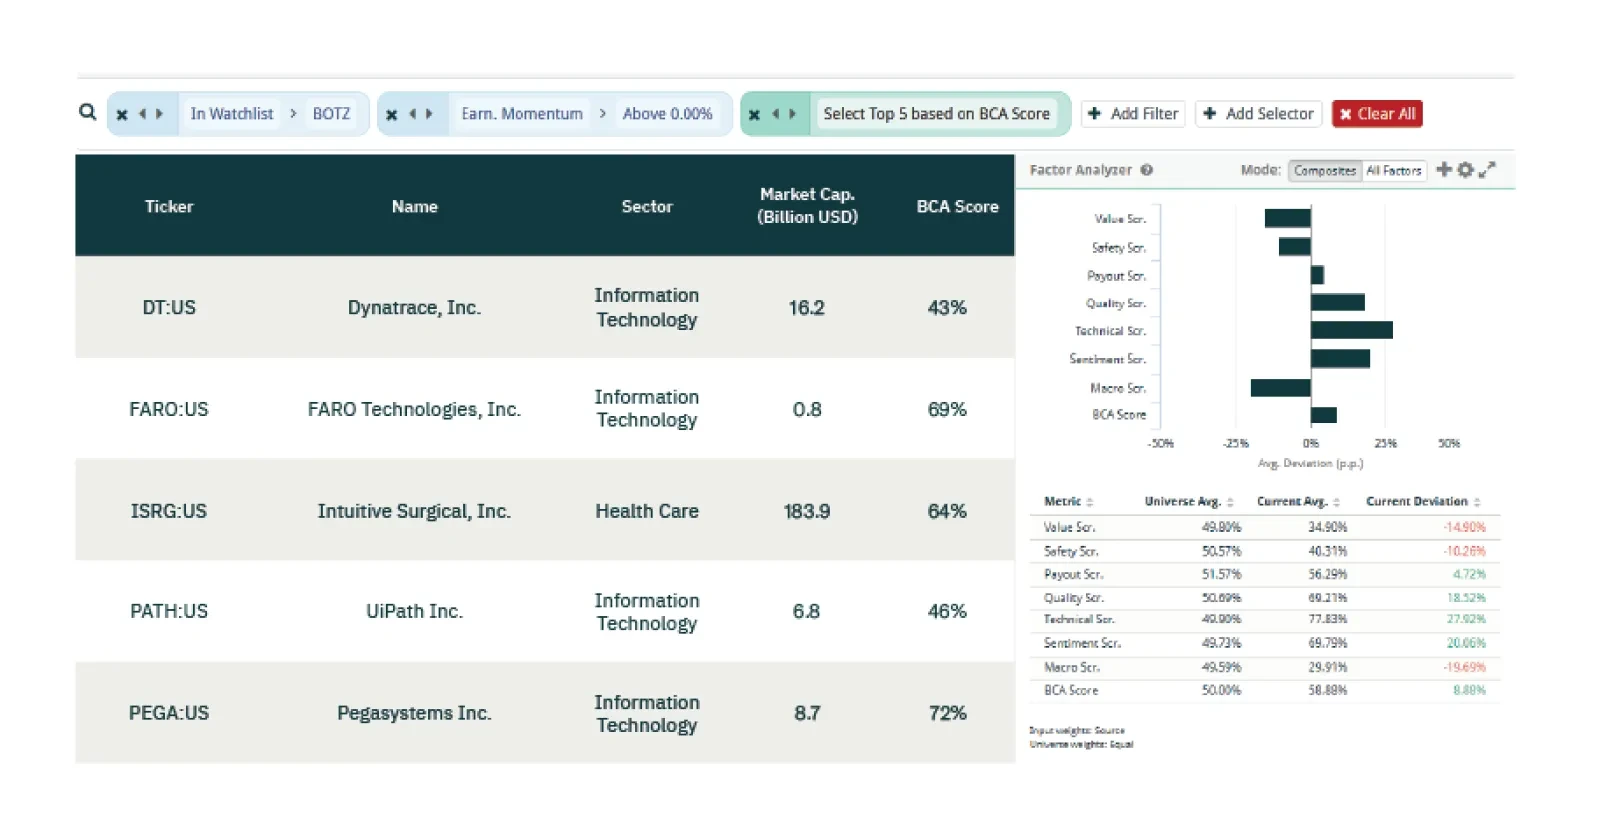
This week our three screeners explore equity trades in Robotics, European Quality and Technical, and Hong Kong.
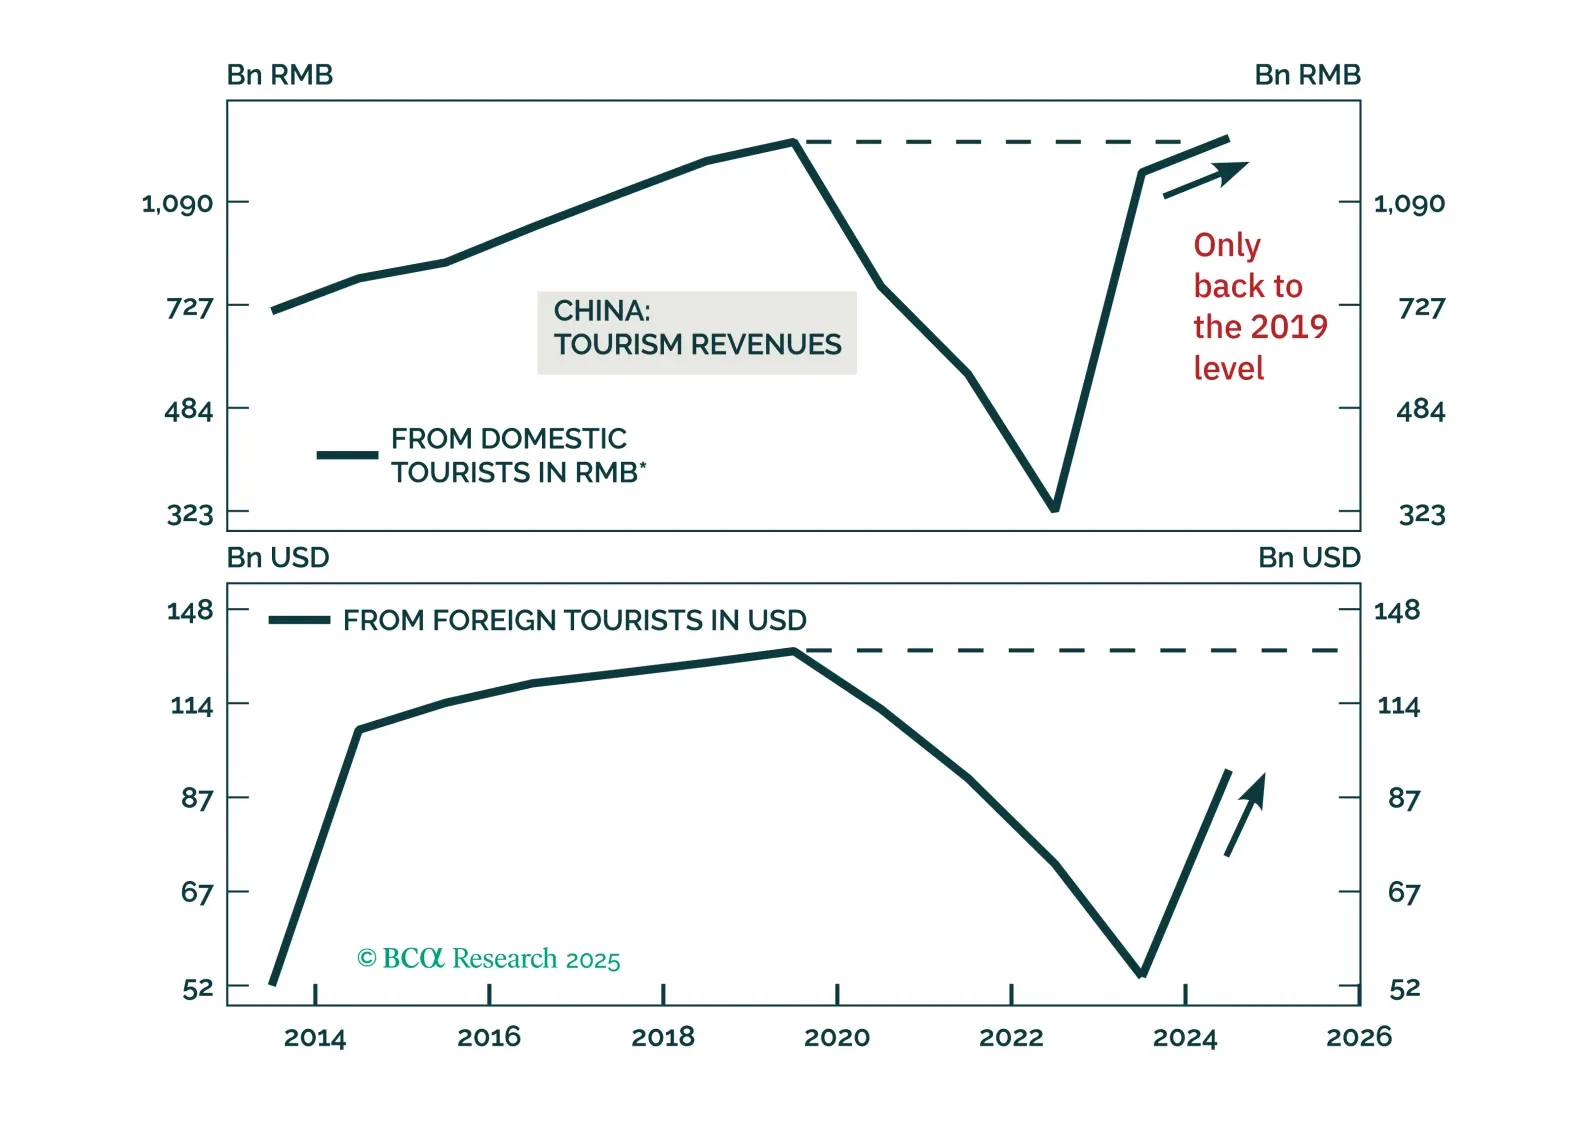
Chinese tourism will continue growing, but investors should be mindful not to overpay for Chinese tourism stocks by extrapolating their past double-digit revenue growth into the future.
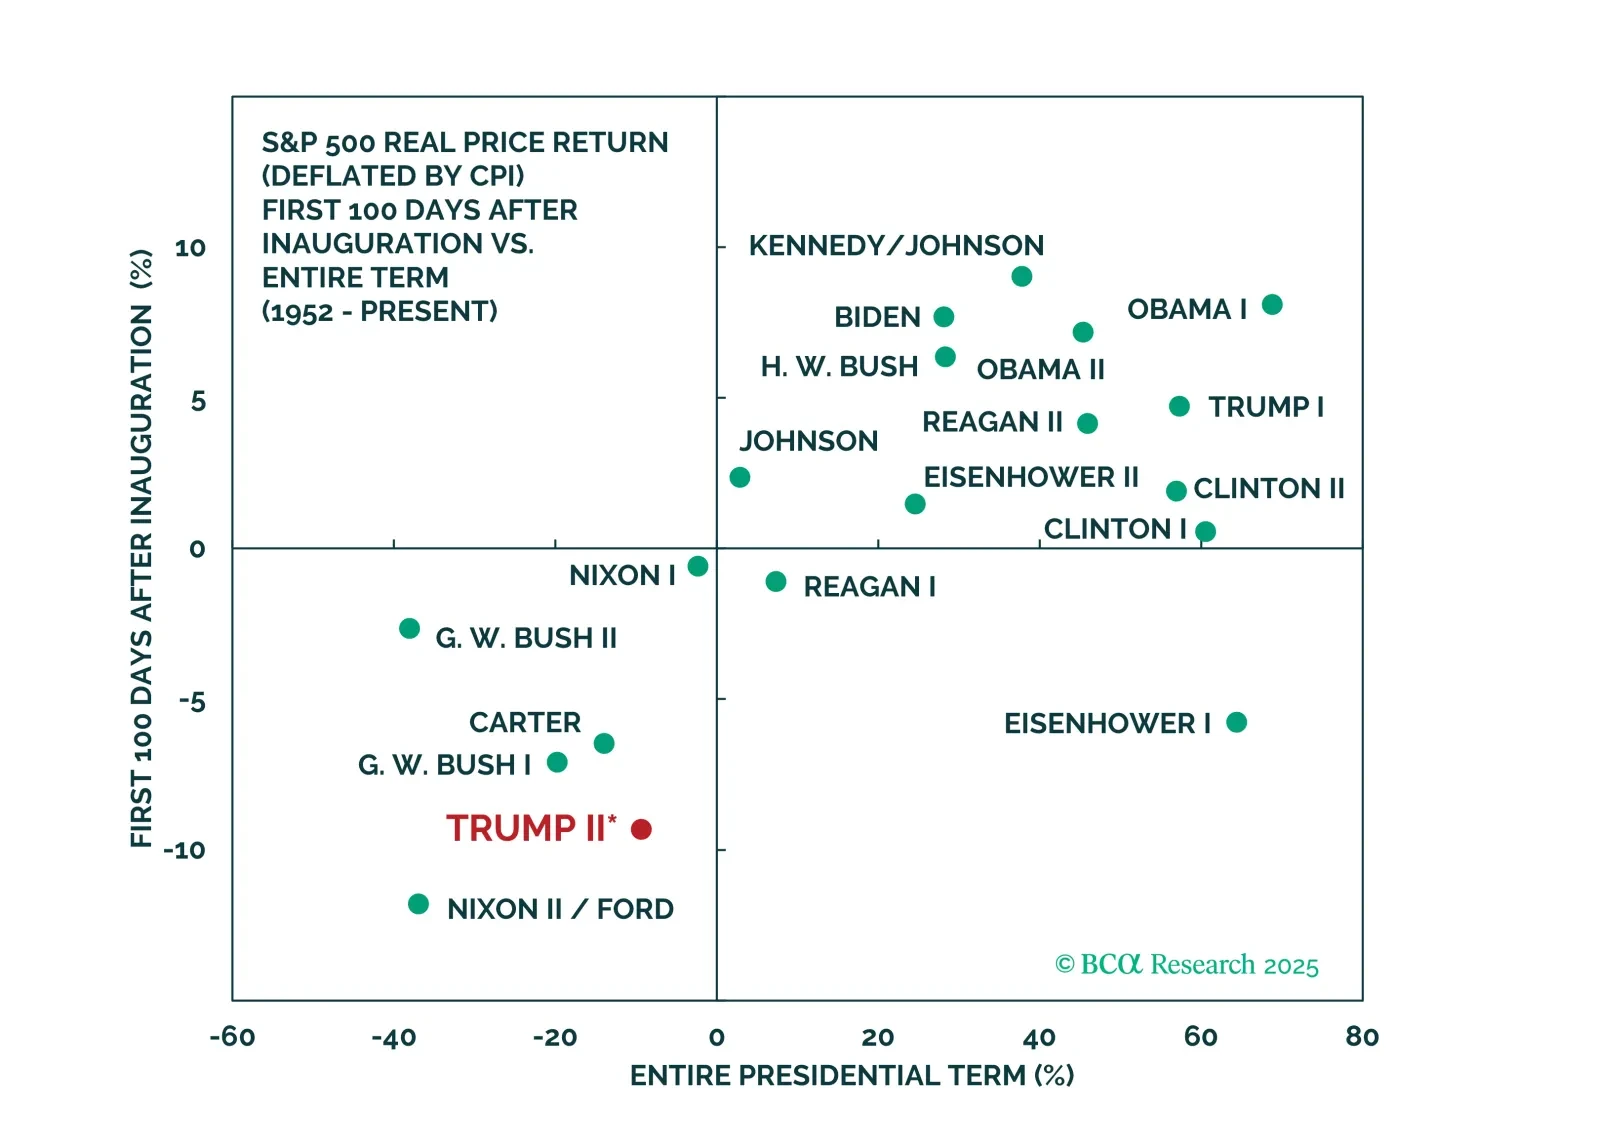
Do not play the bounce in US and global cyclical assets as Trump backpedals from the trade war. China will talk, but the pace will be slow and the outcome disappointing. Fiscal stimulus will surprise marginally in the EU, China, and even the US, but still may not rescue the business cycle.
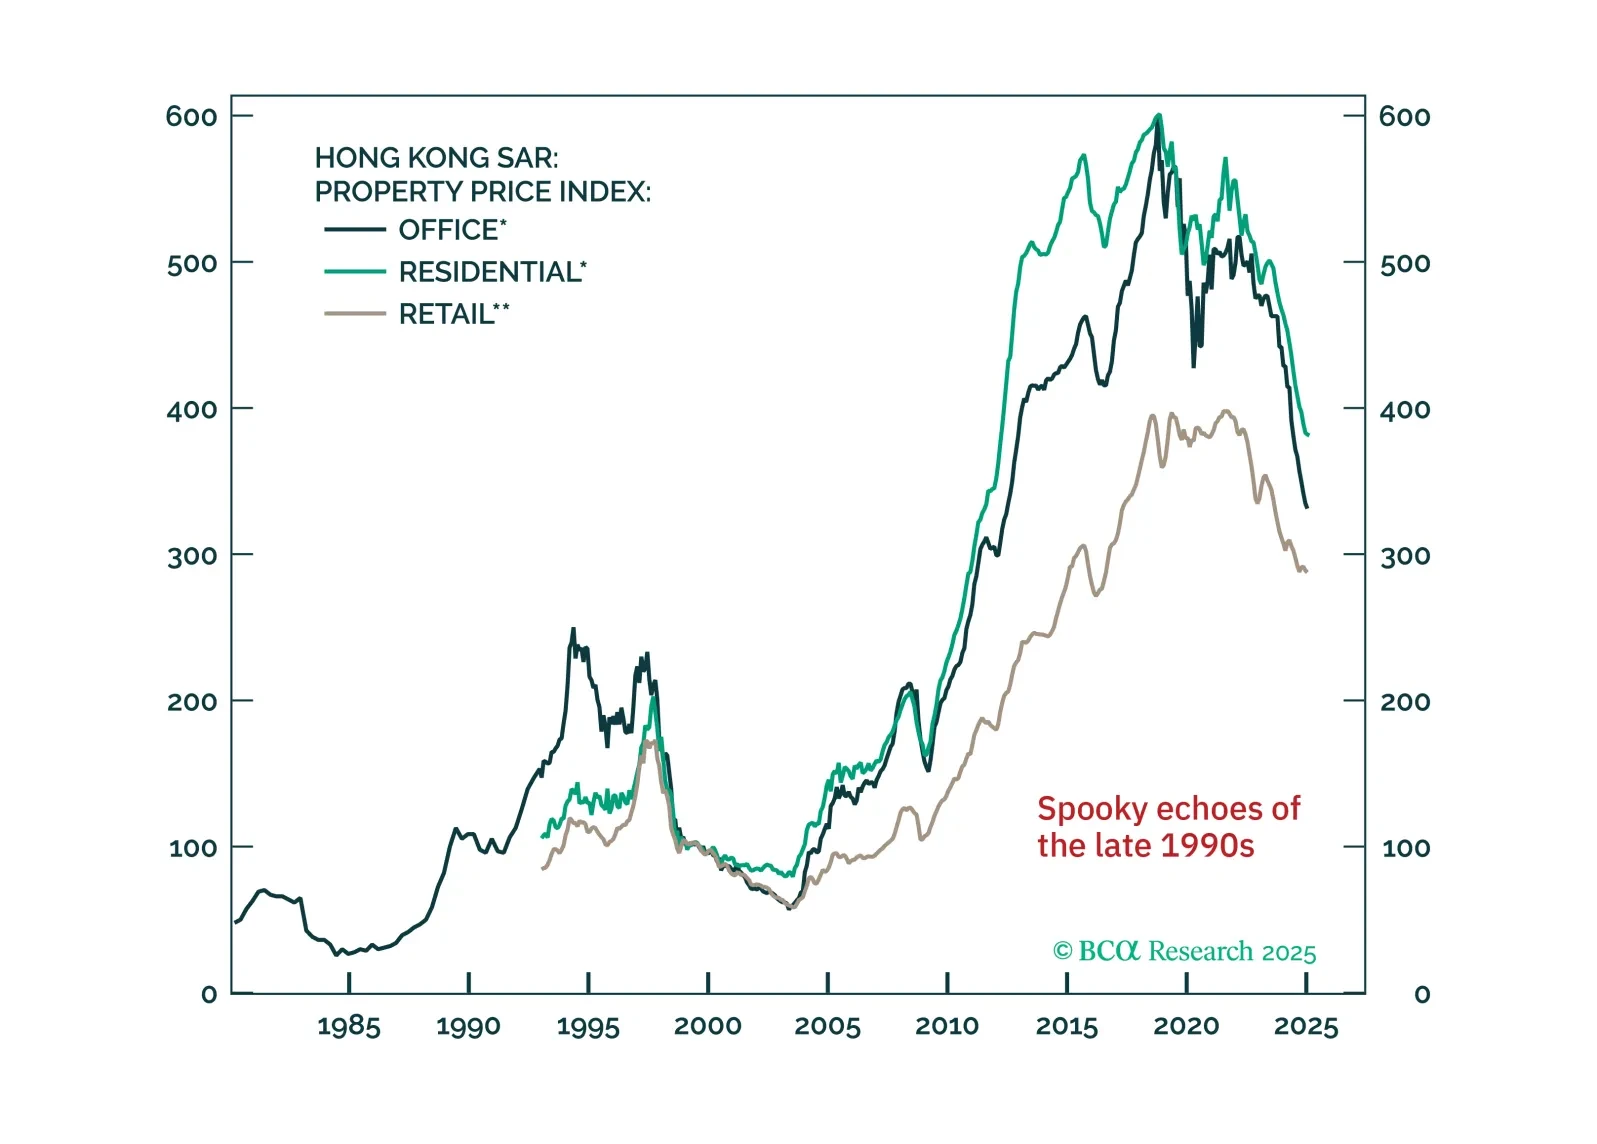
This week, we look at the sustainability of the HKD peg as the next whale to move markets, given what is happening to tariffs. After careful analysis, our bias is that it is here to stay. With the DXY dipping below 100, we are likely to see a rebound, which is actually bad news for the Hong Kong region of China, since it will tighten financial conditions. We have no new short-term trades, but if the peg broke, you want to be short HKD/JPY.
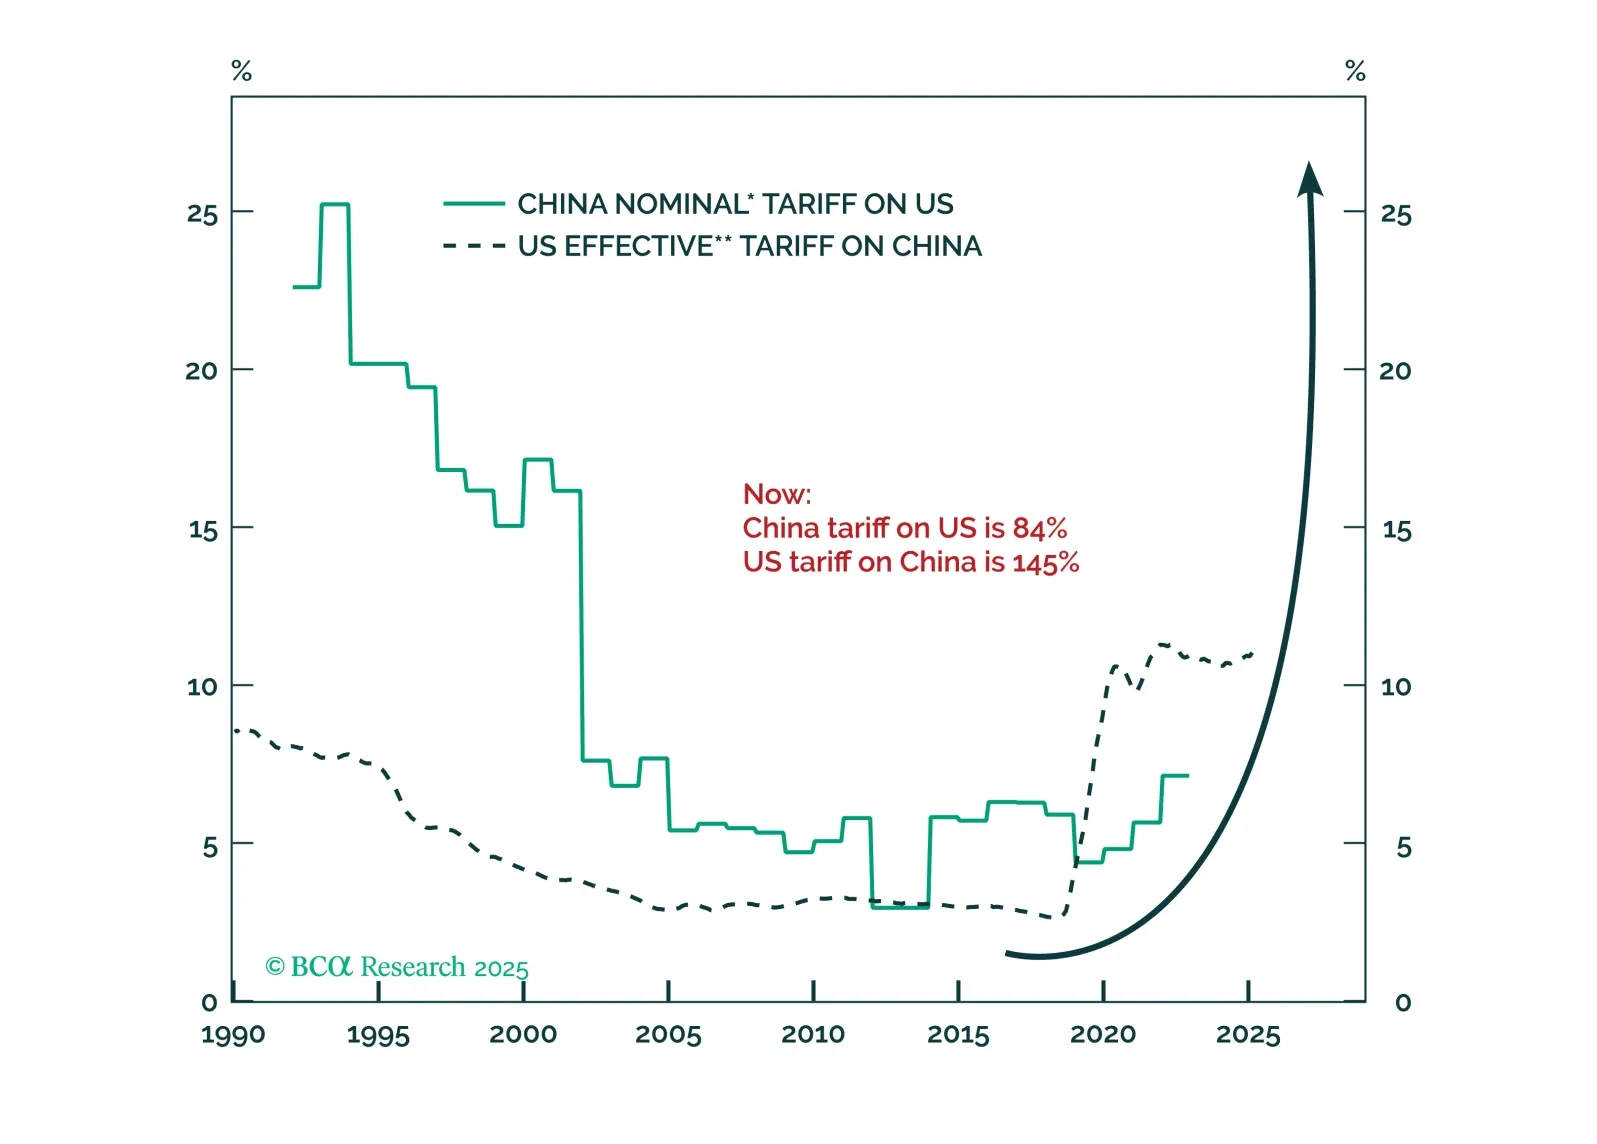
China’s aggressive retaliation against U.S. tariffs will enable President Trump to shift from punishing allies and redirect the trade war toward China. If Beijing does not react to the latest tariffs by doubling its fiscal stimulus, it indicates they are planning something different, as China will encounter economic destabilization. The likelihood of a hybrid military pressure on Taiwan will rise.