Fixed Income
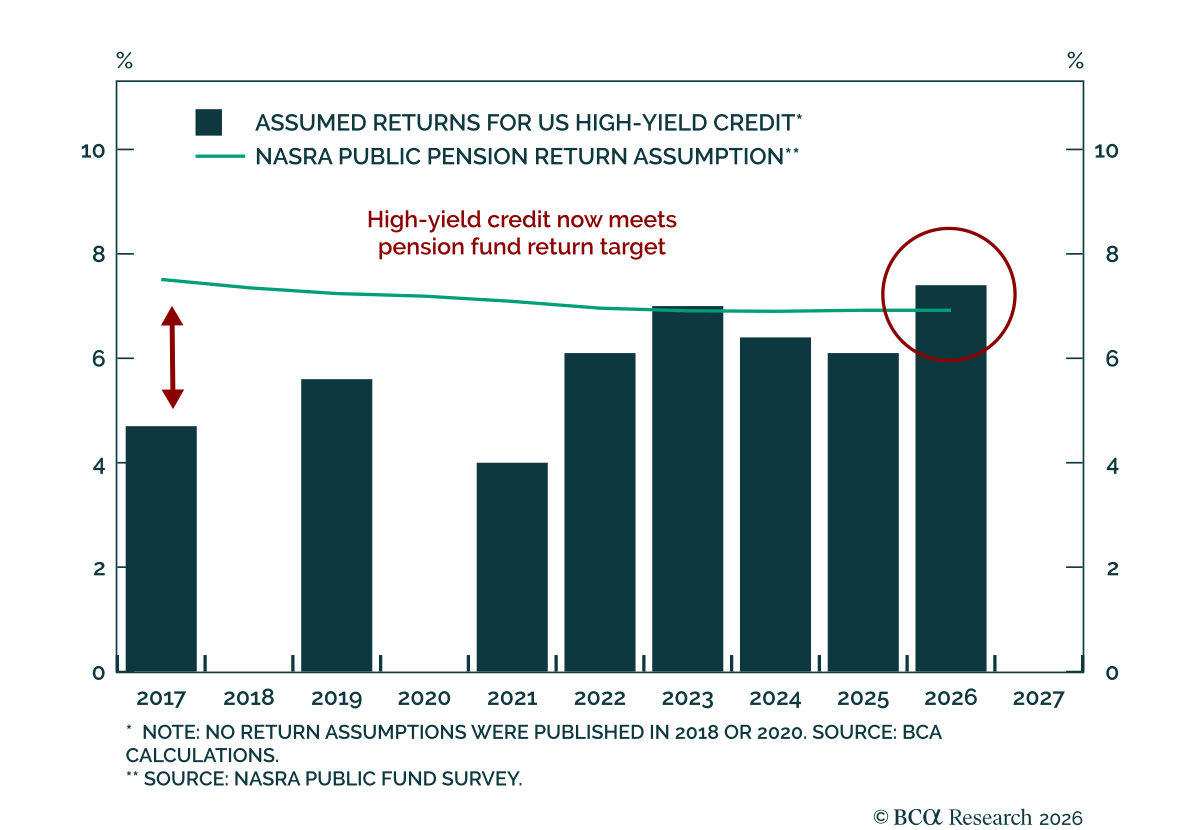
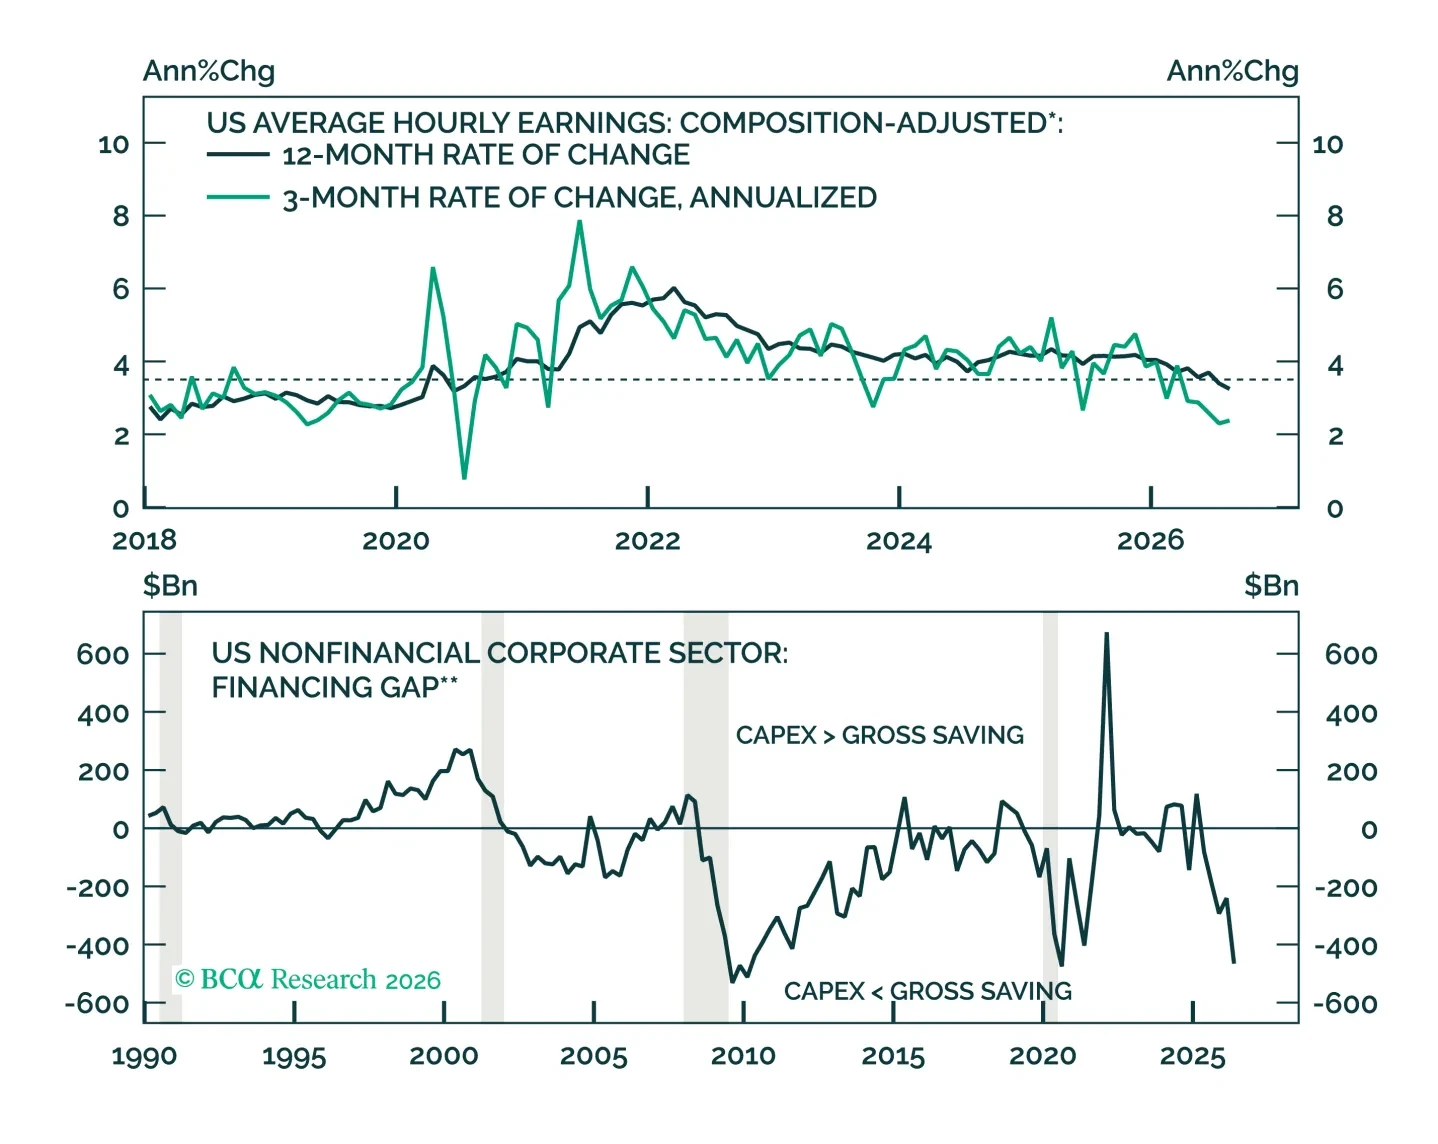
Politics, wars, a global tightening cycle, doubts over AI capex: the wall of worry keeps rising. But the spark that would topple risk assets is missing. Our Q4 FICC outlook explains why to stay long risk, and where the danger lies.
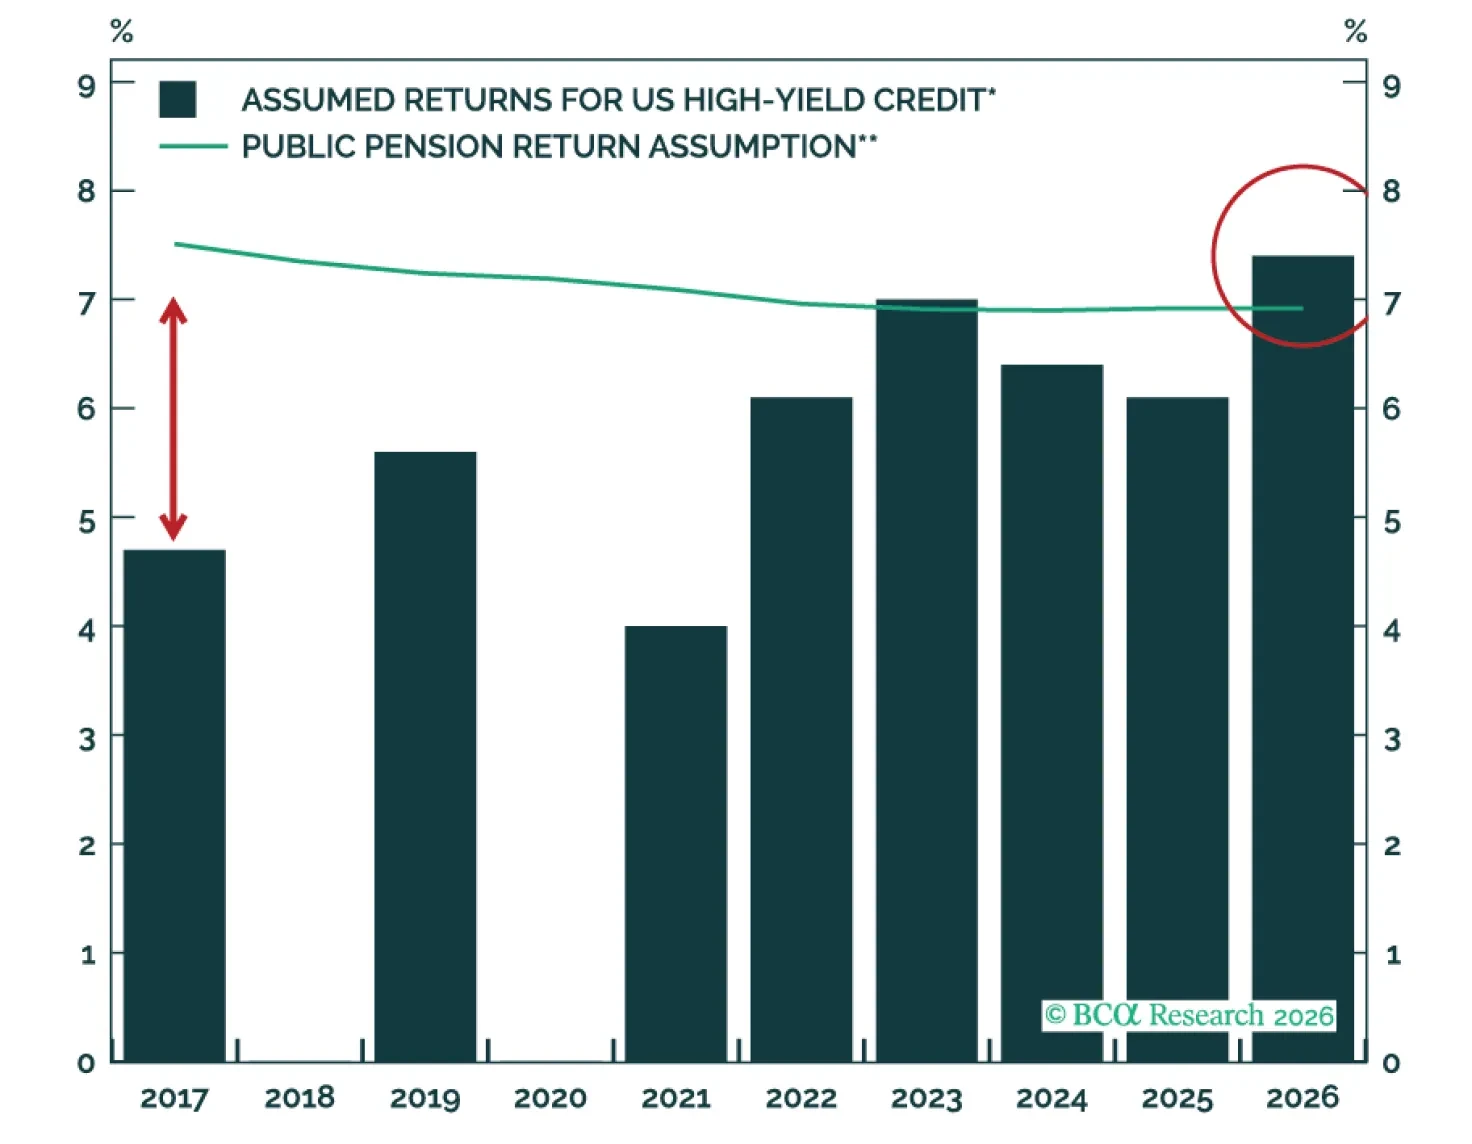
Higher rates have changed the opportunity set. Overweight High-Yield Credit, both within asset allocation and versus Private Credit. Investors are no longer picking up pennies in front of a steamroller.
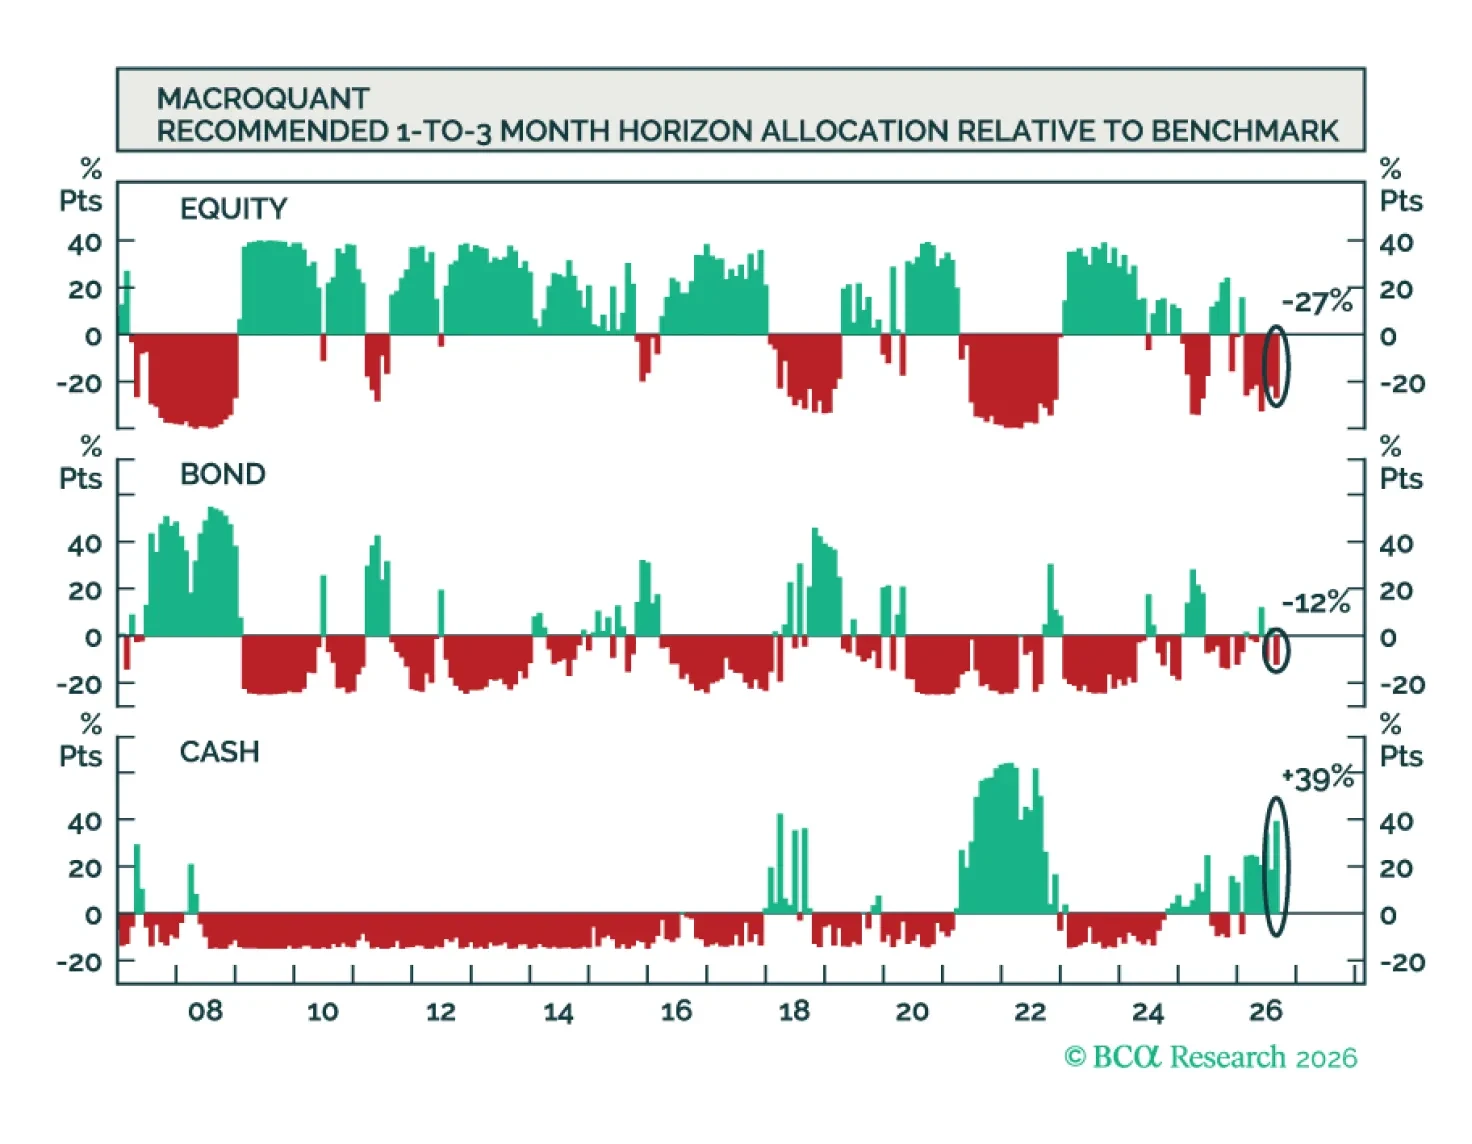
MacroQuant recommends an underweight to equities and bonds, counterbalanced by a significant overweight to cash. The model is very bullish on the US dollar, slightly negative on gold and copper, and positive on oil.
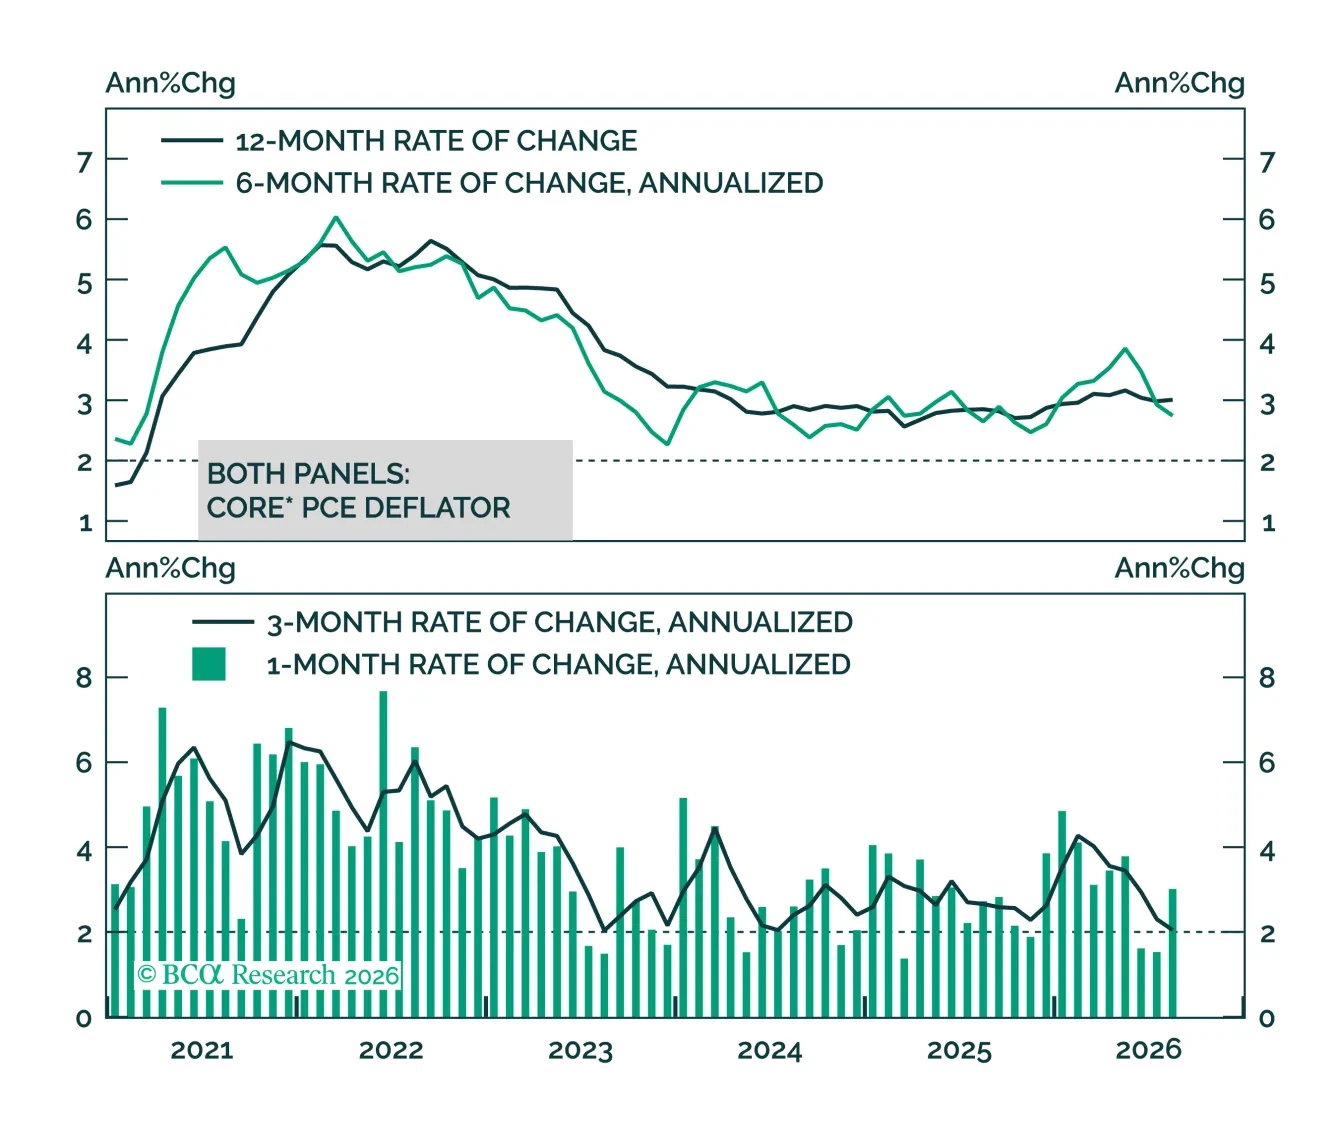
Core US inflation is still running above target. But this morning’s data revisions reveal that the gap is not nearly as large as it appeared yesterday.
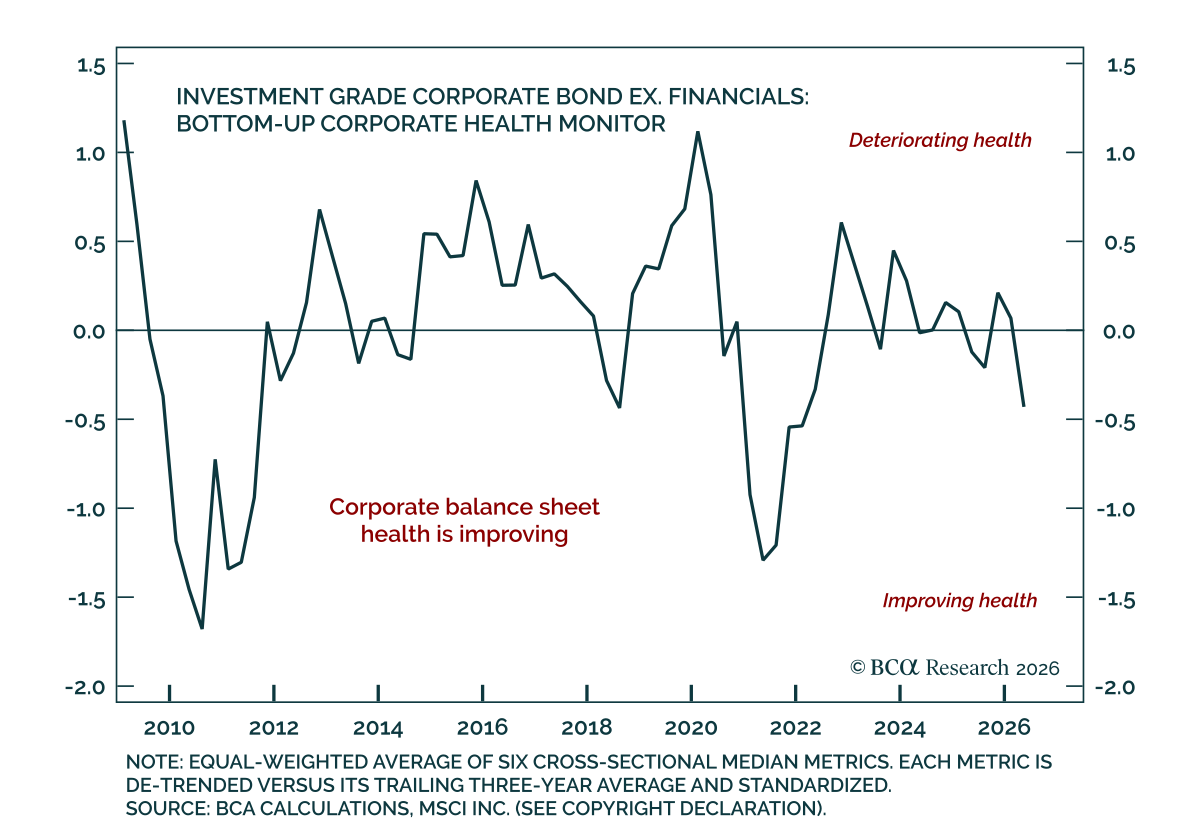
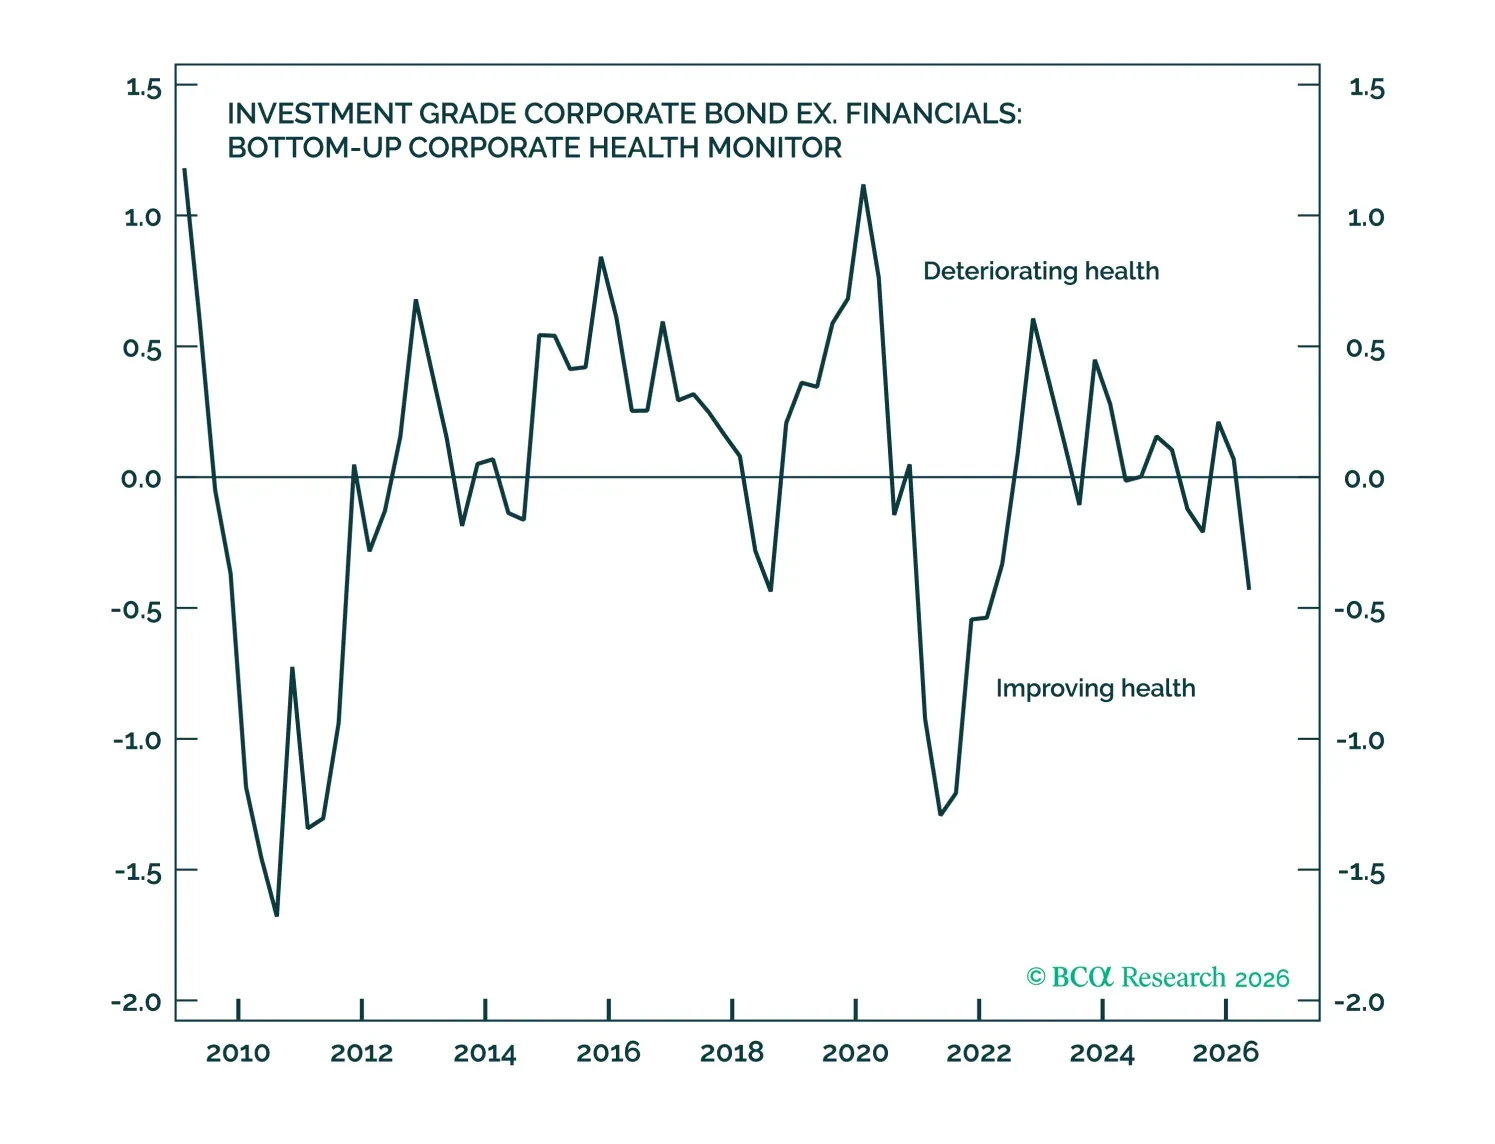
US corporate balance sheet health looks strong overall, and credit metrics aren’t showing any significant negative impact from the AI issuance boom.
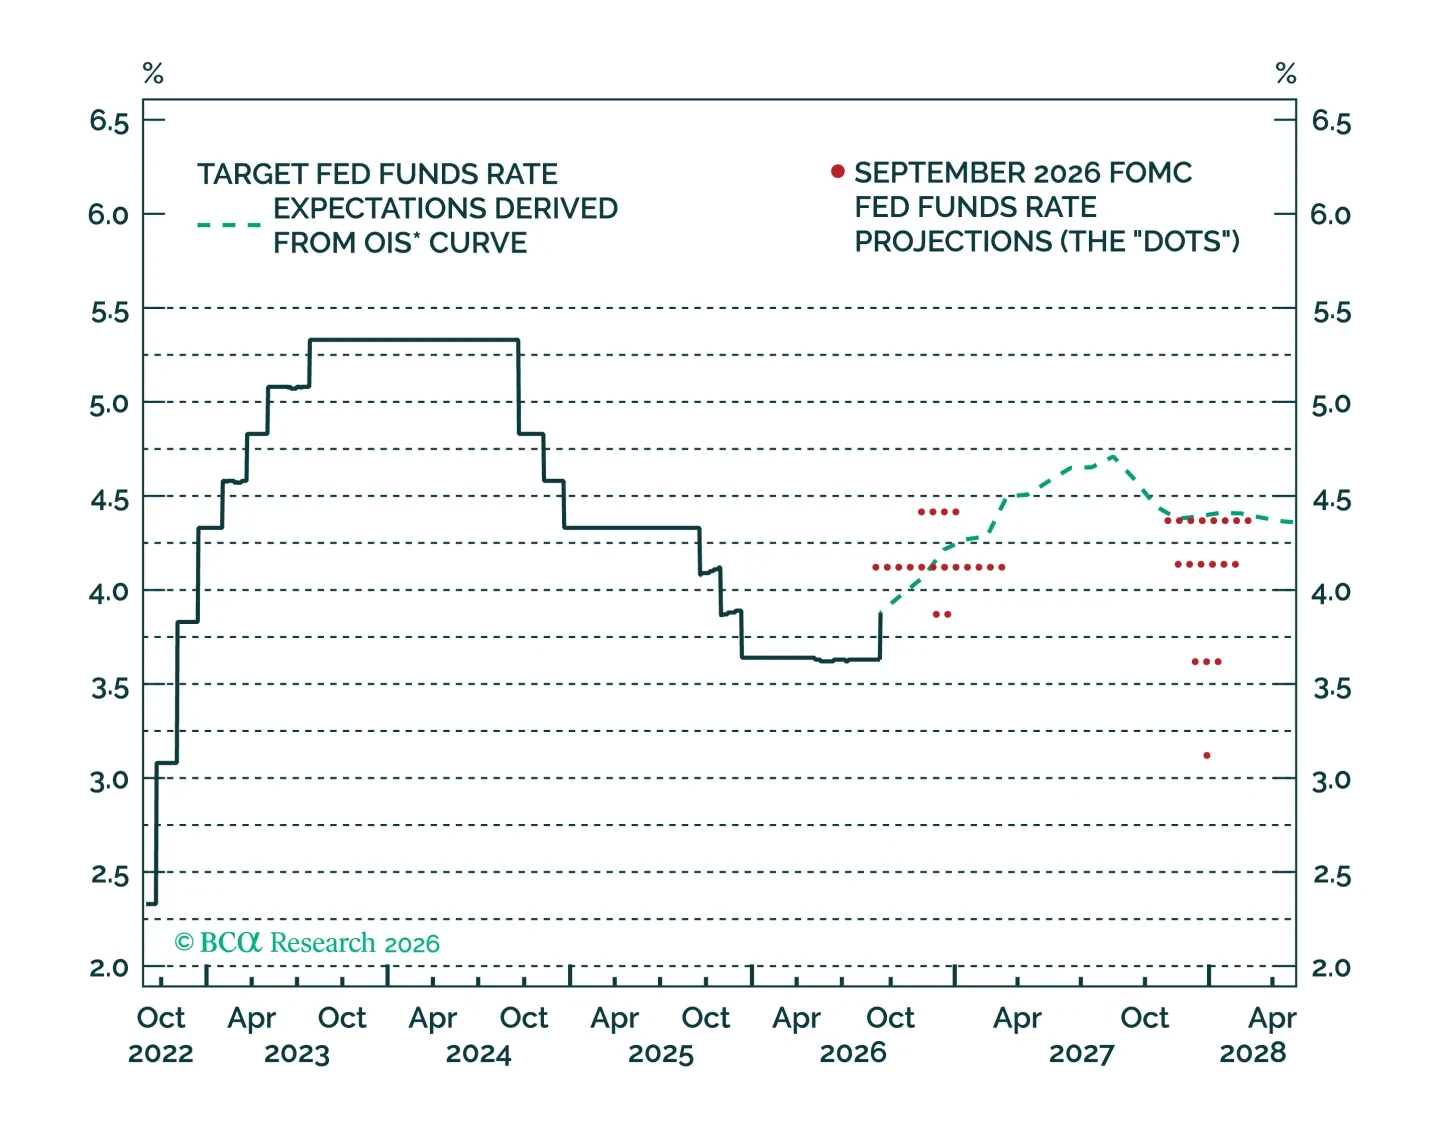
The Fed is unanimous in expecting a mild tightening cycle of no more than 75 bps, but that outcome is contingent on a rapid drop in core inflation in 2027.