 Portfolio
Public-private allocation guidance, capital market assumptions, and strategic insight to help investors build forward-looking portfolios they can act on and defend.

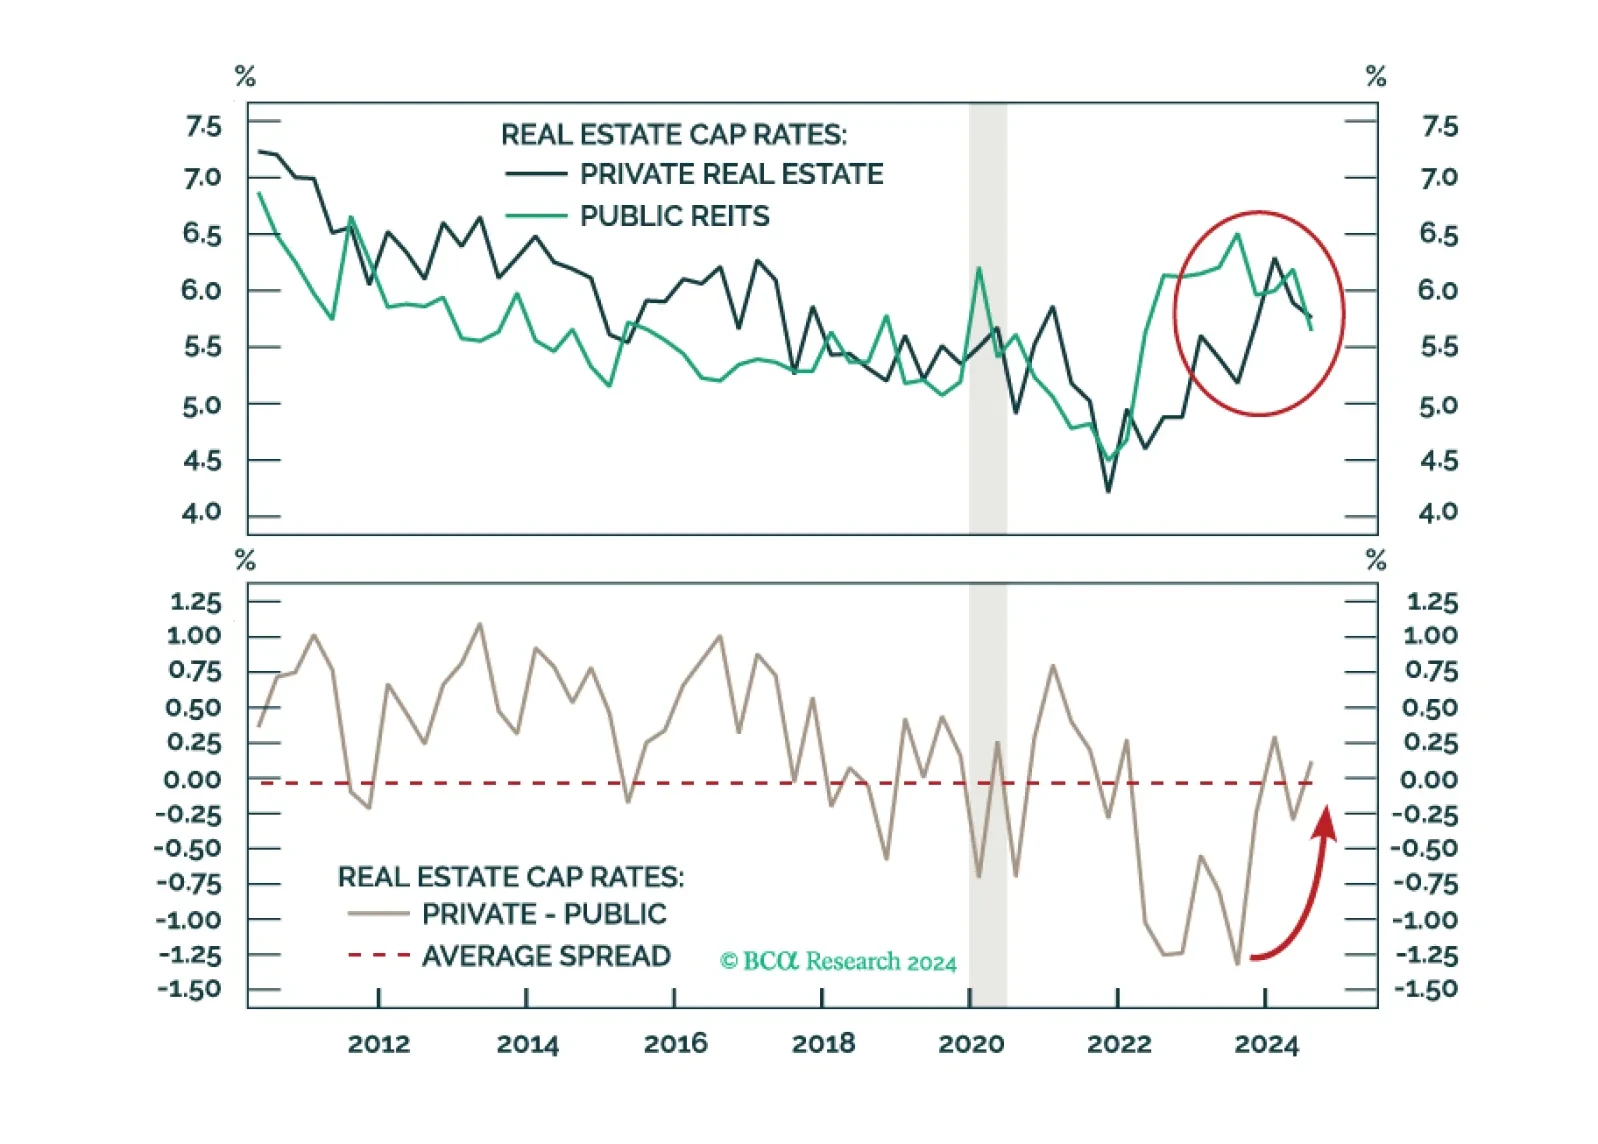
Asset class expectations show mixed shifts from 2024, with Real Estate seeing substantial upgrades and Private Equity benefiting from Venture Capital improvements. Private Credit return expectations decline from 2024 but remain relatively attractive. Infrastructure shows varied dynamics across sub-strategies, with Value-Add offering strong return potential. Within Hedge Funds, Long-Short Equity shows higher tactical returns while Multi-Strategy leads strategic projections.
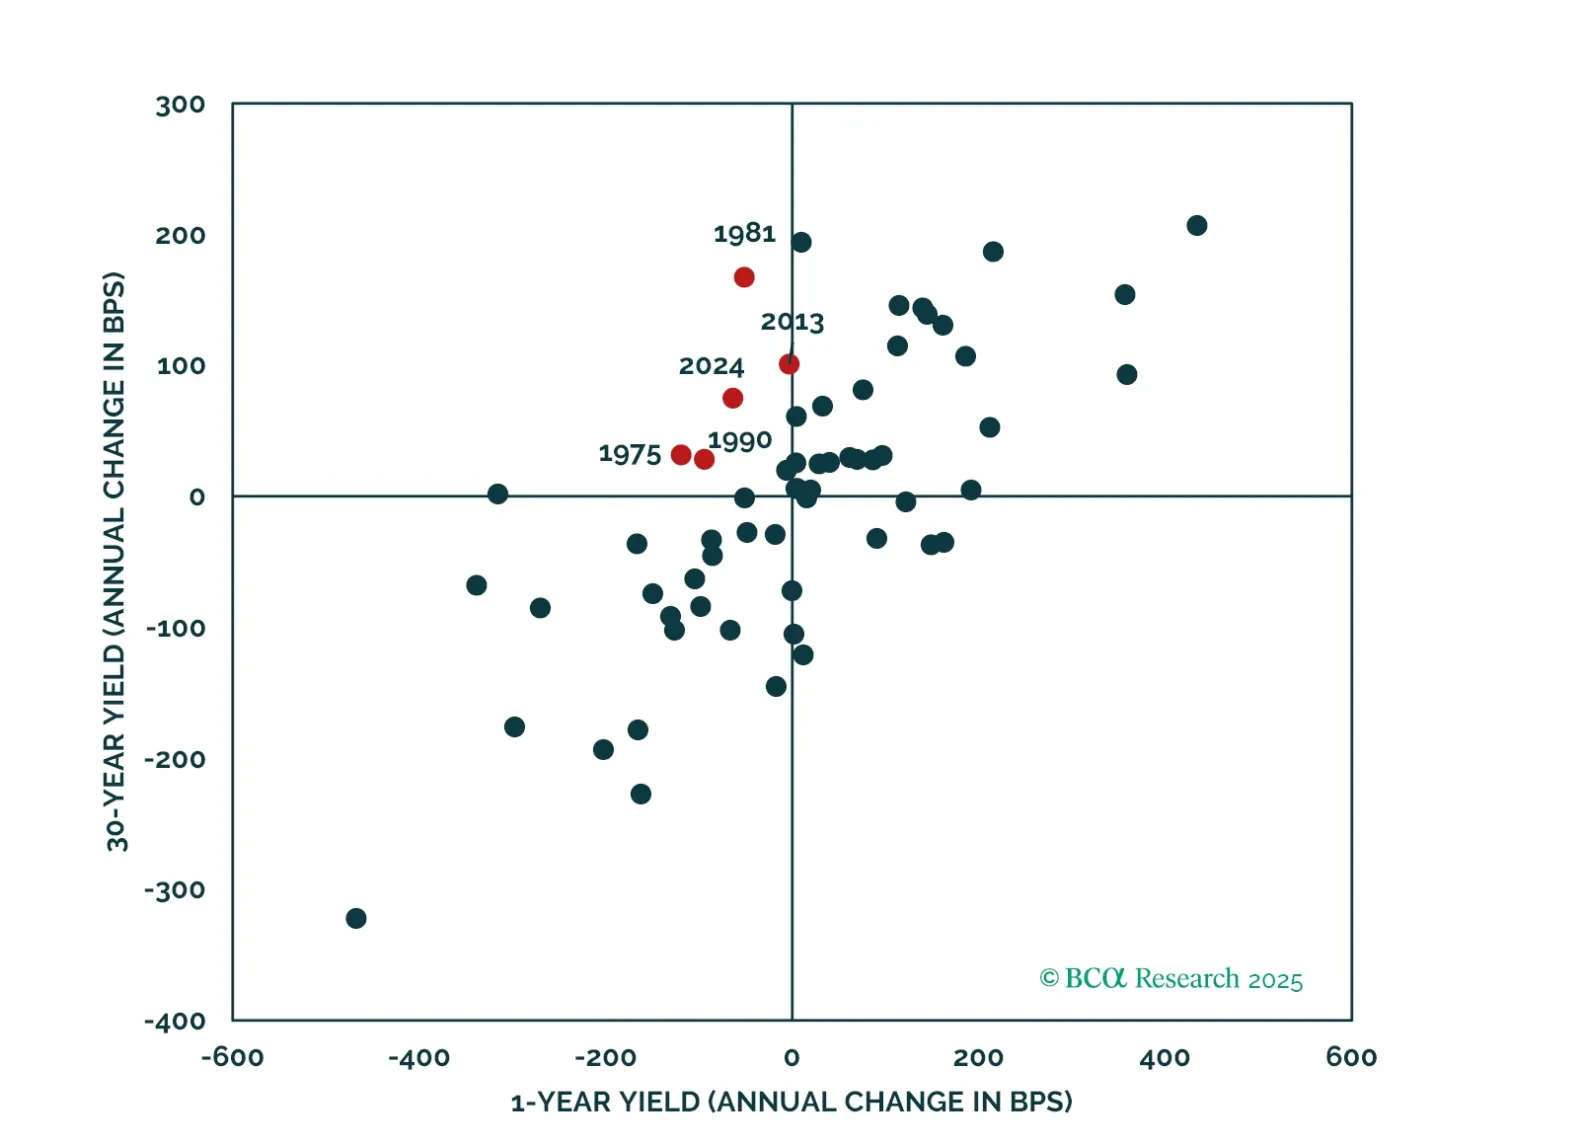
Paradoxically, raging optimism on the US economy is making a reacceleration in growth less likely in 2025. The reaction of the bond market has made the Fed rethink its cutting campaign. Markets are also constraining Trump’s agenda. US manufacturing will not recover with a surging dollar. Fears of inflation and debt sustainability have made moderate House Republicans push back against the President Elect’s wishes. Given the sky-high optimism embedded in asset prices, we believe a defensive portfolio stance is warranted on a 12-month horizon. Overweight gold to hedge the risk of a fiscal crisis.
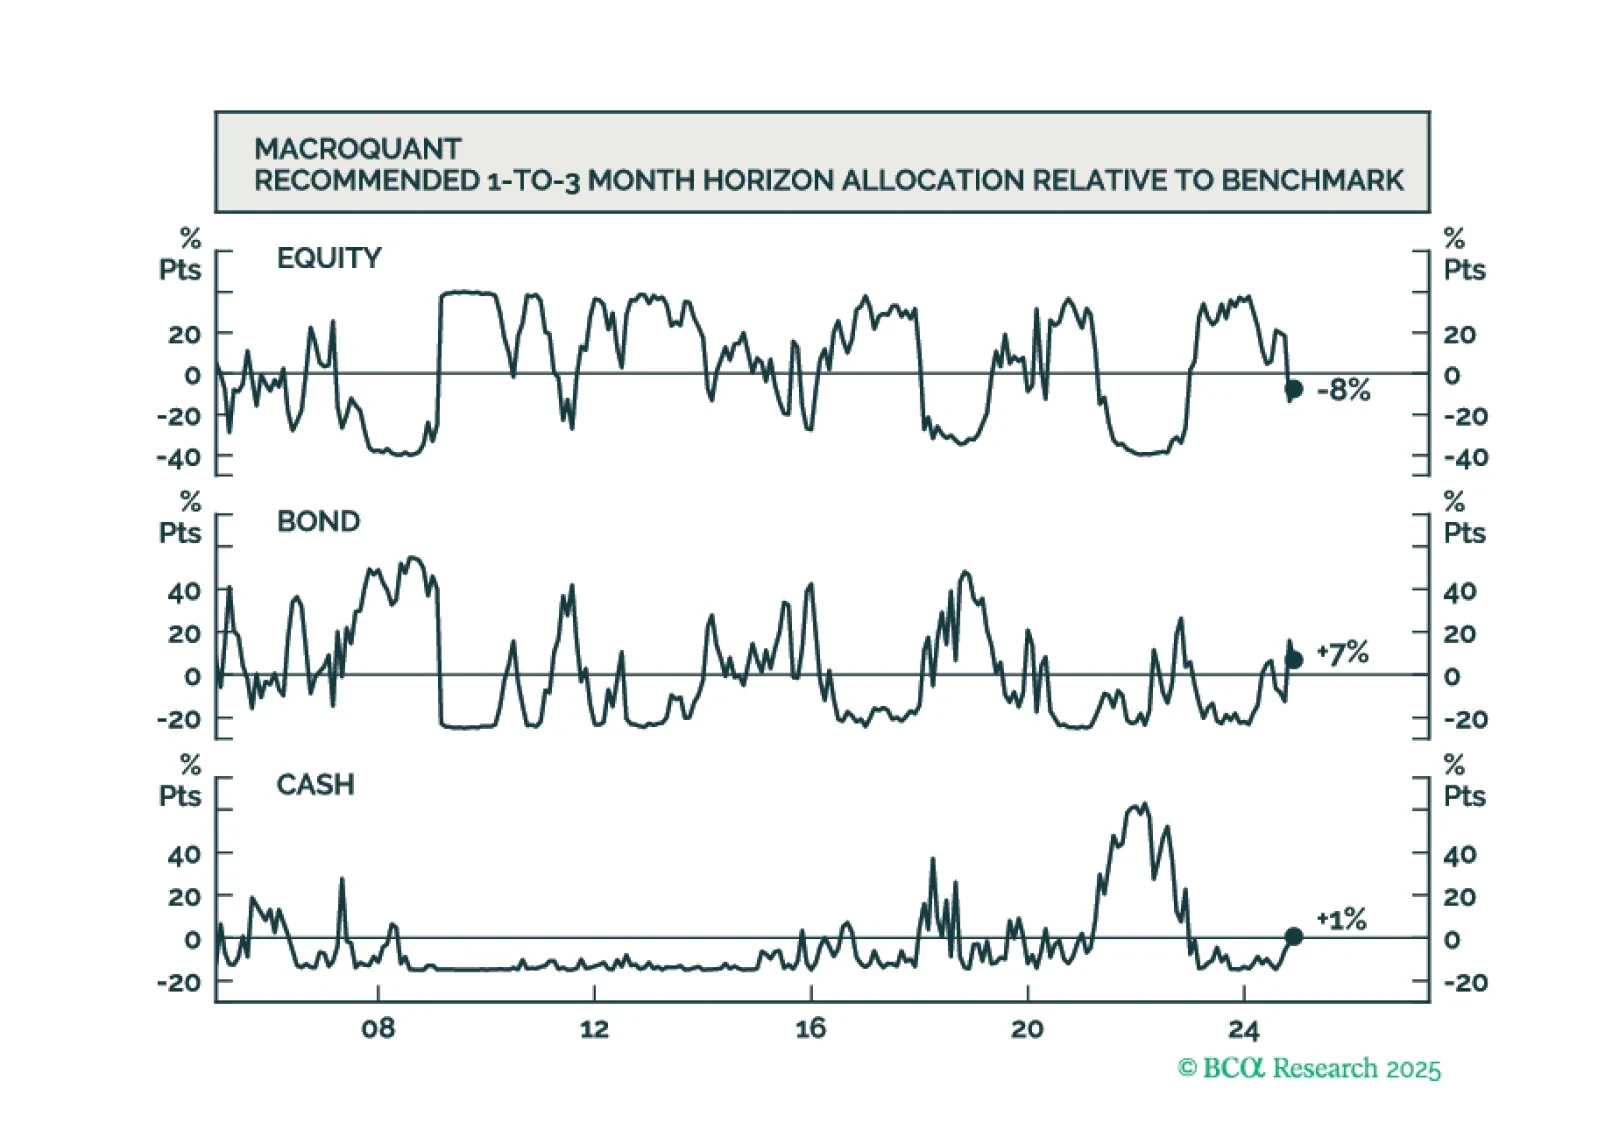
The latest version of the MacroQuant model sees the near-term risks to stocks as slightly tilted to the downside. It is neutral on bond duration and expects the US dollar to continue strengthening in the near term.
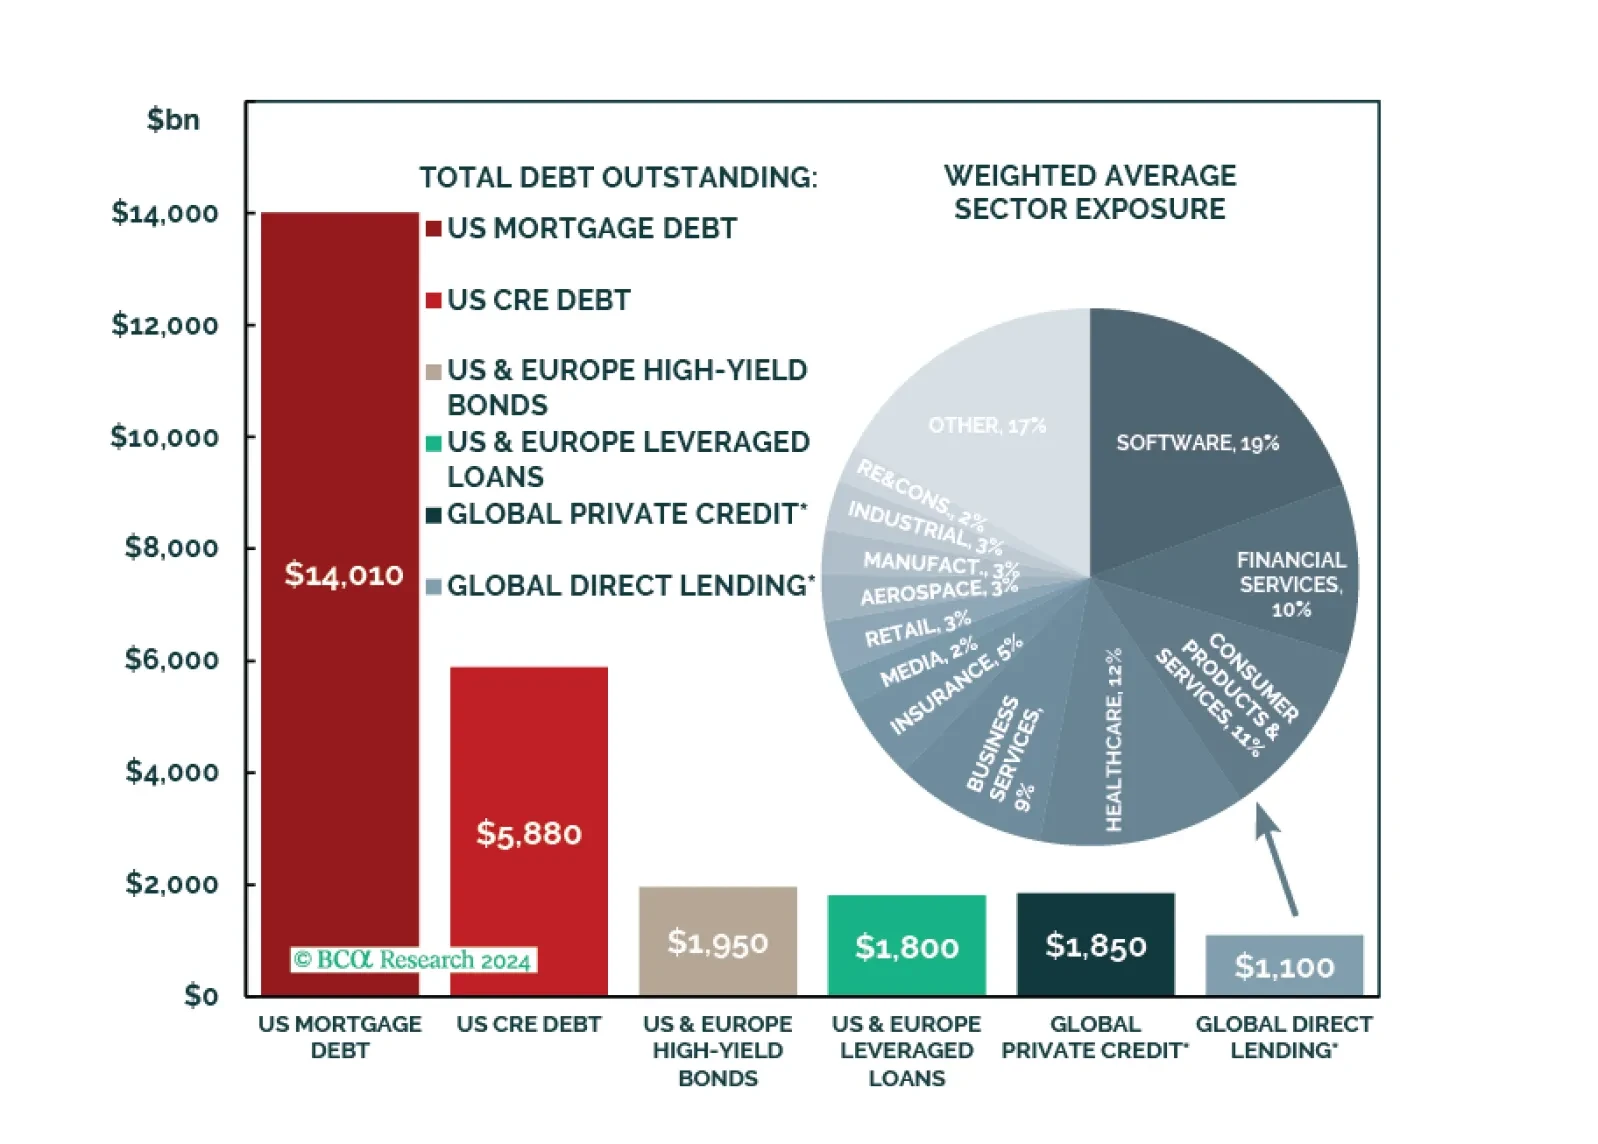
Understanding the risks across Private Credit will enable investors to be offensive, not just with sizing but across their total portfolio. Senior Direct Lending is not risk-free, Private Credit is not systemic, and a liquidity crisis will not be born in this asset class.
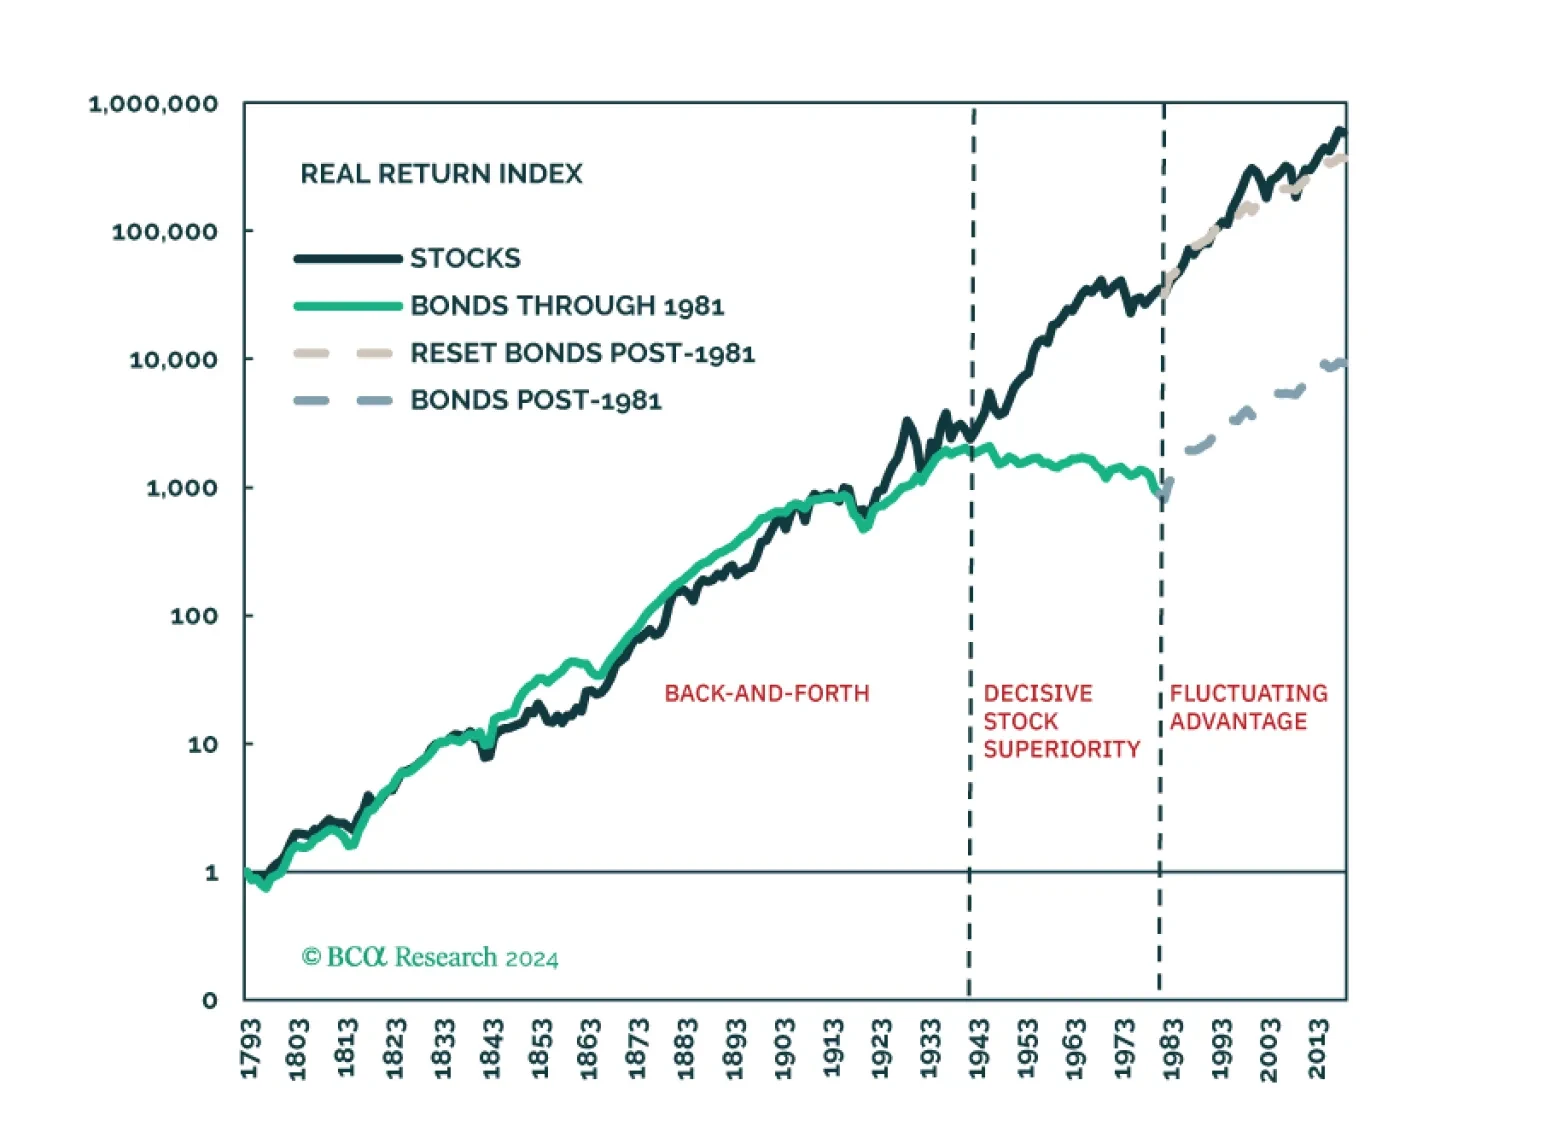
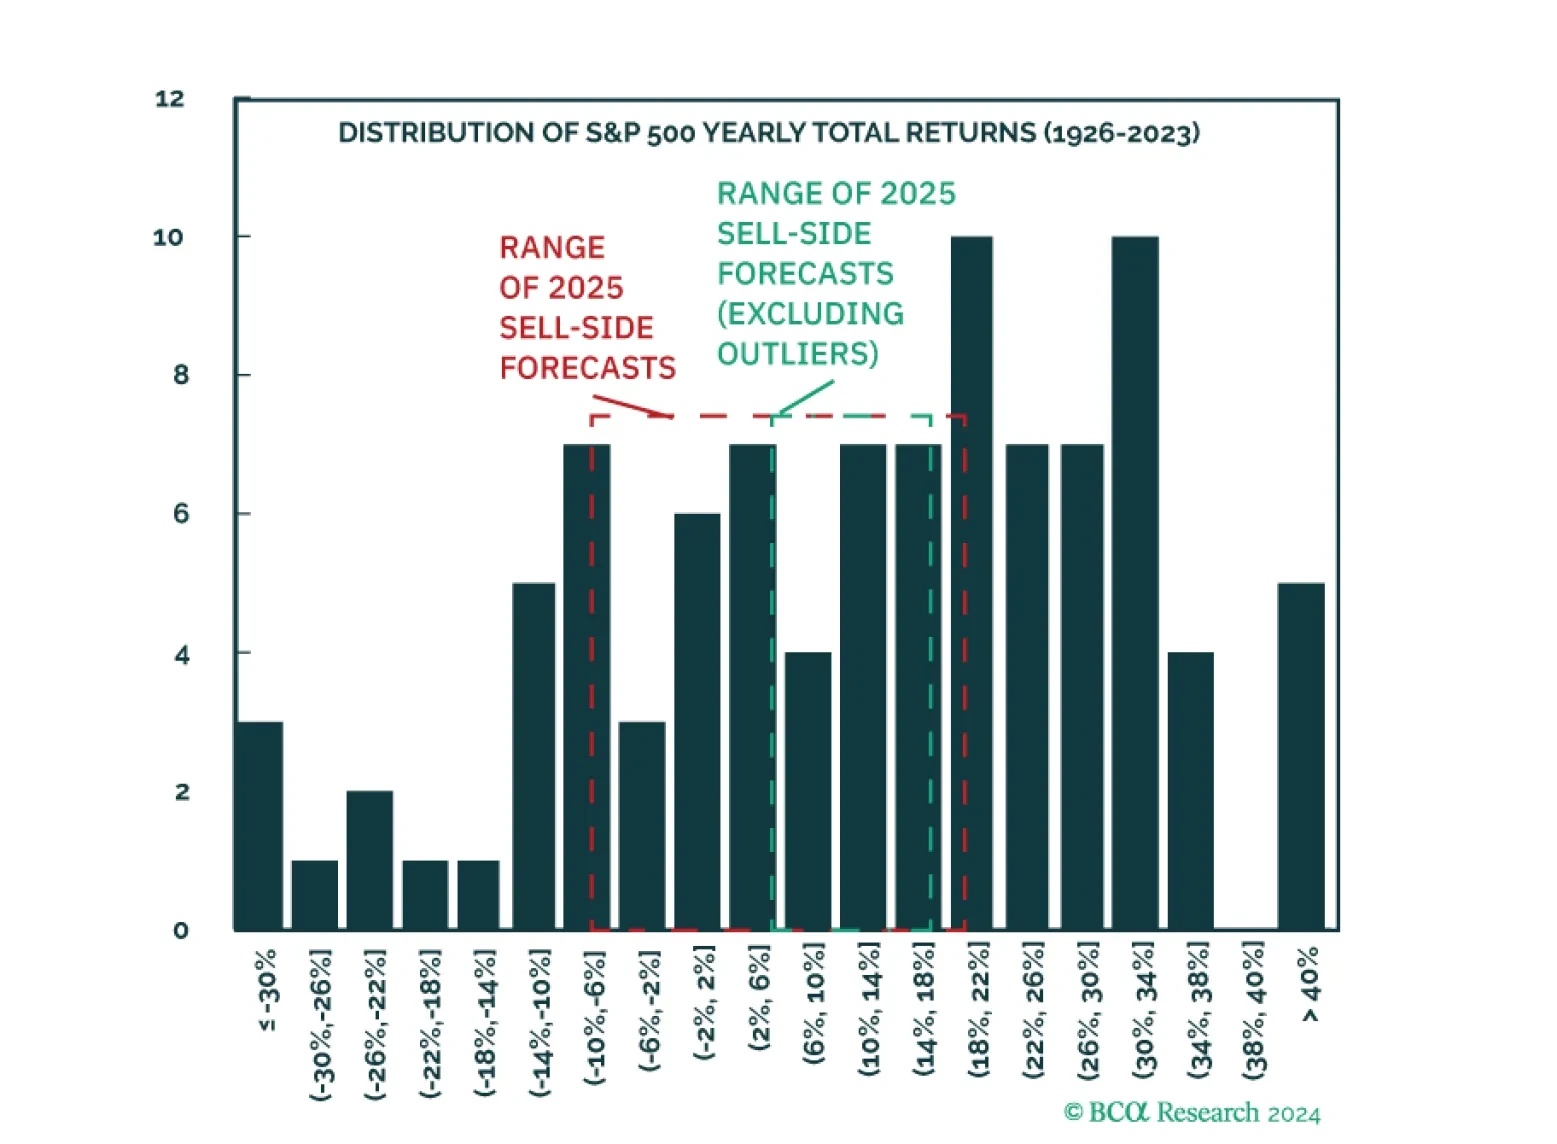
The range of forecast for the S&P 500 is too narrow. While most strategists are predicting an average year for the S&P 500, average returns do not happen often. The S&P is more likely to fall to below 5500 or rise above 7100, than to stay within the range of forecast. As a result, our negative view will either be spectacularly right or spectacularly wrong.
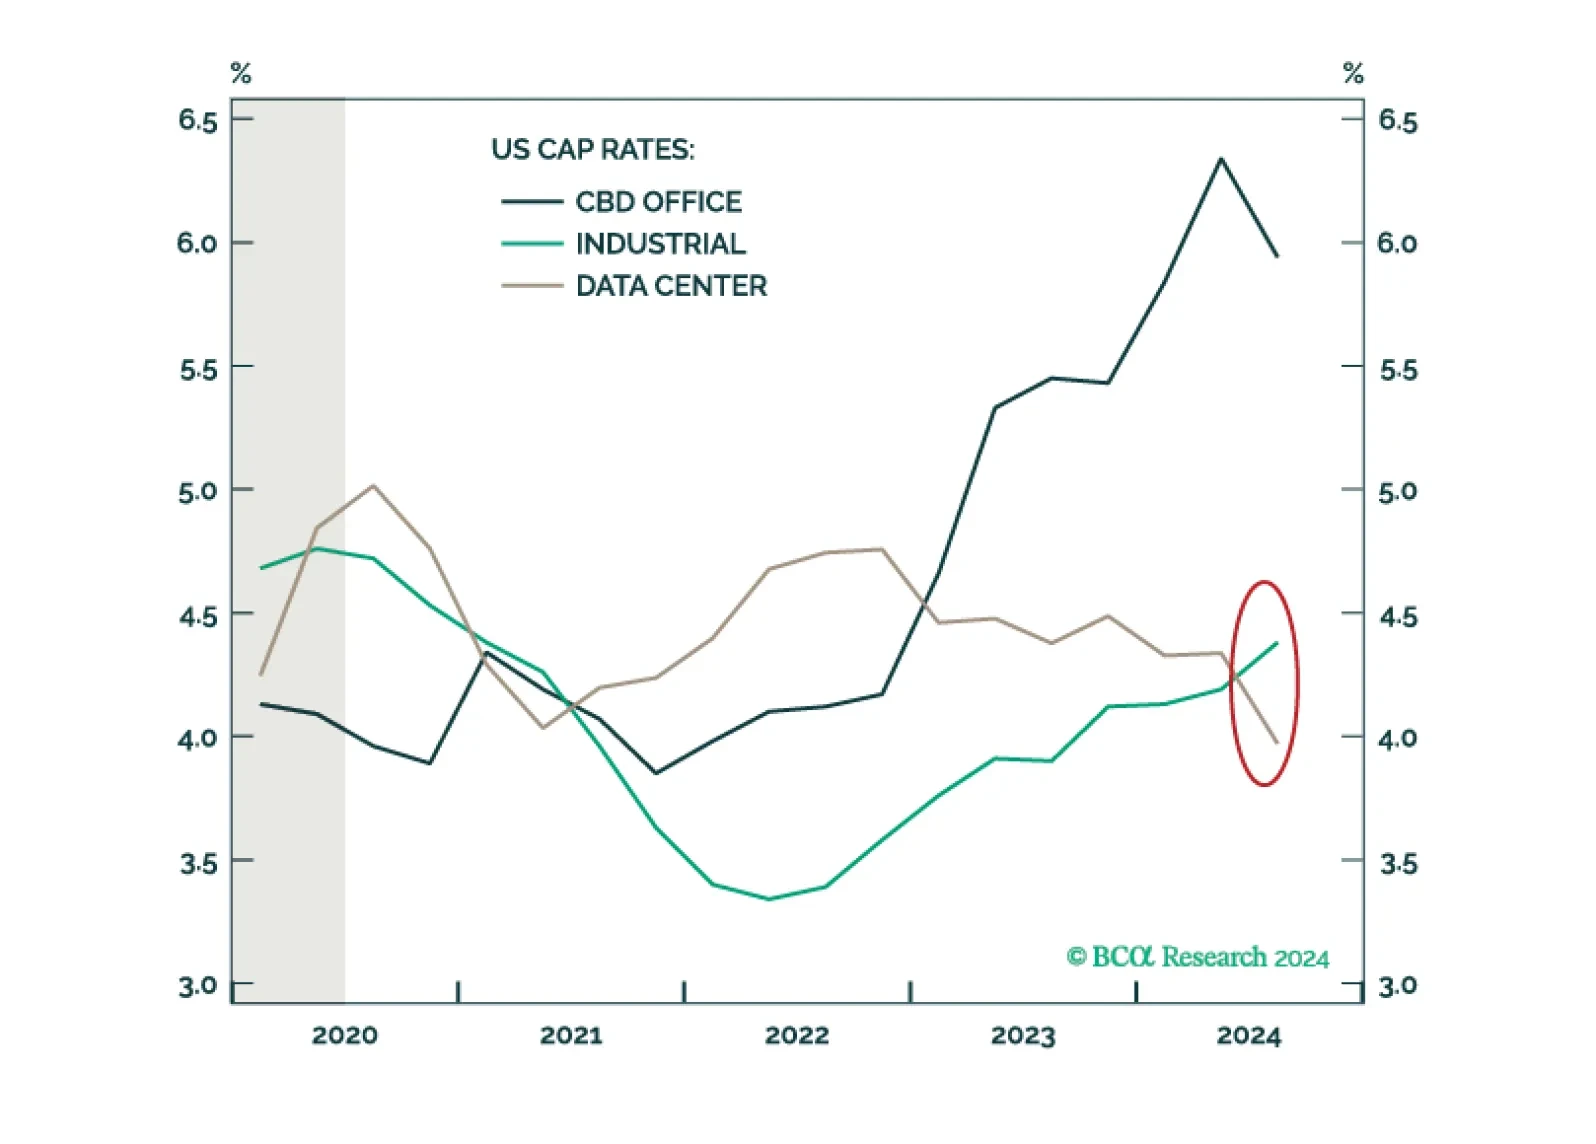
While AI deployment creates compelling investment opportunities, hyperscale facilities are not the only path forward. Investors should consider Office conversions into colocation Data Centers as the next dollar opportunity.
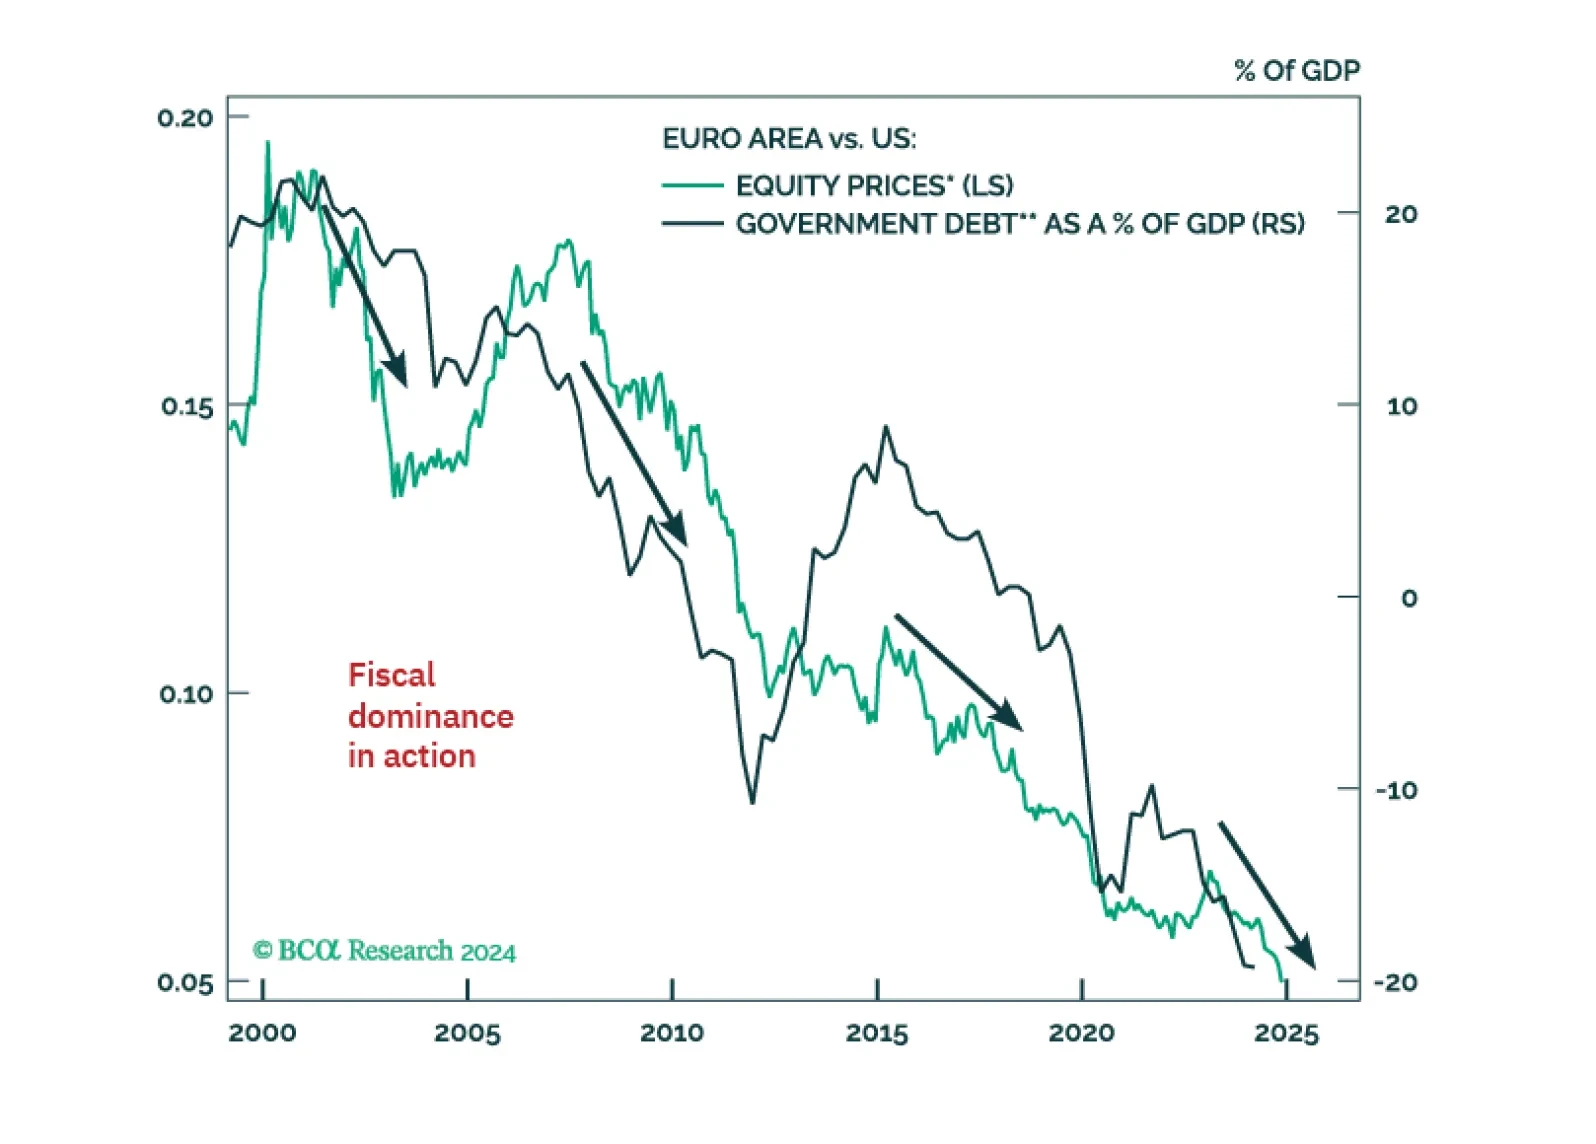
Investors have given up on European assets, which now suffer exceptional discounts to US ones. However, tighter US fiscal policy, the end of Europe’s austerity and deleveraging, the LNG Tsunami about to hit European shores, and the global capex fueled by the Impossible Geopolitical Trinity mean that Europe’s time to shine will soon come back.
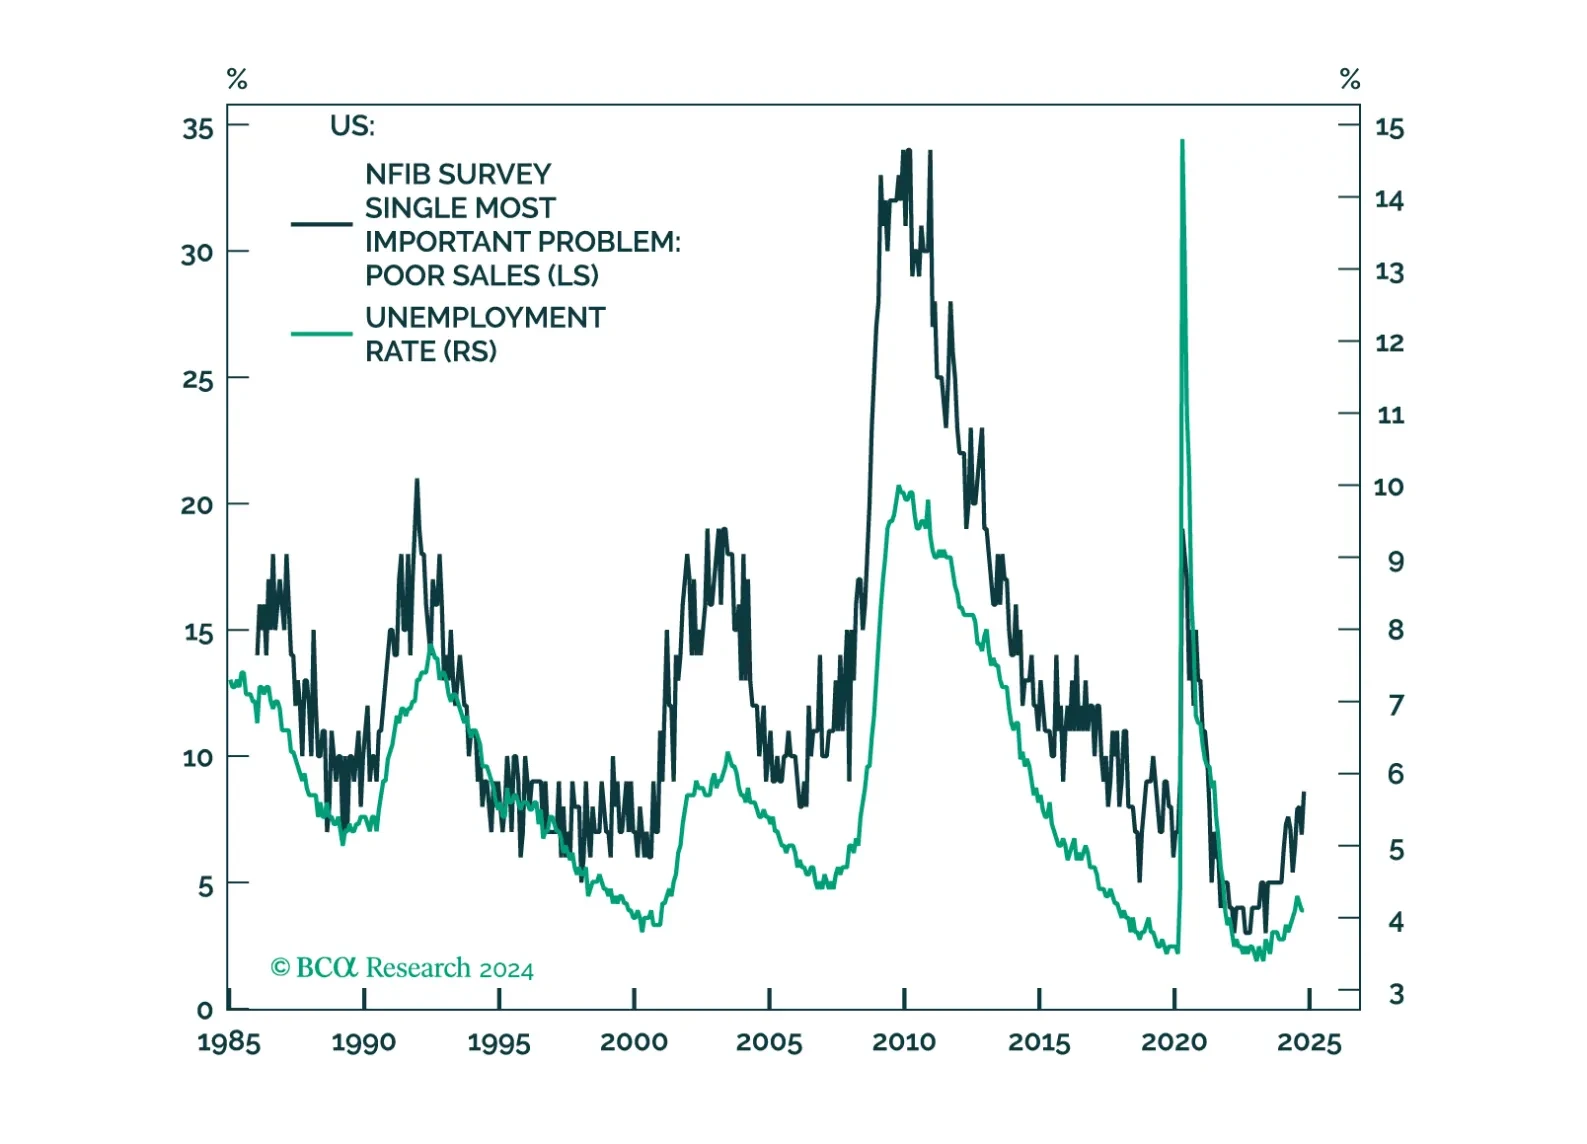
The post-COVID recovery has been one of excesses. Government deficits have ballooned, tight labor markets have led to a windfall of consumer spending, and equity valuations have soared on the back of lofty growth expectations. But these excesses will no longer be sustainable in 2025. Our theme for next year is Thin Is Back In. Government budgets, economic growth, and equity valuations will be leaner than investors expect. We discuss this the reasoning behind this macro view and the asset allocation implications that follow from it.