 Explore FICC
FICC | Bonds
Actionable asset allocation recommendations for your bond portfolio, drawing on macro analysis of interest rates and global debt market dynamics. Typically published weekly.
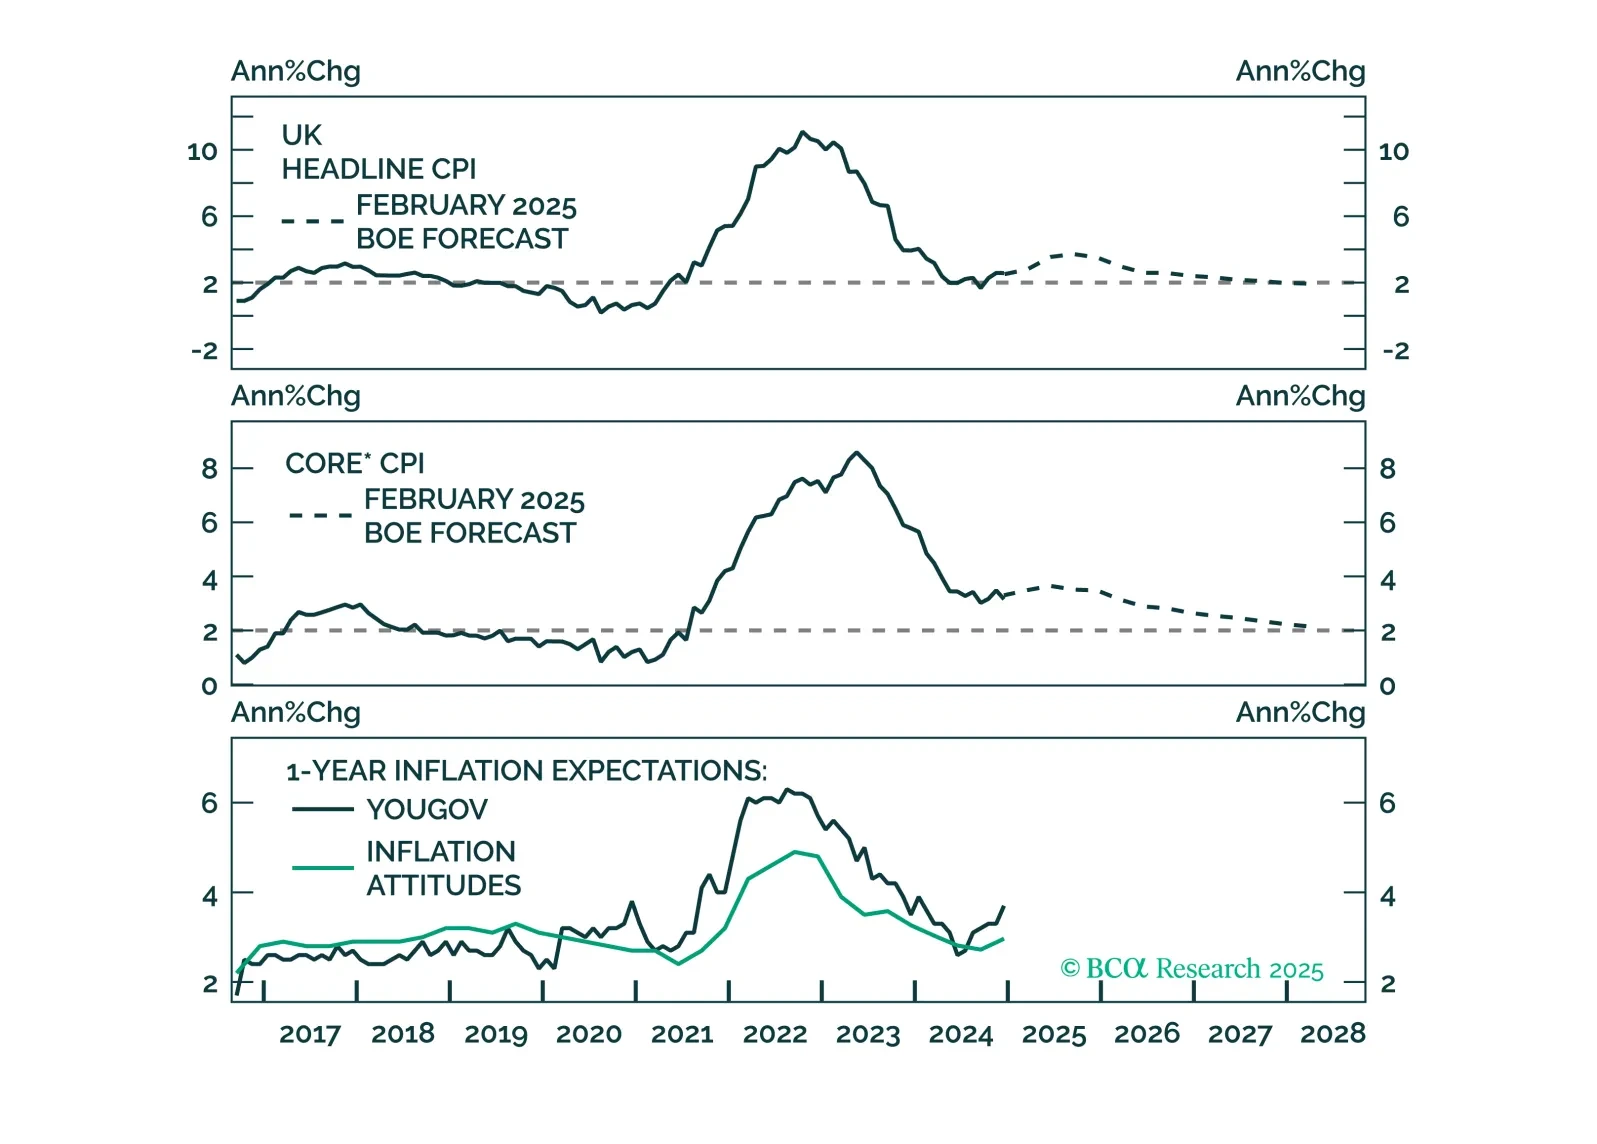
Following today’s Bank of England’s policy meeting, at which the policy rate was cut by 25 bps, we discuss our outlook for monetary policy in the UK. We expect the gradual easing to continue and discuss the investment implications for UK gilts and sterling.
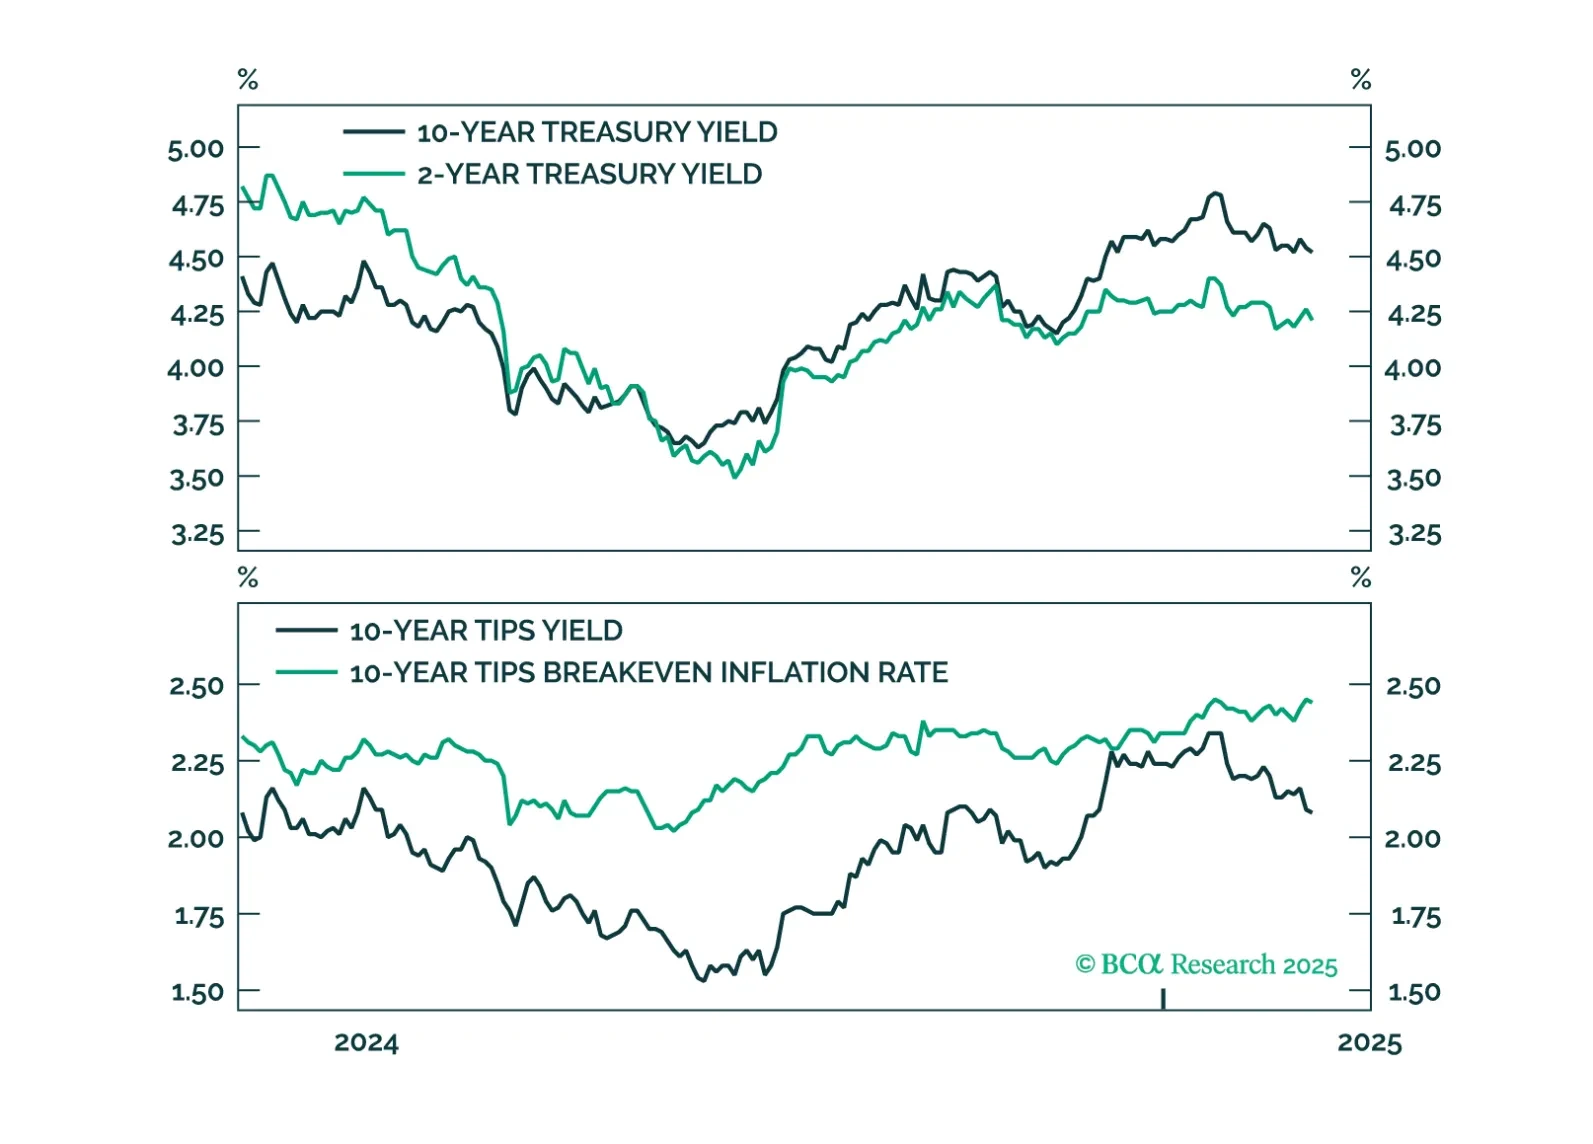
Our Portfolio Allocation Summary for January 2025.
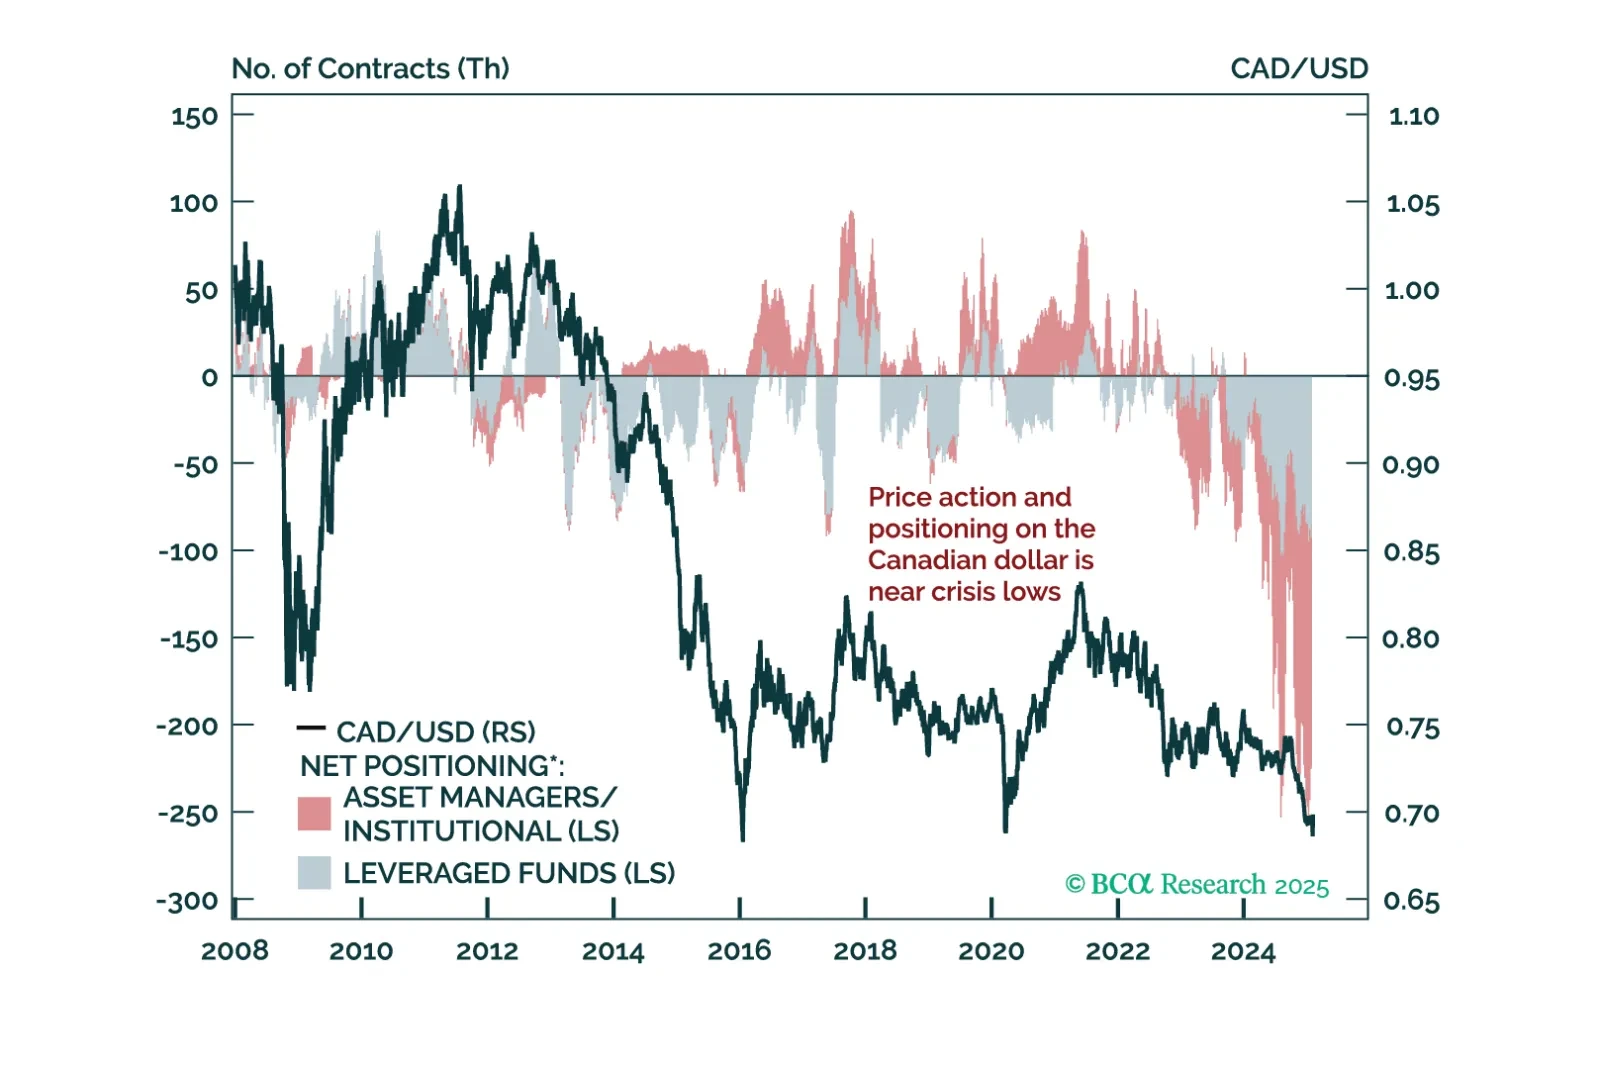
This Insight is a post mortem on Canadian assets, after the threat of tariff wars.
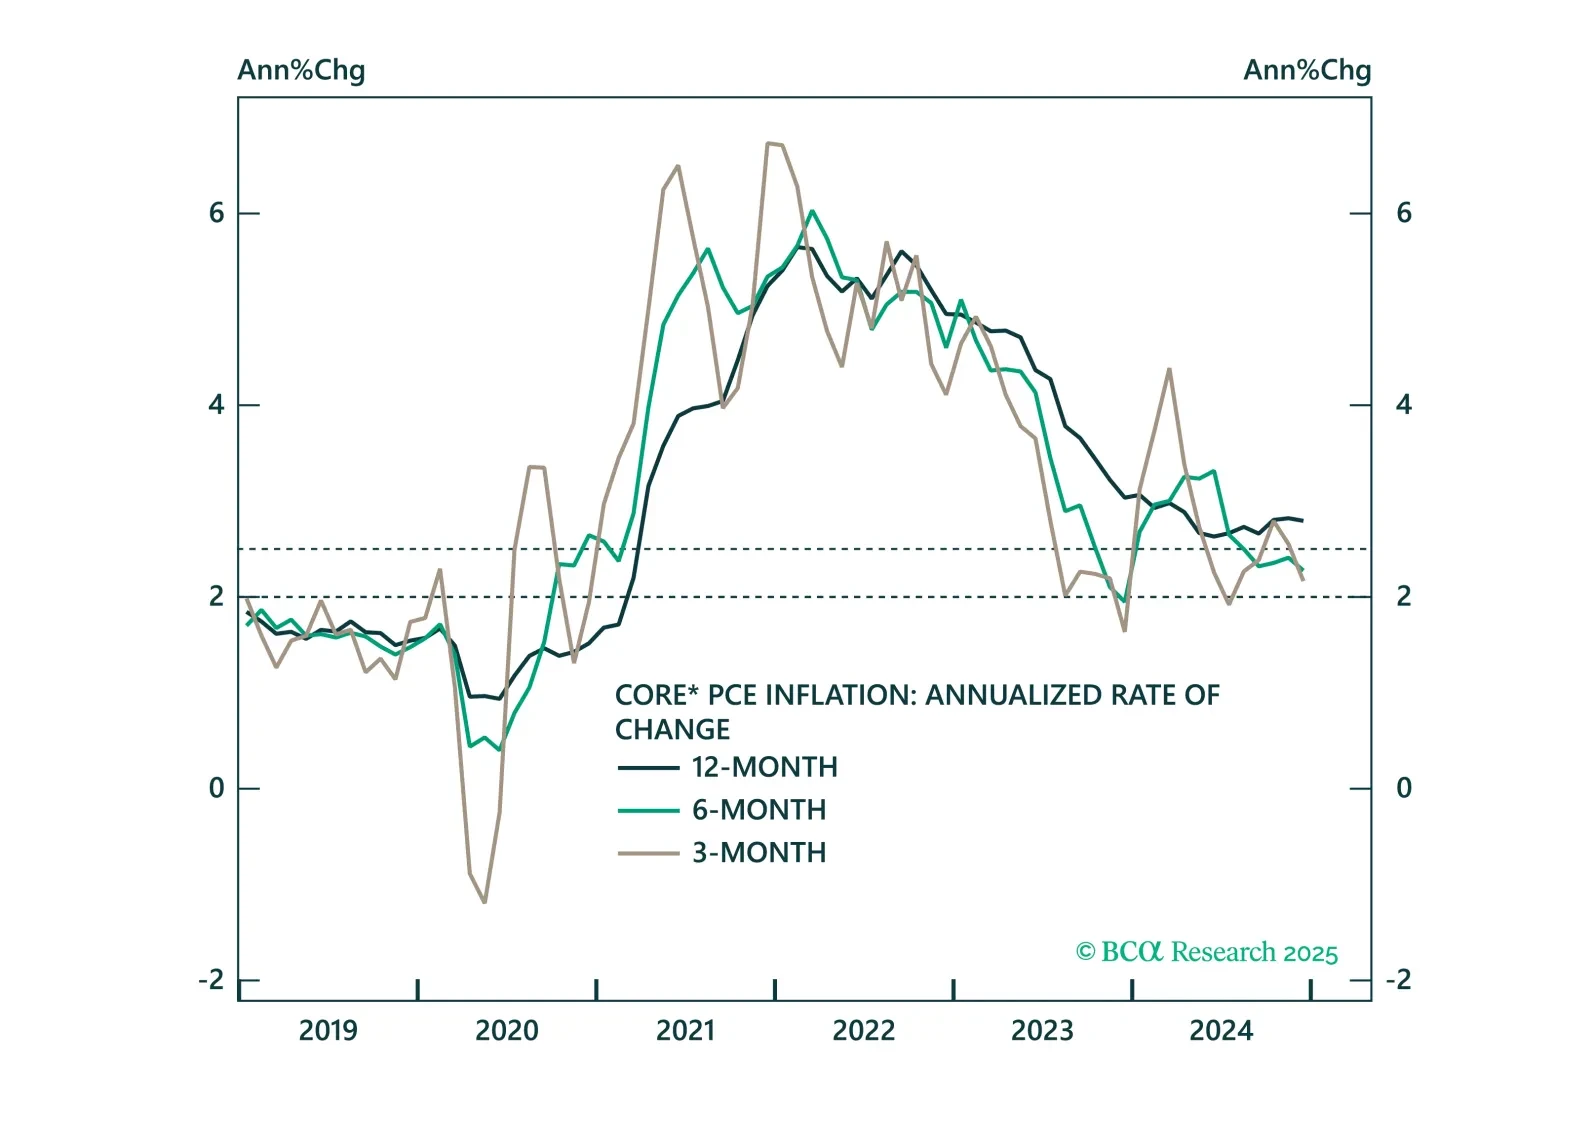
Core PCE inflation came in soft this morning and is tracking well below the Fed’s 2025 forecast. We highlight three upside risks to inflation and preview next week’s employment report.
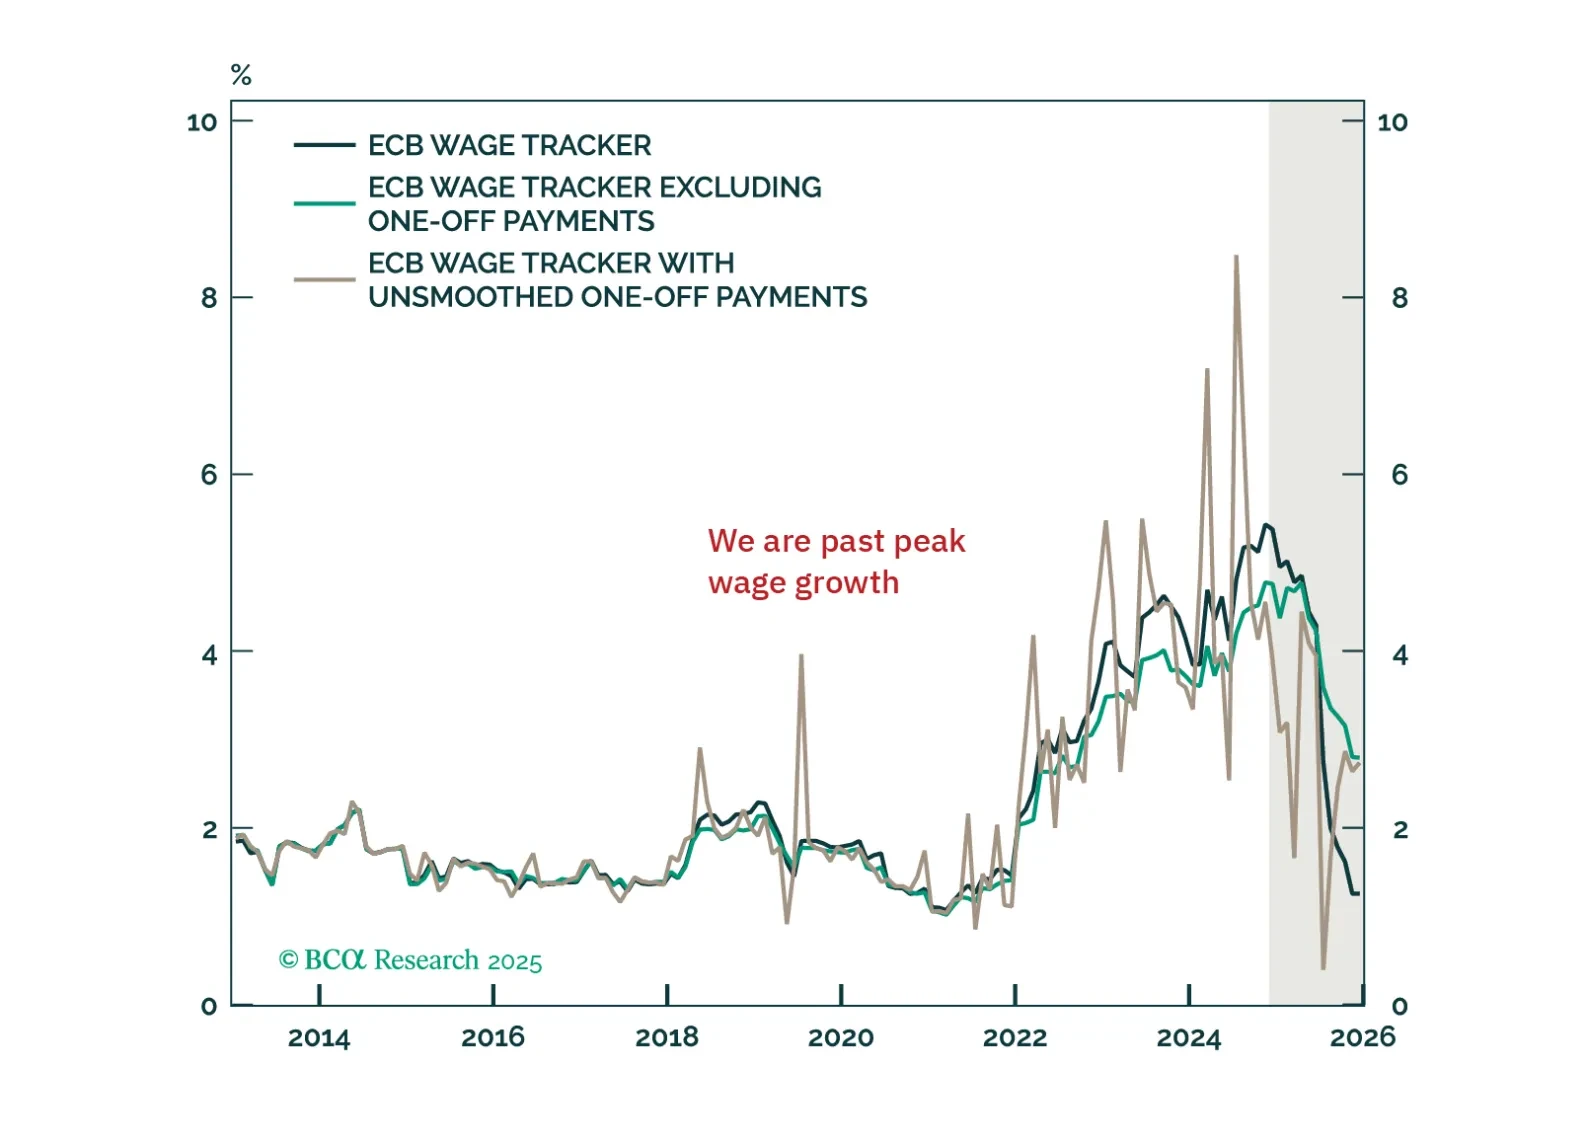
The ECB cut its deposit rate to 2.75%, as was widely anticipated. President Christine Lagarde did not provide any fireworks, but the Governing Council’s message was clear: Policy is restrictive, and inflation will fall further. As a result, if we combine our economic forecasts for the Eurozone with Frankfurt’s data dependency, we continue to expect the ECB’s deposit rate to settle below 2%. Consequently, German bond yields have downside, and the euro has yet to bottomed.
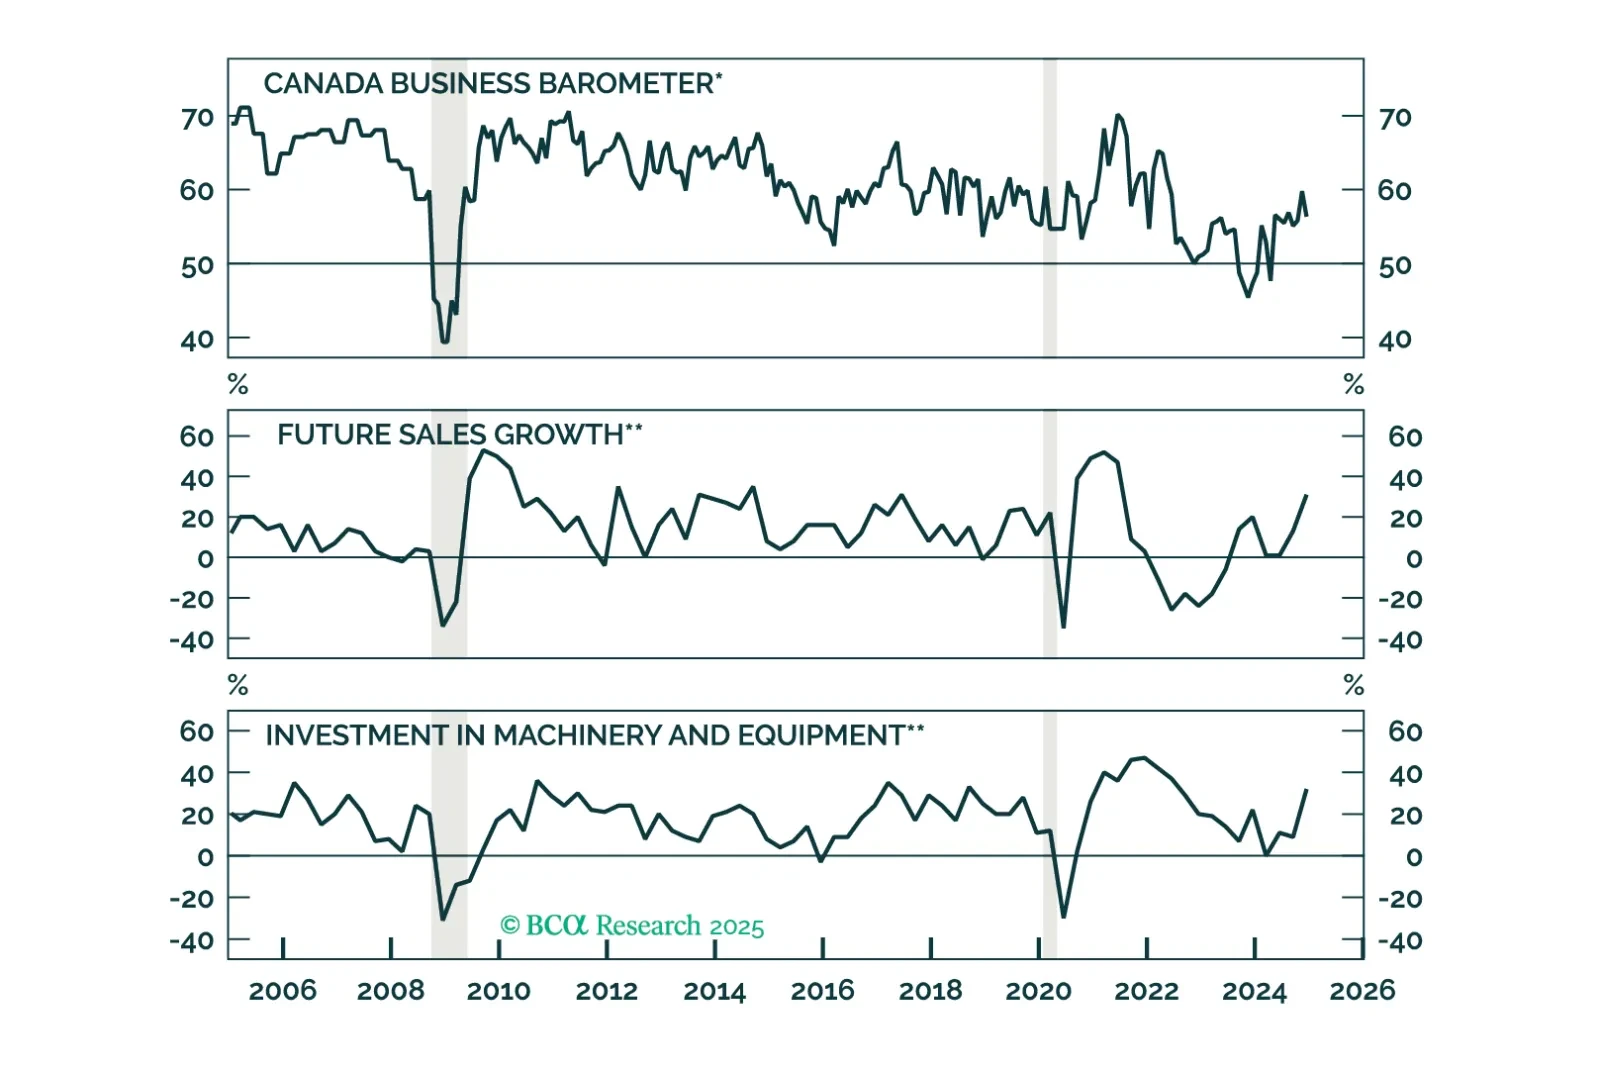
This Insight looks at what investors should do with CAD and fixed-income assets, given the rate cut by the Bank of Canada today.
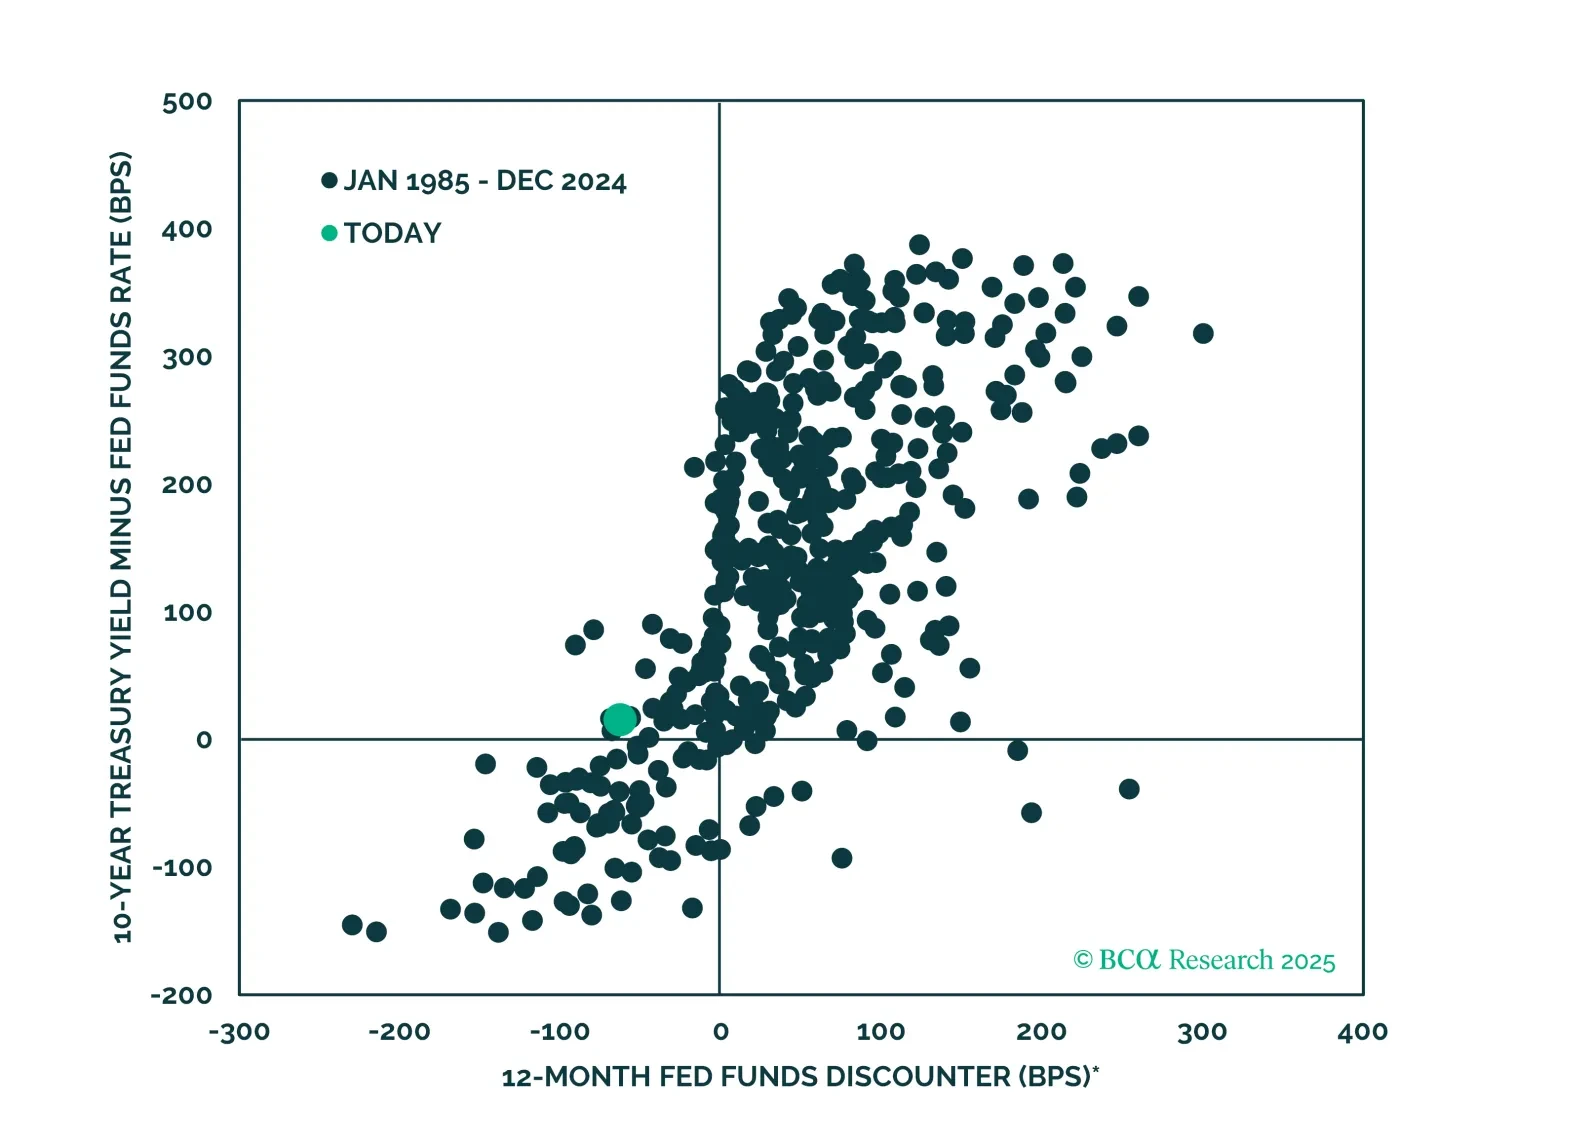
Jay Powell didn’t say much at this afternoon’s FOMC press conference, and monetary policy will continue to take a back seat to fiscal for the next few months.
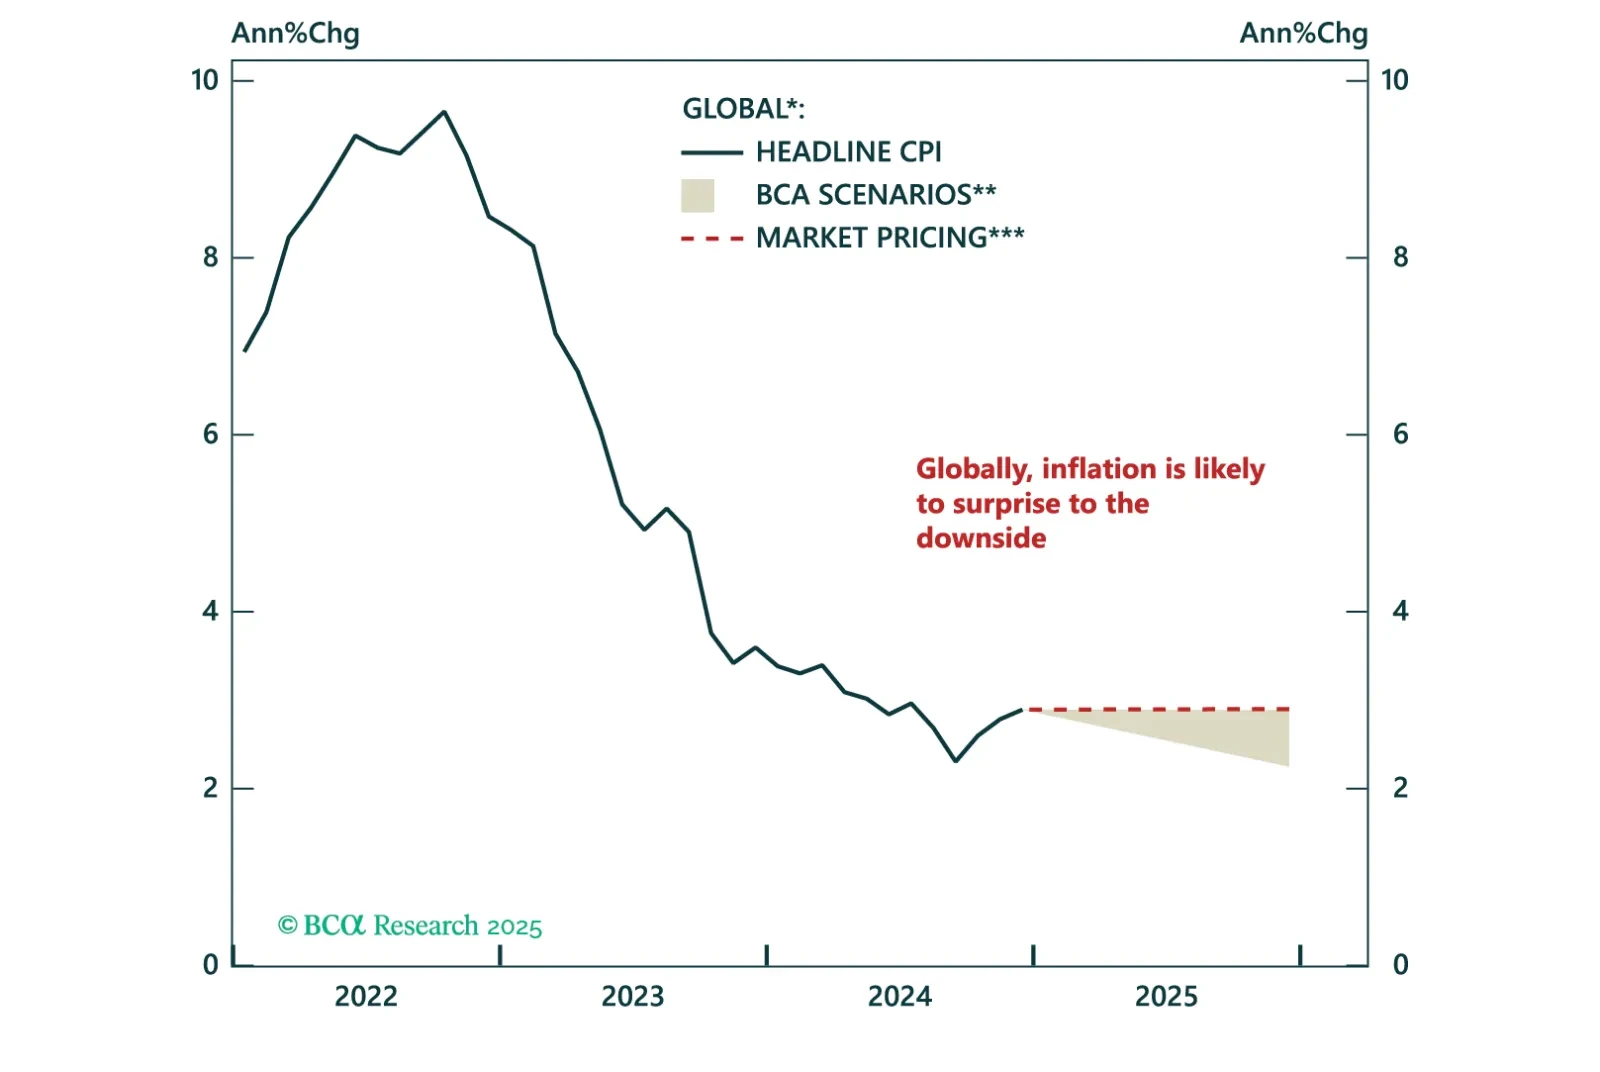
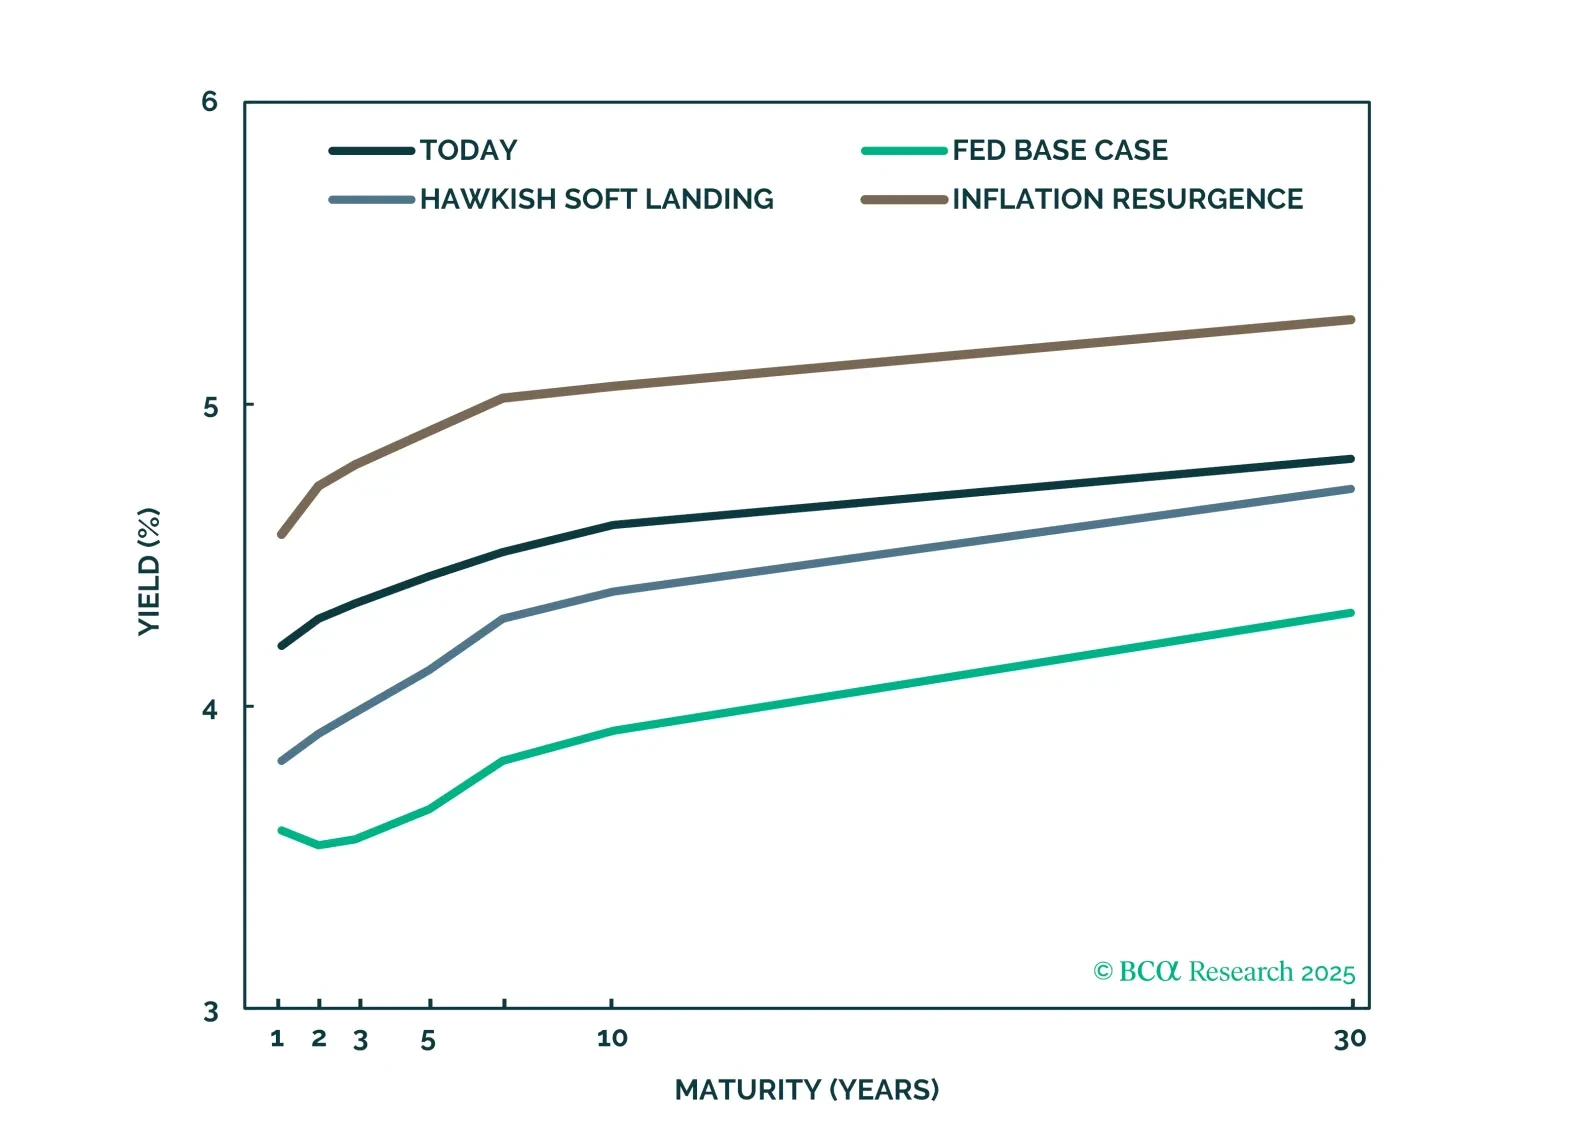
We forecast Treasury and corporate bond returns in three different economic scenarios. This report focuses on what returns might look like in a scenario where inflation is sticky and the Fed makes a hawkish pivot.

In today’s Strategy Insight, we discuss the monetary policy outlook for the Bank of Japan, following the 25-bps rate hike overnight, and what it means for JGBs and the yen.