Skip to main content
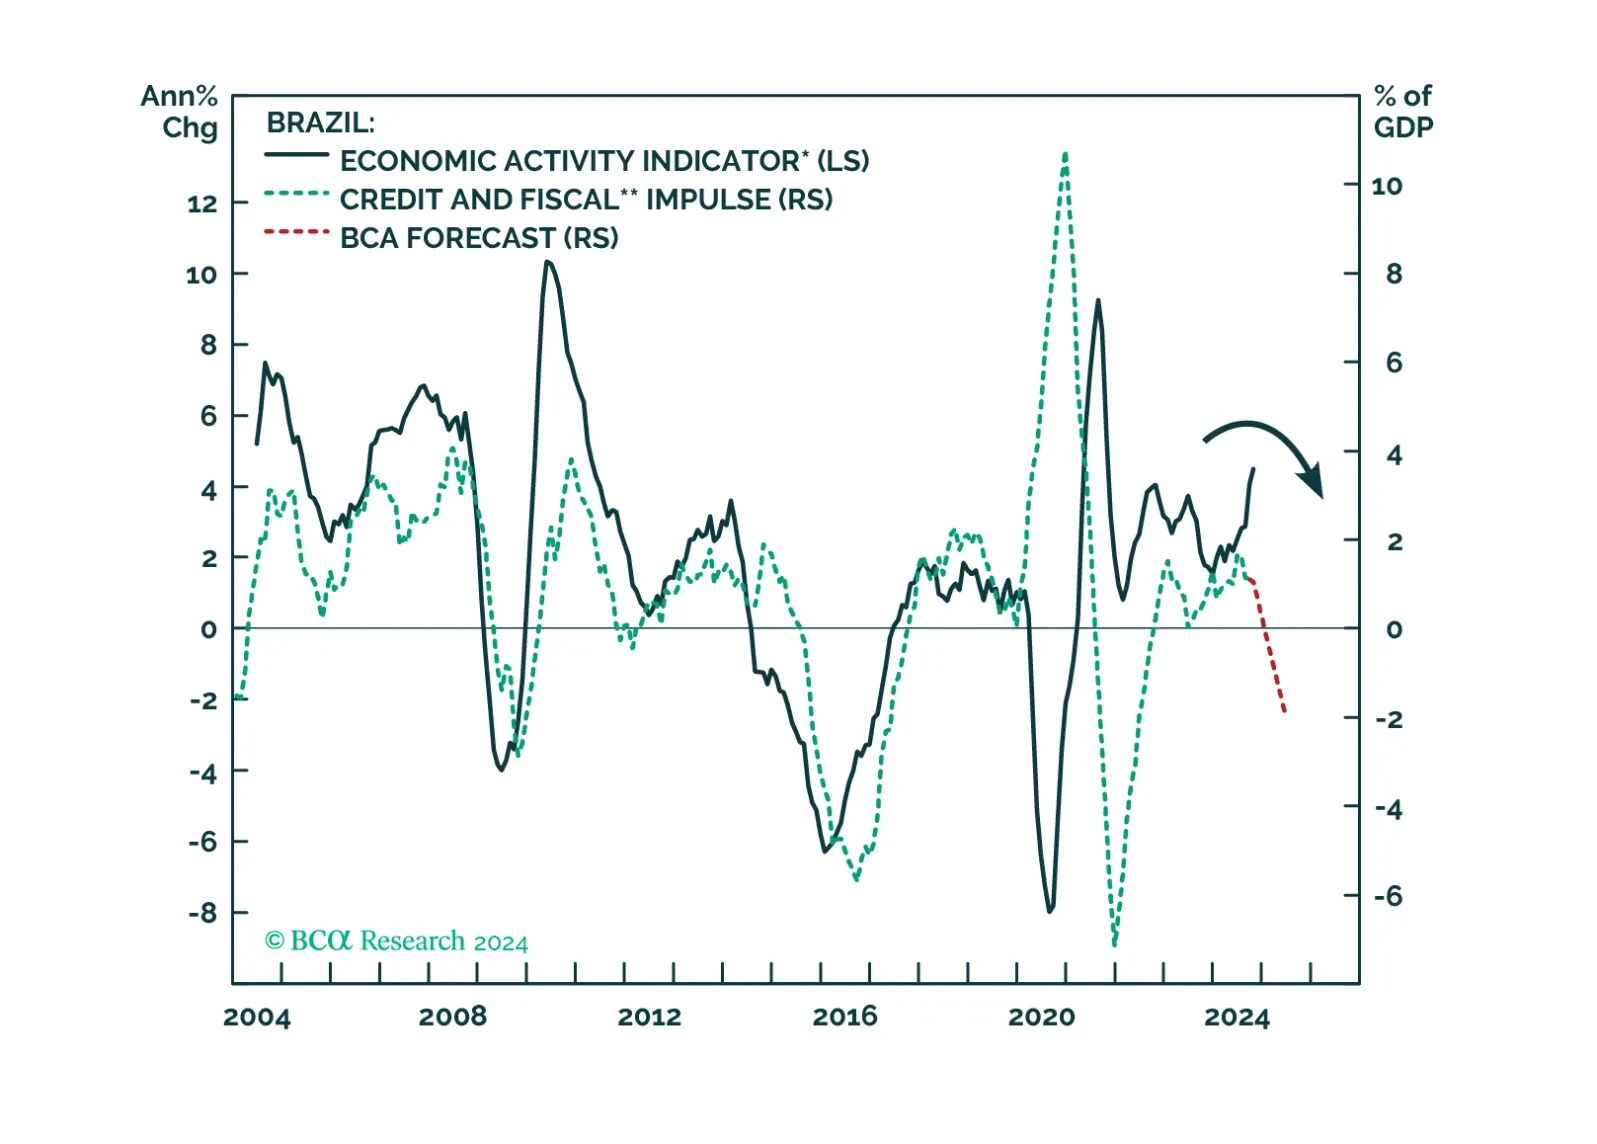
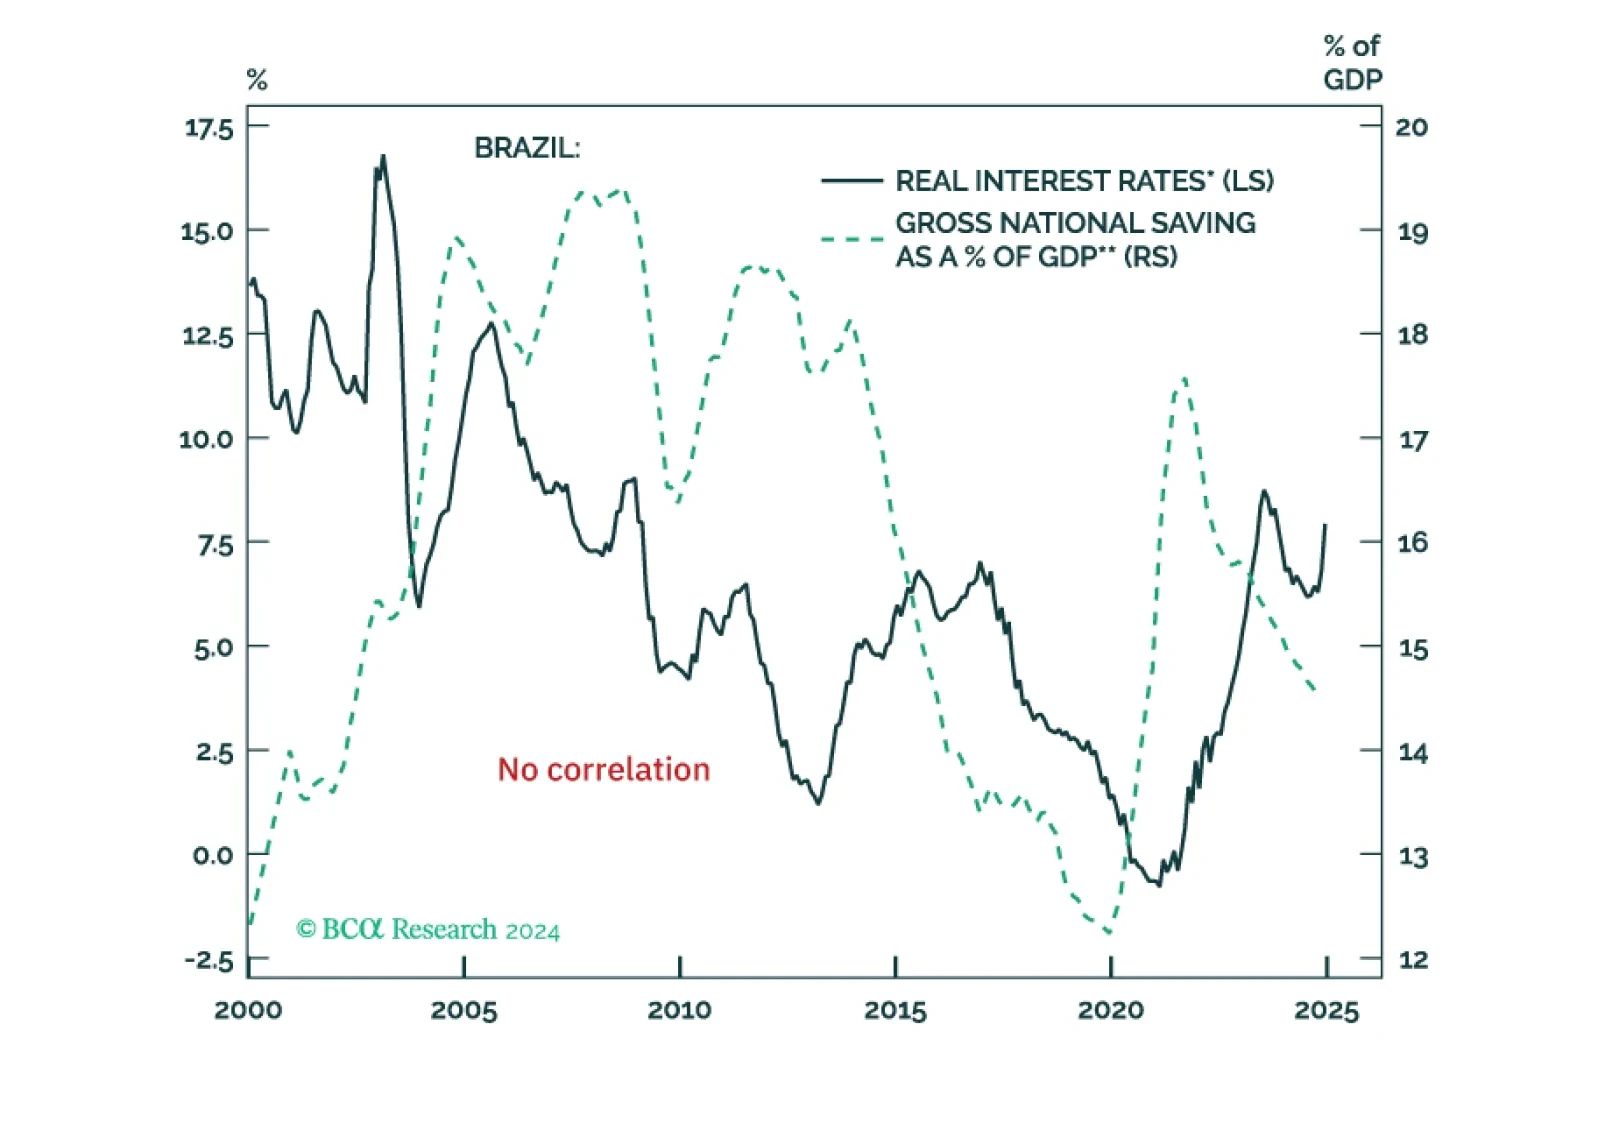
Any additional fiscal tightening and further rate hikes might serve as a band-aid, but not a cure, to Brazilian markets. The country’s risk assets and the currency will continue to face headwinds from an impending recession, a strengthening USD, weak commodity prices, and worsening public debt dynamics. Investors should fade out any relief rallies in Brazilian markets for now.
Special Report This year, our annual "What Else To Read" report focuses on academic work. We asked our research teams to share academic work that has influenced their thinking. The result is a diverse collection of papers and books that span investing, economics and geopolitics. We hope you will find something in this report that broadens your perspective and inspires your work in the year ahead. As always, we wish you all a joyful holiday season and a prosperous and healthy 2025.
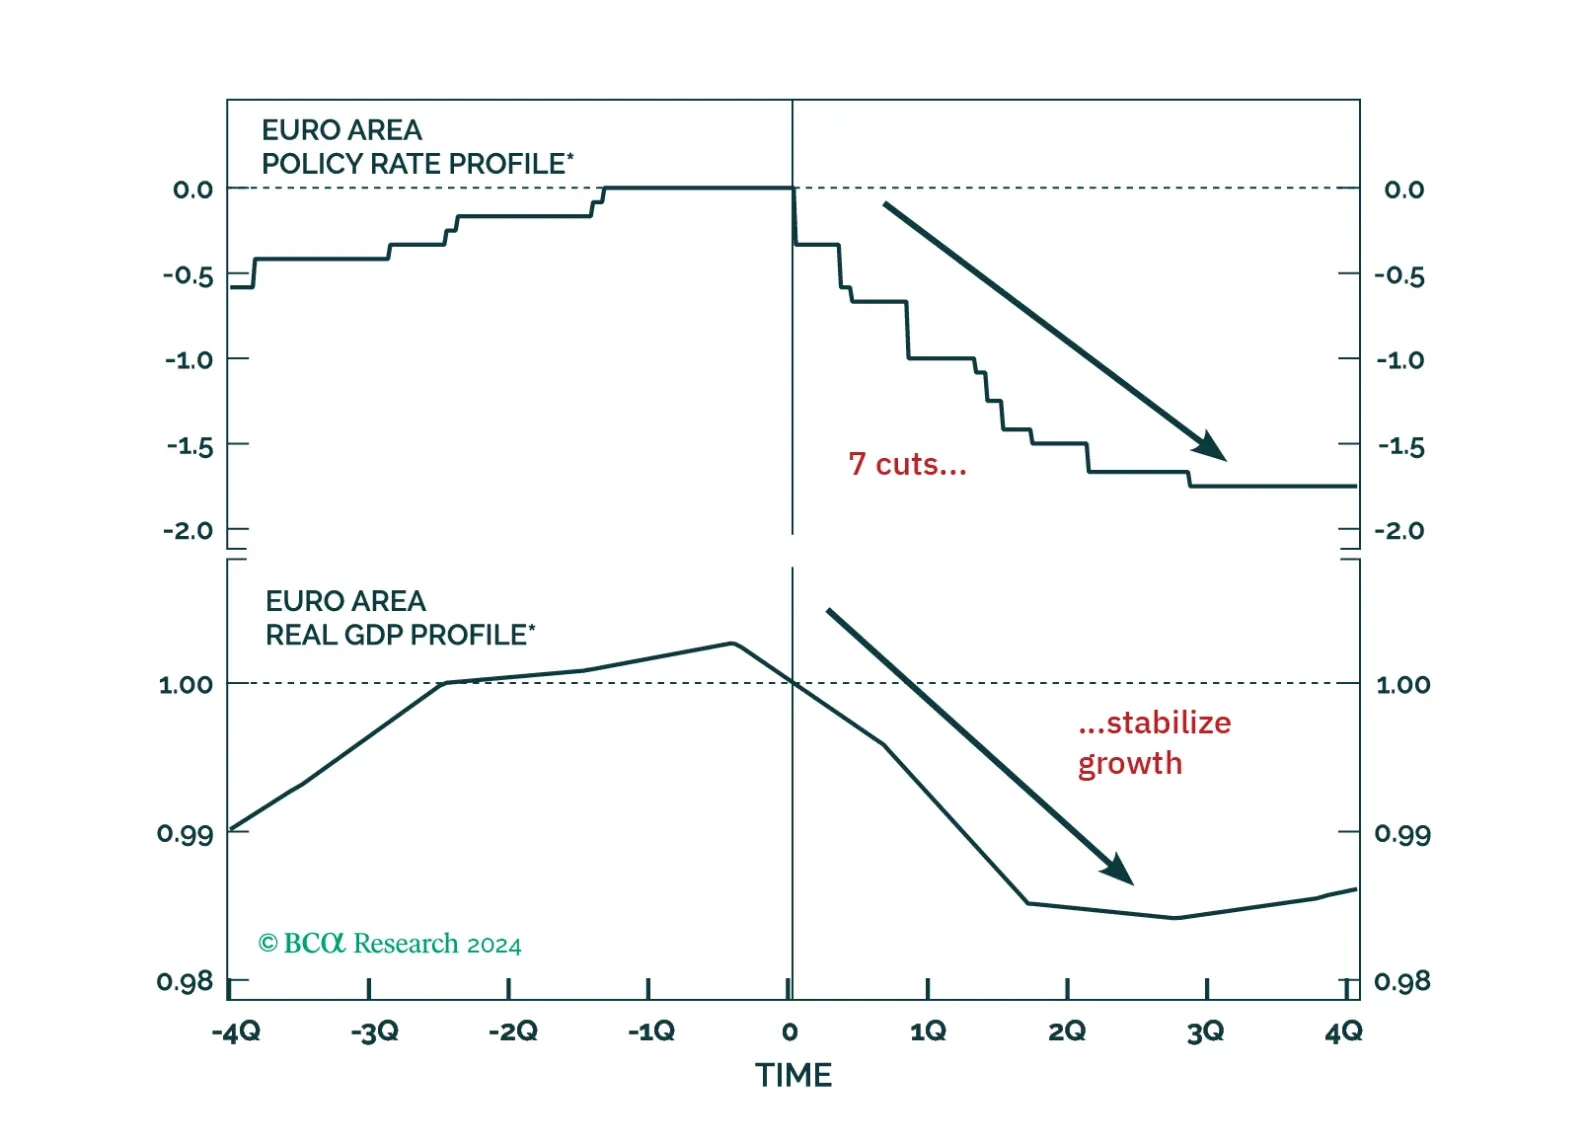
Special Report For our last publication of the year, we explore five key themes that will dominate the European macro landscape and markets next year. While the start of 2025 will be challenging for European assets, the latter part will offer some much-needed relief.
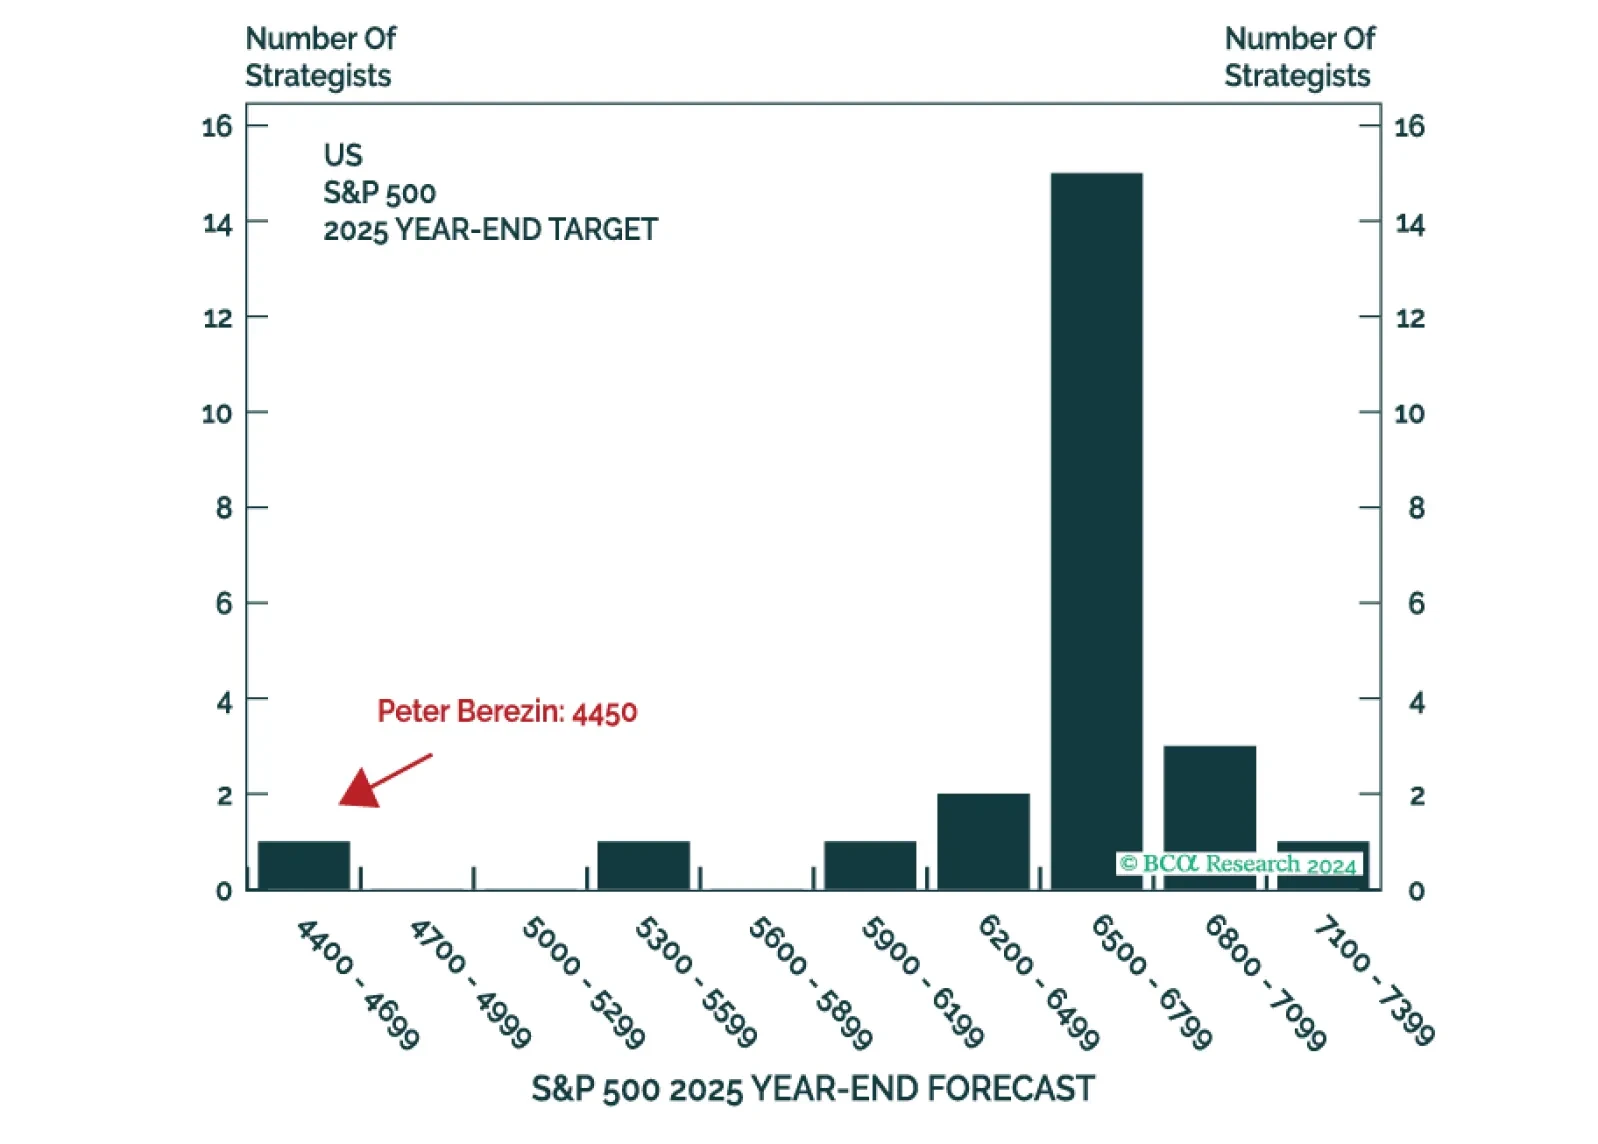
This is the time of the year when strategists are busy sending out their annual outlooks. Here on the Global Investment Strategy team, we decided to go one step further. Rather than pontificating about what could happen in 2025, we decided to harness the power of the multiverse to tell you what did happen (in at least one highly representative timeline). Next week, please join me for a Webcast on Tuesday, December 17 at 10:30 AM EST (3:30 PM GMT, 4:30 PM CET) to discuss the economy and financial markets. And with that, I will sign off for the year. I wish you and your loved ones a very happy and healthy 2025. We will be back in the first week of January with our MacroQuant Model Update.
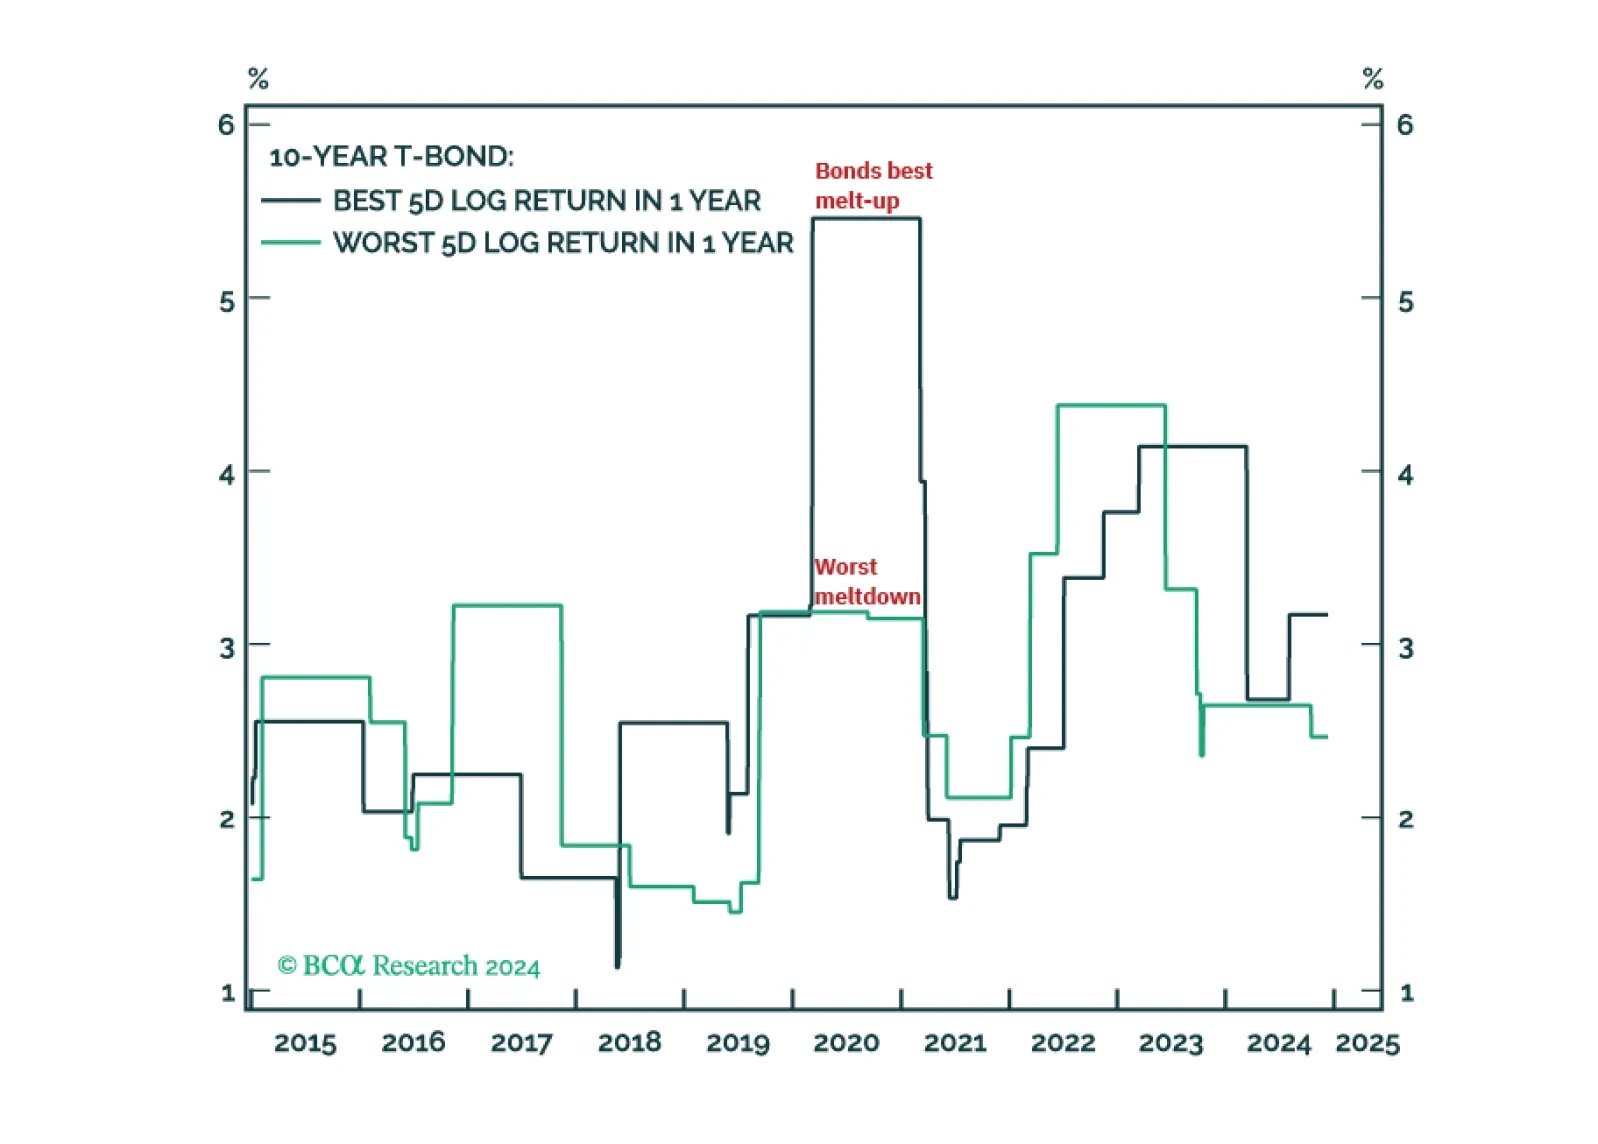
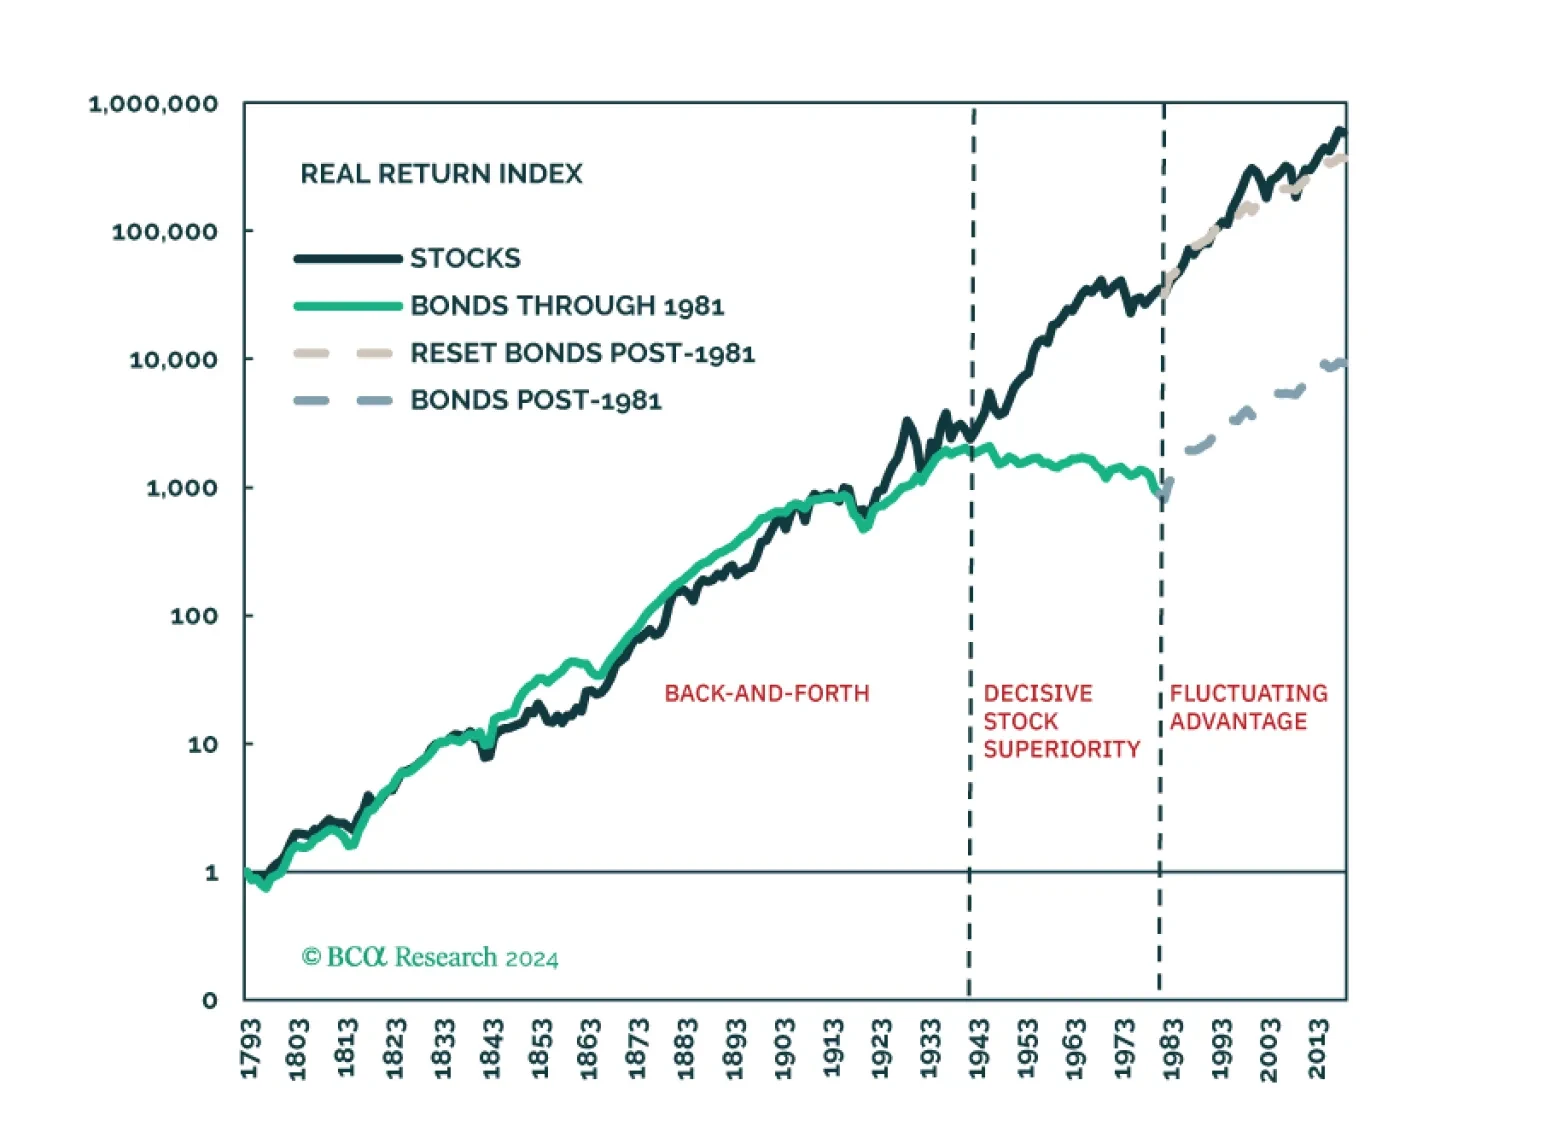
The real reason to own bonds is for their higher propensity to melt up, but anticipating those melt-ups is crucial. We list four indicators to monitor closely in 2025.
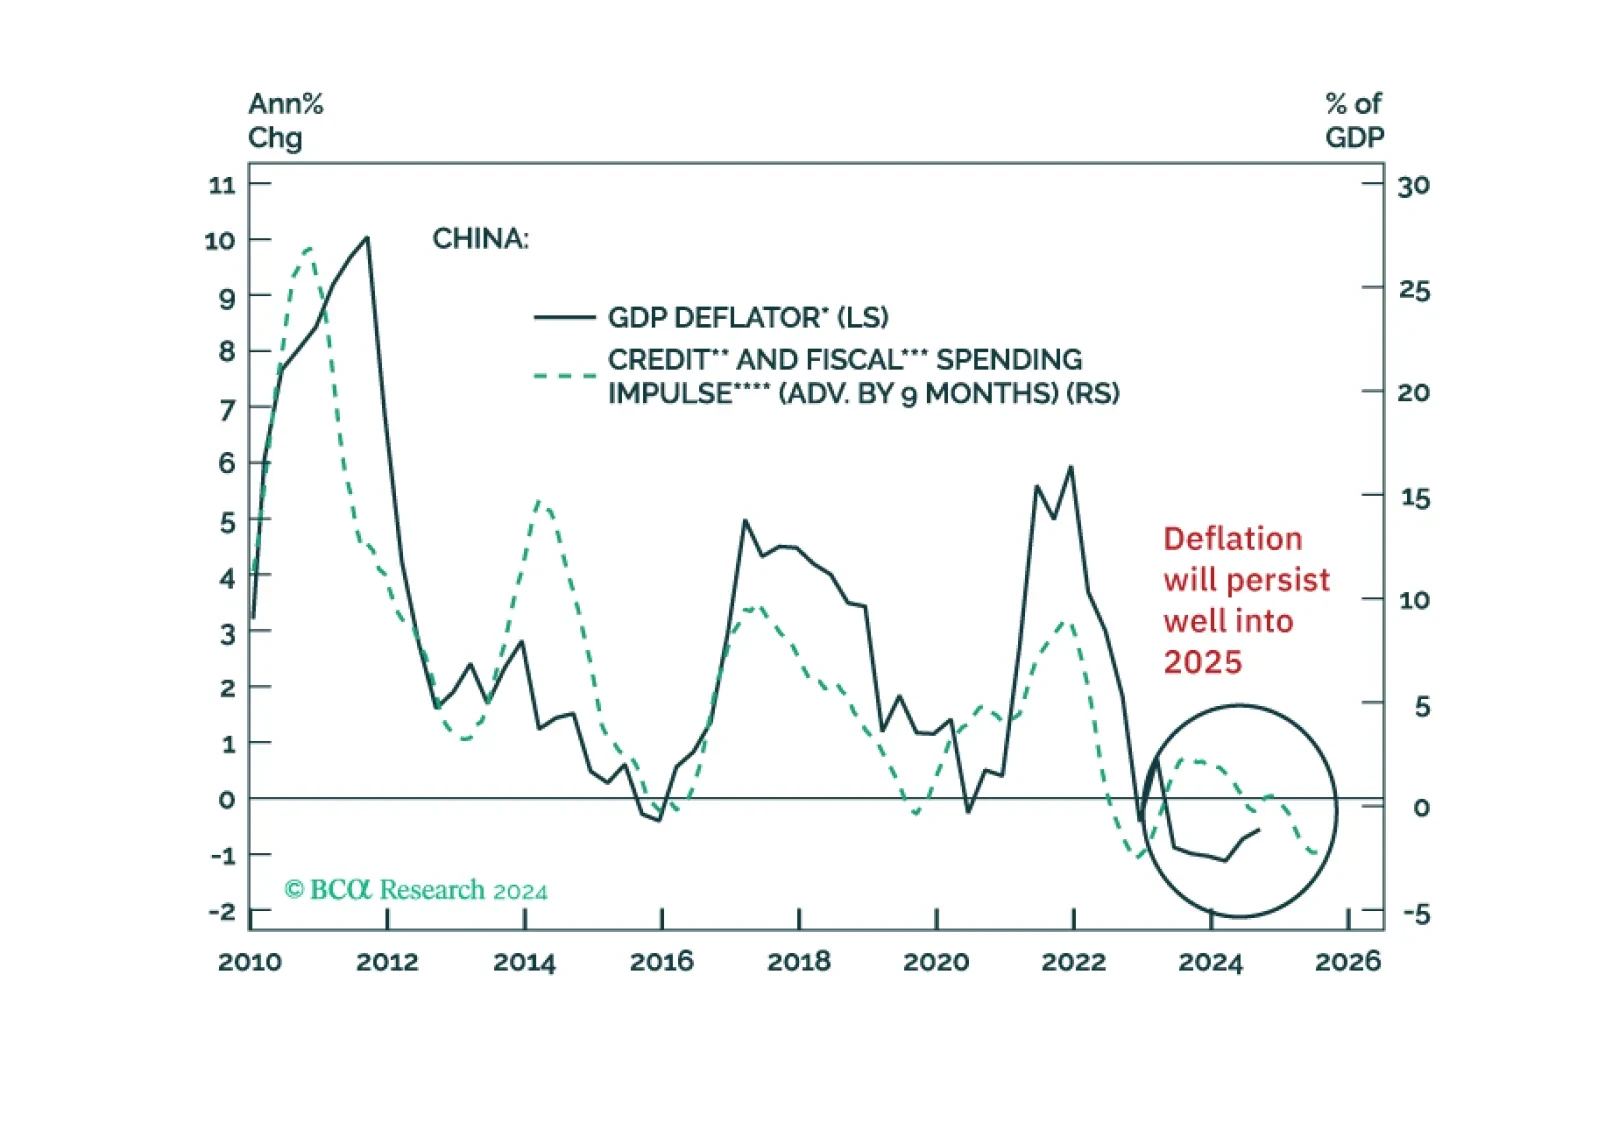
Special Report Odds are rising that the trade-weighted US dollar will roll over and depreciate sometime next year. However, USD weakness will not be due to stronger ex-US growth. Rather, economic conditions in China and Europe will continue to underwhelm. Therefore, a weaker US dollar will not boost prices of cyclical commodities. That said, when we change our view on the US dollar, we will upgrade our stance on EM financial markets – especially EM domestic bonds.
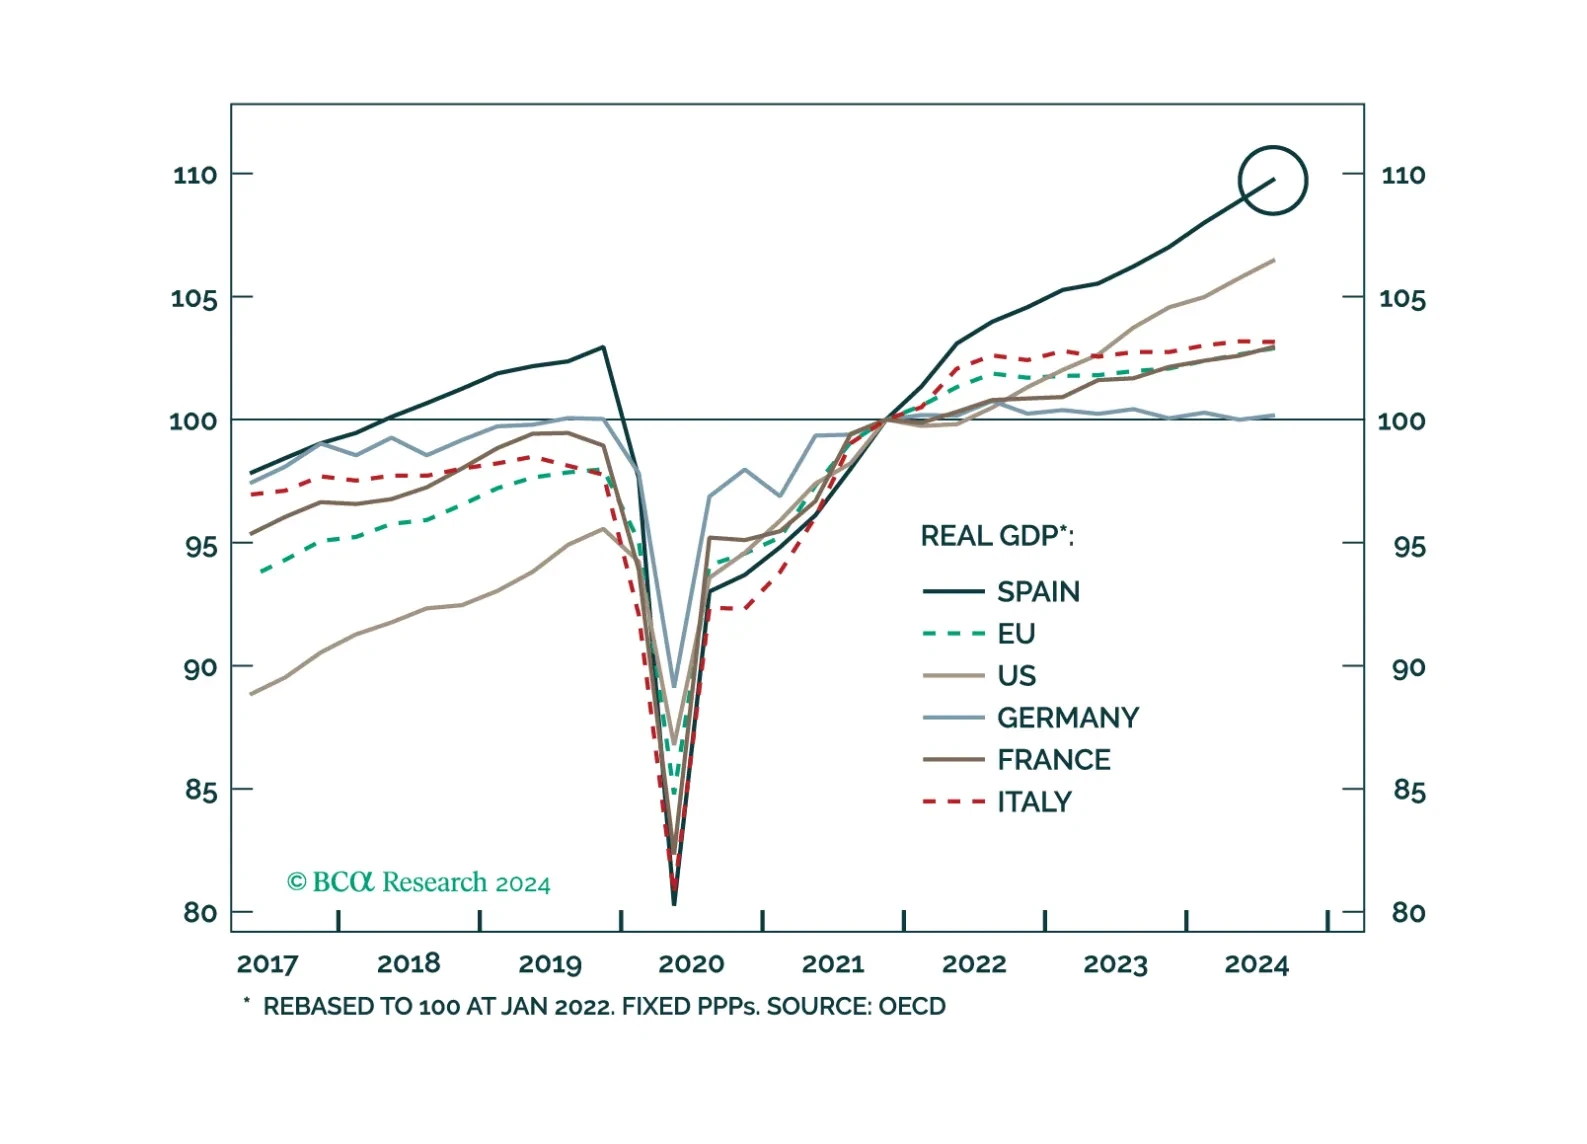
Special Report Spain has outperformed most developed markets since 2022 – real economic output and risk assets alike. Can it last?