Explore CoreMacro
CoreMacro | Emerging Markets
Emerging Markets research - including in-depth country reports. Typically published four times a month.
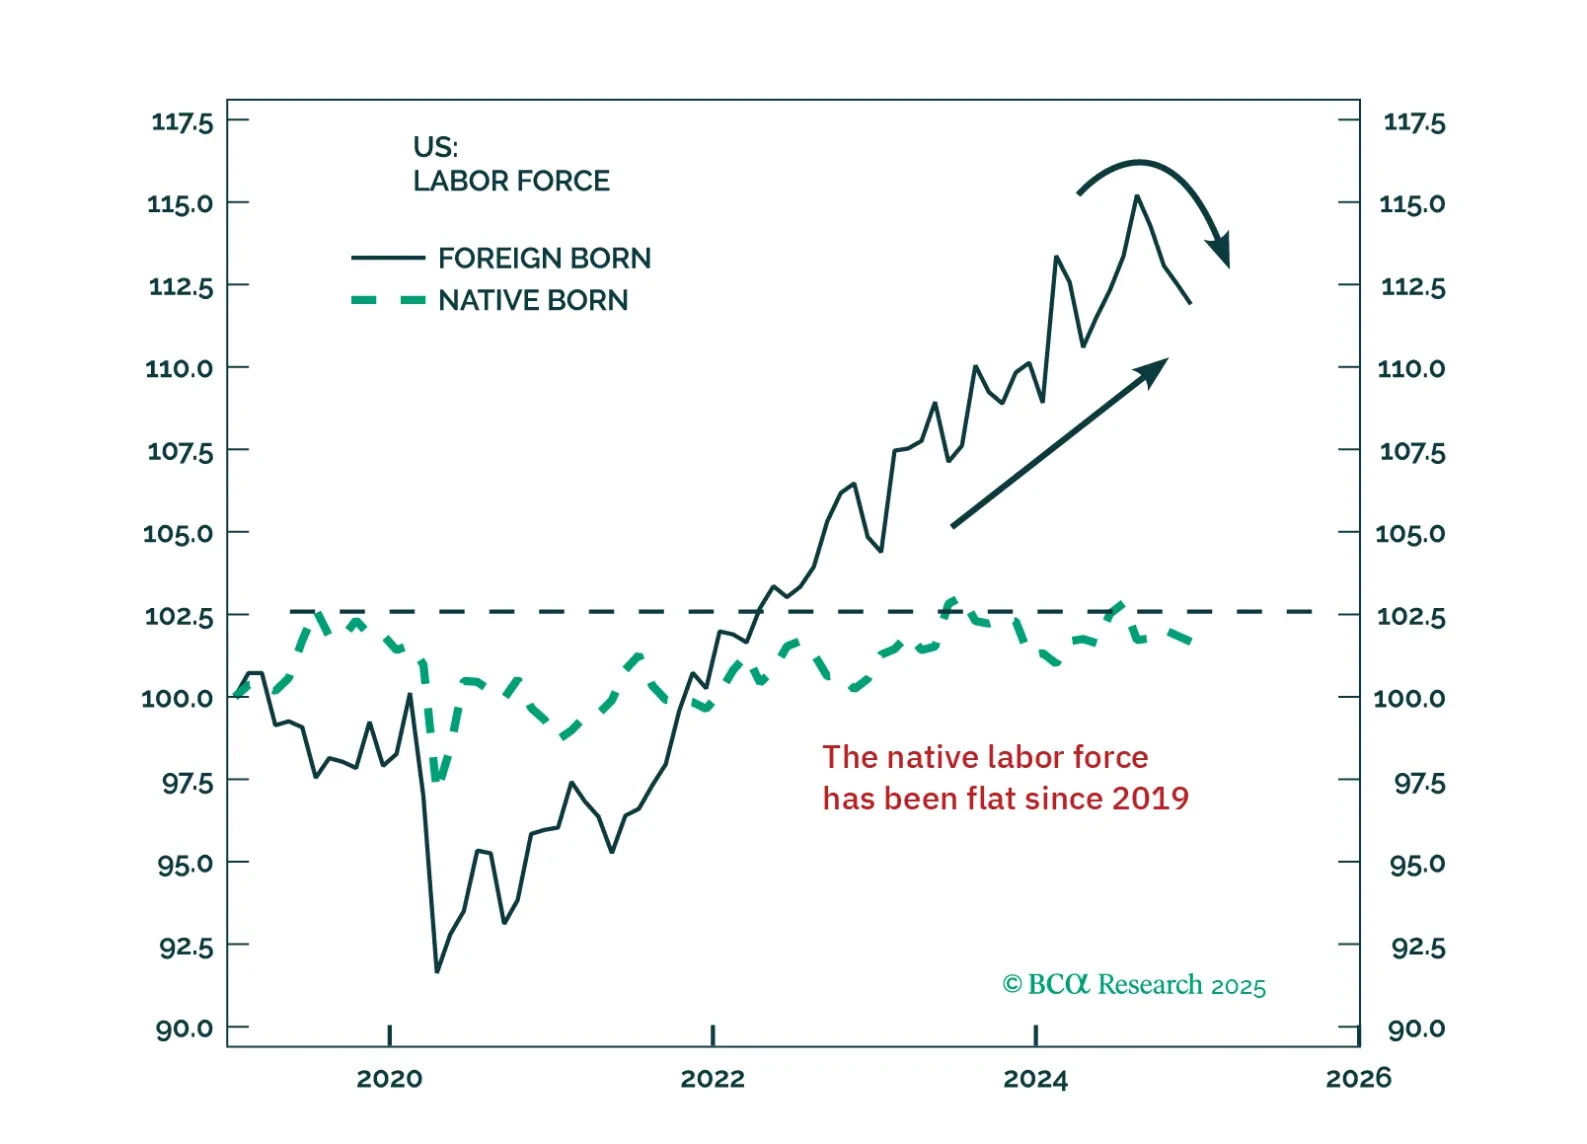
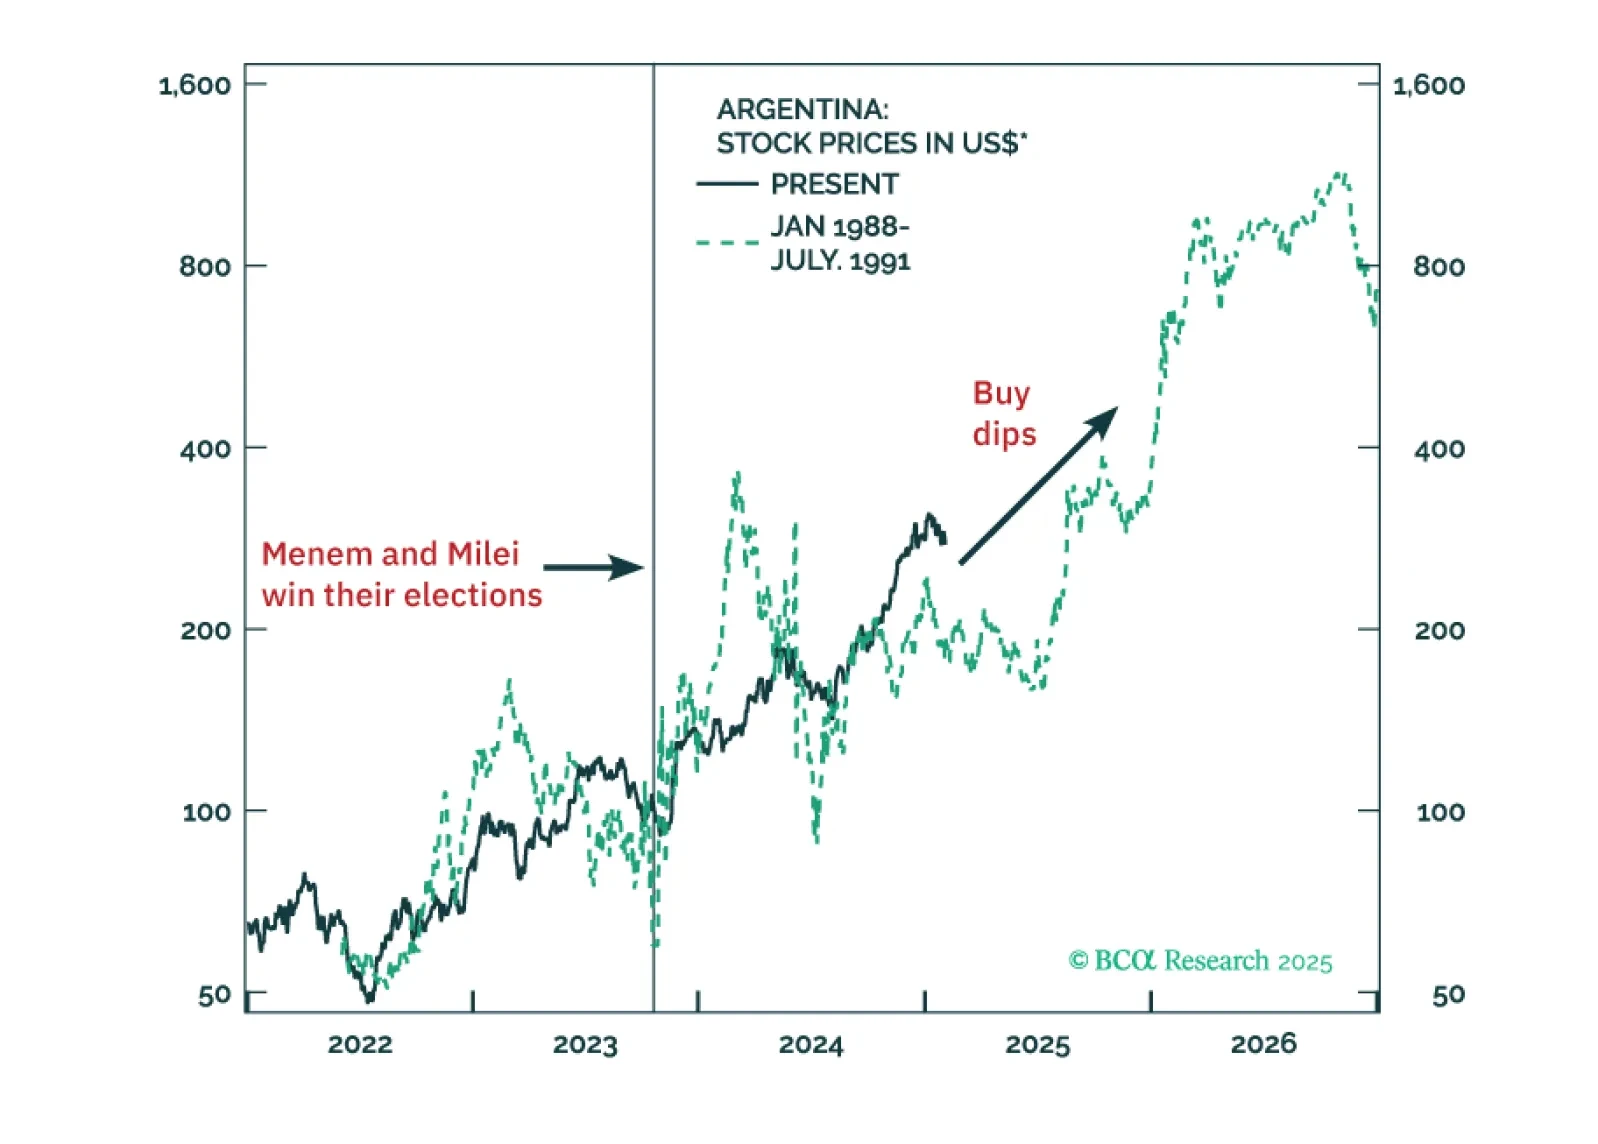
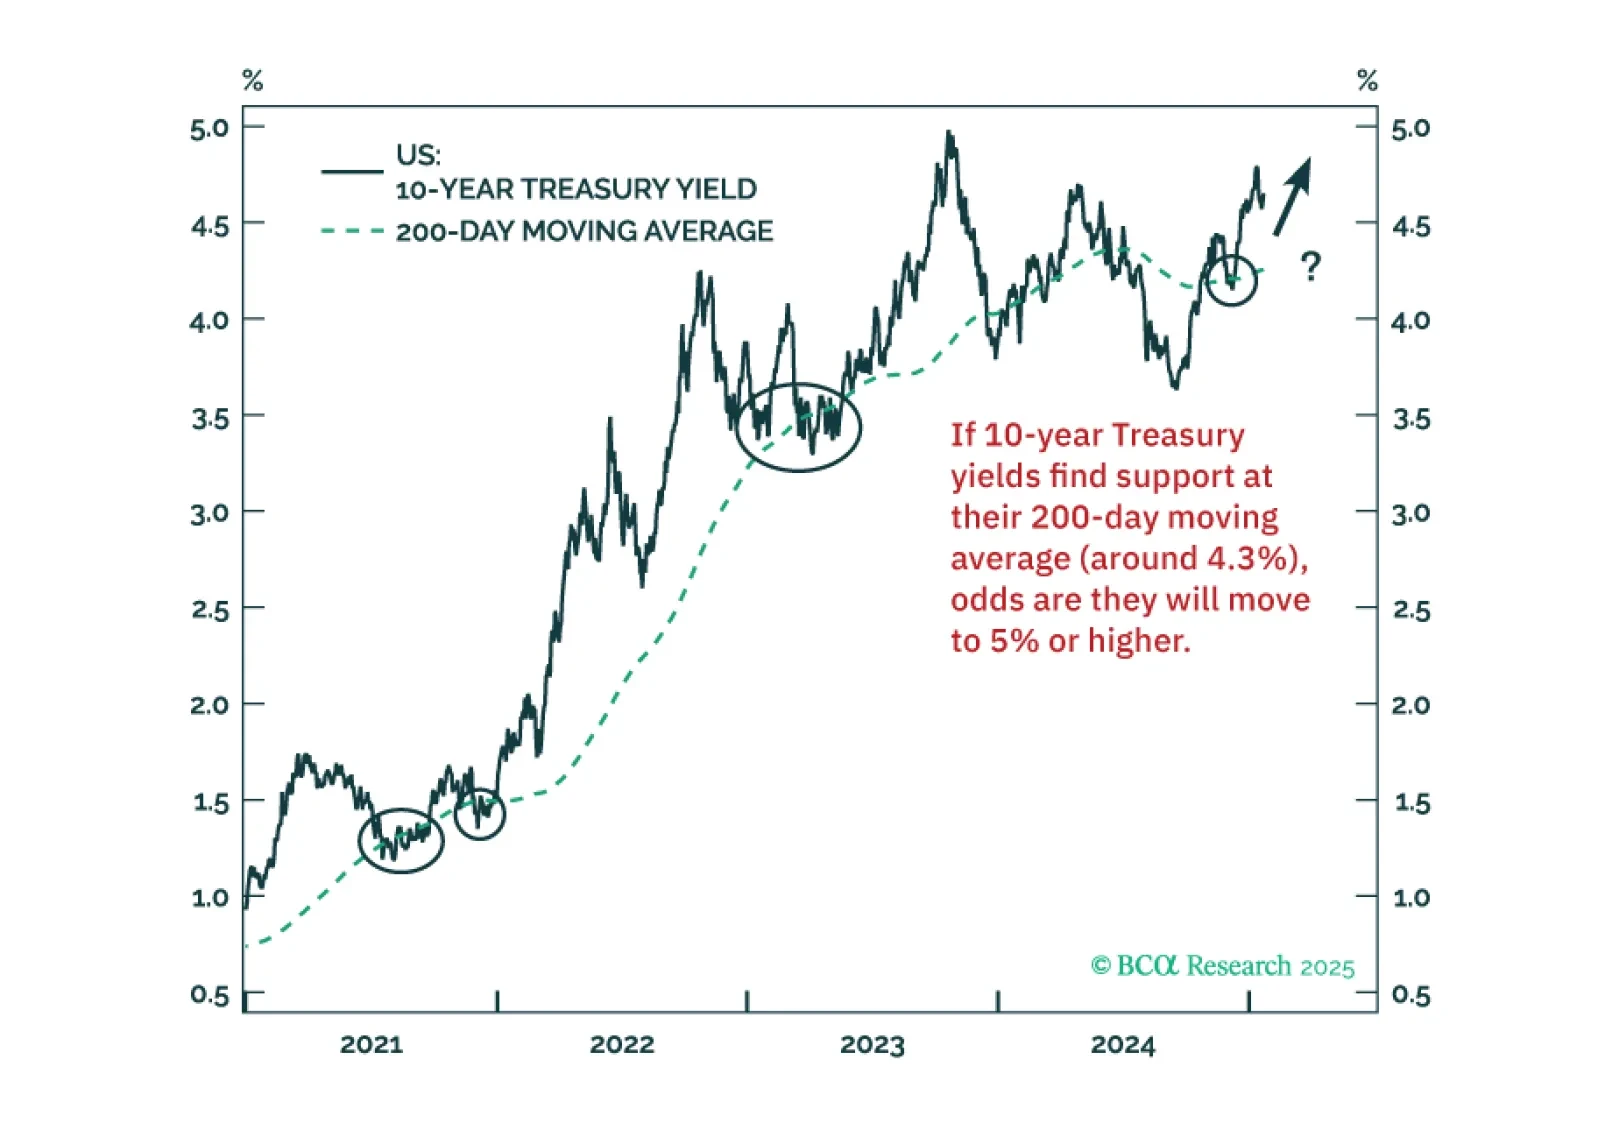
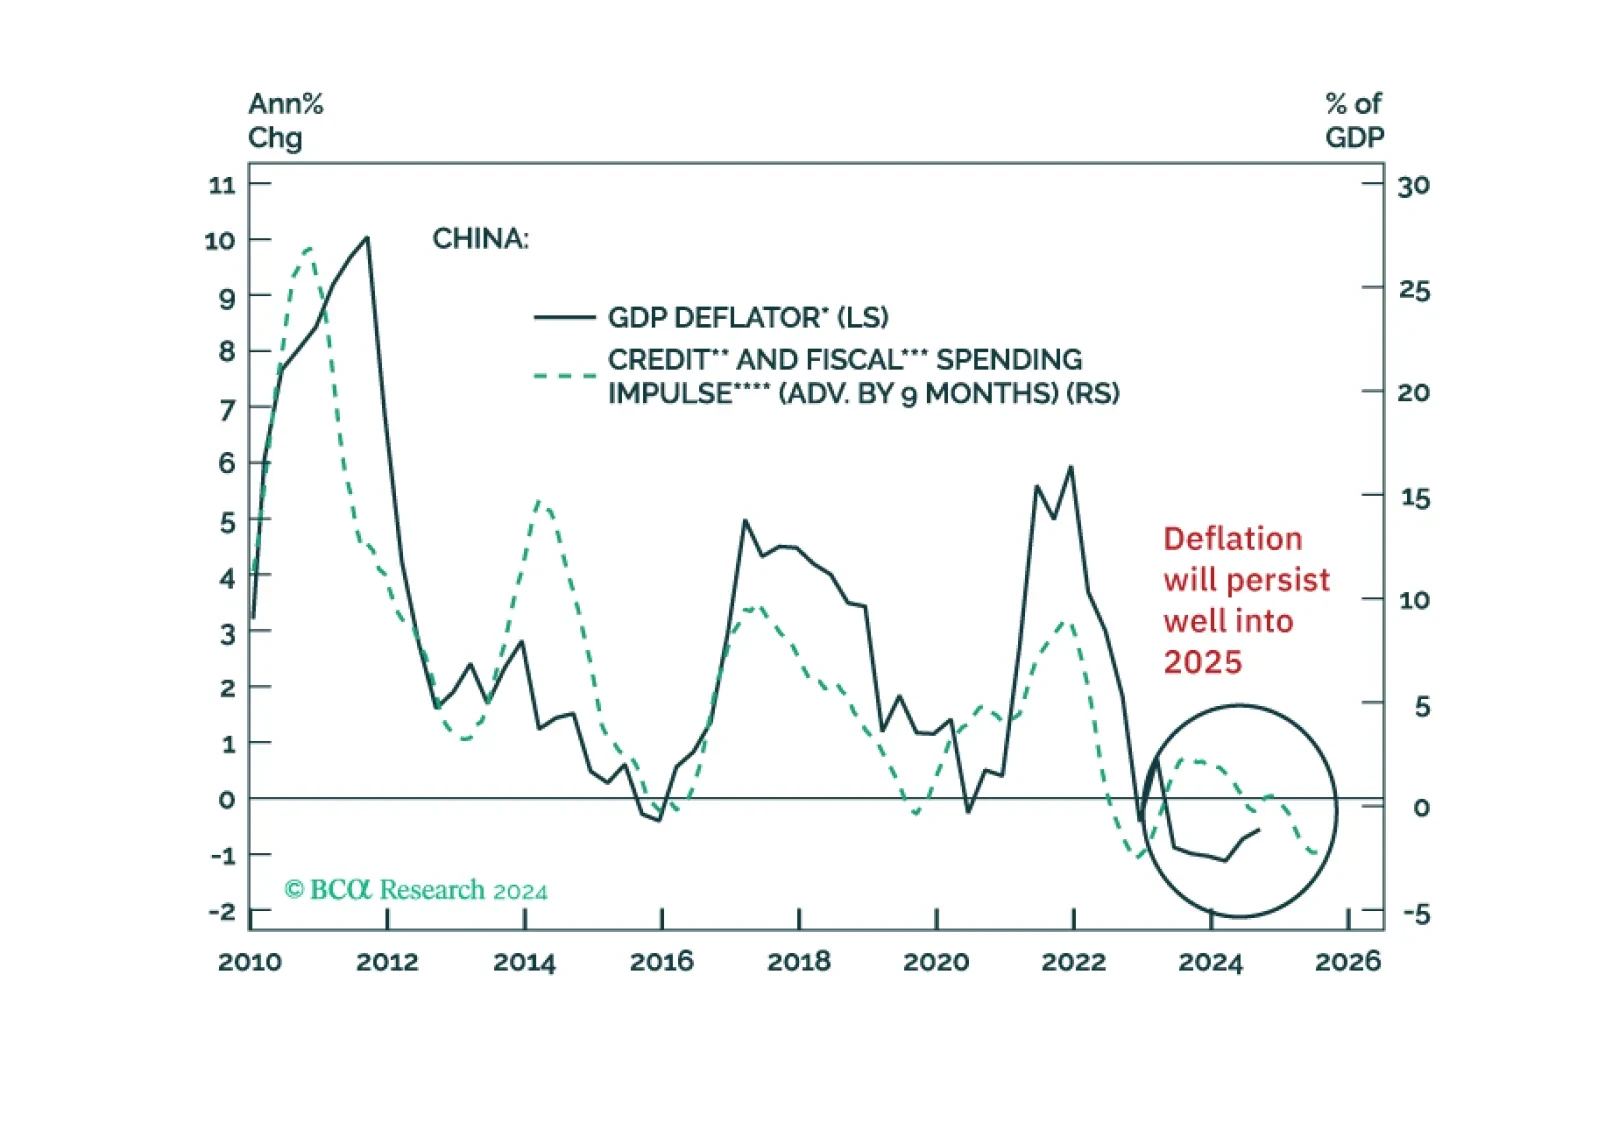
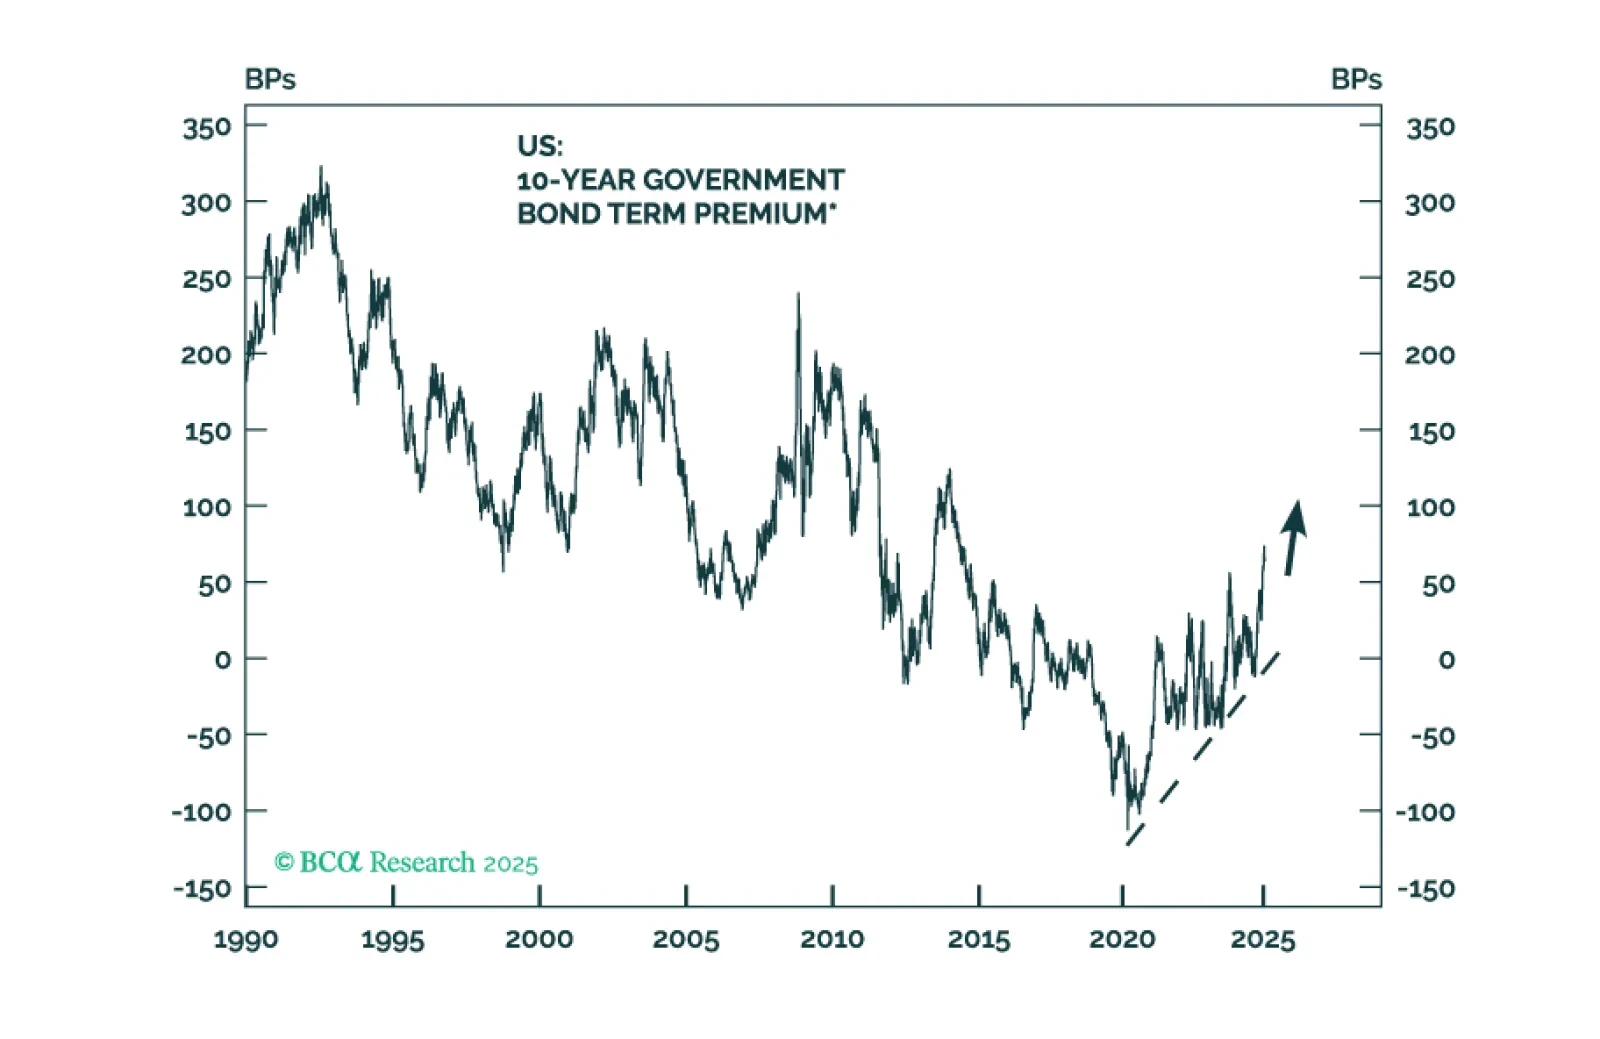
Last week, I visited clients in Europe. My recent report on Bessenomics – the name we gave to US Treasury Secretary Scott Bessent's policy mix – was often the focal point of the discussions. We will continue discussing Bessenomics, its progress, and its investment implications in forthcoming reports. In the meantime, we are sending my chart pack used during this trip as a Charts That Matter publication – a chart-based report. It covers the following areas: China, Bessenomics, US fixed income, global currencies, EM credit markets, the global ex-US business cycle, EM and US equities, and an EM local bond relative value matrix. In my opinion, the most important variable in global financial markets are US long-term Treasury yields. If they hold above their 200-day moving average, odds are that new highs lie ahead. My hunch is that 10-year yields will break above 5%. When and as this happens, global risk assets will sell off considerably.
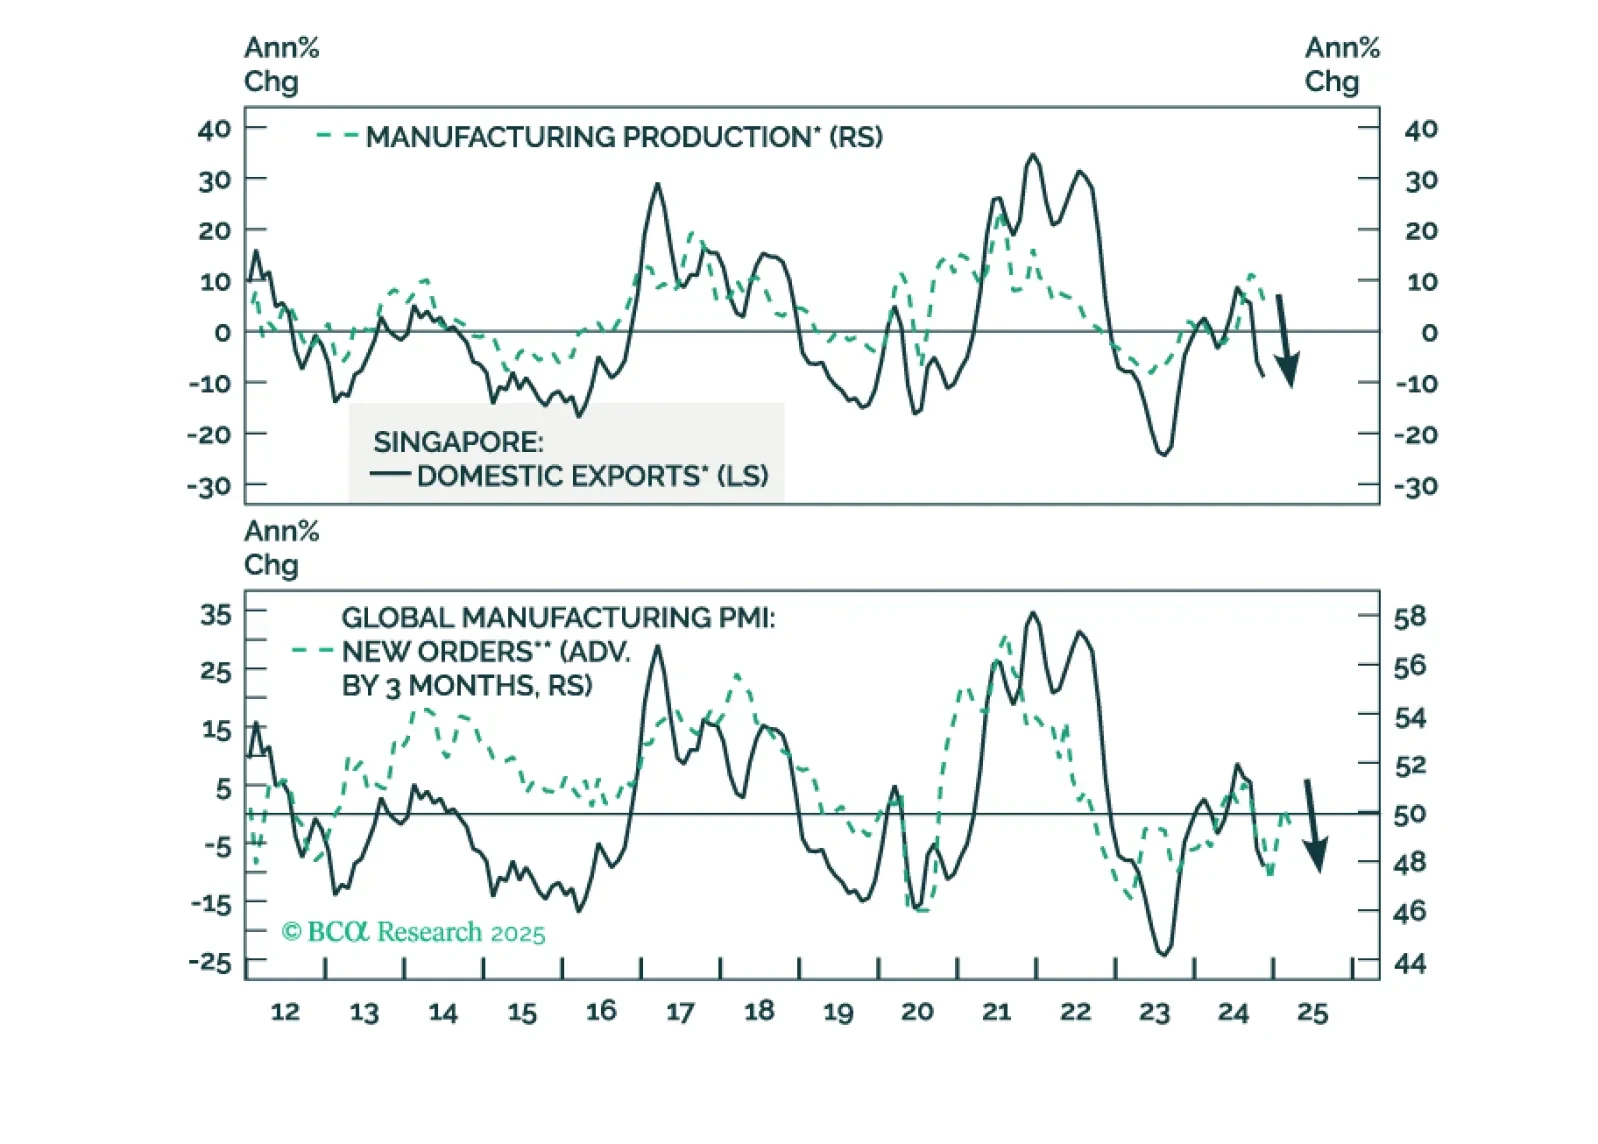
Can Singapore stocks continue the bull run into 2025? What does the city-state’s manufacturing and export outlook foretell? Is the Singapore dollar still competitive? See our analysis and investment recommendations in today’s report.
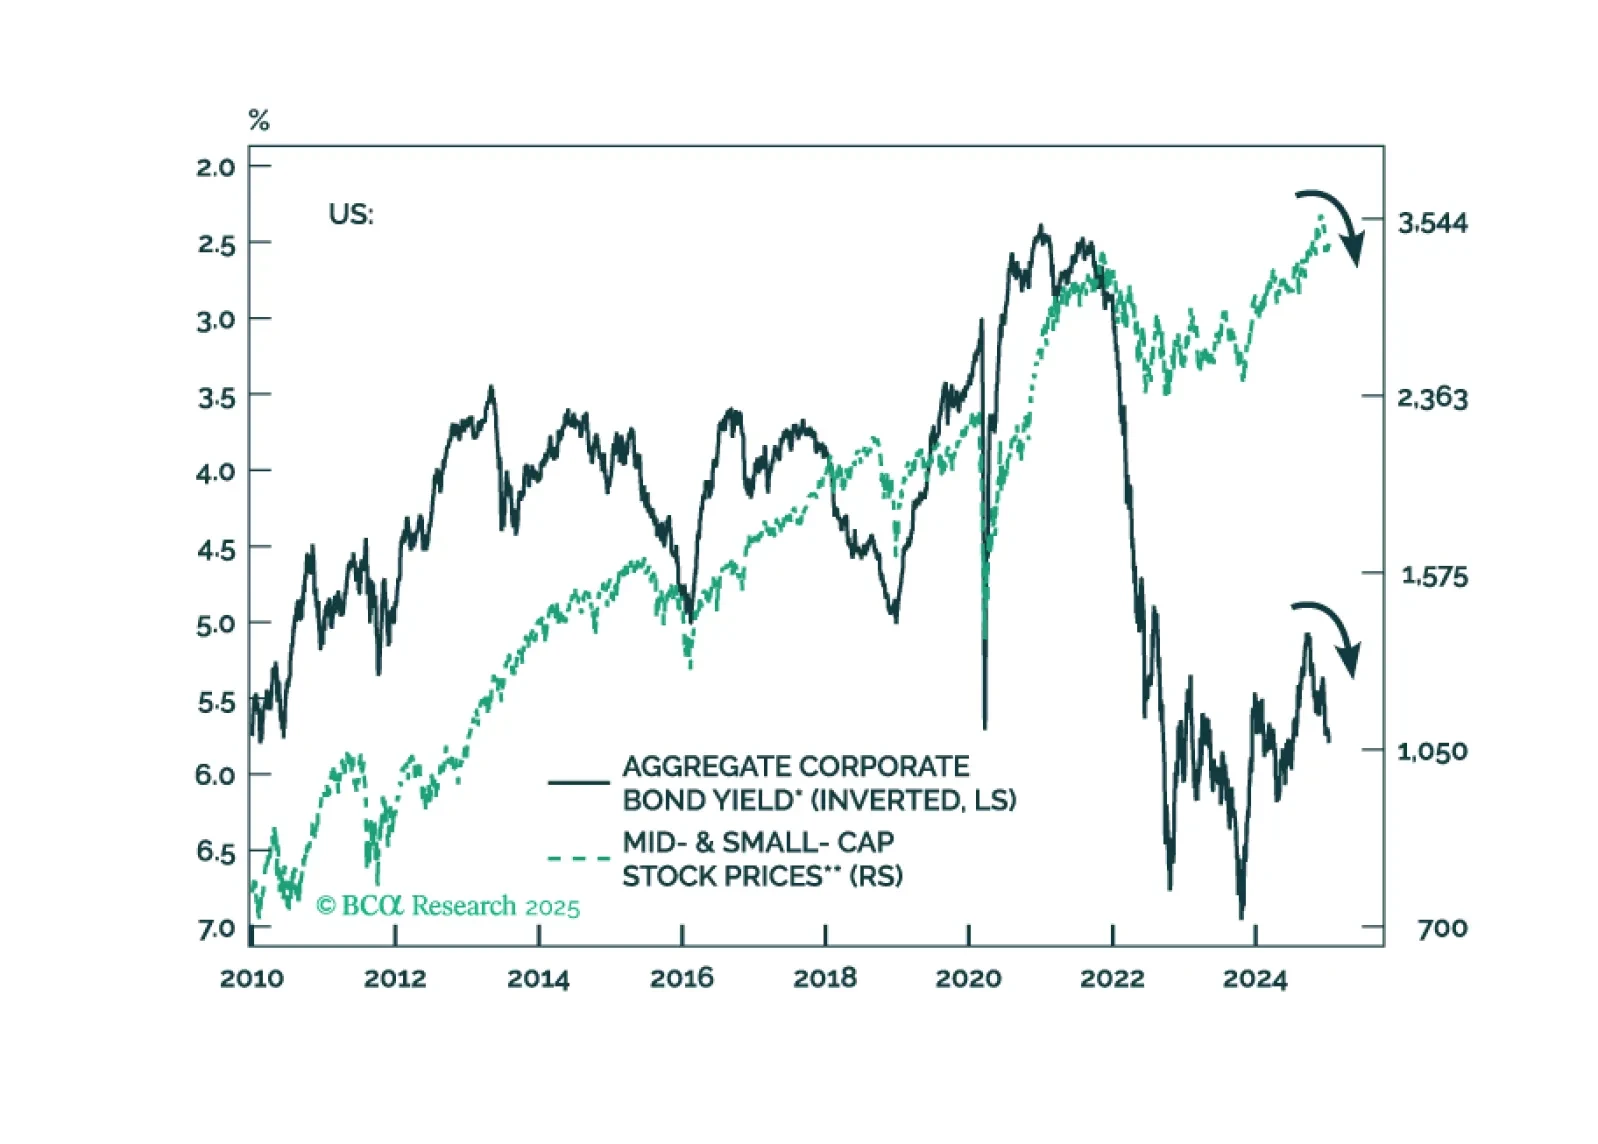
US bond yields will move higher, unleashing a storm in global financial markets. In the US, rising corporate bond yields will produce a selloff in share prices. In Mainstream EM, rising domestic and USD bond yields will weigh on share prices.
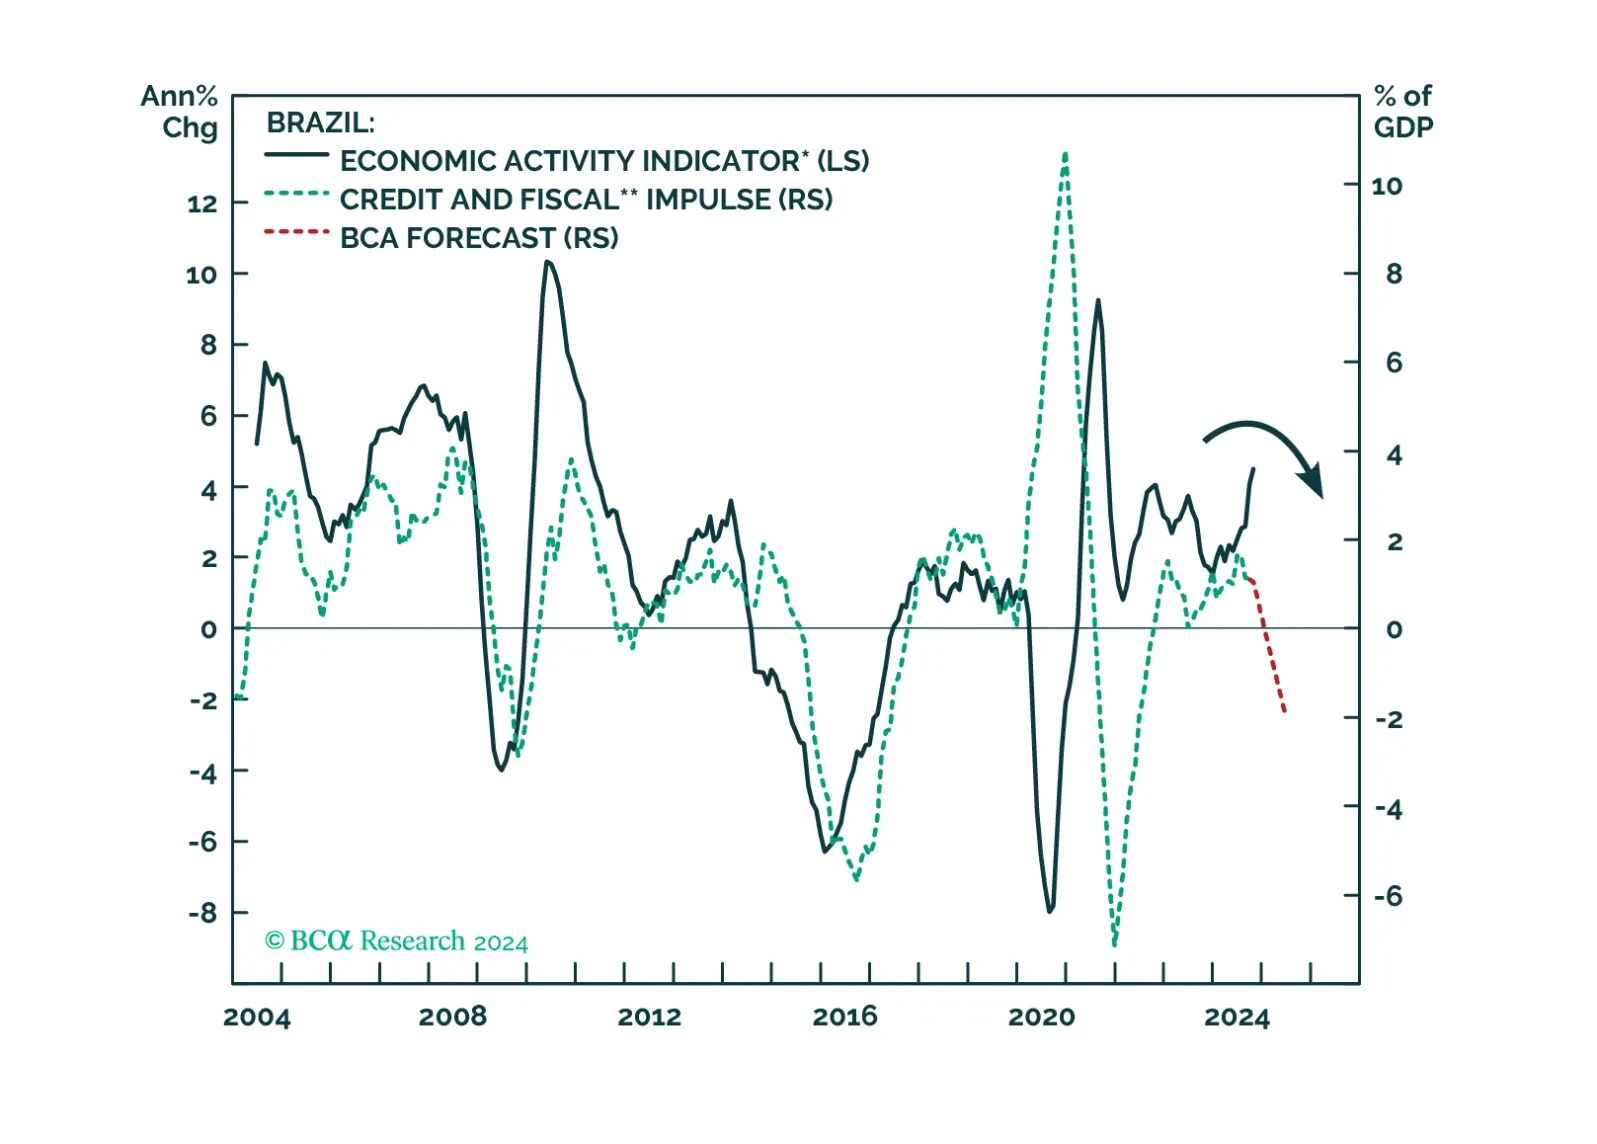
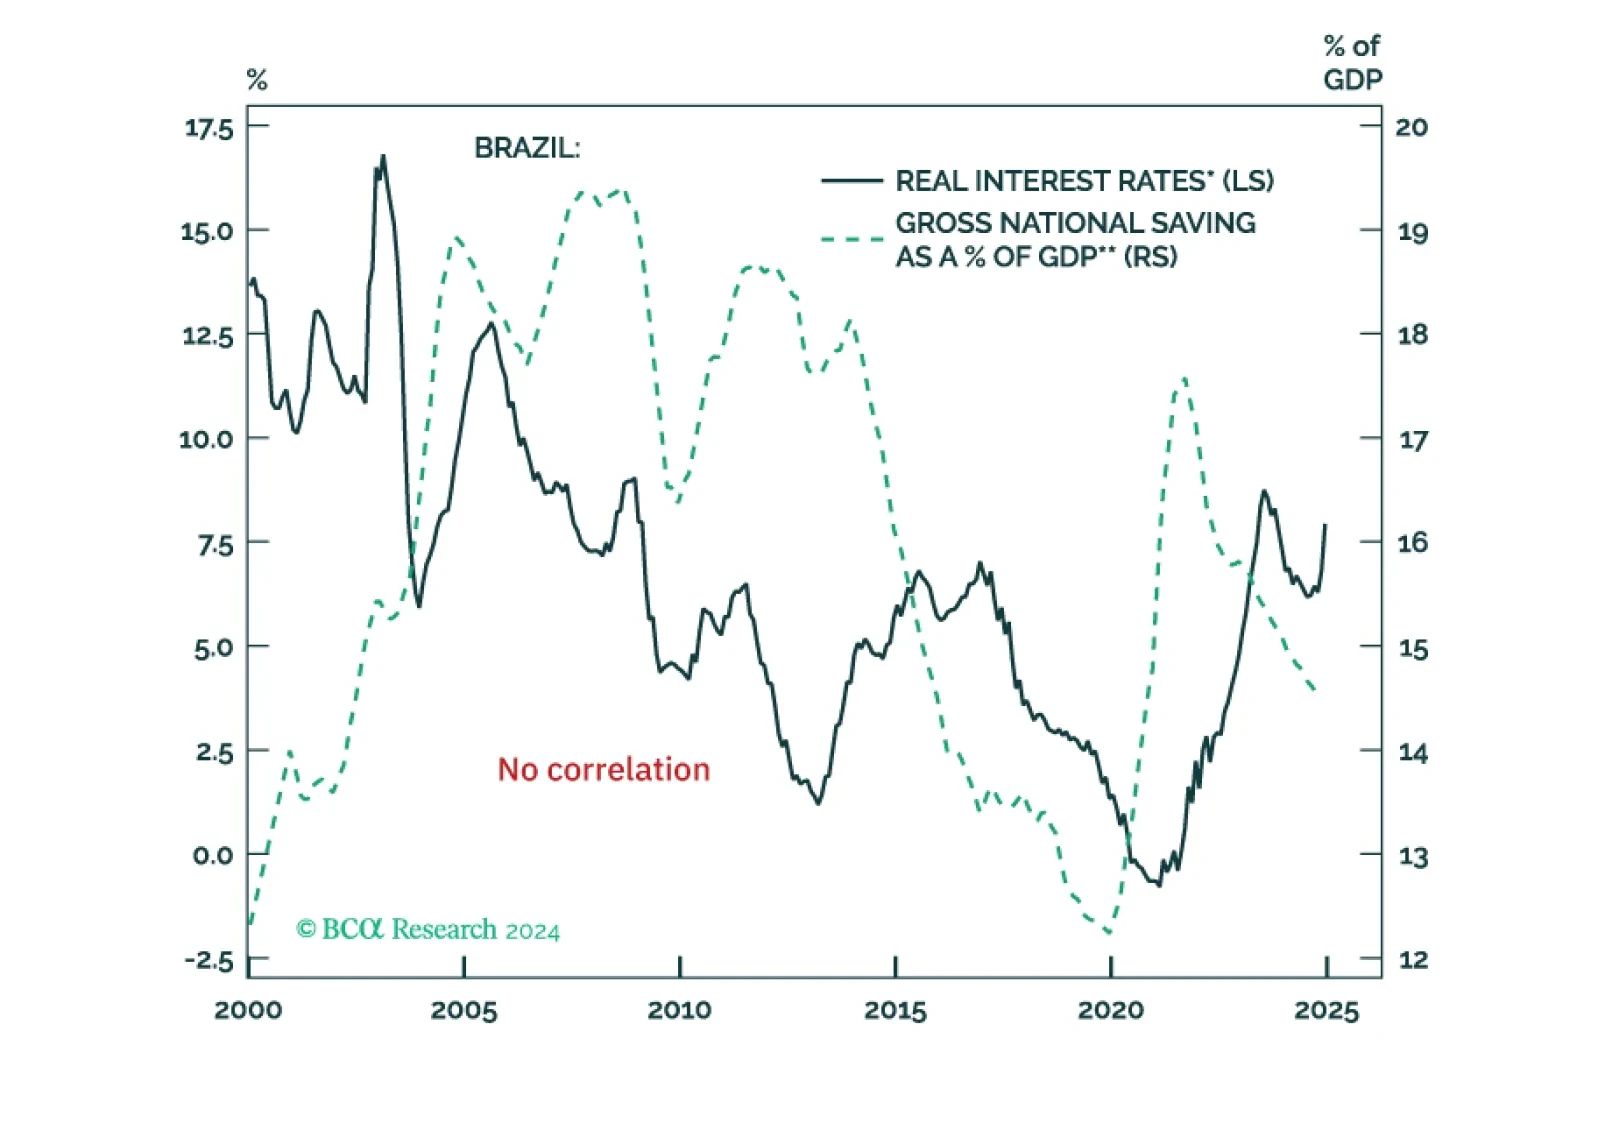
Any additional fiscal tightening and further rate hikes might serve as a band-aid, but not a cure, to Brazilian markets. The country’s risk assets and the currency will continue to face headwinds from an impending recession, a strengthening USD, weak commodity prices, and worsening public debt dynamics. Investors should fade out any relief rallies in Brazilian markets for now.