Monetary
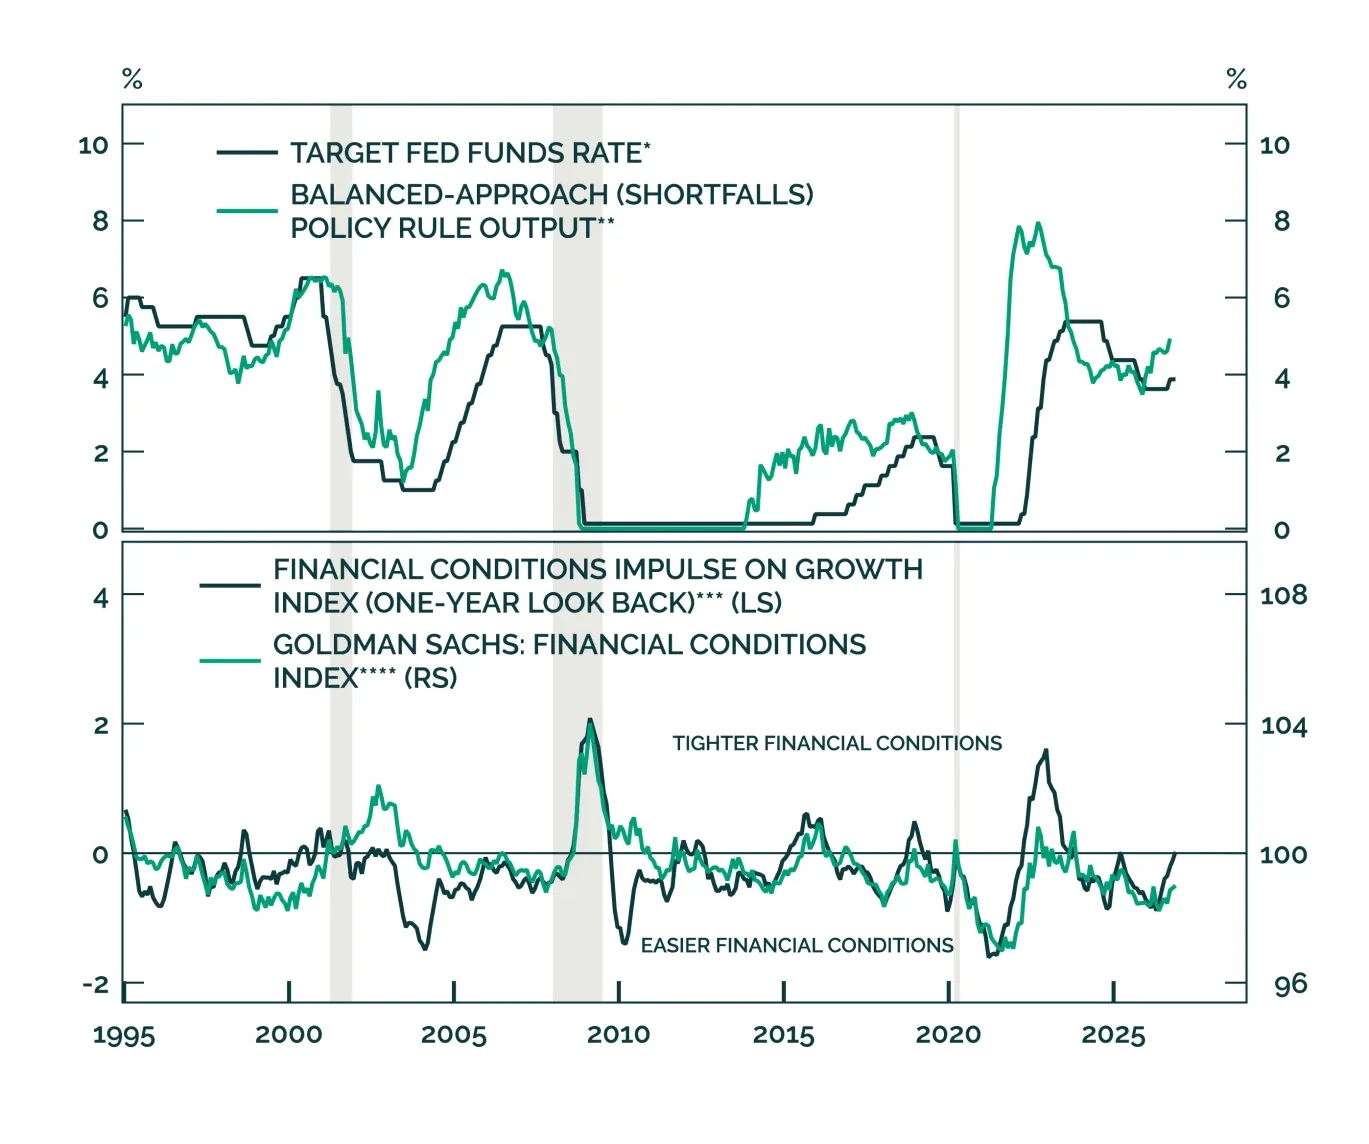
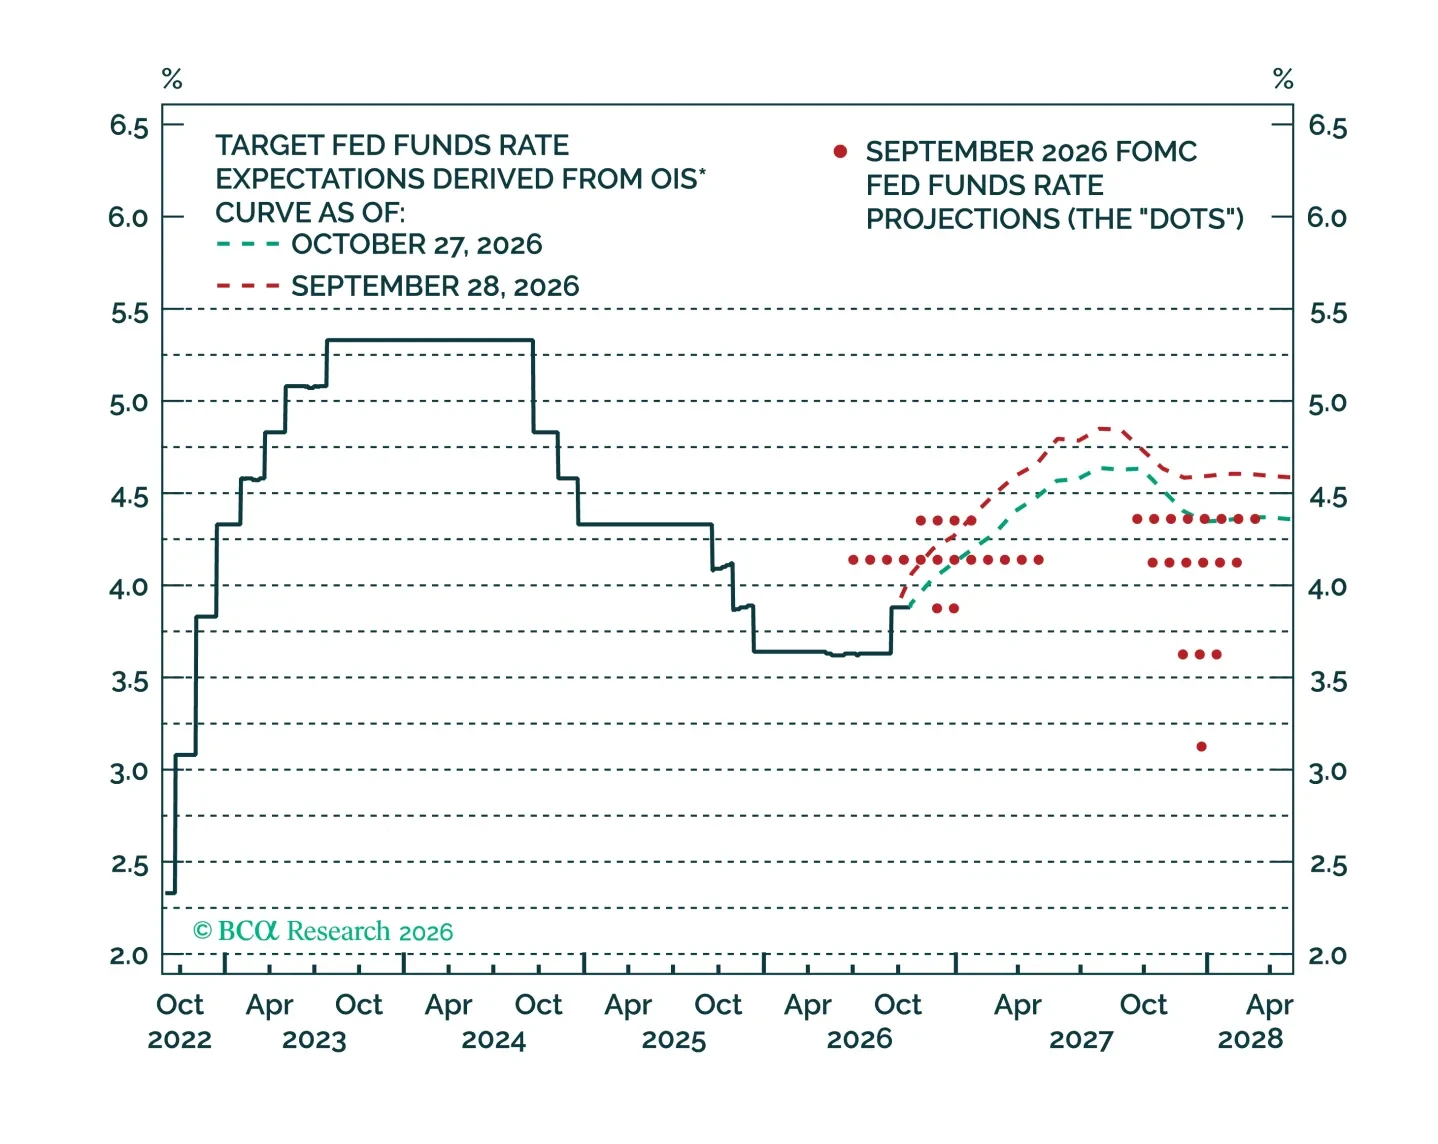
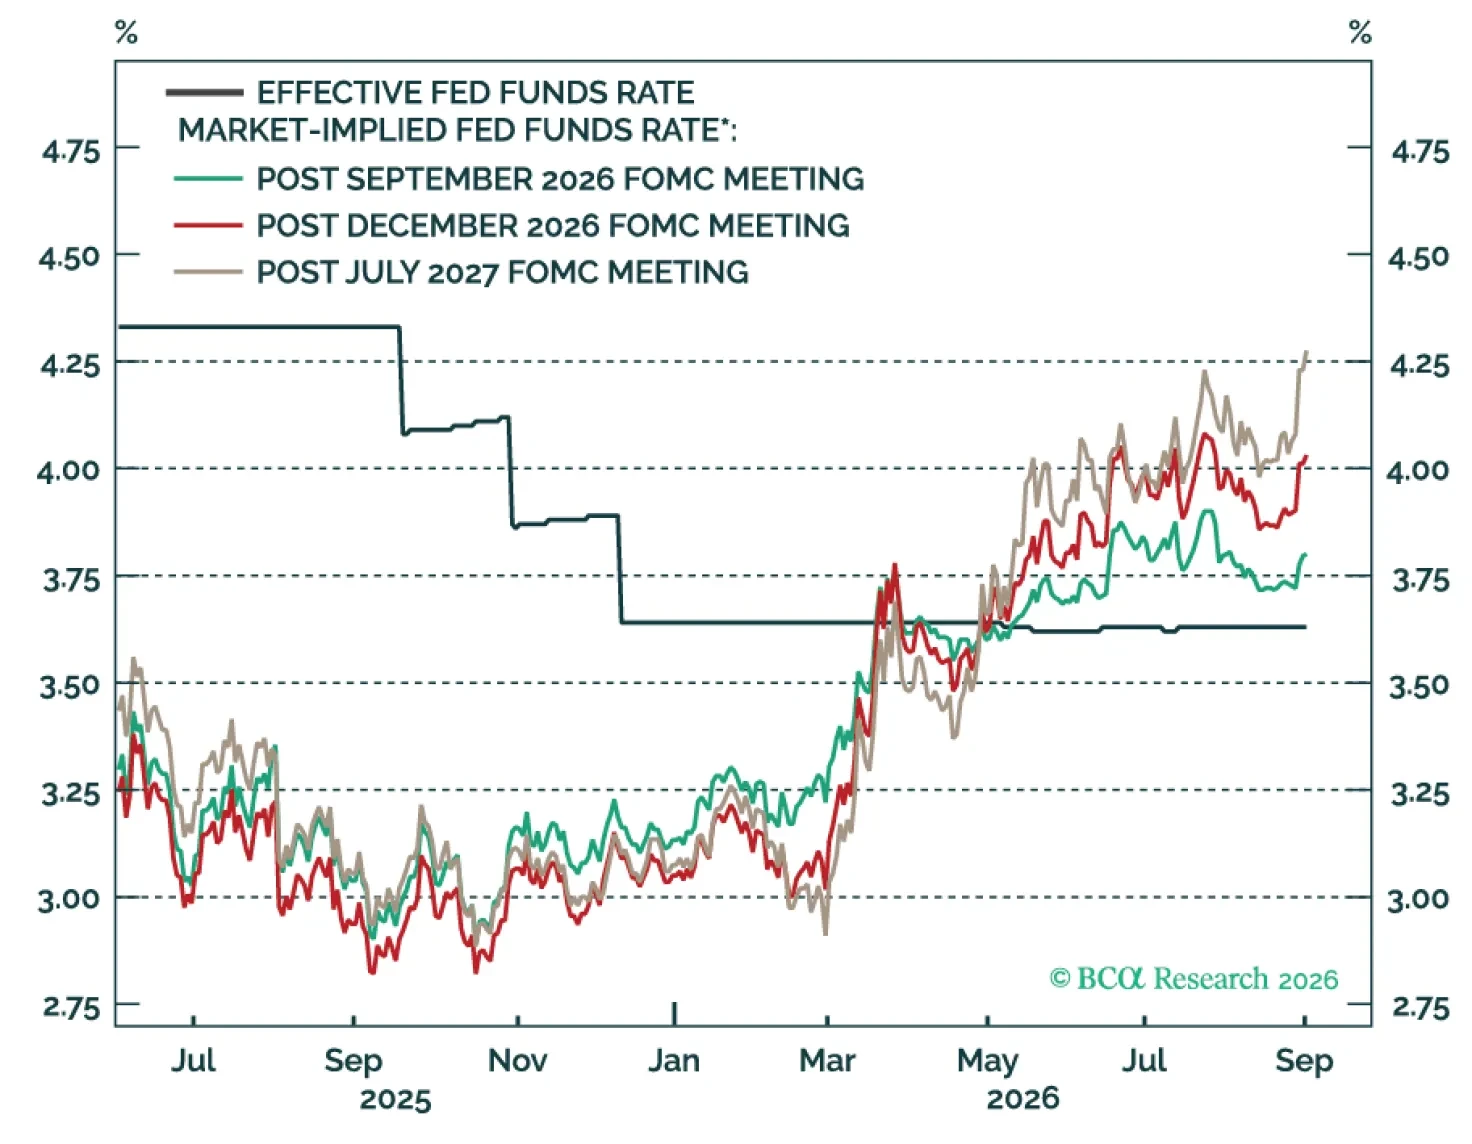
The Fed will hike rates at a pace of 25 bps per quarter until either falling inflation or tighter financial conditions cause it to stop.
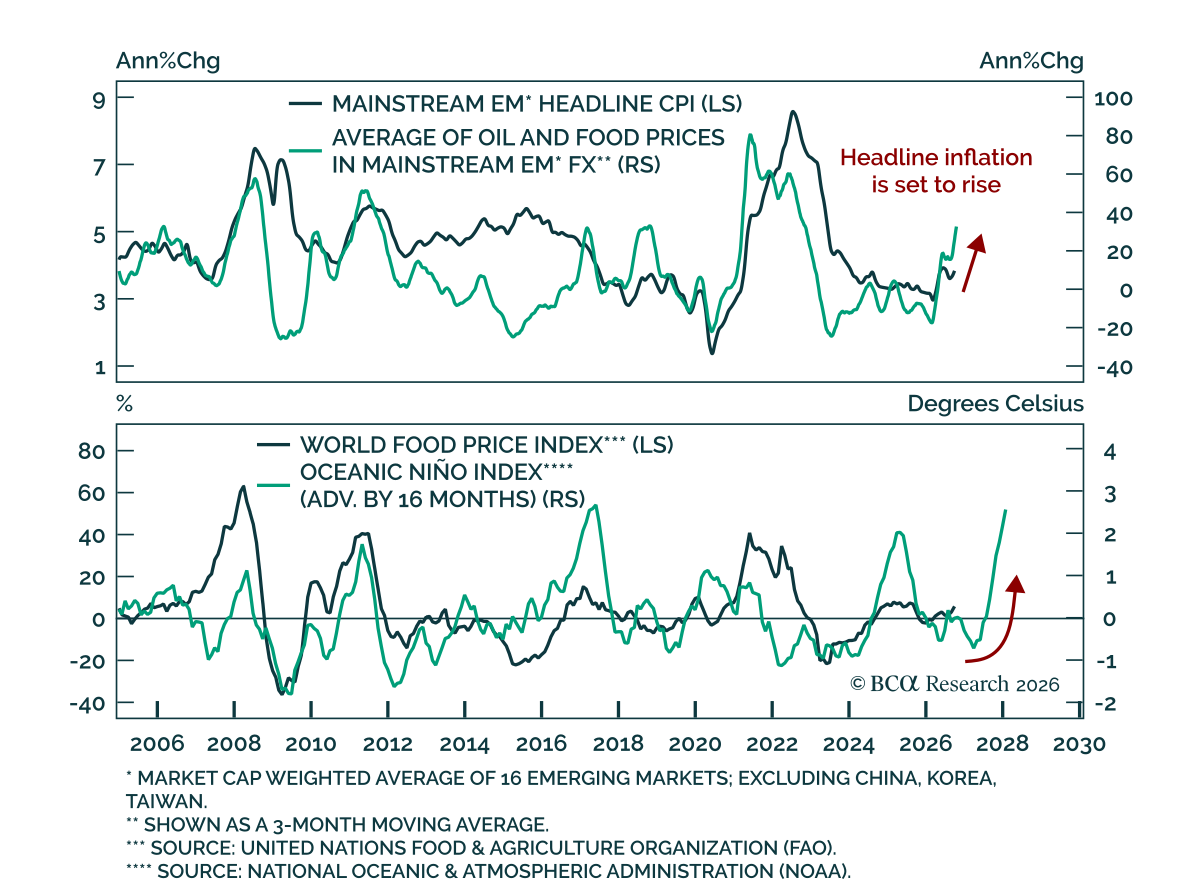
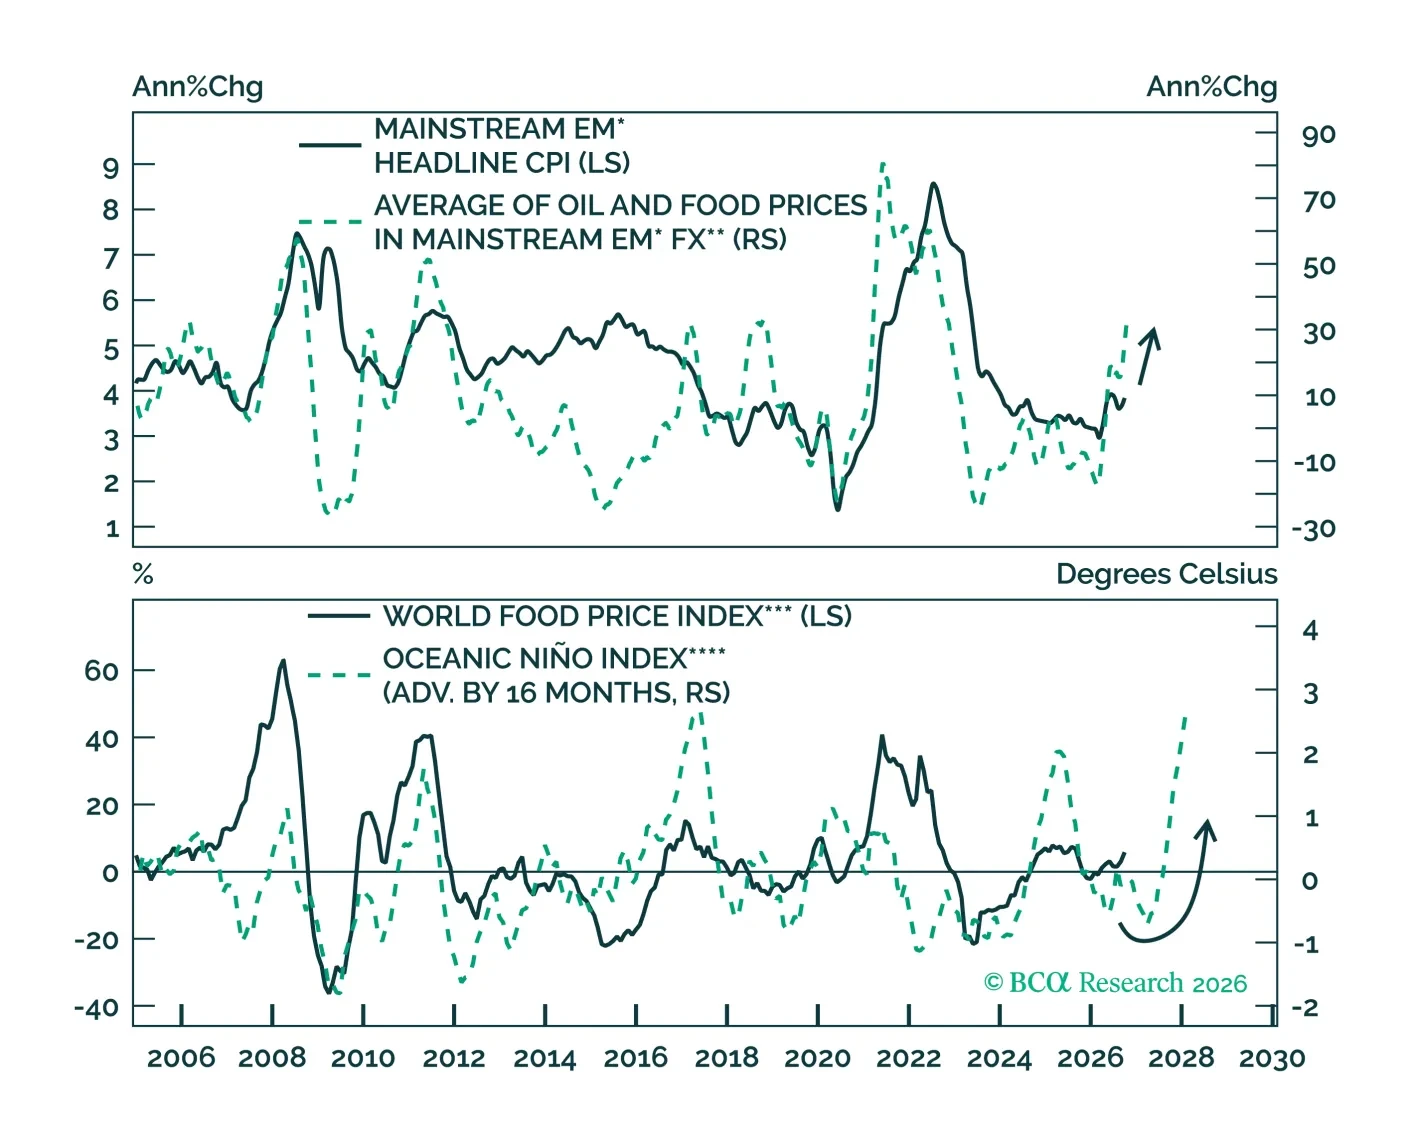
EM local bonds face near-term turbulence from rising inflation, global risk aversion, and currency weakness. Use the sell-off to build exposure: medium- and longer-term fundamentals remain favorable.
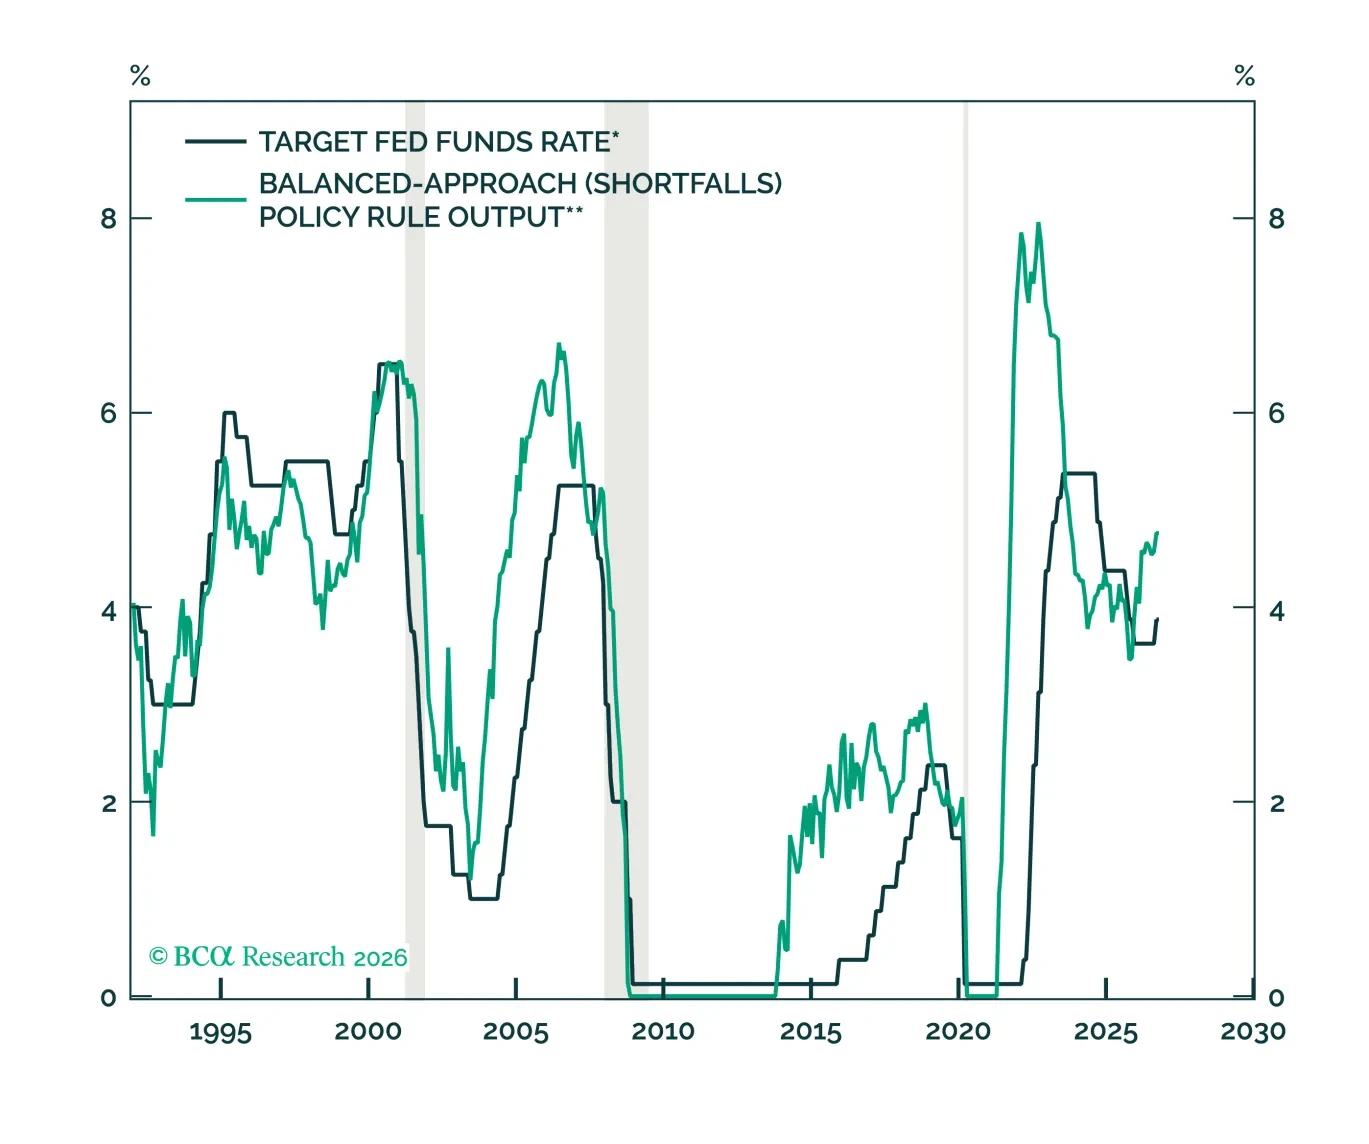
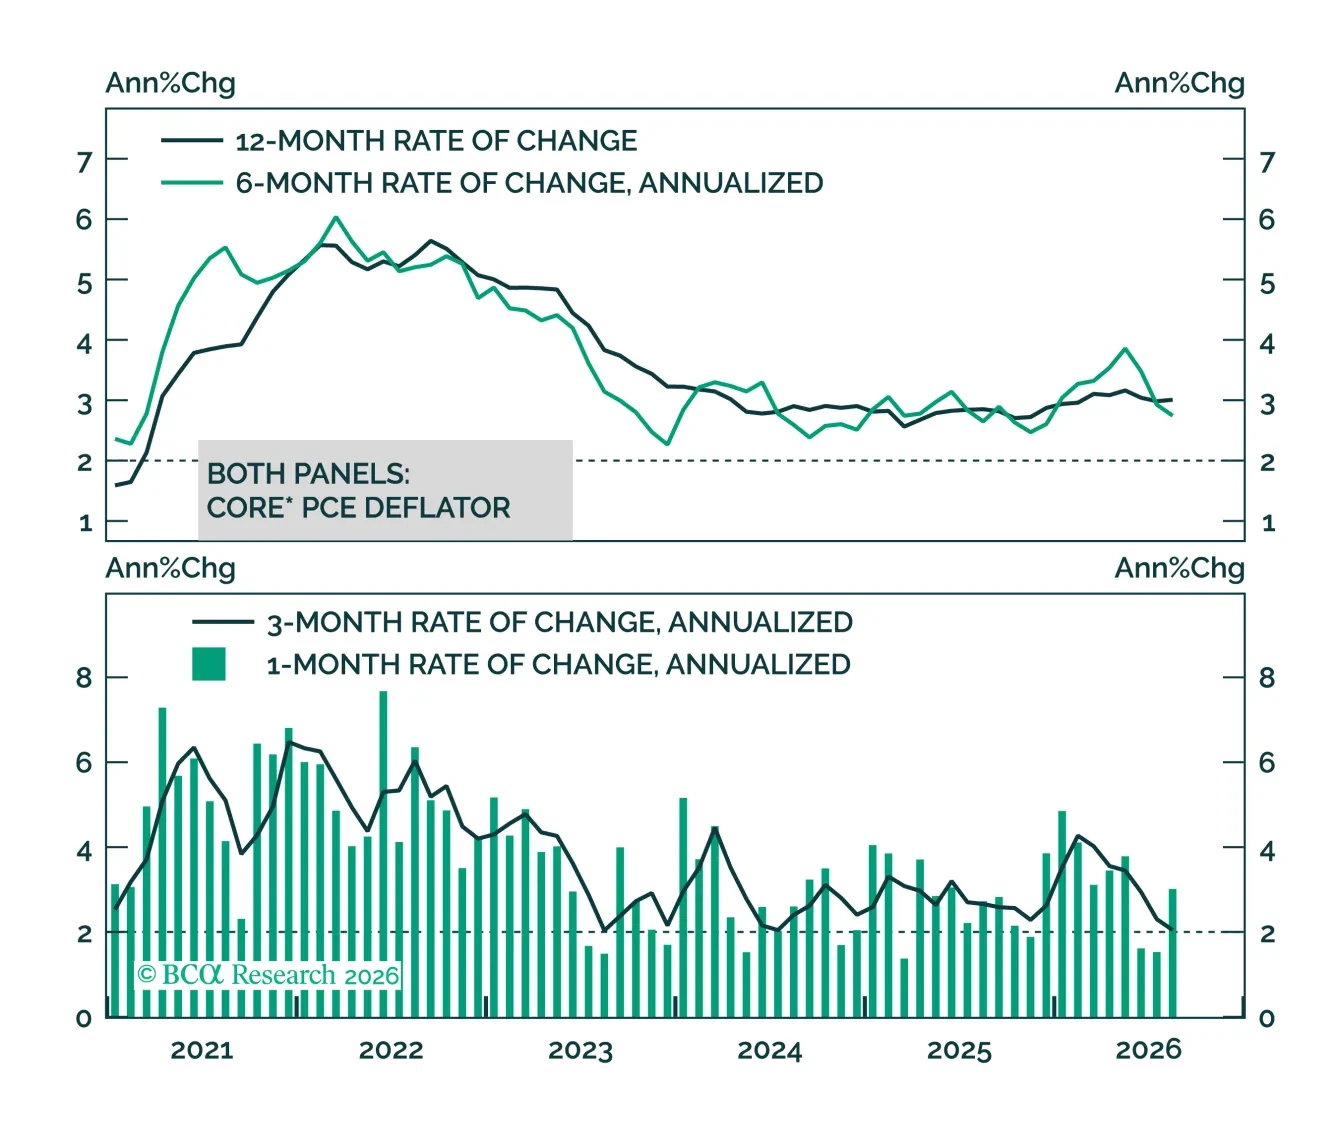
Core US inflation is still running above target. But this morning’s data revisions reveal that the gap is not nearly as large as it appeared yesterday.
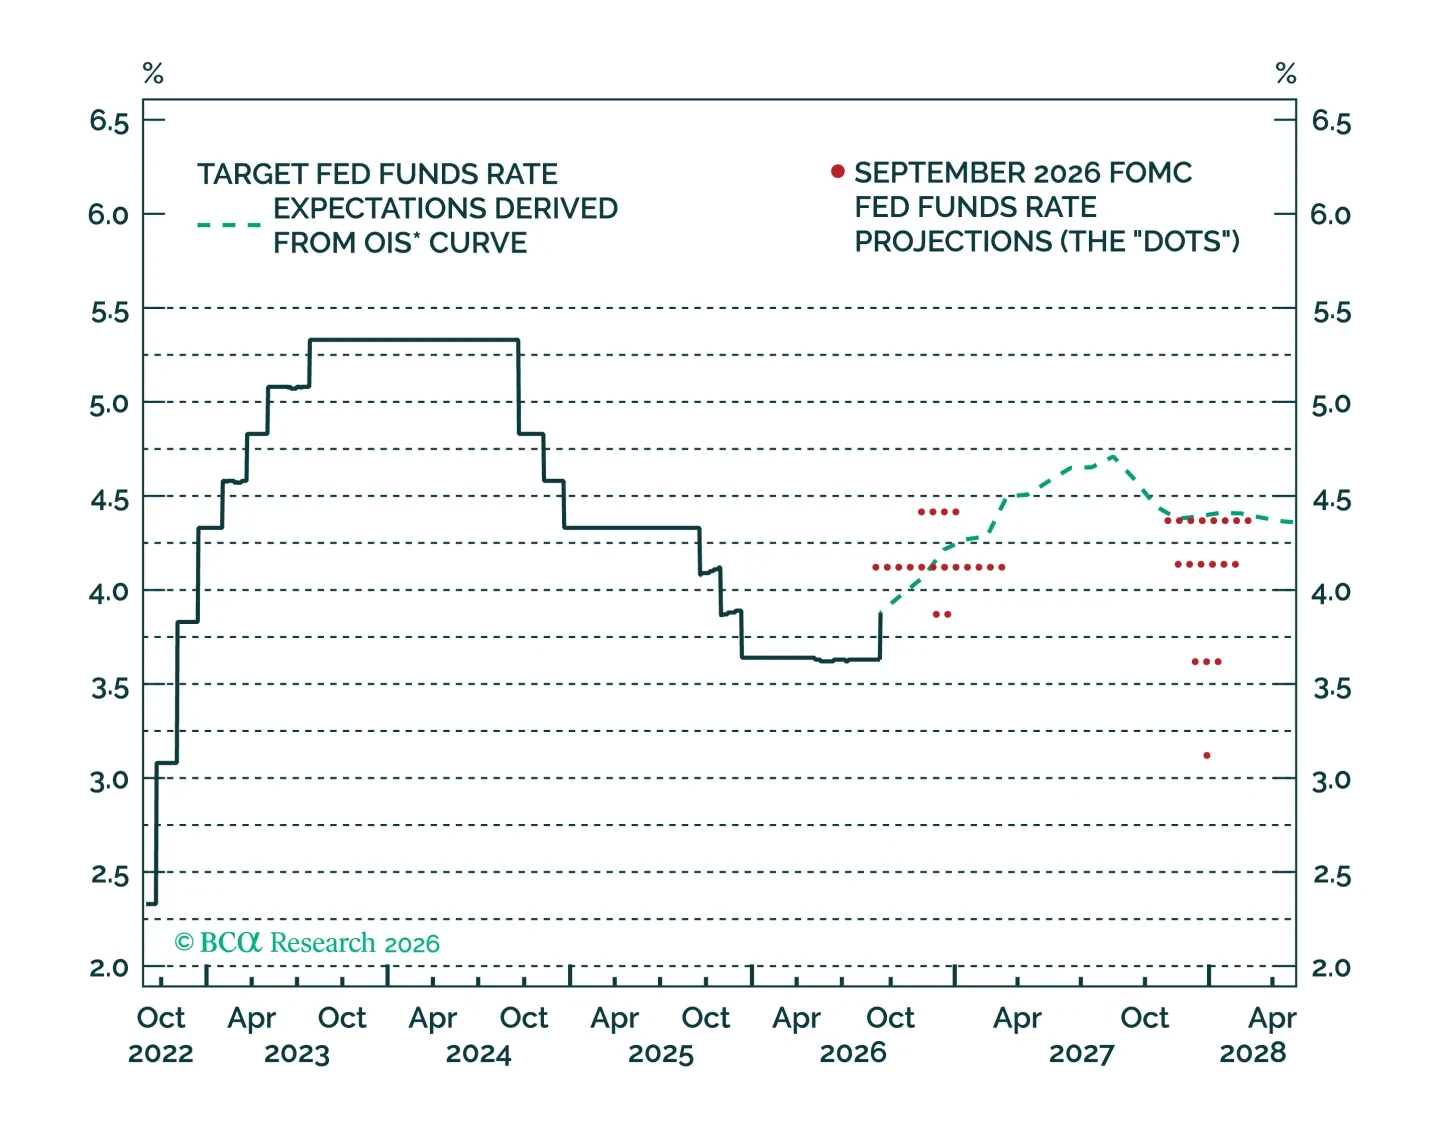
The Fed is unanimous in expecting a mild tightening cycle of no more than 75 bps, but that outcome is contingent on a rapid drop in core inflation in 2027.
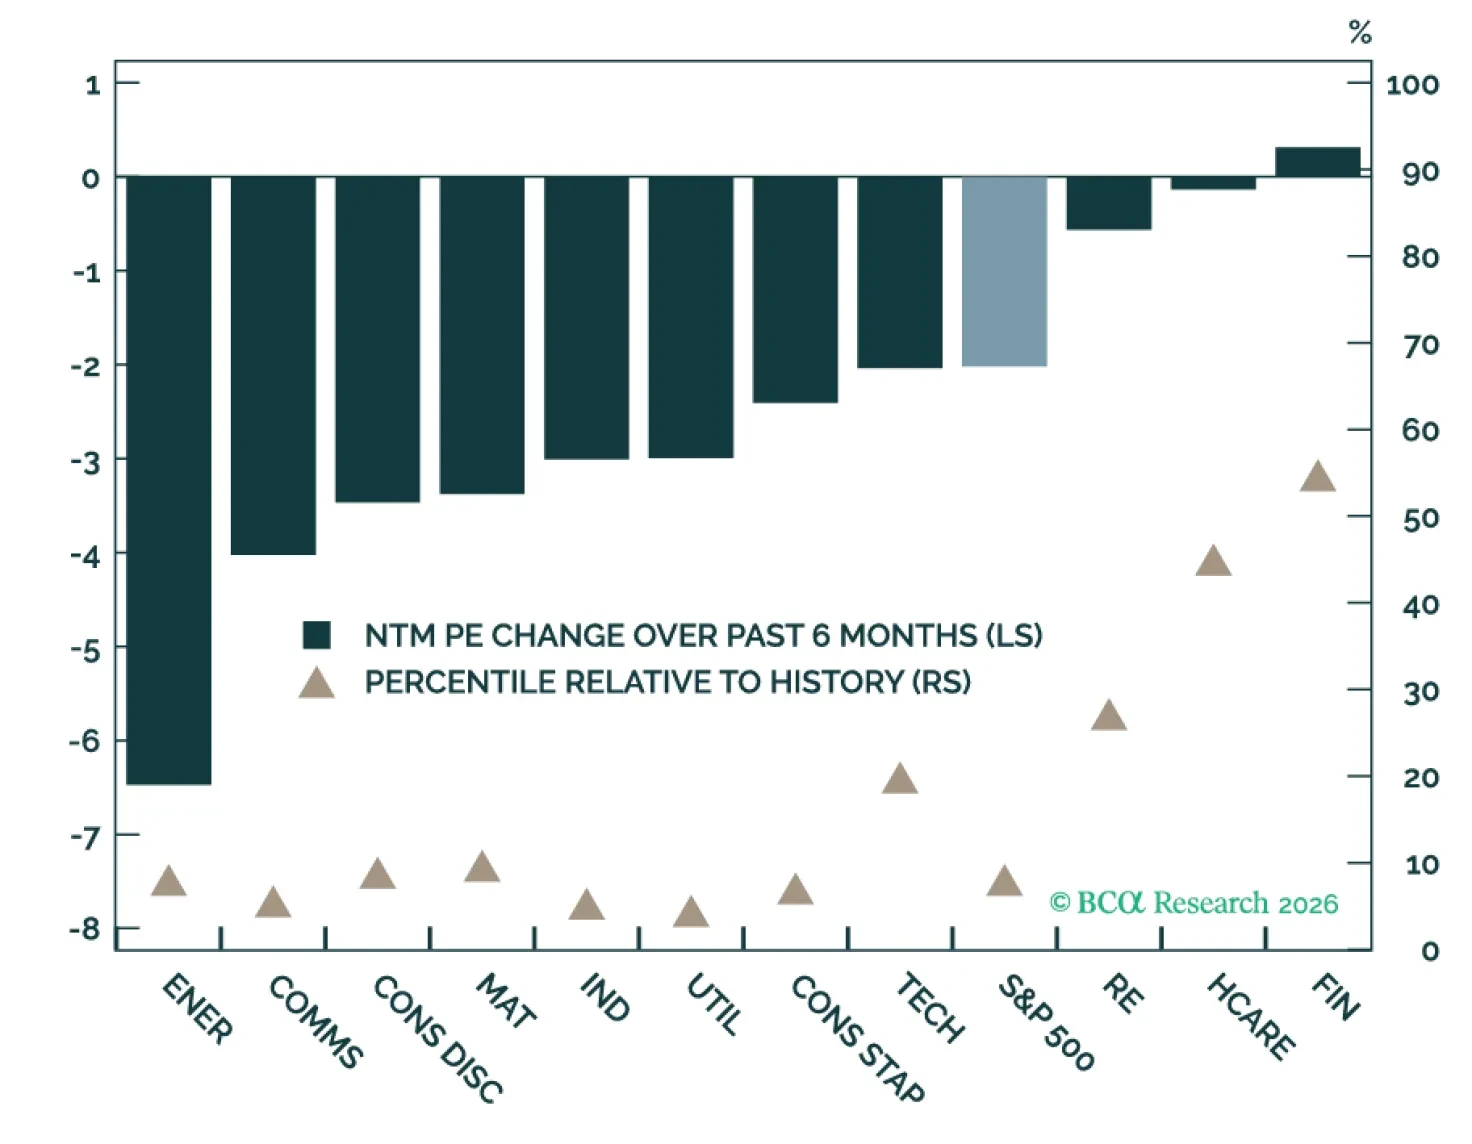
We remain constructive on US equities, but higher yields, slower EPS growth and heavy IPO issuance remain significant risks to valuations, leaving the path to our year-end target increasingly dependent on earnings. Tactically, there has already been a significant, but benign, compression in multiples, as earnings have outpaced prices. A well-communicated Fed hike could ease rather than intensify bond-market uncertainty.
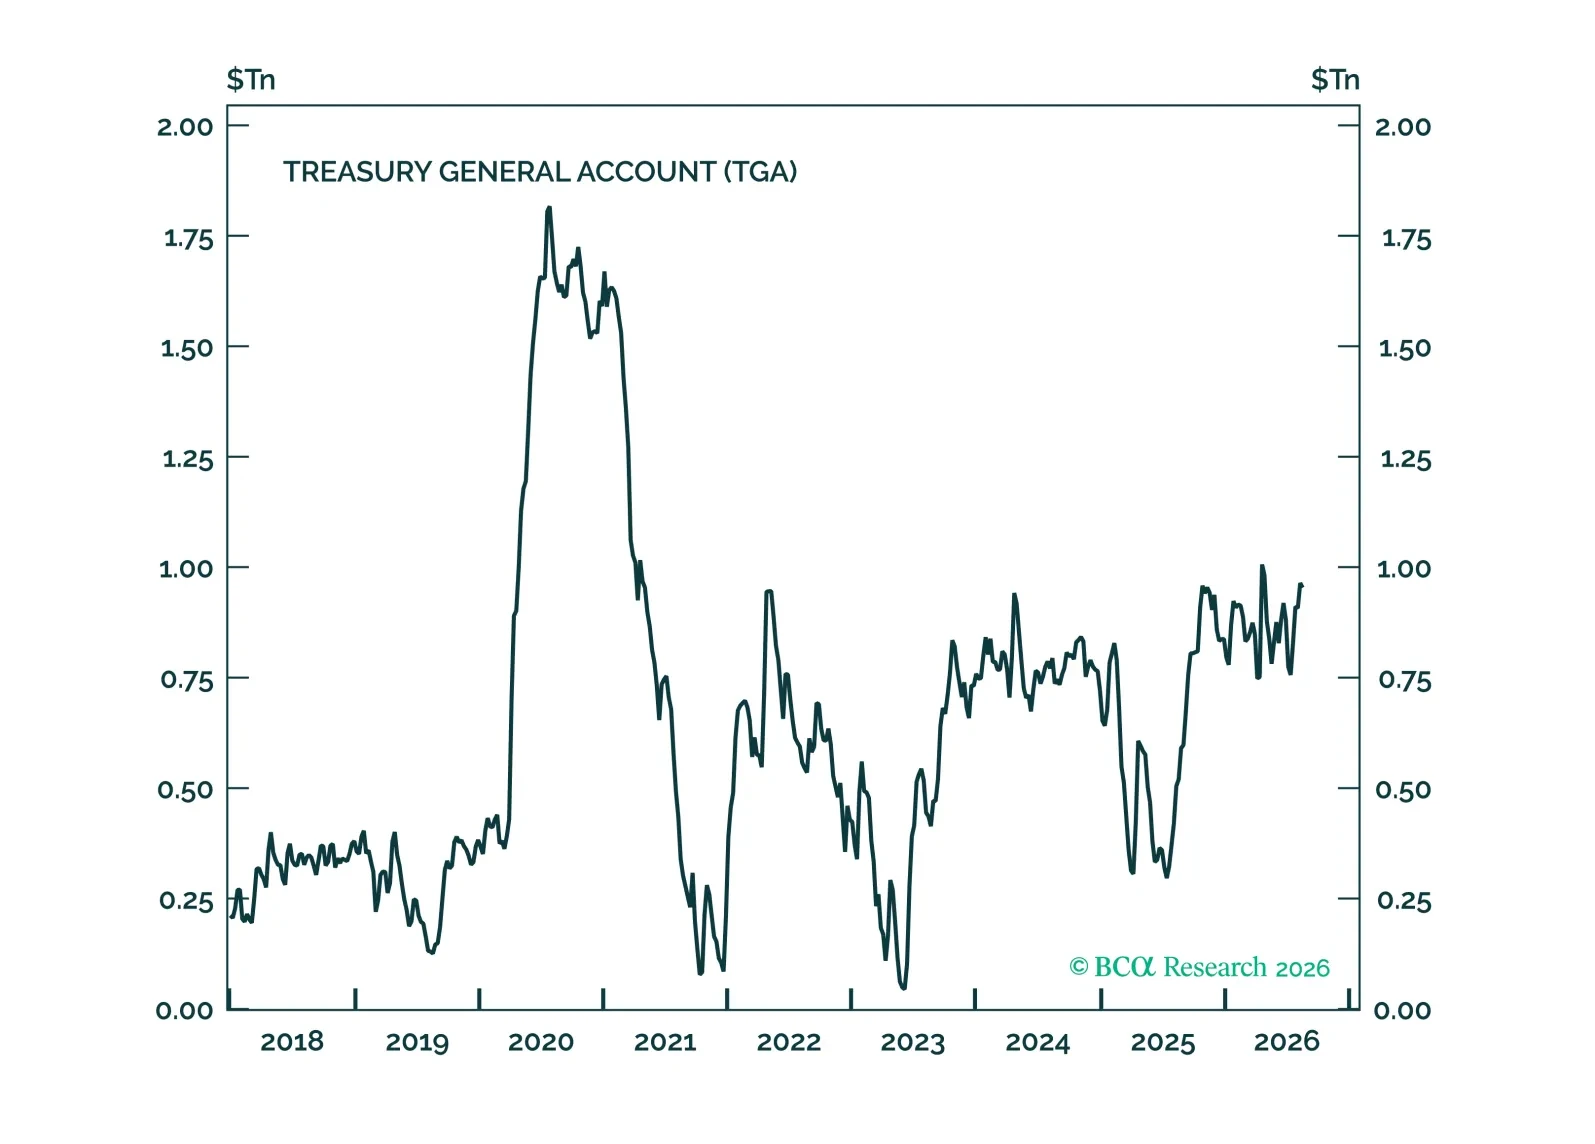
The US Treasury department’s attempts at yield suppression are doomed to fail unless the Federal Reserve gets involved.