Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Inflation

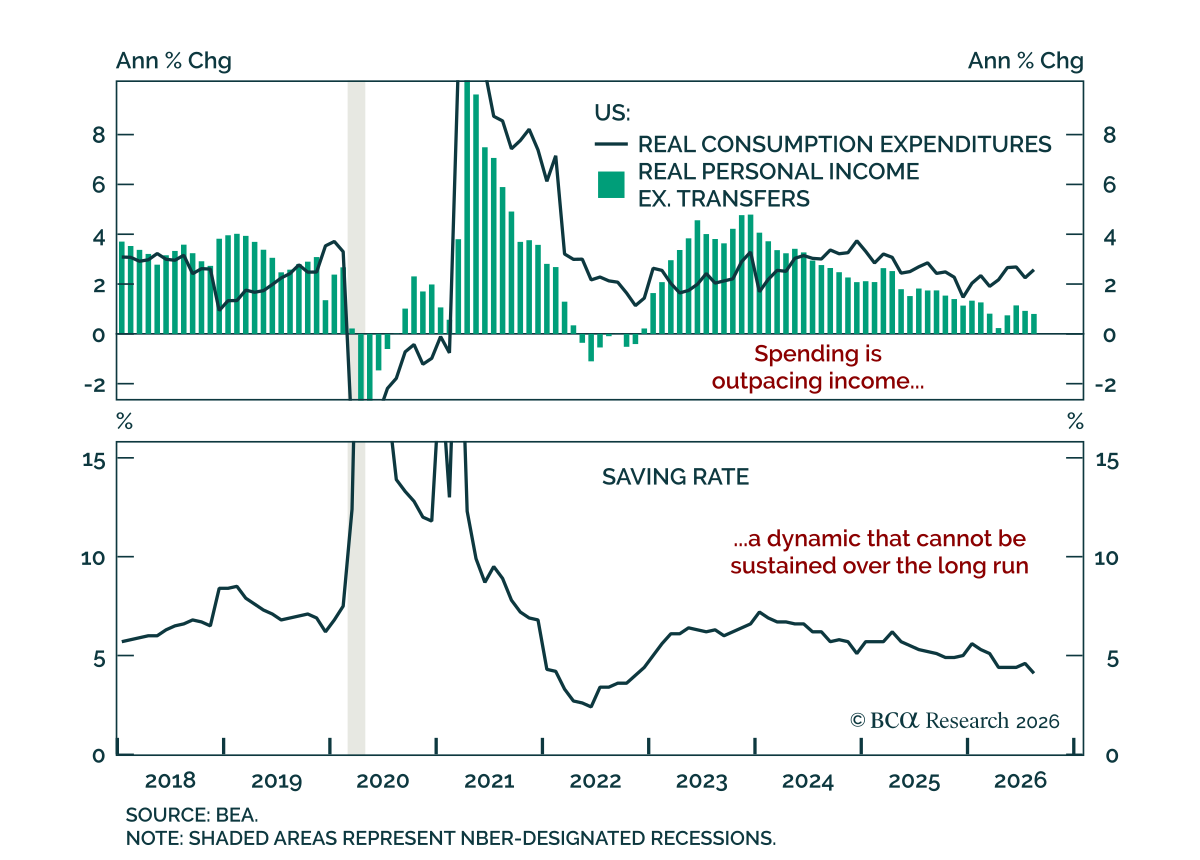
The August Personal Income and Outlays report was soft, with weaker income growth and cooler inflation reinforcing the case for the Fed to remain patient. Nominal spending rose 0.9% m/m, in line with estimates, while real spending increased 0.6%. Personal…
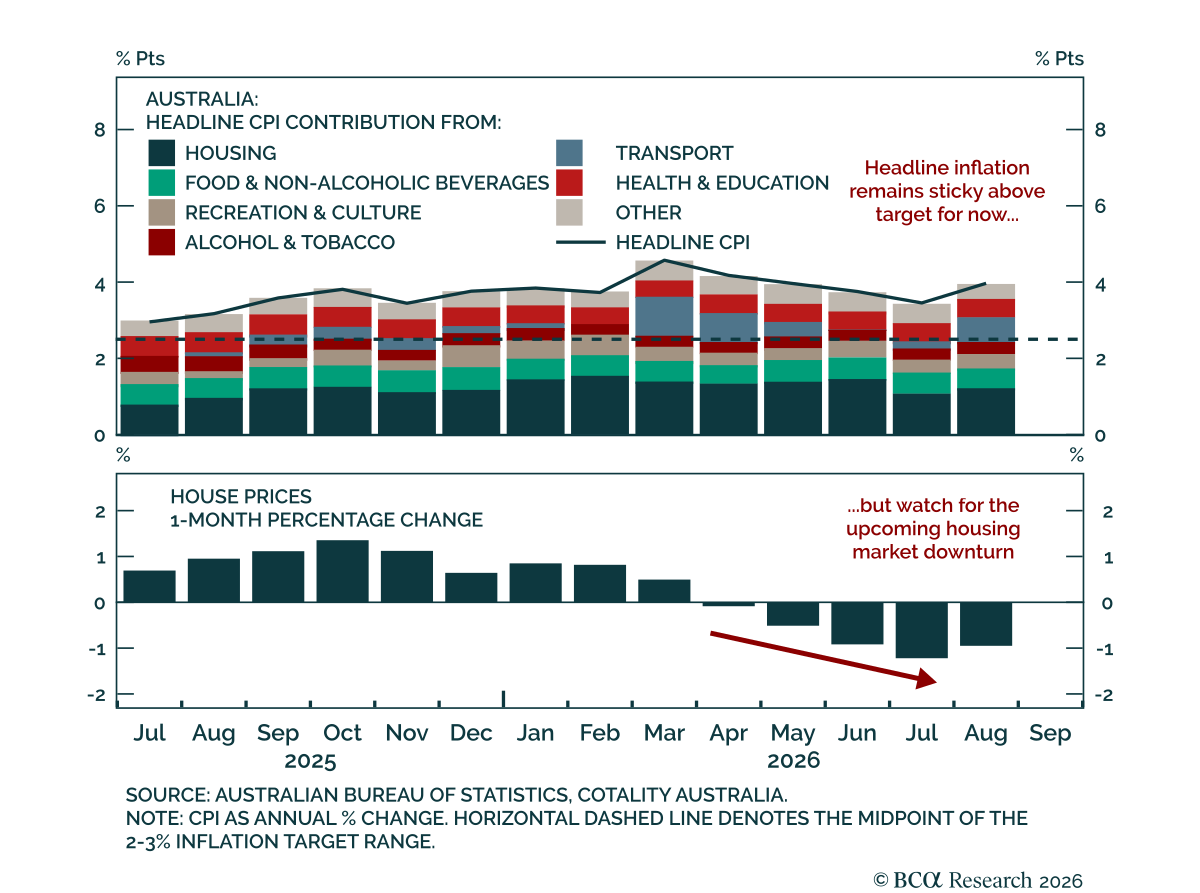
Australia's August CPI shows no sign of re-accelerating core inflation, suggesting a less aggressive RBA tightening than currently priced. Headline CPI rose less than expected in August, to 4.0% y/y from 3.5%, lifted by higher fuel prices in the transport…

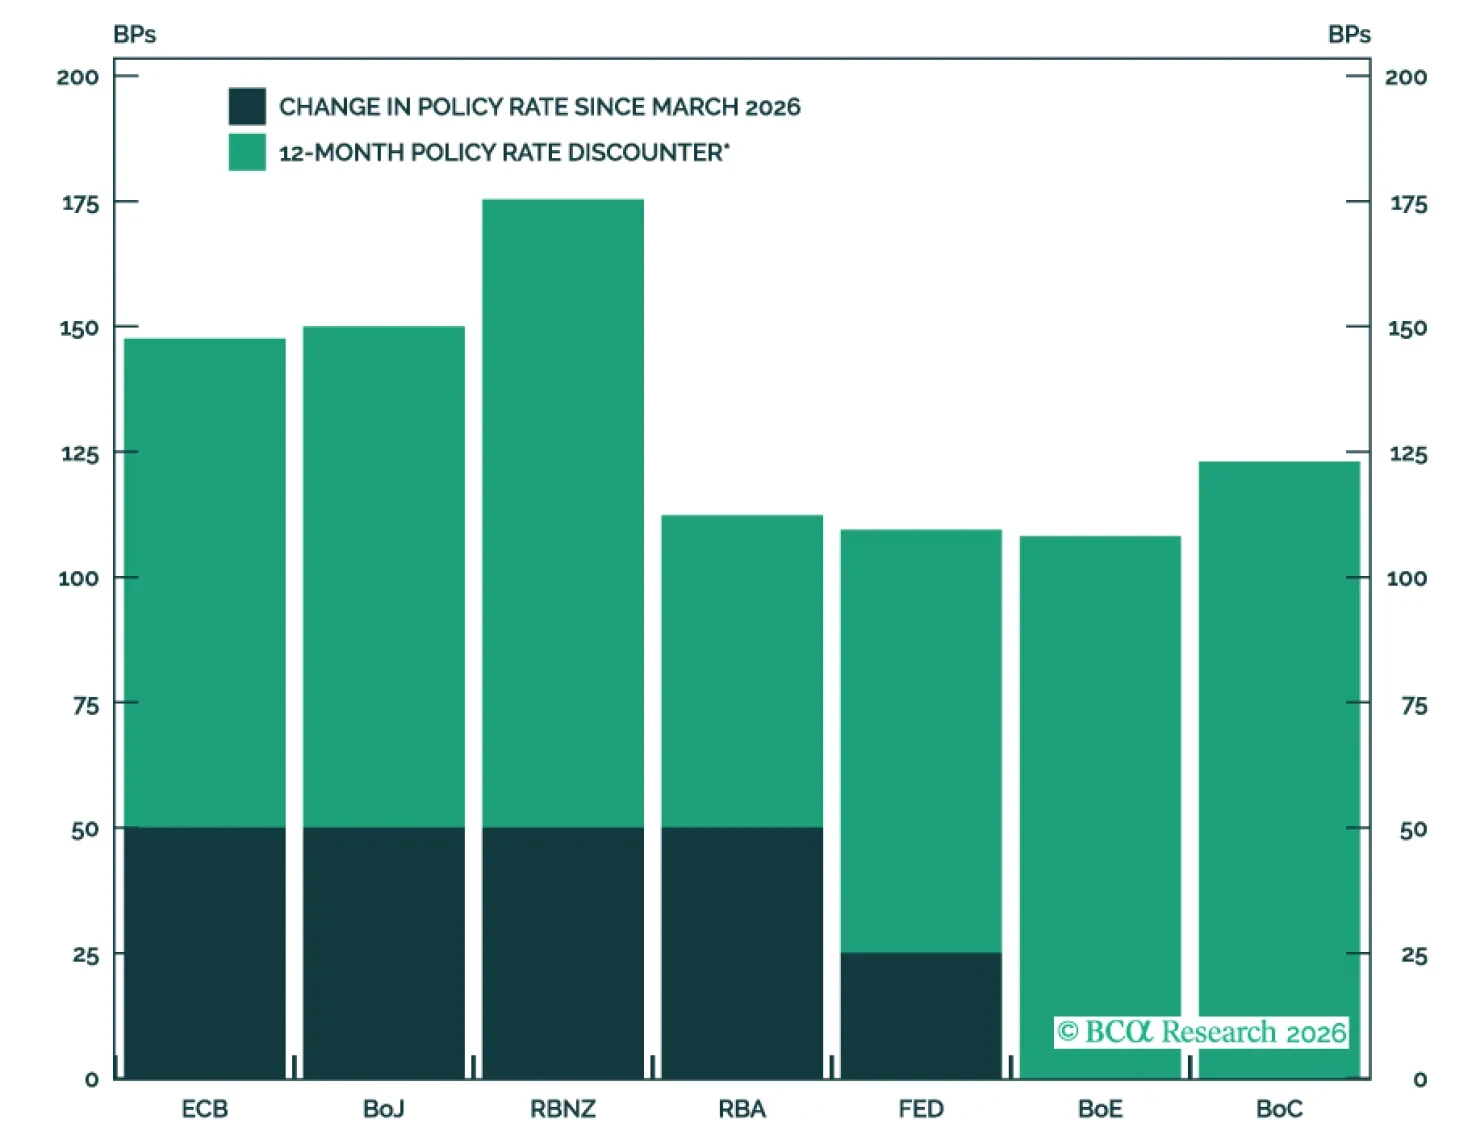
Policy rates are poised to rise across the developed world as central banks are no longer willing to wait out the Iran-US standoff before taking action to combat the inflationary effects of higher oil prices. Outside of Japan, however, we do not think central banks will hike as much as markets expect.
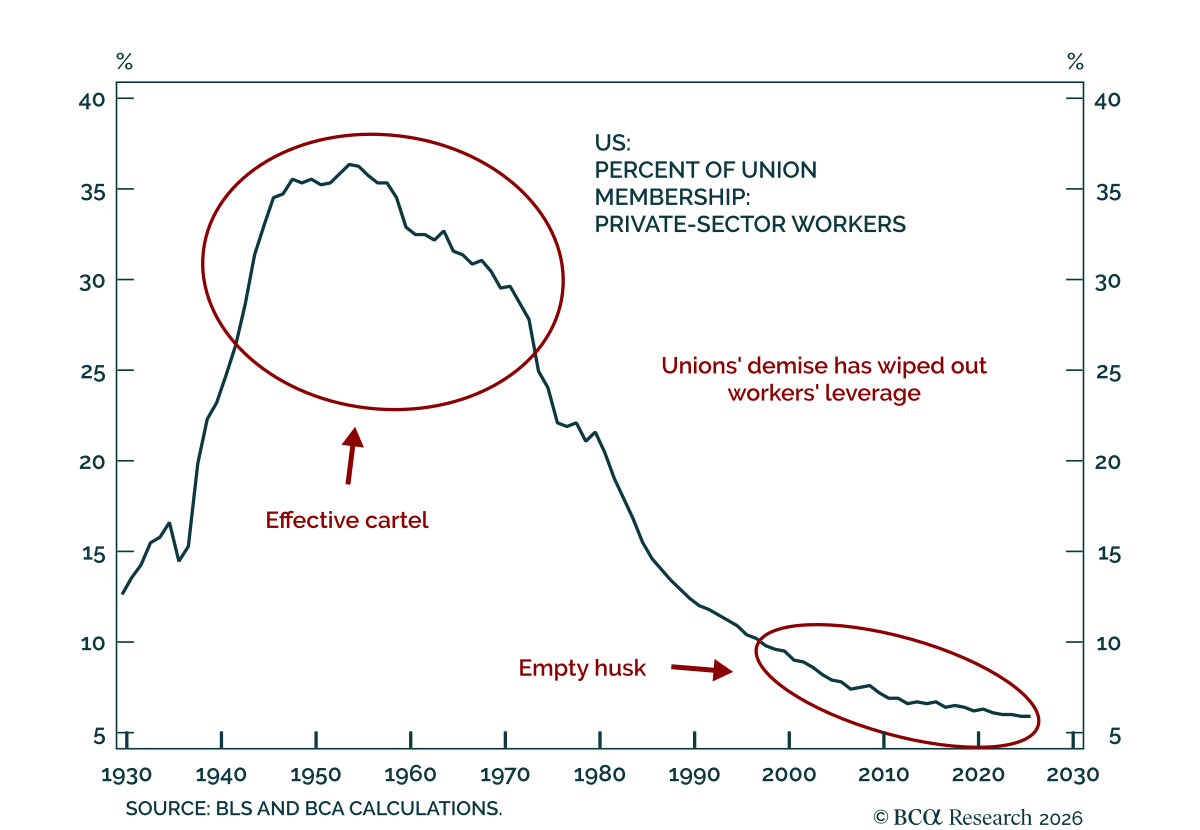
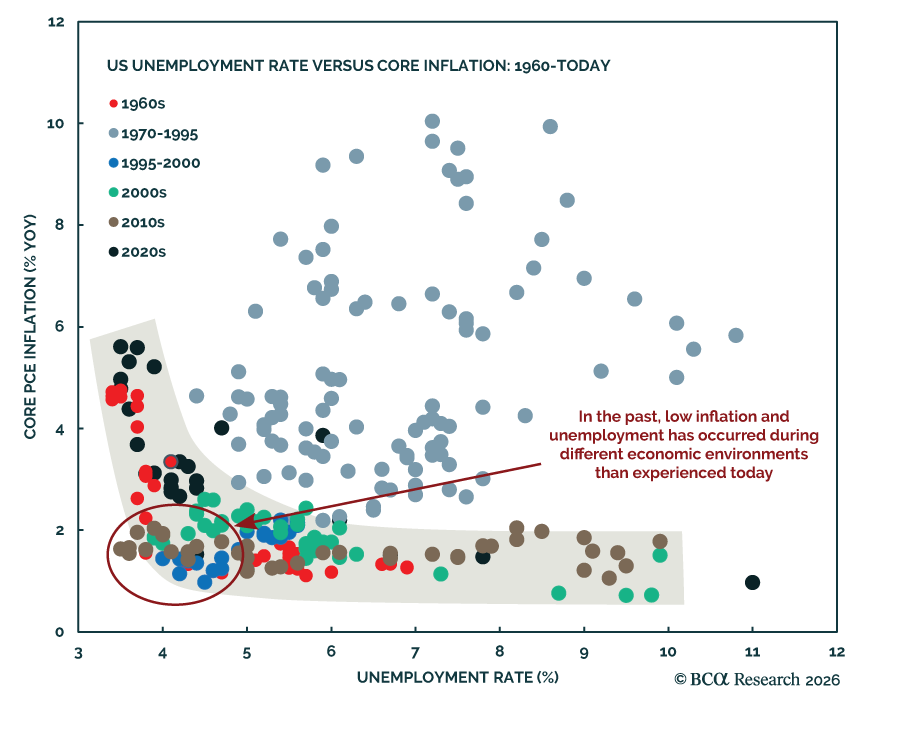
Our US Investment strategists see fears of a significant wage growth breakout as overdone. Entrenched misperceptions die hard, but the structural balance of power between workers and employers has shifted too far to permit a repeat of the 1970s. The…
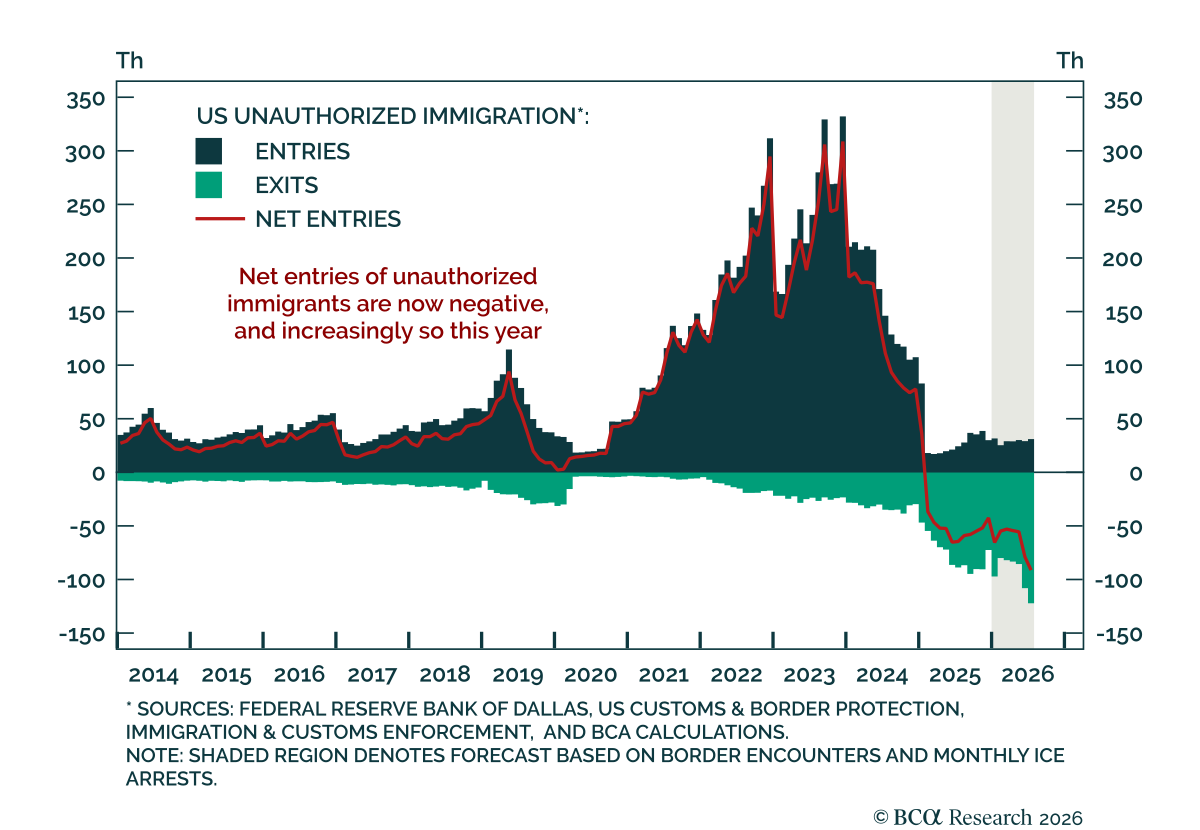
A tighter labor market over the coming year could cause inflation to stay elevated even if tariff and energy shocks dissipate. The US labor force has contracted over the past year, driven by the departure of unauthorized immigrants and a decline in the labor…
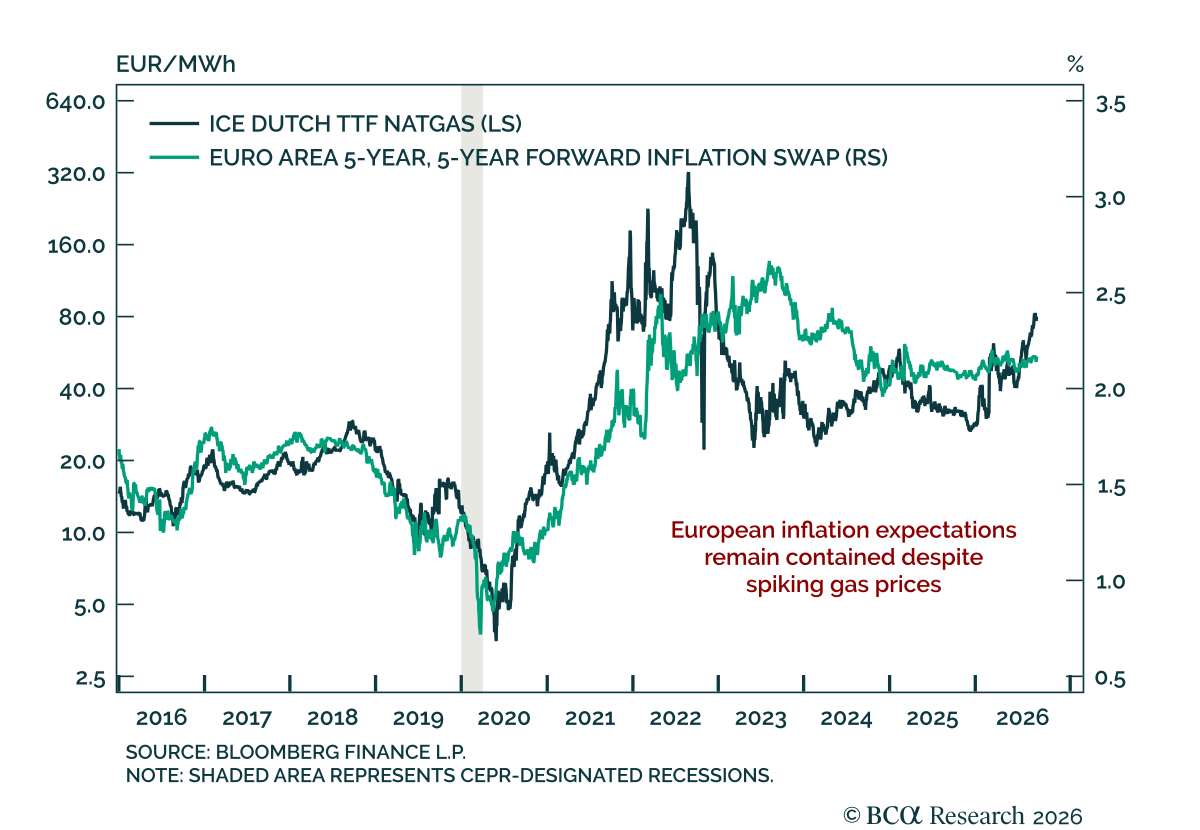
European natural gas prices have surged above recent highs, but the absence of a corresponding rise in longer-term inflation expectations argues against the ECB hiking deeply into restrictive territory. ICE Dutch TTF prices, the European benchmark, have moved…
Our Essentials and CoreMacro strategists find little evidence that tighter labor supply from the US immigration crackdown is boosting inflation today. The net exit of unauthorized immigrants has nonetheless lowered the bar for stronger labor demand to turn…

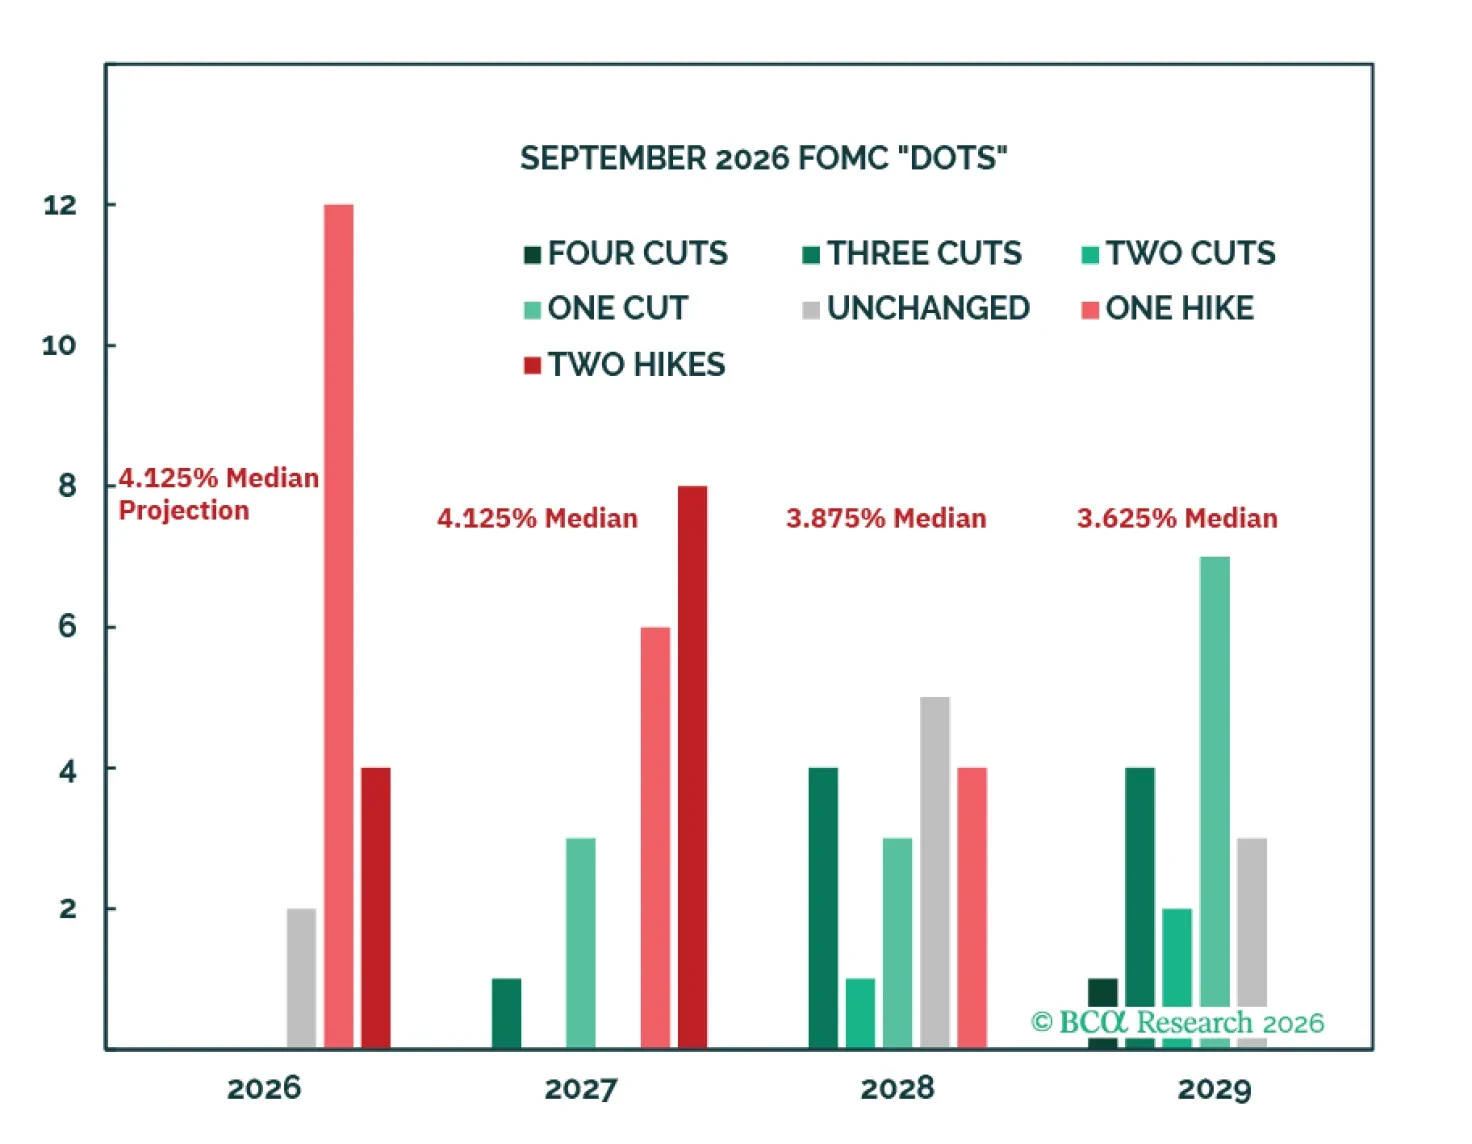
The Fed hiked rates last week, but Fed officials expect this tightening cycle will involve no more than three 25-basis point hikes, contingent on inflation coming down quickly in 2027. We’re inclined to agree.
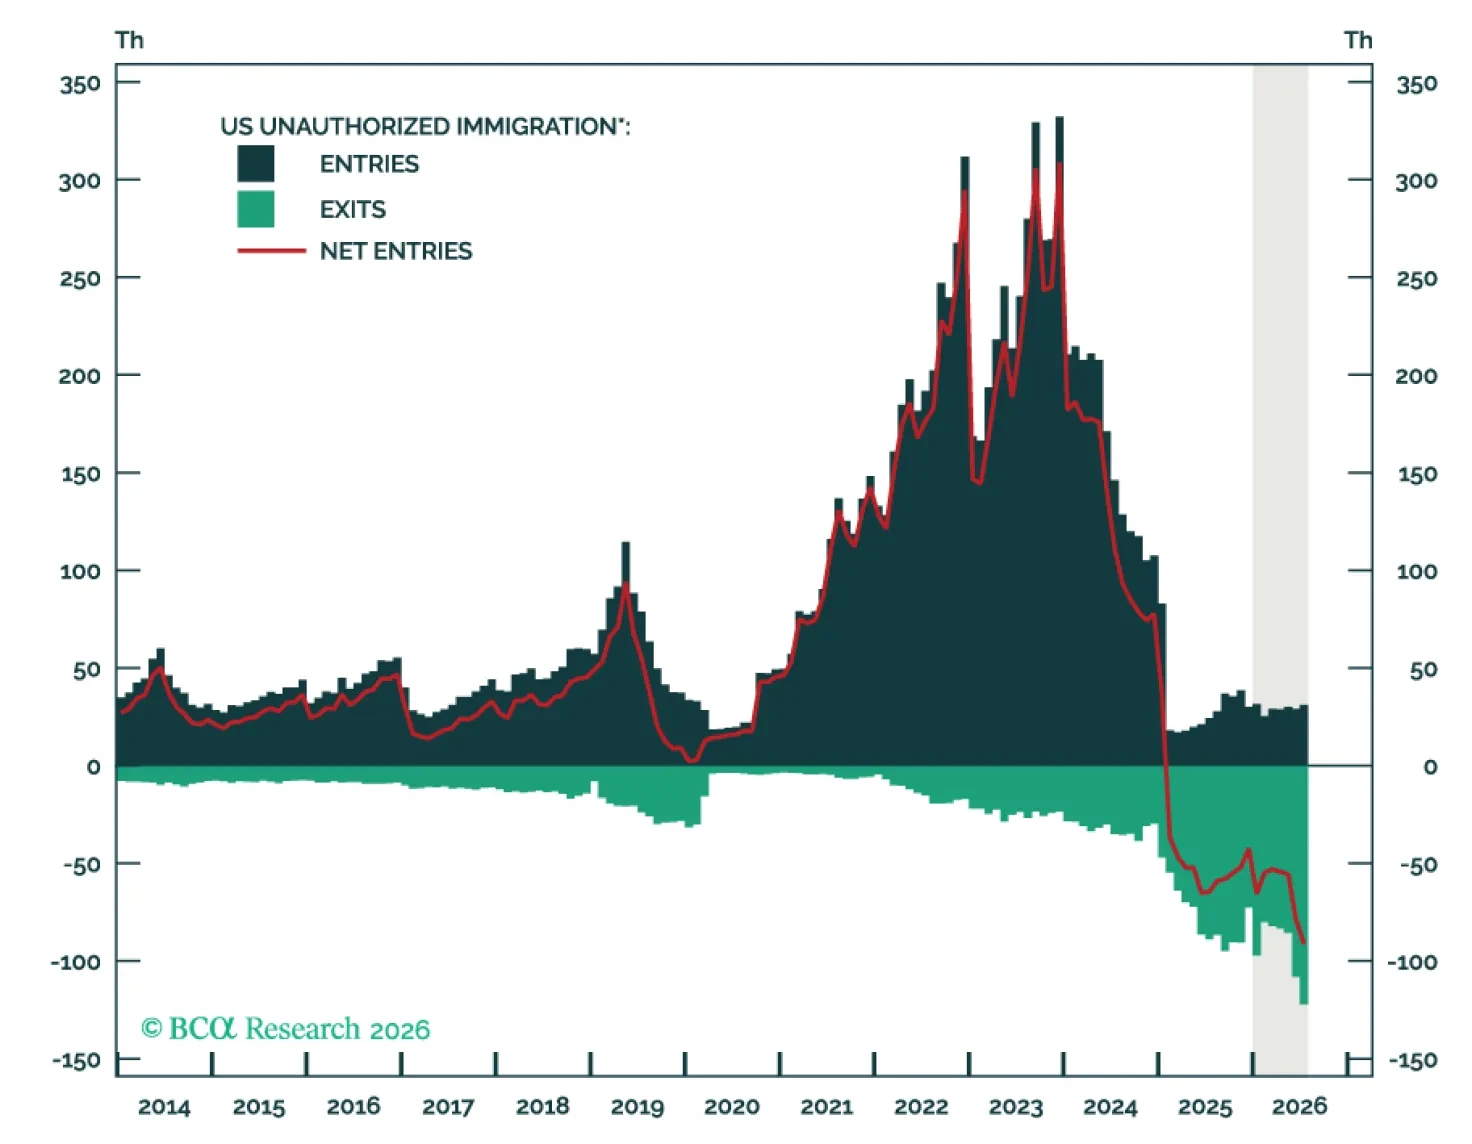
Labor supply is not meaningfully boosting inflation today, but the net exit of unauthorized immigrants has lowered the bar for stronger labor demand to turn inflationary. Hawkish monetary policy surprises over the coming year are possible.
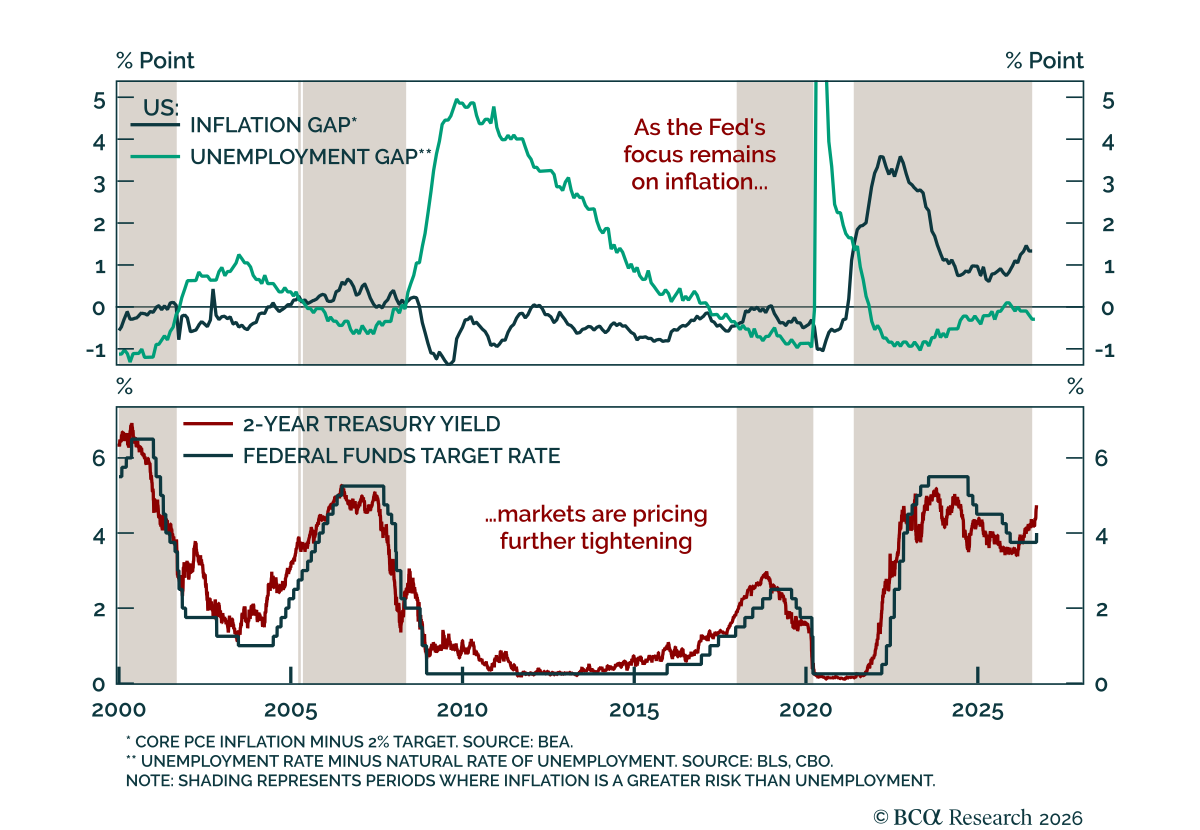
The Fed’s 25 bps hike confirms the start of a new tightening cycle, but our US Bond strategists still expect that cycle to be mild and front-loaded. The FOMC unanimously lifted the fed funds target range to 3.75%-4%, with the statement saying the move was…