Financial Markets
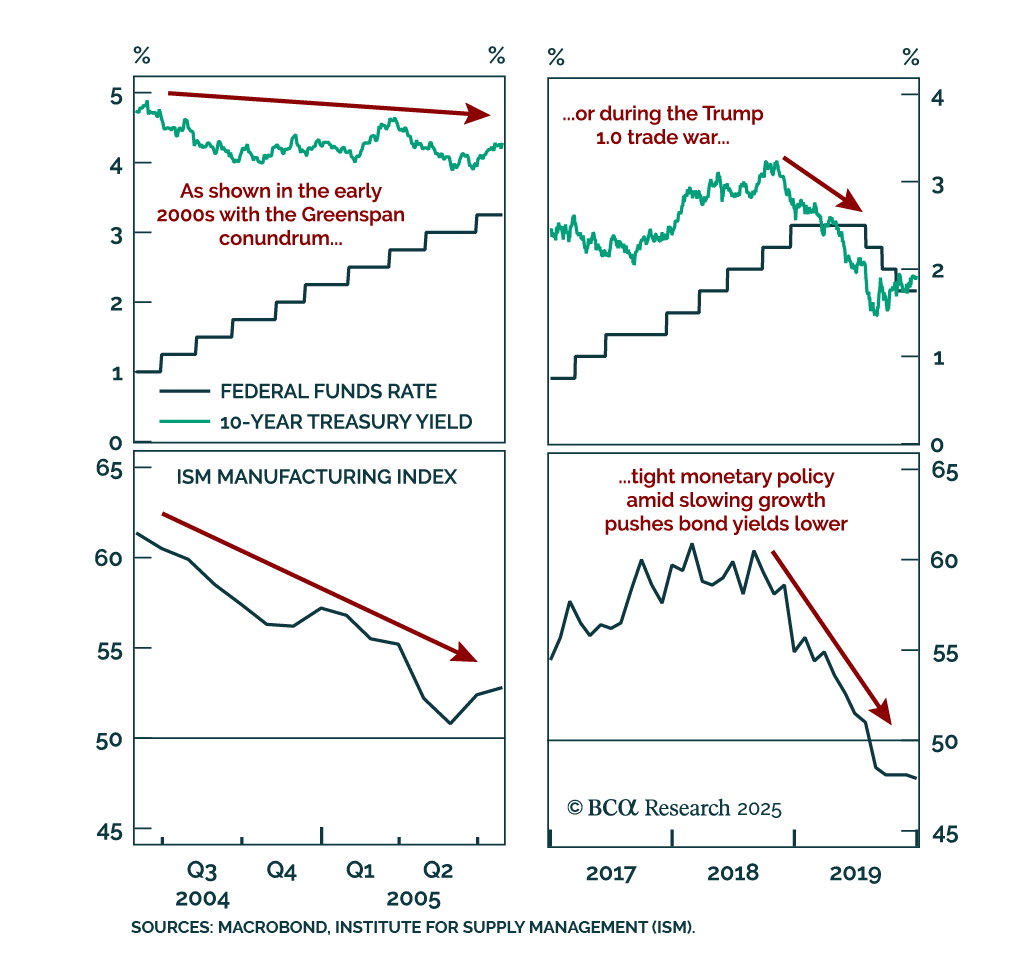
President Trump's pressure on Fed Chairman Powell is intensifying, but keeping Powell in place offers the administration political cover while keeping bond yields contained. Removing Powell would be legally difficult and risk unsettling markets, while his…
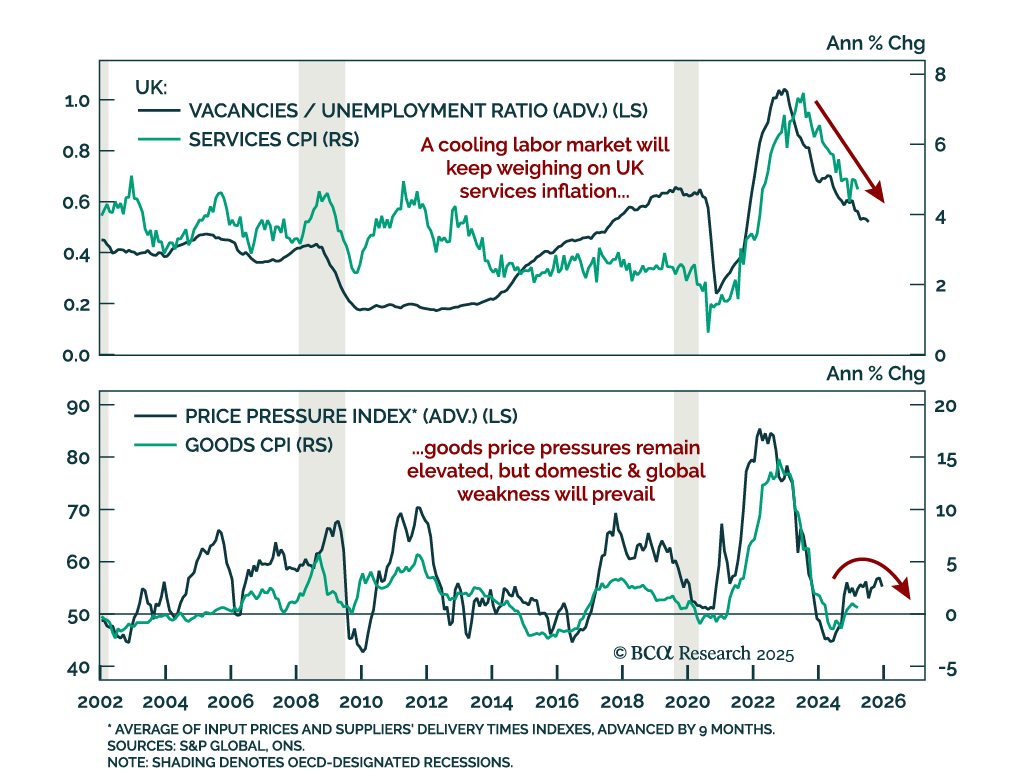
The latest UK data supports a May BoE cut, reinforcing our overweight in Gilts as growth headwinds build and inflation cools. Employment declined by 78k in March, accelerating from February’s downwardly revised 8k drop, while vacancies fell below pre-COVID…
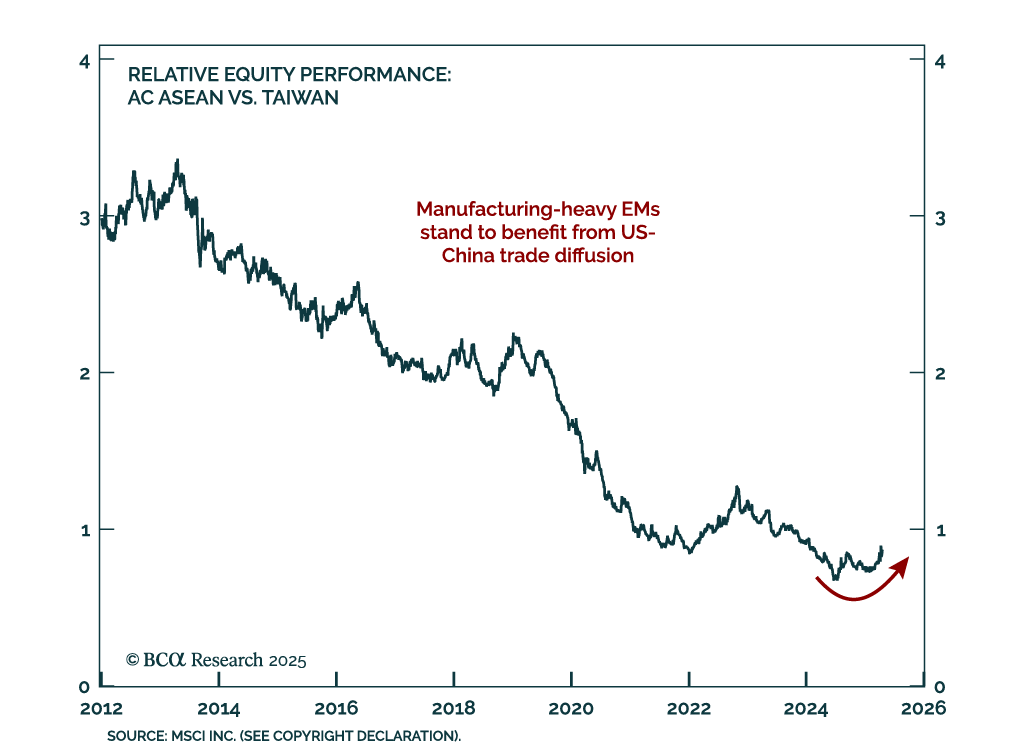
Our Geopolitical and GeoMacro strategists recommend buying tail-risk protection and adding exposure to manufacturing-oriented EMs as the risk of US-China military escalation rises. They now see a 10% chance of full-scale war over Taiwan and a 25% chance of a…

Our China strategists remain defensive and tactically downgrade MSCI China to underweight, citing escalating US China tariff tensions and subdued domestic demand. Favor government bonds over equities, defensive sectors, and A-Shares over offshore Chinese…

Trump’s renewed attacks on Fed Chairman Jerome Powell raise policy uncertainty but are unlikely to lead to Powell’s removal, reinforcing our expectation for continued restrictive policy and supporting our long duration stance. Trump's intensified criticism…
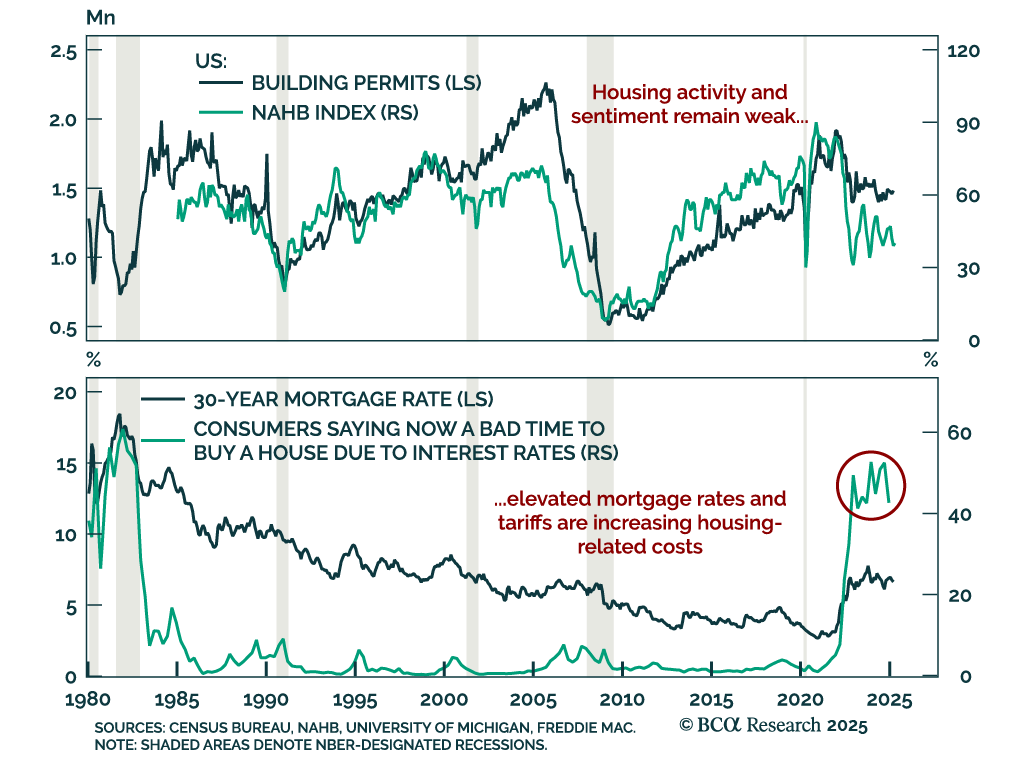
Weak housing data reinforces our defensive positioning, as recession odds remain underpriced in risk assets. US housing starts fell sharply, declining a larger-than-expected annualized rate of 11.4% in March after a 9.8% rebound in February, which was driven…

April’s Philadelphia Fed survey adds to recent stagflationary signals, reinforcing our defensive commodities positioning. The headline index collapsed to -26.4 from 12.5 in March, missing expectations and confirming the April deterioration seen in the Empire…
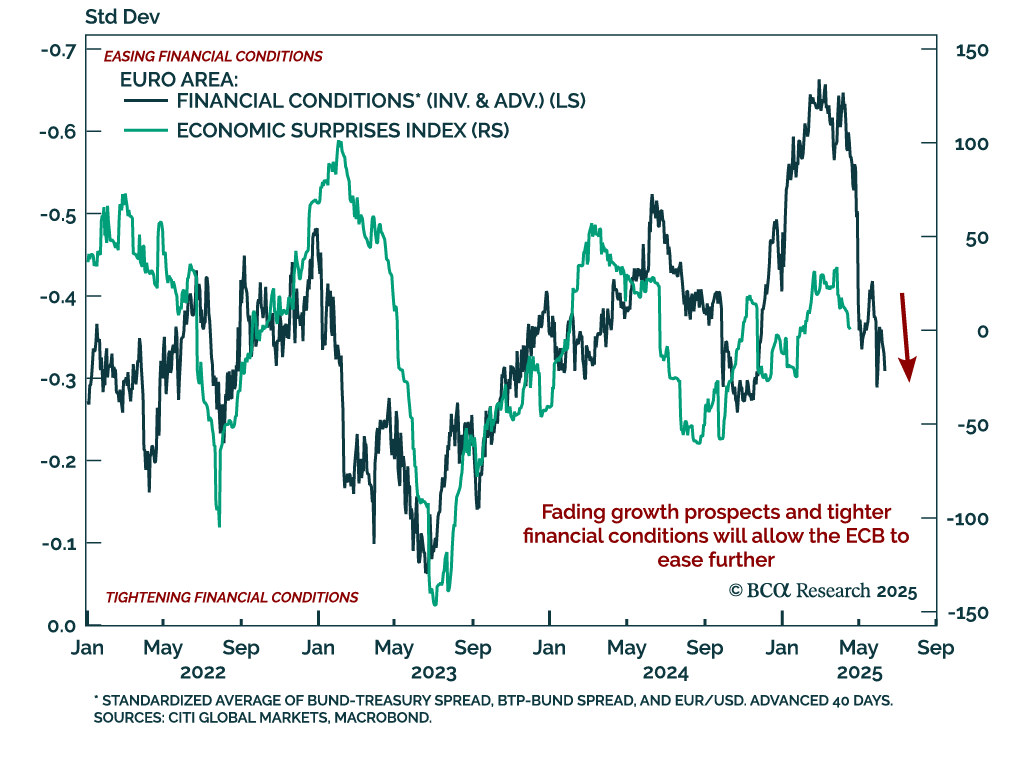
The ECB’s latest 25 bps cut and President Lagarde's notably dovish tone amid rising trade uncertainty reinforce our long December 2025 ESTR futures versus SOFR position. The deposit facility rate now stands at 2.25%, and Lagarde reiterated the disinflationary…
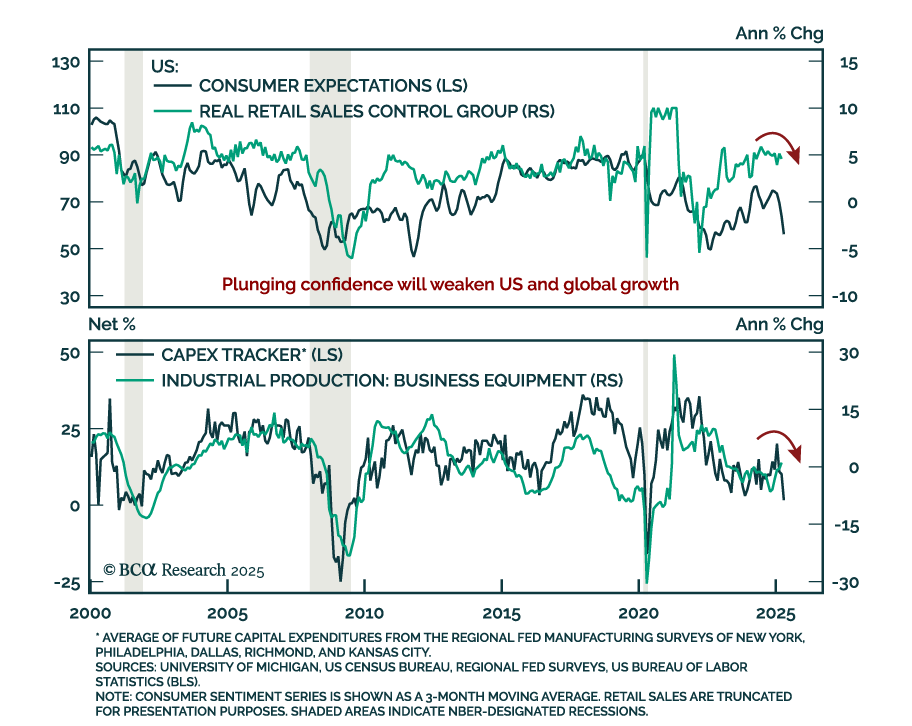
Soft data continues to deteriorate and hard data will soon follow, reinforcing our defensive asset allocation. Consumer and business confidence have plunged as policy uncertainty and inflation expectations rise, with spending, hiring and capex plans…
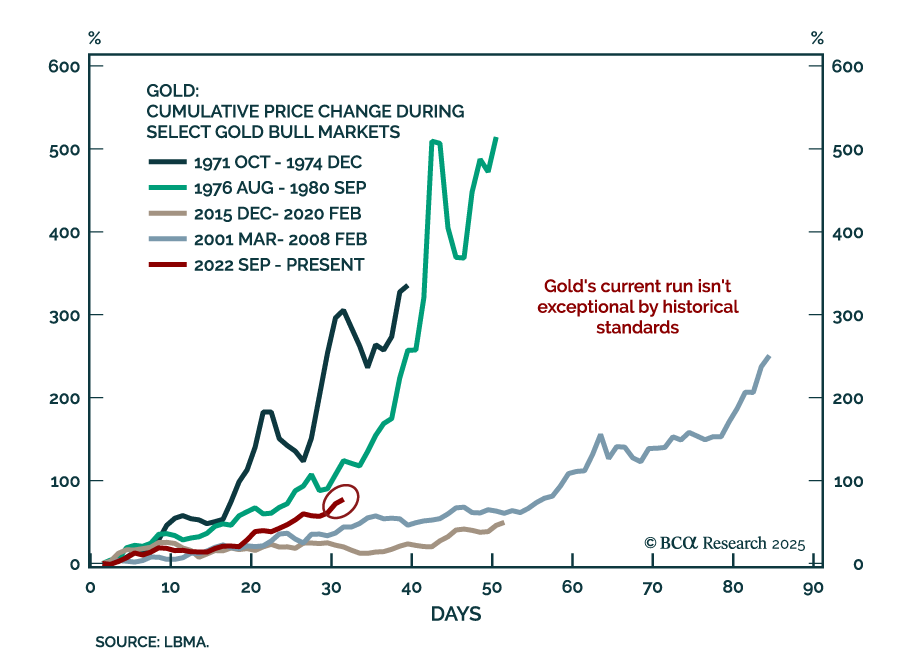
Our Commodity strategists remain defensive as both demand- and supply risks abound. Stay long gold and underweight oil and copper as increasing OPEC+ supply and tariff-driven demand risks will hurt energy and industrial metals prices. The motivations…