Latest from BCA Research
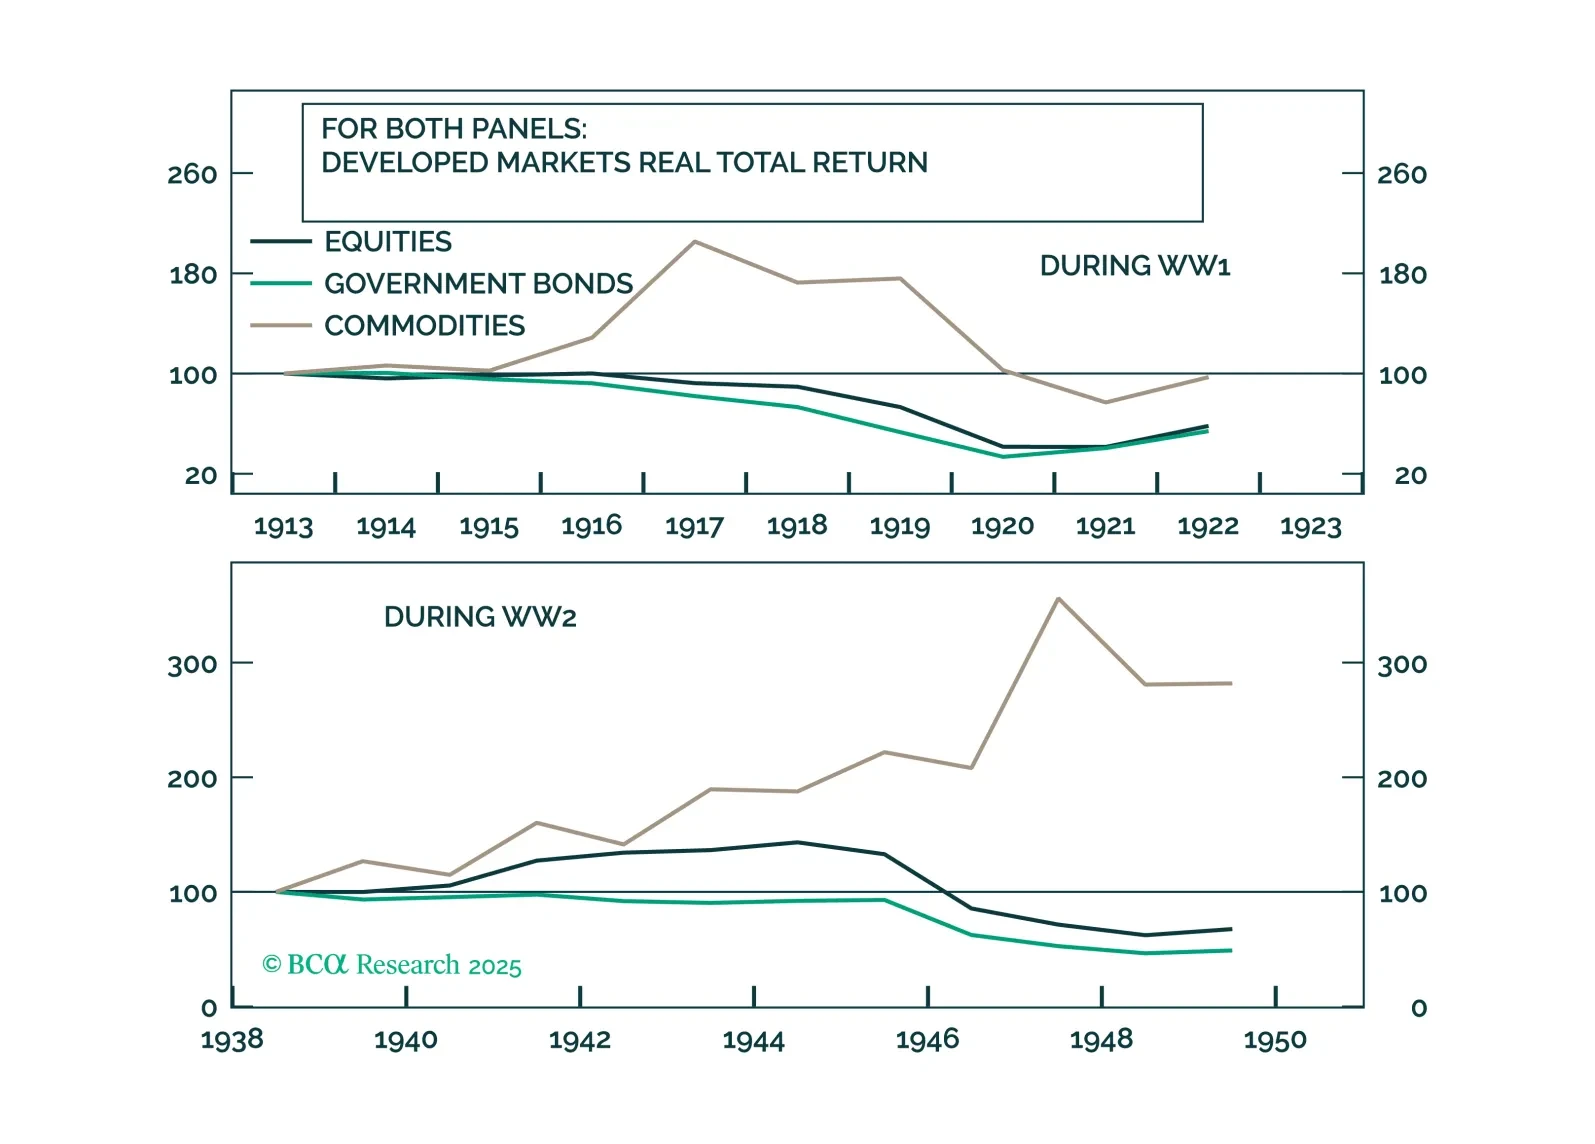
World War III will not happen. But if you disagree, here is our portfolio to hedge it: commodities, neutrals, and crypto.
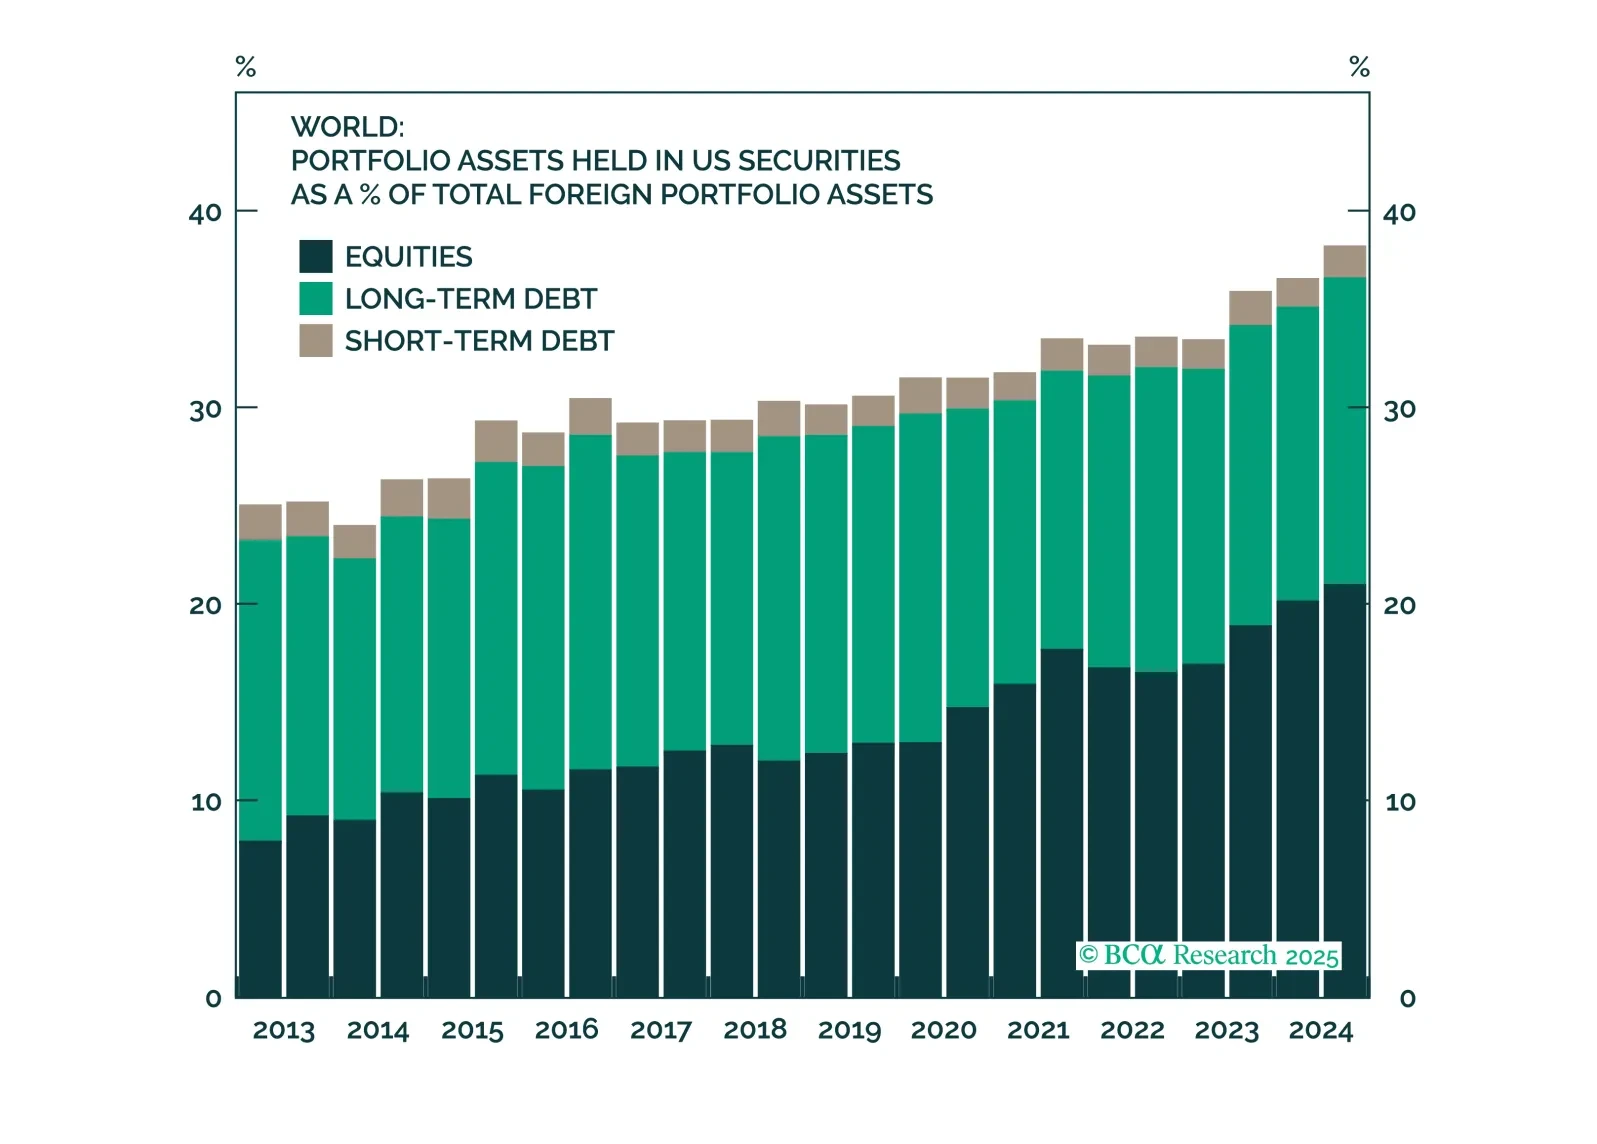
The dollar’s early 2025 decline was a reflection of a global rush to hedge accumulated USD exposure, not a mass exodus from US assets. With most hedging now complete, currency moves should again follow fundamentals, setting the stage for a tactical USD rebound in the months ahead.
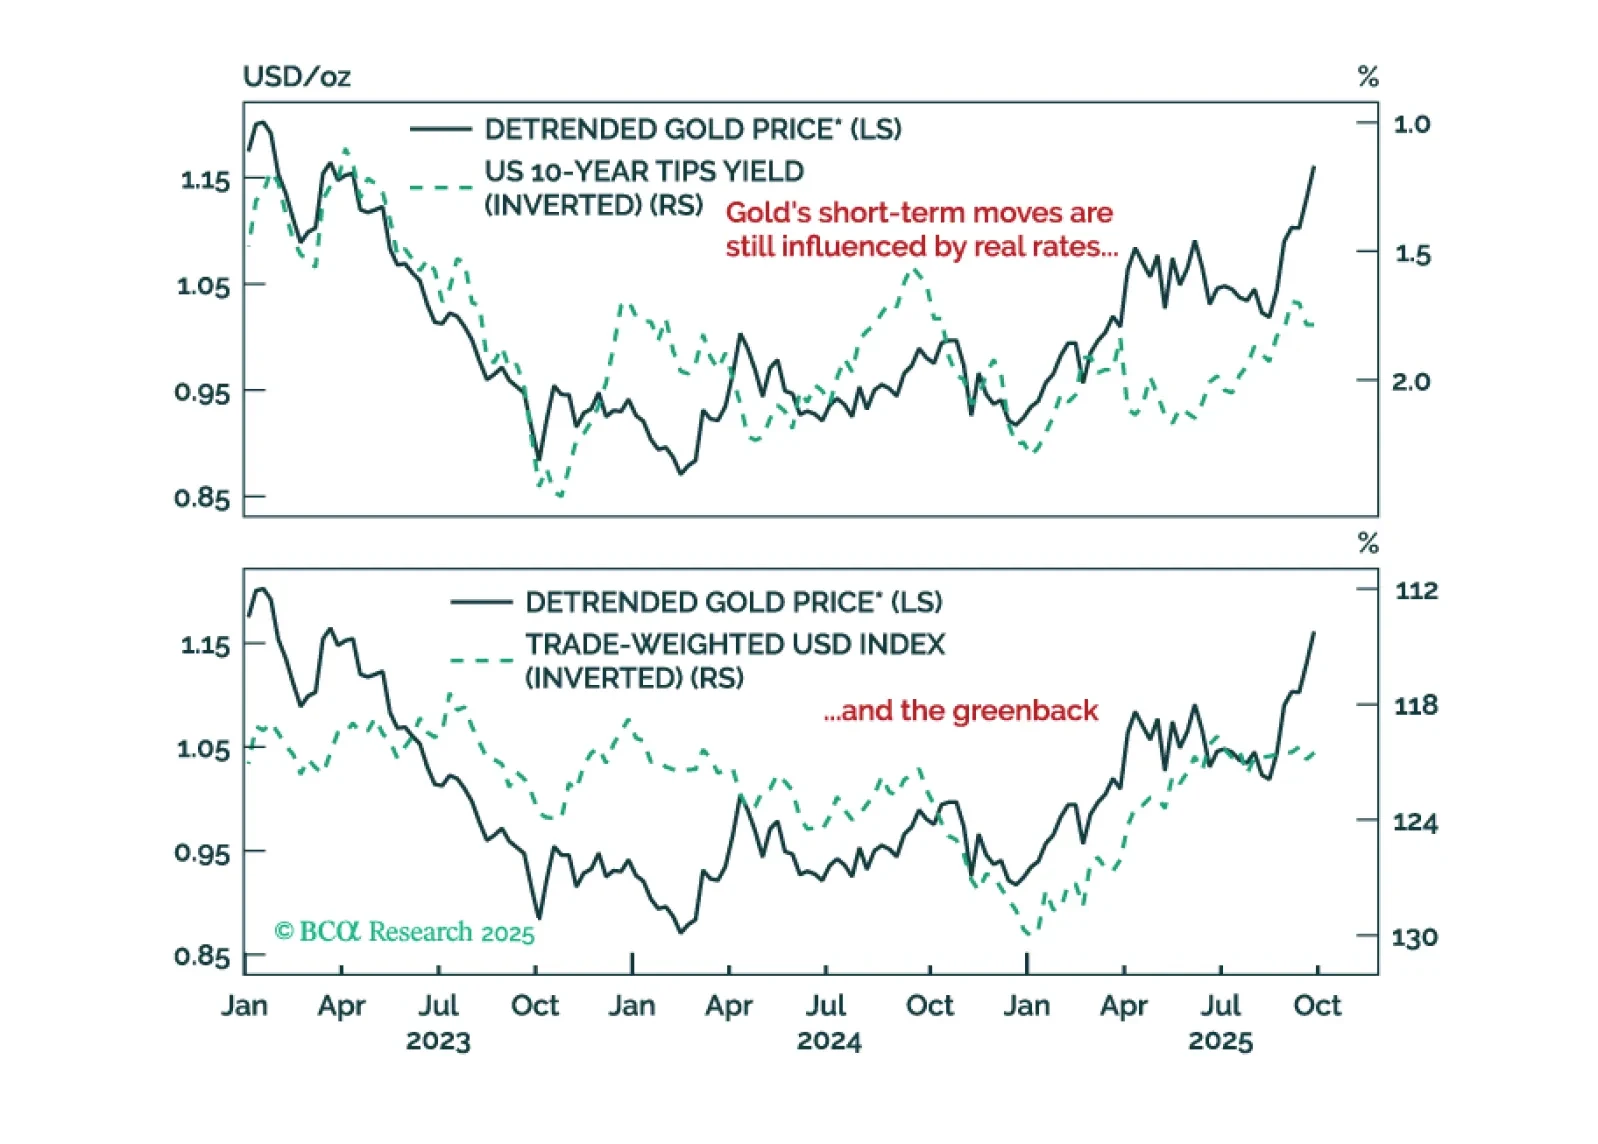
Commodity market breadth would need to improve for it to signal bullish conditions for the aggregate commodity complex. We maintain a defensive tilt within commodities, favoring precious metals over the more cyclically sensitive energy and industrial metals.
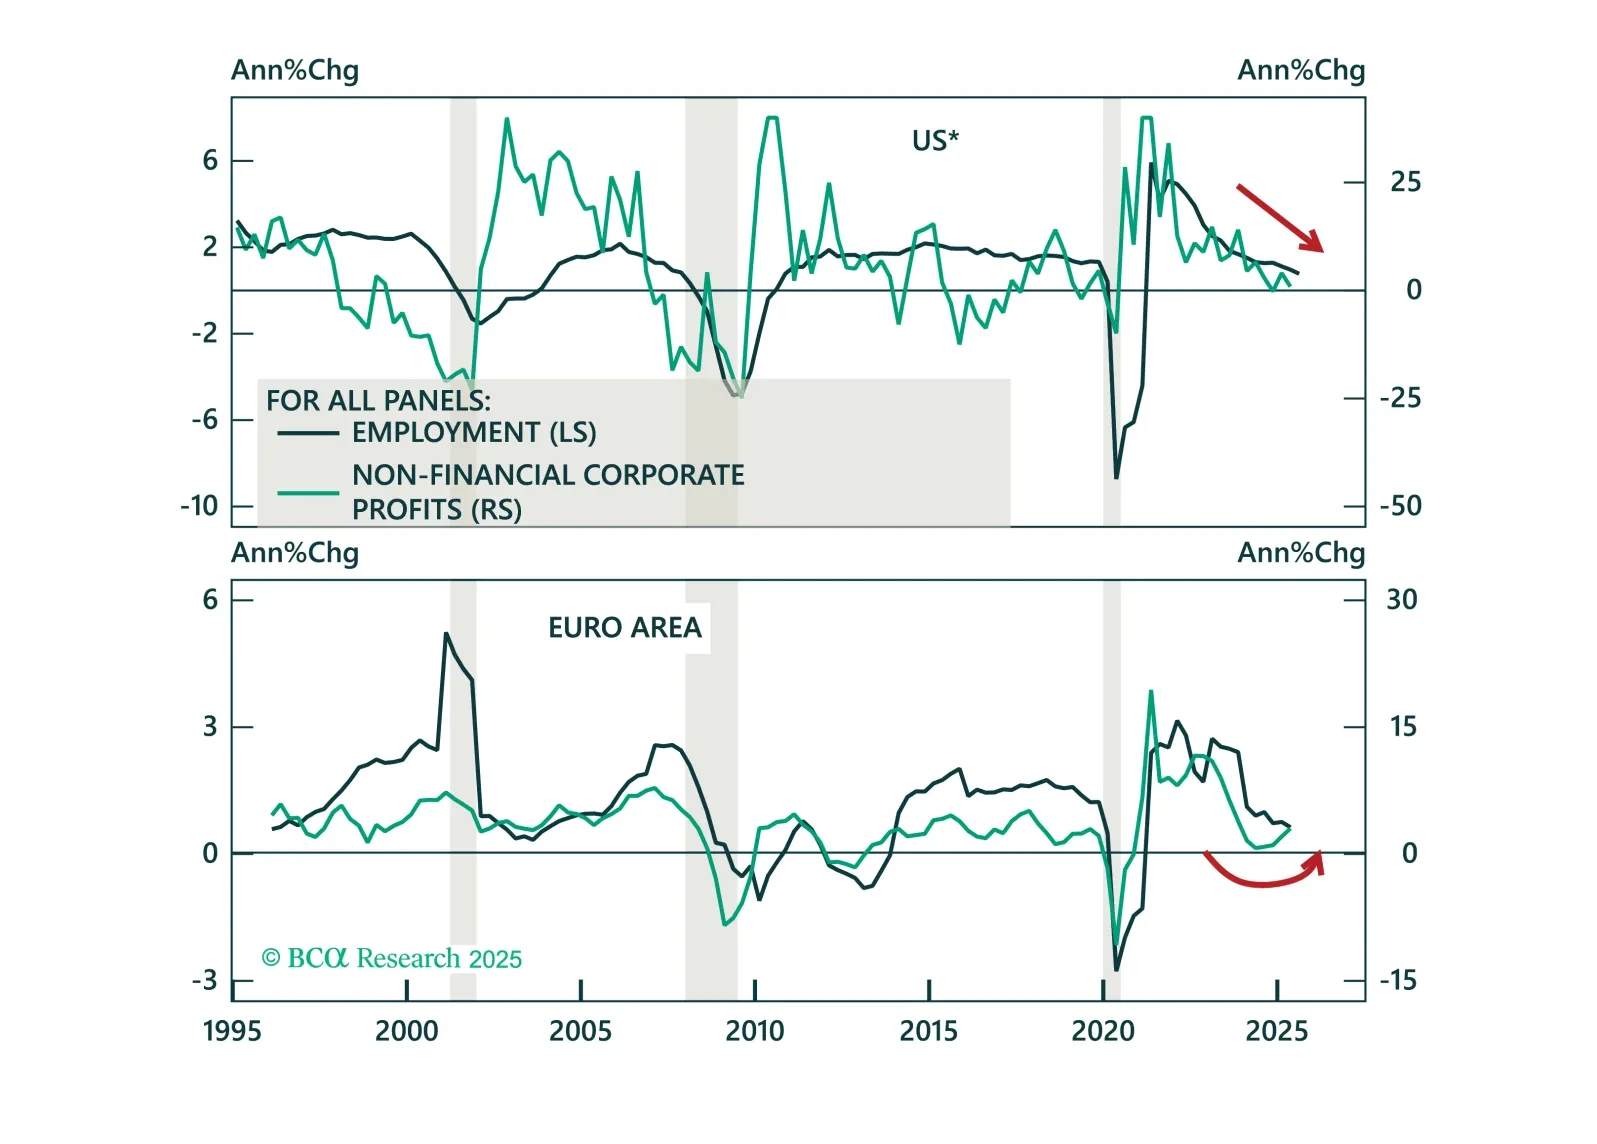
Despite concerns about fiscal sustainability, a rise in term premia, and attacks on central bank independence, monetary policy remains the primary driver of bond markets. In our Q3 Review & Outlook, we update our views and identify opportunities in government bonds, short-term interest rate futures, global yield curves, inflation-linked bonds, and credit.
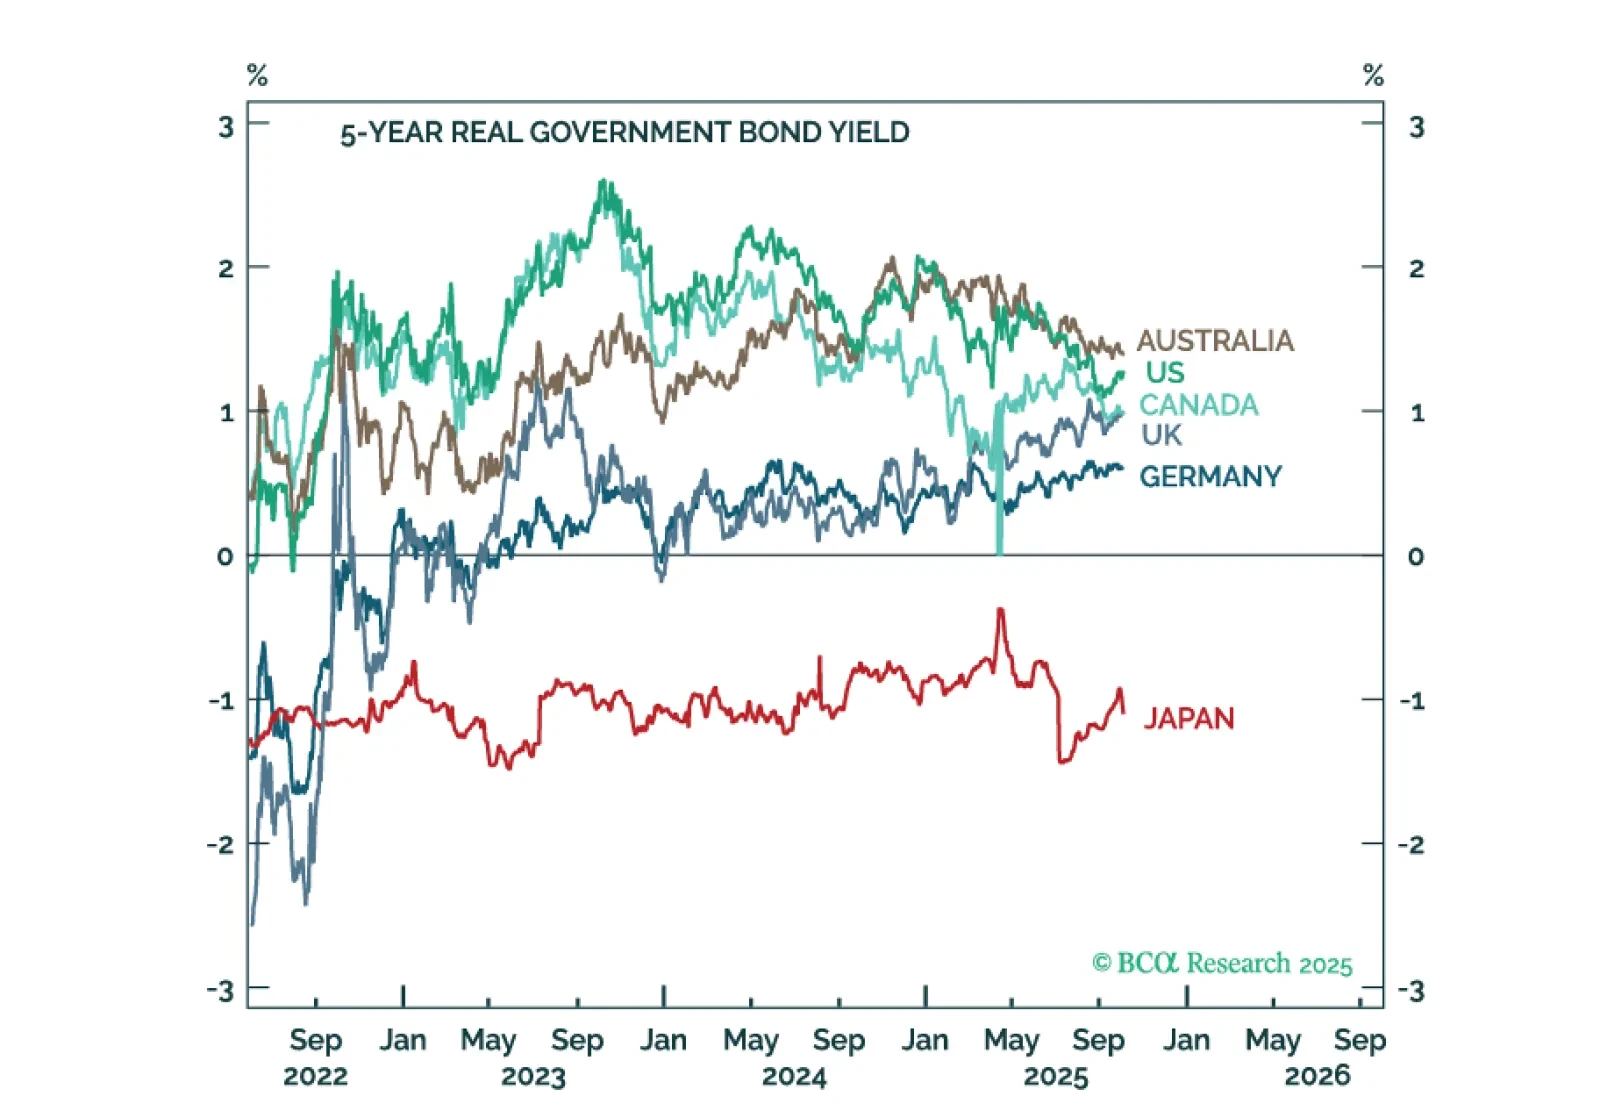
The surprise election of Sanae Takaichi as Japan’s ruling party new leader has delivered yet another blow to the beleaguered yen. Takaichi is widely expected to pursue the basic tenets of Abenomics – easier fiscal and monetary policy.
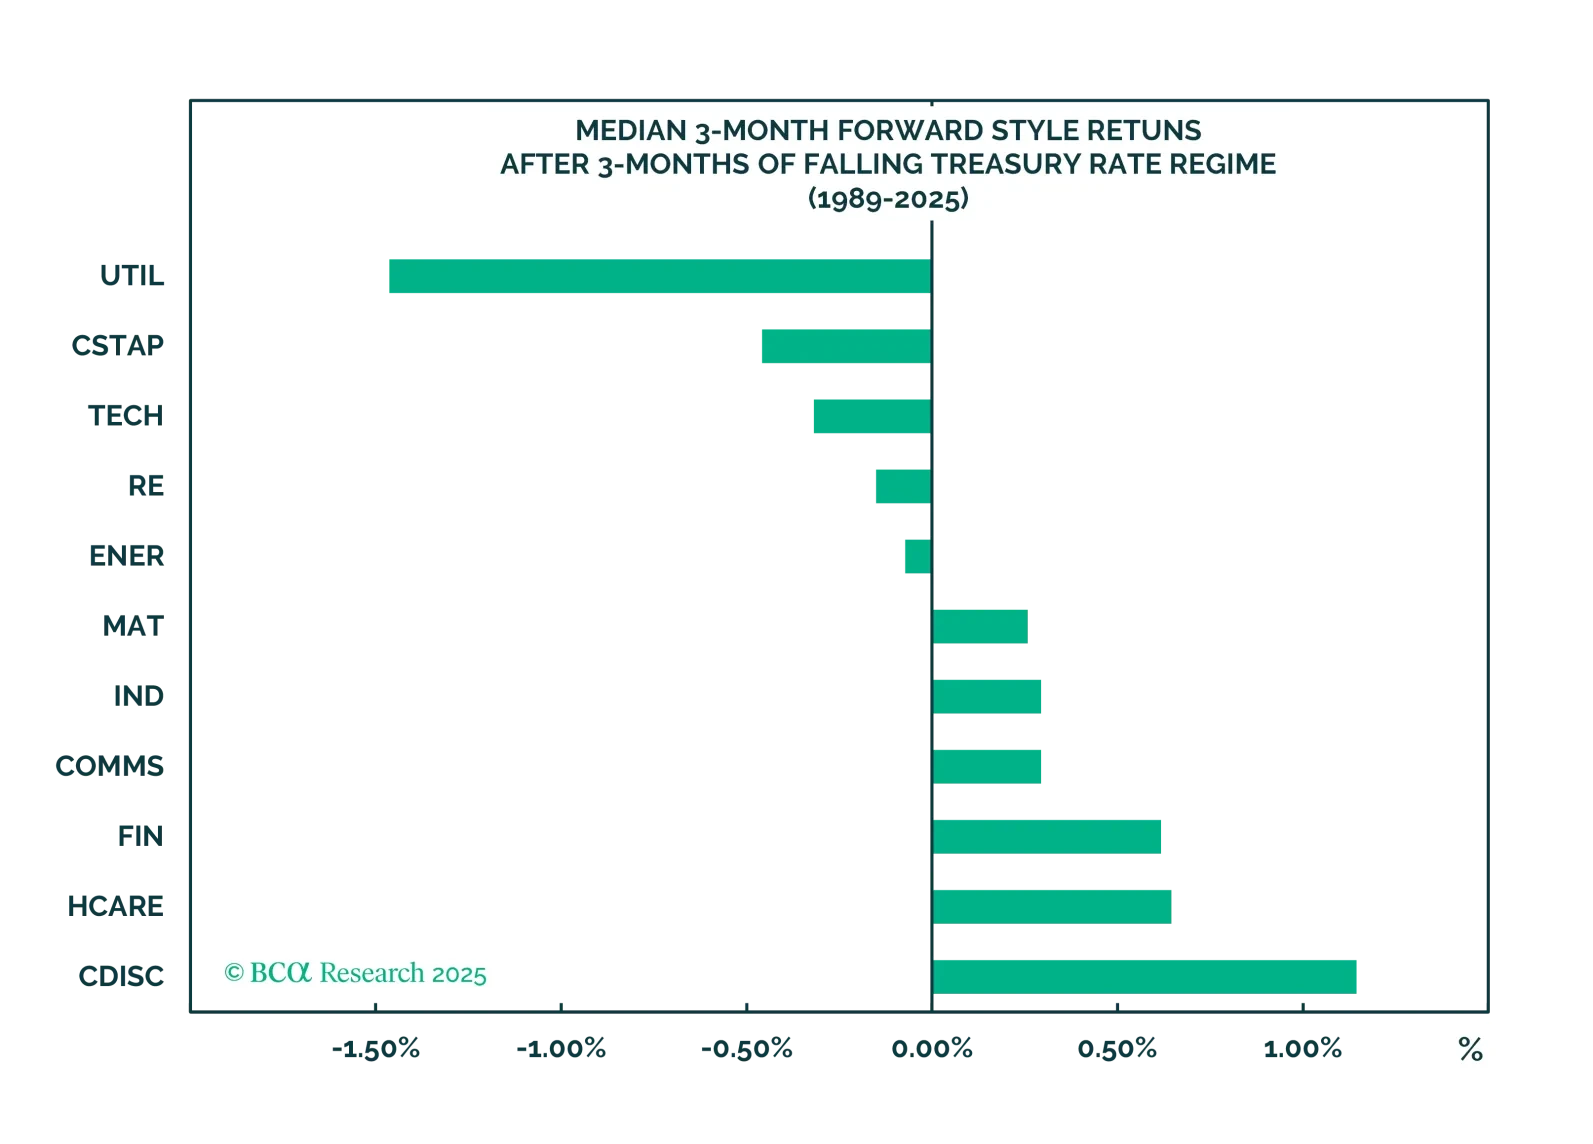
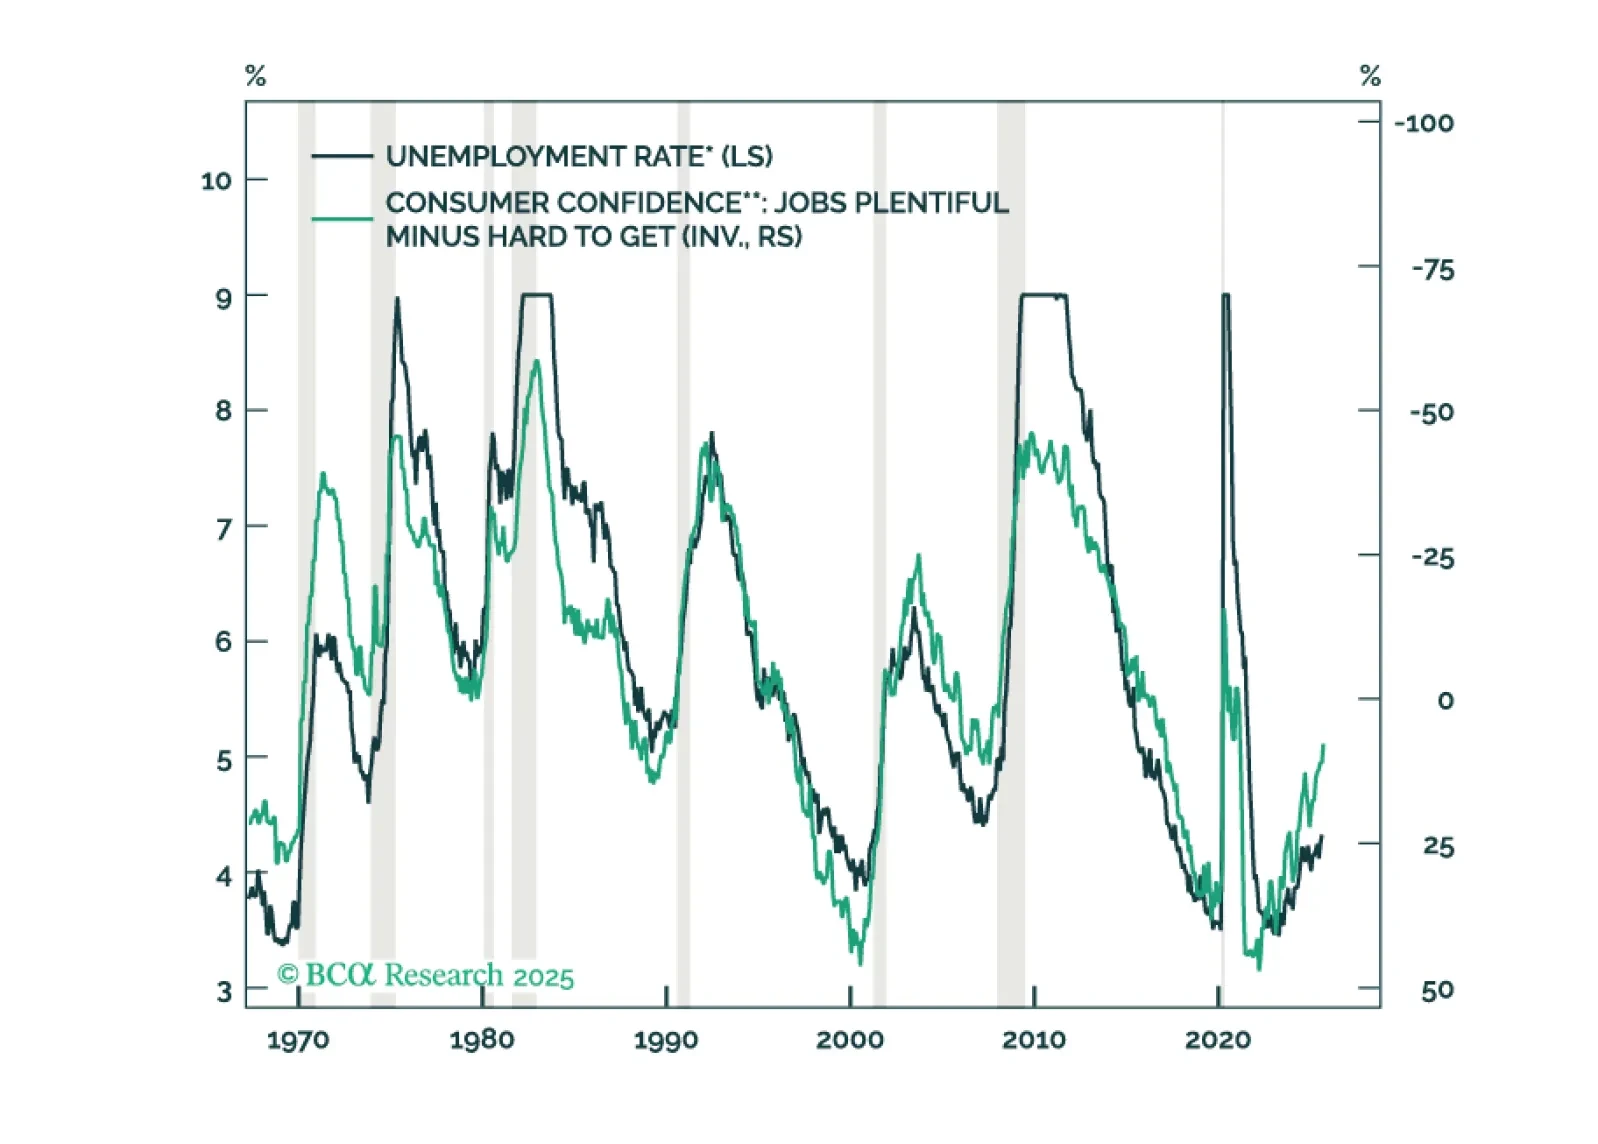
The economy remains resilient despite a softening labor market. As the economy shifts from labor toward capital, we may be in the early stages of a “jobless boom.” Our bull case for equities rests on strong earnings growth, accelerating GenAI adoption, monetary easing, and stimulus from OBBBA. Key risks we continue to monitor are rising bond yields and the threat of stagflation.
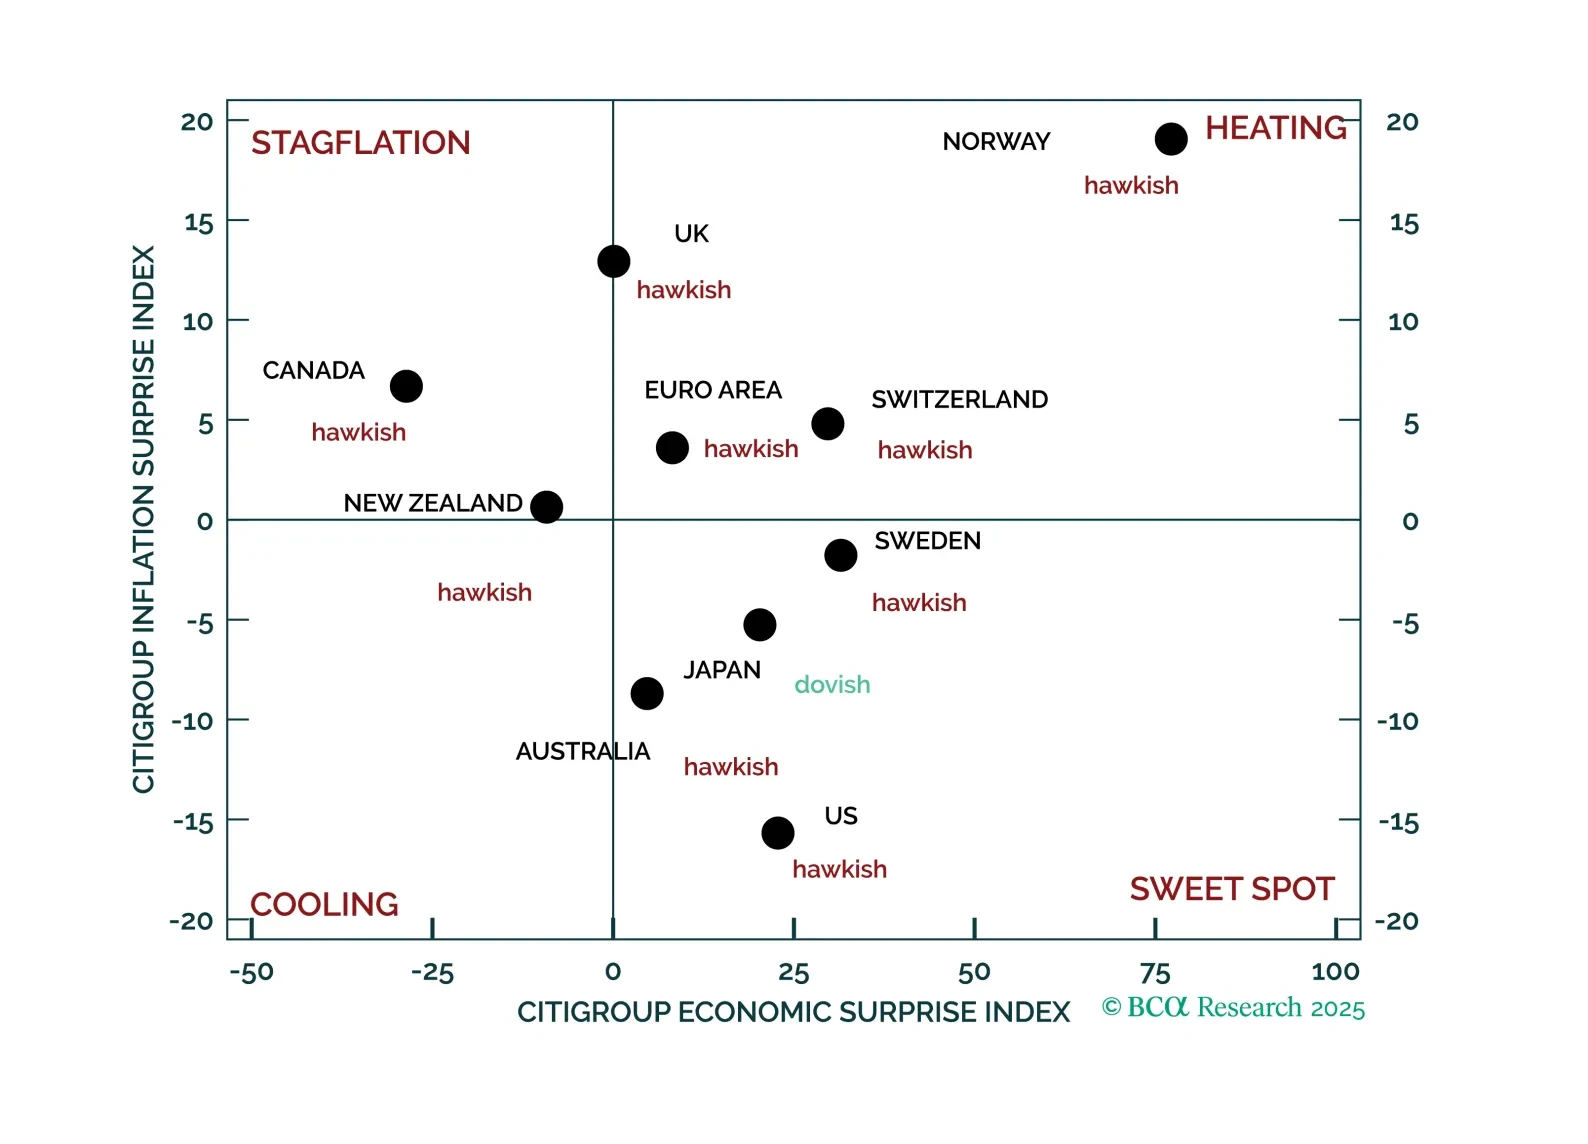
In this update, we apply our Macro Surprises framework to equities for the first time. Overall, the message is broadly consistent with our current equity views: Investors should favor Eurozone equities and continue to overweight cyclical sectors relative to defensive ones.

The K-shaped economy aptly describes the bifurcation between low- and high-end households but it’s not something investors should celebrate if they want the expansion to continue.
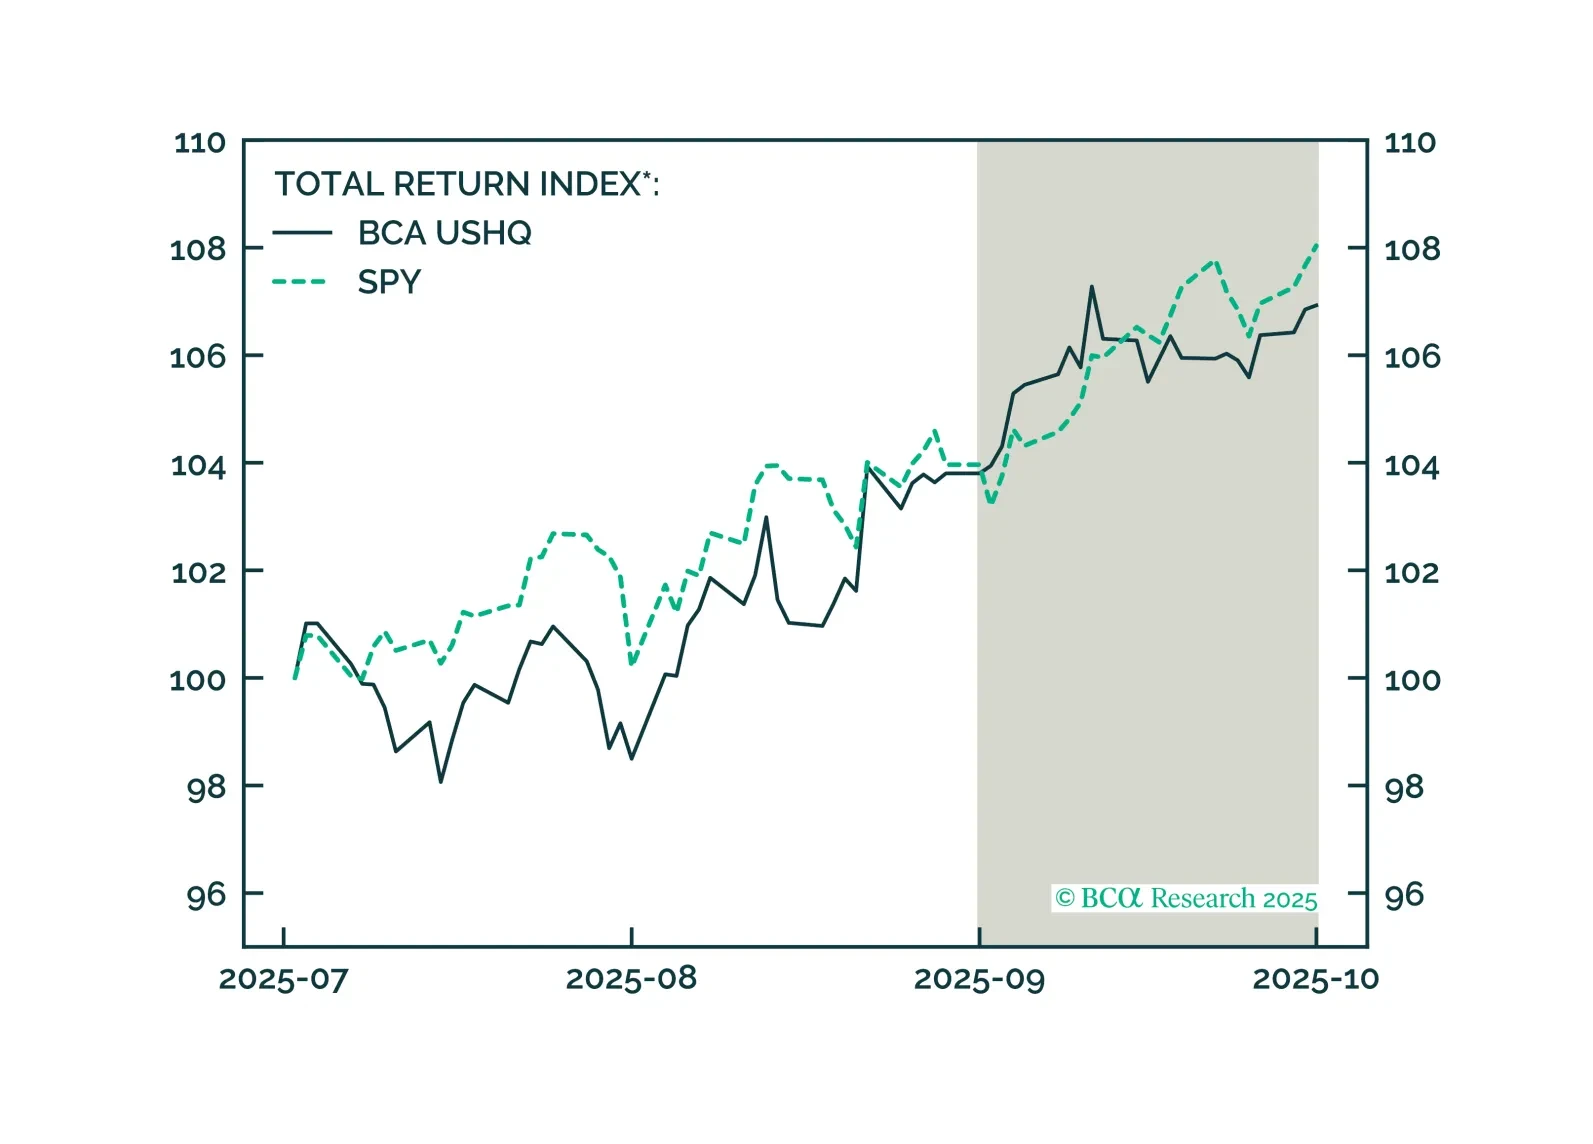
The US High Quality (USHQ) portfolio underperformed its benchmark through September, returning 3.01%, whilst its SPY benchmark returned 3.91%. However, our US High Quality SMID (USHQ SMID) portfolio continues to show strength, with another solid month of performance. The portfolio returned 2.69%, outperforming its MSCI US Mid Cap benchmark by 169bps.