Fixed Income

The November CPI came in line with expectations, accelerating to 0.3% m/m (2.7% y/y) from 0.2% (2.6% y/y) in October. Core also printed at 0.3% m/m, the same as October and remaining at 3.3% y/y. The acceleration was mainly driven by food and used cars.…
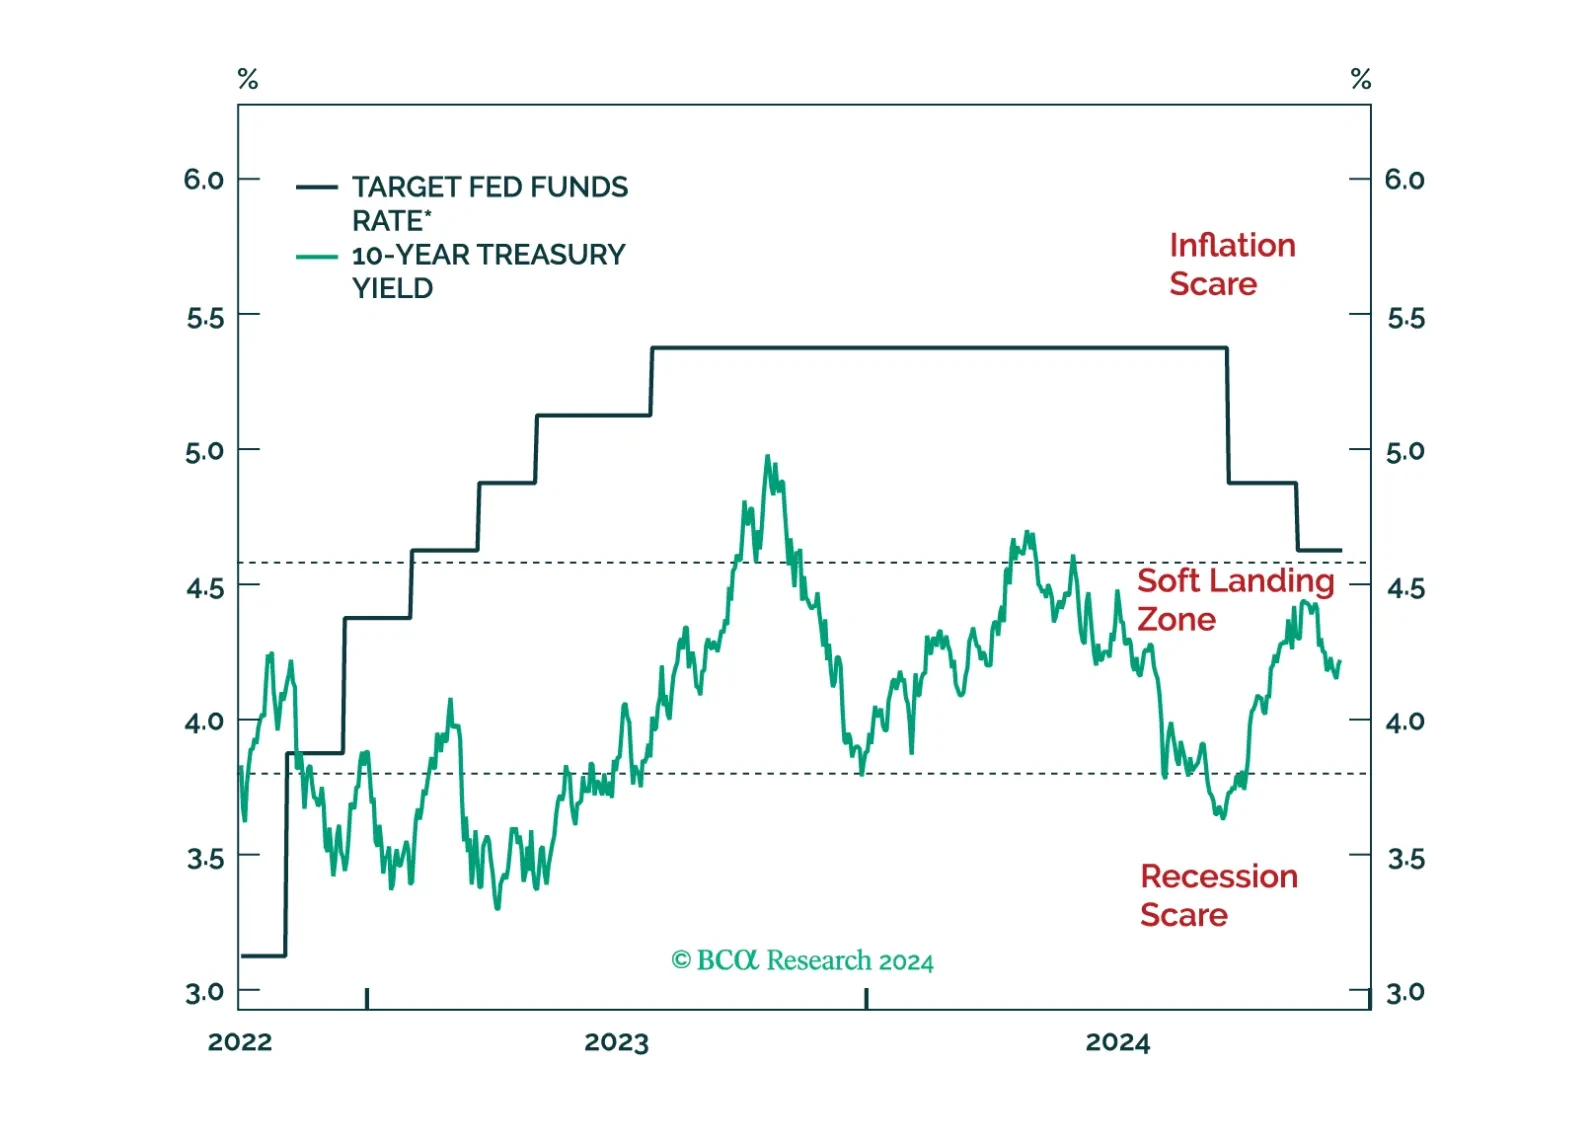
We offer 5 key investment views for US fixed income markets in 2025.
China’s November trade balance increased to CNY 692.8 bln on the back of slowing-but-still-growing exports (down to 5.8% y/y from 11.2% in October), and a worsening imports contraction (-4.7% y/y vs. -3.7% in October). In Japan, growth in machine tools orders…
The December Sentix Economic Index for the Euro Area missed expectations, declining to -17.5 vs. -12.8 in November. Both the current situation and expectations components declined. As the first sentiment indicator for December, the Sentix confirms the recent…
Our Counterpoint strategists published their 2025 outlook; they see major market movements for the year ahead hinging on Japan. Japan remains the cornerstone of global liquidity, with rising Japanese real yields posing a key risk. Monitoring Japanese real…
The US Treasury yield curve recently bull flattened, with the 2-year/10-year segment almost completely flat. Meanwhile, the breakeven inflation curve has re-inverted, with 2-year breakeven inflation rate now above the 10-year maturity by about 25 basis…
Our GeoMacro Strategy service published their 2025 outlook, and they see three peaks shaping the year: Peak fiscal, peak-deglobalization, and peak geopolitical risk. In 2024, our colleagues’ bullish economic outlook proved accurate in the first half, while…
Our European Investment Strategy and GeoMacro Strategy teams published a joint report, digging into the structural challenges behind Europe’s economic underperformance, while pointing out to potential turnaround opportunities. Europe’s prolonged…
Our Global Asset Allocation strategists published their monthly tactical asset allocation report and foresee a change of trend for 2025. “Thin is back in” for government budgets, growth, and valuations. The post-COVID recovery was marked by government…
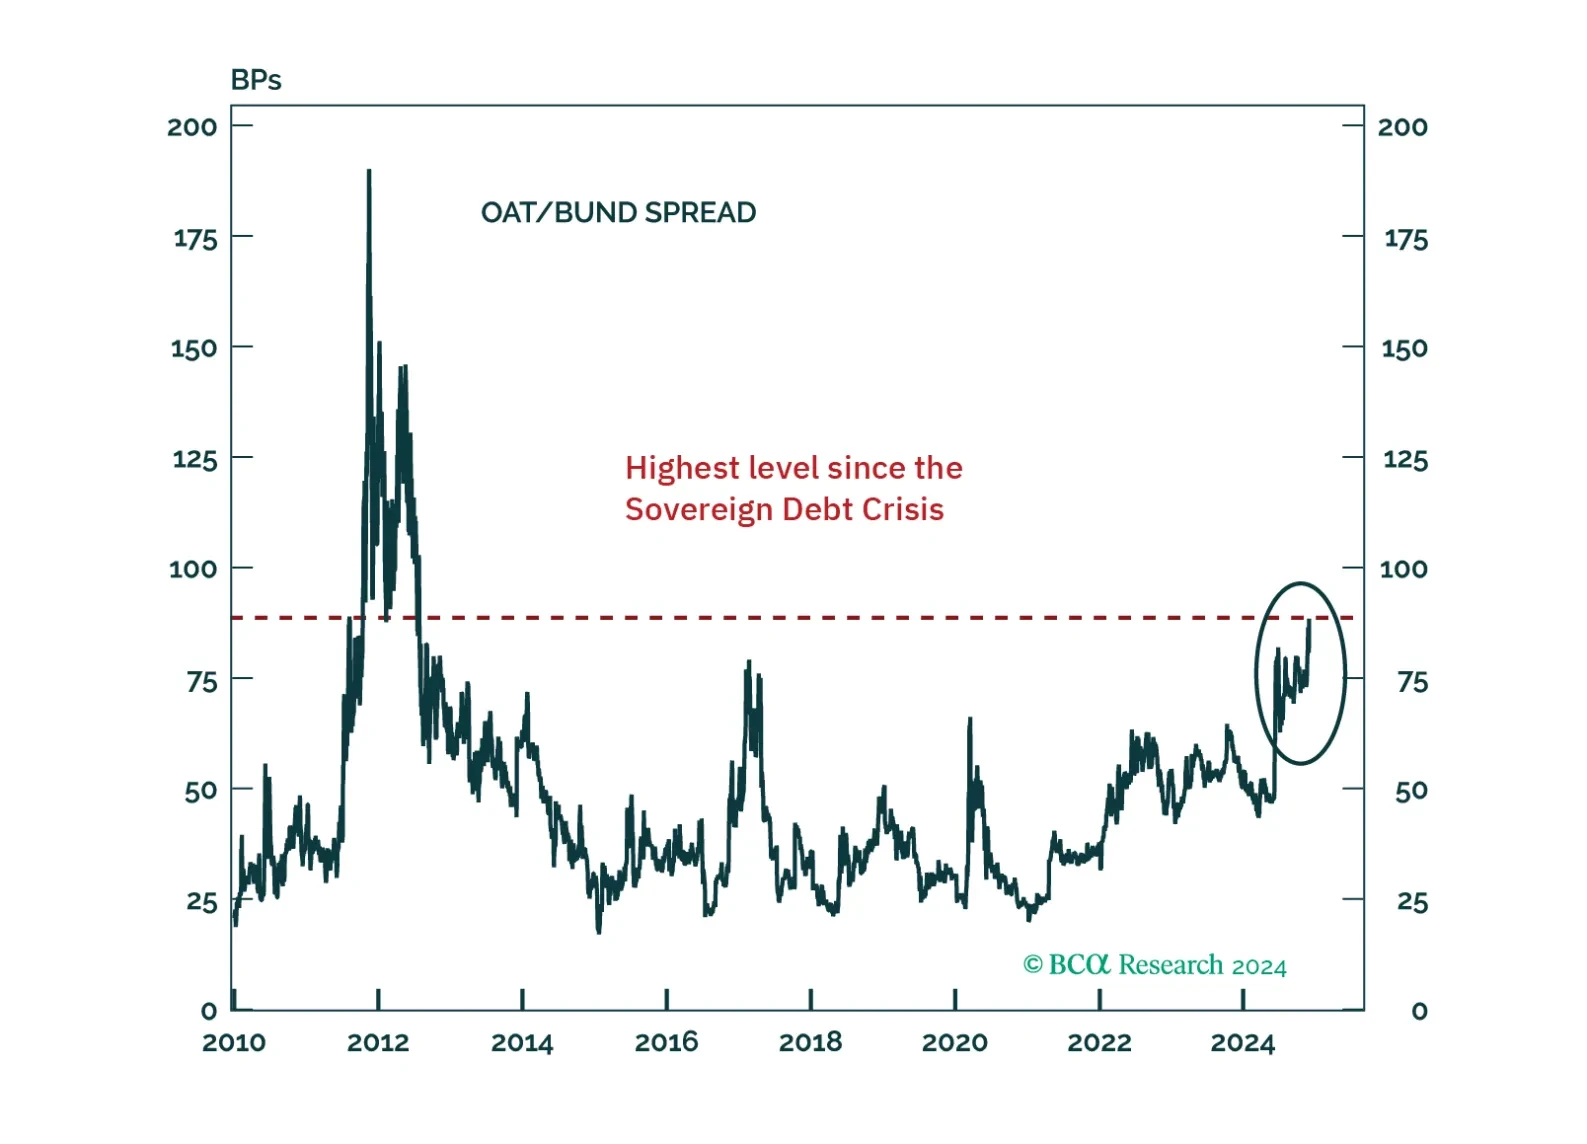
France finds itself in a unique, thorny situation. Can it heave itself out of it? And what does it mean for investors?