Portfolio
Public-private allocation guidance, capital market assumptions, and strategic insight to help investors build forward-looking portfolios they can act on and defend.
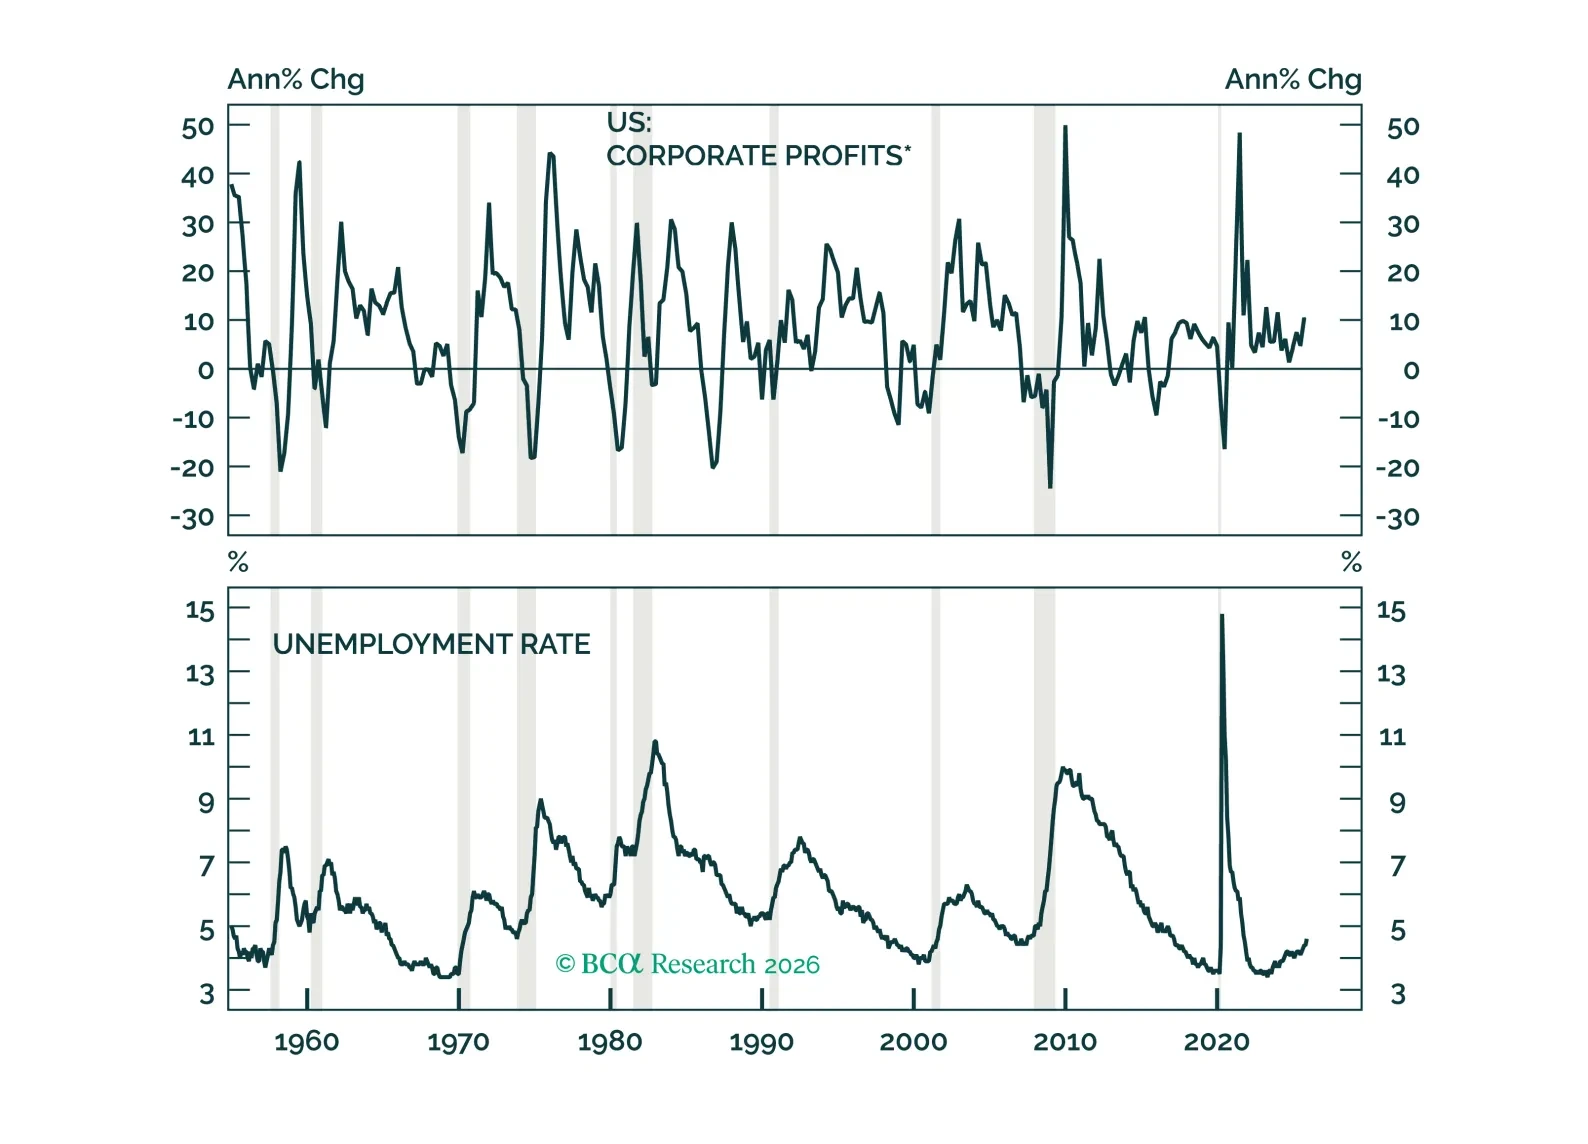
To start 2026, we answer what we believe are the most important questions facing investors surrounding the labor market, monetary and fiscal policy, and AI stocks. Overall, we reiterate our overweight views on risk assets and highlight the risks surrounding the upcoming tariff decision.
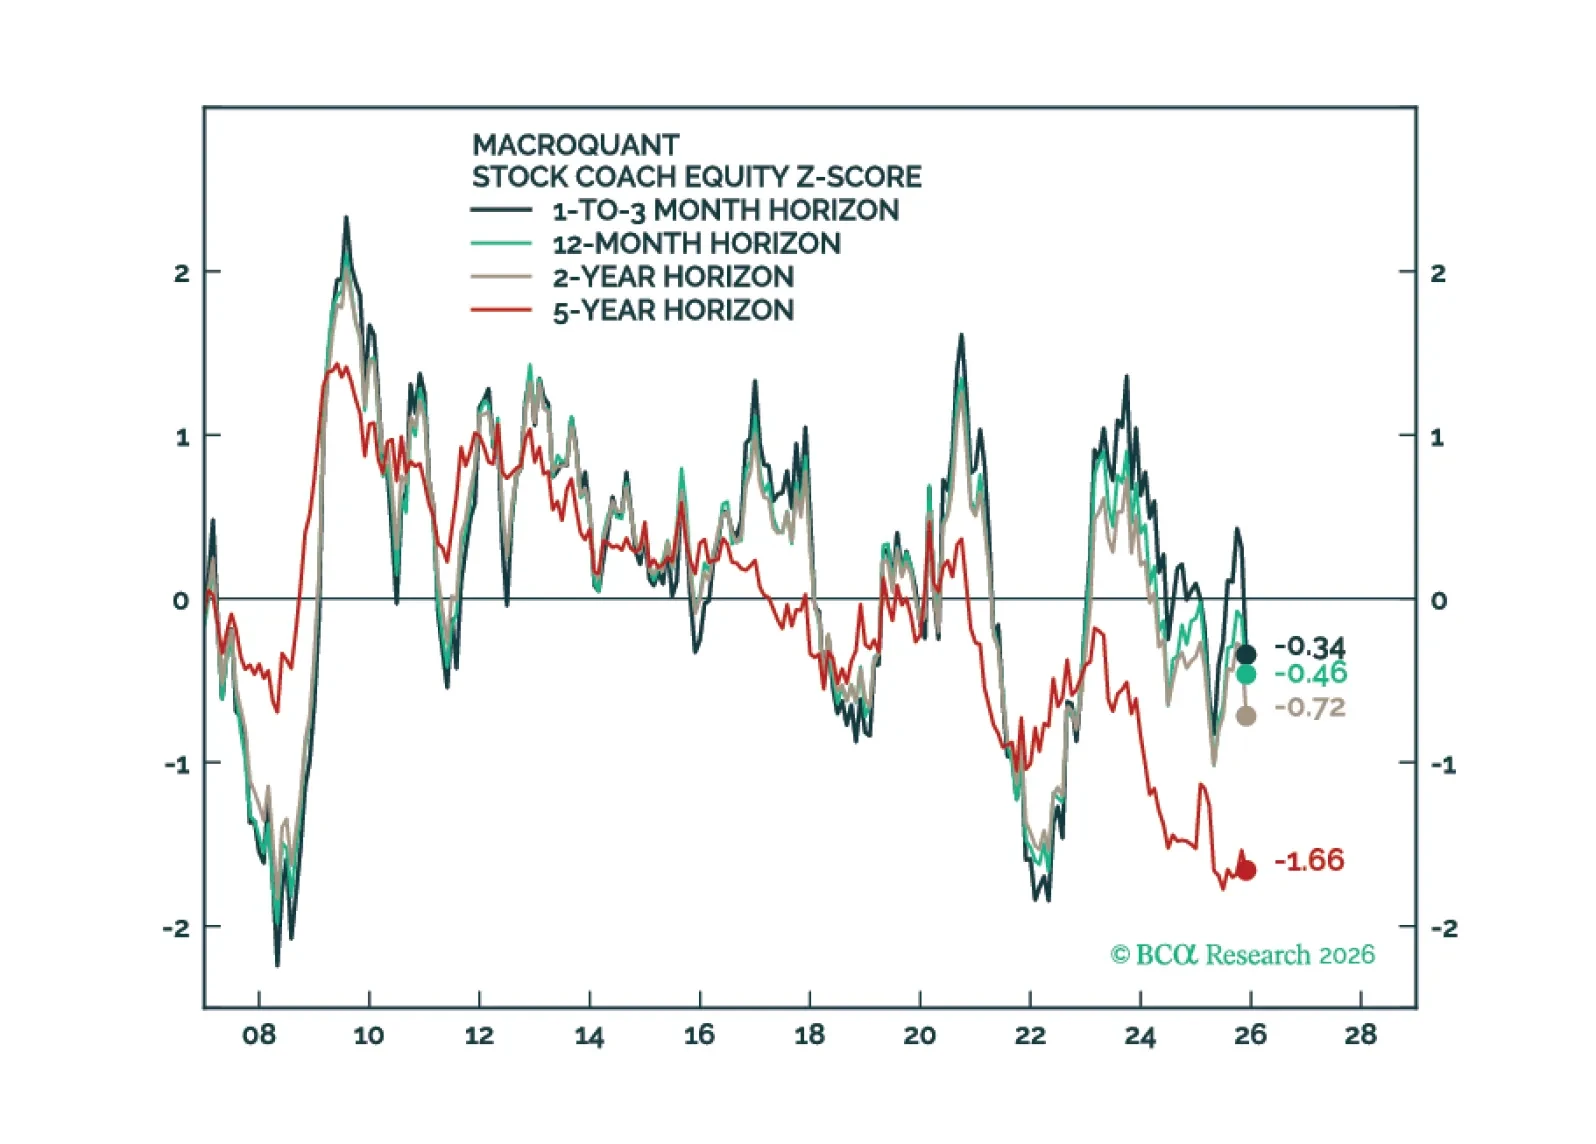
MacroQuant has downgraded equities to underweight, favors a below-benchmark duration stance in fixed-income portfolios, remains bearish on the US dollar, and is still bullish on gold.
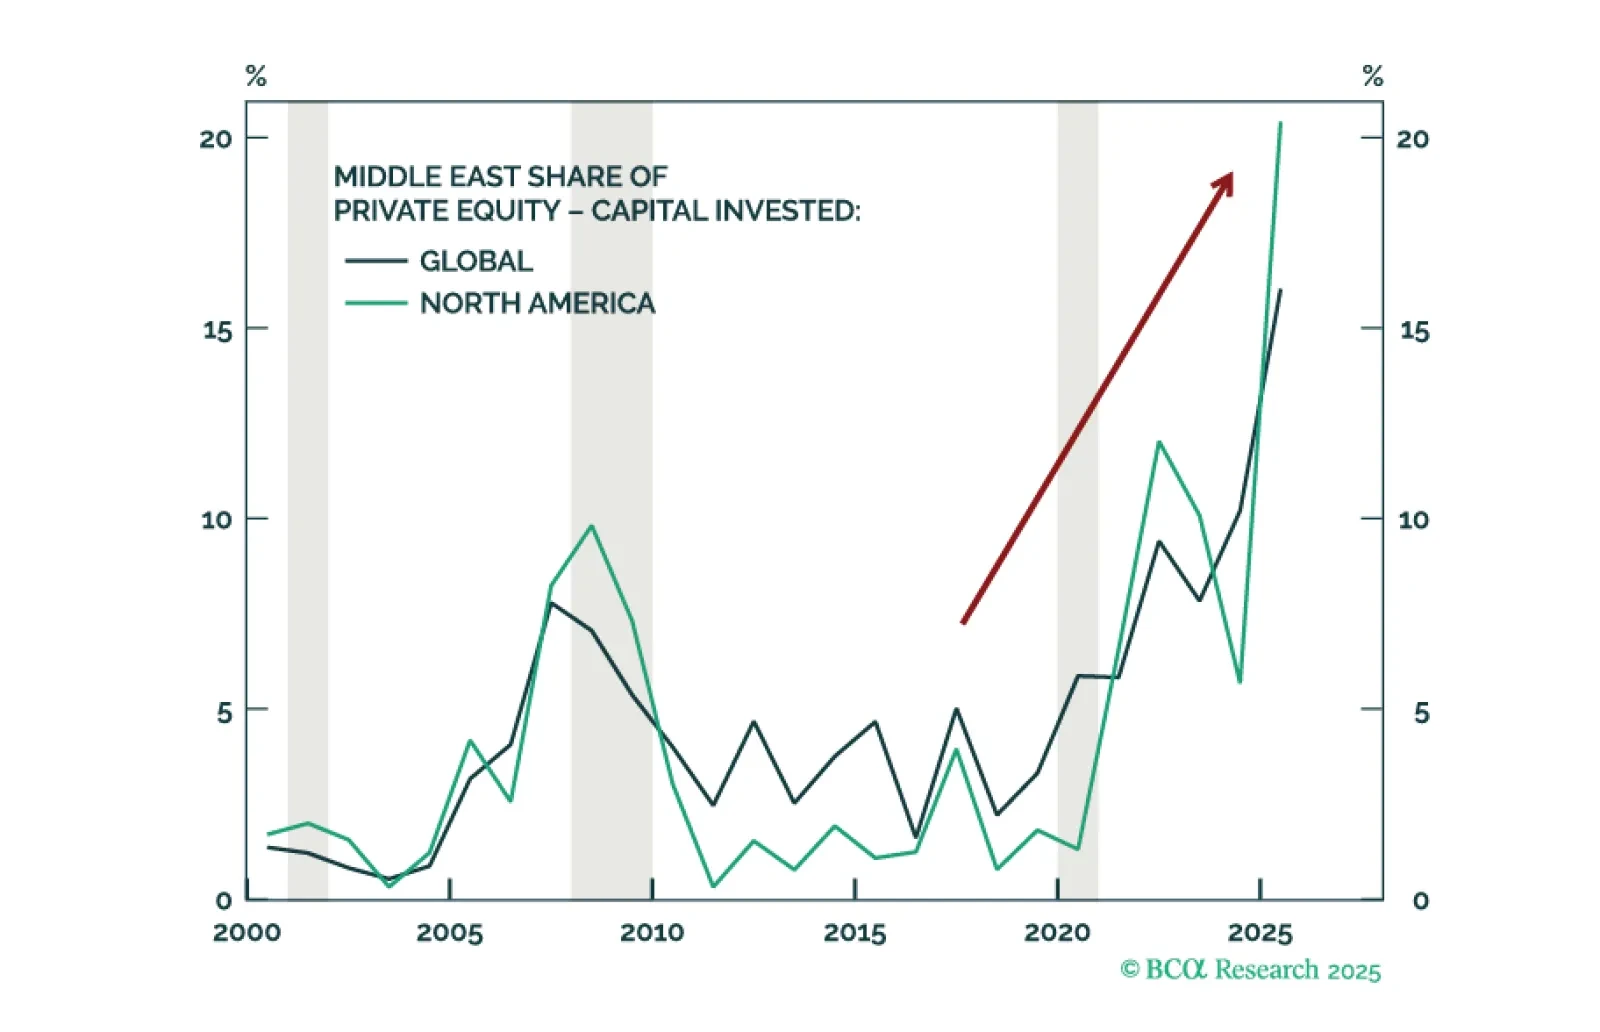
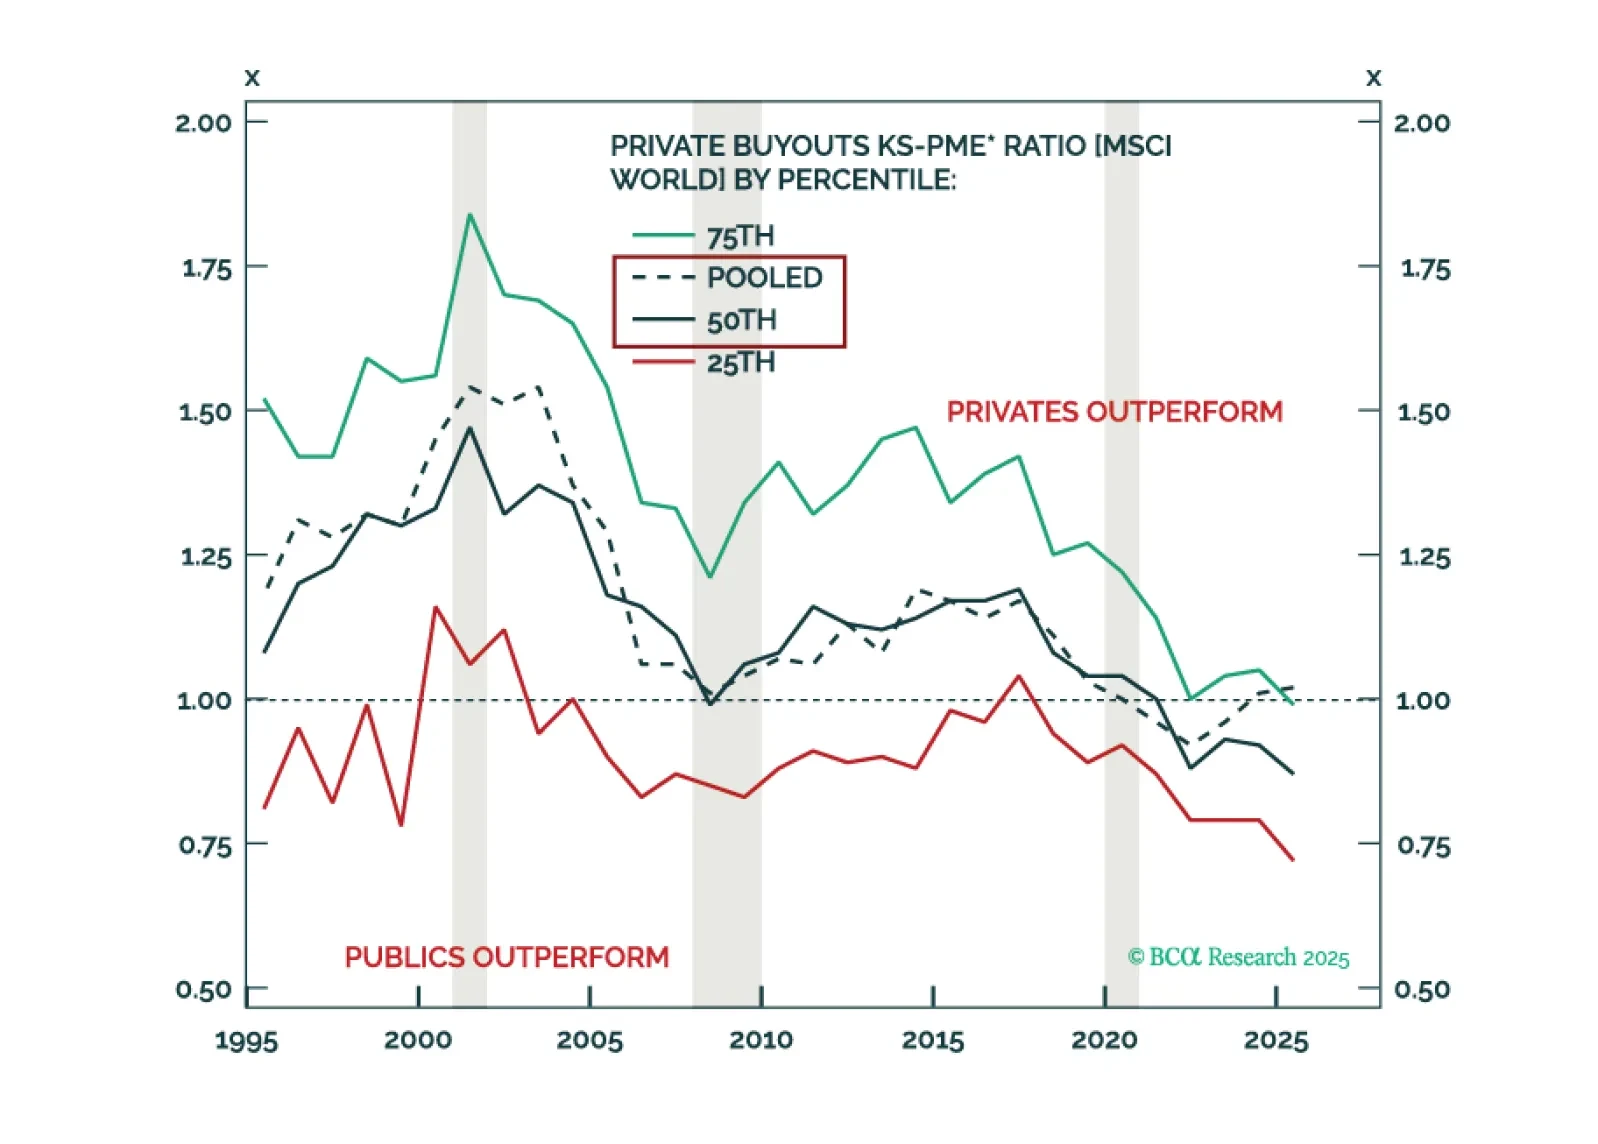
2026 is shaping up to be a fertile backdrop for new Private Equity commitments, and our views are turning increasingly constructive. However, three risks remain on our radar: The overhang, Middle East capital, and Evergreen funds.
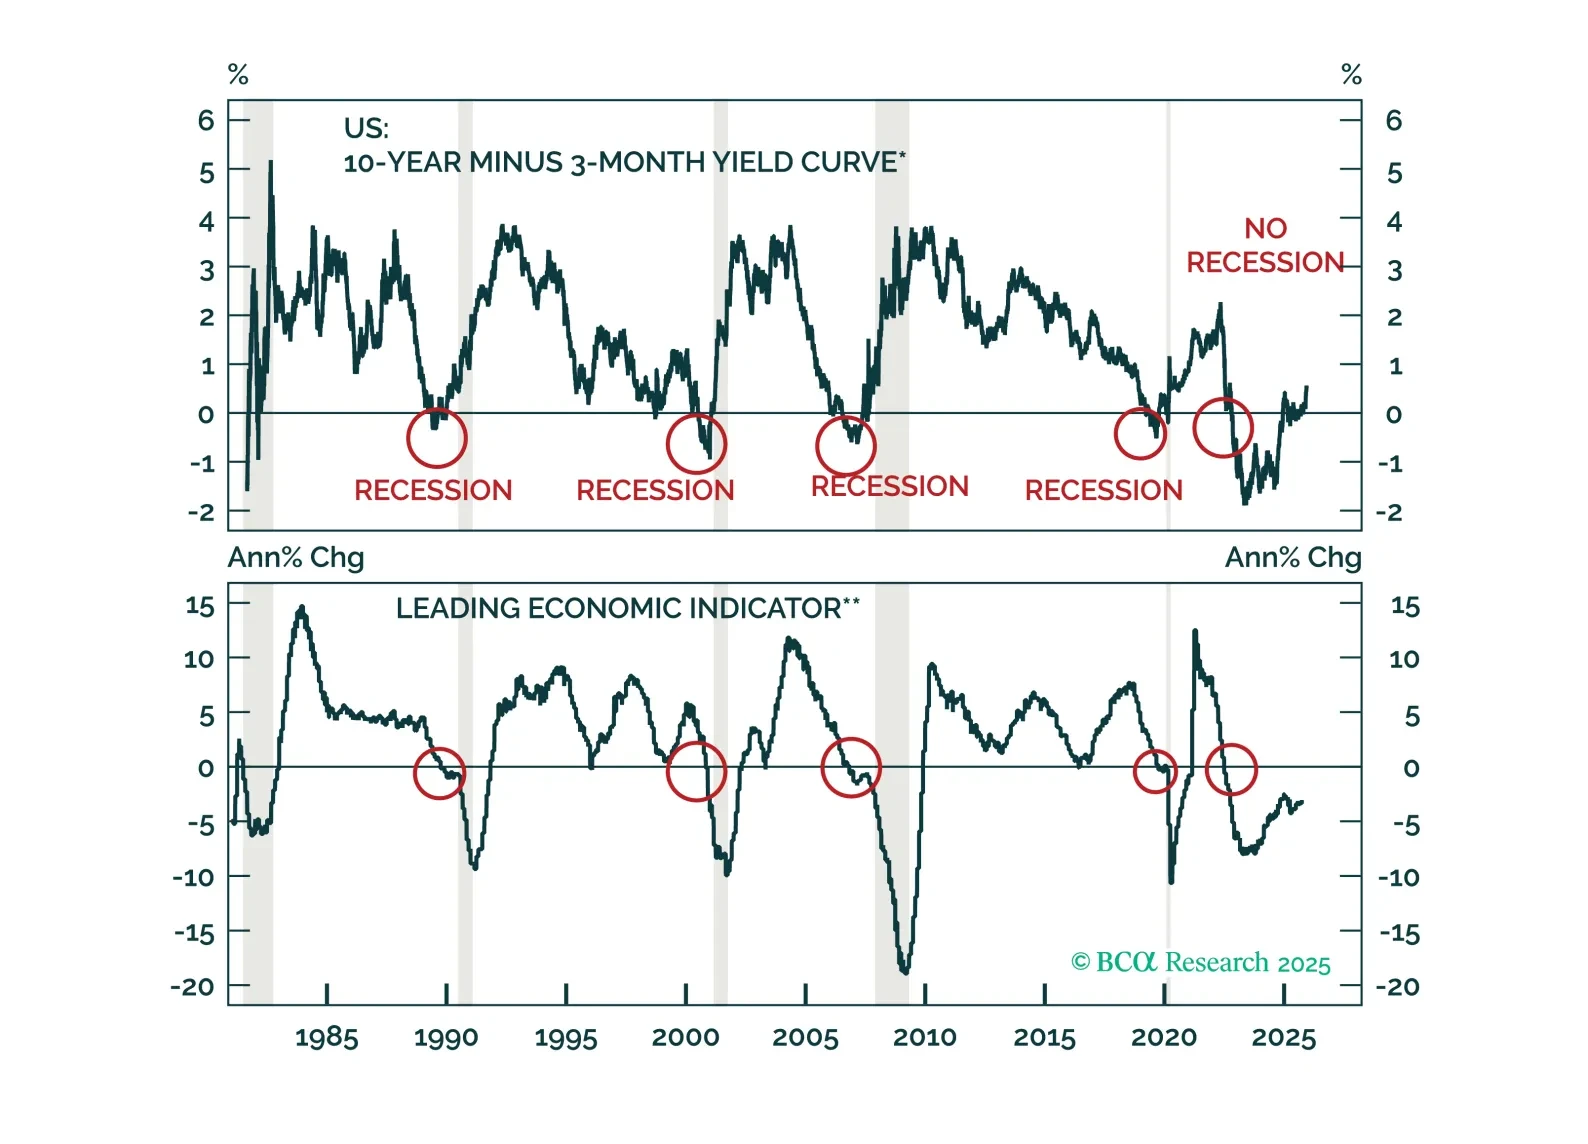
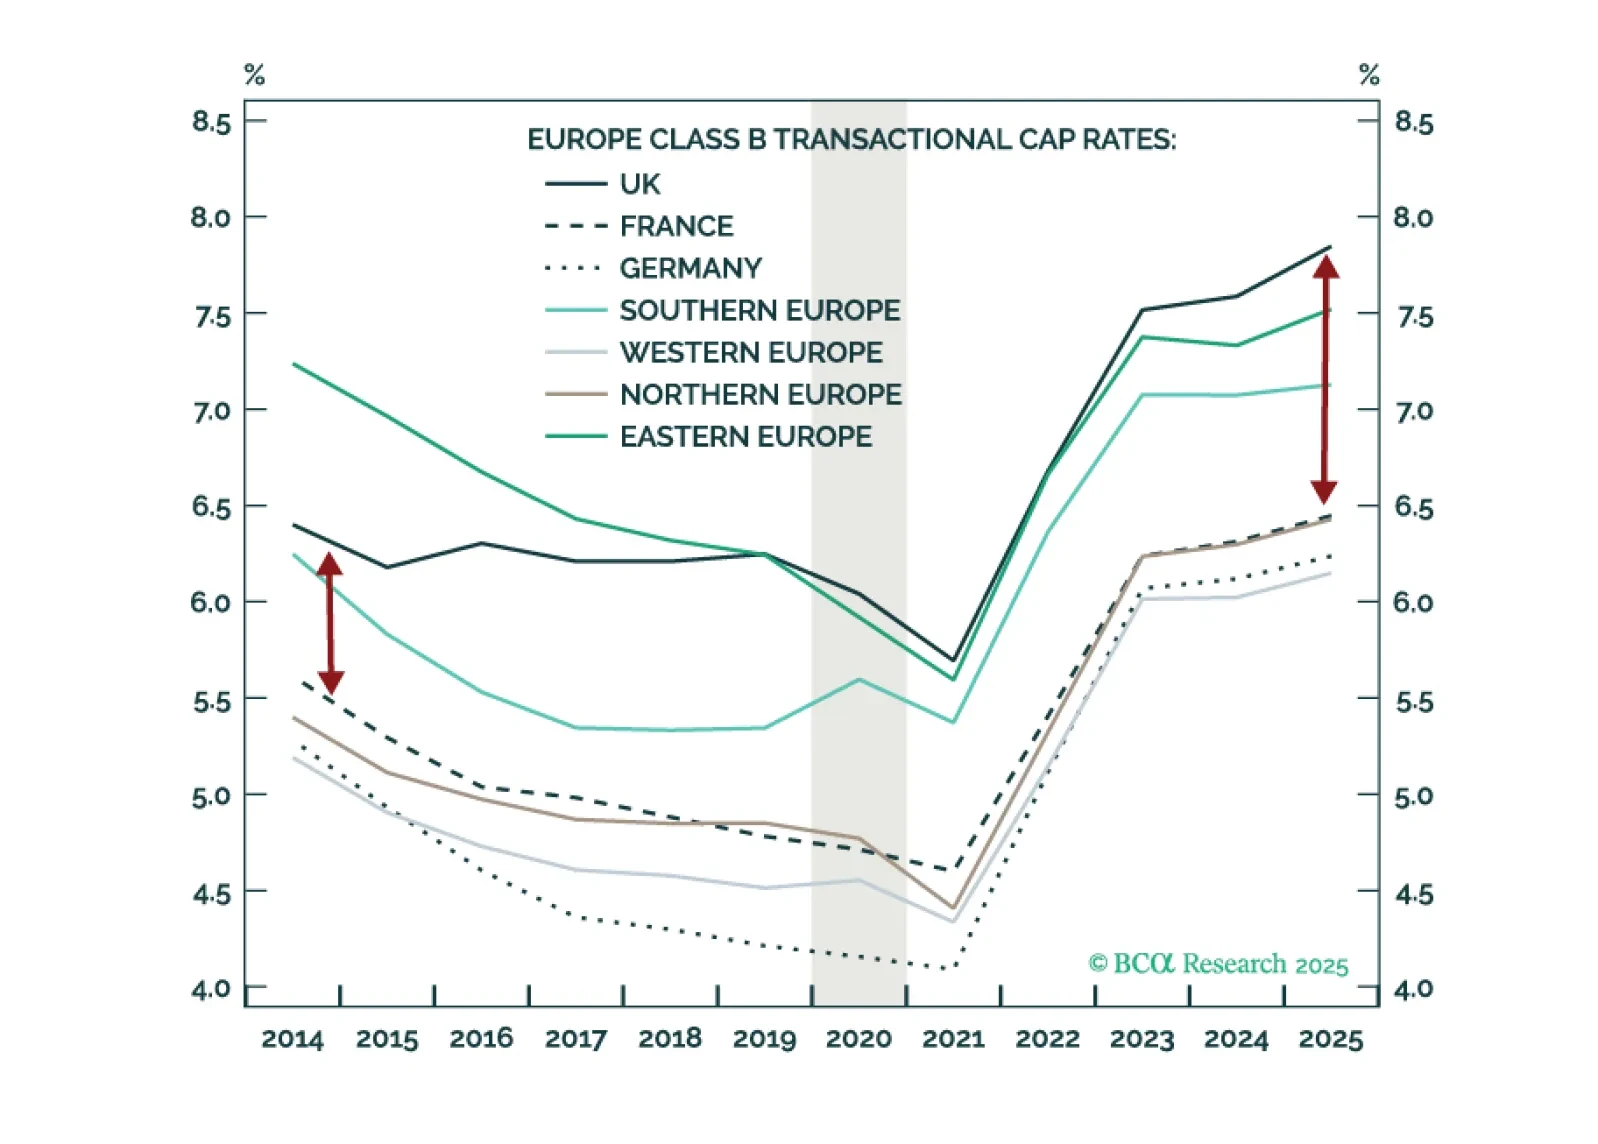
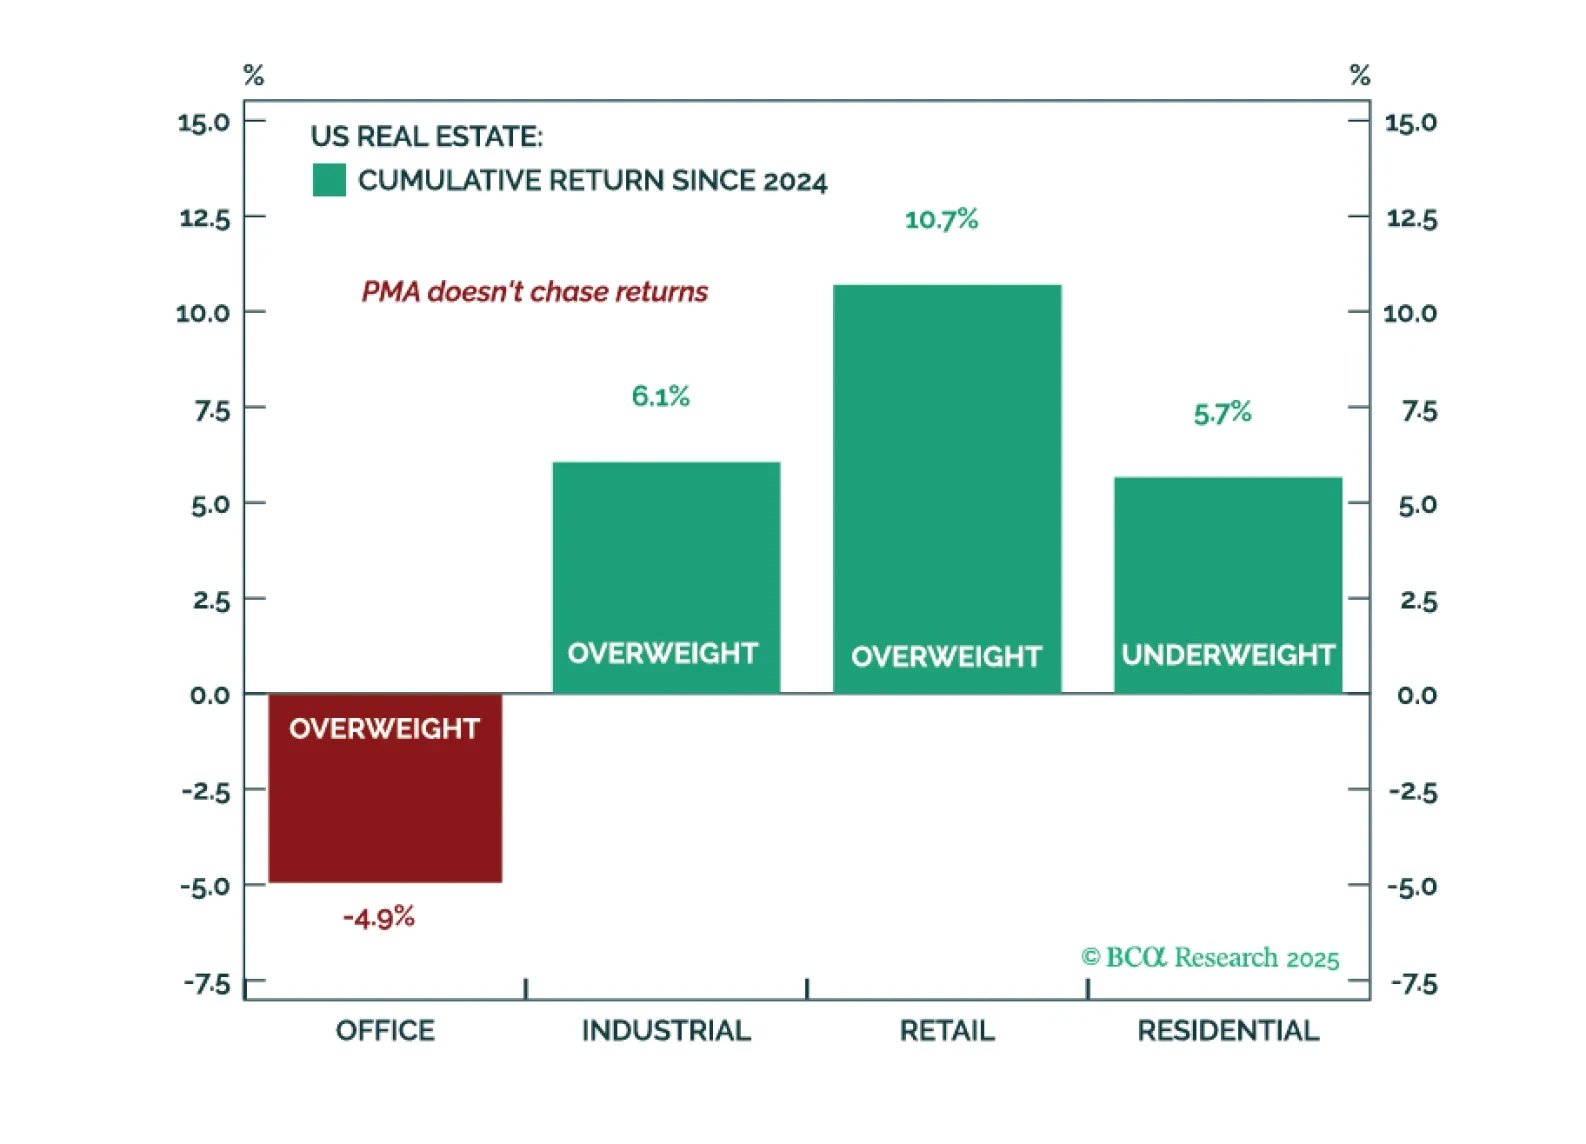
As in the US, Europe now offers compelling opportunities, albeit in different sectors and countries. Multifamily remains resilient amid structurally tight supply, while Industrial continues to cool. The most attractive opportunities are emerging in Office and Retail, where fundamentals are beginning to turn.
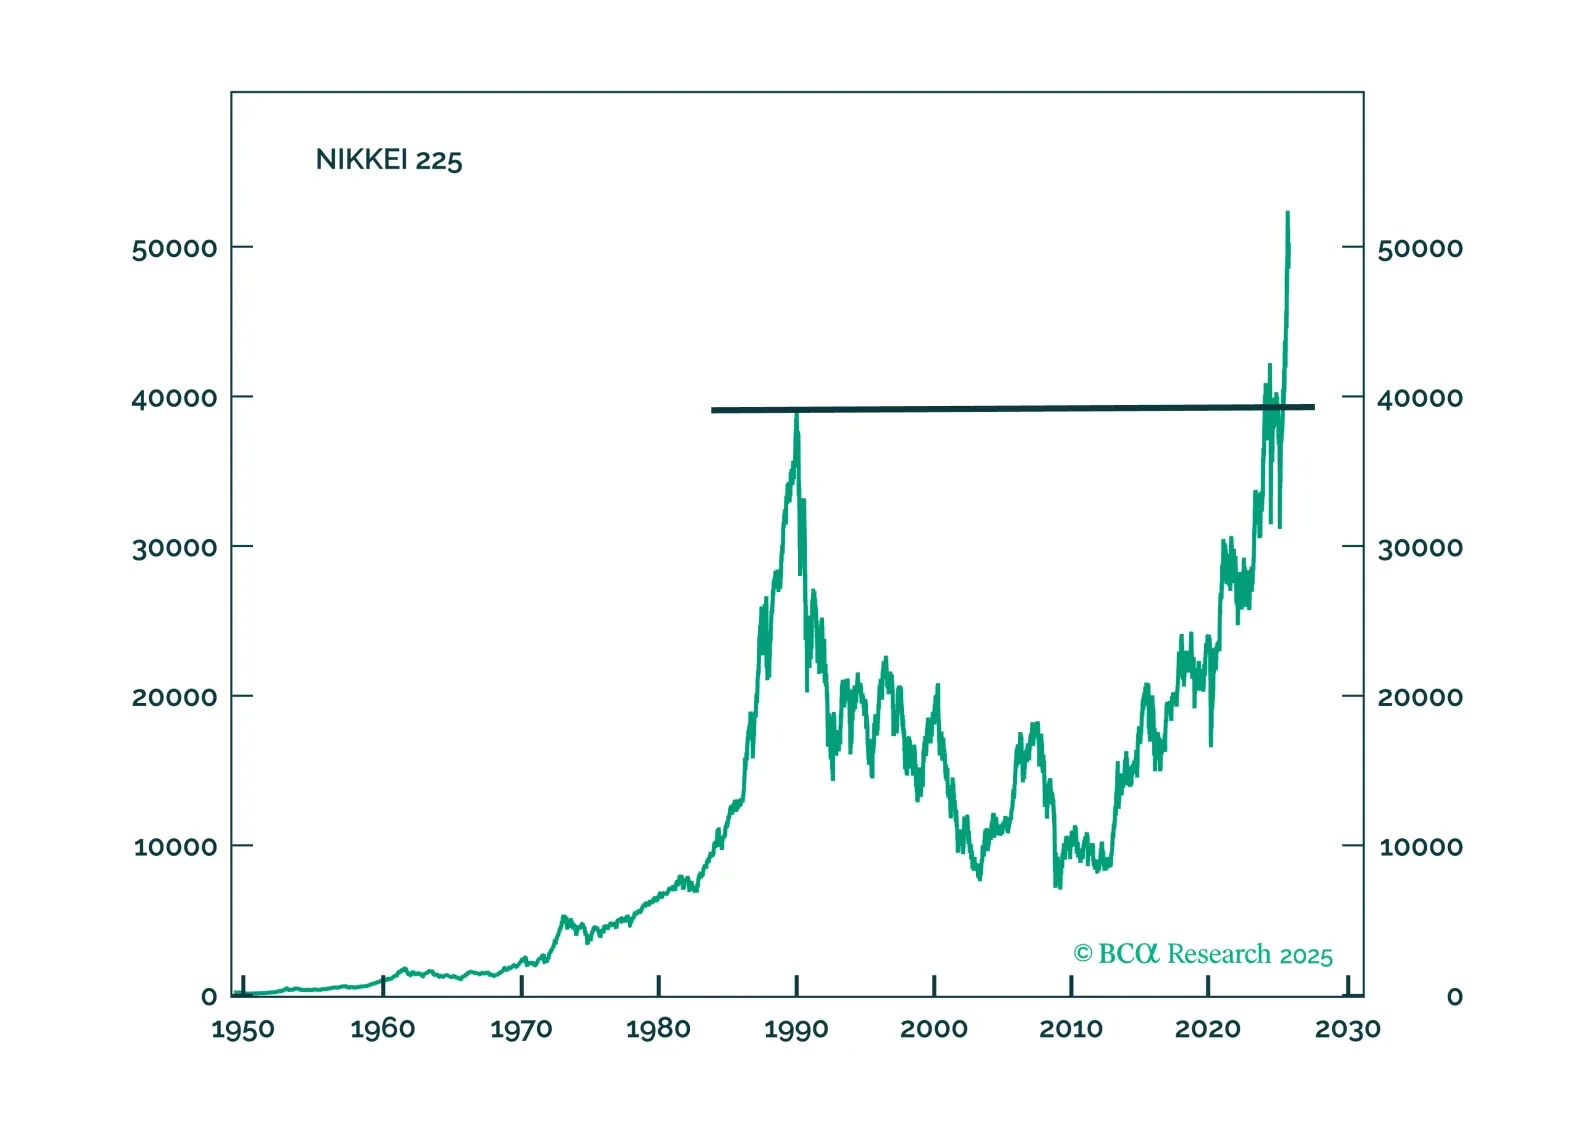
Japanese financial assets will finally have unfettered access to outsized returns. This performance will come in fits and starts, but we are comfortable laying our cards down on buying the yen, and Japanese industrial stocks.
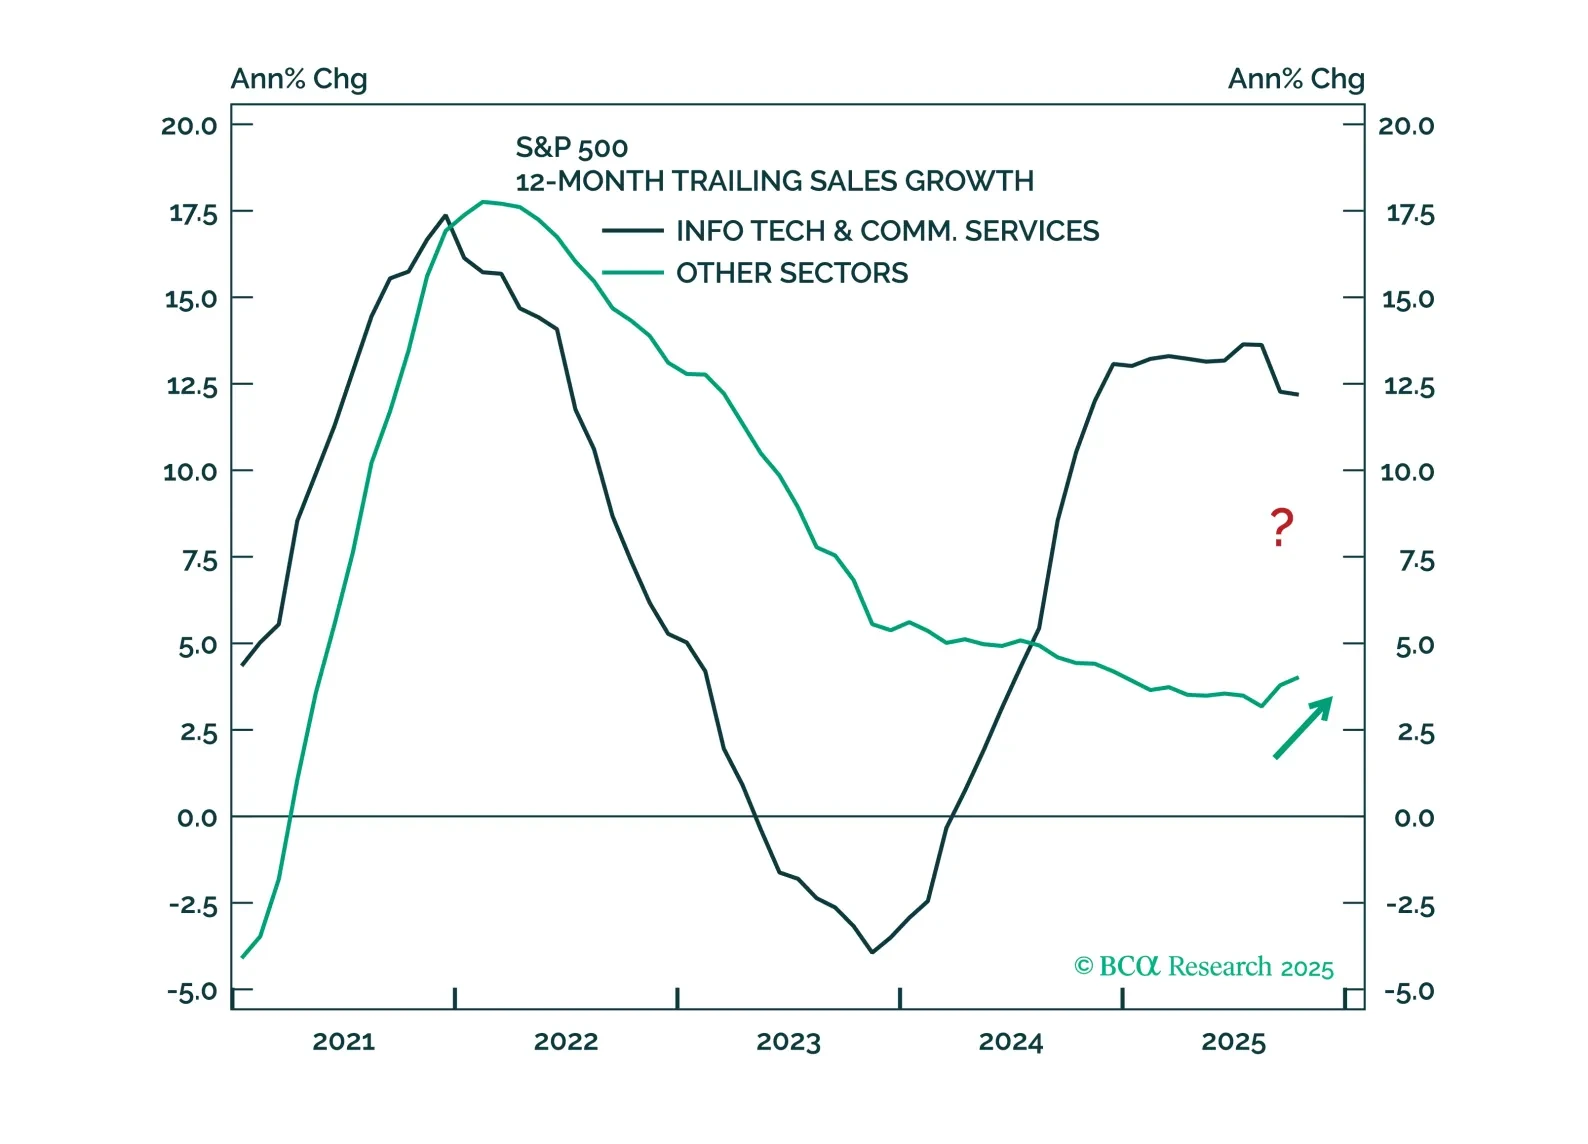
The K-shaped economy will likely reverse in 2026, with the cyclical parts of the economy doing better. Upgrade Financials and Materials from neutral to overweight. Downgrade Communication Services and Utilities from overweight to neutral. Favor value stocks. Upgrade Bitcoin from neutral to overweight.
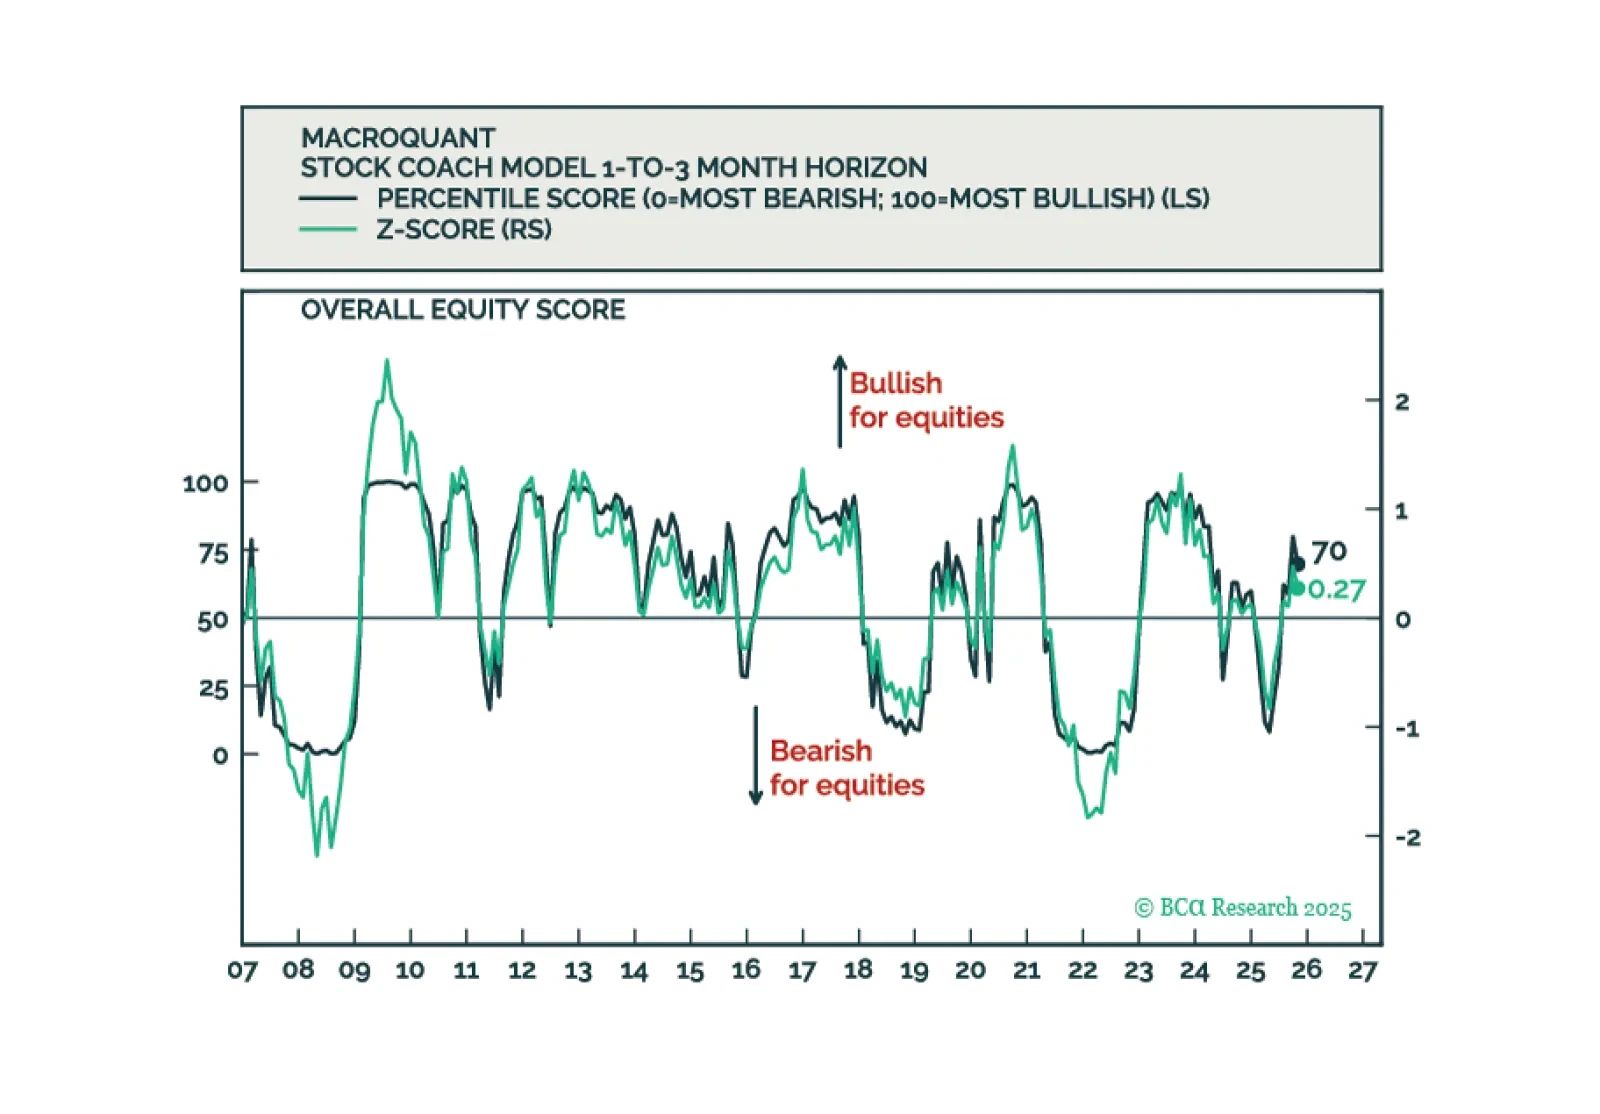
MacroQuant remains tactically overweight equities, favors an above-benchmark duration stance in fixed-income portfolios, remains bearish on the US dollar, and is bullish on gold.