CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
A Trump victory offers a buying opportunity for bonds; a Harris victory offers a selling opportunity for bonds. We explain why.

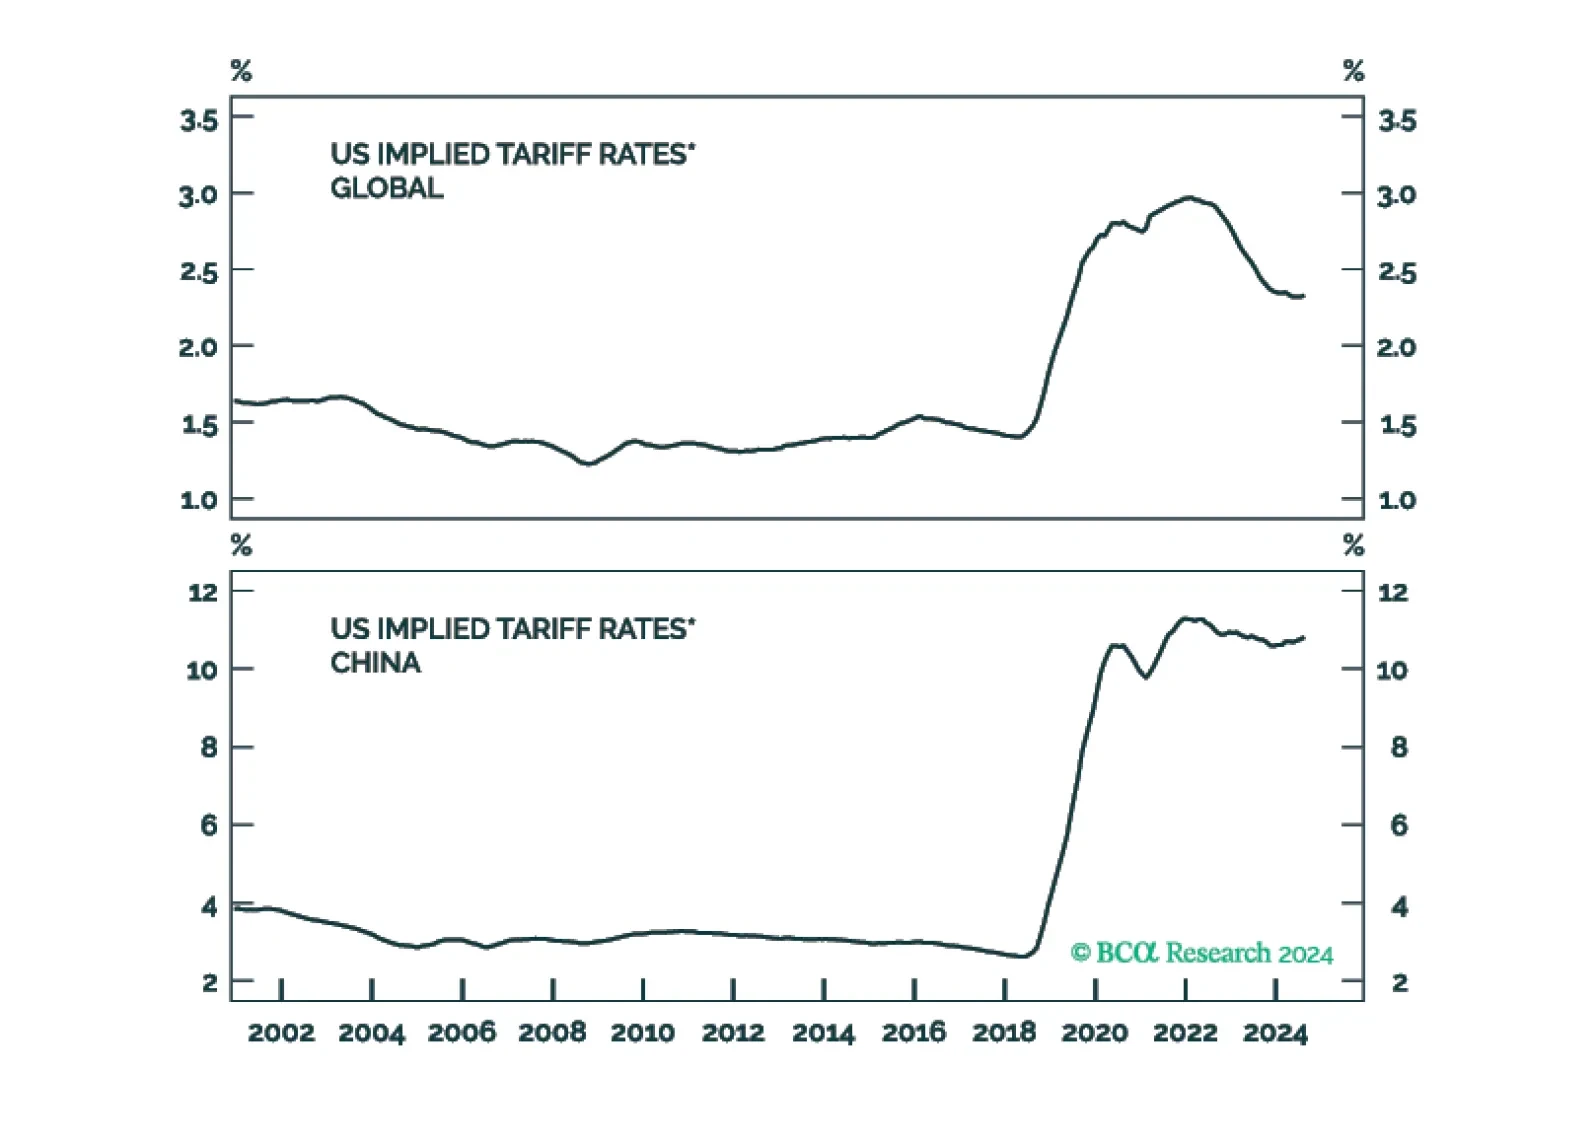
Back in 2016, there was widespread concern that if Donald Trump became president, he would start a trade war. As it turned out, Trump did become president and he did start a trade war, but the US economy continued growing anyway. In a study published in August 2019, the Congressional Budget Office concluded that Trump's tariffs reduced the level of US real GDP by 0.3% - not immaterial but not earth-shattering either.
Middle-aged households have lagged youngish and older households since the pandemic and the 40-to-54 cohort is worse off than it was at the end of 2019. The fragmenting of the seemingly monolithic US consumer widens the path to a recession and we reiterate our defensive asset allocation recommendations.
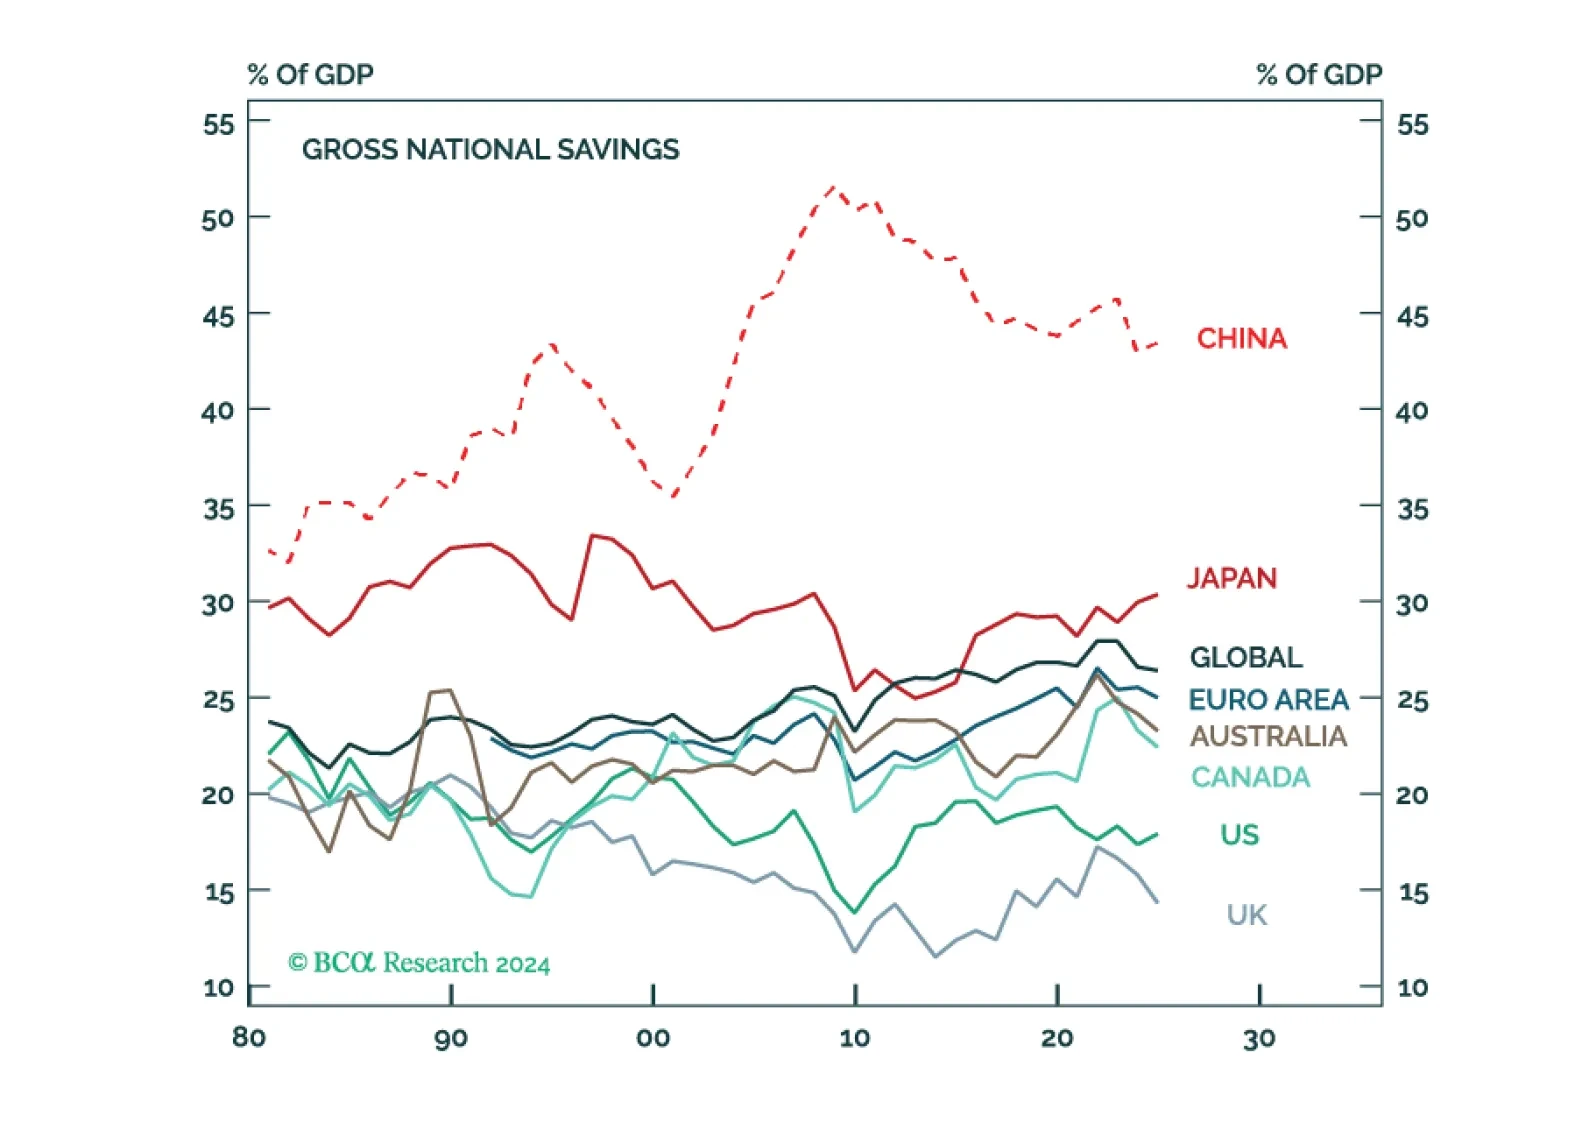
In this report, we discuss why we are lifting our US recession probability from 60% to 65% and explain why China’s latest stimulus announcements are welcome, but probably are “too little, too late.”
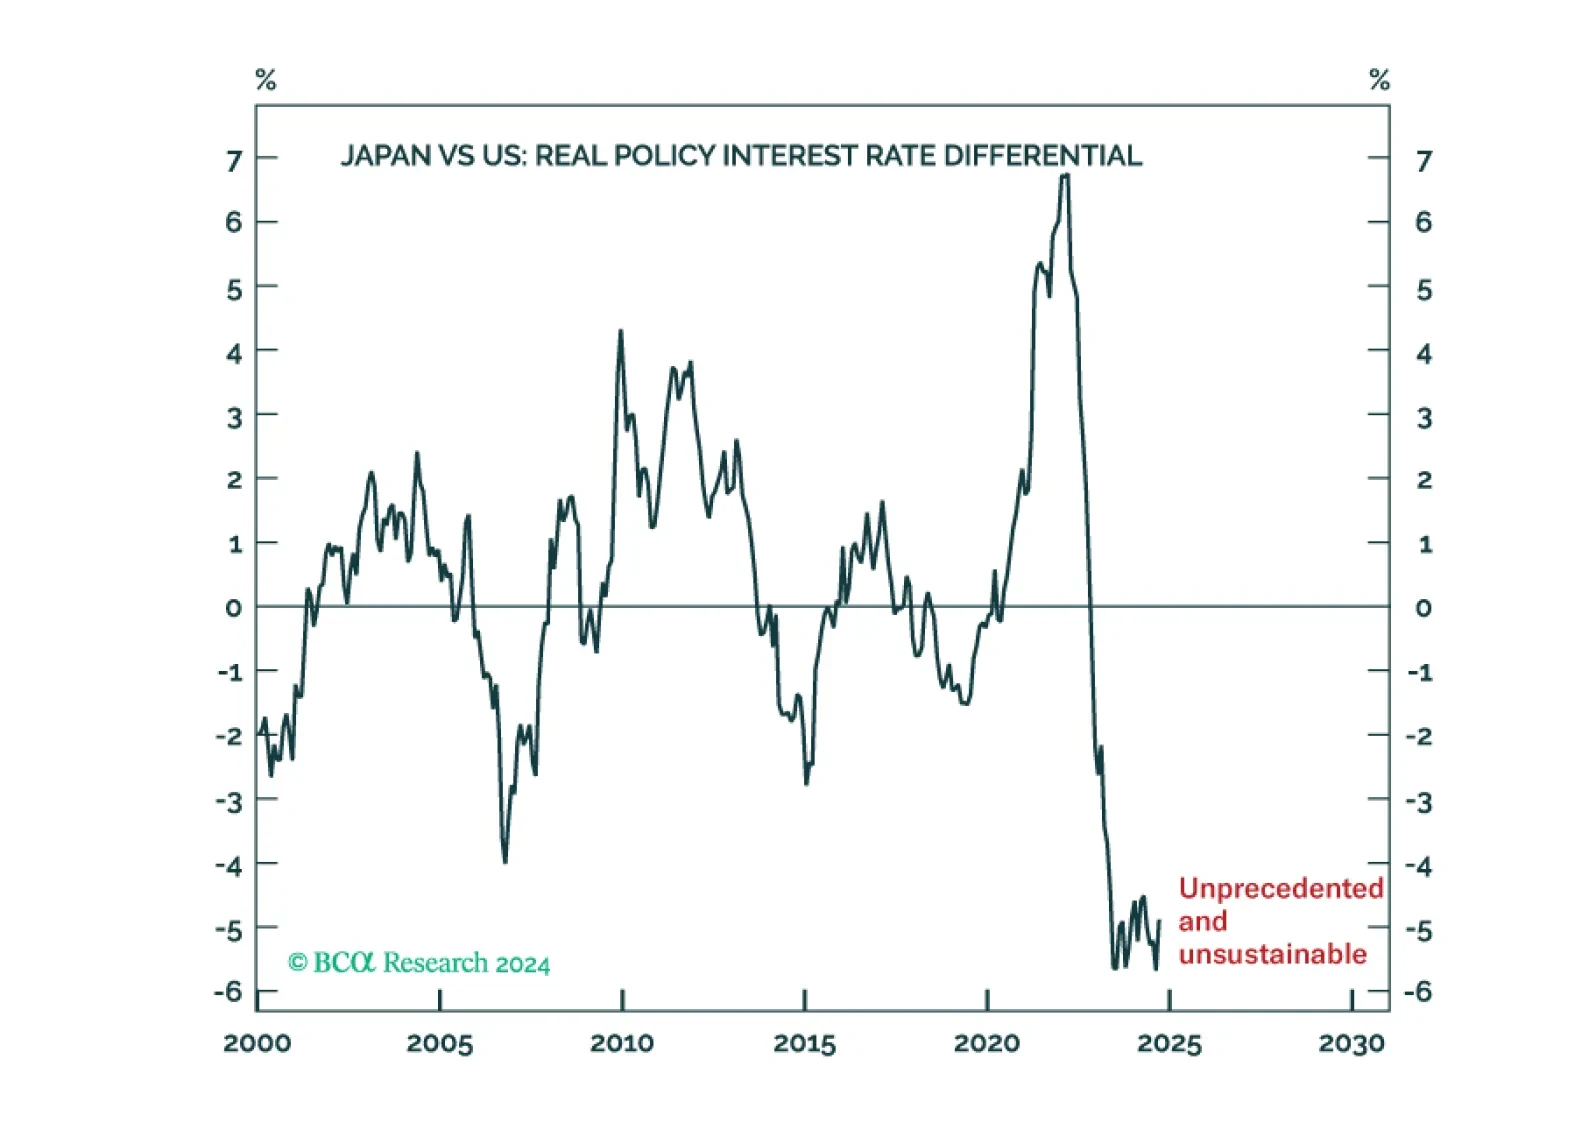
The biggest risk to the equity bull market is not a US recession. The biggest risk is the end of the deeply negative real rates in Japan versus the US that have caused the rampant post-2022 inflation in US tech stock valuations. We go through the investment implications. Plus: bond prices have further tactical downside whoever wins the US election.
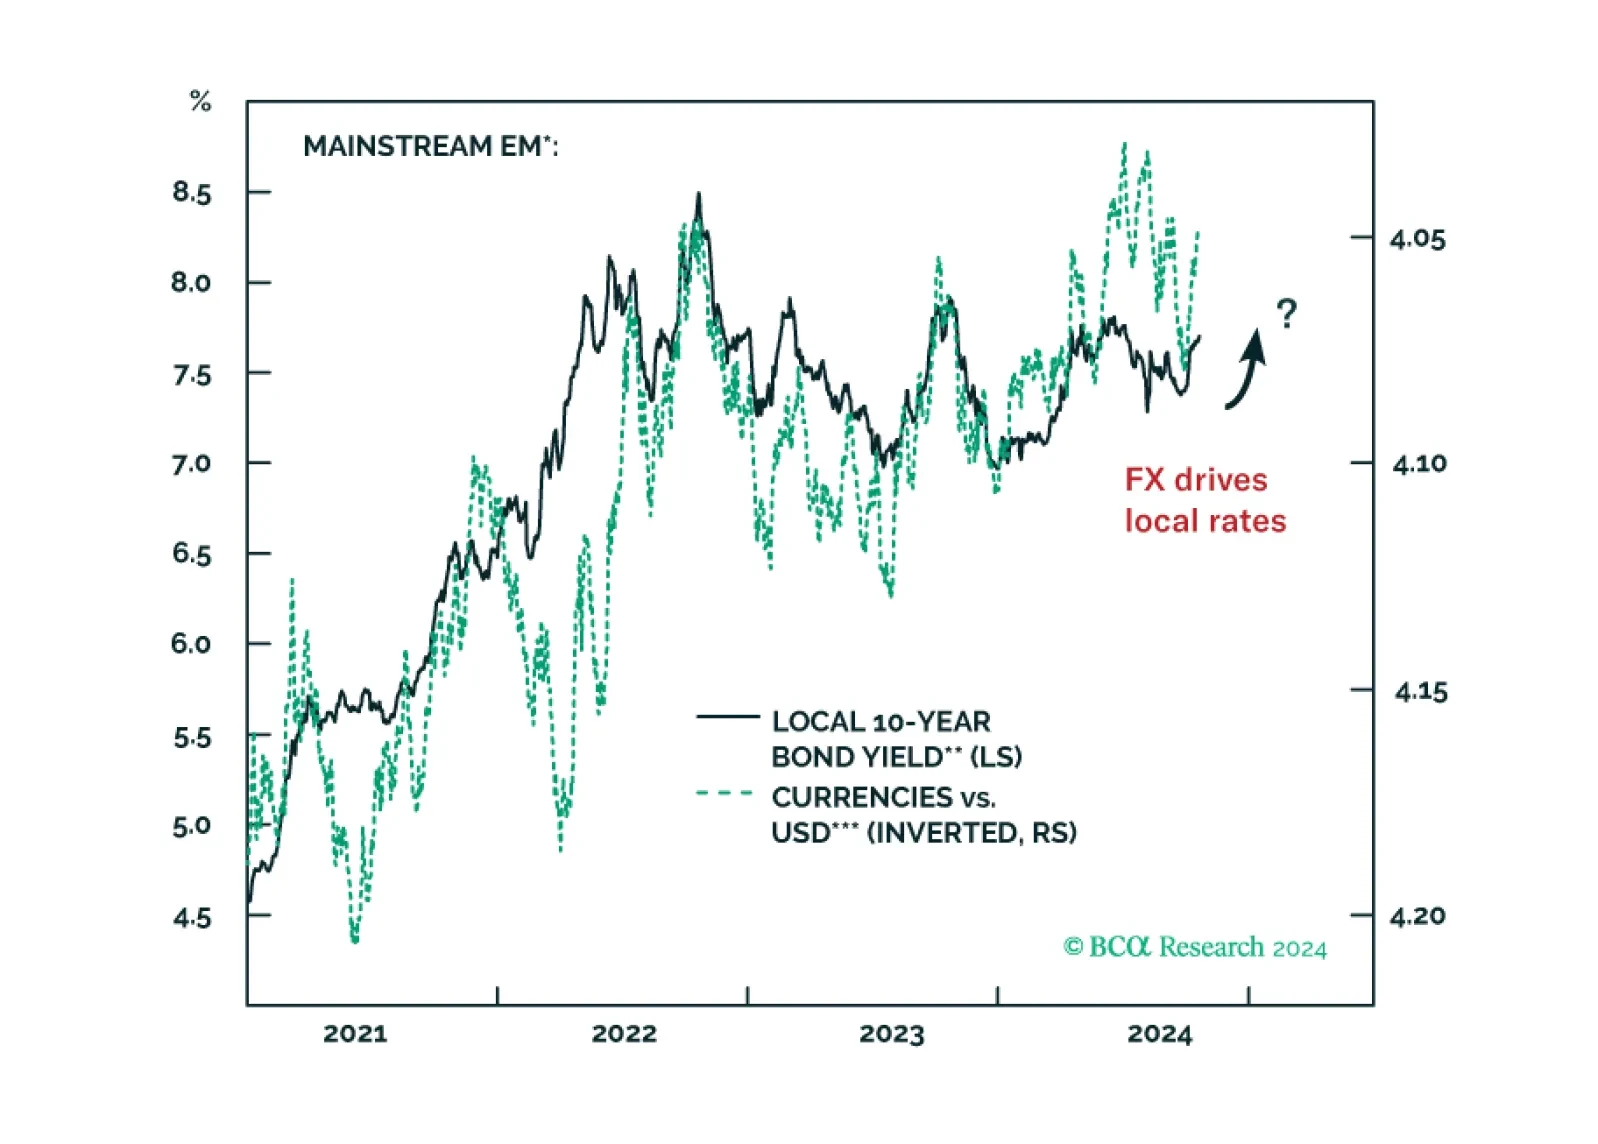
As the odds of a Trump victory increase, there are indications that the “Trump trade” has commenced in global financial markets, with negative short-term implications for EM. In short, the US dollar will strengthen, and US bond yields will rise in the lead-up to and after the election if Trump wins. In response, EM countries’ currencies will depreciate, and their fixed-income and equity markets will suffer over the coming months.
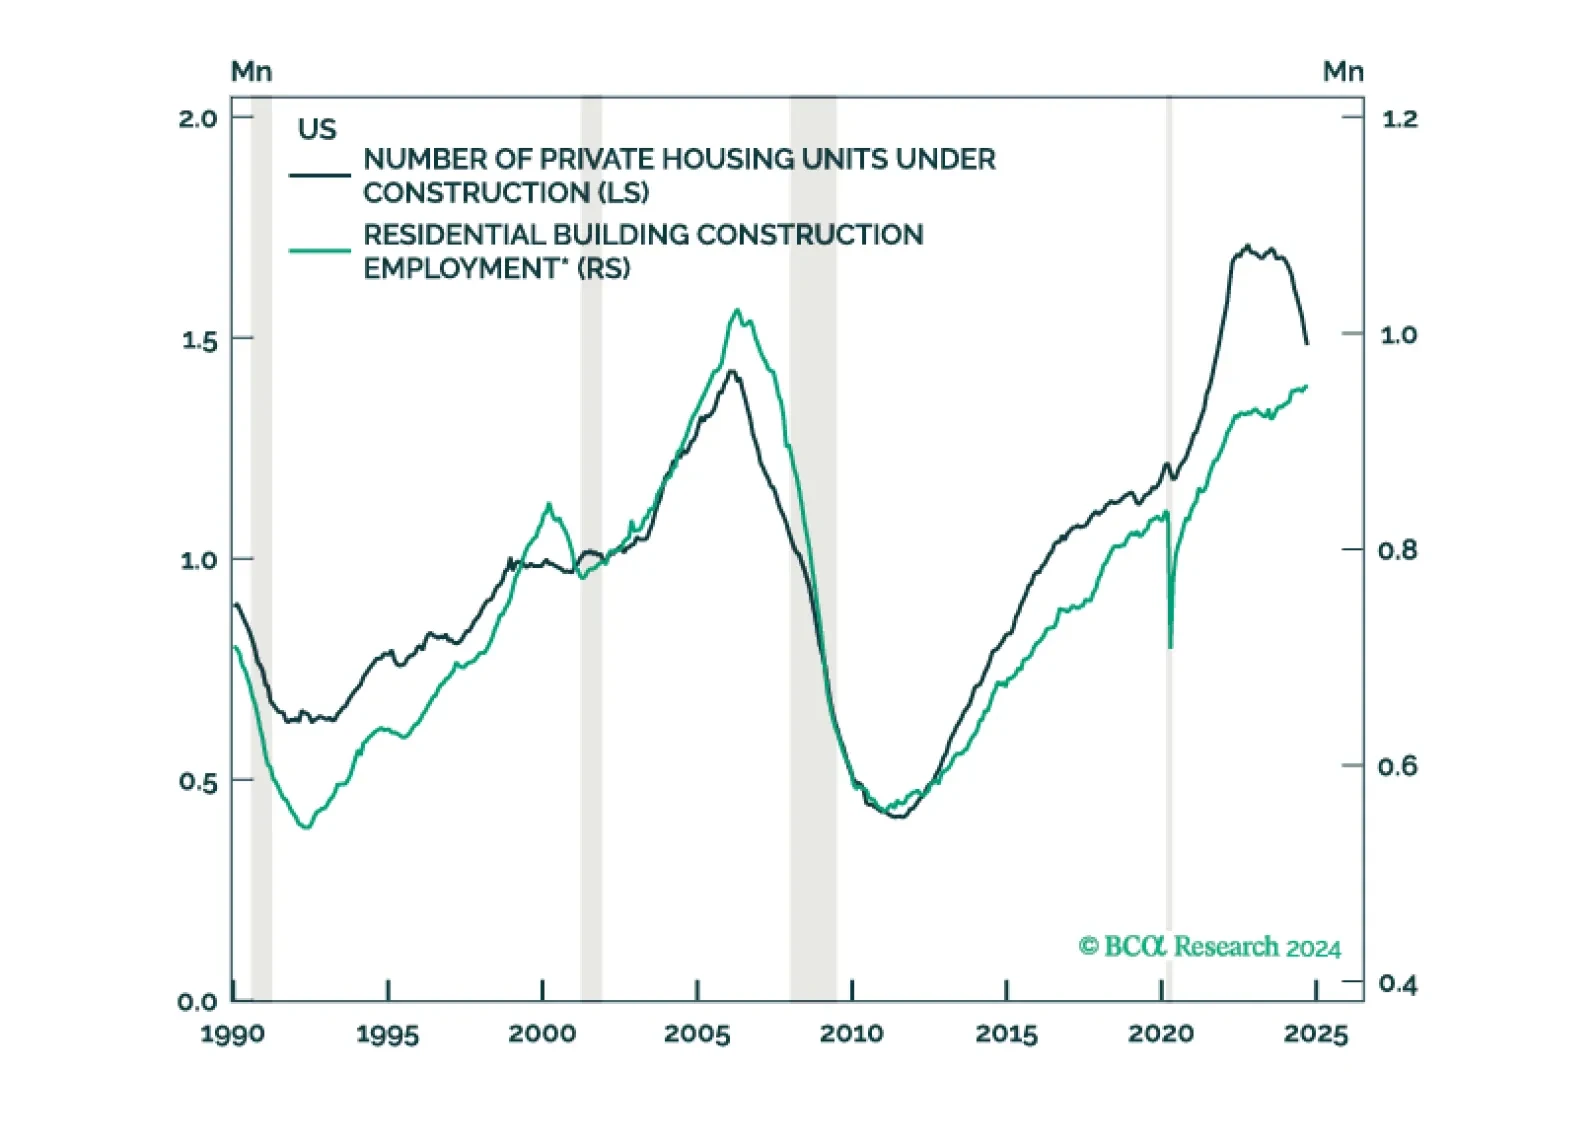
In August 2007, Ed Leamer famously presented a paper entitled Housing IS the Business Cycle at the Jackson Hole symposium. I was reminded of this paper after seeing today's US housing data.
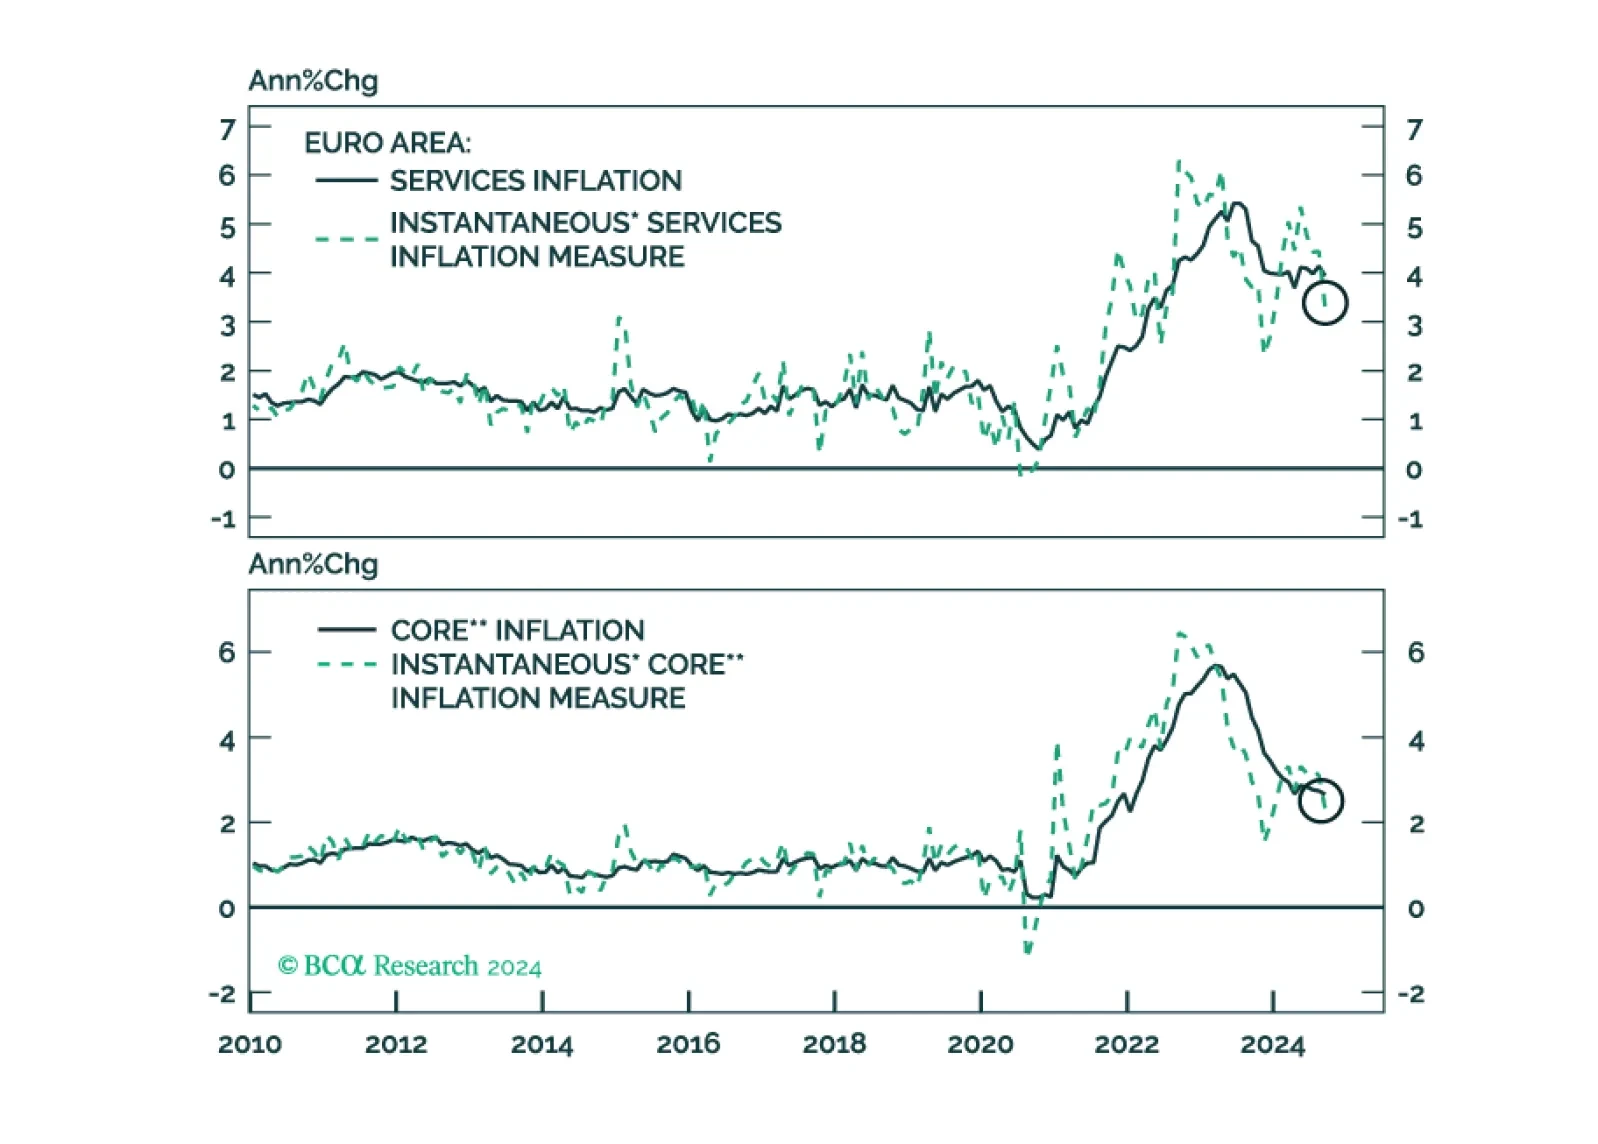
Yesterday, the ECB solidified its recent dovish tilt in response to weaker growth and decreasing inflationary pressures. It is now set to cut rates 25bps each meeting. How low will the ECB deposit rate ultimately go and what does this imply for yields and the euro?